Global FMCG Packaging Market (2026-2032) | Companies, Growth, Investment Trends, Challenges, Opportunities, Consumer Insights, Pricing Analysis, Size, Segmentation, Strategic Insights, Share, Strategy, Segments, Trends, Value, Drivers, Industry, Competitive, Restraints, Analysis, Competition, Forecast, Outlook, Demand, Supply, Revenue
Market Forecast by Regions and Countries (North America, Europe, LATAM, Middle East, Asia and Africa), By Material (Paper, Plastic, Metal, Glass, Others), By End Use Industry (Food and Beverages, Cosmetic and Personal Care, Others) And Competitive Landscape
| Product Code: ETC13195052 | Publication Date: Apr 2025 | Updated Date: Sep 2026 | Product Type: Market Research Report | |
| Publisher: 6Wresearch | Author: Dhaval Chaurasia | No. of Pages: 190 | No. of Figures: 80 | No. of Tables: 40 |
Global FMCG Packaging Market Highlights
| Market Size (2025) | USD 780 Billion |
| Forecast Size (2032) | USD 1050 Billion |
| CAGR | 17.50% |
| Base Year | 2025 |
| Forecast Period | 2026-2032 |
| Largest Region | North America |
| Fastest Growing Region | Asia |
| Largest Segment | Food and Beverages |
| Fastest Growing Segment | Cosmetic and Personal Care |
| Leading Companies | Procter & Gamble, Unilever, Amcor, Nestlé, Coca-Cola |
Global FMCG Packaging Market Size & Growth Rate (2026-2032)
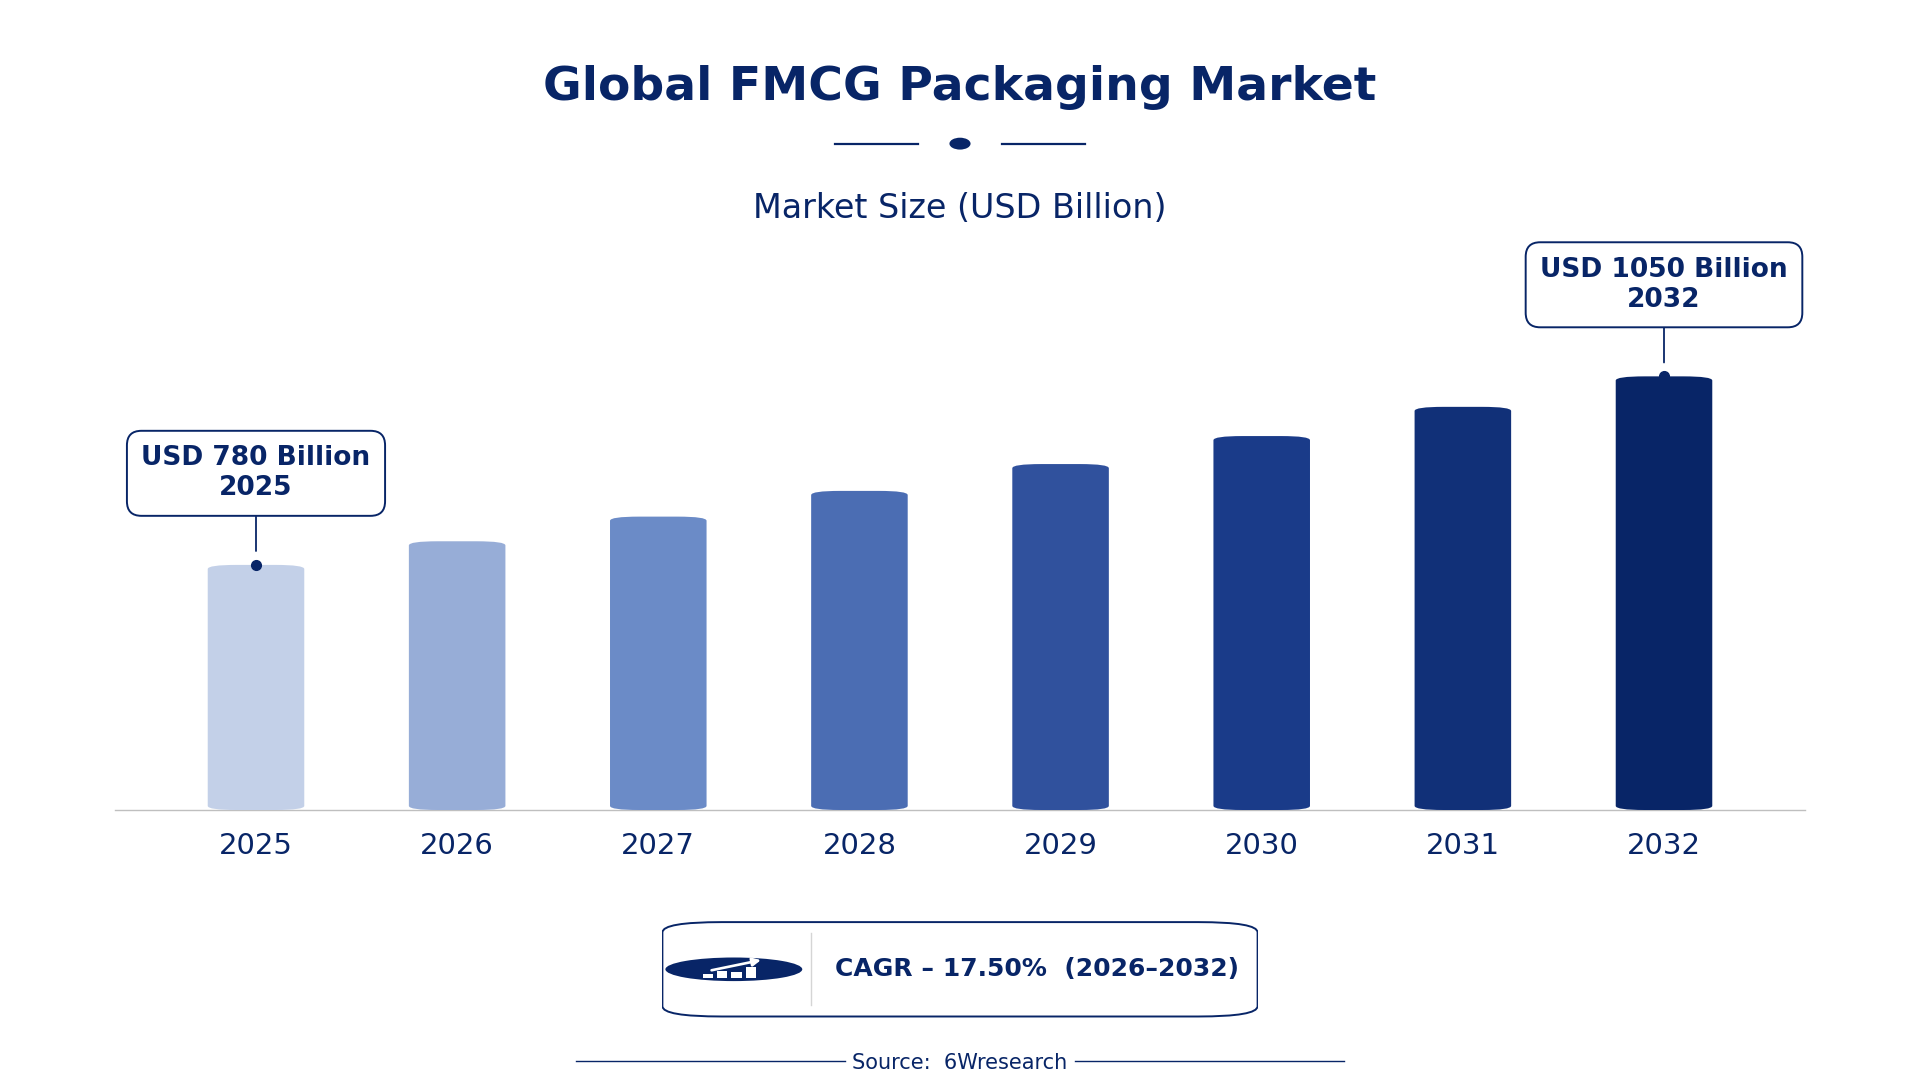
The Global FMCG Packaging Market was estimated at USD 780 Billion in 2025 and is projected to reach USD 1050 Billion by 2032, growing at a CAGR of 17.50% from 2026 to 2032.
Global FMCG Packaging Market Synopsis
Current dynamics within the Global FMCG Packaging Market reveal a pronounced shift towards sustainable packaging solutions that specifically cater to evolving consumer preferences. This market underpins several sectors, focusing squarely on the interplay between packaging and consumer convenience, branding, and sustainability. Key players are increasingly pressured to innovate, aiming to balance functionality and eco-friendliness.
As e-commerce continues its exponential rise, the demand for innovative packaging that facilitates safe delivery and enhances consumer engagement has never been more pronounced. This reshaping is not merely a trend; it's a fundamental transformation propelled by the need for brands to maintain market relevance. The shift in demand is particularly significant in sectors such as food, beverages, and personal care.
Global FMCG Packaging Market Year-wise Growth Rate and Key Drivers
This graph illustrates the annual growth rates of the Global FMCG Packaging Market from 2022 to 2032, highlighting a steady upward trajectory and projected expansion over the forecast period.
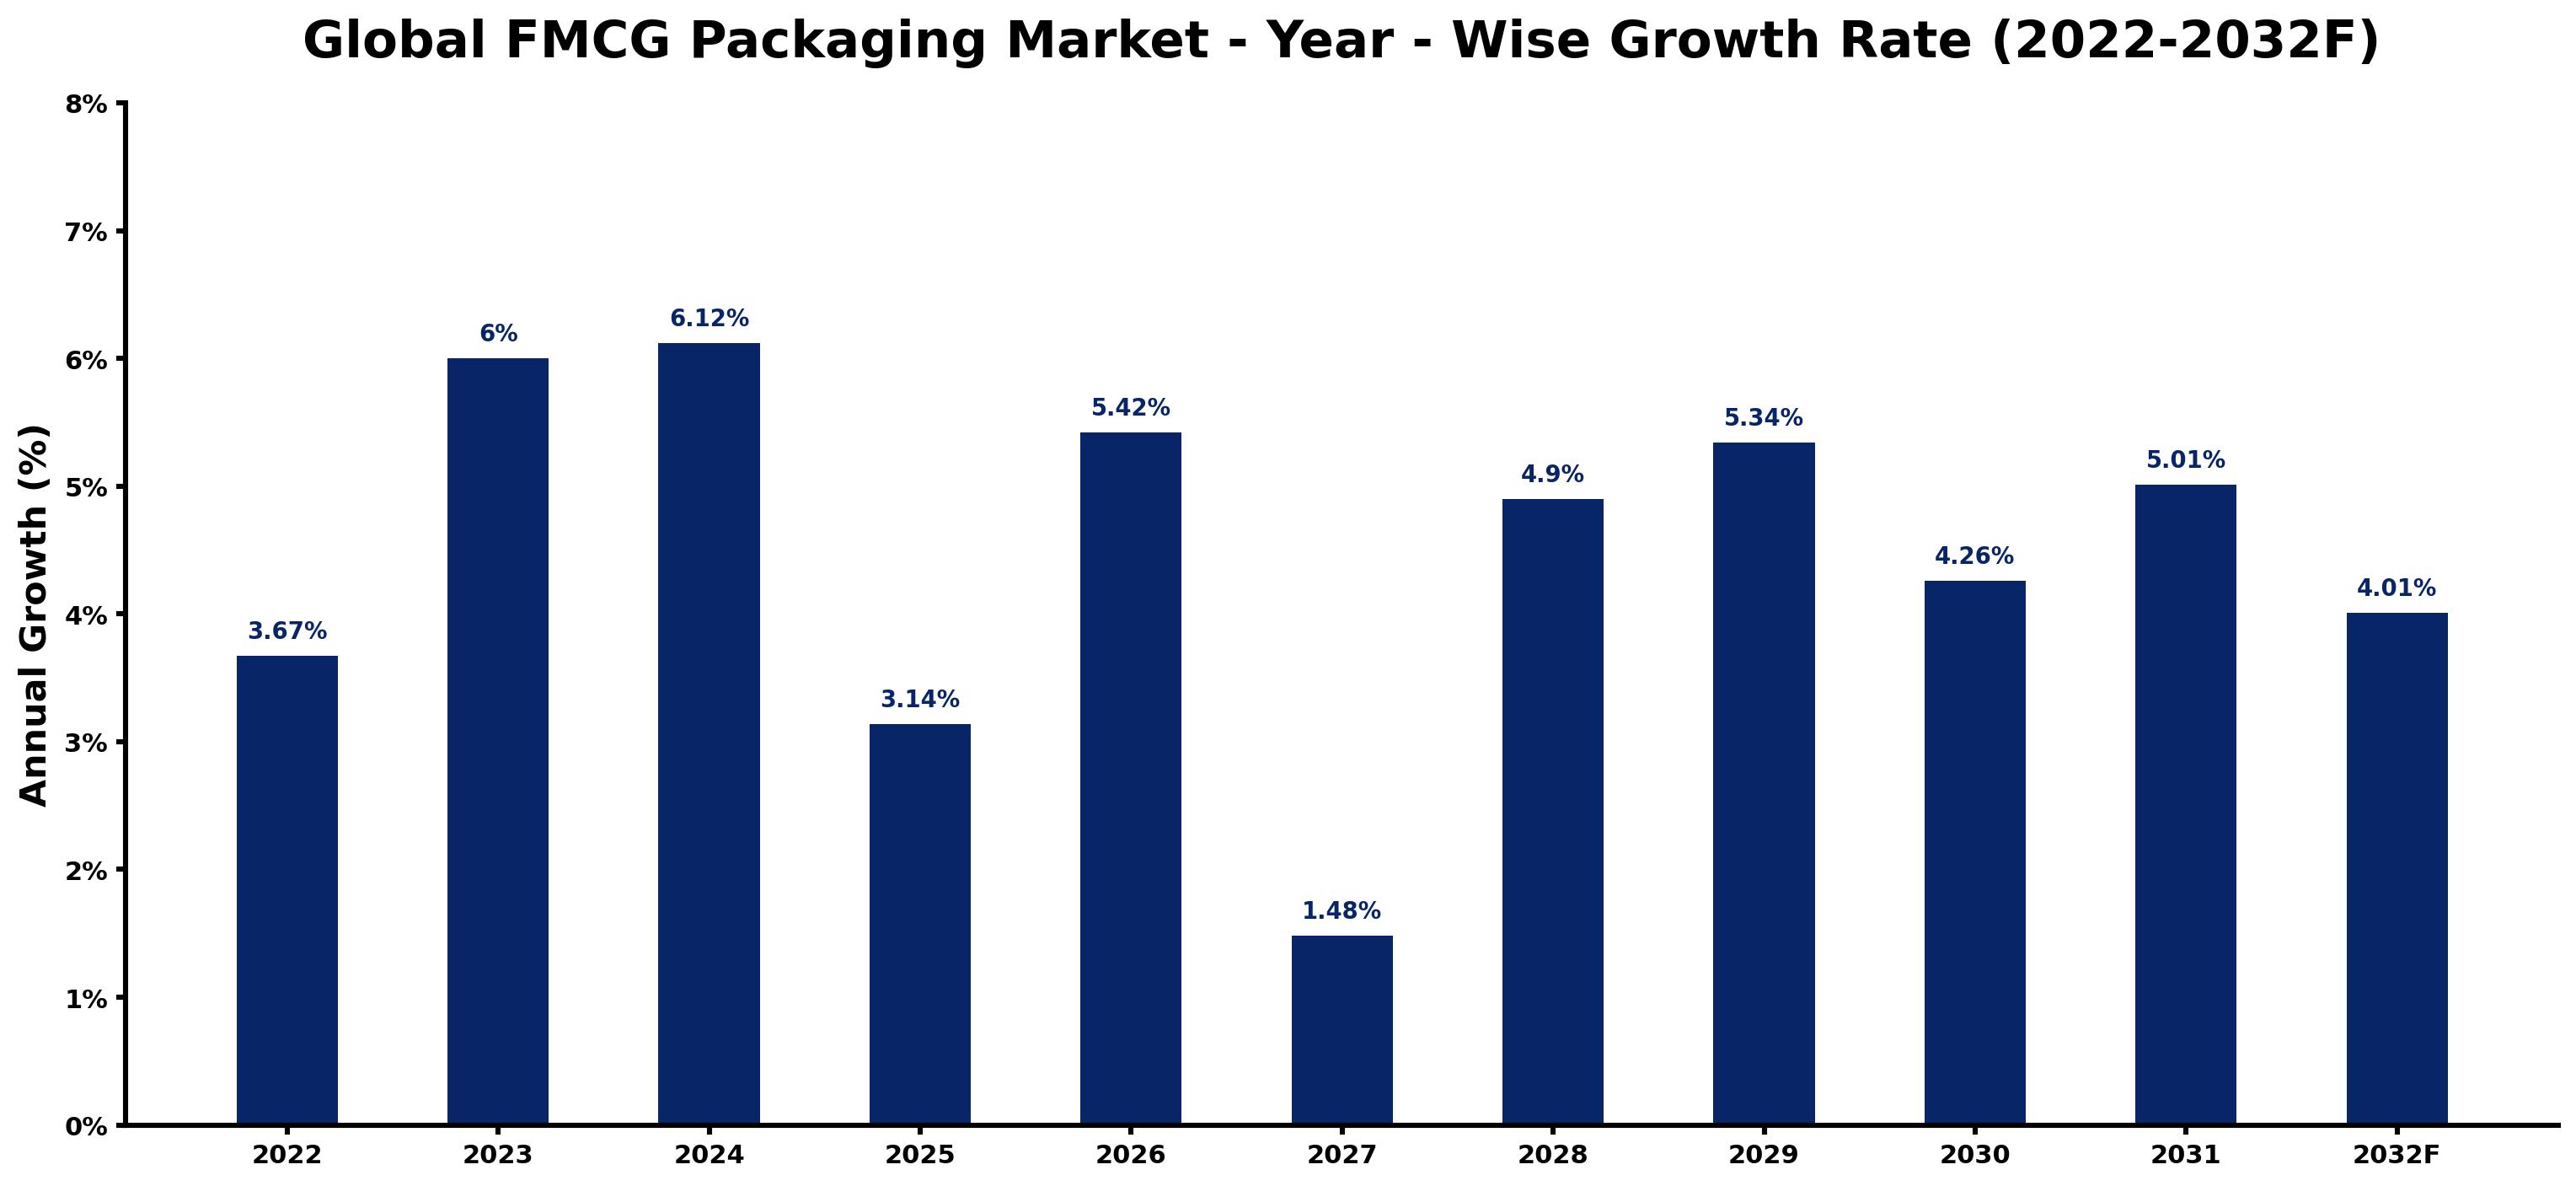
The table below presents the year‑wise growth rates along with the key drivers influencing the market
| Year | Growth Rate (%) | Major Drivers |
| 2022 | 3.67 | Manufacturers are hiring skilled workers to enhance FMCG packaging quality and efficiency. |
| 2023 | 6 | In North America, innovative packaging technologies are increasing brand visibility and customer engagement. |
| 2024 | 6.12 | Shifting market dynamics are prompting companies to invest in sustainable FMCG packaging solutions. |
| 2025 | 3.14 | Rising investment in mergers and acquisitions leads to enhanced FMCG packaging capabilities. |
| 2026 | 5.42 | As sustainability becomes paramount, eco-friendly packaging practices are gaining traction in FMCG. |
| 2027 | 1.48 | Regulatory changes are compelling brands to adopt clean-label formulations in FMCG packaging. |
| 2028 | 4.9 | Utilizing advanced materials influences cost structures in FMCG packaging production processes. |
| 2029 | 5.34 | Retailers are exploring e-commerce channels that prioritize innovative FMCG packaging for consumer convenience. |
| 2030 | 4.26 | Private-label brands are increasingly choosing high-quality FMCG packaging to attract value-driven consumers. |
| 2031 | 5.01 | A shift toward premiumization in consumer habits changes expectations for FMCG packaging aesthetics. |
| 2032 | 4.01 | Sustainable packaging technologies are facilitating geographic expansion within the global FMCG packaging sector. |
Note - Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary research methodology, combining internal industry data, secondary research, and primary validation, updated periodically to reflect current market conditions. As markets evolve rapidly, figures for certain industries may vary slightly and are intended as informed estimates rather than absolute figures. For the most current market sizing, we recommend validating figures with a 6Wresearch analyst.
Global FMCG Packaging Market Key Takeaways
Below are some of the specific key takeaways from the market, including:
- The cosmetic packaging segment is expected to grow at a CAGR of 21% from 2026 to 2032, reflecting an increasing consumer preference for premium personal care products.
- North America holds approximately 40% market share in 2025, driven primarily by a robust manufacturing ecosystem and consumer spending.
- Innovative technologies, such as smart packaging solutions led by companies like Amcor, are gaining traction, enhancing product engagement and tracking.
- Sustainable packaging initiatives are expected to save companies up to 10% in costs by reducing waste at the consumer level.
Evaluation of Restraints in Global FMCG Packaging Market
One significant challenge the Global FMCG Packaging Market faces is the financial strain imposed by regulatory compliance costs, which can be as high as $500 million annually for major corporations. For example, the 2021 European Union regulations mandating recyclability in packaging materials have led companies to invest heavily in redesigning their product lines, thereby straining budgets and affecting profit margins. Tightening regulations surrounding sustainable practices may further complicate operational adjustments while requiring a shift in strategic focus across segments.
Global FMCG Packaging Market Trends
A notable trend in the Global FMCG Packaging Market is the shift towards digitalized packaging solutions. These innovations enable interactive consumer engagement while enhancing supply chain transparency. Companies like Coca-Cola are leading the charge by integrating QR codes on packaging to provide consumers with additional product information and recycling instructions, which aligns with sustainability efforts. As of 2022, about 30% of FMCG brands have adopted some form of smart packaging technology. Additionally, eco-design principles are now being embedded into the R&D processes of packaging companies, a trend that companies such as Procter & Gamble have pioneered to improve material efficiency.
Global FMCG Packaging Market Opportunities
New revenue streams for the Global FMCG Packaging Market can be found in sectors such as medical devices and renewable energy. Companies like Nestlé are increasingly investing in biodegradable packaging alternatives, enhancing their sustainability credentials and capturing eco-conscious consumers. For example, Nestlé aims to make 100% of its packaging recyclable or reusable by 2025, which opens pathways for upstream innovation and cost savings in waste management. Furthermore, the rise of e-commerce platforms invites packaging solutions tailored specifically for home delivery, creating opportunities for significant growth in this segment.
Global FMCG Packaging Market by Material
The leading material segment within the Global FMCG Packaging Market is Plastic, commanding approximately 47% market share in 2025. Conversely, the fastest-growing material is Paper, projected to witness a CAGR of 10% from 2026 to 2032, driven by increasing consumer sentiment toward sustainable packaging options. Companies are rapidly transitioning to Paper for its environmental advantages and versatility, reflecting a broader industry trend where eco-friendliness significantly influences purchasing decisions.
Global FMCG Packaging Market by End Use Industry
The Food and Beverages sector remains the largest end-use industry for the Global FMCG Packaging Market, representing around 60% market share in 2025. However, the fastest-growing segment is Cosmetic and Personal Care, which is expected to expand with a robust CAGR of 22% from 2026 to 2032. Increased disposable income and a persistent trend towards luxury personal care products are pivotal in driving this segment's growth. Consumer preferences toward high-quality packaging solutions are influencing brand strategies across this industry.
Global FMCG Packaging Market by Region
North America is currently the largest region in the Global FMCG Packaging Market, with an estimated 40% share in 2025, benefiting from a strong manufacturing base and high consumer spending. Over the forecast period, Asia is anticipated to become the fastest-growing region, exhibiting a CAGR of 19% from 2026 to 2032. This growth is attributed to rapid urbanization and an expanding middle class, driving demand for consumer goods and, by extension, innovative packaging solutions tailored to diverse market needs.
Government Initiatives in the Global FMCG Packaging Market
The regulatory landscape surrounding the Global FMCG Packaging Market is characterized by strong government initiatives aimed at promoting sustainable practices and innovative packaging solutions. These initiatives not only guide manufacturers but also create competitive advantages for compliant firms in an increasingly environmentally conscious market.
- U.S. Environmental Protection Agency, "Reducing Food Waste: A National Strategy," July 2021. This initiative encourages companies to optimize packaging designs to minimize waste, benefiting firms that adopt eco-friendly materials.
- European Commission, "Single-Use Plastics Directive," May 2021. This regulation aims to reduce plastic pollution by banning certain single-use plastics, prompting FMCG firms to innovate in sustainable alternatives.
- Government of Canada, "Canada Plastics Strategy," March 2022. This initiative invests in the development of sustainable packaging R&D to reduce plastic usage in consumer goods.
- SEV (Sustainable Economics Ventures), "Sustainable Packaging Incentives Program," January 2023. This program provides funding for companies pursuing sustainable packaging projects, further encouraging investment in innovative materials.
Future Insights of the Global FMCG Packaging Market
The Global FMCG Packaging Market is expected to witness transformative advancements driven by technological progress and sustainability commitments. As companies like Unilever aim to achieve 100% reusable, recyclable, or compostable packaging by 2025, the emphasis on eco-friendly materials will shape future offerings. Emerging technologies such as advanced recycling processes and smart packaging are anticipated to facilitate greater consumer engagement and operational efficiencies. This shift is not merely reactive; it reflects a proactive strategy to navigate regulatory pressures and changing consumer dynamics.
Global FMCG Packaging Market Latest Developments
Several noteworthy developments in the Global FMCG Packaging Market highlight ongoing innovation and expansion efforts across leading companies. These initiatives are reshaping market dynamics and competitive landscapes.
- Coca-Cola is rolling out its new Eco-Cycle packaging initiative, aimed at reducing single-use plastics by 2025, reinforcing its commitment to sustainability and appealing to environmentally-conscious consumers.
- Amcor is currently developing an advanced paper-based packaging solution, set for launch in late 2023, to enhance its product line while responding to increasing demand for sustainable alternatives.
- Procter & Gamble is exploring partnerships in innovative material technology, with plans for new product lines in 2024 that leverage biodegradable materials, positioning itself as a leader in eco-friendly packaging.
- Unilever recently completed the acquisition of a biodegradable packaging startup in early 2023, enhancing its capabilities in sustainable packaging and further committing to its green objectives.
Global FMCG Packaging Market Key Players and Industry Positioning
The competitive structure of the Global FMCG Packaging Market is partially consolidated, with a mix of established players and niche innovators driving growth through diverse strategies. Companies are increasingly focusing on sustainability, digital solutions, and market expansion to differentiate themselves.
| Leading Company | Core Strength | Strategic Focus |
|---|---|---|
| Procter & Gamble | Expertise in consumer-centric design | Sustainable materials and biodegradable products |
| Unilever | Strong brand portfolio | Circular economy initiatives for reduced waste |
| Amcor | Advanced material science capabilities | Innovative packaging solutions with a focus on recyclability |
| Nestlé | Global supply chain expertise | Investment in sustainable packaging alternatives |
| Coca-Cola | Extensive distribution network | Sustainability initiatives and product diversification |
The dynamic competitive environment underscores the imperative for players to adapt to sustainable practices and technological advancements, ensuring market relevance through innovative approaches.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year: 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- Global FMCG Packaging Market Outlook
- Market Size of Global FMCG Packaging Market, 2025
- Forecast of Global FMCG Packaging Market, 2032
- Historical Data and Forecast of Global FMCG Packaging Revenues & Volume for the Period 2022-2032
- Global FMCG Packaging Market Trend Evolution
- Global FMCG Packaging Market Drivers and Challenges
- Global FMCG Packaging Price Trends
- Global FMCG Packaging Porter's Five Forces
- Global FMCG Packaging Industry Life Cycle
- Historical Data and Forecast of Global FMCG Packaging Market Revenues & Volume
- Historical Data and Forecast of Global FMCG Packaging Market Revenues & Volume By Material for the Period 2022-2032
- Historical Data and Forecast of Global FMCG Packaging Market Revenues & Volume By Paper for the Period 2022-2032
- Historical Data and Forecast of Global FMCG Packaging Market Revenues & Volume By Plastic for the Period 2022-2032
- Historical Data and Forecast of Global FMCG Packaging Market Revenues & Volume By Metal for the Period 2022-2032
- Historical Data and Forecast of Global FMCG Packaging Market Revenues & Volume By Glass for the Period 2022-2032
- Historical Data and Forecast of Global FMCG Packaging Market Revenues & Volume By Others for the Period 2022-2032
- Historical Data and Forecast of Global FMCG Packaging Market Revenues & Volume By End Use Industry for the Period 2022-2032
- Historical Data and Forecast of Global FMCG Packaging Market Revenues & Volume By Food and Beverages for the Period 2022-2032
- Historical Data and Forecast of Global FMCG Packaging Market Revenues & Volume By Cosmetic and Personal Care for the Period 2022-2032
- Historical Data and Forecast of Global FMCG Packaging Market Revenues & Volume By Others for the Period 2022-2032
- Historical Data and Forecast of North America FMCG Packaging Market Revenues & Volume By Material for the Period 2022-2032
- Historical Data and Forecast of North America FMCG Packaging Market Revenues & Volume By Paper for the Period 2022-2032
- Historical Data and Forecast of North America FMCG Packaging Market Revenues & Volume By Plastic for the Period 2022-2032
- Historical Data and Forecast of North America FMCG Packaging Market Revenues & Volume By Metal for the Period 2022-2032
- Historical Data and Forecast of North America FMCG Packaging Market Revenues & Volume By Glass for the Period 2022-2032
- Historical Data and Forecast of North America FMCG Packaging Market Revenues & Volume By Others for the Period 2022-2032
- Historical Data and Forecast of North America FMCG Packaging Market Revenues & Volume By End Use Industry for the Period 2022-2032
- Historical Data and Forecast of North America FMCG Packaging Market Revenues & Volume By Food and Beverages for the Period 2022-2032
- Historical Data and Forecast of North America FMCG Packaging Market Revenues & Volume By Cosmetic and Personal Care for the Period 2022-2032
- Historical Data and Forecast of North America FMCG Packaging Market Revenues & Volume By Others for the Period 2022-2032
- Historical Data and Forecast of United States of America FMCG Packaging Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Canada FMCG Packaging Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Rest of North America FMCG Packaging Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) FMCG Packaging Market Revenues & Volume By Material for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) FMCG Packaging Market Revenues & Volume By Paper for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) FMCG Packaging Market Revenues & Volume By Plastic for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) FMCG Packaging Market Revenues & Volume By Metal for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) FMCG Packaging Market Revenues & Volume By Glass for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) FMCG Packaging Market Revenues & Volume By Others for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) FMCG Packaging Market Revenues & Volume By End Use Industry for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) FMCG Packaging Market Revenues & Volume By Food and Beverages for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) FMCG Packaging Market Revenues & Volume By Cosmetic and Personal Care for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) FMCG Packaging Market Revenues & Volume By Others for the Period 2022-2032
- Historical Data and Forecast of Brazil FMCG Packaging Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Mexico FMCG Packaging Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Argentina FMCG Packaging Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Rest of LATAM FMCG Packaging Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Asia FMCG Packaging Market Revenues & Volume By Material for the Period 2022-2032
- Historical Data and Forecast of Asia FMCG Packaging Market Revenues & Volume By Paper for the Period 2022-2032
- Historical Data and Forecast of Asia FMCG Packaging Market Revenues & Volume By Plastic for the Period 2022-2032
- Historical Data and Forecast of Asia FMCG Packaging Market Revenues & Volume By Metal for the Period 2022-2032
- Historical Data and Forecast of Asia FMCG Packaging Market Revenues & Volume By Glass for the Period 2022-2032
- Historical Data and Forecast of Asia FMCG Packaging Market Revenues & Volume By Others for the Period 2022-2032
- Historical Data and Forecast of Asia FMCG Packaging Market Revenues & Volume By End Use Industry for the Period 2022-2032
- Historical Data and Forecast of Asia FMCG Packaging Market Revenues & Volume By Food and Beverages for the Period 2022-2032
- Historical Data and Forecast of Asia FMCG Packaging Market Revenues & Volume By Cosmetic and Personal Care for the Period 2022-2032
- Historical Data and Forecast of Asia FMCG Packaging Market Revenues & Volume By Others for the Period 2022-2032
- Historical Data and Forecast of China FMCG Packaging Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of India FMCG Packaging Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Japan FMCG Packaging Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Rest of Asia FMCG Packaging Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Africa FMCG Packaging Market Revenues & Volume By Material for the Period 2022-2032
- Historical Data and Forecast of Africa FMCG Packaging Market Revenues & Volume By Paper for the Period 2022-2032
- Historical Data and Forecast of Africa FMCG Packaging Market Revenues & Volume By Plastic for the Period 2022-2032
- Historical Data and Forecast of Africa FMCG Packaging Market Revenues & Volume By Metal for the Period 2022-2032
- Historical Data and Forecast of Africa FMCG Packaging Market Revenues & Volume By Glass for the Period 2022-2032
- Historical Data and Forecast of Africa FMCG Packaging Market Revenues & Volume By Others for the Period 2022-2032
- Historical Data and Forecast of Africa FMCG Packaging Market Revenues & Volume By End Use Industry for the Period 2022-2032
- Historical Data and Forecast of Africa FMCG Packaging Market Revenues & Volume By Food and Beverages for the Period 2022-2032
- Historical Data and Forecast of Africa FMCG Packaging Market Revenues & Volume By Cosmetic and Personal Care for the Period 2022-2032
- Historical Data and Forecast of Africa FMCG Packaging Market Revenues & Volume By Others for the Period 2022-2032
- Historical Data and Forecast of South Africa FMCG Packaging Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Nigeria FMCG Packaging Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Egypt FMCG Packaging Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Rest of Africa FMCG Packaging Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Europe FMCG Packaging Market Revenues & Volume By Material for the Period 2022-2032
- Historical Data and Forecast of Europe FMCG Packaging Market Revenues & Volume By Paper for the Period 2022-2032
- Historical Data and Forecast of Europe FMCG Packaging Market Revenues & Volume By Plastic for the Period 2022-2032
- Historical Data and Forecast of Europe FMCG Packaging Market Revenues & Volume By Metal for the Period 2022-2032
- Historical Data and Forecast of Europe FMCG Packaging Market Revenues & Volume By Glass for the Period 2022-2032
- Historical Data and Forecast of Europe FMCG Packaging Market Revenues & Volume By Others for the Period 2022-2032
- Historical Data and Forecast of Europe FMCG Packaging Market Revenues & Volume By End Use Industry for the Period 2022-2032
- Historical Data and Forecast of Europe FMCG Packaging Market Revenues & Volume By Food and Beverages for the Period 2022-2032
- Historical Data and Forecast of Europe FMCG Packaging Market Revenues & Volume By Cosmetic and Personal Care for the Period 2022-2032
- Historical Data and Forecast of Europe FMCG Packaging Market Revenues & Volume By Others for the Period 2022-2032
- Historical Data and Forecast of United Kingdom FMCG Packaging Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of France FMCG Packaging Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Germany FMCG Packaging Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Rest of Europe FMCG Packaging Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Middle East FMCG Packaging Market Revenues & Volume By Material for the Period 2022-2032
- Historical Data and Forecast of Middle East FMCG Packaging Market Revenues & Volume By Paper for the Period 2022-2032
- Historical Data and Forecast of Middle East FMCG Packaging Market Revenues & Volume By Plastic for the Period 2022-2032
- Historical Data and Forecast of Middle East FMCG Packaging Market Revenues & Volume By Metal for the Period 2022-2032
- Historical Data and Forecast of Middle East FMCG Packaging Market Revenues & Volume By Glass for the Period 2022-2032
- Historical Data and Forecast of Middle East FMCG Packaging Market Revenues & Volume By Others for the Period 2022-2032
- Historical Data and Forecast of Middle East FMCG Packaging Market Revenues & Volume By End Use Industry for the Period 2022-2032
- Historical Data and Forecast of Middle East FMCG Packaging Market Revenues & Volume By Food and Beverages for the Period 2022-2032
- Historical Data and Forecast of Middle East FMCG Packaging Market Revenues & Volume By Cosmetic and Personal Care for the Period 2022-2032
- Historical Data and Forecast of Middle East FMCG Packaging Market Revenues & Volume By Others for the Period 2022-2032
- Historical Data and Forecast of Saudi Arabia FMCG Packaging Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of UAE FMCG Packaging Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Turkey FMCG Packaging Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Rest of Middle East FMCG Packaging Market Revenues & Volume for the Period 2022-2032
- Global FMCG Packaging Market - Key Performance Indicators
- Global FMCG Packaging Market - Import Export Trade Statistics
- Global FMCG Packaging Market - Opportunity Assessment By Countries
- Global FMCG Packaging Market - Opportunity Assessment By Material
- Global FMCG Packaging Market - Opportunity Assessment By End Use Industry
- Global FMCG Packaging Market - Top Companies Market Share
- Global FMCG Packaging Market - Top Companies Profiles
- Global FMCG Packaging Market - Comparison of Players in Technical and Operating Parameters
- Global FMCG Packaging Market - Strategic Recommendations
Markets Covered
The Global FMCG Packaging Market report provides a detailed analysis of the following market segments:
By Regions and Countries:
- North America
- Europe
- LATAM
- Middle East
- Asia
- Africa
By Material:
- Paper
- Plastic
- Metal
- Glass
- Others
By End Use Industry:
- Food
- Beverages
- Cosmetic
- Personal Care
- Others
Global FMCG Packaging Market - Frequently Asked Questions
The Global FMCG Packaging Market is projected to reach USD 1050 Billion by 2032, growing from USD 780 Billion in 2025.
Major growth drivers include consumer demand for sustainable packaging solutions and the rapid rise of e-commerce, necessitating innovative packaging for safe delivery.
Key challenges include the financial burdens associated with regulatory compliance in sustainable packaging and the need for continuous innovation to meet evolving consumer preferences.
The Food and Beverages sector remains the largest segment, while Cosmetics and Personal Care is the fastest-growing segment, reflecting shifting consumer preferences towards premium products.
Beyond the base year, the market is likely to experience significant transformation through advancements in technology, material science, and an ongoing shift towards sustainable practices across various sectors.
6Wresearch actively monitors the Global FMCG Packaging Market and publishes its comprehensive annual report, highlighting emerging trends, growth drivers, revenue analysis, and forecast outlook. Our insights help businesses to make data-backed strategic decisions with ongoing market dynamics. Our analysts track relevent industries related to the Global FMCG Packaging Market, allowing our clients with actionable intelligence and reliable forecasts tailored to emerging regional needs.
Yes, we provide customisation as per your requirements. To learn more, feel free to contact us on sales@6wresearch.com
Global FMCG Packaging Market |
1 Executive Summary |
2 Introduction |
2.1 Key Highlights of the Report |
2.2 Report Description |
2.3 Market Scope & Segmentation |
2.4 Research Methodology |
2.5 Assumptions |
3 Global FMCG Packaging Market Overview |
3.1 Global Regional Macro Economic Indicators |
3.2 Global FMCG Packaging Market Revenues & Volume, 2022 & 2032F |
3.3 Global FMCG Packaging Market - Industry Life Cycle |
3.4 Global FMCG Packaging Market - Porter's Five Forces |
3.5 Global FMCG Packaging Market Revenues & Volume Share, By Regions, 2022 & 2032F |
3.6 Global FMCG Packaging Market Revenues & Volume Share, By Material, 2022 & 2032F |
3.7 Global FMCG Packaging Market Revenues & Volume Share, By End Use Industry, 2022 & 2032F |
4 Global FMCG Packaging Market Dynamics |
4.1 Impact Analysis |
4.2 Market Drivers |
4.3 Market Restraints |
5 Global FMCG Packaging Market Trends |
6 Global FMCG Packaging Market, 2022-2032 |
6.1 Global FMCG Packaging Market, Revenues & Volume, By Material, 2022-2032 |
6.1.1 Overview & Analysis |
6.1.2 Global FMCG Packaging Market, Revenues & Volume, By Paper, 2022-2032 |
6.1.3 Global FMCG Packaging Market, Revenues & Volume, By Plastic, 2022-2032 |
6.1.4 Global FMCG Packaging Market, Revenues & Volume, By Metal, 2022-2032 |
6.1.5 Global FMCG Packaging Market, Revenues & Volume, By Glass, 2022-2032 |
6.1.6 Global FMCG Packaging Market, Revenues & Volume, By Others, 2022-2032 |
6.2 Global FMCG Packaging Market, Revenues & Volume, By End Use Industry, 2022-2032 |
6.2.1 Overview & Analysis |
6.2.2 Global FMCG Packaging Market, Revenues & Volume, By Food and Beverages, 2022-2032 |
6.2.3 Global FMCG Packaging Market, Revenues & Volume, By Cosmetic and Personal Care, 2022-2032 |
6.2.4 Global FMCG Packaging Market, Revenues & Volume, By Others, 2022-2032 |
6.3.1 Overview & Analysis |
7 North America FMCG Packaging Market, Overview & Analysis |
7.1 North America FMCG Packaging Market Revenues & Volume, 2022-2032 |
7.2 North America FMCG Packaging Market, Revenues & Volume, By Countries, 2022-2032 |
7.2.1 United States (US) FMCG Packaging Market, Revenues & Volume, 2022-2032 |
7.2.2 Canada FMCG Packaging Market, Revenues & Volume, 2022-2032 |
7.2.3 Rest of North America FMCG Packaging Market, Revenues & Volume, 2022-2032 |
7.3 North America FMCG Packaging Market, Revenues & Volume, By Material, 2022-2032 |
7.4 North America FMCG Packaging Market, Revenues & Volume, By End Use Industry, 2022-2032 |
8 Latin America (LATAM) FMCG Packaging Market, Overview & Analysis |
8.1 Latin America (LATAM) FMCG Packaging Market Revenues & Volume, 2022-2032 |
8.2 Latin America (LATAM) FMCG Packaging Market, Revenues & Volume, By Countries, 2022-2032 |
8.2.1 Brazil FMCG Packaging Market, Revenues & Volume, 2022-2032 |
8.2.2 Mexico FMCG Packaging Market, Revenues & Volume, 2022-2032 |
8.2.3 Argentina FMCG Packaging Market, Revenues & Volume, 2022-2032 |
8.2.4 Rest of LATAM FMCG Packaging Market, Revenues & Volume, 2022-2032 |
8.3 Latin America (LATAM) FMCG Packaging Market, Revenues & Volume, By Material, 2022-2032 |
8.4 Latin America (LATAM) FMCG Packaging Market, Revenues & Volume, By End Use Industry, 2022-2032 |
9 Asia FMCG Packaging Market, Overview & Analysis |
9.1 Asia FMCG Packaging Market Revenues & Volume, 2022-2032 |
9.2 Asia FMCG Packaging Market, Revenues & Volume, By Countries, 2022-2032 |
9.2.1 India FMCG Packaging Market, Revenues & Volume, 2022-2032 |
9.2.2 China FMCG Packaging Market, Revenues & Volume, 2022-2032 |
9.2.3 Japan FMCG Packaging Market, Revenues & Volume, 2022-2032 |
9.2.4 Rest of Asia FMCG Packaging Market, Revenues & Volume, 2022-2032 |
9.3 Asia FMCG Packaging Market, Revenues & Volume, By Material, 2022-2032 |
9.4 Asia FMCG Packaging Market, Revenues & Volume, By End Use Industry, 2022-2032 |
10 Africa FMCG Packaging Market, Overview & Analysis |
10.1 Africa FMCG Packaging Market Revenues & Volume, 2022-2032 |
10.2 Africa FMCG Packaging Market, Revenues & Volume, By Countries, 2022-2032 |
10.2.1 South Africa FMCG Packaging Market, Revenues & Volume, 2022-2032 |
10.2.2 Egypt FMCG Packaging Market, Revenues & Volume, 2022-2032 |
10.2.3 Nigeria FMCG Packaging Market, Revenues & Volume, 2022-2032 |
10.2.4 Rest of Africa FMCG Packaging Market, Revenues & Volume, 2022-2032 |
10.3 Africa FMCG Packaging Market, Revenues & Volume, By Material, 2022-2032 |
10.4 Africa FMCG Packaging Market, Revenues & Volume, By End Use Industry, 2022-2032 |
11 Europe FMCG Packaging Market, Overview & Analysis |
11.1 Europe FMCG Packaging Market Revenues & Volume, 2022-2032 |
11.2 Europe FMCG Packaging Market, Revenues & Volume, By Countries, 2022-2032 |
11.2.1 United Kingdom FMCG Packaging Market, Revenues & Volume, 2022-2032 |
11.2.2 Germany FMCG Packaging Market, Revenues & Volume, 2022-2032 |
11.2.3 France FMCG Packaging Market, Revenues & Volume, 2022-2032 |
11.2.4 Rest of Europe FMCG Packaging Market, Revenues & Volume, 2022-2032 |
11.3 Europe FMCG Packaging Market, Revenues & Volume, By Material, 2022-2032 |
11.4 Europe FMCG Packaging Market, Revenues & Volume, By End Use Industry, 2022-2032 |
12 Middle East FMCG Packaging Market, Overview & Analysis |
12.1 Middle East FMCG Packaging Market Revenues & Volume, 2022-2032 |
12.2 Middle East FMCG Packaging Market, Revenues & Volume, By Countries, 2022-2032 |
12.2.1 Saudi Arabia FMCG Packaging Market, Revenues & Volume, 2022-2032 |
12.2.2 UAE FMCG Packaging Market, Revenues & Volume, 2022-2032 |
12.2.3 Turkey FMCG Packaging Market, Revenues & Volume, 2022-2032 |
12.3 Middle East FMCG Packaging Market, Revenues & Volume, By Material, 2022-2032 |
12.4 Middle East FMCG Packaging Market, Revenues & Volume, By End Use Industry, 2022-2032 |
13 Global FMCG Packaging Market Key Performance Indicators |
14 Global FMCG Packaging Market - Export/Import By Countries Assessment |
15 Global FMCG Packaging Market - Opportunity Assessment |
15.1 Global FMCG Packaging Market Opportunity Assessment, By Countries, 2022 & 2032F |
15.2 Global FMCG Packaging Market Opportunity Assessment, By Material, 2022 & 2032F |
15.3 Global FMCG Packaging Market Opportunity Assessment, By End Use Industry, 2022 & 2032F |
16 Global FMCG Packaging Market - Competitive Landscape |
16.1 Global FMCG Packaging Market Revenue Share, By Companies, 2025 |
16.2 Global FMCG Packaging Market Competitive Benchmarking, By Operating and Technical Parameters |
17 Top 10 Company Profiles |
18 Recommendations |
19 Disclaimer |
Global Go To Market Strategy - 2030
Export potential enables firms to identify high-growth global markets with greater confidence by combining advanced trade intelligence with a structured quantitative methodology. The framework analyzes emerging demand trends and country-level import patterns while integrating macroeconomic and trade datasets such as GDP and population forecasts, bilateral import–export flows, tariff structures, elasticity differentials between developed and developing economies, geographic distance, and import demand projections. Using weighted trade values from 2020–2024 as the base period to project country-to-country export potential for 2030, these inputs are operationalized through calculated drivers such as gravity model parameters, tariff impact factors, and projected GDP per-capita growth. Through an analysis of hidden potentials, demand hotspots, and market conditions that are most favorable to success, this method enables firms to focus on target countries, maximize returns, and global expansion with data, backed by accuracy.
By factoring in the projected importer demand gap that is currently unmet and could be potential opportunity, it identifies the potential for the Exporter (Country) among 190 countries, against the general trade analysis, which identifies the biggest importer or exporter.
To discover high-growth global markets and optimize your business strategy:
Click Here
Request Primary Research & Report
- Single User License$ 4,560
- Department License$ 5,055
- Site License$ 5,595
- Global License$ 6,000
Leadership Perspectives from Industry Events
Search
6Wresearch in the News
 Forbes
Citing 6Wresearch analytics to map global infrastructure and pharmaceutical industry trajectories.
 Bloomberg Law
Direct syndication of 6Wresearch's macro data points, capturing complex supply chain shifts.
 Reuters
Tracking industrial manufacturing adjustments and electronic security ecosystem scaling.
 Mint
Utilizing deep-tech sector market sizing to analyze global automation and robotics.
 The Economic Times
Anchoring features on industrial IoT growth metrics and connected smart-grid devices.
 Business Standard
Featuring strategic evaluations of Advanced Driver Assistance Systems (ADAS) and AI road safety.
 The Hindu
Spotlighting core commercial metrics ranging from unmanned aerial vehicles (UAVs) to consumer durables.
 Financial Express
Anchoring quarterly reviews on cross-border real estate tech and structural hardware manufacturing.
 Yahoo Finance
Syndicating the tracker's $30.1 billion untapped-market findings, spotlighting Japan, the US and China as India's top new-potential importers.
 India Today
Carrying the release on smartphones leading India's export potential to $94 billion by 2031, per 6WExportGTM data.
 Dailyhunt
Distributing the tracker findings to its regional readership, framing India's export diversification into Japan and Mexico.
 PR Newswire Original release
Publishing the full India Export Attractiveness Tracker 2026, detailing new trade corridors across iron ore, LCVs and pharmaceuticals.
 The Industrial
Highlighting the tracker's read on India's semiconductor ambitions and long-term chip-assembly export potential.
 PTI News
Reporting on the $66.81 billion pharmaceuticals export opportunity flagged in the tracker, amid looming US generic-drug tariffs.
 Tribune India
Covering the tracker's tariff-versus-regulation analysis across India's mature export markets in the US, China and UAE.
 ANI News
Amplifying the report's findings on polished diamonds, refined petroleum and medicines as India's core export engines.
 International Business Magazine
Covering the report's insight into how AEB, blind spot detection, and driver monitoring are reshaping India's ADAS market.
 Focus Gaming News
Highlighting the research forecast for Egypt's gambling market, projecting steady growth through 2032.
Thought Leadership and Analyst Meet
Our Clients
Latest Reports
- Austria X-ray Imaging Devices Market (2026-2032)
- Armenia X-ray Imaging Devices Market (2026-2032)
- Antigua and Barbuda X-ray Imaging Devices Market (2026-2032)
- Angola X-ray Imaging Devices Market (2026-2032)
- Andorra X-ray Imaging Devices Market (2026-2032)
- Albania X-ray Imaging Devices Market (2026-2032)
- Afghanistan X-ray Imaging Devices Market (2026-2032)
- United States (US) X-ray Imaging Devices Market (2026-2032)
- United Kingdom (UK) X-ray Imaging Devices Market (2026-2032)
- United Arab Emirates (UAE) X-ray Imaging Devices Market (2026-2032)
Industry Events and Analyst Meet

EV India Expo 2026
HIMTEX 2026
India Refining Summit 2026
India EV Show 2026
EV tech India Expo 2026
Whitepaper
- Middle East & Africa Commercial Security Market Click here to view more.
- Middle East & Africa Fire Safety Systems & Equipment Market Click here to view more.
- GCC Drone Market Click here to view more.
- Middle East Lighting Fixture Market Click here to view more.
- GCC Physical & Perimeter Security Market Click here to view more.


