Japan Insulation Materials Market Size & Growth Rate
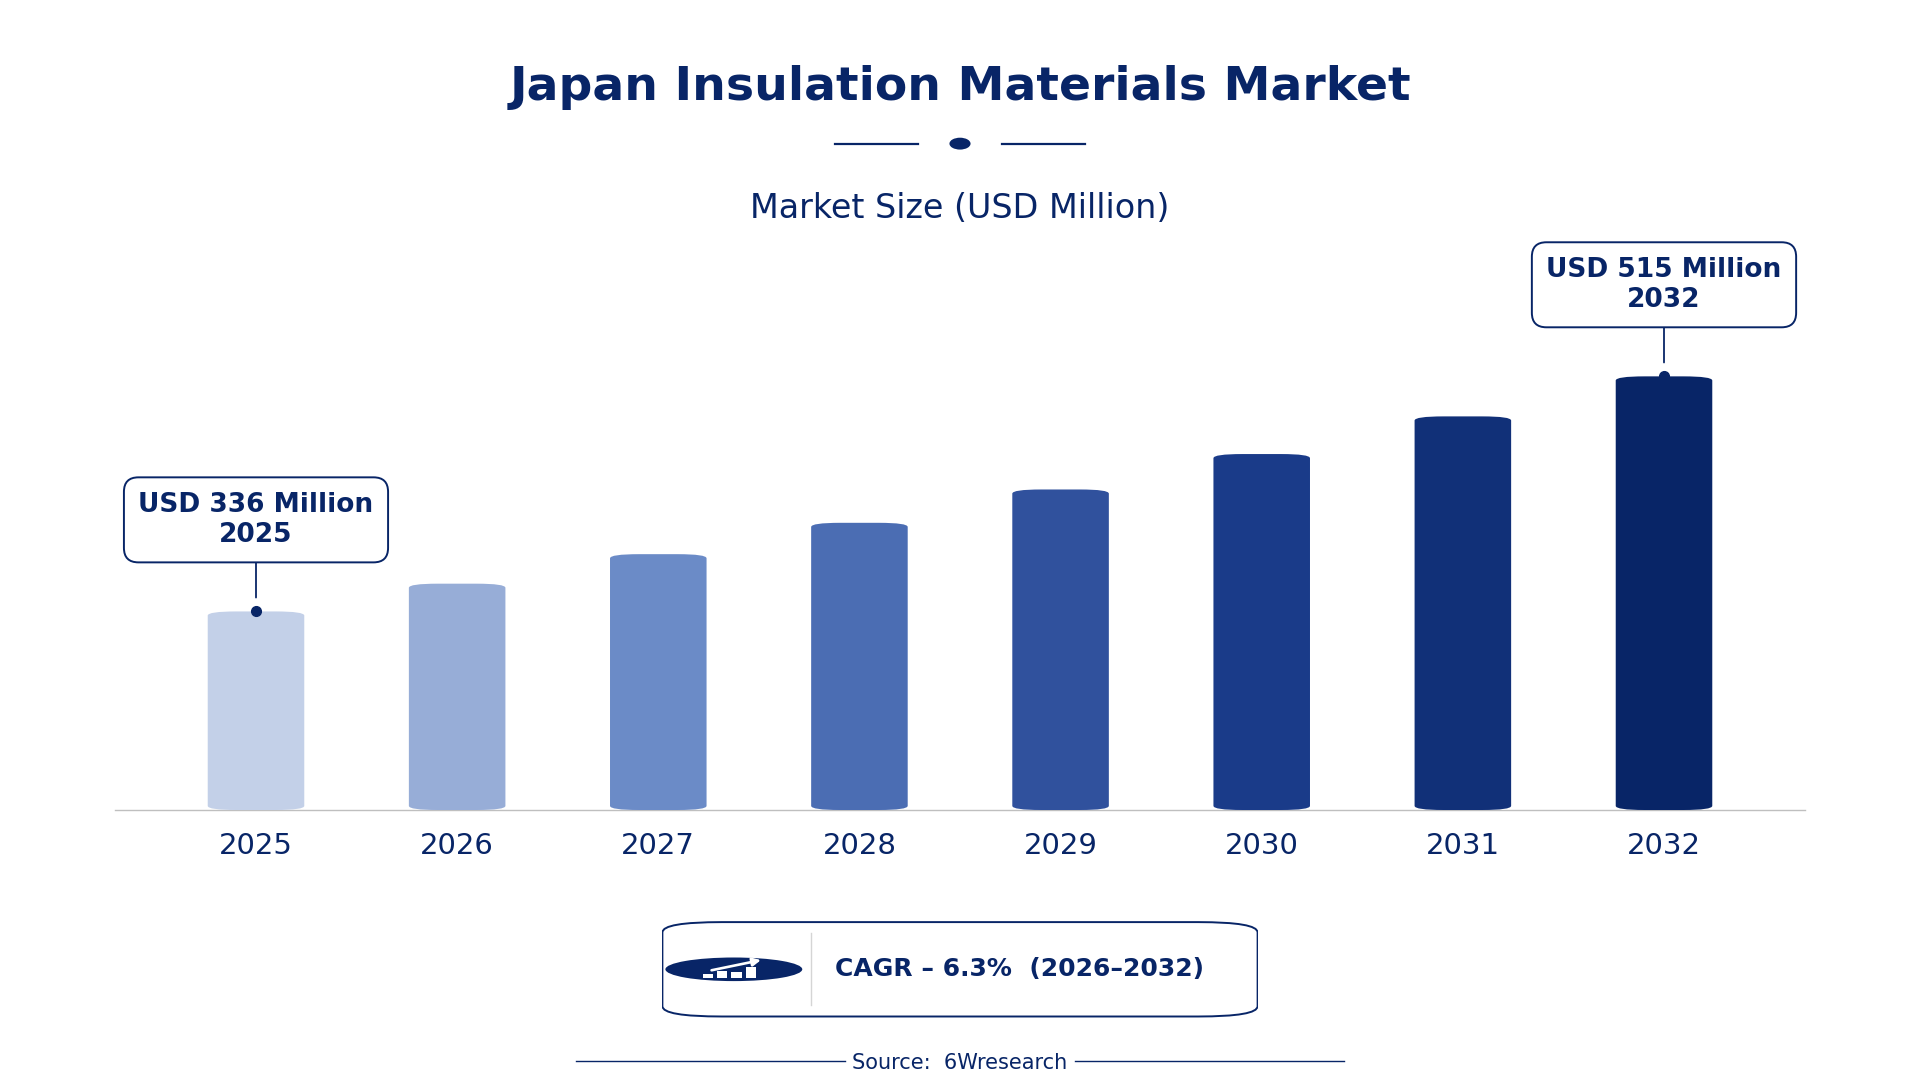
According to 6Wresearch internal database and industry insights, the Japan Insulation Materials Market was valued at USD 336 Million in 2025 and is projected to reach USD 515 Million by 2032, growing at a CAGR of approximately 6.3% during 2026–2032.
Japan Insulation Materials Market Highlights
| Report Metric | Details |
| Report Name | Japan Insulation Materials Market (2026-2032) |
| Market Size 2025 | USD 336 Million |
| Market Size 2032 | USD 515 Million |
| Absolute Growth 2025–2032 | USD 179 Million |
| CAGR 2026–2032 | 6.3% |
| Peak Annual Growth | 7.7% in 2028 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Type, 2025 | Polyurethane Spray Foam (41% share) |
| Leading Category, 2025 | Foam Board or Rigid Foam (41% share) |
| Leading Density, 2025 | > 100 to 200 Kg/m3 (50% share) |
| Leading End-use, 2025 | Building & Construction (41% share) |
| Fastest-Growing Type | Aerogel Insulation (8.7% CAGR) |
| Fastest-Growing Category | Structural Insulated Panels (SIPS) (9.2% CAGR) |
| Fastest-Growing Density | Up to 100 Kg/m3 (8.8% CAGR) |
| Fastest-Growing End-use | Electrical & Electronics (8.6% CAGR) |
| Growing Sector | Electrical & Electronics |
| Key End Users | Building & Construction, Electrical & Electronics, Automotive, Food & Beverages |
Japan Insulation Materials Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
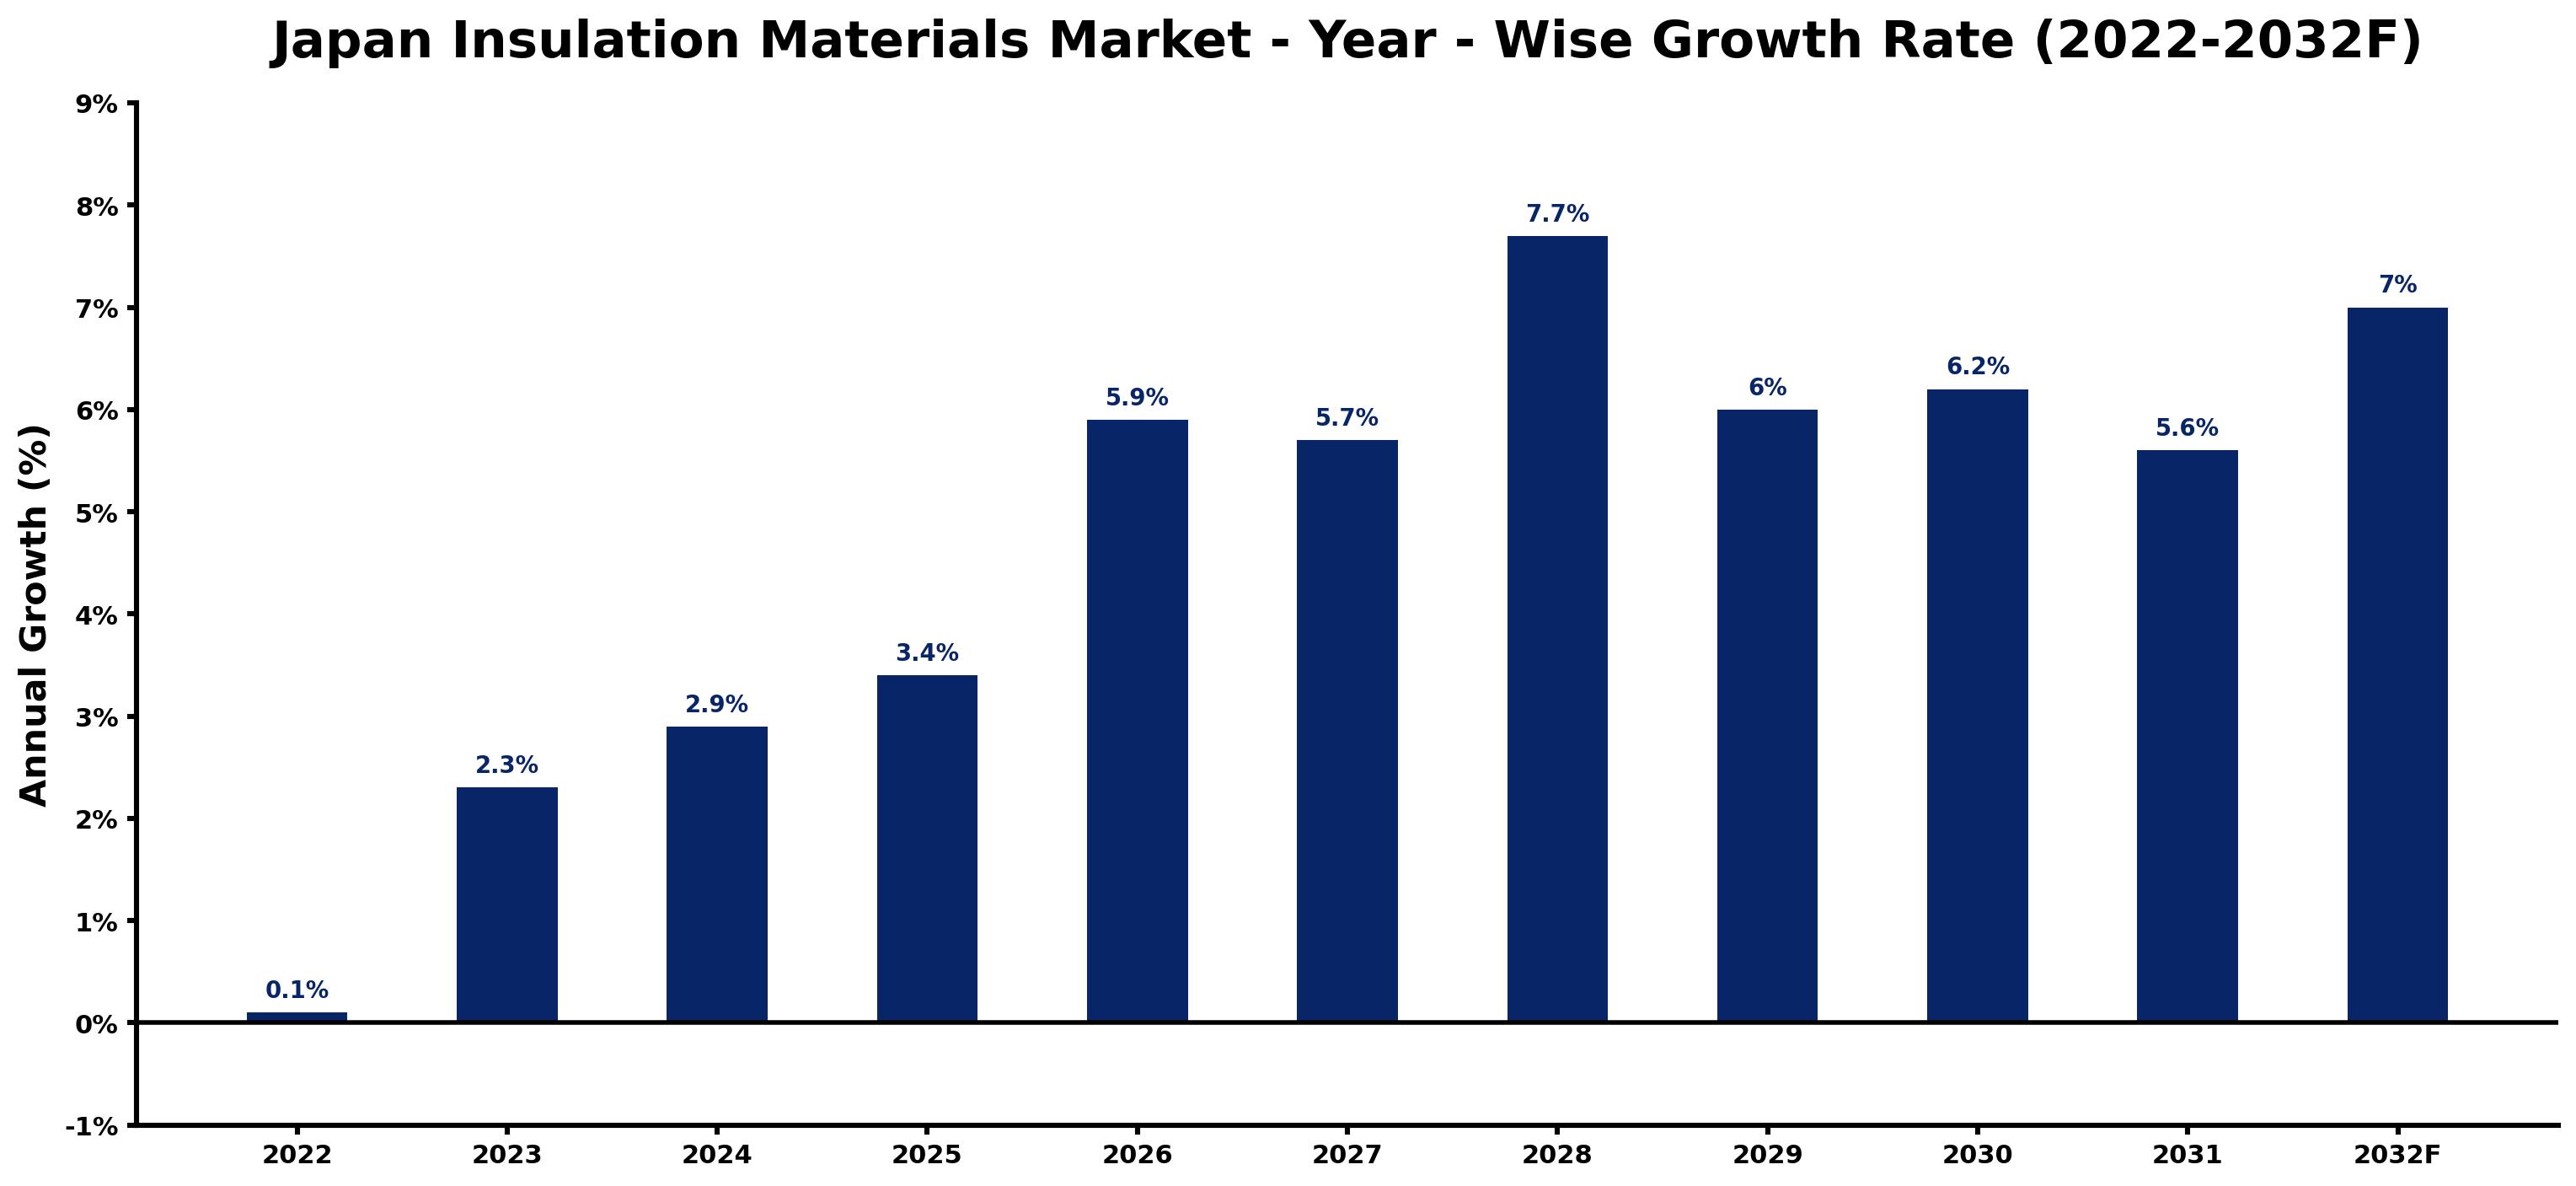
Year by year, the estimates below pair each growth rate with the development that shaped it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 0.1 | The market showed minimal growth amidst ongoing recovery from economic disruptions. |
| 2023 | 2.3 | Demand increased as construction activities resumed following previous delays. |
| 2024 | 2.9 | Growth continued with rising investments in energy-efficient building projects. |
| 2025 | 3.4 | The market peaked historically, driven by heightened construction sector activity. |
| 2026 | 5.9 | Growth accelerated as energy efficiency regulations prompted more insulation use. |
| 2027 | 5.7 | Growth slowed slightly due to market saturation in certain insulation types. |
| 2028 | 7.7 | Demand surged as new energy efficiency standards were implemented. |
| 2029 | 6.0 | Growth decelerated as the market adjusted to previous rapid expansion. |
| 2030 | 6.2 | Demand is expected to rise with ongoing decarbonisation efforts. |
| 2031 | 5.6 | Growth slowed as the market stabilised following strong previous years. |
| 2032 | 7.0 | Demand is projected to increase with new building regulations. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
Japan Insulation Materials Market Synopsis
Insulation materials are crucial for minimising heat transfer, composed of substances like polyurethane and fiberglass. The Japan Insulation Materials Market is valued at approximately 400 billion yen, largely propelled by the construction sector employing around 5 million workers. The government's focus on energy-efficient buildings, underscored by the 2023 programme promoting energy efficiency, is poised to drive demand. With Japan aiming for a 46% reduction in greenhouse gas emissions by 2030, insulation materials will be instrumental in reaching these ambitious objectives.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Growing focus on energy efficiency in construction | Driver | High | Foam Board or Rigid Foam |
| Increased investment in residential and commercial buildings | Driver | High | Rigid Foam Insulation |
| Rising demand for energy-efficient building materials | Opportunity | High | Structural Insulated Panels (SIPS) |
| Emerging trends in eco-friendly construction | Opportunity | Medium | Aerogel Insulation |
| High costs associated with advanced insulation materials | Restraint | High | Aerogel Insulation |
| Limited awareness of insulation benefits among consumers | Restraint | Medium | Blanket Batt Insulation and Roll Insulation |
| Compliance with new energy efficiency standards | Challenge | High | Rigid Foam Insulation |
| Capacity constraints in production facilities | Challenge | Medium | Polyurethane Spray Foam |
Evaluation of Drivers in Japan Insulation Materials Market (2026–2032)
These are the developments adding the most demand over the forecast period.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Government initiatives promoting energy efficiency | Foam Board or Rigid Foam | The 2023 programme encourages the use of insulation materials, increasing demand in construction. |
| Rising construction activities in urban areas | Rigid Foam Insulation | The Tokyo metropolitan area accounts for 30% of insulation demand, driving higher purchases. |
| Investment in eco-friendly building designs | Structural Insulated Panels (SIPS) | Popularity in energy-efficient designs is boosting demand for advanced insulation solutions. |
| Increased consumer awareness of energy savings | Aerogel Insulation | High-performance insulation is gaining traction in high-end building projects, leading to more purchases. |
| Regulatory pressure for emissions reduction | Blanket Batt Insulation and Roll Insulation | The goal of a 46% cut in emissions by 2030 is driving insulation material adoption. |
Most of the extra volume comes from the construction sector, employing approximately 5 million workers, which drives insulation usage. The average residential building uses 150 mm of insulation in walls, further supporting demand. Demand is rising as builders adapt to new energy efficiency standards.
Evaluation of Restraints in Japan Insulation Materials Market
The table below lists the restraints and the evidence behind each.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| High costs of advanced insulation materials | Aerogel Insulation | The average cost of polyurethane spray foam insulation is around 2,000 yen per square meter, limiting affordability. |
| Limited consumer awareness of insulation benefits | Blanket Batt Insulation and Roll Insulation | Many consumers remain unaware of energy savings, hindering market growth. |
| Compliance with stringent regulations | Rigid Foam Insulation | New energy efficiency standards require significant adjustments in production and design. |
| Supply chain disruptions affecting availability | Foam Board or Rigid Foam | Global supply chain issues have led to delays in material procurement. |
| Market saturation in certain insulation types | Polyurethane Spray Foam | Overproduction in previous years has created excess inventory, slowing new purchases. |
Japan Insulation Materials Market Challenges
Japan's insulation materials market, valued at approximately 400 billion yen, contends with fierce competition that compresses prices and narrows profit margins for producers. Supply chain disruptions, intensified by global events, hinder the delivery of essential inputs like polyurethane, affecting project timelines for contractors. The average cost of polyurethane spray foam insulation, around 2,000 yen per square meter, inflates overall construction expenses for builders. Compliance with JIS A 9501 standards incurs additional costs for manufacturers, limiting their ability to respond swiftly to market demands.
Trends in the Japan Insulation Materials Market
Buyers and suppliers in the Japan Insulation Materials Market are adjusting to the following trends.
- Shift towards Energy-Efficient Building Practices: The 2023 programme promoting energy-efficient buildings is transforming construction practices. With a target of a 30% reduction in energy consumption by 2030, demand for insulation materials will increase as builders adapt to new standards.
- Emergence of Structural Insulated Panels: Structural Insulated Panels (SIPS) are gaining traction in eco-friendly construction, with a projected CAGR of 9.2%. This trend reflects a growing preference for sustainable building solutions in Japan.
- Increased Use of Aerogel Insulation: Aerogel insulation is being increasingly adopted in high-performance building projects, driven by its superior thermal properties. This trend is expected to persist as more projects pursue energy efficiency and advanced materials.
- Growing Demand for Lightweight Insulation: The demand for insulation materials with densities up to 100 Kg/m3 is on the rise, indicating a shift towards lightweight applications in construction. This trend is supported by advancements in material technology.
Investment Opportunities in the Japan Insulation Materials Market
The following opportunities in the Japan Insulation Materials Market pair current demand with a clear way in.
- Building & Construction Sector Expansion: The construction sector is expanding rapidly, creating a strong demand for insulation materials. With a projected increase in construction projects, suppliers can benefit from this growth.
- Investment in Energy-Efficient Technologies: With Japan targeting a 46% reduction in greenhouse gas emissions by 2030, there is an opportunity for suppliers of energy-efficient insulation materials to enter the market and meet rising demands.
- Rising Demand for Eco-Friendly Solutions: The increasing focus on sustainability presents an opportunity for insulation producers to supply eco-friendly materials. The Japan Insulation Association promotes energy savings, further driving demand for sustainable products.
- Technological Advancements in Insulation Materials: Innovations in insulation technology, such as the development of advanced materials, create opportunities for suppliers to meet evolving market needs and improve product offerings.
Government Initiatives in the Japan Insulation Materials Market
The Building Energy Efficiency Act, amended in 2022, requires that all new buildings meet energy standards by April 2025. This legislation updates previous regulations by enforcing stricter energy efficiency measures, compelling producers to improve insulation materials and reduce energy consumption.
The PRTR Law mandates businesses to report chemical substances, enabling buyers in the construction sector to ensure compliance with safety standards. This transparency aids buyers in selecting insulation materials that meet regulatory requirements and promote safety in construction.
Future Insight of the Japan Insulation Materials Market
A shift towards decarbonisation will transform the insulation materials market by 2032, urging suppliers to embrace energy-efficient technologies. Japan's GX Basic Policy targets JPY 150 trillion in decarbonisation investment, driving innovation in thermal insulation solutions. As the construction sector adopts eco-friendly practices, structural insulated panels will become increasingly sought after by buyers. The rising use of aerogel insulation in high-performance projects will reflect a commitment to superior energy efficiency in building designs.
Market Segmentation Analysis
Japan Insulation Materials Market report covers a detailed analysis of the following market segments:
By Type – Polyurethane Spray Foam Leads, Aerogel Insulation Expected to Grow Fastest
According to Shubham Deep, Research Manager at 6Wresearch, the largest type category in 2025 was Polyurethane Spray Foam, at 41% of revenue. Polyurethane spray foam commands the largest share as it is extensively used for sealing and insulating gaps in construction, crucial for energy efficiency. Its widespread application in residential and commercial buildings solidifies its dominant position in the insulation materials market. Aerogel Insulation is set to record the highest CAGR in this split, 8.7% over 2026–2032. Aerogel insulation is witnessing rapid growth due to its adoption in high-performance building projects that emphasise energy efficiency. The material's unique properties, despite its higher cost, are attracting increased investment, ensuring its market share continues to rise. Suppliers must consider strategies to improve the accessibility and cost-effectiveness of aerogel insulation to capitalise on its growing market presence.
By Category – Foam Board or Rigid Foam Leads, Structural Insulated Panels (SIPS) Expected to Grow Fastest
With 41% of category revenue in 2025, Foam Board or Rigid Foam was the largest category. Foam board or rigid foam holds the largest share as it is widely applied in various construction projects for insulation purposes. Its effectiveness in enhancing energy efficiency in buildings underpins its dominant market position. The quickest growth will come from Structural Insulated Panels (SIPS), forecast to expand at a CAGR of 9.2% between 2026 and 2032. Structural insulated panels are experiencing the fastest growth as they are increasingly utilised in modern construction for their energy efficiency benefits. This trend is supported by the rising demand for sustainable building practices, which is likely to continue driving their adoption. Suppliers should focus on promoting the benefits of structural insulated panels to align with the growing preference for energy-efficient construction solutions.
By Density – > 100 to 200 Kg/m3 Leads, Up to 100 Kg/m3 Expected to Grow Fastest
> 100 to 200 Kg/m3 held 50% of the Japan Insulation Materials Market by density in 2025. > 100 to 200 Kg/m3 holds the largest share as it is commonly used in standard insulation applications, effectively meeting the needs of various construction projects. The established demand for this density range ensures its continued prominence in the market. Up to 100 Kg/m3 is projected to grow fastest, at a CAGR of 8.8% during 2026–2032. Up to 100 Kg/m3 is the fastest-growing segment, primarily due to its suitability for lightweight applications, which are becoming increasingly popular in modern construction. The shift towards lighter materials is expected to further accelerate this segment's growth. Suppliers should explore opportunities to develop and market lightweight insulation solutions to meet the rising demand in construction.
By End-use – Building & Construction Leads, Electrical & Electronics Expected to Grow Fastest
Building & Construction accounted for 41% of the market by end-use in 2025. Building and construction is the largest end-use sector for insulation materials, reflecting the high demand driven by residential and commercial projects. The sector's significant size ensures a continuous need for effective insulation solutions. Over 2026–2032, Electrical & Electronics is expected to post the fastest growth, at a CAGR of 8.6%. Electrical and electronics is the fastest-growing end-use segment, as insulation materials are increasingly used in specific applications like appliances. This trend highlights the expanding role of insulation in enhancing energy efficiency across various industries. Suppliers should consider diversifying their product offerings to cater to the growing demand from the electrical and electronics sector.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- Japan Insulation Materials Market Outlook
- Market Size of Japan Insulation Materials Market, 2025
- Forecast of Japan Insulation Materials Market, 2032
- Historical Data and Forecast of Japan Insulation Materials Revenues & Volume for the Period 2022-2032
- Japan Insulation Materials Market Trend Evolution
- Japan Insulation Materials Market Drivers and Challenges
- Japan Insulation Materials Price Trends
- Japan Insulation Materials Porter's Five Forces
- Japan Insulation Materials Industry Life Cycle
- Historical Data and Forecast of Japan Insulation Materials Market Revenues & Volume By Type for the Period 2022-2032
- Historical Data and Forecast of Japan Insulation Materials Market Revenues & Volume By Polyurethane Spray Foam for the Period 2022-2032
- Historical Data and Forecast of Japan Insulation Materials Market Revenues & Volume By Rigid Foam Insulation for the Period 2022-2032
- Historical Data and Forecast of Japan Insulation Materials Market Revenues & Volume By Aerogel Insulation for the Period 2022-2032
- Historical Data and Forecast of Japan Insulation Materials Market Revenues & Volume By Others for the Period 2022-2032
- Historical Data and Forecast of Japan Insulation Materials Market Revenues & Volume By Category for the Period 2022-2032
- Historical Data and Forecast of Japan Insulation Materials Market Revenues & Volume By Blanket Batt Insulation and Roll Insulation for the Period 2022-2032
- Historical Data and Forecast of Japan Insulation Materials Market Revenues & Volume By Foam Board or Rigid Foam for the Period 2022-2032
- Historical Data and Forecast of Japan Insulation Materials Market Revenues & Volume By Insulated Concrete Forms for the Period 2022-2032
- Historical Data and Forecast of Japan Insulation Materials Market Revenues & Volume By Loose-Fill and Blown-In Insulation for the Period 2022-2032
- Historical Data and Forecast of Japan Insulation Materials Market Revenues & Volume By Loose-Fill and Blown-In Insulation for the Period 2022-2032
- Historical Data and Forecast of Japan Insulation Materials Market Revenues & Volume By Spray Foam and Foamed-In-Place Insulation for the Period 2022-2032
- Historical Data and Forecast of Japan Insulation Materials Market Revenues & Volume By Structural Insulated Panels (SIPS) for the Period 2022-2032
- Historical Data and Forecast of Japan Insulation Materials Market Revenues & Volume By Others for the Period 2022-2032
- Historical Data and Forecast of Japan Insulation Materials Market Revenues & Volume By Density for the Period 2022-2032
- Historical Data and Forecast of Japan Insulation Materials Market Revenues & Volume By Up to 100 Kg/m3 for the Period 2022-2032
- Historical Data and Forecast of Japan Insulation Materials Market Revenues & Volume By > 100 to 200 Kg/m3 for the Period 2022-2032
- Historical Data and Forecast of Japan Insulation Materials Market Revenues & Volume By > 200 to 500 Kg/m3 for the Period 2022-2032
- Historical Data and Forecast of Japan Insulation Materials Market Revenues & Volume By > 500 to 700 Kg/m3 for the Period 2022-2032
- Historical Data and Forecast of Japan Insulation Materials Market Revenues & Volume By > 700 Kg/m3 for the Period 2022-2032
- Historical Data and Forecast of Japan Insulation Materials Market Revenues & Volume By End-use for the Period 2022-2032
- Historical Data and Forecast of Japan Insulation Materials Market Revenues & Volume By Building & Construction for the Period 2022-2032
- Historical Data and Forecast of Japan Insulation Materials Market Revenues & Volume By Electrical & Electronics for the Period 2022-2032
- Historical Data and Forecast of Japan Insulation Materials Market Revenues & Volume By Packaging for the Period 2022-2032
- Historical Data and Forecast of Japan Insulation Materials Market Revenues & Volume By Food & Beverages for the Period 2022-2032
- Historical Data and Forecast of Japan Insulation Materials Market Revenues & Volume By Automotive for the Period 2022-2032
- Historical Data and Forecast of Japan Insulation Materials Market Revenues & Volume By Oil & Gas for the Period 2022-2032
- Historical Data and Forecast of Japan Insulation Materials Market Revenues & Volume By Consumer Goods for the Period 2022-2032
- Historical Data and Forecast of Japan Insulation Materials Market Revenues & Volume By Others for the Period 2022-2032
- Japan Insulation Materials Import Export Trade Statistics
- Market Opportunity Assessment By Type
- Market Opportunity Assessment By Category
- Market Opportunity Assessment By Density
- Market Opportunity Assessment By End-use
- Japan Insulation Materials Top Companies Market Share
- Japan Insulation Materials Competitive Benchmarking By Technical and Operational Parameters
- Japan Insulation Materials Company Profiles
- Japan Insulation Materials Key Strategic Recommendations
Market Covered
The following segment groups are covered in the report.
By Type
- Polyurethane Spray Foam
- Rigid Foam Insulation
- Aerogel Insulation
- Others
By Category
- Blanket Batt Insulation and Roll Insulation
- Foam Board or Rigid Foam
- Insulated Concrete Forms
- Loose-Fill and Blown-In Insulation
- Spray Foam and Foamed-In-Place Insulation
- Structural Insulated Panels (SIPS)
- Others
By Density
- Up to 100 Kg/m3
- > 100 to 200 Kg/m3
- > 200 to 500 Kg/m3
- > 500 to 700 Kg/m3
- > 700 Kg/m3
By End-use
- Building & Construction
- Electrical & Electronics
- Packaging
- Food & Beverages
- Automotive
- Oil & Gas
- Consumer Goods
- Others































