Japan Packaging Laminates Market Size & Growth Rate
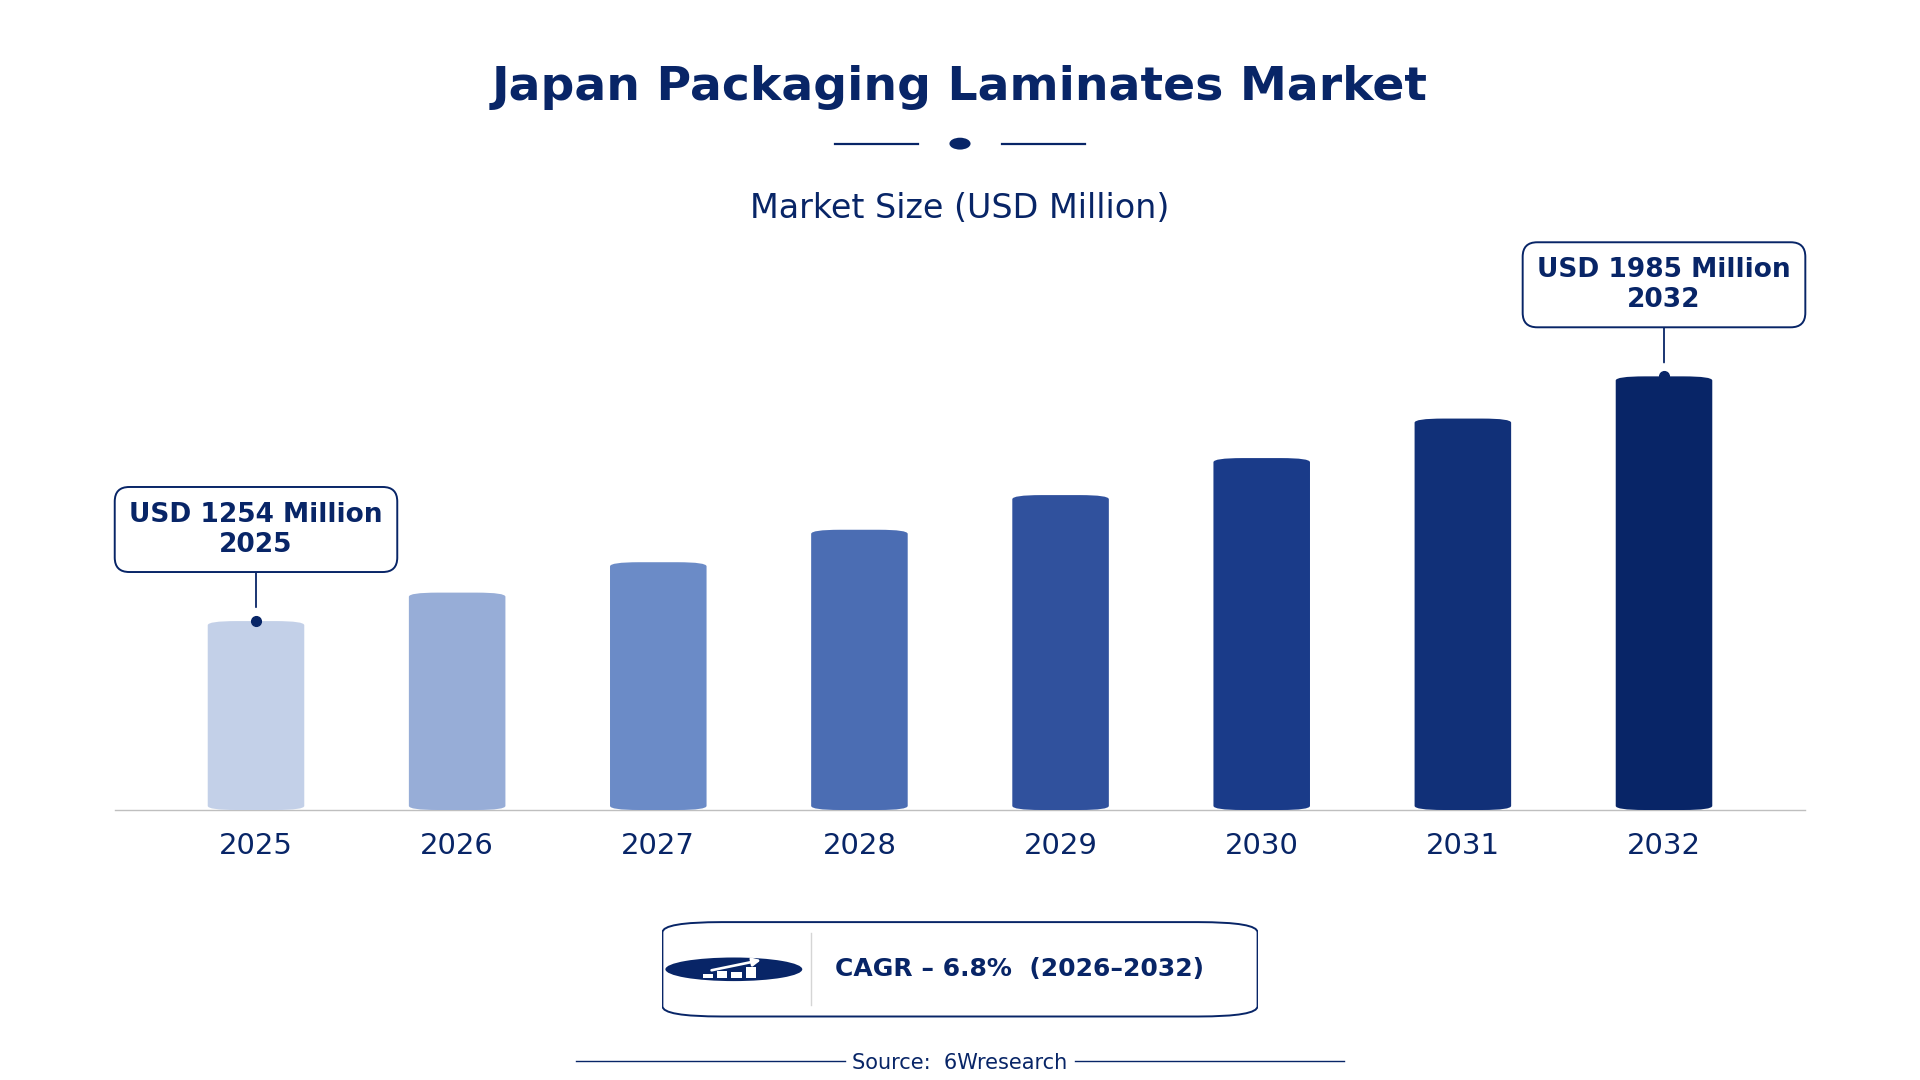
According to 6Wresearch internal database and industry insights, the Japan Packaging Laminates Market was valued at USD 1,254 Million in 2025 and is projected to reach USD 1,985 Million by 2032, growing at a CAGR of approximately 6.8% during 2026–2032.
Japan Packaging Laminates Market Highlights
| Report Metric | Details |
| Report Name | Japan Packaging Laminates Market (2026-2032) |
| Market Size 2025 | USD 1,254 Million |
| Market Size 2032 | USD 1,985 Million |
| Absolute Growth 2025–2032 | USD 731 Million |
| CAGR 2026–2032 | 6.8% |
| Peak Annual Growth | 7.5% in 2032 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Material, 2025 | Aluminium Foil (38% share) |
| Leading Thickness, 2025 | Up to 30 Micron (42% share) |
| Leading Application, 2025 | Aseptic Packaging (57% share) |
| Leading End-use, 2025 | Food (39% share) |
| Fastest-Growing Material | Paper and Paperboard (10.1% CAGR) |
| Fastest-Growing Thickness | 30-45 Micron (8.9% CAGR) |
| Fastest-Growing Application | Non-Aseptic Packaging (9.4% CAGR) |
| Fastest-Growing End-use | Pharmaceuticals (9.1% CAGR) |
| Growing Sector | Food Packaging |
| Key End Users | Food manufacturers, pharmaceutical companies, personal care product producers |
Japan Packaging Laminates Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
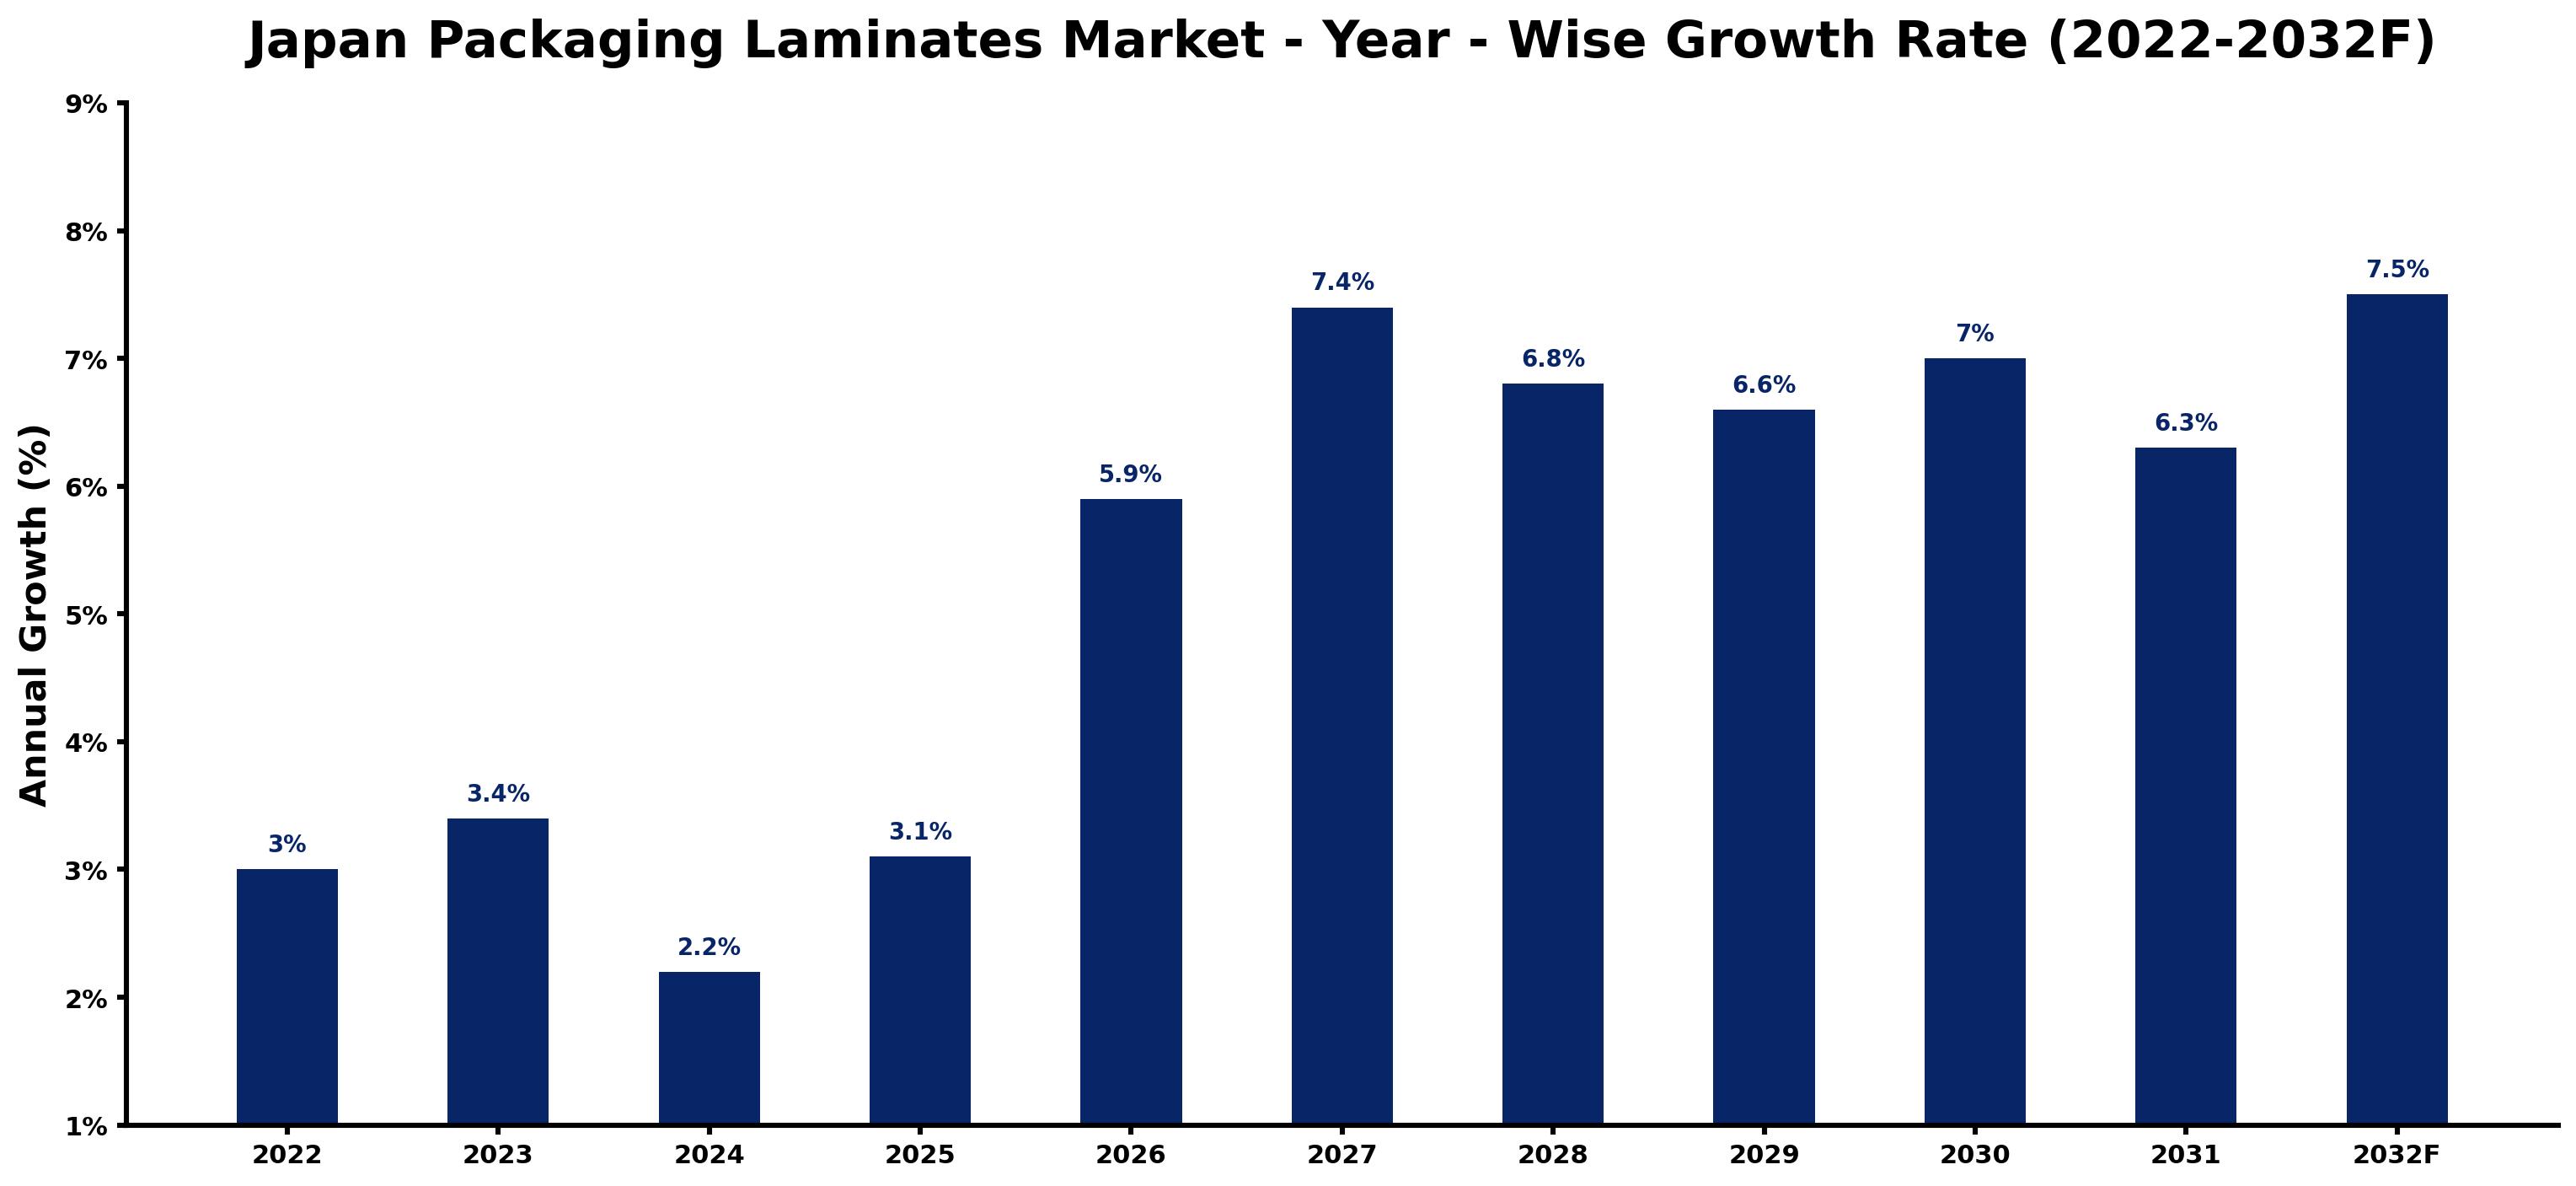
Each row of the following table gives one year's estimated growth and the event or demand shift that explains it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 3.0 | The market experienced steady growth driven by strong domestic demand for packaging solutions. |
| 2023 | 3.4 | Growth accelerated due to increased investments in food packaging technologies and innovations. |
| 2024 | 2.2 | Growth slowed as manufacturers adjusted to evolving consumer preferences and market conditions. |
| 2025 | 3.1 | Demand rose again as innovations in packaging materials gained traction across sectors. |
| 2026 | 5.9 | The market is expected to grow faster with rising health consciousness among consumers. |
| 2027 | 7.4 | Growth is projected to remain strong as sustainability becomes a priority for buyers. |
| 2028 | 6.8 | Demand growth is expected to slow as market saturation approaches in certain segments. |
| 2029 | 6.6 | A slight slowdown is anticipated as competition intensifies among producers in the market. |
| 2030 | 7.0 | Growth is expected to pick up again with new product launches and technological advancements. |
| 2031 | 6.3 | The market is projected to slow as economic conditions stabilise and competition increases. |
| 2032 | 7.5 | Demand is expected to peak as new regulations drive packaging innovation and investment. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
Japan Packaging Laminates Market Synopsis
Packaging laminates consist of composite materials made from multiple layers of different substrates, primarily utilised in food, pharmaceutical, and personal care applications. The Japan Packaging Laminates Market is growing, propelled by a packaging industry valued at over 1 trillion JPY, with food packaging representing around 40% of the market. Increasing health awareness and sustainability efforts are driving demand for aseptic and eco-friendly packaging solutions, leading to investments and advancements in the sector. This growth is further supported by a heightened focus on reducing plastic waste and improving packaging functionality to satisfy consumer expectations.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increasing health consciousness among consumers | Driver | High | Aseptic Packaging |
| Rising demand for eco-friendly packaging solutions | Driver | High | Paper and Paperboard |
| Growing investment in biodegradable packaging materials | Opportunity | High | Others |
| Expansion of food and pharmaceutical sectors | Opportunity | Medium | Food |
| Regulatory pressures on plastic waste reduction | Restraint | High | Metallized PET |
| Competition from alternative packaging materials | Restraint | Medium | Aluminium Foil |
| Supply chain disruptions affecting production capacity | Challenge | High | Non-Aseptic Packaging |
| Fluctuating raw material prices impacting profitability | Challenge | Medium | Cosmetics & Personal Care |
Evaluation of Drivers in Japan Packaging Laminates Market (2026–2032)
The factors lifting demand, and the evidence behind each, are summarised below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Rising health consciousness among consumers drives demand for aseptic packaging solutions, increasing purchases from food manufacturers. | Aseptic Packaging | The demand for aseptic packaging is increasing due to rising health consciousness, with the food packaging segment accounting for approximately 40% of the market. |
| Growing investment in eco-friendly packaging solutions boosts demand for paper and paperboard laminates, attracting packaging producers. | Paper and Paperboard | The Japan Packaging Institute promotes sustainable practices, leading to a 20% increase in demand for eco-friendly packaging solutions. |
| Technological advancements in packaging machinery enhance production efficiency, leading to higher output and sales. | Metallized PET | The installed base of packaging machinery in Japan exceeds 100,000 units, supporting increased production capacity. |
| Expansion of the food sector drives demand for lightweight packaging solutions, increasing purchases of laminates under 30 microns. | Up to 30 Micron | Food packaging accounts for around 40% of the market, driving demand for lightweight packaging options. |
| Rising exports of packaged food products contribute to increased demand for high-quality packaging laminates. | Food | Japan's packaging industry is valued at over 1 trillion JPY, with food exports playing a significant role. |
Purchasing is picking up as the food packaging segment accounts for approximately 40% of the market, driving demand for laminates. The installed base of packaging machinery in Japan exceeds 100,000 units, improving production capabilities and efficiency. Health consciousness among consumers is leading to increased demand for lightweight laminates, particularly those under 30 microns. The expansion of the food sector is fuelling demand for innovative packaging solutions, while the Japan Packaging Institute's promotion of sustainable practices is encouraging the adoption of eco-friendly materials. This combination of factors is resulting in higher purchases from food manufacturers and packaging producers alike.
Evaluation of Restraints in Japan Packaging Laminates Market
The main factors holding the market back are set out below.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Regulatory pressures on plastic waste reduction challenge producers to adapt their materials and processes. | Metallized PET | The government has set targets for reducing plastic waste by 2030, requiring compliance from packaging manufacturers. |
| Competition from alternative packaging materials limits market share for traditional laminates. | Aluminium Foil | The rise of biodegradable and compostable materials is impacting the demand for aluminium foil in packaging. |
| Supply chain disruptions hinder production capacity, affecting timely delivery of packaging solutions. | Non-Aseptic Packaging | Recent global events have caused delays in raw material supply, impacting production schedules. |
| Fluctuating raw material prices create uncertainty for manufacturers in pricing strategies. | Cosmetics & Personal Care | The volatility in resin prices affects the cost structure of packaging for personal care products. |
| Consumer preferences shifting towards minimalistic packaging challenge traditional designs. | Food | The trend for minimalistic packaging is causing a decline in demand for complex laminates. |
Japan Packaging Laminates Market Challenges
Producers of packaging laminates face challenges with outdated machinery, which can result in production inefficiencies that raise costs by 15% for manufacturers. Compliance with regulatory requirements from the Ministry of Health, Labour and Welfare complicates matters, causing delays of up to six months for suppliers launching new products. Rising raw material costs, particularly for plastics and aluminium, have surged by 20% in the past year, squeezing profit margins for buyers in the market. A lack of consumer awareness regarding sustainable packaging practices hinders producers' efforts to achieve recycling targets, risking penalties for non-compliance.
Trends in the Japan Packaging Laminates Market
Below are the shifts with the largest effect on the Japan Packaging Laminates Market.
- Shift towards Sustainable Packaging Solutions: Tokyo is experiencing a shift towards sustainable packaging, with initiatives from the Japan Packaging Institute advocating for eco-friendly options. In 2023, the government allocated funds for research in biodegradable materials, reflecting a growing trend towards sustainable practices.
- Transition from Traditional to Aseptic Packaging: The annual Packaging Technology Conference in Tokyo underscored the rising preference for aseptic packaging, with demand increasing due to health consciousness. This segment is expected to grow, mirroring evolving consumer habits and preferences.
- Food Packaging Prioritised over Other Segments: Food manufacturers are focusing on packaging solutions that extend shelf life, with aseptic packaging projected to capture a 57% share by 2025. This trend is reshaping the packaging focus in Japan, aligning with consumer expectations.
- Emergence of Biodegradable Materials: In 2023, the government initiated a recycling programme for packaging waste, promoting biodegradable materials. This initiative is poised to spur innovation in packaging solutions across various sectors, addressing environmental concerns.
Investment Opportunities in the Japan Packaging Laminates Market
The opportunities below stand out in the Japan Packaging Laminates Market for new entrants and existing suppliers.
- Investment in Biodegradable Packaging Solutions: With the government's 2023 initiative promoting biodegradable materials, there is an opportunity to invest in this sector. Collaborating with local manufacturers can facilitate the development of eco-friendly packaging solutions that meet market demands.
- Supply of Lightweight Laminates for Food Packaging: The demand for lightweight packaging solutions is on the rise, with the average thickness of food packaging laminates around 30-45 microns. Partnering with food manufacturers can help capture this expanding market.
- Expansion of Aseptic Packaging Capabilities: The growing health consciousness among consumers presents an opportunity to supply advanced aseptic packaging solutions. Engaging with food producers in Tokyo can support market entry and growth.
- Development of Eco-Friendly Packaging Solutions: The Japan Flexible Packaging Association endorses initiatives for sustainable packaging. Investing in eco-friendly materials can tap into the increasing demand for sustainable solutions in the packaging sector.
Government Initiatives in the Japan Packaging Laminates Market
The Food Sanitation Act amendment (2018) established a positive list system for synthetic resins used in food packaging, ensuring safety and compliance. This law, fully implemented in June 2021, has strengthened the regulatory framework for food packaging materials, benefiting both consumers and manufacturers by ensuring safer products in the market.
Compliance with the Food Sanitation Act is overseen by the Ministry of Health, Labour and Welfare, which promotes safe packaging practices. In 2023, the government allocated funds for research in biodegradable packaging materials, supporting innovation and sustainability in the packaging sector, which benefits manufacturers and consumers alike.
Future Insight of the Japan Packaging Laminates Market
Buyers of packaging laminates will increasingly seek sustainable solutions by 2032, as government targets for reducing plastic waste gain traction. The introduction of biodegradable materials will transform supplier offerings, aligning with recent government funding for research in this area. Standards like JIS Z 1700 will adapt to incorporate new technologies, ensuring compliance with evolving environmental regulations. The installed base of packaging machinery in Japan exceeds 100,000 units, which will facilitate advancements in production efficiency and sustainability.
Market Segmentation Analysis
Japan Packaging Laminates Market report covers a detailed analysis of the following market segments:
By Material – Aluminium Foil Leads, Paper and Paperboard Expected to Grow Fastest
According to Sachin Kumar Rai, Senior Research Analyst at 6Wresearch, Aluminium Foil held 38% of the Japan Packaging Laminates Market by material in 2025. Aluminium foil commands the largest share in Japan's packaging laminates market due to its excellent barrier properties, particularly for food packaging applications. Its extensive use in preserving food quality aligns with the country's strong food industry and consumer preferences. Paper and Paperboard is set to record the highest CAGR in this split, 10.1% over 2026–2032. The Paper and Paperboard segment is seeing rapid growth as consumers increasingly seek eco-friendly packaging alternatives. The government's recent recycling initiative for packaging waste is propelling demand for sustainable materials, further driving this segment's expansion. Suppliers need to prioritise the development of sustainable packaging solutions to align with consumer preferences and regulatory trends.
By Thickness – Up to 30 Micron Leads, 30-45 Micron Expected to Grow Fastest
The largest thickness category in 2025 was Up to 30 Micron, at 42% of revenue. The Up to 30 Micron thickness segment leads the market as it is widely used for lightweight packaging solutions, catering to various consumer needs. This segment's popularity is reflected in its extensive application across multiple product categories. 30-45 Micron is projected to grow fastest, at a CAGR of 8.9% during 2026–2032. The 30-45 Micron thickness segment is growing quickly, driven by its versatility in various packaging types, including food and pharmaceuticals. This range meets the increasing demand for packaging that balances durability and weight. Buyers will benefit from a wider selection of packaging options as manufacturers expand their offerings in the 30-45 Micron thickness range.
By Application – Aseptic Packaging Leads, Non-Aseptic Packaging Expected to Grow Fastest
With 57% of application revenue in 2025, Aseptic Packaging was the largest category. Aseptic packaging holds the largest share as it is essential for ensuring the long shelf life of food products, which is critical for consumer safety. The stringent food quality regulations in Japan further solidify this segment's position in the market. The quickest growth will come from Non-Aseptic Packaging, forecast to expand at a CAGR of 9.4% between 2026 and 2032. Non-aseptic packaging is witnessing rapid growth due to its extensive use in a variety of consumer products, aligning with changing consumer preferences. The increasing demand for convenience foods is a key factor propelling this segment's expansion. This indicates that suppliers must adapt their strategies to cater to the rising demand for non-aseptic packaging solutions.
By End-use – Food Leads, Pharmaceuticals Expected to Grow Fastest
Food accounted for 39% of the market by end-use in 2025. The Food segment leads the market as it represents the largest application for packaging laminates, driven by Japan's extensive food industry. This segment's strength is underscored by the high demand for food safety and preservation solutions. Over 2026–2032, Pharmaceuticals are expected to post the fastest growth, at a CAGR of 9.1%. Pharmaceuticals are the fastest-growing end-use segment, driven by the need for packaging that maintains product integrity and complies with strict regulations. The increasing focus on health and wellness further propels this growth. Manufacturers should prioritise innovations in pharmaceutical packaging to meet the rising regulatory and consumer demands.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- Japan Packaging Laminates Market Outlook
- Market Size of Japan Packaging Laminates Market, 2025
- Forecast of Japan Packaging Laminates Market, 2032
- Historical Data and Forecast of Japan Packaging Laminates Revenues & Volume for the Period 2022-2032
- Japan Packaging Laminates Market Trend Evolution
- Japan Packaging Laminates Market Drivers and Challenges
- Japan Packaging Laminates Price Trends
- Japan Packaging Laminates Porter's Five Forces
- Japan Packaging Laminates Industry Life Cycle
- Historical Data and Forecast of Japan Packaging Laminates Market Revenues & Volume By Material for the Period 2022-2032
- Historical Data and Forecast of Japan Packaging Laminates Market Revenues & Volume By Aluminium Foil for the Period 2022-2032
- Historical Data and Forecast of Japan Packaging Laminates Market Revenues & Volume By Paper and Paperboard for the Period 2022-2032
- Historical Data and Forecast of Japan Packaging Laminates Market Revenues & Volume By Metallized PP for the Period 2022-2032
- Historical Data and Forecast of Japan Packaging Laminates Market Revenues & Volume By Metallized PET for the Period 2022-2032
- Historical Data and Forecast of Japan Packaging Laminates Market Revenues & Volume By Metallized PA for the Period 2022-2032
- Historical Data and Forecast of Japan Packaging Laminates Market Revenues & Volume By Metallized PE for the Period 2022-2032
- Historical Data and Forecast of Japan Packaging Laminates Market Revenues & Volume By Metallized PVC for the Period 2022-2032
- Historical Data and Forecast of Japan Aluminium Foil Packaging Laminates Market Revenues & Volume By Others for the Period 2022-2032
- Historical Data and Forecast of Japan Packaging Laminates Market Revenues & Volume By Thickness for the Period 2022-2032
- Historical Data and Forecast of Japan Packaging Laminates Market Revenues & Volume By Up to 30 Micron for the Period 2022-2032
- Historical Data and Forecast of Japan Packaging Laminates Market Revenues & Volume By 30-45 Micron for the Period 2022-2032
- Historical Data and Forecast of Japan Packaging Laminates Market Revenues & Volume By 45-60 Micron for the Period 2022-2032
- Historical Data and Forecast of Japan Packaging Laminates Market Revenues & Volume By Above 60 Micron for the Period 2022-2032
- Historical Data and Forecast of Japan Packaging Laminates Market Revenues & Volume By Application for the Period 2022-2032
- Historical Data and Forecast of Japan Packaging Laminates Market Revenues & Volume By Aseptic Packaging for the Period 2022-2032
- Historical Data and Forecast of Japan Packaging Laminates Market Revenues & Volume By Non-Aseptic Packaging for the Period 2022-2032
- Historical Data and Forecast of Japan Packaging Laminates Market Revenues & Volume By End-use for the Period 2022-2032
- Historical Data and Forecast of Japan Packaging Laminates Market Revenues & Volume By Food for the Period 2022-2032
- Historical Data and Forecast of Japan Packaging Laminates Market Revenues & Volume By Pharmaceuticals for the Period 2022-2032
- Historical Data and Forecast of Japan Packaging Laminates Market Revenues & Volume By Cosmetics & Personal Care for the Period 2022-2032
- Historical Data and Forecast of Japan Packaging Laminates Market Revenues & Volume By Others for the Period 2022-2032
- Japan Packaging Laminates Import Export Trade Statistics
- Market Opportunity Assessment By Material
- Market Opportunity Assessment By Thickness
- Market Opportunity Assessment By Application
- Market Opportunity Assessment By End-use
- Japan Packaging Laminates Top Companies Market Share
- Japan Packaging Laminates Competitive Benchmarking By Technical and Operational Parameters
- Japan Packaging Laminates Company Profiles
- Japan Packaging Laminates Key Strategic Recommendations
Market Covered
Coverage by segment is as follows.
By Material
- Aluminium Foil
- Paper and Paperboard
- Metallized PP
- Metallized PET
- Metallized PA
- Metallized PE
- Metallized PVC
- Others
By Thickness
- Up to 30 Micron
- 30-45 Micron
- 45-60 Micron
- Above 60 Micron
By Application
- Aseptic Packaging
- Non-Aseptic Packaging
By End-use
- Food
- Pharmaceuticals
- Cosmetics & Personal Care
- Others































