What Is Driving Growth and Adoption of Pet Insurance in South Africa's Expanding Pet Market?
Objective
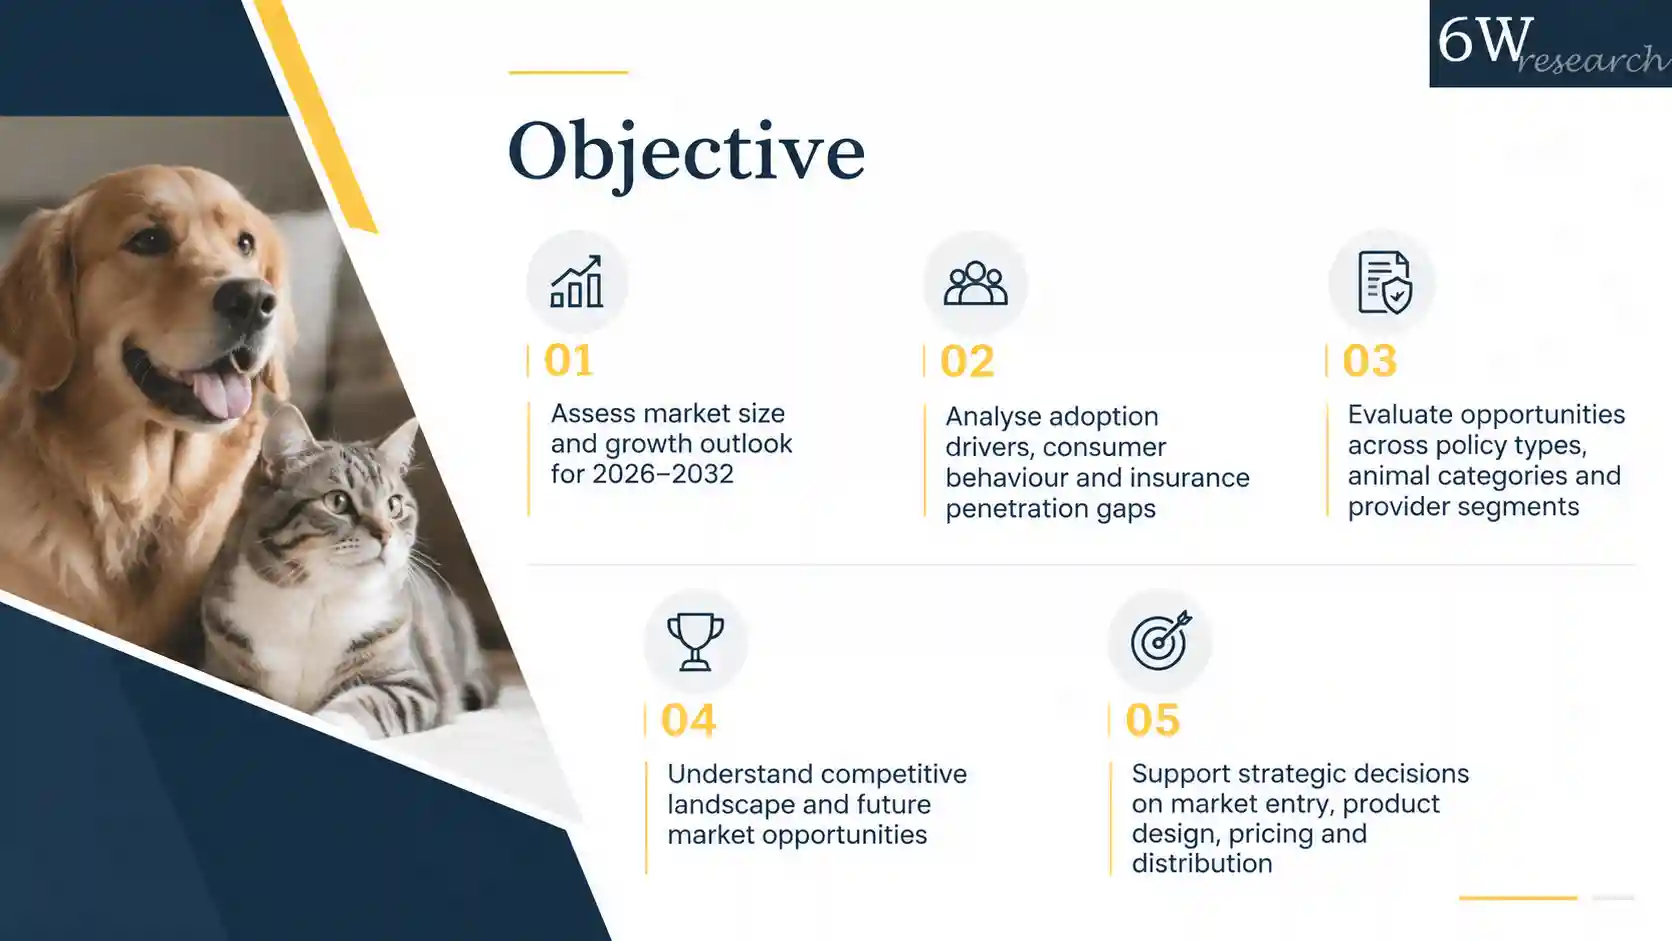
This study set out to understand where South Africa pet insurance market is heading between 2026 and 2032 — market size, growth drivers, consumer behaviour, competitive dynamics and future opportunity. Given how early-stage this market still is, the research focused heavily on potential rather than current scale: sizing the opportunity across policy types, animal categories and provider types, and identifying what's actually stopping adoption from taking off. The intended audience includes pet owners, insurers and other industry stakeholders looking for guidance on market entry, product design, pricing and distribution. The goal throughout was to give clients a realistic read on how quickly this market could grow, and where the early-mover advantages are likely to be.
Business Challenge
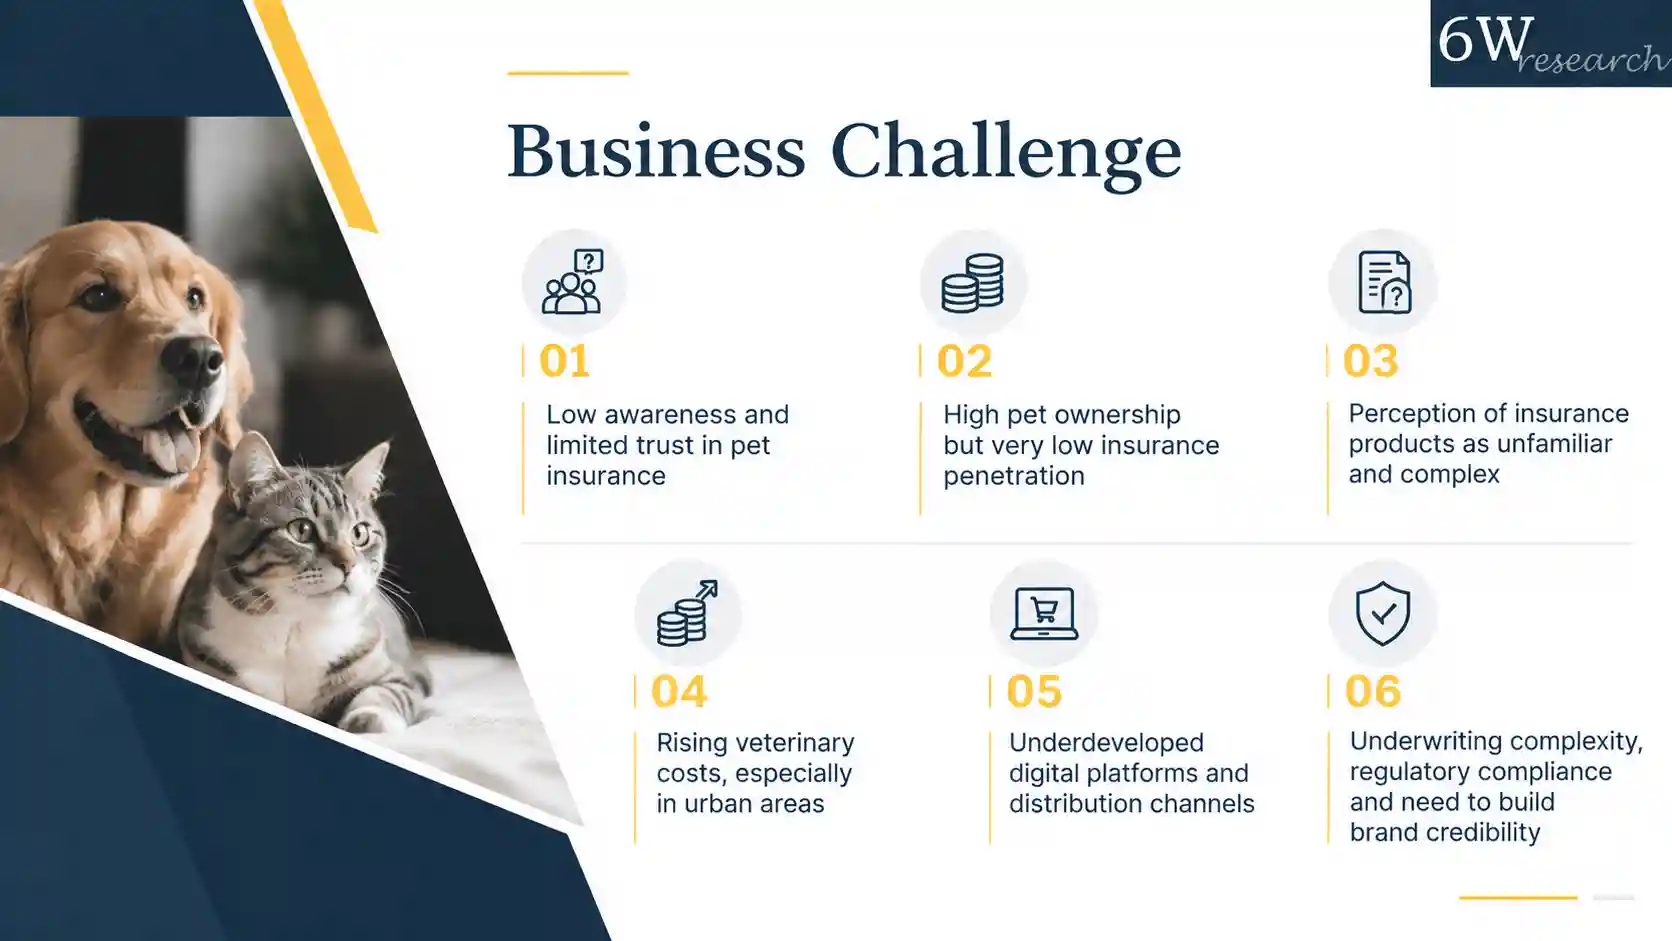
South Africa presents an unusual case — pet ownership is high, with over 45% of households owning a pet, but insurance penetration sits at roughly 1%. That gap comes down to low awareness and limited trust in insurance providers more than anything else. Most pet owners are still self-funding vet bills, largely because insurance products feel unfamiliar or overly complicated. Veterinary costs, particularly in urban areas, can be steep, yet that financial pressure hasn't yet translated into insurance uptake — partly because digital platforms that would make buying and using a policy easier are still underdeveloped. New entrants face their own set of hurdles: underwriting complexity, regulatory compliance, and simply establishing enough brand credibility to be trusted with something as personal as a pet's health. On the operational side, insurers need to invest in consumer education, build out distribution, and design products that actually address long-term conditions rather than just one-off vet visits. None of this is insurmountable, but it does mean growth here will be earned rather than automatic.
How We Did It
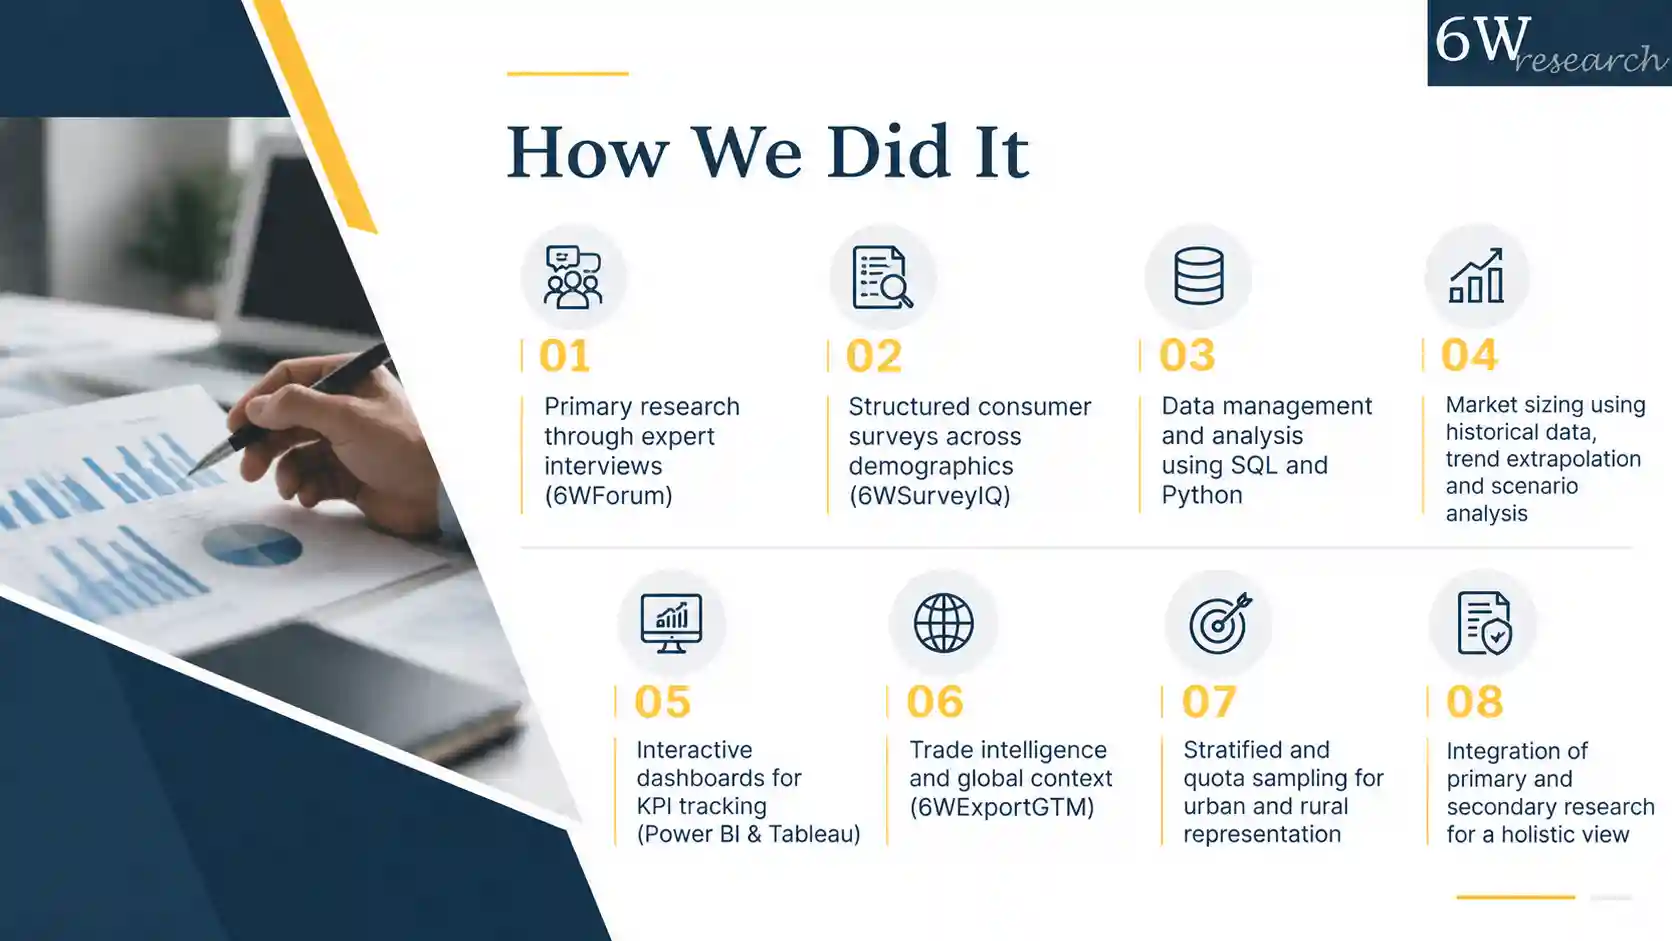
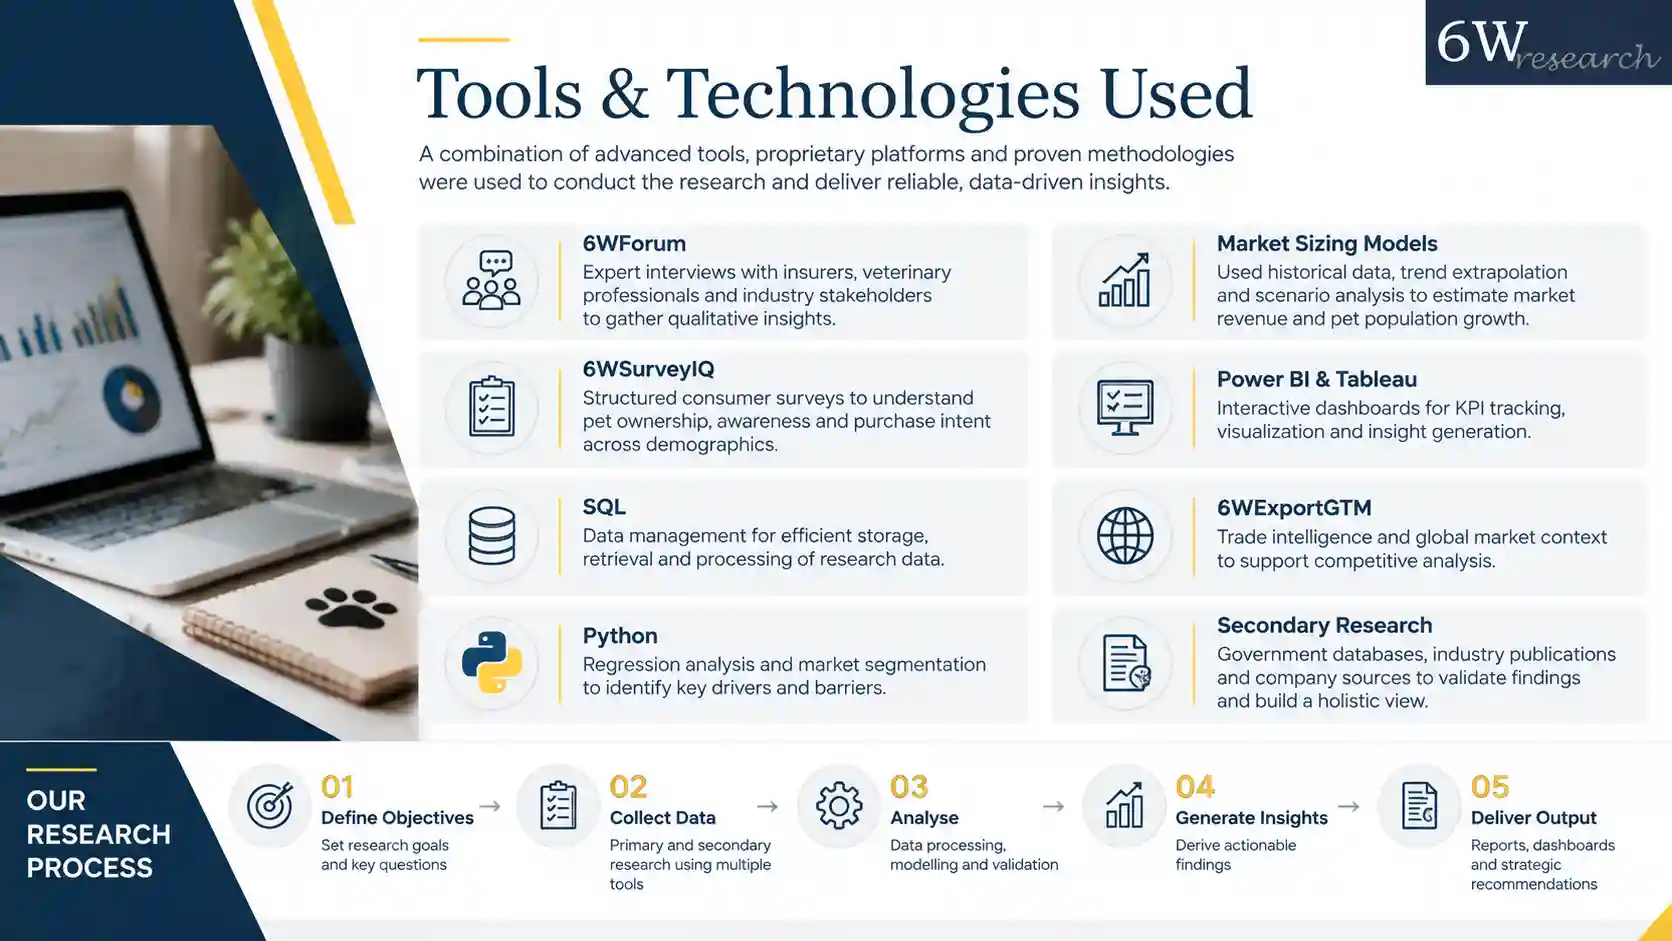
We combined primary and secondary research, using expert interviews via 6WForum to get qualitative input from insurers, veterinary professionals and consumer groups. Structured surveys through 6WSurveyIQ quantified pet ownership trends, awareness levels and purchase intent across different demographics, with stratified and quota sampling used to make sure both urban and rural pet owners were properly represented. SQL was used to manage the data to facilitate quick retrieval and Python assisted with regression analysis and segmentation to determine what’s really driving or blocking adoption. Market sizing utilised historical data, trend extrapolation and scenario analysis to estimate both revenue and pet population growth. We built interactive Power BI and Tableau dashboards for ongoing KPI tracking, and pulled in trade intelligence from 6WExportGTM to round out the picture with international trade context.
Key Findings
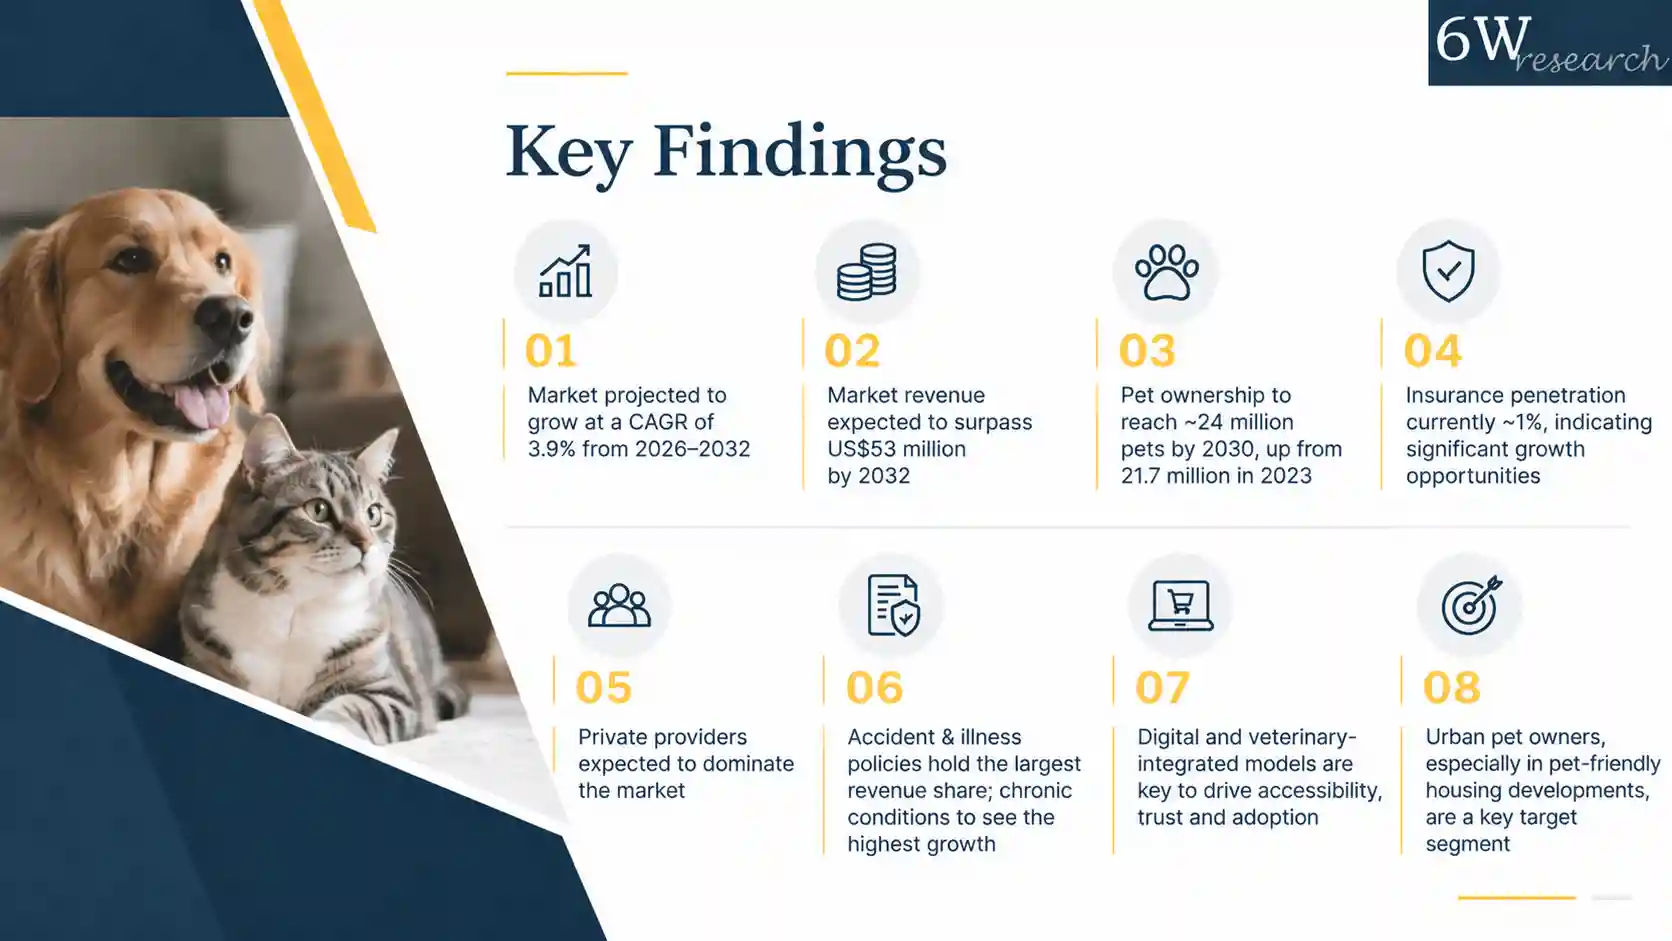
- The South African pet insurance market is projected to grow at a CAGR of 3.9% from 2026 to 2032, driven by rising pet ownership and increasing veterinary costs.
- By 2032, the market revenue is expected to surpass US$53 million, with dogs accounting for the largest share due to higher veterinary treatment expenses and owner willingness to insure them.
- Pet ownership is forecasted to reach approximately 24 million pets by 2030, up from 21.7 million in 2023, indicating a substantial expansion of the insurable pet base.
- Currently, only about 1% of pets are insured, highlighting significant growth opportunities for insurers through awareness campaigns and product innovation.
- Private insurance providers are expected to dominate the market, capturing a larger share owing to their broader product portfolios, digital platforms, and strategic partnerships with veterinary clinics.
- The accident and illness policy segment holds the majority revenue share, with chronic conditions expected to see the highest growth rate, reflecting evolving consumer preferences for long-term health coverage.
- Digital and veterinary-integrated insurance models are identified as key strategic avenues to enhance accessibility, trust, and adoption among pet owners.
- Urban pet owners, especially in pet-friendly housing developments, are emerging as primary target segments for market expansion.
Findings
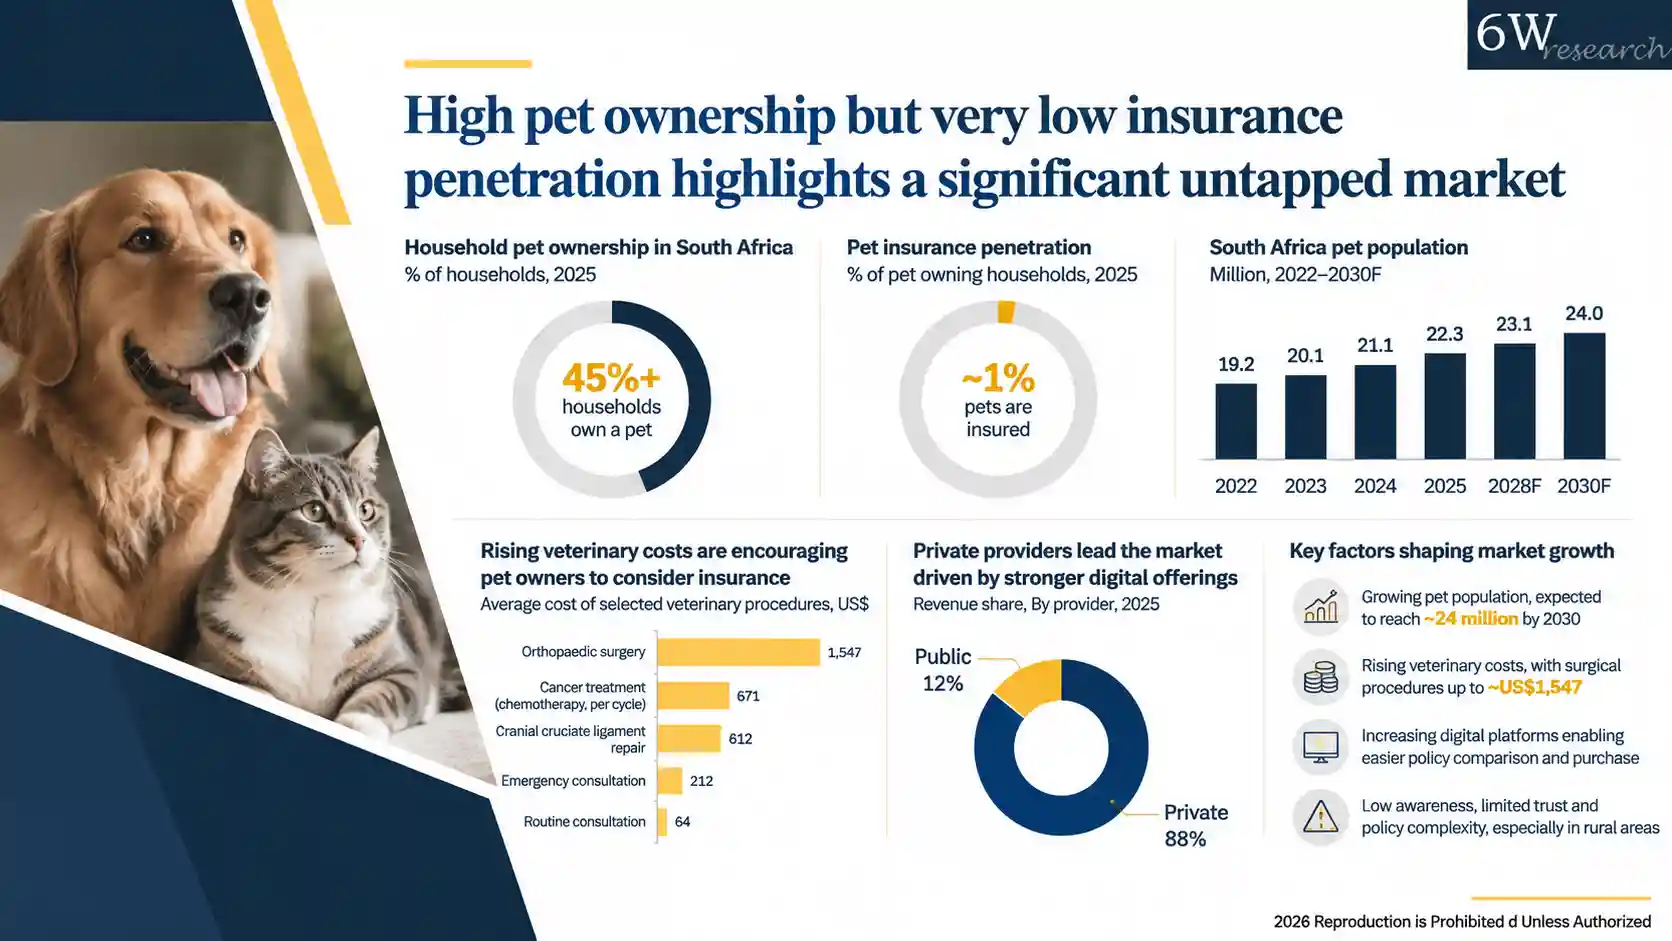
The research reveals that South Africa's pet insurance market is in its nascent stage, with 1% penetration against 45%+ household pet ownership. But the underlying trend is favourable which means the pet population is projected to climb to around 24 million by 2030, driven by a broader cultural shift toward viewing pets as family members rather than just animals. Rising veterinary costs — surgical procedures alone can run up to roughly US$1,547 — are pushing more owners to think seriously about financial protection. Digital platforms are starting to make comparing and buying policies easier, which should help chip away at some of the current inertia. That said, low awareness, limited trust, and policy complexity remain real obstacles, particularly in rural areas where insurers haven't built much of a presence yet. Private providers currently lead the pack, largely because of stronger digital offerings and partnership networks — a lead that's likely to widen as the market matures and awareness grows.
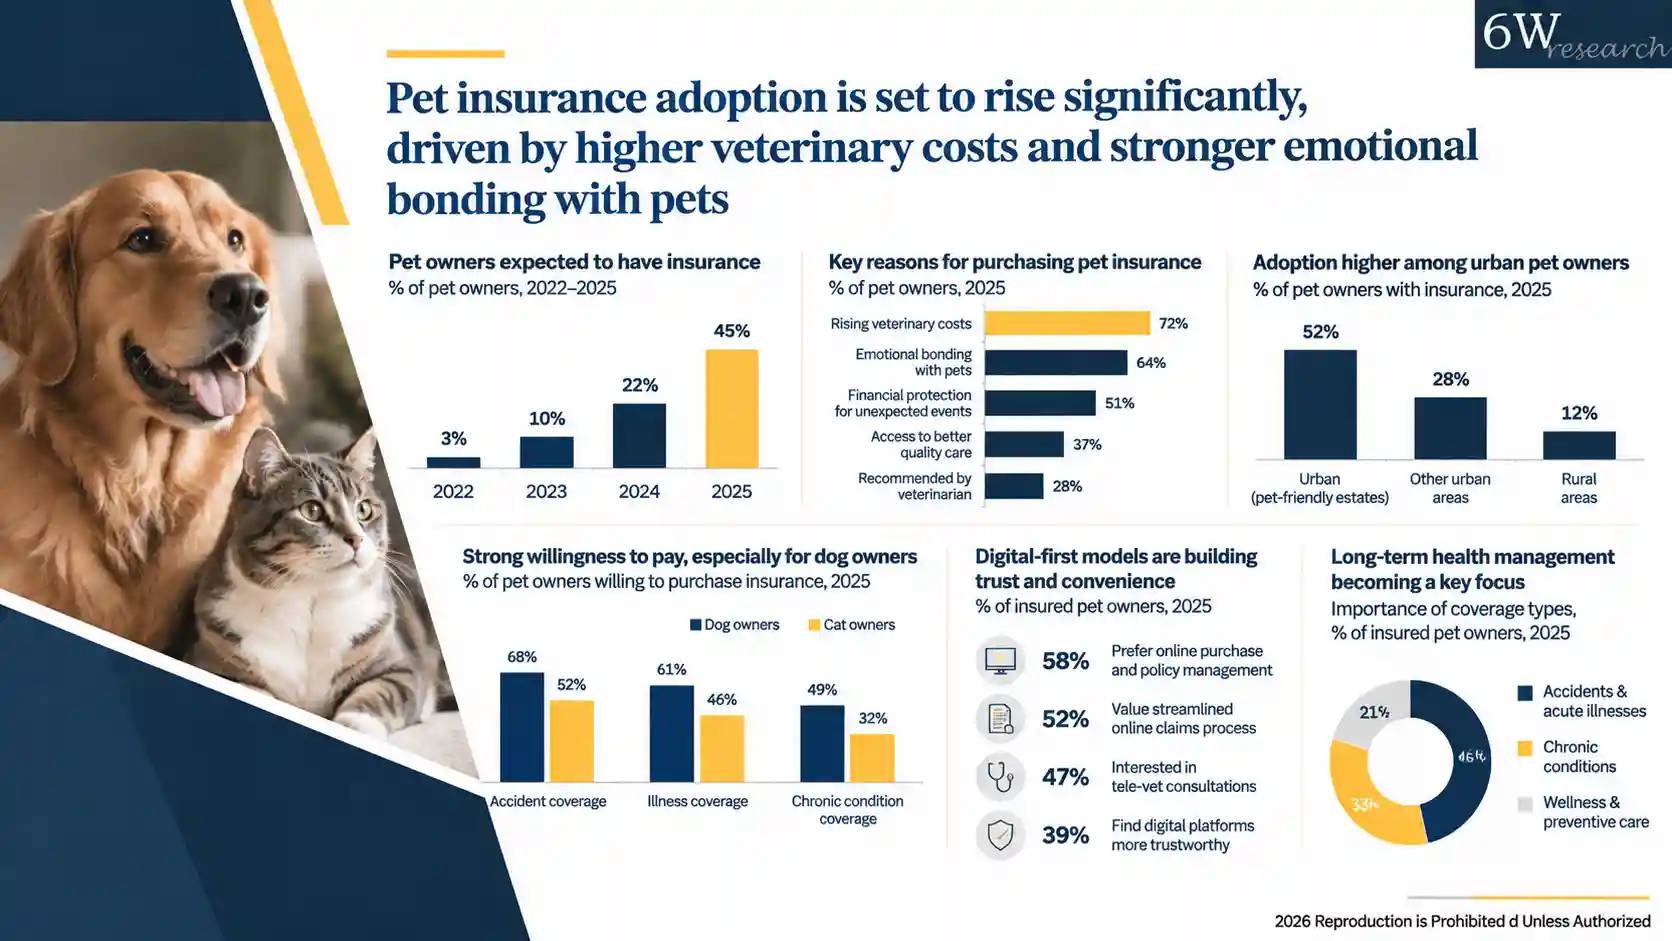
There's a clear shift underway toward more comprehensive pet healthcare coverage, with close to 45% of pet owners expected to have insurance by 2025. Rising vet costs and the emotional weight owners place on their pets are the two biggest forces behind this. Urban owners — particularly those in pet-friendly residential estates — are further ahead on adoption, helped along by amenities and lifestyle developments that normalise pet ownership generally. Even with today's low penetration, there's a real willingness among owners, especially dog owners, to pay for accident, illness and chronic condition coverage. Digital-first insurance models — think streamlined online claims and tele-vet consultations — are proving effective at building the kind of trust and convenience this market still needs. Long-term health management, particularly around chronic conditions, looks set to be a growing focus as owners look for more sustainable ways to manage ongoing veterinary costs.
Business Impact
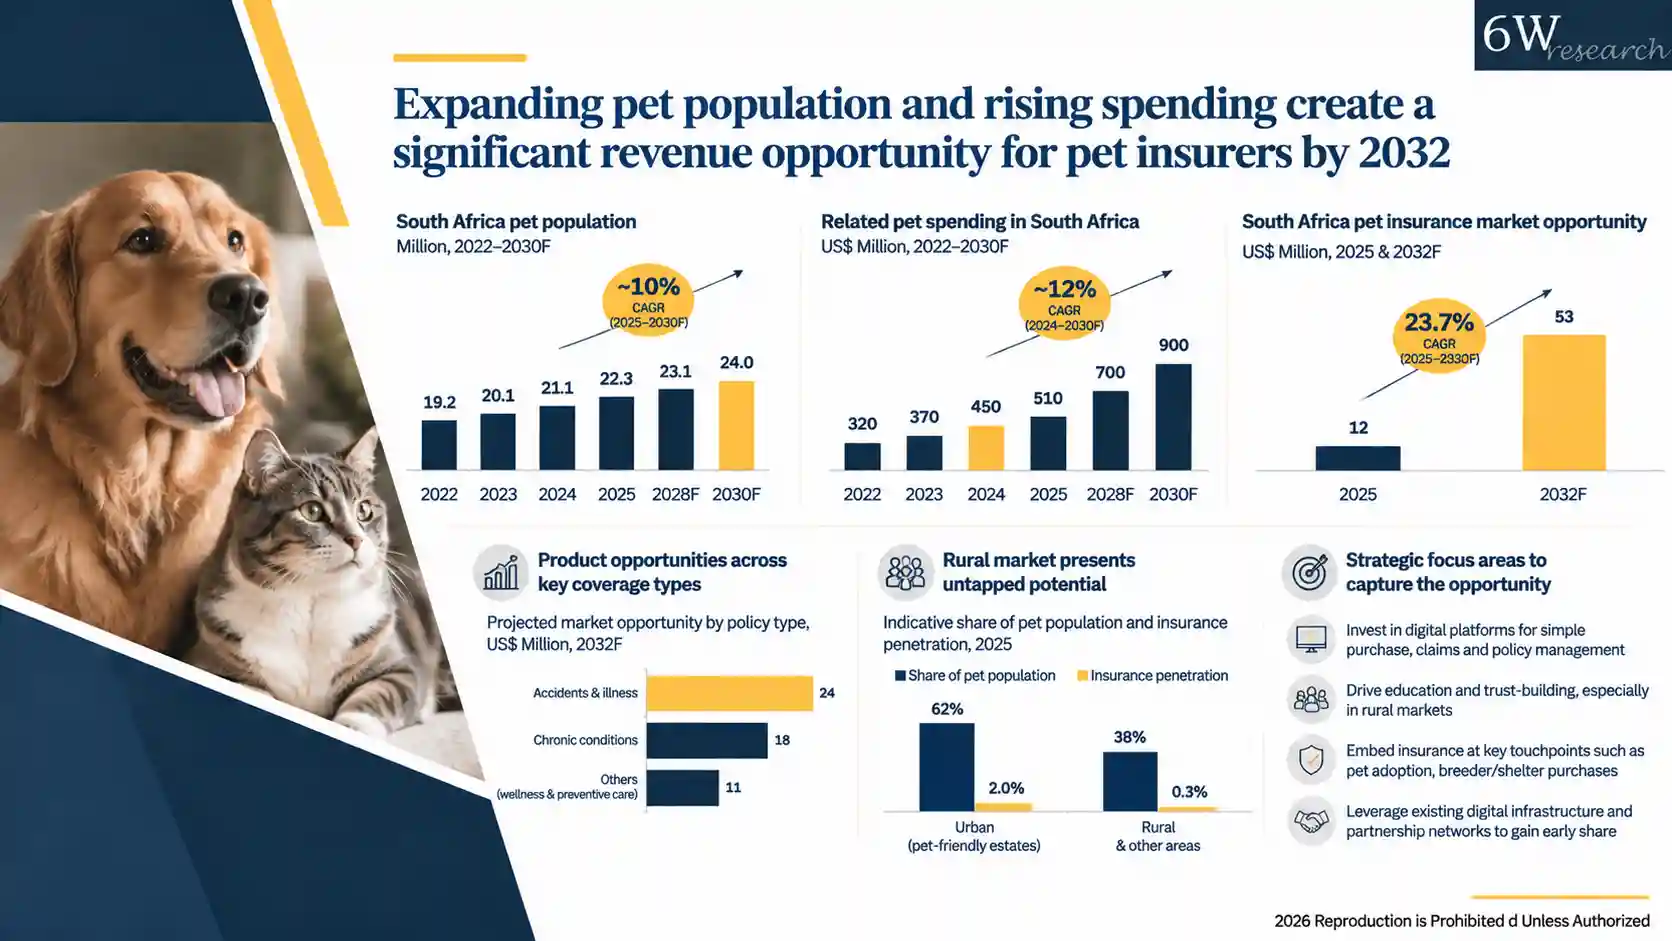
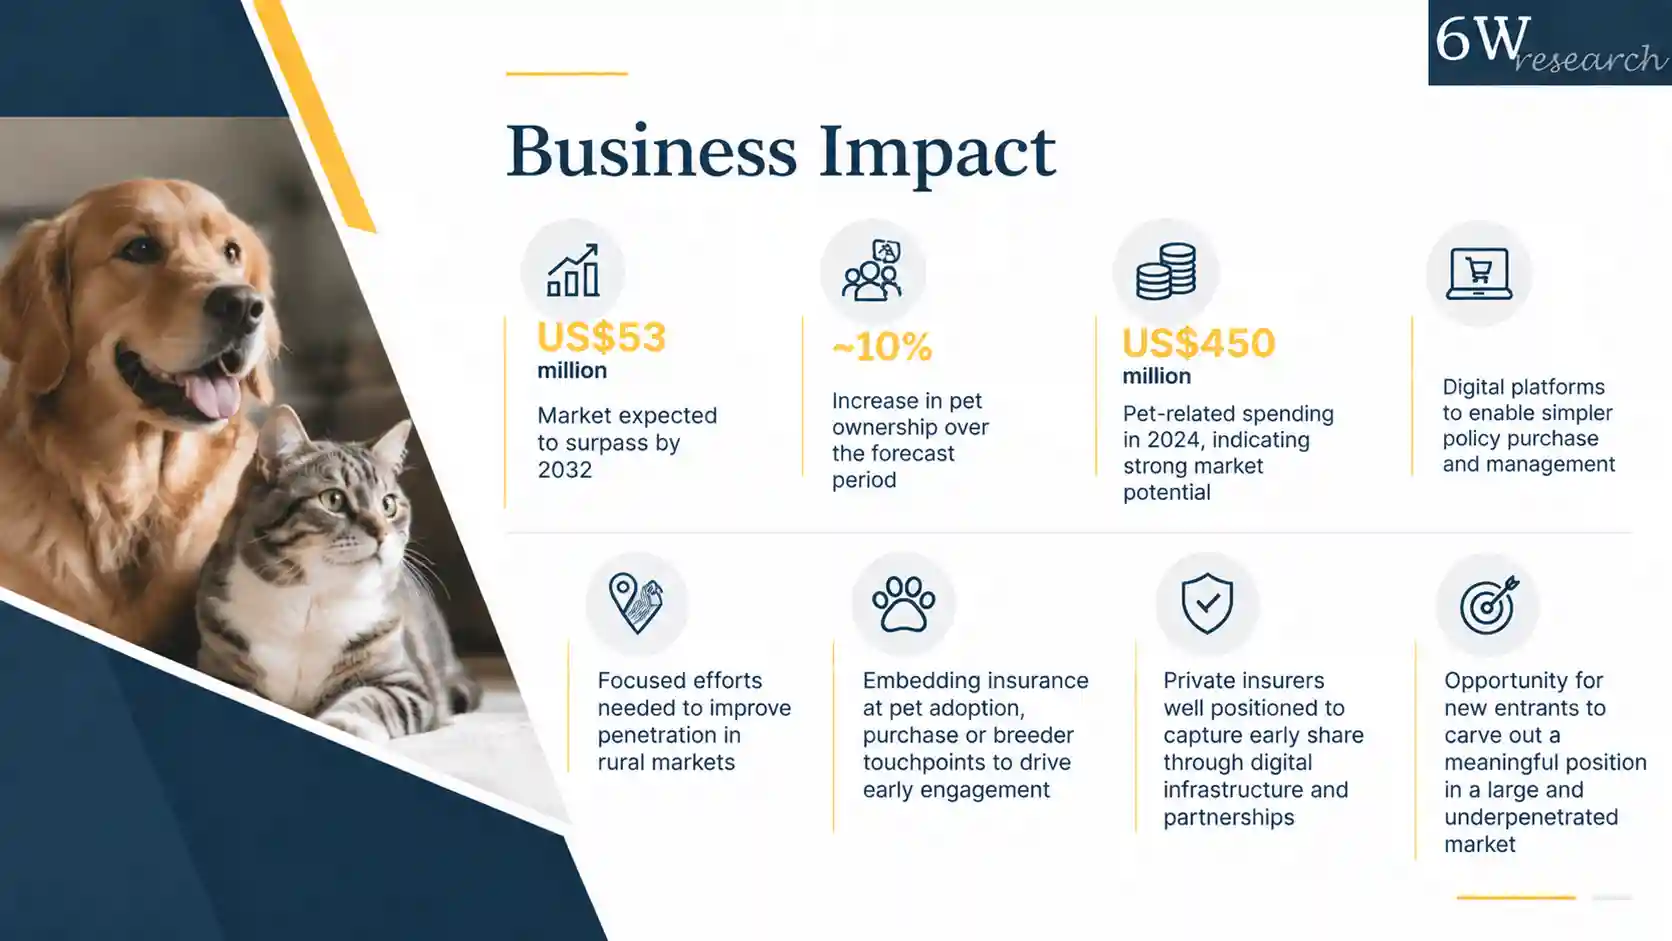
There's genuine opportunity here for insurers willing to invest in education and trust-building rather than expecting fast, easy uptake. With pet ownership set to grow roughly 10% over the forecast period and related spending already past US$450 million in 2024, there's real room to build tailored accident, illness and chronic-condition products. Hitting the projected US$53 million market by 2032 will depend heavily on digital platforms that make buying and managing a policy genuinely simple. Rural market penetration will need dedicated attention, since trust gaps are wider there than in urban centres. Embedding insurance at natural touchpoints — pet adoption, purchase from breeders or shelters — could meaningfully accelerate early engagement and build the kind of loyalty that compounds over time. Private insurers, given their existing digital infrastructure and partnership networks, are best placed to capture early share, but the overall opportunity is large enough that thoughtful new entrants could carve out meaningful position too.


