Market decisions built on evidence, not estimation.
One engagement cluster, from opportunity identification through to implementation — explore the services, the models behind them, and the case studies that prove them out.
we serve
Services Cluster
Click a stage, then a sub-service inside, then jump to its case study.
Customer & End-User Behavior Analysis
Brand, Product & Sales Strategy
Data Analytics & Reporting
Big Data & AI/ML
Corporate & Growth Strategy
Operations & Management Consulting
Digital Transformation & Innovation
Risk, Compliance & Governance
Sustainability & ESG Strategy
Strategy Roadmap
Implementation & Change Management
Partnership & Distributor Development
Case Studies
Click a service, model, data source or industry — matching studies are filtered by the controller.
What Drives Success in India’s Deep Mining Tipper Market?

Determine decision drivers and economic factors for 50–80-ton tippers for deep mining applications in India to help develop product, services, finance and after market strategies.
Undertook a primary face-to-face survey of 50 contractors and fleet owners from the major mining clusters in India through quota sampling. The questionnaire comprised aspects on fleet usage, operating costs, financing, warranty, spare parts, service experiences, and brand perception.
Long haul and high intense fleets have focused revenue streams and predictable fuel-led costs. Mostly loan funded though EMIs are manageable. Warranties are usually span around 3–5 years, after which maintenance costs increase. Leading brands remain resilient with switching decisions, primarily driven by total cost of ownership, fuel efficiency, maintenance costs, and service reliability.
Enabled benchmarking of operational economics, financing, warranty expectations, and brand preferences to improve product strategy, fleet management, and customer retention.
Who Are the Buyers Shaping the Future of SCV & LCV Markets?

Analyze SCV and LCV buyers’ preferences, purchase drivers and their willingness to pay for upgrades to help position the product, determine pricing and market-entry strategies across segments and regions.
Undertook a two-phase quantitative study comprising 1,873 general respondents and 728 vehicle buyers. Conjoint analysis was undertaken to determine attribute preferences and price sensitivity, supported by regional, model-level, payload, and fuel preference segmentation.
The customer values payload, mileage, fuel type, and pickup performance. Payload capacity of 750 kg is preferred the most, followed by 1000 kg. Despite dissatisfaction with SCR systems, diesel fuel along with urea technology remains preferred to a major extent. There are differences in brands preference by regions, while about 35-40% of respondents are ready to pay INR 40,000-60,000 for payload upgrades.
Supported product optimization, pricing strategies, customer segmentation, and technology adoption initiatives by identifying buyer preferences and regional demand patterns.
What Do Users Really Expect from Professional Display Solutions?

Understand professional display deployment, use cases, connectivity preferences, operating patterns, and user satisfaction across sectors to inform product, support, and procurement strategies.
Surveyed 1,000 professional display users in the corporate, education, retail, hospitality, transportation, domestic, government and industrial sectors. The research broadly covered deployment, applications, connectivity, orientation, usage time, technology awareness, and user satisfaction.
Most respondents use two to ten professional displays mainly for meetings, presentations, video conferencing, and dissemination of information. The most common ways to connect are LAN and Wi-Fi. Laptops are often connected via HDMI and wireless. Landscape orientation is preferred, and displays are often operated for extended periods. Awareness of anti-glare technology is still low; overall user satisfaction is largely positive.
Helped refine product positioning, feature communication, and service strategies by understanding display usage patterns and end-user requirements across sectors.
Why Do Customers Switch Brands — and How Can They Be Won Back?

Study the professional display deployment, usage, connectivity preferences, operating patterns, and user satisfaction across key sectors to inform product development, support, procurement approaches.
Conducted a primary lost-cases study of 500 respondents in states such as Gujarat and Uttar Pradesh. Purchase-funnel analysis, switching analysis, product ratings, discounts, feedbacks, and regional segmentation techniques were employed to determine conversion obstacles.
Strong brand consideration did not consistently translate into purchases. Price perceptions and dealer engagement were the biggest conversion barriers, with some buyers perceiving a price gap of ₹50,000-₹1 lakh or more. Other factors that influenced switching decisions were after sales service, availability of spare-parts, product performance and resale value.
Identified purchase drop-off drivers, pricing concerns, service gaps, and competitive factors to improve conversion, customer retention, and market share growth.
What Makes ICV Truck Buyers Choose One Brand Over Another?

Identify the decision drivers for buyers of Intermediate Commercial Vehicles in North India, Tamil Nadu, and Karnataka with an emphasis on regional differences in brand perceptions, performance, prices, and after-sales support.
251 Face to face interviews were conducted in North India, Tamil Nadu and Karnataka using stratified sampling. Respondents evaluated brand perception, service experience, vehicle performance, purchase motives, pricing and competitive preferences using Likert scale and multiple rating questions.
Regional preferences differed significantly. Customers in southern markets perceived greater comfort, aesthetics, performance and service, while northern customers placed greater importance on price, vehicle performance, spare-parts availability and after-sales support. In northern markets, significant barriers to adoption included gaps in service networks, spare-parts issues, and misconceptions about the brand.
Supported improvements in brand positioning, after-sales service, spare availability, and dealer effectiveness to strengthen customer loyalty.
How Can Customer Insights Transform Commercial Vehicle Experiences?

Determine customer satisfaction, usage behavior and competitive positioning in Tier-II & Tier-III cities. Also determine preferred vehicle configurations to guide product development and relaunch strategies.
Conducted stratified random face-to-face surveys with 320 stakeholders across nine states, including vehicle users, RTO officials, body builders, and competitor users. Likert-scale and multiple-rating techniques were used, with Power BI and Python supporting the analysis.
Approximately 75% of users reported satisfaction, driven by total cost of ownership, compactness, and maneuverability. The single-compartment and fully built configurations were strongly preferred by customers. Two-compartment vehicles created communication and operational challenges. Repeated areas of improvement included service quality, body, and paint quality and rear suspension, while air conditioning and factory-built configurations were identified as desirable future features.
Guided product enhancements, vehicle configuration decisions, and comfort improvements to better address school transport customer requirements.
Where Are the Biggest Opportunities to Win in Fire & Security Markets?

Develop a go-to-market strategy for controls, fire, and security products in commercial and industrial mid-market segments across Tier-2 Indian cities, identifying customer needs, competitive gaps, pricing opportunities, and channel priorities.
Conducted a primary quantitative survey of approximately 792 respondents across commercial, industrial, residential and other sectors in Tier-2 Indian cities. The study covered brand awareness, purchase behaviour, pricing, willingness to pay, competitor positioning, product preferences, and channel dynamics.
Most projects are based on existing installations and it is common to adopt a single brand. The market has strong recall of established brands. The main channels are distributors and dealers. Customers are willing to pay for small improvements in technical support, product availability, service quality and delivery reliability. There are opportunities for better aftermarket support, parts availability, technical assistance and supply chain responsiveness.
Provided insights to strengthen after-sales service, channel networks, product quality, pricing strategies, and market penetration in Tier-2 cities.
What Will It Take to Accelerate ADAS Adoption in India?

Assess consumer awareness, willingness to pay, preferred ADAS features, and key adoption barriers while identifying the technology, localization, regulatory, and service requirements needed to scale ADAS in India.
Conducted a structured survey of 250 consumers, supported by interviews with industry executives and dealers. Statistical techniques such as Chi-square, Cramér’s V, PCA, Logistic Regression, Decision Trees, Random Forest, and K-mode Clustering were used to understand consumer preferences, affordability, awareness, and adoption patterns.
ADAS adoption remained limited mainly due to high costs, poor road markings, low awareness, and concerns around technology performance. Consumers showed strong interest in Automatic Emergency Braking, Adaptive Cruise Control, and Blind Spot Detection, while affordable packages, localized technology, dealer training, and stronger OEM partnerships emerged as important enablers.
Helped define a practical roadmap for feature prioritization, localization, pricing, consumer education, dealer readiness, and partnerships, supporting wider ADAS adoption and stronger competitive positioning in India.
When Does Awareness Become Real Behaviour Change?

Study the public awareness, motivation, barriers and effectiveness of campaign to blood donation to improve donor participation and inform communication and engagement strategies.
Conducted large-scale pre- and post-campaign quantitative surveys across national and tiered samples. The study compared awareness, attitudes, motivations, barriers, campaign recall, and behavioral intent to measure changes in perception and willingness to donate.
Post-campaign results majorly indicated improvements in eligibility awareness and donor intention while fear and anxiety levels dropped. Advertising and sponsorship recall increased substantially, and altruistic motivations remained strong. However, message retention and overall knowledge of donation eligibility remained limited, highlighting the need for sustained educational outreach.
Measured campaign effectiveness, improved donor awareness, reduced psychological barriers, and guided communication strategies for higher engagement.
Which Messages Create the Biggest Impact on Solar Adoption?

Study the impact of campaign creative material in increasing the awareness, understanding and purchase intention for rooftop solar adoption among parents and children in households, while identifying messaging improvements and policy levers to accelerate adoption.
Quantitative surveys with parents and kids conducted across 4 zones and 10 cities, including campaign exposure testing, media analysis, regional benchmarking and qualitative follow-ups. The study gauged awareness, message understanding, media influence, household discussion and purchase intent.
The use of campaign materials helped engage children and spark household discussions about rooftop solar among parents who had moderate awareness and gradually increasing purchasing intention. Television, school, media and government subsidies played a vital role in creating awareness and consideration. Recognition of brands differed by regions while financial benefits and information played a vital role in adoption.
Enabled optimization of campaign messaging, media strategies, and educational initiatives to improve solar awareness and purchase intent.
What Will Shape the Next Wave of Electric 3-Wheeler Growth?

Assess stakeholder perspectives and barriers to L5 EV and ICE three-wheeler adoption and help define actionable product, services and finance strategies.
Carried out a mixed-method study with end users, dealers, financiers, mechanics and other ecosystem stakeholders. Surveys, in-depth interviews, conjoint analysis, segmentation and competitive benchmarking were used to assess product preferences, operational challenges, financing constraints and barriers to battery EV adoption.
Service-network gaps and batteries remain major barriers to EV adoption. Other barriers include affordability concerns, high financing costs, charging infrastructure limitations and resale perception limitations. Some priorities that have been identified include predictable range, fast charge ability, good coverage of services, stronger warranty and lifespan assurance, financing assistance, and competitive product pricing.
Supported EV product refinement, financing strategies, service improvements, and adoption initiatives to strengthen market competitiveness.
How Can Local Engagement Turn Awareness into Adoption?
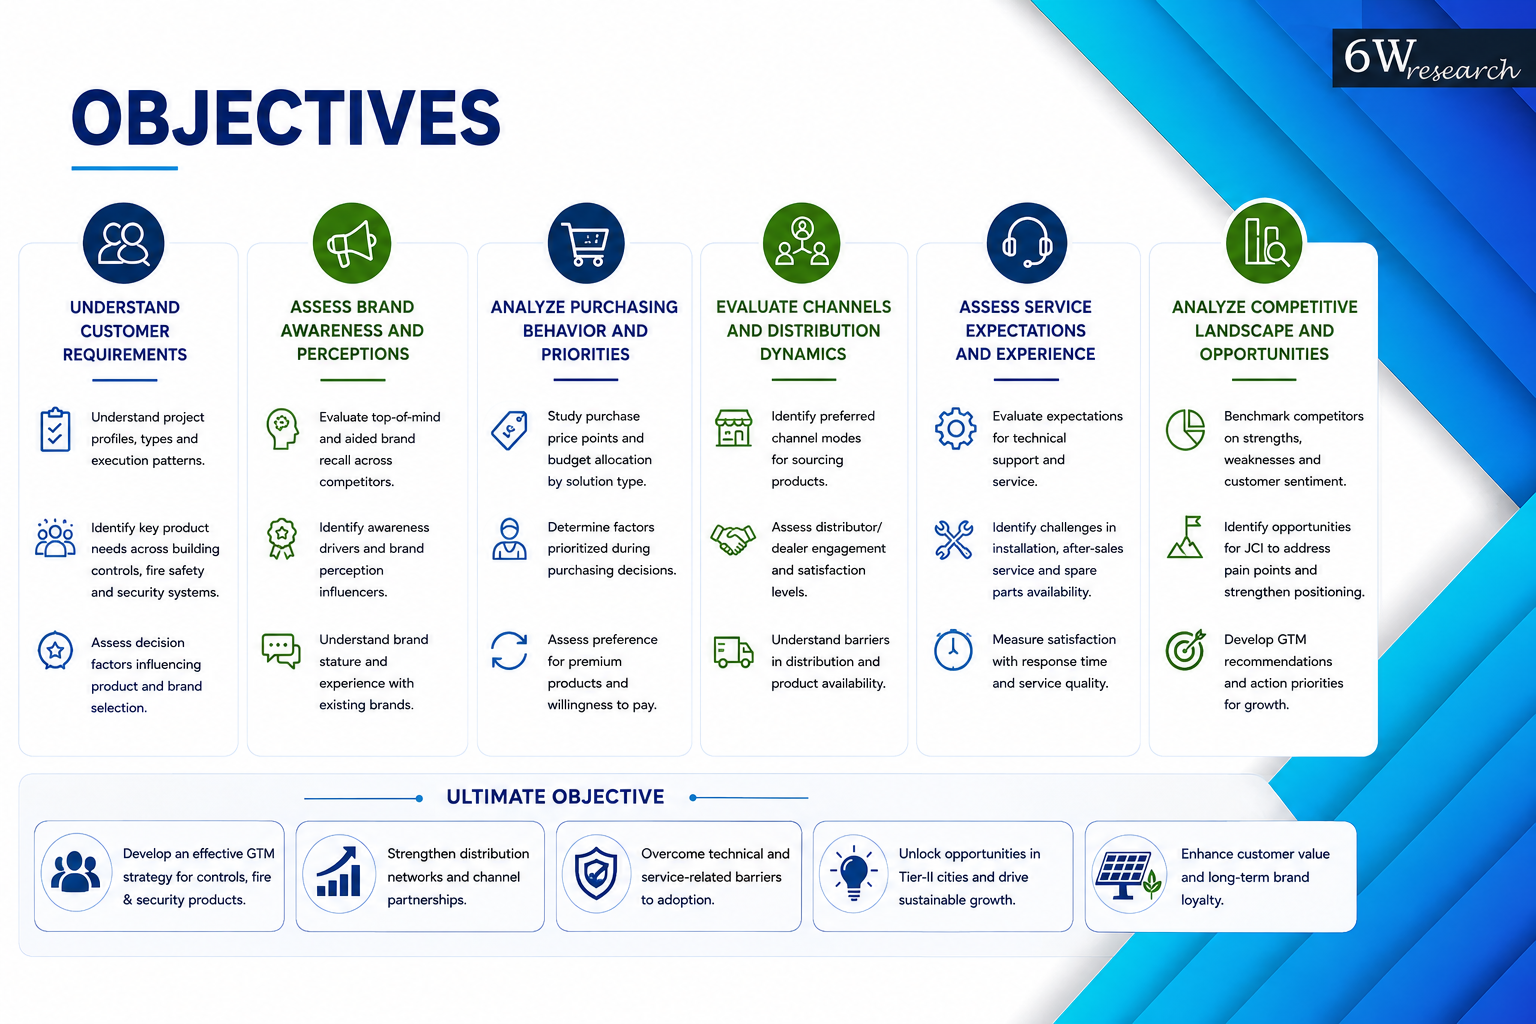
Assess whether on-ground activations increased rooftop solar awareness, subsidy understanding, brand trust, and adoption intent across rural Maharashtra while identifying adoption barriers and effective communication channels.
Carried out field surveys of respondents exposed and unexposed to campaign activations of rooftop solar, stratified by region. The study measured campaign recall, awareness, understanding of subsidies, trust drivers, intent to adopt, barriers to financing, and regional differences.
Campaign exposure materially increased rooftop solar awareness, with high awareness approximately doubling and subsidy clarity improving by around 33 percentage points. In general, local community influencers emerged as important trust drivers. The main barriers to conversion are financing constraints, information gaps, and regional differences and need to be addressed with differentiated strategies across rural markets.
Improved understanding of awareness drivers, subsidy knowledge, and local adoption barriers to optimize rural solar go-to-market strategies.
Does Advertising Create the Momentum Needed for Solar Growth?
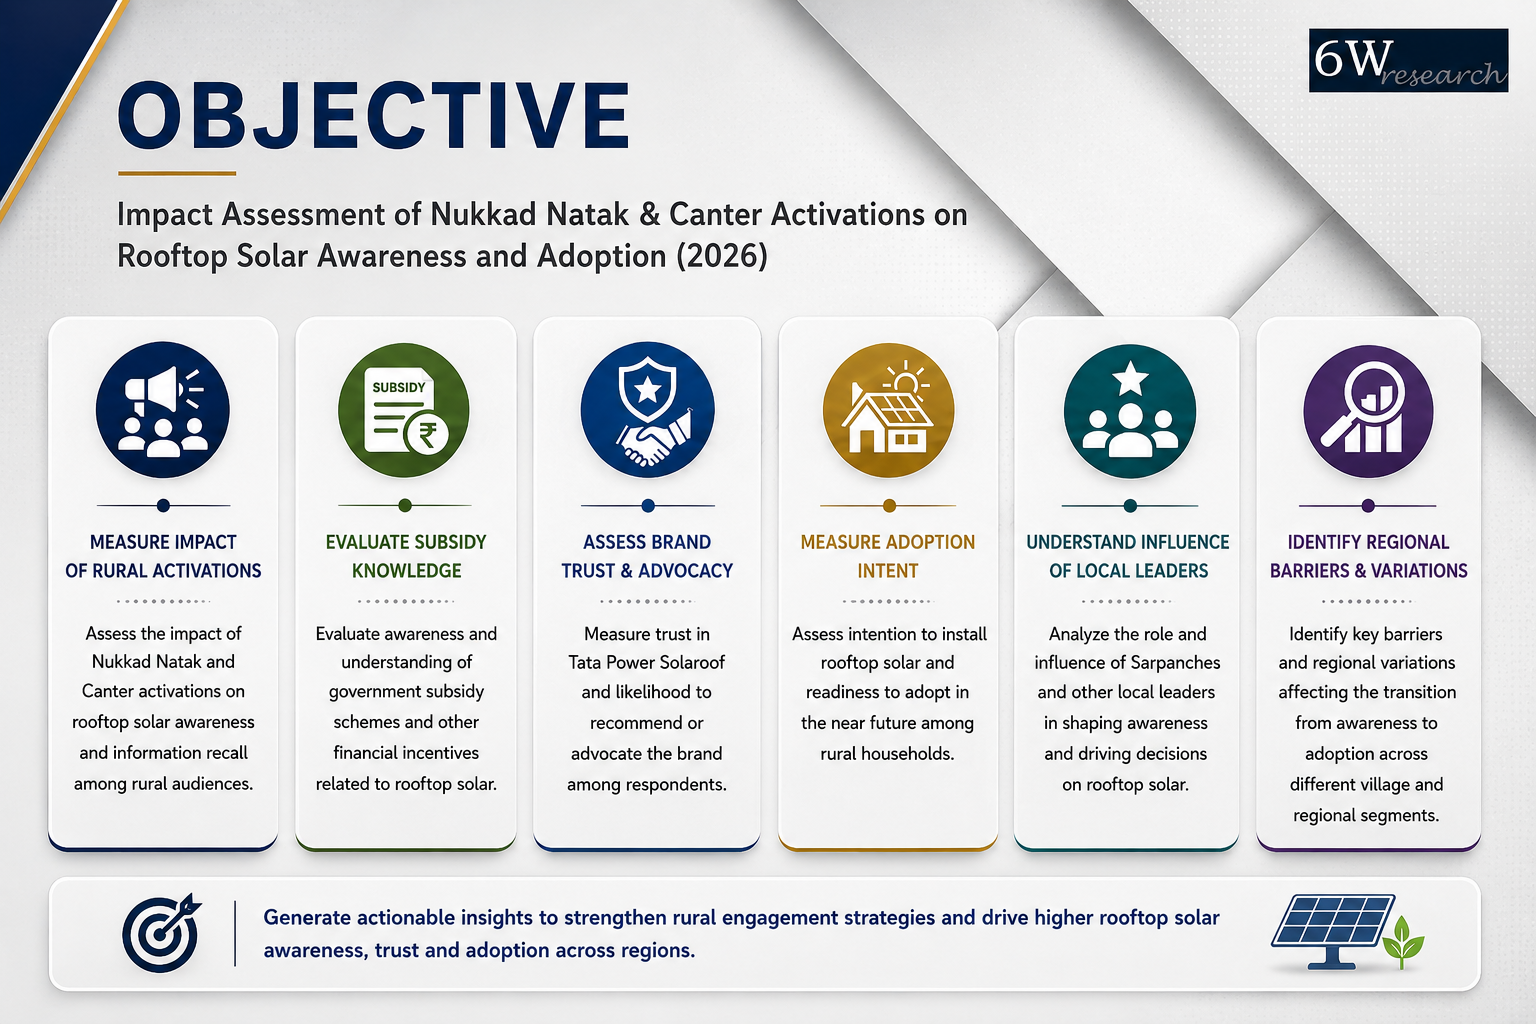
Study the impact of a TV advertising campaign on the awareness of brands, purchase intention, and attitude of consumers toward solar solutions among decision makers in MSMEs. It also evaluated key barriers to adoption and purchase drivers to enable effective marketing and communication strategies.
Carried out a stratified random survey of about 1,000 MSMEs across major industrial clusters of India through online and telephonic interviews. Structured questionnaires and Likert scale ratings were used to evaluate aided and unaided brand awareness, ad recall, campaign exposure, purchase intention, consumer perceptions, adoption barriers, and media preferences.
Leading solar brands showed strong awareness, with roughly 23% ad exposure. Campaign exposure increased brand awareness, but had little effect on short-term purchase intent. MSMEs’ solar adoption remained relatively low with benefits uncertainty and cost concerns identified as the main barriers. Television continued to be a major advertising medium and digital media gained even more ground.
Provided insights on brand awareness, adoption barriers, media preferences, and messaging effectiveness to optimize marketing strategies and accelerate solar solution adoption among MSMEs.
Our Platforms
Our standing panel of industry experts and operators, tapped for primary interviews on every engagement.
Our survey engine for fielding quantitative and qualitative research at scale.
Proprietary forecasting models that power our market sizing and scenario work.
Trade and export-potential intelligence used for market-entry and corridor analysis.
What Experts Say
CXO' Interviews
Expert & Trade Research
Qualitative Surveys
Market Intelligence & Analytics
Market Sizing, Forecasting & Trade
Segmentation & Clustering
Pricing & Value Models
Customer & Behavioral Models
Brand & Marketing Models
Sales & Funnel Models
Competitive & Structural Models
Financial, Risk & Change Models
Decision Models
Data Collection
Quantitative Surveys
Trade & Secondary Data
Digital & Behavioral Data
Frequently Asked Questions
› What services does 6W Strategy offer?
› Can we engage 6W Strategy for a single stage instead of the full cluster?
› What analytical models does 6W Strategy use?
› What data sources back up 6W Strategy's research?
› Which industries does 6W Strategy work across?
› What proprietary platforms does 6W Strategy use?
Start with a scoping call.
Tell us the market and decision — we'll map the right sequence of services.


