Brazil Ethanol Market Size & Growth Rate
According to 6Wresearch internal database and industry insights, the Brazil Ethanol Market was valued at USD 19.62 Billion in 2025 and is projected to reach USD 30.49 Billion by 2032, growing at a CAGR of approximately 6.5% during 2026–2032.
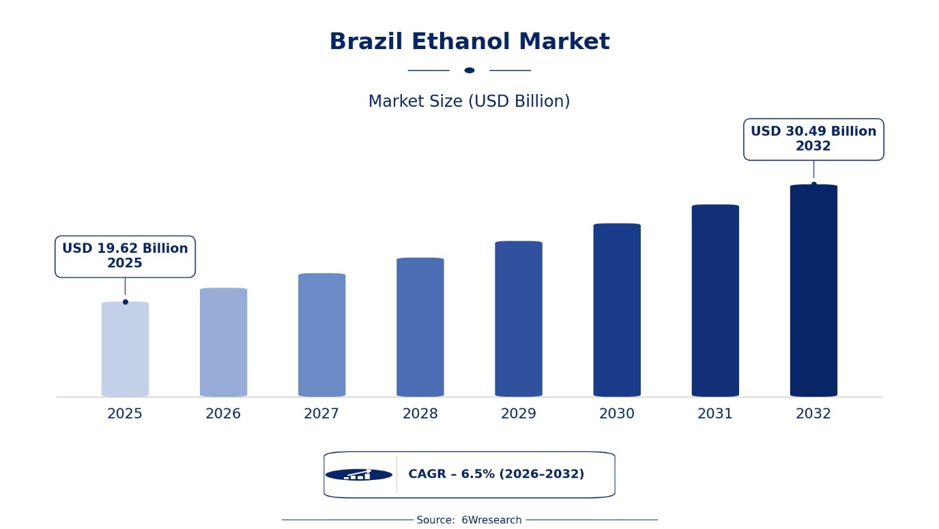
Brazil Ethanol Market Highlights
| Report Metric | Details |
| Report Name | Brazil Ethanol Market (2026-2032) |
| Market Size 2025 | USD 19.62 Billion |
| Market Size 2032 | USD 30.49 Billion |
| Absolute Growth 2025–2032 | USD 10.87 Billion |
| CAGR 2026–2032 | 6.5% |
| Peak Annual Growth | 7.4% (2029) |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Purity, 2025 | Denatured (58% share) |
| Fastest-Growing Purity | Non-Denatured (CAGR of 6.97%) |
| Leading Source, 2025 | Sugar & Molasses Based (78% share) |
| Fastest-Growing Source | Second Generation (CAGR of 14.5%) |
| Leading Application, 2025 | Fuel & Fuel Additives (66% share) |
| Fastest-Growing Application | Personal Care (CAGR of 7.1%) |
| Growing Sector | Transport fuels and low-carbon energy |
| Key End Users | Fuel distributors and blenders, flex-fuel vehicle owners, beverage manufacturers, cosmetics and personal care producers, chemical and solvent processors, healthcare and sanitation product makers |
Brazil Ethanol Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
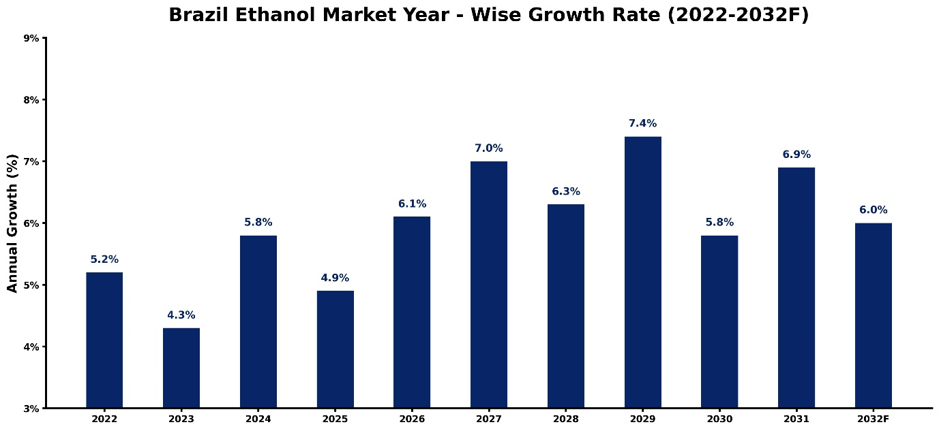
The following table presents the estimated annual growth rate for each year together with the principal factor influencing market performance. The values are intended to highlight year-specific drivers rather than to provide a direct comparison between individual years.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 5.2% | Post-pandemic mobility recovery lifted fuel demand, while temporary state fuel tax caps in mid-2022 improved ethanol’s pump competitiveness. |
| 2023 | 4.3% | A large corn and cane crop pushed ethanol prices lower, compressing mill revenues even as sales volumes remained healthy. |
| 2024 | 5.8% | Strong flex-fuel vehicle sales and improved hydrous ethanol price competitiveness against gasoline supported higher consumption through the year. |
| 2025 | 4.9% | The August 2025 shift to E30 blending added volume, drought and fire damage to cane after 2024 moderated growth. |
| 2026 | 6.1% | Commissioning of new corn distilleries in the Centre-West is expected to add supply and lift volumes. |
| 2027 | 7% | Sustainable aviation fuel obligations are scheduled to begin, creating a new premium outlet for low-carbon ethanol producers. |
| 2028 | 6.3% | Growth is expected to ease as ethanol price corrections and higher freight costs reduce mill margins. |
| 2029 | 7.4% | Second-generation plants are expected to reach commercial scale, adding output from existing cane without new land and lifting overall yields. |
| 2030 | 5.8% | Rising electric vehicle penetration is expected to temper gasoline blend demand and slow growth in pump consumption. |
| 2031 | 6.9% | Rising export demand from markets with low-carbon fuel standards is expected to restore momentum for Brazilian producers. |
| 2032 | 6% | A larger market base and maturing blending levels are expected to moderate growth towards the end of the forecast period. |
Brazil Ethanol Market Synopsis
The Brazil Ethanol Market is expected to gain momentum, supported by rising demand for renewable transportation fuels, mandatory gasoline blending and expanding industrial applications. Ethanol produced from sugarcane, corn, molasses and second-generation feedstocks serves fuel, industrial solvent, beverage, disinfectant and personal care manufacturing. Brazil's large flex-fuel vehicle fleet provides a substantial domestic consumption base, while new distilleries across Mato Grosso and Goiás are expanding production capacity and diversifying feedstock availability. Established integrated mills in São Paulo and Minas Gerais continue to strengthen supply volumes and export capabilities. Government biofuel policies, investments in distillery infrastructure and increasing demand for high-purity ethanol are further supporting market development.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Large flex-fuel vehicle fleet | Driver | High | Fuel & Fuel Additives |
| Higher mandatory gasoline blending | Driver | High | Denatured |
| Second-generation commercial plants at cane mills | Opportunity | High | Second Generation |
| Low-carbon ethanol exports to regulated fuel markets | Opportunity | Medium | Sugar & Molasses Based |
| Weather-driven cane yield volatility | Restraint | High | Sugar & Molasses Based |
| Pump-price parity with gasoline | Restraint | Medium | Fuel & Fuel Additives |
| Distance between inland plants and export terminals | Challenge | Medium | Grained Based |
| Traceability requirements in export markets | Challenge | Medium | Non-Denatured |
Evaluation of Drivers in the Brazil Ethanol Market (2026–2032)
Below mentioned are some major drivers and their influence on the market dynamics:
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Large flex-fuel vehicle fleet | Fuel & Fuel Additives | Flex-fuel engines let owners switch between gasoline and hydrous ethanol at the pump, so price parity moves volumes directly, and the fleet exceeds 30 million vehicles. |
| Higher gasoline blending requirement | Denatured | Each increase in the mandatory blend lifts anhydrous ethanol use per litre of gasoline sold, and the move from 27 to 30 percent in August 2025 added structural volume. |
| Expansion of corn-based capacity in Mato Grosso | Grained Based | Corn distilleries run on a different crop cycle from cane, adding supply outside the cane harvest, and corn now supplies roughly a fifth of national ethanol output. |
| Second-generation commercial plants | Second Generation | Converting bagasse and straw lifts ethanol output per hectare without new land, and Raízen has commissioned units at its Costa Pinto and Bonfim mills. |
| Growth of beauty and personal care manufacturing | Personal Care | Brazil ranks among the four largest beauty and personal care markets globally, and these products rely on high-purity ethanol as a solvent and carrier. |
Brazil’s integrated agro-industrial base supports sustained expansion, with more than 600 million tonnes of cane processed annually, giving mills a deep feedstock pool and the ability to adjust their production mix as prices move. Cogeneration from bagasse allows plants to sell surplus electricity, improving project returns and encouraging reinvestment in distillation capacity. Rising private and foreign investment in new distilleries and blending facilities is widening supply and shortening delivery times to consumption centres. Advances in fermentation yields, precision planting and mechanised harvesting are lowering unit costs, while growing global demand for lower-carbon liquid energy is strengthening export interest in Brazilian volumes.
Evaluation of Restraints in the Brazil Ethanol Market
Below mentioned are some major restraints and their influence on the market dynamics:
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Weather-driven cane yield volatility | Sugar & Molasses Based | Drought and fires in São Paulo state during August and September 2024 damaged cane fields, lowering yields and tightening feedstock for the following season. |
| Pump-price parity with gasoline | Fuel & Fuel Additives | Hydrous ethanol is generally competitive only when priced below roughly 70 percent of gasoline, so Petrobras pricing decisions can quickly reduce consumer demand. |
| Sugar and ethanol allocation decisions | Industrial Solvent | Mills direct close to half of crushed cane to sugar when sugar prices are favourable, reducing ethanol available to industrial buyers. |
| Agroecological zoning limits on cane expansion | Sugar & Molasses Based | Zoning rules bar cane planting in the Amazon, Pantanal and Upper Paraguay Basin, so further growth depends on pasture conversion and yield gains. |
| High capital cost of second-generation processing | Second Generation | Enzymatic hydrolysis and pre-treatment need far higher investment per litre of capacity than conventional distilleries, which slows adoption at smaller mills. |
Brazil Ethanol Market Challenges
Although the Brazil Ethanol Market Growth is projected to witness development, several challenges could influence its development trajectory. Local electric vehicle assembly, including BYD’s Camaçari plant in Bahia with initial capacity of 150,000 vehicles a year, could gradually erode gasoline-blend volumes and weaken pump-price competitiveness. European deforestation due-diligence rules applicable from December 2026 will oblige exporters to document land-use history, a burden for mid-sized mills lacking traceability systems. Inland distilleries in Mato Grosso sit more than 2,000 kilometres from the Santos export terminal, so road-heavy freight erodes their margins. Interior states also face a shortage of trained process engineers, which delays commissioning of new capacity.
Trends in the Brazil Ethanol Market
Significant trends driving the Brazil Ethanol Industry are presented below:
- Transition from Fossil Jet Fuel to Ethanol-Based Aviation Fuel: Brazil is preparing for sustainable aviation fuel obligations that begin in 2027 under the Fuel of the Future Law, and ethanol-to-jet routes are drawing interest from airlines and fuel suppliers. Mills with certified low carbon intensity are positioning to supply this outlet, which offers premium pricing and diversifies sales beyond road fuel. Conversion technology and certification providers stand to benefit.
- Carbon-Credit Value Prioritised over Volume Expansion: Mills are increasingly optimising for carbon intensity due to RenovaBio decarbonisation credits, each representing one tonne of avoided emissions, trade on the São Paulo stock exchange. Producers with efficient agriculture and bagasse cogeneration earn more credits per litre, redirecting investment toward certification and efficiency rather than added crushing volume. Distributors and buyers must now factor credit costs into pricing.
- Shift from Seasonal Cane-Only Operation to Year-Round Multi-Feedstock Plants: Distilleries in Centre-West Brazil are adding corn lines to cane mills and building standalone corn plants so that output can continue beyond the April to November cane harvest. This smooths supply and storage needs, gives distributors steadier delivery schedules, and creates steady orders for equipment suppliers of dryers, fermenters and distillation columns.
Investment Opportunities in the Brazil Ethanol Market
Strategic investment opportunities in the Brazil Ethanol Market include the following:
- Second-Generation Ethanol Plants at Existing Cane Mills: Bagasse and straw already sit at mill gates, and commercial units at Raízen’s mills have proven the process, so incremental capacity is now bankable. Investors can finance enzyme-based conversion modules, pre-treatment equipment and enzyme supply contracts, entering through joint ventures with established mills in São Paulo and Goiás and securing low-carbon certification to earn premium credits.
- Ethanol Storage and Export Logistics in the Centre-West and Santos Corridor: Production is moving inland while consumption and exports remain coastal, leaving a gap in tankage and transfer capacity. Opportunities include bulk storage tanks, rail and truck loading terminals and port berths near Santos and Paranaguá, entered through build-operate agreements with trading groups or concession partnerships with port authorities.
- High-Purity Ethanol for Cosmetics, Beverage and Pharmaceutical Use: Premium grades command higher margins than fuel-grade product, and Brazilian manufacturers need consistent supply. Investors can build rectification and dehydration units producing neutral-spirit and pharmaceutical-grade ethanol close to São Paulo’s industrial belt, entering through long-term offtake agreements with manufacturers, ANVISA-compliant quality certification and partnerships with established distillers.
Leading Players in Brazil Ethanol Market
Below is a curated list of leading companies in the Brazil Ethanol Market:
1. Raízen S.A.
|
Company Name |
Raízen S.A. |
|
Established Year |
2011 |
|
Headquarters |
São Paulo, Brazil |
|
Official Website |
Raízen S.A. (a joint venture between Shell and Cosan) is a global leader in sugarcane-based bioenergy, operating integrated bio-refineries to produce 1G and 2G ethanol, sugar, bio-electricity from bagasse, and managing an extensive fuel distribution network across Brazil.
2. Vibra Energia S.A.
|
Company Name |
Vibra Energia S.A. |
|
Established Year |
1971 |
|
Headquarters |
Rio de Janeiro, Brazil |
|
Official Website |
Vibra Energia (formerly Petrobras Distribuidora) is one of Brazil's largest fuel and hydrated ethanol distributors, managing nationwide logistics, commercial trading platforms, and retail station networks to supply renewable biofuels and traditional fuels.
3. Ipiranga Produtos de Petróleo S.A. (Ultrapar Group)
|
Company Name |
Ipiranga Produtos de Petróleo S.A. (Ultrapar Group) |
|
Established Year |
1937 |
|
Headquarters |
Porto Alegre, Rio Grande do Sul, Brazil |
|
Official Website |
- |
Ipiranga, operating as a subsidiary of Ultrapar, is a major Brazilian fuel distributor holding a significant market share in bioethanol and biodiesel logistics, retail service stations, and B2B fuel distribution solutions.
4. BP Bunge Bioenergia S.A.
|
Company Name |
BP Bunge Bioenergia S.A. |
|
Established Year |
2019 |
|
Headquarters |
São Paulo, Brazil |
|
Official Website |
- |
BP Bunge Bioenergia is a major joint venture operating 11 industrial mills across Brazil, specializing in large-scale sugarcane cultivation, bioethanol production, sugar refining, and renewable electricity generation from biomass.
5. Atvos Agroindustrial S.A.
|
Company Name |
Atvos Agroindustrial S.A. |
|
Established Year |
2007 |
|
Headquarters |
São Paulo, Brazil |
|
Official Website |
Atvos is a major bioenergy producer in Brazil, operating multiple sugarcane processing units that manufacture anhydrous and hydrated bioethanol, clean electricity, and agricultural by-products for commercial energy markets.
Government Initiatives in the Brazil Ethanol Market
The Brazil’s Fuel of the Future Law (Law 14,993), enacted in October 2024, sets the national framework for low-carbon fuels and widens the permitted gasoline ethanol blend to between 22 and 35 percent, with the blend raised to 30 percent from August 2025. The law also establishes a regulatory basis for carbon capture and storage, linking ethanol production to national decarbonisation goals.
RenovaBio, created by Law 13,576 in 2017 and operational since 2020, sets annual decarbonisation targets for fuel distributors, who comply by purchasing credits issued to certified producers. The National Agency of Petroleum, Natural Gas and Biofuels certifies producers and audits compliance, while the Mover programme, launched in 2024 with about BRL 19.3 billion in tax credits through 2028, ties vehicle incentives to lifecycle emissions.
Future Insights of the Brazil Ethanol Market
The Brazil Ethanol Market is expected to gain momentum as several developments support wider use of low-carbon liquid fuels. The Brazilian government’s climate action commitment calls for reducing emissions by 59% to 67% through 2035. This will help maintain the biofuel policies in accordance with decarbonisation objectives. Capturing carbon from fermentation feedstocks will enable the production of high-quality low-carbon volumes which will attract foreign buyers. The improvements in precision farming and fermentation technology will lead to higher yields on a hectare basis as well as reduce the cost per unit of biofuel produced.
Market Segmentation Analysis
The report offers a comprehensive study of the market across its key segments. The chart below highlights the leading segment by market share in 2025 and the fastest-growing segment by CAGR over 2026–2032, followed by a detailed analysis of each segment.
By Purity – Denatured Leads, Non-Denatured Expected to Grow Fastest
According to Ravi Bhandari, Research Head at 6Wresearch, Denatured ethanol was the leader in 2025, accounted for 58% of the market volume, owing to the mandatory blending requirements of gasoline, thus driving substantial and consistent offtake of the product by distributors to fuel stations in São Paulo, Minas Gerais, and Goiás. Meanwhile, non-denatured ethanol is forecast to be the fastest growing segment with a CAGR of approximately 7.0% during 2026-2032 due to increasing demand from cosmetics, beverage, and pharmaceutical companies for high purity products.
By Sources – Sugar & Molasses Based Dominant, Second Generation Expected to Grow Fastest
Sugar & Molasses Based ethanol captured about 78% of the market share in 2025, backed by the cane belt of São Paulo, where mills produce sugar or ethanol depending on their price ratio. On the other hand, Second generation ethanol is expected to have the highest CAGR of around 14.5% during 2026-2032 owing to bagasse and straw conversion plants coming up in established mills.
By Application – Fuel & Fuel Additives Leads, Personal Care Expected to Grow Fastest
Accounted for 66% of the market in 2025, Fuel & Fuel Additives benefited from the pump-price competitiveness of hydrous ethanol in the Centre-South and the scale of Brazil’s national fuel distribution network. On the contrary, Personal Care is expected to expand fastest at a CAGR of about 7.1% over 2026–2032, as Brazil’s large beauty and cosmetics industry increases purchases of high-purity ethanol for fragrances and skincare formulations.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- Brazil Ethanol Market Outlook
- Market Size of Brazil Ethanol Market, 2025
- Forecast of Brazil Ethanol Market, 2032
- Historical Data and Forecast of Ethanol Revenues & Volume for the Period 2022-2032
- Brazil Ethanol Market Trend Evolution
- Brazil Ethanol Market Drivers and Challenges
- Ethanol Price Trends
- Ethanol Porter’s Five Forces
- Ethanol Industry Life Cycle
- Historical Data and Forecast of Brazil Ethanol Market Revenues & Volume By Purity for the Period 2022-2032
- Historical Data and Forecast of Brazil Ethanol Market Revenues & Volume By Denatured for the Period 2022-2032
- Historical Data and Forecast of Brazil Ethanol Market Revenues & Volume By Non-Denatured for the Period 2022-2032
- Historical Data and Forecast of Brazil Ethanol Market Revenues & Volume By Sources for the Period 2022-2032
- Historical Data and Forecast of Brazil Ethanol Market Revenues & Volume By Sugar & Molasses Based for the Period 2022-2032
- Historical Data and Forecast of Brazil Ethanol Market Revenues & Volume By Grained Based for the Period 2022-2032
- Historical Data and Forecast of Brazil Ethanol Market Revenues & Volume By Second Generation for the Period 2022-2032
- Historical Data and Forecast of Brazil Ethanol Market Revenues & Volume By Application for the Period 2022-2032
- Historical Data and Forecast of Brazil Ethanol Market Revenues & Volume By Industrial Solvent for the Period 2022-2032
- Historical Data and Forecast of Brazil Ethanol Market Revenues & Volume By Fuel & Fuel Additives for the Period 2022-2032
- Historical Data and Forecast of Brazil Ethanol Market Revenues & Volume By Beverages for the Period 2022-2032
- Historical Data and Forecast of Brazil Ethanol Market Revenues & Volume By Disinfectant for the Period 2022-2032
- Historical Data and Forecast of Brazil Ethanol Market Revenues & Volume By Personal Care for the Period 2022-2032
- Historical Data and Forecast of Brazil Ethanol Market Revenues & Volume By Others for the Period 2022-2032
- Ethanol Import Export Trade Statistics
- Market Opportunity Assessment By Purity
- Market Opportunity Assessment By Sources
- Market Opportunity Assessment By Application
- Ethanol Top Companies Market Share
- Ethanol Competitive Benchmarking By Technical and Operational Parameters
- Ethanol Company Profiles
- Ethanol Key Strategic Recommendations
Market Scope and Segmentation
The report provides a detailed analysis of the following market segments:
By Purity
- Denatured
- Non-Denatured
By Sources
- Sugar & Molasses Based
- Grained Based
- Second Generation
By Application
- Industrial Solvent
- Fuel & Fuel Additives
- Beverages
- Disinfectant
- Personal Care
- Others































