Chile Cyber Security Market (2026-2032) Outlook | Share, Trends, Revenue, Companies, Forecast, Analysis, Size, Industry, Value & Growth
Market Forecast By Component (Software, Hardware, Services), By Software (IAM, Antivirus/Antimalware, Log Management and SIEM, Encryption and Tokenization, Compliance and Policy Management, Patch Management, Other Software), By Security Type (Network Security, Cloud Security, Application Security, Endpoint and IoT Security), By Deployment Mode (Cloud, On-premises), By Organization Size (Large Enterprises, SMEs), By Vertical (Aerospace and Defense, BFSI, IT and ITeS, Telecommunication, Energy and Utilities, Retail and eCommerce, Healthcare, Transportation and Logistics) And Competitive Landscape
| Product Code: ETC4385409 | Publication Date: Jul 2023 | Updated Date: Jul 2026 | Product Type: Report | |
| Publisher: 6Wresearch | Author: Summon Dutta | No. of Pages: 85 | No. of Figures: 45 | No. of Tables: 25 |
Chile Cyber Security Market Size & Growth Rate (2026-2032)
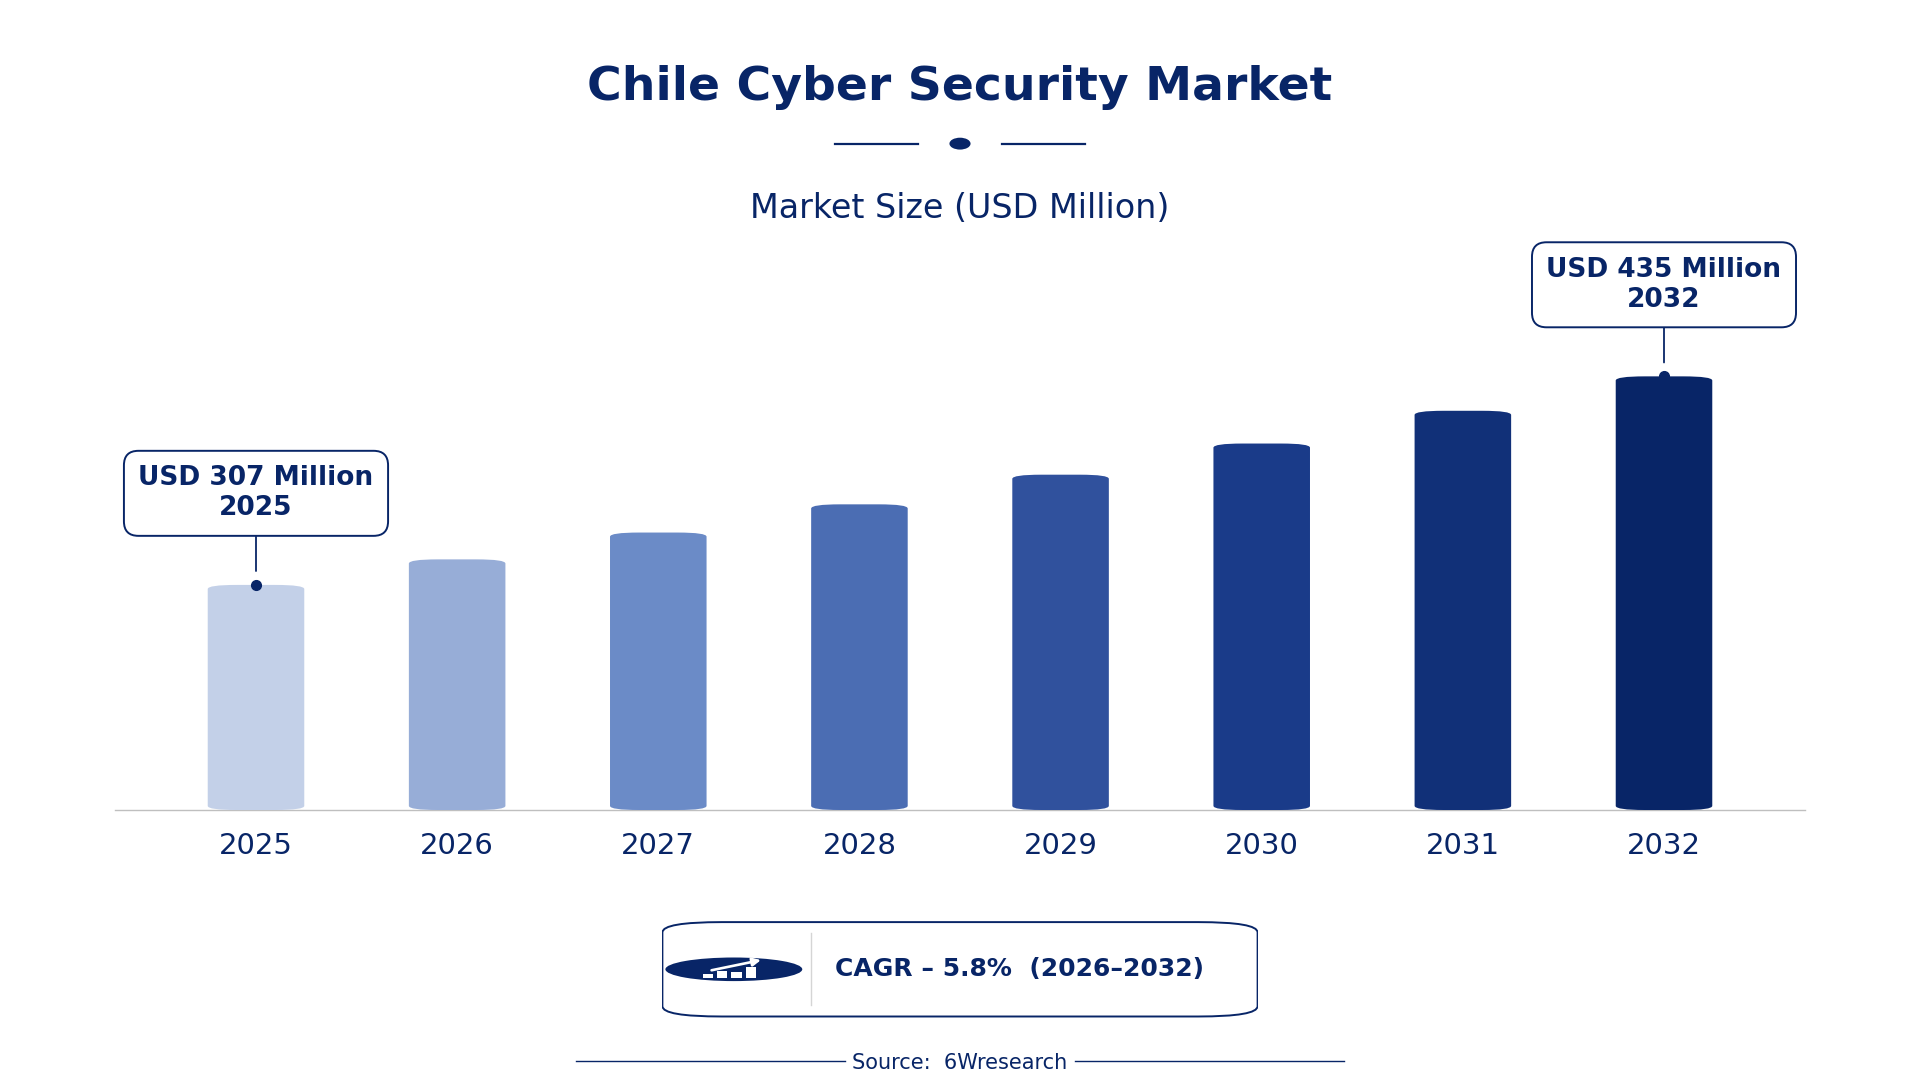
The Chile Cyber Security Market was estimated at USD 307 Million in 2025 and is projected to reach USD 435 Million by 2032, growing at a CAGR of 5.8% from 2026 to 2032.
Chile Cyber Security Market Synopsis
The Chile cyber security market is currently witnessing robust growth, fueled by increasing digitalization and heightened awareness of cyber threats across sectors. As businesses shift towards online platforms and digital services, protecting sensitive data has become a top priority, leading to substantial investments in cybersecurity solutions.
Government initiatives and regulatory frameworks have further catalyzed the demand for effective cybersecurity measures. Companies are increasingly recognizing the value of advanced security tools, such as threat intelligence and data encryption, to mitigate risks associated with cyber incidents. This evolving landscape presents a fertile ground for innovation and investment.
Chile Cyber Security Market Year-wise Growth Rate and Key Drivers
This graph illustrates the annual growth rates of the Chile Cyber Security Market from 2021 to 2032, highlighting a steady upward trajectory and projected expansion over the forecast period.
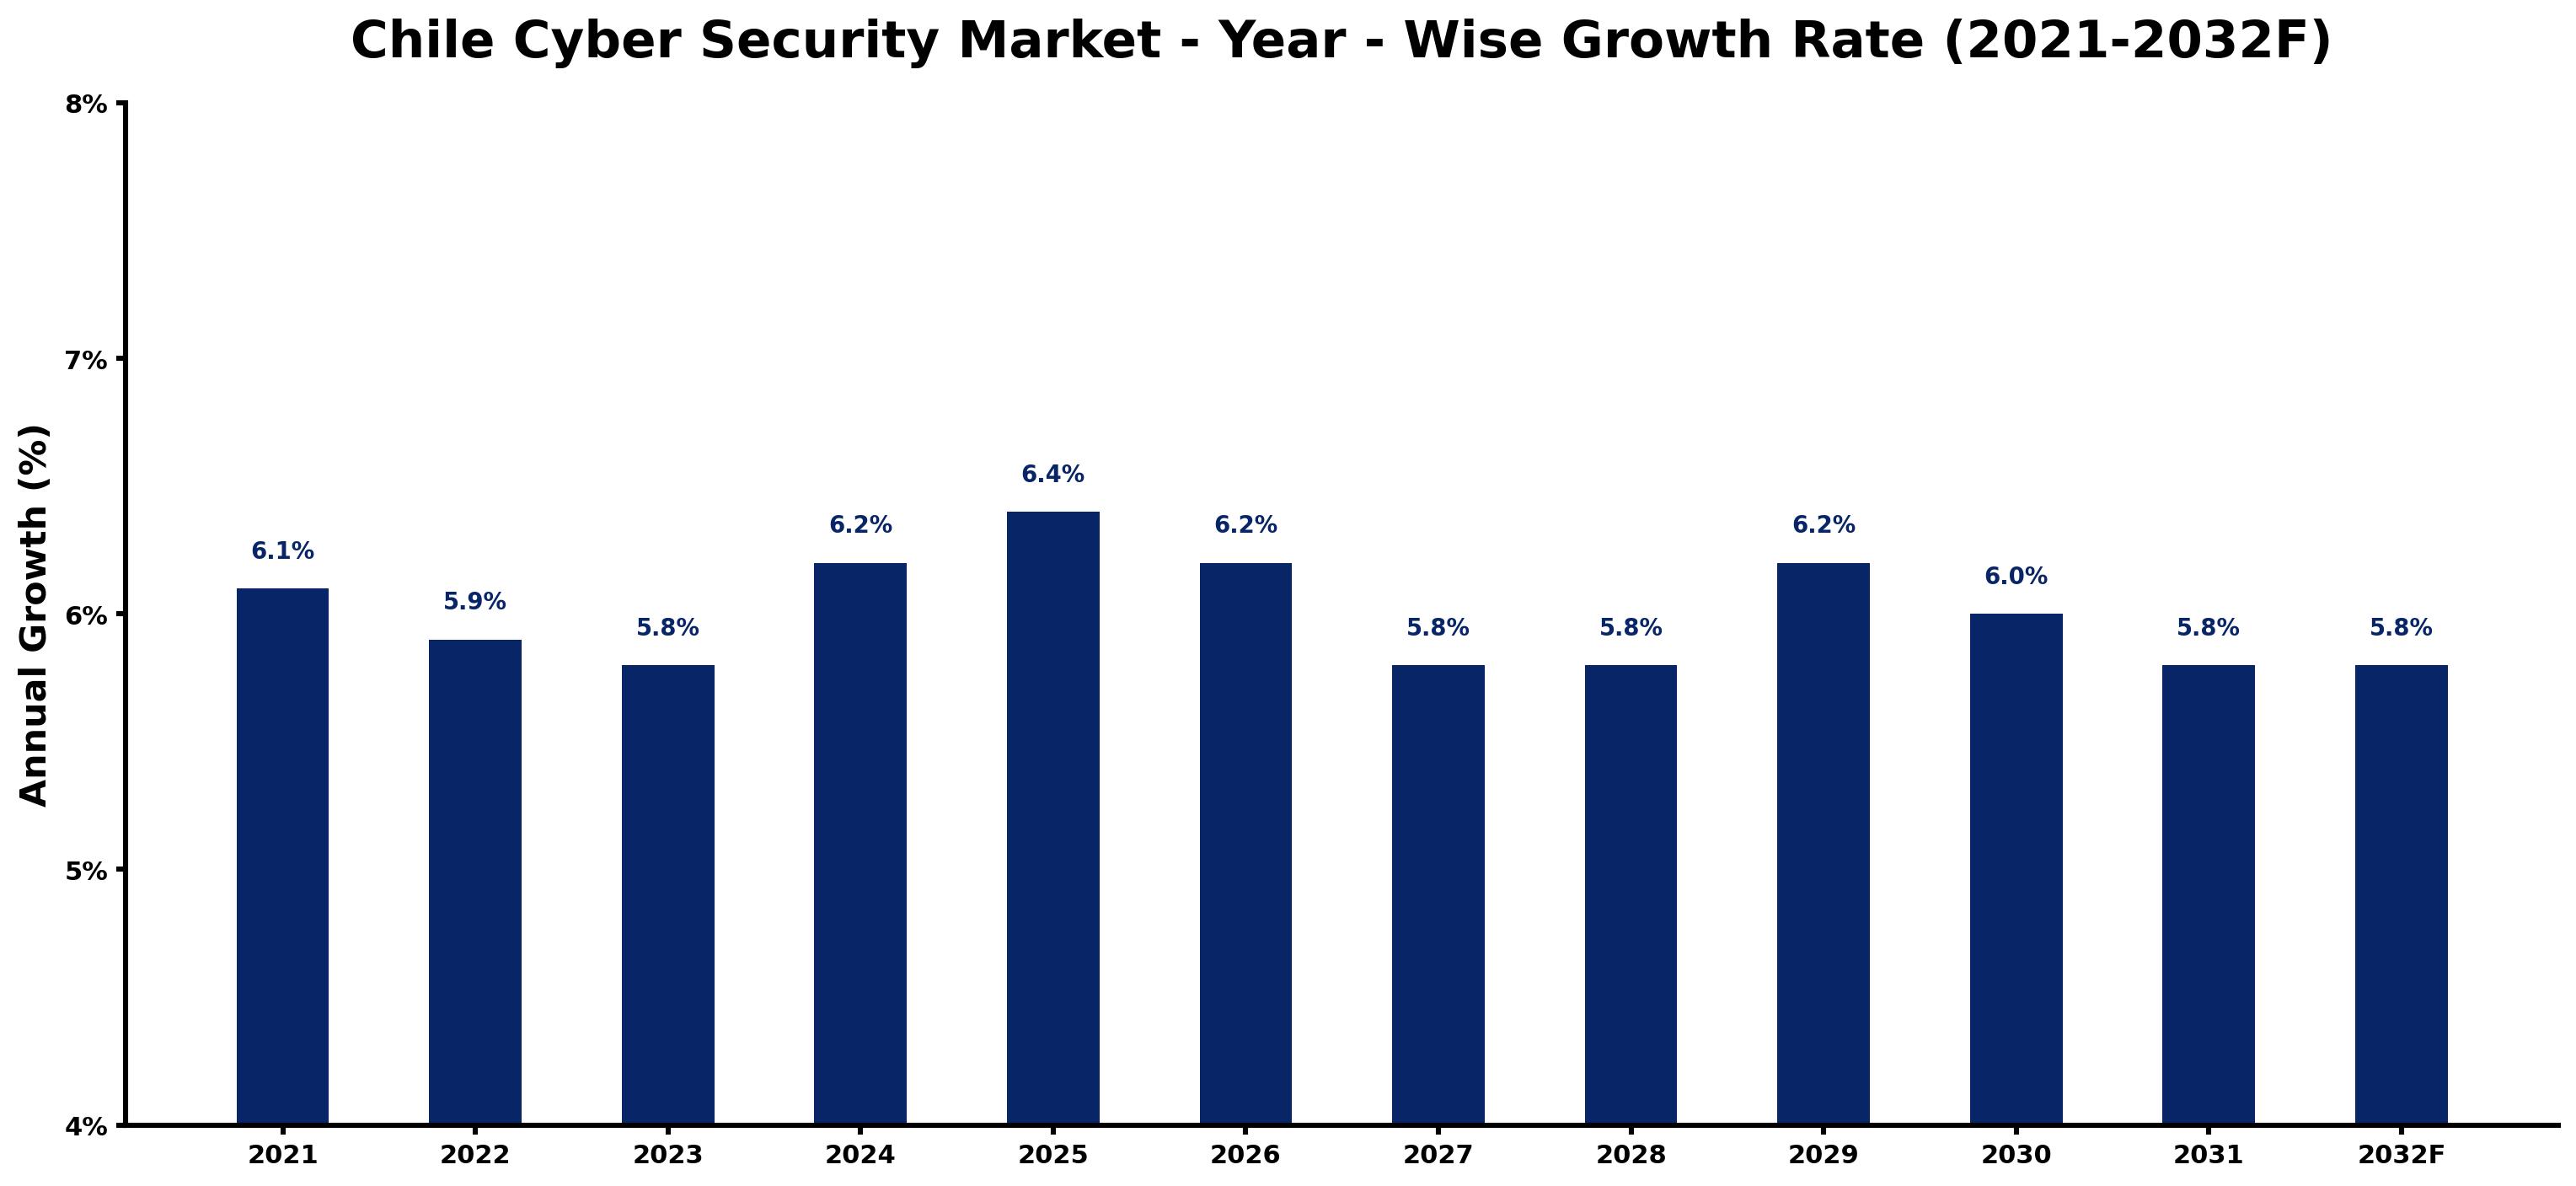
The table below presents the year‑wise growth rates along with the key drivers influencing the market
| Year | Growth Rate | Major Drivers |
| 2021 | 6.1% | Increased government cybersecurity initiatives post-data breaches |
| 2022 | 5.9% | Growing adoption of digital banking security measures |
| 2023 | 5.8% | Rise in e-commerce leading to heightened cyber threats |
| 2024 | 6.2% | Enhanced regulatory frameworks by Chilean Cybersecurity Agency |
| 2025 | 6.4% | Corporate investment in cybersecurity training programs |
| 2026 | 6.2% | Demand for remote work security solutions increasing |
| 2027 | 5.8% | Emergence of local cybersecurity startups driving innovation |
| 2028 | 5.8% | Implementation of new data protection laws enhances compliance |
| 2029 | 6.2% | Regional partnerships for cybersecurity threat intelligence sharing |
| 2030 | 6.0% | Adoption of advanced encryption technologies by enterprises |
| 2031 | 5.8% | Increased awareness of cybersecurity risks among consumers |
| 2032 | 5.8% | Growing focus on cybersecurity in educational institutions |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
Chile Cyber Security Market Key Takeaways
Below are some of the specific key takeaways from the market, including:
- The demand for advanced threat detection solutions is rising, as organizations seek to strengthen their defenses against cyber attacks.
- Cloud security is a focal point, reflecting the growing adoption of cloud services by businesses in Chile.
- Investment in security awareness training programs is increasing, aimed at minimizing risks stemming from human error.
- Regulatory compliance efforts are aligning organizational security strategies with local data protection laws.
- The expansion of e-commerce and online banking is driving the need for robust cybersecurity frameworks.
Evaluation of Restraints in Chile Cyber Security Market
Despite the growth trajectory, several constraints are hindering the Chile cyber security market. One of the most pressing issues is the evolving sophistication of cyber threats, which are becoming increasingly difficult to counteract. Organizations often struggle to keep pace with the rapid technological advancements that cyber criminals utilize to launch targeted attacks.
Additionally, there is a noticeable shortage of skilled cybersecurity professionals in Chile, creating a significant expertise gap that organizations find hard to bridge. Compounding these challenges, many businesses remain unaware of the critical importance of investing in robust cybersecurity measures. This lack of understanding hinders the widespread adoption of effective security practices, exposing them to potential risks.
Chile Cyber Security Market Trends
Current trends in the Chile cyber security market reflect a clear shift toward proactive security measures. Organizations are increasingly prioritizing advanced threat detection and response capabilities to combat evolving threats. This heightened demand for sophisticated cybersecurity solutions highlights the urgent need for innovation and adaptation to new attack vectors.
The emphasis on cloud security continues to grow, driven by widespread cloud adoption across various industries. In parallel, investments in security awareness training programs are gaining traction, as businesses seek to empower employees with the knowledge necessary to recognize and mitigate security risks. Regulatory compliance also plays a critical role, guiding organizations to align their strategies with established data protection laws.
Chile Cyber Security Market Opportunities
Opportunities in the Chile cyber security market are abundant, particularly as digital transformation accelerates across industries. Key areas for investment include advanced cybersecurity software solutions, such as threat detection, prevention tools, and encryption technologies. There is also a growing demand for consulting services focusing on cybersecurity strategy development and risk assessment.
With governmental support aimed at enhancing cybersecurity infrastructure, the landscape is ripe for investment in startups and established companies within the sector. Partnerships with local firms, technology transfers, and collaborations with academic institutions can further fuel growth in this space, ensuring that organizations are equipped to handle emerging threats.
Government Initiatives in the Chile Cyber Security Market
Government policy in Chile is taking a proactive stance to enhance cybersecurity measures, reflecting a commitment to safeguard the nation's digital infrastructure. With initiatives aimed at improving coordination between public and private sectors, these policies are crucial for fostering a culture of cyber resilience across industries.
- The National Cybersecurity Policy, launched in 2017, focuses on strengthening national cyber defense systems and enhancing public awareness of cyber threats.
- The National Cybersecurity Center (CNC) serves as the primary entity for coordinating cybersecurity efforts and providing technical guidance.
- The Cybersecurity Law enacted in 2017 mandates critical infrastructure operators to adopt specific cybersecurity measures and report incidents promptly.
- Currently, a public awareness campaign is underway, aiming to educate businesses and citizens about cybersecurity best practices.
- A planned initiative to develop a national digital infrastructure upgrade is set to improve the overall cyber resilience of public services by 2027.
Future Insights of the Chile Cyber Security Market
Looking ahead to 2026-2032, the Chile cyber security market is expected to maintain its growth momentum as businesses prioritize cybersecurity amid escalating threats. The integration of advanced technologies, such as artificial intelligence and machine learning, will revolutionize threat detection and response strategies.
As digitalization continues to shape the business environment, organizations will be compelled to adapt their cybersecurity frameworks. The ongoing support from the government and regulatory bodies will further bolster market expansion, creating a favorable environment for both existing firms and new entrants in the cybersecurity space.
Chile Cyber Security Market Latest Developments
Recent activity in the Chile cyber security market indicates a heightened focus on enhancing security capabilities. Over the past year, there has been a surge in initiatives aimed at improving cybersecurity frameworks across various sectors.
- A major technology vendor announced the launch of a new threat intelligence platform in early 2025, designed to enhance real-time threat monitoring capabilities for businesses.
- In mid-2025, a regional operator initiated a comprehensive security audit program across its infrastructure to identify and mitigate vulnerabilities.
- By late 2025, a significant collaboration between public and private sectors is expected to roll out a national cybersecurity training program for employees at critical infrastructure organizations.
- Additionally, an upcoming project planned for Q3 2026 will focus on integrating AI-driven solutions into existing security frameworks to improve response times to cyber incidents.
Chile Cyber Security Market - Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year: 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- Chile Cyber Security Market Outlook
- Market Size of Chile Cyber Security Market, 2025
- Forecast of Chile Cyber Security Market, 2032
- Historical Data and Forecast of Chile Cyber Security Revenues & Volume for the Period 2022-2032F
- Chile Cyber Security Market Trend Evolution
- Chile Cyber Security Market Drivers and Challenges
- Chile Cyber Security Price Trends
- Chile Cyber Security Porter's Five Forces
- Chile Cyber Security Industry Life Cycle
- Historical Data and Forecast of Chile Cyber Security Market Revenues & Volume By Component for the Period 2022-2032F
- Historical Data and Forecast of Chile Cyber Security Market Revenues & Volume By Software for the Period 2022-2032F
- Historical Data and Forecast of Chile Cyber Security Market Revenues & Volume By Hardware for the Period 2022-2032F
- Historical Data and Forecast of Chile Cyber Security Market Revenues & Volume By Services for the Period 2022-2032F
- Historical Data and Forecast of Chile Cyber Security Market Revenues & Volume By Software for the Period 2022-2032F
- Historical Data and Forecast of Chile Cyber Security Market Revenues & Volume By IAM for the Period 2022-2032F
- Historical Data and Forecast of Chile Cyber Security Market Revenues & Volume By Antivirus/Antimalware for the Period 2022-2032F
- Historical Data and Forecast of Chile Cyber Security Market Revenues & Volume By Log Management and SIEM for the Period 2022-2032F
- Historical Data and Forecast of Chile Cyber Security Market Revenues & Volume By Encryption and Tokenization for the Period 2022-2032F
- Historical Data and Forecast of Chile Cyber Security Market Revenues & Volume By Compliance and Policy Management for the Period 2022-2032F
- Historical Data and Forecast of Chile Cyber Security Market Revenues & Volume By Patch Management for the Period 2022-2032F
- Historical Data and Forecast of Chile Cyber Security Market Revenues & Volume By Other Software for the Period 2022-2032F
- Historical Data and Forecast of Chile Cyber Security Market Revenues & Volume By Security Type for the Period 2022-2032F
- Historical Data and Forecast of Chile Cyber Security Market Revenues & Volume By Network Security for the Period 2022-2032F
- Historical Data and Forecast of Chile Cyber Security Market Revenues & Volume By Cloud Security for the Period 2022-2032F
- Historical Data and Forecast of Chile Cyber Security Market Revenues & Volume By Application Security for the Period 2022-2032F
- Historical Data and Forecast of Chile Cyber Security Market Revenues & Volume By Endpoint and IoT Security for the Period 2022-2032F
- Historical Data and Forecast of Chile Cyber Security Market Revenues & Volume By Deployment Mode for the Period 2022-2032F
- Historical Data and Forecast of Chile Cyber Security Market Revenues & Volume By Cloud for the Period 2022-2032F
- Historical Data and Forecast of Chile Cyber Security Market Revenues & Volume By On-premises for the Period 2022-2032F
- Historical Data and Forecast of Chile Cyber Security Market Revenues & Volume By Organization Size for the Period 2022-2032F
- Historical Data and Forecast of Chile Cyber Security Market Revenues & Volume By Large Enterprises for the Period 2022-2032F
- Historical Data and Forecast of Chile Cyber Security Market Revenues & Volume By SMEs for the Period 2022-2032F
- Historical Data and Forecast of Chile Cyber Security Market Revenues & Volume By Vertical for the Period 2022-2032F
- Historical Data and Forecast of Chile Cyber Security Market Revenues & Volume By Aerospace and Defense for the Period 2022-2032F
- Historical Data and Forecast of Chile Cyber Security Market Revenues & Volume By BFSI for the Period 2022-2032F
- Historical Data and Forecast of Chile Cyber Security Market Revenues & Volume By IT and ITeS for the Period 2022-2032F
- Historical Data and Forecast of Chile Cyber Security Market Revenues & Volume By Telecommunication for the Period 2022-2032F
- Historical Data and Forecast of Chile Cyber Security Market Revenues & Volume By Energy and Utilities for the Period 2022-2032F
- Historical Data and Forecast of Chile Cyber Security Market Revenues & Volume By Retail and eCommerce for the Period 2022-2032F
- Historical Data and Forecast of Chile Cyber Security Market Revenues & Volume By Healthcare for the Period 2022-2032F
- Historical Data and Forecast of Chile Cyber Security Market Revenues & Volume By Transportation and Logistics for the Period 2022-2032F
- Chile Cyber Security Import Export Trade Statistics
- Market Opportunity Assessment By Component
- Market Opportunity Assessment By Software
- Market Opportunity Assessment By Security Type
- Market Opportunity Assessment By Deployment Mode
- Market Opportunity Assessment By Organization Size
- Market Opportunity Assessment By Vertical
- Chile Cyber Security Top Companies Market Share
- Chile Cyber Security Competitive Benchmarking By Technical and Operational Parameters
- Chile Cyber Security Company Profiles
- Chile Cyber Security Key Strategic Recommendations
Frequently Asked Questions About the Market Study (FAQs):
The growth in the Chile cyber security market is primarily driven by increasing digitalization and the rise in cyber threats. As more businesses transition online, the need for effective cybersecurity measures becomes critical.
The Chile Cyber Security Market was estimated at USD 307 Million in 2025 and is projected to reach USD 435 Million by 2032, growing at a CAGR of 5.8% from 2026 to 2032.
The Chilean government has launched the National Cybersecurity Policy, established the National Cybersecurity Center, and enacted the Cybersecurity Law to promote better security practices among businesses and critical infrastructure operators.
Major challenges include the increasing sophistication of cyber threats, a shortage of skilled professionals, and a lack of awareness among businesses regarding the importance of cybersecurity investments.
Trends include the rising demand for advanced threat detection solutions, a strong emphasis on cloud security, and increased investment in security awareness training programs for employees.
There are significant investment opportunities in cybersecurity software solutions, consulting services, and partnerships with local firms, especially as the government focuses on enhancing national cybersecurity measures.
6Wresearch actively monitors the Chile Cyber Security Market and publishes its comprehensive annual report, highlighting emerging trends, growth drivers, revenue analysis, and forecast outlook. Our insights help businesses to make data-backed strategic decisions with ongoing market dynamics. Our analysts track relevent industries related to the Chile Cyber Security Market, allowing our clients with actionable intelligence and reliable forecasts tailored to emerging regional needs.
Yes, we provide customisation as per your requirements. To learn more, feel free to contact us on sales@6wresearch.com
1 Executive Summary |
2 Introduction |
2.1 Key Highlights of the Report |
2.2 Report Description |
2.3 Market Scope & Segmentation |
2.4 Research Methodology |
2.5 Assumptions |
3 Chile Cyber Security Market Overview |
3.1 Chile Country Macro Economic Indicators |
3.2 Chile Cyber Security Market Revenues & Volume, 2022 & 2032F |
3.3 Chile Cyber Security Market - Industry Life Cycle |
3.4 Chile Cyber Security Market - Porter's Five Forces |
3.5 Chile Cyber Security Market Revenues & Volume Share, By Component, 2022 & 2032F |
3.6 Chile Cyber Security Market Revenues & Volume Share, By Software, 2022 & 2032F |
3.7 Chile Cyber Security Market Revenues & Volume Share, By Security Type, 2022 & 2032F |
3.8 Chile Cyber Security Market Revenues & Volume Share, By Deployment Mode, 2022 & 2032F |
3.9 Chile Cyber Security Market Revenues & Volume Share, By Organization Size, 2022 & 2032F |
3.10 Chile Cyber Security Market Revenues & Volume Share, By Vertical, 2022 & 2032F |
4 Chile Cyber Security Market Dynamics |
4.1 Impact Analysis |
4.2 Market Drivers |
4.2.1 Increasing number of cyber attacks and data breaches in Chile |
4.2.2 Growing adoption of cloud services and IoT devices leading to higher cybersecurity risks |
4.2.3 Stringent government regulations and compliance requirements for data protection |
4.3 Market Restraints |
4.3.1 Lack of skilled cybersecurity professionals in Chile |
4.3.2 Limited awareness among small and medium-sized enterprises (SMEs) regarding cybersecurity importance |
5 Chile Cyber Security Market Trends |
6 Chile Cyber Security Market, By Types |
6.1 Chile Cyber Security Market, By Component |
6.1.1 Overview and Analysis |
6.1.2 Chile Cyber Security Market Revenues & Volume, By Component, 2022-2032F |
6.1.3 Chile Cyber Security Market Revenues & Volume, By Software, 2022-2032F |
6.1.4 Chile Cyber Security Market Revenues & Volume, By Hardware, 2022-2032F |
6.1.5 Chile Cyber Security Market Revenues & Volume, By Services, 2022-2032F |
6.2 Chile Cyber Security Market, By Software |
6.2.1 Overview and Analysis |
6.2.2 Chile Cyber Security Market Revenues & Volume, By IAM, 2022-2032F |
6.2.3 Chile Cyber Security Market Revenues & Volume, By Antivirus/Antimalware, 2022-2032F |
6.2.4 Chile Cyber Security Market Revenues & Volume, By Log Management and SIEM, 2022-2032F |
6.2.5 Chile Cyber Security Market Revenues & Volume, By Encryption and Tokenization, 2022-2032F |
6.2.6 Chile Cyber Security Market Revenues & Volume, By Compliance and Policy Management, 2022-2032F |
6.2.7 Chile Cyber Security Market Revenues & Volume, By Patch Management, 2022-2032F |
6.3 Chile Cyber Security Market, By Security Type |
6.3.1 Overview and Analysis |
6.3.2 Chile Cyber Security Market Revenues & Volume, By Network Security, 2022-2032F |
6.3.3 Chile Cyber Security Market Revenues & Volume, By Cloud Security, 2022-2032F |
6.3.4 Chile Cyber Security Market Revenues & Volume, By Application Security, 2022-2032F |
6.3.5 Chile Cyber Security Market Revenues & Volume, By Endpoint and IoT Security, 2022-2032F |
6.4 Chile Cyber Security Market, By Deployment Mode |
6.4.1 Overview and Analysis |
6.4.2 Chile Cyber Security Market Revenues & Volume, By Cloud, 2022-2032F |
6.4.3 Chile Cyber Security Market Revenues & Volume, By On-premises, 2022-2032F |
6.5 Chile Cyber Security Market, By Organization Size |
6.5.1 Overview and Analysis |
6.5.2 Chile Cyber Security Market Revenues & Volume, By Large Enterprises, 2022-2032F |
6.5.3 Chile Cyber Security Market Revenues & Volume, By SMEs, 2022-2032F |
6.6 Chile Cyber Security Market, By Vertical |
6.6.1 Overview and Analysis |
6.6.2 Chile Cyber Security Market Revenues & Volume, By Aerospace and Defense, 2022-2032F |
6.6.3 Chile Cyber Security Market Revenues & Volume, By BFSI, 2022-2032F |
6.6.4 Chile Cyber Security Market Revenues & Volume, By IT and ITeS, 2022-2032F |
6.6.5 Chile Cyber Security Market Revenues & Volume, By Telecommunication, 2022-2032F |
6.6.6 Chile Cyber Security Market Revenues & Volume, By Energy and Utilities, 2022-2032F |
6.6.7 Chile Cyber Security Market Revenues & Volume, By Retail and eCommerce, 2022-2032F |
6.6.8 Chile Cyber Security Market Revenues & Volume, By Transportation and Logistics, 2022-2032F |
6.6.9 Chile Cyber Security Market Revenues & Volume, By Transportation and Logistics, 2022-2032F |
7 Chile Cyber Security Market Import-Export Trade Statistics |
7.1 Chile Cyber Security Market Export to Major Countries |
7.2 Chile Cyber Security Market Imports from Major Countries |
8 Chile Cyber Security Market Key Performance Indicators |
8.1 Percentage increase in cybersecurity spending by businesses in Chile |
8.2 Number of cybersecurity incidents reported annually |
8.3 Adoption rate of cybersecurity technologies and solutions in the Chilean market |
9 Chile Cyber Security Market - Opportunity Assessment |
9.1 Chile Cyber Security Market Opportunity Assessment, By Component, 2022 & 2032F |
9.2 Chile Cyber Security Market Opportunity Assessment, By Software, 2022 & 2032F |
9.3 Chile Cyber Security Market Opportunity Assessment, By Security Type, 2022 & 2032F |
9.4 Chile Cyber Security Market Opportunity Assessment, By Deployment Mode, 2022 & 2032F |
9.5 Chile Cyber Security Market Opportunity Assessment, By Organization Size, 2022 & 2032F |
9.6 Chile Cyber Security Market Opportunity Assessment, By Vertical, 2022 & 2032F |
10 Chile Cyber Security Market - Competitive Landscape |
10.1 Chile Cyber Security Market Revenue Share, By Companies, 2025 |
10.2 Chile Cyber Security Market Competitive Benchmarking, By Operating and Technical Parameters |
11 Company Profiles |
12 Recommendations |
13 Disclaimer |
Global Go To Market Strategy - 2030
Export potential enables firms to identify high-growth global markets with greater confidence by combining advanced trade intelligence with a structured quantitative methodology. The framework analyzes emerging demand trends and country-level import patterns while integrating macroeconomic and trade datasets such as GDP and population forecasts, bilateral import–export flows, tariff structures, elasticity differentials between developed and developing economies, geographic distance, and import demand projections. Using weighted trade values from 2020–2024 as the base period to project country-to-country export potential for 2030, these inputs are operationalized through calculated drivers such as gravity model parameters, tariff impact factors, and projected GDP per-capita growth. Through an analysis of hidden potentials, demand hotspots, and market conditions that are most favorable to success, this method enables firms to focus on target countries, maximize returns, and global expansion with data, backed by accuracy.
By factoring in the projected importer demand gap that is currently unmet and could be potential opportunity, it identifies the potential for the Exporter (Country) among 190 countries, against the general trade analysis, which identifies the biggest importer or exporter.
To discover high-growth global markets and optimize your business strategy:
Click Here
Request Primary Research & Report
- Single User License$ 1,995
- Department License$ 2,400
- Site License$ 3,120
- Global License$ 3,795
Leadership Perspectives from Industry Events
Search
6Wresearch in the News
 Forbes
Citing 6Wresearch analytics to map global infrastructure and pharmaceutical industry trajectories.
 Bloomberg Law
Direct syndication of 6Wresearch's macro data points, capturing complex supply chain shifts.
 Reuters
Tracking industrial manufacturing adjustments and electronic security ecosystem scaling.
 Mint
Utilizing deep-tech sector market sizing to analyze global automation and robotics.
 The Economic Times
Anchoring features on industrial IoT growth metrics and connected smart-grid devices.
 Business Standard
Featuring strategic evaluations of Advanced Driver Assistance Systems (ADAS) and AI road safety.
 The Hindu
Spotlighting core commercial metrics ranging from unmanned aerial vehicles (UAVs) to consumer durables.
 Financial Express
Anchoring quarterly reviews on cross-border real estate tech and structural hardware manufacturing.
 Yahoo Finance
Syndicating the tracker's $30.1 billion untapped-market findings, spotlighting Japan, the US and China as India's top new-potential importers.
 India Today
Carrying the release on smartphones leading India's export potential to $94 billion by 2031, per 6WExportGTM data.
 Dailyhunt
Distributing the tracker findings to its regional readership, framing India's export diversification into Japan and Mexico.
 PR Newswire Original release
Publishing the full India Export Attractiveness Tracker 2026, detailing new trade corridors across iron ore, LCVs and pharmaceuticals.
 The Industrial
Highlighting the tracker's read on India's semiconductor ambitions and long-term chip-assembly export potential.
 PTI News
Reporting on the $66.81 billion pharmaceuticals export opportunity flagged in the tracker, amid looming US generic-drug tariffs.
 Tribune India
Covering the tracker's tariff-versus-regulation analysis across India's mature export markets in the US, China and UAE.
 ANI News
Amplifying the report's findings on polished diamonds, refined petroleum and medicines as India's core export engines.
 International Business Magazine
Covering the report's insight into how AEB, blind spot detection, and driver monitoring are reshaping India's ADAS market.
 Focus Gaming News
Highlighting the research forecast for Egypt's gambling market, projecting steady growth through 2032.
Thought Leadership and Analyst Meet
Our Clients
Latest Reports
- Global Whey Protein Market (2025-2031)
- Bahrain Vehicle-Supported Bicycle Drive Chains Market (2026-2032)
- Azerbaijan Vehicle-Supported Bicycle Drive Chains Market (2026-2032)
- Australia Vehicle-Supported Bicycle Drive Chains Market (2026-2032)
- Argentina Vehicle-Supported Bicycle Drive Chains Market (2026-2032)
- Algeria Vehicle-Supported Bicycle Drive Chains Market (2026-2032)
- Zimbabwe Vehicle-Grade Aluminum Materials Market (2026-2032)
- Zambia Vehicle-Grade Aluminum Materials Market (2026-2032)
- Yemen Vehicle-Grade Aluminum Materials Market (2026-2032)
- Vanuatu Vehicle-Grade Aluminum Materials Market (2026-2032)
Industry Events and Analyst Meet

EV India Expo 2026
HIMTEX 2026
India Refining Summit 2026
India EV Show 2026
EV tech India Expo 2026
Whitepaper
- Middle East & Africa Commercial Security Market Click here to view more.
- Middle East & Africa Fire Safety Systems & Equipment Market Click here to view more.
- GCC Drone Market Click here to view more.
- Middle East Lighting Fixture Market Click here to view more.
- GCC Physical & Perimeter Security Market Click here to view more.