Global Automotive Composites Market (2026-2032) | Challenges, Size, Analysis, Consumer Insights, Supply, Competitive, Opportunities, Segments, Segmentation, Growth, Investment Trends, Companies, Outlook, Share, Restraints, Strategic Insights, Trends, Industry, Drivers, Forecast, Competition, Revenue, Value, Strategy, Pricing Analysis, Demand
Market Forecast by Regions and Countries (North America, Europe, LATAM, Middle East, Asia and Africa), By Fiber (Glass, Carbon, Others), By Resin (Thermoset, Thermoplastic), By Application (Interior, Exterior, Powertrain, Chassis), By Vehicle (Non-electric, Electric) And Competitive Landscape
| Product Code: ETC13408467 | Publication Date: Apr 2025 | Updated Date: Sep 2026 | Product Type: Market Research Report | |
| Publisher: 6Wresearch | Author: Sachin Kumar Rai | No. of Pages: 190 | No. of Figures: 80 | No. of Tables: 40 |
Global Automotive Composites Market Highlights
| Market Size (2025) | USD 9.1 Billion |
| Forecast Size (2032) | USD 14.1 Billion |
| CAGR | 5.70% |
| Base Year | 2025 |
| Forecast Period | 2026-2032 |
| Largest Region | North America |
| Fastest Growing Region | Asia |
| Largest Segment | Glass |
| Fastest Growing Segment | Carbon |
| Leading Companies | Toray Industries, SGL Group, Teijin Limited, Hexcel Corporation, Covestro AG |
Global Automotive Composites Market Size & Growth Rate (2026-2032)
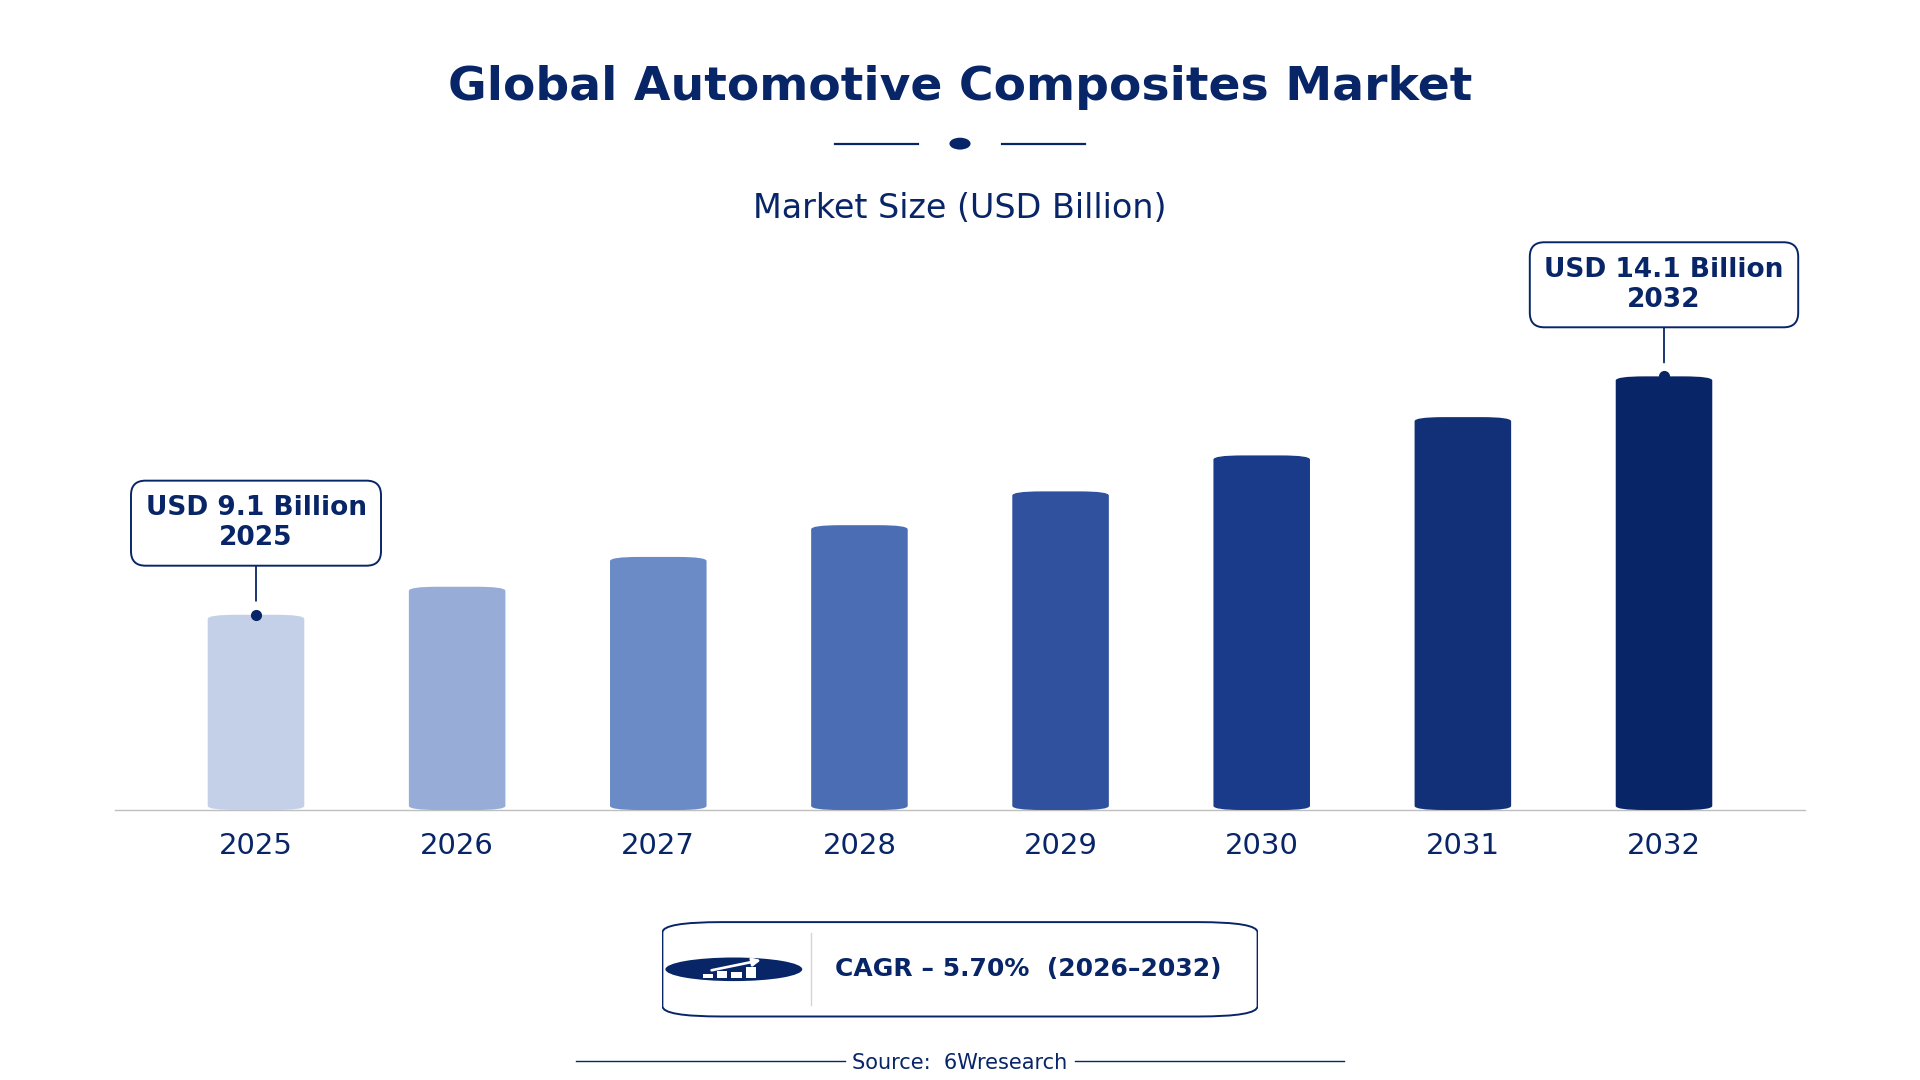
The Global Automotive Composites Market was estimated at USD 9.1 Billion in 2025 and is projected to reach USD 14.1 Billion by 2032, growing at a CAGR of 5.70% from 2026 to 2032.
Global Automotive Composites Market Synopsis
The Global Automotive Composites Market is undergoing transformative changes driven by a fundamental shift towards lightweight materials. This evolution stems from manufacturers’ need to enhance fuel efficiency and satisfy stringent emissions standards. As automakers increasingly integrate composites, they not only reduce vehicle weight but also improve overall performance, effectively enabling a more sustainable approach to automotive design.
This market significantly impacts various sectors, particularly electric and hybrid vehicle production, where advanced materials play a crucial role in energy efficiency. The adoption of composites is distinguishing this market from adjacent materials sectors, exemplifying a targeted response to contemporary regulatory challenges and advancing consumer preferences for sustainability and performance.
Global Automotive Composites Market Year-wise Growth Rate and Key Drivers
This graph illustrates the annual growth rates of the Global Automotive Composites Market from 2022 to 2032, highlighting a steady upward trajectory and projected expansion over the forecast period.
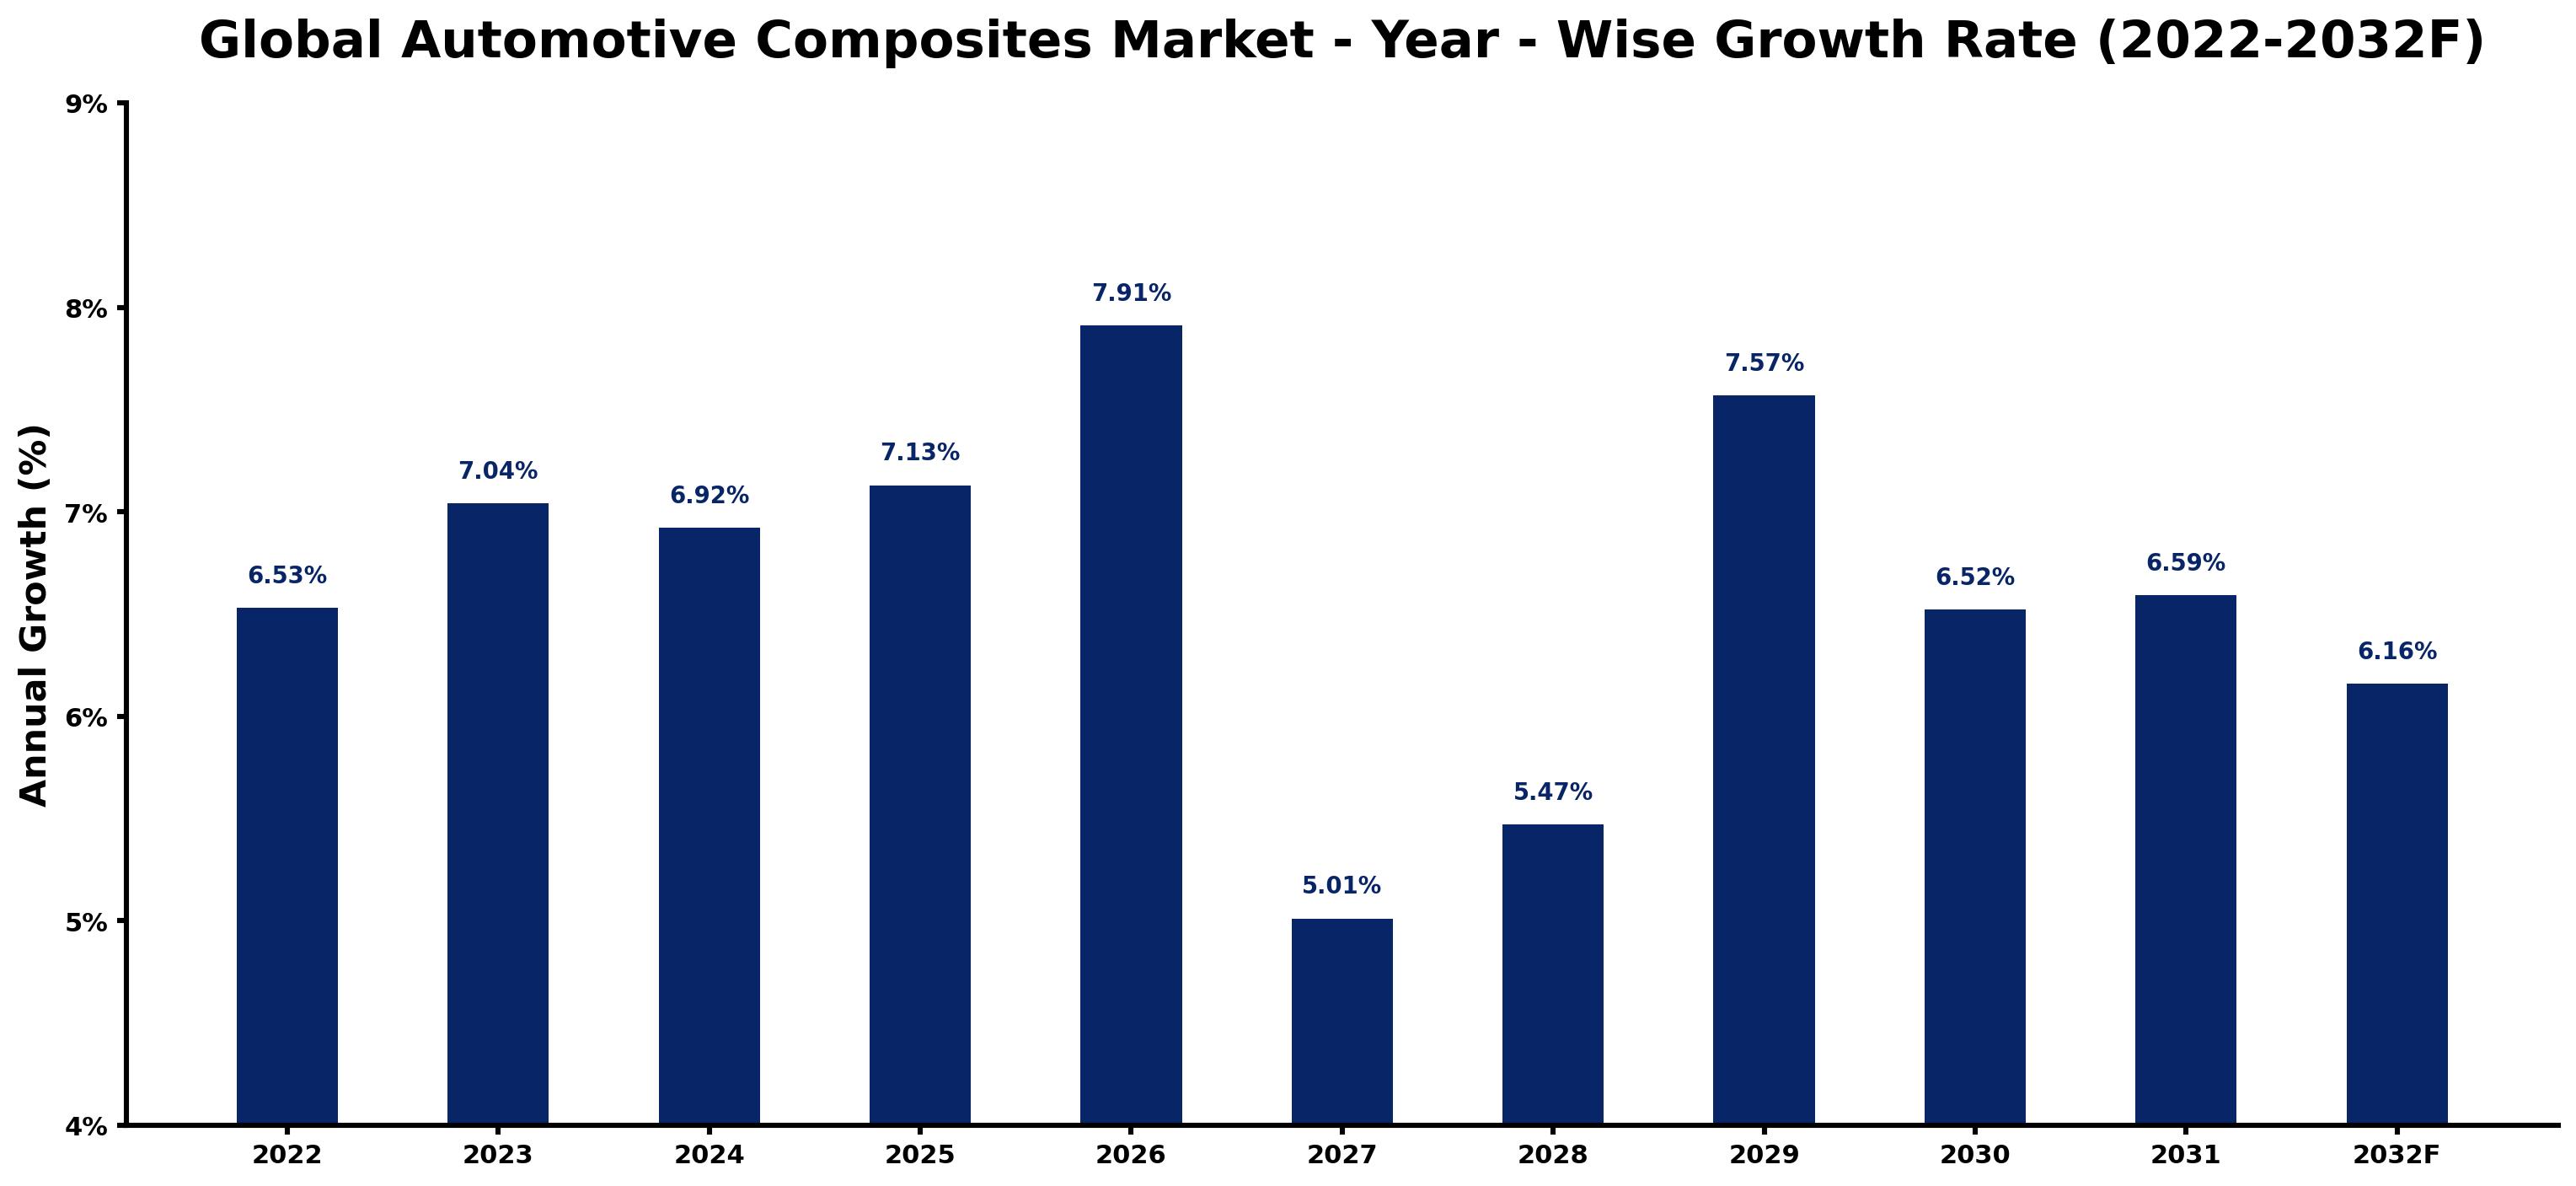
The table below presents the year‑wise growth rates along with the key drivers influencing the market
| Year | Growth Rate (%) | Major Drivers |
| 2022 | 6.53 | In North America, the automotive composites market expands due to increasing regional production capacities. |
| 2023 | 7.04 | A shift toward stringent emissions regulations changes manufacturers' approaches to lightweight automotive composites. |
| 2024 | 6.92 | Investors in automotive firms assertively engage in mergers focused on composite material innovations. |
| 2025 | 7.13 | The rising cost of traditional materials drives manufacturers to adopt advanced automotive composites. |
| 2026 | 7.91 | Streamlining supply chains strengthens the integration of automotive composites in production processes. |
| 2027 | 5.01 | Growing interest among OEMs in sustainable vehicles influences the shift to automotive composite solutions. |
| 2028 | 5.47 | Increasing investments in skilled labor enhance the industry's capacity for automotive composite production. |
| 2029 | 7.57 | Automotive manufacturers increasingly seek innovative composites to meet evolving consumer preferences and demands. |
| 2030 | 6.52 | Research and development teams at automotive firms enhance product offerings in composite technologies. |
| 2031 | 6.59 | Electric vehicle battery technology adoption catalyzes the integration of automotive composites into designs. |
| 2032 | 6.16 | While sustainability becomes paramount, automotive composites evolve to meet environmental performance standards. |
Note - Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary research methodology, combining internal industry data, secondary research, and primary validation, updated periodically to reflect current market conditions. As markets evolve rapidly, figures for certain industries may vary slightly and are intended as informed estimates rather than absolute figures. For the most current market sizing, we recommend validating figures with a 6Wresearch analyst.
Global Automotive Composites Market Key Takeaways
Below are some of the specific key takeaways from the market, including:
- North America held approximately ~45% share in 2025, showcasing its leadership in automotive composites.
- Carbon composites are forecasted to exhibit a CAGR of 7.9% from 2026 to 2032, driven by their demand in high-performance vehicles.
- Toray Industries has invested around USD 300 million in advancing their carbon fiber production capabilities as of 2023.
- The incorporation of environmentally friendly materials is expected to increase significantly, influencing a cross-sector shift towards sustainability.
Evaluation of Restraints in Global Automotive Composites Market
The Global Automotive Composites Market faces significant challenges, notably high production costs that can reach as much as 20-30% above traditional materials like steel. This pricing disparity often limits broader adoption among cost-sensitive manufacturers. For example, carbon fiber composites may cost approximately USD 15 per kilogram compared to steel's USD 1.50, fundamentally impacting manufacturer choices. Moreover, the complexities involved in processing these advanced materials lead to longer production times, further straining cost efficiencies.
Global Automotive Composites Market Trends
Several distinct trends are reshaping the Global Automotive Composites Market. A marked shift towards automated manufacturing processes is becoming evident, as seen in the implementation of UAV technology at production facilities to monitor quality in real-time. For instance, in 2022, Hexcel Corporation incorporated AI-driven robotics to streamline the production of composite parts, which resulted in a 30% reduction in cycle time. Additionally, regulatory evolution is increasingly favoring environmentally sustainable composites, with governments setting stricter emission standards that require automakers to prioritize advanced materials. The growing popularity of hybrid and electric vehicles is another pivotal trend; composites like carbon fiber enhance driving ranges, directly addressing market demands for performance and efficiency.
Global Automotive Composites Market Opportunities
Future revenue opportunities in the Global Automotive Composites Market are substantial, particularly in segments focusing on renewable energy technologies and sustainable practices. For instance, efforts towards the development of bio-based composites are gaining traction; a project by Covestro AG aims to utilize plant-based resources in composite production, targeting a market entry by 2025. Additionally, the automotive sector's shift towards hydrogen fuel cell vehicles presents a viable opportunity; lightweight composites offer crucial advantages in efficiency and design flexibility. These advancements suggest a fruitful landscape for investment and innovation in the upcoming years.
Global Automotive Composites Market by Fiber
Glass fibers lead the Global Automotive Composites Market, holding a dominating share of approximately ~48% in 2025. Meanwhile, carbon fibers represent the fastest-growing segment, projected to achieve a CAGR of 8.5% from 2026 to 2032. The preference for glass fibers stems from their cost-effectiveness and widespread applicability in mass-market vehicles, while carbon fibers are primarily sought for performance-oriented applications due to their superior strength-to-weight ratio, making them ideal for the emerging high-performance vehicle market.
Global Automotive Composites Market by Resin
Thermoset resins hold the largest share in the Global Automotive Composites Market, accounting for approximately ~52% market share as of 2025. Thermoplastics, however, are emerging as the fastest-growing segment, with an anticipated CAGR of 6.5% from 2026 to 2032. The versatility and recyclability of thermoplastics are significant drivers behind their increasing adoption, as they support trends towards sustainability in automotive design while offering rapid processing techniques that appeal to manufacturers looking to enhance efficiency.
Global Automotive Composites Market by Application
The Global Automotive Composites Market's largest application segment is in the exterior components, which captures approximately ~40% of the market share in 2025. The interior segment is expected to be the fastest-growing application, with a CAGR of 7.5% projected from 2026 to 2032. This growth is largely fueled by consumer preferences for lightweight interiors that enhance vehicle efficiency and performance, aligning with overall industry trends focused on reducing weight to meet emission standards.
Global Automotive Composites Market by Vehicle
Non-electric vehicles currently dominate the Global Automotive Composites Market, holding a significant share of approximately ~62% in 2025. However, electric vehicles are anticipated to be the fastest-growing segment, with a projected CAGR of 9.0% from 2026 to 2032. This growth is heavily influenced by the electric vehicle industry's expanding focus on lightweight materials that not only improve energy efficiency but also contribute to extended range capabilities, addressing key consumer demands in the EV market.
Global Automotive Composites Market by Region
As of 2025, North America is anticipated to dominate the Global Automotive Composites Market, with around ~46% share. Notably, the Asia region is expected to exhibit the fastest growth rate, with an estimated CAGR of 7.8% from 2026 to 2032. The United States and Canada benefit from advanced automotive manufacturing ecosystems and innovation leadership, while Asia's growth is fostered by rapid automotive sector expansions, increasing production capabilities, and significant government investments in electric vehicle technologies.
Government Initiatives in the Global Automotive Composites Market
The regulatory landscape for the Global Automotive Composites Market is increasingly shaped by various government initiatives aimed at promoting sustainable automotive practices. This is driven by the need to meet strict emission targets and the push for innovation in alternative materials. Policymakers are implementing incentives to encourage manufacturers to shift towards advanced composites, which align with environmental goals.
- Environmental Protection Agency (EPA) - Clean Cars Program, 2021: This policy sets stringent limits on greenhouse gas emissions for vehicles, encouraging the use of lightweight materials like composites.
- Department of Energy (DOE) - Advanced Research Projects Agency-Energy (ARPA-E) initiative, 2022: This program funds projects that encourage the integration of advanced materials into automotive platforms.
- European Commission - The European Green Deal, 2019: A comprehensive framework aimed at making the EU's economy sustainable, including incentives for low-carbon automotive production.
- Ministry of Industry and Information Technology (MIIT), China - Guidance on Promoting the Development of the Advanced Manufacturing Industry, 2023: This upcoming directive aims to bolster domestic production of high-performance composites in the automotive sector.
Future Insights of the Global Automotive Composites Market
The trajectory of the Global Automotive Composites Market is poised for transformation as it leans into advanced manufacturing techniques and sustainable practices. By 2025, companies such as Toray Industries are expected to elevate their focus on eco-friendly materials, with notable investments aimed at developing bio-based composites. As vehicle electrification accelerates, the demand for lightweight, high-performance materials will increase, directly impacting design choices and manufacturing efficiencies. These shifts are likely to cultivate a robust environment for innovation and investment throughout the industry.
Global Automotive Composites Market Latest Developments
Recent advancements within the Global Automotive Composites Market reflect the industry's move towards efficiency and sustainability. Key developments that underscore this evolution include:
- Toray Industries recently completed a USD 300 million expansion of its carbon fiber manufacturing capabilities, enhancing its competitive position in the high-performance vehicle sector while meeting growing market needs.
- In early 2023, Hexcel Corporation launched a new line of recyclable thermoplastic composites, aiming to respond to the increasing regulatory emphasis on sustainability and material reuse.
- SGL Group is set to introduce advanced manufacturing techniques by late 2024, targeting a significant reduction in production cycle times, which will improve cost efficiencies in composite part manufacturing.
- Covestro AG is planning to initiate a project in 2025 focusing on bio-based composites, with an aim to resonate with consumer trends towards environmentally responsible automotive options.
Global Automotive Composites Market Key Players and Industry Positioning
The Global Automotive Composites Market features a competitive landscape that is moderately consolidated, dominated by a few key players with distinct strengths. The leading companies leverage unique technological capabilities and strategic innovations to establish a stronghold in the rapidly evolving sector, allowing them to respond effectively to market demands.
| Leading Company | Core Strength | Strategic Focus |
|---|---|---|
| Toray Industries | Advanced carbon fiber manufacturing | High-performance vehicles and lightweight materials |
| SGL Group | Strong R&D capabilities in composites | Innovative manufacturing processes and product development |
| Teijin Limited | Wide range of composite materials for diverse applications | Sustainability initiatives and automotive partnerships |
| Hexcel Corporation | Leading provider of advanced composites | Focus on recyclable materials and efficiency in production |
| Covestro AG | Expertise in polyurethane and polycarbonate composites | Sustainable and bio-based material innovations |
This competitive structure indicates a market that is not only emphasizing technological advancement but also a commitment to sustainability—critical for success in the current automotive environment.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year: 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- Global Automotive Composites Market Outlook
- Market Size of Global Automotive Composites Market, 2025
- Forecast of Global Automotive Composites Market, 2032
- Historical Data and Forecast of Global Automotive Composites Revenues & Volume for the Period 2022-2032
- Global Automotive Composites Market Trend Evolution
- Global Automotive Composites Market Drivers and Challenges
- Global Automotive Composites Price Trends
- Global Automotive Composites Porter's Five Forces
- Global Automotive Composites Industry Life Cycle
- Historical Data and Forecast of Global Automotive Composites Market Revenues & Volume
- Historical Data and Forecast of Global Automotive Composites Market Revenues & Volume By Fiber for the Period 2022-2032
- Historical Data and Forecast of Global Automotive Composites Market Revenues & Volume By Glass for the Period 2022-2032
- Historical Data and Forecast of Global Automotive Composites Market Revenues & Volume By Carbon for the Period 2022-2032
- Historical Data and Forecast of Global Automotive Composites Market Revenues & Volume By Others for the Period 2022-2032
- Historical Data and Forecast of Global Automotive Composites Market Revenues & Volume By Resin for the Period 2022-2032
- Historical Data and Forecast of Global Automotive Composites Market Revenues & Volume By Thermoset for the Period 2022-2032
- Historical Data and Forecast of Global Automotive Composites Market Revenues & Volume By Thermoplastic for the Period 2022-2032
- Historical Data and Forecast of Global Automotive Composites Market Revenues & Volume By Application for the Period 2022-2032
- Historical Data and Forecast of Global Automotive Composites Market Revenues & Volume By Interior for the Period 2022-2032
- Historical Data and Forecast of Global Automotive Composites Market Revenues & Volume By Exterior for the Period 2022-2032
- Historical Data and Forecast of Global Automotive Composites Market Revenues & Volume By Powertrain for the Period 2022-2032
- Historical Data and Forecast of Global Automotive Composites Market Revenues & Volume By Chassis for the Period 2022-2032
- Historical Data and Forecast of Global Automotive Composites Market Revenues & Volume By Vehicle for the Period 2022-2032
- Historical Data and Forecast of Global Automotive Composites Market Revenues & Volume By Non-electric for the Period 2022-2032
- Historical Data and Forecast of Global Automotive Composites Market Revenues & Volume By Electric for the Period 2022-2032
- Historical Data and Forecast of North America Automotive Composites Market Revenues & Volume By Fiber for the Period 2022-2032
- Historical Data and Forecast of North America Automotive Composites Market Revenues & Volume By Glass for the Period 2022-2032
- Historical Data and Forecast of North America Automotive Composites Market Revenues & Volume By Carbon for the Period 2022-2032
- Historical Data and Forecast of North America Automotive Composites Market Revenues & Volume By Others for the Period 2022-2032
- Historical Data and Forecast of North America Automotive Composites Market Revenues & Volume By Resin for the Period 2022-2032
- Historical Data and Forecast of North America Automotive Composites Market Revenues & Volume By Thermoset for the Period 2022-2032
- Historical Data and Forecast of North America Automotive Composites Market Revenues & Volume By Thermoplastic for the Period 2022-2032
- Historical Data and Forecast of North America Automotive Composites Market Revenues & Volume By Application for the Period 2022-2032
- Historical Data and Forecast of North America Automotive Composites Market Revenues & Volume By Interior for the Period 2022-2032
- Historical Data and Forecast of North America Automotive Composites Market Revenues & Volume By Exterior for the Period 2022-2032
- Historical Data and Forecast of North America Automotive Composites Market Revenues & Volume By Powertrain for the Period 2022-2032
- Historical Data and Forecast of North America Automotive Composites Market Revenues & Volume By Chassis for the Period 2022-2032
- Historical Data and Forecast of North America Automotive Composites Market Revenues & Volume By Vehicle for the Period 2022-2032
- Historical Data and Forecast of North America Automotive Composites Market Revenues & Volume By Non-electric for the Period 2022-2032
- Historical Data and Forecast of North America Automotive Composites Market Revenues & Volume By Electric for the Period 2022-2032
- Historical Data and Forecast of United States of America Automotive Composites Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Canada Automotive Composites Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Rest of North America Automotive Composites Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) Automotive Composites Market Revenues & Volume By Fiber for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) Automotive Composites Market Revenues & Volume By Glass for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) Automotive Composites Market Revenues & Volume By Carbon for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) Automotive Composites Market Revenues & Volume By Others for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) Automotive Composites Market Revenues & Volume By Resin for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) Automotive Composites Market Revenues & Volume By Thermoset for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) Automotive Composites Market Revenues & Volume By Thermoplastic for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) Automotive Composites Market Revenues & Volume By Application for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) Automotive Composites Market Revenues & Volume By Interior for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) Automotive Composites Market Revenues & Volume By Exterior for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) Automotive Composites Market Revenues & Volume By Powertrain for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) Automotive Composites Market Revenues & Volume By Chassis for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) Automotive Composites Market Revenues & Volume By Vehicle for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) Automotive Composites Market Revenues & Volume By Non-electric for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) Automotive Composites Market Revenues & Volume By Electric for the Period 2022-2032
- Historical Data and Forecast of Brazil Automotive Composites Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Mexico Automotive Composites Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Argentina Automotive Composites Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Rest of LATAM Automotive Composites Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Asia Automotive Composites Market Revenues & Volume By Fiber for the Period 2022-2032
- Historical Data and Forecast of Asia Automotive Composites Market Revenues & Volume By Glass for the Period 2022-2032
- Historical Data and Forecast of Asia Automotive Composites Market Revenues & Volume By Carbon for the Period 2022-2032
- Historical Data and Forecast of Asia Automotive Composites Market Revenues & Volume By Others for the Period 2022-2032
- Historical Data and Forecast of Asia Automotive Composites Market Revenues & Volume By Resin for the Period 2022-2032
- Historical Data and Forecast of Asia Automotive Composites Market Revenues & Volume By Thermoset for the Period 2022-2032
- Historical Data and Forecast of Asia Automotive Composites Market Revenues & Volume By Thermoplastic for the Period 2022-2032
- Historical Data and Forecast of Asia Automotive Composites Market Revenues & Volume By Application for the Period 2022-2032
- Historical Data and Forecast of Asia Automotive Composites Market Revenues & Volume By Interior for the Period 2022-2032
- Historical Data and Forecast of Asia Automotive Composites Market Revenues & Volume By Exterior for the Period 2022-2032
- Historical Data and Forecast of Asia Automotive Composites Market Revenues & Volume By Powertrain for the Period 2022-2032
- Historical Data and Forecast of Asia Automotive Composites Market Revenues & Volume By Chassis for the Period 2022-2032
- Historical Data and Forecast of Asia Automotive Composites Market Revenues & Volume By Vehicle for the Period 2022-2032
- Historical Data and Forecast of Asia Automotive Composites Market Revenues & Volume By Non-electric for the Period 2022-2032
- Historical Data and Forecast of Asia Automotive Composites Market Revenues & Volume By Electric for the Period 2022-2032
- Historical Data and Forecast of China Automotive Composites Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of India Automotive Composites Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Japan Automotive Composites Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Rest of Asia Automotive Composites Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Africa Automotive Composites Market Revenues & Volume By Fiber for the Period 2022-2032
- Historical Data and Forecast of Africa Automotive Composites Market Revenues & Volume By Glass for the Period 2022-2032
- Historical Data and Forecast of Africa Automotive Composites Market Revenues & Volume By Carbon for the Period 2022-2032
- Historical Data and Forecast of Africa Automotive Composites Market Revenues & Volume By Others for the Period 2022-2032
- Historical Data and Forecast of Africa Automotive Composites Market Revenues & Volume By Resin for the Period 2022-2032
- Historical Data and Forecast of Africa Automotive Composites Market Revenues & Volume By Thermoset for the Period 2022-2032
- Historical Data and Forecast of Africa Automotive Composites Market Revenues & Volume By Thermoplastic for the Period 2022-2032
- Historical Data and Forecast of Africa Automotive Composites Market Revenues & Volume By Application for the Period 2022-2032
- Historical Data and Forecast of Africa Automotive Composites Market Revenues & Volume By Interior for the Period 2022-2032
- Historical Data and Forecast of Africa Automotive Composites Market Revenues & Volume By Exterior for the Period 2022-2032
- Historical Data and Forecast of Africa Automotive Composites Market Revenues & Volume By Powertrain for the Period 2022-2032
- Historical Data and Forecast of Africa Automotive Composites Market Revenues & Volume By Chassis for the Period 2022-2032
- Historical Data and Forecast of Africa Automotive Composites Market Revenues & Volume By Vehicle for the Period 2022-2032
- Historical Data and Forecast of Africa Automotive Composites Market Revenues & Volume By Non-electric for the Period 2022-2032
- Historical Data and Forecast of Africa Automotive Composites Market Revenues & Volume By Electric for the Period 2022-2032
- Historical Data and Forecast of South Africa Automotive Composites Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Nigeria Automotive Composites Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Egypt Automotive Composites Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Rest of Africa Automotive Composites Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Europe Automotive Composites Market Revenues & Volume By Fiber for the Period 2022-2032
- Historical Data and Forecast of Europe Automotive Composites Market Revenues & Volume By Glass for the Period 2022-2032
- Historical Data and Forecast of Europe Automotive Composites Market Revenues & Volume By Carbon for the Period 2022-2032
- Historical Data and Forecast of Europe Automotive Composites Market Revenues & Volume By Others for the Period 2022-2032
- Historical Data and Forecast of Europe Automotive Composites Market Revenues & Volume By Resin for the Period 2022-2032
- Historical Data and Forecast of Europe Automotive Composites Market Revenues & Volume By Thermoset for the Period 2022-2032
- Historical Data and Forecast of Europe Automotive Composites Market Revenues & Volume By Thermoplastic for the Period 2022-2032
- Historical Data and Forecast of Europe Automotive Composites Market Revenues & Volume By Application for the Period 2022-2032
- Historical Data and Forecast of Europe Automotive Composites Market Revenues & Volume By Interior for the Period 2022-2032
- Historical Data and Forecast of Europe Automotive Composites Market Revenues & Volume By Exterior for the Period 2022-2032
- Historical Data and Forecast of Europe Automotive Composites Market Revenues & Volume By Powertrain for the Period 2022-2032
- Historical Data and Forecast of Europe Automotive Composites Market Revenues & Volume By Chassis for the Period 2022-2032
- Historical Data and Forecast of Europe Automotive Composites Market Revenues & Volume By Vehicle for the Period 2022-2032
- Historical Data and Forecast of Europe Automotive Composites Market Revenues & Volume By Non-electric for the Period 2022-2032
- Historical Data and Forecast of Europe Automotive Composites Market Revenues & Volume By Electric for the Period 2022-2032
- Historical Data and Forecast of United Kingdom Automotive Composites Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of France Automotive Composites Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Germany Automotive Composites Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Rest of Europe Automotive Composites Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Middle East Automotive Composites Market Revenues & Volume By Fiber for the Period 2022-2032
- Historical Data and Forecast of Middle East Automotive Composites Market Revenues & Volume By Glass for the Period 2022-2032
- Historical Data and Forecast of Middle East Automotive Composites Market Revenues & Volume By Carbon for the Period 2022-2032
- Historical Data and Forecast of Middle East Automotive Composites Market Revenues & Volume By Others for the Period 2022-2032
- Historical Data and Forecast of Middle East Automotive Composites Market Revenues & Volume By Resin for the Period 2022-2032
- Historical Data and Forecast of Middle East Automotive Composites Market Revenues & Volume By Thermoset for the Period 2022-2032
- Historical Data and Forecast of Middle East Automotive Composites Market Revenues & Volume By Thermoplastic for the Period 2022-2032
- Historical Data and Forecast of Middle East Automotive Composites Market Revenues & Volume By Application for the Period 2022-2032
- Historical Data and Forecast of Middle East Automotive Composites Market Revenues & Volume By Interior for the Period 2022-2032
- Historical Data and Forecast of Middle East Automotive Composites Market Revenues & Volume By Exterior for the Period 2022-2032
- Historical Data and Forecast of Middle East Automotive Composites Market Revenues & Volume By Powertrain for the Period 2022-2032
- Historical Data and Forecast of Middle East Automotive Composites Market Revenues & Volume By Chassis for the Period 2022-2032
- Historical Data and Forecast of Middle East Automotive Composites Market Revenues & Volume By Vehicle for the Period 2022-2032
- Historical Data and Forecast of Middle East Automotive Composites Market Revenues & Volume By Non-electric for the Period 2022-2032
- Historical Data and Forecast of Middle East Automotive Composites Market Revenues & Volume By Electric for the Period 2022-2032
- Historical Data and Forecast of Saudi Arabia Automotive Composites Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of UAE Automotive Composites Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Turkey Automotive Composites Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Rest of Middle East Automotive Composites Market Revenues & Volume for the Period 2022-2032
- Global Automotive Composites Market - Key Performance Indicators
- Global Automotive Composites Market - Import Export Trade Statistics
- Global Automotive Composites Market - Opportunity Assessment By Countries
- Global Automotive Composites Market - Opportunity Assessment By Fiber
- Global Automotive Composites Market - Opportunity Assessment By Resin
- Global Automotive Composites Market - Opportunity Assessment By Application
- Global Automotive Composites Market - Opportunity Assessment By Vehicle
- Global Automotive Composites Market - Top Companies Market Share
- Global Automotive Composites Market - Top Companies Profiles
- Global Automotive Composites Market - Comparison of Players in Technical and Operating Parameters
- Global Automotive Composites Market - Strategic Recommendations
Markets Covered
The Global Automotive Composites Market report provides a detailed analysis of the following market segments:
By Regions and Countries:
- North America
- Europe
- LATAM
- Middle East
- Asia
- Africa
By Fiber:
- Glass
- Carbon
- Others
By Resin:
- Thermoset
- Thermoplastic
By Application:
- Interior
- Exterior
- Powertrain
- Chassis
By Vehicle:
- Non-electric
- Electric
Global Automotive Composites Market - Frequently Asked Questions
The Global Automotive Composites Market was estimated at USD 9.1 Billion in 2025.
The market is projected to grow at a CAGR of 5.70% from 2026 to 2032.
The main drivers include stringent regulations focusing on emissions, rising demand for lightweight materials in vehicle design, and advancements in composite technologies.
Glass fibers represent the largest segment, while carbon fibers are experiencing the fastest growth due to their demand in high-performance applications.
High production costs associated with composite materials and complex manufacturing processes pose significant challenges for manufacturers aiming to scale production efficiently.
The market is expected to evolve towards greater integration of sustainable materials and advanced production technologies, aligning with global trends towards electrification and environmental responsibility.
6Wresearch actively monitors the Global Automotive Composites Market and publishes its comprehensive annual report, highlighting emerging trends, growth drivers, revenue analysis, and forecast outlook. Our insights help businesses to make data-backed strategic decisions with ongoing market dynamics. Our analysts track relevent industries related to the Global Automotive Composites Market, allowing our clients with actionable intelligence and reliable forecasts tailored to emerging regional needs.
Yes, we provide customisation as per your requirements. To learn more, feel free to contact us on sales@6wresearch.com
Global Automotive Composites Market |
1 Executive Summary |
2 Introduction |
2.1 Key Highlights of the Report |
2.2 Report Description |
2.3 Market Scope & Segmentation |
2.4 Research Methodology |
2.5 Assumptions |
3 Global Automotive Composites Market Overview |
3.1 Global Regional Macro Economic Indicators |
3.2 Global Automotive Composites Market Revenues & Volume, 2022 & 2032F |
3.3 Global Automotive Composites Market - Industry Life Cycle |
3.4 Global Automotive Composites Market - Porter's Five Forces |
3.5 Global Automotive Composites Market Revenues & Volume Share, By Regions, 2022 & 2032F |
3.6 Global Automotive Composites Market Revenues & Volume Share, By Fiber, 2022 & 2032F |
3.7 Global Automotive Composites Market Revenues & Volume Share, By Resin, 2022 & 2032F |
3.8 Global Automotive Composites Market Revenues & Volume Share, By Application, 2022 & 2032F |
3.9 Global Automotive Composites Market Revenues & Volume Share, By Vehicle, 2022 & 2032F |
4 Global Automotive Composites Market Dynamics |
4.1 Impact Analysis |
4.2 Market Drivers |
4.3 Market Restraints |
5 Global Automotive Composites Market Trends |
6 Global Automotive Composites Market, 2022-2032 |
6.1 Global Automotive Composites Market, Revenues & Volume, By Fiber, 2022-2032 |
6.1.1 Overview & Analysis |
6.1.2 Global Automotive Composites Market, Revenues & Volume, By Glass, 2022-2032 |
6.1.3 Global Automotive Composites Market, Revenues & Volume, By Carbon, 2022-2032 |
6.1.4 Global Automotive Composites Market, Revenues & Volume, By Others, 2022-2032 |
6.2 Global Automotive Composites Market, Revenues & Volume, By Resin, 2022-2032 |
6.2.1 Overview & Analysis |
6.2.2 Global Automotive Composites Market, Revenues & Volume, By Thermoset, 2022-2032 |
6.2.3 Global Automotive Composites Market, Revenues & Volume, By Thermoplastic, 2022-2032 |
6.3 Global Automotive Composites Market, Revenues & Volume, By Application, 2022-2032 |
6.3.1 Overview & Analysis |
6.3.2 Global Automotive Composites Market, Revenues & Volume, By Interior, 2022-2032 |
6.3.3 Global Automotive Composites Market, Revenues & Volume, By Exterior, 2022-2032 |
6.3.4 Global Automotive Composites Market, Revenues & Volume, By Powertrain, 2022-2032 |
6.3.5 Global Automotive Composites Market, Revenues & Volume, By Chassis, 2022-2032 |
6.4 Global Automotive Composites Market, Revenues & Volume, By Vehicle, 2022-2032 |
6.4.1 Overview & Analysis |
6.4.2 Global Automotive Composites Market, Revenues & Volume, By Non-electric, 2022-2032 |
6.4.3 Global Automotive Composites Market, Revenues & Volume, By Electric, 2022-2032 |
7 North America Automotive Composites Market, Overview & Analysis |
7.1 North America Automotive Composites Market Revenues & Volume, 2022-2032 |
7.2 North America Automotive Composites Market, Revenues & Volume, By Countries, 2022-2032 |
7.2.1 United States (US) Automotive Composites Market, Revenues & Volume, 2022-2032 |
7.2.2 Canada Automotive Composites Market, Revenues & Volume, 2022-2032 |
7.2.3 Rest of North America Automotive Composites Market, Revenues & Volume, 2022-2032 |
7.3 North America Automotive Composites Market, Revenues & Volume, By Fiber, 2022-2032 |
7.4 North America Automotive Composites Market, Revenues & Volume, By Resin, 2022-2032 |
7.5 North America Automotive Composites Market, Revenues & Volume, By Application, 2022-2032 |
7.6 North America Automotive Composites Market, Revenues & Volume, By Vehicle, 2022-2032 |
8 Latin America (LATAM) Automotive Composites Market, Overview & Analysis |
8.1 Latin America (LATAM) Automotive Composites Market Revenues & Volume, 2022-2032 |
8.2 Latin America (LATAM) Automotive Composites Market, Revenues & Volume, By Countries, 2022-2032 |
8.2.1 Brazil Automotive Composites Market, Revenues & Volume, 2022-2032 |
8.2.2 Mexico Automotive Composites Market, Revenues & Volume, 2022-2032 |
8.2.3 Argentina Automotive Composites Market, Revenues & Volume, 2022-2032 |
8.2.4 Rest of LATAM Automotive Composites Market, Revenues & Volume, 2022-2032 |
8.3 Latin America (LATAM) Automotive Composites Market, Revenues & Volume, By Fiber, 2022-2032 |
8.4 Latin America (LATAM) Automotive Composites Market, Revenues & Volume, By Resin, 2022-2032 |
8.5 Latin America (LATAM) Automotive Composites Market, Revenues & Volume, By Application, 2022-2032 |
8.6 Latin America (LATAM) Automotive Composites Market, Revenues & Volume, By Vehicle, 2022-2032 |
9 Asia Automotive Composites Market, Overview & Analysis |
9.1 Asia Automotive Composites Market Revenues & Volume, 2022-2032 |
9.2 Asia Automotive Composites Market, Revenues & Volume, By Countries, 2022-2032 |
9.2.1 India Automotive Composites Market, Revenues & Volume, 2022-2032 |
9.2.2 China Automotive Composites Market, Revenues & Volume, 2022-2032 |
9.2.3 Japan Automotive Composites Market, Revenues & Volume, 2022-2032 |
9.2.4 Rest of Asia Automotive Composites Market, Revenues & Volume, 2022-2032 |
9.3 Asia Automotive Composites Market, Revenues & Volume, By Fiber, 2022-2032 |
9.4 Asia Automotive Composites Market, Revenues & Volume, By Resin, 2022-2032 |
9.5 Asia Automotive Composites Market, Revenues & Volume, By Application, 2022-2032 |
9.6 Asia Automotive Composites Market, Revenues & Volume, By Vehicle, 2022-2032 |
10 Africa Automotive Composites Market, Overview & Analysis |
10.1 Africa Automotive Composites Market Revenues & Volume, 2022-2032 |
10.2 Africa Automotive Composites Market, Revenues & Volume, By Countries, 2022-2032 |
10.2.1 South Africa Automotive Composites Market, Revenues & Volume, 2022-2032 |
10.2.2 Egypt Automotive Composites Market, Revenues & Volume, 2022-2032 |
10.2.3 Nigeria Automotive Composites Market, Revenues & Volume, 2022-2032 |
10.2.4 Rest of Africa Automotive Composites Market, Revenues & Volume, 2022-2032 |
10.3 Africa Automotive Composites Market, Revenues & Volume, By Fiber, 2022-2032 |
10.4 Africa Automotive Composites Market, Revenues & Volume, By Resin, 2022-2032 |
10.5 Africa Automotive Composites Market, Revenues & Volume, By Application, 2022-2032 |
10.6 Africa Automotive Composites Market, Revenues & Volume, By Vehicle, 2022-2032 |
11 Europe Automotive Composites Market, Overview & Analysis |
11.1 Europe Automotive Composites Market Revenues & Volume, 2022-2032 |
11.2 Europe Automotive Composites Market, Revenues & Volume, By Countries, 2022-2032 |
11.2.1 United Kingdom Automotive Composites Market, Revenues & Volume, 2022-2032 |
11.2.2 Germany Automotive Composites Market, Revenues & Volume, 2022-2032 |
11.2.3 France Automotive Composites Market, Revenues & Volume, 2022-2032 |
11.2.4 Rest of Europe Automotive Composites Market, Revenues & Volume, 2022-2032 |
11.3 Europe Automotive Composites Market, Revenues & Volume, By Fiber, 2022-2032 |
11.4 Europe Automotive Composites Market, Revenues & Volume, By Resin, 2022-2032 |
11.5 Europe Automotive Composites Market, Revenues & Volume, By Application, 2022-2032 |
11.6 Europe Automotive Composites Market, Revenues & Volume, By Vehicle, 2022-2032 |
12 Middle East Automotive Composites Market, Overview & Analysis |
12.1 Middle East Automotive Composites Market Revenues & Volume, 2022-2032 |
12.2 Middle East Automotive Composites Market, Revenues & Volume, By Countries, 2022-2032 |
12.2.1 Saudi Arabia Automotive Composites Market, Revenues & Volume, 2022-2032 |
12.2.2 UAE Automotive Composites Market, Revenues & Volume, 2022-2032 |
12.2.3 Turkey Automotive Composites Market, Revenues & Volume, 2022-2032 |
12.3 Middle East Automotive Composites Market, Revenues & Volume, By Fiber, 2022-2032 |
12.4 Middle East Automotive Composites Market, Revenues & Volume, By Resin, 2022-2032 |
12.5 Middle East Automotive Composites Market, Revenues & Volume, By Application, 2022-2032 |
12.6 Middle East Automotive Composites Market, Revenues & Volume, By Vehicle, 2022-2032 |
13 Global Automotive Composites Market Key Performance Indicators |
14 Global Automotive Composites Market - Export/Import By Countries Assessment |
15 Global Automotive Composites Market - Opportunity Assessment |
15.1 Global Automotive Composites Market Opportunity Assessment, By Countries, 2022 & 2032F |
15.2 Global Automotive Composites Market Opportunity Assessment, By Fiber, 2022 & 2032F |
15.3 Global Automotive Composites Market Opportunity Assessment, By Resin, 2022 & 2032F |
15.4 Global Automotive Composites Market Opportunity Assessment, By Application, 2022 & 2032F |
15.5 Global Automotive Composites Market Opportunity Assessment, By Vehicle, 2022 & 2032F |
16 Global Automotive Composites Market - Competitive Landscape |
16.1 Global Automotive Composites Market Revenue Share, By Companies, 2025 |
16.2 Global Automotive Composites Market Competitive Benchmarking, By Operating and Technical Parameters |
17 Top 10 Company Profiles |
18 Recommendations |
19 Disclaimer |
Global Go To Market Strategy - 2030
Export potential enables firms to identify high-growth global markets with greater confidence by combining advanced trade intelligence with a structured quantitative methodology. The framework analyzes emerging demand trends and country-level import patterns while integrating macroeconomic and trade datasets such as GDP and population forecasts, bilateral import–export flows, tariff structures, elasticity differentials between developed and developing economies, geographic distance, and import demand projections. Using weighted trade values from 2020–2024 as the base period to project country-to-country export potential for 2030, these inputs are operationalized through calculated drivers such as gravity model parameters, tariff impact factors, and projected GDP per-capita growth. Through an analysis of hidden potentials, demand hotspots, and market conditions that are most favorable to success, this method enables firms to focus on target countries, maximize returns, and global expansion with data, backed by accuracy.
By factoring in the projected importer demand gap that is currently unmet and could be potential opportunity, it identifies the potential for the Exporter (Country) among 190 countries, against the general trade analysis, which identifies the biggest importer or exporter.
To discover high-growth global markets and optimize your business strategy:
Click Here
Request Primary Research & Report
- Single User License$ 4,560
- Department License$ 5,055
- Site License$ 5,595
- Global License$ 6,000
Leadership Perspectives from Industry Events
Search
6Wresearch in the News
 Forbes
Citing 6Wresearch analytics to map global infrastructure and pharmaceutical industry trajectories.
 Bloomberg Law
Direct syndication of 6Wresearch's macro data points, capturing complex supply chain shifts.
 Reuters
Tracking industrial manufacturing adjustments and electronic security ecosystem scaling.
 Mint
Utilizing deep-tech sector market sizing to analyze global automation and robotics.
 The Economic Times
Anchoring features on industrial IoT growth metrics and connected smart-grid devices.
 Business Standard
Featuring strategic evaluations of Advanced Driver Assistance Systems (ADAS) and AI road safety.
 The Hindu
Spotlighting core commercial metrics ranging from unmanned aerial vehicles (UAVs) to consumer durables.
 Financial Express
Anchoring quarterly reviews on cross-border real estate tech and structural hardware manufacturing.
 Yahoo Finance
Syndicating the tracker's $30.1 billion untapped-market findings, spotlighting Japan, the US and China as India's top new-potential importers.
 India Today
Carrying the release on smartphones leading India's export potential to $94 billion by 2031, per 6WExportGTM data.
 Dailyhunt
Distributing the tracker findings to its regional readership, framing India's export diversification into Japan and Mexico.
 PR Newswire Original release
Publishing the full India Export Attractiveness Tracker 2026, detailing new trade corridors across iron ore, LCVs and pharmaceuticals.
 The Industrial
Highlighting the tracker's read on India's semiconductor ambitions and long-term chip-assembly export potential.
 PTI News
Reporting on the $66.81 billion pharmaceuticals export opportunity flagged in the tracker, amid looming US generic-drug tariffs.
 Tribune India
Covering the tracker's tariff-versus-regulation analysis across India's mature export markets in the US, China and UAE.
 ANI News
Amplifying the report's findings on polished diamonds, refined petroleum and medicines as India's core export engines.
 International Business Magazine
Covering the report's insight into how AEB, blind spot detection, and driver monitoring are reshaping India's ADAS market.
 Focus Gaming News
Highlighting the research forecast for Egypt's gambling market, projecting steady growth through 2032.
Thought Leadership and Analyst Meet
Our Clients
Latest Reports
- Austria X-ray Imaging Devices Market (2026-2032)
- Armenia X-ray Imaging Devices Market (2026-2032)
- Antigua and Barbuda X-ray Imaging Devices Market (2026-2032)
- Angola X-ray Imaging Devices Market (2026-2032)
- Andorra X-ray Imaging Devices Market (2026-2032)
- Albania X-ray Imaging Devices Market (2026-2032)
- Afghanistan X-ray Imaging Devices Market (2026-2032)
- United States (US) X-ray Imaging Devices Market (2026-2032)
- United Kingdom (UK) X-ray Imaging Devices Market (2026-2032)
- United Arab Emirates (UAE) X-ray Imaging Devices Market (2026-2032)
Industry Events and Analyst Meet

EV India Expo 2026
HIMTEX 2026
India Refining Summit 2026
India EV Show 2026
EV tech India Expo 2026
Whitepaper
- Middle East & Africa Commercial Security Market Click here to view more.
- Middle East & Africa Fire Safety Systems & Equipment Market Click here to view more.
- GCC Drone Market Click here to view more.
- Middle East Lighting Fixture Market Click here to view more.
- GCC Physical & Perimeter Security Market Click here to view more.


