Global Education Computing Devices Market (2026-2032) | Segmentation, Companies, Challenges, Revenue, Demand, Value, Growth, Supply, Strategy, Industry, Opportunities, Analysis, Forecast, Competitive, Restraints, Consumer Insights, Trends, Outlook, Investment Trends, Strategic Insights, Share, Size, Segments, Drivers, Pricing Analysis, Competition
Market Forecast by Regions and Countries (North America, Europe, LATAM, Middle East, Asia and Africa), By Product Type (Smartphones, Laptops, Tablets), By End User (Primary, Secondary, Higher Secondary) And Competitive Landscape
| Product Code: ETC13258967 | Publication Date: Apr 2025 | Updated Date: Sep 2026 | Product Type: Market Research Report | |
| Publisher: 6Wresearch | Author: Sachin Kumar Rai | No. of Pages: 190 | No. of Figures: 80 | No. of Tables: 40 |
Global Education Computing Devices Market Highlights
| Market Size (2025) | USD 48.3 Billion |
| Forecast Size (2032) | USD 96.7 Billion |
| CAGR | 11.14% |
| Base Year | 2025 |
| Forecast Period | 2026-2032 |
| Largest Region | North America |
| Fastest Growing Region | Asia |
| Largest Segment | Laptops |
| Fastest Growing Segment | Tablets |
| Leading Companies | Dell Technologies, Lenovo Group Limited, HP Inc., Apple Inc., Acer Inc. |
Global Education Computing Devices Market Size & Growth Rate (2026-2032)
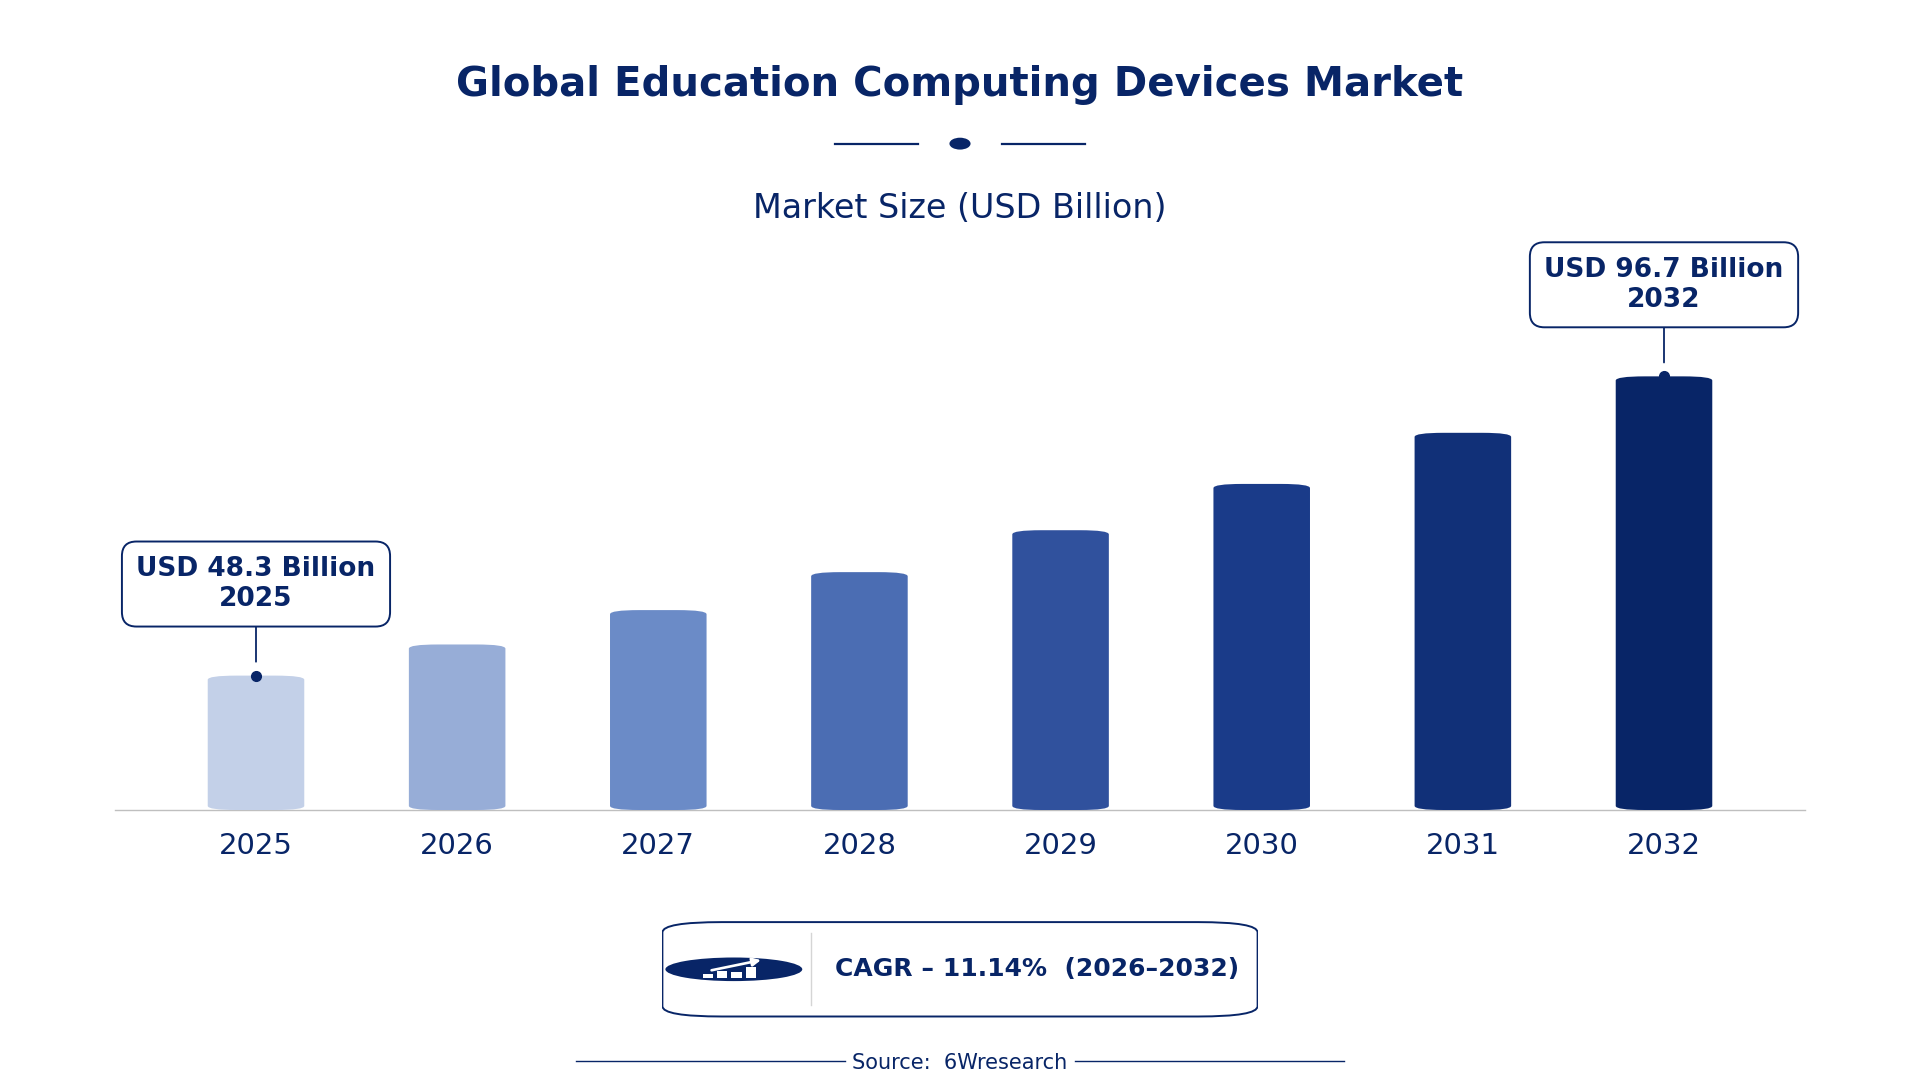
The Global Education Computing Devices Market was estimated at USD 48.3 Billion in 2025 and is projected to reach USD 96.7 Billion by 2032, growing at a CAGR of 11.14% from 2026 to 2032.
Global Education Computing Devices Market Synopsis
The landscape of the Global Education Computing Devices Market is undergoing substantial transformation, driven by the surge in digital learning environments. Educational institutions are increasingly seeking devices tailored for interactive learning, with schools pushing for technologies that facilitate remote education and personalized study experiences. This shift is not merely reactive; it represents a proactive approach to preparing students for a digital future.
Demand for specific computing devices, particularly laptops and tablets, is surging as institutions prioritize integrated technology for curriculum delivery. These devices are being leveraged to enhance student engagement and interdisciplinary learning. Moreover, aligning educational objectives with technological capability ensures that institutions invest in solutions that foster learning outcomes, a strategy that differentiates this market from peripheral tech sectors.
Global Education Computing Devices Market Year-wise Growth Rate and Key Drivers
This graph illustrates the annual growth rates of the Global Education Computing Devices Market from 2022 to 2032, highlighting a steady upward trajectory and projected expansion over the forecast period.
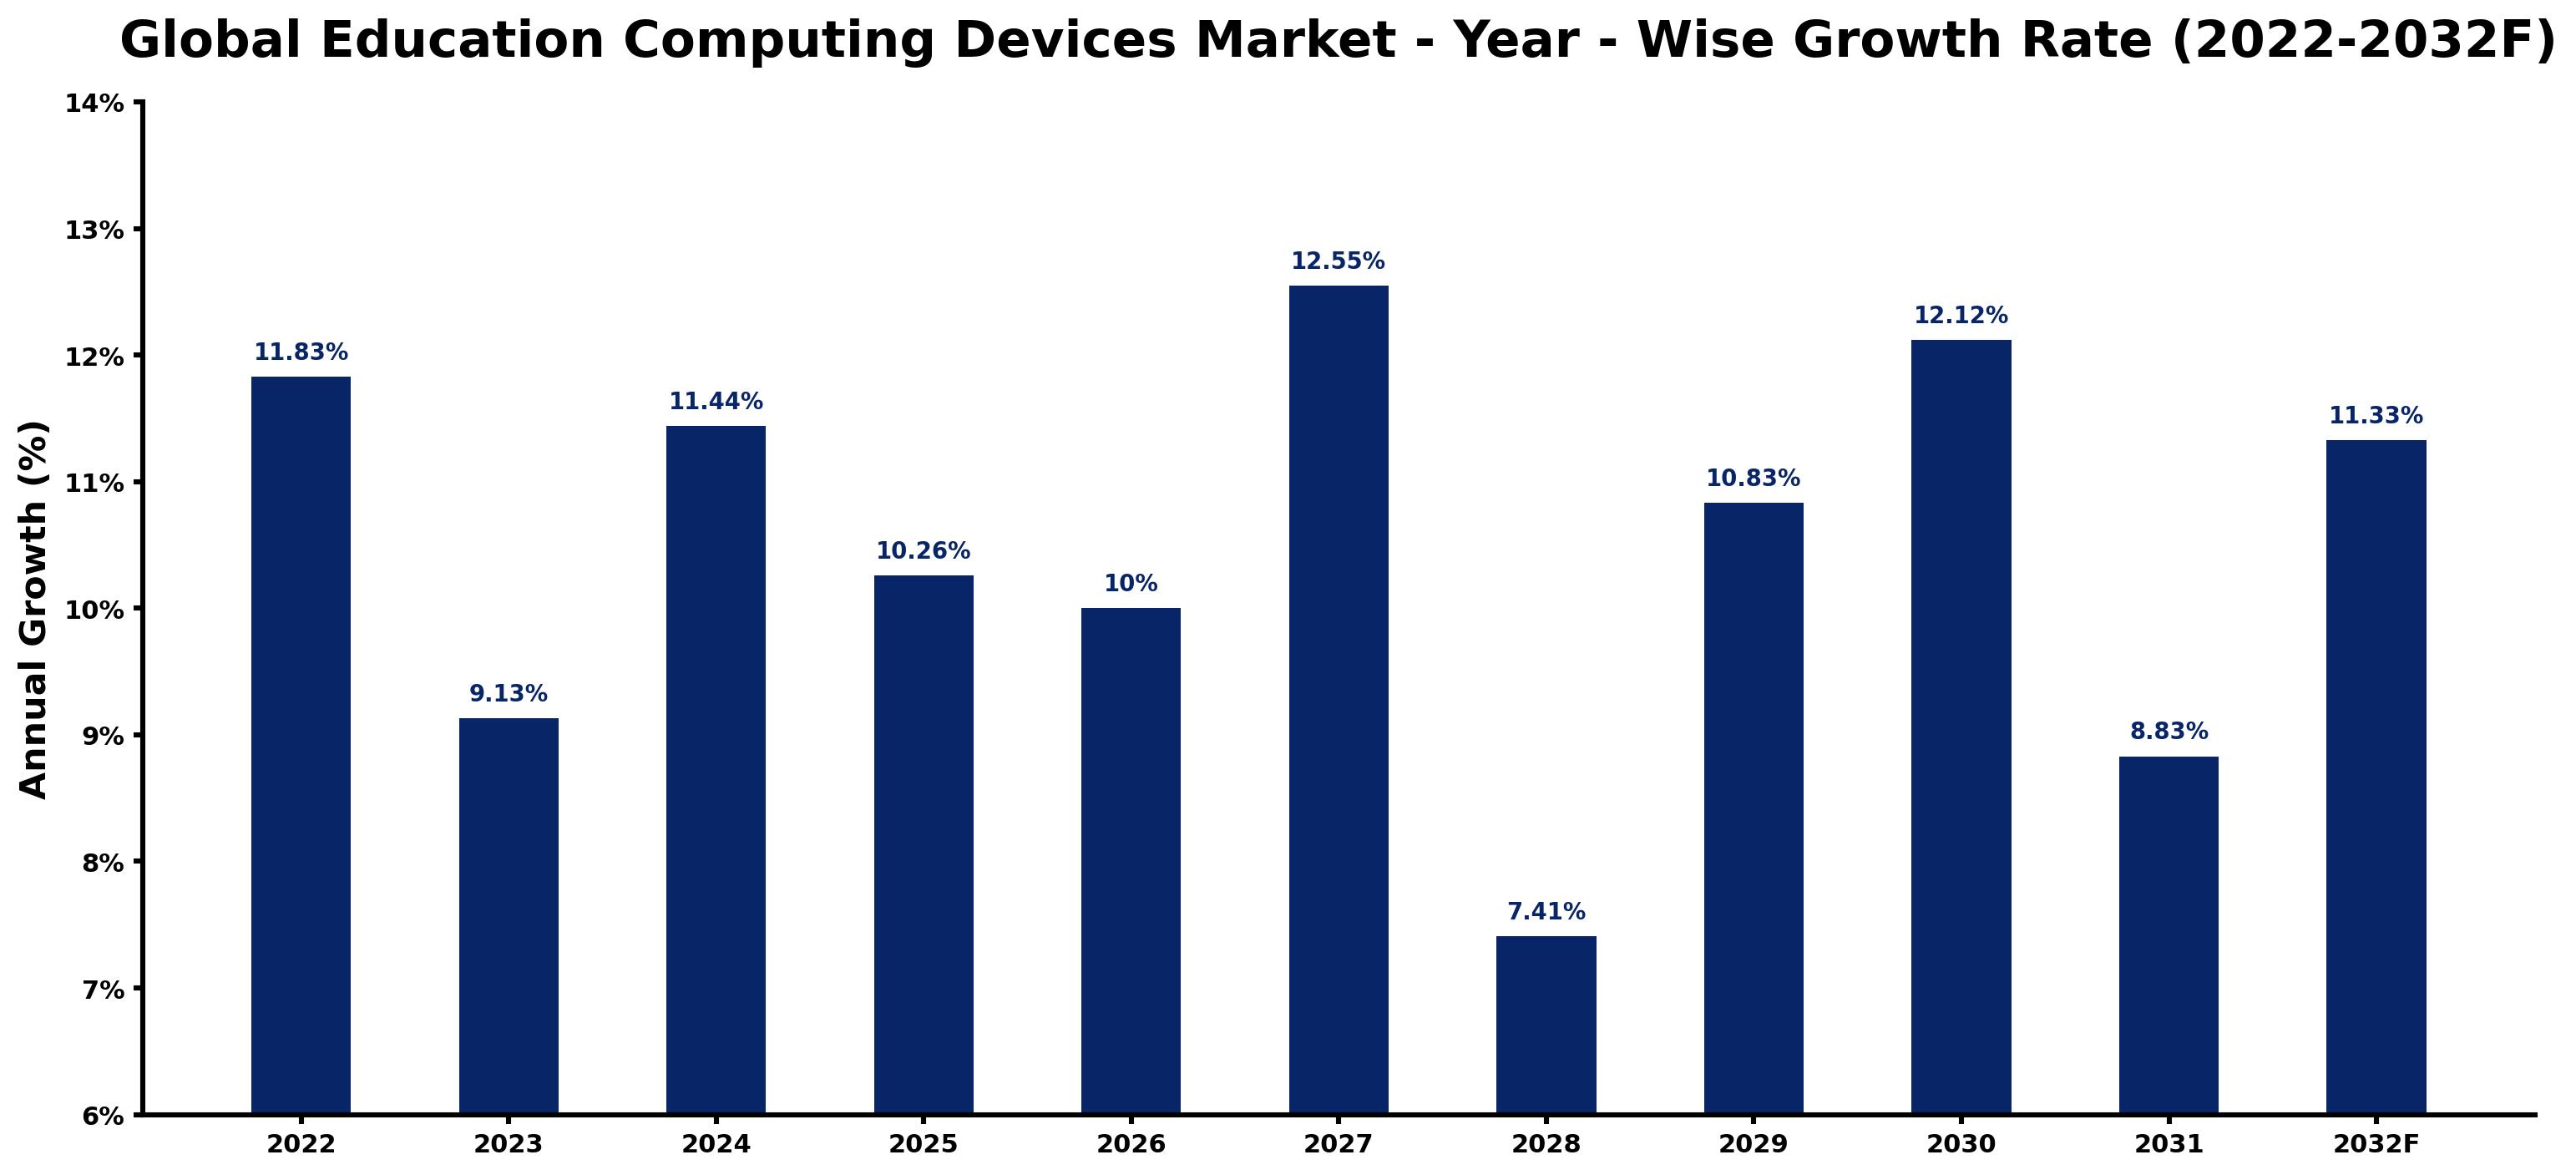
The table below presents the year‑wise growth rates along with the key drivers influencing the market
| Year | Growth Rate (%) | Major Drivers |
| 2022 | 11.83 | Expanding competition among brands enhances innovation in education computing devices. |
| 2023 | 9.13 | Increasing demand for education computing devices drives regional distribution channel expansion. |
| 2024 | 11.44 | Manufacturers engaging in M&A activities are strengthening product offerings in education devices. |
| 2025 | 10.26 | As governments implement educational reforms, adoption of education computing devices accelerates. |
| 2026 | 10 | Emphasizing eco-friendly materials in education computing devices improves sustainability practices across sectors. |
| 2027 | 12.55 | Artificial intelligence advancements are reshaping the functionalities of education computing devices. |
| 2028 | 7.41 | Schools and universities face rising raw material costs, influencing education computing device pricing strategies. |
| 2029 | 10.83 | Students increasingly prioritize interactive features, compelling manufacturers to innovate in education devices. |
| 2030 | 12.12 | A shift toward direct-to-consumer supply chains alters the distribution of education computing devices. |
| 2031 | 8.83 | In corporate training environments, evolving workforce skills are boosting interest in education devices. |
| 2032 | 11.33 | Growing awareness among educators about digital tools highlights the importance of education computing devices. |
Note - Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary research methodology, combining internal industry data, secondary research, and primary validation, updated periodically to reflect current market conditions. As markets evolve rapidly, figures for certain industries may vary slightly and are intended as informed estimates rather than absolute figures. For the most current market sizing, we recommend validating figures with a 6Wresearch analyst.
Global Education Computing Devices Market Key Takeaways
Below are some of the specific key takeaways from the market, including:
- In 2025, laptops will command approximately 45% of the Global Education Computing Devices Market share, largely due to their versatility and established role in education.
- The tablet segment is expected to grow at a CAGR of 15% from 2026 to 2032, reflecting increasing adoption in primary and secondary education settings.
- Government funding initiatives, such as the Digital Education Action Plan (2021) by the European Commission, aim to allocate around EUR 30 billion for digital education improvements and infrastructure.
- Asia is projected to become the fastest-growing region, potentially expanding by approximately 14% CAGR from 2026 to 2032, driven by a rising focus on digital literacy.
- Dell Technologies and Lenovo have emerged as dominant players, with market shares of approximately 20% and 18%, respectively, reflecting their extensive product offerings and brand recognition.
Evaluation of Restraints in Global Education Computing Devices Market
The Global Education Computing Devices Market faces several constraints, primarily stemming from socio-economic disparities in access to technology. For instance, educational institutions in developing regions often contend with budget constraints, limiting their ability to procure adequate devices. Specific data indicates that an estimated 40% of schools in low-income countries lack sufficient computing devices. This inadequacy not only hinders effective teaching but also exacerbates educational inequities. For example, a recent survey highlighted that over 60% of students in underserved areas are unable to carry out online educational activities due to a lack of access to suitable devices.
Global Education Computing Devices Market Trends
The Global Education Computing Devices Market is witnessing several transformative trends driven by evolving technological demands. A notable trend right now is the integration of artificial intelligence in educational devices, as seen with Apple's recent launch of the latest iPad equipped with advanced AI tools aimed specifically at enhancing student learning experiences. This incorporation not only boosts personalized learning but also improves interactive engagement in classrooms. Additionally, the push towards hybrid learning models is prompting schools globally to adopt more multifunctional devices, encouraging manufacturers to innovate rapidly to meet these emerging requirements.
Global Education Computing Devices Market Opportunities
As the education sector adapts continuously to technological advancements, several revenue opportunities are emerging within the Global Education Computing Devices Market. Notably, the rising focus on cybersecurity solutions within educational environments provides a significant revenue stream; firms like Cisco Systems are targeting educational institutions for security solutions capable of safeguarding sensitive student data. Furthermore, the expansion of distance learning programs creates pathways for companies specializing in portable devices. A forecast suggests that the demand for internet-enabled laptops could surge, as educational institutions aim to reach more students through remote learning, potentially increasing revenue capacity by up to 20% by 2032.
Global Education Computing Devices Market by Product Type
In the Global Education Computing Devices Market, laptops hold the largest share, accounting for approximately 45% as of 2025. This dominance stems from their versatility across educational levels, offering enhanced user experiences over other devices. However, tablets are identified as the fastest-growing segment, projected to experience a robust CAGR of 15% from 2026 to 2032. This growth is attributed to tablets' lightweight, portable design and their growing adaptability in primary education, where they are increasingly used to engage younger learners through interactive content and applications.
Global Education Computing Devices Market by End User
Within the Global Education Computing Devices Market, the secondary education segment leads in terms of share, commanding roughly 50% of the market as of 2025. This substantial share reflects the critical role of technology in enriching secondary education environments. Conversely, the primary education sector is emerging as the fastest-growing segment, anticipated to achieve a CAGR of 14% from 2026 to 2032. The increasing investment in early childhood education solutions underscores this growth, as schools seek to introduce sophisticated digital tools aimed at foundational learning.
Global Education Computing Devices Market by Region
North America is the largest region in the Global Education Computing Devices Market, expected to hold around 48% of market share in 2025, driven by significant investments from both governmental and private entities in educational technology. However, Asia stands out as the fastest-growing region, expected to exhibit a CAGR of 14% from 2026 to 2032, reflecting increasing government initiatives aimed at boosting digital literacy across various countries and a burgeoning tech-consuming population eager to integrate technology into education.
Government Initiatives in the Global Education Computing Devices Market
The regulatory landscape for the Global Education Computing Devices Market is actively shaped by various government initiatives aiming to enhance accessibility and quality of education through technology. Policymakers globally are recognizing the urgent need for these initiatives, which impact the market by facilitating infrastructure improvements and providing financial resources to educational institutions.
- The Digital Education Action Plan, European Commission, 2021 - This initiative aims to allocate EUR 30 billion for improving digital education infrastructure, impacting schools' purchasing capacity for computing devices.
- The National Education Technology Plan, U.S. Department of Education, 2020 - This ongoing scheme focuses on funding programs that help integrate technology into classrooms, enhancing the demand for educational computing devices.
- The National Digital Strategy, Government of India, 2022 - A planned initiative to invest $5 billion in technology deployment across educational institutions, aimed at bolstering the availability of educational computing resources.
- The Tech for All Initiative, United Nations Educational, Scientific and Cultural Organization (UNESCO), 2023 - An upcoming global initiative intended to enhance technological access in education with various funding allocations for device procurement.
Future Insights of the Global Education Computing Devices Market
The trajectory of the Global Education Computing Devices Market is anticipated to shift towards enhanced personalization and smart learning environments. Institutions are increasingly exploring immersive technologies such as virtual reality (VR) and augmented reality (AR). Recent initiatives, for instance, by Lenovo have showcased AR headsets designed for classroom applications, highlighting the potential to transform learning experiences. As schools adopt hybrid learning models, integration of cloud-based services will also become pivotal, ensuring that educational content remains accessible and interactive, thereby fostering deeper engagement among students.
Global Education Computing Devices Market Latest Developments
Several key developments in the market have emerged, indicating a dynamic landscape:
- In January 2023, Dell Technologies expanded its portfolio with a new line of ruggedized laptops specifically designed for educational environments, enhancing durability for younger users and promoting increased safety in settings susceptible to wear and tear.
- HP Inc. recently introduced a digital wellness program in March 2023 to support mental health and online learning environments, underscoring the company's commitment to ensuring a conducive learning atmosphere.
- Acer Inc. launched an innovative cloud-based education platform for its devices in February 2023, which enables seamless integration across various devices, thereby streamlining access to learning materials.
- In April 2023, Apple Inc. announced updates to its iPad educational app, incorporating enhanced AI-driven features that facilitate personalized learning paths for students.
Global Education Computing Devices Market Key Players and Industry Positioning
The competitive landscape of the Global Education Computing Devices Market is characterized by a mix of established companies and emerging innovators, leading to a relatively consolidated structure. Key players are focusing on differentiating their offerings through technological advancements and strategic initiatives to capture market share.
| Leading Company | Core Strength | Strategic Focus |
|---|---|---|
| Dell Technologies | Strong focus on education-specific rugged devices. | Expanding product line tailored for young learners. |
| Lenovo Group Limited | Leader in Chromebook sales for schools. | Innovating with immersive AR technology for learning. |
| HP Inc. | Excellent brand reputation in educational tech. | Enhancing online learning through mental health initiatives. |
| Apple Inc. | Strong ecosystem of user-friendly educational apps. | Integrating AI in tools for personalized student experiences. |
| Acer Inc. | Affordable pricing with effective value propositions. | Developing cloud-based platforms for seamless accessibility. |
The interplay among these players indicates a robust competitive framework. Strategic collaborations and technology enhancements are expected to shape the industry’s future.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year: 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- Global Education Computing Devices Market Outlook
- Market Size of Global Education Computing Devices Market, 2025
- Forecast of Global Education Computing Devices Market, 2032
- Historical Data and Forecast of Global Education Computing Devices Revenues & Volume for the Period 2022-2032
- Global Education Computing Devices Market Trend Evolution
- Global Education Computing Devices Market Drivers and Challenges
- Global Education Computing Devices Price Trends
- Global Education Computing Devices Porter's Five Forces
- Global Education Computing Devices Industry Life Cycle
- Historical Data and Forecast of Global Education Computing Devices Market Revenues & Volume
- Historical Data and Forecast of Global Education Computing Devices Market Revenues & Volume By Product Type for the Period 2022-2032
- Historical Data and Forecast of Global Education Computing Devices Market Revenues & Volume By Smartphones for the Period 2022-2032
- Historical Data and Forecast of Global Education Computing Devices Market Revenues & Volume By Laptops for the Period 2022-2032
- Historical Data and Forecast of Global Education Computing Devices Market Revenues & Volume By Tablets for the Period 2022-2032
- Historical Data and Forecast of Global Education Computing Devices Market Revenues & Volume By End User for the Period 2022-2032
- Historical Data and Forecast of Global Education Computing Devices Market Revenues & Volume By Primary for the Period 2022-2032
- Historical Data and Forecast of Global Education Computing Devices Market Revenues & Volume By Secondary for the Period 2022-2032
- Historical Data and Forecast of Global Education Computing Devices Market Revenues & Volume By Higher Secondary for the Period 2022-2032
- Historical Data and Forecast of North America Education Computing Devices Market Revenues & Volume By Product Type for the Period 2022-2032
- Historical Data and Forecast of North America Education Computing Devices Market Revenues & Volume By Smartphones for the Period 2022-2032
- Historical Data and Forecast of North America Education Computing Devices Market Revenues & Volume By Laptops for the Period 2022-2032
- Historical Data and Forecast of North America Education Computing Devices Market Revenues & Volume By Tablets for the Period 2022-2032
- Historical Data and Forecast of North America Education Computing Devices Market Revenues & Volume By End User for the Period 2022-2032
- Historical Data and Forecast of North America Education Computing Devices Market Revenues & Volume By Primary for the Period 2022-2032
- Historical Data and Forecast of North America Education Computing Devices Market Revenues & Volume By Secondary for the Period 2022-2032
- Historical Data and Forecast of North America Education Computing Devices Market Revenues & Volume By Higher Secondary for the Period 2022-2032
- Historical Data and Forecast of United States of America Education Computing Devices Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Canada Education Computing Devices Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Rest of North America Education Computing Devices Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) Education Computing Devices Market Revenues & Volume By Product Type for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) Education Computing Devices Market Revenues & Volume By Smartphones for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) Education Computing Devices Market Revenues & Volume By Laptops for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) Education Computing Devices Market Revenues & Volume By Tablets for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) Education Computing Devices Market Revenues & Volume By End User for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) Education Computing Devices Market Revenues & Volume By Primary for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) Education Computing Devices Market Revenues & Volume By Secondary for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) Education Computing Devices Market Revenues & Volume By Higher Secondary for the Period 2022-2032
- Historical Data and Forecast of Brazil Education Computing Devices Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Mexico Education Computing Devices Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Argentina Education Computing Devices Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Rest of LATAM Education Computing Devices Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Asia Education Computing Devices Market Revenues & Volume By Product Type for the Period 2022-2032
- Historical Data and Forecast of Asia Education Computing Devices Market Revenues & Volume By Smartphones for the Period 2022-2032
- Historical Data and Forecast of Asia Education Computing Devices Market Revenues & Volume By Laptops for the Period 2022-2032
- Historical Data and Forecast of Asia Education Computing Devices Market Revenues & Volume By Tablets for the Period 2022-2032
- Historical Data and Forecast of Asia Education Computing Devices Market Revenues & Volume By End User for the Period 2022-2032
- Historical Data and Forecast of Asia Education Computing Devices Market Revenues & Volume By Primary for the Period 2022-2032
- Historical Data and Forecast of Asia Education Computing Devices Market Revenues & Volume By Secondary for the Period 2022-2032
- Historical Data and Forecast of Asia Education Computing Devices Market Revenues & Volume By Higher Secondary for the Period 2022-2032
- Historical Data and Forecast of China Education Computing Devices Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of India Education Computing Devices Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Japan Education Computing Devices Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Rest of Asia Education Computing Devices Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Africa Education Computing Devices Market Revenues & Volume By Product Type for the Period 2022-2032
- Historical Data and Forecast of Africa Education Computing Devices Market Revenues & Volume By Smartphones for the Period 2022-2032
- Historical Data and Forecast of Africa Education Computing Devices Market Revenues & Volume By Laptops for the Period 2022-2032
- Historical Data and Forecast of Africa Education Computing Devices Market Revenues & Volume By Tablets for the Period 2022-2032
- Historical Data and Forecast of Africa Education Computing Devices Market Revenues & Volume By End User for the Period 2022-2032
- Historical Data and Forecast of Africa Education Computing Devices Market Revenues & Volume By Primary for the Period 2022-2032
- Historical Data and Forecast of Africa Education Computing Devices Market Revenues & Volume By Secondary for the Period 2022-2032
- Historical Data and Forecast of Africa Education Computing Devices Market Revenues & Volume By Higher Secondary for the Period 2022-2032
- Historical Data and Forecast of South Africa Education Computing Devices Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Nigeria Education Computing Devices Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Egypt Education Computing Devices Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Rest of Africa Education Computing Devices Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Europe Education Computing Devices Market Revenues & Volume By Product Type for the Period 2022-2032
- Historical Data and Forecast of Europe Education Computing Devices Market Revenues & Volume By Smartphones for the Period 2022-2032
- Historical Data and Forecast of Europe Education Computing Devices Market Revenues & Volume By Laptops for the Period 2022-2032
- Historical Data and Forecast of Europe Education Computing Devices Market Revenues & Volume By Tablets for the Period 2022-2032
- Historical Data and Forecast of Europe Education Computing Devices Market Revenues & Volume By End User for the Period 2022-2032
- Historical Data and Forecast of Europe Education Computing Devices Market Revenues & Volume By Primary for the Period 2022-2032
- Historical Data and Forecast of Europe Education Computing Devices Market Revenues & Volume By Secondary for the Period 2022-2032
- Historical Data and Forecast of Europe Education Computing Devices Market Revenues & Volume By Higher Secondary for the Period 2022-2032
- Historical Data and Forecast of United Kingdom Education Computing Devices Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of France Education Computing Devices Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Germany Education Computing Devices Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Rest of Europe Education Computing Devices Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Middle East Education Computing Devices Market Revenues & Volume By Product Type for the Period 2022-2032
- Historical Data and Forecast of Middle East Education Computing Devices Market Revenues & Volume By Smartphones for the Period 2022-2032
- Historical Data and Forecast of Middle East Education Computing Devices Market Revenues & Volume By Laptops for the Period 2022-2032
- Historical Data and Forecast of Middle East Education Computing Devices Market Revenues & Volume By Tablets for the Period 2022-2032
- Historical Data and Forecast of Middle East Education Computing Devices Market Revenues & Volume By End User for the Period 2022-2032
- Historical Data and Forecast of Middle East Education Computing Devices Market Revenues & Volume By Primary for the Period 2022-2032
- Historical Data and Forecast of Middle East Education Computing Devices Market Revenues & Volume By Secondary for the Period 2022-2032
- Historical Data and Forecast of Middle East Education Computing Devices Market Revenues & Volume By Higher Secondary for the Period 2022-2032
- Historical Data and Forecast of Saudi Arabia Education Computing Devices Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of UAE Education Computing Devices Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Turkey Education Computing Devices Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Rest of Middle East Education Computing Devices Market Revenues & Volume for the Period 2022-2032
- Global Education Computing Devices Market - Key Performance Indicators
- Global Education Computing Devices Market - Import Export Trade Statistics
- Global Education Computing Devices Market - Opportunity Assessment By Countries
- Global Education Computing Devices Market - Opportunity Assessment By Product Type
- Global Education Computing Devices Market - Opportunity Assessment By End User
- Global Education Computing Devices Market - Top Companies Market Share
- Global Education Computing Devices Market - Top Companies Profiles
- Global Education Computing Devices Market - Comparison of Players in Technical and Operating Parameters
- Global Education Computing Devices Market - Strategic Recommendations
Markets Covered
The Global Education Computing Devices Market report provides a detailed analysis of the following market segments:
By Regions and Countries:
- North America
- Europe
- LATAM
- Middle East
- Asia
- Africa
By Product Type:
- Smartphones
- Laptops
- Tablets
By End User:
- Primary
- Secondary
- Higher Secondary
Global Education Computing Devices Market - Frequently Asked Questions
The Global Education Computing Devices Market is projected to reach USD 96.7 Billion by 2032.
The expected CAGR for the Global Education Computing Devices Market from 2026 to 2032 is 11.14%.
Key drivers include increased government initiatives for digital learning, the rising need for personalized learning environments, and enhanced security measures in educational institutions.
Currently, laptops hold the largest market share, while tablets are the fastest-growing segment, reflecting their expanding use in primary and secondary education.
The market is set to evolve with significant technological integration, leading to enhanced learning experiences, especially with emerging tools like AR and VR expected to shape classroom settings.
6Wresearch actively monitors the Global Education Computing Devices Market and publishes its comprehensive annual report, highlighting emerging trends, growth drivers, revenue analysis, and forecast outlook. Our insights help businesses to make data-backed strategic decisions with ongoing market dynamics. Our analysts track relevent industries related to the Global Education Computing Devices Market, allowing our clients with actionable intelligence and reliable forecasts tailored to emerging regional needs.
Yes, we provide customisation as per your requirements. To learn more, feel free to contact us on sales@6wresearch.com
Global Education Computing Devices Market |
1 Executive Summary |
2 Introduction |
2.1 Key Highlights of the Report |
2.2 Report Description |
2.3 Market Scope & Segmentation |
2.4 Research Methodology |
2.5 Assumptions |
3 Global Education Computing Devices Market Overview |
3.1 Global Regional Macro Economic Indicators |
3.2 Global Education Computing Devices Market Revenues & Volume, 2022 & 2032F |
3.3 Global Education Computing Devices Market - Industry Life Cycle |
3.4 Global Education Computing Devices Market - Porter's Five Forces |
3.5 Global Education Computing Devices Market Revenues & Volume Share, By Regions, 2022 & 2032F |
3.6 Global Education Computing Devices Market Revenues & Volume Share, By Product Type, 2022 & 2032F |
3.7 Global Education Computing Devices Market Revenues & Volume Share, By End User, 2022 & 2032F |
4 Global Education Computing Devices Market Dynamics |
4.1 Impact Analysis |
4.2 Market Drivers |
4.3 Market Restraints |
5 Global Education Computing Devices Market Trends |
6 Global Education Computing Devices Market, 2022-2032 |
6.1 Global Education Computing Devices Market, Revenues & Volume, By Product Type, 2022-2032 |
6.1.1 Overview & Analysis |
6.1.2 Global Education Computing Devices Market, Revenues & Volume, By Smartphones, 2022-2032 |
6.1.3 Global Education Computing Devices Market, Revenues & Volume, By Laptops, 2022-2032 |
6.1.4 Global Education Computing Devices Market, Revenues & Volume, By Tablets, 2022-2032 |
6.2 Global Education Computing Devices Market, Revenues & Volume, By End User, 2022-2032 |
6.2.1 Overview & Analysis |
6.2.2 Global Education Computing Devices Market, Revenues & Volume, By Primary, 2022-2032 |
6.2.3 Global Education Computing Devices Market, Revenues & Volume, By Secondary, 2022-2032 |
6.2.4 Global Education Computing Devices Market, Revenues & Volume, By Higher Secondary, 2022-2032 |
6.3.1 Overview & Analysis |
7 North America Education Computing Devices Market, Overview & Analysis |
7.1 North America Education Computing Devices Market Revenues & Volume, 2022-2032 |
7.2 North America Education Computing Devices Market, Revenues & Volume, By Countries, 2022-2032 |
7.2.1 United States (US) Education Computing Devices Market, Revenues & Volume, 2022-2032 |
7.2.2 Canada Education Computing Devices Market, Revenues & Volume, 2022-2032 |
7.2.3 Rest of North America Education Computing Devices Market, Revenues & Volume, 2022-2032 |
7.3 North America Education Computing Devices Market, Revenues & Volume, By Product Type, 2022-2032 |
7.4 North America Education Computing Devices Market, Revenues & Volume, By End User, 2022-2032 |
8 Latin America (LATAM) Education Computing Devices Market, Overview & Analysis |
8.1 Latin America (LATAM) Education Computing Devices Market Revenues & Volume, 2022-2032 |
8.2 Latin America (LATAM) Education Computing Devices Market, Revenues & Volume, By Countries, 2022-2032 |
8.2.1 Brazil Education Computing Devices Market, Revenues & Volume, 2022-2032 |
8.2.2 Mexico Education Computing Devices Market, Revenues & Volume, 2022-2032 |
8.2.3 Argentina Education Computing Devices Market, Revenues & Volume, 2022-2032 |
8.2.4 Rest of LATAM Education Computing Devices Market, Revenues & Volume, 2022-2032 |
8.3 Latin America (LATAM) Education Computing Devices Market, Revenues & Volume, By Product Type, 2022-2032 |
8.4 Latin America (LATAM) Education Computing Devices Market, Revenues & Volume, By End User, 2022-2032 |
9 Asia Education Computing Devices Market, Overview & Analysis |
9.1 Asia Education Computing Devices Market Revenues & Volume, 2022-2032 |
9.2 Asia Education Computing Devices Market, Revenues & Volume, By Countries, 2022-2032 |
9.2.1 India Education Computing Devices Market, Revenues & Volume, 2022-2032 |
9.2.2 China Education Computing Devices Market, Revenues & Volume, 2022-2032 |
9.2.3 Japan Education Computing Devices Market, Revenues & Volume, 2022-2032 |
9.2.4 Rest of Asia Education Computing Devices Market, Revenues & Volume, 2022-2032 |
9.3 Asia Education Computing Devices Market, Revenues & Volume, By Product Type, 2022-2032 |
9.4 Asia Education Computing Devices Market, Revenues & Volume, By End User, 2022-2032 |
10 Africa Education Computing Devices Market, Overview & Analysis |
10.1 Africa Education Computing Devices Market Revenues & Volume, 2022-2032 |
10.2 Africa Education Computing Devices Market, Revenues & Volume, By Countries, 2022-2032 |
10.2.1 South Africa Education Computing Devices Market, Revenues & Volume, 2022-2032 |
10.2.2 Egypt Education Computing Devices Market, Revenues & Volume, 2022-2032 |
10.2.3 Nigeria Education Computing Devices Market, Revenues & Volume, 2022-2032 |
10.2.4 Rest of Africa Education Computing Devices Market, Revenues & Volume, 2022-2032 |
10.3 Africa Education Computing Devices Market, Revenues & Volume, By Product Type, 2022-2032 |
10.4 Africa Education Computing Devices Market, Revenues & Volume, By End User, 2022-2032 |
11 Europe Education Computing Devices Market, Overview & Analysis |
11.1 Europe Education Computing Devices Market Revenues & Volume, 2022-2032 |
11.2 Europe Education Computing Devices Market, Revenues & Volume, By Countries, 2022-2032 |
11.2.1 United Kingdom Education Computing Devices Market, Revenues & Volume, 2022-2032 |
11.2.2 Germany Education Computing Devices Market, Revenues & Volume, 2022-2032 |
11.2.3 France Education Computing Devices Market, Revenues & Volume, 2022-2032 |
11.2.4 Rest of Europe Education Computing Devices Market, Revenues & Volume, 2022-2032 |
11.3 Europe Education Computing Devices Market, Revenues & Volume, By Product Type, 2022-2032 |
11.4 Europe Education Computing Devices Market, Revenues & Volume, By End User, 2022-2032 |
12 Middle East Education Computing Devices Market, Overview & Analysis |
12.1 Middle East Education Computing Devices Market Revenues & Volume, 2022-2032 |
12.2 Middle East Education Computing Devices Market, Revenues & Volume, By Countries, 2022-2032 |
12.2.1 Saudi Arabia Education Computing Devices Market, Revenues & Volume, 2022-2032 |
12.2.2 UAE Education Computing Devices Market, Revenues & Volume, 2022-2032 |
12.2.3 Turkey Education Computing Devices Market, Revenues & Volume, 2022-2032 |
12.3 Middle East Education Computing Devices Market, Revenues & Volume, By Product Type, 2022-2032 |
12.4 Middle East Education Computing Devices Market, Revenues & Volume, By End User, 2022-2032 |
13 Global Education Computing Devices Market Key Performance Indicators |
14 Global Education Computing Devices Market - Export/Import By Countries Assessment |
15 Global Education Computing Devices Market - Opportunity Assessment |
15.1 Global Education Computing Devices Market Opportunity Assessment, By Countries, 2022 & 2032F |
15.2 Global Education Computing Devices Market Opportunity Assessment, By Product Type, 2022 & 2032F |
15.3 Global Education Computing Devices Market Opportunity Assessment, By End User, 2022 & 2032F |
16 Global Education Computing Devices Market - Competitive Landscape |
16.1 Global Education Computing Devices Market Revenue Share, By Companies, 2025 |
16.2 Global Education Computing Devices Market Competitive Benchmarking, By Operating and Technical Parameters |
17 Top 10 Company Profiles |
18 Recommendations |
19 Disclaimer |
Global Go To Market Strategy - 2030
Export potential enables firms to identify high-growth global markets with greater confidence by combining advanced trade intelligence with a structured quantitative methodology. The framework analyzes emerging demand trends and country-level import patterns while integrating macroeconomic and trade datasets such as GDP and population forecasts, bilateral import–export flows, tariff structures, elasticity differentials between developed and developing economies, geographic distance, and import demand projections. Using weighted trade values from 2020–2024 as the base period to project country-to-country export potential for 2030, these inputs are operationalized through calculated drivers such as gravity model parameters, tariff impact factors, and projected GDP per-capita growth. Through an analysis of hidden potentials, demand hotspots, and market conditions that are most favorable to success, this method enables firms to focus on target countries, maximize returns, and global expansion with data, backed by accuracy.
By factoring in the projected importer demand gap that is currently unmet and could be potential opportunity, it identifies the potential for the Exporter (Country) among 190 countries, against the general trade analysis, which identifies the biggest importer or exporter.
To discover high-growth global markets and optimize your business strategy:
Click Here
Request Primary Research & Report
- Single User License$ 4,560
- Department License$ 5,055
- Site License$ 5,595
- Global License$ 6,000
Leadership Perspectives from Industry Events
Search
6Wresearch in the News
 Forbes
Citing 6Wresearch analytics to map global infrastructure and pharmaceutical industry trajectories.
 Bloomberg Law
Direct syndication of 6Wresearch's macro data points, capturing complex supply chain shifts.
 Reuters
Tracking industrial manufacturing adjustments and electronic security ecosystem scaling.
 Mint
Utilizing deep-tech sector market sizing to analyze global automation and robotics.
 The Economic Times
Anchoring features on industrial IoT growth metrics and connected smart-grid devices.
 Business Standard
Featuring strategic evaluations of Advanced Driver Assistance Systems (ADAS) and AI road safety.
 The Hindu
Spotlighting core commercial metrics ranging from unmanned aerial vehicles (UAVs) to consumer durables.
 Financial Express
Anchoring quarterly reviews on cross-border real estate tech and structural hardware manufacturing.
 Yahoo Finance
Syndicating the tracker's $30.1 billion untapped-market findings, spotlighting Japan, the US and China as India's top new-potential importers.
 India Today
Carrying the release on smartphones leading India's export potential to $94 billion by 2031, per 6WExportGTM data.
 Dailyhunt
Distributing the tracker findings to its regional readership, framing India's export diversification into Japan and Mexico.
 PR Newswire Original release
Publishing the full India Export Attractiveness Tracker 2026, detailing new trade corridors across iron ore, LCVs and pharmaceuticals.
 The Industrial
Highlighting the tracker's read on India's semiconductor ambitions and long-term chip-assembly export potential.
 PTI News
Reporting on the $66.81 billion pharmaceuticals export opportunity flagged in the tracker, amid looming US generic-drug tariffs.
 Tribune India
Covering the tracker's tariff-versus-regulation analysis across India's mature export markets in the US, China and UAE.
 ANI News
Amplifying the report's findings on polished diamonds, refined petroleum and medicines as India's core export engines.
 International Business Magazine
Covering the report's insight into how AEB, blind spot detection, and driver monitoring are reshaping India's ADAS market.
 Focus Gaming News
Highlighting the research forecast for Egypt's gambling market, projecting steady growth through 2032.
Thought Leadership and Analyst Meet
Our Clients
Latest Reports
- Austria X-ray Imaging Devices Market (2026-2032)
- Armenia X-ray Imaging Devices Market (2026-2032)
- Antigua and Barbuda X-ray Imaging Devices Market (2026-2032)
- Angola X-ray Imaging Devices Market (2026-2032)
- Andorra X-ray Imaging Devices Market (2026-2032)
- Albania X-ray Imaging Devices Market (2026-2032)
- Afghanistan X-ray Imaging Devices Market (2026-2032)
- United States (US) X-ray Imaging Devices Market (2026-2032)
- United Kingdom (UK) X-ray Imaging Devices Market (2026-2032)
- United Arab Emirates (UAE) X-ray Imaging Devices Market (2026-2032)
Industry Events and Analyst Meet

EV India Expo 2026
HIMTEX 2026
India Refining Summit 2026
India EV Show 2026
EV tech India Expo 2026
Whitepaper
- Middle East & Africa Commercial Security Market Click here to view more.
- Middle East & Africa Fire Safety Systems & Equipment Market Click here to view more.
- GCC Drone Market Click here to view more.
- Middle East Lighting Fixture Market Click here to view more.
- GCC Physical & Perimeter Security Market Click here to view more.