Global Iron And Steel Mills And Ferroalloy Market (2026-2032) | Demand, Companies, Strategy, Drivers, Growth, Analysis, Trends, Supply, Segments, Opportunities, Consumer Insights, Investment Trends, Industry, Forecast, Competition, Revenue, Challenges, Pricing Analysis, Share, Size, Strategic Insights, Segmentation, Restraints, Value, Competitive, Outlook
Market Forecast by Regions and Countries (North America, Europe, LATAM, Middle East, Asia and Africa), By Type (Ferroalloys, Pig Iron, Crude Steel), By End-User (Automotive, Machinery, Oil and Gas, Construction, Others) And Competitive Landscape
| Product Code: ETC13389236 | Publication Date: Apr 2025 | Updated Date: Sep 2026 | Product Type: Market Research Report | |
| Publisher: 6Wresearch | Author: Shubham Deep | No. of Pages: 190 | No. of Figures: 80 | No. of Tables: 40 |
Global Iron And Steel Mills And Ferroalloy Market Highlights
| Market Size (2025) | USD 942 Billion |
| Forecast Size (2032) | USD 1219 Billion |
| CAGR | 4.60% |
| Base Year | 2025 |
| Forecast Period | 2026-2032 |
| Largest Region | Asia-Pacific |
| Fastest Growing Region | LATAM |
| Largest Segment | Crude Steel |
| Fastest Growing Segment | Ferroalloys |
| Leading Companies | ArcelorMittal, Nucor Corporation, Tata Steel, POSCO, China Baowu Steel Group |
Global Iron And Steel Mills And Ferroalloy Market Size & Growth Rate (2026-2032)
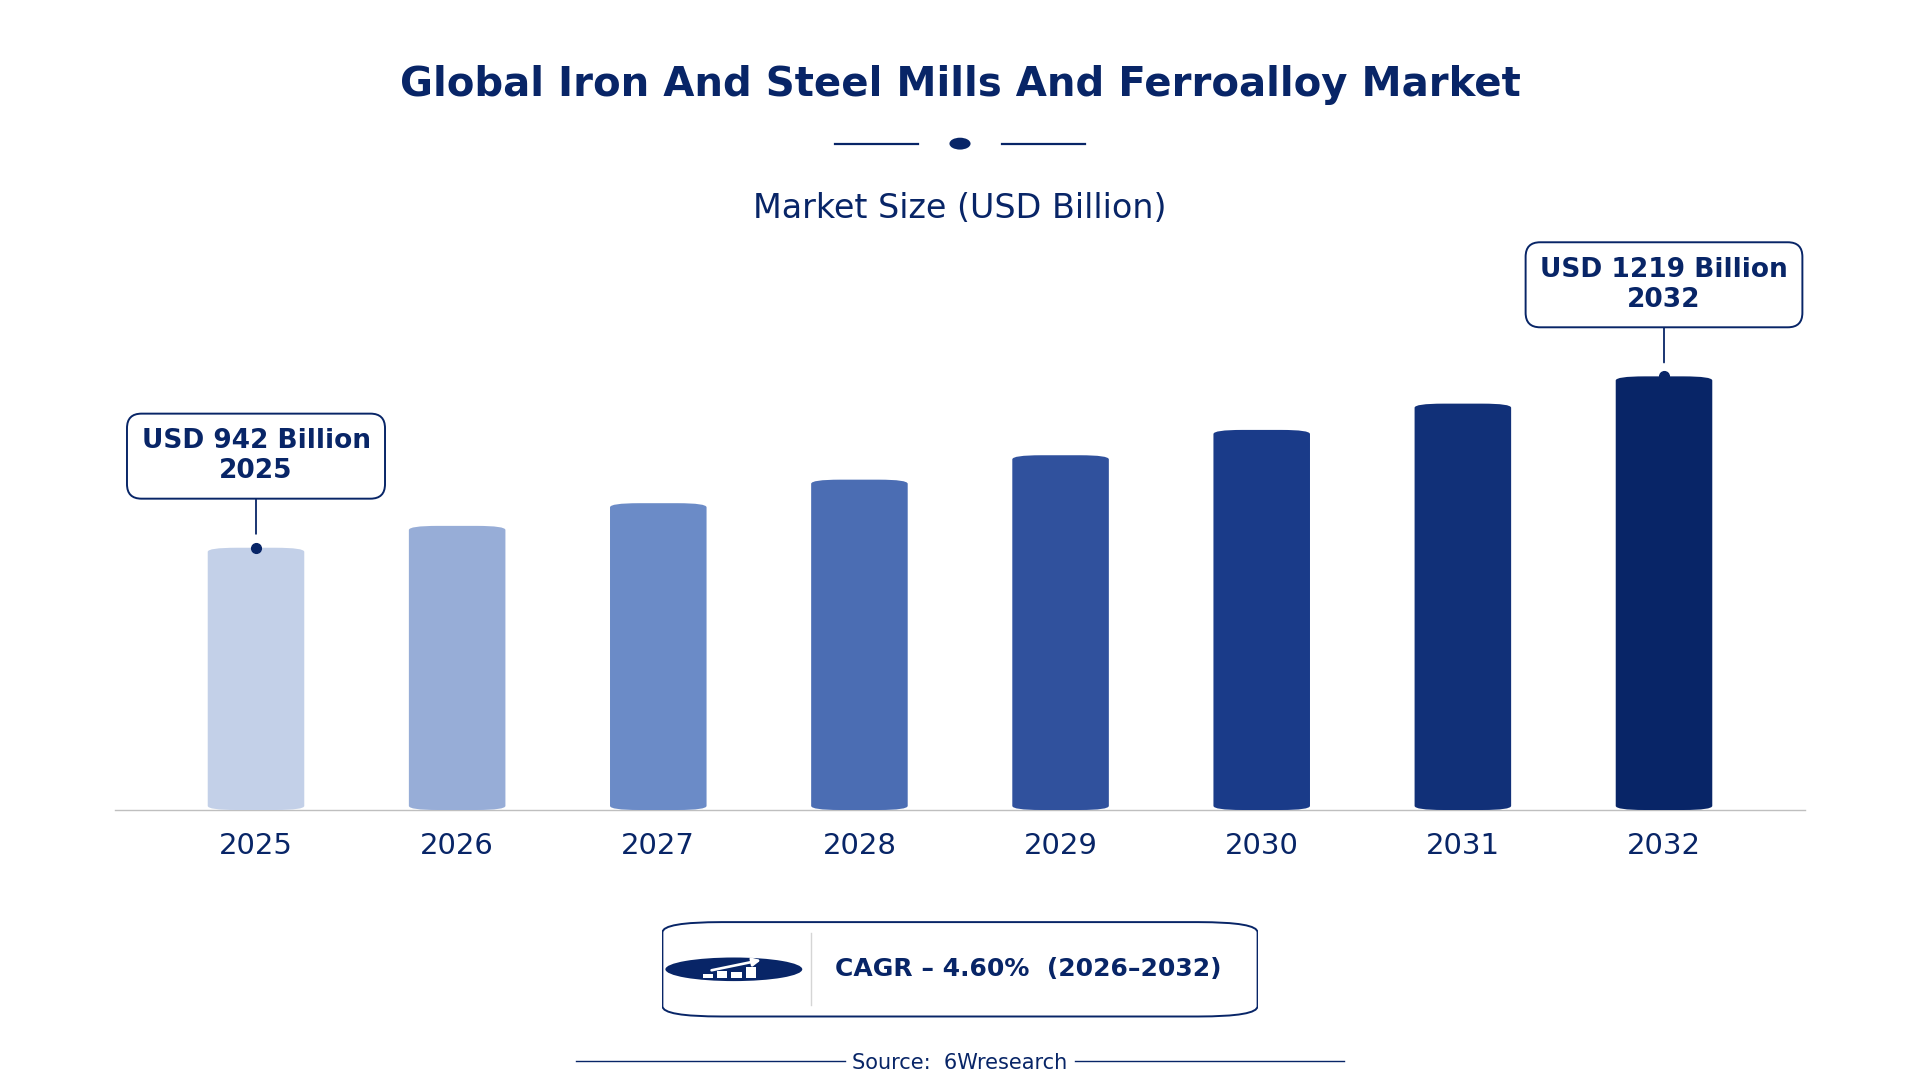
The Global Iron And Steel Mills And Ferroalloy Market was estimated at USD 942 Billion in 2025 and is projected to reach USD 1219 Billion by 2032, growing at a CAGR of 4.60% from 2026 to 2032.
Global Iron And Steel Mills And Ferroalloy Market Synopsis
The global iron and steel mills and ferroalloy market is undergoing transformative changes, with increasing focus on efficiency, sustainability, and advanced manufacturing techniques. Key industries such as construction, automotive, and infrastructure are relying on high-quality materials, thereby influencing production strategies and operational frameworks within the market.
These shifts are not just reshaping supply chains but also setting the stage for innovation in product offerings. The demand for eco-friendly solutions is pushing manufacturers to rethink their operations, resulting in investments towards state-of-the-art technology and eco-conscious production methods, which will delineate this market from others within the metals industry.
Global Iron And Steel Mills And Ferroalloy Market Year-wise Growth Rate and Key Drivers
This graph illustrates the annual growth rates of the Global Iron And Steel Mills And Ferroalloy Market from 2022 to 2032, highlighting a steady upward trajectory and projected expansion over the forecast period.
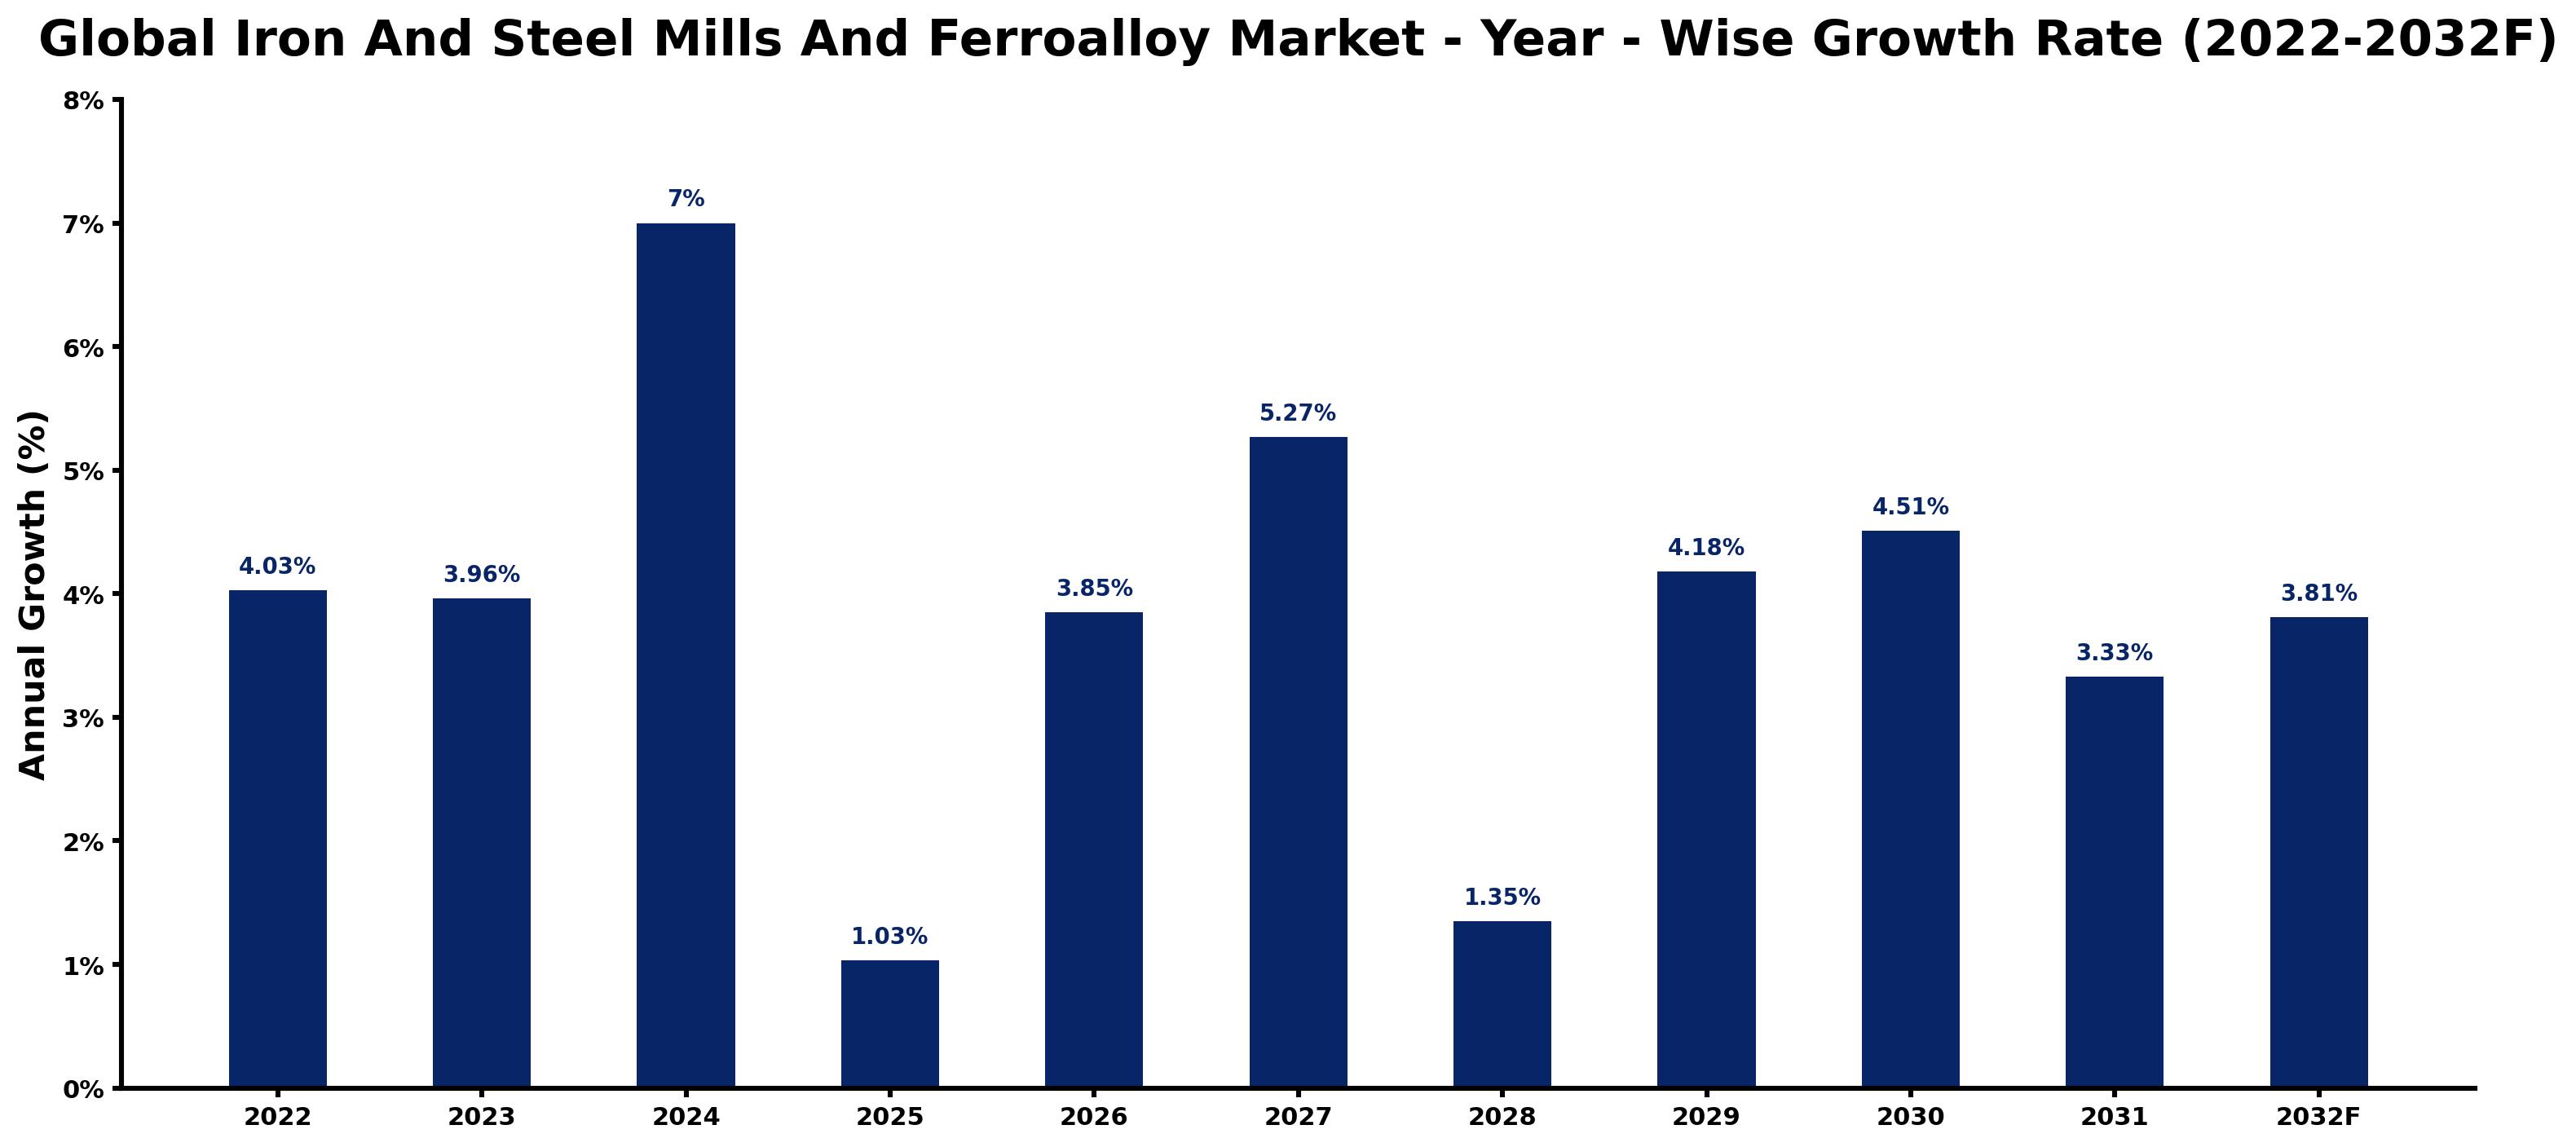
The table below presents the year‑wise growth rates along with the key drivers influencing the market
| Year | Growth Rate (%) | Major Drivers |
| 2022 | 4.03 | Investments in advanced iron and steel mills enhance production capabilities during recovery. |
| 2023 | 3.96 | In North America, competitive shifts are reshaping the iron and steel mills sector. |
| 2024 | 7 | Increasing metal recycling rates improve efficiency in steel production processes significantly. |
| 2025 | 1.03 | Manufacturers shifting preferences toward sustainable ferroalloy sources support changing consumer behavior. |
| 2026 | 3.85 | Producers face challenges from supply chain dynamics affecting steel mills' performance and costs. |
| 2027 | 5.27 | Enhanced regulation around steel production safety standards pushes mills toward compliance improvements. |
| 2028 | 1.35 | A shift toward higher ore extraction yields influences the input cost dynamics in steel production. |
| 2029 | 4.18 | Geographic expansions in Asia lead to increased smelting capacity and industry consolidation across markets. |
| 2030 | 4.51 | Automotive manufacturers increasingly demand high-quality steel, driving market growth and innovation. |
| 2031 | 3.33 | Integrating new metallurgical processing techniques accelerates efficiency in ferroalloy production methods. |
| 2032 | 3.81 | As global focus on sustainability intensifies, iron and steel mills adopt greener practices. |
Note - Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary research methodology, combining internal industry data, secondary research, and primary validation, updated periodically to reflect current market conditions. As markets evolve rapidly, figures for certain industries may vary slightly and are intended as informed estimates rather than absolute figures. For the most current market sizing, we recommend validating figures with a 6Wresearch analyst.
Global Iron And Steel Mills And Ferroalloy Market Key Takeaways
Below are some of the specific key takeaways from the market, including:
- Asia-Pacific accounted for approximately 58% of the market share in 2025, driven by industrial growth in China and India.
- Crude Steel production is leading the market, securing roughly 70% share as of 2025, reflecting its critical use across multiple sectors.
- Ferroalloys are expected to register a notable CAGR of 6.2% from 2026 to 2032, attributed to increasing usage in specialty steels.
- The global iron and steel sector is projected to attract over USD 70 billion in investments toward sustainable practices by 2030, highlighting the shift towards greener initiatives.
- Key players like Tata Steel have committed to reaching carbon neutrality by 2045, which will significantly alter competitive dynamics.
Evaluation of Restraints in Global Iron And Steel Mills And Ferroalloy Market
Fluctuating raw material prices pose a substantial threat to profitability in the global iron and steel mills and ferroalloy market. For instance, iron ore prices have shown volatility, ranging from USD 70 to USD 140 per metric ton in recent years, which pressures margins. Furthermore, regulatory compliance costs associated with environmental sustainability requirements are estimated to escalate by up to 25% in the next few years, particularly as countries tighten emissions standards. For example, the European Union's Green Deal mandates stricter rules on carbon emissions, compelling mills to invest heavily in technology upgrades and process adjustments.
Global Iron And Steel Mills And Ferroalloy Market Trends
The market is experiencing several notable trends impacting its operational and technological landscape. First, the focus on sustainable production methods is intensifying, as evidenced by companies like Nucor Corporation, which aims to achieve net-zero greenhouse gas emissions by 2050 through innovative recycling practices. Second, digitalization is transforming traditional practices; for instance, the integration of AI in supply chain optimization is reported to decrease operational costs by around 15%. Lastly, the rise of advanced manufacturing techniques, particularly in ferroalloy production, signifies a shift towards precision and customization. This trend meets the specific demands of high-performance sectors like aerospace and automotive, pushing the industry towards more versatile solutions.
Global Iron And Steel Mills And Ferroalloy Market Opportunities
Emerging revenue opportunities in the global iron and steel mills and ferroalloy market are linked to technological innovation and evolving consumer preferences. The surge in electric vehicle (EV) manufacturing represents a substantial growth avenue, with companies like Tesla aiming for a production output of 20 million vehicles annually by 2030, leading to increased steel requirements. Another opportunity lies in the growing demand for high-strength, lightweight materials, especially in the construction sector, prompting investments exceeding USD 15 billion in R&D by major players. Moreover, initiatives in carbon capture technology are creating investment potentials, with projections indicating that such technologies could capture 40 million tons of CO2 by 2030, substantially impacting long-term sustainability goals.
Global Iron And Steel Mills And Ferroalloy Market by Type
Crude Steel commands the largest market share, accounting for approximately 70% share in 2025, cementing its role as the backbone of the iron production sector due to extensive applications in automotive and construction. Ferroalloys, however, are emerging as the fastest-growing segment, with a projected CAGR of 6.2% from 2026 to 2032, driven by their essential application in high-strength steel alloys and specialized applications.
Global Iron And Steel Mills And Ferroalloy Market by End-User
The construction sector remains the leading end-user for iron and steel products, holding approximately 47% market share in 2025, fueled by ongoing infrastructure projects globally. However, the automotive industry is anticipated to experience the fastest growth, with a CAGR of 5.3% from 2026 to 2032, as it increasingly demands lighter, more fuel-efficient materials to meet regulatory standards.
Global Iron And Steel Mills And Ferroalloy Market by Region
The Asia-Pacific region continues to dominate the global market, capturing around 58% share in 2025, bolstered by rapid industrial growth in China and India. Conversely, the LATAM region is projected to be the fastest-growing area, with a CAGR of 5.5% from 2026 to 2032, as governments prioritize infrastructure development and clean technology initiatives in countries like Brazil and Argentina.
Government Initiatives in the Global Iron And Steel Mills And Ferroalloy Market
The regulatory landscape for the global iron and steel mills and ferroalloy market is influenced by various governmental initiatives aimed at enhancing sustainability, driving production efficiency, and ensuring environmental compliance. These efforts not only shape operational frameworks but also create incentives for innovation within the market.
- European Commission, "Fit for 55" Initiative, 2021: Aims to reduce greenhouse gas emissions by at least 55% by 2030, impacting production standards across the EU.
- U.S. Department of Energy, "Clean Energy Standard," 2022: Encourages investment in energy-efficient steel technologies through subsidies and tax incentives.
- Government of India, National Steel Policy 2017, Revised in 2021: Aims to enhance production capacity and promote sustainability in steel making, targeting a production of 300 million tonnes by 2030.
- Ministry of Steel, Government of India, "Steel Scrap Recycling Policy," 2022: Focuses on creating a framework for the recycling of scrap steel to reduce reliance on virgin materials.
Future Insights of the Global Iron And Steel Mills And Ferroalloy Market
The landscape of the Global Iron And Steel Mills And Ferroalloy Market is forecasted to shift significantly by 2032. Major corporations are now focusing investments toward carbon-neutral technologies, with Tata Steel aiming for carbon neutrality by 2045. This reflects a broader transition toward sustainable practices across the industry. The increasing integration of advanced materials in construction and automotive applications, particularly in lightweight, high-strength steel, will redefine production capacities and operational methodologies, steering the market toward more eco-friendly solutions.
Global Iron And Steel Mills And Ferroalloy Market Latest Developments
Recent developments in the Global Iron And Steel Mills And Ferroalloy Market highlight significant shifts in focus and strategy among leading players. The following are key updates:
- In July 2023, Nucor Corporation initiated an expansion of its rebar capacity to enhance its production efficiency, reflecting a strategy to meet rising demand in the construction sector.
- By early 2024, POSCO is set to introduce a new line for producing eco-friendly steel, targeting sustainability and the reduced carbon footprint associated with traditional methods.
- ArcelorMittal announced in March 2023 that it will invest USD 1 billion into digital transformation for its production facilities, aiming to streamline operations and bolster technological capabilities.
- China Baowu Steel Group finalized plans in August 2023 to acquire several smaller mills to enhance its market position and increase production capacity amidst intensifying competition.
Global Iron And Steel Mills And Ferroalloy Market Key Players and Industry Positioning
The competitive structure of the Global Iron And Steel Mills And Ferroalloy Market is characterized by both consolidation and fragmentation, involving a mix of established giants and emerging players. This dynamic allows for various competitive strategies, including mergers, acquisitions, and technological investments that shape market offerings.
| Leading Company | Core Strength | Strategic Focus |
|---|---|---|
| ArcelorMittal | Global leader in steel production with diverse product offerings. | Digital transformation and sustainability initiatives. |
| Nucor Corporation | Robust recycling capabilities and efficient operations. | Carbon reduction strategies and expansion into new markets. |
| Tata Steel | Strong brand equity and extensive geographic reach. | Innovation in product development and sustainability commitments. |
| POSCO | Technological leadership in steel manufacturing. | Focus on eco-friendly production techniques and R&D investments. |
| China Baowu Steel Group | Large scale and significant production capacity. | Acquisition strategies to enhance market position. |
As the market evolves, these companies are likely to continue shaping industry standards and consumer expectations, especially in areas related to sustainability and technological advancement.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year: 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- Global Iron And Steel Mills And Ferroalloy Market Outlook
- Market Size of Global Iron And Steel Mills And Ferroalloy Market, 2025
- Forecast of Global Iron And Steel Mills And Ferroalloy Market, 2032
- Historical Data and Forecast of Global Iron And Steel Mills And Ferroalloy Revenues & Volume for the Period 2022-2032
- Global Iron And Steel Mills And Ferroalloy Market Trend Evolution
- Global Iron And Steel Mills And Ferroalloy Market Drivers and Challenges
- Global Iron And Steel Mills And Ferroalloy Price Trends
- Global Iron And Steel Mills And Ferroalloy Porter's Five Forces
- Global Iron And Steel Mills And Ferroalloy Industry Life Cycle
- Historical Data and Forecast of Global Iron And Steel Mills And Ferroalloy Market Revenues & Volume
- Historical Data and Forecast of Global Iron And Steel Mills And Ferroalloy Market Revenues & Volume By Type for the Period 2022-2032
- Historical Data and Forecast of Global Iron And Steel Mills And Ferroalloy Market Revenues & Volume By Ferroalloys for the Period 2022-2032
- Historical Data and Forecast of Global Iron And Steel Mills And Ferroalloy Market Revenues & Volume By Pig Iron for the Period 2022-2032
- Historical Data and Forecast of Global Iron And Steel Mills And Ferroalloy Market Revenues & Volume By Crude Steel for the Period 2022-2032
- Historical Data and Forecast of Global Iron And Steel Mills And Ferroalloy Market Revenues & Volume By End-User for the Period 2022-2032
- Historical Data and Forecast of Global Iron And Steel Mills And Ferroalloy Market Revenues & Volume By Automotive for the Period 2022-2032
- Historical Data and Forecast of Global Iron And Steel Mills And Ferroalloy Market Revenues & Volume By Machinery for the Period 2022-2032
- Historical Data and Forecast of Global Iron And Steel Mills And Ferroalloy Market Revenues & Volume By Oil and Gas for the Period 2022-2032
- Historical Data and Forecast of Global Iron And Steel Mills And Ferroalloy Market Revenues & Volume By Construction for the Period 2022-2032
- Historical Data and Forecast of Global Iron And Steel Mills And Ferroalloy Market Revenues & Volume By Others for the Period 2022-2032
- Historical Data and Forecast of North America Iron And Steel Mills And Ferroalloy Market Revenues & Volume By Type for the Period 2022-2032
- Historical Data and Forecast of North America Iron And Steel Mills And Ferroalloy Market Revenues & Volume By Ferroalloys for the Period 2022-2032
- Historical Data and Forecast of North America Iron And Steel Mills And Ferroalloy Market Revenues & Volume By Pig Iron for the Period 2022-2032
- Historical Data and Forecast of North America Iron And Steel Mills And Ferroalloy Market Revenues & Volume By Crude Steel for the Period 2022-2032
- Historical Data and Forecast of North America Iron And Steel Mills And Ferroalloy Market Revenues & Volume By End-User for the Period 2022-2032
- Historical Data and Forecast of North America Iron And Steel Mills And Ferroalloy Market Revenues & Volume By Automotive for the Period 2022-2032
- Historical Data and Forecast of North America Iron And Steel Mills And Ferroalloy Market Revenues & Volume By Machinery for the Period 2022-2032
- Historical Data and Forecast of North America Iron And Steel Mills And Ferroalloy Market Revenues & Volume By Oil and Gas for the Period 2022-2032
- Historical Data and Forecast of North America Iron And Steel Mills And Ferroalloy Market Revenues & Volume By Construction for the Period 2022-2032
- Historical Data and Forecast of North America Iron And Steel Mills And Ferroalloy Market Revenues & Volume By Others for the Period 2022-2032
- Historical Data and Forecast of United States of America Iron And Steel Mills And Ferroalloy Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Canada Iron And Steel Mills And Ferroalloy Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Rest of North America Iron And Steel Mills And Ferroalloy Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) Iron And Steel Mills And Ferroalloy Market Revenues & Volume By Type for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) Iron And Steel Mills And Ferroalloy Market Revenues & Volume By Ferroalloys for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) Iron And Steel Mills And Ferroalloy Market Revenues & Volume By Pig Iron for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) Iron And Steel Mills And Ferroalloy Market Revenues & Volume By Crude Steel for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) Iron And Steel Mills And Ferroalloy Market Revenues & Volume By End-User for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) Iron And Steel Mills And Ferroalloy Market Revenues & Volume By Automotive for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) Iron And Steel Mills And Ferroalloy Market Revenues & Volume By Machinery for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) Iron And Steel Mills And Ferroalloy Market Revenues & Volume By Oil and Gas for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) Iron And Steel Mills And Ferroalloy Market Revenues & Volume By Construction for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) Iron And Steel Mills And Ferroalloy Market Revenues & Volume By Others for the Period 2022-2032
- Historical Data and Forecast of Brazil Iron And Steel Mills And Ferroalloy Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Mexico Iron And Steel Mills And Ferroalloy Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Argentina Iron And Steel Mills And Ferroalloy Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Rest of LATAM Iron And Steel Mills And Ferroalloy Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Asia Iron And Steel Mills And Ferroalloy Market Revenues & Volume By Type for the Period 2022-2032
- Historical Data and Forecast of Asia Iron And Steel Mills And Ferroalloy Market Revenues & Volume By Ferroalloys for the Period 2022-2032
- Historical Data and Forecast of Asia Iron And Steel Mills And Ferroalloy Market Revenues & Volume By Pig Iron for the Period 2022-2032
- Historical Data and Forecast of Asia Iron And Steel Mills And Ferroalloy Market Revenues & Volume By Crude Steel for the Period 2022-2032
- Historical Data and Forecast of Asia Iron And Steel Mills And Ferroalloy Market Revenues & Volume By End-User for the Period 2022-2032
- Historical Data and Forecast of Asia Iron And Steel Mills And Ferroalloy Market Revenues & Volume By Automotive for the Period 2022-2032
- Historical Data and Forecast of Asia Iron And Steel Mills And Ferroalloy Market Revenues & Volume By Machinery for the Period 2022-2032
- Historical Data and Forecast of Asia Iron And Steel Mills And Ferroalloy Market Revenues & Volume By Oil and Gas for the Period 2022-2032
- Historical Data and Forecast of Asia Iron And Steel Mills And Ferroalloy Market Revenues & Volume By Construction for the Period 2022-2032
- Historical Data and Forecast of Asia Iron And Steel Mills And Ferroalloy Market Revenues & Volume By Others for the Period 2022-2032
- Historical Data and Forecast of China Iron And Steel Mills And Ferroalloy Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of India Iron And Steel Mills And Ferroalloy Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Japan Iron And Steel Mills And Ferroalloy Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Rest of Asia Iron And Steel Mills And Ferroalloy Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Africa Iron And Steel Mills And Ferroalloy Market Revenues & Volume By Type for the Period 2022-2032
- Historical Data and Forecast of Africa Iron And Steel Mills And Ferroalloy Market Revenues & Volume By Ferroalloys for the Period 2022-2032
- Historical Data and Forecast of Africa Iron And Steel Mills And Ferroalloy Market Revenues & Volume By Pig Iron for the Period 2022-2032
- Historical Data and Forecast of Africa Iron And Steel Mills And Ferroalloy Market Revenues & Volume By Crude Steel for the Period 2022-2032
- Historical Data and Forecast of Africa Iron And Steel Mills And Ferroalloy Market Revenues & Volume By End-User for the Period 2022-2032
- Historical Data and Forecast of Africa Iron And Steel Mills And Ferroalloy Market Revenues & Volume By Automotive for the Period 2022-2032
- Historical Data and Forecast of Africa Iron And Steel Mills And Ferroalloy Market Revenues & Volume By Machinery for the Period 2022-2032
- Historical Data and Forecast of Africa Iron And Steel Mills And Ferroalloy Market Revenues & Volume By Oil and Gas for the Period 2022-2032
- Historical Data and Forecast of Africa Iron And Steel Mills And Ferroalloy Market Revenues & Volume By Construction for the Period 2022-2032
- Historical Data and Forecast of Africa Iron And Steel Mills And Ferroalloy Market Revenues & Volume By Others for the Period 2022-2032
- Historical Data and Forecast of South Africa Iron And Steel Mills And Ferroalloy Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Nigeria Iron And Steel Mills And Ferroalloy Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Egypt Iron And Steel Mills And Ferroalloy Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Rest of Africa Iron And Steel Mills And Ferroalloy Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Europe Iron And Steel Mills And Ferroalloy Market Revenues & Volume By Type for the Period 2022-2032
- Historical Data and Forecast of Europe Iron And Steel Mills And Ferroalloy Market Revenues & Volume By Ferroalloys for the Period 2022-2032
- Historical Data and Forecast of Europe Iron And Steel Mills And Ferroalloy Market Revenues & Volume By Pig Iron for the Period 2022-2032
- Historical Data and Forecast of Europe Iron And Steel Mills And Ferroalloy Market Revenues & Volume By Crude Steel for the Period 2022-2032
- Historical Data and Forecast of Europe Iron And Steel Mills And Ferroalloy Market Revenues & Volume By End-User for the Period 2022-2032
- Historical Data and Forecast of Europe Iron And Steel Mills And Ferroalloy Market Revenues & Volume By Automotive for the Period 2022-2032
- Historical Data and Forecast of Europe Iron And Steel Mills And Ferroalloy Market Revenues & Volume By Machinery for the Period 2022-2032
- Historical Data and Forecast of Europe Iron And Steel Mills And Ferroalloy Market Revenues & Volume By Oil and Gas for the Period 2022-2032
- Historical Data and Forecast of Europe Iron And Steel Mills And Ferroalloy Market Revenues & Volume By Construction for the Period 2022-2032
- Historical Data and Forecast of Europe Iron And Steel Mills And Ferroalloy Market Revenues & Volume By Others for the Period 2022-2032
- Historical Data and Forecast of United Kingdom Iron And Steel Mills And Ferroalloy Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of France Iron And Steel Mills And Ferroalloy Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Germany Iron And Steel Mills And Ferroalloy Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Rest of Europe Iron And Steel Mills And Ferroalloy Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Middle East Iron And Steel Mills And Ferroalloy Market Revenues & Volume By Type for the Period 2022-2032
- Historical Data and Forecast of Middle East Iron And Steel Mills And Ferroalloy Market Revenues & Volume By Ferroalloys for the Period 2022-2032
- Historical Data and Forecast of Middle East Iron And Steel Mills And Ferroalloy Market Revenues & Volume By Pig Iron for the Period 2022-2032
- Historical Data and Forecast of Middle East Iron And Steel Mills And Ferroalloy Market Revenues & Volume By Crude Steel for the Period 2022-2032
- Historical Data and Forecast of Middle East Iron And Steel Mills And Ferroalloy Market Revenues & Volume By End-User for the Period 2022-2032
- Historical Data and Forecast of Middle East Iron And Steel Mills And Ferroalloy Market Revenues & Volume By Automotive for the Period 2022-2032
- Historical Data and Forecast of Middle East Iron And Steel Mills And Ferroalloy Market Revenues & Volume By Machinery for the Period 2022-2032
- Historical Data and Forecast of Middle East Iron And Steel Mills And Ferroalloy Market Revenues & Volume By Oil and Gas for the Period 2022-2032
- Historical Data and Forecast of Middle East Iron And Steel Mills And Ferroalloy Market Revenues & Volume By Construction for the Period 2022-2032
- Historical Data and Forecast of Middle East Iron And Steel Mills And Ferroalloy Market Revenues & Volume By Others for the Period 2022-2032
- Historical Data and Forecast of Saudi Arabia Iron And Steel Mills And Ferroalloy Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of UAE Iron And Steel Mills And Ferroalloy Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Turkey Iron And Steel Mills And Ferroalloy Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Rest of Middle East Iron And Steel Mills And Ferroalloy Market Revenues & Volume for the Period 2022-2032
- Global Iron And Steel Mills And Ferroalloy Market - Key Performance Indicators
- Global Iron And Steel Mills And Ferroalloy Market - Import Export Trade Statistics
- Global Iron And Steel Mills And Ferroalloy Market - Opportunity Assessment By Countries
- Global Iron And Steel Mills And Ferroalloy Market - Opportunity Assessment By Type
- Global Iron And Steel Mills And Ferroalloy Market - Opportunity Assessment By End-User
- Global Iron And Steel Mills And Ferroalloy Market - Top Companies Market Share
- Global Iron And Steel Mills And Ferroalloy Market - Top Companies Profiles
- Global Iron And Steel Mills And Ferroalloy Market - Comparison of Players in Technical and Operating Parameters
- Global Iron And Steel Mills And Ferroalloy Market - Strategic Recommendations
Markets Covered
The Global Iron And Steel Mills And Ferroalloy Market report provides a detailed analysis of the following market segments:
By Regions and Countries:
- North America
- Europe
- LATAM
- Middle East
- Asia
- Africa
By Type:
- Ferroalloys
- Pig Iron
- Crude Steel
By End-User:
- Automotive
- Machinery
- Oil
- Gas
- Construction
- Others
Global Iron And Steel Mills And Ferroalloy Market - Frequently Asked Questions
The Global Iron And Steel Mills And Ferroalloy Market is projected to reach USD 1219 Billion by 2032, growing at a CAGR of 4.60% from 2026 to 2032.
Key drivers include increasing construction activities, rising demand for high-strength materials, and advancements in production technology focused on sustainability.
The Crude Steel segment is expected to maintain its leading position, commanding around 70% of the market share in 2025 due to its extensive applications.
The industry faces challenges such as fluctuating raw material prices, increasing regulatory compliance costs, and the need for significant investments in technology upgrades.
The landscape is evolving through consolidation, with major players acquiring smaller firms to enhance production capacity, as well as a focus on sustainable practices and digital transformation to stay competitive.
Innovations such as carbon capture technology, advanced manufacturing techniques, and the increased use of AI for supply chain optimization are revolutionizing the industry.
6Wresearch actively monitors the Global Iron And Steel Mills And Ferroalloy Market and publishes its comprehensive annual report, highlighting emerging trends, growth drivers, revenue analysis, and forecast outlook. Our insights help businesses to make data-backed strategic decisions with ongoing market dynamics. Our analysts track relevent industries related to the Global Iron And Steel Mills And Ferroalloy Market, allowing our clients with actionable intelligence and reliable forecasts tailored to emerging regional needs.
Yes, we provide customisation as per your requirements. To learn more, feel free to contact us on sales@6wresearch.com
Global Iron And Steel Mills And Ferroalloy Market |
1 Executive Summary |
2 Introduction |
2.1 Key Highlights of the Report |
2.2 Report Description |
2.3 Market Scope & Segmentation |
2.4 Research Methodology |
2.5 Assumptions |
3 Global Iron And Steel Mills And Ferroalloy Market Overview |
3.1 Global Regional Macro Economic Indicators |
3.2 Global Iron And Steel Mills And Ferroalloy Market Revenues & Volume, 2022 & 2032F |
3.3 Global Iron And Steel Mills And Ferroalloy Market - Industry Life Cycle |
3.4 Global Iron And Steel Mills And Ferroalloy Market - Porter's Five Forces |
3.5 Global Iron And Steel Mills And Ferroalloy Market Revenues & Volume Share, By Regions, 2022 & 2032F |
3.6 Global Iron And Steel Mills And Ferroalloy Market Revenues & Volume Share, By Type, 2022 & 2032F |
3.7 Global Iron And Steel Mills And Ferroalloy Market Revenues & Volume Share, By End-User, 2022 & 2032F |
4 Global Iron And Steel Mills And Ferroalloy Market Dynamics |
4.1 Impact Analysis |
4.2 Market Drivers |
4.3 Market Restraints |
5 Global Iron And Steel Mills And Ferroalloy Market Trends |
6 Global Iron And Steel Mills And Ferroalloy Market, 2022-2032 |
6.1 Global Iron And Steel Mills And Ferroalloy Market, Revenues & Volume, By Type, 2022-2032 |
6.1.1 Overview & Analysis |
6.1.2 Global Iron And Steel Mills And Ferroalloy Market, Revenues & Volume, By Ferroalloys, 2022-2032 |
6.1.3 Global Iron And Steel Mills And Ferroalloy Market, Revenues & Volume, By Pig Iron, 2022-2032 |
6.1.4 Global Iron And Steel Mills And Ferroalloy Market, Revenues & Volume, By Crude Steel, 2022-2032 |
6.2 Global Iron And Steel Mills And Ferroalloy Market, Revenues & Volume, By End-User, 2022-2032 |
6.2.1 Overview & Analysis |
6.2.2 Global Iron And Steel Mills And Ferroalloy Market, Revenues & Volume, By Automotive, 2022-2032 |
6.2.3 Global Iron And Steel Mills And Ferroalloy Market, Revenues & Volume, By Machinery, 2022-2032 |
6.2.4 Global Iron And Steel Mills And Ferroalloy Market, Revenues & Volume, By Oil and Gas, 2022-2032 |
6.2.5 Global Iron And Steel Mills And Ferroalloy Market, Revenues & Volume, By Construction, 2022-2032 |
6.2.6 Global Iron And Steel Mills And Ferroalloy Market, Revenues & Volume, By Others, 2022-2032 |
6.3.1 Overview & Analysis |
7 North America Iron And Steel Mills And Ferroalloy Market, Overview & Analysis |
7.1 North America Iron And Steel Mills And Ferroalloy Market Revenues & Volume, 2022-2032 |
7.2 North America Iron And Steel Mills And Ferroalloy Market, Revenues & Volume, By Countries, 2022-2032 |
7.2.1 United States (US) Iron And Steel Mills And Ferroalloy Market, Revenues & Volume, 2022-2032 |
7.2.2 Canada Iron And Steel Mills And Ferroalloy Market, Revenues & Volume, 2022-2032 |
7.2.3 Rest of North America Iron And Steel Mills And Ferroalloy Market, Revenues & Volume, 2022-2032 |
7.3 North America Iron And Steel Mills And Ferroalloy Market, Revenues & Volume, By Type, 2022-2032 |
7.4 North America Iron And Steel Mills And Ferroalloy Market, Revenues & Volume, By End-User, 2022-2032 |
8 Latin America (LATAM) Iron And Steel Mills And Ferroalloy Market, Overview & Analysis |
8.1 Latin America (LATAM) Iron And Steel Mills And Ferroalloy Market Revenues & Volume, 2022-2032 |
8.2 Latin America (LATAM) Iron And Steel Mills And Ferroalloy Market, Revenues & Volume, By Countries, 2022-2032 |
8.2.1 Brazil Iron And Steel Mills And Ferroalloy Market, Revenues & Volume, 2022-2032 |
8.2.2 Mexico Iron And Steel Mills And Ferroalloy Market, Revenues & Volume, 2022-2032 |
8.2.3 Argentina Iron And Steel Mills And Ferroalloy Market, Revenues & Volume, 2022-2032 |
8.2.4 Rest of LATAM Iron And Steel Mills And Ferroalloy Market, Revenues & Volume, 2022-2032 |
8.3 Latin America (LATAM) Iron And Steel Mills And Ferroalloy Market, Revenues & Volume, By Type, 2022-2032 |
8.4 Latin America (LATAM) Iron And Steel Mills And Ferroalloy Market, Revenues & Volume, By End-User, 2022-2032 |
9 Asia Iron And Steel Mills And Ferroalloy Market, Overview & Analysis |
9.1 Asia Iron And Steel Mills And Ferroalloy Market Revenues & Volume, 2022-2032 |
9.2 Asia Iron And Steel Mills And Ferroalloy Market, Revenues & Volume, By Countries, 2022-2032 |
9.2.1 India Iron And Steel Mills And Ferroalloy Market, Revenues & Volume, 2022-2032 |
9.2.2 China Iron And Steel Mills And Ferroalloy Market, Revenues & Volume, 2022-2032 |
9.2.3 Japan Iron And Steel Mills And Ferroalloy Market, Revenues & Volume, 2022-2032 |
9.2.4 Rest of Asia Iron And Steel Mills And Ferroalloy Market, Revenues & Volume, 2022-2032 |
9.3 Asia Iron And Steel Mills And Ferroalloy Market, Revenues & Volume, By Type, 2022-2032 |
9.4 Asia Iron And Steel Mills And Ferroalloy Market, Revenues & Volume, By End-User, 2022-2032 |
10 Africa Iron And Steel Mills And Ferroalloy Market, Overview & Analysis |
10.1 Africa Iron And Steel Mills And Ferroalloy Market Revenues & Volume, 2022-2032 |
10.2 Africa Iron And Steel Mills And Ferroalloy Market, Revenues & Volume, By Countries, 2022-2032 |
10.2.1 South Africa Iron And Steel Mills And Ferroalloy Market, Revenues & Volume, 2022-2032 |
10.2.2 Egypt Iron And Steel Mills And Ferroalloy Market, Revenues & Volume, 2022-2032 |
10.2.3 Nigeria Iron And Steel Mills And Ferroalloy Market, Revenues & Volume, 2022-2032 |
10.2.4 Rest of Africa Iron And Steel Mills And Ferroalloy Market, Revenues & Volume, 2022-2032 |
10.3 Africa Iron And Steel Mills And Ferroalloy Market, Revenues & Volume, By Type, 2022-2032 |
10.4 Africa Iron And Steel Mills And Ferroalloy Market, Revenues & Volume, By End-User, 2022-2032 |
11 Europe Iron And Steel Mills And Ferroalloy Market, Overview & Analysis |
11.1 Europe Iron And Steel Mills And Ferroalloy Market Revenues & Volume, 2022-2032 |
11.2 Europe Iron And Steel Mills And Ferroalloy Market, Revenues & Volume, By Countries, 2022-2032 |
11.2.1 United Kingdom Iron And Steel Mills And Ferroalloy Market, Revenues & Volume, 2022-2032 |
11.2.2 Germany Iron And Steel Mills And Ferroalloy Market, Revenues & Volume, 2022-2032 |
11.2.3 France Iron And Steel Mills And Ferroalloy Market, Revenues & Volume, 2022-2032 |
11.2.4 Rest of Europe Iron And Steel Mills And Ferroalloy Market, Revenues & Volume, 2022-2032 |
11.3 Europe Iron And Steel Mills And Ferroalloy Market, Revenues & Volume, By Type, 2022-2032 |
11.4 Europe Iron And Steel Mills And Ferroalloy Market, Revenues & Volume, By End-User, 2022-2032 |
12 Middle East Iron And Steel Mills And Ferroalloy Market, Overview & Analysis |
12.1 Middle East Iron And Steel Mills And Ferroalloy Market Revenues & Volume, 2022-2032 |
12.2 Middle East Iron And Steel Mills And Ferroalloy Market, Revenues & Volume, By Countries, 2022-2032 |
12.2.1 Saudi Arabia Iron And Steel Mills And Ferroalloy Market, Revenues & Volume, 2022-2032 |
12.2.2 UAE Iron And Steel Mills And Ferroalloy Market, Revenues & Volume, 2022-2032 |
12.2.3 Turkey Iron And Steel Mills And Ferroalloy Market, Revenues & Volume, 2022-2032 |
12.3 Middle East Iron And Steel Mills And Ferroalloy Market, Revenues & Volume, By Type, 2022-2032 |
12.4 Middle East Iron And Steel Mills And Ferroalloy Market, Revenues & Volume, By End-User, 2022-2032 |
13 Global Iron And Steel Mills And Ferroalloy Market Key Performance Indicators |
14 Global Iron And Steel Mills And Ferroalloy Market - Export/Import By Countries Assessment |
15 Global Iron And Steel Mills And Ferroalloy Market - Opportunity Assessment |
15.1 Global Iron And Steel Mills And Ferroalloy Market Opportunity Assessment, By Countries, 2022 & 2032F |
15.2 Global Iron And Steel Mills And Ferroalloy Market Opportunity Assessment, By Type, 2022 & 2032F |
15.3 Global Iron And Steel Mills And Ferroalloy Market Opportunity Assessment, By End-User, 2022 & 2032F |
16 Global Iron And Steel Mills And Ferroalloy Market - Competitive Landscape |
16.1 Global Iron And Steel Mills And Ferroalloy Market Revenue Share, By Companies, 2025 |
16.2 Global Iron And Steel Mills And Ferroalloy Market Competitive Benchmarking, By Operating and Technical Parameters |
17 Top 10 Company Profiles |
18 Recommendations |
19 Disclaimer |
Global Go To Market Strategy - 2030
Export potential enables firms to identify high-growth global markets with greater confidence by combining advanced trade intelligence with a structured quantitative methodology. The framework analyzes emerging demand trends and country-level import patterns while integrating macroeconomic and trade datasets such as GDP and population forecasts, bilateral import–export flows, tariff structures, elasticity differentials between developed and developing economies, geographic distance, and import demand projections. Using weighted trade values from 2020–2024 as the base period to project country-to-country export potential for 2030, these inputs are operationalized through calculated drivers such as gravity model parameters, tariff impact factors, and projected GDP per-capita growth. Through an analysis of hidden potentials, demand hotspots, and market conditions that are most favorable to success, this method enables firms to focus on target countries, maximize returns, and global expansion with data, backed by accuracy.
By factoring in the projected importer demand gap that is currently unmet and could be potential opportunity, it identifies the potential for the Exporter (Country) among 190 countries, against the general trade analysis, which identifies the biggest importer or exporter.
To discover high-growth global markets and optimize your business strategy:
Click Here
Request Primary Research & Report
- Single User License$4,560
- Department License$5,055
- Site License$5,595
- Global License$6,000
Leadership Perspectives from Industry Events
Search
6Wresearch in the News
 Forbes
Citing 6Wresearch analytics to map global infrastructure and pharmaceutical industry trajectories.
 Bloomberg Law
Direct syndication of 6Wresearch's macro data points, capturing complex supply chain shifts.
 Reuters
Tracking industrial manufacturing adjustments and electronic security ecosystem scaling.
 Mint
Utilizing deep-tech sector market sizing to analyze global automation and robotics.
 The Economic Times
Anchoring features on industrial IoT growth metrics and connected smart-grid devices.
 Business Standard
Featuring strategic evaluations of Advanced Driver Assistance Systems (ADAS) and AI road safety.
 The Hindu
Spotlighting core commercial metrics ranging from unmanned aerial vehicles (UAVs) to consumer durables.
 Financial Express
Anchoring quarterly reviews on cross-border real estate tech and structural hardware manufacturing.
 Yahoo Finance
Syndicating the tracker's $30.1 billion untapped-market findings, spotlighting Japan, the US and China as India's top new-potential importers.
 India Today
Carrying the release on smartphones leading India's export potential to $94 billion by 2031, per 6WExportGTM data.
 Dailyhunt
Distributing the tracker findings to its regional readership, framing India's export diversification into Japan and Mexico.
 PR Newswire Original release
Publishing the full India Export Attractiveness Tracker 2026, detailing new trade corridors across iron ore, LCVs and pharmaceuticals.
 The Industrial
Highlighting the tracker's read on India's semiconductor ambitions and long-term chip-assembly export potential.
 PTI News
Reporting on the $66.81 billion pharmaceuticals export opportunity flagged in the tracker, amid looming US generic-drug tariffs.
 Tribune India
Covering the tracker's tariff-versus-regulation analysis across India's mature export markets in the US, China and UAE.
 ANI News
Amplifying the report's findings on polished diamonds, refined petroleum and medicines as India's core export engines.
 International Business Magazine
Covering the report's insight into how AEB, blind spot detection, and driver monitoring are reshaping India's ADAS market.
 Focus Gaming News
Highlighting the research forecast for Egypt's gambling market, projecting steady growth through 2032.
Thought Leadership and Analyst Meet
Our Clients
Latest Reports
- Peru Holistic Health Market (2026-2032)
- Pakistan Holistic Health Market (2026-2032)
- Oman Holistic Health Market (2026-2032)
- Nigeria Holistic Health Market (2026-2032)
- Nepal Holistic Health Market (2026-2032)
- Myanmar Holistic Health Market (2026-2032)
- Morocco Holistic Health Market (2026-2032)
- Mexico Holistic Health Market (2026-2032)
- Malaysia Holistic Health Market (2026-2032)
- Lebanon Holistic Health Market (2026-2032)
Industry Events and Analyst Meet

EV India Expo 2026
HIMTEX 2026
India Refining Summit 2026
India EV Show 2026
EV tech India Expo 2026
Whitepaper
- Middle East & Africa Commercial Security Market Click here to view more.
- Middle East & Africa Fire Safety Systems & Equipment Market Click here to view more.
- GCC Drone Market Click here to view more.
- Middle East Lighting Fixture Market Click here to view more.
- GCC Physical & Perimeter Security Market Click here to view more.


