India Cyber Security Market Size & Growth Rate
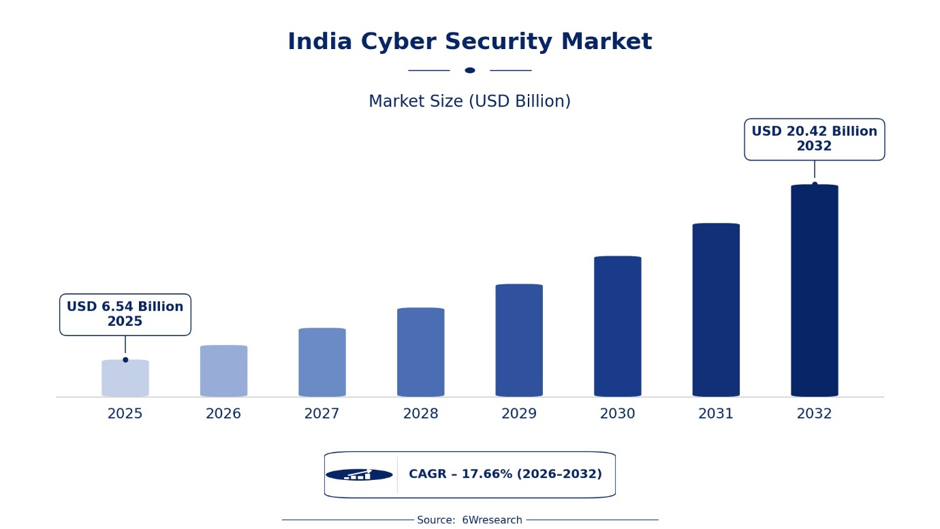
According to 6Wresearch internal database and industry insights, the India Cyber Security Market was valued at USD 6.54 billion in 2025 and is projected to reach USD 20.42 billion by 2032, growing at a CAGR of approximately 17.66% during the forecast period (2026–2032).
India Cyber Security Market Highlights
| Report Metric | Details |
| Report Name | India Cyber Security Market (2026-2032) |
| Market Size 2025 | USD 6.54 billion |
| Market Size 2032 | USD 20.42 billion |
| Absolute Growth 2025–2032 | USD 13.88 billion |
| CAGR 2026–2032 | 17.66% |
| Peak Annual Growth | 19.7% in 2028 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Component, 2025 | Software (44% share) |
| Fastest-Growing Component | Services (19.0% CAGR) |
| Leading Software, 2025 | IAM (24% share) |
| Fastest-Growing Software | Compliance and Policy Management (21.6% CAGR) |
| Leading Security Type, 2025 | Network Security (36% share) |
| Fastest-Growing Security Type | Cloud Security (22.4% CAGR) |
| Leading Deployment Mode, 2025 | On-premises (59% share) |
| Fastest-Growing Deployment Mode | Cloud (21.5% CAGR) |
| Leading Organization Size, 2025 | Large Enterprises (68% share) |
| Fastest-Growing Organization Size | SMEs (21.0% CAGR) |
| Leading Vertical, 2025 | BFSI (27% share) |
| Fastest-Growing Vertical | Healthcare (21.7% CAGR) |
| Growing Sector | Cloud Security and Healthcare |
| Key End Users or Key Procuring Entities | Banks and insurers, IT services firms, telecom operators, hospitals, power and utility companies, retailers, transport operators, defence and aerospace agencies, government departments |
India Cyber Security Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
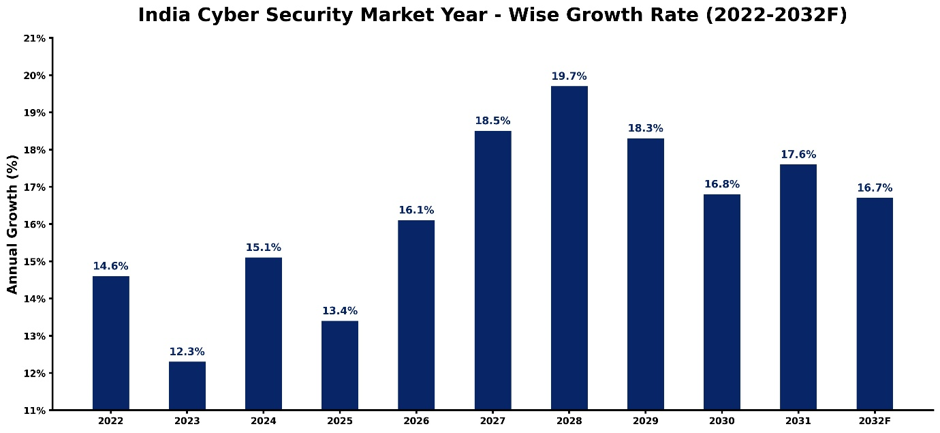
The following table presents the estimated annual growth rate for each year together with the principal factor influencing market performance. The values are intended to highlight year-specific drivers rather than to provide a direct comparison between individual years.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 14.6% | Post-pandemic reopening and the AIIMS Delhi ransomware attack of November 2022 pushed organisations to raise security budgets sharply. |
| 2023 | 12.3% | Global technology budget tightening and delayed enterprise rollouts restrained growth, while the 2023 data protection law only began shaping plans. |
| 2024 | 15.1% | SEBI's Cybersecurity and Cyber Resilience Framework of August 2024 and a rise in phishing fraud lifted demand across regulated institutions. |
| 2025 | 13.4% | Buyers digested earlier compliance-driven purchases and consolidated vendors, moderating new licence additions despite May 2025 conflict-related attacks. |
| 2026 | 16.1% | Phased enforcement of the data protection rules is expected to trigger consent management and data discovery projects at large organisations. |
| 2027 | 18.5% | Application of data fiduciary obligations around May 2027 is expected to accelerate spending on breach detection, encryption and audit readiness. |
| 2028 | 19.7% | Peak rollout of AI-enabled workloads and new data centre capacity is expected to widen exposure and lift security procurement. |
| 2029 | 18.3% | Completion of first-wave compliance programmes at large organisations is expected to ease the pace of new purchases. |
| 2030 | 16.8% | Intensifying price competition among global and domestic vendors is expected to compress contract values and moderate revenue growth. |
| 2031 | 17.6% | Migration to quantum-resistant cryptographic standards is expected to create replacement demand across enterprise and public networks. |
| 2032 | 16.7% | Growth is expected to stabilise as a larger installed base shifts spending toward subscription renewals and managed services. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
India Cyber Security Market Synopsis
The India Cyber Security Market comprehends software, hardware and services that protect networks, endpoints, applications, identities and data across enterprise and public sector environments. Its expansion is driven by national data protection legislation, mandatory incident reporting rules introduced in 2022, one of the world's largest internet user bases and rising ransomware exposure among hospitals and utilities. In response, vendors are expanding managed detection services, India hosted security operations centres and local partnerships, while global OEMs and domestic integrators compete for large account mandates.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Data protection compliance obligations | Driver | High | Compliance and Policy Management |
| Mandatory incident reporting and rising attack volumes | Driver | High | Log Management and SIEM |
| Managed security services for mid-sized organisations | Opportunity | High | Services |
| Security posture tools for new data centre capacity | Opportunity | Medium | Cloud Security |
| Shortage of experienced security analysts | Restraint | High | Log Management and SIEM |
| Limited security budgets among smaller firms | Restraint | Medium | SMEs |
| Ageing infrastructure with delayed patching | Challenge | Medium | Patch Management |
| Overlapping sector regulations and reporting formats | Challenge | Medium | Compliance and Policy Management |
Evaluation of Drivers in the India Cyber Security Market (2026–2032)
Below mentioned are some major drivers and their influence on the market dynamics:
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Data protection compliance obligations | Compliance and Policy Management | The Digital Personal Data Protection Act of 2023 requires consent, breach notification and safeguards for personal data, creating mandatory tooling and audit budgets, with penalties reaching INR 250 crore per instance. |
| Mandatory incident reporting | Log Management and SIEM | CERT-In directions of April 2022 require incident reporting within six hours, forcing organisations to deploy centralised monitoring and correlation tools that detect incidents in time. |
| Rising attack volumes | Endpoint and IoT Security | CERT-In handled over 2 million cyber incidents in 2024, and each ransomware or phishing episode increases board-level pressure to fund endpoint protection and detection capability. |
| Scale of digital payments | IAM | UPI processed more than 20 billion transactions in a single month in August 2025, so every payment channel needs strong authentication and fraud-resistant access controls. |
| Data centre capacity build-out | Cloud Security | Installed data centre capacity in India exceeded 1 GW during 2024, and new hyperscale regions in Mumbai and Chennai bring workloads that need posture management and workload protection. |
The India Cyber Security Market is supported by the scale of the country's digital economy, with more than 900 million internet subscribers creating an expanding attack surface that organisations must protect. Moreover, rising enterprise technology budgets are shifting security from a discretionary expense to a standing operating cost.
A technology workforce exceeding 5.8 million sustains frequent software releases, increasing demand for continuous testing and monitoring tools. Meanwhile, broader AI adoption in software development and customer operations introduces additional data flows requiring protection. Growing private and foreign investment in digital infrastructure and technology centres further expands the installed base of systems requiring security coverage, supporting recurring spending on tools and services.
Evaluation of Restraints in the India Cyber Security Market
Below mentioned are some major restraints and their influence on the market dynamics:
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Limited security budgets among smaller firms | SMEs | Many of India's roughly 63 million micro, small and medium enterprises treat security as a discretionary cost, so adoption stays limited to basic antivirus products and revenue per customer remains low. |
| Shortage of experienced security analysts | Log Management and SIEM | Monitoring platforms need trained analysts to tune alerts, and an around-the-clock desk typically requires at least five analysts, so firms outside the largest metros delay deployments. |
| Overlapping sector regulations | Compliance and Policy Management | The RBI Master Direction on IT Governance of 2023 and IRDAI's information and cyber security guidelines of 2023 prescribe different formats, so multi-sector groups duplicate tooling and postpone purchases. |
| Ageing infrastructure and delayed patching | Patch Management | Microsoft ended Windows 10 support in October 2025, yet many public bodies and small firms still run older systems that cannot be updated quickly, which blocks adoption of modern tools. |
| Unlicensed software and low willingness to pay | Antivirus/Antimalware | Around half of installed software in India was unlicensed in the last published national estimate, which reduces paid conversions and keeps price points for consumer security products low. |
India Cyber Security Market Challenges
The India Cyber Security Market faces cost pressures from log retention rules requiring 180 days of in country storage, which increase infrastructure and analytics expenses and encourage buyers to narrow monitoring scope. Meanwhile, fragmented enterprise environments, where products from multiple vendors rarely interoperate, leave alerts unresolved and discourage further point purchases.
In addition, public tenders evaluated on the lowest bid compress provider margins and limit investment in advanced offerings. The Reserve Bank of India's 2018 payment data storage directive also requires global vendors to establish local infrastructure, extending deployment timelines. Furthermore, buyers often underestimate loss exposure, with the average breach costing about INR 19.5 crore in 2024, resulting in spending that frequently follows an incident rather than precedes it.
Trends in the India Cyber Security Market
Notable trends shaping the growth of the India cyber security industry are listed below:
- Shift from Perimeter Defence to Zero Trust Access: Indian enterprises are replacing VPN-centred perimeters as hybrid work and a technology workforce above 5 million push users beyond office networks. Identity checks, device posture and least-privilege access are becoming standard conditions for application entry.
- Transition from In-house Monitoring to Managed Detection and Response: Mid-sized Indian firms are outsourcing 24x7 monitoring to providers operating India-hosted security operations centres, since building internal teams is slow and costly.
- Post-quantum Readiness Prioritised over Deferred Planning: The National Quantum Mission, with an outlay of INR 6,003 crore, is encouraging early preparation, and banks, telecom operators and government bodies are beginning to inventory cryptographic assets and test quantum-resistant algorithms.
Investment Opportunities in the India Cyber Security Market
Major growth-oriented investment opportunities in the India cyber security market are highlighted below:
- India-hosted Managed Security Operations Centres: Mid-sized firms need round-the-clock monitoring but cannot staff it, and reporting duties require rapid detection. Invest in managed detection and response platforms, analyst teams and local data residency, with delivery hubs in Pune, Hyderabad or Bengaluru.
- Identity Verification and Access Platforms: India's national digital identity and payment infrastructure keeps authentication volumes high and fraud attempts rising. Investment is warranted in adaptive authentication, privileged access management and identity governance products integrated with Aadhaar-based verification.
- Operational Technology Security for Power and Industrial Sites: Utilities and manufacturers are connecting control systems to corporate networks as the power sector follows the Central Electricity Authority's cyber security guidelines of 2021. Suppliers can invest in industrial network monitoring, secure remote access and asset visibility tools certified for Indian grid and plant environments.
Leading Players in the India Cyber Security Market
A compilation of established and emerging companies in the India cyber security market is presented below:
1. Quick Heal Technologies Limited
|
Company Name |
Quick Heal Technologies Limited |
|
Headquarters |
Pune, India |
|
Established Year |
1995 |
|
Official Website |
Quick Heal Technologies Limited develops endpoint and network security software for consumers, businesses and government users through its Seqrite enterprise brand. It is among the leading domestic security product companies in India.
2. Tata Communications Limited
|
Company Name |
Tata Communications Limited |
|
Headquarters |
Mumbai, India |
|
Established Year |
1986 |
|
Official Website |
Tata Communications Limited provides managed security services, secure connectivity and network protection to enterprises. It plays a significant role as a carrier-based security services provider in India.
3. Wipro Limited
|
Company Name |
Wipro Limited |
|
Headquarters |
Bengaluru, India |
|
Established Year |
1945 |
|
Official Website |
Wipro Limited offers consulting, managed detection and response, and identity and risk services as part of its information technology services portfolio. It serves large Indian enterprises as a leading domestic systems integrator.
4. Palo Alto Networks, Inc.
|
Company Name |
Palo Alto Networks, Inc. |
|
Headquarters |
Santa Clara, United States |
|
Established Year |
2005 |
|
Official Website |
Palo Alto Networks, Inc. supplies network, cloud and security operations platforms to large enterprises, telecom operators and public bodies. It serves the Indian market through local channel partners and an in-country engineering presence.
5. Cisco Systems, Inc.
|
Company Name |
Cisco Systems, Inc. |
|
Headquarters |
San Jose, United States |
|
Established Year |
1984 |
|
Official Website |
Cisco Systems, Inc. provides network security, secure access and threat detection products to Indian organisations. It operates through a long-standing local presence and an extensive partner ecosystem.
Government Initiatives in the India Cyber Security Market
The India Cyber Security Market is shaped by a strengthening regulatory framework, led by the Digital Personal Data Protection Act, 2023, which introduces penalties of up to INR 250 crore, and the Digital Personal Data Protection Rules, 2025, which phase in obligations over 18 months. Complementing these measures, the CERT-In directions of April 2022 mandate incident reporting within 6 hours, while the Information Technology Act, 2000 remains the core legal basis for cybercrime and security enforcement.
However, the market also gains from coordinated implementation with the help of CERT-In, National Critical Information Infrastructure Protection Centre that was set up in 2014, and Indian Cyber Crime Coordination Centre which was setup in 2018 to coordinate enforcement across all 36 states and union territories. In addition, Cyber Surakshit Bharat, introduced in 2018, trains the Chief Information Security Officers of the public sector, while the sector regulators prescribe binding standards for banks, securities firms, and power utilities.
Future Insights of the India Cyber Security Market
The India Cyber Security Industry is predicted to grow further due to increased information sharing between industry regulatory bodies, response teams, and enterprises, increasing threat intelligence and creating demand for monitoring, analytics, and incident response services. At the same time, increase in domestic electronics and semiconductors production will enable local sourcing of secure devices and appliances.
The India AI Mission's INR 10,372 crore outlay and the national goal of a USD 1 trillion digital economy by 2028 will further increase the volume of data and applications requiring protection. Additionally, evolving cyber insurance underwriting standards will reward verifiable controls and encourage sustained, multiyear budgets.
Market Segmentation Analysis
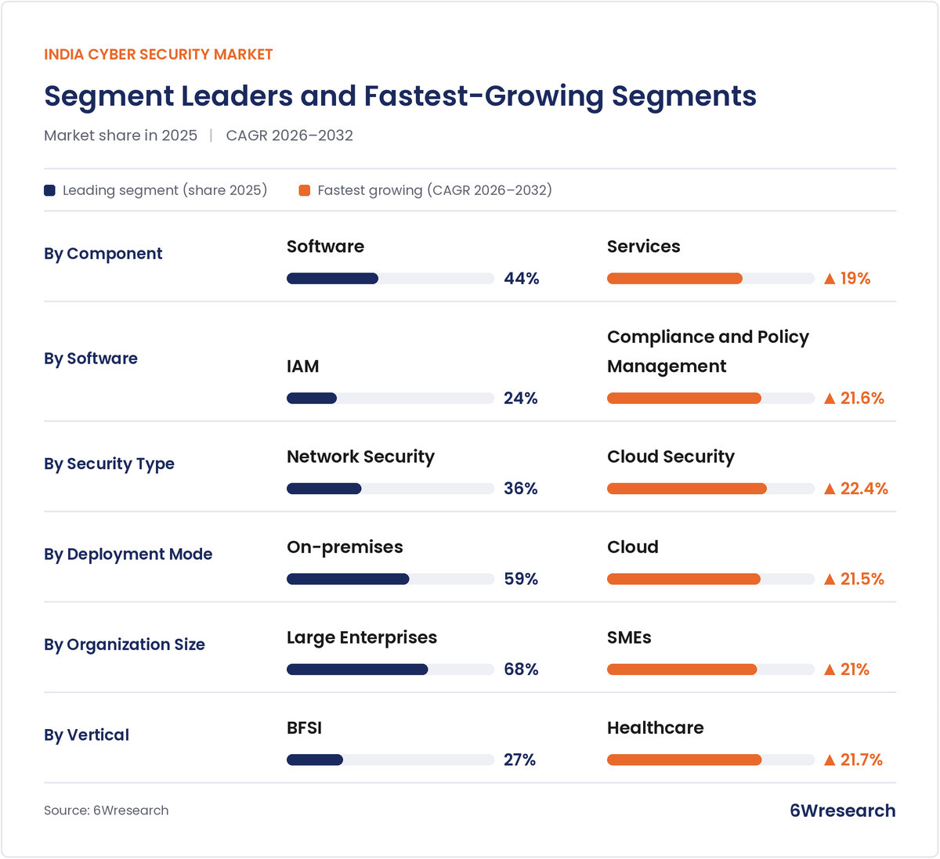
The report offers a comprehensive study of the market across its key segments. The chart below highlights the leading segment by market share in 2025 and the fastest-growing segment by CAGR over 2026–2032, followed by a detailed analysis of each segment.
By Component – Software Leads, Services Expected to Grow Fastest
According to Ravi Bhandari, Research Head at 6Wresearch, Software accounted for the largest share of 44% in 2025, as Indian organisations deploy identity, monitoring and compliance platforms to meet CERT-In and sector regulatory requirements, with licence renewals providing predictable annual spend. Meanwhile, Services is projected to record the fastest CAGR of 19.0% during 2026–2032, driven by a limited pool of in-house security specialists that pushes organisations towards managed detection, consulting and incident response contracts with Indian IT majors.
By Software – IAM Leads, Compliance and Policy Management Expected to Grow Fastest
IAM led with a 24% share in 2025, as the scale of India's digital payments and hybrid technology workforce keeps demand high for authentication, privileged access control and Aadhaar-linked verification. Apart from this, Compliance and Policy Management is expected to expand at the fastest CAGR of 21.6% over 2026–2032, as data protection rules and overlapping sector mandates compel organisations to automate consent records, audit evidence and policy tracking.
By Security Type – Network Security Leads, Cloud Security Expected to Grow Fastest
Network Security led with a 36% share in 2025, supported by extensive enterprise wide-area networks, the 5G rollout that began in October 2022 and the need to protect large corporate campuses across Bengaluru, Hyderabad and Pune. Meanwhile, the fastest growth, at a CAGR of 22.4% over 2026–2032, is expected from Cloud Security as hyperscale regions in Mumbai and Hyderabad attract workloads that require posture management and workload protection.
By Deployment Mode – On-premises Leads, Cloud Expected to Grow Fastest
On-premises deployment retained a 59% share in 2025, as banks, government bodies and defence-linked organisations prefer to keep sensitive data in-house to meet data-residency expectations. In contrast, Cloud is expected to be the faster-growing mode at a CAGR of 21.5% during 2026–2032, as subscription-based security services reduce upfront cost for organisations with limited capital budgets.
By Organization Size – Large Enterprises Lead, SMEs Expected to Grow Fastest
Large Enterprises contributed 68% of 2025 revenue share as banks, IT services majors and telecom operators run multi-site estates under strict regulatory oversight and hold dedicated security budgets. Meanwhile, growth is expected to be fastest among SMEs, at a 21.0% CAGR during 2026–2032, as digital payment acceptance, government e-procurement and supplier security requirements force smaller firms to adopt affordable, bundled protection.
By Vertical – BFSI Leads, Healthcare Expected to Grow Fastest
BFSI represented the largest share at 27% in 2025, reflecting the scale of digital payment infrastructure and binding cyber resilience mandates from RBI, SEBI and IRDAI. In comparison, Healthcare is forecast to grow fastest, at a CAGR of 21.7% over 2026–2032, as hospital networks digitise records and adopt health identity platforms under the Ayushman Bharat Digital Mission after high-profile ransomware incidents.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- India Cyber Security Market Outlook
- Market Size of India Cyber Security Market, 2025
- Forecast of India Cyber Security Market, 2032
- Historical Data and Forecast of India Cyber Security Revenues & Volume for the Period 2022 - 2032
- India Cyber Security Market Trend Evolution
- India Cyber Security Market Drivers and Challenges
- India Cyber Security Price Trends
- India Cyber Security Porter's Five Forces
- India Cyber Security Industry Life Cycle
- Historical Data and Forecast of India Cyber Security Market Revenues & Volume By Component for the Period 2022 - 2032
- Historical Data and Forecast of India Cyber Security Market Revenues & Volume By Software for the Period 2022 - 2032
- Historical Data and Forecast of India Cyber Security Market Revenues & Volume By Hardware for the Period 2022 - 2032
- Historical Data and Forecast of India Cyber Security Market Revenues & Volume By Services for the Period 2022 - 2032
- Historical Data and Forecast of India Cyber Security Market Revenues & Volume By Software for the Period 2022 - 2032
- Historical Data and Forecast of India Cyber Security Market Revenues & Volume By IAM for the Period 2022 - 2032
- Historical Data and Forecast of India Cyber Security Market Revenues & Volume By Antivirus/Antimalware for the Period 2022 - 2032
- Historical Data and Forecast of India Cyber Security Market Revenues & Volume By Log Management and SIEM for the Period 2022 - 2032
- Historical Data and Forecast of India Cyber Security Market Revenues & Volume By Encryption and Tokenization for the Period 2022 - 2032
- Historical Data and Forecast of India Cyber Security Market Revenues & Volume By Compliance and Policy Management for the Period 2022 - 2032
- Historical Data and Forecast of India Cyber Security Market Revenues & Volume By Patch Management for the Period 2022 - 2032
- Historical Data and Forecast of India Cyber Security Market Revenues & Volume By Other Software for the Period 2022 - 2032
- Historical Data and Forecast of India Cyber Security Market Revenues & Volume By Security Type for the Period 2022 - 2032
- Historical Data and Forecast of India Cyber Security Market Revenues & Volume By Network Security for the Period 2022 - 2032
- Historical Data and Forecast of India Cyber Security Market Revenues & Volume By Cloud Security for the Period 2022 - 2032
- Historical Data and Forecast of India Cyber Security Market Revenues & Volume By Application Security for the Period 2022 - 2032
- Historical Data and Forecast of India Cyber Security Market Revenues & Volume By Endpoint and IoT Security for the Period 2022 - 2032
- Historical Data and Forecast of India Cyber Security Market Revenues & Volume By Deployment Mode for the Period 2022 - 2032
- Historical Data and Forecast of India Cyber Security Market Revenues & Volume By Cloud for the Period 2022 - 2032
- Historical Data and Forecast of India Cyber Security Market Revenues & Volume By On-premises for the Period 2022 - 2032
- Historical Data and Forecast of India Cyber Security Market Revenues & Volume By Organization Size for the Period 2022 - 2032
- Historical Data and Forecast of India Cyber Security Market Revenues & Volume By Large Enterprises for the Period 2022 - 2032
- Historical Data and Forecast of India Cyber Security Market Revenues & Volume By SMEs for the Period 2022 - 2032
- Historical Data and Forecast of India Cyber Security Market Revenues & Volume By Vertical for the Period 2022 - 2032
- Historical Data and Forecast of India Cyber Security Market Revenues & Volume By Aerospace and Defense for the Period 2022 - 2032
- Historical Data and Forecast of India Cyber Security Market Revenues & Volume By BFSI for the Period 2022 - 2032
- Historical Data and Forecast of India Cyber Security Market Revenues & Volume By IT and ITeS for the Period 2022 - 2032
- Historical Data and Forecast of India Cyber Security Market Revenues & Volume By Telecommunication for the Period 2022 - 2032
- Historical Data and Forecast of India Cyber Security Market Revenues & Volume By Energy and Utilities for the Period 2022 - 2032
- Historical Data and Forecast of India Cyber Security Market Revenues & Volume By Retail and eCommerce for the Period 2022 - 2032
- Historical Data and Forecast of India Cyber Security Market Revenues & Volume By Healthcare for the Period 2022 - 2032
- Historical Data and Forecast of India Cyber Security Market Revenues & Volume By Transportation and Logistics for the Period 2022 - 2032
- India Cyber Security Import Export Trade Statistics
- Market Opportunity Assessment By Component
- Market Opportunity Assessment By Software
- Market Opportunity Assessment By Security Type
- Market Opportunity Assessment By Deployment Mode
- Market Opportunity Assessment By Organization Size
- Market Opportunity Assessment By Vertical
- India Cyber Security Top Companies Market Share
- India Cyber Security Competitive Benchmarking By Technical and Operational Parameters
- India Cyber Security Company Profiles
- India Cyber Security Key Strategic Recommendations
Market Covered
The report offers an extensive study of the following market segments:
By Component
- Software
- Hardware
- Services
By Software
- IAM
- Antivirus/Antimalware
- Log Management And SIEM
- Encryption And Tokenization
- Compliance And Policy Management
- Patch Management
- Other Software
By Security Type
- Network Security
- Cloud Security
- Application Security
- Endpoint And IoT Security
By Deployment Mode
- Cloud
- On-Premises
By Organization Size
- Large Enterprises
- SMEs
By Vertical
- Aerospace And Defense
- BFSI
- IT And ITeS
- Telecommunication
- Energy And Utilities
- Retail And E-commerce
- Healthcare
- Transportation And Logistics































