Japan Insurance Brokerage Market Size & Growth Rate
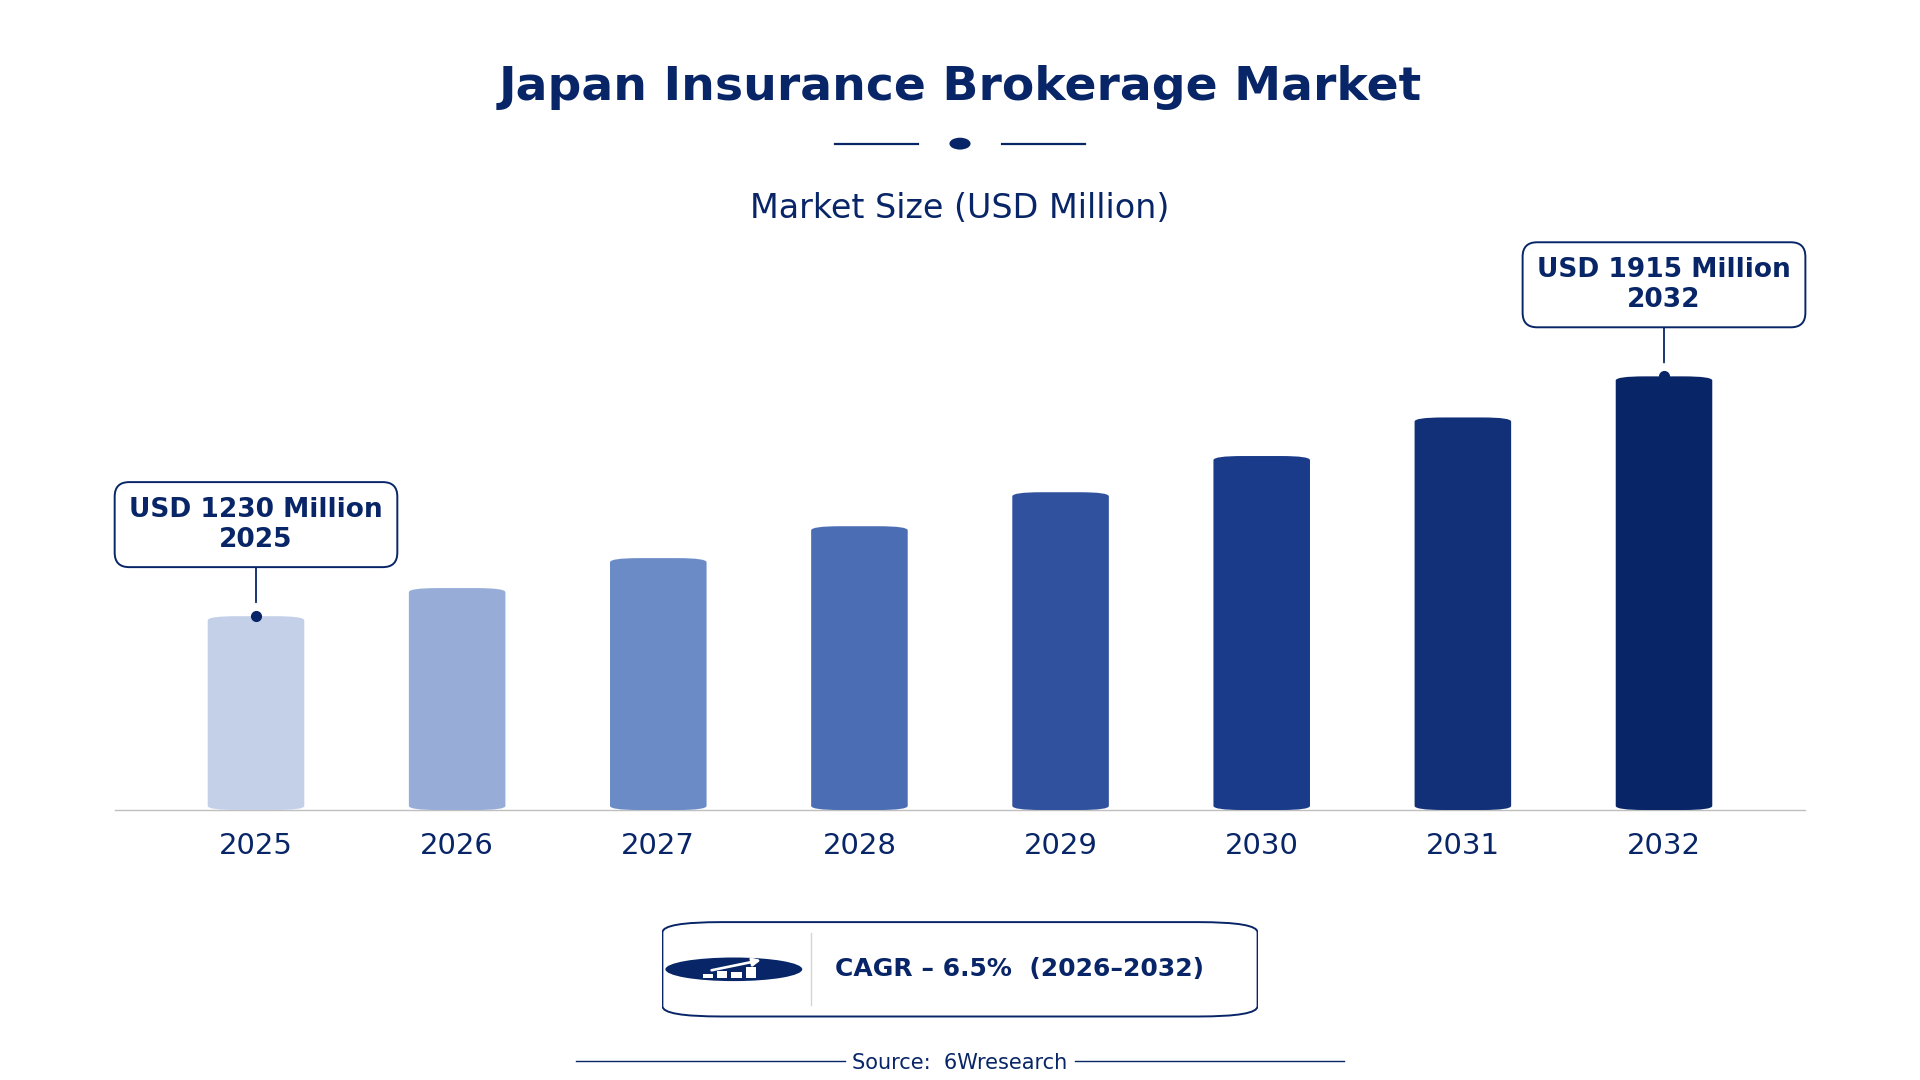
According to 6Wresearch internal database and industry insights, the Japan Insurance Brokerage Market was valued at USD 1,230 Million in 2025 and is projected to reach USD 1,915 Million by 2032, growing at a CAGR of approximately 6.5% during 2026–2032.
Japan Insurance Brokerage Market Highlights
| Report Metric | Details |
| Report Name | Japan Insurance Brokerage Market (2026-2032) |
| Market Size 2025 | USD 1,230 Million |
| Market Size 2032 | USD 1,915 Million |
| Absolute Growth 2025–2032 | USD 685 Million |
| CAGR 2026–2032 | 6.5% |
| Peak Annual Growth | 7.3% in 2028 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Insurance Type, 2025 | Life Insurance (68% share) |
| Leading Brokerage Type, 2025 | Retail (68% share) |
| Fastest-Growing Insurance Type | Property and Casualty Insurance (8.9% CAGR) |
| Growing Sector | Insurance Brokerage |
| Key End Users | Individuals, businesses, financial institutions |
Japan Insurance Brokerage Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
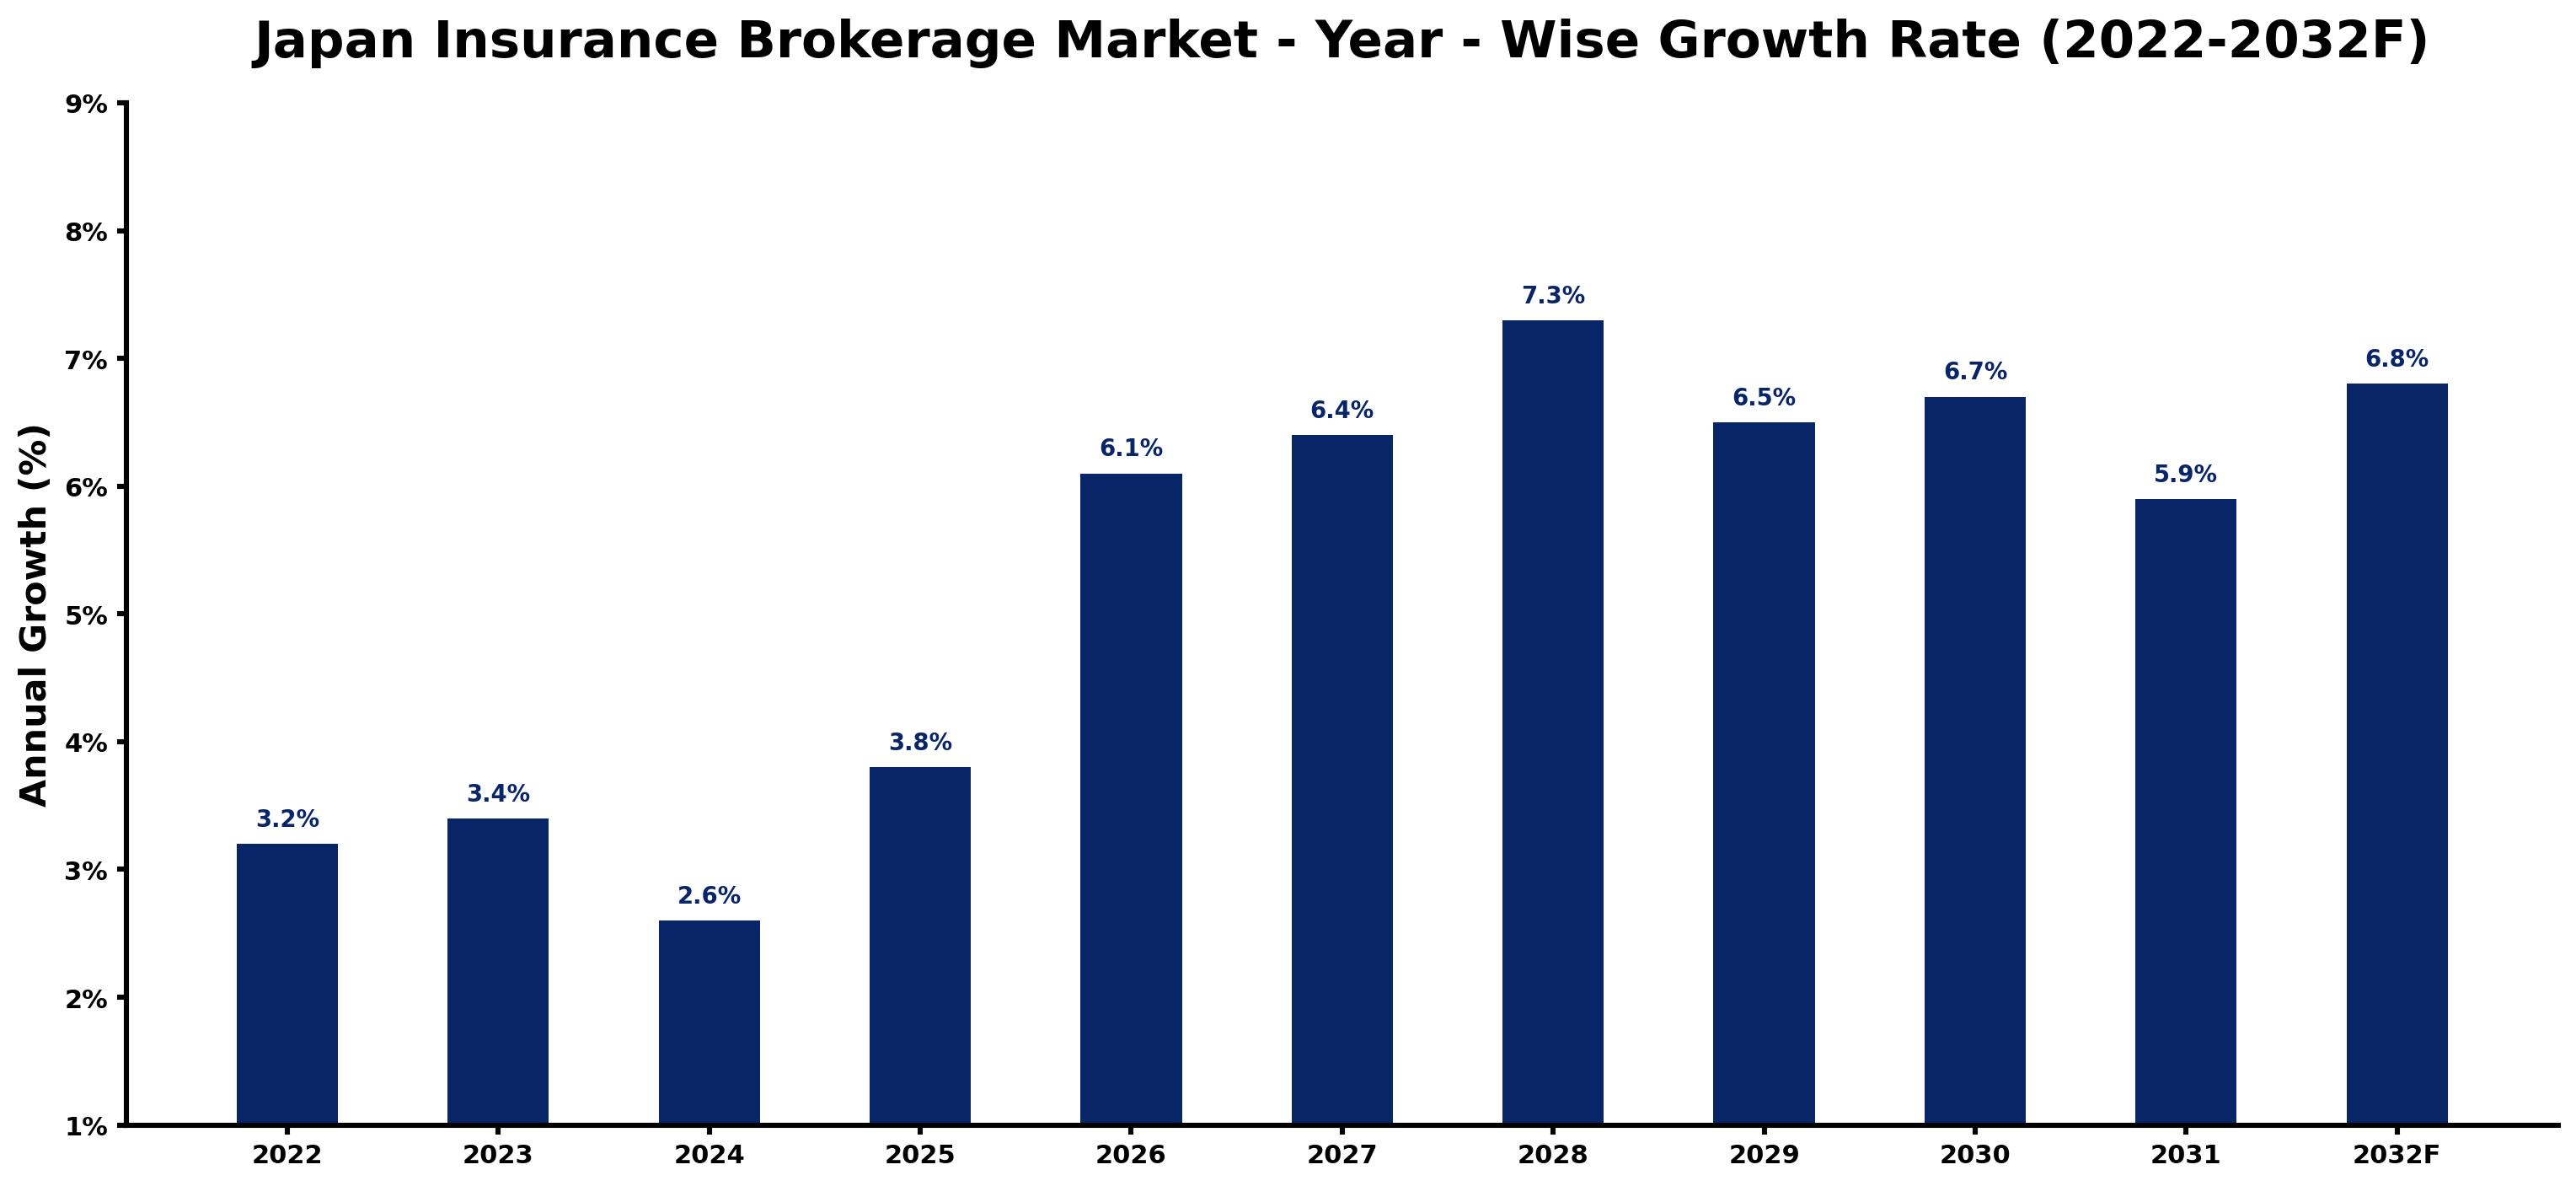
Below, each year's estimated growth is shown next to the factor that most influenced it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 3.2 | The market experienced steady growth due to increasing consumer awareness about insurance products. |
| 2023 | 3.4 | Demand accelerated as more individuals sought financial protection against unforeseen events. |
| 2024 | 2.6 | Growth slowed as market saturation began to impact new policy acquisitions. |
| 2025 | 3.8 | The market rebounded with heightened interest in life insurance products among older demographics. |
| 2026 | 6.1 | Investment in digital platforms is expected to drive further demand for brokerage services. |
| 2027 | 6.4 | Consumer confidence is rising, leading to increased purchases of property and casualty insurance. |
| 2028 | 7.3 | The market will peak as digitalisation initiatives improve service delivery and customer engagement. |
| 2029 | 6.5 | Growth will decelerate slightly as competition intensifies among brokers. |
| 2030 | 6.7 | Demand is projected to rise again with the introduction of new insurance products. |
| 2031 | 5.9 | Growth will slow as the market stabilises and consumer preferences evolve. |
| 2032 | 6.8 | The market will see renewed interest as financial literacy initiatives gain traction. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
Japan Insurance Brokerage Market Synopsis
The Japan Insurance Brokerage Market is expanding, driven by rising consumer awareness, a growing number of licensed brokers, and strong demand for life and property insurance products. With the life insurance market valued at approximately 40 trillion JPY, the sector is set for further growth as digitalisation improves service delivery and customer engagement.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increasing consumer awareness about insurance products | Driver | High | Life Insurance |
| Investment in digital platforms for service delivery | Driver | High | Property and Casualty Insurance |
| Growth in digitalisation initiatives | Opportunity | High | Retail |
| Rising average annual premiums for life insurance | Opportunity | Medium | Life Insurance |
| Market saturation affecting new policy acquisitions | Restraint | Medium | Property and Casualty Insurance |
| Intense competition among brokers | Restraint | High | Retail |
| Evolving consumer preferences impacting policy choices | Challenge | Medium | Life Insurance |
| Regulatory compliance requirements increasing operational costs | Challenge | High | Property and Casualty Insurance |
Evaluation of Drivers in Japan Insurance Brokerage Market (2026–2032)
Demand rests on the following drivers, each shown with the segment it touches most.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Growing consumer awareness about financial protection | Life Insurance | This awareness leads to increased purchases of life insurance policies, with the average annual premium around 150,000 JPY. |
| Investment in digital platforms | Property and Casualty Insurance | This investment increases access to insurance products, resulting in higher demand for property and casualty insurance products. |
| Rising average premiums | Life Insurance | As premiums increase, more individuals seek brokerage services to navigate their options effectively. |
| Expansion of licensed brokers | Retail | The growth of over 300 licensed brokers facilitates greater access to insurance products for consumers. |
| Government initiatives promoting financial literacy | Property and Casualty Insurance | These initiatives encourage consumers to seek insurance coverage, boosting demand in the sector. |
Volumes grow on the back of increasing awareness regarding financial protection, with the average annual premium for life insurance at 150,000 JPY. The expansion of licensed brokers, exceeding 300, increases access to various insurance products. Investment in digital platforms improves service delivery, driving demand for property and casualty insurance.
Evaluation of Restraints in Japan Insurance Brokerage Market
Below are the constraints most often cited by buyers and suppliers, with the segment each affects.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Market saturation affecting new policy acquisitions | Property and Casualty Insurance | As the market matures, fewer new policies are being purchased, limiting growth opportunities. |
| Intense competition among brokers | Retail | Increased competition leads to price wars, affecting profitability for brokers and limiting service differentiation. |
| Changes in consumer preferences impacting policy choices | Life Insurance | Shifts towards alternative financial products reduce demand for traditional insurance. |
| Regulatory compliance requirements increasing operational costs | Property and Casualty Insurance | Compliance with regulations adds to operational costs, which can deter smaller brokers from entering the market. |
| Limited awareness of insurance products among younger consumers | Retail | Younger demographics often lack knowledge about insurance benefits, hindering their purchasing decisions. |
Japan Insurance Brokerage Market Challenges
Clients face challenges with outdated technology, as many brokers rely on traditional methods, resulting in longer processing times for policy applications. This inefficiency can delay coverage, costing clients potential financial protection during critical moments. High compliance costs burden brokers, with regulatory expenses consuming up to 15% of their operational budgets, limiting their capacity to invest in service improvements. In Tokyo, fierce competition among over 300 licensed brokers makes it difficult for new entrants to gain market share, forcing them to lower fees, which can erode profit margins for all providers.
Trends in the Japan Insurance Brokerage Market
Below are the shifts with the largest effect on the Japan Insurance Brokerage Market.
- Shift towards Digital Platforms: The insurance brokerage market is increasingly adopting digital platforms to improve customer engagement. For instance, the 2023 government program to boost digitalisation is expected to transform service delivery, resulting in improved customer satisfaction and efficiency.
- Growing Focus on Financial Literacy: Tokyo Metropolitan Government's initiatives are prioritising financial literacy, particularly regarding insurance. With a significant portion of the population over 50 years old, understanding insurance options is vital for this demographic, driving demand for brokerage services.
- Increased Demand for Property Insurance: As natural disasters become more frequent, there is a rising demand for property insurance. In 2022, property and casualty insurance premiums reached 6 trillion JPY, reflecting the urgent need for comprehensive coverage.
- Emergence of Tailored Insurance Products: Brokers are increasingly offering customised insurance products to meet specific client needs. This trend is evident in the growing variety of policies available, catering to diverse consumer preferences.
Investment Opportunities in the Japan Insurance Brokerage Market
The following opportunities in the Japan Insurance Brokerage Market pair current demand with a clear way in.
- Tokyo as a Financial Hub: Tokyo's status as the largest insurance brokerage hub presents opportunities for expansion. With over 300 licensed brokers, there is a notable demand for innovative insurance solutions.
- Older Demographics Seeking Insurance: With a growing average age of policyholders, there is an opportunity to develop products tailored for older consumers. This demographic shift is driving demand for life insurance products.
- Rising Premiums Indicating Market Potential: The average annual premium for life insurance is around 150,000 JPY, indicating a gap for brokers to offer competitive products. Engaging with older demographics can improve market penetration.
- Government Support for Digitalisation: The 2023 government program to boost digitalisation in the insurance sector opens avenues for investment in technology. Collaborating with local partners can facilitate entry into this growing market.
Government Initiatives in the Japan Insurance Brokerage Market
The GX Basic Policy adopted in 2023 aims to drive public-private investment in decarbonisation, influencing insurance brokerage practices. This initiative builds on the Industrial Standardization Act, ensuring that brokers adhere to evolving standards in the insurance sector.
The Japan Association of Insurance Brokers utilises funding from government schemes to improve training for brokers, ensuring compliance with the latest regulations. This support helps brokers meet consumer expectations and improve service delivery.
Future Insight of the Japan Insurance Brokerage Market
By 2032, digital platforms will transform policy management and claims processing for clients, driven by government initiatives that support digitalisation. The adoption of ISO 9001 standards will improve service quality, fostering greater consumer trust in the sector. As the average age of policyholders increases, insurance offerings will evolve to meet the needs of older demographics. Rising insurance penetration, currently at about 9% of GDP, will drive demand for tailored solutions that address specific client requirements.
Market Segmentation Analysis
Japan Insurance Brokerage Market report covers a detailed analysis of the following market segments:
By Insurance Type – Life Insurance Leads, Property and Casualty Insurance Expected to Grow Fastest
According to Shubham Deep, Research Manager at 6Wresearch, with 68% of insurance type revenue in 2025, Life Insurance was the largest category. Life insurance holds the largest share in Japan as it is vital for financial security and risk management among individuals and families. The average annual premium of around 150,000 JPY reflects a strong demand for comprehensive coverage within the population. Property and Casualty Insurance is projected to grow fastest, at a CAGR of 8.9% during 2026–2032. The property and casualty insurance segment is experiencing rapid growth due to increased awareness of the need for asset protection, particularly in urban areas like Tokyo. The 2022 property and casualty insurance premiums reaching 6 trillion JPY highlight the growing emphasis on safeguarding personal and business assets. This indicates that suppliers should focus on enhancing property and casualty insurance offerings to meet the increasing consumer demand for asset protection.
By Brokerage Type – Retail Leads and Records the Fastest Growth
Retail held 68% of the Japan Insurance Brokerage Market by brokerage type in 2025. Retail brokerage dominates the market as it directly addresses the needs of individual consumers seeking insurance coverage. This segment benefits from the large base of over 300 licensed insurance brokers actively serving clients across Japan. The same category is also set to grow fastest, at a CAGR of 7.6% during 2026–2032. Retail brokerage is also the fastest-growing segment, as it continues to expand its reach among consumers increasingly seeking tailored insurance solutions. The trend towards digitalization in the insurance sector further supports the growth of retail brokerage services. Suppliers must invest in digital tools and customer engagement strategies to capitalise on the growth in retail brokerage.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- Japan Insurance Brokerage Market Outlook
- Market Size of Japan Insurance Brokerage Market, 2025
- Forecast of Japan Insurance Brokerage Market, 2032
- Historical Data and Forecast of Japan Insurance Brokerage Revenues & Volume for the Period 2022-2032
- Japan Insurance Brokerage Market Trend Evolution
- Japan Insurance Brokerage Market Drivers and Challenges
- Japan Insurance Brokerage Price Trends
- Japan Insurance Brokerage Porter's Five Forces
- Japan Insurance Brokerage Industry Life Cycle
- Historical Data and Forecast of Japan Insurance Brokerage Market Revenues & Volume By Insurance Type for the Period 2022-2032
- Historical Data and Forecast of Japan Insurance Brokerage Market Revenues & Volume By Life Insurance for the Period 2022-2032
- Historical Data and Forecast of Japan Insurance Brokerage Market Revenues & Volume By Property and Casualty Insurance for the Period 2022-2032
- Historical Data and Forecast of Japan Insurance Brokerage Market Revenues & Volume By Brokerage Type for the Period 2022-2032
- Historical Data and Forecast of Japan Insurance Brokerage Market Revenues & Volume By Retail for the Period 2022-2032
- Historical Data and Forecast of Japan Insurance Brokerage Market Revenues & Volume By Wholesale for the Period 2022-2032
- Japan Insurance Brokerage Import Export Trade Statistics
- Market Opportunity Assessment By Insurance Type
- Market Opportunity Assessment By Brokerage Type
- Japan Insurance Brokerage Top Companies Market Share
- Japan Insurance Brokerage Competitive Benchmarking By Technical and Operational Parameters
- Japan Insurance Brokerage Company Profiles
- Japan Insurance Brokerage Key Strategic Recommendations
Market Covered
Coverage by segment is as follows.
By Insurance Type
- Life Insurance
- Property and Casualty Insurance
By Brokerage Type
- Retail
- Wholesale































