Global Tractor Engines Market (2026-2032) | Size, Investment Trends, Share, Industry, Consumer Insights, Segmentation, Pricing Analysis, Forecast, Outlook, Strategy, Analysis, Revenue, Challenges, Drivers, Segments, Opportunities, Competition, Demand, Competitive, Trends, Restraints, Strategic Insights, Companies, Value, Growth, Supply
Market Forecast by Regions and Countries (North America, Europe, LATAM, Middle East, Asia and Africa), By Engine Power (Low Power Engine, High Power Engine) And Competitive Landscape
| Product Code: ETC13257741 | Publication Date: Apr 2025 | Updated Date: Sep 2026 | Product Type: Market Research Report | |
| Publisher: 6Wresearch | Author: Bhawna Singh | No. of Pages: 190 | No. of Figures: 80 | No. of Tables: 40 |
Global Tractor Engines Market Highlights
| Market Size (2025) | USD 5.9 Billion |
| Forecast Size (2032) | USD 8.2 Billion |
| CAGR | 4.70% |
| Base Year | 2025 |
| Forecast Period | 2026-2032 |
| Largest Region | Asia-Pacific |
| Fastest Growing Region | LATAM |
| Largest Segment | High Power Engine |
| Fastest Growing Segment | Low Power Engine |
| Leading Companies | John Deere, Caterpillar, Case IH, New Holland, AGCO Corporation |
Global Tractor Engines Market Size & Growth Rate (2026-2032)
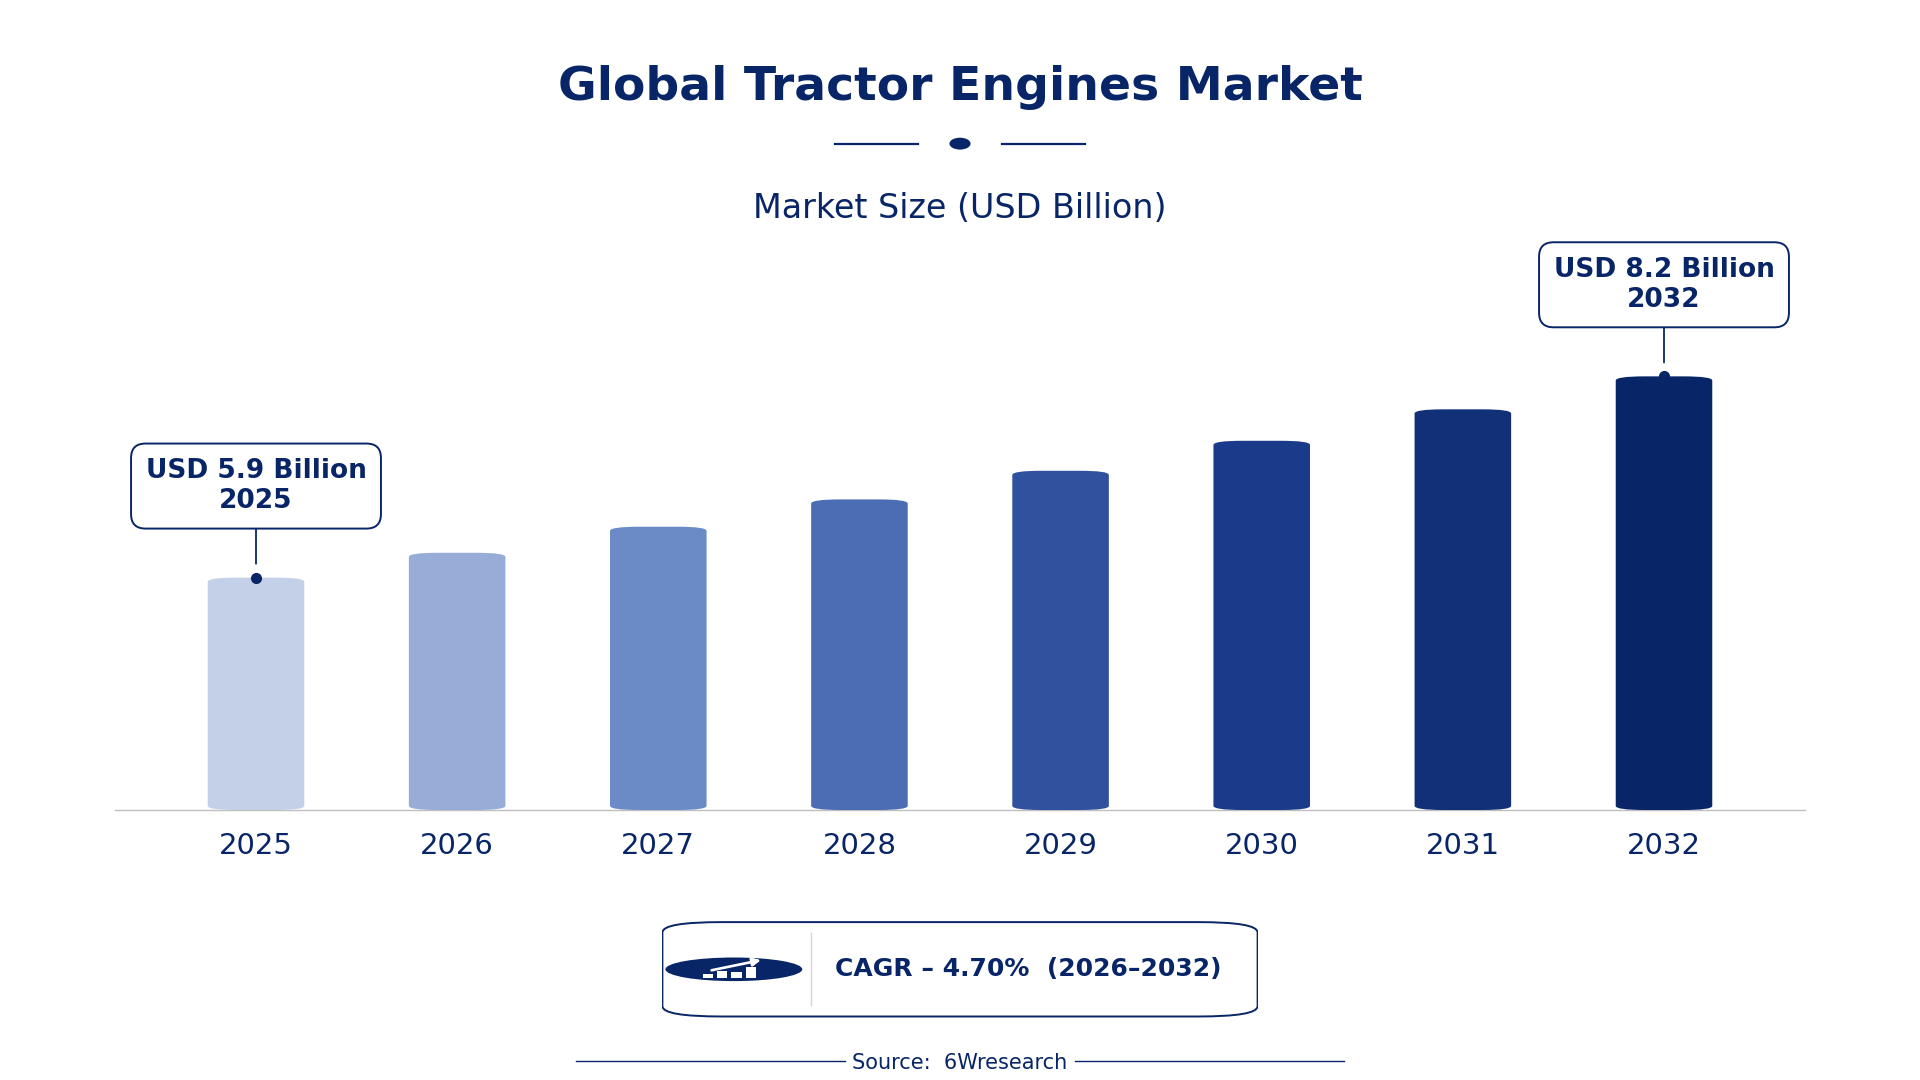
The Global Tractor Engines Market was estimated at USD 5.9 Billion in 2025 and is projected to reach USD 8.2 Billion by 2032, growing at a CAGR of 4.70% from 2026 to 2032.
Global Tractor Engines Market Synopsis
Transformations within the Global Tractor Engines Market are driven primarily by shifts in agricultural practices, notably mechanization and consolidation. As farms scale in size for efficiency, the demand for high-performance engines continues to rise, paving the way for manufacturers to innovate and optimize engine technologies.
This market is crucial not only for agricultural productivity but also for the broader industrial ecosystem, impacting sectors such as construction and logistics through equipment interoperability and shared technological advancements. The emergence of precision agriculture is particularly noteworthy, as it necessitates engines that are both versatile and durable, effectively catering to diverse agricultural needs across various geographic realms.
Global Tractor Engines Market Year-wise Growth Rate and Key Drivers
This graph illustrates the annual growth rates of the Global Tractor Engines Market from 2022 to 2032, highlighting a steady upward trajectory and projected expansion over the forecast period.
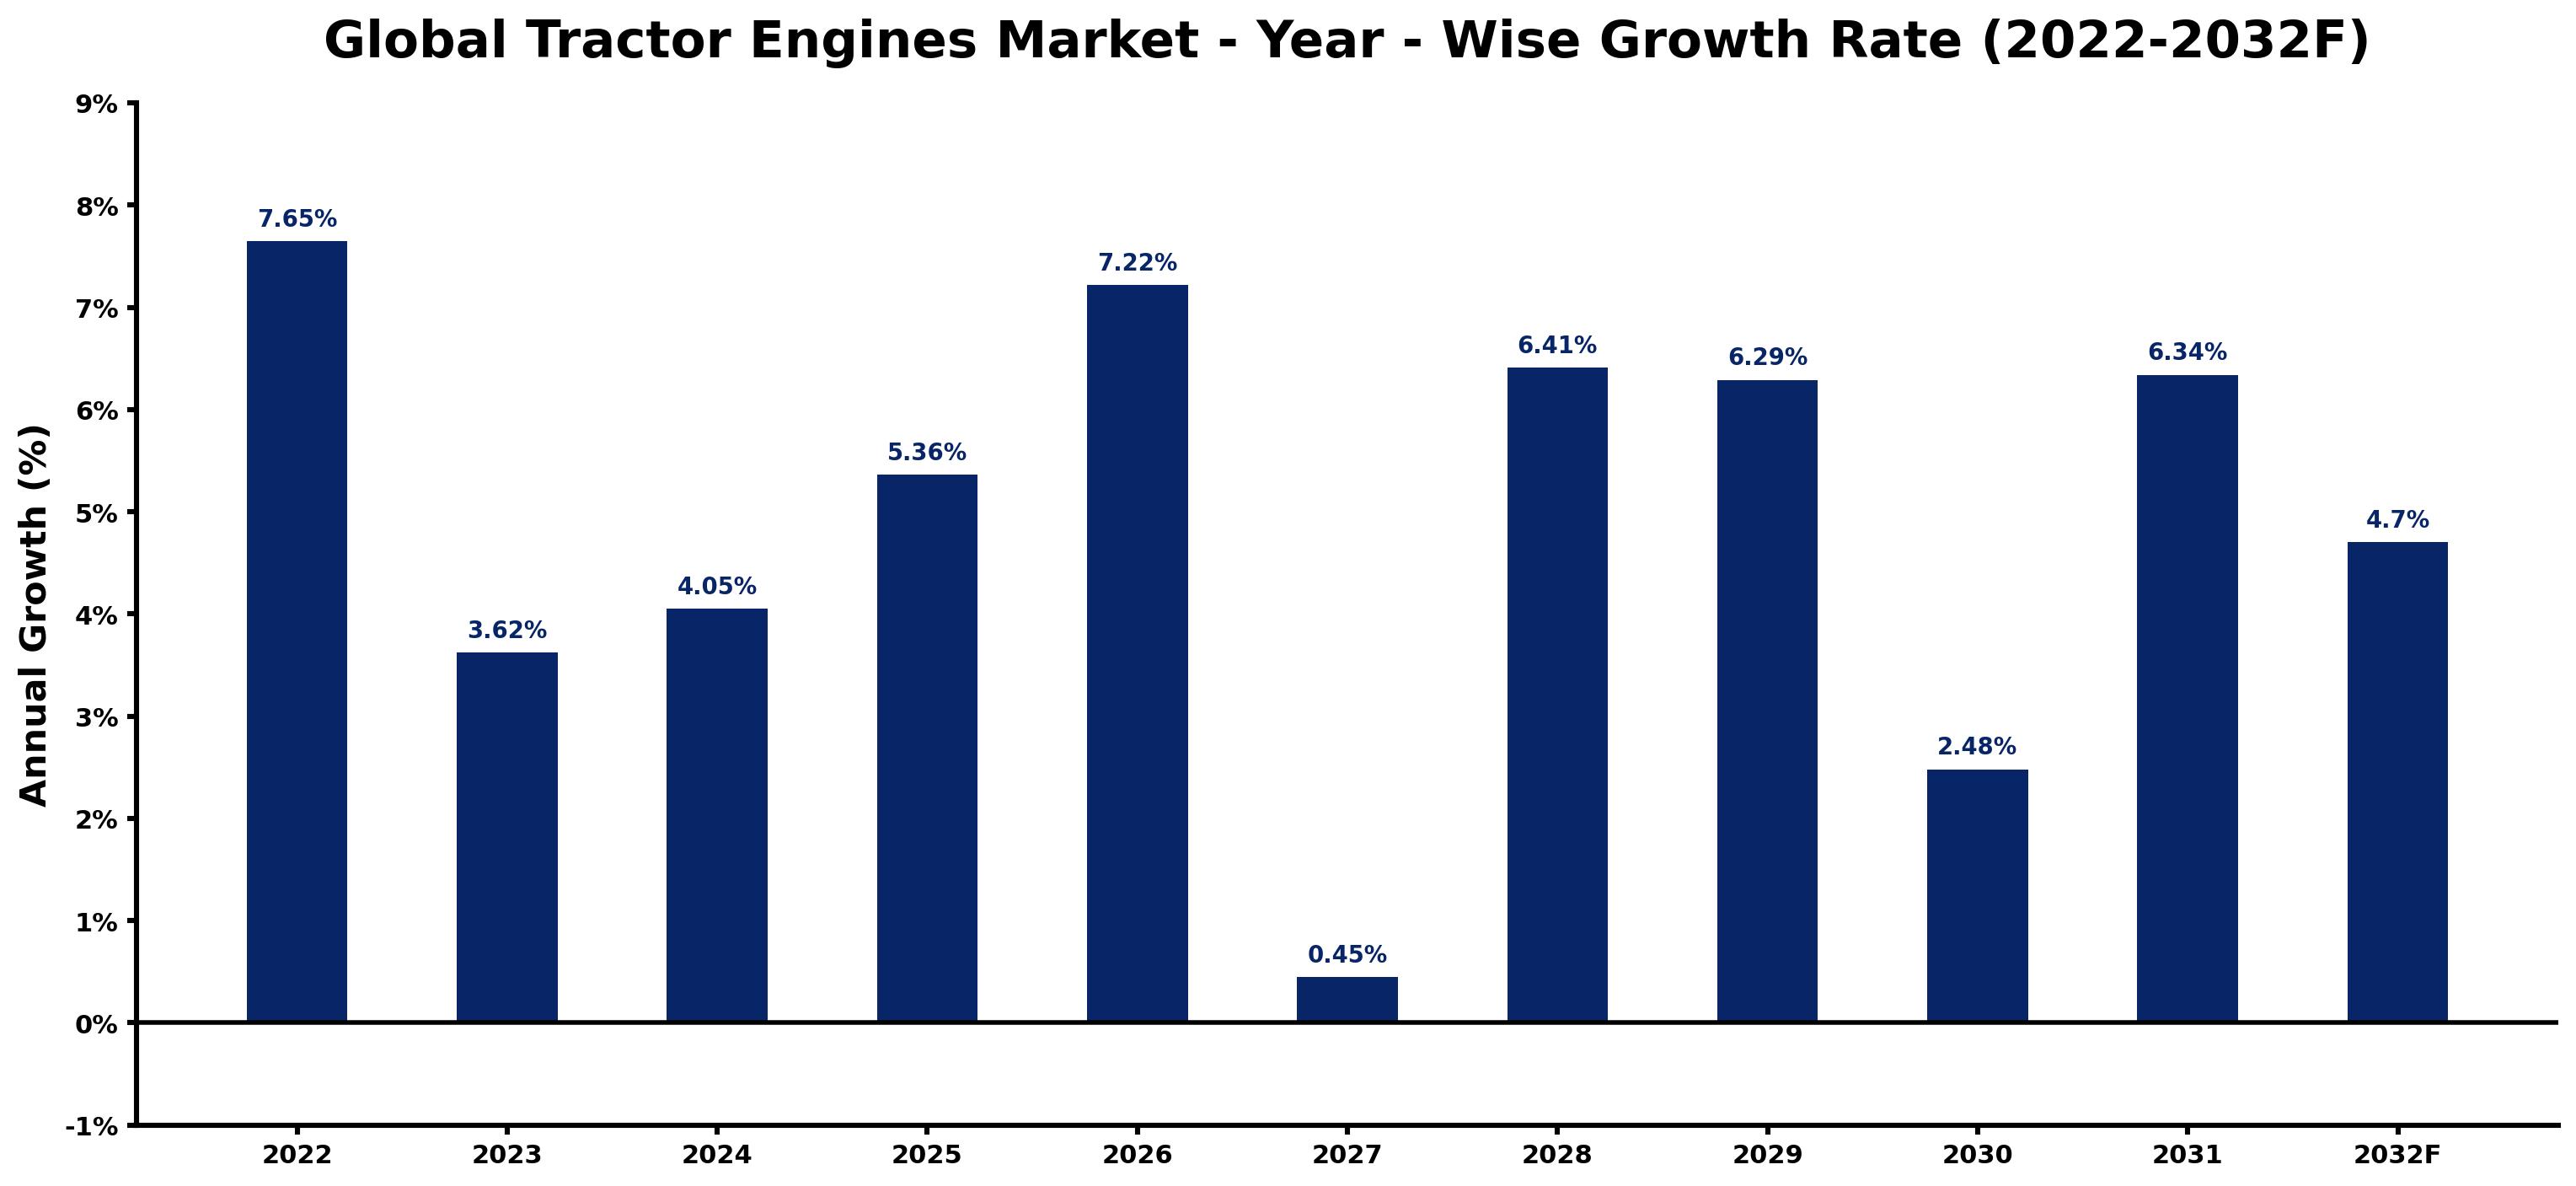
The table below presents the year‑wise growth rates along with the key drivers influencing the market
| Year | Growth Rate (%) | Major Drivers |
| 2022 | 7.65 | Tractor engines equipped with eco-friendly technologies attract attention for sustainability benefits. |
| 2023 | 3.62 | As competition intensifies, manufacturers innovate tractor engines to enhance operational efficiency. |
| 2024 | 4.05 | Farmers increasingly prefer tractor engines that facilitate precision farming and boost crop yields. |
| 2025 | 5.36 | A shift toward strategic acquisitions signals confidence in the tractor engines sector's future. |
| 2026 | 7.22 | New regulations promoting cleaner emissions mandate advancements in tractor engine designs and technologies. |
| 2027 | 0.45 | Rising input costs drive farmers to seek fuel-efficient tractor engines for cost-effective operations. |
| 2028 | 6.41 | Manufacturers introduce advanced tractor engines that optimize productivity through precision farming tools. |
| 2029 | 6.29 | Growing regional interest in tractor engines shapes a competitive environment across emerging markets. |
| 2030 | 2.48 | In North America, farmers demand tractor engines with advanced soil health management capabilities. |
| 2031 | 6.34 | Distributors streamline logistics to enhance delivery efficiency for tractor engines across various channels. |
| 2032 | 4.7 | Increasingly skilled labor forces enhance production capabilities, driving innovation in tractor engine design. |
Note - Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary research methodology, combining internal industry data, secondary research, and primary validation, updated periodically to reflect current market conditions. As markets evolve rapidly, figures for certain industries may vary slightly and are intended as informed estimates rather than absolute figures. For the most current market sizing, we recommend validating figures with a 6Wresearch analyst.
Global Tractor Engines Market Key Takeaways
Below are some of the specific key takeaways from the market, including:
- Asia-Pacific is anticipated to dominate the market with a projected share of approximately 48% as of 2025.
- High Power Engines are expected to lead segment revenue, accounting for an estimated 60% market share.
- The Low Power Engine segment is projected to grow notably at a CAGR of 6.5% from 2026 to 2032.
- John Deere, a major player, reported significant investment increase in R&D, amounting to $1.5 billion for the 2023 fiscal year.
- Growing emission regulations require manufacturers to invest in cleaner technology, with some projecting compliance costs to exceed $200 million per facility.
Evaluation of Restraints in Global Tractor Engines Market
The Global Tractor Engines Market faces significant restraints, primarily due to stringent regulatory frameworks governing emissions and efficiency. For instance, certain regions mandate compliance with Tier 4 emission standards, requiring a transition to advanced technologies that can be capital intensive—reportedly costing manufacturers upwards of $50 million for compliance modifications. Additionally, fluctuating raw material costs, particularly for aluminum and copper, render production unpredictable, compelling companies to rethink their supply chain strategies.
For example, in 2022, rising steel prices resulted in an average production cost increase of 15%, stressing the importance of securing long-term contracts with suppliers to buffer against volatility.
Global Tractor Engines Market Trends
Key operational trends are shaping the Global Tractor Engines Market primarily through technological advancements and better fuel efficiency. Manufacturers are increasingly integrating IoT capabilities into tractor engines, enhancing real-time monitoring and predictive maintenance. For instance, a prominent agricultural firm recently reported a 20% decrease in operating costs after deploying advanced telematics systems in its fleet. Another disruptive trend involves the adoption of AI-driven analytics, leading firms like Caterpillar to develop algorithms that optimize maintenance schedules and reduce downtime, showcasing a shift towards more intelligent agricultural machinery.
Moreover, sustainable practices are increasingly prioritized within the industry. The rise of alternative fuel sources, such as biodiesel and hydrogen, is revolutionizing power generation in tractors. Companies are now investing in research for hydrogen-powered engines, with projections suggesting that these solutions could enter mainstream agricultural use as early as 2025.
Global Tractor Engines Market Opportunities
The future presents several distinctive revenue opportunities within the Global Tractor Engines Market. Notably, advancements in autonomous driving technology open new avenues for market growth, as companies pursue fully automated tractors for precision agriculture. AGCO Corporation, for example, is set to roll out autonomous models capable of operating with minimal human interaction by 2026, targeting a $1 billion sales milestone. Additionally, the trend towards utilizing renewable energy sources in agriculture could drive demand for engine systems compatible with alternative fuels, which organizations project will capture 30% of the market by 2030.
Furthermore, collaborations between technology firms and engine manufacturers are fostering innovation in electrification. For instance, a partnership between a major tractor manufacturer and an electric battery startup aims to launch fully electric tractors by 2027, further diversifying solution offerings in this evolving market.
Global Tractor Engines Market by Engine Power
In the Global Tractor Engines Market, High Power Engines currently lead with a market share of approximately 60% in 2025. This dominance stems from their robust performance capabilities in land cultivation and transportation tasks. On the other hand, Low Power Engines are the fastest-growing segment, anticipated to achieve a CAGR of 6.5% from 2026 to 2032. This increased growth can be attributed to rising demand in smaller farms and the urban agriculture sector, where space optimization is critical, necessitating smaller, more efficient engines.
Global Tractor Engines Market by Region
Asia-Pacific is projected to be the largest regional market, commanding a market share of roughly 48% as of 2025. This dominance is driven by countries like China and India, where there is a concentrated demand for agricultural mechanization. Conversely, LATAM is the fastest-growing region, statistically expected to see a CAGR of 5.5% from 2026 to 2032 due to increasing investments in agricultural development, fueled by government initiatives aimed at enhancing food production and export capacity.
Government Initiatives in the Global Tractor Engines Market
The regulatory landscape for the Global Tractor Engines Market is continuously evolving, with various government initiatives aimed at promoting cleaner technologies, enhancing productivity, and addressing emission standards. These efforts often influence market dynamics, offering targeted support for certain engine technologies while imposing stricter regulations that require compliance.
- U.S. Environmental Protection Agency (EPA), Clean Air Act Enforcement, 2021 - This initiative mandates stricter emissions standards, incentivizing manufacturers to develop cleaner engines.
- European Commission, EU Green Deal, 2020 - The Green Deal focuses on making Europe the first climate-neutral continent, which directly affects agricultural machinery requirements for emissions reductions.
- Government of India, Pradhan Mantri Kisan Samman Nidhi Yojana, 2019 - This ongoing plan provides farmers direct income support, promoting the purchase of modern tractors and engines.
- Brazilian Ministry of Agriculture, Plan for Strengthening Family Farm Production, 2022 - This upcoming plan aims to improve farmer's access to modern agricultural machinery, including environmentally-friendly engine technologies.
Future Insights of the Global Tractor Engines Market
Future dynamics in the Global Tractor Engines Market are expected to shift significantly due to the rise of artificial intelligence in agriculture and sustainable farming practices. For example, companies are increasingly pursuing electrification, with John Deere investing heavily in hybrid technologies to cater to eco-conscious consumers. As regulations against emissions become more stringent, manufacturers will likely prioritize research in cleaner engine alternatives, including hydrogen solutions, expected to be commercialized by 2025, reshaping the competitive landscape.
Global Tractor Engines Market Latest Developments
Recent developments in the Global Tractor Engines Market illustrate the industry's responsiveness to technological advancements and market needs. Below are some noteworthy updates:
- Recently, John Deere introduced its latest line of hybrid tractors, enhancing fuel efficiency by 15% and targeting eco-friendly farmers seeking sustainable solutions.
- In early 2023, Caterpillar announced a partnership with a battery technology company to develop electric tractor engines, aiming for a rollout by late 2025.
- Ongoing research initiatives at AGCO Corporation focus on integrating AI-driven analytics for predictive maintenance, expected to debut in their 2026 product releases.
- Upcoming in 2024, Case IH plans to launch a completely autonomous tractor to bolster precision farming, positioning itself strongly in the competitive landscape.
Global Tractor Engines Market Key Players and Industry Positioning
The Global Tractor Engines Market is characterized by a consolidated competitive structure, primarily due to major players who dominate through innovative technologies and extensive distribution networks. The leading companies leverage their strengths to maintain significant market shares, often pursuing aggressive expansion strategies to enhance their technological edge.
| Leading Company | Core Strength | Strategic Focus |
|---|---|---|
| John Deere | Strong focus on R&D with a portfolio of advanced machinery. | Targeting hybrid technology and sustainable solutions. |
| Caterpillar | Expert in heavy machinery with robust global supply chains. | Emphasis on electrification and automation technologies. |
| Case IH | Renowned for high-performance engines and precision farming. | Expanding offerings in autonomous machinery. |
| New Holland | Leader in fuel-efficient engines and sustainability. | Implementing innovative farming techniques to boost productivity. |
| AGCO Corporation | Specializes in diversified agriculture and technology integration. | Investing in AI and machine learning for operational efficiency. |
As these companies adapt to emerging trends and technologies, the competitive dynamics will continue to evolve, underscoring the essential role of innovation in shaping the future of the Global Tractor Engines Market.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year: 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- Global Tractor Engines Market Outlook
- Market Size of Global Tractor Engines Market, 2025
- Forecast of Global Tractor Engines Market, 2032
- Historical Data and Forecast of Global Tractor Engines Revenues & Volume for the Period 2022-2032
- Global Tractor Engines Market Trend Evolution
- Global Tractor Engines Market Drivers and Challenges
- Global Tractor Engines Price Trends
- Global Tractor Engines Porter's Five Forces
- Global Tractor Engines Industry Life Cycle
- Historical Data and Forecast of Global Tractor Engines Market Revenues & Volume
- Historical Data and Forecast of Global Tractor Engines Market Revenues & Volume By Engine Power for the Period 2022-2032
- Historical Data and Forecast of Global Tractor Engines Market Revenues & Volume By Low Power Engine for the Period 2022-2032
- Historical Data and Forecast of Global Tractor Engines Market Revenues & Volume By High Power Engine for the Period 2022-2032
- Historical Data and Forecast of North America Tractor Engines Market Revenues & Volume By Engine Power for the Period 2022-2032
- Historical Data and Forecast of North America Tractor Engines Market Revenues & Volume By Low Power Engine for the Period 2022-2032
- Historical Data and Forecast of North America Tractor Engines Market Revenues & Volume By High Power Engine for the Period 2022-2032
- Historical Data and Forecast of United States of America Tractor Engines Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Canada Tractor Engines Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Rest of North America Tractor Engines Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) Tractor Engines Market Revenues & Volume By Engine Power for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) Tractor Engines Market Revenues & Volume By Low Power Engine for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) Tractor Engines Market Revenues & Volume By High Power Engine for the Period 2022-2032
- Historical Data and Forecast of Brazil Tractor Engines Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Mexico Tractor Engines Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Argentina Tractor Engines Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Rest of LATAM Tractor Engines Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Asia Tractor Engines Market Revenues & Volume By Engine Power for the Period 2022-2032
- Historical Data and Forecast of Asia Tractor Engines Market Revenues & Volume By Low Power Engine for the Period 2022-2032
- Historical Data and Forecast of Asia Tractor Engines Market Revenues & Volume By High Power Engine for the Period 2022-2032
- Historical Data and Forecast of China Tractor Engines Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of India Tractor Engines Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Japan Tractor Engines Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Rest of Asia Tractor Engines Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Africa Tractor Engines Market Revenues & Volume By Engine Power for the Period 2022-2032
- Historical Data and Forecast of Africa Tractor Engines Market Revenues & Volume By Low Power Engine for the Period 2022-2032
- Historical Data and Forecast of Africa Tractor Engines Market Revenues & Volume By High Power Engine for the Period 2022-2032
- Historical Data and Forecast of South Africa Tractor Engines Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Nigeria Tractor Engines Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Egypt Tractor Engines Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Rest of Africa Tractor Engines Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Europe Tractor Engines Market Revenues & Volume By Engine Power for the Period 2022-2032
- Historical Data and Forecast of Europe Tractor Engines Market Revenues & Volume By Low Power Engine for the Period 2022-2032
- Historical Data and Forecast of Europe Tractor Engines Market Revenues & Volume By High Power Engine for the Period 2022-2032
- Historical Data and Forecast of United Kingdom Tractor Engines Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of France Tractor Engines Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Germany Tractor Engines Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Rest of Europe Tractor Engines Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Middle East Tractor Engines Market Revenues & Volume By Engine Power for the Period 2022-2032
- Historical Data and Forecast of Middle East Tractor Engines Market Revenues & Volume By Low Power Engine for the Period 2022-2032
- Historical Data and Forecast of Middle East Tractor Engines Market Revenues & Volume By High Power Engine for the Period 2022-2032
- Historical Data and Forecast of Saudi Arabia Tractor Engines Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of UAE Tractor Engines Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Turkey Tractor Engines Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Rest of Middle East Tractor Engines Market Revenues & Volume for the Period 2022-2032
- Global Tractor Engines Market - Key Performance Indicators
- Global Tractor Engines Market - Import Export Trade Statistics
- Global Tractor Engines Market - Opportunity Assessment By Countries
- Global Tractor Engines Market - Opportunity Assessment By Engine Power
- 0
- Global Tractor Engines Market - Top Companies Market Share
- Global Tractor Engines Market - Top Companies Profiles
- Global Tractor Engines Market - Comparison of Players in Technical and Operating Parameters
- Global Tractor Engines Market - Strategic Recommendations
Markets Covered
The Global Tractor Engines Market report provides a detailed analysis of the following market segments:
By Regions and Countries:
- North America
- Europe
- LATAM
- Middle East
- Asia
- Africa
By Engine Power:
- Low Power Engine
- High Power Engine
Global Tractor Engines Market - Frequently Asked Questions
The Global Tractor Engines Market is projected to reach USD 8.2 Billion by 2032, growing from USD 5.9 Billion in 2025.
Key drivers include advancements in agricultural mechanization, increasing demand for fuel-efficient engines, and technological integration in farming practices.
The market faces challenges such as stringent emissions regulations, fluctuating raw material costs, and the need for significant investment in cleaner technologies.
High Power Engines are expected to continue leading the market, accounting for about 60% of total segment revenue in the foreseeable future.
The Low Power Engine segment is projected to grow notably, with expectations of a CAGR of 6.5% from 2026 to 2032, driven mainly by demand from smaller farms.
Emerging trends include the rise of electrification, the integration of AI for predictive maintenance, and advancements in sustainable fuel technologies such as hydrogen.
6Wresearch actively monitors the Global Tractor Engines Market and publishes its comprehensive annual report, highlighting emerging trends, growth drivers, revenue analysis, and forecast outlook. Our insights help businesses to make data-backed strategic decisions with ongoing market dynamics. Our analysts track relevent industries related to the Global Tractor Engines Market, allowing our clients with actionable intelligence and reliable forecasts tailored to emerging regional needs.
Yes, we provide customisation as per your requirements. To learn more, feel free to contact us on sales@6wresearch.com
Global Tractor Engines Market |
1 Executive Summary |
2 Introduction |
2.1 Key Highlights of the Report |
2.2 Report Description |
2.3 Market Scope & Segmentation |
2.4 Research Methodology |
2.5 Assumptions |
3 Global Tractor Engines Market Overview |
3.1 Global Regional Macro Economic Indicators |
3.2 Global Tractor Engines Market Revenues & Volume, 2022 & 2032F |
3.3 Global Tractor Engines Market - Industry Life Cycle |
3.4 Global Tractor Engines Market - Porter's Five Forces |
3.5 Global Tractor Engines Market Revenues & Volume Share, By Regions, 2022 & 2032F |
3.6 Global Tractor Engines Market Revenues & Volume Share, By Engine Power, 2022 & 2032F |
4 Global Tractor Engines Market Dynamics |
4.1 Impact Analysis |
4.2 Market Drivers |
4.3 Market Restraints |
5 Global Tractor Engines Market Trends |
6 Global Tractor Engines Market, 2022-2032 |
6.1 Global Tractor Engines Market, Revenues & Volume, By Engine Power, 2022-2032 |
6.1.1 Overview & Analysis |
6.1.2 Global Tractor Engines Market, Revenues & Volume, By Low Power Engine, 2022-2032 |
6.1.3 Global Tractor Engines Market, Revenues & Volume, By High Power Engine, 2022-2032 |
6.2.1 Overview & Analysis |
6.3.1 Overview & Analysis |
7 North America Tractor Engines Market, Overview & Analysis |
7.1 North America Tractor Engines Market Revenues & Volume, 2022-2032 |
7.2 North America Tractor Engines Market, Revenues & Volume, By Countries, 2022-2032 |
7.2.1 United States (US) Tractor Engines Market, Revenues & Volume, 2022-2032 |
7.2.2 Canada Tractor Engines Market, Revenues & Volume, 2022-2032 |
7.2.3 Rest of North America Tractor Engines Market, Revenues & Volume, 2022-2032 |
7.3 North America Tractor Engines Market, Revenues & Volume, By Engine Power, 2022-2032 |
8 Latin America (LATAM) Tractor Engines Market, Overview & Analysis |
8.1 Latin America (LATAM) Tractor Engines Market Revenues & Volume, 2022-2032 |
8.2 Latin America (LATAM) Tractor Engines Market, Revenues & Volume, By Countries, 2022-2032 |
8.2.1 Brazil Tractor Engines Market, Revenues & Volume, 2022-2032 |
8.2.2 Mexico Tractor Engines Market, Revenues & Volume, 2022-2032 |
8.2.3 Argentina Tractor Engines Market, Revenues & Volume, 2022-2032 |
8.2.4 Rest of LATAM Tractor Engines Market, Revenues & Volume, 2022-2032 |
8.3 Latin America (LATAM) Tractor Engines Market, Revenues & Volume, By Engine Power, 2022-2032 |
9 Asia Tractor Engines Market, Overview & Analysis |
9.1 Asia Tractor Engines Market Revenues & Volume, 2022-2032 |
9.2 Asia Tractor Engines Market, Revenues & Volume, By Countries, 2022-2032 |
9.2.1 India Tractor Engines Market, Revenues & Volume, 2022-2032 |
9.2.2 China Tractor Engines Market, Revenues & Volume, 2022-2032 |
9.2.3 Japan Tractor Engines Market, Revenues & Volume, 2022-2032 |
9.2.4 Rest of Asia Tractor Engines Market, Revenues & Volume, 2022-2032 |
9.3 Asia Tractor Engines Market, Revenues & Volume, By Engine Power, 2022-2032 |
10 Africa Tractor Engines Market, Overview & Analysis |
10.1 Africa Tractor Engines Market Revenues & Volume, 2022-2032 |
10.2 Africa Tractor Engines Market, Revenues & Volume, By Countries, 2022-2032 |
10.2.1 South Africa Tractor Engines Market, Revenues & Volume, 2022-2032 |
10.2.2 Egypt Tractor Engines Market, Revenues & Volume, 2022-2032 |
10.2.3 Nigeria Tractor Engines Market, Revenues & Volume, 2022-2032 |
10.2.4 Rest of Africa Tractor Engines Market, Revenues & Volume, 2022-2032 |
10.3 Africa Tractor Engines Market, Revenues & Volume, By Engine Power, 2022-2032 |
11 Europe Tractor Engines Market, Overview & Analysis |
11.1 Europe Tractor Engines Market Revenues & Volume, 2022-2032 |
11.2 Europe Tractor Engines Market, Revenues & Volume, By Countries, 2022-2032 |
11.2.1 United Kingdom Tractor Engines Market, Revenues & Volume, 2022-2032 |
11.2.2 Germany Tractor Engines Market, Revenues & Volume, 2022-2032 |
11.2.3 France Tractor Engines Market, Revenues & Volume, 2022-2032 |
11.2.4 Rest of Europe Tractor Engines Market, Revenues & Volume, 2022-2032 |
11.3 Europe Tractor Engines Market, Revenues & Volume, By Engine Power, 2022-2032 |
12 Middle East Tractor Engines Market, Overview & Analysis |
12.1 Middle East Tractor Engines Market Revenues & Volume, 2022-2032 |
12.2 Middle East Tractor Engines Market, Revenues & Volume, By Countries, 2022-2032 |
12.2.1 Saudi Arabia Tractor Engines Market, Revenues & Volume, 2022-2032 |
12.2.2 UAE Tractor Engines Market, Revenues & Volume, 2022-2032 |
12.2.3 Turkey Tractor Engines Market, Revenues & Volume, 2022-2032 |
12.3 Middle East Tractor Engines Market, Revenues & Volume, By Engine Power, 2022-2032 |
13 Global Tractor Engines Market Key Performance Indicators |
14 Global Tractor Engines Market - Export/Import By Countries Assessment |
15 Global Tractor Engines Market - Opportunity Assessment |
15.1 Global Tractor Engines Market Opportunity Assessment, By Countries, 2022 & 2032F |
15.2 Global Tractor Engines Market Opportunity Assessment, By Engine Power, 2022 & 2032F |
16 Global Tractor Engines Market - Competitive Landscape |
16.1 Global Tractor Engines Market Revenue Share, By Companies, 2025 |
16.2 Global Tractor Engines Market Competitive Benchmarking, By Operating and Technical Parameters |
17 Top 10 Company Profiles |
18 Recommendations |
19 Disclaimer |
Global Go To Market Strategy - 2030
Export potential enables firms to identify high-growth global markets with greater confidence by combining advanced trade intelligence with a structured quantitative methodology. The framework analyzes emerging demand trends and country-level import patterns while integrating macroeconomic and trade datasets such as GDP and population forecasts, bilateral import–export flows, tariff structures, elasticity differentials between developed and developing economies, geographic distance, and import demand projections. Using weighted trade values from 2020–2024 as the base period to project country-to-country export potential for 2030, these inputs are operationalized through calculated drivers such as gravity model parameters, tariff impact factors, and projected GDP per-capita growth. Through an analysis of hidden potentials, demand hotspots, and market conditions that are most favorable to success, this method enables firms to focus on target countries, maximize returns, and global expansion with data, backed by accuracy.
By factoring in the projected importer demand gap that is currently unmet and could be potential opportunity, it identifies the potential for the Exporter (Country) among 190 countries, against the general trade analysis, which identifies the biggest importer or exporter.
To discover high-growth global markets and optimize your business strategy:
Click Here
Request Primary Research & Report
- Single User License$ 4,560
- Department License$ 5,055
- Site License$ 5,595
- Global License$ 6,000
Leadership Perspectives from Industry Events
Search
6Wresearch in the News
 Forbes
Citing 6Wresearch analytics to map global infrastructure and pharmaceutical industry trajectories.
 Bloomberg Law
Direct syndication of 6Wresearch's macro data points, capturing complex supply chain shifts.
 Reuters
Tracking industrial manufacturing adjustments and electronic security ecosystem scaling.
 Mint
Utilizing deep-tech sector market sizing to analyze global automation and robotics.
 The Economic Times
Anchoring features on industrial IoT growth metrics and connected smart-grid devices.
 Business Standard
Featuring strategic evaluations of Advanced Driver Assistance Systems (ADAS) and AI road safety.
 The Hindu
Spotlighting core commercial metrics ranging from unmanned aerial vehicles (UAVs) to consumer durables.
 Financial Express
Anchoring quarterly reviews on cross-border real estate tech and structural hardware manufacturing.
 Yahoo Finance
Syndicating the tracker's $30.1 billion untapped-market findings, spotlighting Japan, the US and China as India's top new-potential importers.
 India Today
Carrying the release on smartphones leading India's export potential to $94 billion by 2031, per 6WExportGTM data.
 Dailyhunt
Distributing the tracker findings to its regional readership, framing India's export diversification into Japan and Mexico.
 PR Newswire Original release
Publishing the full India Export Attractiveness Tracker 2026, detailing new trade corridors across iron ore, LCVs and pharmaceuticals.
 The Industrial
Highlighting the tracker's read on India's semiconductor ambitions and long-term chip-assembly export potential.
 PTI News
Reporting on the $66.81 billion pharmaceuticals export opportunity flagged in the tracker, amid looming US generic-drug tariffs.
 Tribune India
Covering the tracker's tariff-versus-regulation analysis across India's mature export markets in the US, China and UAE.
 ANI News
Amplifying the report's findings on polished diamonds, refined petroleum and medicines as India's core export engines.
 International Business Magazine
Covering the report's insight into how AEB, blind spot detection, and driver monitoring are reshaping India's ADAS market.
 Focus Gaming News
Highlighting the research forecast for Egypt's gambling market, projecting steady growth through 2032.
Thought Leadership and Analyst Meet
Our Clients
Latest Reports
- Global Whey Protein Market (2025-2031)
- Bahrain Vehicle-Supported Bicycle Drive Chains Market (2026-2032)
- Azerbaijan Vehicle-Supported Bicycle Drive Chains Market (2026-2032)
- Australia Vehicle-Supported Bicycle Drive Chains Market (2026-2032)
- Argentina Vehicle-Supported Bicycle Drive Chains Market (2026-2032)
- Algeria Vehicle-Supported Bicycle Drive Chains Market (2026-2032)
- Zimbabwe Vehicle-Grade Aluminum Materials Market (2026-2032)
- Zambia Vehicle-Grade Aluminum Materials Market (2026-2032)
- Yemen Vehicle-Grade Aluminum Materials Market (2026-2032)
- Vanuatu Vehicle-Grade Aluminum Materials Market (2026-2032)
Industry Events and Analyst Meet

EV India Expo 2026
HIMTEX 2026
India Refining Summit 2026
India EV Show 2026
EV tech India Expo 2026
Whitepaper
- Middle East & Africa Commercial Security Market Click here to view more.
- Middle East & Africa Fire Safety Systems & Equipment Market Click here to view more.
- GCC Drone Market Click here to view more.
- Middle East Lighting Fixture Market Click here to view more.
- GCC Physical & Perimeter Security Market Click here to view more.