United States (US) Endpoint Detection and Response Market (2026-2032) Outlook | Share, Growth, Companies, Analysis, Forecast, Value, Revenue, Industry, Trends & Size
Market Forecast By Component (Solution , Service), By Enforcement Point (Workstations, Mobile Devices, Servers, POS Terminals), By Deployment Mode (Cloud, On-premises), By Organization Size (Small and Medium Enterprises (SMEs), Large enterprises), By Vertical (Banking, Financial Services, and Insurance (BFSI), IT and telecom, Government and public utilities, Aerospace and defense, Manufacturing, Healthcare, Retail, Others) And Competitive Landscape
| Product Code: ETC4392362 | Publication Date: Jul 2023 | Updated Date: Jul 2026 | Product Type: Report | |
| Publisher: 6Wresearch | Author: Ravi Bhandari | No. of Pages: 85 | No. of Figures: 45 | No. of Tables: 25 |
United States (US) Endpoint Detection and Response Market Size & Growth Rate (2026-2032)
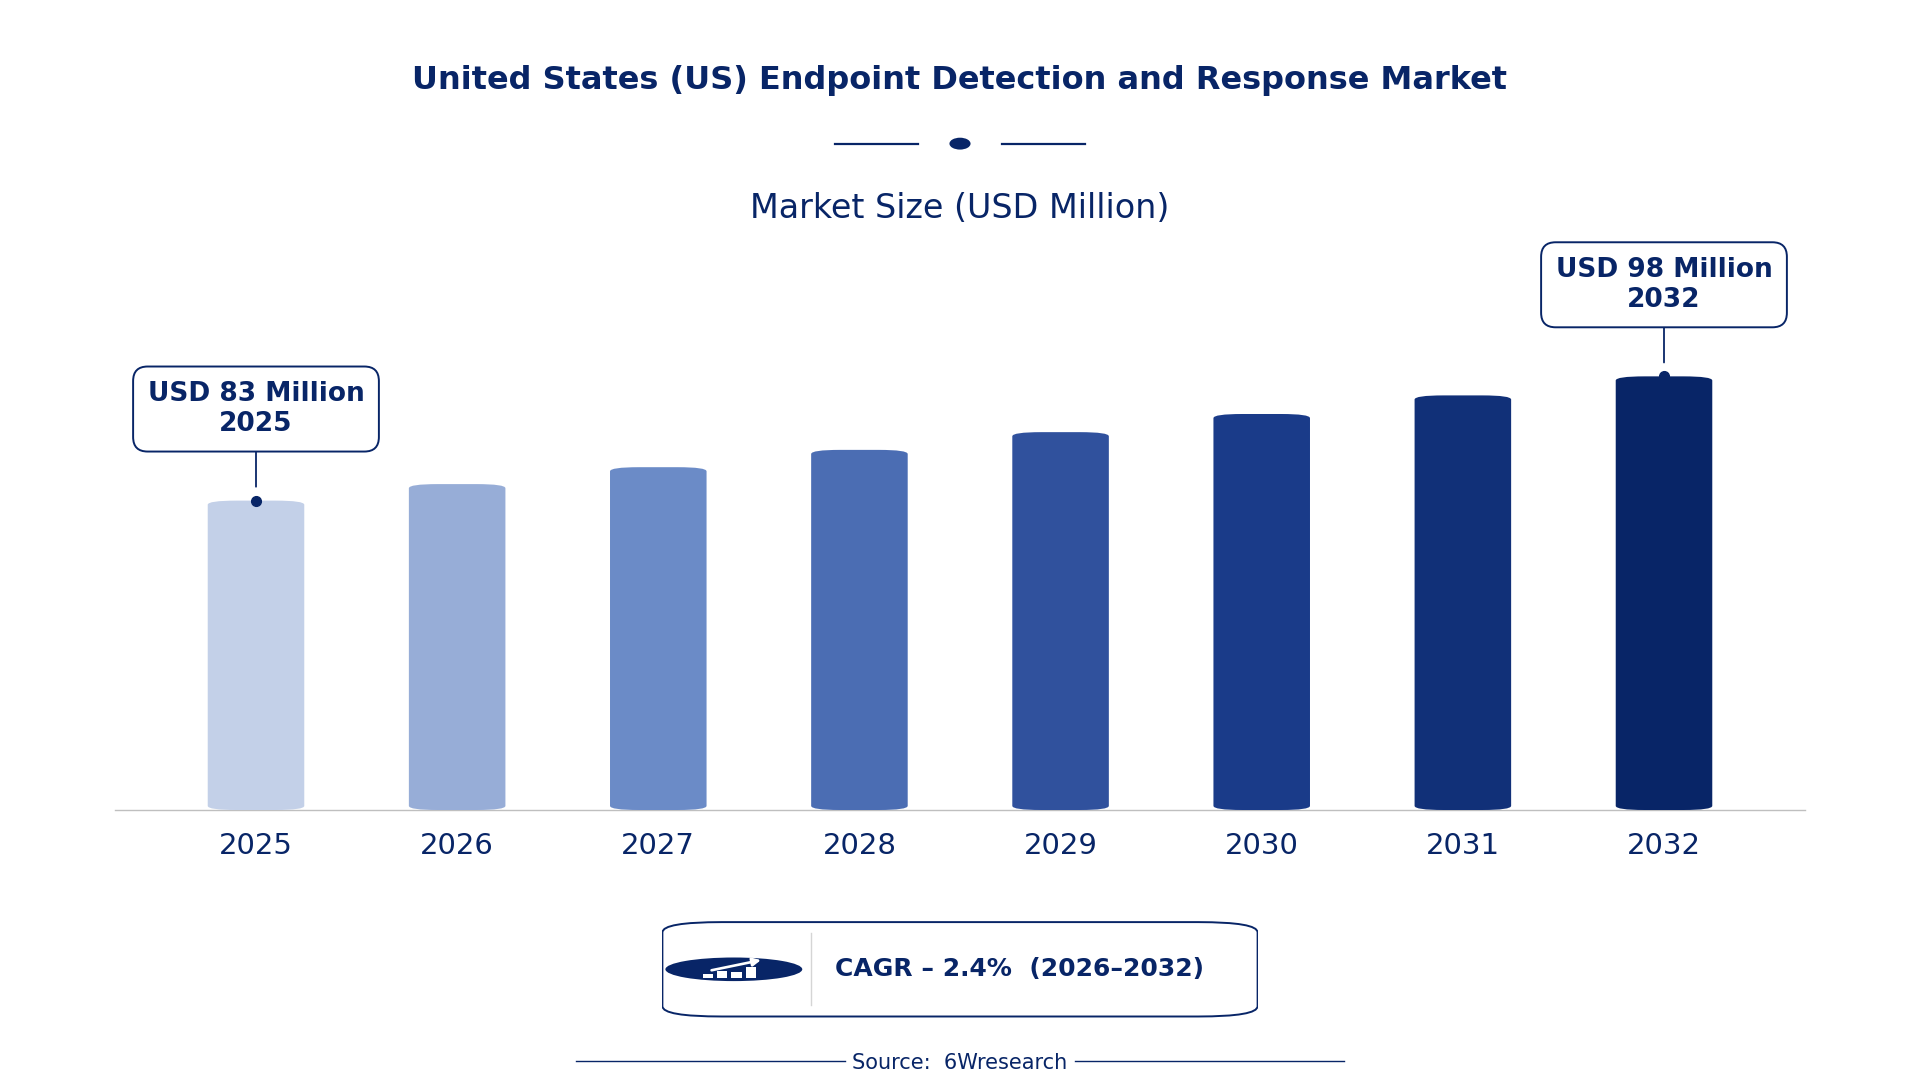
The United States (US) Endpoint Detection and Response Market was estimated at USD 83 Million in 2025 and is projected to reach USD 98 Million by 2032, growing at a CAGR of 2.4% from 2026 to 2032.
United States (US) Endpoint Detection and Response Market Synopsis
The rise in sophisticated cyber threats is pushing organizations in the US to prioritize endpoint detection and response solutions. As remote work becomes the norm, the vulnerabilities associated with diverse endpoint devices continue to escalate, creating a heightened demand for effective EDR solutions.
Companies now recognize that traditional security measures are insufficient against modern cyberattacks. Consequently, real-time visibility and response capabilities offered by EDR systems have emerged as critical components in safeguarding sensitive data and maintaining business continuity.
United States (US) Endpoint Detection and Response Market Year-wise Growth Rate and Key Drivers
This graph illustrates the annual growth rates of the United States (US) Endpoint Detection and Response Market from 2021 to 2032, highlighting a steady upward trajectory and projected expansion over the forecast period.
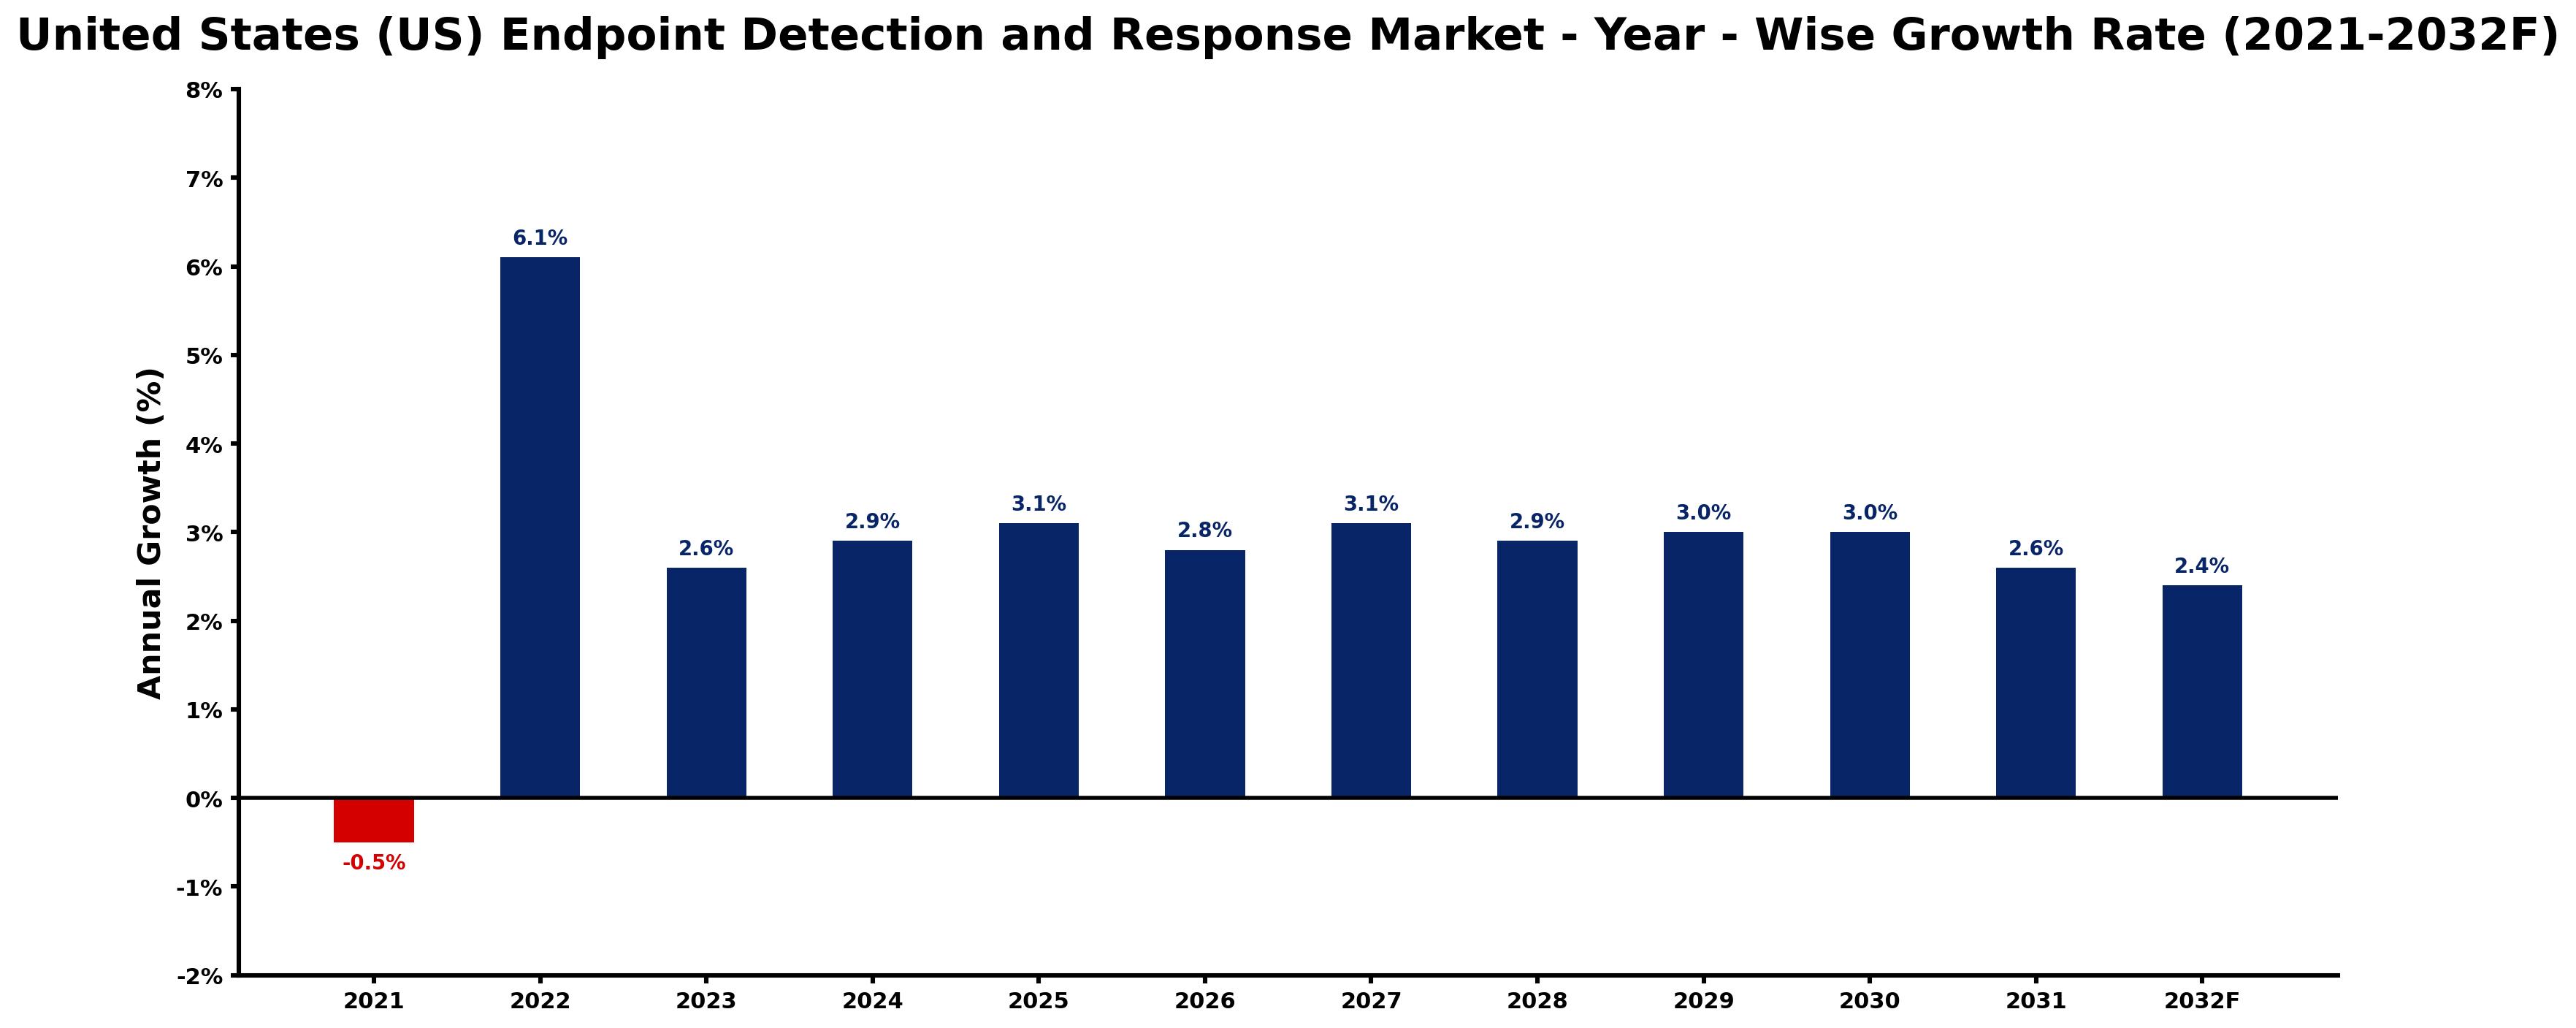
The table below presents the year‑wise growth rates along with the key drivers influencing the market
| Year | Growth Rate | Major Drivers |
| 2021 | -0.5% | CISA guidance limited adoption of new EDR solutions. |
| 2022 | 6.1% | Increased federal investment in cybersecurity through CISA programs. |
| 2023 | 2.6% | Rising sophistication of cyber threats in US landscape. |
| 2024 | 2.9% | Growth of remote work necessitating stronger endpoint protections. |
| 2025 | 3.1% | Implementation of state-level data privacy regulations. |
| 2026 | 2.8% | Adoption of Zero Trust architectures among US enterprises. |
| 2027 | 3.1% | Increased focus on ransomware response solutions following attacks. |
| 2028 | 2.9% | Emergence of advanced persistent threats targeting critical infrastructure. |
| 2029 | 3.0% | Widespread adoption of IoT devices driving security upgrades. |
| 2030 | 3.0% | Legislation requiring more stringent protection of consumer data. |
| 2031 | 2.6% | Enhanced federal guidelines on secure software development practices. |
| 2032 | 2.4% | Greater emphasis on multi-factor authentication by companies. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
United States (US) Endpoint Detection and Response Market Key Takeaways
Below are some of the specific key takeaways from the market, including:
- Cyber threats are growing more sophisticated, prompting businesses to invest heavily in EDR solutions.
- The shift towards cloud-based EDR systems aligns with the increasing adoption of remote work practices.
- Integration of AI and machine learning in EDR tools enhances their ability to detect threats proactively.
- Regulatory pressures are pushing organizations to adopt compliant EDR systems across various industries.
- Managed EDR services are gaining traction as firms seek external expertise to bolster their cybersecurity efforts.
Evaluation of Restraints in United States (US) Endpoint Detection and Response Market
Despite the growth trajectory, the US Endpoint Detection and Response market grapples with challenges that could hinder its potential. Organizations often face alert fatigue, caused by the overwhelming number of notifications generated by EDR solutions. This can lead to significant hurdles in accurately identifying and responding to genuine threats.
on top of that, a shortage of skilled cybersecurity professionals who can effectively manage these sophisticated tools presents a critical barrier. Concerns about data privacy and compliance also complicate the decision-making process for businesses looking to implement robust EDR systems. Addressing these issues is essential to enhance the overall effectiveness of endpoint security solutions.
United States (US) Endpoint Detection and Response Market Trends
Current trends indicate a marked shift towards cloud-based EDR solutions, responding to the demands of an increasingly mobile workforce. Companies are also prioritizing the integration of AI and machine learning technologies, which significantly elevate threat detection capabilities and response times.
The popularity of managed EDR services is on the rise, as organizations seek to leverage external expertise in combating advanced cyber threats. These trends reflect a broader recognition of the need for proactive and responsive security measures in a complex digital environment.
United States (US) Endpoint Detection and Response Market Opportunities
Significant investment opportunities are emerging within the US Endpoint Detection and Response market. Organizations are eager to adopt advanced platforms equipped with machine learning, which allows for more efficient threat identification and response. This presents a chance for investors to capitalize on companies that provide innovative EDR solutions.
on top of that, there is a growing market for service providers offering managed detection and response services, which help companies strengthen their cybersecurity frameworks without necessitating a large in-house team. As the cyber threat landscape continues to evolve, the potential for investment in this sector remains promising.
Government Initiatives in the United States (US) Endpoint Detection and Response Market
Government policies are significantly influencing the United States Endpoint Detection and Response market. With the establishment of the Cybersecurity and Infrastructure Security Agency (CISA) as a leading federal body for cybersecurity, there is a stronger focus on implementing frameworks that enhance organizational security measures.
- A recently completed initiative involved the launch of the National Cybersecurity Strategy, aimed at improving overall national resilience against cyber threats.
- A current program mandates increased collaboration between federal agencies and private sector organizations to bolster endpoint security measures.
- Upcoming regulations are expected to introduce stricter compliance requirements for data protection, compelling organizations to adopt EDR solutions.
- The introduction of the Cyber Safety Review Board has encouraged organizations to adopt higher standards for endpoint security practices.
- Plans for a public-private partnership aimed at advancing EDR technology adoption across critical infrastructure sectors are underway.
Future Insights of the United States (US) Endpoint Detection and Response Market
Looking ahead to 2026-2032, the US Endpoint Detection and Response market is set for robust growth. The continued rise in remote work, coupled with escalating cyber threats, will drive demand for EDR solutions. As organizations increasingly recognize the necessity of a multi-layered cybersecurity approach, the adoption of advanced EDR systems will likely accelerate.
on top of that, technological advancements in AI and machine learning will further enhance the efficacy of EDR solutions, making them indispensable tools in any comprehensive cybersecurity strategy. Stakeholders must remain agile to capitalize on these trends, ensuring they remain ahead of emerging threats.
United States (US) Endpoint Detection and Response Market Latest Developments
In recent months, the US Endpoint Detection and Response market has witnessed notable advancements, indicating a commitment to enhancing cybersecurity measures across industries. Companies are actively evolving their offerings to incorporate more intelligent threat detection and user-centric designs, showcasing their responsiveness to market needs.
- A major technology vendor launched a next-generation EDR platform in early 2025, featuring advanced predictive analytics to combat evolving cyber threats.
- An initiative that began in mid-2025 focuses on enhancing interoperability between various EDR solutions and existing security infrastructures.
- A recent partnership between multiple cybersecurity firms aims to develop integrated EDR solutions tailored to specific industry needs, enhancing sector-specific defenses.
- A rollout expected to begin in the second half of 2026 will introduce a training program for cybersecurity professionals, addressing the skills gap in the industry.
- Several companies are currently upgrading their EDR offerings to include automation capabilities, improving response times and minimizing human intervention.
United States (US) Endpoint Detection and Response Market - Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year: 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- United States (US) Endpoint Detection and Response Market Outlook
- Market Size of United States (US) Endpoint Detection and Response Market, 2025
- Forecast of United States (US) Endpoint Detection and Response Market, 2032
- Historical Data and Forecast of United States (US) Endpoint Detection and Response Revenues & Volume for the Period 2022-2032F
- United States (US) Endpoint Detection and Response Market Trend Evolution
- United States (US) Endpoint Detection and Response Market Drivers and Challenges
- United States (US) Endpoint Detection and Response Price Trends
- United States (US) Endpoint Detection and Response Porter's Five Forces
- United States (US) Endpoint Detection and Response Industry Life Cycle
- Historical Data and Forecast of United States (US) Endpoint Detection and Response Market Revenues & Volume By Component for the Period 2022-2032F
- Historical Data and Forecast of United States (US) Endpoint Detection and Response Market Revenues & Volume By Solution for the Period 2022-2032F
- Historical Data and Forecast of United States (US) Endpoint Detection and Response Market Revenues & Volume By Service for the Period 2022-2032F
- Historical Data and Forecast of United States (US) Endpoint Detection and Response Market Revenues & Volume By Enforcement Point for the Period 2022-2032F
- Historical Data and Forecast of United States (US) Endpoint Detection and Response Market Revenues & Volume By Workstations for the Period 2022-2032F
- Historical Data and Forecast of United States (US) Endpoint Detection and Response Market Revenues & Volume By Mobile Devices for the Period 2022-2032F
- Historical Data and Forecast of United States (US) Endpoint Detection and Response Market Revenues & Volume By Servers for the Period 2022-2032F
- Historical Data and Forecast of United States (US) Endpoint Detection and Response Market Revenues & Volume By POS Terminals for the Period 2022-2032F
- Historical Data and Forecast of United States (US) Endpoint Detection and Response Market Revenues & Volume By Deployment Mode for the Period 2022-2032F
- Historical Data and Forecast of United States (US) Endpoint Detection and Response Market Revenues & Volume By Cloud for the Period 2022-2032F
- Historical Data and Forecast of United States (US) Endpoint Detection and Response Market Revenues & Volume By On-premises for the Period 2022-2032F
- Historical Data and Forecast of United States (US) Endpoint Detection and Response Market Revenues & Volume By Organization Size for the Period 2022-2032F
- Historical Data and Forecast of United States (US) Endpoint Detection and Response Market Revenues & Volume By Small and Medium Enterprises (SMEs) for the Period 2022-2032F
- Historical Data and Forecast of United States (US) Endpoint Detection and Response Market Revenues & Volume By Large enterprises for the Period 2022-2032F
- Historical Data and Forecast of United States (US) Endpoint Detection and Response Market Revenues & Volume By Vertical for the Period 2022-2032F
- Historical Data and Forecast of United States (US) Endpoint Detection and Response Market Revenues & Volume By Banking, Financial Services, and Insurance (BFSI) for the Period 2022-2032F
- Historical Data and Forecast of United States (US) Endpoint Detection and Response Market Revenues & Volume By IT and telecom for the Period 2022-2032F
- Historical Data and Forecast of United States (US) Endpoint Detection and Response Market Revenues & Volume By Government and public utilities for the Period 2022-2032F
- Historical Data and Forecast of United States (US) Endpoint Detection and Response Market Revenues & Volume By Aerospace and defense for the Period 2022-2032F
- Historical Data and Forecast of United States (US) Endpoint Detection and Response Market Revenues & Volume By Manufacturing for the Period 2022-2032F
- Historical Data and Forecast of United States (US) Endpoint Detection and Response Market Revenues & Volume By Healthcare for the Period 2022-2032F
- Historical Data and Forecast of United States (US) Endpoint Detection and Response Market Revenues & Volume By Retail for the Period 2022-2032F
- Historical Data and Forecast of United States (US) Endpoint Detection and Response Market Revenues & Volume By Others for the Period 2022-2032F
- United States (US) Endpoint Detection and Response Import Export Trade Statistics
- Market Opportunity Assessment By Component
- Market Opportunity Assessment By Enforcement Point
- Market Opportunity Assessment By Deployment Mode
- Market Opportunity Assessment By Organization Size
- Market Opportunity Assessment By Vertical
- United States (US) Endpoint Detection and Response Top Companies Market Share
- United States (US) Endpoint Detection and Response Competitive Benchmarking By Technical and Operational Parameters
- United States (US) Endpoint Detection and Response Company Profiles
- United States (US) Endpoint Detection and Response Key Strategic Recommendations
Frequently Asked Questions About the Market Study (FAQs):
The increasing frequency of cyber threats and the shift towards remote work are major factors driving growth. Organizations are realizing the necessity of enhanced endpoint security to protect sensitive information and ensure business continuity.
The United States Endpoint Detection and Response Market was estimated at USD 83 Million in 2025 and is projected to reach USD 98 Million by 2032, growing at a CAGR of 2.4% from 2026 to 2032.
Key trends include a significant move towards cloud-based solutions, increasing reliance on AI for advanced threat detection, and growing interest in managed EDR services among organizations.
Government initiatives such as the establishment of CISA and the introduction of new cybersecurity regulations are crucial. They provide frameworks that organizations must adhere to, thereby driving demand for compliant EDR solutions.
There are ample opportunities for investing in companies that develop cutting-edge EDR platforms and services, especially those utilizing machine learning and behavioral analysis capabilities.
6Wresearch actively monitors the United States (US) Endpoint Detection and Response Market and publishes its comprehensive annual report, highlighting emerging trends, growth drivers, revenue analysis, and forecast outlook. Our insights help businesses to make data-backed strategic decisions with ongoing market dynamics. Our analysts track relevent industries related to the United States (US) Endpoint Detection and Response Market, allowing our clients with actionable intelligence and reliable forecasts tailored to emerging regional needs.
Yes, we provide customisation as per your requirements. To learn more, feel free to contact us on sales@6wresearch.com
1 Executive Summary |
2 Introduction |
2.1 Key Highlights of the Report |
2.2 Report Description |
2.3 Market Scope & Segmentation |
2.4 Research Methodology |
2.5 Assumptions |
3 United States (US) Endpoint Detection and Response Market Overview |
3.1 United States (US) Country Macro Economic Indicators |
3.2 United States (US) Endpoint Detection and Response Market Revenues & Volume, 2022 & 2032F |
3.3 United States (US) Endpoint Detection and Response Market - Industry Life Cycle |
3.4 United States (US) Endpoint Detection and Response Market - Porter's Five Forces |
3.5 United States (US) Endpoint Detection and Response Market Revenues & Volume Share, By Component, 2022 & 2032F |
3.6 United States (US) Endpoint Detection and Response Market Revenues & Volume Share, By Enforcement Point, 2022 & 2032F |
3.7 United States (US) Endpoint Detection and Response Market Revenues & Volume Share, By Deployment Mode, 2022 & 2032F |
3.8 United States (US) Endpoint Detection and Response Market Revenues & Volume Share, By Organization Size, 2022 & 2032F |
3.9 United States (US) Endpoint Detection and Response Market Revenues & Volume Share, By Vertical, 2022 & 2032F |
4 United States (US) Endpoint Detection and Response Market Dynamics |
4.1 Impact Analysis |
4.2 Market Drivers |
4.2.1 Increasing cyber threats and sophisticated cyber attacks targeting endpoints |
4.2.2 Stringent data protection regulations and compliance requirements |
4.2.3 Growing adoption of Bring Your Own Device (BYOD) policies in organizations |
4.3 Market Restraints |
4.3.1 High initial investment and ongoing costs associated with implementing endpoint detection and response solutions |
4.3.2 Lack of skilled cybersecurity professionals to effectively manage and respond to endpoint security incidents |
5 United States (US) Endpoint Detection and Response Market Trends |
6 United States (US) Endpoint Detection and Response Market, By Types |
6.1 United States (US) Endpoint Detection and Response Market, By Component |
6.1.1 Overview and Analysis |
6.1.2 United States (US) Endpoint Detection and Response Market Revenues & Volume, By Component, 2022-2032F |
6.1.3 United States (US) Endpoint Detection and Response Market Revenues & Volume, By Solution , 2022-2032F |
6.1.4 United States (US) Endpoint Detection and Response Market Revenues & Volume, By Service, 2022-2032F |
6.2 United States (US) Endpoint Detection and Response Market, By Enforcement Point |
6.2.1 Overview and Analysis |
6.2.2 United States (US) Endpoint Detection and Response Market Revenues & Volume, By Workstations, 2022-2032F |
6.2.3 United States (US) Endpoint Detection and Response Market Revenues & Volume, By Mobile Devices, 2022-2032F |
6.2.4 United States (US) Endpoint Detection and Response Market Revenues & Volume, By Servers, 2022-2032F |
6.2.5 United States (US) Endpoint Detection and Response Market Revenues & Volume, By POS Terminals, 2022-2032F |
6.3 United States (US) Endpoint Detection and Response Market, By Deployment Mode |
6.3.1 Overview and Analysis |
6.3.2 United States (US) Endpoint Detection and Response Market Revenues & Volume, By Cloud, 2022-2032F |
6.3.3 United States (US) Endpoint Detection and Response Market Revenues & Volume, By On-premises, 2022-2032F |
6.4 United States (US) Endpoint Detection and Response Market, By Organization Size |
6.4.1 Overview and Analysis |
6.4.2 United States (US) Endpoint Detection and Response Market Revenues & Volume, By Small and Medium Enterprises (SMEs), 2022-2032F |
6.4.3 United States (US) Endpoint Detection and Response Market Revenues & Volume, By Large enterprises, 2022-2032F |
6.5 United States (US) Endpoint Detection and Response Market, By Vertical |
6.5.1 Overview and Analysis |
6.5.2 United States (US) Endpoint Detection and Response Market Revenues & Volume, By Banking, Financial Services, and Insurance (BFSI), 2022-2032F |
6.5.3 United States (US) Endpoint Detection and Response Market Revenues & Volume, By IT and telecom, 2022-2032F |
6.5.4 United States (US) Endpoint Detection and Response Market Revenues & Volume, By Government and public utilities, 2022-2032F |
6.5.5 United States (US) Endpoint Detection and Response Market Revenues & Volume, By Aerospace and defense, 2022-2032F |
6.5.6 United States (US) Endpoint Detection and Response Market Revenues & Volume, By Manufacturing, 2022-2032F |
6.5.7 United States (US) Endpoint Detection and Response Market Revenues & Volume, By Healthcare, 2022-2032F |
6.5.8 United States (US) Endpoint Detection and Response Market Revenues & Volume, By Others, 2022-2032F |
6.5.9 United States (US) Endpoint Detection and Response Market Revenues & Volume, By Others, 2022-2032F |
7 United States (US) Endpoint Detection and Response Market Import-Export Trade Statistics |
7.1 United States (US) Endpoint Detection and Response Market Export to Major Countries |
7.2 United States (US) Endpoint Detection and Response Market Imports from Major Countries |
8 United States (US) Endpoint Detection and Response Market Key Performance Indicators |
8.1 Average time to detect and respond to security incidents on endpoints |
8.2 Percentage reduction in successful endpoint security breaches |
8.3 Rate of endpoint security incidents per month |
9 United States (US) Endpoint Detection and Response Market - Opportunity Assessment |
9.1 United States (US) Endpoint Detection and Response Market Opportunity Assessment, By Component, 2022 & 2032F |
9.2 United States (US) Endpoint Detection and Response Market Opportunity Assessment, By Enforcement Point, 2022 & 2032F |
9.3 United States (US) Endpoint Detection and Response Market Opportunity Assessment, By Deployment Mode, 2022 & 2032F |
9.4 United States (US) Endpoint Detection and Response Market Opportunity Assessment, By Organization Size, 2022 & 2032F |
9.5 United States (US) Endpoint Detection and Response Market Opportunity Assessment, By Vertical, 2022 & 2032F |
10 United States (US) Endpoint Detection and Response Market - Competitive Landscape |
10.1 United States (US) Endpoint Detection and Response Market Revenue Share, By Companies, 2025 |
10.2 United States (US) Endpoint Detection and Response Market Competitive Benchmarking, By Operating and Technical Parameters |
11 Company Profiles |
12 Recommendations |
13 Disclaimer |
Global Go To Market Strategy - 2030
Export potential enables firms to identify high-growth global markets with greater confidence by combining advanced trade intelligence with a structured quantitative methodology. The framework analyzes emerging demand trends and country-level import patterns while integrating macroeconomic and trade datasets such as GDP and population forecasts, bilateral import–export flows, tariff structures, elasticity differentials between developed and developing economies, geographic distance, and import demand projections. Using weighted trade values from 2020–2024 as the base period to project country-to-country export potential for 2030, these inputs are operationalized through calculated drivers such as gravity model parameters, tariff impact factors, and projected GDP per-capita growth. Through an analysis of hidden potentials, demand hotspots, and market conditions that are most favorable to success, this method enables firms to focus on target countries, maximize returns, and global expansion with data, backed by accuracy.
By factoring in the projected importer demand gap that is currently unmet and could be potential opportunity, it identifies the potential for the Exporter (Country) among 190 countries, against the general trade analysis, which identifies the biggest importer or exporter.
To discover high-growth global markets and optimize your business strategy:
Click Here
Request Primary Research & Report
- Single User License$ 1,995
- Department License$ 2,400
- Site License$ 3,120
- Global License$ 3,795
Leadership Perspectives from Industry Events
Search
6Wresearch in the News
 Forbes
Citing 6Wresearch analytics to map global infrastructure and pharmaceutical industry trajectories.
 Bloomberg Law
Direct syndication of 6Wresearch's macro data points, capturing complex supply chain shifts.
 Reuters
Tracking industrial manufacturing adjustments and electronic security ecosystem scaling.
 Mint
Utilizing deep-tech sector market sizing to analyze global automation and robotics.
 The Economic Times
Anchoring features on industrial IoT growth metrics and connected smart-grid devices.
 Business Standard
Featuring strategic evaluations of Advanced Driver Assistance Systems (ADAS) and AI road safety.
 The Hindu
Spotlighting core commercial metrics ranging from unmanned aerial vehicles (UAVs) to consumer durables.
 Financial Express
Anchoring quarterly reviews on cross-border real estate tech and structural hardware manufacturing.
 Yahoo Finance
Syndicating the tracker's $30.1 billion untapped-market findings, spotlighting Japan, the US and China as India's top new-potential importers.
 India Today
Carrying the release on smartphones leading India's export potential to $94 billion by 2031, per 6WExportGTM data.
 Dailyhunt
Distributing the tracker findings to its regional readership, framing India's export diversification into Japan and Mexico.
 PR Newswire Original release
Publishing the full India Export Attractiveness Tracker 2026, detailing new trade corridors across iron ore, LCVs and pharmaceuticals.
 The Industrial
Highlighting the tracker's read on India's semiconductor ambitions and long-term chip-assembly export potential.
 PTI News
Reporting on the $66.81 billion pharmaceuticals export opportunity flagged in the tracker, amid looming US generic-drug tariffs.
 Tribune India
Covering the tracker's tariff-versus-regulation analysis across India's mature export markets in the US, China and UAE.
 ANI News
Amplifying the report's findings on polished diamonds, refined petroleum and medicines as India's core export engines.
 International Business Magazine
Covering the report's insight into how AEB, blind spot detection, and driver monitoring are reshaping India's ADAS market.
 Focus Gaming News
Highlighting the research forecast for Egypt's gambling market, projecting steady growth through 2032.
Thought Leadership and Analyst Meet
Our Clients
Latest Reports
- Global Whey Protein Market (2025-2031)
- Bahrain Vehicle-Supported Bicycle Drive Chains Market (2026-2032)
- Azerbaijan Vehicle-Supported Bicycle Drive Chains Market (2026-2032)
- Australia Vehicle-Supported Bicycle Drive Chains Market (2026-2032)
- Argentina Vehicle-Supported Bicycle Drive Chains Market (2026-2032)
- Algeria Vehicle-Supported Bicycle Drive Chains Market (2026-2032)
- Zimbabwe Vehicle-Grade Aluminum Materials Market (2026-2032)
- Zambia Vehicle-Grade Aluminum Materials Market (2026-2032)
- Yemen Vehicle-Grade Aluminum Materials Market (2026-2032)
- Vanuatu Vehicle-Grade Aluminum Materials Market (2026-2032)
Industry Events and Analyst Meet

EV India Expo 2026
HIMTEX 2026
India Refining Summit 2026
India EV Show 2026
EV tech India Expo 2026
Whitepaper
- Middle East & Africa Commercial Security Market Click here to view more.
- Middle East & Africa Fire Safety Systems & Equipment Market Click here to view more.
- GCC Drone Market Click here to view more.
- Middle East Lighting Fixture Market Click here to view more.
- GCC Physical & Perimeter Security Market Click here to view more.