Myanmar’s Mung Beans Exports to Existing Partners Could Reach USD 1.41 Billion, While Milled Rice Opens USD 351.56 Million Across New Markets by 2031.
Myanmar's established export base remains heavily concentrated in China, which alone accounts for 45.14% of total opportunity — a level of dependence that leaves relatively little room for error. The picture looks quite different on the emerging side, though, where trade corridors point toward real diversification potential, led by the United States at 18.83% and Hong Kong at 10.93%. That shift is worth paying attention to, as it suggests Myanmar has genuine room to move beyond its traditional trading relationships and build out stronger export ties across new markets in Asia and other global trading hubs.
 Source: 6WExportGTM
China’s Established Dominance Gives Way to a Genuinely Contested New-Corridor Field Led by the United States
Myanmar's export opportunities show a genuinely diversified picture, led by the United States at USD 0.47 billion, followed by Hong Kong at USD 0.27 billion and China at USD 0.18 billion. India and South Korea round out the list with USD 0.17 billion and USD 0.14 billion respectively. There is real potential for Myanmar to diversify away from its traditional trade channels through these markets, with openings across agricultural products, gemstones, minerals and other resource-based exports. Hong Kong, as a regional trading and financial hub, is a natural gateway for Myanmar’s higher value commodities, while South Korea and India offer opportunity mainly by rising demand for raw materials, agricultural inputs and processed goods.
| Top 5 Existing Leading Importers | Export Potential (USD Billion) | Top 5 New Potential Importers | Export Potential (USD Billion) |
| China | 6.38 | United States | 0.47 |
| United States | 2.10 | Hong Kong | 0.27 |
| India | 1.26 | China | 0.18 |
| Japan | 0.80 | India | 0.17 |
| Malaysia | 0.47 | South Korea | 0.14 |
Source: 6WExportGTM
Myanmar’s established export opportunities are heavily concentrated in China at USD 6.38 billion, followed by the United States at USD 2.10 billion and India at USD 1.26 billion. Japan and Malaysia represent additional major destinations with export potential of USD 0.80 billion and USD 0.47 billion, respectively. China’s leading position reflects its strong demand for Myanmar’s natural resources, agricultural commodities, minerals, and energy products, supported by geographic proximity and established trade linkages. The United States and India provide significant demand across sectors such as garments, pulses, agricultural products, and raw materials, while Japan and Malaysia contribute through diversified trade relationships across industrial and commodity categories.
Myanmar’s New Export Corridors Driven by Milled Rice, Maize and Gemstones Across Asia, Middle East and Africa
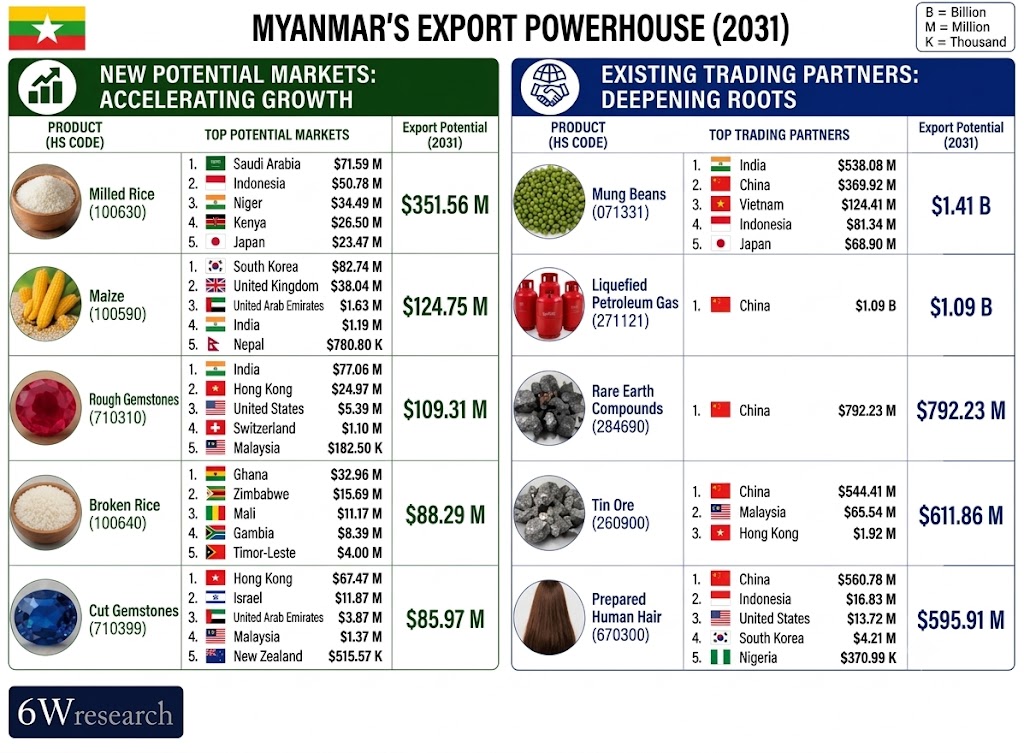
Milled rice is the leading new-corridor product at USD 351.56 million, led by Saudi Arabia (USD 71.59 million), Indonesia (USD 50.78 million) and Niger (USD 34.49 million). Saudi Arabia and other Gulf states’ large expatriate populations and heavy food-import dependence create steady demand for affordable Asian rice; Indonesia represents a major rice-consuming market periodically topping up domestic production with imports; and Niger and Kenya reflect growing Sub-Saharan African demand for affordable staple grains as domestic production struggles to keep pace with population growth.
Maize and rough gemstones together account for another USD 234.07 million of new-corridor potential. Maize’s USD 124.75 million is led by South Korea (USD 82.74 million) and the United Kingdom (USD 38.06 million), with South Korea’s large livestock and animal-feed industry the more conventional driver of demand. Rough gemstones’ USD 109.31 million is led by India (USD 77.06 million) and Hong Kong (USD 24.97 million); India’s massive gemstone-cutting and jewelry-manufacturing industry imports rough stones for processing, while Hong Kong functions as a regional gem-trading and re-export hub.
Broken rice and cut gemstones close out the new-corridor top five opportunity. Broken rice’s USD 88.29 million is led by Ghana (USD 32.96 million), Zimbabwe (USD 15.69 million) and Mali (USD 11.17 million), reflecting Myanmar’s role as an affordable rice supplier to price-sensitive West and Southern African markets. Cut gemstones’ USD 85.97 million is led by Hong Kong (USD 67.47 million) and Israel (USD 11.87 million), both major global gemstone trading and cutting centers absorbing Myanmar’s finished jade and ruby output for international jewelry markets. Taken together, the five products show Myanmar’s new-corridor opportunity mixing affordable-grain exports reaching food-insecure or import-dependent markets across the Middle East and Africa with a genuinely distinct gemstone-trading relationship into India, Hong Kong and Israel a meaningfully different composition from the mineral-and-commodity-heavy, China-anchored established base.
Myanmar’s Established Exports Led by Mung Beans to India and Resource Products Dominated by China
Mung beans, Myanmar’s largest established product at USD 1.41 billion, are led by India (USD 538.08 million), China (USD 369.92 million) and Vietnam (USD 124.41 million). India is the world’s largest consumer of mung beans, a staple pulse used for dal and sprouts, and Myanmar is one of its largest suppliers given geographic proximity and longstanding bilateral trade arrangements; China’s substantial demand reflects its own culinary, feed and industrial applications, while Vietnam represents a smaller regional culinary market.
Liquefied petroleum gas (USD 1.09 billion) and rare earth compounds (USD 792.23 million) are sold entirely to China. LPG exports flow through cross-border pipeline and trade infrastructure directly into China’s energy market, reflecting deep bilateral energy-infrastructure integration. Rare earth compounds mined chiefly in Kachin State along the Chinese border feed directly into China’s dominant rare-earth-processing and magnet-manufacturing industry, with no alternative buyer currently in the picture given China’s near-total control of global rare-earth refining capacity.
Tin ore (USD 611.86 million) and prepared human hair (USD 595.91 million) close out the top five, both overwhelmingly China-bound. Tin ore is led by China (USD 544.41 million) and Malaysia (USD 65.54 million), reflecting China’s vast electronics and solder-manufacturing industry alongside Malaysia’s own historically significant tin-smelting base. Prepared human hair is led by China (USD 560.78 million), Indonesia (USD 16.83 million) and the United States (USD 13.72 million), reflecting China’s globally dominant wig and hair-extension manufacturing industry sourcing raw human hair from Myanmar for processing into finished products for worldwide beauty markets. Read together, the established base reveals extreme buyer concentration in China across nearly every product LPG, rare earths, tin ore and hair are all overwhelmingly or entirely China-bound with mung beans the one product showing genuine buyer diversity, underscoring how structurally dependent Myanmar’s established export base is on a single neighboring market.
|
Myanmar’s export outlook highlights a clear shift from a China-centered resource trade model toward broader global market diversification. While established exports remain dominated by pulses, natural gas, rare earths, tin, and processed resources linked to China, new opportunities are emerging in rice, maize, and gemstones across the Middle East, Asia, and Africa. This indicates potential to leverage Myanmar’s agricultural and mineral strengths while expanding into higher-value, geographically diversified export channels. 6WExportGTM Analysis |
Top Global Export Opportunities (2031), By Product
| Product | Export Opportunity (USD Billion) |
| Electronic Integrated Circuits | 685.7 |
| Refined Petroleum Oils | 668.4 |
| Light Petroleum Oils | 588.9 |
| Logic Electronic Integrated Circuits | 507.9 |
| Medicines | 381.2 |
| Gasoline Passenger Cars (1.5–3.0L) | 360.9 |
| Smartphones | 343.6 |
| Electronic Integrated Circuits with Memory | 333.2 |
| Data Transmission Equipment | 216.9 |
| Immunological Products | 209.6 |
Excludes naturally occurring products (e.g., crude oil, raw gold). Source: 6WExportGTM
Global export opportunities through 2031 are expected to be driven by advanced electronics, energy products, pharmaceuticals, and automotive sectors, creating new avenues for countries to strengthen their export capabilities. For Myanmar, these trends align with its existing strengths in agriculture, natural resources, gemstones, garments, and energy products. The country has significant potential to benefit from rising demand for processed agricultural goods, minerals, and value-added resource exports. With its strategic location between major Asian markets, Myanmar can gradually expand into agro-processing, industrial manufacturing, and electronics assembly. Strengthening value-added production, improving processing capabilities, and integrating into regional supply chains will enable Myanmar to capture greater opportunities in global trade while diversifying its export base.
Global export growth through 2031 is expected to be led by advanced electronics, energy products, pharmaceuticals, and automotive-related goods, opening up new avenues for countries positioned to serve those sectors. For Myanmar, several of these trends line up reasonably well with strengths it already has — agriculture, natural resources, gemstones, garments, and energy products among them. There's real potential here to capture more value from rising demand for processed agricultural goods, minerals, and other value-added resource exports, rather than continuing to export mostly raw material. Myanmar's location, sitting between several major Asian markets, also gives it a genuine strategic advantage, one that could support a gradual move into agro-processing, industrial manufacturing, and electronics assembly over time. Realistically, this comes down to a few things — building up value-added production, improving processing capability, and working toward deeper integration into regional supply chains. Getting that right would put Myanmar in a much stronger position to capture a larger share of global trade, while also reducing how concentrated its export base currently is.
Two Developments Shaping Myanmar’s Export Base: A Contested Rare-Earth Relationship and an Expiring Pulses Agreement
Two key developments are shaping Myanmar’s export outlook. The first is the evolving control and trade dynamics around rare-earth minerals, which represent a significant export opportunity but remain closely linked to China as the primary buyer and processing destination. The second is the upcoming review of the government-to-government agreement supporting Myanmar’s mung bean exports to India, highlighting the importance of maintaining stable trade relationships for one of the country’s most important agricultural export categories.
India’s Push for Direct Access to Kachin-Controlled Rare Earths Challenges China’s Total Buyer Monopoly
Nearly all of Myanmar’s heavy rare-earth elements, including dysprosium and terbium used in electric-vehicle motors and wind turbines, are extracted from mines in Kachin State controlled not by Myanmar’s military government but by the Kachin Independence Army, which seized the mining hubs of Chipwi and Pangwa in October 2024. Nearly all of this output has historically flowed directly to China, which controls more than 90% of global rare-earth refining capacity; in 2025 China briefly closed its border to pressure the KIA into peace talks, halting exports before the two sides reached a new arrangement resuming trade at a fixed price plus a 20% tax. That near-total dependence on a single buyer is now facing its first serious external challenge: throughout 2025 and into 2026, India’s Ministry of Mines has directed state-owned IREL India and private firms including NTPC Mining and Himadri Speciality to pursue direct procurement from KIA-controlled areas, with rare-earth samples transferred to Indian laboratories for verification in July 2025 and Indian officials attending a Mandalay mining forum in July 2026 to advance the effort. No formal supply contracts have been signed as of this writing, and any large-volume commercial trade would still require transit cooperation through centrally governed regions of Myanmar. For an established rare-earth line worth USD 792.23 million, currently 100% dependent on China, even a partial diversification toward India would mark the first real crack in a buyer relationship that has so far had no alternative at all.
|
Myanmar’s rare-earth sector represents both a strategic opportunity and a supply-chain vulnerability. While China remains the dominant buyer, emerging interest from India signals potential for market diversification and greater bargaining power. Expanding beyond a single export destination could help Myanmar capture more value from its critical mineral resources and strengthen its position in global clean-energy supply chains. Manish Pant, Senior Data Scientist, Data Science & Market Intelligence, 6Wresearch |
An Expiring Five-Year Pulses Agreement Puts Myanmar’s Largest Export Relationship with India Up for Renewal
A government-to-government memorandum of understanding signed in June 2021 committed India to importing 250,000 tonnes of black gram and 100,000 tonnes of pigeon peas from Myanmar annually for five consecutive years, running from the 2021-22 to the 2025-26 financial years a period that concludes at the end of March 2026. India has separately extended duty-free import windows for these pulses on a rolling, short-term basis: the black gram (urad) exemption was extended to March 2026, while the pigeon pea (tur) exemption has been pushed out to March 2027, giving traders only partial visibility beyond the original MOU’s expiry. The relationship is economically significant on both sides: Myanmar shipped roughly 1.5 million tonnes of pulses in the first nine months of FY2024-25 alone, targeted 2 million tonnes for FY2025-26, and earned an estimated USD 1.82 billion from pulses exports in the prior fiscal year, with black gram and mung/moong beans accounting for the majority of India-bound volume; With mung beans already Myanmar’s largest established export product at USD 1.41 billion and India its top buyer at USD 538.08 million, how India structures the next phase of this relationship a renewed multi-year G2G commitment, a shorter rolling extension, or a lapse into ordinary market-based trade will materially shape the single largest line in Myanmar’s entire established export base.
|
Myanmar’s pulse export strength is closely tied to policy-driven access to the Indian market, making trade continuity a key factor for future growth. Securing a long-term export framework with India would provide greater stability for farmers and exporters, while diversification into additional markets would reduce reliance on a single buyer for a critical agricultural export segment. Manisha Gupta, Data Analyst, Data Science & Market Intelligence, 6Wresearch |
The Takeaway
Myanmar's export base stays heavily dependent on China, particularly when it comes to LPG, rare earths, tin ore, and human hair — categories where alternative buyers are still fairly limited. Mung beans are something of an exception here, offering more diversification through India and a broader set of other buyers. On the emerging side, opportunities across the US, Hong Kong, India, South Korea, and China point to real potential for Myanmar to expand beyond its traditional markets, particularly through agricultural exports, gemstones, and critical minerals.
Myanmar's main strategic priorities are:
- Track the India-Kachin rare-earth outreach closely, since the USD 792.23 million established rare-earth line is currently 100% dependent on China, and India's 2025-26 push for direct procurement from Kachin Independence Army-controlled mines represents the first real diversification prospect for a product with no other buyer today.
- Prepare for multiple pulses-agreement renewal scenarios with India, given the five-year government-to-government MOU covering black gram and pigeon pea imports expires at the end of March 2026, and mung beans already represent USD 1.41 billion in established value with India alone accounting for USD 538.08 million.
- Build on the gemstone-trading relationships in India, Hong Kong and Israel, since rough and cut gemstones together already generate USD 195.28 million in new-corridor demand across three genuinely distinct trading and cutting hubs with limited presence in Myanmar's established top five.
- Scale affordable rice exports to food-insecure African and Middle Eastern markets, given milled and broken rice together already represent USD 439.85 million in new-corridor demand across Saudi Arabia, Indonesia, Niger, Kenya, Ghana, Zimbabwe and Mali a genuinely diversified buyer base distinct from Myanmar's established China-anchored trade.
Ultimately, Myanmar's 2031 export outlook depends on how two live and uncertain relationships with its two largest trading partners China's near-total hold on rare earths and India's expiring pulses commitment resolve over the coming year, and on whether the country can convert the genuine buyer diversity already visible in its new-corridor grain and gemstone trade into a more resilient established base.
Leadership Perspectives from Industry Events
Search
6Wresearch in the News
 Forbes
Citing 6Wresearch analytics to map global infrastructure and pharmaceutical industry trajectories.
 Bloomberg Law
Direct syndication of 6Wresearch's macro data points, capturing complex supply chain shifts.
 Reuters
Tracking industrial manufacturing adjustments and electronic security ecosystem scaling.
 Mint
Utilizing deep-tech sector market sizing to analyze global automation and robotics.
 The Economic Times
Anchoring features on industrial IoT growth metrics and connected smart-grid devices.
 Business Standard
Featuring strategic evaluations of Advanced Driver Assistance Systems (ADAS) and AI road safety.
 The Hindu
Spotlighting core commercial metrics ranging from unmanned aerial vehicles (UAVs) to consumer durables.
 Financial Express
Anchoring quarterly reviews on cross-border real estate tech and structural hardware manufacturing.
 Yahoo Finance
Syndicating the tracker's $30.1 billion untapped-market findings, spotlighting Japan, the US and China as India's top new-potential importers.
 India Today
Carrying the release on smartphones leading India's export potential to $94 billion by 2031, per 6WExportGTM data.
 Dailyhunt
Distributing the tracker findings to its regional readership, framing India's export diversification into Japan and Mexico.
 PR Newswire Original release
Publishing the full India Export Attractiveness Tracker 2026, detailing new trade corridors across iron ore, LCVs and pharmaceuticals.
 The Industrial
Highlighting the tracker's read on India's semiconductor ambitions and long-term chip-assembly export potential.
 PTI News
Reporting on the $66.81 billion pharmaceuticals export opportunity flagged in the tracker, amid looming US generic-drug tariffs.
 Tribune India
Covering the tracker's tariff-versus-regulation analysis across India's mature export markets in the US, China and UAE.
 ANI News
Amplifying the report's findings on polished diamonds, refined petroleum and medicines as India's core export engines.
 International Business Magazine
Covering the report's insight into how AEB, blind spot detection, and driver monitoring are reshaping India's ADAS market.
 Focus Gaming News
Highlighting the research forecast for Egypt's gambling market, projecting steady growth through 2032.
Thought Leadership and Analyst Meet
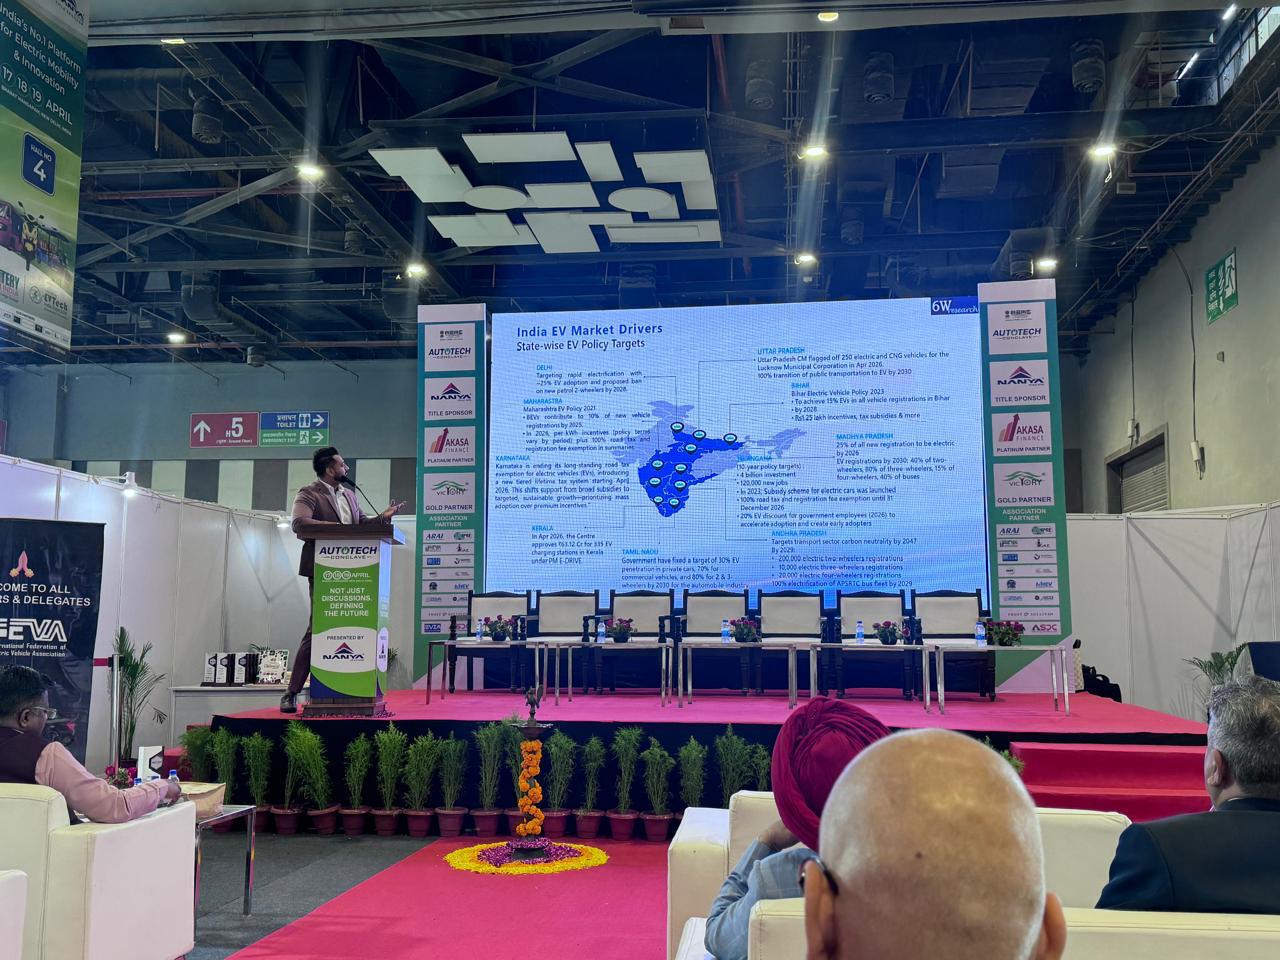
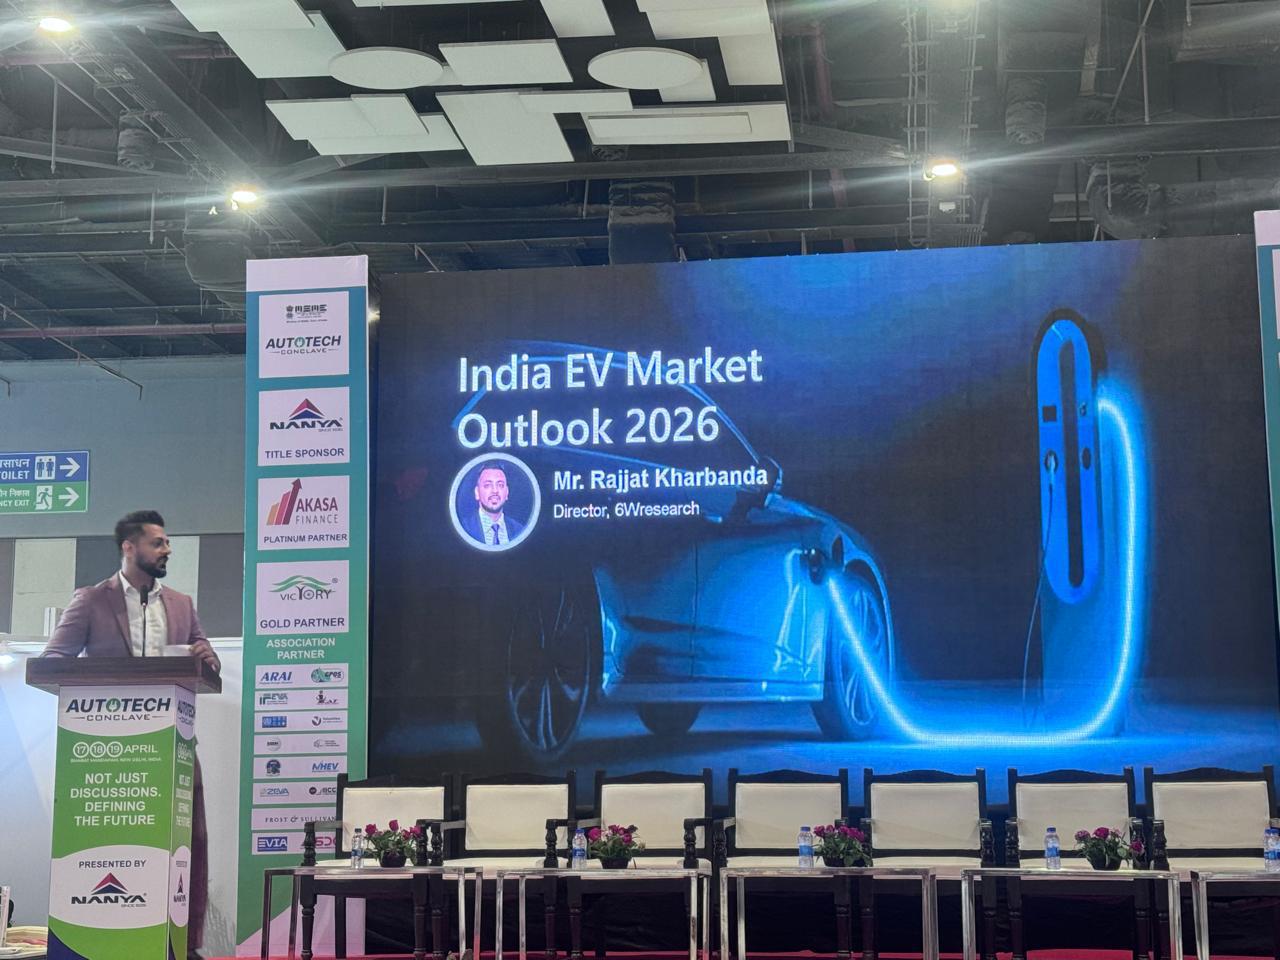
Our Clients
Latest Reports
- Austria X-ray Imaging Devices Market (2026-2032)
- Armenia X-ray Imaging Devices Market (2026-2032)
- Antigua and Barbuda X-ray Imaging Devices Market (2026-2032)
- Angola X-ray Imaging Devices Market (2026-2032)
- Andorra X-ray Imaging Devices Market (2026-2032)
- Albania X-ray Imaging Devices Market (2026-2032)
- Afghanistan X-ray Imaging Devices Market (2026-2032)
- United States (US) X-ray Imaging Devices Market (2026-2032)
- United Kingdom (UK) X-ray Imaging Devices Market (2026-2032)
- United Arab Emirates (UAE) X-ray Imaging Devices Market (2026-2032)
Industry Events and Analyst Meet

EV India Expo 2026
HIMTEX 2026
India Refining Summit 2026
India EV Show 2026
EV tech India Expo 2026
Whitepaper
- Middle East & Africa Commercial Security Market Click here to view more.
- Middle East & Africa Fire Safety Systems & Equipment Market Click here to view more.
- GCC Drone Market Click here to view more.
- Middle East Lighting Fixture Market Click here to view more.
- GCC Physical & Perimeter Security Market Click here to view more.


