Global Titanium Market Size & Growth Rate
According to 6Wresearch internal database and industry insights, the Global Titanium Market was valued at USD 30.44 Billion in 2025 and is projected to reach USD 48.56 Billion by 2032, registering a CAGR of approximately 6.9% during 2026–2032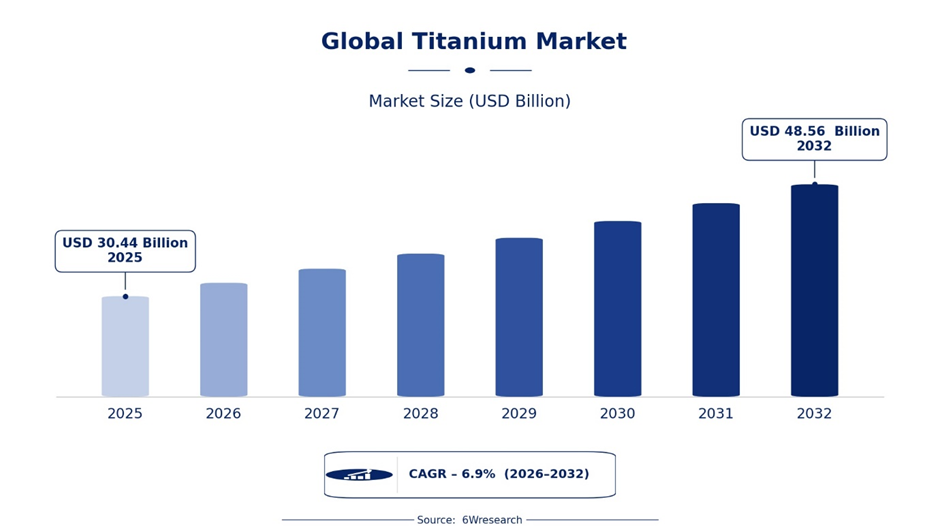
Global Titanium Market Highlights
|
Report Metric |
Details |
|
Report Name |
Global Titanium Market (2026-2032) |
|
Market Size 2025 |
USD 30.44 Billion |
|
Market Size 2032 |
USD 48.56 Billion |
|
Absolute Growth 2025–2032 |
USD 18.12 Billion |
|
CAGR 2026–2032 |
6.9% |
|
Peak Annual Growth |
7.8% in 2028 |
|
Forecast Period |
2026–2032 |
|
Historical Data |
2022–2025 |
|
Base Year |
2025 |
|
Leading Application, 2025 |
Pigments, Additives & Coatings (44% share) |
|
Fastest-Growing Application |
Medical (9.6% CAGR) |
|
Leading Product Type, 2025 |
Titanium Pigment (48% share) |
|
Fastest-Growing Product Type |
Titanium Sponge (9.1% CAGR) |
|
Leading Region, 2025 |
Asia Pacific (46% share) |
|
Fastest-Growing Region |
Middle East (8.3% CAGR) |
|
Growing Sector |
Medical implants and aerospace components |
|
Key End Users |
Aircraft and engine manufacturers, paint and coating formulators, plastics and paper producers, medical device makers, power and desalination operators, chemical processors |
Global Titanium Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.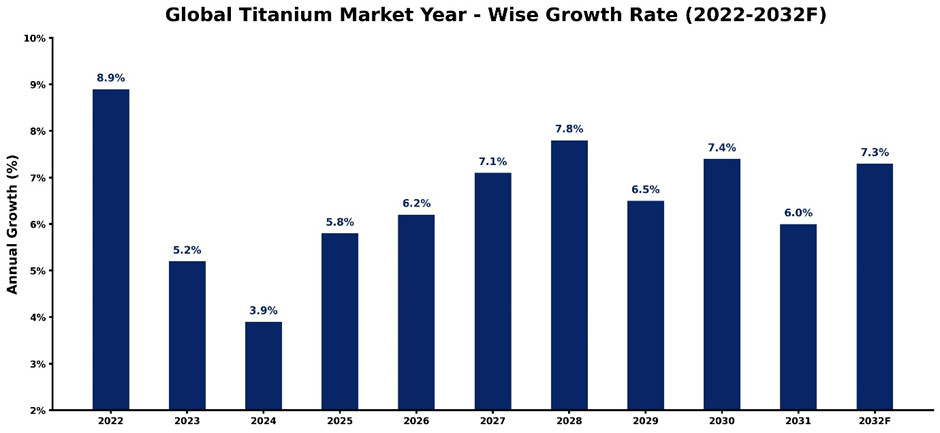 The following table presents the estimated annual growth rate for each year together with the principal factor influencing market performance. The values are intended to highlight year-specific drivers rather than to provide a direct comparison between individual years.
|
Year |
Estimated Annual Growth (%) |
Market Rationale |
|
2022 |
8.9% |
Aircraft deliveries and construction activity rebounded after pandemic closures, lifting both titanium mill products and pigment shipments. |
|
2023 |
5.2% |
Higher interest rates weakened housing and paint demand across Europe and North America, while energy costs squeezed European pigment producers. |
|
2024 |
3.9% |
Boeing production limits following the January 2024 door plug incident and weak Chinese property activity curtailed titanium purchases. |
|
2025 |
5.8% |
Pigment destocking ended and engine makers lifted forging orders, restoring purchasing across mill product and pigment channels. |
|
2026 |
6.2% |
Airline order backlogs are expected to convert into higher airframe and engine build rates, lifting forging and sheet demand. |
|
2027 |
7.1% |
Newly qualified non-Russian sponge and melting capacity is expected to ease allocation limits and support wider mill product procurement. |
|
2028 |
7.8% |
Additive manufacturing adoption in qualified aerospace and medical parts is expected to lift powder and wrought demand to its peak. |
|
2029 |
6.5% |
Completion of aerospace inventory rebuilding and higher energy and magnesium costs are expected to temper growth after the peak. |
|
2030 |
7.4% |
Hydrogen electrolyser installations and desalination plant additions are scheduled to broaden corrosion-resistant titanium equipment demand beyond aerospace. |
|
2031 |
6% |
Mature pigment consumption in construction and packaging is expected to plateau, while substitution pressure from alternative opacifiers limits upward momentum. |
|
2032 |
7.3% |
Defence modernisation programmes and replacement of ageing commercial fleets are expected to lift growth again by 2032. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch’s proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
Global Titanium Market Synopsis
The Global Titanium Market is expected to witness constant expansion on account of several reasons such as rising demand from the aerospace and marine industries, increasing applications in medical implants and industrial equipment. Demand rests on the high strength-to-weight ratio and corrosion resistance of the metal and the opacity of its oxide. Commercial aircraft build programmes, expanding hydrogen and desalination equipment, orthopaedic implant volumes and sustained pigment use in paints and plastics are lifting consumption, while diversification away from single-country sponge supply is reshaping procurement and creating openings for new processors across mineral sands regions.
Market Dynamics Impact Analysis (2026–2032)
|
Factor |
Type |
Impact |
Primary Segment Affected |
|
Commercial aircraft production ramp |
Driver |
High |
Aerospace & Marine |
|
Steady pigment consumption in paints and plastics |
Driver |
High |
Pigments, Additives & Coatings |
|
Titanium scrap recycling and remelting capacity |
Opportunity |
Medium |
Titanium Sponge |
|
Titanium components for hydrogen electrolysers |
Opportunity |
Medium |
Energy |
|
Energy and magnesium intensity of sponge production |
Restraint |
High |
Titanium Sponge |
|
Concentration of sponge capacity in few countries |
Restraint |
High |
Titanium Sponge |
|
Shortage of skilled machinists and inspectors |
Challenge |
Medium |
Industrial |
|
Long qualification of new melt sources |
Challenge |
High |
Aerospace & Marine |
Evaluation of Drivers in the Global Titanium Market (2026–2032)
Below mentioned are some major drivers and their influence on the market dynamics:
|
Drivers |
Primary Segment Affected |
Why It Matters (Evidence) |
|
Commercial aircraft production ramp |
Aerospace & Marine |
Airframe and engine makers use titanium where fatigue strength and weight matter, so each additional aircraft adds forging and sheet demand. Titanium makes up about 15% of the Boeing 787 airframe by weight. |
|
Steady pigment consumption in paints and plastics |
Pigments, Additives & Coatings |
Titanium dioxide provides opacity and brightness that cheaper substitutes cannot match, so paint, plastic and paper output translates directly into tonnage. Roughly 90% of titanium mineral concentrate is consumed as pigment. |
|
Coastal power and desalination capacity |
Energy |
Titanium is close to immune to seawater corrosion, so plants specify it for condenser and heat exchanger tubes to avoid frequent replacement. Titanium condenser tubes have operated for several decades in seawater-cooled power stations. |
|
Rising joint replacement and dental implant volumes |
Medical |
Titanium bonds directly with bone through osseointegration, which makes it the standard implant material and ties demand to procedure volumes. Per-Ingvar Brånemark described osseointegration in the 1950s. |
|
Qualification of alternative aerospace titanium sources |
Titanium Sponge |
Customers diversifying away from single-source supply must buy and test new sponge and ingot, which adds volume to new producers. Toho Titanium and OSAKA Titanium Technologies are established aerospace-grade sponge suppliers. |
Growth is supported by technology and capital factors that widen the use of the metal. With a density of about 4.5 grams per cubic centimetre, roughly 60% that of steel, titanium delivers weight savings that raise its value wherever handling or operating costs matter. Advances in vacuum melting, forging control and powder metallurgy are reducing scrap generation and lowering the effective cost of finished parts. Rising private investment in mineral sands mining, smelting and chloride-process capacity is broadening the feedstock base, and improved bulk shipping and port handling are widening access to ilmenite and rutile.
Evaluation of Restraints in the Global Titanium Market
Below mentioned are some major restraints and their influence on the market dynamics:
|
Market Restraint |
Primary Segment Affected |
Why It Matters (Evidence) |
|
Energy and magnesium intensity of sponge production |
Titanium Sponge |
The Kroll route is a multi-day batch process that consumes large volumes of electricity and magnesium, which raises unit cost and exposes margins to power prices. Magnesium chloride must be electrolysed to recover magnesium. |
|
Concentration of sponge capacity in few countries |
Titanium Sponge |
Output sits in a small group of producers, so sanctions or trade restrictions can interrupt supply to downstream melters. China produces more than half of the world’s sponge. |
|
Pigment overcapacity and price volatility |
Titanium Pigment |
Capacity additions depress selling prices and force producers elsewhere to curtail output or close older plants. China holds more than 40% of global pigment capacity. |
|
Competition from carbon-fibre composites |
Aerospace & Marine |
Composites are lighter than metals across large structures, which caps titanium content on new airframes. Composites account for about 53% of the Airbus A350 structure by weight. |
|
Mining permits and radioactive by-products |
Titanium Concentrate |
Heavy mineral sands often contain naturally occurring radioactive thorium and uranium, which requires licensed handling, rehabilitation bonds and extended permitting that delays new projects. |
Global Titanium Market Challenges
The market faces structural challenges as shortage of skilled machinists, welders and inspectors forces fabricators to decline orders, which stretches delivery times for finished parts. Cost pressure compounds this, since forged parts often start as billets with buy-to-fly ratios near 10 to 1, so most purchased metal is machined away. Qualifying a new melt source with engine makers can take more than 2 years, which slows new entrants and keeps buyers tied to incumbents. Reactivity with oxygen and nitrogen above roughly 600°C forces processing under vacuum or inert gas, which raises capital cost for new melting and heat-treatment facilities.
Trends in the Global Titanium Market
Below mentioned are some of the trends shaping the Global Titanium Market:
- Shift from Concentrated to Diversified Sponge Supply: Aerospace buyers have reduced dependence on Russian-linked titanium since 2022 and are qualifying producers in Japan, Kazakhstan and North America. Supply security now outweighs lowest price in procurement decisions. This favours sponge and ingot makers holding aerospace approvals and encourages long-term offtake agreements between mills and airframe suppliers.
- Transition from Subtractive Machining to Additive Production: Medical device makers and aerospace suppliers are printing titanium alloy implants and brackets to cut machining waste and shorten lead times. Powder-bed fusion machines now operate in qualified production lines rather than prototyping cells. The trend benefits atomised powder suppliers and service bureaus able to certify consistent powder chemistry.
- Shift from Alpha-Beta to High-Strength Beta Alloys: Aerospace programmes are specifying high-strength beta alloys such as Ti-5553 and Ti-10V-2Fe-3Al for landing gear and structural forgings in place of conventional Ti-6Al-4V. Higher strength-to-weight ratios allow thinner sections and fewer parts. The shift favours forgers and melters with beta alloy processing experience and the metallurgical control needed for segregation-sensitive chemistry.
Investment Opportunities in the Global Titanium Market
Some of the investment opportunities in the Global Titanium Market are mentioned below:
- Titanium Scrap Recycling and Remelting: Machining generates large volumes of swarf and turnings, and cold-hearth and vacuum melting can return this material to ingot at lower cost than virgin sponge. Suppliers should invest in segregation, cleaning and melting capacity near fabrication clusters in the United States, Europe and Asia. A tolling agreement with an existing melter is the lowest-risk way to enter.
- Chloride-Grade Feedstock Upgrading: Chloride-route pigment and sponge plants need titanium slag, synthetic rutile or high-grade rutile, and few mineral sands projects supply it at scale. Investors can build ilmenite upgrading furnaces or beneficiation plants in Australia and East Africa. Offtake agreements with pigment and sponge producers, combined with partnerships with mining operators, de-risk entry.
- Titanium Components for Hydrogen Electrolysers: Proton exchange membrane electrolysers use coated titanium porous transport layers and bipolar plates because the metal withstands acidic, oxidising conditions. Suppliers can invest in titanium sheet, felt and coating capacity near electrolyser assembly hubs in Europe, China and the United States. Partnerships with stack manufacturers and qualification of coatings are the main entry routes.
Leading Players in Global Titanium Market
Below is a comprehensive list of companies contributing to the growth of Global Titanium Market:
1. The Chemours Company
| Company Name | The Chemours Company |
|---|---|
| Established Year | 2015 |
| Headquarters | Wilmington, United States |
| Official Website | Click Here |
The Chemours Company is a global chemical producer and a leading supplier of chloride-route titanium dioxide pigment. It serves coatings, plastics and laminate customers across major consuming regions.
2. Tronox Holdings plc
| Company Name | Tronox Holdings plc |
|---|---|
| Established Year | 2005 |
| Headquarters | Stamford, United States |
| Official Website | Click Here |
Tronox Holdings plc is a vertically integrated producer of titanium feedstock and titanium dioxide pigment. It operates mining and processing assets that supply both its own pigment plants and external customers.
3. Toho Titanium Co., Ltd.
| Company Name | Toho Titanium Co., Ltd. |
|---|---|
| Established Year | 1953 |
| Headquarters | Yokohama, Japan |
| Official Website | Click Here |
Toho Titanium Co., Ltd. manufactures titanium sponge and related metal products for aerospace and industrial customers. It is one of the established non-Russian sponge suppliers to global melters and mill product makers.
4. Rio Tinto
| Company Name | Rio Tinto |
|---|---|
| Established Year | 1873 |
| Headquarters | London, United Kingdom |
| Official Website | Click Here |
Rio Tinto is a diversified mining group that supplies titanium dioxide slag and related feedstock through its minerals operations. It provides raw material to pigment and sponge producers worldwide.
Government Initiatives in the Global Titanium Market
The European Union’s Critical Raw Materials Act, in force since 2024, lists titanium metal among critical raw materials and sets 2030 benchmarks of 10% domestic extraction, 40% domestic processing and 25% recycling of annual consumption. It also caps dependence on any single third country at 65% for strategic raw materials, reinforcing the wider push towards diversified supply.
In implementation, the European Commission selected 47 strategic projects within the Union in March 2025 to expand extraction, processing and recycling of critical materials. In the United States, the Geological Survey’s 2022 final list of 50 critical minerals includes titanium, and Defense Production Act funding has supported domestic processing capacity for listed minerals.
Future Insights of the Global Titanium Market
Several developments are expected to support Global titanium market growth over the coming years. Hydrogen-assisted and electrolytic reduction routes under development should lower the cost of producing metal, which is significant because titanium ranks 9th in crustal abundance and critical grades are usually refined through 2 to 3 vacuum remelts. Digital melt monitoring and batch-level traceability will give buyers stronger assurance of quality and widen acceptance of new suppliers. Harmonised material specifications and wider testing infrastructure are expected to support the introduction of new alloys, while rising venture funding into advanced metals will deepen process development.
Market Segmentation Analysis
The report offers a comprehensive study of the market across its key segments. The chart below highlights the leading segment by market share in 2025 and the fastest-growing segment by CAGR over 2026–2032, followed by a detailed analysis of each segment.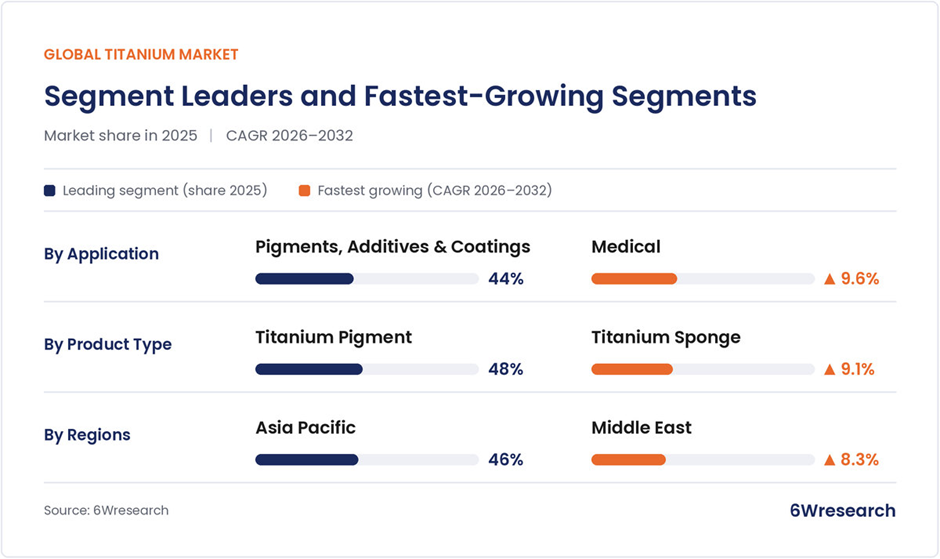
By Application – Pigments, Additives & Coatings Leads, Medical Expected to Grow Fastest
According to Ravi Bhandari, Research Head at 6Wresearch, pigments, additives and coatings led with a 44% share in 2025 as titanium dioxide remains the dominant white pigment for architectural and protective paints and inks, with demand tied to construction and manufacturing output worldwide. On the other hand, medical is expected to grow fastest at a 9.6% CAGR during the forecast period 2026–2032 as ageing populations raise joint replacement and dental implant volumes and as additively manufactured, patient-specific titanium implants gain regulatory clearance.
By Product Type – Titanium Pigment Leads, Titanium Sponge Expected to Grow Fastest
Titanium pigment accounted for the largest 2025 share at 48%, reflecting the scale of chloride and sulphate plants operated by major producers and its steady use in decorative and protective paints, plastics and inks. Apart from this, titanium sponge is forecast to record the fastest 2026–2032 CAGR of 9.1%, driven by aerospace buyers qualifying new non-Russian capacity and by rising demand for melt feedstock from engine and structural forging programmes.
By Regions – Asia Pacific Leads, Middle East Expected to Grow Fastest
Asia Pacific dominated the Global titanium market share with approximately 46% in 2025, supported by China’s dominant sponge and pigment capacity, Japan’s aerospace-grade sponge producers and large construction and manufacturing demand. On the contrary, the Middle East is projected to expand fastest at an 8.3% compound annual growth rate (CAGR) over the forecast period (2026–2032) as desalination plants, power stations and aircraft maintenance facilities in the Gulf widen their use of corrosion-resistant titanium.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- Global Titanium Market Outlook
- Global Titanium Market Overview
- Global Titanium Market Forecast
- Historical Data for the period 2022-2032 and Market Forecast of Global Titanium Market Revenues until 2032
- Historical Data for the period 2022-2032 and Market Forecast of the market until 2032, By Product Type
- Historical Data for the period 2022-2032 and Market Forecast of the market until 2032, By Application
- Historical Data for the period 2022-2032 and Market Forecast of the market until 2032, By Regions
- Historical Data for the period 2022-2032 and Market Forecast until 2032 for Latin America Global Titanium Market
- Historical Data for the period 2022-2032 and Market Forecast until 2032 for North America Global Titanium Market
- Historical Data for the period 2022-2032 and Market Forecast until 2032 for Europe Global Titanium Market
- Historical Data for the period 2022-2032 and Market Forecast until 2032 for Asia Pacific Global Titanium Market
- Historical Data for the period 2022-2032 and Market Forecast until 2032 for the Middle East Global Titanium Market
- Historical Data for the period 2022-2032 and Market Forecast until 2032 for Africa Global Titanium Market
- Market Drivers and Restraints
- Global Titanium Market Trends
- Industry Life Cycle
- Porter’s Five Force Analysis
- Market Opportunity Assessment
- Global Titanium Market Share, By Players
- Competitive Benchmarking
Market Covered
The report offers an extensive study of the following market segments.
By Application
- Aerospace & Marine
- Medical
- Industrial
- Energy
- Pigments, Additives & Coatings
- Paper & Plastics
- Others
By Product Type
- Titanium Concentrate
- Ferrotitanium
- Titanium Sponge
- Titanium Tetrachloride
- Titanium Pigment
- Others
By Regions
- Latin America
- North America
- Europe
- Asia Pacific
- Middle East
- Africa































