China Air Conditioner (AC) Market Size & Growth Rate
According to 6Wresearch internal database and industry insights, the China Air Conditioner (AC) Market was valued at USD 40.2 billion in 2025 and is projected to reach USD 57.32 billion by 2032, growing at a CAGR of approximately 5.2% during the forecast period (2026–2032).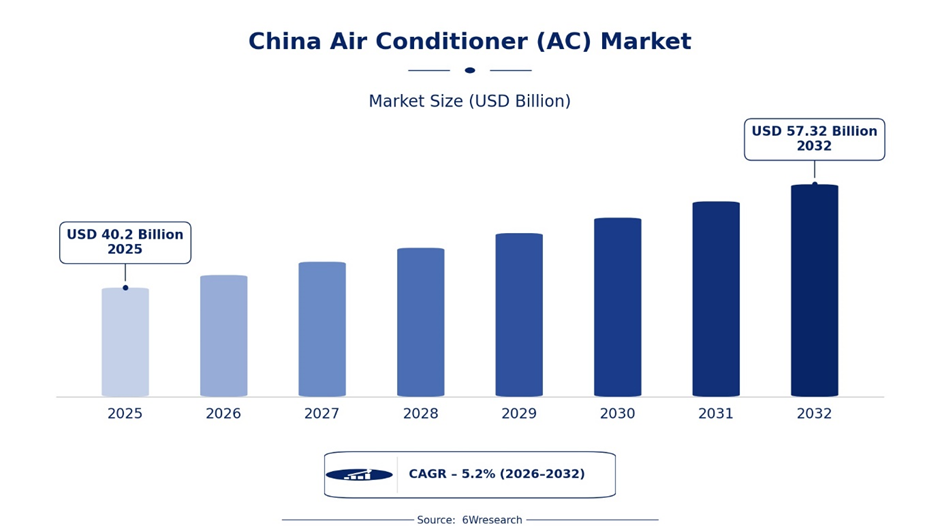
China Air Conditioner (AC) Market Highlights
|
Report Metric |
Details |
|
Report Name |
China Air Conditioner (AC) Market (2026-2032) |
|
Market Size 2025 |
USD 40.2 billion |
|
Market Size 2032 |
USD 57.32 billion |
|
Absolute Growth 2025–2032 |
USD 17.12 billion |
|
CAGR 2026–2032 |
5.2% |
|
Peak Annual Growth |
7.8% in 2023 (historical) and 6.4% in 2028 (forecast) |
|
Forecast Period |
2026–2032 |
|
Historical Data |
2022–2025 |
|
Base Year |
2025 |
|
Leading Type, 2025 |
Room Air Conditioner (41.0% share) |
|
Fastest-Growing Type |
Ductless Air Conditioner (7.1% CAGR) |
|
Leading Application, 2025 |
Residential (52.0% share) |
|
Fastest-Growing Application |
Healthcare (7.4% CAGR) |
|
Growing Sector |
Healthcare and Transportation & Infrastructure |
|
Key End Users |
Households, property developers, hospital operators, commercial real estate owners, rail and airport operators, hotel chains, data centre operators |
China Air Conditioner (AC) Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
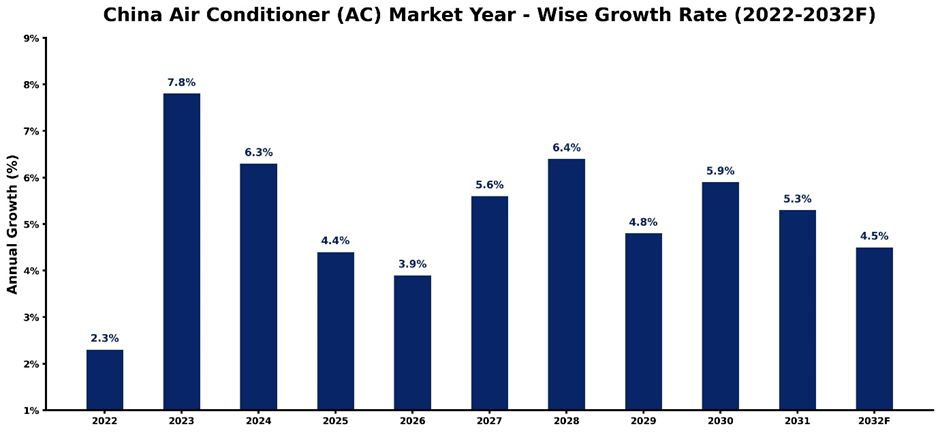 The following table presents the estimated annual growth rate for each year together with the principal factor influencing market performance.
|
Year |
Estimated Annual Growth (%) |
Market Rationale |
|
2022 |
2.3% |
Spring lockdowns in Shanghai and nearby cities disrupted production, logistics and installation, which held growth to a low level. |
|
2023 |
7.8% |
Reopening after the end of zero-COVID controls in December 2022 released pent-up demand and boosted purchases by consumers and businesses. |
|
2024 |
6.3% |
The post-reopening rebound eased against a high 2023 base, which moderated unit sales growth. |
|
2025 |
4.4% |
Subsidised appliance trade-in support raised replacement sales, although cautious household spending kept overall growth below the level of 2024. |
|
2026 |
3.9% |
Subdued new-home completions are expected to limit built-in installations in residential projects and temper sales volumes. |
|
2027 |
5.6% |
Extension of retail and installation networks into county markets is expected to raise first-time purchases among rural buyers. |
|
2028 |
6.4% |
Approved urban rail and airport projects are scheduled to reach fit-out stage, supporting centralised cooling installations. |
|
2029 |
4.8% |
The first scheduled step of the global HFC phase-down is expected to raise refrigerant conversion and compliance costs. |
|
2030 |
5.9% |
The national carbon peaking deadline is expected to increase retrofits of efficient cooling systems in public and commercial buildings. |
|
2031 |
5.3% |
Near saturation in urban markets is set to leave replacement as the main sales source and moderate expansion. |
|
2032 |
4.5% |
Intensifying price competition among manufacturers is likely to compress average selling prices and restrain value growth. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch’s proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Air Conditioner (AC) Market Synopsis
The China Air Conditioner (AC) Market is expected to develop steadily during 2026-2032, fuelled by longer cooling seasons, replacement of units bought during the 2010s, rising demand for energy-efficient inverter models and new cooling loads at computing hubs. Domestic manufacturers such as Gree, Midea and Haier add scale through compressor integration and online retail reach. The market covers room, ducted, ductless and centralised cooling systems used in homes, hospitals, commercial buildings, transport hubs and hotels.
Market Dynamics Impact Analysis (2026–2032)
|
Factor |
Type |
Impact |
Primary Segment Affected |
|
Longer and warmer cooling seasons |
Driver |
High |
Room Air Conditioner |
|
Replacement of ageing installed units |
Driver |
High |
Room Air Conditioner |
|
Cooling systems for computing hubs and infrastructure |
Opportunity |
High |
Centralized Air Conditioner |
|
Climate systems for new hospital capacity |
Opportunity |
Medium |
Healthcare |
|
Weak new-home completions |
Restraint |
High |
Residential |
|
Intense price competition among brands |
Restraint |
Medium |
Room Air Conditioner |
|
Summer peak load pressure on power grids |
Challenge |
Medium |
Centralized Air Conditioner |
|
Shortage of certified installers in smaller cities |
Challenge |
Medium |
Ductless Air Conditioner |
Evaluation of Drivers in China Air Conditioner (AC) Market (2026–2032)
Below mentioned are some major drivers and their influence on market dynamics:
|
Drivers |
Primary Segment Affected |
Why It Matters (Evidence) |
|
Longer and warmer cooling seasons |
Room Air Conditioner |
Record heat, with 2024 the warmest year in China’s meteorological records, lengthens the cooling season and raises first-time purchases and replacement of ageing units. |
|
Replacement of ageing installed units |
Room Air Conditioner |
Units bought during the rapid household adoption of the 2010s are reaching end of life, and owners upgrading to efficient models sustain annual replacement volumes. |
|
Cooling demand from computing hubs |
Centralized Air Conditioner |
The Eastern Data, Western Computing project, launched in 2022 with eight national computing hubs, creates large continuous cooling loads in data centres. |
|
Untapped rural ownership base |
Residential |
Urban households own well over 100 units per 100 households, while rural ownership remains lower, leaving a large base of first-time buyers. |
|
Ageing population and care capacity |
Healthcare |
About 310 million people were aged 60 and above by end-2024, increasing hospital and care facility construction that needs continuous climate control. |
Rising consumer incomes underpin demand, with per capita disposable income reaching about 41,300 yuan in 2024, which widens access to premium models with advanced comfort features. China’s position as the largest production base for compressors, motors and electronic controls keeps unit costs competitive and supports steady product refresh cycles.
In addition, expanding online retail platforms and bundled delivery and installation services shorten the path from product launch to purchase and widen the buyer base. Alongside, continuous private investment by manufacturers in automated lines and export capacity is supporting output, expanding supplier networks around Guangdong, Shandong and Zhejiang, and strengthening shipments to overseas markets.
Evaluation of Restraints in China Air Conditioner (AC) Market
Below mentioned are some major restraints and their influence on market dynamics:
|
Market Restraint |
Primary Segment Affected |
Why It Matters (Evidence) |
|
Weak new-home completions |
Residential |
Floor area of completed residential property fell sharply in 2024, reducing installations in new apartments that earlier generated first-time purchases of air conditioners. |
|
Intense price competition among brands |
Room Air Conditioner |
Leading brands run frequent promotional campaigns and price cuts, which compress margins and slow the shift toward higher-priced premium models. |
|
Raw material cost volatility |
Centralized Air Conditioner |
Copper and aluminium form a large share of unit cost, and price fluctuations in these metals compress margins and complicate annual pricing for manufacturers. |
|
Slowdown in commercial property investment |
Commercial & Retail |
Weak office and retail property investment delays new commercial projects, which postpones orders for centralised plants and multi-connected systems from developers and operators. |
|
Seasonal and weather dependence |
Room Air Conditioner |
Sales concentrate between May and August, and a cool or rainy summer leaves inventory with distributors and weakens full-year revenue. |
China Air Conditioner (AC) Market Challenges
In the China Air Conditioner (AC) Market, summer peak electricity demand is one of the primary challenges, as cooling equipment is widely estimated to account for 30% to 40% of peak load in large cities, which can prompt demand management measures and delay larger projects. Quality installation depends on trained technicians, and a lack of certified installers in smaller cities raises callback rates and warranty costs for suppliers.
In addition, export-oriented producers face tariff measures introduced in 2025 by major trading partners, which redirect shipments and reduce margins on overseas orders. Retrofitting centralised systems into buildings completed before 2000 requires costly structural work and control integration, which delays decisions by owners and prolongs project payback.
China Air Conditioner (AC) Market Trends
Key trends shaping the China Air Conditioner (AC) Market are outlined below:
- Smart Control Emerging as a Standard Feature: Gree, Midea and Haier now ship app-connected models with occupancy sensing as mainstream offerings. This makes software capability a requirement for suppliers and raises value per unit.
- Shifting from HFCs to R290 Refrigerants: The industry is developing the range of R290 room air conditioners before the HFC phase-down stage in 2029. Suitable compressors and approved parts can enjoy benefits; the network should be trained.
- Moving from Isolated Equipment to a Comprehensive Building System: The operators of commercial buildings, hospitals, and metro routes extending more than 10,000 kilometers have set the requirement of variable refrigerant flow and centralized systems.
- Transition from Hardware Sales to Services-Based Income: Major brands offer extended warranty, scheduled cleaning, and remote monitoring with the new equipment. The buyer can have stable operating costs, and the supplier gets recurring income.
Investment Opportunities in the China Air Conditioner (AC) Market
Attractive investment opportunities within the China Air Conditioner (AC) Market include the following:
- Variable-Speed Compressor and Control Board Supply: Domestic brands are expanding inverter output, creating room for component suppliers. Foreign investors can enter through joint ventures with OEMs in Guangdong or Zhejiang clusters, or through licensed technology transfer.
- Production Capacity of Propane Refrigerant: As more manufacturers increase their product lines of propane refrigerants, there is still not enough production capacity available for leak sensors and certified charging devices. The investment avenue could be focused on contract manufacturing for brands based on local safety certification.
- Data Center and Infrastructure Cooling: Cooling systems, chilled water plants, and liquid-cooled interfaces are required for computer hubs in Inner Mongolia, Gansu and Guizhou. Cooperation with computer hub providers or local engineering companies would provide access.
- Hospitals Climate Systems: Construction of hospitals requires ducted climate systems equipped with filtration and humidity regulation. Contract with hospital provider and construction companies provides entry into market based on medical certification.
Leading Players in the China Air Conditioner (AC) Market
The following is a comprehensive list of key companies operating in the China Air Conditioner (AC) Market:
1. Gree Electric Appliances
| Company Name | Gree Electric Appliances |
|---|---|
| Established Year | 1991 |
| Headquarters | Zhuhai, China |
| Official Website | Click Here |
Gree Electric Appliances manufactures residential and commercial air conditioners and is among the largest domestic suppliers, with a strong presence in room and central systems across China.
2. Midea Group
| Company Name | Midea Group |
|---|---|
| Established Year | 1968 |
| Headquarters | Foshan, China |
| Official Website | Click Here |
Midea Group produces room, multi-split and commercial air conditioning systems alongside compressors and building technologies, serving domestic buyers through extensive retail and project channels.
3. Haier Smart Home
| Company Name | Haier Smart Home |
|---|---|
| Established Year | 1984 |
| Headquarters | Qingdao, China |
| Official Website | Click Here |
Haier Smart Home supplies room air conditioners and commercial systems under several brands, with a focus on connected products and wide distribution across Chinese cities.
4. Daikin Industries
| Company Name | Daikin Industries |
|---|---|
| Established Year | 1924 |
| Headquarters | Osaka, Japan |
| Official Website | Click Here |
Daikin Industries is a global air conditioning manufacturer with substantial manufacturing and service operations in China, supplying residential, commercial and building-scale systems.
Government Initiatives in the China Air Conditioner (AC) Industry
The government has a major role in the expansion of the market through efficiency regulation, climate targets and consumption policy. China’s dual carbon goals target a carbon peak before 2030 and neutrality by 2060, placing cooling efficiency at the centre of appliance and building policy. The national standard GB 21455-2019, in force since July 2020, raised minimum efficiency thresholds for room air conditioners, and the 2024 Action Plan for Large-Scale Equipment Renewal and Consumer Goods Trade-in extended support to appliance replacement. In 2025 the programme drew on 300 billion yuan of ultra-long special treasury bonds, with appliance subsidies of up to 20% of the sale price, capped at 2,000 yuan per item.
Future Insights of the China Air Conditioner (AC) Market
Several developments will shape China Air Conditioner (AC) Market Growth and long-term demand. Wider adoption of heat pump technology will extend the use of cooling equipment into year-round heating, which raises annual utilisation and lowers operating costs for owners. In addition, the national goal of supporting the non-fossil share of energy consumption to about 25% by 2030 will support cleaner grids and electrified cooling. Expanding green building codes will require efficient climate systems in new construction and refurbishment, creating steady specification demand for qualified suppliers.
Market Segmentation Analysis
The report offers a comprehensive study of the market across its key segments. The chart below highlights the leading segment by market share in 2025 and the fastest-growing segment by CAGR over 2026–2032, followed by a detailed analysis of each segment.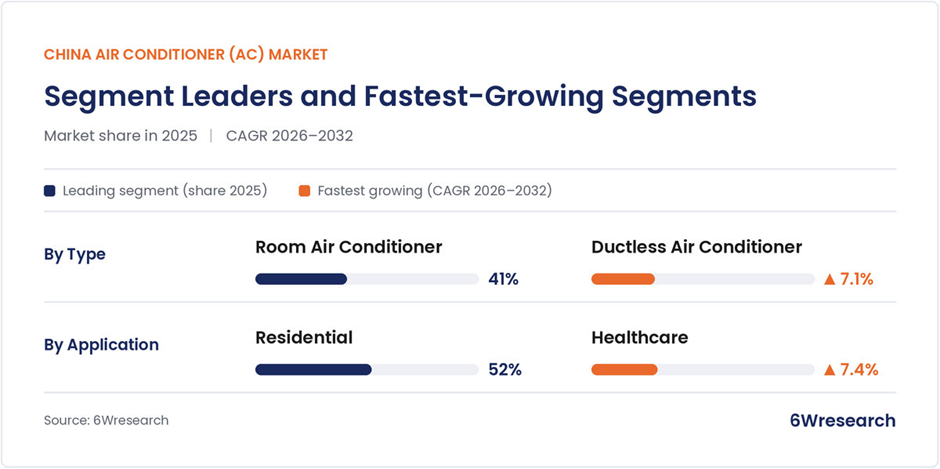
By Type – Room Air Conditioner Leads, Ductless Air Conditioner Expected to Grow Fastest
According to Ravi Bhandari, Research Head at 6Wresearch, the Room Air Conditioners accounted for the largest share of 41% in 2025, supported by high ownership across urban China, recurring replacement purchases and the retail strength of domestic brands.
Meanwhile, the Ductless Air Conditioners are expected to record the fastest growth at a CAGR of 7.1% during 2026–2032, driven by rising use of multi-split systems in apartments, demand for quiet inverter operation and flexible installation without structural work.
By Application – Residential Leads, Healthcare Expected to Grow Fastest
The Residential segment accounted for 52% of China Air Conditioner (AC) Market Share in 2025, owing to large urban household ownership, regular replacement of older units and consumer demand for energy-efficient models.
In parallel, Healthcare is projected to expand at a CAGR of 7.4% over 2026–2032, fuelled by hospital capacity additions, upgraded ward and operating-theatre ventilation, and higher filtered-air expectations in care facilities.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Air Conditioner Market Outlook
- Market Size of China Air Conditioner Market, 2025
- Forecast of China Air Conditioner Market, 2032
- Historical Data and Forecast of China Air Conditioner Revenues & Volume for the Period 2022-2032
- China Air Conditioner Market Trend Evolution
- China Air Conditioner Market Drivers and Challenges
- China Air Conditioner Price Trends
- China Air Conditioner Porter's Five Forces
- China Air Conditioner Industry Life Cycle
- Historical Data and Forecast of China Air Conditioner Market Revenues & Volume By Type for the Period 2022-2032
- Historical Data and Forecast of China Air Conditioner Market Revenues & Volume By Room Air Conditioner for the Period 2022-2032
- Historical Data and Forecast of China Air Conditioner Market Revenues & Volume By Ducted Air Conditioner for the Period 2022-2032
- Historical Data and Forecast of China Air Conditioner Market Revenues & Volume By Ductless Air Conditioner for the Period 2022-2032
- Historical Data and Forecast of China Air Conditioner Market Revenues & Volume By Centralized Air Conditioner for the Period 2022-2032
- Historical Data and Forecast of China Air Conditioner Market Revenues & Volume By Application for the Period 2022-2032
- Historical Data and Forecast of China Air Conditioner Market Revenues & Volume By Residential for the Period 2022-2032
- Historical Data and Forecast of China Air Conditioner Market Revenues & Volume By Healthcare for the Period 2022-2032
- Historical Data and Forecast of China Air Conditioner Market Revenues & Volume By Commercial & Retail for the Period 2022-2032
- Historical Data and Forecast of China Air Conditioner Market Revenues & Volume By Transportation & Infrastructure for the Period 2022-2032
- Historical Data and Forecast of China Air Conditioner Market Revenues & Volume By Hospitality for the Period 2022-2032
- Historical Data and Forecast of China Air Conditioner Market Revenues & Volume By Others for the Period 2022-2032
- China Air Conditioner Import Export Trade Statistics
- Market Opportunity Assessment By Type
- Market Opportunity Assessment By Application
- China Air Conditioner Top Companies Market Share
- China Air Conditioner Competitive Benchmarking By Technical and Operational Parameters
- China Air Conditioner Company Profiles
- China Air Conditioner Key Strategic Recommendations
Market Covered
The report offers a comprehensive study of the subsequent market segments:
By Types
- Room Air Conditioner
- Ducted Air Conditioner
- Ductless Air Conditioner
- Centralized Air Conditioner
By Application
- Residential
- Commercial & Retail
- Healthcare
- Hospitality
- Transportation & Infrastructure
- Others

































