China Industrial Fluorine Compounds Market Size & Growth Rate
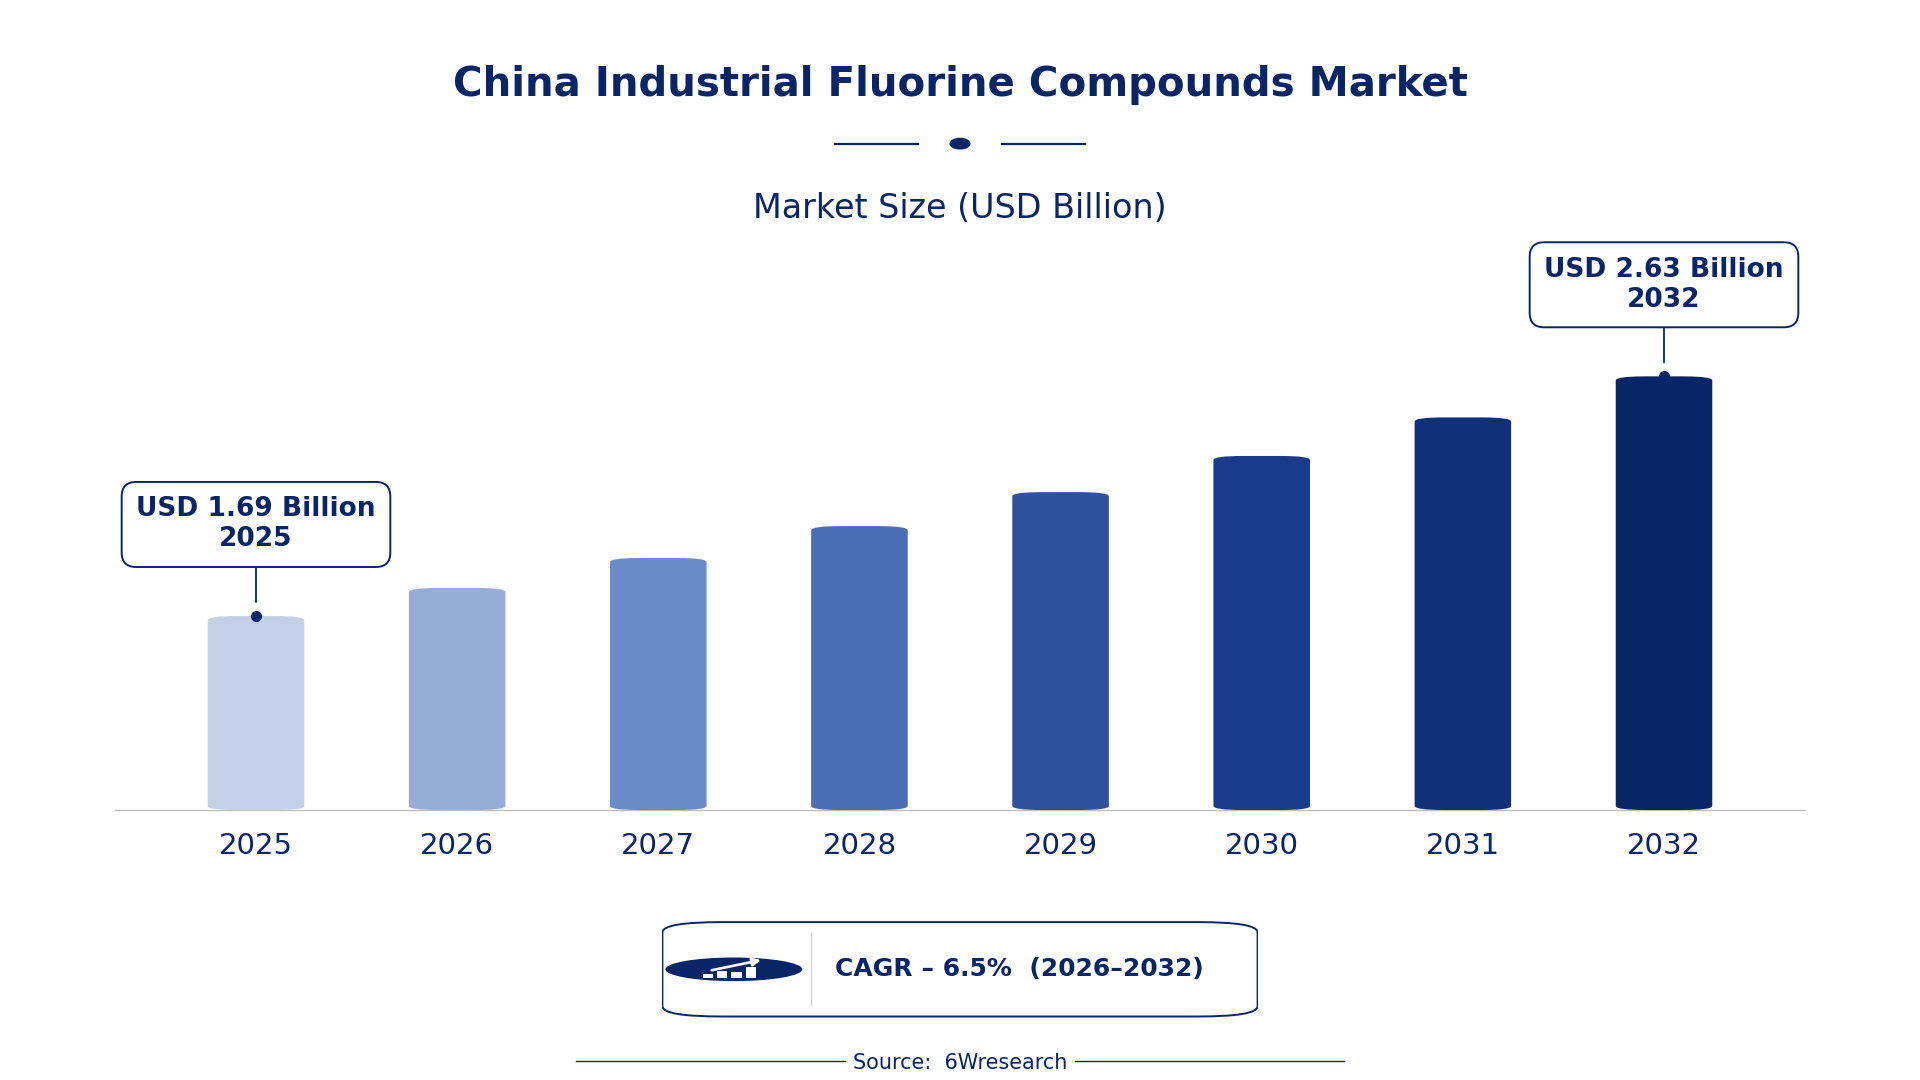
According to 6Wresearch internal database and industry insights, the China Industrial Fluorine Compounds Market was valued at USD 1.69 billion in 2025 and is projected to reach USD 2.63 billion by 2032, growing at a CAGR of approximately 6.5% during 2026–2032.
China Industrial Fluorine Compounds Market Highlights
| Report Metric | Details |
| Report Name | China Industrial Fluorine Compounds Market |
| Market Size 2025 | USD 1.69 billion |
| Market Size 2032 | USD 2.63 billion |
| Absolute Growth 2025–2032 | USD 0.94 billion |
| CAGR 2026–2032 | 6.5% |
| Peak Annual Growth | 8.1% in 2032 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Compound Type, 2025 | Fluorinated Polymers (40% share) |
| Leading State, 2025 | Gas (42% share) |
| Leading Functionality, 2025 | Etching (44% share) |
| Leading End User, 2025 | Semiconductor Industry (50% share) |
| Fastest-Growing Compound Type | Fluorosurfactants (9.1% CAGR) |
| Fastest-Growing State | Solid (PTFE, FEP) (8.1% CAGR) |
| Fastest-Growing Functionality | Chemical Resistance (9.2% CAGR) |
| Fastest-Growing End User | Coatings & Sealing Industry (8.3% CAGR) |
| Growing Sector | Coatings & Sealing Industry |
| Key End Users | Semiconductor Industry, Electronics Sector, Coatings & Sealing Industry, Cleaning/Chemical Firms |
China Industrial Fluorine Compounds Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
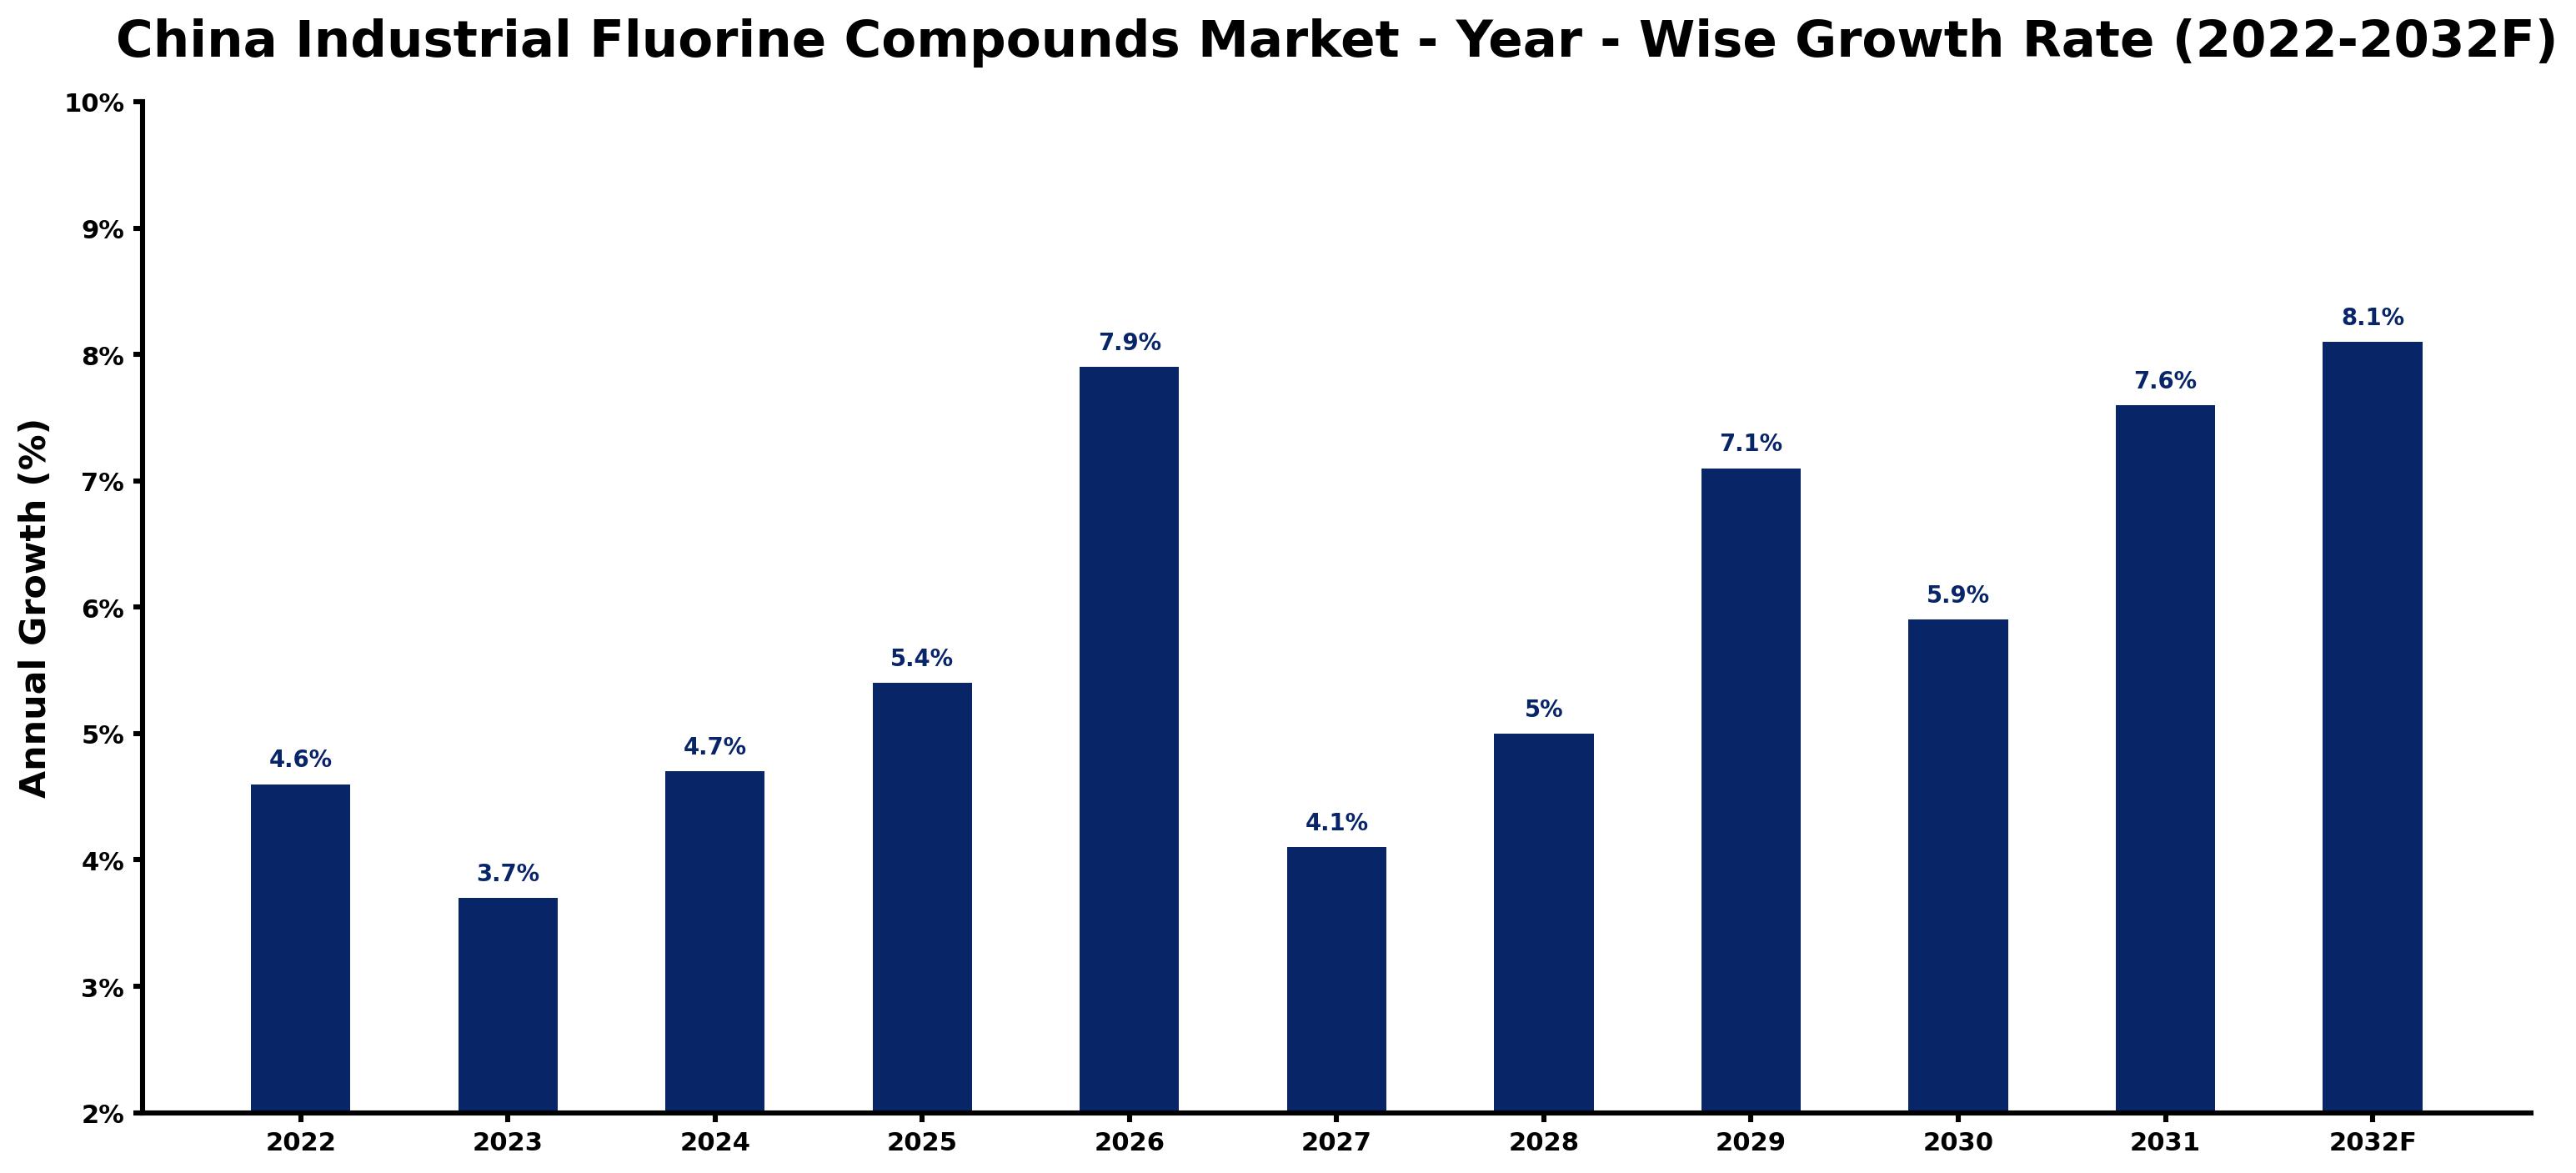
Each row of the following table gives one year's estimated growth and the event or demand shift that explains it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 4.6 | The market experienced steady growth due to strong domestic demand from the semiconductor sector. |
| 2023 | 3.7 | Growth slowed as manufacturers adjusted to supply chain challenges affecting production rates. |
| 2024 | 4.7 | Increased investment in semiconductor facilities boosted demand for fluorine compounds. |
| 2025 | 5.4 | The semiconductor industry's expansion led to heightened demand for etching materials. |
| 2026 | 7.9 | Rising production in the semiconductor sector is expected to drive demand for fluorine gas. |
| 2027 | 4.1 | Manufacturers will face challenges in sourcing raw materials, slowing growth. |
| 2028 | 5.0 | The coatings industry is projected to see increased demand for fluorinated polymers, enhancing market growth. |
| 2029 | 7.1 | Rising exports of electronics will contribute to increased fluorine compound requirements. |
| 2030 | 5.9 | Growth is expected to slow as the market adjusts to evolving regulatory standards. |
| 2031 | 7.6 | The semiconductor sector's continued expansion will lead to increased demand for etching processes. |
| 2032 | 8.1 | Demand is projected to surge as new technologies in semiconductor fabrication require advanced fluorine compounds. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Industrial Fluorine Compounds Market Synopsis
The China Industrial Fluorine Compounds Market includes chemical substances containing fluorine, produced through processes like fluorination. These compounds play a key role in semiconductor manufacturing, coatings, and cleaning agents. Growth in the market stems from rising domestic demand in the semiconductor industry, valued at over 200 billion USD, alongside substantial investments in semiconductor manufacturing, which reached 30 billion USD in 2023. The coatings industry also fuels this expansion, with fluorinated polymers being integral to a variety of applications.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increased domestic demand from the semiconductor sector | Driver | High | Perfluorocarbons (PFCs) |
| Rising production of fluorinated polymers for coatings | Driver | High | Fluorinated Polymers |
| Growing demand for fluorinated polymers in the coatings industry | Opportunity | High | Fluorinated Polymers |
| Expansion in the electronics sector requiring fluorine compounds | Opportunity | High | Electronics Sector |
| Regulatory compliance costs impacting production | Restraint | Medium | Fluorinated Polymers |
| Supply chain disruptions affecting raw material availability | Restraint | High | Perfluorocarbons (PFCs) |
| Technological advancements requiring constant adaptation | Challenge | Medium | Semiconductor Industry |
| Environmental regulations increasing production costs | Challenge | High | Fluorinated Polymers |
Evaluation of Drivers in China Industrial Fluorine Compounds Market (2026–2032)
Below mentioned are some major drivers and their influence on market dynamics.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Surge in semiconductor production | Perfluorocarbons (PFCs) | The semiconductor industry in China, valued at over 200 billion USD, drives demand for PFCs used in etching processes. |
| Increased production of fluorinated polymers | Fluorinated Polymers | Fluorinated polymers are used in over 70% of industrial coatings, with demand rising due to the coatings industry's projected growth of 5% annually. |
| Rising demand for fluorine gas | Fluorine Gas | The demand for fluorine gas is increasing, linked to the semiconductor sector's expansion and its need for various fluorinated compounds. |
| Expansion in the coatings industry | Fluorinated Polymers | The coatings industry is projected to grow by 5% annually, increasing the need for fluorinated polymers in various applications. |
| Technological advancements in electronics | Electronics Sector | The electronics sector employs over 3 million workers and drives increased demand for fluorine compounds across various applications. |
The Industrial Fluorine Compounds market in China is growing on the back of increased domestic demand from the semiconductor and coatings industries. The semiconductor sector, valued at over 200 billion USD, drives demand for perfluorocarbons used in etching processes. Investment in semiconductor manufacturing reached 30 billion USD in 2023, boosting production capabilities. The coatings industry is projected to grow by 5% annually, increasing the need for fluorinated polymers. Furthermore, the electronics sector, employing over 3 million workers, continues to drive demand for fluorine compounds across various applications.
Evaluation of Restraints in China Industrial Fluorine Compounds Market
The main factors holding the market back are set out below.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Intense competition among producers | Perfluorocarbons (PFCs) | This competition drives down prices, reducing profit margins for manufacturers and limiting their capacity to invest in new technologies. |
| Regulatory compliance costs | Fluorinated Polymers | The national standard GB/T 12345-2019 imposes strict compliance requirements that raise operational costs for suppliers by up to 15%. |
| Rising raw material costs | Fluorine Gas | Increasing costs of raw materials burden producers, forcing them to increase prices for end-users across various sectors. |
| Supply chain disruptions | Fluorosurfactants | Disruptions in supply chains can delay production schedules and affect the availability of fluorine compounds in the market. |
| Limited awareness of environmental impacts | Fluorinated Polymers | Some buyers may not fully understand the environmental implications of fluorinated compounds, affecting their purchasing decisions. |
China Industrial Fluorine Compounds Market Challenges
The China Industrial Fluorine Compounds Market encounters several practical challenges, primarily stemming from fierce competition among producers. This rivalry leads to price reductions, squeezing profit margins for manufacturers and restricting their ability to invest in new technologies. Buyers in the semiconductor industry face pressure to cut costs, which can affect the quality of the materials they procure. Compliance with national standard GB/T 12345-2019 imposes stringent requirements that can raise operational costs for suppliers by up to 15%, while increasing raw material costs further strain producers, compelling them to raise prices for end-users across various sectors.
Trends in the China Industrial Fluorine Compounds Market
Several trends are reshaping the China Industrial Fluorine Compounds Market; the most important are set out below.
- Shift towards Eco-Friendly Production: The 'Green Fluorine Initiative' launched in 2023 aims to promote environmentally friendly production methods for fluorinated materials, reflecting a growing trend towards sustainability in the industry.
- Transition to Advanced Etching Techniques: The semiconductor industry is increasingly adopting advanced etching techniques, with fluorinated compounds being critical for precision and efficiency in manufacturing processes.
- Emergence of Fluorinated Polymers in Coatings: Fluorinated polymers are becoming more prevalent in coatings applications, with over 70% of industrial coatings utilizing these materials, driven by their chemical resistance.
- Growth in Semiconductor Exports: China's electronics exports reached 600 billion USD in 2022, driving demand for fluorine compounds used in semiconductor manufacturing and related applications.
Investment Opportunities in the China Industrial Fluorine Compounds Market
Below are the investment opportunities with the strongest case in the China Industrial Fluorine Compounds Market.
- Investment in Semiconductor Facilities: Investment in semiconductor facilities is projected to exceed 40 billion USD, creating opportunities for suppliers of fluorine compounds in this sector.
- Expansion in Coatings Industry: The coatings industry is expected to grow by 5% annually, providing opportunities for suppliers of fluorinated polymers to meet increasing demand.
- Development of New Fluorinated Compounds: There is a growing need for innovative fluorinated compounds, supported by the 'Fluorine Innovation Fund' to enhance research and development efforts.
- Partnerships with Electronics Manufacturers: Collaborating with electronics manufacturers can open new avenues for suppliers, as the sector continues to expand and require fluorine compounds.
Government Initiatives in the China Industrial Fluorine Compounds Market
In 2021, the Ministry of Industry and Information Technology launched the 'Fluorine Compound Development Plan' to enhance production efficiency and reduce emissions, building on previous regulations. This initiative aims to improve the overall sustainability of fluorine compound production, ensuring compliance with environmental standards and boosting competitiveness in the market.
The Ministry of Ecology and Environment oversees the 'Green Fluorine Initiative', which promotes environmentally friendly production methods for fluorinated materials. This initiative supports manufacturers in adopting sustainable practices and provides funding for research into greener alternatives, ensuring compliance with evolving regulations.
Future Insight of the China Industrial Fluorine Compounds Market
The China Industrial Fluorine Compounds Market is set to evolve by 2032, primarily driven by advancements in semiconductor manufacturing. Investment in this sector is expected to exceed 40 billion USD, boosting production capabilities and efficiency. The coatings industry will likely expand at an annual rate of 5%, significantly increasing demand for fluorinated compounds. Innovation supported by the National Development and Reform Commission will create new applications for these compounds, providing opportunities for both buyers and suppliers in the changing market.
Market Segmentation Analysis
Each segment group is reviewed below, with the leader by share and the fastest grower by CAGR.
By Compound Type – Fluorinated Polymers Dominated, Fluorosurfactants Expected to Grow Fastest
According to Sachin Kumar Rai, Senior Research Analyst at 6Wresearch, in 2025, Fluorinated Polymers led the compound type split with a 40% share. Fluorinated polymers dominate the market due to their essential role in coatings and sealing applications, which require high chemical resistance. For instance, these polymers are integral to over 70% of industrial coatings, showcasing their widespread adoption across multiple sectors. Fluorosurfactants are set to record the highest CAGR in this split, 9.1% over 2026–2032. The rapid growth of fluorosurfactants is attributed to their extensive use in cleaning agents, where they are found in over 50% of products. This surge is primarily driven by the increasing demand for effective cleaning solutions across various industries. Suppliers should focus on enhancing their fluorosurfactant offerings to capitalise on this growing market segment.
By State – Gas Dominated, Solid (PTFE, FEP) Expected to Grow Fastest
The largest state category in 2025 was Gas, with a 42% share of total revenue. Gas holds the largest market share as it is crucial for semiconductor processes and refrigeration applications, both of which are essential for the electronics sector. The significant production of fluorine gas supports its extensive utilisation in these high-demand areas. Solid (PTFE, FEP) is projected to grow fastest, at a CAGR of 8.1% during 2026–2032. Solid fluorinated compounds, such as PTFE and FEP, are gaining popularity due to their non-stick properties, making them increasingly desirable in coatings. This trend reflects the ongoing demand for durable materials in various industrial applications. Buyers should invest in solid fluorinated compounds to meet the growing need for advanced coating solutions.
By Functionality – Etching Dominated, Chemical Resistance Expected to Grow Fastest
Etching held a 44% share of the China Industrial Fluorine Compounds Market by functionality in 2025. Etching leads the functionality segment, being vital in semiconductor fabrication processes where precision is paramount. Its critical role in producing high-quality semiconductor components ensures it maintains a dominant market share. Over 2026–2032, Chemical Resistance is expected to post the fastest growth, at a CAGR of 9.2%. The chemical resistance functionality is witnessing rapid growth as industries seek coatings that can endure harsh environments. This demand is particularly strong in sectors prioritising the durability and longevity of materials. Suppliers should concentrate on developing chemical-resistant materials to fulfil industry needs for robust coatings.
By End User – Semiconductor Industry Dominated, Coatings & Sealing Industry Expected to Grow Fastest
Semiconductor Industry accounted for a 50% market share by end user in 2025. The semiconductor industry is the largest consumer of fluorine compounds, with its market value exceeding 200 billion USD. This sector's continuous growth and reliance on fluorinated materials solidify its leading position in the market. The quickest growth will come from Coatings & Sealing Industry, forecast to expand at a CAGR of 8.3% between 2026 and 2032. The coatings and sealing industry is expanding quickly as it increasingly incorporates fluorinated polymers for improved performance. This trend indicates a broader shift towards high-quality, durable coatings across various applications. Buyers in the coatings sector should consider fluorinated polymers to enhance their product offerings and meet market demands.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Industrial Fluorine Compounds Market Outlook
- Market Size of China Industrial Fluorine Compounds Market, 2025
- Forecast of China Industrial Fluorine Compounds Market, 2032
- Historical Data and Forecast of China Industrial Fluorine Compounds Revenues & Volume for the Period 2022 - 2032F
- China Industrial Fluorine Compounds Market Trend Evolution
- China Industrial Fluorine Compounds Market Drivers and Challenges
- China Industrial Fluorine Compounds Price Trends
- China Industrial Fluorine Compounds Porter's Five Forces
- China Industrial Fluorine Compounds Industry Life Cycle
- Historical Data and Forecast of China Industrial Fluorine Compounds Market Revenues & Volume By Compound Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Fluorine Compounds Market Revenues & Volume By Perfluorocarbons (PFCs) for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Fluorine Compounds Market Revenues & Volume By Fluorinated Polymers for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Fluorine Compounds Market Revenues & Volume By Fluorosurfactants for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Fluorine Compounds Market Revenues & Volume By Fluorine Gas for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Fluorine Compounds Market Revenues & Volume By State for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Fluorine Compounds Market Revenues & Volume By Gas for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Fluorine Compounds Market Revenues & Volume By Solid (PTFE, FEP) for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Fluorine Compounds Market Revenues & Volume By Liquid for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Fluorine Compounds Market Revenues & Volume By Elemental Gas for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Fluorine Compounds Market Revenues & Volume By Functionality for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Fluorine Compounds Market Revenues & Volume By Heat Transfer, Etching for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Fluorine Compounds Market Revenues & Volume By Chemical Resistance for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Fluorine Compounds Market Revenues & Volume By Surface Tension Control for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Fluorine Compounds Market Revenues & Volume By Plasma Etching for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Fluorine Compounds Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Fluorine Compounds Market Revenues & Volume By Semiconductor Industry for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Fluorine Compounds Market Revenues & Volume By Coatings & Sealing Industry for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Fluorine Compounds Market Revenues & Volume By Cleaning/Chemical Firms for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Fluorine Compounds Market Revenues & Volume By Electronics Sector for the Period 2022 - 2032F
- China Industrial Fluorine Compounds Import Export Trade Statistics
- Market Opportunity Assessment By Compound Type
- Market Opportunity Assessment By State
- Market Opportunity Assessment By Functionality
- Market Opportunity Assessment By End User
- China Industrial Fluorine Compounds Top Companies Market Share
- China Industrial Fluorine Compounds Competitive Benchmarking By Technical and Operational Parameters
- China Industrial Fluorine Compounds Company Profiles
- China Industrial Fluorine Compounds Key Strategic Recommendations
Market Covered
Segments analysed in this report are listed below.
By Compound Type
- Perfluorocarbons (PFCs)
- Fluorinated Polymers
- Fluorosurfactants
- Fluorine Gas
By State
- Gas
- Solid (PTFE, FEP)
- Liquid
- Elemental Gas
By Functionality
- Heat Transfer
- Etching
- Chemical Resistance
- Surface Tension Control
- Plasma Etching
By End User
- Semiconductor Industry
- Coatings & Sealing Industry
- Cleaning/Chemical Firms
- Electronics Sector































