China Industrial Foil Market Size & Growth Rate
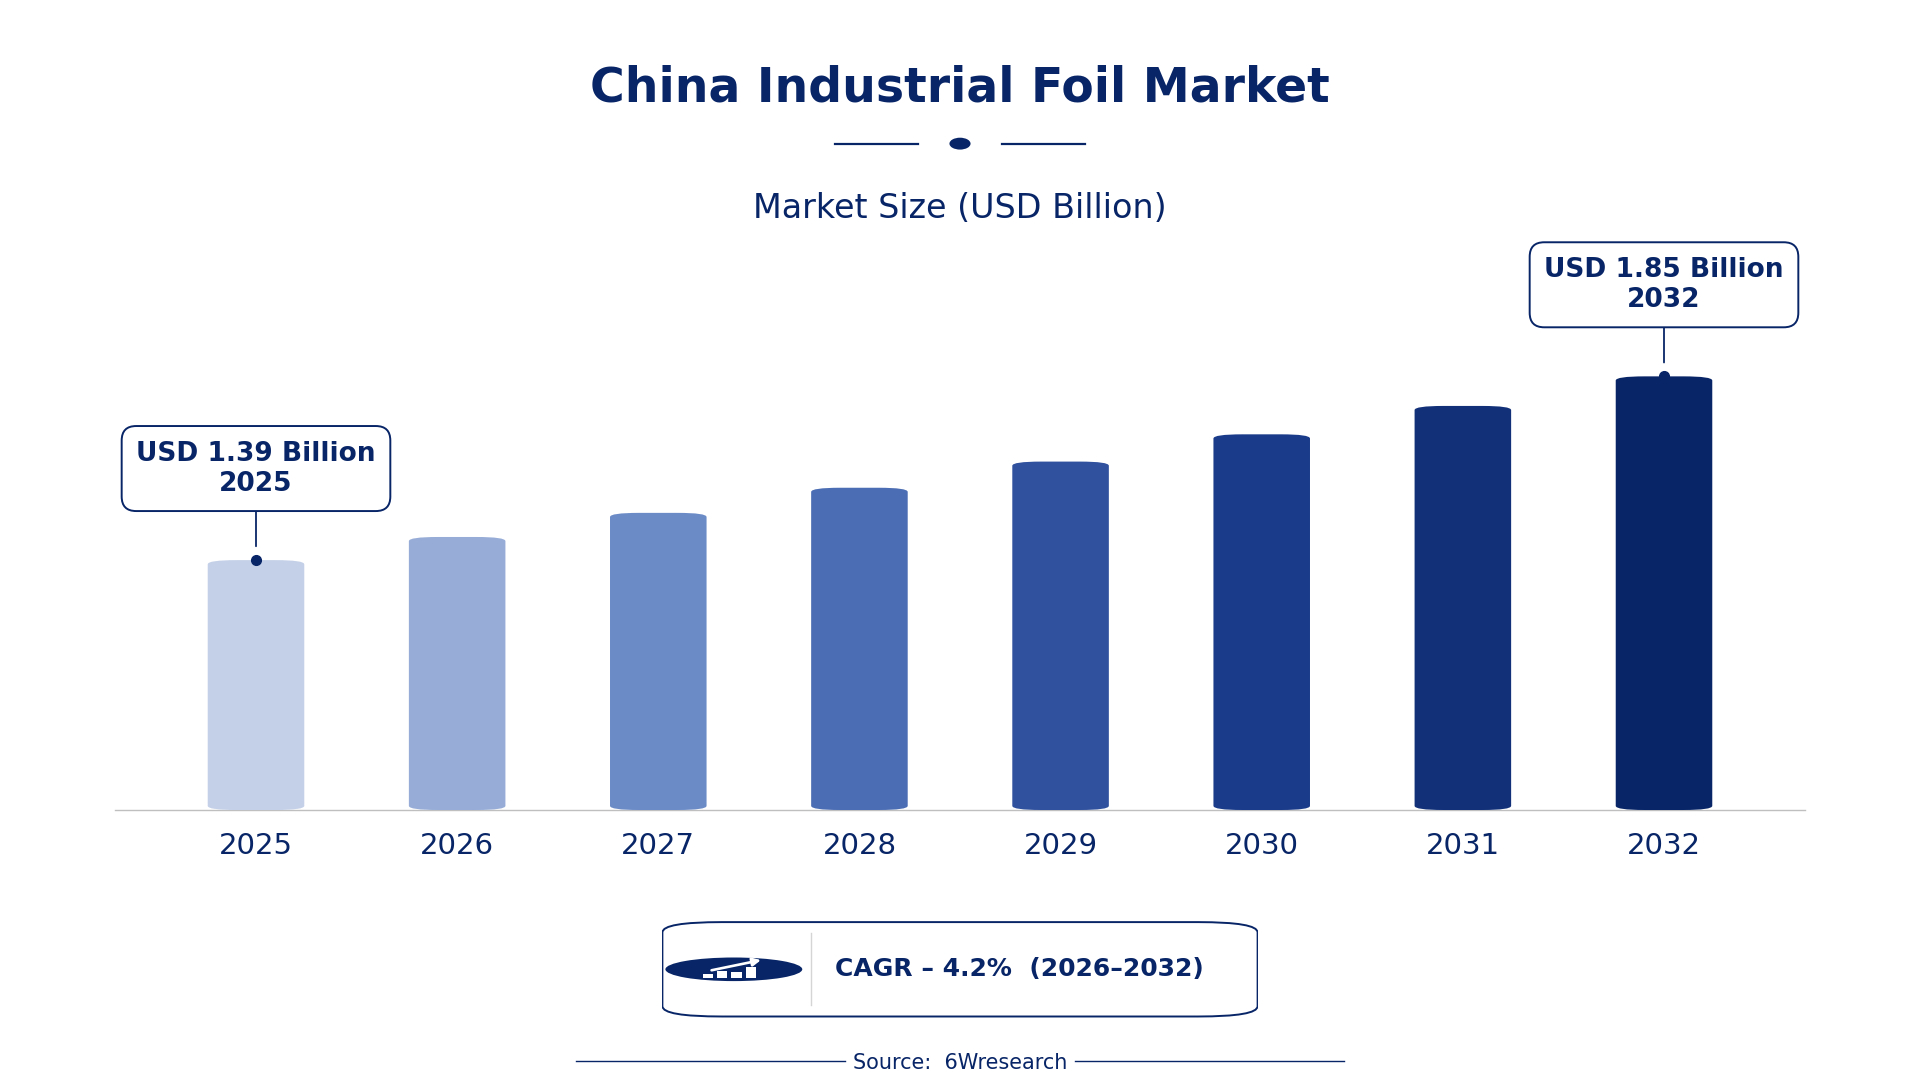
According to 6Wresearch internal database and industry insights, the China Industrial Foil Market was valued at USD 1.39 billion in 2025 and is projected to reach USD 1.85 billion by 2032, growing at a CAGR of approximately 4.2% during 2026–2032.
China Industrial Foil Market Highlights
| Report Metric | Details |
| Report Name | China Industrial Foil Market |
| Market Size 2025 | USD 1.39 billion |
| Market Size 2032 | USD 1.85 billion |
| Absolute Growth 2025–2032 | USD 0.46 billion |
| CAGR 2026–2032 | 4.2% |
| Peak Annual Growth | 6.1% in 2030 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Foil Type, 2025 | Aluminum Foil (37% share) |
| Leading Base Metal, 2025 | Pure/Alloy Aluminum (42% share) |
| Leading Thickness Range, 2025 | 9–70 μm (45% share) |
| Leading End User, 2025 | Packaging (37% share) |
| Fastest-Growing Foil Type | Copper Foil (5.9% CAGR) |
| Fastest-Growing Base Metal | Austenitic Steel (6.3% CAGR) |
| Fastest-Growing End User | PCB Manufacturers (6.1% CAGR) |
| Growing Sector | Packaging |
| Key End Users | Electronics manufacturers, HVAC contractors, healthcare providers |
China Industrial Foil Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
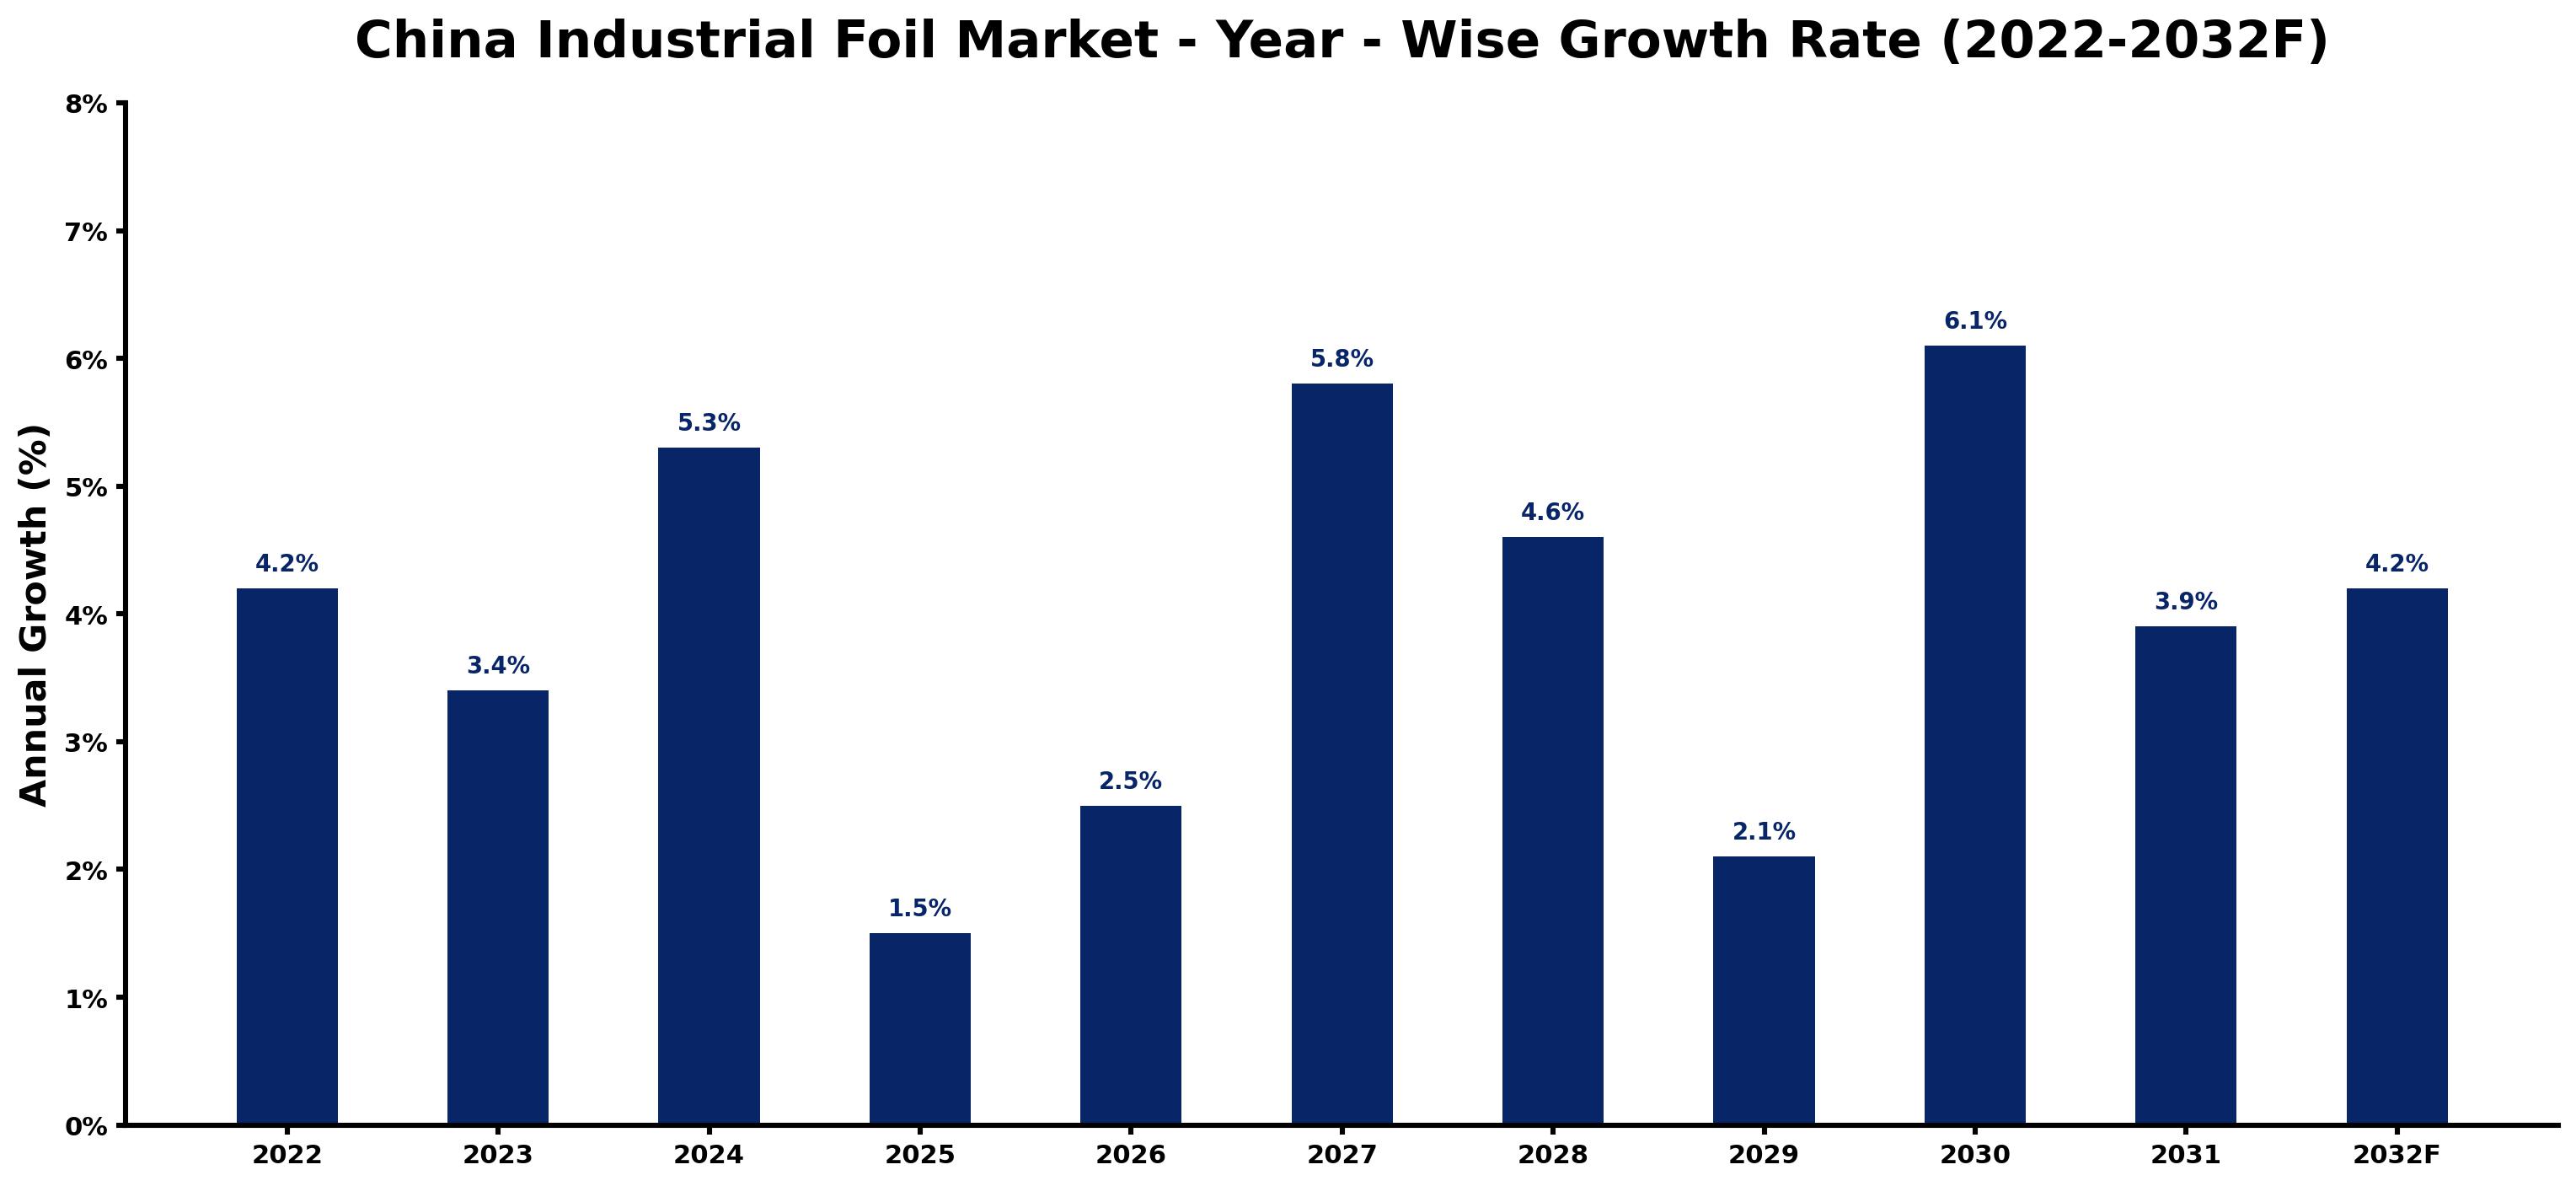
Annual growth estimates for each year appear below with the principal reason behind them, explaining the shifts that set the pace of the market.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 4.2 | The industrial foil market showed steady demand from the packaging sector and electronics. |
| 2023 | 3.4 | Growth slowed due to fluctuations in raw material prices affecting production costs. |
| 2024 | 5.3 | Increased demand from the healthcare sector boosted growth in industrial foil applications. |
| 2025 | 1.5 | The market experienced a slowdown as manufacturers adjusted to changing regulations. |
| 2026 | 2.5 | Demand is expected to rise with the growth of the HVAC market in China. |
| 2027 | 5.8 | The electronics sector will drive growth as production value continues to expand. |
| 2028 | 4.6 | Demand growth will slow due to market saturation in flexible packaging applications. |
| 2029 | 2.1 | The market will see slower growth as manufacturers face increased competition from alternative materials. |
| 2030 | 6.1 | A surge in demand from the aerospace sector will drive growth in stainless steel foil applications. |
| 2031 | 3.9 | Growth will slow as the market stabilises after rapid expansion in previous years. |
| 2032 | 4.2 | The industrial foil market will see a resurgence in demand from the packaging sector, particularly in food applications. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Industrial Foil Market Synopsis
Industrial Foil in China includes thin sheets of metal, mainly aluminium, copper, and stainless steel, produced for a variety of applications. These foils play a crucial role in packaging, electrical applications, and thermal insulation. The China Industrial Foil Market is expanding due to robust demand from domestic users, particularly in the electronics and construction sectors. The packaging industry, valued at over 1.5 trillion CNY, is a key driver of this growth. Additionally, the healthcare sector's expansion is increasing the need for industrial foils in medical devices.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Strong growth in the packaging sector drives demand for aluminum foil. | Driver | High | Aluminum Foil |
| Rising production in the electronics sector increases the need for copper foil. | Driver | High | Copper Foil |
| Investment in eco-friendly manufacturing processes presents opportunities for suppliers. | Opportunity | Medium | Stainless Steel Foil |
| Growing demand for flexible electronics opens new markets for ultra-thin foils. | Opportunity | High | Ultra-Thin (<0.1 mm) |
| Health concerns limit the use of lead foil in various applications. | Restraint | High | Lead Foil |
| Stringent quality standards may increase production costs for manufacturers. | Restraint | Medium | Aluminum Foil |
| The market faces challenges from fluctuating raw material prices affecting profitability. | Challenge | High | Copper Foil |
| Competition from alternative materials may hinder market growth. | Challenge | Medium | Stainless Steel Foil |
Evaluation of Drivers in China Industrial Foil Market (2026–2032)
The table below links each growth driver to the segment it affects and the evidence for it.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Rising demand from the packaging industry is driving aluminum foil usage. | Aluminum Foil | Aluminum foil accounts for approximately 40% of the total industrial foil market in China. |
| Increased production in the electronics sector boosts copper foil demand. | Copper Foil | The electronics sector in China has a production value exceeding 1 trillion CNY. |
| The growth of the HVAC market supports demand for stainless steel foil. | Stainless Steel Foil | The HVAC market in China is projected to grow at a CAGR of 5% through 2026. |
| The healthcare sector's expansion increases the need for industrial foils. | Healthcare & Laboratories | China's healthcare sector is anticipated to grow, increasing demand for industrial foil in medical devices. |
| Technological advancements in manufacturing processes improve production efficiency. | Pure/Alloy Aluminum | ISO 9001:2015 certification is commonly pursued by foil manufacturers in China. |
Expansion of the Industrial Foil market in China is backed by increased production in the electronics sector, strong demand from the packaging industry, and advancements in manufacturing technology. The electronics sector, valued at over 1 trillion CNY, drives demand for copper foil, particularly in PCB manufacturing, which reached 300,000 tons in 2022. The healthcare sector's growth is increasing the use of industrial foils in medical devices, particularly as manufacturers adopt new technologies to meet rising standards. Additionally, the HVAC market's expansion supports the need for stainless steel foil as it grows, further propelling market demand.
Evaluation of Restraints in China Industrial Foil Market
The table below lists the restraints and the evidence behind each.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Health concerns limit the use of lead foil in various applications. | Lead Foil | Lead foil has limited use in specialized applications due to health concerns. |
| Stringent quality standards may increase production costs for manufacturers. | Aluminum Foil | The updated 'Product Quality Law' enforces stricter quality standards for industrial foils. |
| Fluctuating raw material prices can affect profitability for manufacturers. | Copper Foil | The demand for copper foil in PCB manufacturing reached 300,000 tons in 2022. |
| Increased competition from alternative materials may hinder market growth. | Stainless Steel Foil | The aerospace industry is expected to require more than 50,000 tons of stainless steel foil by 2025. |
| Market saturation in certain applications may limit growth potential. | Packaging | Aluminum foil is widely used in food packaging, accounting for about 30% of the packaging market. |
China Industrial Foil Market Challenges
The China Industrial Foil Market encounters several practical issues, starting with technological limitations in production processes. Many manufacturers struggle to implement advanced rolling techniques, which can delay production timelines and raise costs by up to 15% for suppliers. Regulatory complexities arise from compliance with the National Standard GB/T 3190-2015, leading to potential fines or production halts for non-compliant plants. Supply chain disruptions often occur, particularly in sourcing raw materials like aluminium and copper, causing delivery delays of up to three weeks for buyers. Intense competition from domestic and international producers pressures prices, compelling local manufacturers to reduce margins and affecting profitability.
Trends in the China Industrial Foil Market
Buyers and suppliers in the China Industrial Foil Market are adjusting to the following trends.
- Shift towards Eco-Friendly Manufacturing: In 2023, the government allocated 500 million CNY for the development of advanced materials, including industrial foils. This funding encourages manufacturers to adopt sustainable production methods, aligning with environmental goals.
- Increasing Demand for Ultra-Thin Foils: The demand for ultra-thin foils is rising in the electronics sector, particularly for flexible devices. In 2022, the thickness range of 9–70 μm was commonly used in packaging applications.
- Growth in Healthcare Applications: The healthcare sector is expanding, increasing demand for industrial foils in medical devices. This trend is supported by the government's focus on improving healthcare infrastructure.
- Expansion of PCB Manufacturing: The Guangdong province is a leading area for PCB manufacturing, driving copper foil demand. In 2022, the demand for copper foil in PCB manufacturing reached 300,000 tons.
Investment Opportunities in the China Industrial Foil Market
Several openings in the China Industrial Foil Market merit attention from investors.
- Investment in Eco-Friendly Technologies: With the government's 2023 budget of 300 million CNY for advanced materials, there is an opportunity for suppliers to invest in eco-friendly manufacturing technologies, particularly in the Guangdong province.
- Growing Demand in the Aerospace Sector: The aerospace industry is set to require more than 50,000 tons of stainless steel foil by 2025, presenting an opportunity for manufacturers to cater to this expanding market.
- Supply of Ultra-Thin Foils for Electronics: The rising need for ultra-thin foils in flexible electronic devices offers a valuable opportunity for suppliers to meet this specific demand in the electronics sector.
- Expansion of Packaging Solutions: The packaging industry, valued at over 1.5 trillion CNY, presents opportunities for manufacturers to supply aluminium foils, particularly for food packaging applications.
Government Initiatives in the China Industrial Foil Market
The 'Advanced Manufacturing Industry Development Plan' launched by the Ministry of Industry and Information Technology in 2021 aims to improve the competitiveness of the foil manufacturing sector. This plan supports manufacturers in adopting advanced technologies and improving production efficiency. The '2023 Industrial Upgrading Strategy' approved by the National Development and Reform Commission promotes sustainable practices in the foil industry, targeting a 15% reduction in energy consumption by 2025. These initiatives improve production capabilities and encourage eco-friendly practices among manufacturers.
The National Development and Reform Commission oversees regulations for the foil production sector, approving various initiatives aimed at improving production capabilities. The Ministry of Ecology and Environment initiated the 'Green Manufacturing Program' in 2022 to support eco-friendly practices in the industrial foil sector. This program encourages manufacturers to adopt sustainable practices and reduce emissions, aligning with the government's broader environmental goals. The Ministry of Finance's subsidy program for innovative technologies in foil production has a budget of 300 million CNY, further supporting advancements in the sector.
Future Insight of the China Industrial Foil Market
The China Industrial Foil Market will transform by 2032, driven by several pivotal factors. The 'Made in China 2025' initiative will improve manufacturing capabilities in advanced materials, ensuring higher production efficiency. The healthcare sector's growth will escalate demand for industrial foil in medical devices, while the HVAC market is projected to expand at a CAGR of 5% through 2026, boosting foil applications. Demand for ultra-thin foils in the electronics sector will surge, particularly for flexible devices, further stimulating market growth.
Market Segmentation Analysis
The analysis below covers each segmentation, its leading category in 2025 and its fastest-growing category through 2032.
By Foil Type – Aluminum Foil Dominated, Copper Foil Expected to Grow Fastest
According to Sachin Kumar Rai, Senior Research Analyst at 6Wresearch, in 2025, Aluminum Foil led the foil type split with a 37% share. Aluminum foil holds the largest market share in China due to its extensive use in packaging and insulation applications. Its critical role in food packaging, accounting for around 30% of the packaging market, highlights its significance in consumer goods. The quickest growth will come from Copper Foil, forecast to expand at a CAGR of 5.9% between 2026 and 2032. Copper foil is experiencing rapid growth, primarily driven by its essential role in PCB manufacturing, with demand reaching 300,000 tons in 2022. As the electronics sector continues to expand, the demand for copper foil is expected to rise further, reinforcing its market position. Suppliers should enhance their production capabilities for copper foil to effectively meet the rising industry demand.
By Base Metal – Pure/Alloy Aluminum Dominated, Austenitic Steel Expected to Grow Fastest
Pure/Alloy Aluminum took a 42% share of base metal in 2025, more than any other category. Pure and alloy aluminum dominate the market share in China, as they are widely used across various industrial applications. Their versatility and cost-effectiveness make them a preferred choice in multiple manufacturing sectors, ensuring sustained demand. Austenitic Steel is set to record the highest CAGR in this split, 6.3% over 2026–2032. Austenitic steel is witnessing the fastest growth, particularly in high-stress applications such as aerospace. The increasing requirement for durable materials in these industries is propelling this growth trend, indicating a shift in material preferences. Suppliers should consider expanding their product lines to include austenitic steel to capitalise on the growing demand in high-performance applications.
By Thickness Range – 9–70 μm Dominated and Is Expected to Record the Fastest Growth
9–70 μm held a 45% share of the China Industrial Foil Market by thickness range in 2025. The 9–70 μm thickness range leads the market share in China as it is widely used for various applications, particularly in packaging. This thickness is ideal for balancing flexibility and strength in products. The same category is also set to grow fastest, at a CAGR of 5.3% during 2026–2032. The 9–70 μm thickness range is also the fastest-growing segment, driven by its increasing adoption in both packaging and electronics. This dual demand ensures that its market position will continue to strengthen. Suppliers should invest in technologies that support the production of foils within this thickness range to meet the rising demand.
By End User – Packaging Dominated, PCB Manufacturers Expected to Grow Fastest
Packaging accounted for a 37% market share by end user in 2025. The packaging sector commands the largest market share, serving as a primary application for industrial foil, particularly in food and consumer goods. With the packaging industry valued at over 1.5 trillion CNY, its influence on the overall market is substantial. Over 2026–2032, PCB Manufacturers are expected to post the fastest growth, at a CAGR of 6.1%. PCB manufacturers represent the fastest-growing end-user segment, driven by the flourishing electronics market. As production values in this sector exceed 1 trillion CNY, the demand for industrial foil is poised for significant growth. Suppliers should prioritise collaborations with PCB manufacturers to align with the anticipated growth in the electronics market.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Industrial Foil Market Outlook
- Market Size of China Industrial Foil Market, 2025
- Forecast of China Industrial Foil Market, 2032
- Historical Data and Forecast of China Industrial Foil Revenues & Volume for the Period 2022 - 2032F
- China Industrial Foil Market Trend Evolution
- China Industrial Foil Market Drivers and Challenges
- China Industrial Foil Price Trends
- China Industrial Foil Porter's Five Forces
- China Industrial Foil Industry Life Cycle
- Historical Data and Forecast of China Industrial Foil Market Revenues & Volume By Foil Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Foil Market Revenues & Volume By Aluminum Foil for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Foil Market Revenues & Volume By Copper Foil for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Foil Market Revenues & Volume By Lead Foil for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Foil Market Revenues & Volume By Stainless Steel Foil for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Foil Market Revenues & Volume By Base Metal for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Foil Market Revenues & Volume By Pure/Alloy Aluminum for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Foil Market Revenues & Volume By Electro-Deposited for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Foil Market Revenues & Volume By Dense Metal Sheets for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Foil Market Revenues & Volume By Austenitic Steel for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Foil Market Revenues & Volume By Thickness Range for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Foil Market Revenues & Volume By 0.2 mm for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Foil Market Revenues & Volume By 9 70 m for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Foil Market Revenues & Volume By Radiation Shielding for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Foil Market Revenues & Volume By Ultra-Thin ( 0.1 mm) for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Foil Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Foil Market Revenues & Volume By HVAC Ducting, Packaging for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Foil Market Revenues & Volume By PCB Manufacturers for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Foil Market Revenues & Volume By Healthcare & Laboratories for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Foil Market Revenues & Volume By Aerospace Components for the Period 2022 - 2032F
- China Industrial Foil Import Export Trade Statistics
- Market Opportunity Assessment By Foil Type
- Market Opportunity Assessment By Base Metal
- Market Opportunity Assessment By Thickness Range
- Market Opportunity Assessment By End User
- China Industrial Foil Top Companies Market Share
- China Industrial Foil Competitive Benchmarking By Technical and Operational Parameters
- China Industrial Foil Company Profiles
- China Industrial Foil Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By Foil Type
- Aluminum Foil
- Copper Foil
- Lead Foil
- Stainless Steel Foil
By Base Metal
- Pure/Alloy Aluminum
- Electro-Deposited
- Dense Metal Sheets
- Austenitic Steel
By Thickness Range
- <0.2 mm
- 9–70 μm
- Radiation Shielding
- Ultra-Thin (<0.1 mm)
By End User
- HVAC Ducting
- Packaging
- PCB Manufacturers
- Healthcare & Laboratories
- Aerospace Components































