China Industrial Gas Sensor Market Size & Growth Rate
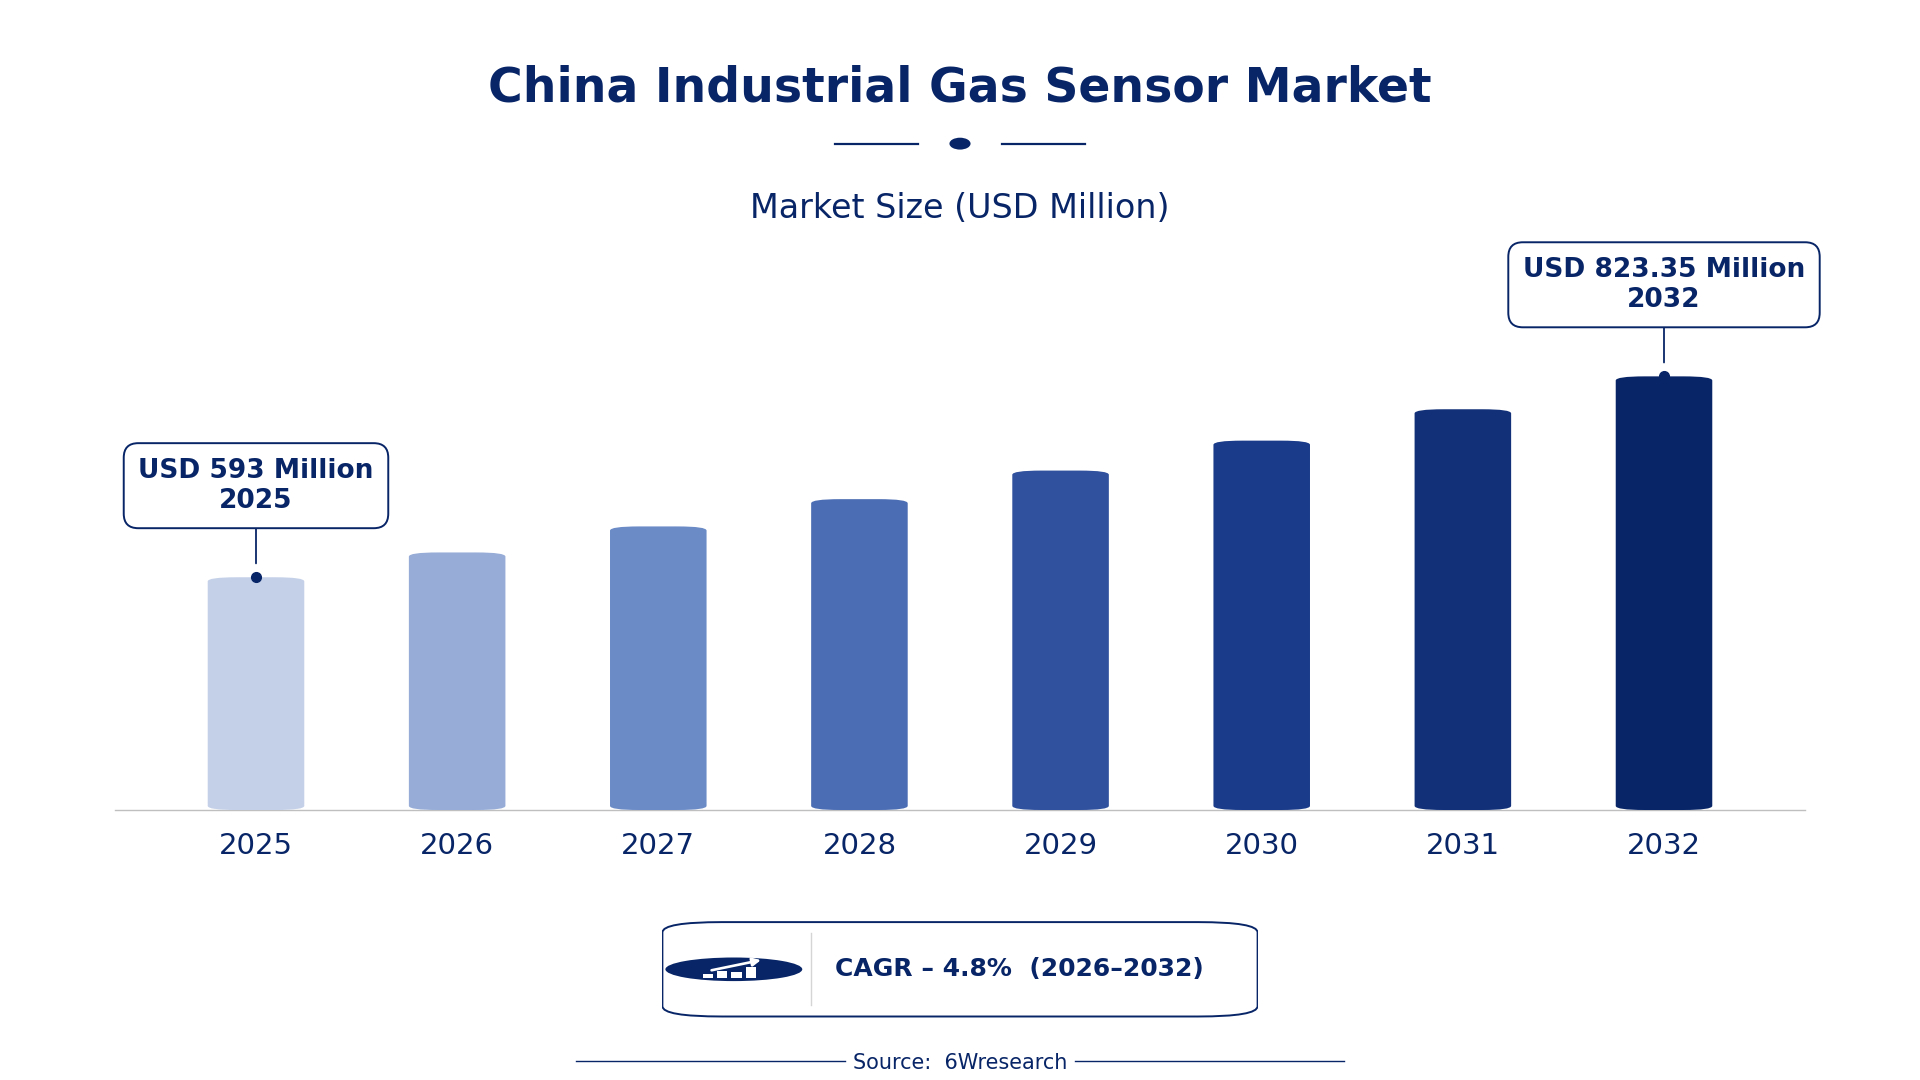
According to 6Wresearch internal database and industry insights, the China Industrial Gas Sensor Market was valued at USD 593.0 million in 2025 and is projected to reach USD 823.35 million by 2032, growing at a CAGR of approximately 4.8% during 2026–2032.
China Industrial Gas Sensor Market Highlights
| Report Metric | Details |
| Report Name | China Industrial Gas Sensor Market |
| Market Size 2025 | USD 593.0 million |
| Market Size 2032 | USD 823.35 million |
| Absolute Growth 2025–2032 | USD 230.35 million |
| CAGR 2026–2032 | 4.8% |
| Peak Annual Growth | 6.9% in 2028 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Sensor Type, 2025 | Electrochemical Sensors (46% share) |
| Leading Detection Principle, 2025 | Redox Reactions (49% share) |
| Leading Target Gas, 2025 | O₂ (36% share) |
| Leading End User, 2025 | Oil & Gas Facilities (46% share) |
| Fastest-Growing Sensor Type | Infrared (NDIR) Sensors (6.4% CAGR) |
| Fastest-Growing Detection Principle | Absorption Spectroscopy (7.4% CAGR) |
| Fastest-Growing Target Gas | VOCs (7.1% CAGR) |
| Fastest-Growing End User | HVAC and Air Monitoring (6.1% CAGR) |
| Growing Sector | Oil and Gas Facilities |
| Key End Users | Oil & Gas Facilities, HVAC and Air Monitoring, Chemical Plants, Environmental Testing Labs |
China Industrial Gas Sensor Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
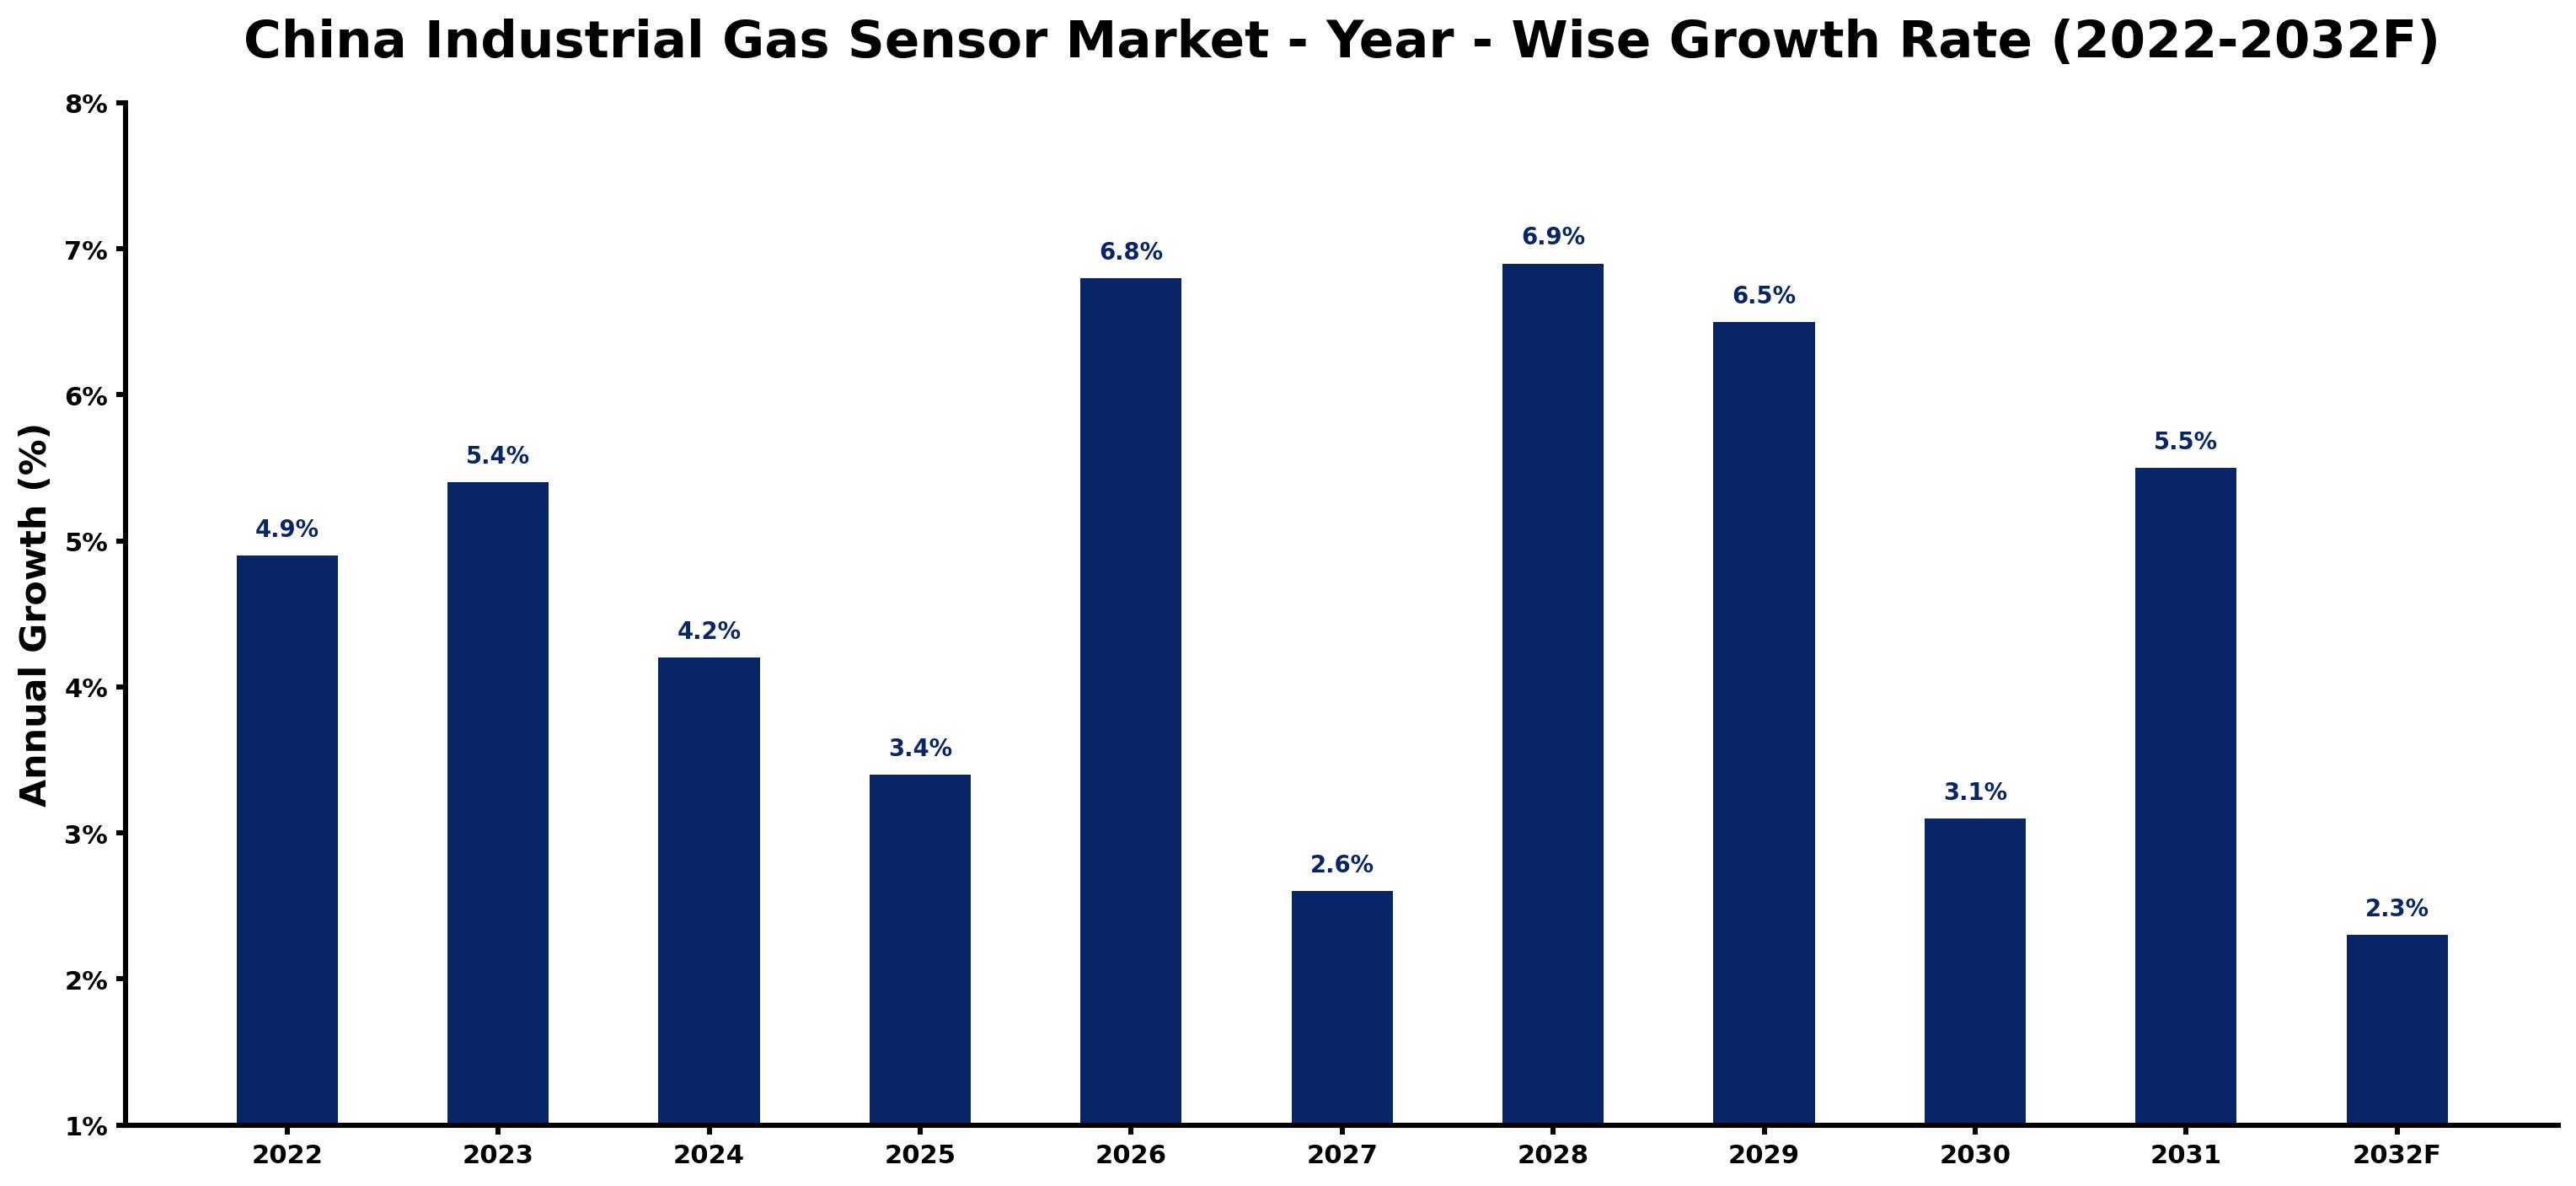
Each row of the following table gives one year's estimated growth and the event or demand shift that explains it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 4.9 | The market showed steady growth due to increased industrial activities and demand for safety measures. |
| 2023 | 5.4 | Growth accelerated as the oil and gas sector expanded, employing over 1.5 million workers. |
| 2024 | 4.2 | A slowdown occurred as demand stabilised following the previous year's surge in sensor installations. |
| 2025 | 3.4 | Continued growth was observed, albeit at a slower rate as market conditions normalised. |
| 2026 | 6.8 | Demand surged again as investments in advanced gas detection technologies gained momentum. |
| 2027 | 2.6 | The market experienced a slowdown as growth rates moderated after reaching a peak. |
| 2028 | 6.9 | A peak in growth was achieved, driven by heightened safety regulations in industrial sectors. |
| 2029 | 6.5 | Growth slowed slightly as the market adjusted to the previous year's high demand. |
| 2030 | 3.1 | The market continued to grow, but at a slower pace as new installations stabilised. |
| 2031 | 5.5 | An increase in growth was noted as the HVAC sector expanded its sensor requirements. |
| 2032 | 2.3 | Growth is expected to slow further as the market matures and competition increases. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Industrial Gas Sensor Market Synopsis
Industrial Gas Sensor Market in China encompasses devices that detect and measure gas concentrations across various environments. These sensors play a crucial role in monitoring air quality and ensuring safety in industrial processes. The market is expanding due to increasing demand from the oil and gas sector, which employs over 1.5 million workers. Investments in advanced gas detection technologies and regulatory support are propelling this growth. The installed base of gas sensors in oil and gas facilities is estimated at 500,000 units, underscoring the sector's reliance on these technologies.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Growing demand for safety compliance in industrial environments | Driver | High | Electrochemical Sensors |
| Increasing installations of gas sensors in HVAC systems | Driver | High | Infrared (NDIR) Sensors |
| Expansion of oil and gas facilities requiring advanced monitoring solutions | Opportunity | High | Oil & Gas Facilities |
| Rising investments in air quality monitoring technologies | Opportunity | High | HVAC and Air Monitoring |
| Regulatory compliance costs for manufacturers | Restraint | Medium | Electrochemical Sensors |
| Market saturation in certain sensor types | Restraint | Medium | Infrared (NDIR) Sensors |
| Supply chain disruptions affecting sensor availability | Challenge | High | Catalytic Bead Sensors |
| Technological advancements requiring constant updates in production | Challenge | Medium | Photoionization Detectors |
Evaluation of Drivers in China Industrial Gas Sensor Market (2026–2032)
The table below links each growth driver to the segment it affects and the evidence for it.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased safety regulations in industrial sectors boost demand for gas sensors. | Electrochemical Sensors | The National Standard GB/T 18655-2020 mandates improved safety measures, leading to higher sensor purchases. |
| Rising installations of CO₂ sensors in HVAC systems improve air quality monitoring. | Infrared (NDIR) Sensors | In 2022, demand for CO₂ sensors reached 200,000 units, prompting HVAC manufacturers to invest in these technologies. |
| Expansion of oil and gas facilities drives the need for advanced monitoring solutions. | Oil & Gas Facilities | The installed base of gas sensors in oil and gas facilities is estimated at 500,000 units, indicating strong demand. |
| Growing focus on environmental compliance increases demand for gas sensors in chemical plants. | Chemical Plants | The Chemical Industry Association of China promotes the use of gas sensors for safety compliance, pushing manufacturers to adopt these technologies. |
| Investment in research on advanced gas detection technologies supports market growth. | Environmental Testing Labs | In 2023, $10 million was allocated to support research, enhancing sensor capabilities and encouraging purchases. |
The oil and gas sector, employing over 1.5 million workers, is a primary driver of demand for advanced monitoring solutions. The installed base of gas sensors in oil and gas facilities is estimated at 500,000 units, reflecting the sector's dependence on these technologies. Investment in research for advanced gas detection technologies is also contributing to market growth, with $10 million allocated in 2023 to improve sensor capabilities.
Evaluation of Restraints in China Industrial Gas Sensor Market
The main factors holding the market back are set out below.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Compliance costs associated with safety regulations can burden manufacturers. | Electrochemical Sensors | Manufacturers face increased expenses to meet the National Standard GB/T 18655-2020, impacting profit margins. |
| Market saturation in certain sensor types limits growth opportunities. | Infrared (NDIR) Sensors | As the market matures, demand for traditional sensor types may plateau, reducing new installations. |
| Supply chain disruptions can delay sensor production and delivery. | Catalytic Bead Sensors | Global supply chain issues have led to longer lead times, affecting availability for buyers. |
| Technological advancements necessitate continuous updates in production processes. | Photoionization Detectors | Manufacturers must invest in R&D to keep up with evolving technologies, increasing operational costs. |
| Competition from alternative monitoring technologies may hinder sensor adoption. | Environmental Testing Labs | Emerging technologies can offer lower-cost solutions, challenging traditional gas sensor sales. |
China Industrial Gas Sensor Market Challenges
Buyers in the China industrial gas sensor market encounter fierce competition, as numerous manufacturers compete for contracts, leading to price reductions that squeeze supplier profit margins. A lack of skilled professionals in gas sensor technology restricts producers' ability to innovate, resulting in delayed product launches that impede market responsiveness. Regulatory requirements, such as the National Standard GB/T 18655-2020, impose additional operational costs on manufacturers, which can lead to higher prices for buyers. Rising raw material costs for electrochemical sensors create procurement challenges for buyers in the oil and gas sector, potentially extending project timelines by several months.
Trends in the China Industrial Gas Sensor Market
The trends below show where the China Industrial Gas Sensor Market is heading.
- Shift towards Advanced Monitoring Technologies: The "Air Quality Improvement Plan" launched in 2023 emphasises reducing VOCs through improved monitoring technologies. This initiative has spurred increased investments in gas sensors, particularly in the Beijing-Tianjin-Hebei region, where advancements in air quality management are taking place.
- Transition from Traditional to Smart Sensors: Since 2021, the "Smart Manufacturing 2025" initiative has promoted the adoption of smart sensors in industrial applications. This shift aims for a 20% increase in efficiency by 2025, encouraging manufacturers to innovate their product offerings.
- Emergence of VOCs as a Key Target Gas: Demand for VOC monitoring has surged since 2023, driven by regulatory pressures. This trend is particularly noticeable in the HVAC sector, where installations of VOC sensors are expected to grow as compliance becomes increasingly critical.
- Increase in Regulatory Standards for Gas Sensors: The introduction of the "National Standard for Gas Sensors" in 2022 has raised performance expectations for manufacturers. Adhering to these standards is becoming crucial for product development and market entry.
Investment Opportunities in the China Industrial Gas Sensor Market
The following opportunities in the China Industrial Gas Sensor Market pair current demand with a clear way in.
- Investment in Oil & Gas Facilities: The Yangtze River Delta region is seeing increased investments in oil and gas facilities, which will drive sensor demand. This creates opportunities for suppliers to deliver advanced gas detection solutions.
- Expansion of HVAC Systems: With a growing emphasis on air quality, the demand for sensors in HVAC systems is projected to rise. The increasing installations of CO₂ sensors present opportunities for manufacturers to introduce innovative products.
- Development of Environmental Testing Labs: The need for precise pollutant measurements in environmental testing labs is driving demand for gas sensors. Suppliers can enter this market by collaborating with local testing facilities to provide tailored solutions.
- Enhancement of Chemical Plant Safety Standards: Increasing safety standards in chemical plants offer opportunities for gas sensor manufacturers. By aligning products with the latest regulations, suppliers can capture a share of this expanding market.
Government Initiatives in the China Industrial Gas Sensor Market
The National Standard for Gas Sensors issued by the State Administration for Market Regulation in 2022 is important for buyers in the industrial gas sensor market. This standard improves safety and performance requirements for gas sensors, ensuring that manufacturers meet strict quality benchmarks. Compliance with this regulation is necessary for producers to maintain market access and for buyers to ensure the reliability of their monitoring solutions. Additionally, the "Smart Manufacturing 2025" initiative, launched by the Ministry of Industry and Information Technology in 2021, aims to enhance sensor technology development, targeting a 20% increase in efficiency by 2025. This initiative encourages investment in advanced manufacturing processes and technologies, directly impacting the production of industrial gas sensors.
The Ministry of Ecology and Environment oversees the implementation of the "Air Quality Improvement Plan," which focuses on improving monitoring technologies for industrial emissions. This plan allocates funding to support research and development in gas detection technologies, benefiting both manufacturers and users. The China National Institute of Standardization plays a key role in establishing and updating standards for industrial gas sensors, ensuring that products meet national safety and performance criteria. Furthermore, the Ministry of Science and Technology's "Innovative Sensor Technology Development Plan" launched in 2023 allocates $5 million for research in gas detection technologies, promoting innovation in the sector. These measures collectively improve the operational capabilities of buyers and producers in the industrial gas sensor market.
Future Insight of the China Industrial Gas Sensor Market
The China industrial gas sensor market is set for transformative changes by 2032, driven by technological advancements and heightened regulatory scrutiny. The government's "Air Quality Improvement Plan" will necessitate a significant increase in CO₂ sensor demand, with projections estimating 200,000 units required by 2030. Investment in air monitoring technologies in the Yangtze River Delta will bolster safety compliance across industrial sectors. Enhanced research funding for advanced gas detection technologies will lead to improved sensor capabilities, benefiting both buyers and suppliers in the market.
Market Segmentation Analysis
Each segment group is reviewed below, with the leader by share and the fastest grower by CAGR.
By Sensor Type – Electrochemical Sensors Dominated, Infrared (NDIR) Sensors Expected to Grow Fastest
According to Sachin Kumar Rai, Senior Research Analyst at 6Wresearch, Electrochemical Sensors held a 46% share of the China Industrial Gas Sensor Market by sensor type in 2025. Electrochemical sensors hold the largest share in the China industrial gas sensor market due to their high sensitivity and specificity for toxic gas detection. Their prevalent use in oil and gas facilities, with an installed base of approximately 500,000 units, highlights their critical role in maintaining safety standards. Infrared (NDIR) Sensors are projected to grow fastest, at a CAGR of 6.4% during 2026–2032. Infrared (NDIR) sensors are experiencing rapid growth as they are increasingly adopted for measuring gases such as CO₂ and CH₄, especially in HVAC systems where demand reached 200,000 units in 2022. This upward trend is expected to continue due to stricter air quality regulations. Suppliers should focus on enhancing infrared sensor technologies to meet the growing demand in HVAC applications.
By Detection Principle – Redox Reactions Dominated, Absorption Spectroscopy Expected to Grow Fastest
Redox Reactions took a 49% share of detection principle in 2025, more than any other category. Redox reactions are the leading detection principle in the market, primarily due to their essential function in electrochemical sensors widely utilised across various industries. This principle is crucial for ensuring safety and compliance, particularly in sectors like oil and gas. Absorption Spectroscopy is set to record the highest CAGR in this split, 7.4% over 2026–2032. Absorption spectroscopy is the fastest-growing detection principle, driven by its increasing use in advanced gas sensors for accurate measurements in environmental monitoring. As regulations on air quality become more stringent, this method is anticipated to see wider adoption. Manufacturers should invest in developing technologies that leverage absorption spectroscopy to align with regulatory changes and market demands.
By Target Gas – O₂ Dominated, VOCs Expected to Grow Fastest
With a 36% revenue share in 2025, O₂ was the largest target gas category. O₂ is the dominant target gas in the industrial gas sensor market, as it is essential for monitoring safety and operational efficiency in various industrial processes. Its critical role in environments like oil and gas facilities ensures a steady demand for sensors. Over 2026–2032, VOCs are expected to post the fastest growth, at a CAGR of 7.1%. VOCs represent the fastest-growing target gas segment, largely due to rising concerns over air quality and the implementation of stricter regulations. The focus on VOC reduction as part of the Air Quality Improvement Plan will further fuel this growth. Buyers should prioritise VOC detection capabilities in their gas sensor procurement to comply with new environmental standards.
By End User – Oil & Gas Facilities Dominated, HVAC and Air Monitoring Expected to Grow Fastest
Oil & Gas Facilities accounted for a 46% market share by end user in 2025. Oil and gas facilities represent the largest end user of industrial gas sensors, as these devices are essential for maintaining safety and operational efficiency. With over 1.5 million workers in this sector, the demand for reliable gas detection solutions is substantial. The quickest growth will come from HVAC and Air Monitoring, forecast to expand at a CAGR of 6.1% between 2026 and 2032. HVAC and air monitoring are the fastest-growing end user segments, propelled by rising investments in air quality technologies and the necessity to comply with health standards. The notable increase in CO₂ sensor demand in HVAC systems highlights this trend. Suppliers should customise their products to cater to the specific requirements of HVAC applications to capitalise on this rapid growth.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Industrial Gas Sensor Market Outlook
- Market Size of China Industrial Gas Sensor Market, 2025
- Forecast of China Industrial Gas Sensor Market, 2032
- Historical Data and Forecast of China Industrial Gas Sensor Revenues & Volume for the Period 2022 - 2032F
- China Industrial Gas Sensor Market Trend Evolution
- China Industrial Gas Sensor Market Drivers and Challenges
- China Industrial Gas Sensor Price Trends
- China Industrial Gas Sensor Porter's Five Forces
- China Industrial Gas Sensor Industry Life Cycle
- Historical Data and Forecast of China Industrial Gas Sensor Market Revenues & Volume By Sensor Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Gas Sensor Market Revenues & Volume By Electrochemical Sensors for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Gas Sensor Market Revenues & Volume By Infrared (NDIR) Sensors for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Gas Sensor Market Revenues & Volume By Catalytic Bead Sensors for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Gas Sensor Market Revenues & Volume By Photoionization Detectors for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Gas Sensor Market Revenues & Volume By Detection Principle for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Gas Sensor Market Revenues & Volume By Redox Reactions for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Gas Sensor Market Revenues & Volume By Absorption Spectroscopy for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Gas Sensor Market Revenues & Volume By Combustion Heat for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Gas Sensor Market Revenues & Volume By UV Ionization for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Gas Sensor Market Revenues & Volume By Target Gas for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Gas Sensor Market Revenues & Volume By O , CO, H S for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Gas Sensor Market Revenues & Volume By CO , CH for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Gas Sensor Market Revenues & Volume By Hydrocarbons for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Gas Sensor Market Revenues & Volume By VOCs for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Gas Sensor Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Gas Sensor Market Revenues & Volume By Oil & Gas Facilities for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Gas Sensor Market Revenues & Volume By HVAC and Air Monitoring for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Gas Sensor Market Revenues & Volume By Chemical Plants for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Gas Sensor Market Revenues & Volume By Environmental Testing Labs for the Period 2022 - 2032F
- China Industrial Gas Sensor Import Export Trade Statistics
- Market Opportunity Assessment By Sensor Type
- Market Opportunity Assessment By Detection Principle
- Market Opportunity Assessment By Target Gas
- Market Opportunity Assessment By End User
- China Industrial Gas Sensor Top Companies Market Share
- China Industrial Gas Sensor Competitive Benchmarking By Technical and Operational Parameters
- China Industrial Gas Sensor Company Profiles
- China Industrial Gas Sensor Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By Sensor Type
- Electrochemical Sensors
- Infrared (NDIR) Sensors
- Catalytic Bead Sensors
- Photoionization Detectors
By Detection Principle
- Redox Reactions
- Absorption Spectroscopy
- Combustion Heat
- UV Ionization
By Target Gas
- O₂
- CO
- H₂S
- CO₂
- CH₄
- Hydrocarbons
- VOCs
By End User
- Oil & Gas Facilities
- HVAC and Air Monitoring
- Chemical Plants
- Environmental Testing Labs































