China Industrial Mining Market Size & Growth Rate
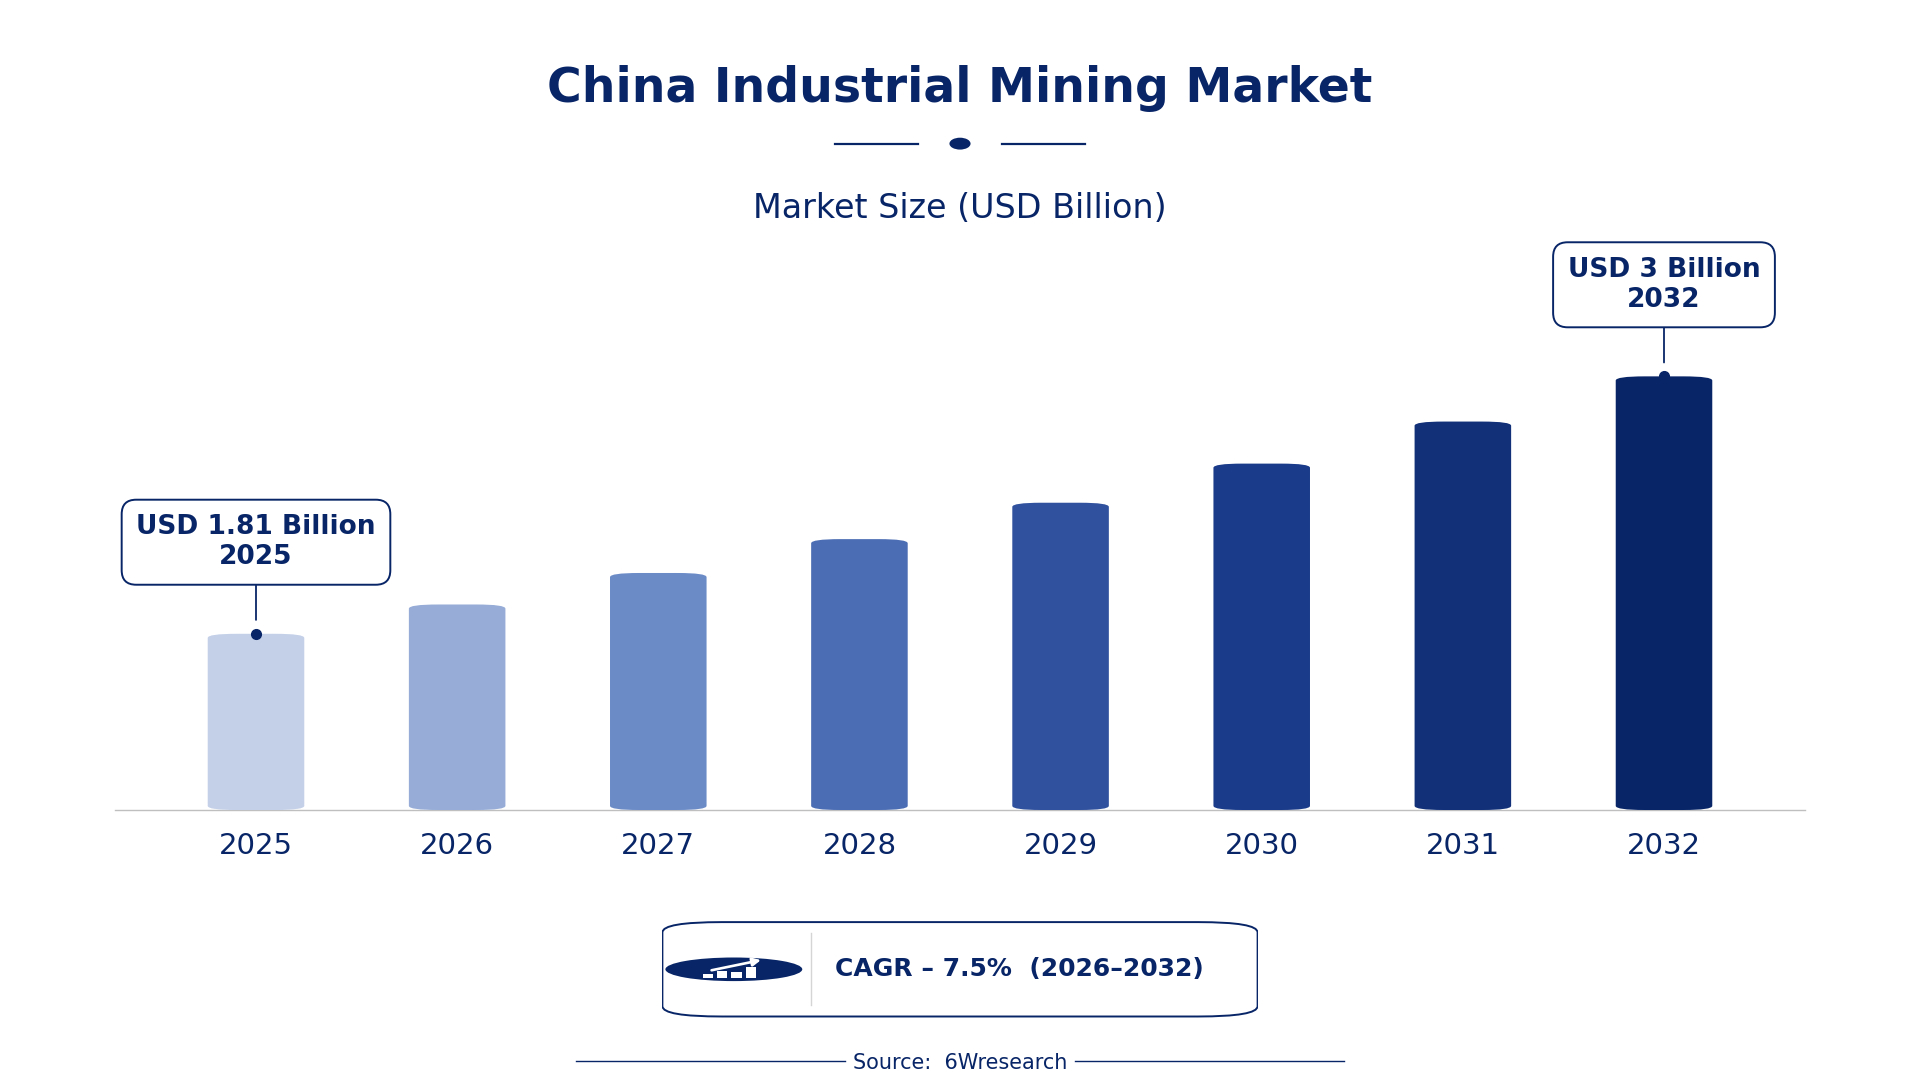
According to 6Wresearch internal database and industry insights, the China Industrial Mining Market was valued at USD 1.81 billion in 2025 and is projected to reach USD 3 billion by 2032, growing at a CAGR of approximately 7.5% during 2026–2032.
China Industrial Mining Market Highlights
| Report Metric | Details |
| Report Name | China Industrial Mining Market |
| Market Size 2025 | USD 1.81 billion |
| Market Size 2032 | USD 3 billion |
| Absolute Growth 2025–2032 | USD 1.19 billion |
| CAGR 2026–2032 | 7.5% |
| Peak Annual Growth | 10.0% in 2031 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Mining Method, 2025 | Surface Mining (52% share) |
| Leading Mineral Type, 2025 | Coal (38% share) |
| Leading Equipment Type, 2025 | Excavators & Drills (39% share) |
| Leading Application Area, 2025 | Ore Extraction (40% share) |
| Leading End User Industry, 2025 | Heavy Industry (39% share) |
| Fastest-Growing Mining Method | Underground Mining (10.2% CAGR) |
| Fastest-Growing Mineral Type | Copper (9.4% CAGR) |
| Fastest-Growing Equipment Type | Loaders & Crushers (9.8% CAGR) |
| Fastest-Growing Application Area | Mineral Transport (10.2% CAGR) |
| Fastest-Growing End User Industry | Metals and Minerals (10.0% CAGR) |
| Growing Sector | Heavy Industry |
| Key End Users | Energy sector, Construction firms, Manufacturing industries, Mining equipment suppliers |
China Industrial Mining Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
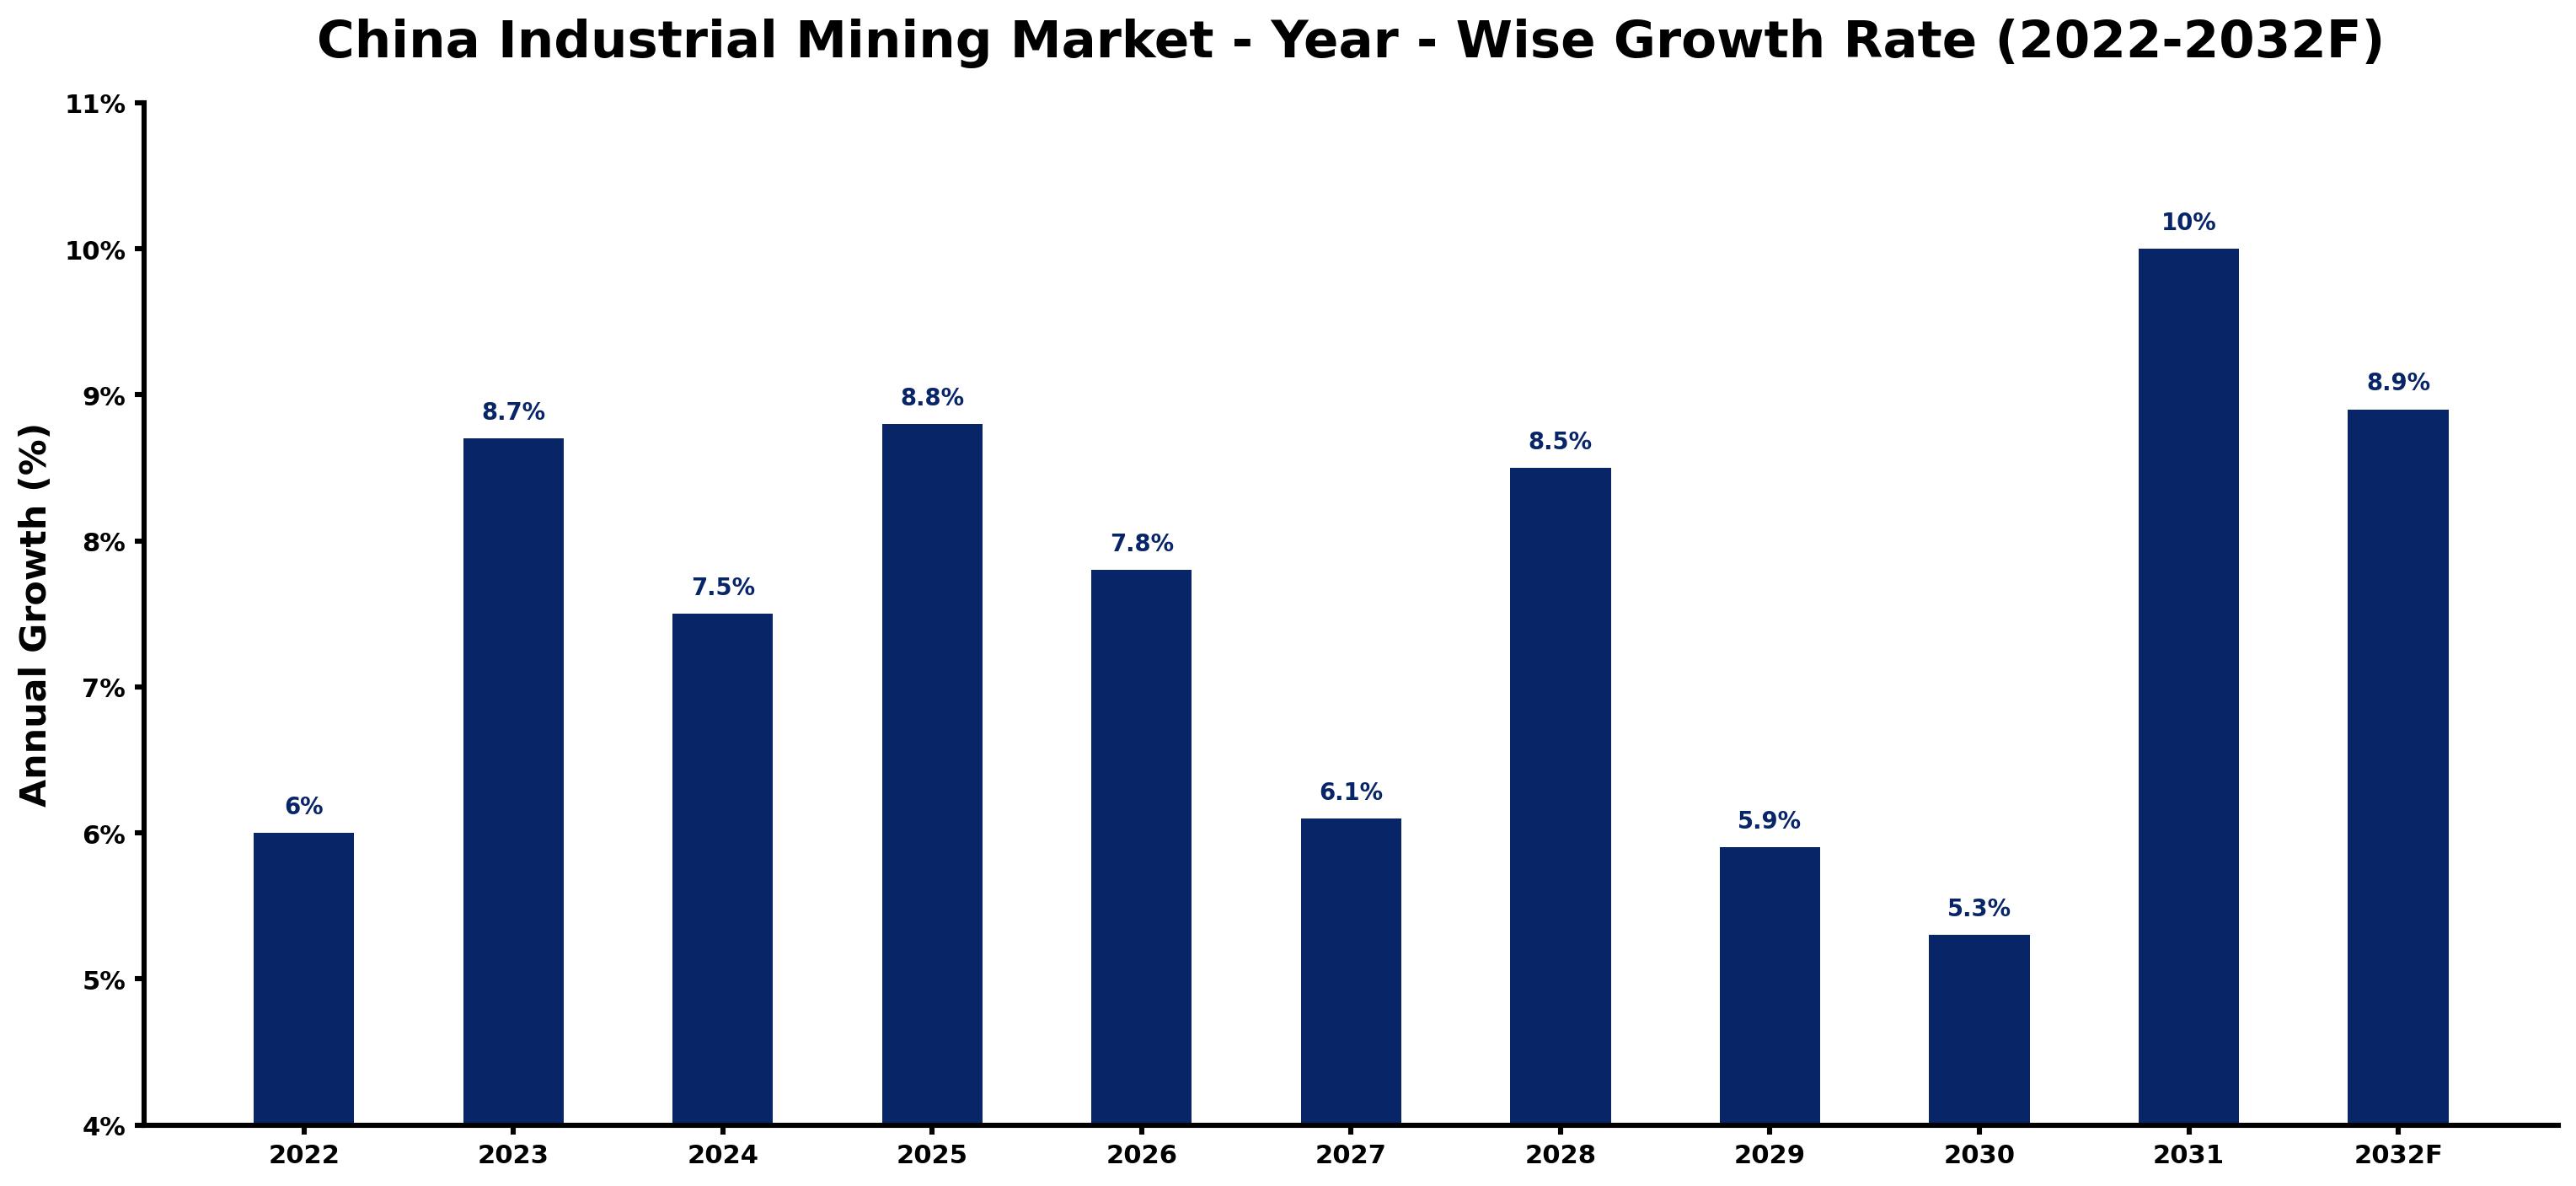
Annual growth estimates for each year appear below with the principal reason behind them, explaining the shifts that set the pace of the market.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 6.0 | The mining sector demonstrated steady activity with strong demand from heavy manufacturing. |
| 2023 | 8.7 | Growth accelerated due to increased infrastructure investments and demand for raw materials. |
| 2024 | 7.5 | The market experienced a slowdown as production faced regulatory adjustments and environmental scrutiny. |
| 2025 | 8.8 | Demand surged with coal production reaching over 3.8 billion tons, primarily for energy generation. |
| 2026 | 7.8 | A slowdown is expected as miners adjust to new environmental regulations and safety standards. |
| 2027 | 6.1 | Growth will continue to slow as the industry faces challenges in resource management and sustainability efforts. |
| 2028 | 8.5 | Demand is projected to rebound with rising copper consumption driven by infrastructure development. |
| 2029 | 5.9 | The market will slow again as heavy industry faces fluctuations in demand for minerals. |
| 2030 | 5.3 | Growth is expected to decelerate as investments in clean coal technologies begin to take effect. |
| 2031 | 10.0 | The market is projected to peak as demand surges for sustainable mining practices and advanced technologies. |
| 2032 | 8.9 | Growth will slow as the 'Green Mining Development Plan' leads to regulatory adjustments. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Industrial Mining Market Synopsis
Industrial Mining in China encompasses the extraction of minerals and ores using advanced technologies and heavy machinery. Key operations include surface and underground mining, primarily supplying materials for construction and energy production. The China Industrial Mining Market is expanding due to strong demand from heavy manufacturing and energy sectors. In 2022, coal production reached over 3.8 billion tons, highlighting the sector's economic significance. Initiatives like the 'Mineral Resource Development Plan' are promoting sustainable practices and technological advancements in mining operations.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increased coal production driven by energy demands | Driver | High | Coal |
| Growing infrastructure investments in urban areas | Driver | High | Copper |
| Investment in clean coal technologies | Opportunity | High | Coal |
| Rising demand for sustainable mining practices | Opportunity | High | Iron Ore |
| Environmental regulations impacting operational efficiency | Restraint | High | Surface Mining |
| Challenges in resource management and sustainability | Restraint | Medium | Surface Mining |
| Safety compliance costs affecting profitability | Challenge | High | Surface Mining |
| Technological adaptation delays in mining operations | Challenge | Medium | Surface Mining |
Evaluation of Drivers in China Industrial Mining Market (2026–2032)
The main growth drivers and the segments they affect most are set out below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased coal production | Coal | Coal production reached over 3.8 billion tons in 2022, boosting demand from power generation sectors. |
| Rising infrastructure investments | Copper | China's copper consumption is projected to exceed 12 million tons annually, driven by infrastructure development in urban areas. |
| Investment in clean coal technologies | Coal | The government allocated 5 billion yuan for clean coal technologies, improving operational efficiency across the sector. |
| Growing demand for steel production | Iron Ore | China's iron ore production was around 300 million tons in 2022, primarily for domestic steel manufacturing. |
| Technological advancements in mining equipment | Excavators & Drills | The adoption of advanced machinery improves extraction efficiency, attracting investments in mining operations. |
The Industrial Mining market in China is growing due to increased investment in clean coal technologies, rising infrastructure investments, and advancements in mining equipment. At the same time, China's copper consumption is projected to exceed 12 million tons annually, driven by infrastructure development in urban areas. The adoption of advanced machinery, such as excavators and drills, is improving extraction efficiency, attracting more investments in mining operations. Additionally, the rising demand for steel production is driving iron ore production, which was around 300 million tons in 2022, mainly for domestic steel manufacturing.
Evaluation of Restraints in China Industrial Mining Market
Below mentioned are some major restraints and their influence on market dynamics.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Environmental regulations impacting operational efficiency | Surface Mining | Stricter regulations have increased compliance costs by over 15%, affecting operational efficiency in mining operations. |
| Challenges in resource management and sustainability | Surface Mining | Sustainability initiatives require investments exceeding 2 billion yuan, limiting immediate resource extraction capabilities. |
| Market fluctuations affecting demand stability | Heavy Industry | Volatility in heavy industry demand leads to uncertainties in mineral extraction and supply, impacting revenue by 10%. |
| Safety compliance costs affecting profitability | Surface Mining | Revised safety regulations increase operational costs by 20% for equipment manufacturers and operators. |
| Technological adaptation delays in mining operations | Surface Mining | Adoption of new technologies is slow, with a 30% delay in productivity improvements in mining processes. |
China Industrial Mining Market Challenges
China's industrial mining market still has to solve a few problems, starting with regulatory compliance, which imposes strict environmental standards that producers must meet. This results in increased operational costs, often exceeding 20% of total expenses for mining companies. Competition is another challenge, as domestic producers face pressure from cheaper imports, which can lead to reduced market share and profit margins for local firms. Buyers experience delays due to fluctuating supply chains, often waiting up to six weeks for essential materials. Skills shortages hinder productivity, with an estimated 30% of mining jobs remaining unfilled, impacting output for producers.
Trends in the China Industrial Mining Market
Buyers and suppliers in the China Industrial Mining Market are adjusting to the following trends.
- Shift Towards Sustainable Mining Practices: China's mining sector is increasingly adopting sustainable practices, driven by the 'Green Mining' initiative. In 2023, the government launched this initiative to reduce environmental impact, with over 20 national standards established since 2020.
- Transition to Advanced Mining Technologies: The mining industry is embracing advanced technologies to improve efficiency. The '13th Five-Year Plan for Mineral Resources' focuses on technological innovation, aiming for improved extraction methods and resource management.
- Emergence of Cleaner Coal Technologies: The focus on cleaner coal technologies is reshaping the coal mining sector. The 'Coal Industry Development Plan (2021-2025)' promotes cleaner technologies, with 5 billion yuan allocated for development.
- Increased Demand for Copper in Infrastructure: Rising infrastructure projects are driving copper demand in China. With consumption projected to exceed 12 million tons annually, the sector is prioritising copper sourcing for construction and electronics.
Investment Opportunities in the China Industrial Mining Market
Several openings in the China Industrial Mining Market merit attention from investors.
- Investment in Clean Coal Technologies: The opportunity to invest in clean coal technologies is substantial, with 5 billion yuan allocated for development. Buyers in the energy sector are seeking sustainable solutions to reduce emissions.
- Supply of Advanced Mining Equipment: With a projected growth in mining operations, the demand for advanced equipment is rising. Suppliers can target heavy industry buyers in major mining regions like Shanxi and Shaanxi.
- Development of Sustainable Mining Solutions: The push for sustainable mining practices presents an opportunity for suppliers of eco-friendly technologies. The 'Green Mining Development Plan' highlights the need for innovative solutions in the sector.
- Expansion of Infrastructure Projects: As infrastructure investments increase, there is a demand for raw materials. Suppliers can engage with construction firms in urban areas to meet rising mineral needs.
Government Initiatives in the China Industrial Mining Market
The 'Mineral Resources Law' updated in 2021 by the Ministry of Natural Resources enhances resource management and sustainability practices in mining. This law mandates stricter compliance for mining operations, ensuring responsible extraction and environmental protection. Additionally, the 'Environmental Protection Law' amended in 2022 imposes regulations that mining companies must adhere to, promoting sustainable practices and reducing ecological impact. These measures significantly affect how mining operations are conducted, pushing for cleaner technologies and improved safety standards.
The National Development and Reform Commission oversees the approval of mining projects and funds initiatives aimed at promoting sustainable practices. In 2023, the commission initiated the 'Green Mining Development Plan', which allocates resources for projects that enhance environmental protection in mining. The Ministry of Natural Resources also plays a key role in approving mining licenses and ensuring compliance with safety regulations. These agencies are instrumental in shaping the operational environment for mining companies in China.
Future Insight of the China Industrial Mining Market
The industrial mining market in China is expected to evolve by 2032, influenced by the 'Mineral Resource Development Plan' and the 'Green Mining' initiative. These programmes will improve sustainability and resource efficiency, benefiting both buyers and suppliers. The government's investment in clean technologies will promote innovation in mining practices, while advancements in automation will streamline operations. A focus on safety standards will enhance workforce training, ensuring a more skilled labour pool for the industry.
Market Segmentation Analysis
Each segment group is reviewed below, with the leader by share and the fastest grower by CAGR.
By Mining Method – Surface Mining Dominated, Underground Mining Expected to Grow Fastest
According to Sachin Kumar Rai, Senior Research Analyst at 6Wresearch, the largest mining method category in 2025 was Surface Mining, with a 52% share of total revenue. Surface mining holds the largest market share in China as it is the most effective method for large-scale mineral extraction, particularly in key regions like Shanxi and Shaanxi. This technique is favoured for its ability to efficiently access vast mineral deposits using advanced machinery. The quickest growth will come from Underground Mining, forecast to expand at a CAGR of 10.2% between 2026 and 2032. Underground mining is experiencing rapid growth, driven by the necessity to access deeper mineral deposits as surface resources diminish. The increasing demand for minerals in construction and manufacturing sectors is propelling this segment's swift expansion. Suppliers should focus on enhancing underground mining technologies to meet the rising demand for deeper resource extraction.
By Mineral Type – Coal Dominated, Copper Expected to Grow Fastest
Coal took a 38% share of mineral type in 2025, more than any other category. Coal leads the market share as the primary energy source for power generation in China, with production surpassing 3.8 billion tons in 2022. This substantial output underscores coal's critical role in fulfilling the country's energy requirements. Copper is projected to grow fastest, at a CAGR of 9.4% during 2026–2032. Copper is experiencing the fastest growth due to its essential applications in electrical and construction sectors, with consumption anticipated to exceed 12 million tons annually. This increase is largely driven by ongoing infrastructure development projects nationwide. Buyers should secure long-term contracts for copper to mitigate potential supply shortages as demand escalates.
By Equipment Type – Excavators & Drills Dominated, Loaders & Crushers Expected to Grow Fastest
In 2025, Excavators & Drills led the equipment type split with a 39% share. Excavators and drills dominate the market share, being crucial for mineral extraction processes across various mining operations. Their widespread application in large-scale projects underscores their importance within the industry. Loaders & Crushers are set to record the highest CAGR in this split, 9.8% over 2026–2032. Loaders and crushers are rapidly gaining market share, essential for the efficient processing of mined materials. As mining operations grow, the demand for effective material handling equipment is set to rise significantly. Suppliers must prioritise innovation in loader and crusher technologies to address the increasing processing demands of mining operations.
By Application Area – Ore Extraction Dominated, Mineral Transport Expected to Grow Fastest
With a 40% revenue share in 2025, Ore Extraction was the largest application area category. Ore extraction leads the market share as the fundamental activity in the mining sector, directly contributing to the supply of minerals. This essential process is critical for meeting the raw material requirements of multiple industries. Over 2026–2032, Mineral Transport is expected to post the fastest growth, at a CAGR of 10.2%. Mineral transport is the fastest-growing application area, driven by the need for efficient movement of materials to processing sites. The expansion of mining operations necessitates improved logistics for mineral transportation, ensuring timely delivery. Investing in advanced mineral transport solutions will be vital for suppliers to support the expanding mining sector.
By End User Industry – Heavy Industry Dominated, Metals and Minerals Expected to Grow Fastest
Heavy Industry accounted for a 39% market share by end user industry in 2025. Heavy industry is the largest end user, consuming a significant share of extracted minerals for manufacturing and construction purposes. This sector's dependence on raw materials solidifies its dominant position in the market. The quickest growth will come from Metals and Minerals, forecast to expand at a CAGR of 10.0% between 2026 and 2032. The metals and minerals industry is witnessing the fastest growth, closely linked to the output of the mining sector. As the demand for metal products rises, this segment is well-positioned for substantial expansion. Suppliers should align their strategies with the metals and minerals industry to capitalise on the increasing demand for mined resources.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Industrial Mining Market Outlook
- Market Size of China Industrial Mining Market, 2025
- Forecast of China Industrial Mining Market, 2032
- Historical Data and Forecast of China Industrial Mining Revenues & Volume for the Period 2022 - 2032F
- China Industrial Mining Market Trend Evolution
- China Industrial Mining Market Drivers and Challenges
- China Industrial Mining Price Trends
- China Industrial Mining Porter's Five Forces
- China Industrial Mining Industry Life Cycle
- Historical Data and Forecast of China Industrial Mining Market Revenues & Volume By Mining Method for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Mining Market Revenues & Volume By Surface Mining for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Mining Market Revenues & Volume By Underground Mining for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Mining Market Revenues & Volume By Placer Mining for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Mining Market Revenues & Volume By Mountaintop Removal for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Mining Market Revenues & Volume By Mineral Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Mining Market Revenues & Volume By Iron Ore for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Mining Market Revenues & Volume By Copper for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Mining Market Revenues & Volume By Gold for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Mining Market Revenues & Volume By Coal for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Mining Market Revenues & Volume By Equipment Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Mining Market Revenues & Volume By Excavators & Drills for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Mining Market Revenues & Volume By Conveying Equipment for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Mining Market Revenues & Volume By Screening Equipment for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Mining Market Revenues & Volume By Loaders & Crushers for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Mining Market Revenues & Volume By Application Area for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Mining Market Revenues & Volume By Ore Extraction for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Mining Market Revenues & Volume By Mineral Transport for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Mining Market Revenues & Volume By Precious Metal Recovery for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Mining Market Revenues & Volume By Energy Generation for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Mining Market Revenues & Volume By End User Industry for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Mining Market Revenues & Volume By Heavy Industry for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Mining Market Revenues & Volume By Metals and Minerals for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Mining Market Revenues & Volume By Consumer Staples for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Mining Market Revenues & Volume By Power, Utility and Oil & Gas for the Period 2022 - 2032F
- China Industrial Mining Import Export Trade Statistics
- Market Opportunity Assessment By Mining Method
- Market Opportunity Assessment By Mineral Type
- Market Opportunity Assessment By Equipment Type
- Market Opportunity Assessment By Application Area
- Market Opportunity Assessment By End User Industry
- China Industrial Mining Top Companies Market Share
- China Industrial Mining Competitive Benchmarking By Technical and Operational Parameters
- China Industrial Mining Company Profiles
- China Industrial Mining Key Strategic Recommendations
Market Covered
The report offers an extensive study of the following market segments.
By Mining Method
- Surface Mining
- Underground Mining
- Placer Mining
- Mountaintop Removal
By Mineral Type
- Iron Ore
- Copper
- Gold
- Coal
By Equipment Type
- Excavators & Drills
- Conveying Equipment
- Screening Equipment
- Loaders & Crushers
By Application Area
- Ore Extraction
- Mineral Transport
- Precious Metal Recovery
- Energy Generation
By End User Industry
- Heavy Industry
- Metals and Minerals
- Consumer Staples
- Power
- Utility and Oil & Gas































