China Red Teaming Services Market Size & Growth Rate
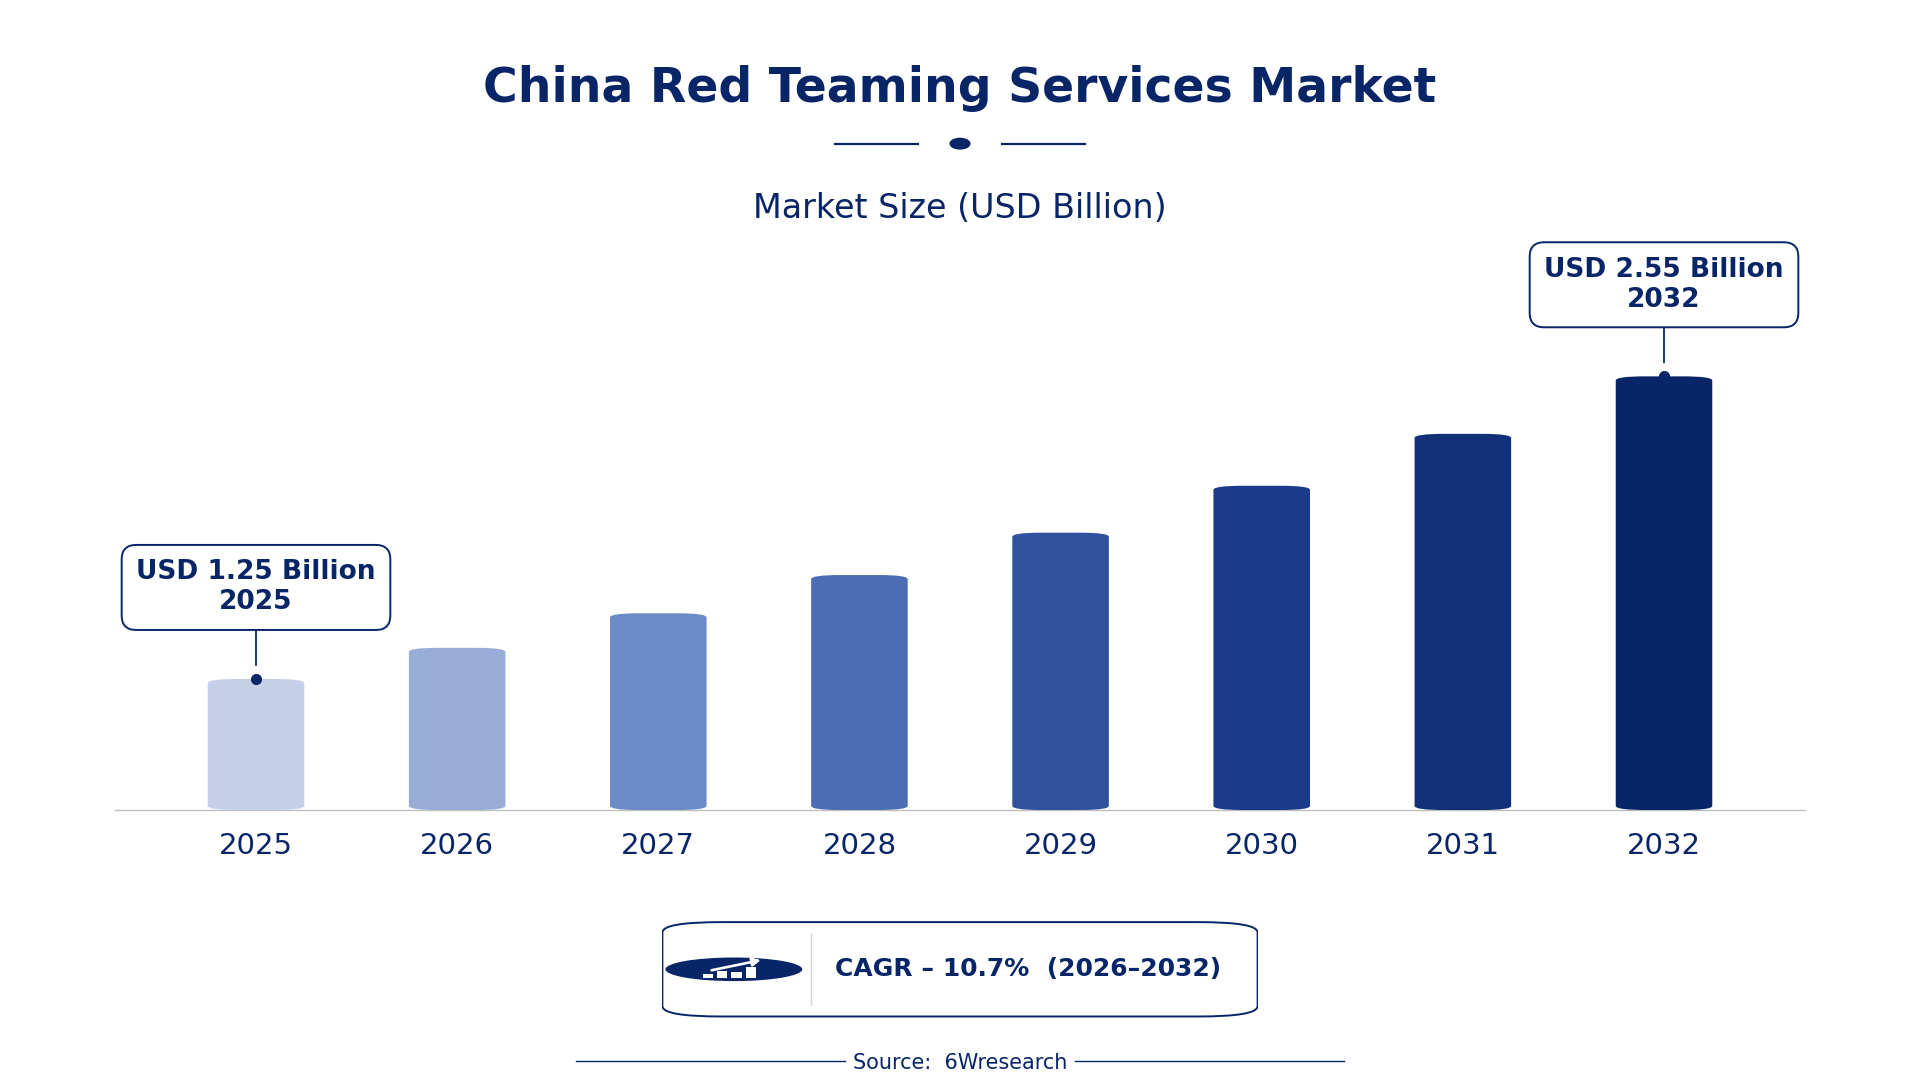
According to 6Wresearch internal database and industry insights, the China Red Teaming Services Market was valued at USD 1.25 billion in 2025 and is projected to reach USD 2.55 billion by 2032, growing at a CAGR of approximately 10.7% during 2026–2032.
China Red Teaming Services Market Highlights
| Report Metric | Details |
| Report Name | China Red Teaming Services Market |
| Market Size 2025 | USD 1.25 billion |
| Market Size 2032 | USD 2.55 billion |
| Absolute Growth 2025–2032 | USD 1.30 billion |
| CAGR 2026–2032 | 10.7% |
| Peak Annual Growth | 12.7% in 2032 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Service Type, 2025 | External Pen Testing (43% share) |
| Leading Simulation Type, 2025 | Covert Testing (40% share) |
| Leading Delivery Mode, 2025 | Onsite/Remote (43% share) |
| Leading End User, 2025 | Enterprises & Governments (41% share) |
| Fastest-Growing Service Type | Adversary-Based Simulation (11.7% CAGR) |
| Fastest-Growing Simulation Type | Phishing & Physical Entry (11.9% CAGR) |
| Fastest-Growing Delivery Mode | Hybrid (12.1% CAGR) |
| Fastest-Growing End User | Cybersecurity-aware Firms (13.2% CAGR) |
| Growing Sector | Cybersecurity |
| Key End Users | Enterprises, Government Agencies, Financial Institutions, Defense Contractors |
China Red Teaming Services Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
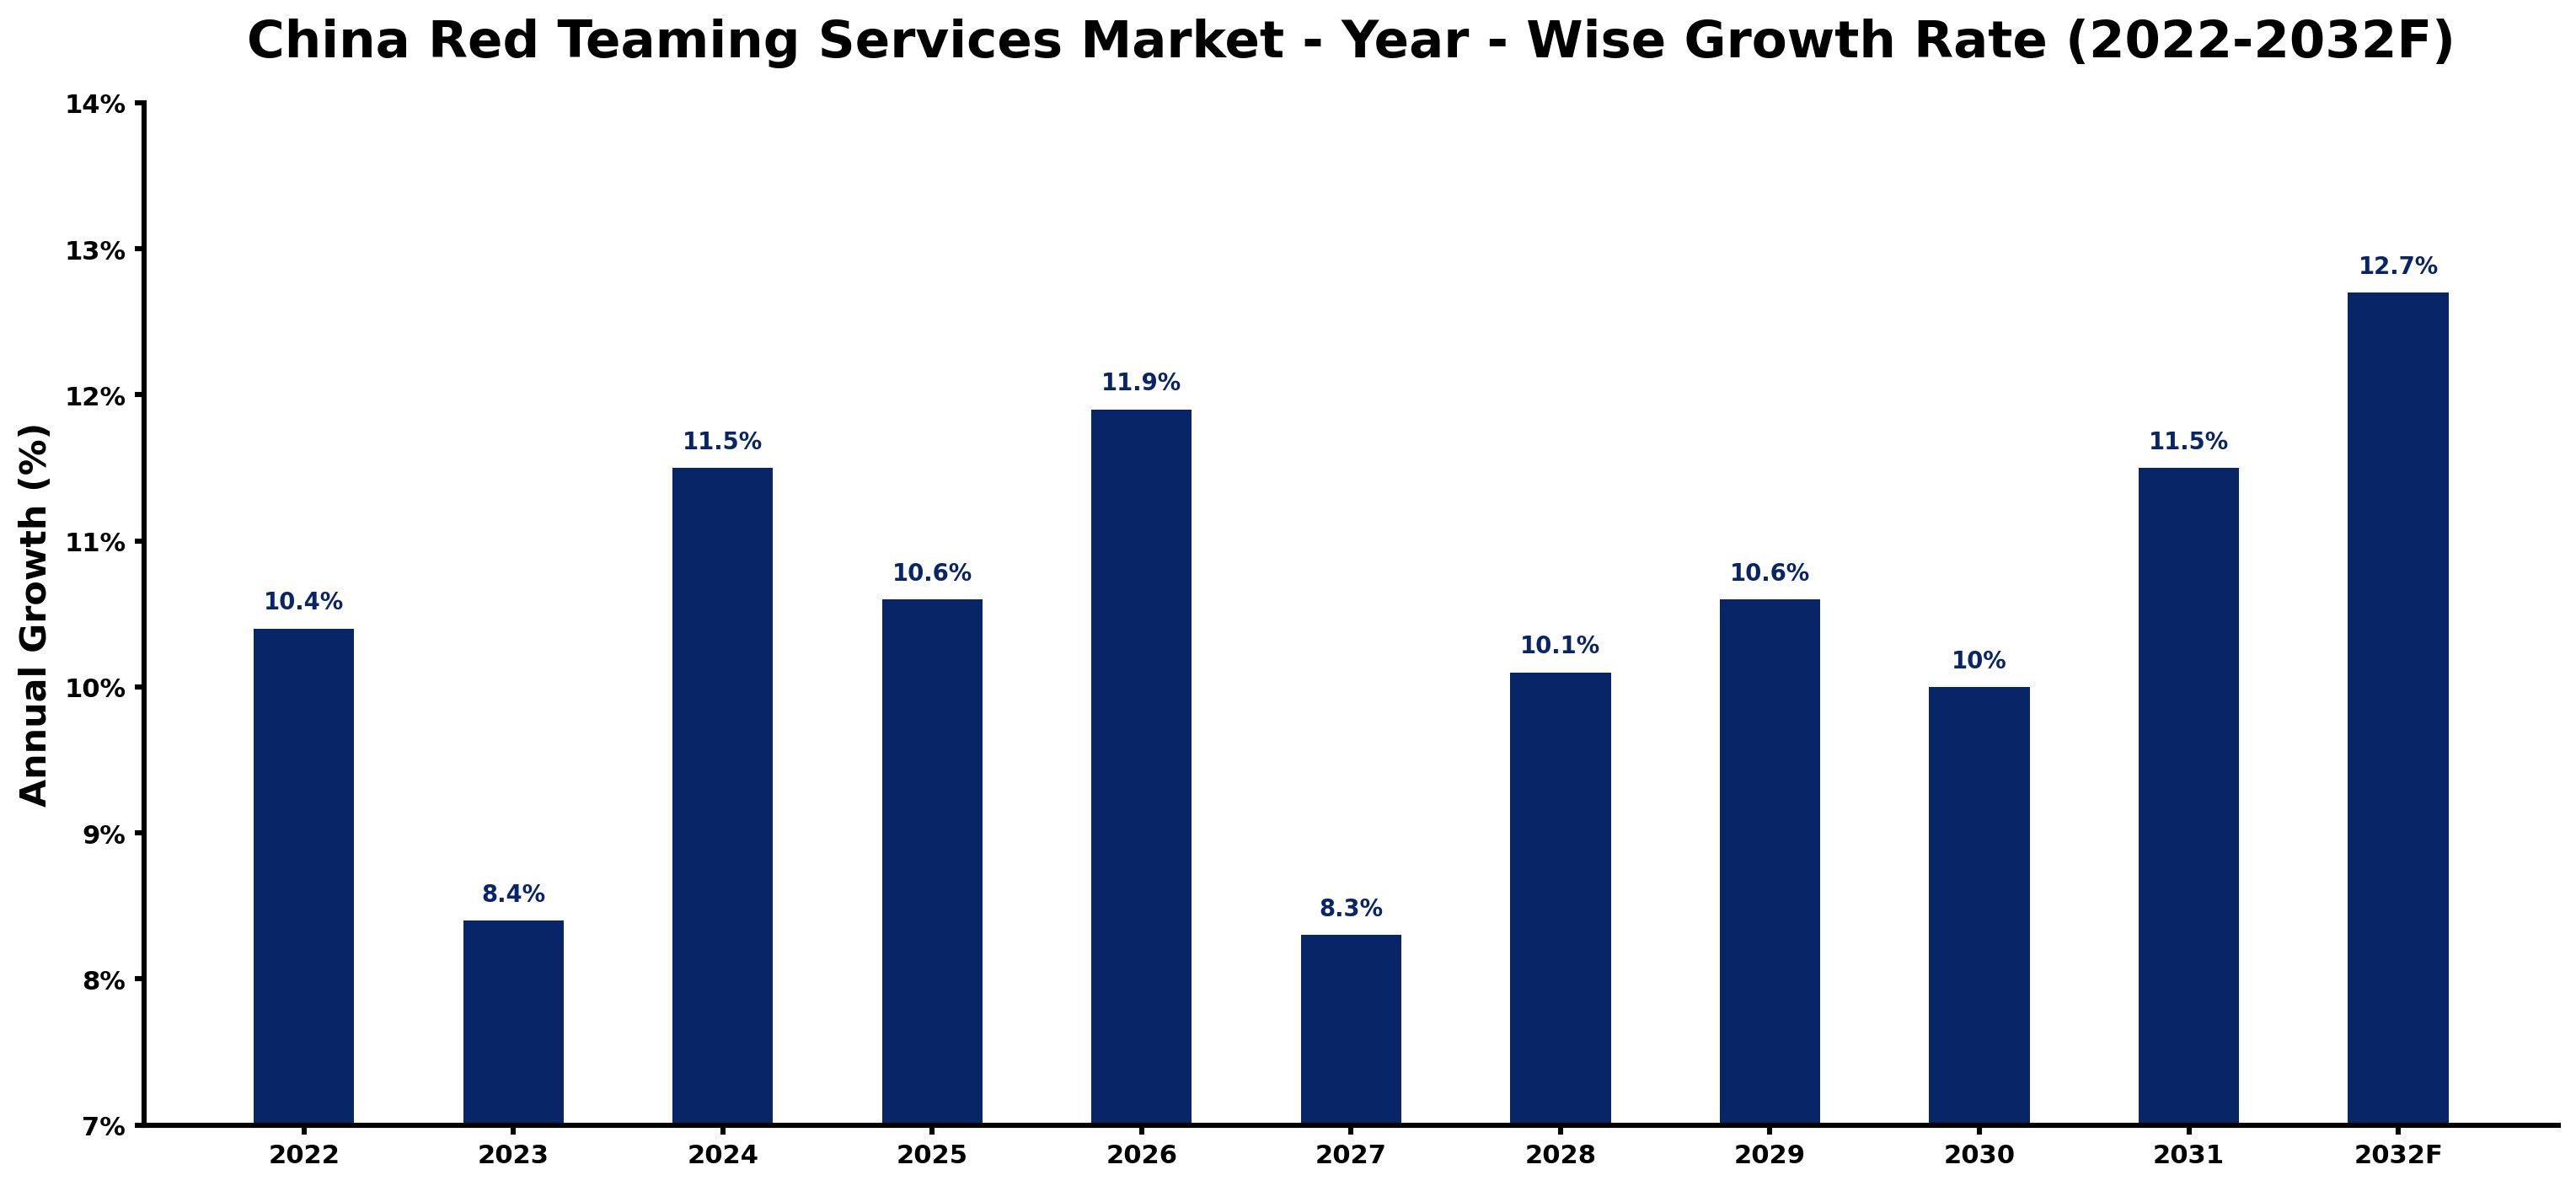
The table below sets out the estimated growth rate for each year and the main factor behind it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 10.4 | The market showed strong demand from enterprises adopting cybersecurity measures. |
| 2023 | 8.4 | Growth slowed as the Cybersecurity Improvement Program initiated by the Ministry of Industry and Information Technology began to take effect. |
| 2024 | 11.5 | Demand surged due to the National Cybersecurity Strategy promoting cybersecurity practices. |
| 2025 | 10.6 | Growth decelerated as firms reassessed their cybersecurity budgets amid economic pressures. |
| 2026 | 11.9 | Investment in cybersecurity infrastructure is expected to drive demand for red teaming services. |
| 2027 | 8.3 | A slowdown in growth is anticipated as firms consolidate their security strategies. |
| 2028 | 10.1 | Increased awareness of cyber threats is projected to boost demand for red teaming, supported by the Cybersecurity Talent Development Program. |
| 2029 | 10.6 | Demand growth is expected to rise as firms seek to enhance security measures. |
| 2030 | 10.0 | Growth is projected to slow as the Cybersecurity Law requires regular assessments. |
| 2031 | 11.5 | Demand is expected to increase as enterprises adopt advanced cybersecurity protocols. |
| 2032 | 12.7 | The market is projected to peak as red teaming becomes integral to security strategies. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Red Teaming Services Market Synopsis
Red Teaming Services in China involve simulated cyber attacks to test and strengthen security systems. These services are crucial for improving cybersecurity for enterprises and government agencies, while also training personnel in threat detection. The China Red Teaming Services Market is expanding due to rising cyber threats and strong contributions from domestic users and government initiatives. In 2023, over 70% of large enterprises adopted red teaming exercises, reflecting robust demand. Support from government initiatives and a growing number of cybersecurity firms are further driving this expansion.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Government initiatives promoting cybersecurity practices are increasing demand for red teaming services. | Driver | High | Enterprises & Governments |
| The rise in cyber threats is driving organizations to seek red teaming services for vulnerability assessments. | Driver | High | Financial & Critical Infrastructure |
| The growing need for cybersecurity training presents opportunities for red teaming service providers. | Opportunity | High | Cybersecurity-aware Firms |
| Investment in cybersecurity infrastructure is creating demand for red teaming services. | Opportunity | Medium | Defense Contractors |
| High costs associated with red teaming services may limit access for smaller firms. | Restraint | High | Cybersecurity-aware Firms |
| Limited awareness of red teaming benefits among some enterprises may hinder market growth. | Restraint | Medium | Enterprises & Governments |
| Buyers face challenges in finding qualified red teaming providers that meet their needs. | Challenge | High | Financial & Critical Infrastructure |
| Suppliers encounter difficulties in keeping up with evolving cybersecurity threats and technologies. | Challenge | Medium | Enterprises & Governments |
Evaluation of Drivers in China Red Teaming Services Market (2026–2032)
Below mentioned are some major drivers and their influence on market dynamics.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Government initiatives such as the National Cybersecurity Strategy promote red teaming practices. | Enterprises & Governments | This drives demand as organizations align with national security priorities, with over 1,000 firms providing these services. |
| The increasing frequency of cyber attacks compels organizations to adopt red teaming services. | Financial & Critical Infrastructure | This necessity leads to higher investments in security assessments, with over 60% of financial institutions utilizing these services. |
| The Cybersecurity Talent Development Program aims to train specialists, improving service quality. | Cybersecurity-aware Firms | This results in better red teaming capabilities and service offerings, addressing the skills gap in the industry. |
| Growing awareness of the importance of cybersecurity among enterprises is driving red teaming adoption. | Defense Contractors | This trend leads to increased budgets for security assessments and training, as firms invest more in protective measures. |
| The average cost of red teaming services ranges from 100,000 to 500,000 CNY per engagement. | Cybersecurity-aware Firms | This pricing structure influences purchasing decisions among enterprises, making it essential to balance cost and quality. |
The Red Teaming Services market in China is growing on the back of increased investment in cybersecurity infrastructure, rising end-user demand, and support from initiatives like the Cybersecurity Improvement Program. In 2023, over 70% of large enterprises adopted red teaming exercises, reflecting a trend towards improved security measures. The Cybersecurity Improvement Program, initiated in 2022, allocated 300 million CNY to support red teaming initiatives. As organizations face a surge in cyber threats, the need for effective vulnerability assessments becomes critical, prompting more enterprises to invest in red teaming services. This growing recognition of the importance of red teaming is driving further demand among enterprises and government agencies.
Evaluation of Restraints in China Red Teaming Services Market
The following restraints limit how fast demand can grow.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| High costs of red teaming services limit access for smaller enterprises. | Cybersecurity-aware Firms | The average cost ranges from 100,000 to 500,000 CNY, making it prohibitive for some. |
| Limited awareness of red teaming benefits may hinder market growth among enterprises. | Enterprises & Governments | Many organizations are still unfamiliar with the potential advantages of these services. |
| Shortage of qualified red teaming professionals affects service quality and availability. | Financial & Critical Infrastructure | The demand for skilled personnel exceeds the current supply, impacting service delivery. |
| Regulatory compliance requirements can complicate red teaming engagements for firms. | Defense Contractors | Organizations must navigate complex regulations, which can delay assessments. |
| Market fragmentation leads to inconsistencies in service quality across providers. | Cybersecurity-aware Firms | With over 1,000 firms in the market, quality assurance becomes challenging. |
China Red Teaming Services Market Challenges
In the China Red Teaming Services market, high service costs pose a barrier for buyers, with average engagements costing between 100,000 and 500,000 CNY, making it difficult for smaller enterprises to afford these critical assessments. Intense competition among over 1,000 cybersecurity firms leads to aggressive pricing strategies, which can result in compromised quality and diminished trust for buyers seeking reliable services. Regulatory changes, particularly the updated Cybersecurity Law in 2023, impose strict compliance requirements that can delay service delivery, negatively affecting the security readiness of organizations. A shortage of skilled professionals trained in red teaming techniques further restricts service availability, leading to longer wait times for assessments and heightened vulnerability to cyber threats for many firms.
Trends in the China Red Teaming Services Market
Four trends stand out in the China Red Teaming Services Market.
- Shift from Traditional Security Assessments to Red Teaming: Since 2021, organizations have increasingly adopted red teaming over traditional assessments, recognising its effectiveness in identifying vulnerabilities. Over 70% of large enterprises now utilise these services, reflecting a shift in approach.
- Rise in Demand for Covert Testing: In 2023, Covert Testing emerged as a leading simulation type, capturing 40% of the market share. This trend highlights the need for unannounced assessments to improve security protocols.
- Increased Focus on Cybersecurity Training: The Cybersecurity Talent Development Program launched in 2022 aims to train 10,000 professionals by 2025. This initiative addresses the skills gap in red teaming services, ensuring a qualified workforce.
- Growing Adoption of Hybrid Delivery Models: As of 2025, Hybrid delivery models are expected to grow rapidly, with a projected CAGR of 12.1%. This trend reflects the need for flexible service options to meet diverse client requirements.
Investment Opportunities in the China Red Teaming Services Market
Below are the investment opportunities with the strongest case in the China Red Teaming Services Market.
- Investment in Cybersecurity Infrastructure: With 500 million CNY allocated for cybersecurity initiatives in 2023, there is an opportunity for red teaming service providers to engage with government projects and improve their offerings.
- Growing Demand from Financial Institutions: Over 60% of financial institutions in China utilise red teaming services, presenting an opportunity for providers to tailor their services to this critical sector.
- Forming Alliances with Cybersecurity Firms: Now is an ideal time for new entrants to form partnerships with established cybersecurity firms, leveraging their expertise to penetrate the market effectively.
- Expansion into Emerging Markets: As demand for red teaming services grows, firms should consider entering emerging markets, particularly in Beijing and Shanghai, where cybersecurity needs are escalating.
Government Initiatives in the China Red Teaming Services Market
The National Cybersecurity Strategy 2021 mandates improved red teaming practices for critical infrastructure protection, significantly driving growth in the sector. In 2022, the Ministry of Industry and Information Technology launched the Cybersecurity Improvement Program with a budget of 300 million CNY, aimed at supporting red teaming initiatives. This program ensures that funds are allocated effectively to enhance security measures across various sectors. The Cybersecurity Talent Development Program, initiated in 2022, aims to train 10,000 cybersecurity professionals by 2025, addressing the industry's skills gap and improving service quality.
The Cybersecurity Law of 2023, enforced by the National People's Congress, requires regular red team assessments for all major enterprises. This law ensures compliance and improved security for organizations, compelling them to adopt red teaming practices. The Ministry of Education also plays a role in implementing training programs, while the National Information Security Standardization Technical Committee published guidelines in 2023 for effective red teaming practices across industries, further supporting the sector.
Future Insight of the China Red Teaming Services Market
Several forward-looking factors should support the China Red Teaming Services market by 2032. The government’s allocation of 500 million CNY for cybersecurity initiatives will enhance service quality and accessibility across the sector. The Cybersecurity Talent Development Program, launched in 2022, is expected to significantly boost the number of trained specialists, addressing the skills gap. As over 70% of large enterprises adopt regular red teaming exercises, there will be an increasing emphasis on implementing best practices and adhering to established standards, ultimately improving overall cybersecurity resilience.
Market Segmentation Analysis
The report offers a comprehensive study of the following market segments and their leading categories in the market.
By Service Type – External Pen Testing Dominated, Adversary-Based Simulation Expected to Grow Fastest
According to Ravi Bhandari, Research Head at 6Wresearch, with a 43% revenue share in 2025, External Pen Testing was the largest service type category. External Pen Testing holds the largest market share as it is vital for identifying vulnerabilities in security systems, particularly for enterprises and government agencies. With over 1,000 cybersecurity firms in China, the supply of these services is robust and well-established. The quickest growth will come from Adversary-Based Simulation, forecast to expand at a CAGR of 11.7% between 2026 and 2032. Adversary-Based Simulation is experiencing rapid growth due to its effectiveness in mimicking real-world attacks, which enhances personnel training and preparedness. This method is increasingly sought after as organisations recognise the need for practical threat detection and response strategies. Suppliers must focus on enhancing their external pen testing offerings to align with the growing demand from enterprises and government clients.
By Simulation Type – Covert Testing Dominated, Phishing & Physical Entry Expected to Grow Fastest
Covert Testing accounted for a 40% market share by simulation type in 2025. Covert Testing leads the market because it enables security assessments without prior notice, which is crucial for organisations aiming to identify weaknesses in their systems. This approach is particularly favoured by enterprises that prioritise improving their security posture. Over 2026–2032, Phishing & Physical Entry is expected to post the fastest growth, at a CAGR of 11.9%. Phishing & Physical Entry is the fastest-growing segment, driven by the urgent need to test responses to social engineering attacks. As cyber threats become more sophisticated, the demand for these simulations continues to rise significantly. Buyers should prioritise covert testing and phishing simulations to ensure comprehensive security assessments against evolving threats.
By Delivery Mode – Onsite/Remote Dominated, Hybrid Expected to Grow Fastest
Onsite/Remote held a 43% share of the China Red Teaming Services Market by delivery mode in 2025. Onsite/Remote services dominate the market due to their flexibility in catering to diverse client needs, enabling tailored security assessments. This adaptability is vital for enterprises and government agencies with varying operational requirements. Hybrid is projected to grow fastest, at a CAGR of 12.1% during 2026–2032. Hybrid delivery modes are gaining popularity as they combine the advantages of onsite and remote methods, improving efficiency in service provision. Clients increasingly seek cost-effective solutions that this model offers. Suppliers must invest in hybrid service models to meet the growing preference for flexible delivery options among clients.
By End User – Enterprises & Governments Dominated, Cybersecurity-aware Firms Expected to Grow Fastest
Enterprises & Governments took a 41% share of end user in 2025, more than any other category. Enterprises & Governments represent the largest share of the market, being the primary users of red teaming services for enhancing their security measures. Their substantial investments in cybersecurity initiatives underscore the critical nature of these services in safeguarding sensitive information. Cybersecurity-aware Firms are set to record the highest CAGR in this split, 13.2% over 2026–2032. Cybersecurity-aware Firms are the fastest-growing segment, actively seeking red teaming to strengthen their defences against cyber threats. This trend reflects a broader movement towards increased awareness and proactive measures in the cybersecurity landscape. Suppliers should target cybersecurity-aware firms to capitalise on the increasing demand for red teaming services across various sectors.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Red Teaming Services Market Outlook
- Market Size of China Red Teaming Services Market, 2025
- Forecast of China Red Teaming Services Market, 2032
- Historical Data and Forecast of China Red Teaming Services Revenues & Volume for the Period 2022 - 2032F
- China Red Teaming Services Market Trend Evolution
- China Red Teaming Services Market Drivers and Challenges
- China Red Teaming Services Price Trends
- China Red Teaming Services Porter's Five Forces
- China Red Teaming Services Industry Life Cycle
- Historical Data and Forecast of China Red Teaming Services Market Revenues & Volume By Service Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Red Teaming Services Market Revenues & Volume By External Pen Testing for the Period 2022 - 2032F
- Historical Data and Forecast of China Red Teaming Services Market Revenues & Volume By Social Engineering for the Period 2022 - 2032F
- Historical Data and Forecast of China Red Teaming Services Market Revenues & Volume By Adversary-Based Simulation for the Period 2022 - 2032F
- Historical Data and Forecast of China Red Teaming Services Market Revenues & Volume By Purple Team Exercises for the Period 2022 - 2032F
- Historical Data and Forecast of China Red Teaming Services Market Revenues & Volume By Simulation Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Red Teaming Services Market Revenues & Volume By Covert Testing for the Period 2022 - 2032F
- Historical Data and Forecast of China Red Teaming Services Market Revenues & Volume By Phishing & Physical Entry for the Period 2022 - 2032F
- Historical Data and Forecast of China Red Teaming Services Market Revenues & Volume By APT Emulation for the Period 2022 - 2032F
- Historical Data and Forecast of China Red Teaming Services Market Revenues & Volume By Collaborative Defense for the Period 2022 - 2032F
- Historical Data and Forecast of China Red Teaming Services Market Revenues & Volume By Delivery Mode for the Period 2022 - 2032F
- Historical Data and Forecast of China Red Teaming Services Market Revenues & Volume By Onsite/Remote for the Period 2022 - 2032F
- Historical Data and Forecast of China Red Teaming Services Market Revenues & Volume By Red Team Engagement for the Period 2022 - 2032F
- Historical Data and Forecast of China Red Teaming Services Market Revenues & Volume By Hybrid for the Period 2022 - 2032F
- Historical Data and Forecast of China Red Teaming Services Market Revenues & Volume By Remote/In-House for the Period 2022 - 2032F
- Historical Data and Forecast of China Red Teaming Services Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Red Teaming Services Market Revenues & Volume By Enterprises & Governments for the Period 2022 - 2032F
- Historical Data and Forecast of China Red Teaming Services Market Revenues & Volume By Financial & Critical Infrastructure for the Period 2022 - 2032F
- Historical Data and Forecast of China Red Teaming Services Market Revenues & Volume By Cybersecurity-aware Firms for the Period 2022 - 2032F
- Historical Data and Forecast of China Red Teaming Services Market Revenues & Volume By Defense Contractors for the Period 2022 - 2032F
- China Red Teaming Services Import Export Trade Statistics
- Market Opportunity Assessment By Service Type
- Market Opportunity Assessment By Simulation Type
- Market Opportunity Assessment By Delivery Mode
- Market Opportunity Assessment By End User
- China Red Teaming Services Top Companies Market Share
- China Red Teaming Services Competitive Benchmarking By Technical and Operational Parameters
- China Red Teaming Services Company Profiles
- China Red Teaming Services Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By Service Type
- External Pen Testing
- Social Engineering
- Adversary-Based Simulation
- Purple Team Exercises
By Simulation Type
- Covert Testing
- Phishing & Physical Entry
- APT Emulation
- Collaborative Defense
By Delivery Mode
- Onsite/Remote
- Red Team Engagement
- Hybrid
- Remote/In-House
By End User
- Enterprises & Governments
- Financial & Critical Infrastructure
- Cybersecurity-aware Firms
- Defense Contractors































