China Sandblasting Equipment Market Size & Growth Rate
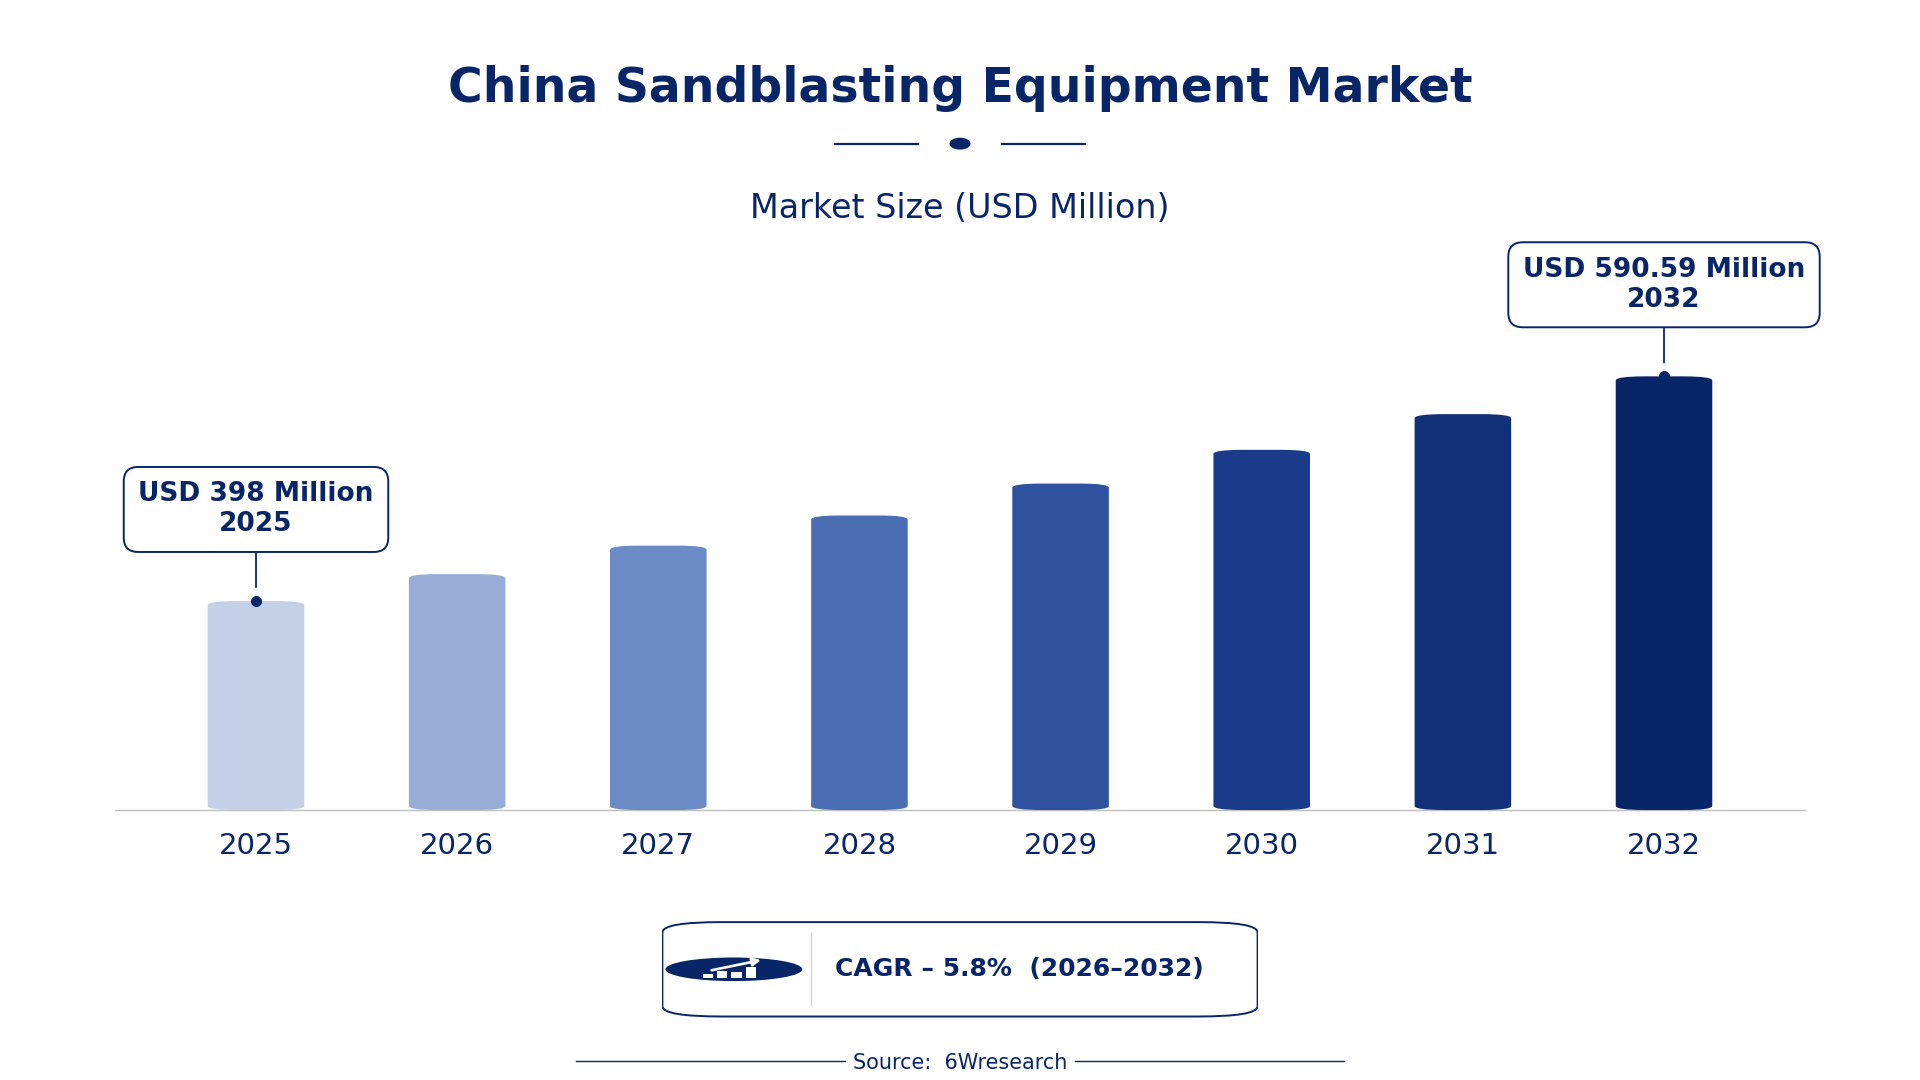
According to 6Wresearch internal database and industry insights, the China Sandblasting Equipment Market was valued at USD 398.0 million in 2025 and is projected to reach USD 590.59 million by 2032, growing at a CAGR of approximately 5.8% during 2026–2032.
China Sandblasting Equipment Market Highlights
| Report Metric | Details |
| Report Name | China Sandblasting Equipment Market |
| Market Size 2025 | USD 398.0 million |
| Market Size 2032 | USD 590.59 million |
| Absolute Growth 2025–2032 | USD 192.59 million |
| CAGR 2026–2032 | 5.8% |
| Peak Annual Growth | 7.6% in 2032 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Equipment Type, 2025 | Portable Blasters (45% share) |
| Leading Blasting Media, 2025 | Grit/Glass Beads (48% share) |
| Leading Power Source, 2025 | Pneumatic (40% share) |
| Leading End User, 2025 | Automotive Refurbishers (42% share) |
| Fastest-Growing Equipment Type | Cabinet Blasters (7.1% CAGR) |
| Fastest-Growing Blasting Media | Aluminum Oxide (7.1% CAGR) |
| Fastest-Growing Power Source | Electric (8.5% CAGR) |
| Fastest-Growing End User | Metal Fabricators (7.5% CAGR) |
| Growing Sector | Automotive |
| Key End Users | Automotive Refurbishers, Metal Fabricators, Aerospace Industry, Marine Industry |
China Sandblasting Equipment Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
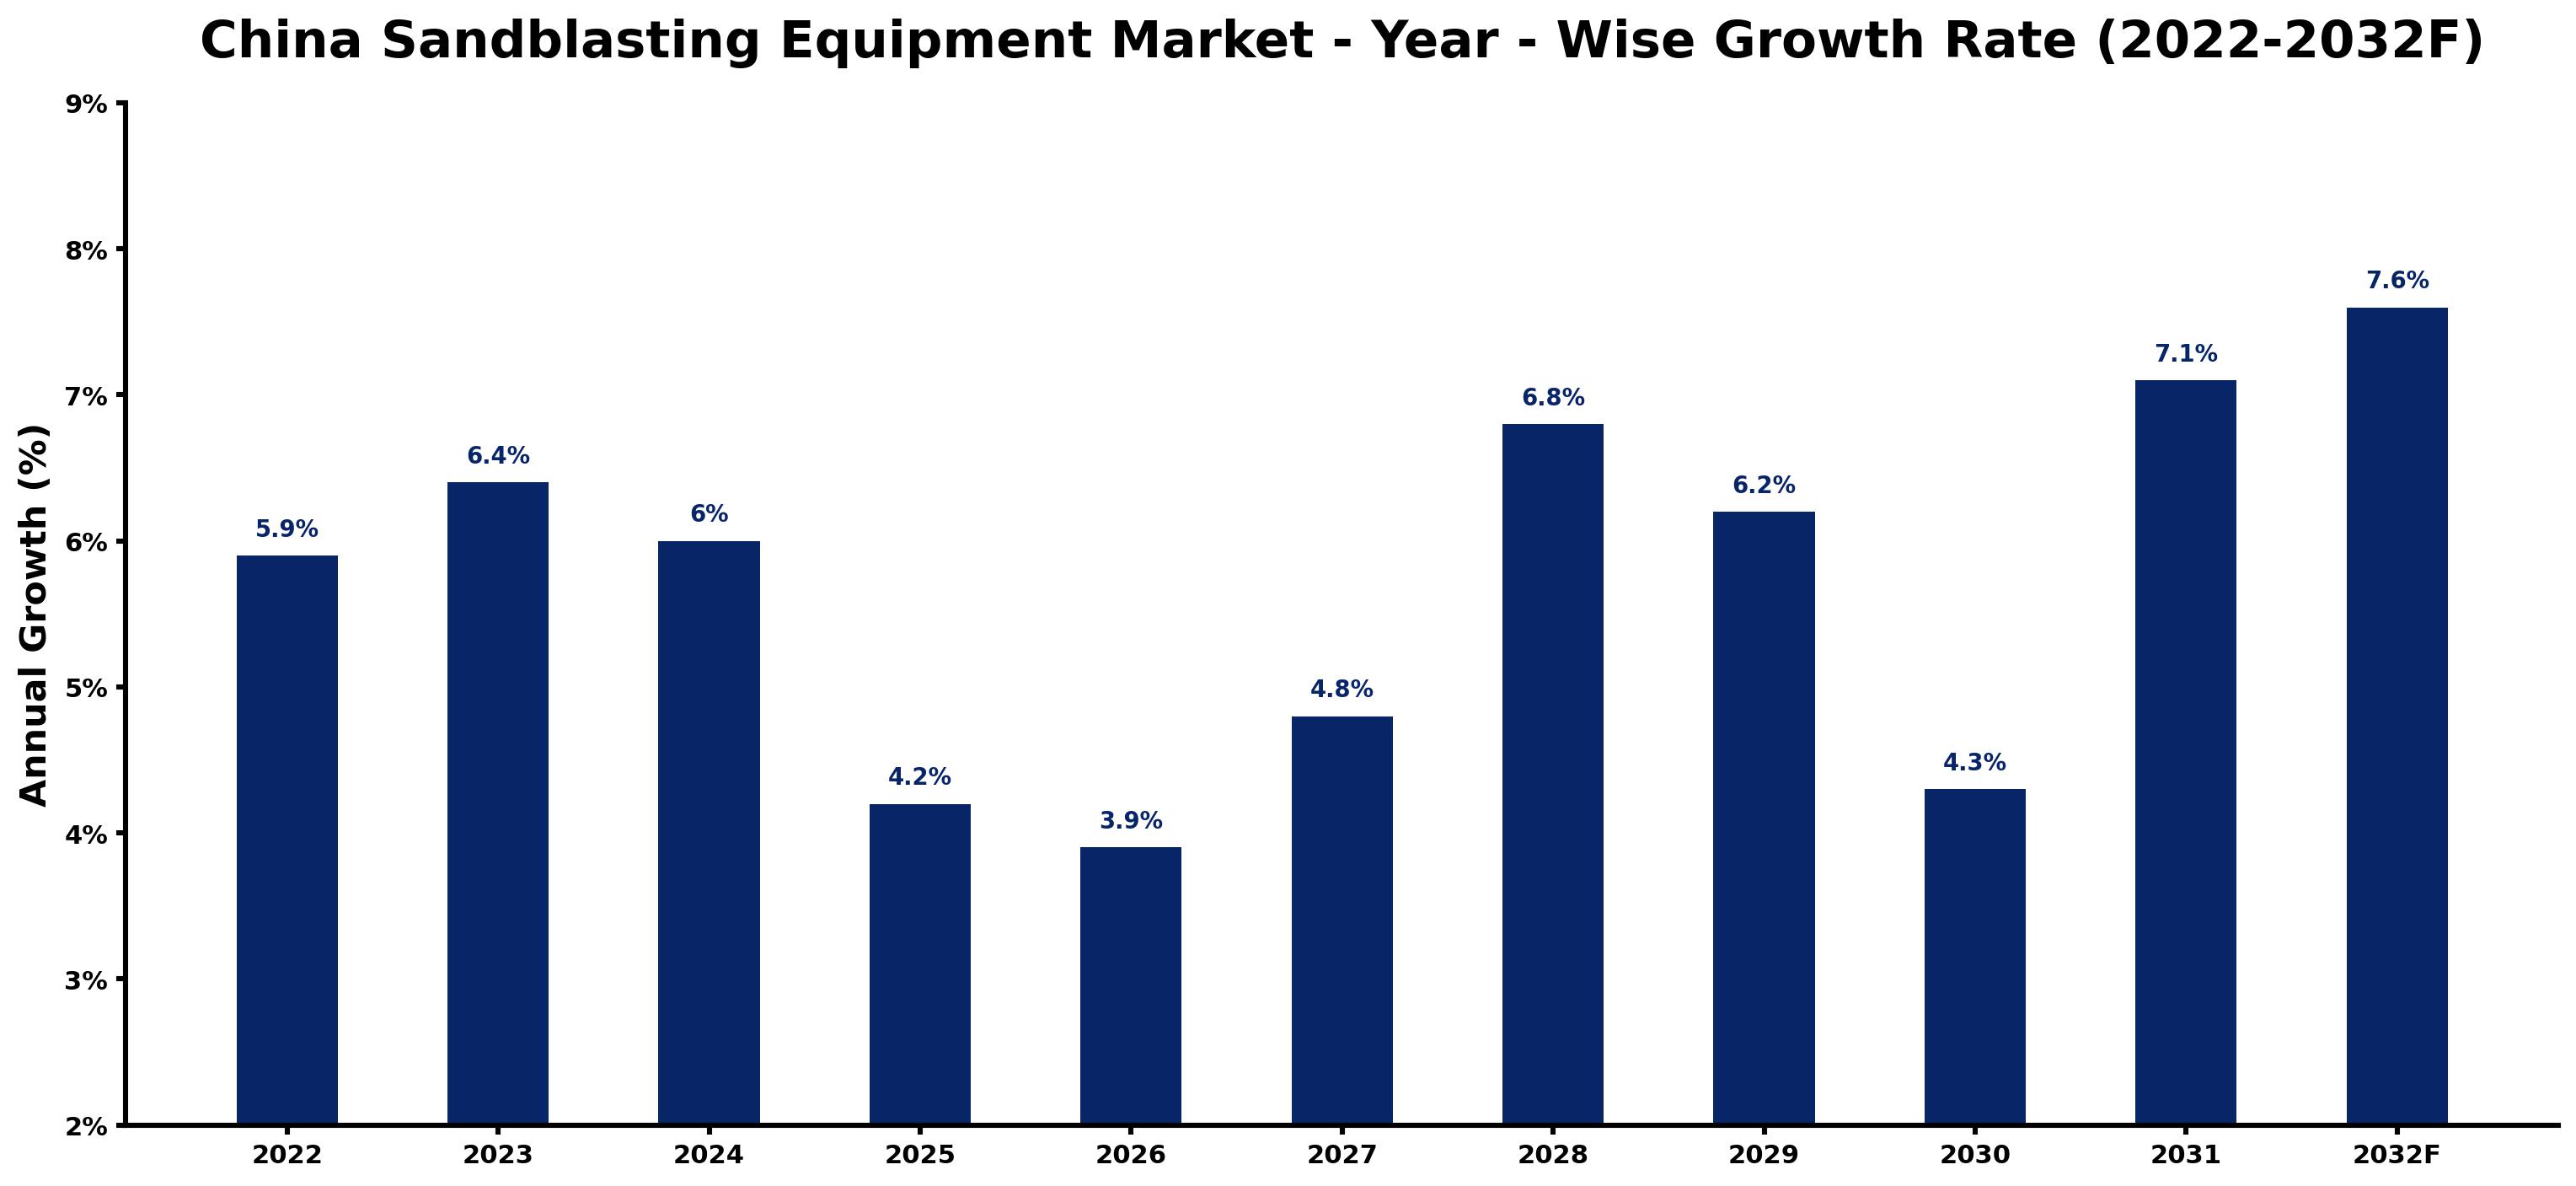
Each row of the following table gives one year's estimated growth and the event or demand shift that explains it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 5.9 | The market experienced steady demand from the automotive sector, reflecting ongoing restoration projects. |
| 2023 | 6.4 | Growth was driven by increased production in the automotive industry, with over 30 million vehicles projected by 2025. |
| 2024 | 6.0 | The market saw a slowdown as demand stabilised following the previous year's surge in automotive projects. |
| 2025 | 4.2 | Demand continued to grow, albeit at a slower pace, influenced by ongoing investments in metal fabrication. |
| 2026 | 3.9 | A further slowdown occurred as the market adjusted to the previous high levels of demand and investment. |
| 2027 | 4.8 | Growth accelerated again due to rising demand from metal fabricators seeking to enhance production efficiency. |
| 2028 | 6.8 | The market experienced a significant uptick as the aerospace sector expanded, driving demand for precision sandblasting. |
| 2029 | 6.2 | Growth slowed slightly as the market adjusted to the rapid expansion in the previous year. |
| 2030 | 4.3 | Demand remained steady but slowed due to market saturation in certain segments. |
| 2031 | 7.1 | A resurgence in growth was observed as the automotive sector ramped up production and restoration efforts. |
| 2032 | 7.6 | The market peaked with strong demand from various industries, supported by technological advancements. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Sandblasting Equipment Market Synopsis
Sandblasting Equipment in China includes technologies for surface preparation and cleaning through abrasive blasting. This equipment is crucial in industries like automotive, metal fabrication, and aerospace. The China Sandblasting Equipment Market is on an upward trend, driven by rising demand from domestic users and substantial investments in manufacturing sectors. The automotive industry, expected to surpass 30 million vehicles by 2025, serves as a primary source of demand. Furthermore, initiatives such as the 'Advanced Manufacturing 2025' programme are promoting automation, which further stimulates demand for sandblasting equipment.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Growing demand from the automotive sector for vehicle restoration and surface preparation. | Driver | High | Automotive Refurbishers |
| Increased investments in metal fabrication technologies enhancing production efficiency. | Driver | High | Metal Fabricators |
| The rise of environmental regulations necessitating advanced sandblasting technologies. | Opportunity | Medium | Wet Sandblasters |
| The growing aerospace sector requiring precision sandblasting for component preparation. | Opportunity | High | Aerospace Industry |
| High costs associated with robotic blasting units limiting adoption among small manufacturers. | Restraint | High | Robotic Blasting Units |
| Environmental regulations impacting the use of traditional blasting media. | Restraint | Medium | Portable Blasters |
| Supply chain disruptions affecting the availability of key components for sandblasting equipment. | Challenge | High | Portable Blasters |
| The need for continuous technological upgrades to meet market demands and standards. | Challenge | Medium | Portable Blasters |
Evaluation of Drivers in China Sandblasting Equipment Market (2026–2032)
The table below links each growth driver to the segment it affects and the evidence for it.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased production in the automotive sector driving demand for sandblasting services. | Automotive Refurbishers | The automotive industry in China is projected to have over 30 million vehicles by 2025, boosting sandblasting requirements. |
| Rising investments in the metal fabrication sector improving production capabilities. | Metal Fabricators | In 2022, the total investment in the metal fabrication sector reached approximately 200 billion yuan, increasing demand for sandblasting services. |
| Expansion of the aerospace sector requiring precise surface preparation. | Aerospace Industry | The aerospace sector in China is expected to grow by 10% annually, increasing the demand for precision sandblasting services. |
| Growing environmental regulations pushing for cleaner sandblasting technologies. | Wet Sandblasters | The demand for wet sandblasting technology is increasing due to environmental regulations on dust emissions, enhancing safety and compliance. |
| Government initiatives promoting automation in manufacturing processes. | Robotic Blasting Units | The 'Advanced Manufacturing 2025' initiative aims to boost automation, increasing the need for robotic sandblasting solutions. |
Growth across the Sandblasting Equipment market in China is anchored in rising investments and expanding end-use demand. The automotive sector's projected vehicle count exceeding 30 million by 2025 creates substantial requirements for sandblasting services. In 2022, the metal fabrication sector saw investments of approximately 200 billion yuan, improving production capabilities and driving demand. The aerospace industry is anticipated to grow by 10% annually, necessitating precise surface preparation.
Evaluation of Restraints in China Sandblasting Equipment Market
The following restraints limit how fast demand can grow.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| High costs of robotic blasting units limiting adoption among smaller manufacturers. | Robotic Blasting Units | The average cost of a robotic blasting unit is around 500,000 yuan, making it less accessible for small businesses. |
| Environmental regulations restricting the use of certain abrasive materials. | Portable Blasters | The Ministry of Ecology and Environment has set guidelines to reduce environmental impact, affecting traditional blasting media usage. |
| Supply chain disruptions impacting the availability of key components for sandblasting equipment. | Portable Blasters | Supply chain disruptions have delayed the procurement of essential parts for sandblasting machines, affecting production timelines. |
| Limited awareness of advanced sandblasting technologies among small manufacturers. | Portable Blasters | Many small manufacturers are unaware of the benefits of upgrading to advanced sandblasting technologies, hindering market growth. |
| The average lifespan of sandblasting equipment necessitating regular replacements. | Portable Blasters | With an average lifespan of around 10 years, regular replacements are required, impacting purchasing decisions. |
China Sandblasting Equipment Market Challenges
In the China sandblasting equipment market, buyers and suppliers encounter fierce competition from low-cost imports that challenge local pricing strategies. This situation arises because foreign manufacturers can produce at lower costs, compelling domestic suppliers to lower prices and diminishing profit margins by up to 20%. Supply chain disruptions for key components have emerged, leading to delays in equipment delivery for manufacturers, which can extend project timelines by three months, adversely affecting productivity for buyers in the metal fabrication sector. High upgrade costs for modern sandblasting systems, often exceeding 500,000 yuan, deter smaller manufacturers from investing. A skills gap remains, as many technicians lack training in advanced technologies, hindering efficiency improvements for producers.
Trends in the China Sandblasting Equipment Market
Buyers and suppliers in the China Sandblasting Equipment Market are adjusting to the following trends.
- Shift towards Wet Sandblasting Technology: The demand for wet sandblasting technology is increasing due to stringent environmental regulations on dust emissions. In 2023, the Ministry of Ecology and Environment introduced guidelines mandating reduced emissions, prompting manufacturers to adopt this technology.
- Rise of Robotic Blasting Units: Robotic blasting units are gaining traction as manufacturers seek efficiency and consistency in their operations. In 2023, pilot projects for AI-controlled systems were initiated, showcasing a shift towards automation in sandblasting.
- Growth in Aerospace Sector: The aerospace sector is expanding rapidly, leading to increased demand for precision sandblasting. This sector is set to grow by 10% annually, increasing the need for advanced surface preparation technologies.
- Increased Investment in Metal Fabrication: Investment in the metal fabrication sector reached approximately 200 billion yuan in 2022, reflecting a growing focus on improving production capabilities. This trend is driving demand for sandblasting services across various applications.
Investment Opportunities in the China Sandblasting Equipment Market
Below are the investment opportunities with the strongest case in the China Sandblasting Equipment Market.
- Partnerships with Local Manufacturers: Now is an ideal time to collaborate with local manufacturers to supply advanced sandblasting technologies, as the market is primed for growth. The automotive sector's demand for restoration services presents a strong opportunity.
- Supply of Wet Sandblasting Equipment: With environmental regulations driving demand for cleaner technologies, supplying wet sandblasting equipment is a timely opportunity. The automotive and metal fabrication sectors are particularly keen on adopting these solutions.
- Investment in Robotic Blasting Solutions: Investing in robotic blasting solutions is timely, given the increasing focus on automation in manufacturing. The aerospace industry, projected to grow by 10% annually, represents a key buyer group for these technologies.
- Expansion into Emerging Regions: The average annual trade volume of blasting media in China is estimated at over 300 million yuan, indicating a significant market gap. Expanding into emerging regions like Shandong and Jiangsu can capture this growing demand.
Government Initiatives in the China Sandblasting Equipment Market
The 'Intelligent Manufacturing Development Plan' launched by the Ministry of Industry and Information Technology in 2021 aims to promote automation in manufacturing, including sandblasting. This initiative has a budget of 50 billion yuan, supporting the adoption of advanced technologies in the sector. Additionally, the 'Green Manufacturing Program' approved by the National Development and Reform Commission in 2022 aims to reduce emissions in sandblasting processes by 20% by 2025, ensuring sustainability in the industry.
The Ministry of Ecology and Environment introduced the 'Air Quality Improvement Initiative' in 2023, mandating stricter controls on dust emissions from sandblasting operations, ensuring manufacturers comply with environmental standards. The State Administration for Market Regulation updated the 'Quality Standards for Abrasive Materials' in 2022, enforcing safety protocols for sandblasting media that manufacturers must adhere to for compliance.
Future Insight of the China Sandblasting Equipment Market
Several forward-looking factors should support the sandblasting equipment market in China over the coming years. The 'Advanced Manufacturing 2025' initiative will drive automation, improving production efficiency across various sectors. The automotive industry is expected to demand over 30 million vehicles by 2025, creating significant opportunities for sandblasting services. The aerospace sector's growth will further heighten the need for precision sandblasting. The government's subsidy program for small manufacturers will ease access to modern equipment, boosting competitiveness in the market.
Market Segmentation Analysis
The report offers a comprehensive study of the following market segments and their leading categories in the market.
By Equipment Type – Portable Blasters Dominated, Cabinet Blasters Expected to Grow Fastest
According to Shubham Padhi, Research Analyst at 6Wresearch, Portable Blasters took a 45% share of equipment type in 2025, more than any other category. Portable Blasters hold the largest market share due to their versatility and effectiveness in on-site cleaning and surface preparation. They are particularly vital in the automotive industry, where immediate surface treatment is crucial for maintaining operational efficiency. Cabinet Blasters are set to record the highest CAGR in this split, 7.1% over 2026–2032. Cabinet Blasters are experiencing rapid growth, driven by the need for controlled environments that ensure precision in applications such as aerospace. As manufacturers increasingly focus on quality control, this segment's expansion will likely continue to accelerate. Suppliers should focus on enhancing their cabinet blaster offerings to meet the growing demand for precision in various industrial applications.
By Blasting Media – Grit/Glass Beads Dominated, Aluminum Oxide Expected to Grow Fastest
In 2025, Grit/Glass Beads led the blasting media split with a 48% share. Grit/Glass Beads dominate the market share as they are commonly used for effective surface treatment in industries like automotive and metal fabrication. Their proven performance and availability make them a go-to choice for many users across different sectors. Over 2026–2032, Aluminum Oxide is expected to post the fastest growth, at a CAGR of 7.1%. Aluminum Oxide is the fastest-growing blasting media, valued for its durability and effectiveness, especially in the aerospace sector, which is expanding rapidly. Its strong performance in demanding applications ensures it remains a preferred option for users seeking high-quality results. Buyers should consider integrating aluminum oxide into their sandblasting processes to improve efficiency and quality.
By Power Source – Pneumatic Dominated, Electric Expected to Grow Fastest
With a 40% revenue share in 2025, Pneumatic was the largest power source category. Pneumatic systems are the leading power source for sandblasting equipment, primarily due to their reliability and effectiveness in portable applications. They are widely adopted in industries requiring immediate surface preparation, such as automotive refurbishing. Electric is projected to grow fastest, at a CAGR of 8.5% during 2026–2032. Electric power sources are growing rapidly as they are ideal for environments where pneumatic systems are impractical, such as indoor facilities. The push for cleaner and quieter operations is further accelerating this trend. Suppliers should explore developing more efficient electric systems to cater to the evolving demands of the market.
By End User – Automotive Refurbishers Dominated, Metal Fabricators Expected to Grow Fastest
The largest end user category in 2025 was Automotive Refurbishers, with a 42% share of total revenue. Automotive Refurbishers represent the largest share of end users, as they rely heavily on sandblasting for vehicle restoration and surface preparation. With the automotive industry projected to grow, their demand for sandblasting services will continue to rise. The quickest growth will come from Metal Fabricators, forecast to expand at a CAGR of 7.5% between 2026 and 2032. Metal Fabricators are the fastest-growing end users as they increasingly utilise sandblasting for cleaning and finishing metal parts, driven by the substantial investment in the metal fabrication sector. This trend reflects the broader shift towards automation and efficiency in manufacturing. Suppliers should target metal fabricators with tailored solutions to capitalise on their growing demand for sandblasting services.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Sandblasting Equipment Market Outlook
- Market Size of China Sandblasting Equipment Market, 2025
- Forecast of China Sandblasting Equipment Market, 2032
- Historical Data and Forecast of China Sandblasting Equipment Revenues & Volume for the Period 2022 - 2032F
- China Sandblasting Equipment Market Trend Evolution
- China Sandblasting Equipment Market Drivers and Challenges
- China Sandblasting Equipment Price Trends
- China Sandblasting Equipment Porter's Five Forces
- China Sandblasting Equipment Industry Life Cycle
- Historical Data and Forecast of China Sandblasting Equipment Market Revenues & Volume By Equipment Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Sandblasting Equipment Market Revenues & Volume By Portable Blasters for the Period 2022 - 2032F
- Historical Data and Forecast of China Sandblasting Equipment Market Revenues & Volume By Cabinet Blasters for the Period 2022 - 2032F
- Historical Data and Forecast of China Sandblasting Equipment Market Revenues & Volume By Wet Sandblasters for the Period 2022 - 2032F
- Historical Data and Forecast of China Sandblasting Equipment Market Revenues & Volume By Robotic Blasting Units for the Period 2022 - 2032F
- Historical Data and Forecast of China Sandblasting Equipment Market Revenues & Volume By Blasting Media for the Period 2022 - 2032F
- Historical Data and Forecast of China Sandblasting Equipment Market Revenues & Volume By Grit/Glass Beads for the Period 2022 - 2032F
- Historical Data and Forecast of China Sandblasting Equipment Market Revenues & Volume By Aluminum Oxide for the Period 2022 - 2032F
- Historical Data and Forecast of China Sandblasting Equipment Market Revenues & Volume By Water + Abrasive Mix for the Period 2022 - 2032F
- Historical Data and Forecast of China Sandblasting Equipment Market Revenues & Volume By AI-Controlled for the Period 2022 - 2032F
- Historical Data and Forecast of China Sandblasting Equipment Market Revenues & Volume By Power Source for the Period 2022 - 2032F
- Historical Data and Forecast of China Sandblasting Equipment Market Revenues & Volume By Pneumatic for the Period 2022 - 2032F
- Historical Data and Forecast of China Sandblasting Equipment Market Revenues & Volume By Electric for the Period 2022 - 2032F
- Historical Data and Forecast of China Sandblasting Equipment Market Revenues & Volume By Diesel for the Period 2022 - 2032F
- Historical Data and Forecast of China Sandblasting Equipment Market Revenues & Volume By Programmable for the Period 2022 - 2032F
- Historical Data and Forecast of China Sandblasting Equipment Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Sandblasting Equipment Market Revenues & Volume By Automotive Refurbishers for the Period 2022 - 2032F
- Historical Data and Forecast of China Sandblasting Equipment Market Revenues & Volume By Metal Fabricators for the Period 2022 - 2032F
- Historical Data and Forecast of China Sandblasting Equipment Market Revenues & Volume By Marine Industry for the Period 2022 - 2032F
- Historical Data and Forecast of China Sandblasting Equipment Market Revenues & Volume By Aerospace Industry for the Period 2022 - 2032F
- China Sandblasting Equipment Import Export Trade Statistics
- Market Opportunity Assessment By Equipment Type
- Market Opportunity Assessment By Blasting Media
- Market Opportunity Assessment By Power Source
- Market Opportunity Assessment By End User
- China Sandblasting Equipment Top Companies Market Share
- China Sandblasting Equipment Competitive Benchmarking By Technical and Operational Parameters
- China Sandblasting Equipment Company Profiles
- China Sandblasting Equipment Key Strategic Recommendations
Market Covered
The report offers an extensive study of the following market segments.
By Equipment Type
- Portable Blasters
- Cabinet Blasters
- Wet Sandblasters
- Robotic Blasting Units
By Blasting Media
- Grit/Glass Beads
- Aluminum Oxide
- Water + Abrasive Mix
- AI-Controlled
By Power Source
- Pneumatic
- Electric
- Diesel
- Programmable
By End User
- Automotive Refurbishers
- Metal Fabricators
- Marine Industry
- Aerospace Industry































