China Security Management Software Market Size & Growth Rate
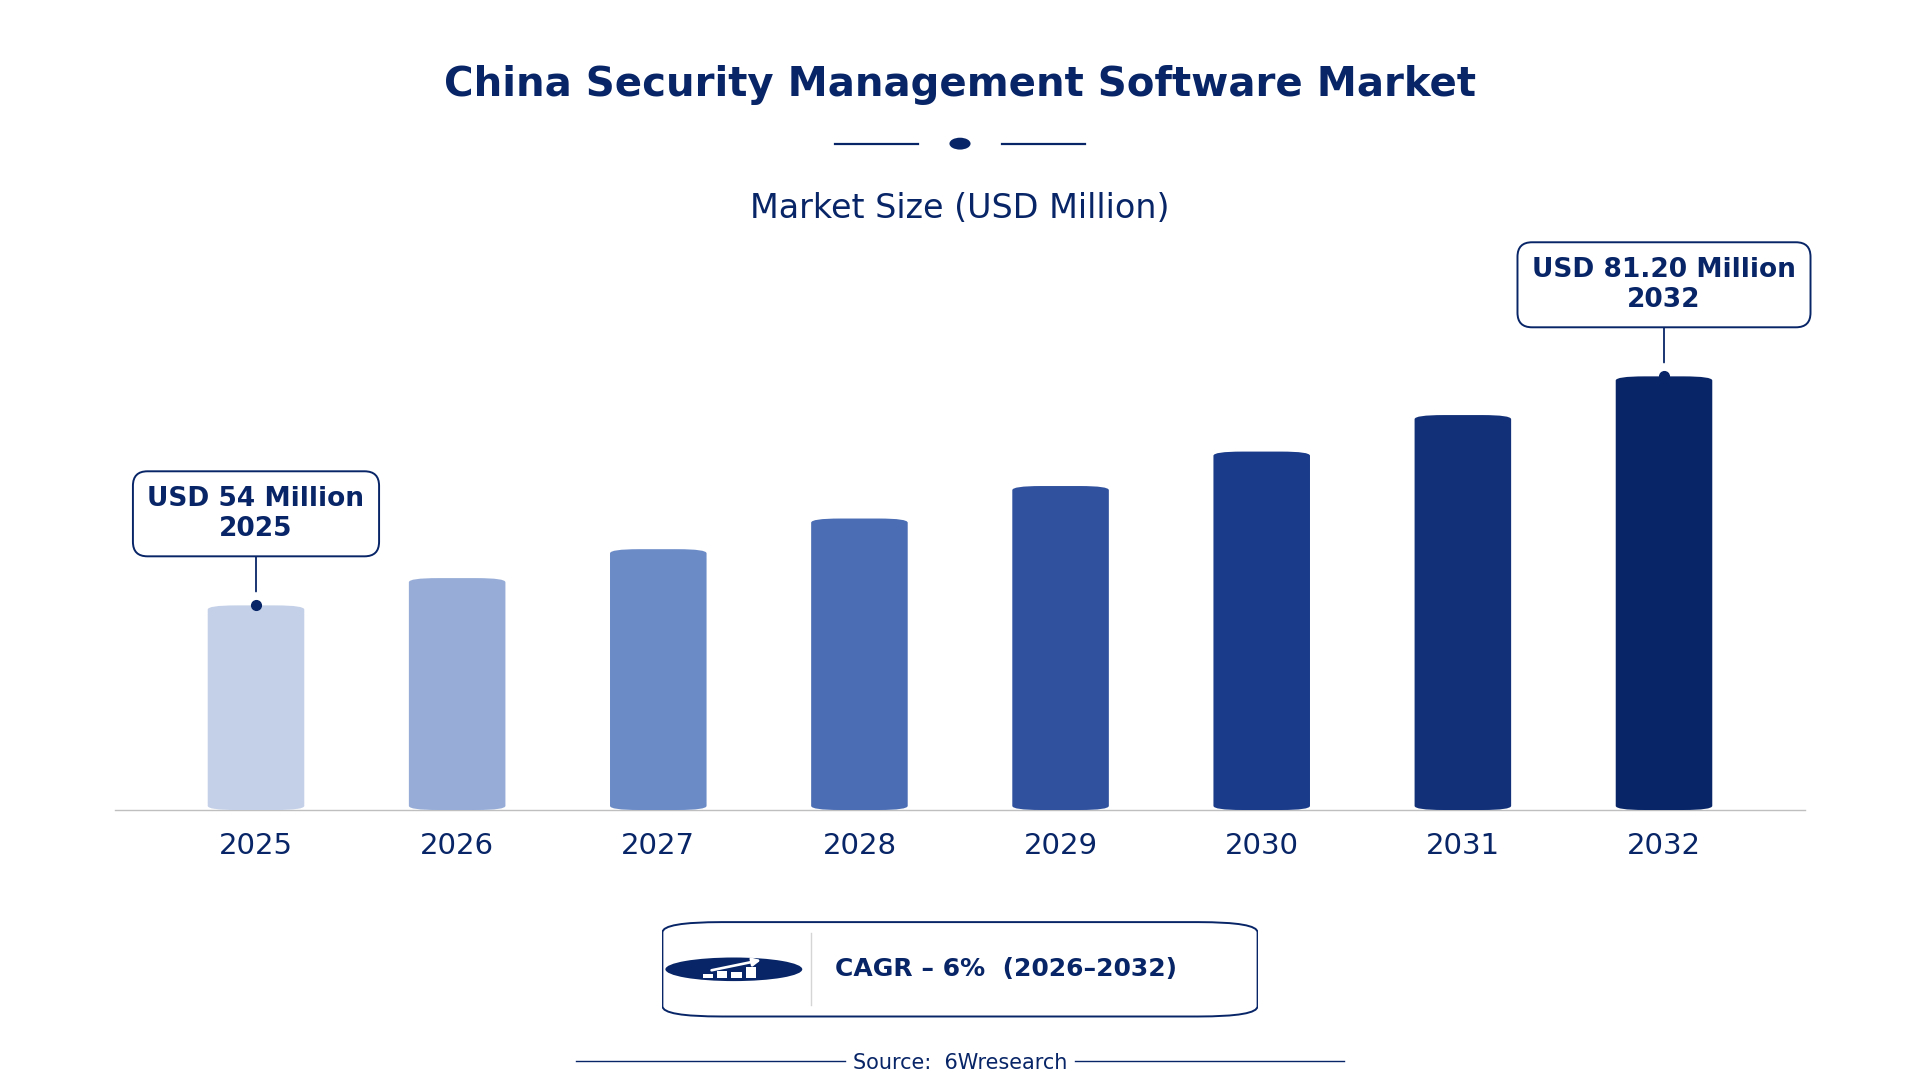
According to 6Wresearch internal database and industry insights, the China Security Management Software Market was valued at USD 54.0 million in 2025 and is projected to reach USD 81.20 million by 2032, growing at a CAGR of approximately 6% during 2026–2032.
China Security Management Software Market Highlights
| Report Metric | Details |
| Report Name | China Security Management Software Market |
| Market Size 2025 | USD 54.0 million |
| Market Size 2032 | USD 81.20 million |
| Absolute Growth 2025–2032 | USD 27.20 million |
| CAGR 2026–2032 | 6% |
| Peak Annual Growth | 8.5% in 2031 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Module Type, 2025 | Identity & Access Mgmt (44% share) |
| Leading Feature Focus, 2025 | SSO/MFA (46% share) |
| Leading Deployment Option, 2025 | SaaS or On-Premise (54% share) |
| Leading End User, 2025 | Enterprises & Gov Enterprises (35% share) |
| Fastest-Growing Module Type | Video Management System (7.3% CAGR) |
| Fastest-Growing Feature Focus | CCTV Integration (8.8% CAGR) |
| Fastest-Growing Deployment Option | Cloud/Hybrid (7.9% CAGR) |
| Fastest-Growing End User | Retail & Transportation (7.6% CAGR) |
| Growing Sector | Retail & Transportation |
| Key End Users | Enterprises & Gov Enterprises, Retail & Transportation, Enterprise IT Teams, Data Center Operators |
China Security Management Software Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
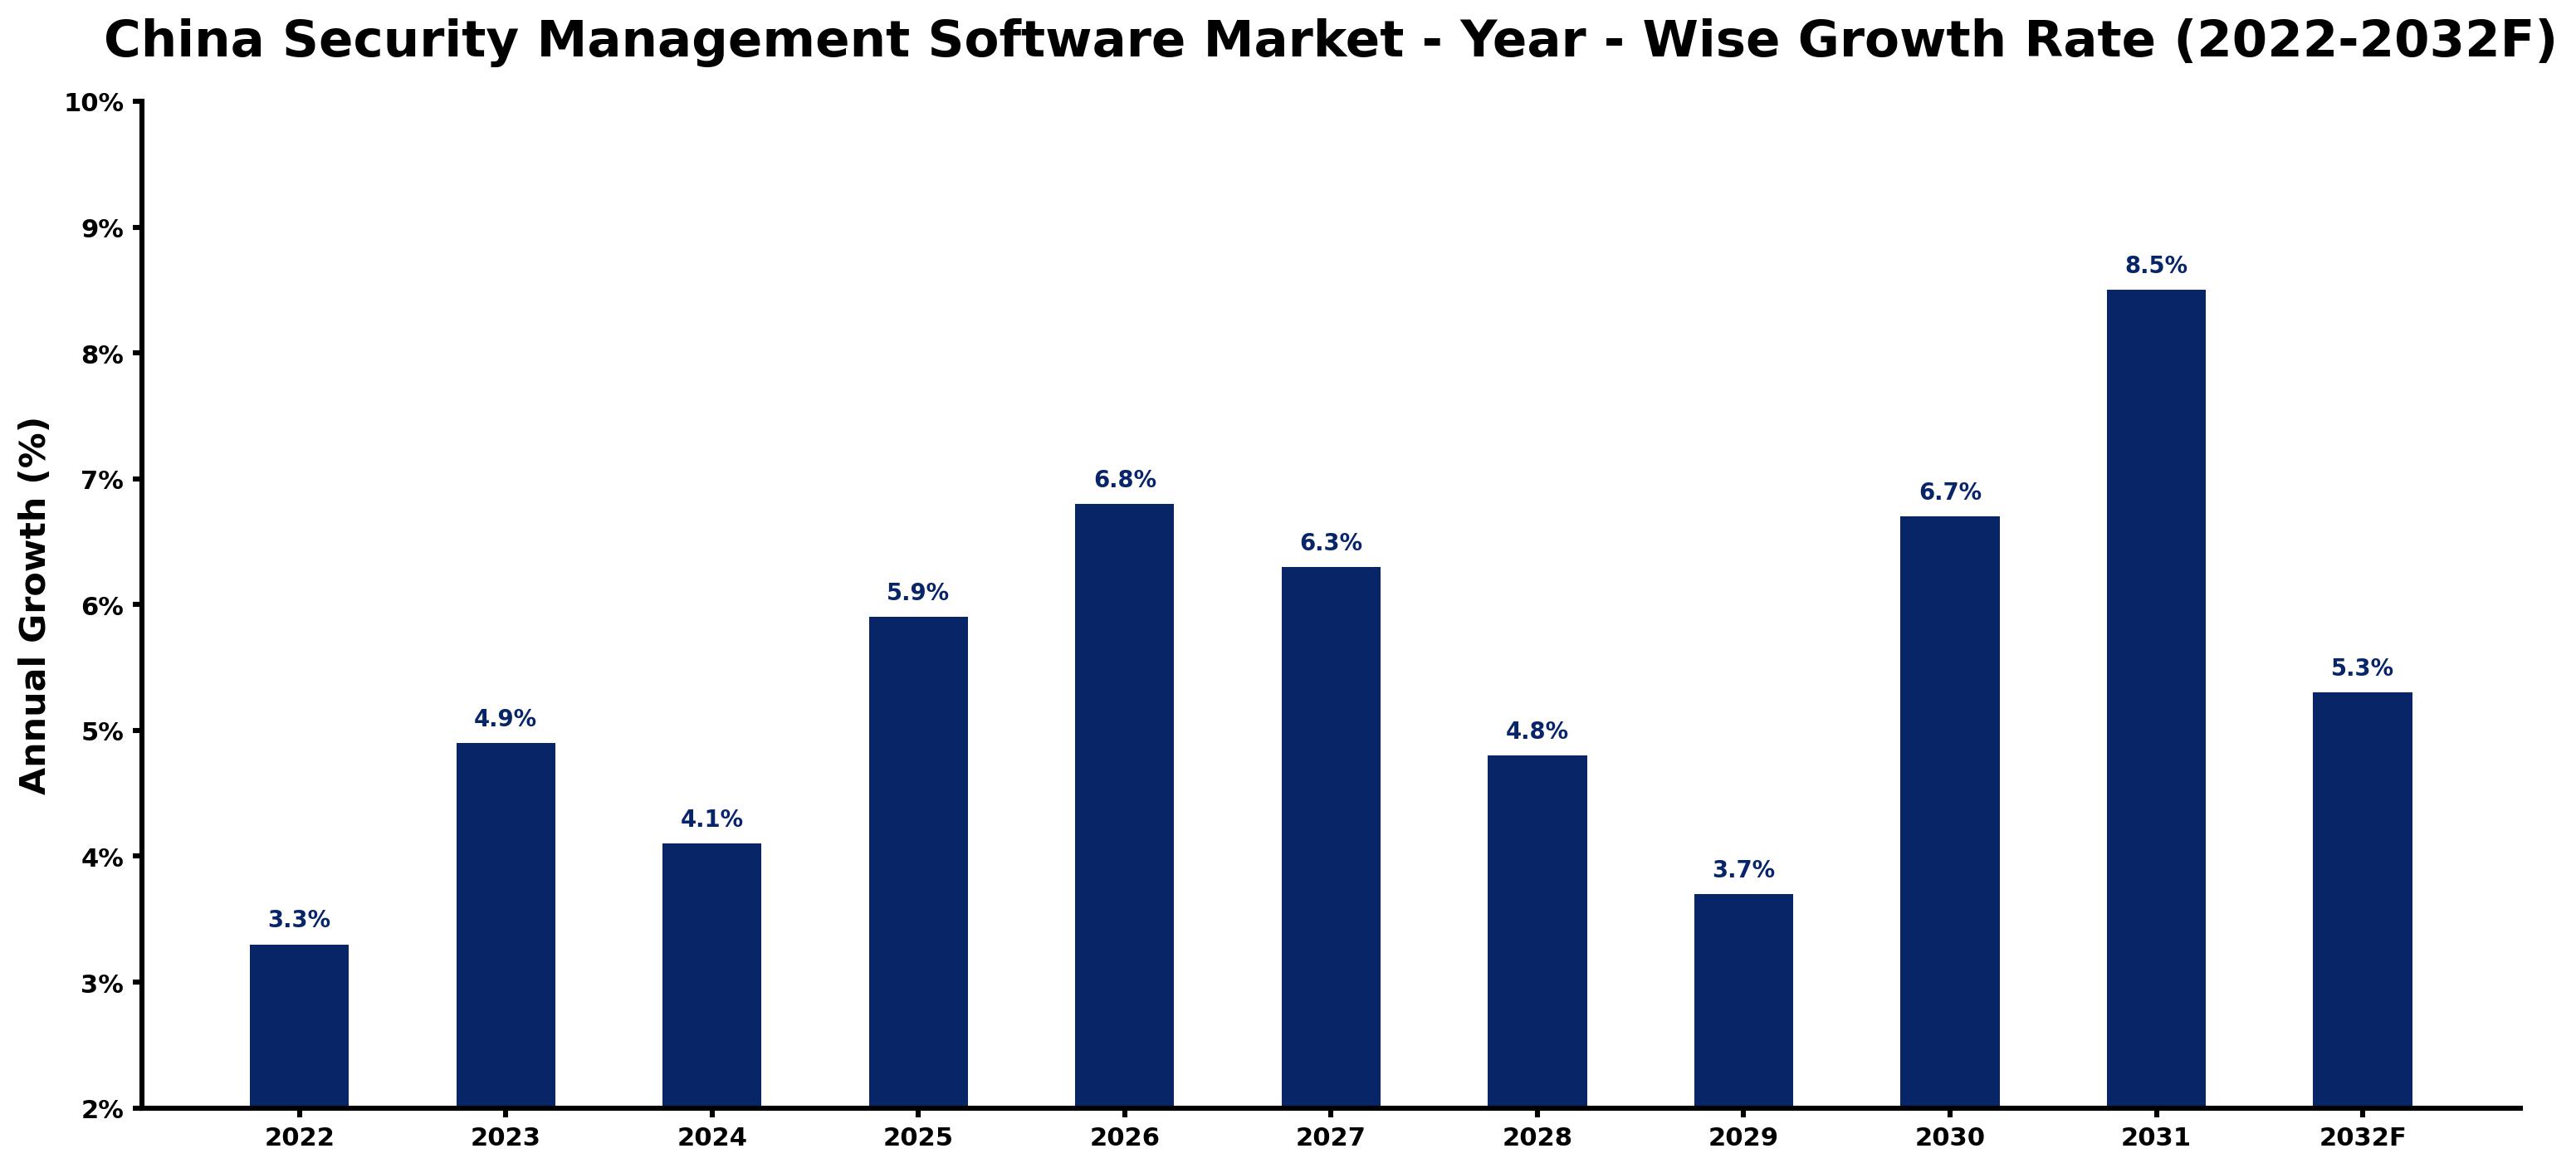
Each row of the following table gives one year's estimated growth and the event or demand shift that explains it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 3.3 | The market experienced steady demand due to ongoing digital security needs. |
| 2023 | 4.9 | Growth accelerated as enterprises increased investments in cybersecurity measures. |
| 2024 | 4.1 | The market saw a slowdown as some enterprises delayed upgrades amid economic uncertainty. |
| 2025 | 5.9 | Demand surged with the implementation of updated cybersecurity regulations. |
| 2026 | 6.8 | Growth continued as businesses adopted more advanced security technologies. |
| 2027 | 6.3 | The market slowed as some sectors faced budget constraints on IT spending. |
| 2028 | 4.8 | Demand decreased slightly as companies reassessed their security investments. |
| 2029 | 3.7 | A further slowdown occurred as enterprises prioritised cost-saving measures. |
| 2030 | 6.7 | Growth rebounded as new technologies drove renewed investment in security. |
| 2031 | 8.5 | The market peaked with significant demand for advanced security solutions. |
| 2032 | 5.3 | Growth slowed as the market began to stabilise after rapid expansion. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Security Management Software Market Synopsis
Security Management Software in China includes technologies designed to manage and secure digital assets, such as identity management and network security. The market thrives on the commitment of enterprises and government bodies to improve digital security. With China's cybersecurity market valued at 1.5 trillion CNY in 2022, demand is poised for substantial growth. The updated National Cybersecurity Strategy and the increasing use of multi-factor authentication are key drivers of this expansion. The retail and transportation sectors stand out as primary users of these solutions, further contributing to market growth.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increased demand for endpoint protection solutions due to remote work trends. | Driver | High | Endpoint Protection |
| Growing adoption of multi-factor authentication among enterprises. | Driver | High | Identity & Access Mgmt |
| Rising need for integrated security solutions in retail and transportation sectors. | Opportunity | High | Video Management System |
| Investment in cybersecurity talent development programmes by the government. | Opportunity | High | Network Security Mgmt |
| Budget constraints in some sectors limiting IT security investments. | Restraint | Medium | Endpoint Protection |
| Challenges in compliance with evolving cybersecurity regulations. | Restraint | Medium | Identity & Access Mgmt |
| The Security Management Software market in China faces significant regulatory hurdles. | Challenge | High | Video Management System |
| Limited awareness among smaller enterprises regarding the importance of security management. | Challenge | Medium | Network Security Mgmt |
Evaluation of Drivers in China Security Management Software Market (2026–2032)
Below mentioned are some major drivers and their influence on market dynamics.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Growing demand for remote work solutions boosts endpoint protection needs. | Endpoint Protection | The rise in remote work has led to increased purchases of endpoint protection solutions, with businesses prioritising device security to protect remote workers. |
| High adoption rates of multi-factor authentication drive identity management solutions. | Identity & Access Mgmt | Over 70% of enterprises in China have adopted multi-factor authentication, increasing the need for effective identity management solutions to secure user access. |
| Increased investment in video surveillance systems supports security management. | Video Management System | The installed base of video management systems in China exceeds 5 million units, indicating strong market demand for enhanced security infrastructure. |
| Rising security concerns in retail and transportation sectors drive software adoption. | Network Security Mgmt | These sectors are increasingly investing in security management software to protect their operations and assets from potential threats. |
| Government initiatives promote cybersecurity talent cultivation. | Identity & Access Mgmt | The Cybersecurity Talent Cultivation Programme aims to train 1 million professionals by 2025, boosting demand for security management solutions. |
Growth across the Security Management Software market in China is anchored in rising end-use demand from sectors such as retail and transportation, alongside a strong supply response from software developers. The installed base of video management systems exceeds 5 million units, reflecting high investment in security infrastructure. Over 70% of enterprises have adopted multi-factor authentication, which drives demand for identity management solutions.
Evaluation of Restraints in China Security Management Software Market
The following restraints limit how fast demand can grow.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Budget constraints limiting IT security investments in some sectors. | Endpoint Protection | As companies face economic pressures, many are reducing their IT budgets, affecting security spending, particularly in endpoint protection solutions. |
| Compliance challenges with evolving cybersecurity regulations. | Identity & Access Mgmt | Enterprises struggle to keep up with changing regulations, which can delay security upgrades and compliance efforts, impacting their overall security posture. |
| Limited awareness of security management importance among smaller enterprises. | Network Security Mgmt | Many smaller businesses do not prioritise security management, resulting in lower adoption rates and increased vulnerability to cyber threats. |
| Complex integration processes for security management solutions. | Video Management System | Integrating new systems with existing infrastructure can be time-consuming and costly for enterprises, hindering the adoption of advanced security solutions. |
| Shortage of qualified cybersecurity professionals in the market. | Identity & Access Mgmt | The demand for skilled professionals outpaces supply, hindering the implementation of effective security solutions across various sectors. |
China Security Management Software Market Challenges
The China Security Management Software market faces a critical challenge as over 70% of enterprises contend with outdated systems, hindering their ability to manage digital security effectively. This dependence on legacy technology arises from insufficient investment in modern solutions, resulting in prolonged threat detection times. Furthermore, the rapid rise in remote work has created vulnerabilities in endpoint protection, exposing many organisations to potential attacks. Suppliers also face compliance hurdles due to the recent Cybersecurity Law Amendment, which increases operational costs for buyers implementing new security measures.
Trends in the China Security Management Software Market
Buyers and suppliers in the China Security Management Software Market are adjusting to the following trends.
- Shift from On-Premise to Cloud Solutions: Many enterprises in China are moving from on-premise security management solutions to cloud-based alternatives. This shift is driven by the growing need for scalable and flexible security solutions, with cloud adoption anticipated to rise by 30% in the coming years.
- Increased Focus on Multi-Factor Authentication: The uptake of multi-factor authentication has surged across various sectors in China, with over 70% of enterprises adopting it. This trend not only strengthens security but also improves user access management, reflecting a broader commitment to digital security and compliance.
- Emergence of Integrated Security Solutions: Integrated security solutions that combine video surveillance and access management are gaining popularity in China. This trend is highlighted by the increasing installation of systems that provide comprehensive security coverage across enterprises, with an annual growth rate of 6%.
- Growth of Cybersecurity Talent Development: The Cybersecurity Talent Cultivation Programme, launched in 2022, aims to train 1 million professionals by 2025. This initiative underscores the growing recognition of cybersecurity's importance in protecting digital assets and enhancing workforce capabilities.
Investment Opportunities in the China Security Management Software Market
Some of the investment opportunities in the China Security Management Software Market are mentioned below.
- Investment in Cybersecurity Training Facilities: Beijing is emerging as a hub for cybersecurity training facilities, with the government aiming to train 1 million professionals by 2025. This initiative creates opportunities for educational institutions to develop specialised programmes, catering to the growing demand for skilled workers in the Security Management Software sector.
- Supply of Advanced Video Management Systems: The demand for video management systems is surging, particularly in Shanghai, where over 5 million units are currently installed. Suppliers can capitalise on this by offering innovative solutions that enhance surveillance capabilities, meeting the needs of enterprises and government entities.
- Partnerships with Retail and Transportation Sectors: Retail and transportation sectors are increasingly adopting security management solutions, driven by the need for operational security. Collaborating with industry players in these sectors can provide suppliers with a direct entry point to meet their growing security demands.
- Expansion of Cloud-Based Security Solutions: The shift towards cloud-based security solutions is gaining traction, especially in urban areas. With a projected CAGR of 7.9% for Cloud/Hybrid deployment options, suppliers can focus on developing flexible solutions that cater to enterprises seeking scalable security management.
Government Initiatives in the China Security Management Software Market
The Cybersecurity Law Amendment, introduced in 2023, significantly influences the Security Management Software market by tightening data protection requirements for enterprises. This law enforces stricter compliance measures, compelling businesses to invest in updated security solutions to align with the new standards. Additionally, the National Cybersecurity Strategy, revised in 2021, aims to improve digital security across sectors, encouraging investments in advanced security technologies.
The Ministry of Industry and Information Technology oversees the implementation of the Cybersecurity Talent Cultivation Programme, which funds initiatives aimed at training cybersecurity professionals. This programme supports various educational projects and partnerships with universities, ensuring a steady influx of skilled workers into the industry. The State Administration for Market Regulation enforces compliance with cybersecurity regulations, approving standards and practices that strengthen security management across enterprises.
Future Insight of the China Security Management Software Market
The China Security Management Software market is poised for substantial transformation by 2032, driven by the National Cybersecurity Strategy's commitment to enhancing digital security protocols. The installed base of video management systems is expected to exceed 10 million units, reflecting a growing demand for robust surveillance capabilities. The Cybersecurity Talent Cultivation Programme aims to produce 1 million trained professionals by 2025, addressing the skills gap in the industry. Furthermore, the adoption of ISO/IEC 27001 standards will promote uniformity in information security practices across enterprises.
Market Segmentation Analysis
The analysis below covers each segmentation, its leading category in 2025 and its fastest-growing category through 2032.
By Module Type – Identity & Access Mgmt Dominated, Video Management System Expected to Grow Fastest
According to Shubham Padhi, Research Analyst at 6Wresearch, with a 44% revenue share in 2025, Identity & Access Mgmt was the largest module type category. Identity and Access Management holds the largest share as it is crucial for securing user access across various systems, particularly in sectors where data protection is paramount. The implementation of multi-factor authentication by over 70% of enterprises highlights its essential role in maintaining security. Video Management System is set to record the highest CAGR in this split, 7.3% over 2026–2032. The Video Management System segment is growing rapidly due to the increasing demand for surveillance solutions, especially in urban areas like Beijing and Shanghai. With more than 5 million video management systems installed, this technology is set for continued expansion. This trend suggests that suppliers should focus on enhancing features related to identity management and surveillance to meet the market's growing demands.
By Feature Focus – SSO/MFA Dominated, CCTV Integration Expected to Grow Fastest
SSO/MFA held a 46% share of the China Security Management Software Market by feature focus in 2025. SSO/MFA is the leading feature focus because it significantly enhances user authentication processes, which are essential for effective security management. The widespread adoption of multi-factor authentication among enterprises underscores its critical role in safeguarding digital assets against threats. The quickest growth will come from CCTV Integration, forecast to expand at a CAGR of 8.8% between 2026 and 2032. CCTV Integration is the fastest-growing feature, driven by the need for cohesive surveillance systems that streamline security operations. This integration is becoming increasingly crucial in sectors like retail and transportation, where effective monitoring is vital for operational safety. Suppliers should prioritise developing integrated solutions that combine SSO/MFA with CCTV capabilities to seize this expanding market opportunity.
By Deployment Option – SaaS or On-Premise Dominated, Cloud/Hybrid Expected to Grow Fastest
The largest deployment option category in 2025 was SaaS or On-Premise, with a 54% share of total revenue. SaaS or On-Premise deployment options dominate the market due to their flexibility, allowing organisations to choose solutions that best fit their operational needs. This adaptability is particularly advantageous for enterprises and government entities requiring tailored security measures. Cloud/Hybrid is projected to grow fastest, at a CAGR of 7.9% during 2026–2032. The Cloud/Hybrid deployment option is witnessing the fastest growth as organisations increasingly prefer scalable solutions that accommodate remote work and changing operational demands. This shift reflects a broader trend towards cloud-based technologies across various sectors. This indicates that suppliers must invest in enhancing their cloud offerings to meet the rising demand for hybrid solutions in the market.
By End User – Enterprises & Gov Enterprises Dominated, Retail & Transportation Expected to Grow Fastest
Enterprises & Gov Enterprises accounted for a 35% market share by end user in 2025. Enterprises and government enterprises represent the largest share of users for security management solutions, as they are the primary stakeholders in protecting sensitive information. Their extensive IT infrastructure necessitates robust security measures to mitigate risks associated with data breaches. Over 2026–2032, Retail & Transportation is expected to post the fastest growth, at a CAGR of 7.6%. The Retail and Transportation sectors are the fastest-growing end users, driven by the need for operational security in high-traffic environments. The increasing focus on securing customer data and assets in these industries is propelling this growth forward. Suppliers should tailor their offerings to meet the specific security needs of the retail and transportation sectors to capitalise on this growth opportunity.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Security Management Software Market Outlook
- Market Size of China Security Management Software Market, 2025
- Forecast of China Security Management Software Market, 2032
- Historical Data and Forecast of China Security Management Software Revenues & Volume for the Period 2022 - 2032F
- China Security Management Software Market Trend Evolution
- China Security Management Software Market Drivers and Challenges
- China Security Management Software Price Trends
- China Security Management Software Porter's Five Forces
- China Security Management Software Industry Life Cycle
- Historical Data and Forecast of China Security Management Software Market Revenues & Volume By Module Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Security Management Software Market Revenues & Volume By Identity & Access Mgmt for the Period 2022 - 2032F
- Historical Data and Forecast of China Security Management Software Market Revenues & Volume By Video Management System for the Period 2022 - 2032F
- Historical Data and Forecast of China Security Management Software Market Revenues & Volume By Endpoint Protection for the Period 2022 - 2032F
- Historical Data and Forecast of China Security Management Software Market Revenues & Volume By Network Security Mgmt for the Period 2022 - 2032F
- Historical Data and Forecast of China Security Management Software Market Revenues & Volume By Feature Focus for the Period 2022 - 2032F
- Historical Data and Forecast of China Security Management Software Market Revenues & Volume By SSO/MFA for the Period 2022 - 2032F
- Historical Data and Forecast of China Security Management Software Market Revenues & Volume By CCTV Integration for the Period 2022 - 2032F
- Historical Data and Forecast of China Security Management Software Market Revenues & Volume By AV + EDR for the Period 2022 - 2032F
- Historical Data and Forecast of China Security Management Software Market Revenues & Volume By Firewall/NAC Control for the Period 2022 - 2032F
- Historical Data and Forecast of China Security Management Software Market Revenues & Volume By Deployment Option for the Period 2022 - 2032F
- Historical Data and Forecast of China Security Management Software Market Revenues & Volume By SaaS or On-Premise for the Period 2022 - 2032F
- Historical Data and Forecast of China Security Management Software Market Revenues & Volume By Cloud/Hybrid for the Period 2022 - 2032F
- Historical Data and Forecast of China Security Management Software Market Revenues & Volume By Agent-Based for the Period 2022 - 2032F
- Historical Data and Forecast of China Security Management Software Market Revenues & Volume By Virtual Appliance for the Period 2022 - 2032F
- Historical Data and Forecast of China Security Management Software Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Security Management Software Market Revenues & Volume By Enterprises & Gov Enterprises for the Period 2022 - 2032F
- Historical Data and Forecast of China Security Management Software Market Revenues & Volume By Retail & Transportation for the Period 2022 - 2032F
- Historical Data and Forecast of China Security Management Software Market Revenues & Volume By Enterprise IT Teams for the Period 2022 - 2032F
- Historical Data and Forecast of China Security Management Software Market Revenues & Volume By Data Center Operators for the Period 2022 - 2032F
- China Security Management Software Import Export Trade Statistics
- Market Opportunity Assessment By Module Type
- Market Opportunity Assessment By Feature Focus
- Market Opportunity Assessment By Deployment Option
- Market Opportunity Assessment By End User
- China Security Management Software Top Companies Market Share
- China Security Management Software Competitive Benchmarking By Technical and Operational Parameters
- China Security Management Software Company Profiles
- China Security Management Software Key Strategic Recommendations
Market Covered
The report offers an extensive study of the following market segments.
By Module Type
- Identity & Access Mgmt
- Video Management System
- Endpoint Protection
- Network Security Mgmt
By Feature Focus
- SSO/MFA
- CCTV Integration
- AV + EDR
- Firewall/NAC Control
By Deployment Option
- SaaS or On-Premise
- Cloud/Hybrid
- Agent-Based
- Virtual Appliance
By End User
- Enterprises & Gov Enterprises
- Retail & Transportation
- Enterprise IT Teams
- Data Center Operators































