China Security Tech Market Size & Growth Rate
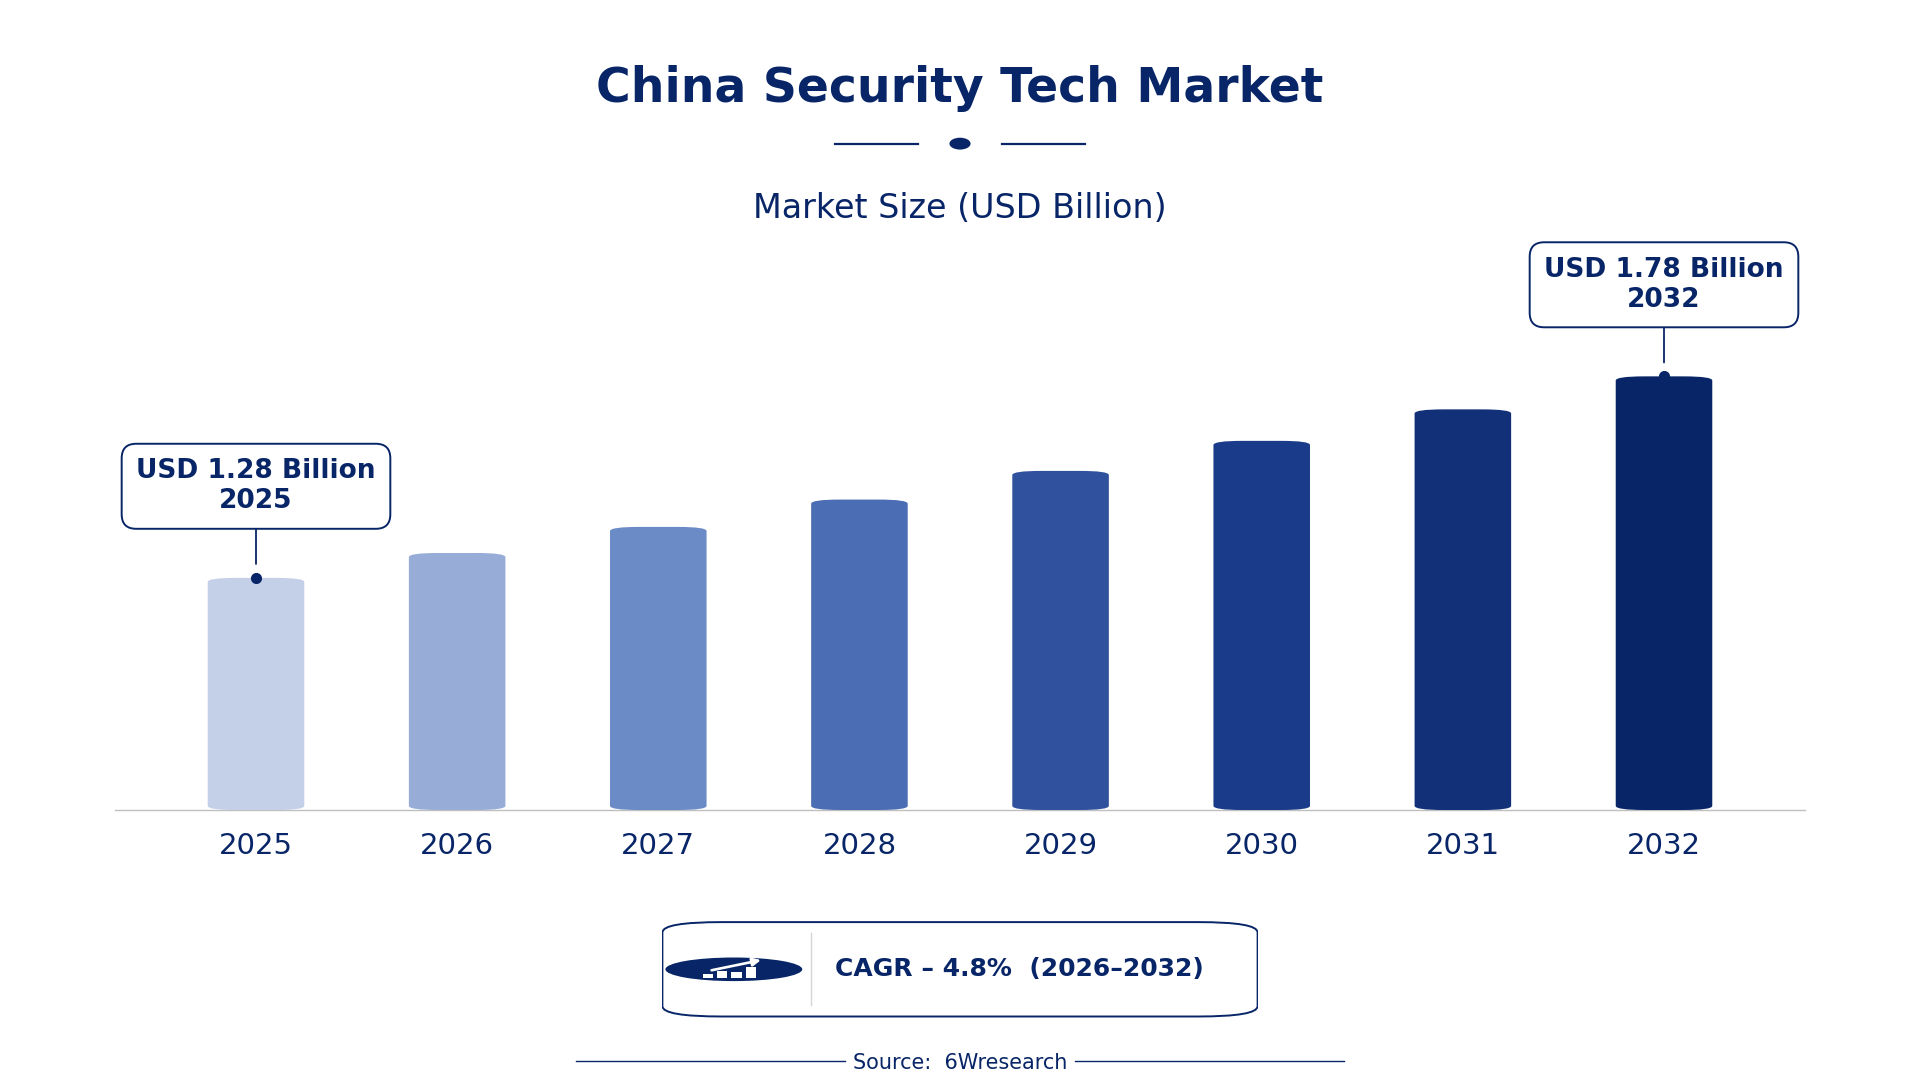
According to 6Wresearch internal database and industry insights, the China Security Tech Market was valued at USD 1.28 billion in 2025 and is projected to reach USD 1.78 billion by 2032, growing at a CAGR of approximately 4.8% during 2026–2032.
China Security Tech Market Highlights
| Report Metric | Details |
| Report Name | China Security Tech Market |
| Market Size 2025 | USD 1.28 billion |
| Market Size 2032 | USD 1.78 billion |
| Absolute Growth 2025–2032 | USD 0.50 billion |
| CAGR 2026–2032 | 4.8% |
| Peak Annual Growth | 7.3% in 2032 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Tech Category, 2025 | Cybersecurity Solutions (40% share) |
| Leading Functionality, 2025 | Endpoint + Network (40% share) |
| Leading Usage Frequency, 2025 | Continuously Operated (45% share) |
| Leading End User, 2025 | Enterprise IT Teams (49% share) |
| Fastest-Growing Tech Category | Analytics & AI Security Tech (7.3% CAGR) |
| Fastest-Growing Functionality | IAM Platforms (6.5% CAGR) |
| Fastest-Growing Usage Frequency | Real-time (7.5% CAGR) |
| Fastest-Growing End User | Security Command Centers (7.1% CAGR) |
| Growing Sector | Urban Security Solutions |
| Key End Users | Government agencies, enterprise IT teams, institutional buildings, Fortune 500 companies |
China Security Tech Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
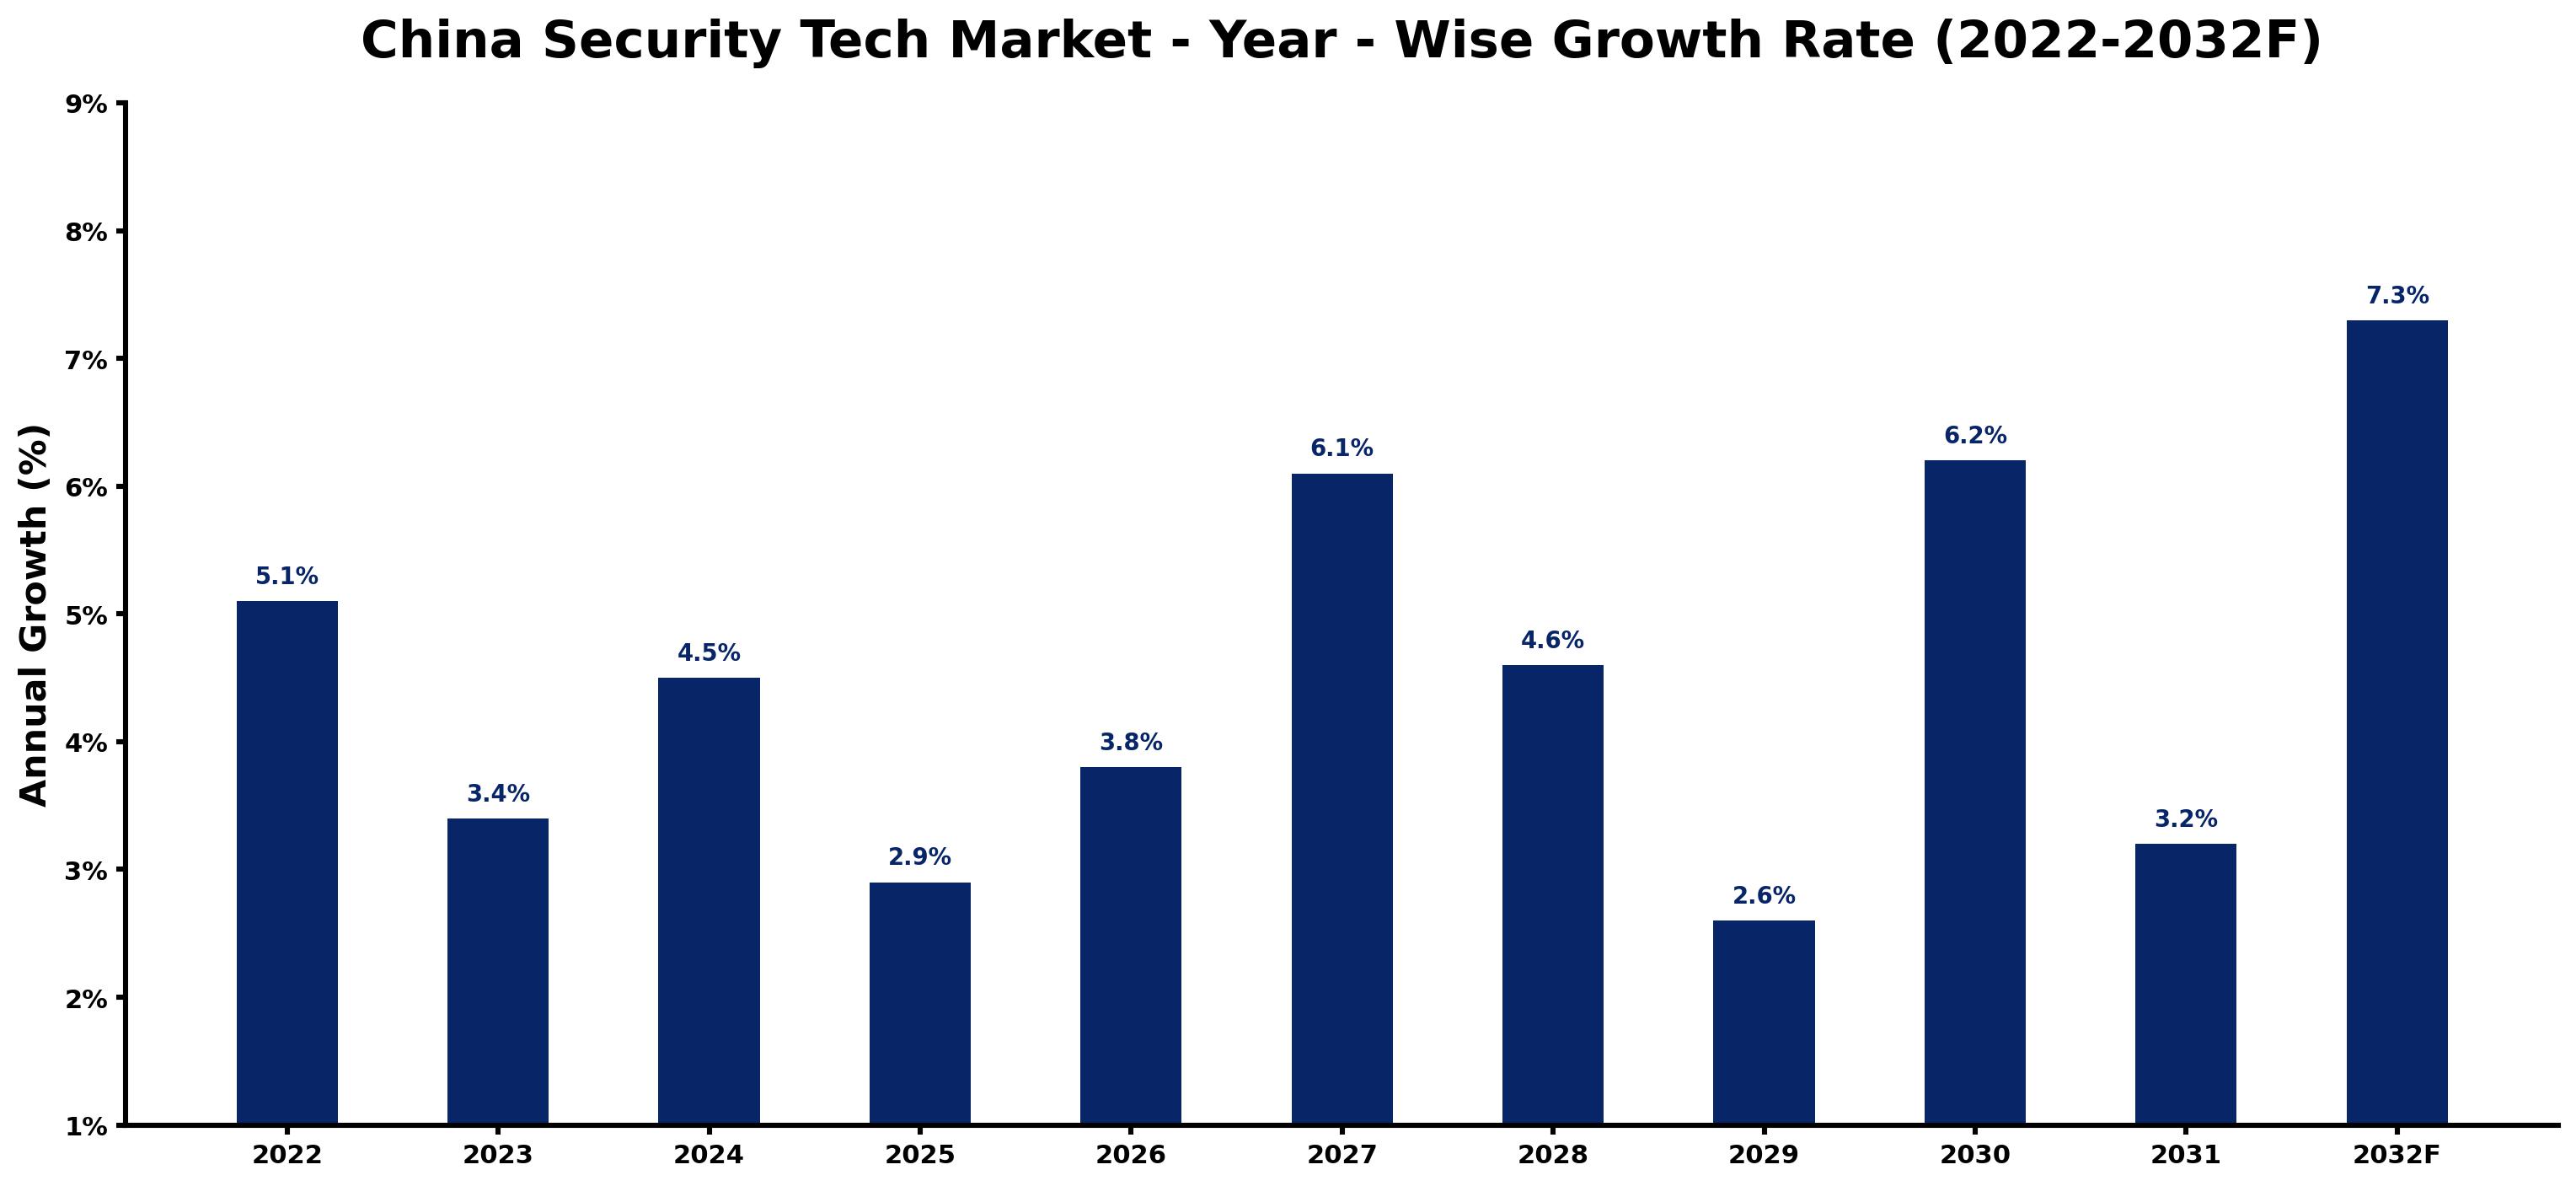
Year by year, the estimates below pair each growth rate with the development that shaped it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 5.1 | The market experienced strong demand due to increased cybersecurity threats and investments in technology. |
| 2023 | 3.4 | Growth slowed as enterprises adjusted to new cybersecurity regulations and standards. |
| 2024 | 4.5 | Demand increased as more companies adopted advanced security solutions to protect digital assets. |
| 2025 | 2.9 | Growth slowed again as market saturation began to affect new investments in security tech. |
| 2026 | 3.8 | The market saw renewed interest as the government launched initiatives to enhance urban security. |
| 2027 | 6.1 | Demand surged with the rise of AI-driven security analytics and increased public safety investments. |
| 2028 | 4.6 | Growth slowed as the market stabilised following rapid technological advancements. |
| 2029 | 2.6 | Demand decreased as companies reassessed their security budgets amid economic uncertainties. |
| 2030 | 6.2 | A resurgence in growth occurred as new standards for cybersecurity were implemented nationwide. |
| 2031 | 3.2 | Growth slowed as the market adjusted to the impact of new regulations and compliance requirements. |
| 2032 | 7.3 | Demand peaked as urban areas adopted comprehensive security solutions under the Smart City Initiative. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Security Tech Market Synopsis
Security Tech in China includes systems and solutions aimed at safeguarding assets, information, and individuals. This encompasses both hardware and software components such as surveillance cameras and access control systems. The China Security Tech Market is expanding due to rising cybersecurity threats and substantial investments in smart city initiatives. In 2022, the cybersecurity market reached $45 billion, highlighting the robust demand for security solutions across multiple sectors. Key buyer groups, including government agencies and enterprise IT teams, are driving the adoption of advanced security technologies.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increased investment in smart city initiatives drives demand for integrated security solutions. | Driver | High | Physical Security Tech |
| Growing concerns over cybersecurity threats lead to higher adoption of cybersecurity solutions. | Driver | High | Cybersecurity Solutions |
| The demand for AI-driven security analytics is expanding rapidly, creating opportunities for suppliers. | Opportunity | High | Analytics & AI Security Tech |
| Urban areas are increasingly adopting advanced security technologies, presenting new market prospects. | Opportunity | Medium | Physical Security Tech |
| High competition among security tech providers can lead to pricing pressures and reduced margins. | Restraint | Medium | Cybersecurity Solutions |
| Regulatory compliance requirements can increase operational costs for security tech providers. | Restraint | High | Identity & Access Mgmt Tech |
| The Security Tech Market in China faces challenges from rapid technological changes and evolving threats. | Challenge | High | Cybersecurity Solutions |
| Economic fluctuations may lead to reduced budgets for security investments among enterprises. | Challenge | Medium | Physical Security Tech |
Evaluation of Drivers in China Security Tech Market (2026–2032)
The factors lifting demand, and the evidence behind each, are summarised below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased government funding for public safety technologies boosts demand for security solutions. | Physical Security Tech | In 2023, the government allocated $1 billion for public safety technologies, prompting local governments to invest in security systems. |
| The rise in cybersecurity threats necessitates the adoption of advanced cybersecurity solutions. | Cybersecurity Solutions | Over 70% of enterprises in China have adopted cybersecurity solutions to protect against increasing digital threats. |
| The Smart City Initiative promotes the integration of advanced security technologies in urban areas. | Physical Security Tech | Launched in 2023, the Smart City Initiative focuses on urban security systems, driving demand for various security technologies. |
| The growing need for real-time threat detection increases demand for continuous monitoring solutions. | Continuously Operated | The demand for continuous monitoring systems is essential for real-time threat detection in urban environments. |
| The adoption of ISO/IEC 27001 standard encourages organizations to improve their information security management. | Identity & Access Mgmt Tech | The widespread recognition of the ISO/IEC 27001 standard drives enterprises to invest in identity and access management technologies. |
Market growth for Security Tech in China is underpinned by increased government funding, rising cybersecurity threats, and the Smart City Initiative. In 2023, the government allocated $1 billion for public safety technologies, prompting local governments to invest in security systems. More than 70% of enterprises have adopted cybersecurity solutions to combat digital threats. The Smart City Initiative promotes the integration of advanced security technologies in urban areas, driving demand. Continuous monitoring systems are essential for real-time threat detection, especially in urban environments.
Evaluation of Restraints in China Security Tech Market
The key brakes on demand, and where they bite hardest, are shown below.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| High competition among security tech providers can lead to pricing pressures and reduced margins. | Cybersecurity Solutions | In a crowded market, providers struggle to maintain profitability as they compete on price. |
| Regulatory compliance requirements can increase operational costs for security tech providers. | Identity & Access Mgmt Tech | The Cybersecurity Law mandates organizations to improve their cybersecurity practices, raising costs for compliance. |
| Rapid technological changes can make existing solutions obsolete, impacting market stability. | Analytics & AI Security Tech | As technology evolves, providers must continuously innovate to stay relevant, which can strain resources. |
| Economic fluctuations may lead to reduced budgets for security investments among enterprises. | Physical Security Tech | In uncertain economic times, companies often cut back on discretionary spending, including security tech. |
| Market saturation in urban areas can limit growth opportunities for new entrants. | Cybersecurity Solutions | As major cities become saturated with security solutions, new providers find it challenging to gain market share. |
China Security Tech Market Challenges
China's security tech market encounters a skills shortage, with only 30% of professionals qualified in cybersecurity, limiting the effectiveness of protective measures for enterprises. Supply chain delays are common, as over 60% of suppliers report hardware shortages, extending project timelines for buyers by six months. Regulatory challenges arise from the Cybersecurity Law, imposing strict compliance requirements that elevate operational costs for companies, especially in critical infrastructure sectors. Technological integration poses difficulties, with 40% of firms struggling to implement AI-driven solutions, impeding their capacity to improve security analytics and threat responses.
Trends in the China Security Tech Market
The trends below show where the China Security Tech Market is heading.
- Shift towards AI-Driven Security Solutions: Demand for AI-driven security analytics is projected to grow by 15% annually as enterprises seek advanced solutions to improve operations. This trend reflects a broader shift towards integrating AI technologies in security systems.
- Increased Adoption of Continuous Monitoring: Enterprise IT teams are increasingly implementing continuously operated security systems, with a share of 45% in 2025. This trend highlights the need for ongoing security monitoring to address evolving threats.
- Expansion of Smart City Initiatives: Beijing and Shanghai are leading regions for security tech adoption, driven by the Smart City Initiative launched in 2023. This initiative aims to integrate advanced security technologies into urban management, improving public safety.
- Growing Importance of Cybersecurity Standards: The ISO/IEC 27001 standard is widely recognized in China, promoting best practices in information security management. Its adoption is expected to increase as organizations seek to strengthen their cybersecurity frameworks.
Investment Opportunities in the China Security Tech Market
The following opportunities in the China Security Tech Market pair current demand with a clear way in.
- $1 billion allocated for public safety technologies: With the government designating $1 billion in 2023 for public safety technologies, there exists an opportunity for suppliers of security tech solutions to address the growing demand in urban areas.
- Emerging demand for AI-driven analytics: As the appetite for AI-driven security analytics increases, suppliers can concentrate on developing advanced solutions to meet the needs of enterprises seeking enhanced security measures, particularly in urban settings.
- Urban areas seeking integrated security solutions: Cities are increasingly pursuing integrated security solutions under the Smart City Initiative, presenting opportunities for providers to deliver comprehensive security systems and services.
- Fortune 500 Companies investing in advanced security: Fortune 500 companies are prominent adopters of advanced security solutions, creating opportunities for suppliers to engage with these enterprises and offer tailored security technologies.
Government Initiatives in the China Security Tech Market
The Cybersecurity Law, enacted in 2017 and updated in 2020, mandates organizations to enhance their cybersecurity practices and reporting. This law requires critical infrastructure sectors to implement stringent security measures, ensuring the protection of sensitive data. The National Cybersecurity Strategy, implemented by the Cyberspace Administration of China in 2021, aims to strengthen national cybersecurity measures and promote technological innovation across various sectors. Additionally, the Ministry of Public Security's 2022 plan emphasizes the development of physical security technologies, enhancing public safety in urban areas. Together, these regulations shape the operational landscape for security tech producers and buyers in China.
The Smart City Initiative, launched by the Ministry of Housing and Urban-Rural Development in 2023, focuses on integrating advanced security technologies into urban management. This initiative allocates funding for the deployment of smart surveillance systems and public safety technologies in metropolitan areas. The Ministry of Public Security oversees the integration of physical security technologies, ensuring compliance with national standards. Furthermore, the National Information Security Standardization Technical Committee, established in 2021, develops and promotes security technology standards, facilitating better practices among producers and users of security tech. These measures collectively enhance the effectiveness of security solutions in urban environments.
Future Insight of the China Security Tech Market
By 2032, buyers and suppliers in the China security tech market can expect significant advancements driven by the Smart City Initiative, which will enhance urban security systems. The government's $1 billion investment in public safety technologies will bolster infrastructure and response capabilities. As over 70% of enterprises adopt cybersecurity solutions, adherence to emerging standards will be essential for maintaining effective security management. The projected 15% annual growth in AI-driven security analytics will enable more efficient threat detection and response strategies.
Market Segmentation Analysis
The report offers a comprehensive study of the following market segments and their leading categories in the market.
By Tech Category – Cybersecurity Solutions Dominated, Analytics & AI Security Tech Expected to Grow Fastest
According to Shubham Padhi, Research Analyst at 6Wresearch, Cybersecurity Solutions held a 40% share of the China Security Tech Market by tech category in 2025. Cybersecurity Solutions hold the largest market share due to their crucial function in safeguarding digital assets against cyber threats. With over 70% of enterprises in China adopting these solutions, their importance is underscored by the implementation of the National Cybersecurity Strategy in 2021. The quickest growth will come from Analytics & AI Security Tech, forecast to expand at a CAGR of 7.3% between 2026 and 2032. Analytics & AI Security Tech is experiencing rapid growth as businesses increasingly leverage data analysis to bolster security measures. The projected 15% annual increase in demand for these technologies highlights their vital role in enhancing overall security effectiveness. Suppliers should focus on developing advanced analytics solutions to align with the growing demand in the cybersecurity segment.
By Functionality – Endpoint + Network Dominated, IAM Platforms Expected to Grow Fastest
Endpoint + Network accounted for a 40% market share by functionality in 2025. Endpoint + Network solutions dominate the market share as they are essential for securing both endpoints and network infrastructure. Their critical role in protecting against cyber threats makes them a preferred choice among enterprises, ensuring sustained demand. IAM Platforms are projected to grow fastest, at a CAGR of 6.5% during 2026–2032. IAM Platforms are witnessing the fastest growth due to the rising need for effective management of user identities and permissions. As security breaches frequently stem from identity mismanagement, the demand for these platforms is expected to rise significantly. Buyers must prioritise IAM solutions to strengthen their security posture and mitigate risks associated with identity management.
By Usage Frequency – Continuously Operated Dominated, Real-time Expected to Grow Fastest
With a 45% revenue share in 2025, Continuously Operated was the largest usage frequency category. Continuously Operated systems capture the largest market share as they are necessary for ongoing security monitoring across various sectors. Their requirement for constant vigilance ensures they remain a fundamental aspect of security operations. Over 2026–2032, Real-time is expected to post the fastest growth, at a CAGR of 7.5%. Real-time systems are growing rapidly as they enable immediate responses to security incidents, which is crucial in today’s fast-paced environment. The increasing demand for instant alerts and actions drives their adoption among security teams. Suppliers should innovate in real-time technologies to cater to the rising demand for immediate security responses.
By End User – Enterprise IT Teams Dominated, Security Command Centers Expected to Grow Fastest
The largest end user category in 2025 was Enterprise IT Teams, with a 49% share of total revenue. Enterprise IT Teams represent the largest market share as they are the primary users of security technology for organisational protection. Their direct involvement in managing security measures ensures a steady demand for relevant solutions across various industries. Security Command Centers are set to record the highest CAGR in this split, 7.1% over 2026–2032. Security Command Centers are experiencing the fastest growth as they centralise monitoring and response operations, becoming essential in managing security incidents effectively. The increasing complexity of security threats necessitates their expansion. Buyers should invest in enhancing their security command capabilities to improve incident response and management.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Security Tech Market Outlook
- Market Size of China Security Tech Market, 2025
- Forecast of China Security Tech Market, 2032
- Historical Data and Forecast of China Security Tech Revenues & Volume for the Period 2022 - 2032F
- China Security Tech Market Trend Evolution
- China Security Tech Market Drivers and Challenges
- China Security Tech Price Trends
- China Security Tech Porter's Five Forces
- China Security Tech Industry Life Cycle
- Historical Data and Forecast of China Security Tech Market Revenues & Volume By Tech Category for the Period 2022 - 2032F
- Historical Data and Forecast of China Security Tech Market Revenues & Volume By Cybersecurity Solutions for the Period 2022 - 2032F
- Historical Data and Forecast of China Security Tech Market Revenues & Volume By Physical Security Tech for the Period 2022 - 2032F
- Historical Data and Forecast of China Security Tech Market Revenues & Volume By Identity & Access Mgmt Tech for the Period 2022 - 2032F
- Historical Data and Forecast of China Security Tech Market Revenues & Volume By Analytics & AI Security Tech for the Period 2022 - 2032F
- Historical Data and Forecast of China Security Tech Market Revenues & Volume By Functionality for the Period 2022 - 2032F
- Historical Data and Forecast of China Security Tech Market Revenues & Volume By Endpoint + Network for the Period 2022 - 2032F
- Historical Data and Forecast of China Security Tech Market Revenues & Volume By Sensors + Alarms for the Period 2022 - 2032F
- Historical Data and Forecast of China Security Tech Market Revenues & Volume By IAM Platforms for the Period 2022 - 2032F
- Historical Data and Forecast of China Security Tech Market Revenues & Volume By Video/Log Analysis for the Period 2022 - 2032F
- Historical Data and Forecast of China Security Tech Market Revenues & Volume By Usage Frequency for the Period 2022 - 2032F
- Historical Data and Forecast of China Security Tech Market Revenues & Volume By Continuously Operated for the Period 2022 - 2032F
- Historical Data and Forecast of China Security Tech Market Revenues & Volume By 24/7 Monitoring for the Period 2022 - 2032F
- Historical Data and Forecast of China Security Tech Market Revenues & Volume By Ongoing User Management for the Period 2022 - 2032F
- Historical Data and Forecast of China Security Tech Market Revenues & Volume By Real-time for the Period 2022 - 2032F
- Historical Data and Forecast of China Security Tech Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Security Tech Market Revenues & Volume By Enterprise IT Teams for the Period 2022 - 2032F
- Historical Data and Forecast of China Security Tech Market Revenues & Volume By Institutional Buildings for the Period 2022 - 2032F
- Historical Data and Forecast of China Security Tech Market Revenues & Volume By Fortune 500 Companies for the Period 2022 - 2032F
- Historical Data and Forecast of China Security Tech Market Revenues & Volume By Security Command Centers for the Period 2022 - 2032F
- China Security Tech Import Export Trade Statistics
- Market Opportunity Assessment By Tech Category
- Market Opportunity Assessment By Functionality
- Market Opportunity Assessment By Usage Frequency
- Market Opportunity Assessment By End User
- China Security Tech Top Companies Market Share
- China Security Tech Competitive Benchmarking By Technical and Operational Parameters
- China Security Tech Company Profiles
- China Security Tech Key Strategic Recommendations
Market Covered
Segments analysed in this report are listed below.
By Tech Category
- Cybersecurity Solutions
- Physical Security Tech
- Identity & Access Mgmt Tech
- Analytics & AI Security Tech
By Functionality
- Endpoint + Network
- Sensors + Alarms
- IAM Platforms
- Video/Log Analysis
By Usage Frequency
- Continuously Operated
- 24/7 Monitoring
- Ongoing User Management
- Real-time
By End User
- Enterprise IT Teams
- Institutional Buildings
- Fortune 500 Companies
- Security Command Centers































