China Semiconductor Devices Market Size & Growth Rate
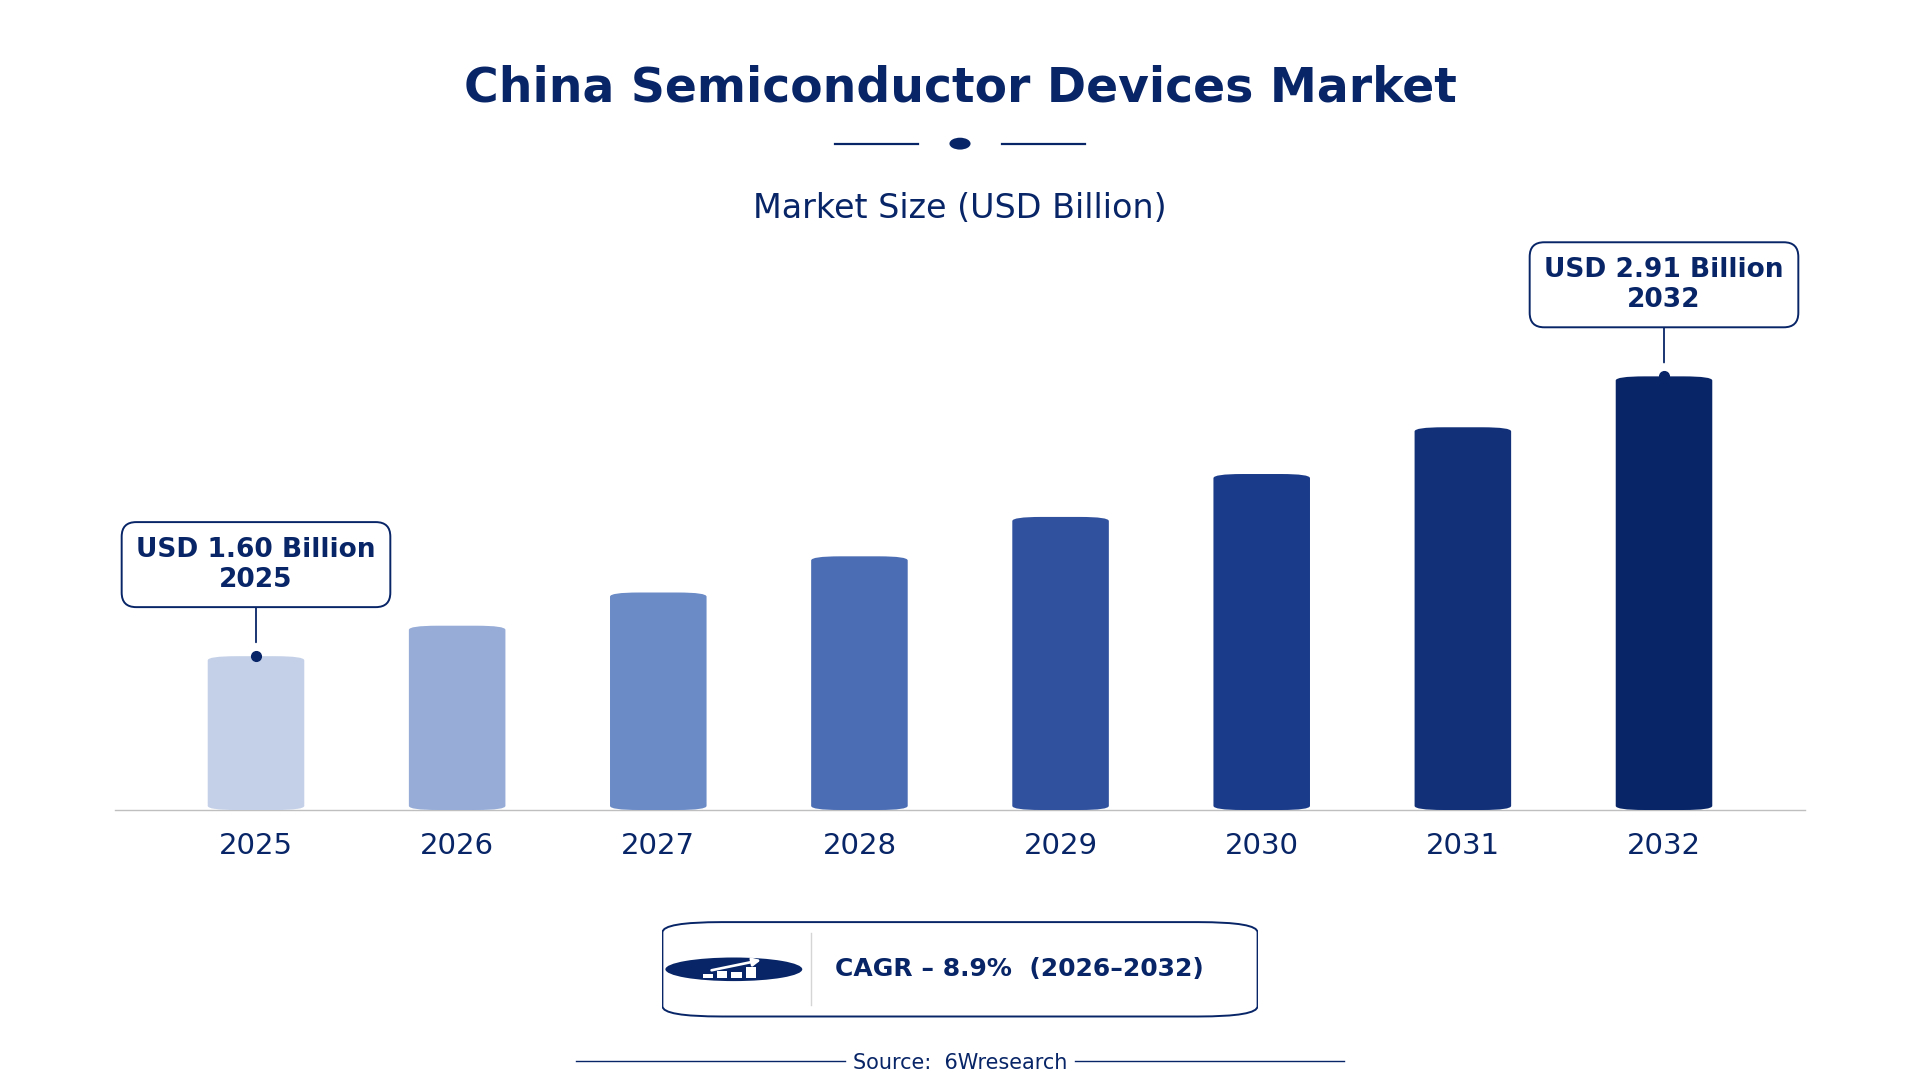
According to 6Wresearch internal database and industry insights, the China Semiconductor Devices Market was valued at USD 1.60 billion in 2025 and is projected to reach USD 2.91 billion by 2032, growing at a CAGR of approximately 8.9% during 2026–2032.
China Semiconductor Devices Market Highlights
| Report Metric | Details |
| Report Name | China Semiconductor Devices Market |
| Market Size 2025 | USD 1.60 billion |
| Market Size 2032 | USD 2.91 billion |
| Absolute Growth 2025–2032 | USD 1.31 billion |
| CAGR 2026–2032 | 8.9% |
| Peak Annual Growth | 10.9% in 2028 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Device Type, 2025 | ICs (Analog/Digital) (39% share) |
| Leading Functionality, 2025 | Signal Processing (37% share) |
| Leading Material Type, 2025 | Silicon (40% share) |
| Leading End User, 2025 | Consumer Electronics OEMs (45% share) |
| Fastest-Growing Device Type | Optoelectronic Devices (10.1% CAGR) |
| Fastest-Growing Functionality | Light Conversion (11.2% CAGR) |
| Fastest-Growing Material Type | GaN (10.6% CAGR) |
| Fastest-Growing End User | LED Manufacturers (11.2% CAGR) |
| Growing Sector | Consumer Electronics |
| Key End Users | Consumer Electronics OEMs, Mobile Device Makers, Industrial Electronics, LED Manufacturers |
China Semiconductor Devices Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
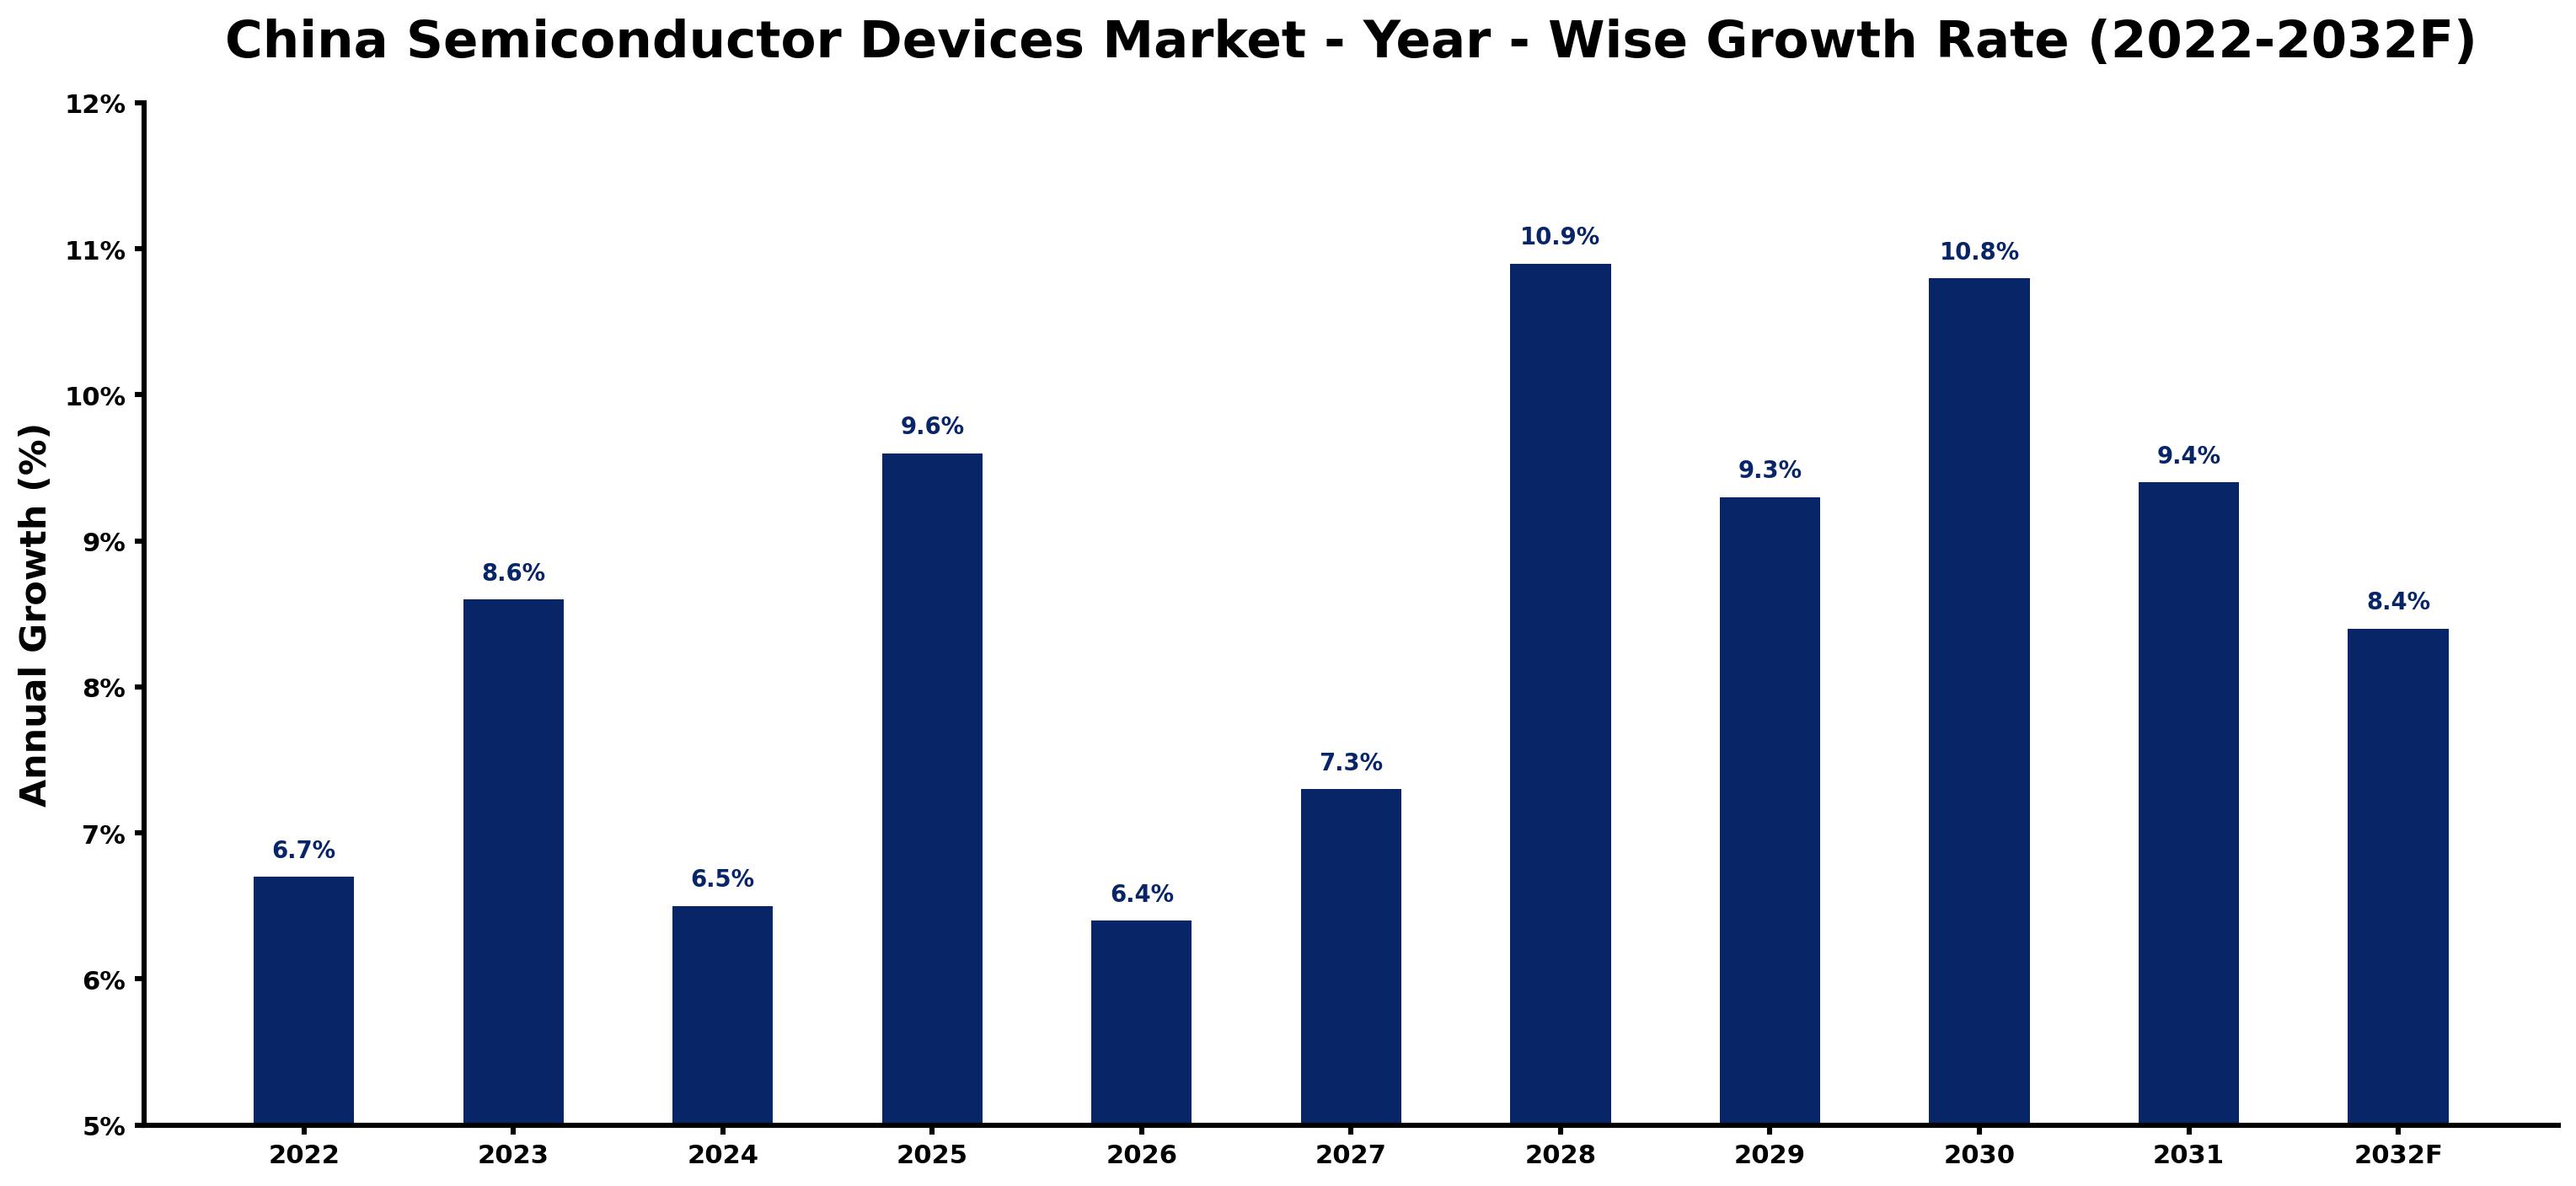
Below, each year's estimated growth is shown next to the factor that most influenced it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 6.7 | The market saw steady demand from consumer electronics and industrial applications. |
| 2023 | 8.6 | Growth accelerated due to increased domestic production and investment in technology. |
| 2024 | 6.5 | Demand growth slowed as supply chain issues impacted production timelines. |
| 2025 | 9.6 | A surge in consumer electronics demand led to faster growth rates this year. |
| 2026 | 6.4 | Growth slowed again as market adjustments took place following previous peaks. |
| 2027 | 7.3 | A rise in automation and smart devices spurred demand for semiconductor devices. |
| 2028 | 10.9 | The market is expected to peak due to advancements in technology and production. |
| 2029 | 9.3 | Growth will decelerate slightly as the market stabilises after rapid expansion. |
| 2030 | 10.8 | An increase in demand for high-performance devices will boost growth again. |
| 2031 | 9.4 | The market is projected to grow at a slower rate as it matures. |
| 2032 | 8.4 | Demand remains strong, but growth is expected to normalise after previous highs. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Semiconductor Devices Market Synopsis
Semiconductor Devices in China include electronic components that manage electricity flow, primarily composed of silicon and gallium nitride. These devices play a crucial role in consumer electronics, telecommunications, and industrial equipment. The China Semiconductor Devices Market is on an upward trajectory, driven by robust domestic demand and investments in local production capabilities. The National Semiconductor Innovation Plan aims to strengthen local manufacturing, while the country's population exceeding 1.4 billion fuels the appetite for consumer electronics. This combination of elements is poised to sustain the market's growth in the coming years.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increasing demand for consumer electronics drives the need for more semiconductor devices, leading to higher production volumes. | Driver | High | Consumer Electronics OEMs |
| Investment in local manufacturing capabilities enhances production efficiency and reduces reliance on imports. | Driver | High | ICs (Analog/Digital) |
| The growing population of over 1.4 billion creates a substantial market for semiconductor devices, particularly in consumer electronics. | Opportunity | High | Consumer Electronics OEMs |
| The Yangtze River Delta's status as a major manufacturing hub offers opportunities for expansion and collaboration within the semiconductor sector. | Opportunity | High | Industrial Electronics |
| High production costs, driven by outdated technology, hinder competitiveness in the semiconductor market. | Restraint | High | Transistors |
| Regulatory compliance requirements can delay product launches, affecting sales timelines and revenue for manufacturers. | Restraint | High | Optoelectronic Devices |
| The China Semiconductor Devices Market faces challenges from global supply chain disruptions impacting raw material availability. | Challenge | Medium | Diodes |
| Competition from international semiconductor manufacturers pressures local companies to innovate and reduce costs. | Challenge | Medium | ICs (Analog/Digital) |
Evaluation of Drivers in China Semiconductor Devices Market (2026–2032)
Below mentioned are some major drivers and their influence on market dynamics.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased production of consumer electronics drives demand for semiconductor devices. | Consumer Electronics OEMs | China's population of over 1.4 billion creates a vast market for electronics. |
| Investment in semiconductor manufacturing capabilities supports local production. | ICs (Analog/Digital) | The 'National Semiconductor Innovation Plan' aims to boost local production efficiency. |
| Growing automation in industrial sectors increases demand for semiconductor devices. | Industrial Electronics | Industrial electronics require advanced semiconductors for automation and control. |
| Rising smartphone sales lead to higher demand for integrated circuits. | Mobile Device Makers | Smartphones heavily rely on ICs for enhanced functionality. |
| The expansion of R&D facilities fosters innovation in semiconductor technologies. | Si | The Beijing-Tianjin-Hebei region is key for semiconductor research and development. |
Growth in the Semiconductor Devices market in China comes from increasing end-use demand in consumer electronics, industrial automation, and mobile devices. The population of over 1.4 billion drives purchases of electronic devices, leading to semiconductor production, which reached over 1.5 billion units in 2022. Investment in local manufacturing capabilities is boosting production efficiency, while rising smartphone sales further increase demand for integrated circuits. The expansion of research and development facilities in the Beijing-Tianjin-Hebei region supports innovation in semiconductor technologies. These factors create a dynamic environment for semiconductor growth.
Evaluation of Restraints in China Semiconductor Devices Market
The main factors holding the market back are set out below.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Supply chain disruptions hinder timely production and delivery. | Si | In 2022, global supply chain issues affected semiconductor availability significantly. |
| High competition among manufacturers may limit profit margins. | Si | The presence of over 300 semiconductor design firms intensifies market competition. |
| Limited access to advanced materials can restrict production capabilities. | Silicon | Silicon wafers account for 70% of the market, making material access critical. |
| Technological advancements require continuous investment in R&D. | ICs (Analog/Digital) | Manufacturers must invest heavily to keep pace with evolving technology. |
| Regulatory compliance can increase operational costs for manufacturers. | ICs (Analog/Digital) | The Integrated Circuit Industry Development Promotion Law imposes specific requirements. |
China Semiconductor Devices Market Challenges
The China Semiconductor Devices Market struggles with high demand from buyers that outstrips local production capabilities. This imbalance exists because domestic manufacturing cannot keep pace with the rapid growth in consumer electronics, resulting in product shortages for manufacturers. Producers also face challenges from outdated technology, which raises production costs by approximately 15%, impacting their competitiveness. Regulatory compliance adds to the burden; navigating government standards can delay product launches, affecting sales timelines for distributors and ultimately resulting in lost revenue for end-users.
Trends in the China Semiconductor Devices Market
Several trends are reshaping the China Semiconductor Devices Market; the most important are set out below.
- Shift from Silicon to Gallium Nitride in Power Applications: The semiconductor industry is increasingly adopting gallium nitride for high-efficiency power devices. This shift is driven by the need for improved thermal performance, with GaN projected to grow at a CAGR of 10.6% from 2026 to 2032.
- Rise of Smart Devices in Consumer Electronics: The demand for smart home devices is surging, resulting in increased semiconductor usage. In 2022, consumer electronics accounted for 45% of the semiconductor market, underscoring this trend.
- Expansion of R&D Facilities in Beijing-Tianjin-Hebei: The Beijing-Tianjin-Hebei region is emerging as a hub for semiconductor research and development. This area is expected to attract significant investment, boosting innovation capabilities in the sector.
- Increasing Focus on LED Technology: LED manufacturers are prioritising advancements in optoelectronic devices, with this segment anticipated to grow at 11.2%. This trend reflects the rising demand for energy-efficient lighting solutions.
Investment Opportunities in the China Semiconductor Devices Market
Investors looking at the China Semiconductor Devices Market should consider the following areas.
- Investment in Semiconductor Startups in Yangtze River Delta: The Yangtze River Delta is a crucial area for semiconductor startups, with $10 billion allocated in 2023 to support innovation. This investment creates opportunities for partnerships and technology development.
- Growing Demand for Optoelectronic Devices: With optoelectronic devices projected to grow at a CAGR of 10.1%, suppliers can concentrate on this segment. The increase in LED technology usage presents a substantial opportunity for manufacturers.
- Collaboration with R&D Institutions in Beijing-Tianjin-Hebei: Collaboration with research institutions in the Beijing-Tianjin-Hebei region is vital. This area is a focal point for semiconductor innovation, providing avenues for joint ventures.
- Supply of Advanced Materials for Semiconductor Production: Now is an opportune moment to invest in advanced materials for semiconductor production, as silicon remains dominant. Suppliers can target semiconductor manufacturers requiring high-quality materials.
Government Initiatives in the China Semiconductor Devices Market
In 2023, the 'National Semiconductor Innovation Plan' was launched by the Ministry of Industry and Information Technology to strengthen local semiconductor production capabilities. This plan aims to boost domestic manufacturing and reduce reliance on imports. The '14th Five-Year Plan for the Development of the Semiconductor Industry', approved in 2021, targets a $300 billion market size by 2025. This ambitious goal is backed by substantial government funding and strategic initiatives to promote innovation within the sector.
In 2022, the State Council announced a $20 billion investment to support semiconductor research and development projects. The Ministry of Industry and Information Technology oversees the implementation of these funds, which aim to encourage collaboration among industry players. The 'China Semiconductor Industry Association' was established to promote innovation and cooperation in the semiconductor sector. This association plays a crucial role in facilitating partnerships and sharing best practices among semiconductor manufacturers.
Future Insight of the China Semiconductor Devices Market
By 2032, buyers and suppliers in the China Semiconductor Devices Market will experience notable changes driven by the National Semiconductor Innovation Plan and the 'Made in China 2025' initiative, which prioritise local production. The government's investment of $10 billion to support semiconductor startups will advance technological progress. With the Yangtze River Delta solidifying its role as a major manufacturing hub, production capacity is set to expand significantly. This shift will lead to greater self-sufficiency, reducing reliance on imports.
Market Segmentation Analysis
Each segment group is reviewed below, with the leader by share and the fastest grower by CAGR.
By Device Type – ICs (Analog/Digital) Dominated, Optoelectronic Devices Expected to Grow Fastest
According to Shubham Padhi, Research Analyst at 6Wresearch, the largest device type category in 2025 was ICs (Analog/Digital), with a 39% share of total revenue. ICs, both analog and digital, dominate the China Semiconductor Devices Market due to their essential role in processing signals for consumer electronics. The substantial production of over 1.5 billion semiconductor devices in 2022 highlights the robust demand from this sector. The quickest growth will come from Optoelectronic Devices, forecast to expand at a CAGR of 10.1% between 2026 and 2032. Optoelectronic devices are experiencing rapid growth, driven by their expanding applications in displays and lighting solutions. The increasing integration of smart technologies in consumer electronics is significantly propelling this segment forward, indicating a shift in market focus. Suppliers should prioritise advancements in optoelectronic technology to capture the growing market share.
By Functionality – Signal Processing Dominated, Light Conversion Expected to Grow Fastest
Signal Processing accounted for a 37% market share by functionality in 2025. Signal processing functionality leads the market as ICs are crucial for processing audio and video signals, which are integral to consumer electronics. This high demand from various sectors solidifies its position as the largest segment in the market. Light Conversion is set to record the highest CAGR in this split, 11.2% over 2026–2032. Light conversion is the fastest-growing functionality, spurred by the rising adoption of optoelectronic devices in modern lighting applications. The increasing focus on energy-efficient lighting solutions is significantly boosting this segment's growth, indicating a trend towards sustainability. Buyers should consider the advancements in light conversion technologies to stay competitive in the evolving market.
By Material Type – Silicon Dominated, GaN Expected to Grow Fastest
Silicon took a 40% share of material type in 2025, more than any other category. Silicon is the predominant material in the China Semiconductor Devices Market, accounting for 70% of the market share due to its widespread use in semiconductor manufacturing. Its established supply chain and production processes make it the preferred choice among manufacturers, ensuring consistent availability. GaN is projected to grow fastest, at a CAGR of 10.6% during 2026–2032. Gallium nitride (GaN) is witnessing the fastest growth, particularly in high-efficiency power devices, as industries seek more efficient alternatives. The increasing demand for energy-efficient solutions is driving this segment's rapid expansion, highlighting a shift towards advanced materials. Suppliers should explore opportunities in GaN technology to meet the rising demand for high-efficiency devices.
By End User – Consumer Electronics OEMs Dominated, LED Manufacturers Expected to Grow Fastest
With a 45% revenue share in 2025, Consumer Electronics OEMs was the largest end user category. Consumer electronics OEMs represent the largest end-user segment, as they consistently require semiconductor devices for their products. This sector's vast scale and continuous innovation ensure a steady demand for various semiconductor components, solidifying its market position. Over 2026–2032, LED Manufacturers are expected to post the fastest growth, at a CAGR of 11.2%. LED manufacturers are the fastest-growing end-user group, leveraging optoelectronic devices for advanced lighting solutions. The trend towards smart and energy-efficient lighting is fuelling rapid growth in this area, reflecting broader market shifts towards sustainability. Suppliers must align their offerings with the needs of LED manufacturers to capitalise on this fast-expanding market segment.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Semiconductor Devices Market Outlook
- Market Size of China Semiconductor Devices Market, 2025
- Forecast of China Semiconductor Devices Market, 2032
- Historical Data and Forecast of China Semiconductor Devices Revenues & Volume for the Period 2022 - 2032F
- China Semiconductor Devices Market Trend Evolution
- China Semiconductor Devices Market Drivers and Challenges
- China Semiconductor Devices Price Trends
- China Semiconductor Devices Porter's Five Forces
- China Semiconductor Devices Industry Life Cycle
- Historical Data and Forecast of China Semiconductor Devices Market Revenues & Volume By Device Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Devices Market Revenues & Volume By Diodes for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Devices Market Revenues & Volume By Transistors for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Devices Market Revenues & Volume By ICs (Analog/Digital) for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Devices Market Revenues & Volume By Optoelectronic Devices for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Devices Market Revenues & Volume By Functionality for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Devices Market Revenues & Volume By Rectification for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Devices Market Revenues & Volume By Switching/Amplification for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Devices Market Revenues & Volume By Signal Processing for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Devices Market Revenues & Volume By Light Conversion for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Devices Market Revenues & Volume By Material Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Devices Market Revenues & Volume By Silicon for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Devices Market Revenues & Volume By Si, GaN, SiC for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Devices Market Revenues & Volume By Mixed Signal for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Devices Market Revenues & Volume By Compound Semiconductors for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Devices Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Devices Market Revenues & Volume By Consumer Electronics OEMs for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Devices Market Revenues & Volume By Industrial Electronics for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Devices Market Revenues & Volume By Mobile Device Makers for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Devices Market Revenues & Volume By LED Manufacturers for the Period 2022 - 2032F
- China Semiconductor Devices Import Export Trade Statistics
- Market Opportunity Assessment By Device Type
- Market Opportunity Assessment By Functionality
- Market Opportunity Assessment By Material Type
- Market Opportunity Assessment By End User
- China Semiconductor Devices Top Companies Market Share
- China Semiconductor Devices Competitive Benchmarking By Technical and Operational Parameters
- China Semiconductor Devices Company Profiles
- China Semiconductor Devices Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By Device Type
- Diodes
- Transistors
- ICs (Analog/Digital)
- Optoelectronic Devices
By Functionality
- Rectification
- Switching/Amplification
- Signal Processing
- Light Conversion
By Material Type
- Silicon
- Si
- GaN
- SiC
- Mixed Signal
- Compound Semiconductors
By End User
- Consumer Electronics OEMs
- Industrial Electronics
- Mobile Device Makers
- LED Manufacturers































