China Semiconductor Testing Market Size & Growth Rate
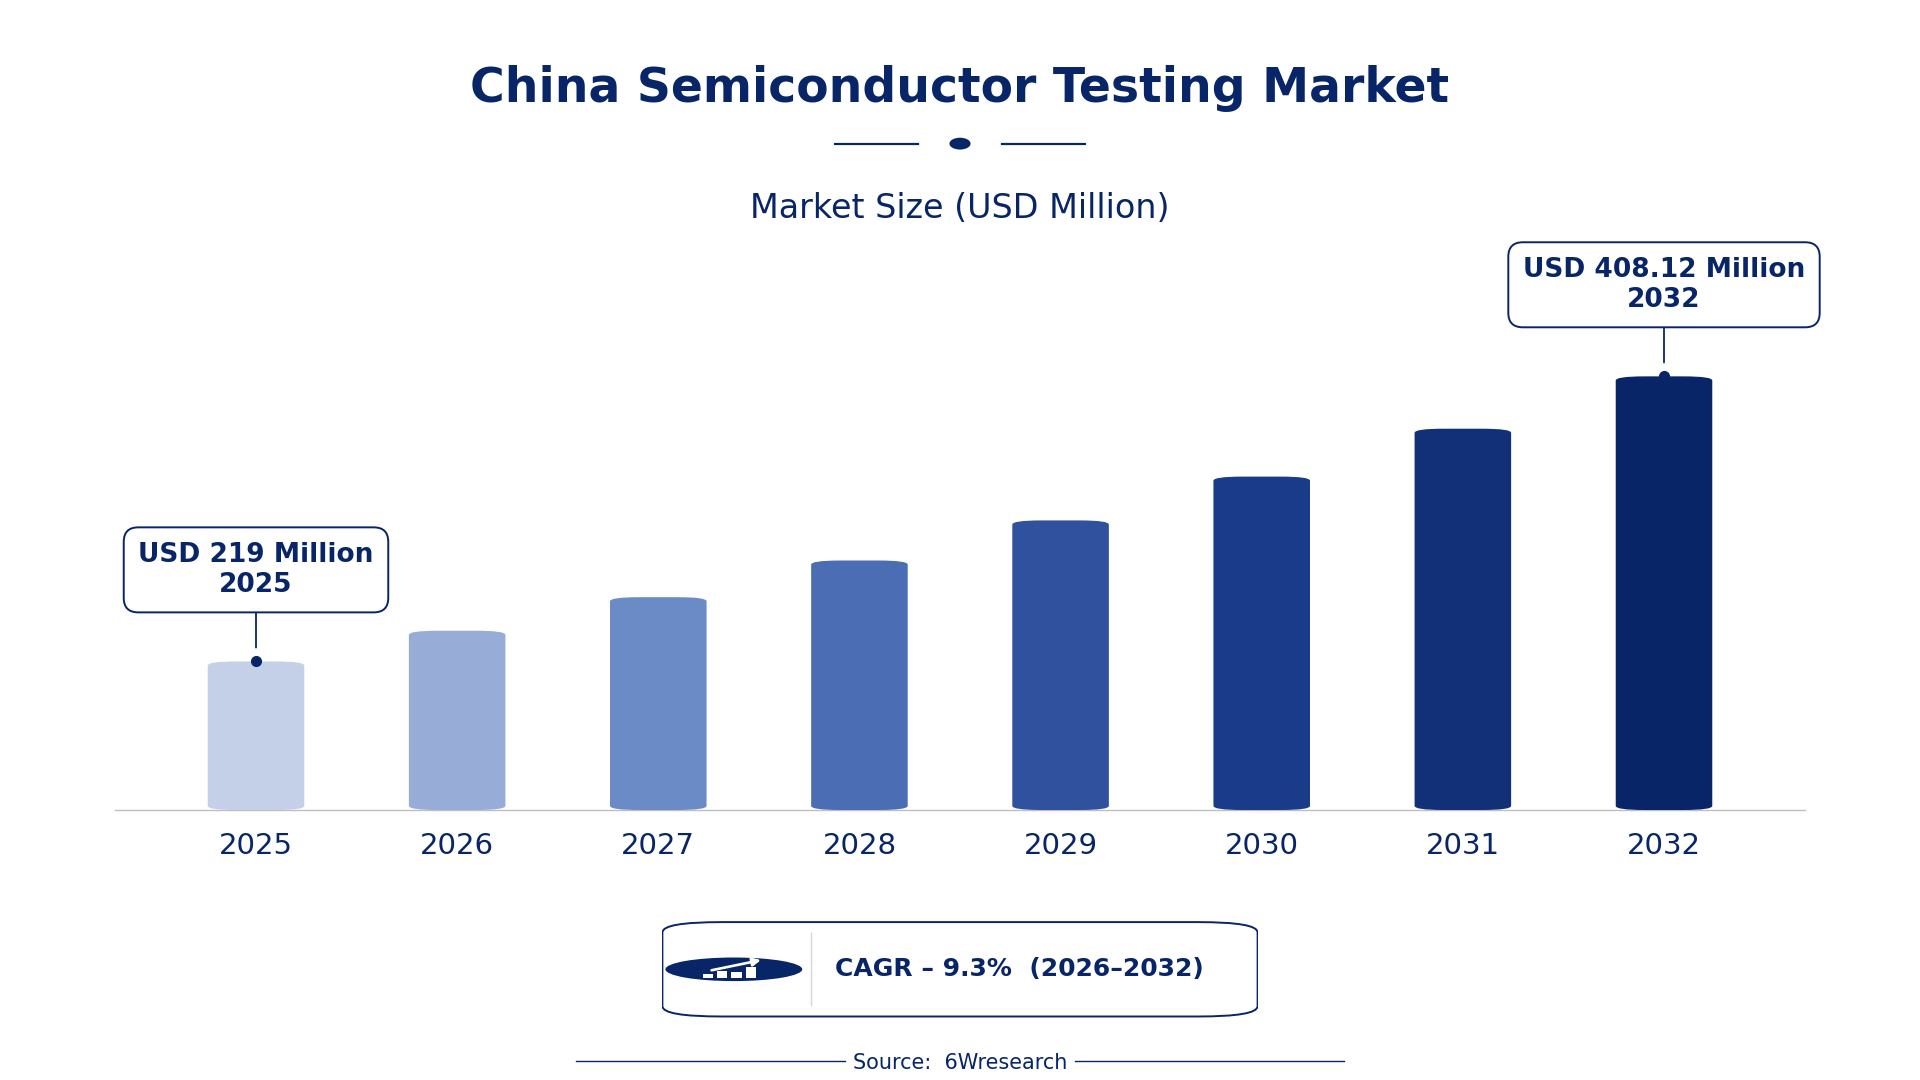
According to 6Wresearch internal database and industry insights, the China Semiconductor Testing Market was valued at USD 219.0 million in 2025 and is projected to reach USD 408.12 million by 2032, growing at a CAGR of approximately 9.3% during 2026–2032.
China Semiconductor Testing Market Highlights
| Report Metric | Details |
| Report Name | China Semiconductor Testing Market |
| Market Size 2025 | USD 219.0 million |
| Market Size 2032 | USD 408.12 million |
| Absolute Growth 2025–2032 | USD 189.12 million |
| CAGR 2026–2032 | 9.3% |
| Peak Annual Growth | 12.0% in 2032 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Testing Type, 2025 | Functional Testing (43% share) |
| Leading Test Stage, 2025 | Post-Fabrication (35% share) |
| Leading Device Tested, 2025 | Logic Devices (43% share) |
| Leading End User, 2025 | Mobile Chip Companies (54% share) |
| Fastest-Growing Testing Type | Parametric Testing (10.8% CAGR) |
| Fastest-Growing Test Stage | Wafer Level (11.0% CAGR) |
| Fastest-Growing Device Tested | Automotive & Military ICs (11.6% CAGR) |
| Fastest-Growing End User | Auto Electronics Vendors (10.6% CAGR) |
| Growing Sector | Automotive Electronics |
| Key End Users | Mobile Chip Companies, Auto Electronics Vendors, Power Semiconductor Makers, Foundries |
China Semiconductor Testing Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
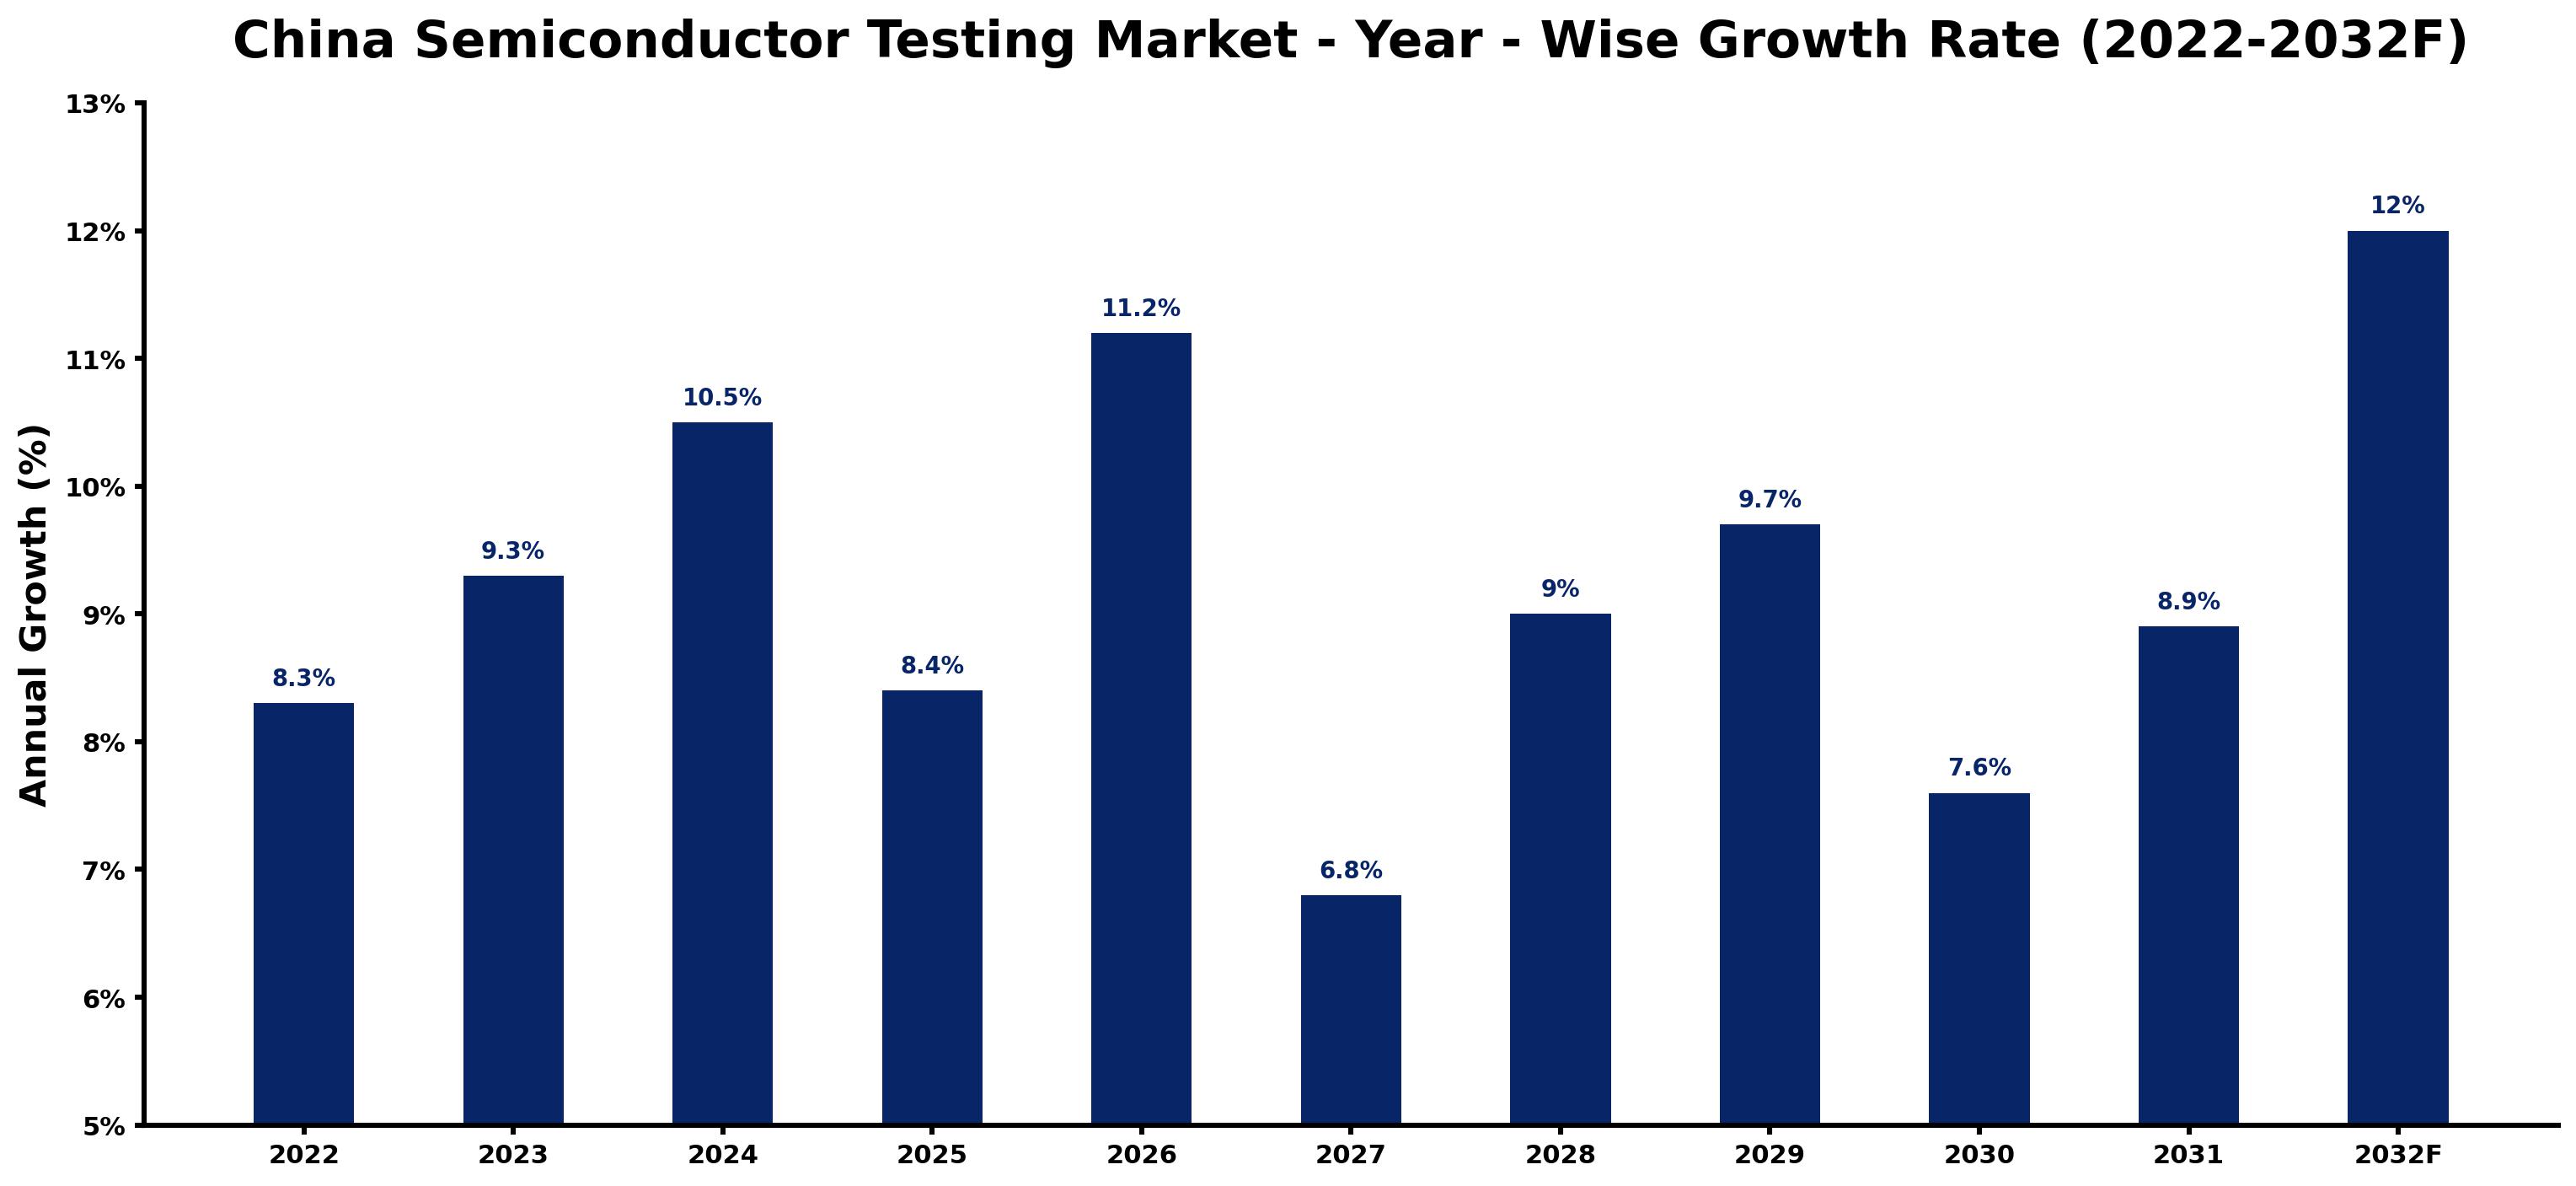
Each row of the following table gives one year's estimated growth and the event or demand shift that explains it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 8.3 | The market showed steady demand from local manufacturers and technology initiatives. |
| 2023 | 9.3 | Growth accelerated due to increased investment in semiconductor testing capabilities. |
| 2024 | 10.5 | Demand surged as domestic companies expanded their production capacity. |
| 2025 | 8.4 | Growth slowed as the market adjusted to previous high rates of expansion. |
| 2026 | 11.2 | Investment in new testing technologies is expected to drive demand for functional testing. |
| 2027 | 6.8 | The 'National Semiconductor Testing Capability Enhancement Program' will support growth in testing services. |
| 2028 | 9.0 | Demand is expected to increase as automotive and military sectors require more reliability testing. |
| 2029 | 9.7 | Renewed interest from mobile chip companies seeking quality assurance will boost demand for parametric testing. |
| 2030 | 7.6 | Growth is projected to slow as the market faces challenges in supply chain management. |
| 2031 | 8.9 | Demand is expected to rise as new standards improve testing efficiency and reliability. |
| 2032 | 12.0 | The market peaks with substantial investment in advanced semiconductor technologies. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Semiconductor Testing Market Synopsis
Semiconductor Testing in China involves assessing the functionality, reliability, and performance of semiconductor devices. This process includes functional, parametric, and yield testing, ensuring product quality and adherence to industry standards. The China Semiconductor Testing Market is expanding due to rising domestic demand from local manufacturers and substantial investments in technology self-sufficiency. Key initiatives such as the 'Integrated Circuit Industry Development Action Plan' are generating new demand, especially from mobile chip companies.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increasing investment in semiconductor testing technologies | Driver | High | Functional Testing |
| Rising demand from mobile chip companies for quality assurance | Driver | High | Mobile Chip Companies |
| Growing need for advanced testing facilities in automotive sectors | Opportunity | High | Auto Electronics Vendors |
| Emerging demand for testing in new energy vehicles | Opportunity | Medium | Auto Electronics Vendors |
| High costs associated with advanced testing equipment | Restraint | High | Parametric Testing |
| Limited availability of skilled workforce in semiconductor testing | Restraint | Medium | Reliability Testing |
| Supply chain disruptions affecting equipment availability | Challenge | High | Yield Testing |
| Approval delays for new testing technologies and standards | Challenge | Medium | Post-Fabrication |
Evaluation of Drivers in China Semiconductor Testing Market (2026–2032)
Below mentioned are some major drivers and their influence on market dynamics.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased investment in semiconductor testing facilities | Functional Testing | The government allocated 10 billion CNY for semiconductor technology innovation, improving testing capabilities. |
| Rising demand from mobile chip companies | Mobile Chip Companies | Domestic mobile chip companies are increasingly utilising testing services to ensure product quality. |
| Expansion of automotive electronics requiring stringent testing | Auto Electronics Vendors | The automotive sector's growth leads to higher demand for reliable semiconductor testing. |
| Technological advancements in testing methods | Parametric Testing | New standards like GB/T 19466 improve testing efficiency and attract investment. |
| Government initiatives supporting semiconductor industry growth | Post-Fabrication | The 'National Semiconductor Testing Capability Enhancement Program' boosts local testing capabilities. |
Market growth for Semiconductor Testing in China is underpinned by increased investment in testing facilities and demand from mobile chip companies. Mobile chip companies are utilising testing services to ensure product quality, driving demand for functional testing. The expansion of automotive electronics requires stringent testing, further boosting the market. New standards like GB/T 19466 improve testing efficiency and attract further investment into the sector.
Evaluation of Restraints in China Semiconductor Testing Market
The key brakes on demand, and where they bite hardest, are shown below.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| High costs associated with advanced testing equipment | Parametric Testing | The need for sophisticated testing tools raises operational costs for manufacturers. |
| Limited availability of skilled workforce in semiconductor testing | Reliability Testing | A shortage of qualified personnel hampers the efficiency of testing processes. |
| Supply chain disruptions affecting equipment availability | Yield Testing | Global supply chain issues delay the procurement of essential testing equipment. |
| Regulatory hurdles for new testing technologies | Post-Fabrication | Approval delays for new standards slow down the adoption of advanced testing methods. |
| Market competition leading to price pressures | Functional Testing | Intense competition among testing service providers affects pricing strategies. |
China Semiconductor Testing Market Challenges
The China semiconductor testing market faces intense competition, with over 1,000 companies vying for market share. This saturation leads to aggressive pricing tactics, which erode profit margins for suppliers and limit their capacity to invest in new testing technologies. High operational costs pose another challenge; the installed base of semiconductor testing equipment is valued at over 5 billion USD, making it difficult for smaller firms to compete effectively. Buyers struggle with slow technology adoption, as the implementation of national standards like GB/T 19466 can delay product launches and increase time-to-market for new devices.
Trends in the China Semiconductor Testing Market
Below mentioned are some of the trends shaping the China Semiconductor Testing Market growth.
- Shift Towards Automated Testing Solutions: The semiconductor testing market is increasingly adopting automated testing solutions to improve efficiency. In 2023, the market saw a 15% rise in automated testing implementations, particularly among mobile chip companies.
- Growing Importance of Reliability Testing: Reliability testing has gained prominence, driven by the automotive sector's demand for safety. In 2022, the automotive segment accounted for 25% of reliability testing services.
- Increased Focus on Compliance with National Standards: Compliance with updated national standards is becoming critical for semiconductor testing. The 'National Standard for Semiconductor Testing' was updated in 2022, impacting testing protocols across the industry.
- Emergence of New Testing Technologies: New testing technologies are reshaping the market, particularly in parametric testing. The introduction of advanced testing methods in 2023 led to a 10% increase in testing efficiency.
Investment Opportunities in the China Semiconductor Testing Market
The following opportunities in the China Semiconductor Testing Market pair current demand with a clear way in.
- Investment in Advanced Testing Facilities: With the semiconductor testing market projected to grow, there is a need for advanced testing facilities. Investing in state-of-the-art facilities in Shanghai can satisfy the increasing demand from local manufacturers.
- Partnerships for Technology Development: Collaborating with local universities for research and development can enhance testing capabilities. The timing is favourable as the government encourages innovation in semiconductor technologies.
- Targeting Automotive Electronics Vendors: The automotive sector is expanding rapidly, creating a demand for reliable testing services. Focusing on auto electronics vendors in Shenzhen can present valuable opportunities for growth.
- Focus on Compliance and Certification Services: As adherence to national standards becomes critical, providing certification services can address a market gap. The 'National Semiconductor Testing Capability Enhancement Program' supports these initiatives.
Government Initiatives in the China Semiconductor Testing Market
The '14th Five-Year Plan for National Economic and Social Development' approved in 2021 emphasizes advancements in semiconductor testing. This plan aims to improve the capabilities of local testing facilities and promote technology innovation. Additionally, the 'Semiconductor Industry Development Fund' launched in 2022 provides financial support for establishing and upgrading testing infrastructures. This funding is essential for enhancing the quality and efficiency of semiconductor testing processes across the country.
The 'Integrated Circuit Industry Development Action Plan' facilitates funding for testing facilities, ensuring they meet national standards. The National Development and Reform Commission also introduced the 'New Energy Vehicle Industry Development Plan', which includes semiconductor testing initiatives. These measures collectively improve the capabilities of testing facilities and support the growth of the semiconductor industry.
Future Insight of the China Semiconductor Testing Market
By 2032, buyers and suppliers in the China semiconductor testing market can anticipate substantial advancements driven by government initiatives and technological innovations. The 'Integrated Circuit Industry Development Action Plan' will encourage improved testing methodologies and standards. A government allocation of 10 billion CNY for semiconductor technology innovation in 2023 will further bolster growth. With the semiconductor testing market expected to expand at an average annual rate of around 15% until 2025, local manufacturers will benefit from enhanced testing capabilities and increased efficiency.
Market Segmentation Analysis
The analysis below covers each segmentation, its leading category in 2025 and its fastest-growing category through 2032.
By Testing Type – Functional Testing Dominated, Parametric Testing Expected to Grow Fastest
According to Shubham Padhi, Research Analyst at 6Wresearch, the largest testing type category in 2025 was Functional Testing, with a 43% share of total revenue. Functional Testing holds the largest share in China's semiconductor testing market because it is essential for verifying the functionality of devices across various applications. The extensive installed base valued at over 5 billion USD in testing equipment underlines the importance of this sub-segment. The quickest growth will come from Parametric Testing, forecast to expand at a CAGR of 10.8% between 2026 and 2032. Parametric Testing is witnessing rapid growth as it becomes increasingly crucial for measuring the electrical characteristics of semiconductor devices. The government's allocation of 10 billion CNY for semiconductor technology innovation in 2023 is expected to further fuel this expansion. Suppliers should enhance their parametric testing capabilities to effectively address the rising demand from local manufacturers.
By Test Stage – Post-Fabrication Dominated, Wafer Level Expected to Grow Fastest
Post-Fabrication accounted for a 35% market share by test stage in 2025. Post-Fabrication testing leads the market as it is vital for ensuring the quality and performance of completed chips before they reach consumers. This stage is critical for maintaining high standards in a competitive landscape with over 1,000 active semiconductor companies in China. Wafer Level is set to record the highest CAGR in this split, 11.0% over 2026–2032. Wafer Level testing is the fastest-growing segment, driven by its importance in early-stage testing processes that can significantly reduce time-to-market for new devices. The increasing focus on rapid innovation in semiconductor technology is propelling this growth. Buyers should prioritise suppliers that offer advanced wafer level testing solutions to remain competitive in the fast-paced semiconductor industry.
By Device Tested – Logic Devices Dominated, Automotive & Military ICs Expected to Grow Fastest
In 2025, Logic Devices led the device tested split with a 43% share. Logic Devices dominate the market due to their widespread use in various applications, ranging from consumer electronics to industrial systems. This broad applicability ensures consistent demand, making them a staple in the semiconductor testing landscape. Over 2026–2032, Automotive & Military ICs are expected to post the fastest growth, at a CAGR of 11.6%. Automotive & Military ICs are the fastest-growing segment, reflecting the heightened emphasis on safety and reliability in automotive technology. The surge in electric vehicle production is a key factor driving this rapid expansion. Suppliers must adapt their testing services to cater to the specific needs of automotive and military applications to capitalise on this growth opportunity.
By End User – Mobile Chip Companies Dominated, Auto Electronics Vendors Expected to Grow Fastest
Mobile Chip Companies held a 54% share of the China Semiconductor Testing Market by end user in 2025. Mobile Chip Companies represent the largest share of the market, as they are pivotal players in the semiconductor industry, driving demand for testing services to ensure high-quality products. Their substantial investments in R&D further solidify their position as market leaders. Auto Electronics Vendors are projected to grow fastest, at a CAGR of 10.6% during 2026–2032. Auto Electronics Vendors are the fastest-growing end-user segment, propelled by the increasing integration of advanced semiconductor technologies in automotive applications. The shift towards smart vehicles is a major catalyst for this growth. Suppliers should enhance their offerings to meet the evolving needs of auto electronics vendors, ensuring they remain competitive in a rapidly changing market.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Semiconductor Testing Market Outlook
- Market Size of China Semiconductor Testing Market, 2025
- Forecast of China Semiconductor Testing Market, 2032
- Historical Data and Forecast of China Semiconductor Testing Revenues & Volume for the Period 2022 - 2032F
- China Semiconductor Testing Market Trend Evolution
- China Semiconductor Testing Market Drivers and Challenges
- China Semiconductor Testing Price Trends
- China Semiconductor Testing Porter's Five Forces
- China Semiconductor Testing Industry Life Cycle
- Historical Data and Forecast of China Semiconductor Testing Market Revenues & Volume By Testing Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Testing Market Revenues & Volume By Functional Testing for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Testing Market Revenues & Volume By Parametric Testing for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Testing Market Revenues & Volume By Reliability Testing for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Testing Market Revenues & Volume By Yield Testing for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Testing Market Revenues & Volume By Test Stage for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Testing Market Revenues & Volume By Post-Fabrication for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Testing Market Revenues & Volume By Wafer Level for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Testing Market Revenues & Volume By Final Packaged Chips for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Testing Market Revenues & Volume By Production for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Testing Market Revenues & Volume By Device Tested for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Testing Market Revenues & Volume By Logic Devices for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Testing Market Revenues & Volume By Analog ICs for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Testing Market Revenues & Volume By Automotive & Military ICs for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Testing Market Revenues & Volume By Memory & SoCs for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Testing Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Testing Market Revenues & Volume By Mobile Chip Companies for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Testing Market Revenues & Volume By Power Semiconductor Makers for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Testing Market Revenues & Volume By Auto Electronics Vendors for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Testing Market Revenues & Volume By Foundries for the Period 2022 - 2032F
- China Semiconductor Testing Import Export Trade Statistics
- Market Opportunity Assessment By Testing Type
- Market Opportunity Assessment By Test Stage
- Market Opportunity Assessment By Device Tested
- Market Opportunity Assessment By End User
- China Semiconductor Testing Top Companies Market Share
- China Semiconductor Testing Competitive Benchmarking By Technical and Operational Parameters
- China Semiconductor Testing Company Profiles
- China Semiconductor Testing Key Strategic Recommendations
Market Covered
Segments analysed in this report are listed below.
By Testing Type
- Functional Testing
- Parametric Testing
- Reliability Testing
- Yield Testing
By Test Stage
- Post-Fabrication
- Wafer Level
- Final Packaged Chips
- Production
By Device Tested
- Logic Devices
- Analog ICs
- Automotive & Military ICs
- Memory & SoCs
By End User
- Mobile Chip Companies
- Power Semiconductor Makers
- Auto Electronics Vendors
- Foundries































