China Shrink Packaging Films Market Size & Growth Rate
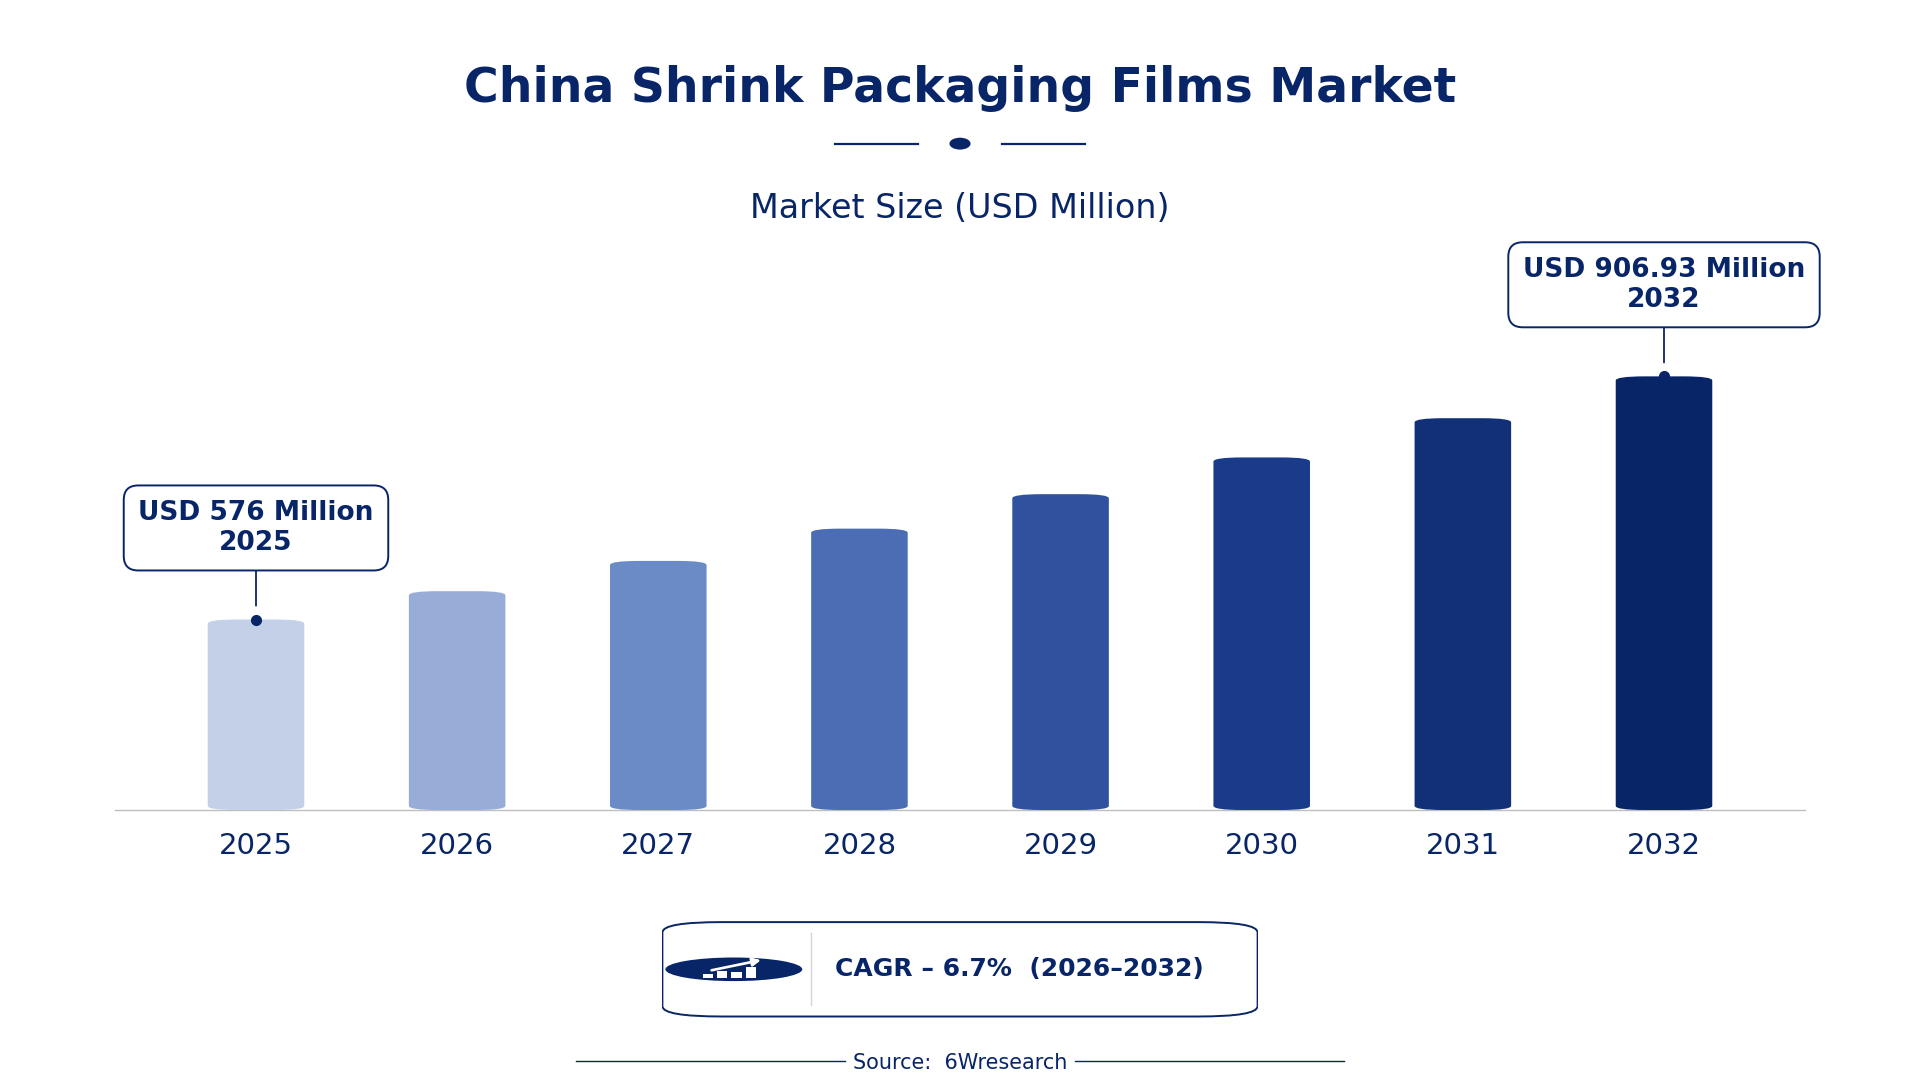
According to 6Wresearch internal database and industry insights, the China Shrink Packaging Films Market was valued at USD 576.0 million in 2025 and is projected to reach USD 906.93 million by 2032, growing at a CAGR of approximately 6.7% during 2026–2032.
China Shrink Packaging Films Market Highlights
| Report Metric | Details |
| Report Name | China Shrink Packaging Films Market |
| Market Size 2025 | USD 576.0 million |
| Market Size 2032 | USD 906.93 million |
| Absolute Growth 2025–2032 | USD 330.93 million |
| CAGR 2026–2032 | 6.7% |
| Peak Annual Growth | 8.3% in 2032 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Film Type, 2025 | Polyolefin Shrink Films (45% share) |
| Leading Material Used, 2025 | POF (45% share) |
| Leading Application Area, 2025 | Food Packaging (41% share) |
| Leading End User, 2025 | FMCG Companies (38% share) |
| Fastest-Growing Film Type | PVC Shrink Films (9.1% CAGR) |
| Fastest-Growing Material Used | Polyvinyl Chloride (8.5% CAGR) |
| Fastest-Growing Application Area | Retail Product Wrapping (8.3% CAGR) |
| Fastest-Growing End User | Retail Chains (8.4% CAGR) |
| Growing Sector | Retail Product Wrapping |
| Key End Users | Food Packaging, Retail Product Wrapping, Industrial Bundling, Eco-Packaging |
China Shrink Packaging Films Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
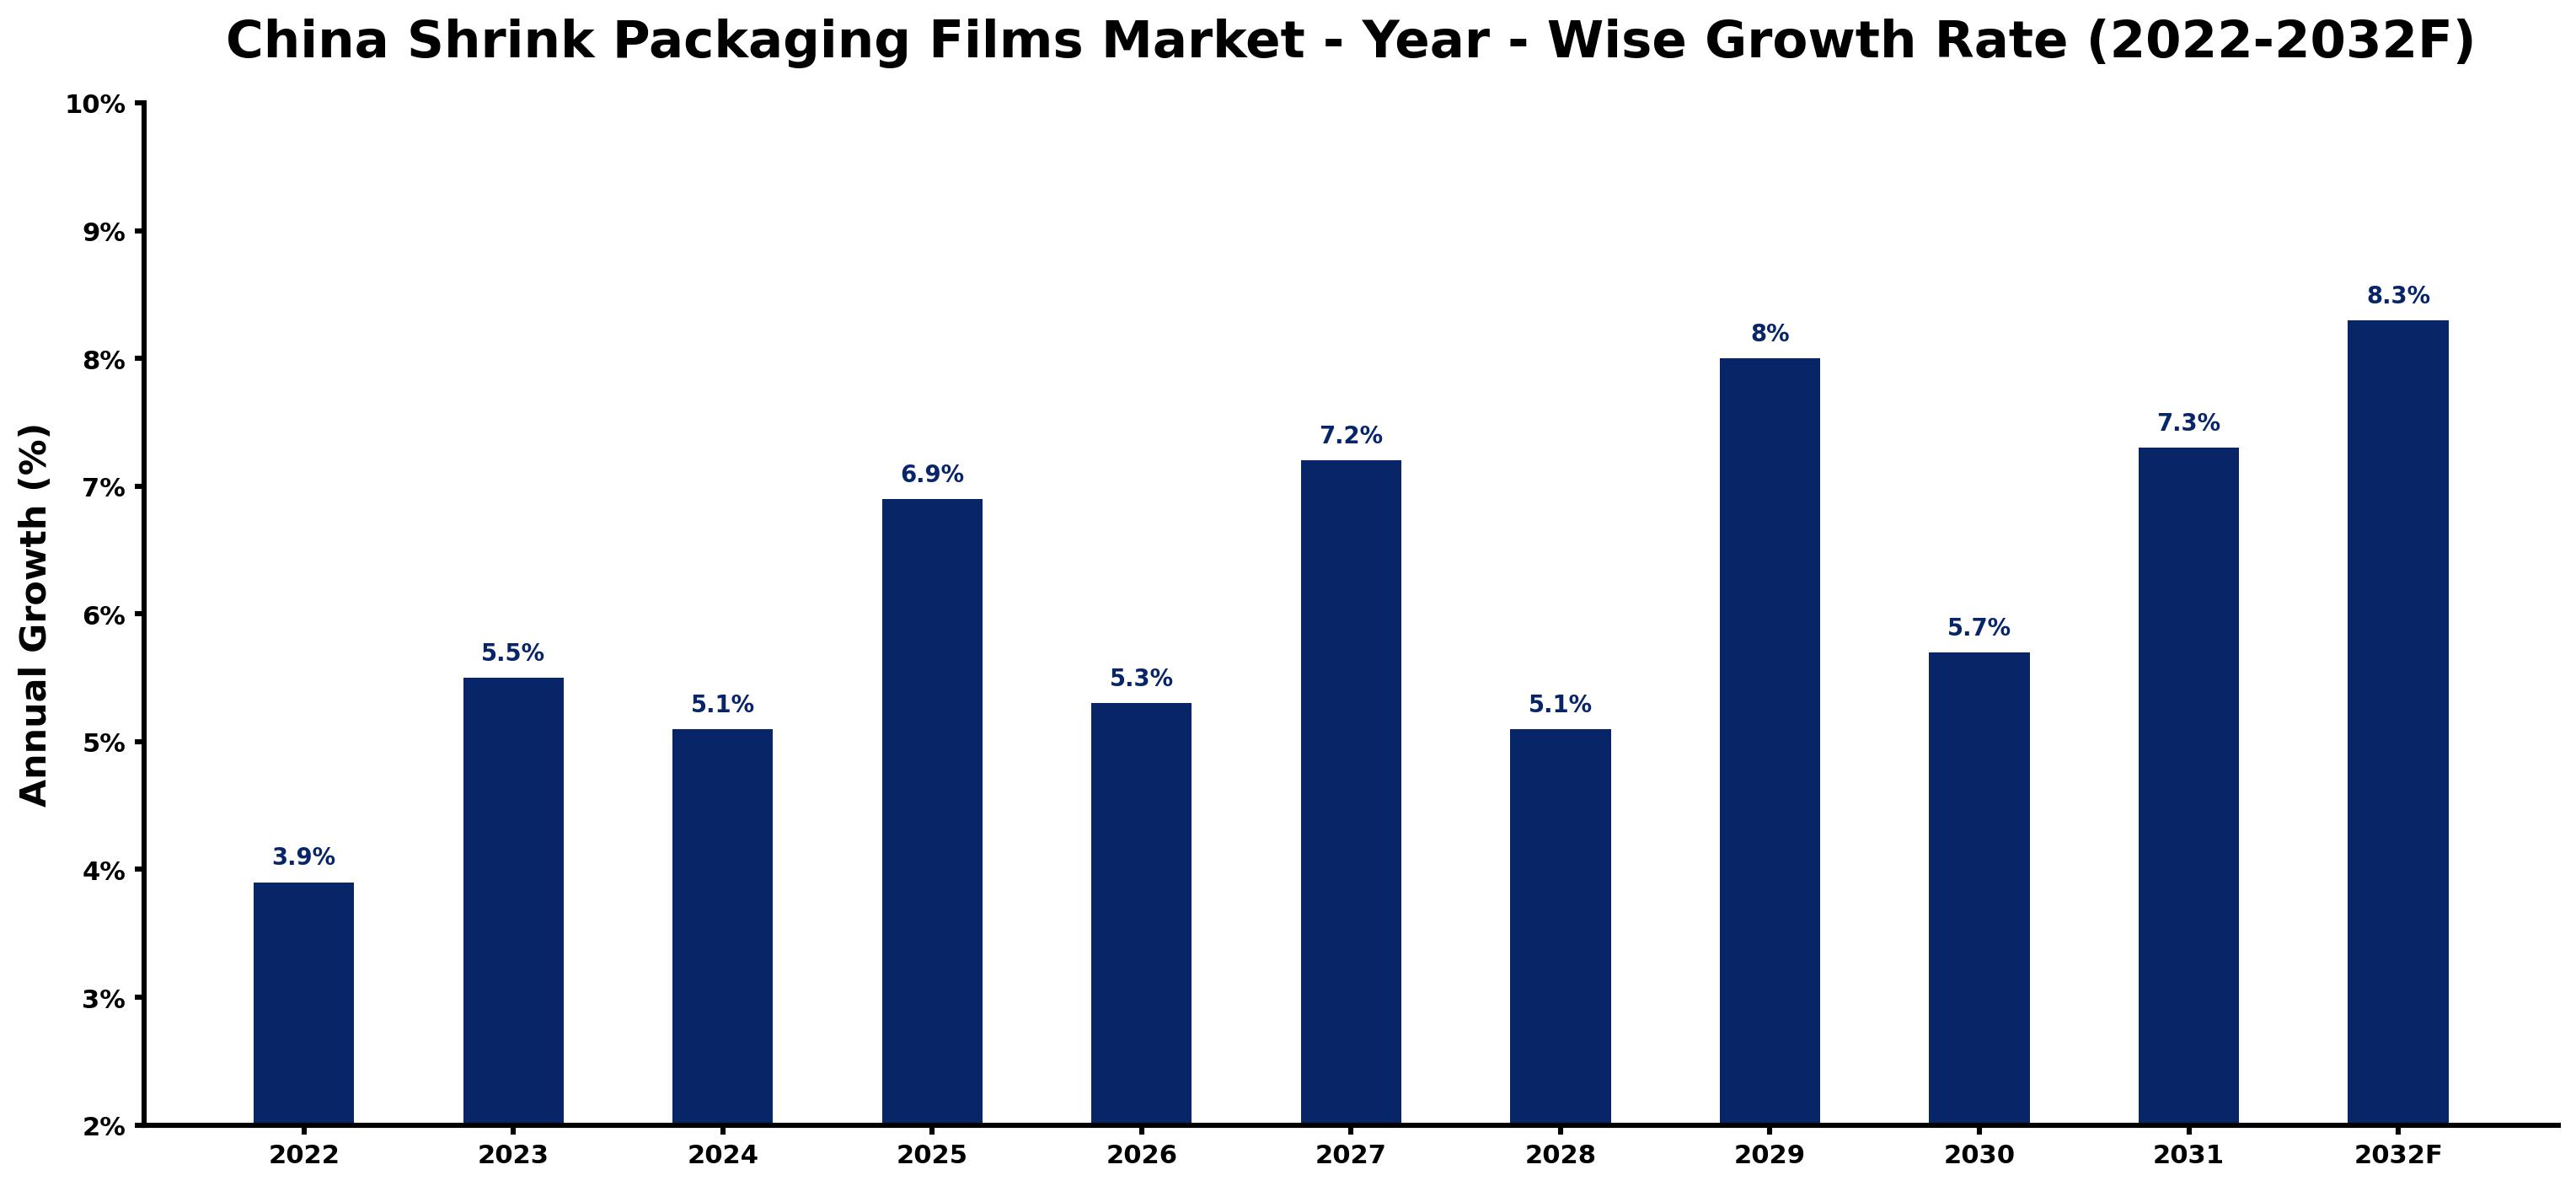
Below, each year's estimated growth is shown next to the factor that most influenced it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 3.9 | The market experienced stable growth supported by rising demand from the food packaging sector. |
| 2023 | 5.5 | Growth accelerated due to increased production capacity in the eastern provinces, such as Jiangsu and Zhejiang. |
| 2024 | 5.1 | The growth rate slowed as manufacturers faced supply chain challenges in sourcing materials. |
| 2025 | 6.9 | Demand surged with the food packaging sector accounting for a large share of shrink film usage. |
| 2026 | 5.3 | A slight slowdown occurred as competition intensified among local manufacturers in the market. |
| 2027 | 7.2 | Growth rebounded with rising demand from logistics and warehousing sectors requiring more packaging. |
| 2028 | 5.1 | The market saw a slowdown as buyers adjusted to new pricing structures in the supply chain. |
| 2029 | 8.0 | Demand increased sharply driven by retail chains requiring more packaging solutions for products. |
| 2030 | 5.7 | Growth slowed as manufacturers faced challenges in sourcing raw materials for production. |
| 2031 | 7.3 | The market grew faster as eco-friendly initiatives gained traction among buyers in the retail sector. |
| 2032 | 8.3 | A peak in growth is expected as the biodegradable segment expands due to rising consumer interest. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Shrink Packaging Films Market Synopsis
Shrink Packaging Films in China are polymer-based materials used to tightly wrap products, primarily in food packaging, retail product wrapping, and industrial bundling. These films are produced by extruding or casting polymers into sheets. The China Shrink Packaging Films Market is expanding due to increasing demand from FMCG companies and retail chains. In 2022, China produced 1.2 million tons of shrink films, with the food packaging sector accounting for 40% of usage. The Green Manufacturing Initiative is driving further adoption of eco-friendly materials, promoting market growth.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Rising demand from the food packaging sector drives the need for efficient packaging solutions. | Driver | High | Food Packaging |
| Growing logistics and warehousing sectors increase the need for bundling solutions. | Driver | High | Industrial Bundling |
| The biodegradable shrink film segment presents opportunities for sustainable packaging solutions. | Opportunity | High | Biodegradable Shrink Films |
| Retail chains are expanding their operations, increasing demand for shrink films. | Opportunity | High | Retail Product Wrapping |
| Environmental regulations pose challenges for traditional PVC shrink films. | Restraint | High | PVC Shrink Films |
| Supply chain disruptions can delay the availability of raw materials for production. | Restraint | Medium | Polyolefin Shrink Films |
| High competition among manufacturers can lead to price wars, affecting profitability. | Challenge | High | Polyethylene Shrink Films |
| Shifts in consumer preferences towards sustainable packaging can disrupt traditional markets. | Challenge | Medium | Biodegradable Shrink Films |
Evaluation of Drivers in China Shrink Packaging Films Market (2026–2032)
Below mentioned are some major drivers and their influence on market dynamics.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Rising demand in the food packaging sector boosts production. | Food Packaging | The food packaging sector accounted for 40% of shrink film usage in 2022. |
| The logistics sector's expansion increases demand for bundling solutions. | Industrial Bundling | Logistics is projected to increase its use of shrink films by 10% by 2025. |
| The Green Manufacturing Initiative promotes eco-friendly materials. | Biodegradable Shrink Films | The biodegradable shrink film market is projected to grow by 15% annually. |
| Retail chains require more shrink films for product display. | Retail Product Wrapping | Retail chains in China utilize over 500,000 tons of shrink films annually. |
| ISO 9001 certification ensures adherence to quality standards. | Polyolefin Shrink Films | Compliance with ISO 9001 is vital for maintaining competitiveness in the market. |
Growth in the Shrink Packaging Films market in China comes from rising demand in the food packaging sector, which accounted for 40% of usage in 2022. Enhanced production capacity in major regions, particularly Jiangsu and Zhejiang, supports this demand. The logistics sector is expected to increase its use of shrink films by 10% by 2025, stimulating further growth. Retail chains are expanding their operations, requiring substantial quantities of shrink films annually for effective product display. The ongoing push for eco-friendly materials is encouraging manufacturers to innovate and adapt their offerings.
Evaluation of Restraints in China Shrink Packaging Films Market
The following restraints limit how fast demand can grow.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Raw material supply issues hinder production timelines. | Polyolefin Shrink Films | Producers face challenges sourcing specific polymers, leading to delays and increased costs. |
| Intense competition drives down prices, affecting profitability. | PVC Shrink Films | Local manufacturers compete aggressively, squeezing profit margins and limiting investments. |
| Regulatory compliance burdens manufacturers with documentation requirements. | Biodegradable Shrink Films | Compliance with national standards can slow down the approval process for new products. |
| Adoption of eco-friendly materials increases production costs. | PLA-based | The shift towards biodegradable options raises costs for producers, impacting pricing for end users. |
| Market saturation limits growth potential for new entrants. | Polyethylene Shrink Films | Established players dominate the market, making it difficult for newcomers to gain traction. |
China Shrink Packaging Films Market Challenges
Manufacturers in the China shrink packaging films market encounter raw material supply issues, as reliance on specific polymers can lead to shortages, causing production delays that increase costs for producers. Intense local competition drives prices down, squeezing profit margins for suppliers and limiting their ability to invest in quality improvements. Compliance with the national standard GB/T 19001-2016 complicates operations, requiring extensive documentation that can delay product approval processes for manufacturers. The push for eco-friendly materials under the Green Packaging Initiative raises production costs for producers, ultimately affecting pricing for end users in the retail sector, where over 500,000 tons of shrink films are consumed annually.
Trends in the China Shrink Packaging Films Market
The trends below show where the China Shrink Packaging Films Market is heading.
- Retail Chains Adopting Eco-Friendly Packaging: Retail chains in China are increasingly adopting eco-friendly packaging solutions, driven by consumer demand for sustainability. The biodegradable shrink film market is expected to grow by 15% annually, reflecting this shift.
- Transition Towards Biodegradable Materials: The market is shifting towards biodegradable shrink films, with 20% of sustainable brands adopting PLA-based options. This change aligns with the Green Manufacturing Initiative launched in 2023.
- Growth of the Logistics Sector Driving Demand: The logistics sector's expansion is leading to increased demand for shrink films, with a projected 10% rise in usage by 2025. This trend highlights the need for efficient bundling solutions.
- Food Packaging Continues to Dominate: Food packaging remains the largest application area for shrink films, accounting for 40% of usage in 2022. This sector's stability supports ongoing production and innovation in film technology.
Investment Opportunities in the China Shrink Packaging Films Market
Investors looking at the China Shrink Packaging Films Market should consider the following areas.
- Investment in Eco-Friendly Shrink Films: The biodegradable shrink film market is expected to grow by 15% annually, creating opportunities for suppliers to invest in sustainable materials. Retail chains are increasingly seeking eco-friendly packaging solutions.
- Expansion of Production Capacity: With China producing 1.2 million tons of shrink films in 2022, there is a significant gap for increased production capacity. Facilities in Jiangsu and Zhejiang are ideal for investment.
- Rising Demand for Innovative Packaging Solutions: The demand for innovative packaging solutions is increasing, particularly in the food sector. Collaborating with logistics companies can enhance product offerings and market reach.
- Entry into the Retail Sector: Retail chains require substantial quantities of shrink films annually, presenting a lucrative opportunity for manufacturers. Forming joint ventures with local distributors can facilitate market entry.
Government Initiatives in the China Shrink Packaging Films Market
The National Plastic Waste Reduction Strategy, launched by the Ministry of Ecology and Environment in 2021, promotes sustainable packaging solutions, impacting producers by encouraging the adoption of eco-friendly materials. This strategy aims to reduce plastic waste and improve recycling efforts across the industry. Additionally, the Packaging Waste Management Regulation introduced by the State Administration for Market Regulation in 2022 enforces recycling standards, requiring manufacturers to comply with specific guidelines to ensure sustainable practices.
The Eco-Friendly Packaging Promotion Program initiated by the Ministry of Commerce in 2022 incentivizes companies adopting sustainable packaging practices. This program provides funding and support for businesses transitioning to eco-friendly materials, helping them meet regulatory requirements. The Green Manufacturing Initiative announced by the Ministry of Industry and Information Technology in 2023 further supports the development of eco-friendly packaging materials, with a budget of 500 million yuan to encourage innovation in the sector.
Future Insight of the China Shrink Packaging Films Market
By 2032, the China shrink packaging films market will undergo significant changes, driven by advancements in polymer technology and a shift towards biodegradable materials. The logistics sector is expected to increase its shrink film usage by 10% by 2025, creating additional demand for innovative solutions. Support from the China Plastics Processing Industry Association will encourage further innovation in the sector. As more brands adopt eco-friendly solutions, the market will evolve, providing diverse product options for buyers and suppliers.
Market Segmentation Analysis
The analysis below covers each segmentation, its leading category in 2025 and its fastest-growing category through 2032.
By Film Type – Polyolefin Shrink Films Dominated, PVC Shrink Films Expected to Grow Fastest
According to Dhaval Chaurasia, Assistant Manager at 6Wresearch, the largest film type category in 2025 was Polyolefin Shrink Films, with a 45% share of total revenue. Polyolefin shrink films hold the largest share in the market due to their clarity and strength, making them particularly suitable for food packaging applications. The food packaging sector, which accounts for 40% of shrink film usage, is a key driver for this material's widespread adoption. PVC Shrink Films are projected to grow fastest, at a CAGR of 9.1% during 2026–2032. PVC shrink films are experiencing notable growth as they find niche applications in specific retail and promotional packaging contexts. This segment's expansion is propelled by their cost-effectiveness, despite facing scrutiny over environmental concerns. Suppliers should prioritise the production of polyolefin films while also exploring PVC applications to cater to diverse market requirements.
By Material Used – POF Dominated, Polyvinyl Chloride Expected to Grow Fastest
With a 45% revenue share in 2025, POF was the largest material used category. POF holds the largest market share due to its versatility and superior performance in food packaging, where clarity and durability are essential. This material is particularly popular among manufacturers in the eastern provinces, such as Jiangsu and Zhejiang, known for their robust production capabilities. The quickest growth will come from Polyvinyl Chloride, forecast to expand at a CAGR of 8.5% between 2026 and 2032. Polyvinyl Chloride is experiencing growth in specific applications, driven by its cost-effectiveness in certain retail environments. Despite facing regulatory challenges, its affordability continues to attract interest from some sectors, ensuring its relevance in the market. Suppliers should focus on compliance with regulations while exploring innovative applications for polyvinyl chloride to capitalise on emerging opportunities.
By Application Area – Food Packaging Dominated, Retail Product Wrapping Expected to Grow Fastest
Food Packaging took a 41% share of application area in 2025, more than any other category. Food packaging represents the largest application area for shrink films, driven by high demand from the food sector. This segment's substantial share is supported by the extensive use of shrink films in preserving product freshness and appeal. Retail Product Wrapping is set to record the highest CAGR in this split, 8.3% over 2026–2032. Retail product wrapping is growing rapidly as consumer goods require effective display and protection. The increasing number of retail chains utilising shrink films for packaging is a key factor in this segment's growth. Suppliers must align their product offerings with the needs of the retail sector to capitalise on the rising demand for effective packaging solutions.
By End User – FMCG Companies Dominated, Retail Chains Expected to Grow Fastest
FMCG Companies accounted for a 38% market share by end user in 2025. FMCG companies are the primary consumers of shrink films, using them extensively for packaging their products. This segment's leading position stems from the high volume of goods that necessitate effective and visually appealing packaging solutions. Over 2026–2032, Retail Chains are expected to post the fastest growth, at a CAGR of 8.4%. Retail chains are rapidly increasing their consumption of shrink films for product display and protection, highlighting the growing significance of packaging in retail strategies. The demand from this sector is projected to surge as competition heightens. Suppliers should focus on building partnerships with retail chains to ensure their products align with the evolving packaging needs of the market.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Shrink Packaging Films Market Outlook
- Market Size of China Shrink Packaging Films Market, 2025
- Forecast of China Shrink Packaging Films Market, 2032
- Historical Data and Forecast of China Shrink Packaging Films Revenues & Volume for the Period 2022 - 2032F
- China Shrink Packaging Films Market Trend Evolution
- China Shrink Packaging Films Market Drivers and Challenges
- China Shrink Packaging Films Price Trends
- China Shrink Packaging Films Porter's Five Forces
- China Shrink Packaging Films Industry Life Cycle
- Historical Data and Forecast of China Shrink Packaging Films Market Revenues & Volume By Film Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Shrink Packaging Films Market Revenues & Volume By Polyolefin Shrink Films for the Period 2022 - 2032F
- Historical Data and Forecast of China Shrink Packaging Films Market Revenues & Volume By PVC Shrink Films for the Period 2022 - 2032F
- Historical Data and Forecast of China Shrink Packaging Films Market Revenues & Volume By Polyethylene Shrink Films for the Period 2022 - 2032F
- Historical Data and Forecast of China Shrink Packaging Films Market Revenues & Volume By Biodegradable Shrink Films for the Period 2022 - 2032F
- Historical Data and Forecast of China Shrink Packaging Films Market Revenues & Volume By Material Used for the Period 2022 - 2032F
- Historical Data and Forecast of China Shrink Packaging Films Market Revenues & Volume By POF for the Period 2022 - 2032F
- Historical Data and Forecast of China Shrink Packaging Films Market Revenues & Volume By Polyvinyl Chloride for the Period 2022 - 2032F
- Historical Data and Forecast of China Shrink Packaging Films Market Revenues & Volume By LDPE/HDPE for the Period 2022 - 2032F
- Historical Data and Forecast of China Shrink Packaging Films Market Revenues & Volume By PLA-based for the Period 2022 - 2032F
- Historical Data and Forecast of China Shrink Packaging Films Market Revenues & Volume By Application Area for the Period 2022 - 2032F
- Historical Data and Forecast of China Shrink Packaging Films Market Revenues & Volume By Food Packaging for the Period 2022 - 2032F
- Historical Data and Forecast of China Shrink Packaging Films Market Revenues & Volume By Retail Product Wrapping for the Period 2022 - 2032F
- Historical Data and Forecast of China Shrink Packaging Films Market Revenues & Volume By Industrial Bundling for the Period 2022 - 2032F
- Historical Data and Forecast of China Shrink Packaging Films Market Revenues & Volume By Eco-Packaging for the Period 2022 - 2032F
- Historical Data and Forecast of China Shrink Packaging Films Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Shrink Packaging Films Market Revenues & Volume By FMCG Companies for the Period 2022 - 2032F
- Historical Data and Forecast of China Shrink Packaging Films Market Revenues & Volume By Retail Chains for the Period 2022 - 2032F
- Historical Data and Forecast of China Shrink Packaging Films Market Revenues & Volume By Logistics & Warehousing for the Period 2022 - 2032F
- Historical Data and Forecast of China Shrink Packaging Films Market Revenues & Volume By Sustainable Brands for the Period 2022 - 2032F
- China Shrink Packaging Films Import Export Trade Statistics
- Market Opportunity Assessment By Film Type
- Market Opportunity Assessment By Material Used
- Market Opportunity Assessment By Application Area
- Market Opportunity Assessment By End User
- China Shrink Packaging Films Top Companies Market Share
- China Shrink Packaging Films Competitive Benchmarking By Technical and Operational Parameters
- China Shrink Packaging Films Company Profiles
- China Shrink Packaging Films Key Strategic Recommendations
Market Covered
The report offers an extensive study of the following market segments.
By Film Type
- Polyolefin Shrink Films
- PVC Shrink Films
- Polyethylene Shrink Films
- Biodegradable Shrink Films
By Material Used
- POF
- Polyvinyl Chloride
- LDPE/HDPE
- PLA-based
By Application Area
- Food Packaging
- Retail Product Wrapping
- Industrial Bundling
- Eco-Packaging
By End User
- FMCG Companies
- Retail Chains
- Logistics & Warehousing
- Sustainable Brands































