China Shrink Packaging Market Size & Growth Rate
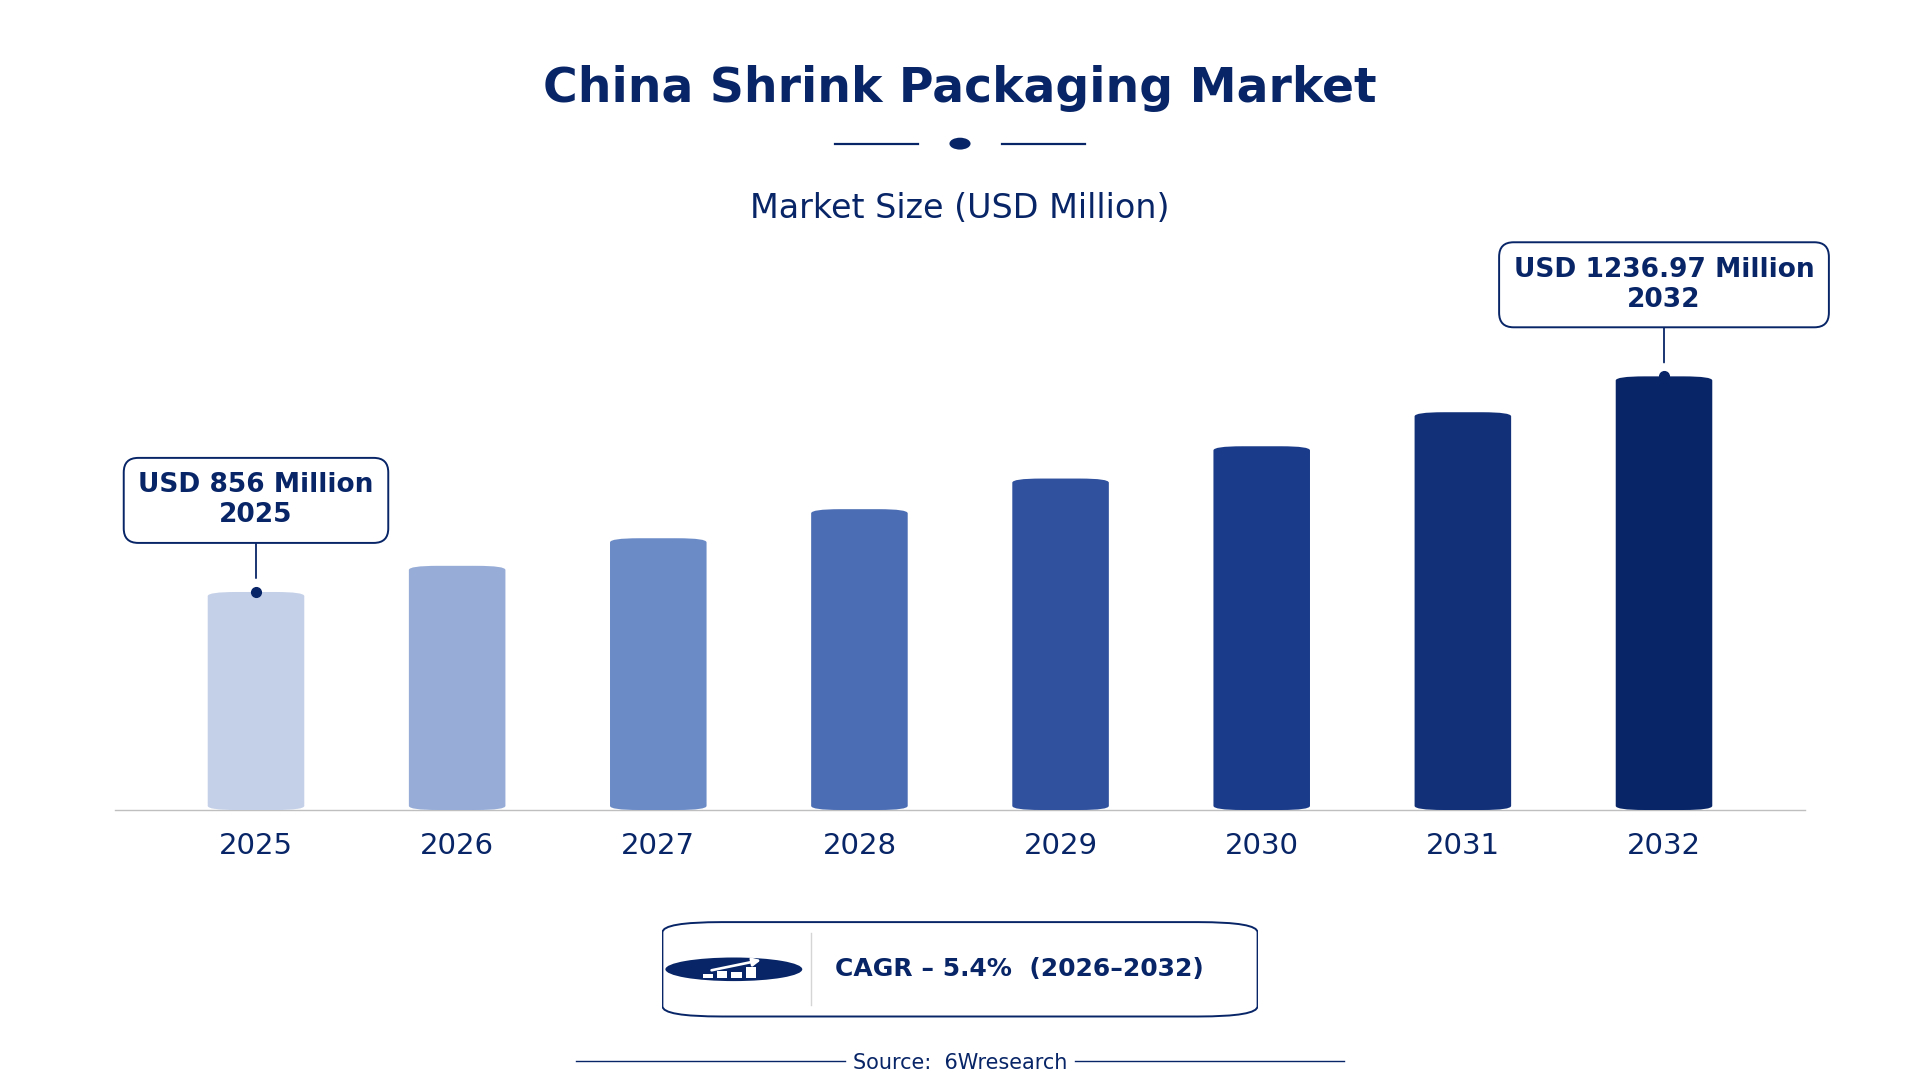
According to 6Wresearch internal database and industry insights, the China Shrink Packaging Market was valued at USD 856.0 million in 2025 and is projected to reach USD 1,236.97 million by 2032, growing at a CAGR of approximately 5.4% during 2026–2032.
China Shrink Packaging Market Highlights
| Report Metric | Details |
| Report Name | China Shrink Packaging Market |
| Market Size 2025 | USD 856.0 million |
| Market Size 2032 | USD 1,236.97 million |
| Absolute Growth 2025–2032 | USD 380.97 million |
| CAGR 2026–2032 | 5.4% |
| Peak Annual Growth | 7.3% in 2030 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Packaging Type, 2025 | Shrink Wrap (41% share) |
| Leading Material Type, 2025 | Polyolefin (41% share) |
| Leading Application, 2025 | Product Unitization (39% share) |
| Leading End User, 2025 | Food & Beverage Companies (40% share) |
| Fastest-Growing Packaging Type | Shrink Sleeves (6.9% CAGR) |
| Fastest-Growing Material Type | PET-G/OPS (7.6% CAGR) |
| Fastest-Growing Application | Labeling (7.4% CAGR) |
| Fastest-Growing End User | Bottling Companies (7.6% CAGR) |
| Growing Sector | Food and Beverage |
| Key End Users | Food & Beverage Companies, Bottling Companies, Consumer Product Brands |
China Shrink Packaging Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
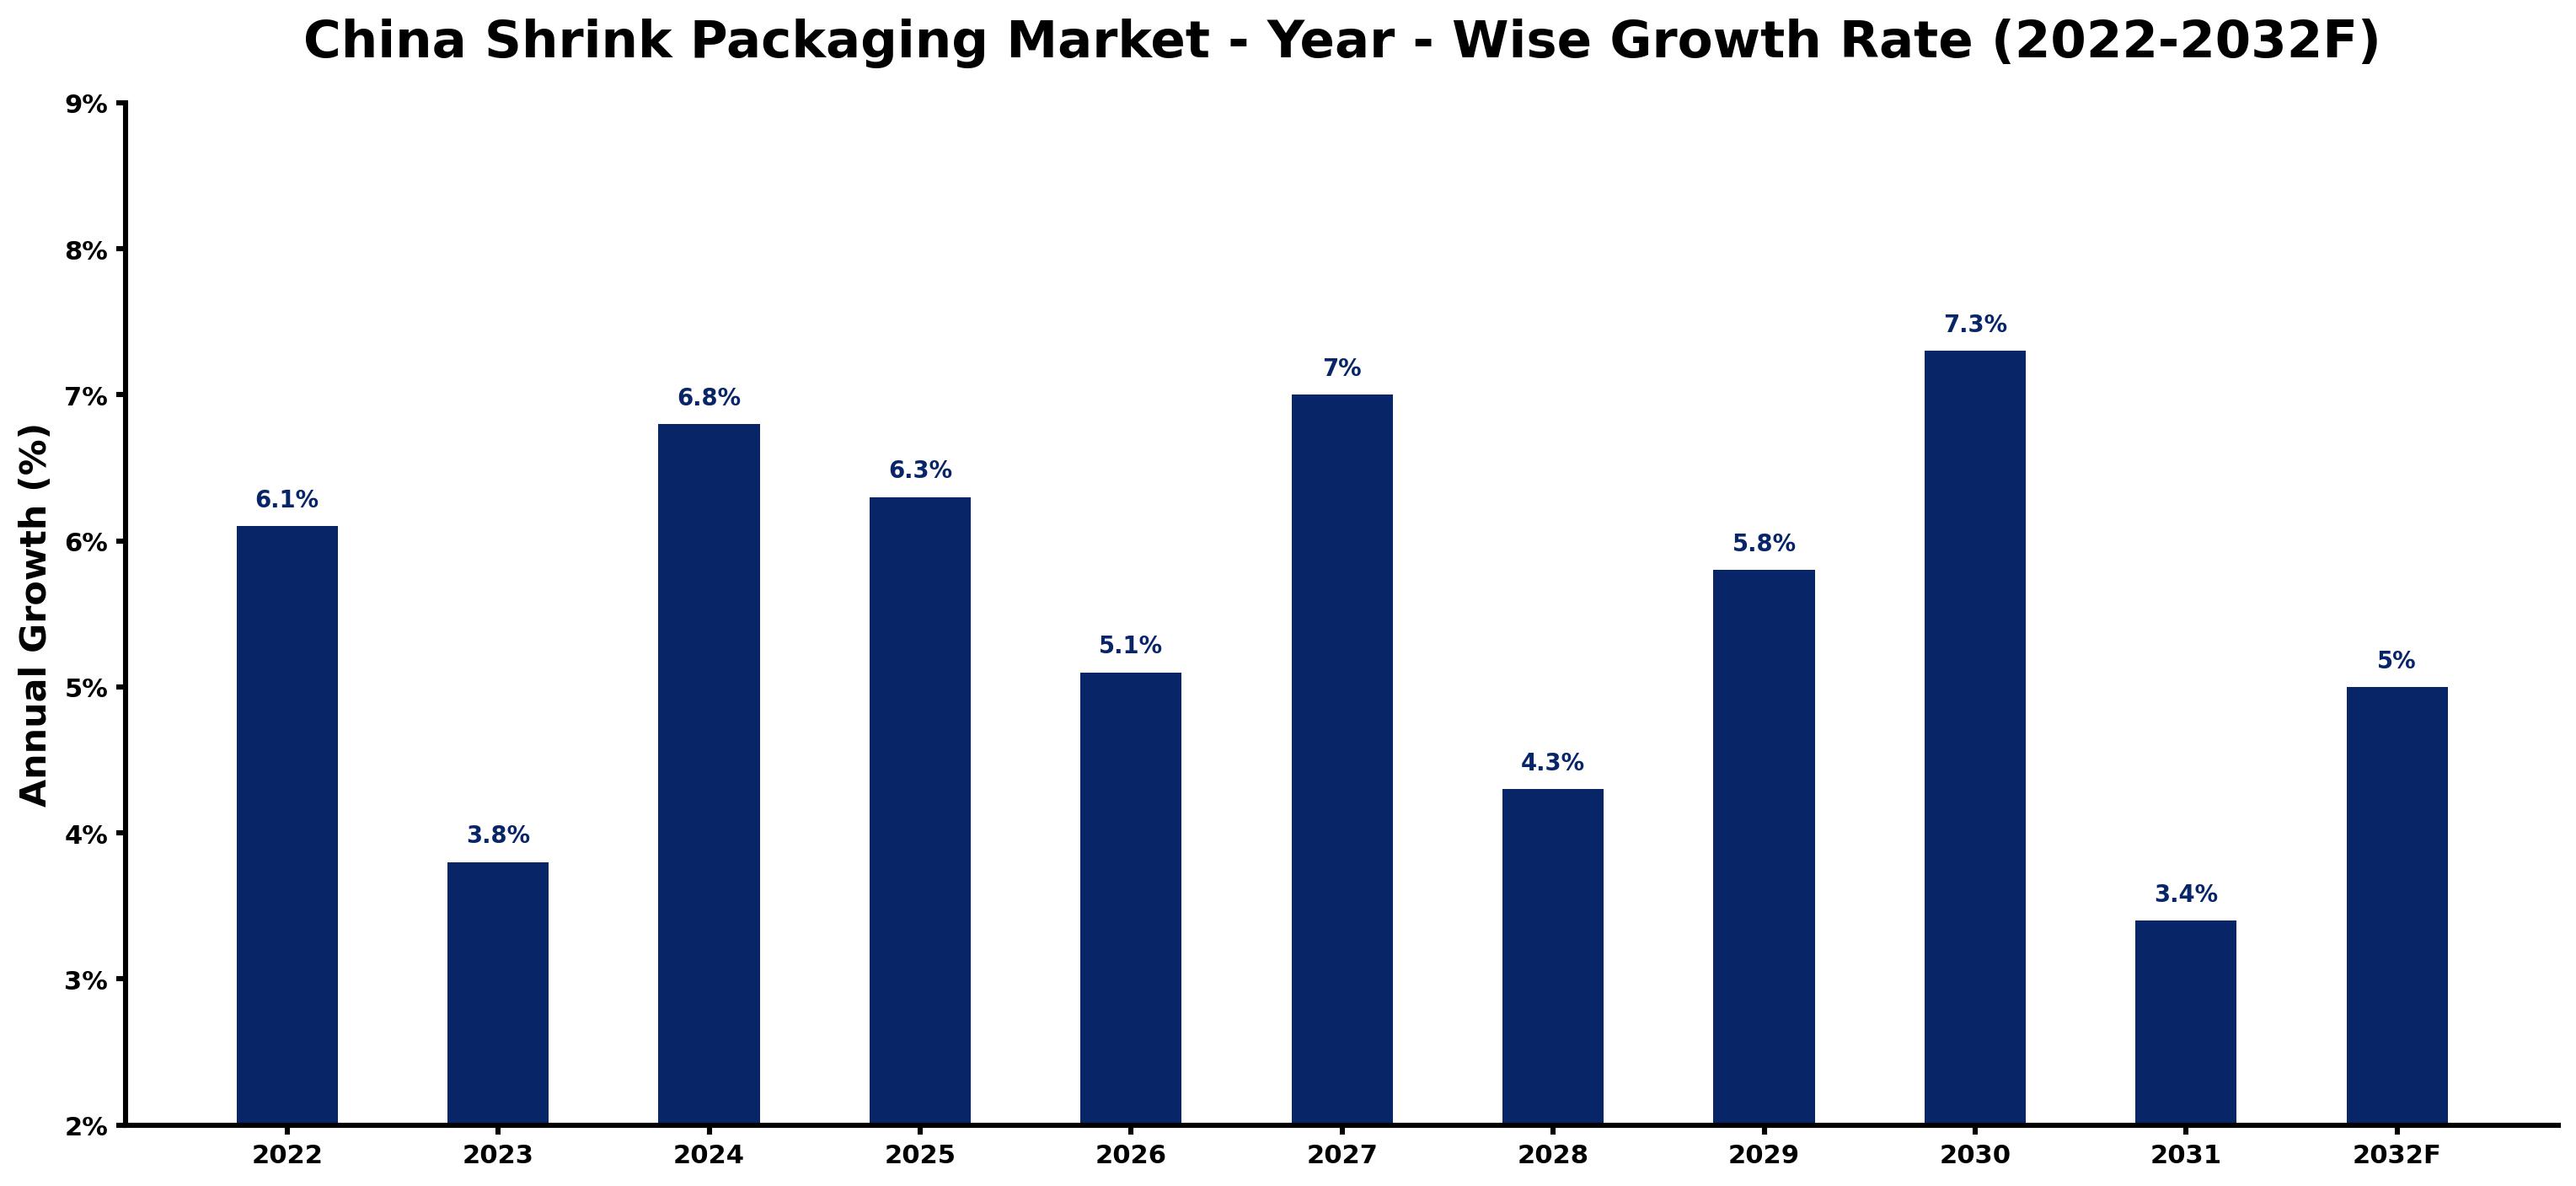
Below, each year's estimated growth is shown next to the factor that most influenced it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 6.1 | The market experienced steady growth, supported by the food and beverage sector's demand for effective packaging solutions. |
| 2023 | 3.8 | Growth slowed as manufacturers adjusted to the 'Green Packaging Initiative' promoting sustainable practices. |
| 2024 | 6.8 | Demand surged due to increased production in the food and beverage sector, particularly for shrink packaging. |
| 2025 | 6.3 | The market maintained growth as retail sales continued to rise in China, boosting packaging needs. |
| 2026 | 5.1 | Growth slowed as manufacturers faced challenges in sourcing raw materials, impacting production efficiency. |
| 2027 | 7.0 | Demand accelerated with the adoption of eco-friendly packaging solutions driven by consumer preferences. |
| 2028 | 4.3 | Growth decelerated as competition intensified among packaging suppliers, affecting market dynamics. |
| 2029 | 5.8 | Demand increased as food and beverage companies expanded their product lines, requiring more packaging. |
| 2030 | 7.3 | The market peaked with strong demand driven by promotional packaging needs in the retail sector. |
| 2031 | 3.4 | Growth slowed as market saturation began to influence purchasing decisions among manufacturers. |
| 2032 | 5.0 | Demand is expected to rise as sustainability becomes a priority for buyers, aligning with market trends. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Shrink Packaging Market Synopsis
Shrink Packaging in China involves using heat to shrink plastic films around products for protection and presentation. This technology is primarily made from polyolefin films, which are valued for their durability. The China Shrink Packaging Market is growing, driven by the food and beverage sector, which accounts for approximately 60% of demand. With retail sales estimated at 44 trillion yuan in 2022, the need for effective packaging solutions continues to rise. The 'Green Packaging Initiative' launched in 2023 further supports sustainable packaging innovations.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Rising consumer demand for packaged food products drives the need for effective shrink packaging solutions. | Driver | High | Shrink Wrap |
| The increasing focus on branding and promotional packaging creates opportunities for shrink sleeves. | Driver | High | Shrink Sleeves |
| Food and beverage companies are increasingly seeking sustainable packaging options, creating demand for eco-friendly shrink films. | Opportunity | High | Shrink Wrap |
| The growing retail sector in eastern provinces like Jiangsu and Zhejiang presents opportunities for suppliers. | Opportunity | Medium | Shrink Bundles |
| Rising raw material costs can limit profit margins for shrink packaging manufacturers. | Restraint | High | Shrink Wrap |
| Competition from alternative packaging solutions may hinder market growth for shrink packaging. | Restraint | Medium | Shrink Sleeves |
| The Shrink Packaging market in China faces challenges from fluctuating raw material prices, affecting production costs. | Challenge | High | Shrink Wrap |
| Technological advancements in alternative packaging materials pose a risk to traditional shrink packaging. | Challenge | Medium | Shrink Bundles |
Evaluation of Drivers in China Shrink Packaging Market (2026–2032)
The table below links each growth driver to the segment it affects and the evidence for it.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increasing retail sales in the food and beverage sector boost demand for shrink packaging solutions. | Shrink Wrap | Retail sales in China were estimated at 44 trillion yuan in 2022, prompting food companies to seek effective packaging solutions. |
| The shift towards eco-friendly packaging solutions drives demand for polyolefin films in shrink packaging. | Shrink Sleeves | Polyolefin films are preferred for their durability and cost-effectiveness, aligning with sustainability trends in packaging. |
| The rise of e-commerce increases the need for multipack packaging solutions, driving shrink packaging demand. | Printed Shrink Packs | As e-commerce grows, companies require efficient packaging for shipping and display, driving demand for shrink solutions. |
| The 'Green Packaging Initiative' launched in 2023 promotes sustainable packaging practices among manufacturers. | Shrink Wrap | This initiative encourages the adoption of eco-friendly materials in packaging, driving demand for sustainable solutions. |
| The expansion of food and beverage companies in eastern provinces stimulates growth in shrink packaging. | Shrink Bundles | Major hubs like Jiangsu and Zhejiang are increasing production capacity to meet rising demand from local manufacturers. |
The Shrink Packaging market in China is expanding as rising retail sales, particularly in the food and beverage sector, create strong demand for packaging solutions. In 2022, retail sales were estimated at 44 trillion yuan, prompting food companies to seek effective shrink packaging. The shift towards sustainable practices is further driving demand for eco-friendly materials like polyolefin films. As e-commerce continues to grow, the need for efficient multipack packaging solutions is becoming increasingly important. With major hubs in eastern provinces expanding production capacity, the market is set to grow further, reflecting the evolving needs of consumers and manufacturers alike.
Evaluation of Restraints in China Shrink Packaging Market
The key brakes on demand, and where they bite hardest, are shown below.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Fluctuating raw material prices can lead to increased production costs for manufacturers. | Shrink Wrap | Rising costs of polyolefin and other materials can squeeze profit margins for producers, impacting pricing strategies. |
| Intense competition from alternative packaging solutions may limit market share for shrink packaging. | Shrink Sleeves | As companies explore various packaging options, traditional shrink packaging faces challenges in maintaining market presence. |
| Regulatory compliance for packaging materials can complicate production processes for manufacturers. | Shrink Wrap | Standards such as GB/T 10004-2008 require stringent quality checks, impacting operational efficiency and costs. |
| Supply chain disruptions can affect the availability of shrink packaging materials. | Shrink Bundles | Global supply chain issues have led to delays in sourcing essential materials for production, hindering growth. |
| Market saturation in certain regions may restrict growth opportunities for new entrants. | Printed Shrink Packs | As the market matures, finding new customers becomes increasingly challenging, limiting expansion potential. |
China Shrink Packaging Market Challenges
The China shrink packaging market faces notable production cost increases that directly impact buyers in the food and beverage sector, with raw material prices rising by 15% this year. Buyers struggle to maintain profit margins, as this sector constitutes about 60% of shrink packaging demand, leading to financial strain. A shortage of skilled workers in advanced manufacturing techniques hampers producers' ability to innovate, resulting in delays for new product launches. Regulatory compliance, particularly with the National Standard GB/T 10004-2008, imposes additional costs on manufacturers, complicating their operational efficiency.
Trends in the China Shrink Packaging Market
Four trends stand out in the China Shrink Packaging Market.
- Increase in Eco-Friendly Packaging Solutions: The shift towards sustainable packaging is gaining momentum as the 'Green Packaging Initiative' promotes eco-friendly practices. In 2023, the use of polyolefin films increased by 25%, aligning with consumer preferences for sustainable products.
- Rise of E-Commerce Packaging Needs: Food and beverage companies are adapting to the e-commerce boom by enhancing their packaging solutions. The demand for multipack packaging has surged, reflecting the changing retail dynamics in China, with a notable increase in online sales by 30%.
- Growth in Branding and Promotional Packaging: The beverage sector has seen a 25% increase in the use of shrink sleeves for labelling in 2023. This trend highlights the importance of branding in attracting consumers and differentiating products in a competitive market.
- Expansion of Production in Eastern Provinces: Jiangsu and Zhejiang are becoming major hubs for shrink packaging production, reflecting the regional growth in consumer goods. This trend is supported by the increasing demand for effective packaging solutions, driving investments in production facilities.
Investment Opportunities in the China Shrink Packaging Market
Several openings in the China Shrink Packaging Market merit attention from investors.
- Food & Beverage Companies Seeking Sustainable Solutions: Food and beverage companies are increasingly looking for eco-friendly packaging options, creating a market gap. With the food sector accounting for 60% of shrink packaging demand, suppliers can invest in sustainable materials to meet this need.
- Investment in Advanced Packaging Technologies: The demand for advanced packaging solutions presents opportunities for investment in new technologies. Companies in Jiangsu and Zhejiang are focusing on enhancing their production capabilities to meet evolving market requirements.
- Growing Demand for Multipack Packaging: The surge in e-commerce has created a significant gap for multipack packaging solutions. Retail distributors in urban areas are looking for efficient packaging to meet consumer needs, driving demand for effective solutions.
- Expansion of Shrink Sleeve Applications: The increase in branding and promotional activities offers opportunities for suppliers of shrink sleeves. The beverage sector's growth in labelling solutions indicates a strong demand for this packaging type, creating avenues for suppliers.
Government Initiatives in the China Shrink Packaging Market
The National Standard GB/T 10004-2008 regulates the quality of plastic packaging materials in China, ensuring that producers meet specific quality requirements. This standard impacts shrink packaging manufacturers by mandating rigorous testing and certification processes, which ensures product safety and consumer trust. Compliance with this regulation is essential for maintaining market access and competitiveness, as it ensures that products meet consumer expectations and safety standards.
The Ministry of Industry and Information Technology oversees the implementation of various packaging initiatives, including the 'Green Packaging Initiative'. This agency funds projects aimed at promoting sustainable packaging practices among manufacturers, helping them transition to eco-friendly materials. By supporting innovations in sustainable packaging, the ministry facilitates the growth of the shrink packaging market, ensuring that manufacturers can meet evolving consumer demands.
Future Insight of the China Shrink Packaging Market
The China shrink packaging market is set for transformative changes by 2032, driven by the 'Green Packaging Initiative' that encourages the use of sustainable materials. This shift will require buyers to embrace eco-friendly options, reflecting growing consumer preferences for sustainability. The 'Made in China 2025' plan will motivate manufacturers to adopt advanced technologies, improving production processes. With retail sales projected to reach 44 trillion yuan by 2032, the demand for innovative packaging solutions will present new growth avenues for suppliers.
Market Segmentation Analysis
The analysis below covers each segmentation, its leading category in 2025 and its fastest-growing category through 2032.
By Packaging Type – Shrink Wrap Dominated, Shrink Sleeves Expected to Grow Fastest
According to Dhaval Chaurasia, Assistant Manager at 6Wresearch, Shrink Wrap took a 41% share of packaging type in 2025, more than any other category. Shrink Wrap holds the largest market share in China due to its widespread application in packaging food and consumer goods. Its effectiveness in preserving product integrity is particularly crucial in the food and beverage sector, which significantly influences demand. The quickest growth will come from Shrink Sleeves, forecast to expand at a CAGR of 6.9% between 2026 and 2032. Shrink Sleeves are experiencing rapid growth, with a 25% increase in their use for labeling in the beverage sector in 2023. This surge highlights a shift towards enhanced branding and consumer engagement, suggesting that the lead of Shrink Wrap will continue to widen as both applications grow. Suppliers should focus on developing shrink sleeves to cater to the rising demand for effective labeling solutions.
By Material Type – Polyolefin Dominated, PET-G/OPS Expected to Grow Fastest
In 2025, Polyolefin led the material type split with a 41% share. Polyolefin films dominate the market share in China, valued for their durability and cost-effectiveness in shrink packaging applications. This material is preferred by manufacturers for its flexibility and strength, making it a staple in the food and beverage industry. PET-G/OPS is projected to grow fastest, at a CAGR of 7.6% during 2026–2032. PET-G/OPS is the fastest-growing material type, driven by its specific applications in high-quality packaging solutions. As companies seek to differentiate their products, the demand for PET-G/OPS is expected to rise, widening the gap with other materials. Manufacturers should consider diversifying their material offerings to include PET-G/OPS to meet the evolving needs of high-end packaging.
By Application – Product Unitization Dominated, Labeling Expected to Grow Fastest
Product Unitization accounted for a 39% market share by application in 2025. Product Unitization dominates the market share as it is essential for the efficient organisation of products during shipping and display. This application is particularly important in the food and beverage sector, where it ensures the safety and visibility of products, driving substantial demand. Over 2026–2032, Labeling is expected to post the fastest growth, at a CAGR of 7.4%. Labeling is the fastest-growing application, propelled by the increasing emphasis on branding and consumer information. The uptick in shrink sleeves for labeling indicates a shift towards prioritising product presentation, which will further stimulate growth in this area. Suppliers need to enhance their labeling capabilities to align with the growing focus on branding and consumer engagement.
By End User – Food & Beverage Companies Dominated, Bottling Companies Expected to Grow Fastest
The largest end user category in 2025 was Food & Beverage Companies, with a 40% share of total revenue. Food & Beverage Companies represent the largest end users of shrink packaging in China, accounting for approximately 60% of total demand. The scale and continuous growth of this sector in consumer goods drive significant utilisation of shrink packaging solutions. Bottling Companies are set to record the highest CAGR in this split, 7.6% over 2026–2032. Bottling Companies are the fastest-growing end users, increasingly adopting shrink packaging for beverage products. This trend is expected to accelerate alongside ongoing expansion and innovation within the beverage market. Suppliers should tailor their solutions to bottling companies to capitalise on the growing demand for beverage packaging.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Shrink Packaging Market Outlook
- Market Size of China Shrink Packaging Market, 2025
- Forecast of China Shrink Packaging Market, 2032
- Historical Data and Forecast of China Shrink Packaging Revenues & Volume for the Period 2022 - 2032F
- China Shrink Packaging Market Trend Evolution
- China Shrink Packaging Market Drivers and Challenges
- China Shrink Packaging Price Trends
- China Shrink Packaging Porter's Five Forces
- China Shrink Packaging Industry Life Cycle
- Historical Data and Forecast of China Shrink Packaging Market Revenues & Volume By Packaging Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Shrink Packaging Market Revenues & Volume By Shrink Wrap for the Period 2022 - 2032F
- Historical Data and Forecast of China Shrink Packaging Market Revenues & Volume By Shrink Sleeves for the Period 2022 - 2032F
- Historical Data and Forecast of China Shrink Packaging Market Revenues & Volume By Shrink Bundles for the Period 2022 - 2032F
- Historical Data and Forecast of China Shrink Packaging Market Revenues & Volume By Printed Shrink Packs for the Period 2022 - 2032F
- Historical Data and Forecast of China Shrink Packaging Market Revenues & Volume By Material Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Shrink Packaging Market Revenues & Volume By Polyolefin for the Period 2022 - 2032F
- Historical Data and Forecast of China Shrink Packaging Market Revenues & Volume By PET-G/OPS for the Period 2022 - 2032F
- Historical Data and Forecast of China Shrink Packaging Market Revenues & Volume By PE Films for the Period 2022 - 2032F
- Historical Data and Forecast of China Shrink Packaging Market Revenues & Volume By Custom Films for the Period 2022 - 2032F
- Historical Data and Forecast of China Shrink Packaging Market Revenues & Volume By Application for the Period 2022 - 2032F
- Historical Data and Forecast of China Shrink Packaging Market Revenues & Volume By Product Unitization for the Period 2022 - 2032F
- Historical Data and Forecast of China Shrink Packaging Market Revenues & Volume By Labeling for the Period 2022 - 2032F
- Historical Data and Forecast of China Shrink Packaging Market Revenues & Volume By Multipack Packaging for the Period 2022 - 2032F
- Historical Data and Forecast of China Shrink Packaging Market Revenues & Volume By Branding & Promotion for the Period 2022 - 2032F
- Historical Data and Forecast of China Shrink Packaging Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Shrink Packaging Market Revenues & Volume By Food & Beverage Companies for the Period 2022 - 2032F
- Historical Data and Forecast of China Shrink Packaging Market Revenues & Volume By Bottling Companies for the Period 2022 - 2032F
- Historical Data and Forecast of China Shrink Packaging Market Revenues & Volume By Retail Distributors for the Period 2022 - 2032F
- Historical Data and Forecast of China Shrink Packaging Market Revenues & Volume By Consumer Product Brands for the Period 2022 - 2032F
- China Shrink Packaging Import Export Trade Statistics
- Market Opportunity Assessment By Packaging Type
- Market Opportunity Assessment By Material Type
- Market Opportunity Assessment By Application
- Market Opportunity Assessment By End User
- China Shrink Packaging Top Companies Market Share
- China Shrink Packaging Competitive Benchmarking By Technical and Operational Parameters
- China Shrink Packaging Company Profiles
- China Shrink Packaging Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By Packaging Type
- Shrink Wrap
- Shrink Sleeves
- Shrink Bundles
- Printed Shrink Packs
By Material Type
- Polyolefin
- PET-G/OPS
- PE Films
- Custom Films
By Application
- Product Unitization
- Labeling
- Multipack Packaging
- Branding & Promotion
By End User
- Food & Beverage Companies
- Bottling Companies
- Retail Distributors
- Consumer Product Brands































