China Silicon Carbide Devices Market Size & Growth Rate
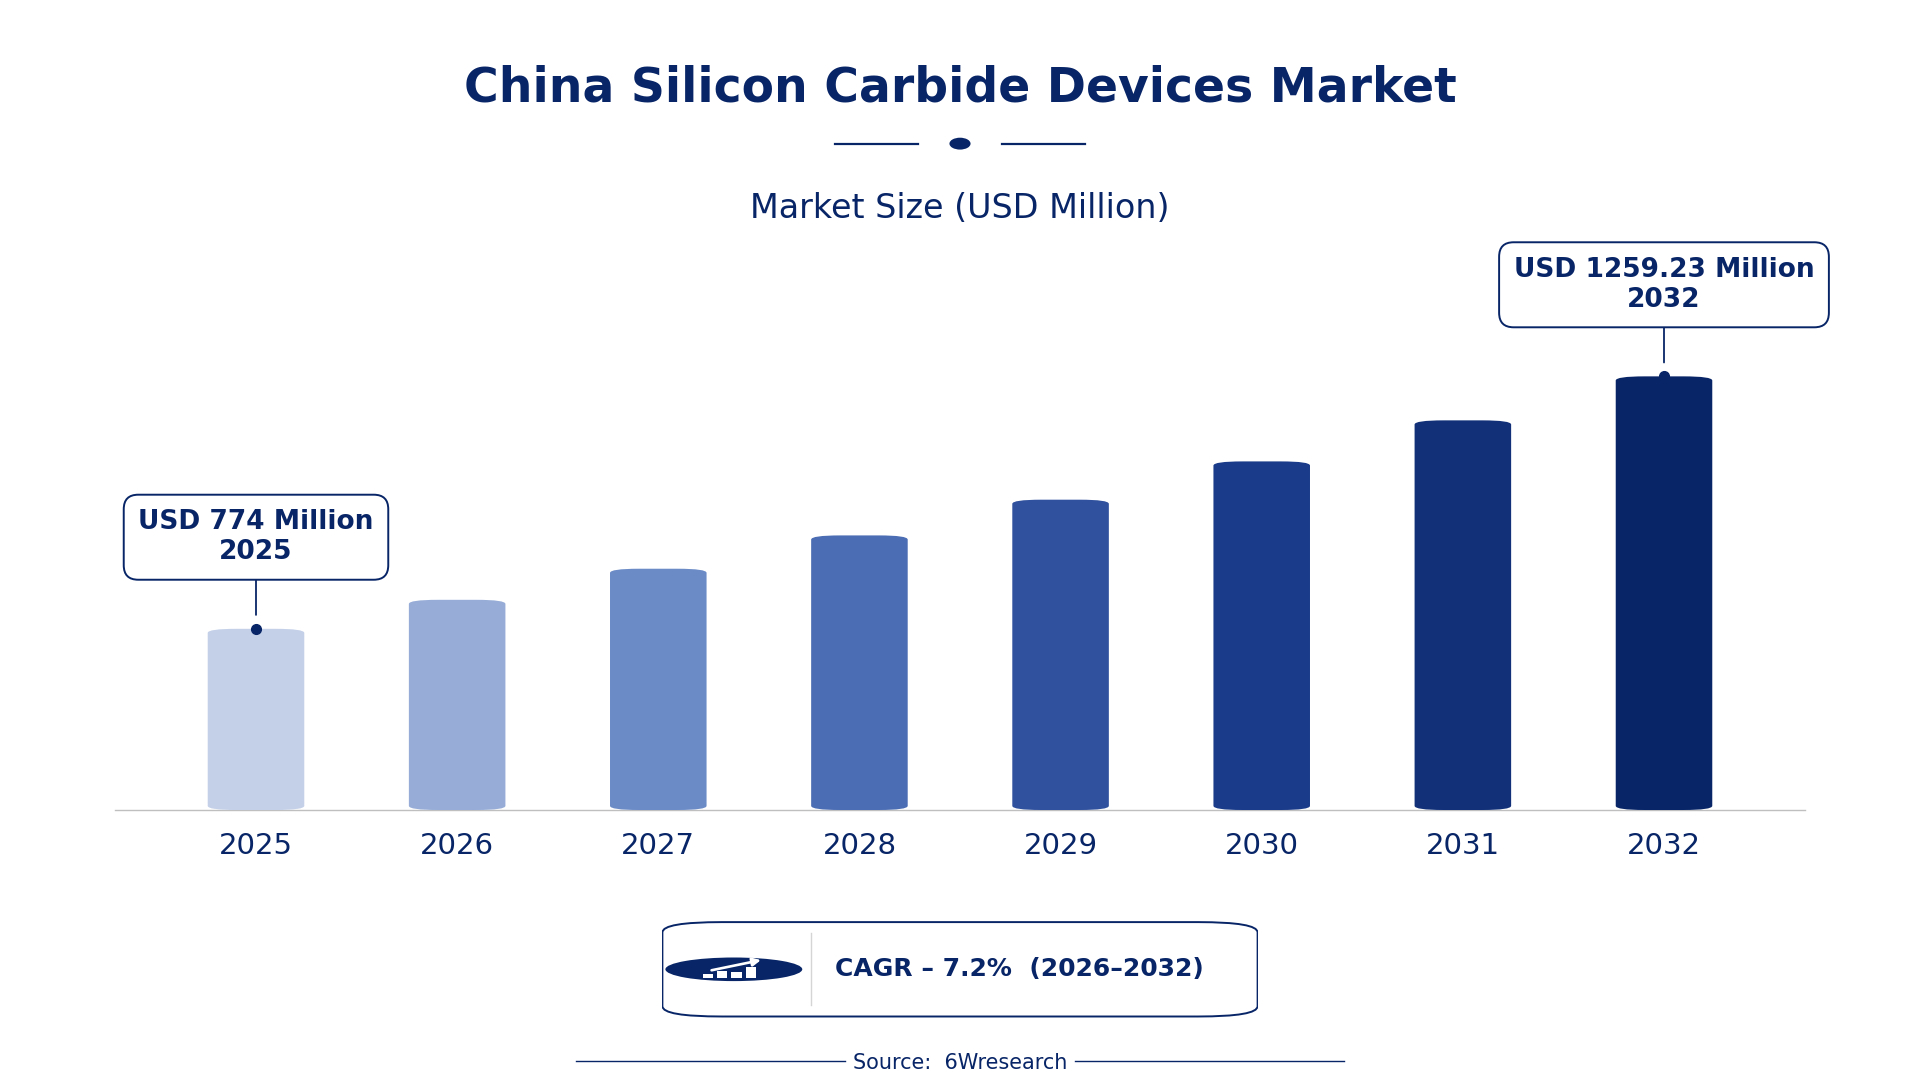
According to 6Wresearch internal database and industry insights, the China Silicon Carbide Devices Market was valued at USD 774.0 million in 2025 and is projected to reach USD 1,259.23 million by 2032, growing at a CAGR of approximately 7.2% during 2026–2032.
China Silicon Carbide Devices Market Highlights
| Report Metric | Details |
| Report Name | China Silicon Carbide Devices Market |
| Market Size 2025 | USD 774.0 million |
| Market Size 2032 | USD 1,259.23 million |
| Absolute Growth 2025–2032 | USD 485.23 million |
| CAGR 2026–2032 | 7.2% |
| Peak Annual Growth | 9.1% in 2031 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Device Type, 2025 | SiC MOSFETs (53% share) |
| Leading Application Area, 2025 | Power Conversion (45% share) |
| Leading Voltage Range, 2025 | 600V–1700V (48% share) |
| Leading End User, 2025 | Automotive Inverters (48% share) |
| Fastest-Growing Device Type | SiC Diodes (8.8% CAGR) |
| Fastest-Growing Application Area | Switching Circuits (9.1% CAGR) |
| Fastest-Growing Voltage Range | Medium to High Voltage (8.8% CAGR) |
| Fastest-Growing End User | Industrial Motor Drives (8.3% CAGR) |
| Growing Sector | automotive and renewable energy |
| Key End Users | electric vehicle manufacturers, semiconductor producers, renewable energy companies, industrial equipment manufacturers |
China Silicon Carbide Devices Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
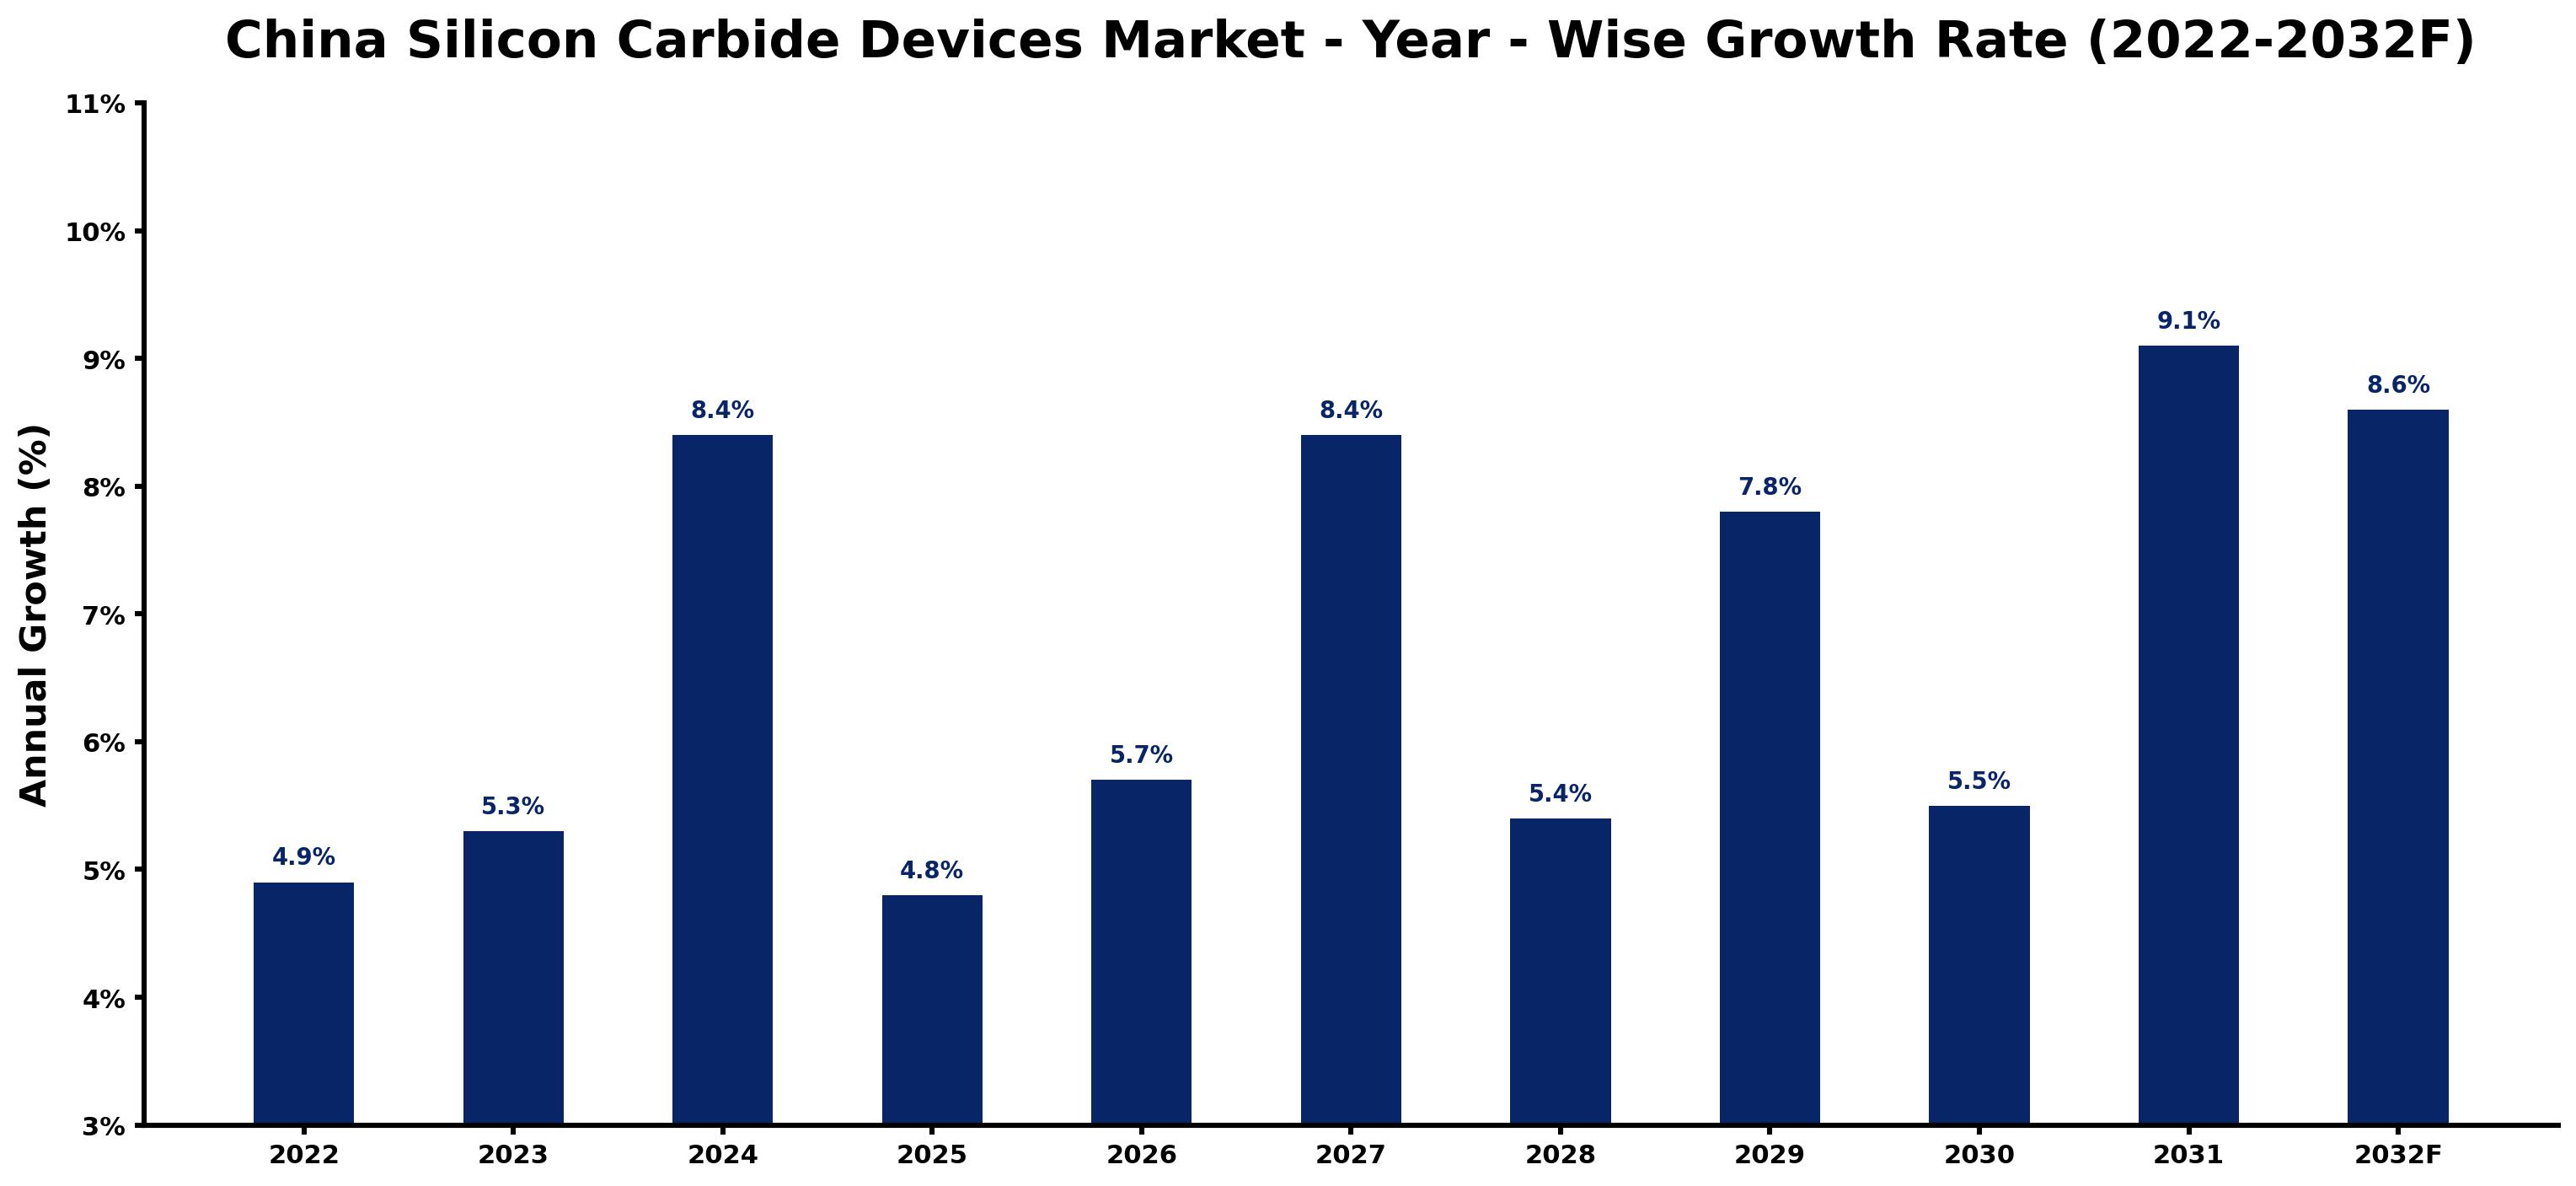
The following table presents the estimated annual growth rate for each year together with the principal factor influencing market performance.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 4.9 | The market experienced steady growth, driven by rising electric vehicle production. |
| 2023 | 5.3 | Demand accelerated as electric vehicle manufacturers increased their reliance on SiC devices. |
| 2024 | 8.4 | Growth peaked due to heightened investments in renewable energy technologies. |
| 2025 | 4.8 | The market slowed slightly as manufacturers adjusted to production capacities. |
| 2026 | 5.7 | Demand is expected to rise again with a focus on energy-efficient technologies. |
| 2027 | 8.4 | Growth will surge as industrial motor drives expand in various sectors. |
| 2028 | 5.4 | The market is projected to experience a slowdown as production stabilises and demand normalises. |
| 2029 | 7.8 | Demand is expected to increase with the push for more efficient renewable energy systems. |
| 2030 | 5.5 | The market will slow again as manufacturers face temporary production constraints. |
| 2031 | 9.1 | Growth will peak again as demand from automotive inverters surges. |
| 2032 | 8.6 | The market continues to grow, driven by sustained interest in renewable energy applications. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Silicon Carbide Devices Market Synopsis
Silicon Carbide Devices in China are semiconductor devices crafted from silicon carbide, known for their efficiency and thermal conductivity. These devices find primary application in power electronics, particularly within the automotive and renewable energy sectors. The China Silicon Carbide Devices Market is growing due to rising domestic demand from electric vehicle manufacturers and the renewable energy industry. In 2022, China produced more than 10 million electric vehicles, driving the need for SiC devices. The government's commitment to boosting semiconductor production is propelling market expansion.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Rising electric vehicle production drives demand for efficient power electronics. | Driver | High | Automotive Inverters |
| Growing renewable energy capacity increases the need for SiC devices in power systems. | Driver | High | Renewable Energy Systems |
| Investment in semiconductor production facilities creates opportunities for local suppliers. | Opportunity | High | SiC Substrates |
| The push for energy-efficient technologies opens new markets for SiC modules. | Opportunity | High | SiC Modules |
| High production costs limit the affordability of SiC devices for some manufacturers. | Restraint | Medium | SiC Diodes |
| Regulatory compliance requirements can delay product launches in the market. | Restraint | Medium | SiC MOSFETs |
| The Silicon Carbide Devices market in China faces challenges from high production costs. | Challenge | High | SiC Modules |
| Limited access to advanced manufacturing technologies hampers growth potential. | Challenge | Medium | SiC Substrates |
Evaluation of Drivers in China Silicon Carbide Devices Market (2026–2032)
Below mentioned are some major drivers and their influence on market dynamics.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increasing electric vehicle production drives demand for SiC devices. | Automotive Inverters | China produced over 10 million electric vehicles in 2022, leading to higher demand for efficient power electronics. |
| Growing renewable energy capacity enhances the need for SiC technology. | Renewable Energy Systems | The Chinese government aims to increase renewable energy capacity to 1,200 GW by 2030, boosting SiC device demand. |
| Investment in semiconductor production facilities supports local manufacturing. | SiC Substrates | The National Development and Reform Commission announced a plan to boost semiconductor production by 30% in 2023. |
| Expansion of industrial motor drives increases demand for SiC devices. | Industrial Motor Drives | The installed base of industrial motor drives in China was estimated at 15 million units in 2023. |
| The average efficiency improvement in power conversion systems using SiC devices is significant. | SiC MOSFETs | The average efficiency improvement is around 20%, making SiC devices attractive for manufacturers. |
Growth across the Silicon Carbide Devices market in China is anchored in rising electric vehicle production, growing renewable energy capacity, and increased investments in semiconductor facilities. In 2022, over 10 million electric vehicles were produced, driving demand for efficient power electronics. The installed base of industrial motor drives reached 15 million units in 2023, further increasing demand for SiC devices. The average efficiency improvement in power conversion systems using SiC devices is around 20%, making them a preferred choice for manufacturers.
Evaluation of Restraints in China Silicon Carbide Devices Market
The main factors holding the market back are set out below.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| High production costs limit the affordability of SiC devices for manufacturers. | SiC Diodes | The production costs for SiC devices can be higher than traditional silicon alternatives. |
| Regulatory compliance requirements can delay product launches in the market. | SiC MOSFETs | Manufacturers must adhere to the National Standard GB/T 33592-2017 for testing semiconductor devices. |
| Limited access to advanced manufacturing technologies hampers growth potential. | SiC Substrates | Many local manufacturers lack the necessary technology to produce high-quality SiC substrates. |
| Market volatility can affect investment in SiC device production. | SiC Modules | Fluctuations in raw material prices can lead to uncertainty in production costs. |
| Competition from traditional silicon devices may limit market share. | Power Conversion | Silicon devices are often less expensive, making them attractive alternatives for some applications. |
China Silicon Carbide Devices Market Challenges
The China Silicon Carbide Devices market encounters strict regulations that complicate production for manufacturers, as compliance with the National Standard GB/T 33592-2017 requires extensive testing, which can delay product availability. A shortage of skilled workers in the semiconductor sector limits growth potential, possibly leading to a 15% reduction in output capacity. Supply chain disruptions, particularly in Guangdong province, impede the procurement of SiC substrates, resulting in postponed product launches for clients in the automotive and renewable energy sectors. Rapid technological advancements necessitate continuous investment in research and development, putting financial strain on smaller producers and affecting their competitiveness.
Trends in the China Silicon Carbide Devices Market
Several trends are reshaping the China Silicon Carbide Devices Market; the most important are set out below.
- Shift from Traditional to Advanced Semiconductor Materials: Since 2021, the emphasis has shifted towards advanced materials such as silicon carbide in semiconductor manufacturing. The 2023 'Green Energy Action Plan' highlights the use of SiC in renewable technologies, with a projected demand for 5 million SiC modules by 2025.
- Increase in Electric Vehicle Adoption: In 2022, China produced over 10 million electric vehicles, influencing the demand for SiC devices. This trend is expected to persist as more manufacturers incorporate SiC technology into automotive applications.
- Expansion of Renewable Energy Systems: The Chinese government aims to boost renewable energy capacity to 1,200 GW by 2030, driving the demand for SiC devices in energy systems. This transition will create new opportunities for suppliers in the semiconductor market.
- Growth in Industrial Motor Drives: The installed base of industrial motor drives in China reached 15 million units in 2023, indicating a rising demand for SiC devices across various industrial applications. This trend is likely to generate new market opportunities for manufacturers.
Investment Opportunities in the China Silicon Carbide Devices Market
Some of the investment opportunities in the China Silicon Carbide Devices Market are mentioned below.
- Investment in Semiconductor Manufacturing Facilities: The Guangdong province is a key area for SiC substrate manufacturing, with the government allocating $10 billion for semiconductor R&D through 2025. This investment creates opportunities for local suppliers to enter the market.
- Supply of SiC Modules for Renewable Energy Systems: China's renewable energy systems are projected to require 5 million SiC modules by 2025, creating a supply opportunity for manufacturers. Collaborating with local partners can facilitate market entry.
- Development of Advanced SiC Devices for Automotive Applications: With the installed base of automotive inverters expected to exceed 10 million units by 2025, there is a growing need for advanced SiC devices. Suppliers can target electric vehicle manufacturers to meet this demand.
- Provision of Testing and Compliance Services: As the National Standard GB/T 33592-2017 governs testing for semiconductor devices, there is an opportunity for service providers to offer compliance testing solutions. This service is essential for manufacturers aiming to enter the market.
Government Initiatives in the China Silicon Carbide Devices Market
Several key laws and initiatives shape the regulatory framework for Silicon Carbide Devices in China. The '14th Five-Year Plan for Semiconductor Industry' released in 2021 focuses on advancing SiC technology and aims to improve domestic production capabilities. The National Energy Administration's 'Green Energy Action Plan' emphasises the use of advanced materials like SiC in renewable technologies, reflecting the government's commitment to supporting this sector. In 2023, the Chinese government allocated $10 billion for semiconductor R&D through 2025, which will boost the semiconductor industry and ensure compliance with international standards.
In 2023, the Chinese government allocated $10 billion for semiconductor R&D through 2025, administered by the Ministry of Industry and Information Technology. This funding supports the development of SiC technologies and improves domestic production capabilities. Furthermore, the National Development and Reform Commission oversees initiatives to increase semiconductor production by 30%, promoting investment in local manufacturing facilities. These efforts are vital for ensuring that manufacturers can meet the rising demand for Silicon Carbide Devices.
Future Insight of the China Silicon Carbide Devices Market
Several forward-looking factors are expected to support the China Silicon Carbide Devices market in the coming years. The National Development and Reform Commission's plan to boost semiconductor production by 30% will enhance local manufacturing capabilities. By 2025, the anticipated requirement for 5 million SiC modules in renewable energy systems will create substantial growth opportunities. The government's 2023 'Green Energy Action Plan' will promote the integration of advanced materials, benefiting suppliers. Additionally, the expected installation of over 10 million automotive inverters by 2025 will further accelerate the adoption of SiC technology.
Market Segmentation Analysis
The report offers a comprehensive study of the following market segments and their leading categories in the market.
By Device Type – SiC MOSFETs Dominated, SiC Diodes Expected to Grow Fastest
According to Dhaval Chaurasia, Assistant Manager at 6Wresearch, SiC MOSFETs took a 53% share of device type in 2025, more than any other category. SiC MOSFETs hold the largest market share as they are widely used in power conversion applications, particularly in the electric vehicle sector where efficiency is paramount. Their ability to improve efficiency by around 20% makes them a preferred choice for manufacturers aiming for superior performance. The quickest growth will come from SiC Diodes, forecast to expand at a CAGR of 8.8% between 2026 and 2032. SiC Diodes are experiencing rapid growth due to their essential role in high-voltage applications, particularly as the demand for renewable energy systems escalates. This increasing reliance on SiC Diodes will likely enhance their market share as industries seek dependable solutions. Suppliers should prioritise increasing SiC Diode production to satisfy the rising demand in high-voltage applications.
By Application Area – Power Conversion Dominated, Switching Circuits Expected to Grow Fastest
The largest application area category in 2025 was Power Conversion, with a 45% share of total revenue. Power Conversion commands a significant market share, being crucial for energy efficiency across multiple sectors, including electric vehicles and renewable energy. The consistent focus on energy-efficient technologies solidifies its dominant position in the market. Switching Circuits are projected to grow fastest, at a CAGR of 9.1% during 2026–2032. Switching Circuits are growing quickly as they are vital for controlling power flow, which is increasingly important in modern energy systems. The rising emphasis on efficient power management is expected to drive their adoption in the near future. Buyers in the energy sector should consider investing in Switching Circuits to improve power management and overall efficiency.
By Voltage Range – 600V–1700V Dominated, Medium to High Voltage Expected to Grow Fastest
600V–1700V accounted for a 48% market share by voltage range in 2025. The 600V–1700V segment holds the largest market share, as it is widely used in industrial applications. This voltage range is integral to various power conversion systems, ensuring its strong presence in the market. Over 2026–2032, Medium to High Voltage is expected to post the fastest growth, at a CAGR of 8.8%. Medium to High Voltage segments are expanding rapidly due to their necessity for grid applications, particularly as China aims to increase its renewable energy capacity to 1,200 GW by 2030. This growth will likely drive demand for devices operating within this voltage range. Suppliers focusing on the Medium to High Voltage segment should prepare for heightened demand as grid applications continue to grow.
By End User – Automotive Inverters Dominated, Industrial Motor Drives Expected to Grow Fastest
Automotive Inverters held a 48% share of the China Silicon Carbide Devices Market by end user in 2025. Automotive Inverters lead the market as they are a key component in electric vehicles, which have seen substantial production in China. The forecasted installed base of automotive inverters exceeding 10 million units by 2025 reinforces their dominant market share. Industrial Motor Drives are set to record the highest CAGR in this split, 8.3% over 2026–2032. Industrial Motor Drives are witnessing the fastest growth due to their widespread application in various industrial sectors, which are crucial for efficiency and automation. The estimated installed base of 15 million units in 2023 supports this segment's rapid expansion. Manufacturers should focus on developing Industrial Motor Drives to capitalise on the increasing trend of industrial automation.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Silicon Carbide Devices Market Outlook
- Market Size of China Silicon Carbide Devices Market, 2025
- Forecast of China Silicon Carbide Devices Market, 2032
- Historical Data and Forecast of China Silicon Carbide Devices Revenues & Volume for the Period 2022 - 2032F
- China Silicon Carbide Devices Market Trend Evolution
- China Silicon Carbide Devices Market Drivers and Challenges
- China Silicon Carbide Devices Price Trends
- China Silicon Carbide Devices Porter's Five Forces
- China Silicon Carbide Devices Industry Life Cycle
- Historical Data and Forecast of China Silicon Carbide Devices Market Revenues & Volume By Device Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Silicon Carbide Devices Market Revenues & Volume By SiC MOSFETs for the Period 2022 - 2032F
- Historical Data and Forecast of China Silicon Carbide Devices Market Revenues & Volume By SiC Diodes for the Period 2022 - 2032F
- Historical Data and Forecast of China Silicon Carbide Devices Market Revenues & Volume By SiC Modules for the Period 2022 - 2032F
- Historical Data and Forecast of China Silicon Carbide Devices Market Revenues & Volume By SiC Substrates for the Period 2022 - 2032F
- Historical Data and Forecast of China Silicon Carbide Devices Market Revenues & Volume By Application Area for the Period 2022 - 2032F
- Historical Data and Forecast of China Silicon Carbide Devices Market Revenues & Volume By Power Conversion for the Period 2022 - 2032F
- Historical Data and Forecast of China Silicon Carbide Devices Market Revenues & Volume By Switching Circuits for the Period 2022 - 2032F
- Historical Data and Forecast of China Silicon Carbide Devices Market Revenues & Volume By Integrated Packaging for the Period 2022 - 2032F
- Historical Data and Forecast of China Silicon Carbide Devices Market Revenues & Volume By Base Component for the Period 2022 - 2032F
- Historical Data and Forecast of China Silicon Carbide Devices Market Revenues & Volume By Voltage Range for the Period 2022 - 2032F
- Historical Data and Forecast of China Silicon Carbide Devices Market Revenues & Volume By 600V 1700V for the Period 2022 - 2032F
- Historical Data and Forecast of China Silicon Carbide Devices Market Revenues & Volume By Medium to High Voltage for the Period 2022 - 2032F
- Historical Data and Forecast of China Silicon Carbide Devices Market Revenues & Volume By 1200V 3300V for the Period 2022 - 2032F
- Historical Data and Forecast of China Silicon Carbide Devices Market Revenues & Volume By Wide Bandgap Semiconductors for the Period 2022 - 2032F
- Historical Data and Forecast of China Silicon Carbide Devices Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Silicon Carbide Devices Market Revenues & Volume By Automotive Inverters for the Period 2022 - 2032F
- Historical Data and Forecast of China Silicon Carbide Devices Market Revenues & Volume By Industrial Motor Drives for the Period 2022 - 2032F
- Historical Data and Forecast of China Silicon Carbide Devices Market Revenues & Volume By Renewable Energy Systems for the Period 2022 - 2032F
- Historical Data and Forecast of China Silicon Carbide Devices Market Revenues & Volume By Chip Fabricators for the Period 2022 - 2032F
- China Silicon Carbide Devices Import Export Trade Statistics
- Market Opportunity Assessment By Device Type
- Market Opportunity Assessment By Application Area
- Market Opportunity Assessment By Voltage Range
- Market Opportunity Assessment By End User
- China Silicon Carbide Devices Top Companies Market Share
- China Silicon Carbide Devices Competitive Benchmarking By Technical and Operational Parameters
- China Silicon Carbide Devices Company Profiles
- China Silicon Carbide Devices Key Strategic Recommendations
Market Covered
Segments analysed in this report are listed below.
By Device Type
- SiC MOSFETs
- SiC Diodes
- SiC Modules
- SiC Substrates
By Application Area
- Power Conversion
- Switching Circuits
- Integrated Packaging
- Base Component
By Voltage Range
- 600V–1700V
- Medium to High Voltage
- 1200V–3300V
- Wide Bandgap Semiconductors
By End User
- Automotive Inverters
- Industrial Motor Drives
- Renewable Energy Systems
- Chip Fabricators































