China Soda Can Market Size & Growth Rate
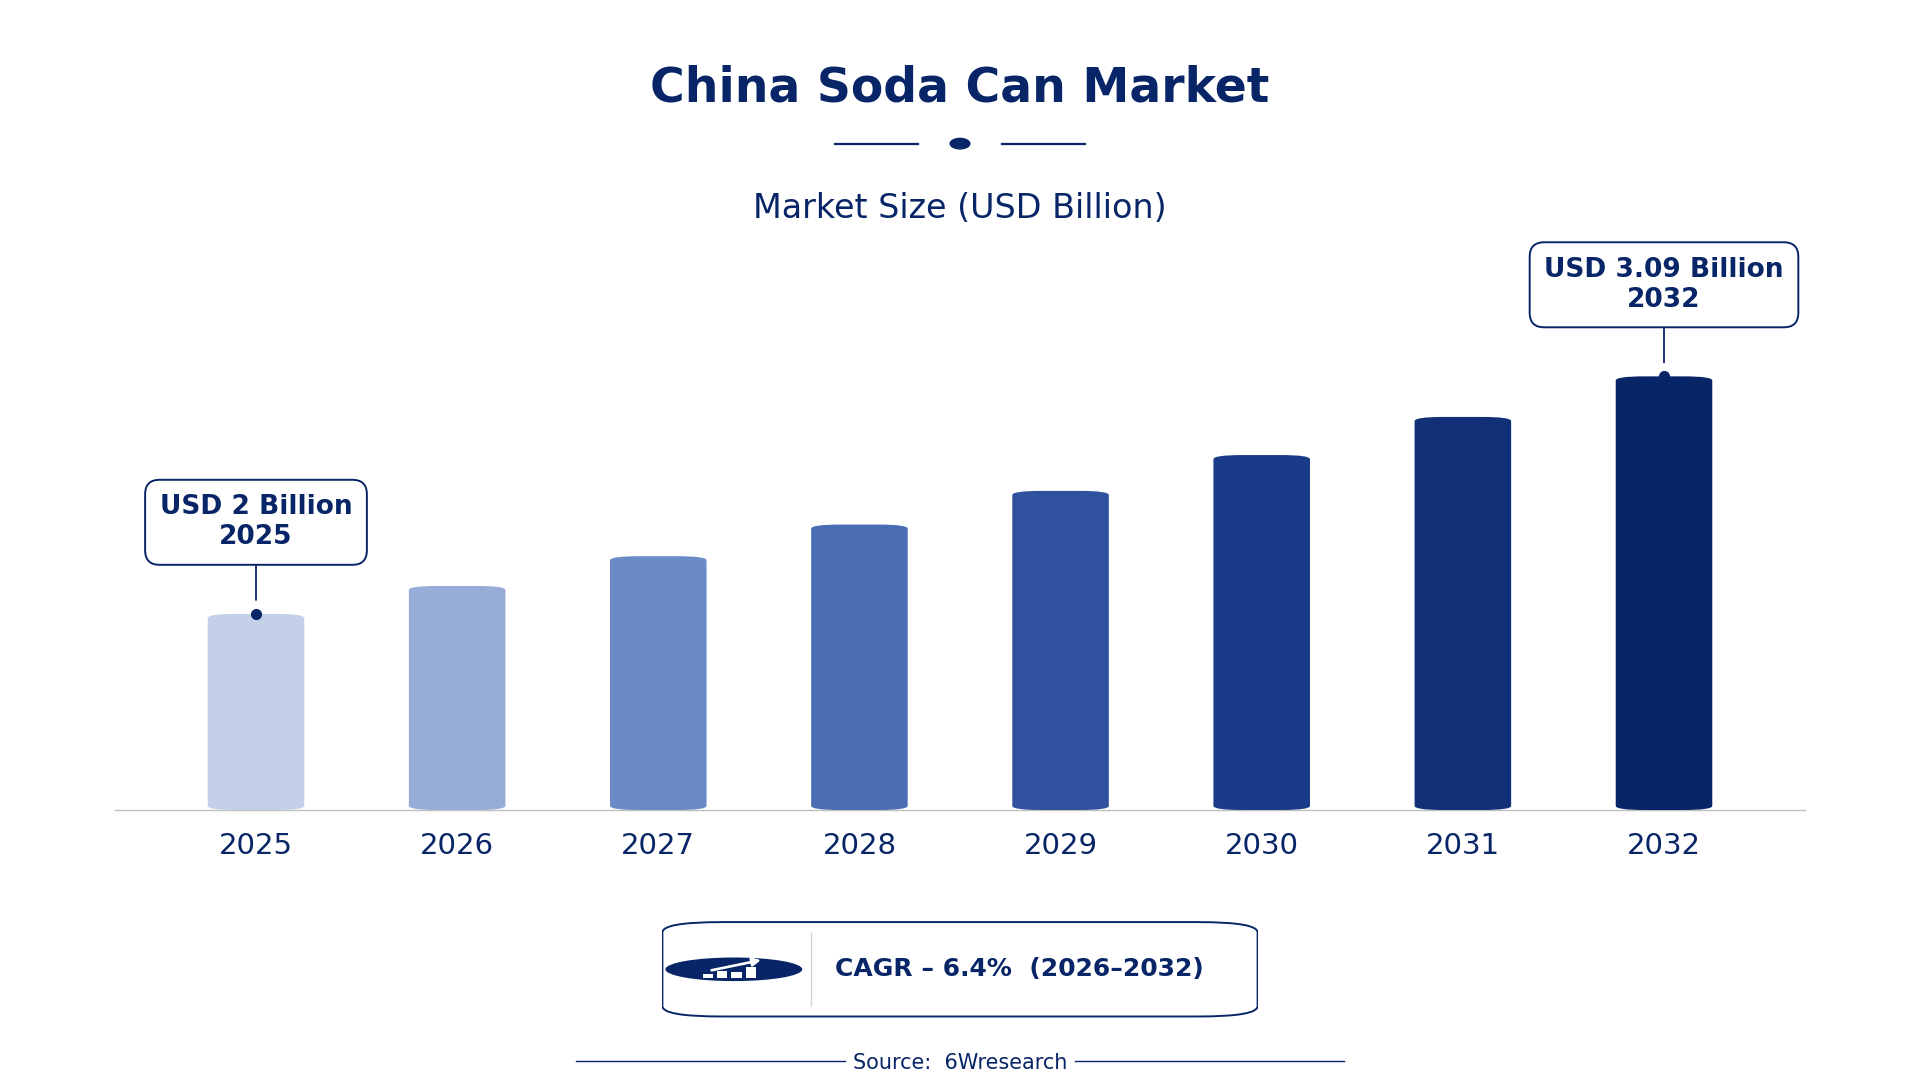
According to 6Wresearch internal database and industry insights, the China Soda Can Market was valued at USD 2.00 billion in 2025 and is projected to reach USD 3.09 billion by 2032, growing at a CAGR of approximately 6.4% during 2026–2032.
China Soda Can Market Highlights
| Report Metric | Details |
| Report Name | China Soda Can Market |
| Market Size 2025 | USD 2.00 billion |
| Market Size 2032 | USD 3.09 billion |
| Absolute Growth 2025–2032 | USD 1.09 billion |
| CAGR 2026–2032 | 6.4% |
| Peak Annual Growth | 8.8% in 2031 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Can Type, 2025 | Standard 330ml (46% share) |
| Leading Material Used, 2025 | Aluminum (48% share) |
| Leading Coating Type, 2025 | BPA-Free (43% share) |
| Leading End User Product, 2025 | Soft Drinks (42% share) |
| Fastest-Growing Can Type | Slim 250ml (9.1% CAGR) |
| Fastest-Growing Material Used | Recycled Aluminum (7.5% CAGR) |
| Fastest-Growing Coating Type | Water-Based Liner (9.0% CAGR) |
| Fastest-Growing End User Product | Energy Drinks (8.3% CAGR) |
| Growing Sector | Energy Drinks |
| Key End Users | Soft Drinks, Energy Drinks, Alcoholic Beverages, Kids' Beverages |
China Soda Can Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
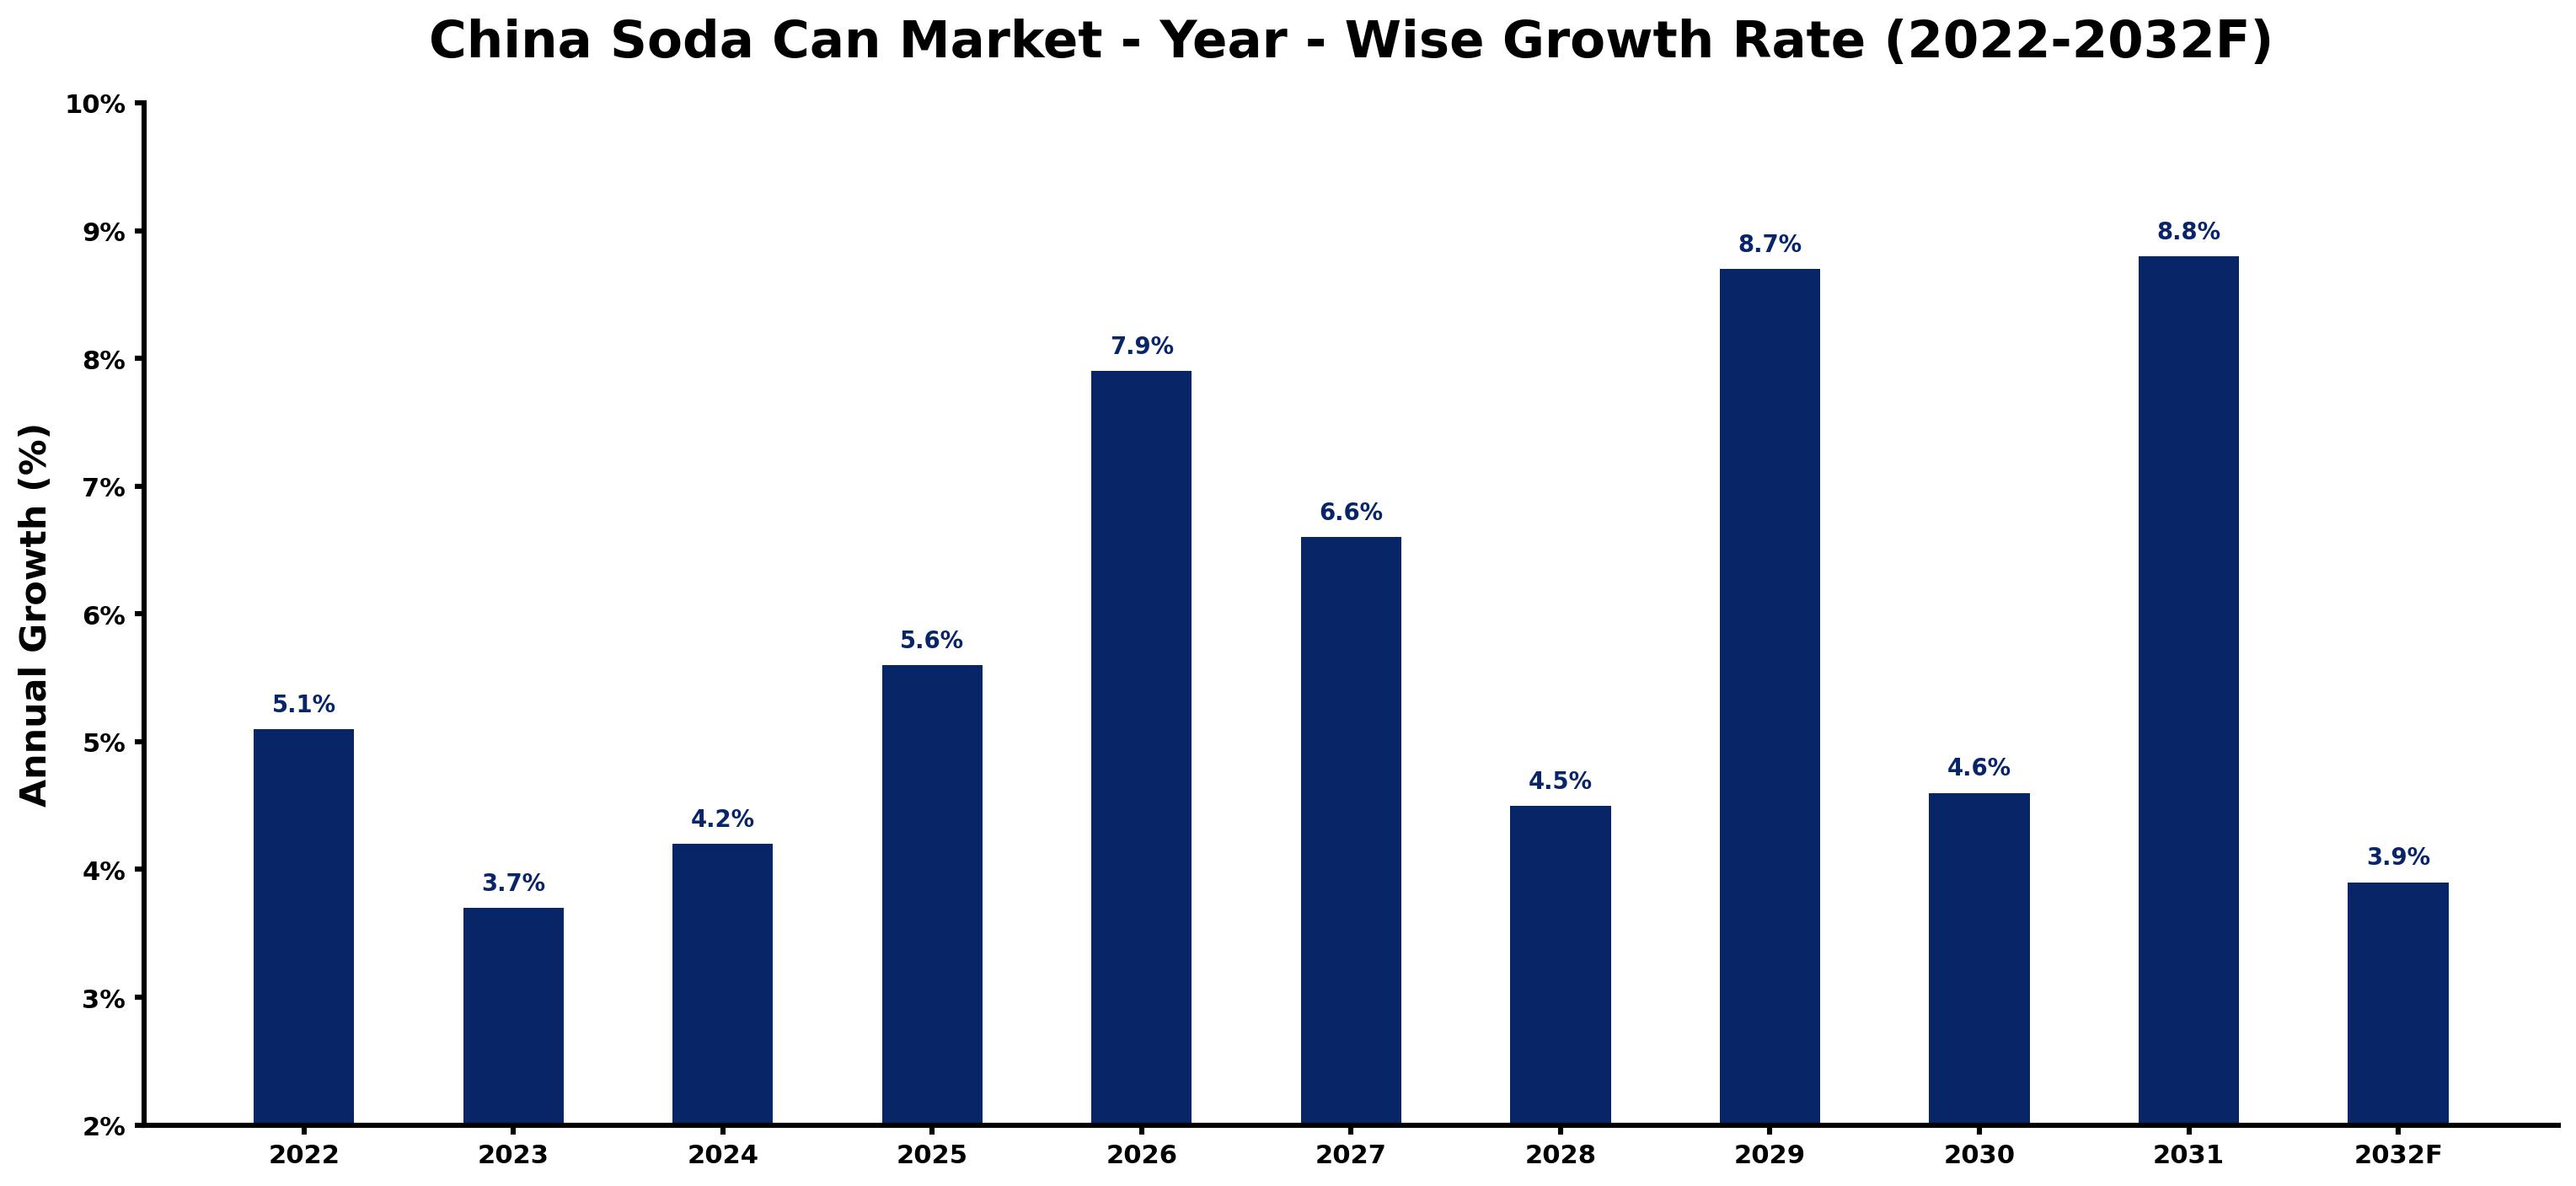
The table below sets out the estimated growth rate for each year and the main factor behind it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 5.1 | The beverage industry was valued at over 1 trillion CNY, driving can demand. |
| 2023 | 3.7 | A 10% increase in beverage consumption reported by the China Beverage Industry Association slowed growth compared to last year. |
| 2024 | 4.2 | The rising popularity of energy drinks contributed to an uptick in can demand. |
| 2025 | 5.6 | The market saw accelerated growth as the standard 330ml can remained the most popular size. |
| 2026 | 7.9 | Increased beverage consumption is expected to drive demand for aluminum cans significantly. |
| 2027 | 6.6 | The market growth slowed as competition among beverage manufacturers intensified. |
| 2028 | 4.5 | The demand for BPA-free coatings increased due to consumer health concerns, impacting growth. |
| 2029 | 8.7 | The energy drinks segment is projected to grow by 15% annually, boosting can demand. |
| 2030 | 4.6 | Growth slowed as the market adjusted to changing consumer preferences and sustainability practices. |
| 2031 | 8.8 | The introduction of new lightweight alloy cans for energy drinks spurred growth in the market. |
| 2032 | 3.9 | The market is expected to stabilise as sustainability initiatives continue to shape consumer choices. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Soda Can Market Synopsis
The Soda Can Market in China includes aluminum and steel cans primarily used for packaging beverages. These cans are produced through stamping and forming processes, with aluminum being the preferred choice due to its lightweight and recyclable nature. The market is expanding as beverage consumption rises, with the beverage industry valued at over 1 trillion CNY in 2022. Increased demand from local beverage manufacturers and a focus on sustainability are propelling investments in this sector.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Rising beverage consumption in urban areas drives demand for soda cans. | Driver | High | Soft Drinks |
| The increasing popularity of energy drinks boosts demand for specialized can types. | Driver | High | Energy Drinks |
| Growing demand for sustainable packaging creates opportunities for recycled aluminum cans. | Opportunity | High | Recycled Aluminum |
| The rise of BPA-free coatings presents a chance for manufacturers to innovate. | Opportunity | Medium | BPA-Free |
| High competition among beverage manufacturers limits pricing flexibility for can producers. | Restraint | High | Aluminum |
| Stricter regulations on packaging materials may increase compliance costs for producers. | Restraint | Medium | Epoxy Resin |
| The Soda Can Market in China faces challenges from rising raw material costs, affecting profitability. | Challenge | High | Aluminum |
| Consumer preferences shifting towards eco-friendly products can complicate market strategies. | Challenge | Medium | BPA-Free |
Evaluation of Drivers in China Soda Can Market (2026–2032)
Below mentioned are some major drivers and their influence on market dynamics.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased beverage consumption drives demand for standard 330ml cans, which account for approximately 60% of the market. | Standard 330ml | The beverage industry in China was valued at over 1 trillion CNY in 2022. |
| The popularity of energy drinks leads to higher demand for Slim 250ml cans, which are becoming increasingly popular. | Slim 250ml | The energy drinks market is projected to grow by 15% annually. |
| Sustainability efforts are pushing the use of recycled aluminum, projected to grow at a CAGR of 7.5%. | Recycled Aluminum | The 'Green Recycling Initiative' aims to increase aluminum recycling rates by 20% by 2025. |
| Consumer health concerns are driving demand for BPA-free coatings, which hold a 43% market share. | BPA-Free | The demand for BPA-free coatings is rising due to health concerns among consumers. |
| The introduction of lightweight alloy cans for energy drinks is anticipated to improve product offerings. | Lightweight Alloy | Testing of lightweight alloy cans aims to reduce packaging weight for energy drinks. |
The Soda Can market in China is growing on the back of rising beverage consumption, increased interest in energy drinks, and sustainability efforts. The beverage industry was valued at over 1 trillion CNY in 2022, creating substantial demand for standard 330ml cans, which dominate the market. The energy drinks segment is set to expand rapidly, leading to higher demand for Slim 250ml cans. Sustainability efforts are encouraging the use of recycled aluminum, which is gaining traction among producers. Health concerns are prompting manufacturers to adopt BPA-free coatings, further driving market growth as they seek to meet consumer safety expectations.
Evaluation of Restraints in China Soda Can Market
The key brakes on demand, and where they bite hardest, are shown below.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| High competition among beverage manufacturers limits pricing flexibility for can producers. | Aluminum | Intense competition pressures producers to maintain lower prices, affecting profit margins. |
| Stricter regulations on packaging materials may increase compliance costs for producers. | Epoxy Resin | The implementation of the 'National Standard for Food Safety' adds compliance costs for can manufacturers. |
| The rising costs of raw materials, such as aluminum, impact overall production expenses. | Recycled Aluminum | Fluctuations in aluminum prices can lead to increased production costs for can producers. |
| Limited consumer awareness regarding recycling practices can hinder the adoption of sustainable cans. | BPA-Free | Low consumer engagement in recycling initiatives affects the growth of sustainable packaging. |
| Market saturation in urban areas may limit growth opportunities for can producers. | Soft Drinks | High population density in urban areas leads to intense competition among beverage brands. |
China Soda Can Market Challenges
In the China soda can market, buyers face rising costs as raw material prices have surged by 15% in the last year, constraining profit margins for beverage manufacturers. This inflation can hinder smaller producers from maintaining competitive pricing, ultimately resulting in higher consumer prices. Supply chain disruptions particularly impact local producers in urban areas like Shanghai, where logistical inefficiencies can delay deliveries and increase costs by up to 20%. Rapid technological advancements in can production require substantial investment, which can prevent smaller producers from adopting more efficient manufacturing processes promptly.
Trends in the China Soda Can Market
The trends below show where the China Soda Can Market is heading.
- Shift from Traditional to Sustainable Packaging: The trend towards sustainable packaging began in 2021 with the 'Green Recycling Initiative', aiming to increase aluminum recycling rates by 20% by 2025. This shift encourages manufacturers to invest in recycled materials, improving their market appeal and compliance with sustainability standards.
- Rise of BPA-Free Can Coatings: The demand for BPA-free coatings has surged since 2022 due to health concerns, with a 43% market share. This trend is prompting manufacturers to innovate and meet consumer safety expectations, ensuring compliance with updated safety standards.
- Growth in Energy Drink Packaging: Energy drinks have gained popularity since 2023, leading to increased demand for Slim 250ml cans. This segment is projected to grow at a CAGR of 9.1%, reflecting changing consumer preferences and health trends in the beverage market.
- Urban Areas Driving Can Demand: Urban centres like Shanghai and Beijing are central to soda can demand, with high population density supporting beverage consumption. The average per capita consumption of soft drinks is around 30 litres per year, driving can sales and increasing competition among producers.
Investment Opportunities in the China Soda Can Market
The following opportunities in the China Soda Can Market pair current demand with a clear way in.
- Beverage Manufacturers Seeking Sustainable Solutions: Beverage manufacturers are increasingly seeking sustainable packaging solutions, particularly recycled aluminum cans. With a projected growth of 7.5% for recycled aluminum, partnerships with local recyclers can facilitate market entry and support sustainability efforts in urban areas.
- Collaborations for Innovative Can Designs: Collaborations with local firms can facilitate the introduction of innovative can designs, particularly lightweight alloy cans. This approach is essential in urban areas where competition is fierce, allowing for differentiation in product offerings and appealing to health-conscious consumers.
- Investing in BPA-Free Coatings: Investing in BPA-free coatings presents a significant opportunity as consumer health concerns rise. The growing demand for these coatings can be met through collaborations with local suppliers, ensuring compliance with safety standards and enhancing market competitiveness.
- Expanding into Energy Drink Packaging: Energy drink manufacturers are looking for suppliers of specialized cans, particularly Slim 250ml. Entering this market segment through local partnerships can yield substantial returns, capitalising on the growing consumer interest in health-oriented beverages.
Government Initiatives in the China Soda Can Market
The 'Green Recycling Initiative' launched by the Ministry of Ecology and Environment in 2021 aims to increase aluminum recycling rates by 20% by 2025. This initiative encourages producers to adopt sustainable practices and improve recycling infrastructure. The 'Circular Economy Development Strategy', introduced in 2020, promotes sustainable packaging practices across industries, including beverage cans. This strategy aims to reduce waste and improve recycling, positively impacting the soda can market. Furthermore, the 'National Standard for Food Safety' (GB 4806.6-2016) was updated in 2021 to strengthen safety regulations for food contact materials, including can linings, ensuring consumer safety and compliance with industry standards.
The Ministry of Industry and Information Technology oversees the implementation of various standards and regulations affecting the soda can market. It approves safety certifications and supports initiatives that enhance packaging sustainability. The State Administration for Market Regulation enforces compliance with packaging guidelines, ensuring that producers meet safety and environmental standards. In 2023, the National Development and Reform Commission announced a plan to reduce packaging waste by 30% by 2025, which will impact the soda can industry significantly.
Future Insight of the China Soda Can Market
The China soda can market will experience notable changes by 2032, primarily driven by a shift towards sustainable packaging solutions supported by government initiatives like the 'Green Recycling Initiative'. The energy drink sector will expand, with demand for lightweight cans increasing as this segment grows by 15% annually. BPA-free coatings will become more prevalent, addressing health concerns and enhancing consumer trust. Advances in recycling technology are expected to elevate the recycling rate beyond 50%, aligning with the objectives of the 'Circular Economy Development Strategy'.
Market Segmentation Analysis
Each segment group is reviewed below, with the leader by share and the fastest grower by CAGR.
By Can Type – Standard 330ml Dominated, Slim 250ml Expected to Grow Fastest
According to Summon Dutta, Assistant Manager at 6Wresearch, Standard 330ml took a 46% share of can type in 2025, more than any other category. The standard 330ml can holds the largest market share due to its widespread use for packaging soft drinks, which dominate the beverage sector. This can size accounts for approximately 60% of the total soda can market in China, reflecting its established presence among consumers. The quickest growth will come from Slim 250ml, forecast to expand at a CAGR of 9.1% between 2026 and 2032. The slim 250ml can is experiencing rapid growth driven by the rising popularity of energy drinks, which are expected to grow by 15% annually. This trend indicates a shift towards more premium beverage options that appeal to health-conscious consumers. Suppliers should focus on expanding their offerings in the slim can segment to capture the growing demand for energy drinks.
By Material Used – Aluminum Dominated, Recycled Aluminum Expected to Grow Fastest
Aluminum held a 48% share of the China Soda Can Market by material used in 2025. Aluminum commands the largest market share as the primary material for soda cans, valued for its lightweight and recyclable properties. This material is essential for manufacturers in regions like Guangdong, where logistics efficiency is a priority. Recycled Aluminum is set to record the highest CAGR in this split, 7.5% over 2026–2032. Recycled aluminum is witnessing significant growth, driven by a societal shift towards sustainability and government initiatives that promote recycling. This trend is expected to accelerate as consumer preferences increasingly favour environmentally friendly options. Suppliers must prioritise the use of recycled aluminum to align with consumer expectations for sustainable packaging solutions.
By Coating Type – BPA-Free Dominated, Water-Based Liner Expected to Grow Fastest
The largest coating type category in 2025 was BPA-Free, with a 43% share of total revenue. BPA-free coatings lead the market due to growing consumer safety concerns regarding food packaging. This type of coating is increasingly preferred by manufacturers to ensure compliance with health regulations and consumer expectations. Water-Based Liner is projected to grow fastest, at a CAGR of 9.0% during 2026–2032. Water-based liners are rapidly gaining traction as an eco-friendly alternative, driven by environmental agencies promoting safer packaging options. This shift reflects a broader trend towards sustainable practices in the beverage industry. Suppliers should invest in developing and marketing water-based liner technologies to meet the rising demand for environmentally friendly packaging solutions.
By End User Product – Soft Drinks Dominated, Energy Drinks Expected to Grow Fastest
In 2025, Soft Drinks led the end user product split with a 42% share. Soft drinks dominate the soda can market, accounting for a substantial share of the beverage industry, which is valued at over 1 trillion CNY. The high average per capita consumption of around 30 litres per year reinforces the strong demand for this segment. Over 2026–2032, Energy Drinks are expected to post the fastest growth, at a CAGR of 8.3%. Energy drinks are emerging as the fastest-growing segment, projected to expand by 15% annually, reflecting a rising consumer interest in functional beverages. This growth indicates a shift in preferences, particularly among younger consumers seeking energy-boosting options. Manufacturers should consider diversifying their product lines to include more energy drink options to capitalise on this rapidly expanding market segment.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Soda Can Market Outlook
- Market Size of China Soda Can Market, 2025
- Forecast of China Soda Can Market, 2032
- Historical Data and Forecast of China Soda Can Revenues & Volume for the Period 2022 - 2032F
- China Soda Can Market Trend Evolution
- China Soda Can Market Drivers and Challenges
- China Soda Can Price Trends
- China Soda Can Porter's Five Forces
- China Soda Can Industry Life Cycle
- Historical Data and Forecast of China Soda Can Market Revenues & Volume By Can Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Soda Can Market Revenues & Volume By Standard 330ml for the Period 2022 - 2032F
- Historical Data and Forecast of China Soda Can Market Revenues & Volume By Slim 250ml for the Period 2022 - 2032F
- Historical Data and Forecast of China Soda Can Market Revenues & Volume By Tallboy 500ml for the Period 2022 - 2032F
- Historical Data and Forecast of China Soda Can Market Revenues & Volume By Mini 150ml for the Period 2022 - 2032F
- Historical Data and Forecast of China Soda Can Market Revenues & Volume By Material Used for the Period 2022 - 2032F
- Historical Data and Forecast of China Soda Can Market Revenues & Volume By Aluminum for the Period 2022 - 2032F
- Historical Data and Forecast of China Soda Can Market Revenues & Volume By Recycled Aluminum for the Period 2022 - 2032F
- Historical Data and Forecast of China Soda Can Market Revenues & Volume By Steel for the Period 2022 - 2032F
- Historical Data and Forecast of China Soda Can Market Revenues & Volume By Lightweight Alloy for the Period 2022 - 2032F
- Historical Data and Forecast of China Soda Can Market Revenues & Volume By Coating Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Soda Can Market Revenues & Volume By BPA-Free for the Period 2022 - 2032F
- Historical Data and Forecast of China Soda Can Market Revenues & Volume By Epoxy Resin for the Period 2022 - 2032F
- Historical Data and Forecast of China Soda Can Market Revenues & Volume By Acrylic Coating for the Period 2022 - 2032F
- Historical Data and Forecast of China Soda Can Market Revenues & Volume By Water-Based Liner for the Period 2022 - 2032F
- Historical Data and Forecast of China Soda Can Market Revenues & Volume By End User Product for the Period 2022 - 2032F
- Historical Data and Forecast of China Soda Can Market Revenues & Volume By Soft Drinks for the Period 2022 - 2032F
- Historical Data and Forecast of China Soda Can Market Revenues & Volume By Energy Drinks for the Period 2022 - 2032F
- Historical Data and Forecast of China Soda Can Market Revenues & Volume By Alcoholic Beverages for the Period 2022 - 2032F
- Historical Data and Forecast of China Soda Can Market Revenues & Volume By Kids Beverages for the Period 2022 - 2032F
- China Soda Can Import Export Trade Statistics
- Market Opportunity Assessment By Can Type
- Market Opportunity Assessment By Material Used
- Market Opportunity Assessment By Coating Type
- Market Opportunity Assessment By End User Product
- China Soda Can Top Companies Market Share
- China Soda Can Competitive Benchmarking By Technical and Operational Parameters
- China Soda Can Company Profiles
- China Soda Can Key Strategic Recommendations
Market Covered
The report offers an extensive study of the following market segments.
By Can Type
- Standard 330ml
- Slim 250ml
- Tallboy 500ml
- Mini 150ml
By Material Used
- Aluminum
- Recycled Aluminum
- Steel
- Lightweight Alloy
By Coating Type
- BPA-Free
- Epoxy Resin
- Acrylic Coating
- Water-Based Liner
By End User Product
- Soft Drinks
- Energy Drinks
- Alcoholic Beverages
- Kids' Beverages































