China Streaming Media Advertising Market Size & Growth Rate
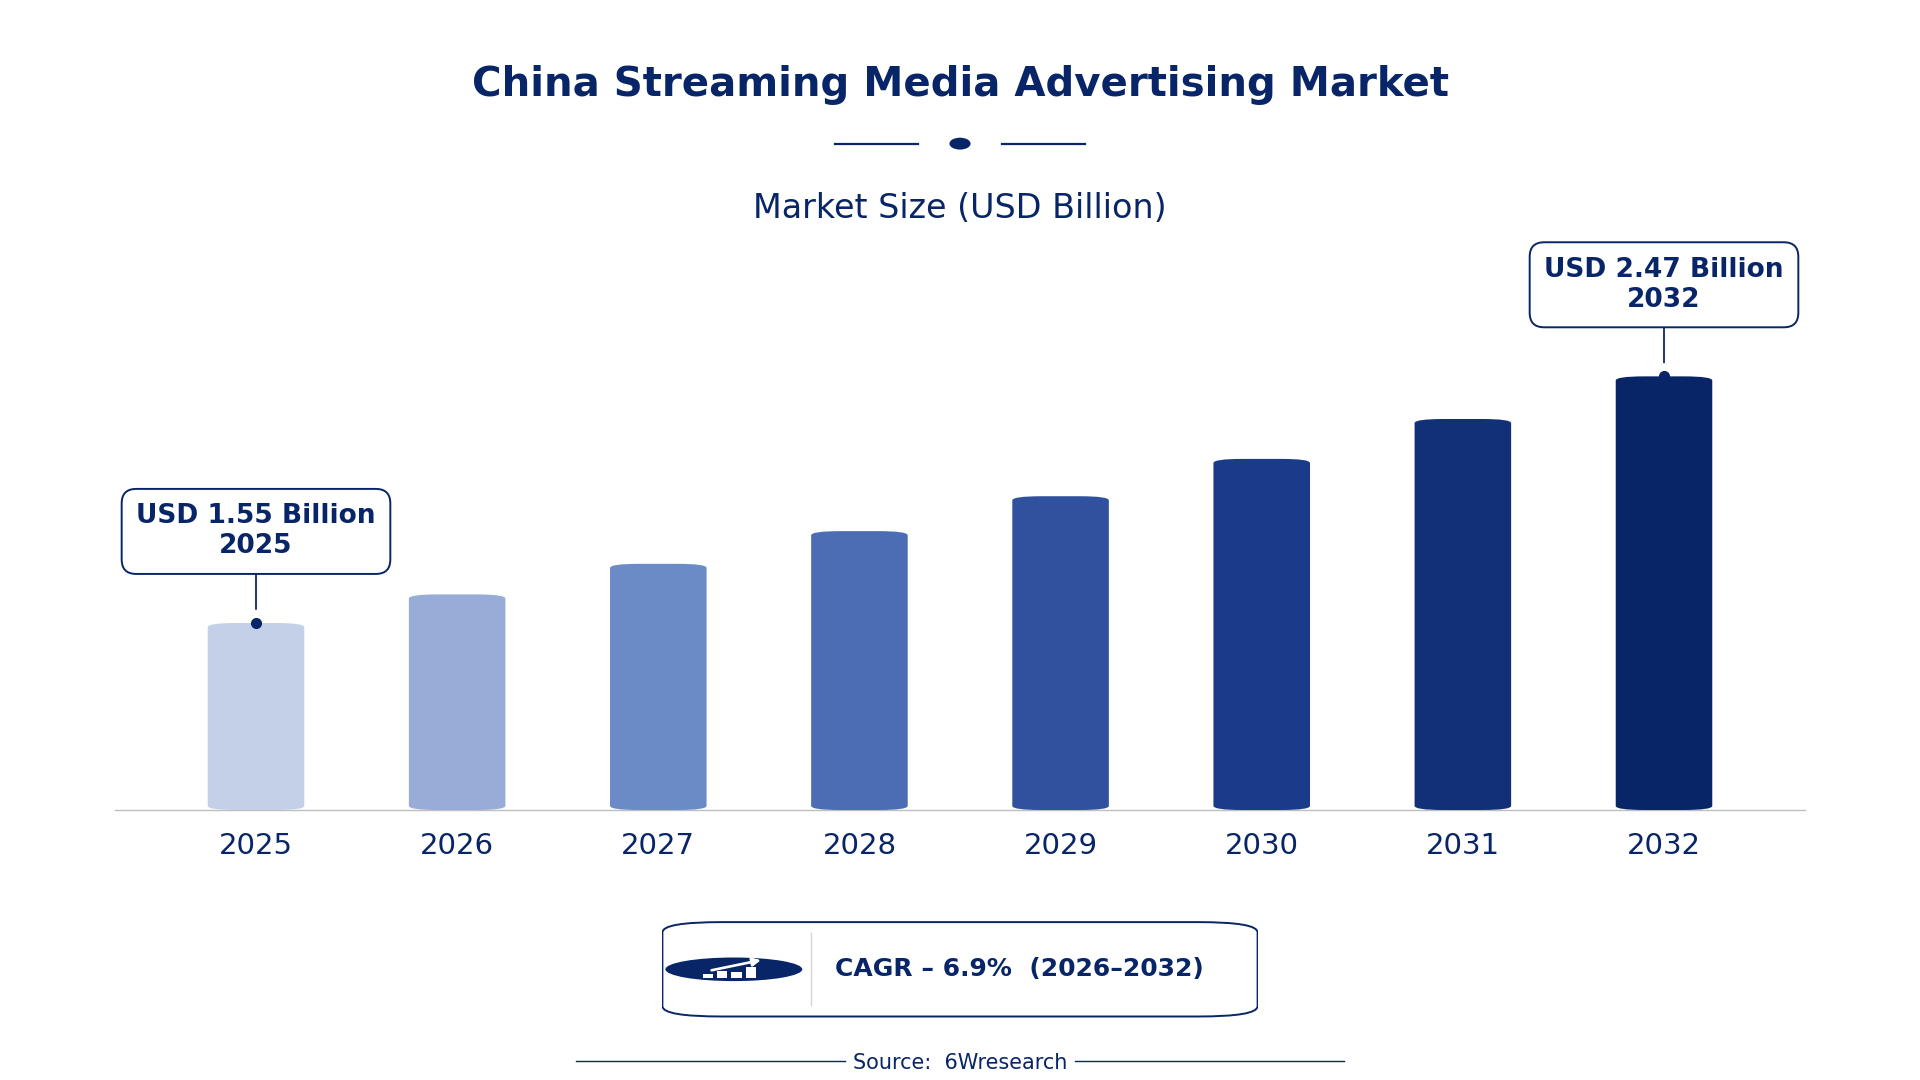
According to 6Wresearch internal database and industry insights, the China Streaming Media Advertising Market was valued at USD 1.55 billion in 2025 and is projected to reach USD 2.47 billion by 2032, growing at a CAGR of approximately 6.9% during 2026–2032.
China Streaming Media Advertising Market Highlights
| Report Metric | Details |
| Report Name | China Streaming Media Advertising Market |
| Market Size 2025 | USD 1.55 billion |
| Market Size 2032 | USD 2.47 billion |
| Absolute Growth 2025–2032 | USD 0.92 billion |
| CAGR 2026–2032 | 6.9% |
| Peak Annual Growth | 9.6% in 2032 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Ad Format, 2025 | Pre-Roll Ads (52% share) |
| Leading Platform Type, 2025 | OTT Platforms (44% share) |
| Leading Targeting Strategy, 2025 | Behavioral (36% share) |
| Leading End User, 2025 | E-commerce Platforms (35% share) |
| Fastest-Growing Ad Format | Interactive Ads (8.4% CAGR) |
| Fastest-Growing Platform Type | AVOD Services (8.0% CAGR) |
| Fastest-Growing End User | FMCG Brands (7.9% CAGR) |
| Growing Sector | FMCG Brands |
| Key End Users | E-commerce Platforms, FMCG Brands, Retail Advertisers, Tech Companies |
China Streaming Media Advertising Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
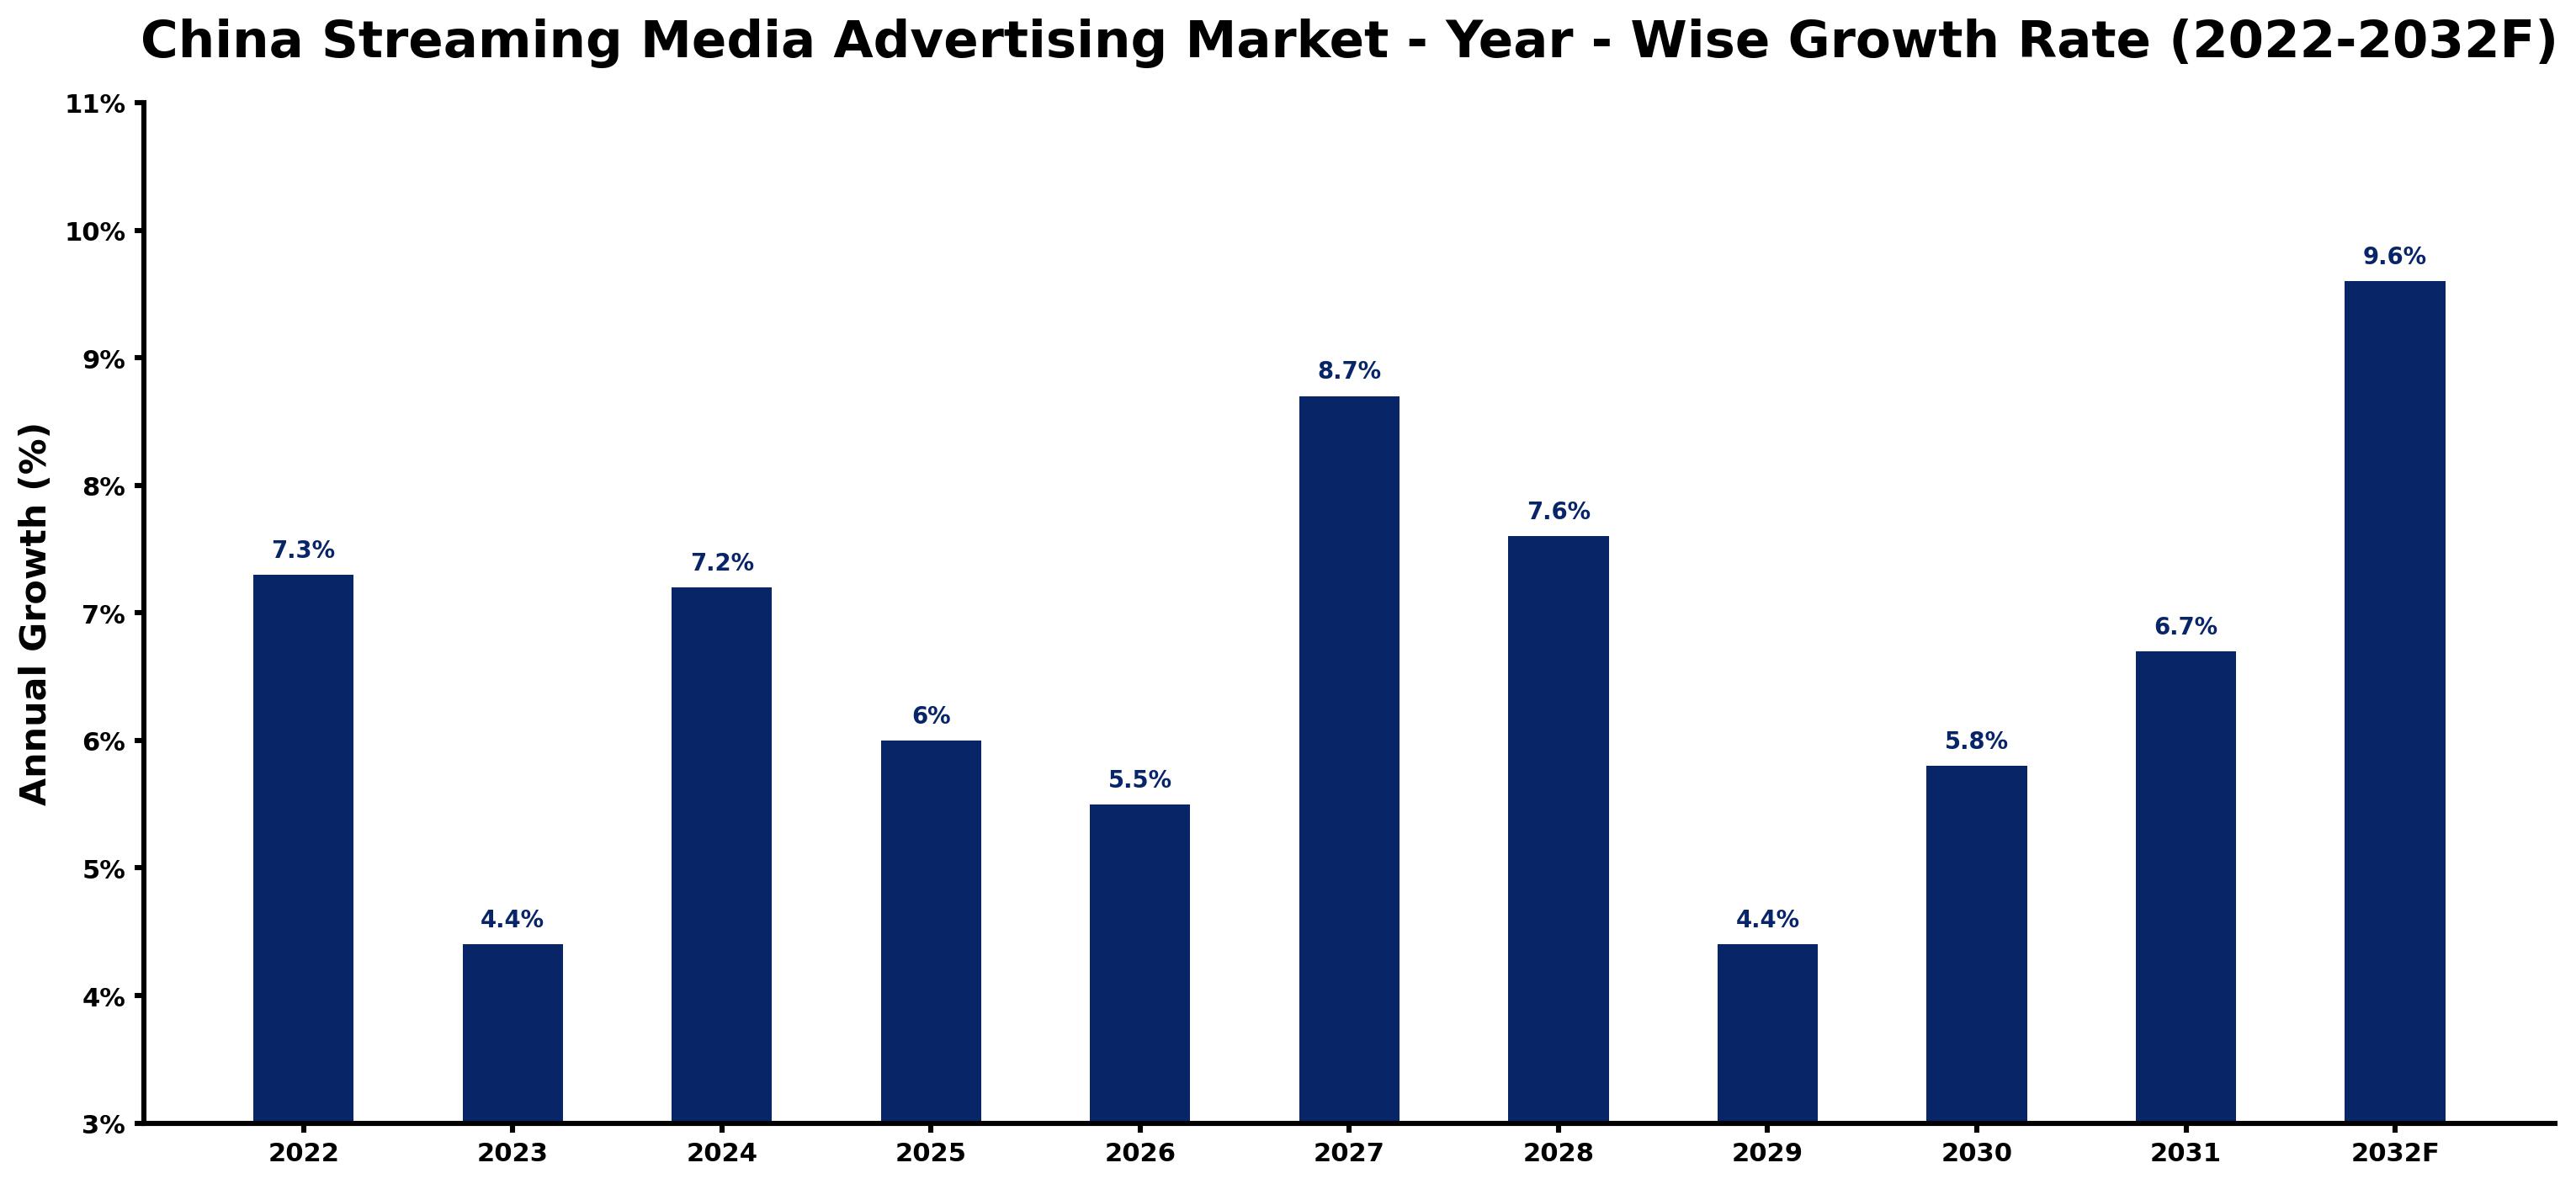
Year by year, the estimates below pair each growth rate with the development that shaped it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 7.3 | The market experienced strong growth due to rising internet user numbers and increased digital advertising spending. |
| 2023 | 4.4 | Growth slowed as advertisers adjusted budgets amidst economic uncertainties, yet demand remained strong. |
| 2024 | 7.2 | The market rebounded with increased spending on streaming ads, driven by higher engagement rates. |
| 2025 | 6.0 | Growth moderated as competition intensified among platforms and advertisers focused on efficiency. |
| 2026 | 5.5 | A further slowdown is expected as advertisers seek to optimise their digital strategies and budgets. |
| 2027 | 8.7 | The market is projected to surge as new advertising technologies gain traction, improving targeting capabilities. |
| 2028 | 7.6 | Growth is anticipated to decelerate as market saturation begins to affect ad placements and effectiveness. |
| 2029 | 4.4 | Another slowdown is expected as advertisers become more cautious in their spending habits. |
| 2030 | 5.8 | A recovery is projected as new ad formats attract renewed interest from brands. |
| 2031 | 6.7 | Growth is expected to rise as the e-commerce sector expands, driving ad demand. |
| 2032 | 9.6 | The market is projected to peak as streaming platforms innovate and capture larger advertising budgets. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Streaming Media Advertising Market Synopsis
The China Streaming Media Advertising Market involves promoting products through digital video content delivered online. This market is characterised by the integration of advertisements into various streaming platforms, boosting brand awareness and customer engagement. The market is growing due to a surge in internet users, with 1.05 billion users in 2022, and the booming e-commerce sector, projected to reach 40 trillion yuan by 2025. The average daily time spent on video streaming platforms is approximately 1.5 hours, indicating strong consumer engagement with digital content.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increasing internet penetration and user engagement drive demand for streaming ads. | Driver | High | OTT Platforms |
| The rapid growth of the e-commerce sector fuels advertising spending on streaming media. | Driver | High | E-commerce Platforms |
| The rise of interactive ads presents opportunities for advertisers to engage viewers more effectively. | Opportunity | Medium | Interactive Ads |
| The demand for targeted advertising strategies is growing, creating openings for innovative solutions. | Opportunity | Medium | Behavioral |
| Regulatory changes may impose stricter guidelines on advertising practices, affecting compliance costs. | Restraint | High | Pre-Roll Ads |
| Competition among platforms can lead to price wars, impacting profitability for advertisers. | Restraint | Medium | Pre-Roll Ads |
| The Streaming Media Advertising market in China faces challenges from evolving consumer preferences. | Challenge | High | Pre-Roll Ads |
| Technological advancements require continuous investment, posing a challenge for smaller advertisers. | Challenge | Medium | Pre-Roll Ads |
Evaluation of Drivers in China Streaming Media Advertising Market (2026–2032)
The factors lifting demand, and the evidence behind each, are summarised below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Rising internet user numbers increase the audience for streaming ads. | OTT Platforms | In 2022, the number of internet users in China reached 1.05 billion, driving ad demand. |
| E-commerce platforms are increasing their advertising budgets to capture consumer attention. | E-commerce Platforms | The e-commerce sector is expected to reach 40 trillion yuan by 2025, boosting ad spending. |
| High engagement rates on streaming platforms encourage brands to invest in ads. | AVOD Services | In 2023, 60% of consumers reported engaging with ads on streaming platforms. |
| New ad formats, such as interactive ads, attract more advertisers seeking engagement. | Interactive Ads | Interactive ads saw a 15% increase in adoption in 2023, enhancing viewer interaction. |
| The average revenue per user for streaming services supports higher advertising budgets. | Pre-Roll Ads | The average revenue per user for streaming services in China is around 100 yuan annually. |
Expansion of the Streaming Media Advertising market in China is backed by rising internet user numbers, increasing e-commerce spending, and high engagement rates. With 1.05 billion internet users in 2022, advertisers are eager to reach a larger audience through streaming platforms. The e-commerce sector is projected to hit 40 trillion yuan by 2025, prompting brands to allocate more budgets for digital advertising. In 2023, 60% of consumers engaged with ads on streaming platforms, highlighting the effectiveness of this medium. The average revenue per user for streaming services in China is around 100 yuan annually, supporting higher advertising budgets.
Evaluation of Restraints in China Streaming Media Advertising Market
The key brakes on demand, and where they bite hardest, are shown below.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Ineffective technology integration hinders effective ad targeting. | OTT Platforms | Around 60% of advertisers struggle to leverage advanced analytics tools, resulting in poor ad targeting. |
| Regulatory hurdles complicate advertising approvals. | E-commerce Platforms | Strict guidelines from the National Radio and Television Administration can delay ad approvals, extending campaign timelines. |
| Supply chain disruptions arise from the rapid proliferation of OTT platforms. | AVOD Services | This can hinder timely ad placements, causing frustration for buyers eager for immediate exposure. |
| Fierce competition among advertisers limits visibility. | Pre-Roll Ads | E-commerce ad spending is projected to hit 40 trillion yuan by 2025, making visibility a challenge for smaller brands. |
| Market saturation affects ad placements and effectiveness. | Interactive Ads | As more advertisers enter the market, the effectiveness of ad placements may decline. |
China Streaming Media Advertising Market Challenges
In the China Streaming Media Advertising market, around 60% of advertisers face challenges with technology integration, leading to ineffective ad targeting and lost engagement opportunities. Regulatory complexities arise from strict guidelines imposed by the National Radio and Television Administration, which can delay ad approvals and increase costs for suppliers. Supply chain issues stem from the rapid increase in the number of OTT platforms, disrupting timely ad placements and frustrating buyers who seek immediate visibility. Additionally, fierce competition in the e-commerce sector, with ad spending projected to reach 40 trillion yuan by 2025, makes it difficult for smaller brands to stand out in a crowded marketplace.
Trends in the China Streaming Media Advertising Market
Buyers and suppliers in the China Streaming Media Advertising Market are adjusting to the following trends.
- Shift Towards Interactive Advertising: In 2023, the adoption of interactive ads rose by 15%, reflecting a shift towards more engaging formats. This trend is particularly relevant among e-commerce platforms, which utilise interactive content to boost consumer engagement and conversion rates.
- Growth of AVOD Services: AVOD services represented 30% of total streaming revenue in 2023, highlighting their increasing importance. This growth is especially notable in urban areas, where consumers favour ad-supported content over subscription models.
- Increase in OTT Platform Usage: The number of active OTT platforms in China surpassed 50 in 2023, indicating a growing market. This expansion provides advertisers with more opportunities to reach diverse audiences across various content genres.
- E-commerce Platforms Leading Ad Spend: E-commerce platforms are set to dominate ad spending, with the sector expected to reach 40 trillion yuan by 2025. This growth fuels demand for targeted streaming ads, boosting brand visibility.
Investment Opportunities in the China Streaming Media Advertising Market
The following opportunities in the China Streaming Media Advertising Market pair current demand with a clear way in.
- Gap in Interactive Ad Formats: With a 15% increase in interactive ad adoption in 2023, advertisers have a chance to invest in engaging formats. E-commerce platforms are particularly well-positioned to benefit from this trend, enhancing customer interaction.
- Rising Demand for Video Content: As the average daily time spent on video streaming platforms is around 1.5 hours, there is a growing need for advertisers to provide engaging video content. Retail advertisers are increasingly eager to tap into this trend.
- Investment in AVOD Services: AVOD services accounted for 30% of total streaming revenue in 2023, presenting a strong opportunity for advertisers. Brands can enter this space by collaborating with local streaming platforms to boost visibility.
- Expansion of Digital Advertising Standards: The 'Digital Advertising Standardization Program' launched in 2023 aims to improve industry practices. This initiative offers advertisers a chance to align with evolving standards and enhance their credibility.
Government Initiatives in the China Streaming Media Advertising Market
The '14th Five-Year Plan for the Digital Economy' launched in 2021 by the State Council aims to enhance digital advertising capabilities and infrastructure. This initiative provides a framework for advertisers to innovate and improve their strategies in the digital space. The updated 'Regulations on the Administration of Internet Advertising' in 2022 by the National Radio and Television Administration strengthens content oversight and consumer protection, ensuring that advertising practices are transparent and fair. These measures are essential for maintaining consumer trust and encouraging investment in digital advertising.
The 'Digital Advertising Standardization Program' initiated by the Ministry of Industry and Information Technology in 2023 focuses on improving industry standards and practices. This program supports advertisers by providing guidelines that enhance the effectiveness of their campaigns. Additionally, the State Administration for Market Regulation introduced new guidelines on advertising practices in 2022, ensuring fair competition and transparency in the market. These initiatives help create a conducive environment for advertisers to thrive and reach their target audiences effectively.
Future Insight of the China Streaming Media Advertising Market
The China Streaming Media Advertising market is set for transformation by 2032, driven by a rise in internet users and the rapid growth of OTT platforms. The increasing adoption of interactive ads will improve user engagement and overall campaign effectiveness. Government initiatives under the '14th Five-Year Plan' will promote advancements in digital advertising, paving the way for new strategies. As the e-commerce sector expands, demand for targeted streaming ads will rise, creating fresh opportunities for both buyers and suppliers.
Market Segmentation Analysis
The report offers a comprehensive study of the following market segments and their leading categories in the market.
By Ad Format – Pre-Roll Ads Dominated, Interactive Ads Expected to Grow Fastest
According to Summon Dutta, Assistant Manager at 6Wresearch, Pre-Roll Ads took a 52% share of ad format in 2025, more than any other category. Pre-Roll Ads hold the largest market share in the China Streaming Media Advertising Market because they effectively capture viewer attention before content begins. This format is particularly appealing to advertisers looking to maximise visibility in a country with over 1.05 billion internet users. Over 2026–2032, Interactive Ads are expected to post the fastest growth, at a CAGR of 8.4%. Interactive Ads are experiencing rapid growth due to their ability to enhance user engagement, with a 15% increase in adoption reported in 2023. This shift towards more engaging formats reflects a changing preference among advertisers who aim to create memorable experiences for their audiences. Suppliers should focus on developing innovative ad formats to meet the increasing demand for interactive advertising.
By Platform Type – OTT Platforms Dominated, AVOD Services Expected to Grow Fastest
OTT Platforms held a 44% share of the China Streaming Media Advertising Market by platform type in 2025. OTT Platforms dominate the market owing to their extensive viewership, making them a prime channel for advertisers. With over 50 active OTT platforms in China, they offer a diverse range of content that attracts large audiences, ensuring high engagement rates. AVOD Services are projected to grow fastest, at a CAGR of 8.0% during 2026–2032. AVOD Services are growing rapidly as they represent a significant revenue source through ad placements, capitalising on the increasing number of viewers seeking free content. This trend highlights a shift in consumer behaviour towards ad-supported models, further boosting their market presence. Advertisers should prioritise partnerships with OTT and AVOD platforms to leverage their expansive reach and engage with a broader audience.
By Targeting Strategy – Behavioral Dominated and Is Expected to Record the Fastest Growth
With a 36% revenue share in 2025, Behavioral was the largest targeting strategy category. Behavioral targeting commands the largest market share as it allows advertisers to tailor messages based on user behaviour, leading to higher engagement rates. This strategy is particularly effective in a digital landscape where personalisation is essential for success. The same category is also set to grow fastest, at a CAGR of 8.4% during 2026–2032. The ongoing success of Behavioral targeting ensures it remains the fastest-growing strategy, as advertisers increasingly recognise its effectiveness in reaching specific consumer segments. This trend will likely reinforce its dominance in the market, making it a critical focus for future campaigns. Marketers need to invest in advanced analytics tools to enhance their behavioural targeting capabilities and improve ad performance.
By End User – E-commerce Platforms Dominated, FMCG Brands Expected to Grow Fastest
The largest end user category in 2025 was E-commerce Platforms, with a 35% share of total revenue. E-commerce Platforms are the leading end users of streaming media advertising, relying heavily on these ads to drive traffic and conversions. With the e-commerce sector projected to reach 40 trillion yuan by 2025, their advertising spend is substantial. The quickest growth will come from FMCG Brands, forecast to expand at a CAGR of 7.9% between 2026 and 2032. FMCG Brands are rapidly increasing their investment in streaming ads to effectively reach consumers, reflecting a broader trend in the industry. This growth indicates a shift towards more dynamic advertising strategies within the FMCG sector. Advertisers should tailor their strategies to meet the specific needs of e-commerce and FMCG brands to capture their growing ad budgets.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Streaming Media Advertising Market Outlook
- Market Size of China Streaming Media Advertising Market, 2025
- Forecast of China Streaming Media Advertising Market, 2032
- Historical Data and Forecast of China Streaming Media Advertising Revenues & Volume for the Period 2022 - 2032F
- China Streaming Media Advertising Market Trend Evolution
- China Streaming Media Advertising Market Drivers and Challenges
- China Streaming Media Advertising Price Trends
- China Streaming Media Advertising Porter's Five Forces
- China Streaming Media Advertising Industry Life Cycle
- Historical Data and Forecast of China Streaming Media Advertising Market Revenues & Volume By Ad Format for the Period 2022 - 2032F
- Historical Data and Forecast of China Streaming Media Advertising Market Revenues & Volume By Pre-Roll Ads for the Period 2022 - 2032F
- Historical Data and Forecast of China Streaming Media Advertising Market Revenues & Volume By Mid-Roll Ads for the Period 2022 - 2032F
- Historical Data and Forecast of China Streaming Media Advertising Market Revenues & Volume By Interactive Ads for the Period 2022 - 2032F
- Historical Data and Forecast of China Streaming Media Advertising Market Revenues & Volume By Banner Overlays for the Period 2022 - 2032F
- Historical Data and Forecast of China Streaming Media Advertising Market Revenues & Volume By Platform Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Streaming Media Advertising Market Revenues & Volume By OTT Platforms for the Period 2022 - 2032F
- Historical Data and Forecast of China Streaming Media Advertising Market Revenues & Volume By Live Streaming for the Period 2022 - 2032F
- Historical Data and Forecast of China Streaming Media Advertising Market Revenues & Volume By AVOD Services for the Period 2022 - 2032F
- Historical Data and Forecast of China Streaming Media Advertising Market Revenues & Volume By Music Streaming for the Period 2022 - 2032F
- Historical Data and Forecast of China Streaming Media Advertising Market Revenues & Volume By Targeting Strategy for the Period 2022 - 2032F
- Historical Data and Forecast of China Streaming Media Advertising Market Revenues & Volume By Behavioral for the Period 2022 - 2032F
- Historical Data and Forecast of China Streaming Media Advertising Market Revenues & Volume By Demographic for the Period 2022 - 2032F
- Historical Data and Forecast of China Streaming Media Advertising Market Revenues & Volume By Geographic for the Period 2022 - 2032F
- Historical Data and Forecast of China Streaming Media Advertising Market Revenues & Volume By Contextual for the Period 2022 - 2032F
- Historical Data and Forecast of China Streaming Media Advertising Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Streaming Media Advertising Market Revenues & Volume By FMCG Brands for the Period 2022 - 2032F
- Historical Data and Forecast of China Streaming Media Advertising Market Revenues & Volume By Retail Advertisers for the Period 2022 - 2032F
- Historical Data and Forecast of China Streaming Media Advertising Market Revenues & Volume By E-commerce Platforms for the Period 2022 - 2032F
- Historical Data and Forecast of China Streaming Media Advertising Market Revenues & Volume By Tech Companies for the Period 2022 - 2032F
- China Streaming Media Advertising Import Export Trade Statistics
- Market Opportunity Assessment By Ad Format
- Market Opportunity Assessment By Platform Type
- Market Opportunity Assessment By Targeting Strategy
- Market Opportunity Assessment By End User
- China Streaming Media Advertising Top Companies Market Share
- China Streaming Media Advertising Competitive Benchmarking By Technical and Operational Parameters
- China Streaming Media Advertising Company Profiles
- China Streaming Media Advertising Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By Ad Format
- Pre-Roll Ads
- Mid-Roll Ads
- Interactive Ads
- Banner Overlays
By Platform Type
- OTT Platforms
- Live Streaming
- AVOD Services
- Music Streaming
By Targeting Strategy
- Behavioral
- Demographic
- Geographic
- Contextual
By End User
- FMCG Brands
- Retail Advertisers
- E-commerce Platforms
- Tech Companies































