Europe Electric Bus Market Size & Growth Rate
According to 6Wresearch internal database and industry insights, the Europe Electric Bus Market was valued at USD 5.1 billion in 2025 and is projected to reach USD 17.03 billion by 2032, growing at a CAGR of approximately 18.8% during the forecast period (2026–2032).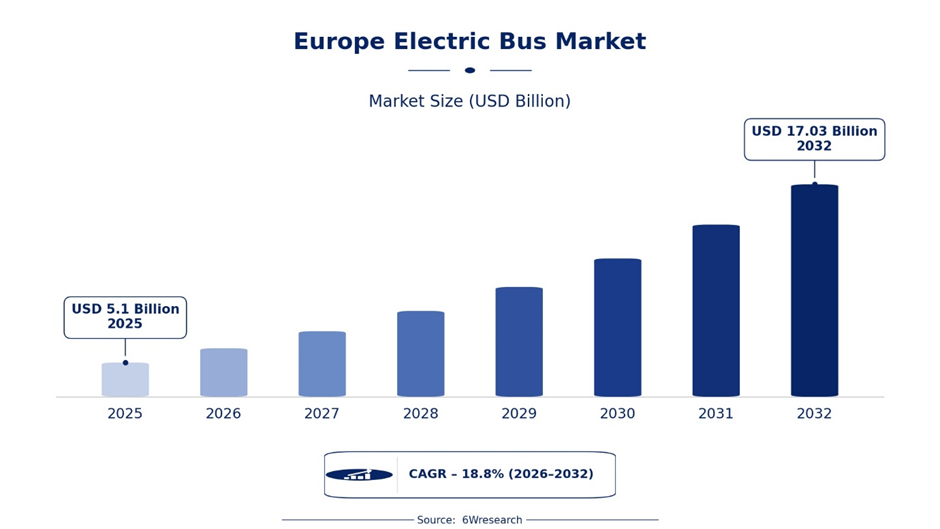
Europe Electric Bus Market Highlights
|
Report Metric |
Details |
|
Report Name |
Europe Electric Bus Market |
|
Market Size 2025 |
USD 5.1 Billion |
|
Market Size 2032 |
USD 17.03 Billion |
|
Absolute Growth 2025–2032 |
USD 11.93 Billion |
|
CAGR 2026–2032 |
18.8% |
|
Peak Annual Growth |
21.1% (2031) |
|
Forecast Period (2026–2032) |
2026–2032 |
|
Historical Data (2022–2025) |
2022–2025 |
|
Base Year (2025) |
2025 |
|
Leading Vehicle Types, 2025 |
Battery Electric Bus (76%) |
|
Leading Charging Infrastructure, 2025 |
Plug Only (40%) |
|
Leading End Users, 2025 |
Public (84%) |
|
Leading Countries, 2025 |
Rest of Europe (30%) |
|
Fastest-Growing Charging Infrastructure |
Induction (24.1% CAGR) |
|
Fastest-Growing End Users |
Private (21.7% CAGR) |
|
Fastest-Growing Countries |
Italy (23.4% CAGR) |
|
Growing Sector |
Urban Public Transport Electrification |
|
Key End Users or Key Procuring Entities |
Municipal transit authorities, regional public transport operators, private bus and coach operators, airport and campus shuttle operators |
Europe Electric Bus Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.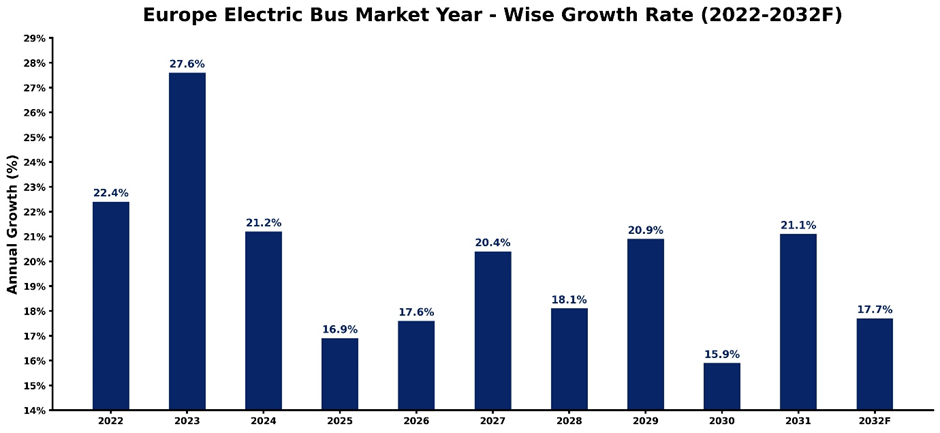 The following table presents the estimated annual growth rate for each year together with the principal factor influencing market performance.
|
Year |
Estimated Annual Growth (%) |
Market Rationale |
|
2022 |
22.4% |
Recovery in transit ridership and the Clean Vehicles Directive taking effect lifted electric bus orders across European cities. |
|
2023 |
27.6% |
Large UK ZEBRA awards and new battery-electric model launch accelerated deliveries, producing the strongest expansion of the period. |
|
2024 |
21.2% |
Growth moderated on a higher base, while stricter heavy-duty CO2 standards adopted in May 2024 sustained operator orders. |
|
2025 |
16.9% |
Italian registrations eased after the exceptional 2024 peak, tempering regional growth despite continued expansion in United Kingdom zero-emission fleets. |
|
2026 |
17.6% |
Fresh national funding rounds for municipal fleets in Britain and Germany are likely to lift orders from public transport operators. |
|
2027 |
20.4% |
Italy’s recovery plan fleet deliveries and expanding depot charging capacity are set to accelerate orders across southern European cities. |
|
2028 |
18.1% |
Expiry of one-off public funding windows is expected to moderate demand as buyers return to standard fleet replacement cycles. |
|
2029 |
20.9% |
Manufacturer preparation for the 2030 urban bus emission milestone is likely to bring forward fleet orders. |
|
2030 |
15.9% |
Early-adopter cities completing main fleet conversions are expected to ease orders after the compliance-driven procurement peak. |
|
2031 |
21.1% |
Replacement of first-generation electric buses ordered in the early 2020s is set to create a fresh procurement cycle. |
|
2032 |
17.7% |
Growth is expected to normalise as large urban fleets approach full electrification ahead of the 2035 urban bus requirement. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch’s proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
Europe Electric Bus Market Synopsis
The Europe Electric Bus Market is projected to grow rapidly, supported by EU procurement and emission rules for urban buses, national fleet funding programmes, municipal renewal plans across southern and western Europe, and expanding regional manufacturing capacity. The market covers battery electric, plug-in electric and hybrid electric buses together with depot, pantograph and inductive charging systems used by transit authorities and private operators.
Market Dynamics Impact Analysis (2026–2032)
|
Factor |
Type |
Impact |
Primary Segment Affected |
|
Stricter CO2 targets for new urban buses |
Driver |
High |
Battery Electric Bus |
|
Binding public procurement targets for clean buses |
Driver |
High |
Public |
|
Depot and terminal charging build-out |
Opportunity |
High |
Roof Pantograph |
|
Replacement of ageing diesel fleets in southern and eastern Europe |
Opportunity |
Medium |
Italy |
|
High upfront vehicle and infrastructure cost |
Restraint |
High |
Public |
|
Delays in depot grid connections |
Restraint |
Medium |
Plug Only |
|
Price competition from Asian manufacturers |
Challenge |
Medium |
Battery Electric Bus |
|
Shortage of high-voltage maintenance skills |
Challenge |
Medium |
Gantry Pantograph |
Evaluation of Drivers in Europe Electric Bus Market (2026–2032)
Below mentioned are some major drivers and their influence on market dynamics:
|
Drivers |
Primary Segment Affected |
Why It Matters (Evidence) |
|
Stricter CO2 targets for new urban buses |
Battery Electric Bus |
Regulation (EU) 2024/1610 sets a 90 percent emission cut for new urban buses from 2030, steering operators towards electric models. |
|
Public procurement targets under the Clean Vehicles Directive |
Public |
Binding national targets for 2026 to 2030 require half of clean bus purchases to be zero-emission, creating predictable demand from transit authorities. |
|
Zero-emission bus grant programmes |
United Kingdom |
Government funding schemes have supported more than 4,000 zero-emission buses in the United Kingdom, narrowing the price gap against diesel for operators. |
|
Longer range from larger batteries |
Battery Electric Bus |
Newer city buses such as the Italian-built Eltron carry 280 kWh batteries, delivering ranges above 200 km and allowing operation on most urban routes. |
|
Operator fleet electrification plans |
Italy |
Milan’s ATM plans to convert its 1,200-bus fleet to zero-emission by 2030, giving suppliers multi-year repeat orders for vehicles and charging equipment. |
In Europe, lower energy and maintenance costs per kilometre are improving lifetime economics against diesel buses, which encourages buyers to commit to electric purchases. An estimated one third of electric buses sold in Europe are assembled in Poland, and this concentration of capacity is shortening delivery times and containing unit prices.
Further, growing availability of leasing and battery-as-a-service financing from banks and manufacturers is widening buyers’ access to capital for vehicle purchases. Annual registrations reached 11,607 units in 2025, which gives component suppliers the volumes needed to invest in battery and charger capacity, and that investment in turn supports faster deployment and further cost reduction.
Evaluation of Restraints in Europe Electric Bus Market
Below mentioned are some major restraints and their influence on market dynamics:
|
Market Restraint |
Primary Segment Affected |
Why It Matters (Evidence) |
|
High upfront vehicle price |
Public |
An electric city bus typically costs roughly double a diesel equivalent, which stretches municipal budgets and delays replacement decisions. |
|
Depot grid connection delays |
Plug Only |
Distribution network operators often need several years to approve and energise high-capacity depot connections, postponing fleet conversion even after vehicles are ordered. |
|
Reliance on grant-funded procurement |
United Kingdom |
Fleet orders depend on grant rounds such as the £45 million third Scottish zero-emission bus fund, and award delays shift deliveries between budget years. |
|
Cold-weather range loss |
Battery Electric Bus |
Cold weather can cut battery range by up to 30 percent, and Nordic and alpine operators size fleets conservatively or retain diesel vehicles. |
|
Fragmented charging interfaces |
Induction |
Operators in different cities specify different charging interfaces, and open standards such as CCS cover plug-in charging only, limiting interoperability for inductive systems. |
Europe Electric Bus Market Challenges
The Europe Electric Bus Market faces several obstacles that need to be addressed for sustained growth. BYD registrations jumped to 1,305 units in 2025, raising price competition from Asian manufacturers that squeezes margins at European builders and raises questions about local-content requirements. However, the smaller capacity of depots in smaller cities and the increased downtime for operators are due to the shortage of technicians qualified in high-voltage maintenance. Residual value estimates are harder to make because of uncertainty around battery life beyond the typical eight-year warranty, so lenders are hesitant to finance older cars.
Europe Electric Bus Market Trends
Emerging trends shaping the Europe Electric Bus Market are mentioned below:
- Shift from Diesel and Hybrid to Battery Electric Buses: Battery electric buses took 56 percent of new EU city bus sales in 2025, leaving hybrid drivetrains a lessening niche. Manufacturers are redirecting production towards battery platforms.
- Transition from Depot-Only to Mixed Pantograph Charging: Operators are adding pantograph chargers at terminals alongside overnight plug-in charging, and manufacturers have agreed interoperable interfaces with ABB, Heliox and Siemens. This favours charger vendors and lighter battery packs.
- Shift from Single-Brand Fleets to Multi-Supplier Procurement: MAN registrations rose 224 percent in 2025 as Asian entrants and European builders expanded capacity together, widening buyer choice. Procurement is moving towards multi-supplier frameworks.
- Fuel Cell Buses Emerging as a Niche Complement to Battery Fleets: Germany accounted for 60 percent of fuel cell bus registrations in 2025 as operators trialled them on longer regional routes. Hydrogen suppliers address a specialised rather than mass demand pool.
Investment Opportunities in the Europe Electric Bus Market
Key opportunities in the Europe Electric Bus Market are mentioned below:
- Depot Charging Infrastructure: Depots must be energised before buses enter service, so charger vendors and energy-service firms can supply high-power plug-in and pantograph systems through framework agreements with transit authorities.
- Battery Leasing and Second-Life Platforms: Financiers can back battery-as-a-service and residual value guarantee products that spread vehicle cost, while recyclers can set up second-life storage operations near large depots under partnerships with manufacturers.
- Local Component Assembly in Central Europe: Polish assembly sites supply a large share of European demand, so component makers can establish axle, body and battery pack lines near Poznań or Starachowice through joint ventures with builders.
- Fleet Software and Energy Management: Operators run mixed fleets from several manufacturers, creating room for charge-scheduling and telematics software, with entry through pilot contracts at large urban operators such as Naples’ ANM.
Leading Players in the Europe Electric Bus Industry
Notable trends influencing the Europe electric bus market are listed below:
1. Solaris Bus & Coach
| Company Name | Solaris Bus & Coach |
|---|---|
| Established Year | 1996 |
| Headquarters | Bolechowo-Osiedle, Poland |
| Official Website | Click Here |
Solaris Bus & Coach is a Polish manufacturer of urban buses, trolleybuses and electric drivetrains, and it is among the most established suppliers of battery electric city buses to European transit operators.
2. MAN Truck & Bus
| Company Name | MAN Truck & Bus |
|---|---|
| Established Year | 1758 |
| Headquarters | Munich, Germany |
| Official Website | Click Here |
MAN Truck & Bus produces trucks, city buses and coaches, and supplies battery electric city buses to transit operators across Europe from its German and Central European production network.
3. BYD
| Company Name | BYD |
|---|---|
| Established Year | 1995 |
| Headquarters | Shenzhen, China |
| Official Website | Click Here |
BYD manufactures battery electric buses, batteries and power electronics, and serves European operators through regional sales, assembly and service operations.
4. Irizar
| Company Name | Irizar |
|---|---|
| Established Year | 1889 |
| Headquarters | Ormaiztegi, Spain |
| Official Website | Click Here |
Irizar is a Spanish bus and coach builder whose e-mobility division produces integrated electric buses, charging systems and batteries for urban and intercity operators in Europe.
5. Volvo Buses
| Company Name | Volvo Buses |
|---|---|
| Established Year | 1927 |
| Headquarters | Gothenburg, Sweden |
| Official Website | Click Here |
Volvo Buses supplies electric city buses, double-deckers and charging solutions to operators across Europe, with electric bus production based at its facility in Poland.
Government Initiatives in the Europe Electric Bus Market
Governments shape Europe electric bus market growth through binding procurement and emission rules that guarantee demand for zero-emission buses. The Clean Vehicles Directive (EU) 2019/1161 requires half of the clean bus purchases made under national targets for 2026 to 2030 to be zero-emission. Regulation (EU) 2024/1610, applicable from July 2024, sets a 90 percent emission cut for new urban buses from 2030 and 100 percent from 2035. In addition, the National programmes convert these rules into fleet orders. Italy’s recovery plan commits EUR 1.65 billion to regional zero-emission bus fleets, covering at least 3,000 buses and 1,000 charging stations. In England, the ZEBRA scheme awarded £73.2 million in March 2026 for 484 buses.
Future Insight of the Europe Electric Bus Market
In the coming years, the Europe Electric Bus Market is predicted to gain momentum, driven by continued technology maturity, as higher-density battery chemistries and faster charging extend vehicle range and operating flexibility. Expanding electricity grid capacity will lower energy costs and widen the routes that electric buses can serve. Apart from this, stricter procurement rules will extend zero-emission buying into regions that have been slower adopters, and funding programmes will keep improving affordability. Zero-emission buses already account for 60 percent of new EU city bus sales, and five member states recorded 100 percent in 2025, showing the pace at which remaining markets can follow.
Market Segmentation Analysis
The report offers a comprehensive study of the market across its key segments. The chart below highlights the leading segment by market share in 2025 and the fastest-growing segment by CAGR over 2026–2032, followed by a detailed analysis of each segment.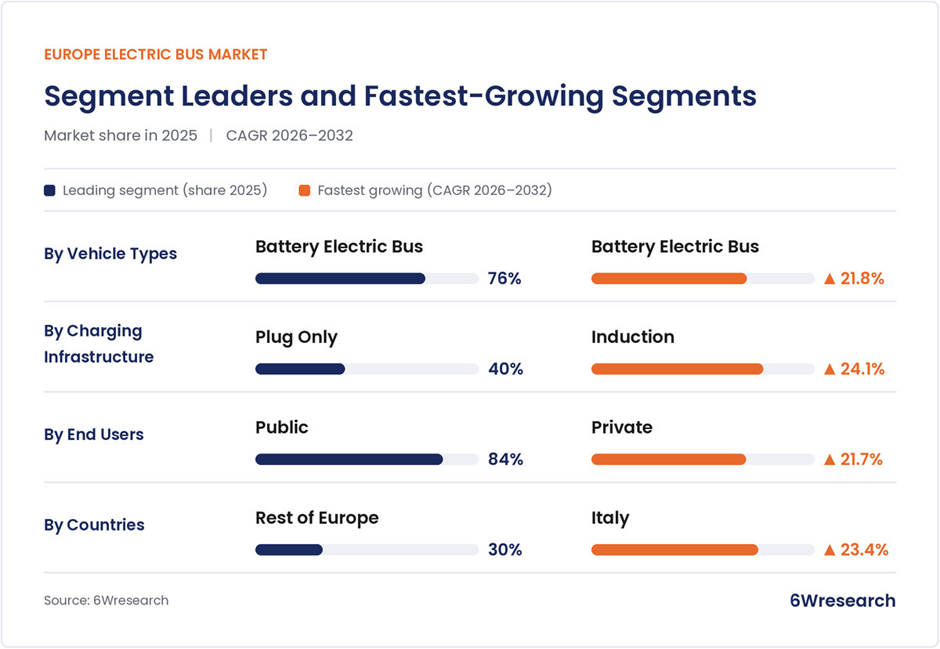
By Vehicle Types – Battery Electric Bus Leads and Records the Fastest Growth
According to Ravi Bhandari, Research Head, 6Wresearch, the Battery Electric Bus led the market with approximately 76% share in 2025, supported by rapid model launches from Solaris, MAN and Mercedes-Benz and its rising weight in new city bus registrations.
The segment is also projected to record the fastest growth at a CAGR of 21.8% during 2026–2032, driven by stricter urban bus emission targets, declining battery costs and expanding depot charging capacity.
By Charging Infrastructure – Plug Only Leads, Induction Expected to Grow Fastest
Plug Only accounted for 40% of the Europe Electric Bus Market Share in 2025, owing to the dominance of overnight depot charging in European fleets and wide adoption of the CCS connector standard.
In contrast, Induction is expected to grow faster CAGR of 24.1% during 2026–2032, due to pilot installations in city centres, demand for smaller batteries and the removal of overhead equipment in heritage districts.
By End Users – Public Leads, Private Expected to Grow Fastest
The Public segment held nearly 84% share of the market in 2025, backed by municipal ownership of most urban bus fleets and procurement targets that apply directly to transit authorities.
On the other hand, Private operators are projected to grow fastest at a CAGR of 21.7% during 2026–2032, driven by electrification of airport, contract and intercity services, wider leasing offers and lower running costs.
By Countries – Rest of Europe Leads, Italy Expected to Grow Fastest
Rest of Europe led with approximately 30% share of the market in 2025, supported by large procurement programmes in Spain, the Nordic countries and Central and Eastern Europe.
Meanwhile, Italy is expected to record the fastest growth at a CAGR of 23.4% during 2026–2032, fuelled by recovery plan fleet renewals in Rome and other metropolitan areas, ageing diesel fleets and a rising zero-emission share of city bus registrations.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- Europe Electric Bus Market Overview
- Europe Electric Bus Market Outlook
- Europe Electric Bus Market Forecast
- Historical Data of Europe Electric Bus Market Revenues & Volume for the Period 2022-2032
- Europe Electric Bus Market Size and Forecast of Revenues & Volume, Until 2032
- Historical Data of Europe Electric Bus Market Revenues & Volume, by Vehicle Types, for the Period 2022-2032
- Market Size & Forecast of Europe Electric Bus Market Revenues & Volume, by Vehicle Types, Until 2032
- Historical Data of Europe Electric Bus Market Revenues and Volume, By Charging Infrastructure, for the Period 2022-2032
- Market Size & Forecast of Europe Electric Bus Market Revenues and Volume, By Charging Infrastructure, Until 2032
- Historical Data of Europe Electric Bus Market Revenues and Volume, By End Users, for the Period 2022-2032
- Market Size & Forecast of Europe Electric Bus Market Revenues and Volume, By End Users, Until 2032
- Historical Data of Germany Electric Bus Market Revenues and Volume, for the Period 2022-2032
- Market Size & Forecast of Germany Electric Bus Market Revenues and Volume, Until 2032
- Historical Data of France Electric Bus Market Revenues and Volume, for the Period 2022-2032
- Market Size & Forecast of France Electric Bus Market Revenues and Volume, Until 2032
- Historical Data of Italy Electric Bus Market Revenues and Volume, for the Period 2022-2032
- Market Size & Forecast of Italy Electric Bus Market Revenues and Volume, Until 2032
- Historical Data of United Kingdom Electric Bus Market Revenues and Volume, for the Period 2022-2032
- Market Size & Forecast of United Kingdom Electric Bus Market Revenues and Volume, Until 2032
- Historical Data of Netherland Electric Bus Market Revenues and Volume, for the Period 2022-2032
- Market Size & Forecast of Netherland Electric Bus Market Revenues and Volume, Until 2032
- Market Drivers and Restraints
- Europe Electric Bus Market Price Trends
- Europe Electric Bus Market Trends and Industry Life Cycle
- Porter’s Five Force Analysis
- Market Opportunity Assessment
- Europe Electric Bus Market Share, By Regions
- Europe Electric Bus Market Share, By Players
- Europe Electric Bus Market Overview on Competitive Benchmarking
- Company Profiles
- Key Strategic Recommendations
Market Covered
The report offers a comprehensive study of the subsequent market segments:
By Vehicle Types
- Battery Electric Bus (BEB)
- Plug-In Electric Bus (PHEB)
- Hybrid Electric Bus (HEB)
By Charging Infrastructure
- Ground Contact
- Roof Pantograph
- Gantry Pantograph
- Plug Only
- Induction
By End User
- Public
- Private
By Countries
- Germany
- France
- Italy
- United Kingdom
- Netherland
- Rest of Europe































