Global Refractory Material Market (2026-2032) | Share, Strategic Insights, Demand, Forecast, Segmentation, Industry, Consumer Insights, Companies, Growth, Outlook, Competitive, Opportunities, Size, Restraints, Value, Investment Trends, Supply, Revenue, Drivers, Pricing Analysis, Challenges, Segments, Strategy, Competition, Trends, Analysis
Market Forecast by Regions and Countries (North America, Europe, LATAM, Middle East, Asia and Africa), By Form (Shaped, Unshaped), By Chemical Composition (Alumina, Silica, Magnesia, Fireclay, Others), By Chemistry (Acidic, Basic, Neutral), By End-use (Metals & Metallurgy, Cement, Glass & Ceramics, Power Generation, Others) And Competitive Landscape
| Product Code: ETC13224816 | Publication Date: Apr 2025 | Updated Date: Sep 2026 | Product Type: Market Research Report | |
| Publisher: 6Wresearch | Author: Sachin Kumar Rai | No. of Pages: 190 | No. of Figures: 80 | No. of Tables: 40 |
Global Refractory Material Market Highlights
| Market Size (2025) | USD 29.5 Billion |
| Forecast Size (2032) | USD 47.2 Billion |
| CAGR | 11.00% |
| Base Year | 2025 |
| Forecast Period | 2026-2032 |
| Largest Region | Asia Pacific |
| Fastest Growing Region | Europe |
| Largest Segment | Iron & Steel |
| Fastest Growing Segment | Non-Ferrous Metals |
| Leading Companies | RHI Magnesita, Vesuvius, Krosaki Harima Corporation, Imerys, Shinagawa Refractories Co., Ltd. |
Global Refractory Material Market Size & Growth Rate (2026-2032)
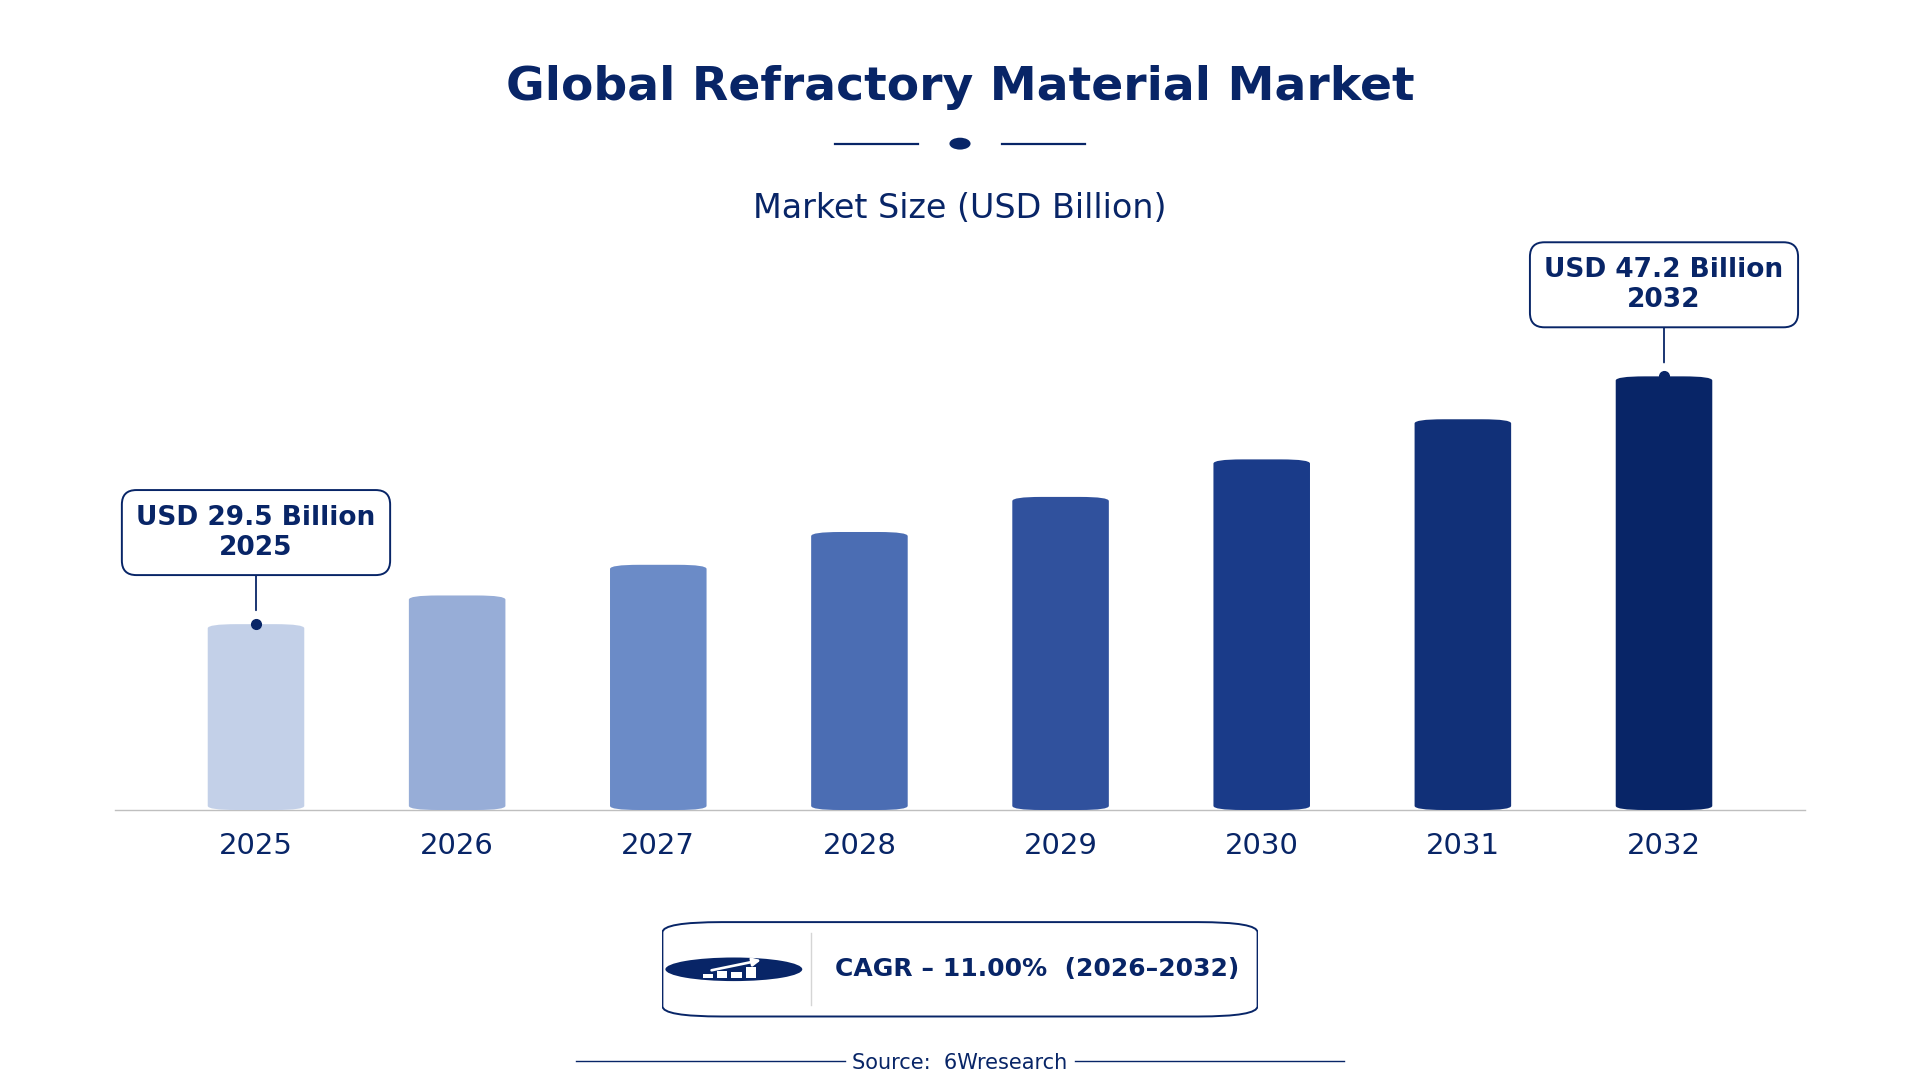
The Global Refractory Material Market was estimated at USD 29.5 Billion in 2025 and is projected to reach USD 47.2 Billion by 2032, growing at a CAGR of 11.00% from 2026 to 2032.
Global Refractory Material Market Synopsis
The global refractory material market is undergoing a significant transformation, driven by the evolving demands of high-temperature industries. The shift towards more sustainable and energy-efficient manufacturing processes is reshaping the landscape, with refractory materials playing a pivotal role in these advancements. This evolution is not merely a trend but a fundamental change in how industries approach thermal management and material durability.
The market's growth is closely tied to the expansion of sectors such as steel, cement, and glass manufacturing. These industries are increasingly investing in infrastructure and modernization projects, leading to a heightened need for advanced refractory solutions. This demand is not just about volume but also about the performance and longevity of materials used in extreme conditions, highlighting the critical role of refractories in industrial operations.
Global Refractory Material Market Year-wise Growth Rate and Key Drivers
This graph illustrates the annual growth rates of the Global Refractory Material Market from 2022 to 2032, highlighting a steady upward trajectory and projected expansion over the forecast period.
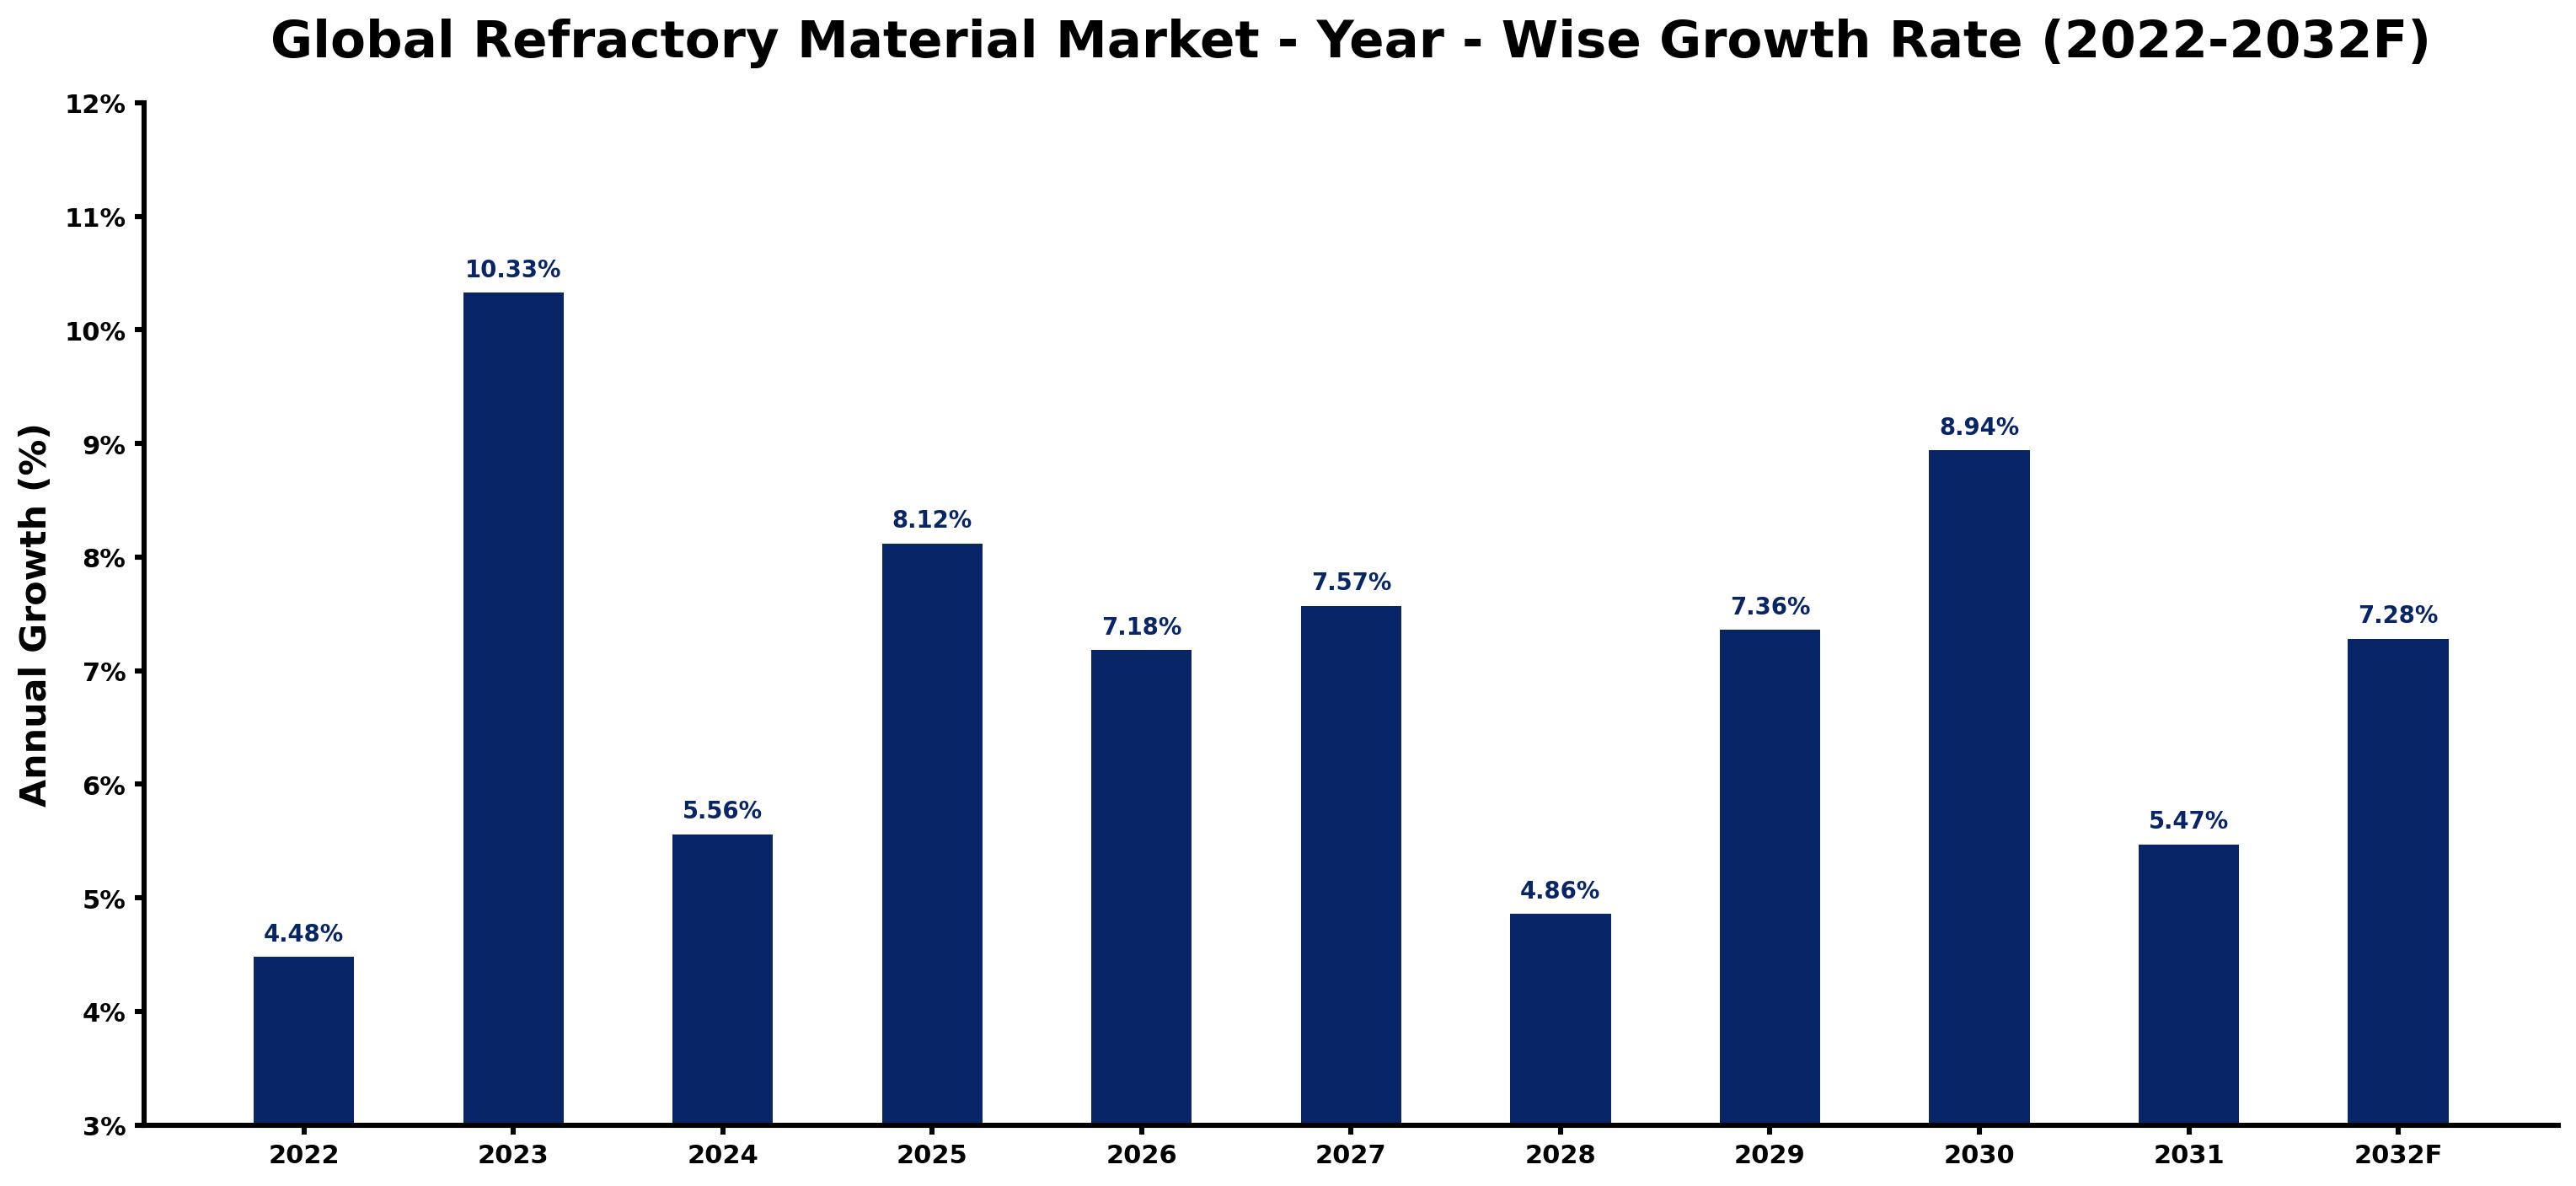
The table below presents the year‑wise growth rates along with the key drivers influencing the market
| Year | Growth Rate (%) | Major Drivers |
| 2022 | 4.48 | Expanding metallurgical processing capabilities enables higher consumption of refractory materials. |
| 2023 | 10.33 | Steel manufacturers in Asia are increasing their use of refractory materials. |
| 2024 | 5.56 | Regulators are promoting stricter thermal efficiency standards for industries using refractory materials. |
| 2025 | 8.12 | Increased smelting capacity among primary aluminum producers enhances the demand for refractories. |
| 2026 | 7.18 | Fluctuations in commodity price cycles create heightened interest in refractory material sourcing. |
| 2027 | 7.57 | A shift toward skilled labor in metal recycling changes the dynamics of refractory material usage. |
| 2028 | 4.86 | Rising demand for durable materials influences end-user preferences for refractory products. |
| 2029 | 7.36 | In Europe, decreasing raw material costs are improving the accessibility of refractory solutions. |
| 2030 | 8.94 | While acquisitions among refractory manufacturers are increasing, capacity building remains critical. |
| 2031 | 5.47 | Sustainable practices among steel manufacturers are driving the innovation of eco-friendly refractory materials. |
| 2032 | 7.28 | Advanced ceramic composites are transforming the efficiency of refractory materials in high-temperature applications. |
Note - Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary research methodology, combining internal industry data, secondary research, and primary validation, updated periodically to reflect current market conditions. As markets evolve rapidly, figures for certain industries may vary slightly and are intended as informed estimates rather than absolute figures. For the most current market sizing, we recommend validating figures with a 6Wresearch analyst.
Global Refractory Material Market Key Takeaways
Below are some of the specific key takeaways from the market, including:
- The Asia Pacific region accounted for approximately 75% of the global refractory material market share in 2025, underscoring its dominance in the industry.
- The iron and steel sector represented about 67% of the market revenue in 2025, highlighting its critical role in driving demand for refractories.
- The non-ferrous metals segment is projected to experience a CAGR of 12.5% from 2026 to 2032, indicating its rapid growth compared to other sectors.
- RHI Magnesita, a leading company in the market, reported a revenue of €2.8 billion in 2024, reflecting its significant presence in the industry.
Evaluation of Restraints in Global Refractory Material Market
The global refractory material market faces several challenges that could impede its growth trajectory. Fluctuations in raw material prices, such as alumina, silica, and magnesia, can significantly impact production costs and profitability. For instance, a 10% increase in alumina prices can lead to a proportional rise in refractory production costs, affecting the overall market dynamics. Additionally, stringent environmental regulations, particularly in regions like the European Union, require manufacturers to invest in cleaner technologies and processes, potentially increasing operational expenses. Moreover, the emergence of alternative materials that offer similar performance at lower costs poses a competitive threat to traditional refractory products, compelling companies to innovate continually to maintain market share.
Global Refractory Material Market Trends
The global refractory material market is witnessing several notable trends that are shaping its future direction. One significant trend is the increasing adoption of advanced refractory materials designed for high-performance applications. For example, the development of ultra-low cement castables has enhanced the durability and thermal efficiency of refractories used in steelmaking furnaces. Another trend is the integration of digital technologies in refractory manufacturing processes. Companies like Vesuvius are implementing Industry 4.0 solutions to monitor and optimize production, leading to improved product quality and reduced operational costs. Additionally, there is a growing emphasis on sustainability, with manufacturers focusing on producing eco-friendly refractories that comply with stringent environmental standards, thereby meeting the dual objectives of performance and environmental responsibility.
Global Refractory Material Market Opportunities
The global refractory material market presents several promising opportunities for growth and innovation. The expansion of the electric vehicle (EV) ecosystem is one such opportunity, as the demand for high-performance refractories in battery manufacturing processes is expected to rise. For instance, the development of solid-state batteries requires advanced refractory materials capable of withstanding high temperatures during production. Another opportunity lies in the renewable energy sector, where the construction of concentrated solar power (CSP) plants necessitates the use of specialized refractories to handle extreme thermal conditions. Additionally, the ongoing infrastructure development in emerging economies, particularly in Asia Pacific, is driving the need for refractories in cement and glass manufacturing, presenting a substantial market opportunity for suppliers.
Global Refractory Material Market by Form
In the global refractory material market, the shaped refractories segment leads with a market share of approximately 57.4% in 2025. This dominance is attributed to their widespread application in industries such as steelmaking and cement production, where precise and durable linings are essential. The unshaped refractories segment is the fastest-growing, projected to experience a CAGR of 8.5% from 2026 to 2032. This growth is driven by the increasing demand for monolithic refractories that offer flexibility and ease of installation, particularly in complex furnace designs and maintenance operations.
Global Refractory Material Market by Chemical Composition
In the global refractory material market, alumina-based refractories lead with a market share of approximately 32.4% in 2025. Their dominance is due to their high thermal stability and resistance to chemical corrosion, making them ideal for applications in steel and cement industries. The fastest-growing segment is the magnesia-based refractories, projected to experience a CAGR of 9.0% from 2026 to 2032. This growth is driven by the increasing demand for refractories in non-ferrous metal production, where magnesia refractories offer superior performance in high-temperature environments.
Global Refractory Material Market by Chemistry
In the global refractory material market, the acidic & neutral refractories segment leads with a market share of approximately 60% in 2025. Their widespread use is due to their ability to resist acid slag erosion, making them suitable for applications in industries such as cement and glass manufacturing. The fastest-growing segment is the basic refractories, projected to experience a CAGR of 10.5% from 2026 to 2032. This growth is driven by the increasing demand for refractories in steelmaking processes, where basic refractories provide enhanced resistance to basic slag and high-temperature stability.
Global Refractory Material Market by End-use
In the global refractory material market, the iron & steel industry leads with a market share of approximately 67% in 2025. This dominance is due to the extensive use of refractories in blast furnaces, converters, and ladles, where they protect equipment from extreme temperatures and chemical wear. The fastest-growing segment is the non-ferrous metals industry, projected to experience a CAGR of 12.5% from 2026 to 2032. This growth is driven by the increasing demand for refractories in aluminum and copper production, where high-performance refractories are essential for maintaining process efficiency and product quality.
Global Refractory Material Market by Region
In the global refractory material market, the Asia Pacific region leads with a market share of approximately 75% in 2025. This dominance is attributed to the region's robust industrial base, particularly in countries like China and India, which are major consumers of refractories in steel and cement production. The fastest-growing region is Europe, projected to experience a CAGR of 12.0% from 2026 to 2032. This growth is driven by the region's focus on sustainable manufacturing practices and the adoption of advanced refractory materials in industries such as steelmaking and cement production.
Government Initiatives in the Global Refractory Material Market
The global refractory material market operates within a complex regulatory framework that influences its growth and development. Various government initiatives and regulations play a crucial role in shaping the market dynamics, particularly concerning environmental standards and industrial practices. These initiatives aim to promote sustainability, enhance safety, and encourage technological advancements within the industry. Below are some notable government actions affecting the refractory materials sector:
- The U.S. Environmental Protection Agency (EPA) finalized amendments to the National Emission Standards for Hazardous Air Pollutants (NESHAP) for Refractory Products Manufacturing in October 2025. These amendments require facilities to implement maximum achievable control technology (MACT) to reduce emissions of hazardous air pollutants, thereby promoting cleaner production processes in the refractory industry.
- In January 2021, the EPA proposed amendments to the NESHAP for Refractory Products Manufacturing, focusing on improving work practice standards during scheduled maintenance of control devices for emissions of organic air toxics from continuous kilns. This initiative aims to enhance environmental compliance and operational efficiency within the industry.
- The European Union has implemented stringent environmental regulations that impact the refractory materials market, particularly concerning the reduction of carbon emissions. These regulations encourage the development and adoption of eco-friendly refractories, aligning with the EU's broader sustainability goals.
- China's government has introduced policies to promote the modernization of the steel industry, including the adoption of electric arc furnaces (EAF). This shift influences the demand for specific types of refractories, such as those suitable for EAF applications, thereby affecting market dynamics.
Future Insights of the Global Refractory Material Market
The Global Refractory Material Market is expected to undergo transformative changes due to advancements in manufacturing technologies. Companies are increasingly investing in automation and digital manufacturing processes to enhance efficiency. For instance, RHI Magnesita is leading efforts toward Industry 4.0 implementation to optimize operational workflows. Additionally, the expected rise in electric arc furnace usage in the steel industry will catalyze the development of specialized refractories capable of handling fluctuating temperatures, signaling a shift in material performance and design requirements through 2032.
Global Refractory Material Market Latest Developments
Recent activities within the industry demonstrate significant progress towards technological advancements and market positioning.
- In late 2023, Vesuvius initiated a project to integrate artificial intelligence into their manufacturing processes, expected to improve product precision and reduce wastage over the coming years.
- Ongoing in 2023, Krosaki Harima Corporation is expanding its production capacity in Southeast Asia, aimed at capturing the growing market in non-ferrous metals, enhancing its regional presence.
- Imerys is set to unveil a new eco-friendly refractory product line in early 2024, aligning with global sustainability efforts and addressing increasing regulatory demands.
- Shinagawa Refractories Co., Ltd. is actively pursuing strategic partnerships within the renewable energy sector, focused on meeting the critical refractory needs for solar power infrastructures by 2025.
Global Refractory Material Market Key Players and Industry Positioning
The competitive structure of the Global Refractory Material Market is moderately consolidated, with leading companies holding substantial market shares while facing competition from specialized firms focusing on niche applications. Each company's distinct advantages foster a diverse marketplace.
| Leading Company | Core Strength | Strategic Focus |
|---|---|---|
| RHI Magnesita | Leader in high-performance refractories, with a strong focus on the steel industry. | Investing in digital technologies to enhance manufacturing efficiency. |
| Vesuvius | Expertise in foundry and steel applications, supported by a global manufacturing footprint. | Strengthening product lines through innovation and environmental solutions. |
| Krosaki Harima Corporation | Robust position in the Asian market with a focus on non-ferrous sectors. | Expanding production capacity to meet regional demands. |
| Imerys | Diverse range of advanced materials, particularly in the eco-friendly segment. | Launching sustainable products to comply with international regulations. |
| Shinagawa Refractories Co., Ltd. | Strong reputation in traditional refractories complemented by modern offerings. | Fostering partnerships within renewable energy sectors. |
As the refractory landscape evolves, companies that focus on technology adoption and sustainable practices are likely to consolidate their market positions while meeting the industry's high-performance demands.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year: 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- Global Refractory Material Market Outlook
- Market Size of Global Refractory Material Market, 2025
- Forecast of Global Refractory Material Market, 2032
- Historical Data and Forecast of Global Refractory Material Revenues & Volume for the Period 2022-2032
- Global Refractory Material Market Trend Evolution
- Global Refractory Material Market Drivers and Challenges
- Global Refractory Material Price Trends
- Global Refractory Material Porter's Five Forces
- Global Refractory Material Industry Life Cycle
- Historical Data and Forecast of Global Refractory Material Market Revenues & Volume
- Historical Data and Forecast of Global Refractory Material Market Revenues & Volume By Form for the Period 2022-2032
- Historical Data and Forecast of Global Refractory Material Market Revenues & Volume By Shaped for the Period 2022-2032
- Historical Data and Forecast of Global Refractory Material Market Revenues & Volume By Unshaped for the Period 2022-2032
- Historical Data and Forecast of Global Refractory Material Market Revenues & Volume By Chemical Composition for the Period 2022-2032
- Historical Data and Forecast of Global Refractory Material Market Revenues & Volume By Alumina for the Period 2022-2032
- Historical Data and Forecast of Global Refractory Material Market Revenues & Volume By Silica for the Period 2022-2032
- Historical Data and Forecast of Global Refractory Material Market Revenues & Volume By Magnesia for the Period 2022-2032
- Historical Data and Forecast of Global Refractory Material Market Revenues & Volume By Fireclay for the Period 2022-2032
- Historical Data and Forecast of Global Refractory Material Market Revenues & Volume By Others for the Period 2022-2032
- Historical Data and Forecast of Global Refractory Material Market Revenues & Volume By Chemistry for the Period 2022-2032
- Historical Data and Forecast of Global Refractory Material Market Revenues & Volume By Acidic for the Period 2022-2032
- Historical Data and Forecast of Global Refractory Material Market Revenues & Volume By Basic for the Period 2022-2032
- Historical Data and Forecast of Global Refractory Material Market Revenues & Volume By Neutral for the Period 2022-2032
- Historical Data and Forecast of Global Refractory Material Market Revenues & Volume By End-use for the Period 2022-2032
- Historical Data and Forecast of Global Refractory Material Market Revenues & Volume By Metals & Metallurgy for the Period 2022-2032
- Historical Data and Forecast of Global Refractory Material Market Revenues & Volume By Cement for the Period 2022-2032
- Historical Data and Forecast of Global Refractory Material Market Revenues & Volume By Glass & Ceramics for the Period 2022-2032
- Historical Data and Forecast of Global Refractory Material Market Revenues & Volume By Power Generation for the Period 2022-2032
- Historical Data and Forecast of Global Refractory Material Market Revenues & Volume By Others for the Period 2022-2032
- Historical Data and Forecast of North America Refractory Material Market Revenues & Volume By Form for the Period 2022-2032
- Historical Data and Forecast of North America Refractory Material Market Revenues & Volume By Shaped for the Period 2022-2032
- Historical Data and Forecast of North America Refractory Material Market Revenues & Volume By Unshaped for the Period 2022-2032
- Historical Data and Forecast of North America Refractory Material Market Revenues & Volume By Chemical Composition for the Period 2022-2032
- Historical Data and Forecast of North America Refractory Material Market Revenues & Volume By Alumina for the Period 2022-2032
- Historical Data and Forecast of North America Refractory Material Market Revenues & Volume By Silica for the Period 2022-2032
- Historical Data and Forecast of North America Refractory Material Market Revenues & Volume By Magnesia for the Period 2022-2032
- Historical Data and Forecast of North America Refractory Material Market Revenues & Volume By Fireclay for the Period 2022-2032
- Historical Data and Forecast of North America Refractory Material Market Revenues & Volume By Others for the Period 2022-2032
- Historical Data and Forecast of North America Refractory Material Market Revenues & Volume By Chemistry for the Period 2022-2032
- Historical Data and Forecast of North America Refractory Material Market Revenues & Volume By Acidic for the Period 2022-2032
- Historical Data and Forecast of North America Refractory Material Market Revenues & Volume By Basic for the Period 2022-2032
- Historical Data and Forecast of North America Refractory Material Market Revenues & Volume By Neutral for the Period 2022-2032
- Historical Data and Forecast of North America Refractory Material Market Revenues & Volume By End-use for the Period 2022-2032
- Historical Data and Forecast of North America Refractory Material Market Revenues & Volume By Metals & Metallurgy for the Period 2022-2032
- Historical Data and Forecast of North America Refractory Material Market Revenues & Volume By Cement for the Period 2022-2032
- Historical Data and Forecast of North America Refractory Material Market Revenues & Volume By Glass & Ceramics for the Period 2022-2032
- Historical Data and Forecast of North America Refractory Material Market Revenues & Volume By Power Generation for the Period 2022-2032
- Historical Data and Forecast of North America Refractory Material Market Revenues & Volume By Others for the Period 2022-2032
- Historical Data and Forecast of United States of America Refractory Material Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Canada Refractory Material Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Rest of North America Refractory Material Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) Refractory Material Market Revenues & Volume By Form for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) Refractory Material Market Revenues & Volume By Shaped for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) Refractory Material Market Revenues & Volume By Unshaped for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) Refractory Material Market Revenues & Volume By Chemical Composition for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) Refractory Material Market Revenues & Volume By Alumina for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) Refractory Material Market Revenues & Volume By Silica for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) Refractory Material Market Revenues & Volume By Magnesia for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) Refractory Material Market Revenues & Volume By Fireclay for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) Refractory Material Market Revenues & Volume By Others for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) Refractory Material Market Revenues & Volume By Chemistry for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) Refractory Material Market Revenues & Volume By Acidic for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) Refractory Material Market Revenues & Volume By Basic for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) Refractory Material Market Revenues & Volume By Neutral for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) Refractory Material Market Revenues & Volume By End-use for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) Refractory Material Market Revenues & Volume By Metals & Metallurgy for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) Refractory Material Market Revenues & Volume By Cement for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) Refractory Material Market Revenues & Volume By Glass & Ceramics for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) Refractory Material Market Revenues & Volume By Power Generation for the Period 2022-2032
- Historical Data and Forecast of Latin America (LATAM) Refractory Material Market Revenues & Volume By Others for the Period 2022-2032
- Historical Data and Forecast of Brazil Refractory Material Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Mexico Refractory Material Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Argentina Refractory Material Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Rest of LATAM Refractory Material Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Asia Refractory Material Market Revenues & Volume By Form for the Period 2022-2032
- Historical Data and Forecast of Asia Refractory Material Market Revenues & Volume By Shaped for the Period 2022-2032
- Historical Data and Forecast of Asia Refractory Material Market Revenues & Volume By Unshaped for the Period 2022-2032
- Historical Data and Forecast of Asia Refractory Material Market Revenues & Volume By Chemical Composition for the Period 2022-2032
- Historical Data and Forecast of Asia Refractory Material Market Revenues & Volume By Alumina for the Period 2022-2032
- Historical Data and Forecast of Asia Refractory Material Market Revenues & Volume By Silica for the Period 2022-2032
- Historical Data and Forecast of Asia Refractory Material Market Revenues & Volume By Magnesia for the Period 2022-2032
- Historical Data and Forecast of Asia Refractory Material Market Revenues & Volume By Fireclay for the Period 2022-2032
- Historical Data and Forecast of Asia Refractory Material Market Revenues & Volume By Others for the Period 2022-2032
- Historical Data and Forecast of Asia Refractory Material Market Revenues & Volume By Chemistry for the Period 2022-2032
- Historical Data and Forecast of Asia Refractory Material Market Revenues & Volume By Acidic for the Period 2022-2032
- Historical Data and Forecast of Asia Refractory Material Market Revenues & Volume By Basic for the Period 2022-2032
- Historical Data and Forecast of Asia Refractory Material Market Revenues & Volume By Neutral for the Period 2022-2032
- Historical Data and Forecast of Asia Refractory Material Market Revenues & Volume By End-use for the Period 2022-2032
- Historical Data and Forecast of Asia Refractory Material Market Revenues & Volume By Metals & Metallurgy for the Period 2022-2032
- Historical Data and Forecast of Asia Refractory Material Market Revenues & Volume By Cement for the Period 2022-2032
- Historical Data and Forecast of Asia Refractory Material Market Revenues & Volume By Glass & Ceramics for the Period 2022-2032
- Historical Data and Forecast of Asia Refractory Material Market Revenues & Volume By Power Generation for the Period 2022-2032
- Historical Data and Forecast of Asia Refractory Material Market Revenues & Volume By Others for the Period 2022-2032
- Historical Data and Forecast of China Refractory Material Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of India Refractory Material Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Japan Refractory Material Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Rest of Asia Refractory Material Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Africa Refractory Material Market Revenues & Volume By Form for the Period 2022-2032
- Historical Data and Forecast of Africa Refractory Material Market Revenues & Volume By Shaped for the Period 2022-2032
- Historical Data and Forecast of Africa Refractory Material Market Revenues & Volume By Unshaped for the Period 2022-2032
- Historical Data and Forecast of Africa Refractory Material Market Revenues & Volume By Chemical Composition for the Period 2022-2032
- Historical Data and Forecast of Africa Refractory Material Market Revenues & Volume By Alumina for the Period 2022-2032
- Historical Data and Forecast of Africa Refractory Material Market Revenues & Volume By Silica for the Period 2022-2032
- Historical Data and Forecast of Africa Refractory Material Market Revenues & Volume By Magnesia for the Period 2022-2032
- Historical Data and Forecast of Africa Refractory Material Market Revenues & Volume By Fireclay for the Period 2022-2032
- Historical Data and Forecast of Africa Refractory Material Market Revenues & Volume By Others for the Period 2022-2032
- Historical Data and Forecast of Africa Refractory Material Market Revenues & Volume By Chemistry for the Period 2022-2032
- Historical Data and Forecast of Africa Refractory Material Market Revenues & Volume By Acidic for the Period 2022-2032
- Historical Data and Forecast of Africa Refractory Material Market Revenues & Volume By Basic for the Period 2022-2032
- Historical Data and Forecast of Africa Refractory Material Market Revenues & Volume By Neutral for the Period 2022-2032
- Historical Data and Forecast of Africa Refractory Material Market Revenues & Volume By End-use for the Period 2022-2032
- Historical Data and Forecast of Africa Refractory Material Market Revenues & Volume By Metals & Metallurgy for the Period 2022-2032
- Historical Data and Forecast of Africa Refractory Material Market Revenues & Volume By Cement for the Period 2022-2032
- Historical Data and Forecast of Africa Refractory Material Market Revenues & Volume By Glass & Ceramics for the Period 2022-2032
- Historical Data and Forecast of Africa Refractory Material Market Revenues & Volume By Power Generation for the Period 2022-2032
- Historical Data and Forecast of Africa Refractory Material Market Revenues & Volume By Others for the Period 2022-2032
- Historical Data and Forecast of South Africa Refractory Material Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Nigeria Refractory Material Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Egypt Refractory Material Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Rest of Africa Refractory Material Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Europe Refractory Material Market Revenues & Volume By Form for the Period 2022-2032
- Historical Data and Forecast of Europe Refractory Material Market Revenues & Volume By Shaped for the Period 2022-2032
- Historical Data and Forecast of Europe Refractory Material Market Revenues & Volume By Unshaped for the Period 2022-2032
- Historical Data and Forecast of Europe Refractory Material Market Revenues & Volume By Chemical Composition for the Period 2022-2032
- Historical Data and Forecast of Europe Refractory Material Market Revenues & Volume By Alumina for the Period 2022-2032
- Historical Data and Forecast of Europe Refractory Material Market Revenues & Volume By Silica for the Period 2022-2032
- Historical Data and Forecast of Europe Refractory Material Market Revenues & Volume By Magnesia for the Period 2022-2032
- Historical Data and Forecast of Europe Refractory Material Market Revenues & Volume By Fireclay for the Period 2022-2032
- Historical Data and Forecast of Europe Refractory Material Market Revenues & Volume By Others for the Period 2022-2032
- Historical Data and Forecast of Europe Refractory Material Market Revenues & Volume By Chemistry for the Period 2022-2032
- Historical Data and Forecast of Europe Refractory Material Market Revenues & Volume By Acidic for the Period 2022-2032
- Historical Data and Forecast of Europe Refractory Material Market Revenues & Volume By Basic for the Period 2022-2032
- Historical Data and Forecast of Europe Refractory Material Market Revenues & Volume By Neutral for the Period 2022-2032
- Historical Data and Forecast of Europe Refractory Material Market Revenues & Volume By End-use for the Period 2022-2032
- Historical Data and Forecast of Europe Refractory Material Market Revenues & Volume By Metals & Metallurgy for the Period 2022-2032
- Historical Data and Forecast of Europe Refractory Material Market Revenues & Volume By Cement for the Period 2022-2032
- Historical Data and Forecast of Europe Refractory Material Market Revenues & Volume By Glass & Ceramics for the Period 2022-2032
- Historical Data and Forecast of Europe Refractory Material Market Revenues & Volume By Power Generation for the Period 2022-2032
- Historical Data and Forecast of Europe Refractory Material Market Revenues & Volume By Others for the Period 2022-2032
- Historical Data and Forecast of United Kingdom Refractory Material Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of France Refractory Material Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Germany Refractory Material Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Rest of Europe Refractory Material Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Middle East Refractory Material Market Revenues & Volume By Form for the Period 2022-2032
- Historical Data and Forecast of Middle East Refractory Material Market Revenues & Volume By Shaped for the Period 2022-2032
- Historical Data and Forecast of Middle East Refractory Material Market Revenues & Volume By Unshaped for the Period 2022-2032
- Historical Data and Forecast of Middle East Refractory Material Market Revenues & Volume By Chemical Composition for the Period 2022-2032
- Historical Data and Forecast of Middle East Refractory Material Market Revenues & Volume By Alumina for the Period 2022-2032
- Historical Data and Forecast of Middle East Refractory Material Market Revenues & Volume By Silica for the Period 2022-2032
- Historical Data and Forecast of Middle East Refractory Material Market Revenues & Volume By Magnesia for the Period 2022-2032
- Historical Data and Forecast of Middle East Refractory Material Market Revenues & Volume By Fireclay for the Period 2022-2032
- Historical Data and Forecast of Middle East Refractory Material Market Revenues & Volume By Others for the Period 2022-2032
- Historical Data and Forecast of Middle East Refractory Material Market Revenues & Volume By Chemistry for the Period 2022-2032
- Historical Data and Forecast of Middle East Refractory Material Market Revenues & Volume By Acidic for the Period 2022-2032
- Historical Data and Forecast of Middle East Refractory Material Market Revenues & Volume By Basic for the Period 2022-2032
- Historical Data and Forecast of Middle East Refractory Material Market Revenues & Volume By Neutral for the Period 2022-2032
- Historical Data and Forecast of Middle East Refractory Material Market Revenues & Volume By End-use for the Period 2022-2032
- Historical Data and Forecast of Middle East Refractory Material Market Revenues & Volume By Metals & Metallurgy for the Period 2022-2032
- Historical Data and Forecast of Middle East Refractory Material Market Revenues & Volume By Cement for the Period 2022-2032
- Historical Data and Forecast of Middle East Refractory Material Market Revenues & Volume By Glass & Ceramics for the Period 2022-2032
- Historical Data and Forecast of Middle East Refractory Material Market Revenues & Volume By Power Generation for the Period 2022-2032
- Historical Data and Forecast of Middle East Refractory Material Market Revenues & Volume By Others for the Period 2022-2032
- Historical Data and Forecast of Saudi Arabia Refractory Material Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of UAE Refractory Material Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Turkey Refractory Material Market Revenues & Volume for the Period 2022-2032
- Historical Data and Forecast of Rest of Middle East Refractory Material Market Revenues & Volume for the Period 2022-2032
- Global Refractory Material Market - Key Performance Indicators
- Global Refractory Material Market - Import Export Trade Statistics
- Global Refractory Material Market - Opportunity Assessment By Countries
- Global Refractory Material Market - Opportunity Assessment By Form
- Global Refractory Material Market - Opportunity Assessment By Chemical Composition
- Global Refractory Material Market - Opportunity Assessment By Chemistry
- Global Refractory Material Market - Opportunity Assessment By End-use
- Global Refractory Material Market - Top Companies Market Share
- Global Refractory Material Market - Top Companies Profiles
- Global Refractory Material Market - Comparison of Players in Technical and Operating Parameters
- Global Refractory Material Market - Strategic Recommendations
Markets Covered
The Global Refractory Material Market report provides a detailed analysis of the following market segments:
By Regions and Countries:
- North America
- Europe
- LATAM
- Middle East
- Asia
- Africa
By Form:
- Shaped
- Unshaped
By Chemical Composition:
- Alumina
- Silica
- Magnesia
- Fireclay
- Others
By Chemistry:
- Acidic
- Basic
- Neutral
By End-use:
- Metals & Metallurgy
- Cement
- Glass & Ceramics
- Power Generation
- Others
Global Refractory Material Market - Frequently Asked Questions
The Global Refractory Material Market was estimated at USD 29.5 Billion in 2025 and is projected to reach USD 47.2 Billion by 2032, growing at a CAGR of 11.00% from 2026 to 2032.
Significant expansion in industries such as steel, cement, and glass manufacturing is propelling the market, as they increasingly require durable and high-performance refractory solutions.
Fluctuations in raw material prices and stringent environmental regulations pose challenges, impacting production costs and operational efficiency within the industry.
The iron & steel industry dominates with approximately 67% market share, while the non-ferrous metals segment is the fastest-growing, expected to experience a CAGR of 12.5% through 2032.
The market is anticipated to see structural changes, with greater focus on sustainable manufacturing practices and advancements in refractory technology such as automation and digital processes for efficacy.
6Wresearch actively monitors the Global Refractory Material Market and publishes its comprehensive annual report, highlighting emerging trends, growth drivers, revenue analysis, and forecast outlook. Our insights help businesses to make data-backed strategic decisions with ongoing market dynamics. Our analysts track relevent industries related to the Global Refractory Material Market, allowing our clients with actionable intelligence and reliable forecasts tailored to emerging regional needs.
Yes, we provide customisation as per your requirements. To learn more, feel free to contact us on sales@6wresearch.com
Global Refractory Material Market |
1 Executive Summary |
2 Introduction |
2.1 Key Highlights of the Report |
2.2 Report Description |
2.3 Market Scope & Segmentation |
2.4 Research Methodology |
2.5 Assumptions |
3 Global Refractory Material Market Overview |
3.1 Global Regional Macro Economic Indicators |
3.2 Global Refractory Material Market Revenues & Volume, 2022 & 2032F |
3.3 Global Refractory Material Market - Industry Life Cycle |
3.4 Global Refractory Material Market - Porter's Five Forces |
3.5 Global Refractory Material Market Revenues & Volume Share, By Regions, 2022 & 2032F |
3.6 Global Refractory Material Market Revenues & Volume Share, By Form, 2022 & 2032F |
3.7 Global Refractory Material Market Revenues & Volume Share, By Chemical Composition, 2022 & 2032F |
3.8 Global Refractory Material Market Revenues & Volume Share, By Chemistry, 2022 & 2032F |
3.9 Global Refractory Material Market Revenues & Volume Share, By End-use, 2022 & 2032F |
4 Global Refractory Material Market Dynamics |
4.1 Impact Analysis |
4.2 Market Drivers |
4.3 Market Restraints |
5 Global Refractory Material Market Trends |
6 Global Refractory Material Market, 2022-2032 |
6.1 Global Refractory Material Market, Revenues & Volume, By Form, 2022-2032 |
6.1.1 Overview & Analysis |
6.1.2 Global Refractory Material Market, Revenues & Volume, By Shaped, 2022-2032 |
6.1.3 Global Refractory Material Market, Revenues & Volume, By Unshaped, 2022-2032 |
6.2 Global Refractory Material Market, Revenues & Volume, By Chemical Composition, 2022-2032 |
6.2.1 Overview & Analysis |
6.2.2 Global Refractory Material Market, Revenues & Volume, By Alumina, 2022-2032 |
6.2.3 Global Refractory Material Market, Revenues & Volume, By Silica, 2022-2032 |
6.2.4 Global Refractory Material Market, Revenues & Volume, By Magnesia, 2022-2032 |
6.2.5 Global Refractory Material Market, Revenues & Volume, By Fireclay, 2022-2032 |
6.2.6 Global Refractory Material Market, Revenues & Volume, By Others, 2022-2032 |
6.3 Global Refractory Material Market, Revenues & Volume, By Chemistry, 2022-2032 |
6.3.1 Overview & Analysis |
6.3.2 Global Refractory Material Market, Revenues & Volume, By Acidic, 2022-2032 |
6.3.3 Global Refractory Material Market, Revenues & Volume, By Basic, 2022-2032 |
6.3.4 Global Refractory Material Market, Revenues & Volume, By Neutral, 2022-2032 |
6.4 Global Refractory Material Market, Revenues & Volume, By End-use, 2022-2032 |
6.4.1 Overview & Analysis |
6.4.2 Global Refractory Material Market, Revenues & Volume, By Metals & Metallurgy, 2022-2032 |
6.4.3 Global Refractory Material Market, Revenues & Volume, By Cement, 2022-2032 |
6.4.4 Global Refractory Material Market, Revenues & Volume, By Glass & Ceramics, 2022-2032 |
6.4.5 Global Refractory Material Market, Revenues & Volume, By Power Generation, 2022-2032 |
6.4.6 Global Refractory Material Market, Revenues & Volume, By Others, 2022-2032 |
7 North America Refractory Material Market, Overview & Analysis |
7.1 North America Refractory Material Market Revenues & Volume, 2022-2032 |
7.2 North America Refractory Material Market, Revenues & Volume, By Countries, 2022-2032 |
7.2.1 United States (US) Refractory Material Market, Revenues & Volume, 2022-2032 |
7.2.2 Canada Refractory Material Market, Revenues & Volume, 2022-2032 |
7.2.3 Rest of North America Refractory Material Market, Revenues & Volume, 2022-2032 |
7.3 North America Refractory Material Market, Revenues & Volume, By Form, 2022-2032 |
7.4 North America Refractory Material Market, Revenues & Volume, By Chemical Composition, 2022-2032 |
7.5 North America Refractory Material Market, Revenues & Volume, By Chemistry, 2022-2032 |
7.6 North America Refractory Material Market, Revenues & Volume, By End-use, 2022-2032 |
8 Latin America (LATAM) Refractory Material Market, Overview & Analysis |
8.1 Latin America (LATAM) Refractory Material Market Revenues & Volume, 2022-2032 |
8.2 Latin America (LATAM) Refractory Material Market, Revenues & Volume, By Countries, 2022-2032 |
8.2.1 Brazil Refractory Material Market, Revenues & Volume, 2022-2032 |
8.2.2 Mexico Refractory Material Market, Revenues & Volume, 2022-2032 |
8.2.3 Argentina Refractory Material Market, Revenues & Volume, 2022-2032 |
8.2.4 Rest of LATAM Refractory Material Market, Revenues & Volume, 2022-2032 |
8.3 Latin America (LATAM) Refractory Material Market, Revenues & Volume, By Form, 2022-2032 |
8.4 Latin America (LATAM) Refractory Material Market, Revenues & Volume, By Chemical Composition, 2022-2032 |
8.5 Latin America (LATAM) Refractory Material Market, Revenues & Volume, By Chemistry, 2022-2032 |
8.6 Latin America (LATAM) Refractory Material Market, Revenues & Volume, By End-use, 2022-2032 |
9 Asia Refractory Material Market, Overview & Analysis |
9.1 Asia Refractory Material Market Revenues & Volume, 2022-2032 |
9.2 Asia Refractory Material Market, Revenues & Volume, By Countries, 2022-2032 |
9.2.1 India Refractory Material Market, Revenues & Volume, 2022-2032 |
9.2.2 China Refractory Material Market, Revenues & Volume, 2022-2032 |
9.2.3 Japan Refractory Material Market, Revenues & Volume, 2022-2032 |
9.2.4 Rest of Asia Refractory Material Market, Revenues & Volume, 2022-2032 |
9.3 Asia Refractory Material Market, Revenues & Volume, By Form, 2022-2032 |
9.4 Asia Refractory Material Market, Revenues & Volume, By Chemical Composition, 2022-2032 |
9.5 Asia Refractory Material Market, Revenues & Volume, By Chemistry, 2022-2032 |
9.6 Asia Refractory Material Market, Revenues & Volume, By End-use, 2022-2032 |
10 Africa Refractory Material Market, Overview & Analysis |
10.1 Africa Refractory Material Market Revenues & Volume, 2022-2032 |
10.2 Africa Refractory Material Market, Revenues & Volume, By Countries, 2022-2032 |
10.2.1 South Africa Refractory Material Market, Revenues & Volume, 2022-2032 |
10.2.2 Egypt Refractory Material Market, Revenues & Volume, 2022-2032 |
10.2.3 Nigeria Refractory Material Market, Revenues & Volume, 2022-2032 |
10.2.4 Rest of Africa Refractory Material Market, Revenues & Volume, 2022-2032 |
10.3 Africa Refractory Material Market, Revenues & Volume, By Form, 2022-2032 |
10.4 Africa Refractory Material Market, Revenues & Volume, By Chemical Composition, 2022-2032 |
10.5 Africa Refractory Material Market, Revenues & Volume, By Chemistry, 2022-2032 |
10.6 Africa Refractory Material Market, Revenues & Volume, By End-use, 2022-2032 |
11 Europe Refractory Material Market, Overview & Analysis |
11.1 Europe Refractory Material Market Revenues & Volume, 2022-2032 |
11.2 Europe Refractory Material Market, Revenues & Volume, By Countries, 2022-2032 |
11.2.1 United Kingdom Refractory Material Market, Revenues & Volume, 2022-2032 |
11.2.2 Germany Refractory Material Market, Revenues & Volume, 2022-2032 |
11.2.3 France Refractory Material Market, Revenues & Volume, 2022-2032 |
11.2.4 Rest of Europe Refractory Material Market, Revenues & Volume, 2022-2032 |
11.3 Europe Refractory Material Market, Revenues & Volume, By Form, 2022-2032 |
11.4 Europe Refractory Material Market, Revenues & Volume, By Chemical Composition, 2022-2032 |
11.5 Europe Refractory Material Market, Revenues & Volume, By Chemistry, 2022-2032 |
11.6 Europe Refractory Material Market, Revenues & Volume, By End-use, 2022-2032 |
12 Middle East Refractory Material Market, Overview & Analysis |
12.1 Middle East Refractory Material Market Revenues & Volume, 2022-2032 |
12.2 Middle East Refractory Material Market, Revenues & Volume, By Countries, 2022-2032 |
12.2.1 Saudi Arabia Refractory Material Market, Revenues & Volume, 2022-2032 |
12.2.2 UAE Refractory Material Market, Revenues & Volume, 2022-2032 |
12.2.3 Turkey Refractory Material Market, Revenues & Volume, 2022-2032 |
12.3 Middle East Refractory Material Market, Revenues & Volume, By Form, 2022-2032 |
12.4 Middle East Refractory Material Market, Revenues & Volume, By Chemical Composition, 2022-2032 |
12.5 Middle East Refractory Material Market, Revenues & Volume, By Chemistry, 2022-2032 |
12.6 Middle East Refractory Material Market, Revenues & Volume, By End-use, 2022-2032 |
13 Global Refractory Material Market Key Performance Indicators |
14 Global Refractory Material Market - Export/Import By Countries Assessment |
15 Global Refractory Material Market - Opportunity Assessment |
15.1 Global Refractory Material Market Opportunity Assessment, By Countries, 2022 & 2032F |
15.2 Global Refractory Material Market Opportunity Assessment, By Form, 2022 & 2032F |
15.3 Global Refractory Material Market Opportunity Assessment, By Chemical Composition, 2022 & 2032F |
15.4 Global Refractory Material Market Opportunity Assessment, By Chemistry, 2022 & 2032F |
15.5 Global Refractory Material Market Opportunity Assessment, By End-use, 2022 & 2032F |
16 Global Refractory Material Market - Competitive Landscape |
16.1 Global Refractory Material Market Revenue Share, By Companies, 2025 |
16.2 Global Refractory Material Market Competitive Benchmarking, By Operating and Technical Parameters |
17 Top 10 Company Profiles |
18 Recommendations |
19 Disclaimer |
Global Go To Market Strategy - 2030
Export potential enables firms to identify high-growth global markets with greater confidence by combining advanced trade intelligence with a structured quantitative methodology. The framework analyzes emerging demand trends and country-level import patterns while integrating macroeconomic and trade datasets such as GDP and population forecasts, bilateral import–export flows, tariff structures, elasticity differentials between developed and developing economies, geographic distance, and import demand projections. Using weighted trade values from 2020–2024 as the base period to project country-to-country export potential for 2030, these inputs are operationalized through calculated drivers such as gravity model parameters, tariff impact factors, and projected GDP per-capita growth. Through an analysis of hidden potentials, demand hotspots, and market conditions that are most favorable to success, this method enables firms to focus on target countries, maximize returns, and global expansion with data, backed by accuracy.
By factoring in the projected importer demand gap that is currently unmet and could be potential opportunity, it identifies the potential for the Exporter (Country) among 190 countries, against the general trade analysis, which identifies the biggest importer or exporter.
To discover high-growth global markets and optimize your business strategy:
Click Here
Request Primary Research & Report
- Single User License$ 4,560
- Department License$ 5,055
- Site License$ 5,595
- Global License$ 6,000
Leadership Perspectives from Industry Events
Search
6Wresearch in the News
 Forbes
Citing 6Wresearch analytics to map global infrastructure and pharmaceutical industry trajectories.
 Bloomberg Law
Direct syndication of 6Wresearch's macro data points, capturing complex supply chain shifts.
 Reuters
Tracking industrial manufacturing adjustments and electronic security ecosystem scaling.
 Mint
Utilizing deep-tech sector market sizing to analyze global automation and robotics.
 The Economic Times
Anchoring features on industrial IoT growth metrics and connected smart-grid devices.
 Business Standard
Featuring strategic evaluations of Advanced Driver Assistance Systems (ADAS) and AI road safety.
 The Hindu
Spotlighting core commercial metrics ranging from unmanned aerial vehicles (UAVs) to consumer durables.
 Financial Express
Anchoring quarterly reviews on cross-border real estate tech and structural hardware manufacturing.
 Yahoo Finance
Syndicating the tracker's $30.1 billion untapped-market findings, spotlighting Japan, the US and China as India's top new-potential importers.
 India Today
Carrying the release on smartphones leading India's export potential to $94 billion by 2031, per 6WExportGTM data.
 Dailyhunt
Distributing the tracker findings to its regional readership, framing India's export diversification into Japan and Mexico.
 PR Newswire Original release
Publishing the full India Export Attractiveness Tracker 2026, detailing new trade corridors across iron ore, LCVs and pharmaceuticals.
 The Industrial
Highlighting the tracker's read on India's semiconductor ambitions and long-term chip-assembly export potential.
 PTI News
Reporting on the $66.81 billion pharmaceuticals export opportunity flagged in the tracker, amid looming US generic-drug tariffs.
 Tribune India
Covering the tracker's tariff-versus-regulation analysis across India's mature export markets in the US, China and UAE.
 ANI News
Amplifying the report's findings on polished diamonds, refined petroleum and medicines as India's core export engines.
 International Business Magazine
Covering the report's insight into how AEB, blind spot detection, and driver monitoring are reshaping India's ADAS market.
 Focus Gaming News
Highlighting the research forecast for Egypt's gambling market, projecting steady growth through 2032.
Thought Leadership and Analyst Meet
Our Clients
Latest Reports
- Global Whey Protein Market (2025-2031)
- Bahrain Vehicle-Supported Bicycle Drive Chains Market (2026-2032)
- Azerbaijan Vehicle-Supported Bicycle Drive Chains Market (2026-2032)
- Australia Vehicle-Supported Bicycle Drive Chains Market (2026-2032)
- Argentina Vehicle-Supported Bicycle Drive Chains Market (2026-2032)
- Algeria Vehicle-Supported Bicycle Drive Chains Market (2026-2032)
- Zimbabwe Vehicle-Grade Aluminum Materials Market (2026-2032)
- Zambia Vehicle-Grade Aluminum Materials Market (2026-2032)
- Yemen Vehicle-Grade Aluminum Materials Market (2026-2032)
- Vanuatu Vehicle-Grade Aluminum Materials Market (2026-2032)
Industry Events and Analyst Meet

EV India Expo 2026
HIMTEX 2026
India Refining Summit 2026
India EV Show 2026
EV tech India Expo 2026
Whitepaper
- Middle East & Africa Commercial Security Market Click here to view more.
- Middle East & Africa Fire Safety Systems & Equipment Market Click here to view more.
- GCC Drone Market Click here to view more.
- Middle East Lighting Fixture Market Click here to view more.
- GCC Physical & Perimeter Security Market Click here to view more.