India Regional Airline Market Size & Growth Rate
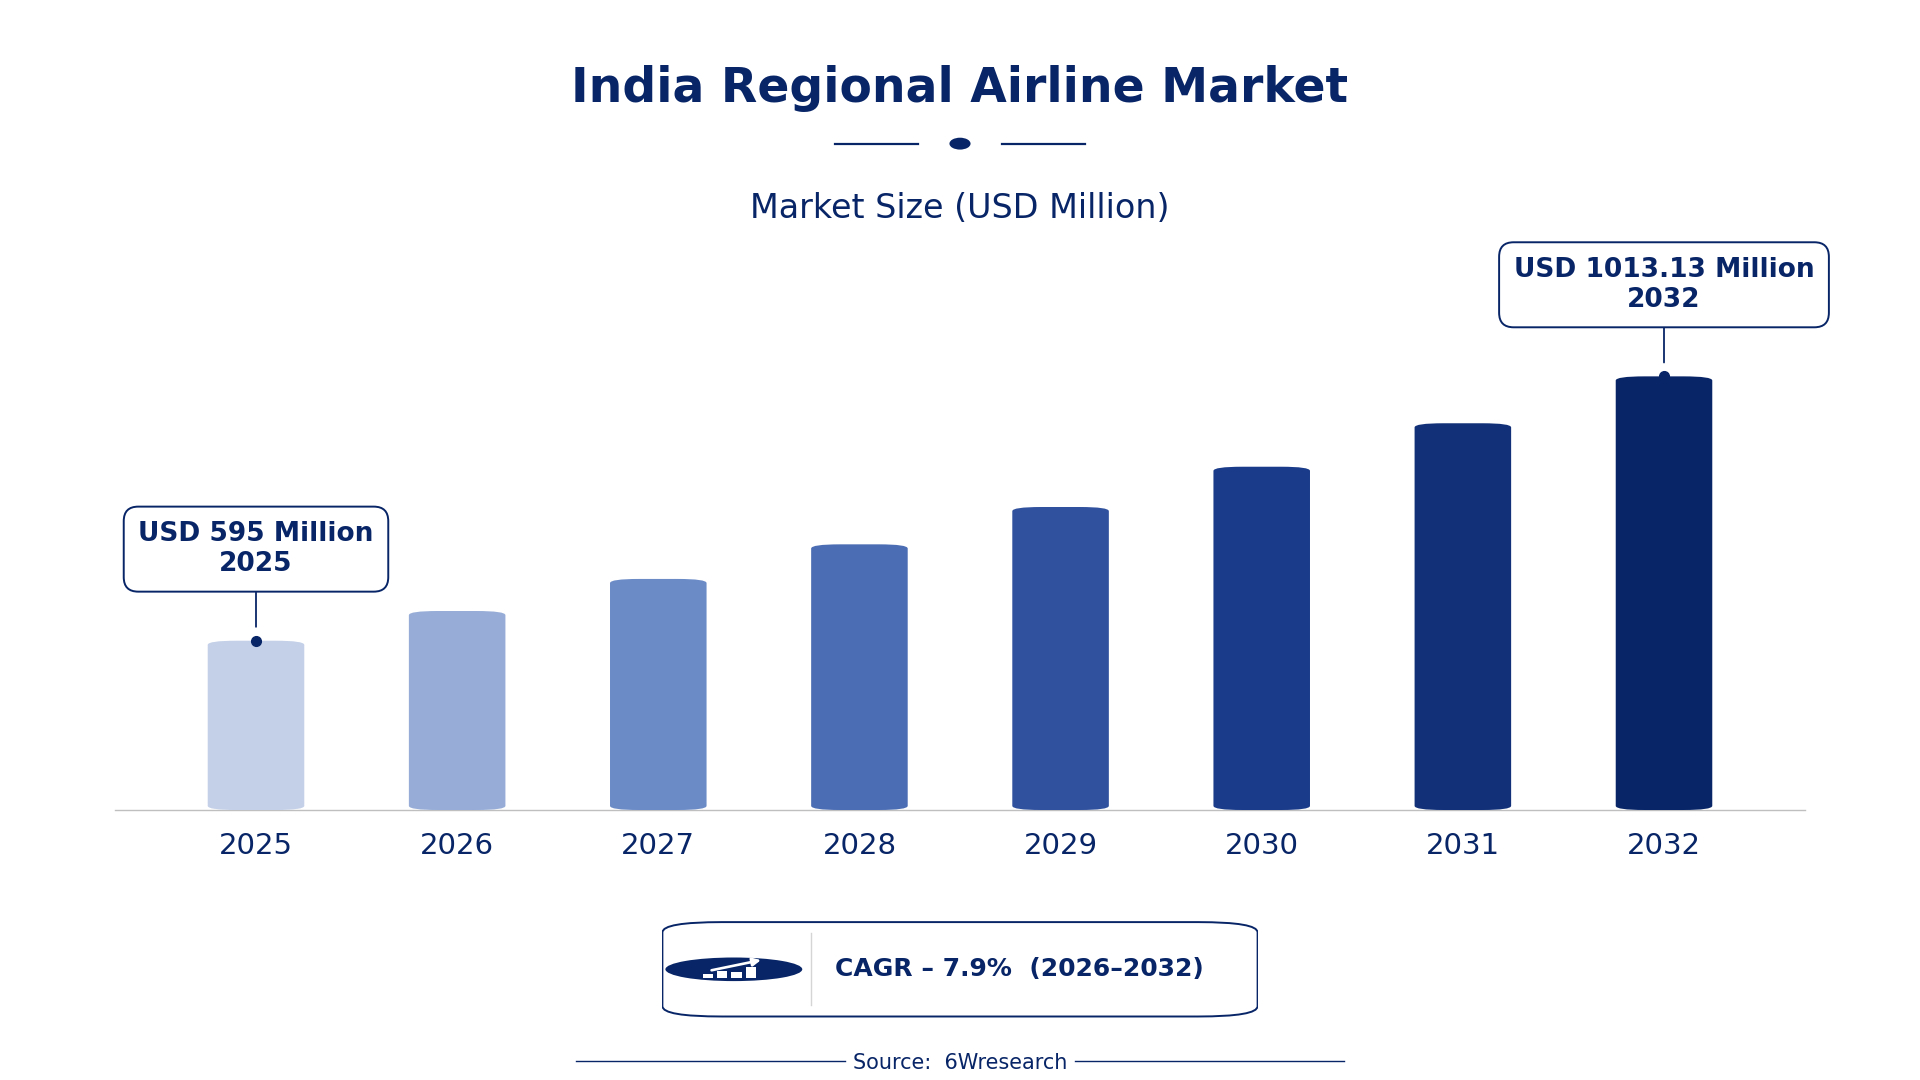
According to 6Wresearch internal database and industry insights, the India Regional Airline Market was valued at USD 595.0 million in 2025 and is projected to reach USD 1,013.13 million by 2032, growing at a CAGR of approximately 7.9% during 2026–2032.
India Regional Airline Market Highlights
| Report Metric | Details |
| Report Name | India Regional Airline Market |
| Market Size 2025 | USD 595.0 million |
| Market Size 2032 | USD 1,013.13 million |
| Absolute Growth 2025–2032 | USD 418.13 million |
| CAGR 2026–2032 | 7.9% |
| Peak Annual Growth | 10.1% in 2027 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Service Type, 2025 | Commuter Airlines (51% share) |
| Leading Route Type, 2025 | Point-to-Point (42% share) |
| Leading Fleet Type, 2025 | Turboprop / Small Jets (44% share) |
| Leading End User, 2025 | Business/Leisure Travelers (48% share) |
| Fastest-Growing Service Type | Public Service Aviation (10.5% CAGR) |
| Fastest-Growing Route Type | Hub Feeding (10.4% CAGR) |
| Fastest-Growing End User | Governments & Authorities (10.6% CAGR) |
| Growing Sector | Public Service Aviation |
| Key End Users | Business/Leisure Travelers, Governments & Authorities, Major Airline Partners |
India Regional Airline Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
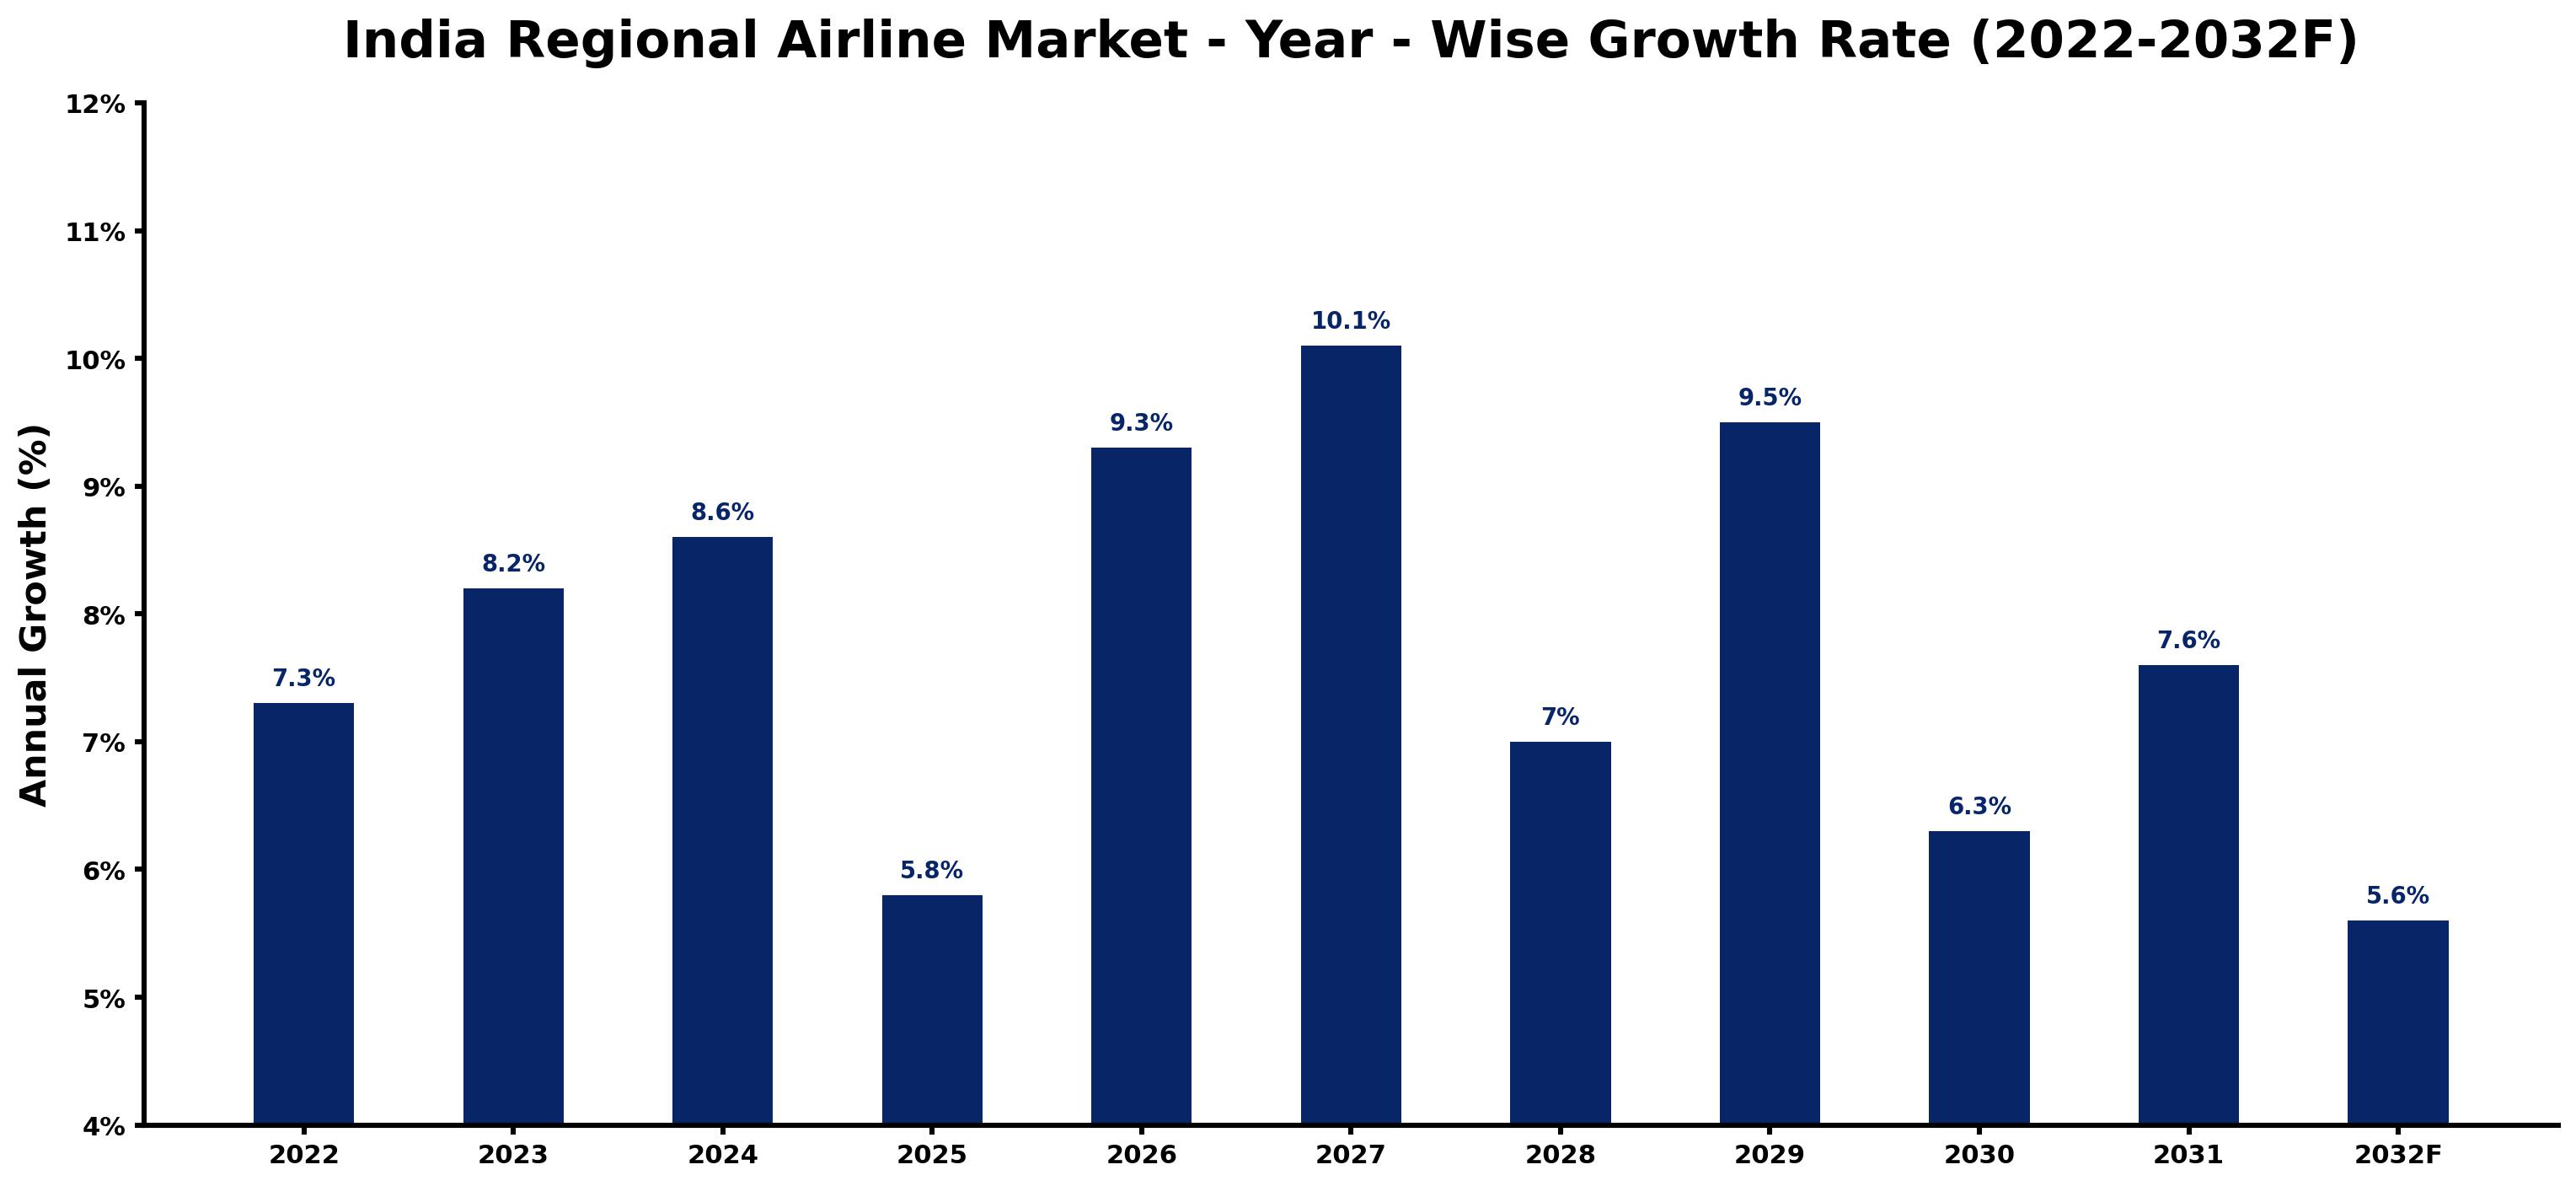
Annual growth estimates for each year appear below with the principal reason behind them, explaining the shifts that set the pace of the market.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 7.3 | The market experienced steady growth due to increased domestic travel demand driven by government initiatives like the UDAN scheme. |
| 2023 | 8.2 | Demand rose as regional airlines expanded their services under the UDAN scheme, connecting underserved areas. |
| 2024 | 8.6 | The continued implementation of the UDAN scheme boosted connectivity and demand for regional flights across the country. |
| 2025 | 5.8 | Growth slowed as competition intensified among regional carriers in the market, affecting pricing strategies. |
| 2026 | 9.3 | A resurgence in demand is expected with increased investments in regional infrastructure and airport upgrades. |
| 2027 | 10.1 | The market is projected to peak as the government targets new route additions under the UDAN scheme, enhancing access. |
| 2028 | 7.0 | Growth is expected to slow as market adjustments occur following peak demand and increased competition. |
| 2029 | 9.5 | Demand will increase with the rise of government-supported regional initiatives that improve connectivity for underserved regions. |
| 2030 | 6.3 | Growth is projected to decelerate as market saturation begins to set in, affecting new route developments. |
| 2031 | 7.6 | A rebound in travel demand will contribute to improved growth rates for regional airlines, supported by government initiatives. |
| 2032 | 5.6 | The market will continue to grow, albeit at a slower pace than before due to various factors, including competition. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
India Regional Airline Market Synopsis
The India Regional Airline Market involves airlines operating short-haul flights that connect smaller cities to major hubs. These airlines primarily use turboprops and regional jets to serve routes with lower passenger volumes. In 2023, regional airlines served over 30 million passengers, reflecting a strong demand for these services. The market is expanding due to a population of approximately 1.4 billion and government initiatives like the UDAN scheme, which improve connectivity and stimulate air travel demand across the country.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Growing domestic travel demand driven by increased disposable income and urbanisation. | Driver | High | Commuter Airlines |
| Government support through schemes like UDAN is creating new routes and opportunities. | Driver | High | Public Service Aviation |
| The regional airline sector is ripe for investment, particularly in underserved areas. | Opportunity | High | Feeder Airlines |
| There is a significant gap in services connecting Tier-2 and Tier-3 cities. | Opportunity | Medium | Point-to-Point |
| Intense competition among airlines may lead to price wars affecting profitability. | Restraint | High | Feeder Airlines |
| Operational challenges due to regulatory compliance can hinder growth. | Restraint | Medium | Commuter Airlines |
| Buyers face delays due to fluctuating operational costs and fuel prices. | Challenge | High | Business/Leisure Travelers |
| Suppliers encounter difficulties in maintaining safety standards amid rising demand. | Challenge | Medium | Governments & Authorities |
Evaluation of Drivers in India Regional Airline Market (2026–2032)
Below mentioned are some major drivers and their influence on market dynamics.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased disposable income leading to higher travel frequency. | Business/Leisure Travelers | As disposable income rises, more individuals opt for regional air travel, increasing overall demand. |
| Government initiatives like the UDAN scheme facilitate new routes. | Public Service Aviation | The UDAN scheme encourages airlines to operate in underserved regions, boosting connectivity and passenger numbers. |
| Growing tourism in India increases demand for regional flights. | Feeder Airlines | Tourism growth drives the need for more regional flights, connecting tourists to various destinations. |
| The rise in digital technology adoption improves ticketing and customer service. | Commuter Airlines | Digital advancements streamline booking processes, attracting more passengers to regional airlines. |
| Investment in regional airport infrastructure increases operational capacity. | Point-to-Point | Upgraded regional airports enable airlines to handle more flights, thus expanding service offerings. |
The ongoing development of regional infrastructure is likely to draw more passengers, with investments surpassing INR 10,000 crores by 2025. In 2023, regional airlines catered to over 30 million passengers, indicative of strong demand for these services. The average passenger load factor of approximately 75% reflects a solid interest in regional flights. As digital technology adoption increases, improvements in ticketing and customer service will further elevate the travel experience for passengers.
Evaluation of Restraints in India Regional Airline Market
The table below lists the restraints and the evidence behind each.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Intense competition may lead to unsustainable pricing strategies. | Feeder Airlines | Increased competition among regional airlines can drive down prices, impacting profitability and market stability. |
| Regulatory compliance costs can hinder operational efficiency. | Commuter Airlines | Meeting safety and operational standards set by the Directorate General of Civil Aviation adds to operational costs for airlines. |
| Fluctuating fuel prices create uncertainty for operational budgets. | Business/Leisure Travelers | Rising fuel costs can lead to increased ticket prices, deterring some travelers from choosing regional airlines. |
| Limited awareness of regional airline options affects passenger numbers. | Governments & Authorities | Many potential travelers remain unaware of available regional services, limiting market growth opportunities. |
| Infrastructure limitations at regional airports can restrict operations. | Point-to-Point | Inadequate facilities at some regional airports can hinder airlines from expanding their operations effectively. |
India Regional Airline Market Challenges
Operational costs in the India regional airline market are rising sharply, with fuel prices climbing by 20% over the past year, which compresses profit margins for operators. Supply chain disruptions impact over 100 operational regional airports, causing delays that diminish service reliability for customers. Many regional operators contend with outdated technology, resulting in longer turnaround times and reduced customer satisfaction. Competition intensifies as larger carriers encroach on regional routes, compelling smaller airlines to lower fares, which threatens their financial stability and market presence.
Trends in the India Regional Airline Market
Below mentioned are some of the trends shaping the India Regional Airline Market growth.
- Shift towards Digital Ticketing Solutions: In recent years, regional airlines have increasingly embraced digital ticketing solutions to enhance customer experiences. In 2023, over 60% of bookings were made online, reflecting a shift in consumer behaviour towards convenience.
- Growth in Public Service Aviation: Public Service Aviation has experienced a notable increase, with a CAGR of 10.5% projected through 2032. This trend is particularly pronounced in remote areas where government initiatives are enhancing connectivity and access to air travel.
- Expansion of Hub Feeding Routes: Hub Feeding routes are gaining momentum, with a CAGR of 10.4% anticipated from 2026 to 2032. This shift is driven by the necessity for efficient passenger transfers to major airlines, thereby improving overall connectivity.
- Increase in Charter Services Post-2020: Post-2020, demand for charter services among regional airlines has surged, with a 15% increase in bookings in 2023, reflecting changing travel preferences among consumers.
Investment Opportunities in the India Regional Airline Market
Some of the investment opportunities in the India Regional Airline Market are mentioned below.
- Investment in Regional Airport Upgrades: With INR 1,500 crores allocated in 2023 for regional connectivity schemes, there exists an opportunity to invest in upgrading regional airports, enhancing service capabilities and attracting more airlines.
- Expansion of Public Service Aviation: The growing need for connectivity in remote areas presents opportunities for airlines to broaden public service aviation offerings, particularly in underserved regions where access is limited.
- Development of New Regional Routes: Collaborating with local governments to establish subsidised routes can improve service viability and attract more passengers, especially in Tier-2 cities where demand is on the rise.
- Focus on Charter Services: The increasing demand for charter services provides airlines with an opportunity to diversify their offerings, particularly in regions with limited scheduled flights, catering to specific travel needs.
Government Initiatives in the India Regional Airline Market
The regulatory framework governing regional airlines in India has evolved in recent years. The National Civil Aviation Policy 2022 aims to improve regional air transport infrastructure and increase investments in regional airlines. The UDAN 4.0 scheme, launched in 2022, targets the addition of 100 new routes by 2025, enhancing connectivity for underserved regions. Additionally, the Civil Aviation Requirement issued in 2021 mandates safety and operational standards for regional airlines, ensuring compliance with national regulations and improving service quality.
Local governments and authorities utilise the Regional Connectivity Scheme to improve air travel access. The Airports Authority of India is responsible for implementing upgrades at over 50 regional airports by 2025, ensuring they can accommodate increased traffic. The Ministry of Civil Aviation oversees the allocation of INR 1,500 crores in 2023 to support new regional routes and improve airport facilities, benefiting both airlines and passengers. These measures collectively aim to enhance the operational capabilities of regional airlines across the country.
Future Insight of the India Regional Airline Market
By 2032, buyers and suppliers in the India regional airline market can expect enhanced connectivity as the UDAN scheme broadens its reach to underserved regions. Investments exceeding INR 10,000 crores in regional connectivity initiatives will improve airport infrastructure, benefiting both airlines and passengers. The adoption of digital technologies for ticketing and customer service will streamline operations and improve the travel experience. With the Indian aviation sector targeting 1 billion passenger trips by 2030, regional airlines will play a vital role in meeting this ambitious goal.
Market Segmentation Analysis
The report offers a comprehensive study of the following market segments and their leading categories in the market.
By Service Type – Commuter Airlines Dominated, Public Service Aviation Expected to Grow Fastest
According to Ravi Bhandari, Research Head at 6Wresearch, with a 51% revenue share in 2025, Commuter Airlines was the largest service type category. Commuter Airlines hold the largest market share as they provide vital connectivity for short distances, catering to the needs of a growing base of domestic travellers. The UDAN scheme has notably improved their operations, enhancing access to underserved regions across India. The quickest growth will come from Public Service Aviation, forecast to expand at a CAGR of 10.5% between 2026 and 2032. Public Service Aviation is witnessing rapid growth due to increased government initiatives aimed at enhancing services in remote areas, with INR 1,500 crores allocated for regional connectivity schemes in 2023. This trend shows a rising reliance on these services for official travel and support. Suppliers should prioritise service enhancements to meet the increasing demand for regional connectivity.
By Route Type – Point-to-Point Dominated, Hub Feeding Expected to Grow Fastest
In 2025, Point-to-Point led the route type split with a 42% share. Point-to-Point routes dominate the market as they enable direct travel between cities, appealing to passengers who value convenience and efficiency. This model thrives in India, where over 100 operational regional airports facilitate seamless connections. Hub Feeding is set to record the highest CAGR in this split, 10.4% over 2026–2032. Hub Feeding routes are expanding quickly as they effectively funnel passengers to central hubs, crucial for improving overall connectivity. The rise in domestic air travel further accelerates this growth, indicating a shift towards more integrated travel solutions. Buyers should recognise the advantages of point-to-point travel for quicker access to destinations, while suppliers may need to refine hub feeding strategies.
By Fleet Type – Turboprop / Small Jets Dominated and Is Expected to Record the Fastest Growth
Turboprop / Small Jets accounted for a 44% market share by fleet type in 2025. Turboprop / Small Jets account for the largest share of the fleet used in regional operations, as these aircraft are ideal for short-haul flights connecting smaller cities. Their efficiency and suitability for lower passenger volumes make them a preferred choice in the market. Its lead should widen, with a projected CAGR of 9.3% during 2026–2032, the highest in this split. Turboprop / Small Jets are also the fastest-growing fleet type, as their versatility and cost-effectiveness align with the increasing demand for regional air travel. This dual role solidifies their market position and ensures continued investment in this fleet category. Suppliers must focus on maintaining and upgrading turboprop and small jet fleets to meet the rising demand.
By End User – Business/Leisure Travelers Dominated, Governments & Authorities Expected to Grow Fastest
Business/Leisure Travelers held a 48% share of the India Regional Airline Market by end user in 2025. Business/Leisure Travelers represent the largest segment of regional airline passengers, driven by the increasing need for connectivity in a rapidly growing economy. Their diverse travel needs support the sustained growth of regional airlines, particularly in connecting Tier-2 and Tier-3 cities. Over 2026–2032, Governments & Authorities are expected to post the fastest growth, at a CAGR of 10.6%. Governments & Authorities are the fastest-growing end-user segment, utilising regional airlines for official travel and services, especially in underserved areas. This growth reflects the government's commitment to improving regional connectivity through various initiatives. Suppliers should tailor their services to meet the specific needs of government clients while continuing to attract business and leisure travellers.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- India Regional Airline Market Outlook
- Market Size of India Regional Airline Market, 2025
- Forecast of India Regional Airline Market, 2032
- Historical Data and Forecast of India Regional Airline Revenues & Volume for the Period 2022 - 2032F
- India Regional Airline Market Trend Evolution
- India Regional Airline Market Drivers and Challenges
- India Regional Airline Price Trends
- India Regional Airline Porter's Five Forces
- India Regional Airline Industry Life Cycle
- Historical Data and Forecast of India Regional Airline Market Revenues & Volume By Service Type for the Period 2022 - 2032F
- Historical Data and Forecast of India Regional Airline Market Revenues & Volume By Commuter Airlines for the Period 2022 - 2032F
- Historical Data and Forecast of India Regional Airline Market Revenues & Volume By Feeder Airlines for the Period 2022 - 2032F
- Historical Data and Forecast of India Regional Airline Market Revenues & Volume By Charter/On-Demand for the Period 2022 - 2032F
- Historical Data and Forecast of India Regional Airline Market Revenues & Volume By Public Service Aviation for the Period 2022 - 2032F
- Historical Data and Forecast of India Regional Airline Market Revenues & Volume By Route Type for the Period 2022 - 2032F
- Historical Data and Forecast of India Regional Airline Market Revenues & Volume By Point-to-Point for the Period 2022 - 2032F
- Historical Data and Forecast of India Regional Airline Market Revenues & Volume By Hub Feeding for the Period 2022 - 2032F
- Historical Data and Forecast of India Regional Airline Market Revenues & Volume By Ad-Hoc Routes for the Period 2022 - 2032F
- Historical Data and Forecast of India Regional Airline Market Revenues & Volume By Subsidized Routes for the Period 2022 - 2032F
- Historical Data and Forecast of India Regional Airline Market Revenues & Volume By Fleet Type for the Period 2022 - 2032F
- Historical Data and Forecast of India Regional Airline Market Revenues & Volume By Turboprop / Small Jets for the Period 2022 - 2032F
- Historical Data and Forecast of India Regional Airline Market Revenues & Volume By Regional Jets for the Period 2022 - 2032F
- Historical Data and Forecast of India Regional Airline Market Revenues & Volume By Mixed Fleet for the Period 2022 - 2032F
- Historical Data and Forecast of India Regional Airline Market Revenues & Volume By STOL Aircraft for the Period 2022 - 2032F
- Historical Data and Forecast of India Regional Airline Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of India Regional Airline Market Revenues & Volume By Business/Leisure Travelers for the Period 2022 - 2032F
- Historical Data and Forecast of India Regional Airline Market Revenues & Volume By Major Airline Partners for the Period 2022 - 2032F
- Historical Data and Forecast of India Regional Airline Market Revenues & Volume By Corporate & VIP Travel for the Period 2022 - 2032F
- Historical Data and Forecast of India Regional Airline Market Revenues & Volume By Governments & Authorities for the Period 2022 - 2032F
- India Regional Airline Import Export Trade Statistics
- Market Opportunity Assessment By Service Type
- Market Opportunity Assessment By Route Type
- Market Opportunity Assessment By Fleet Type
- Market Opportunity Assessment By End User
- India Regional Airline Top Companies Market Share
- India Regional Airline Competitive Benchmarking By Technical and Operational Parameters
- India Regional Airline Company Profiles
- India Regional Airline Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By Service Type
- Commuter Airlines
- Feeder Airlines
- Charter/On-Demand
- Public Service Aviation
By Route Type
- Point-to-Point
- Hub Feeding
- Ad-Hoc Routes
- Subsidized Routes
By Fleet Type
- Turboprop / Small Jets
- Regional Jets
- Mixed Fleet
- STOL Aircraft
By End User
- Business/Leisure Travelers
- Major Airline Partners
- Corporate & VIP Travel
- Governments & Authorities































