India Special Education Technology Market Size & Growth Rate
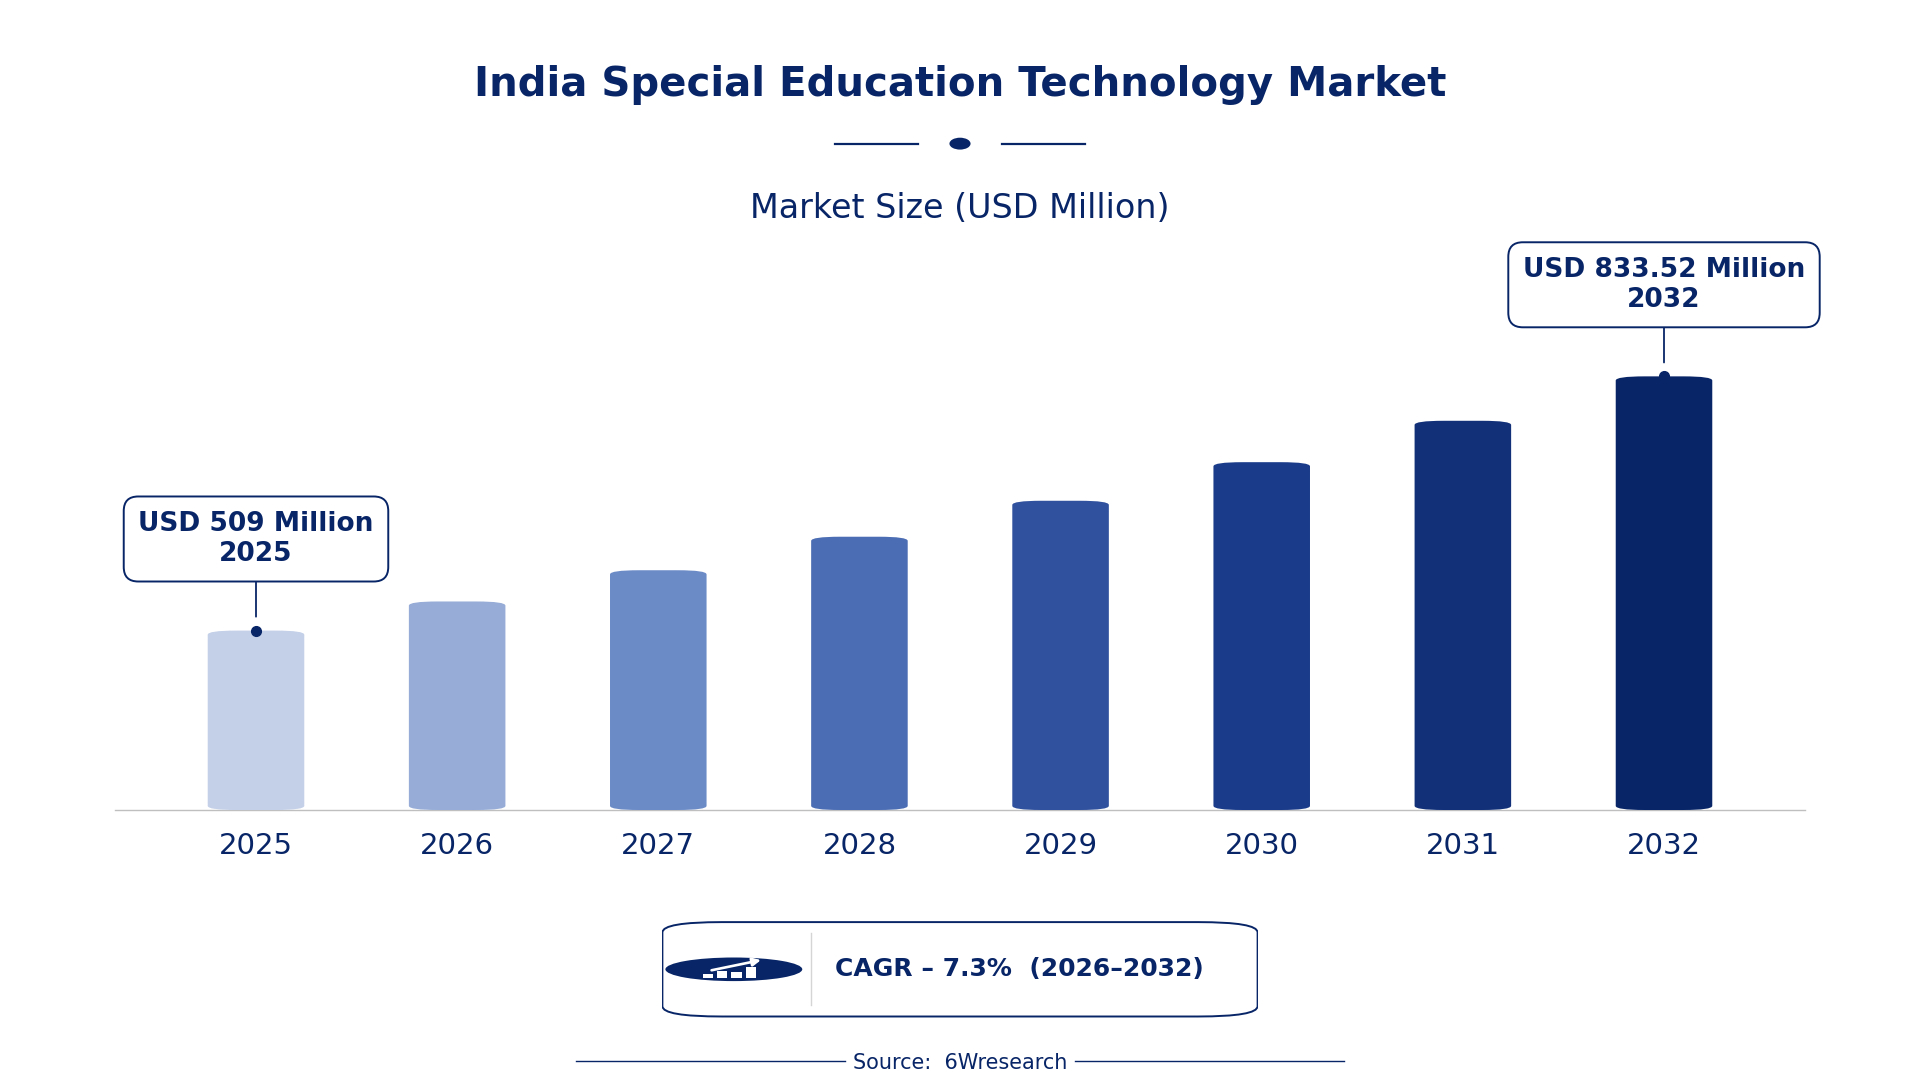
According to 6Wresearch internal database and industry insights, the India Special Education Technology Market was valued at USD 509.0 million in 2025 and is projected to reach USD 833.52 million by 2032, growing at a CAGR of approximately 7.3% during 2026–2032.
India Special Education Technology Market Highlights
| Report Metric | Details |
| Report Name | India Special Education Technology Market |
| Market Size 2025 | USD 509.0 million |
| Market Size 2032 | USD 833.52 million |
| Absolute Growth 2025–2032 | USD 324.52 million |
| CAGR 2026–2032 | 7.3% |
| Peak Annual Growth | 8.8% in 2031 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Technology Type, 2025 | EdTech Software (48% share) |
| Leading Learning Focus, 2025 | Communication Aid (46% share) |
| Leading Platform Type, 2025 | Cloud-Based (45% share) |
| Leading End User, 2025 | Schools for Disabled (36% share) |
| Fastest-Growing Technology Type | AR/VR Learning Tools (8.7% CAGR) |
| Fastest-Growing Learning Focus | Experiential Learning (9.6% CAGR) |
| Fastest-Growing End User | EdTech Startups (9.8% CAGR) |
| Growing Sector | Special Education |
| Key End Users | Schools for Disabled, Speech Therapists, EdTech Startups, Special Needs Users |
India Special Education Technology Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
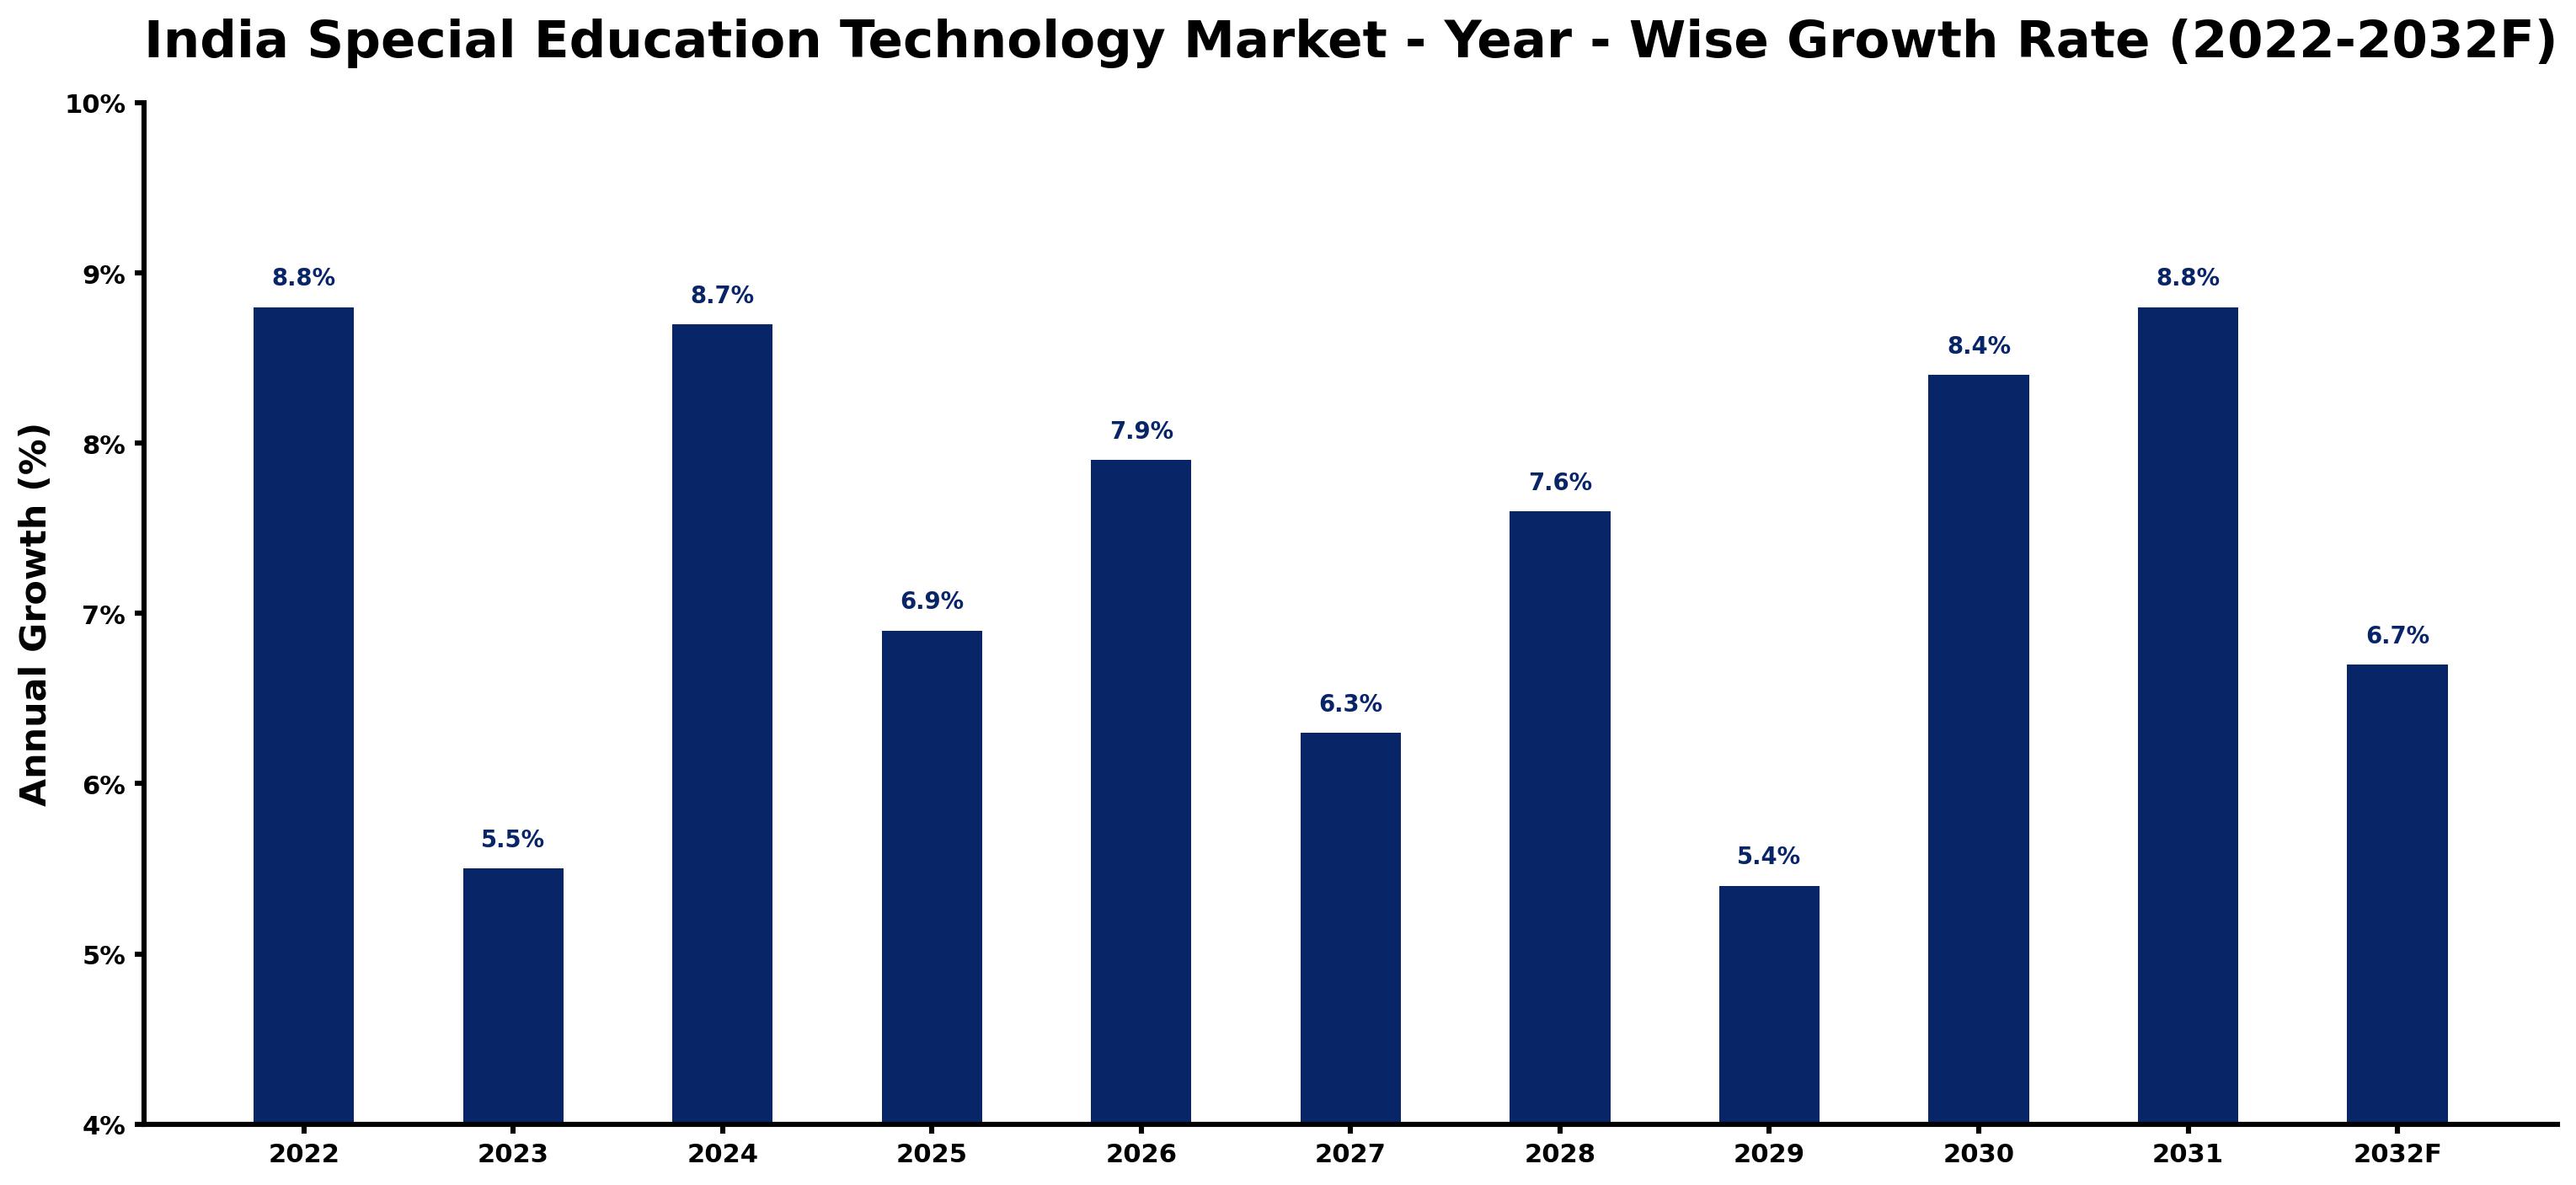
Year by year, the estimates below pair each growth rate with the development that shaped it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 8.8 | The market exhibited strong demand due to increased awareness and initiatives for inclusive education. |
| 2023 | 5.5 | Growth slowed as the implementation of new educational policies took time to materialise. |
| 2024 | 8.7 | Demand surged as educational institutions began integrating AR/VR tools into their curricula. |
| 2025 | 6.9 | The market experienced a slowdown as funding challenges affected technology adoption in schools. |
| 2026 | 7.9 | Investment in special education technology increased, driven by government initiatives and private sector interest. |
| 2027 | 6.3 | Growth slowed as the market adjusted to the saturation of certain technology types. |
| 2028 | 7.6 | Demand rose again as more schools adopted adaptive input tools for personalised learning. |
| 2029 | 5.4 | The market slowed due to budget constraints faced by educational institutions. |
| 2030 | 8.4 | A resurgence in growth occurred as new funding programmes were introduced for special education. |
| 2031 | 8.8 | The market peaked as the integration of technology in education reached new heights. |
| 2032 | 6.7 | Growth slowed as the market stabilised after rapid expansion in the previous years. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
India Special Education Technology Market Synopsis
Special Education Technology Market in India includes tools and resources designed to assist individuals with disabilities in learning environments. This encompasses assistive devices, software, and adaptive technologies that improve communication and learning experiences. The market is expanding due to rising demand from educational institutions and therapy centres, spurred by initiatives like the National Education Policy 2020 and the Samagra Shiksha Abhiyan. With over 2.68 million children needing special education services, the demand for effective solutions is crucial. The incorporation of advanced technologies, such as AR/VR tools, further drives market growth.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increased government funding for special education initiatives | Driver | High | AAC Devices |
| Growing adoption of AR/VR tools in educational settings | Driver | High | AR/VR Learning Tools |
| Rising demand for personalised learning solutions | Opportunity | High | EdTech Software |
| Expansion of special education schools across urban areas | Opportunity | Medium | Schools for Disabled |
| Budget constraints faced by educational institutions | Restraint | High | Adaptive Input Tools |
| Slow integration of technology in traditional curricula | Restraint | Medium | Communication Aid |
| Limited awareness among educators regarding available technologies | Challenge | High | Visual/Auditory Learning |
| High costs associated with implementing advanced technologies | Challenge | Medium | Hardware |
Evaluation of Drivers in India Special Education Technology Market (2026–2032)
The main growth drivers and the segments they affect most are set out below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased government funding for special education initiatives | AAC Devices | The Indian government allocated ₹1,000 crores for special education initiatives, boosting demand for AAC devices in schools. |
| Growing adoption of AR/VR tools in educational settings | AR/VR Learning Tools | Integration of AR/VR tools in over 100 special education institutions improves learning experiences, driving demand. |
| Rising demand for personalised learning solutions | Schools for Disabled | The target to establish 1,000 new special education schools by 2025 increases the need for various technologies. |
| Increased collaboration between educators and technologists | Adaptive Input Tools | The collaboration leads to tailored solutions for users, resulting in higher adoption rates in therapy sessions. |
| Expansion of cloud-based EdTech solutions | Cloud-Based | A 30% increase in demand for cloud-based solutions in 2023 supports broader access to educational resources. |
The integration of AR/VR tools in over 100 special education institutions improves learning experiences, driving further demand. The target to establish 1,000 new special education schools by 2025 increases the need for various technologies, creating a favourable environment for growth. Collaboration between educators and technologists is expected to lead to tailored solutions for users, resulting in higher adoption rates in therapy sessions.
Evaluation of Restraints in India Special Education Technology Market
The table below lists the restraints and the evidence behind each.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Budget constraints faced by educational institutions | Adaptive Input Tools | Many schools struggle with budget limitations, which restricts their ability to invest in adaptive input tools. |
| Slow integration of technology in traditional curricula | Communication Aid | Traditional teaching methods hinder the adoption of communication aids, limiting their effectiveness in classrooms. |
| Limited awareness among educators regarding available technologies | Visual/Auditory Learning | Many educators lack knowledge about the latest technologies, resulting in underutilisation of available resources. |
| High costs associated with implementing advanced technologies | Hardware | The high initial investment for hardware deters many schools from adopting necessary special education technologies. |
| Inconsistent training for staff on new technologies | EdTech Software | Without proper training, staff may struggle to effectively implement EdTech solutions in their teaching. |
India Special Education Technology Market Challenges
In India, the influx of new entrants in the special education technology market drives down prices, potentially compromising product quality for educational institutions that depend on effective tools. Supply chain issues obstruct access to essential components, delaying the delivery of adaptive technologies to therapy centres, which ultimately impacts over 2.68 million children with disabilities who require timely support. Buyers encounter challenges due to inconsistent product availability, which can disrupt learning for special needs users and frustrate educators. Additionally, a shortage of trained professionals in this field restricts the effective implementation of these technologies, creating obstacles for therapists aiming to improve learning outcomes.
Trends in the India Special Education Technology Market
Several trends are reshaping the India Special Education Technology Market; the most important are set out below.
- Growing Adoption of AR/VR Tools: Educational institutions are increasingly adopting AR/VR tools to enhance learning experiences for students with disabilities. Over 100 special education institutions have integrated these technologies into their curricula, reflecting a trend towards immersive learning.
- Rise of Cloud-Based Solutions: Cloud-based EdTech solutions are becoming more prevalent, with a reported 30% increase in demand in 2023. This shift allows for greater accessibility and flexibility in educational resources for students with disabilities.
- Focus on Experiential Learning: Experiential Learning is gaining traction as a key approach in special education. The fastest-growing segment, with a CAGR of 9.6%, underscores the importance of hands-on learning experiences tailored for diverse abilities.
- Investment in Adaptive Technologies: Investment in adaptive technologies is on the rise, driven by the need for personalised learning solutions. Schools are increasingly adopting adaptive input tools to cater to individual student needs.
Investment Opportunities in the India Special Education Technology Market
The following opportunities in the India Special Education Technology Market pair current demand with a clear way in.
- Gap in Adaptive Input Tools Supply: With over 200 rehabilitation centres using adaptive input tools, there is a gap in supply. Investing in these technologies now can meet the growing demand from therapy centres and schools.
- Demand for AR/VR Learning Tools: The demand for AR/VR learning tools is increasing, particularly in special education settings. Suppliers can focus on developing tailored solutions for schools and therapy centres to seize this market opportunity.
- Partnerships with Schools for Disabled: Forming partnerships with schools for disabled can facilitate entry into the market. Collaborating with these institutions can help suppliers understand specific needs and tailor their offerings accordingly.
- Investment in Cloud-Based Solutions: The current growth in cloud-based EdTech solutions presents an opportunity for investment. With a rise in demand, suppliers can capitalise on this trend by offering innovative cloud-based products.
Government Initiatives in the India Special Education Technology Market
The National Trust for the Welfare of Persons with Autism, Cerebral Palsy, Mental Retardation, and Multiple Disabilities launched several programmes since 2020 to support technology adoption in special education. This initiative aims to ensure that these technologies are accessible to all children with disabilities. The Samagra Shiksha Abhiyan focuses on improving the quality of education for children with disabilities, with an annual budget of ₹1,000 crores, enhancing access to necessary technologies in educational settings.
In 2023, the Ministry of Electronics and Information Technology's Digital India initiative promotes the use of technology in education, including special education technology. This initiative supports various projects aimed at integrating technology into classrooms, improving learning experiences for disabled students. The Accessible India Campaign continues to promote accessibility in education and technology for disabled individuals, ensuring that educational institutions are equipped with the necessary resources.
Future Insight of the India Special Education Technology Market
The special education technology market in India will evolve significantly by 2032, driven by technological advancements and supportive government policies. The National Education Policy 2020 will catalyse inclusive educational practices, increasing the demand for tailored solutions. By 2025, the establishment of 1,000 new special education schools will facilitate broader technology adoption. Moreover, a 30% rise in cloud-based EdTech solutions in 2023 indicates a shift towards more accessible and effective learning resources for both educators and students.
Market Segmentation Analysis
Each segment group is reviewed below, with the leader by share and the fastest grower by CAGR.
By Technology Type – EdTech Software Dominated, AR/VR Learning Tools Expected to Grow Fastest
According to Summon Dutta, Assistant Manager at 6Wresearch, EdTech Software held a 48% share of the India Special Education Technology Market by technology type in 2025. EdTech Software holds the largest share in the India Special Education Technology Market due to its widespread adoption in educational institutions, facilitating personalised learning for students with special needs. The substantial number of over 2.68 million children requiring special education services drives continuous demand for such software. The quickest growth will come from AR/VR Learning Tools, forecast to expand at a CAGR of 8.7% between 2026 and 2032. AR/VR Learning Tools are experiencing rapid growth as they provide immersive learning experiences tailored for diverse learning abilities. Their integration into curricula across more than 100 special education institutions signifies their increasing importance in enhancing educational outcomes. Suppliers should focus on developing EdTech Software while also investing in AR/VR solutions to meet the growing demands of educational institutions.
By Learning Focus – Communication Aid Dominated, Experiential Learning Expected to Grow Fastest
The largest learning focus category in 2025 was Communication Aid, with a 46% share of total revenue. Communication Aid leads in market share as it is essential for enabling effective communication among users with disabilities, a vital aspect of their educational experience. The emphasis on inclusive education, as outlined in the National Education Policy 2020, further drives the demand for these aids. Over 2026–2032, Experiential Learning is expected to post the fastest growth, at a CAGR of 9.6%. Experiential Learning is the fastest-growing focus area, as it promotes hands-on learning experiences that are crucial for engaging students with disabilities. This growth is supported by initiatives like the Samagra Shiksha Abhiyan, which aim to enhance educational access and quality. Buyers should prioritise tools that support experiential learning to improve engagement and educational outcomes for students with special needs.
By Platform Type – Cloud-Based Dominated and Is Expected to Record the Fastest Growth
In 2025, Cloud-Based led the platform type split with a 45% share. Cloud-Based solutions dominate the market share because they offer convenient access to educational resources and tools from any location, making them highly effective for users. The reported 30% increase in demand for cloud-based EdTech solutions in 2023 underscores their critical role in education. The same category is also set to grow fastest, at a CAGR of 8.4% during 2026–2032. The Cloud-Based segment is also the fastest-growing category, as its scalability and flexibility are essential for addressing the diverse requirements of educational institutions. This dual role ensures that cloud solutions remain central to technological advancements in the sector. Suppliers must ensure their cloud-based offerings are robust and adaptable to maintain a competitive edge in the market.
By End User – Schools for Disabled Dominated, EdTech Startups Expected to Grow Fastest
Schools for Disabled accounted for a 36% market share by end user in 2025. Schools for Disabled account for the largest share of the market as they are primary users of special education technology, directly catering to the needs of students with disabilities. The Indian government's initiative to establish 1,000 new special education schools by 2025 will further propel this segment's growth. EdTech Startups are projected to grow fastest, at a CAGR of 9.8% during 2026–2032. EdTech Startups represent the fastest-growing end user group, as they are developing innovative solutions specifically tailored to special education needs. This trend reflects a rising entrepreneurial spirit aimed at addressing the challenges faced by students with disabilities. Suppliers should collaborate with EdTech Startups to explore opportunities for creating advanced solutions that meet the evolving needs of the market.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- India Special Education Technology Market Outlook
- Market Size of India Special Education Technology Market, 2025
- Forecast of India Special Education Technology Market, 2032
- Historical Data and Forecast of India Special Education Technology Revenues & Volume for the Period 2022 - 2032F
- India Special Education Technology Market Trend Evolution
- India Special Education Technology Market Drivers and Challenges
- India Special Education Technology Price Trends
- India Special Education Technology Porter's Five Forces
- India Special Education Technology Industry Life Cycle
- Historical Data and Forecast of India Special Education Technology Market Revenues & Volume By Technology Type for the Period 2022 - 2032F
- Historical Data and Forecast of India Special Education Technology Market Revenues & Volume By AAC Devices for the Period 2022 - 2032F
- Historical Data and Forecast of India Special Education Technology Market Revenues & Volume By EdTech Software for the Period 2022 - 2032F
- Historical Data and Forecast of India Special Education Technology Market Revenues & Volume By AR/VR Learning Tools for the Period 2022 - 2032F
- Historical Data and Forecast of India Special Education Technology Market Revenues & Volume By Adaptive Input Tools for the Period 2022 - 2032F
- Historical Data and Forecast of India Special Education Technology Market Revenues & Volume By Learning Focus for the Period 2022 - 2032F
- Historical Data and Forecast of India Special Education Technology Market Revenues & Volume By Communication Aid for the Period 2022 - 2032F
- Historical Data and Forecast of India Special Education Technology Market Revenues & Volume By Visual/Auditory Learning for the Period 2022 - 2032F
- Historical Data and Forecast of India Special Education Technology Market Revenues & Volume By Experiential Learning for the Period 2022 - 2032F
- Historical Data and Forecast of India Special Education Technology Market Revenues & Volume By Physical Assistance for the Period 2022 - 2032F
- Historical Data and Forecast of India Special Education Technology Market Revenues & Volume By Platform Type for the Period 2022 - 2032F
- Historical Data and Forecast of India Special Education Technology Market Revenues & Volume By Hardware for the Period 2022 - 2032F
- Historical Data and Forecast of India Special Education Technology Market Revenues & Volume By Cloud-Based for the Period 2022 - 2032F
- Historical Data and Forecast of India Special Education Technology Market Revenues & Volume By Wearable/Tablet for the Period 2022 - 2032F
- Historical Data and Forecast of India Special Education Technology Market Revenues & Volume By Touchless/Wireless for the Period 2022 - 2032F
- Historical Data and Forecast of India Special Education Technology Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of India Special Education Technology Market Revenues & Volume By Speech Therapists for the Period 2022 - 2032F
- Historical Data and Forecast of India Special Education Technology Market Revenues & Volume By Schools for Disabled for the Period 2022 - 2032F
- Historical Data and Forecast of India Special Education Technology Market Revenues & Volume By EdTech Startups for the Period 2022 - 2032F
- Historical Data and Forecast of India Special Education Technology Market Revenues & Volume By Special Needs Users for the Period 2022 - 2032F
- India Special Education Technology Import Export Trade Statistics
- Market Opportunity Assessment By Technology Type
- Market Opportunity Assessment By Learning Focus
- Market Opportunity Assessment By Platform Type
- Market Opportunity Assessment By End User
- India Special Education Technology Top Companies Market Share
- India Special Education Technology Competitive Benchmarking By Technical and Operational Parameters
- India Special Education Technology Company Profiles
- India Special Education Technology Key Strategic Recommendations
Market Covered
Segments analysed in this report are listed below.
By Technology Type
- AAC Devices
- EdTech Software
- AR/VR Learning Tools
- Adaptive Input Tools
By Learning Focus
- Communication Aid
- Visual/Auditory Learning
- Experiential Learning
- Physical Assistance
By Platform Type
- Hardware
- Cloud-Based
- Wearable/Tablet
- Touchless/Wireless
By End User
- Speech Therapists
- Schools for Disabled
- EdTech Startups
- Special Needs Users































