India Telecom Revenue Market Size & Growth Rate
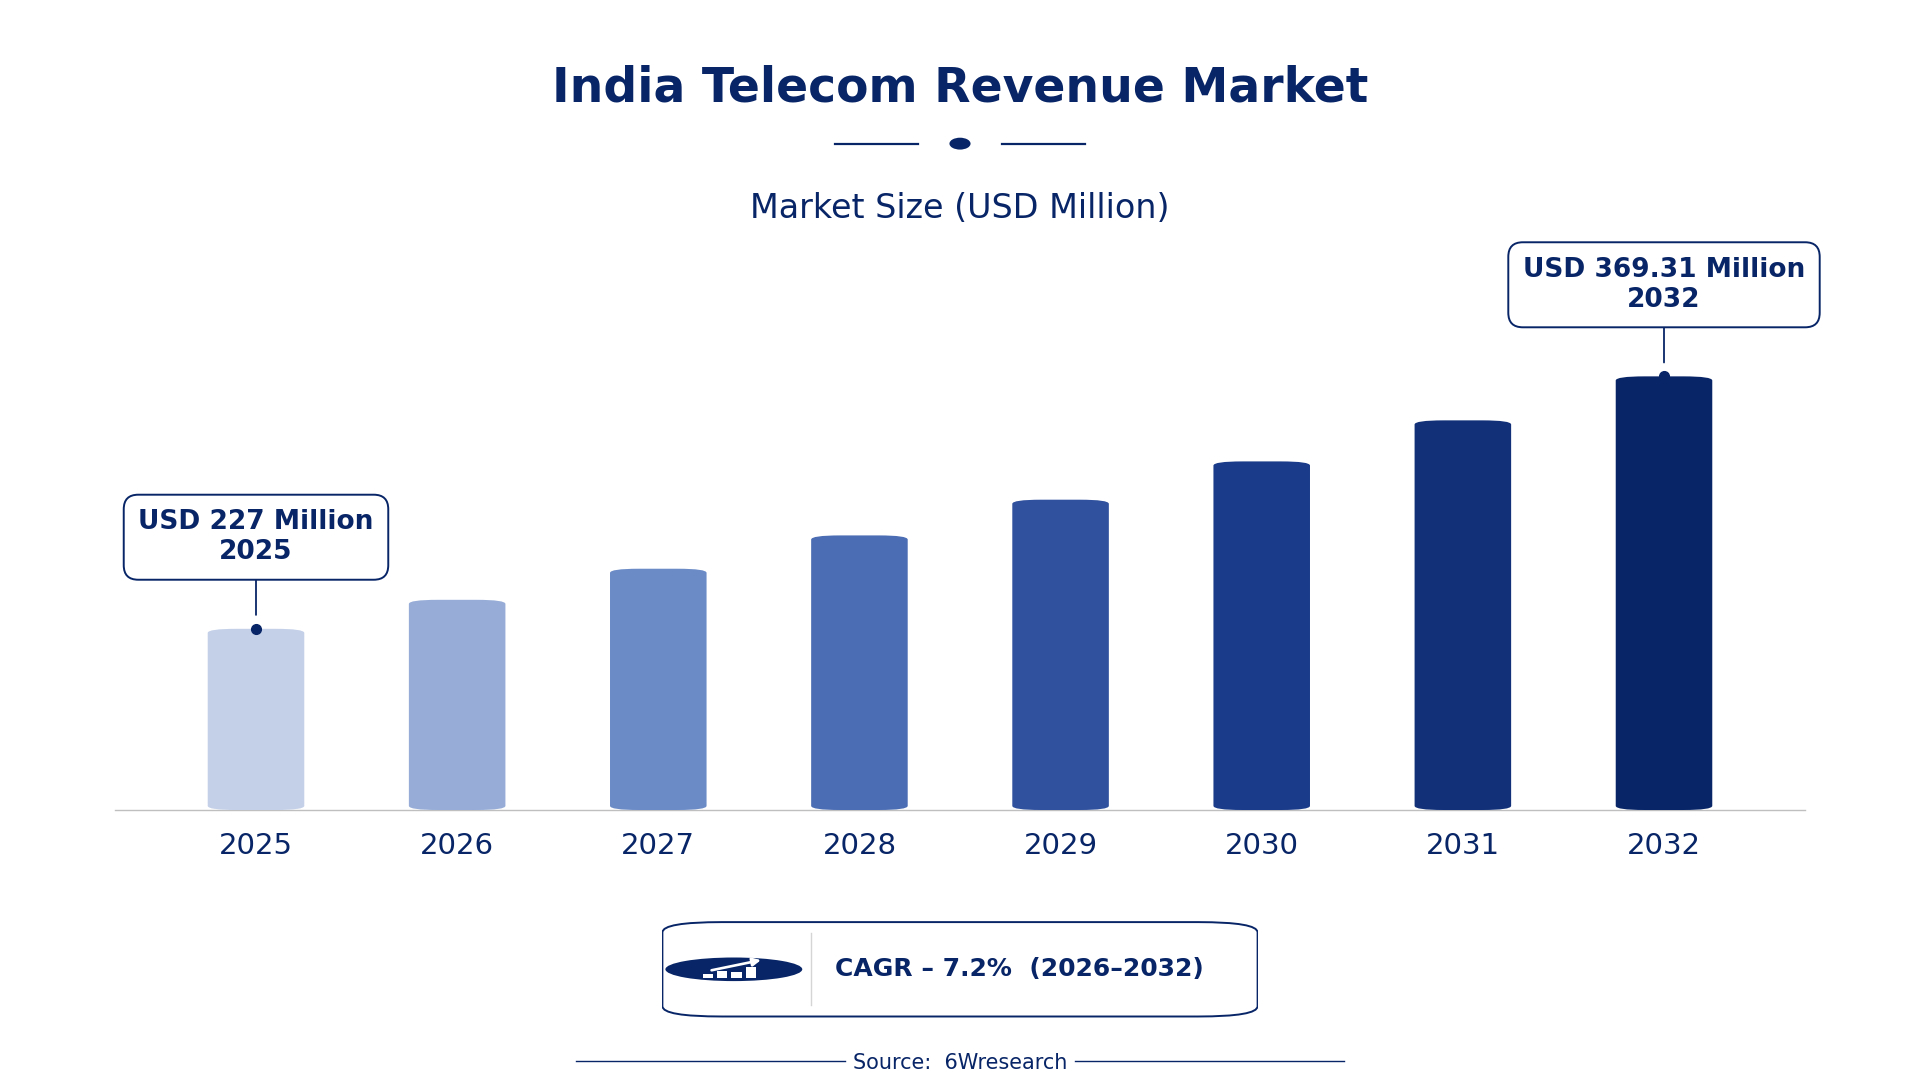
According to 6Wresearch internal database and industry insights, the India Telecom Revenue Market was valued at USD 227.0 million in 2025 and is projected to reach USD 369.31 million by 2032, growing at a CAGR of approximately 7.2% during 2026–2032.
India Telecom Revenue Market Highlights
| Report Metric | Details |
| Report Name | India Telecom Revenue Market |
| Market Size 2025 | USD 227.0 million |
| Market Size 2032 | USD 369.31 million |
| Absolute Growth 2025–2032 | USD 142.31 million |
| CAGR 2026–2032 | 7.2% |
| Peak Annual Growth | 8.8% in 2028 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Telecom Revenue Type, 2025 | Subscription Revenue (42% share) |
| Leading Product Type, 2025 | Mobile/Data Plans (49% share) |
| Leading Revenue Stream, 2025 | Recurring Billing (41% share) |
| Leading Distribution Channel, 2025 | Direct-to-Consumer (44% share) |
| Leading End User Industry, 2025 | CSPs (37% share) |
| Fastest-Growing Telecom Revenue Type | Value-Added Services (9.4% CAGR) |
| Fastest-Growing Product Type | OTT/Cloud Services (8.7% CAGR) |
| Fastest-Growing Revenue Stream | Upselling Streams (9.9% CAGR) |
| Fastest-Growing Distribution Channel | B2B Sales (9.5% CAGR) |
| Fastest-Growing End User Industry | Enterprise Clients (9.6% CAGR) |
| Growing Sector | Enterprise Clients |
| Key End Users | CSPs, Network Providers, Enterprise Clients, Digital Advertisers |
India Telecom Revenue Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
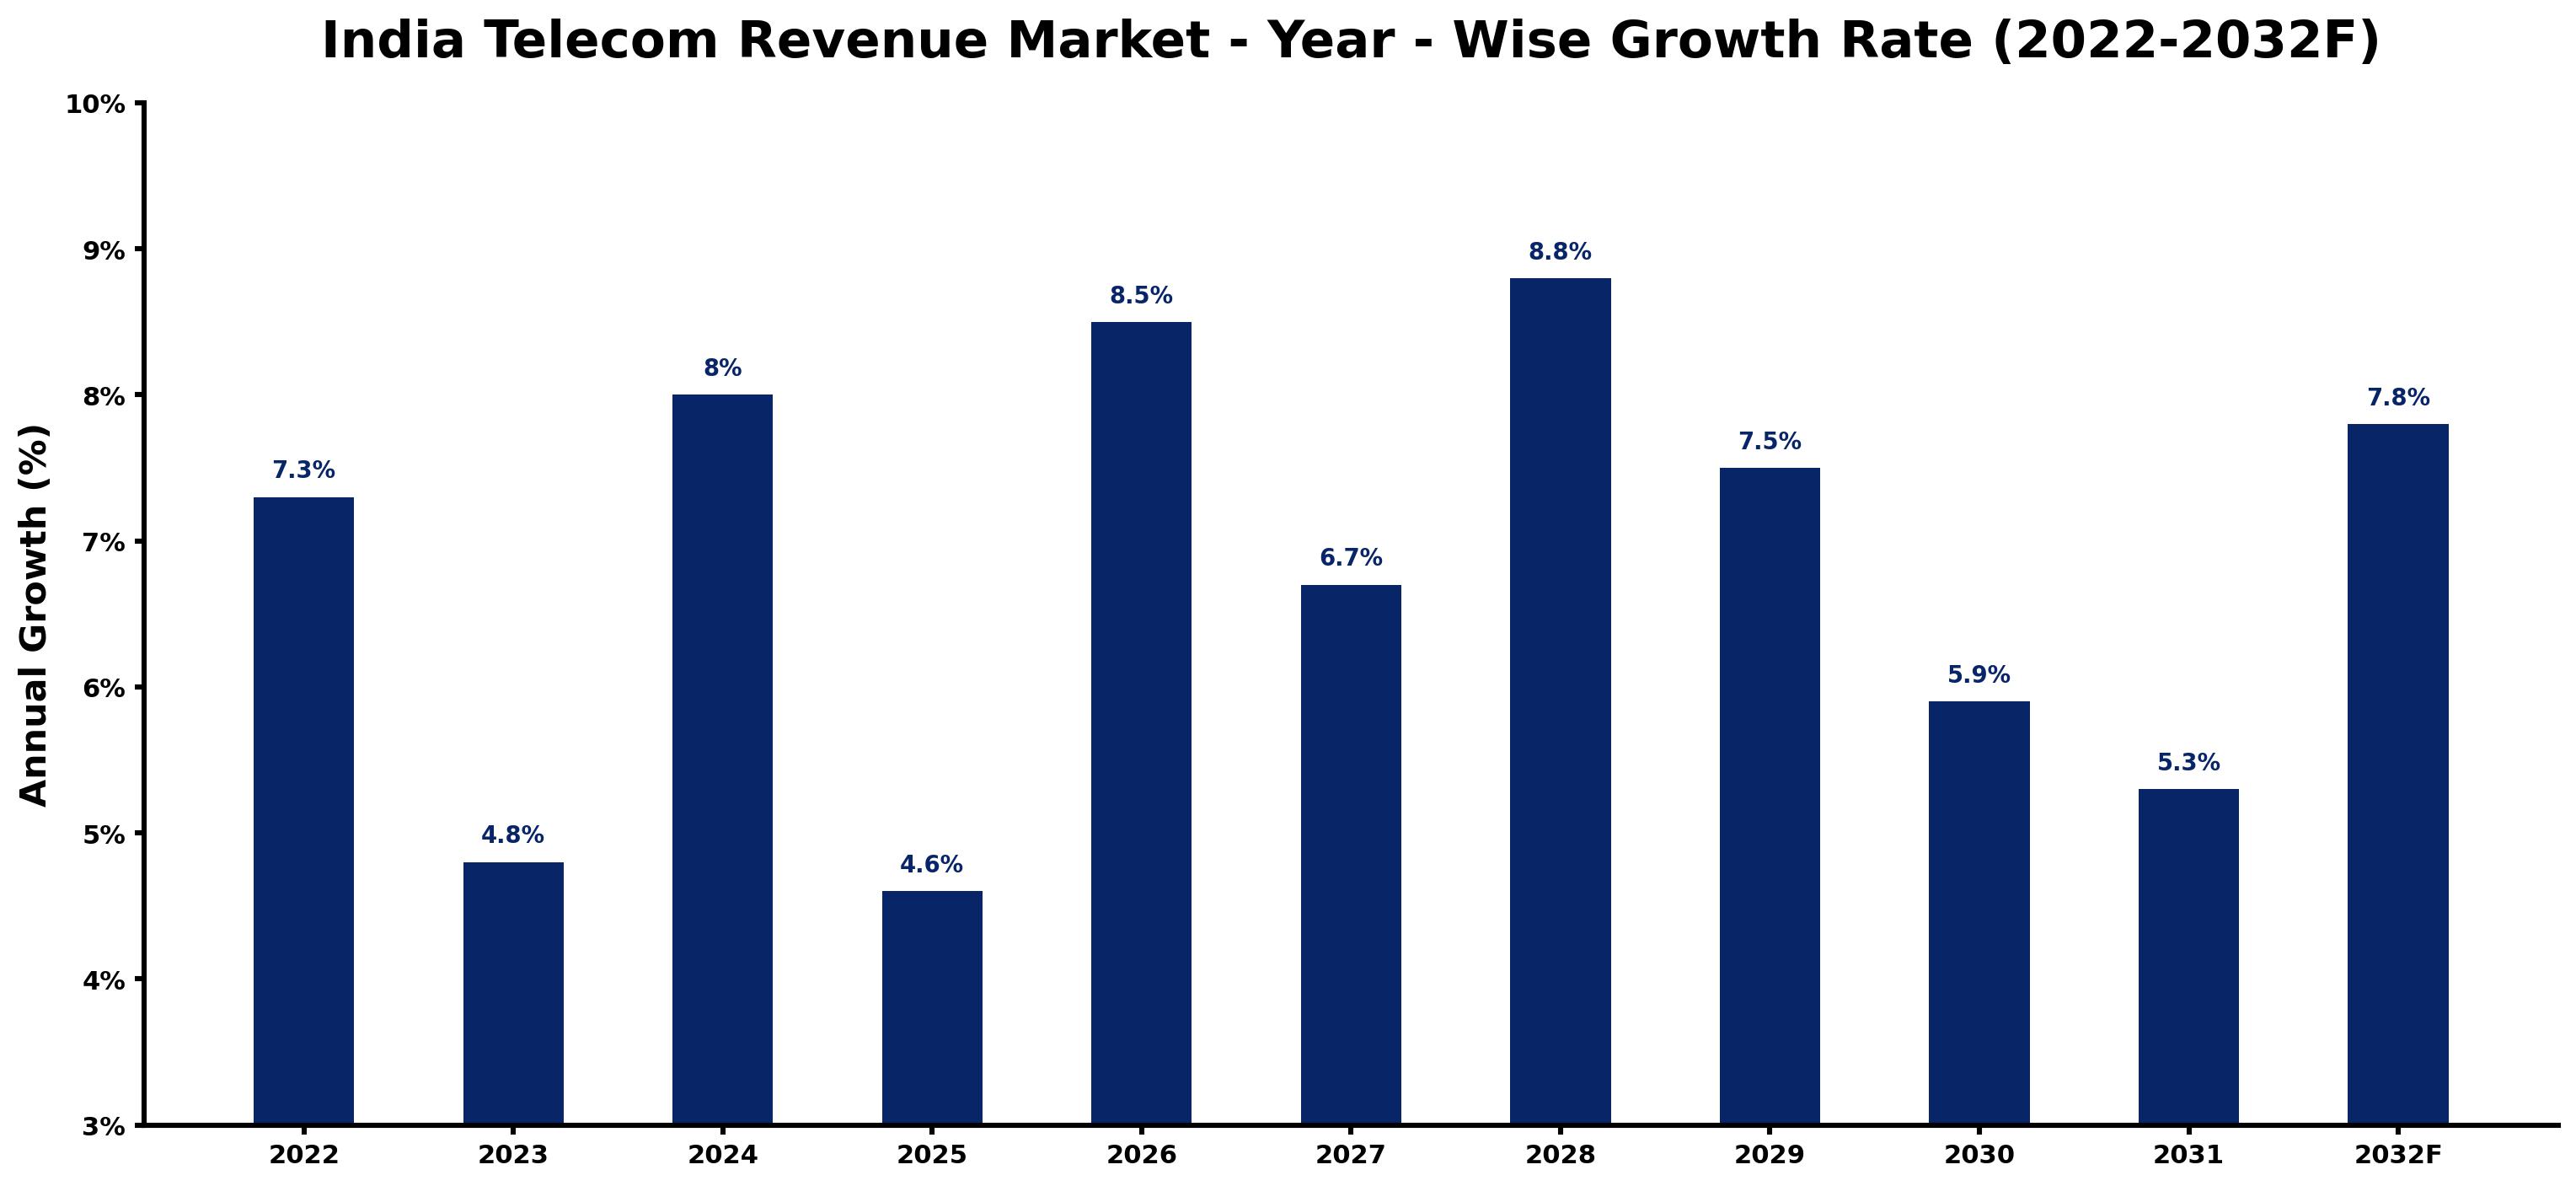
Below, each year's estimated growth is shown next to the factor that most influenced it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 7.3 | The telecom sector contributed approximately 6% to India's GDP, indicating strong market activity. |
| 2023 | 4.8 | Mobile data consumption reached 12 GB per user per month, reflecting a slower growth rate than the previous year. |
| 2024 | 8.0 | The rollout of 5G services across major cities spurred faster growth in the telecom sector. |
| 2025 | 4.6 | A slowdown occurred despite ongoing investments in digital infrastructure and connectivity improvements. |
| 2026 | 8.5 | The National Digital Communications Policy aims to attract $100 billion in investments, boosting growth. |
| 2027 | 6.7 | Growth slowed as the market adjusted to new consumer demands and competitive pressures. |
| 2028 | 8.8 | The peak growth rate was driven by increased demand for mobile and data services. |
| 2029 | 7.5 | As the market stabilises, demand for value-added services is expected to increase. |
| 2030 | 5.9 | Growth is projected to slow as competition among service providers intensifies. |
| 2031 | 5.3 | The market is expected to grow at a slower pace, influenced by evolving consumer preferences. |
| 2032 | 7.8 | A resurgence in growth is anticipated as digital literacy initiatives gain traction across the country. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
India Telecom Revenue Market Synopsis
Telecom Revenue Market in India encompasses the income generated from services provided by telecommunications companies. This includes voice and data services, subscription fees, and value-added services. The market is driven by over 1.2 billion mobile subscribers and increasing smartphone penetration. The telecom sector contributed approximately 6% to India's GDP in 2022, reflecting its significance in the economy. Factors such as the rollout of 5G services and the National Digital Communications Policy are expected to stimulate growth in the coming years.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Growing mobile data consumption drives demand for telecom services. | Driver | High | Mobile/Data Plans |
| Increasing investments in digital infrastructure create opportunities for expansion. | Driver | High | Value-Added Services |
| Rising smartphone penetration presents opportunities for service providers. | Opportunity | High | OTT/Cloud Services |
| The National Broadband Mission aims to enhance connectivity in rural areas. | Opportunity | High | Subscription Revenue |
| Intense competition among service providers can limit profit margins. | Restraint | High | CSPs |
| Regulatory compliance costs can burden smaller operators, affecting their viability. | Restraint | Medium | Network Providers |
| High infrastructure costs can deter new entrants from the market. | Challenge | High | B2B Sales |
| Rapid technological advancements require constant upgrades, straining resources. | Challenge | Medium | Enterprise Clients |
Evaluation of Drivers in India Telecom Revenue Market (2026–2032)
The table below links each growth driver to the segment it affects and the evidence for it.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increasing mobile data consumption drives demand for mobile plans. | Mobile/Data Plans | India's mobile data consumption reached 12 GB per user per month in 2023, prompting users to seek more data services. |
| The National Digital Communications Policy aims to attract investments. | Value-Added Services | This policy aims to improve digital infrastructure, leading to increased demand for value-added telecom services. |
| The rollout of 5G services improves user experience and connectivity. | Subscription Revenue | As 5G services are rolled out, users are likely to subscribe to higher-tier plans for better service. |
| Growing enterprise demand for digital services boosts B2B sales. | B2B Sales | As businesses increasingly rely on digital solutions, telecom providers see rising demand for B2B services. |
| The Telecom Sector Skill Council promotes skill development in the industry. | CSPs | By developing workforce skills, the council supports the growth of service providers in the competitive market. |
Growth in the Telecom Revenue market in India comes from rising investments in digital infrastructure, increasing mobile data consumption, and the rollout of 5G services. India's mobile data consumption reached 12 GB per user per month in 2023, leading to higher demand for mobile plans. As businesses seek digital solutions, demand for B2B services is rising. The rollout of 5G services is expected to improve user experience, prompting users to subscribe to higher-tier plans. The Telecom Sector Skill Council is also promoting skill development, further supporting the growth of service providers in this competitive market.
Evaluation of Restraints in India Telecom Revenue Market
Below mentioned are some major restraints and their influence on market dynamics.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Intense competition among service providers can limit profit margins. | CSPs | With numerous players in the market, price wars can erode profitability for service providers. |
| Regulatory compliance costs can burden smaller operators. | Network Providers | Smaller operators may struggle with the costs associated with meeting regulatory requirements. |
| High infrastructure costs deter new entrants from the market. | B2B Sales | The investment required for infrastructure can prevent new companies from entering the telecom sector. |
| Rapid technological advancements require constant upgrades. | Enterprise Clients | Companies must invest continuously in technology to remain competitive, straining financial resources. |
| Consumer preferences shift rapidly, making it hard to predict demand. | Value-Added Services | Providers may struggle to keep up with changing consumer expectations, impacting service offerings. |
India Telecom Revenue Market Challenges
Producers in the India Telecom Revenue Market struggle with a skills shortage that hampers service delivery efficiency. This issue stems from a lack of adequate training programmes, leading to project delays that can cost firms up to 20% in potential revenue. Distributors face rising compliance costs due to stringent regulations from the Telecom Regulatory Authority of India, inflating operational expenses by 15%. Buyers are frustrated by the slow rollout of 5G technology, as infrastructure delays can restrict access to advanced services, negatively impacting user satisfaction and retention.
Trends in the India Telecom Revenue Market
Below mentioned are some of the trends shaping the India Telecom Revenue Market growth.
- Shift Towards 5G Services: India is experiencing a shift towards 5G services as major cities begin to roll out this technology. As of 2023, 5G services are being deployed, improving connectivity and user experience for over 1.2 billion mobile subscribers.
- Increase in OTT/Cloud Services: OTT and cloud services are gaining traction in India, with a projected growth rate of 8.7% from 2026 to 2032. This trend reflects the increasing demand for digital content and services among consumers.
- Expansion of Digital Literacy Initiatives: The National Digital Mission aims to improve digital literacy across India by 2025. This initiative supports the growing need for telecom services as more users become digitally literate.
- Rural Connectivity Enhancement: The Telecom Infrastructure Policy 2021 focuses on improving telecom services in rural areas. This policy aims for 100% connectivity, which is important for expanding the telecom market in underserved regions.
Investment Opportunities in the India Telecom Revenue Market
Some of the investment opportunities in the India Telecom Revenue Market are mentioned below.
- Growing Demand for Digital Services: With over 1.2 billion mobile subscribers, telecom providers have the chance to broaden their digital service offerings. The National Broadband Mission aims to ensure broadband access to all villages by 2024.
- Investment in Value-Added Services: The rising consumer demand for enhanced services presents an opportunity for telecom operators to invest in value-added services. This sector is expected to grow as users seek more from their providers.
- Partnerships for Improved Offerings: Telecom operators can explore partnerships to enhance their service offerings. Collaborating with tech firms can improve service delivery and customer satisfaction.
- Focus on B2B Services: As businesses increasingly rely on digital solutions, there is a growing demand for B2B telecom services. This sector is projected to expand as companies seek reliable connectivity and digital services.
Government Initiatives in the India Telecom Revenue Market
The National Digital Communications Policy 2020, by the Department of Telecommunications, aims to attract $100 billion in investments by 2024 to improve digital infrastructure. This policy encourages telecom operators to innovate and expand their service offerings, ultimately benefiting consumers with improved connectivity and services. Additionally, the Telecom Infrastructure Policy 2021 focuses on improving telecom services in rural areas, ensuring 100% connectivity and addressing the digital divide in India.
The Telecom Sector Skill Council, established by the Ministry of Skill Development and Entrepreneurship in 2020, promotes skill development in the telecom industry. This initiative helps ensure that the workforce is equipped with the necessary skills to meet the demands of a rapidly evolving sector. Furthermore, the National Broadband Mission, launched in 2020, aims to provide broadband access to all villages in India by 2024, improving connectivity and supporting the growth of the telecom market.
Future Insight of the India Telecom Revenue Market
The India Telecom Revenue Market will evolve significantly by 2032, driven by the National Digital Communications Policy, which aims to attract $100 billion in investments. The rollout of 5G services will increase mobile data consumption, projected to reach 12 GB per user per month, enabling richer digital experiences. The National Broadband Mission will ensure broadband access to all villages by 2024, expanding market reach for service providers. The Digital India initiative will boost digital literacy, encouraging greater adoption of telecom services across diverse demographics.
Market Segmentation Analysis
Each segment group is reviewed below, with the leader by share and the fastest grower by CAGR.
By Telecom Revenue Type – Subscription Revenue Dominated, Value-Added Services Expected to Grow Fastest
According to Sumit Sagar, AM at 6Wresearch, Subscription Revenue accounted for a 42% market share by telecom revenue type in 2025. Subscription revenue holds the largest market share in India as it is the primary source of income for telecom operators, driven by over 1.2 billion mobile subscribers relying on consistent voice and data services. This model ensures a steady cash flow, as users are accustomed to regular payments for their connectivity needs. The quickest growth will come from Value-Added Services, forecast to expand at a CAGR of 9.4% between 2026 and 2032. Value-added services are experiencing rapid growth as telecom operators enhance user experiences with features like premium content and personalised plans. With mobile data consumption reaching 12 GB per user per month in 2023, the demand for these supplementary services is clearly on the rise, indicating a shift in consumer preferences. Suppliers should prioritise the enhancement of subscription offerings while exploring innovative value-added services to attract the expanding consumer base.
By Product Type – Mobile/Data Plans Dominated, OTT/Cloud Services Expected to Grow Fastest
The largest product type category in 2025 was Mobile/Data Plans, with a 49% share of total revenue. Mobile and data plans dominate the market share as they are essential for consumers seeking reliable connectivity in the telecom sector. The ongoing rollout of 5G services further solidifies the importance of these plans for users demanding high-speed internet access, ensuring their continued relevance. Over 2026–2032, OTT/Cloud Services are expected to post the fastest growth, at a CAGR of 8.7%. OTT and cloud services are rapidly gaining traction as consumers and businesses seek flexible communication solutions. The increasing smartphone penetration in India supports this trend, making these services more accessible to a wider audience, thus driving their growth. Providers must focus on developing robust mobile and data plans while also expanding their OTT and cloud service offerings to meet the evolving needs of consumers.
By Revenue Stream – Recurring Billing Dominated, Upselling Streams Expected to Grow Fastest
With a 41% revenue share in 2025, Recurring Billing was the largest revenue stream category. Recurring billing is the primary revenue stream, aligning seamlessly with subscription services that consumers regularly utilise. This model ensures predictable cash flow for telecom companies, capitalising on India's vast subscriber base and their ongoing demand for connectivity services. Upselling Streams are projected to grow fastest, at a CAGR of 9.9% during 2026–2032. Upselling streams are gaining traction as telecom operators aim to maximise revenue from existing customers by offering additional services. This strategy is becoming increasingly vital as competition intensifies in the telecom sector, pushing companies to enhance customer lifetime value and drive profitability. Telecom companies should refine their upselling strategies while maintaining strong recurring billing practices to optimise revenue generation.
By Distribution Channel – Direct-to-Consumer Dominated, B2B Sales Expected to Grow Fastest
Direct-to-Consumer took a 44% share of distribution channel in 2025, more than any other category. Direct-to-consumer channels capture the largest market share, allowing telecom companies to engage directly with end users for tailored services and immediate feedback. This approach is crucial in a competitive landscape where customer experience is a top priority, ensuring customer loyalty and satisfaction. B2B Sales is set to record the highest CAGR in this split, 9.5% over 2026–2032. B2B sales are rapidly expanding as telecom companies increasingly target enterprise clients, recognising the potential for substantial contracts and long-term partnerships. This shift aligns with the broader trend of digital transformation among businesses seeking reliable communication solutions, thus accelerating growth in this segment. Telecom providers should enhance their direct-to-consumer strategies while also developing targeted offerings for B2B clients to diversify their revenue streams.
By End User Industry – CSPs Dominated, Enterprise Clients Expected to Grow Fastest
In 2025, CSPs led the end user industry split with a 37% share. Communications service providers (CSPs) dominate the revenue share as they are the primary entities delivering essential telecom services to India's vast population. Their established infrastructure and extensive customer base ensure a steady revenue flow from various service offerings, making them pivotal players in the market. The quickest growth will come from Enterprise Clients, forecast to expand at a CAGR of 9.6% between 2026 and 2032. Enterprise clients are emerging as the fastest-growing segment, driven by the increasing demand for robust communication solutions in the business sector. This growth is supported by initiatives like the National Digital Mission, which aims to improve digital literacy and connectivity for enterprises, highlighting the potential for CSPs in this area. CSPs should focus on catering to enterprise clients while continuing to strengthen their offerings for individual consumers to maintain a balanced revenue portfolio.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- India Telecom Revenue Market Outlook
- Market Size of India Telecom Revenue Market, 2025
- Forecast of India Telecom Revenue Market, 2032
- Historical Data and Forecast of India Telecom Revenue Revenues & Volume for the Period 2022 - 2032F
- India Telecom Revenue Market Trend Evolution
- India Telecom Revenue Market Drivers and Challenges
- India Telecom Revenue Price Trends
- India Telecom Revenue Porter's Five Forces
- India Telecom Revenue Industry Life Cycle
- Historical Data and Forecast of India Telecom Revenue Market Revenues & Volume By Telecom Revenue Type for the Period 2022 - 2032F
- Historical Data and Forecast of India Telecom Revenue Market Revenues & Volume By Subscription Revenue for the Period 2022 - 2032F
- Historical Data and Forecast of India Telecom Revenue Market Revenues & Volume By Roaming Revenue for the Period 2022 - 2032F
- Historical Data and Forecast of India Telecom Revenue Market Revenues & Volume By Value-Added Services for the Period 2022 - 2032F
- Historical Data and Forecast of India Telecom Revenue Market Revenues & Volume By Advertising Revenue for the Period 2022 - 2032F
- Historical Data and Forecast of India Telecom Revenue Market Revenues & Volume By Product Type for the Period 2022 - 2032F
- Historical Data and Forecast of India Telecom Revenue Market Revenues & Volume By Mobile/Data Plans for the Period 2022 - 2032F
- Historical Data and Forecast of India Telecom Revenue Market Revenues & Volume By Global Usage Fees for the Period 2022 - 2032F
- Historical Data and Forecast of India Telecom Revenue Market Revenues & Volume By OTT/Cloud Services for the Period 2022 - 2032F
- Historical Data and Forecast of India Telecom Revenue Market Revenues & Volume By Targeted Ads for the Period 2022 - 2032F
- Historical Data and Forecast of India Telecom Revenue Market Revenues & Volume By Revenue Stream for the Period 2022 - 2032F
- Historical Data and Forecast of India Telecom Revenue Market Revenues & Volume By Recurring Billing for the Period 2022 - 2032F
- Historical Data and Forecast of India Telecom Revenue Market Revenues & Volume By Inter-Operator for the Period 2022 - 2032F
- Historical Data and Forecast of India Telecom Revenue Market Revenues & Volume By Upselling Streams for the Period 2022 - 2032F
- Historical Data and Forecast of India Telecom Revenue Market Revenues & Volume By Telecom Media for the Period 2022 - 2032F
- Historical Data and Forecast of India Telecom Revenue Market Revenues & Volume By Distribution Channel for the Period 2022 - 2032F
- Historical Data and Forecast of India Telecom Revenue Market Revenues & Volume By Direct-to-Consumer for the Period 2022 - 2032F
- Historical Data and Forecast of India Telecom Revenue Market Revenues & Volume By Partnerships for the Period 2022 - 2032F
- Historical Data and Forecast of India Telecom Revenue Market Revenues & Volume By B2B Sales for the Period 2022 - 2032F
- Historical Data and Forecast of India Telecom Revenue Market Revenues & Volume By Mobile Portals for the Period 2022 - 2032F
- Historical Data and Forecast of India Telecom Revenue Market Revenues & Volume By End User Industry for the Period 2022 - 2032F
- Historical Data and Forecast of India Telecom Revenue Market Revenues & Volume By CSPs for the Period 2022 - 2032F
- Historical Data and Forecast of India Telecom Revenue Market Revenues & Volume By Network Providers for the Period 2022 - 2032F
- Historical Data and Forecast of India Telecom Revenue Market Revenues & Volume By Enterprise Clients for the Period 2022 - 2032F
- Historical Data and Forecast of India Telecom Revenue Market Revenues & Volume By Digital Advertisers for the Period 2022 - 2032F
- India Telecom Revenue Import Export Trade Statistics
- Market Opportunity Assessment By Telecom Revenue Type
- Market Opportunity Assessment By Product Type
- Market Opportunity Assessment By Revenue Stream
- Market Opportunity Assessment By Distribution Channel
- Market Opportunity Assessment By End User Industry
- India Telecom Revenue Top Companies Market Share
- India Telecom Revenue Competitive Benchmarking By Technical and Operational Parameters
- India Telecom Revenue Company Profiles
- India Telecom Revenue Key Strategic Recommendations
Market Covered
Segments analysed in this report are listed below.
By Telecom Revenue Type
- Subscription Revenue
- Roaming Revenue
- Value-Added Services
- Advertising Revenue
By Product Type
- Mobile/Data Plans
- Global Usage Fees
- OTT/Cloud Services
- Targeted Ads
By Revenue Stream
- Recurring Billing
- Inter-Operator
- Upselling Streams
- Telecom Media
By Distribution Channel
- Direct-to-Consumer
- Partnerships
- B2B Sales
- Mobile Portals
By End User Industry
- CSPs
- Network Providers
- Enterprise Clients
- Digital Advertisers































