Japan Medical Insurance Market Size & Growth Rate
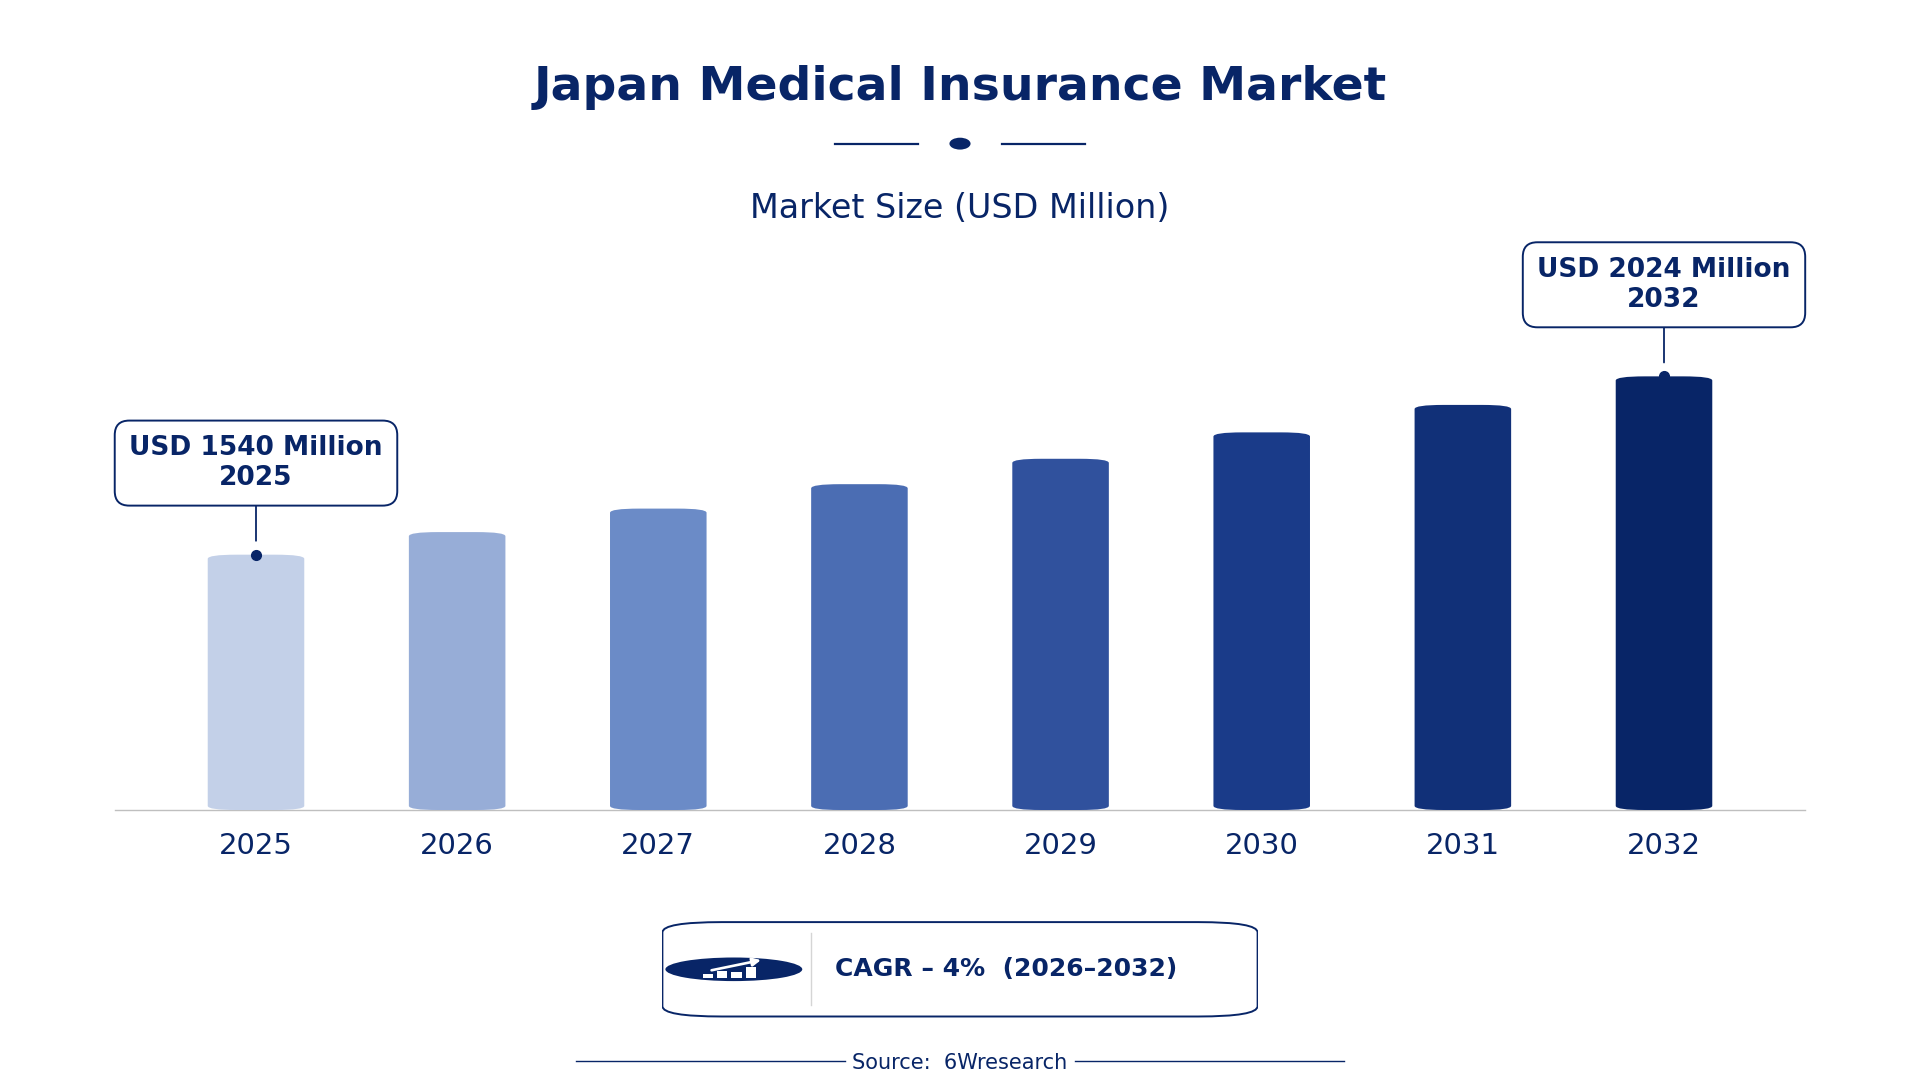
According to 6Wresearch internal database and industry insights, the Japan Medical Insurance Market was valued at USD 1,540 Million in 2025 and is projected to reach USD 2,024 Million by 2032, growing at a CAGR of approximately 4% during 2026–2032.
Japan Medical Insurance Market Highlights
| Report Metric | Details |
| Report Name | Japan Medical Insurance Market (2026-2032) |
| Market Size 2025 | USD 1,540 Million |
| Market Size 2032 | USD 2,024 Million |
| Absolute Growth 2025–2032 | USD 484 Million |
| CAGR 2026–2032 | 4% |
| Peak Annual Growth | 5.3% in 2032 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Type, 2025 | Products (60% share) |
| Leading Services, 2025 | Inpatient Treatment (42% share) |
| Leading Level of Coverage, 2025 | Gold (40% share) |
| Leading Service Providers, 2025 | Public Health Insurance Providers (63% share) |
| Leading Health Insurance Plans, 2025 | Health Maintenance Organization (HMO) (44% share) |
| Fastest-Growing Type | Solutions (5.5% CAGR) |
| Fastest-Growing Services | Outpatient Treatment (5.3% CAGR) |
| Fastest-Growing Level of Coverage | Silver (5.6% CAGR) |
| Fastest-Growing Service Providers | Private Health Insurance Providers (5.2% CAGR) |
| Growing Sector | Healthcare Services |
| Key End Users | Individuals, Employers, Healthcare Providers |
Japan Medical Insurance Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
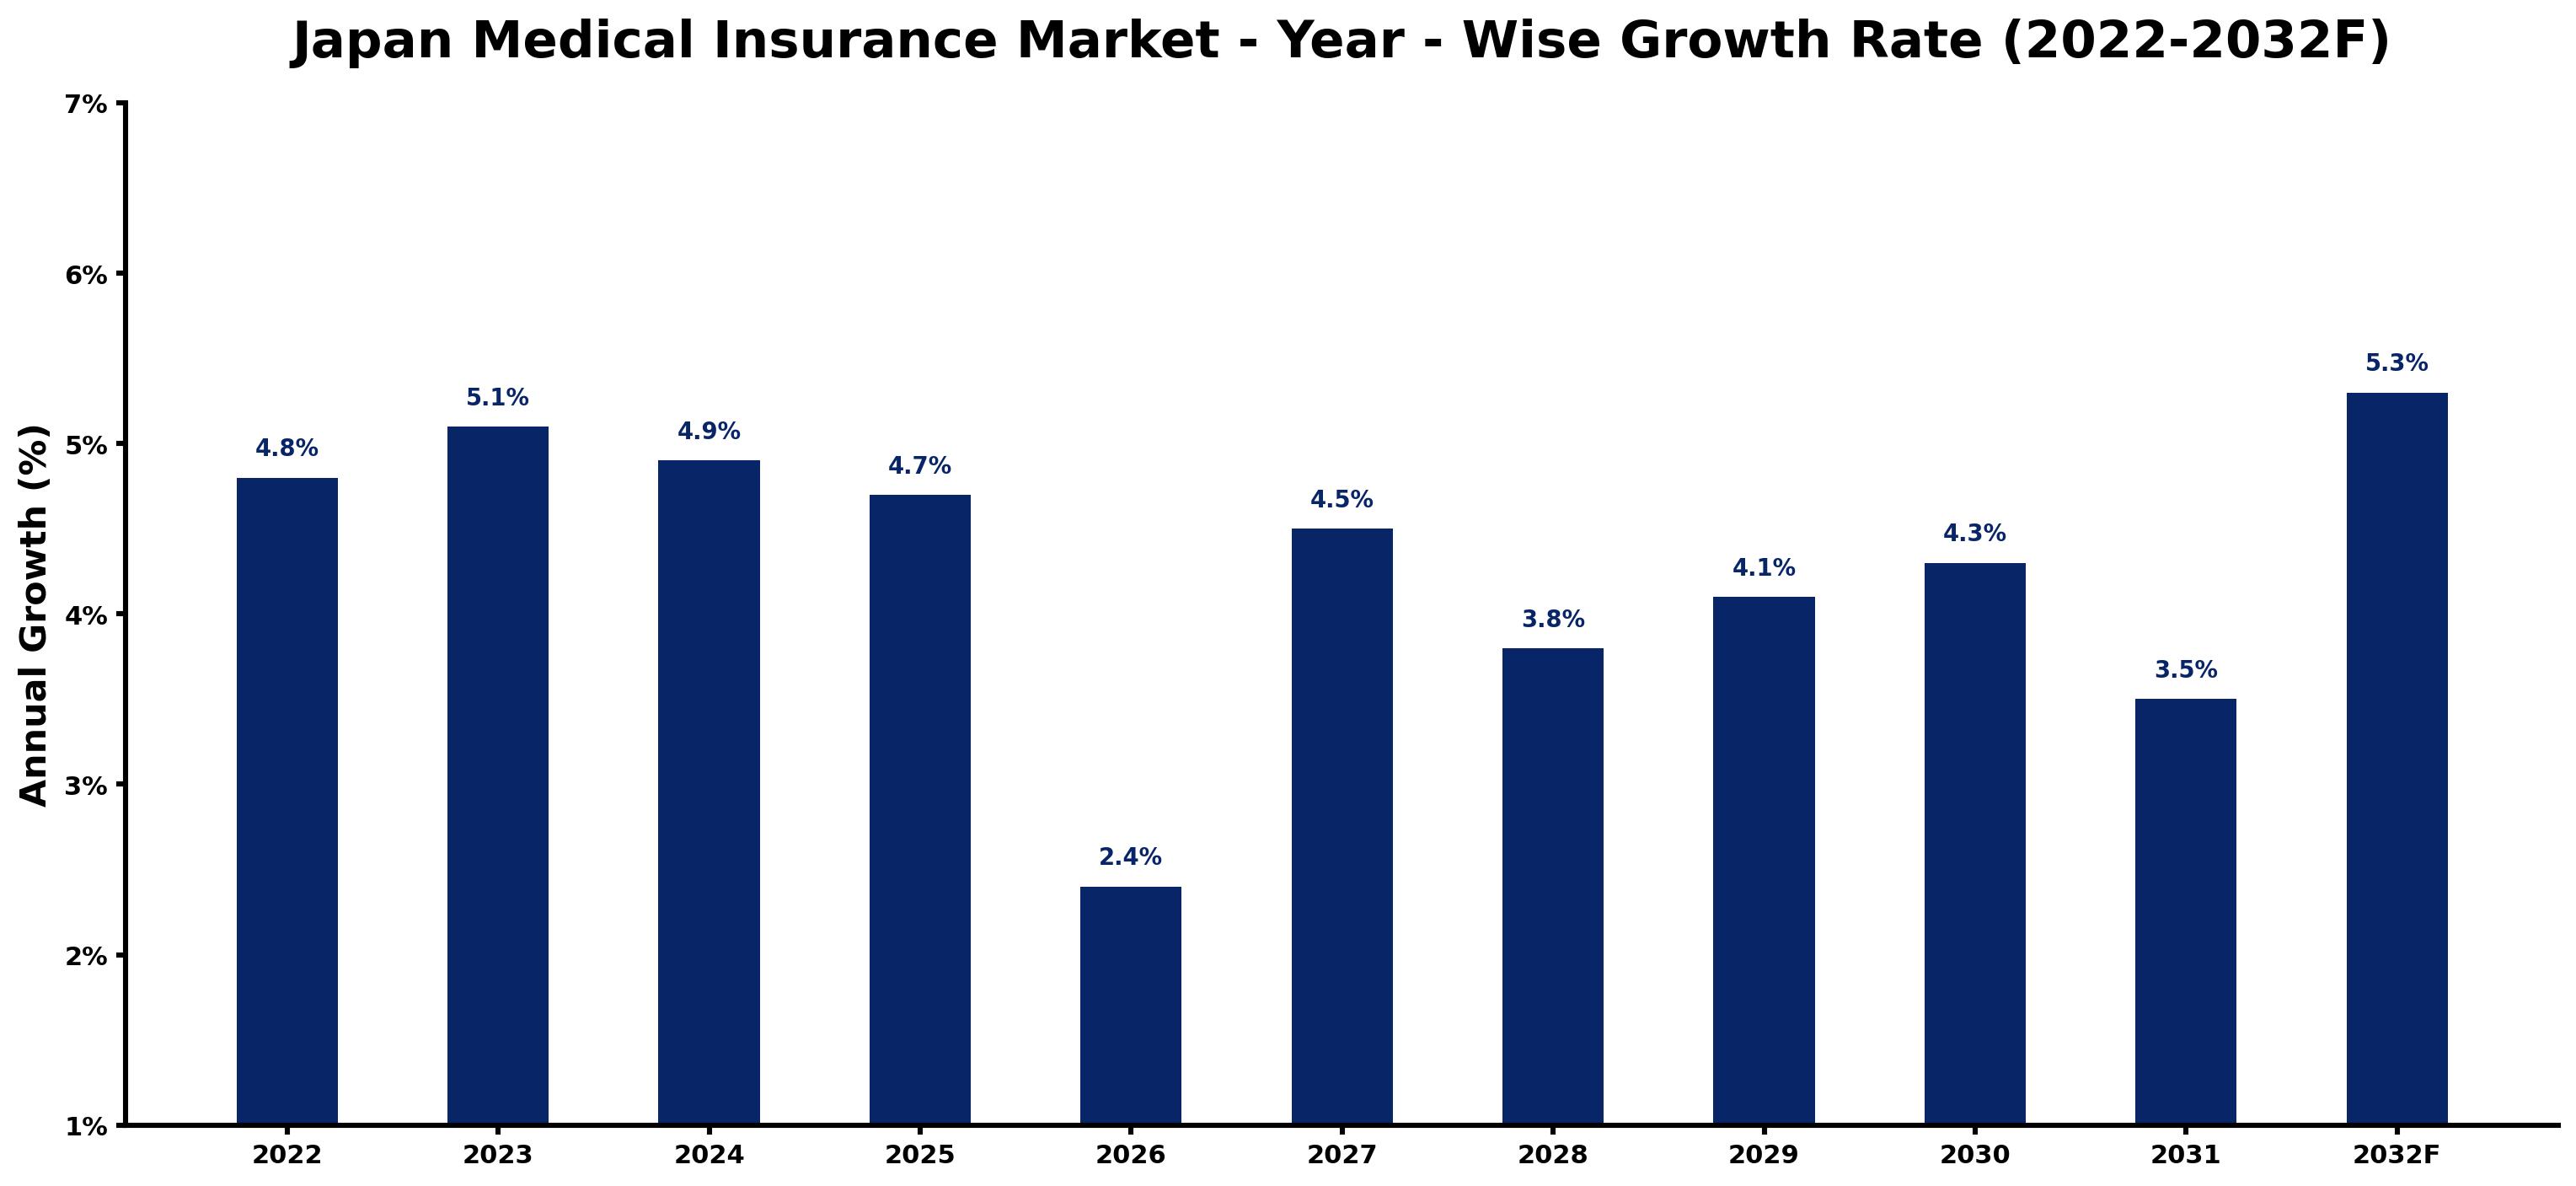
Each row of the following table gives one year's estimated growth and the event or demand shift that explains it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 4.8 | The market showed solid growth due to increased healthcare awareness among the population. |
| 2023 | 5.1 | Growth accelerated as Japan's aging population increased demand for medical services. |
| 2024 | 4.9 | The market experienced a slowdown as premium costs began to rise. |
| 2025 | 4.7 | Continued growth was noted, driven by the expansion of outpatient services. |
| 2026 | 2.4 | A slowdown occurred as the market is expected to adjust to changing healthcare policies. |
| 2027 | 4.5 | Demand is projected to rebound with rising investments in healthcare infrastructure. |
| 2028 | 3.8 | Growth is anticipated to slow as insurance providers face increased operational costs. |
| 2029 | 4.1 | The market is expected to pick up again as preventive care initiatives gain traction. |
| 2030 | 4.3 | Growth will continue with the introduction of new health insurance plans. |
| 2031 | 3.5 | A slowdown is projected as competition intensifies among providers. |
| 2032 | 5.3 | The market is expected to peak as diverse coverage options become more popular. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
Japan Medical Insurance Market Synopsis
Medical insurance in Japan provides financial coverage for healthcare services, funded through premiums and government support. The Japan Medical Insurance Market is expanding due to a growing aging population, with 29.3% aged 65 or older, and rising healthcare expenditures, which reached JPY 46.7 trillion in fiscal 2022. Demand is further driven by the expansion of outpatient services and government initiatives to improve telemedicine, creating new opportunities for health insurance providers.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Aging population driving demand for comprehensive coverage | Driver | High | Health Maintenance Organization (HMO) |
| Government initiatives to improve healthcare access | Driver | High | Public Health Insurance Providers |
| Growing demand for outpatient services | Opportunity | Medium | Outpatient Treatment |
| Expansion of telemedicine services | Opportunity | High | Health Maintenance Organization (HMO) |
| Rising healthcare costs impacting affordability | Restraint | High | Gold |
| Limited awareness of available insurance options | Restraint | Medium | Silver |
| Intense competition among insurance providers | Challenge | High | Private Health Insurance Providers |
| Regulatory changes affecting premium structures | Challenge | Medium | Public Health Insurance Providers |
Evaluation of Drivers in Japan Medical Insurance Market (2026–2032)
Below are the drivers that matter most for revenue growth, with supporting evidence.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increasing healthcare expenditure | Inpatient Treatment | Japan's national medical care expenditure was about JPY 46.7 trillion in fiscal 2022, leading to higher demand for inpatient services. |
| Aging population | Health Maintenance Organization (HMO) | With 29.3% of the population aged 65 or older, there is a greater need for health coverage. |
| Government support for preventive care | Silver | The government promotes preventive care through health insurance incentives, increasing the uptake of health plans. |
| Expansion of outpatient services | Outpatient Treatment | The average annual healthcare expenditure per capita is approximately 500,000 JPY, driving demand for outpatient care. |
| Telemedicine adoption | Health Maintenance Organization (HMO) | In 2023, the government initiated a program to improve telemedicine services, increasing demand for flexible health plans. |
Spending rises because healthcare expenditure in Japan reached JPY 46.7 trillion in fiscal 2022, driving demand for various medical services. The aging population increases the need for health coverage, with a notable portion of the population over 65 years old. In 2023, the introduction of telemedicine services has further expanded access to healthcare, boosting demand for Health Maintenance Organizations. Outpatient services have gained traction, with average healthcare spending per capita at approximately 500,000 JPY, encouraging more patients to seek timely medical attention.
Evaluation of Restraints in Japan Medical Insurance Market
The following restraints limit how fast demand can grow.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Rising healthcare costs affecting affordability | Gold | The average premium for health insurance was around 30,000 JPY per month, making it less affordable for some individuals. |
| Limited awareness of insurance options | Silver | A considerable portion of the population lacks knowledge about the benefits of various insurance plans, resulting in underutilisation. |
| Regulatory changes impacting premium structures | Public Health Insurance Providers | Changes in regulations can create uncertainties in premium pricing, which may affect consumer decisions. |
| Intense competition among providers | Private Health Insurance Providers | Competition can lead to aggressive pricing strategies, which may reduce profit margins for providers. |
| Operational costs increasing for providers | Health Maintenance Organization (HMO) | Rising costs associated with healthcare delivery can strain HMO budgets, affecting service quality. |
Japan Medical Insurance Market Challenges
In 2023, hospitals face escalating operational expenses, with average monthly premiums at 30,000 JPY, squeezing budgets for families. Increased competition among healthcare providers leads to service quality deterioration, impacting patient satisfaction. Clinics encounter a shortage of skilled healthcare professionals, resulting in longer wait times for patients and increasing reliance on temporary staff, which raises operational costs for providers. Regulatory changes from the Ministry of Health, Labour and Welfare impose compliance costs that complicate insurance offerings, ultimately raising premiums for consumers.
Trends in the Japan Medical Insurance Market
The following changes are redrawing the Japan Medical Insurance Market.
- Shift towards Telemedicine: Healthcare providers are increasingly adopting telemedicine services, with the government launching a program in 2023 to improve these services, expanding access for patients.
- Growing Preference for Outpatient Care: Outpatient treatment has gained popularity, with a CAGR of 5.3% anticipated from 2026 to 2032, reflecting a shift in patient preferences towards less invasive care.
- Increased Adoption of Silver Plans: Silver plans are becoming more popular among middle-income families, with a projected CAGR of 5.6%, driven by government incentives for preventive care.
- Expansion of Health Maintenance Organizations: Health Maintenance Organizations (HMOs) are increasingly preferred, with a CAGR of 5.9%, as they offer extensive coverage and flexibility in provider choice.
Investment Opportunities in the Japan Medical Insurance Market
Several openings in the Japan Medical Insurance Market merit attention from investors.
- Public Health Insurance Providers: Public health insurance providers can expand their offerings to include telemedicine services, tapping into the growing demand for remote healthcare solutions, with a potential market of 1 trillion JPY allocated for healthcare improvements.
- Health Maintenance Organization (HMO): Investing in Health Maintenance Organizations (HMOs) can meet the rising demand for health coverage, particularly in urban areas like Tokyo, where healthcare facilities are concentrated.
- Outpatient Treatment Services: There is an opportunity to invest in outpatient treatment services, as demand is increasing due to rising healthcare expenditures, particularly in metropolitan regions.
- Silver Plans for Middle-Income Families: Developing tailored Silver plans can cater to middle-income families, who are increasingly seeking affordable yet extensive coverage options.
Government Initiatives in the Japan Medical Insurance Market
The Medical Care Act of 1948 established standards for hospitals and clinics, ensuring that public health insurance covers about 90% of the population. The Next-Generation Medical Infrastructure Act of 2017 allows for the anonymisation of medical data to support research and development, which directly impacts the medical insurance sector by improving data-driven decision-making for providers and insurers.
The Pharmaceuticals and Medical Devices Agency (PMDA) reviews pharmaceuticals and medical devices, ensuring safety and efficacy. The Japan Agency for Medical Research and Development (AMED) funds medical research and development initiatives, contributing to healthcare improvements and innovations that benefit medical insurance providers and their clients.
Future Insight of the Japan Medical Insurance Market
By 2032, the healthcare investment pipeline will reach 1 trillion JPY, generating demand for new services and technologies. The expansion of telemedicine will improve access to care, particularly for rural populations, enabling buyers to receive treatment remotely. New standards like ISO 9001 will drive quality improvements across health insurance providers, benefiting consumers. The government's focus on preventive care will reshape insurance models, encouraging healthier lifestyles and reducing long-term expenses for both buyers and suppliers.
Market Segmentation Analysis
Japan Medical Insurance Market report covers a detailed analysis of the following market segments:
By Type – Products Lead, Solutions Expected to Grow Fastest
According to Shubham Padhi, Research Analyst at 6Wresearch, Products held 60% of the Japan Medical Insurance Market by type in 2025. Products dominate the market as they are essential for providing healthcare coverage to a large portion of the population. With public health insurance covering around 90% of individuals, the demand for these products remains robust. The quickest growth will come from Solutions, forecast to expand at a CAGR of 5.5% between 2026 and 2032. Solutions are rapidly gaining traction due to the increasing complexity of managing insurance plans. The government's initiative to enhance telemedicine services illustrates the rising necessity for efficient solutions in the insurance sector. Suppliers should prioritise the development of effective products to address the growing demand for healthcare coverage.
By Services – Inpatient Treatment Leads, Outpatient Treatment Expected to Grow Fastest
Inpatient Treatment accounted for 42% of the market by services in 2025. Inpatient Treatment leads this segment as it is a primary service covered by medical insurance, addressing critical healthcare needs. The high number of hospitals, approximately 8,100, supports the prevalence of inpatient services across the country. Outpatient Treatment is set to record the highest CAGR in this split, 5.3% over 2026–2032. Outpatient Treatment is growing quickly due to the increasing preference for less invasive procedures and preventive care. The government's encouragement of preventive care through health insurance incentives is a key factor driving this growth. Providers must adapt to the shift towards outpatient services to remain competitive in the market.
By Level of Coverage – Gold Leads, Silver Expected to Grow Fastest
In 2025, Gold led the level of coverage split with a 40% share. Gold plans lead this segment as they are preferred for comprehensive coverage, appealing to individuals seeking extensive healthcare benefits. This preference is underscored by the average healthcare expenditure per capita, which stands at approximately 500,000 JPY. Over 2026–2032, Silver is expected to post the fastest growth, at a CAGR of 5.6%. Silver plans are experiencing rapid growth, particularly among average income earners who desire affordable yet sufficient coverage. The Silver plan's popularity among middle-income families signifies its increasing acceptance in the market. Insurers should tailor their offerings to cater to the diverse needs of various income groups.
By Service Providers – Public Health Insurance Providers Lead, Private Health Insurance Providers Expected to Grow Fastest
Public Health Insurance Providers took 63% of service providers revenue in 2025, more than any other category. Public Health Insurance Providers are pivotal to the insurance system, offering coverage to a significant segment of the population. With over 1,500 public health insurance providers, they are crucial in ensuring access to healthcare services. Private Health Insurance Providers are projected to grow fastest, at a CAGR of 5.2% during 2026–2032. Private Health Insurance Providers are expanding quickly as they complement public insurance options, catering to individuals seeking additional coverage. The growing demand for personalised healthcare solutions is driving this segment's growth. Collaboration between public and private providers could improve service delivery and enhance patient satisfaction.
By Health Insurance Plans – Health Maintenance Organization (HMO) Leads and Records the Fastest Growth
The largest health insurance plans category in 2025 was Health Maintenance Organization (HMO), at 44% of revenue. The Health Maintenance Organization (HMO) model holds the largest share as it is a prevalent structure for managed care, ensuring coordinated healthcare services. Its efficiency in managing patient care has led to widespread adoption across the market. The same category is also set to grow fastest, at a CAGR of 5.9% during 2026–2032. The Health Maintenance Organization (HMO) is also the fastest-growing plan type, effectively addressing the needs of a changing healthcare landscape. The ongoing focus on preventive care within HMOs is likely to further strengthen their market position. Providers should concentrate on optimising HMO offerings to leverage their increasing popularity.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- Japan Medical Insurance Market Outlook
- Market Size of Japan Medical Insurance Market, 2025
- Forecast of Japan Medical Insurance Market, 2032
- Historical Data and Forecast of Japan Medical Insurance Revenues & Volume for the Period 2022-2032
- Japan Medical Insurance Market Trend Evolution
- Japan Medical Insurance Market Drivers and Challenges
- Japan Medical Insurance Price Trends
- Japan Medical Insurance Porter's Five Forces
- Japan Medical Insurance Industry Life Cycle
- Historical Data and Forecast of Japan Medical Insurance Market Revenues & Volume By Type for the Period 2022-2032
- Historical Data and Forecast of Japan Medical Insurance Market Revenues & Volume By Products for the Period 2022-2032
- Historical Data and Forecast of Japan Medical Insurance Market Revenues & Volume By Solutions for the Period 2022-2032
- Historical Data and Forecast of Japan Medical Insurance Market Revenues & Volume By Services for the Period 2022-2032
- Historical Data and Forecast of Japan Medical Insurance Market Revenues & Volume By Inpatient Treatment for the Period 2022-2032
- Historical Data and Forecast of Japan Medical Insurance Market Revenues & Volume By Outpatient Treatment for the Period 2022-2032
- Historical Data and Forecast of Japan Medical Insurance Market Revenues & Volume By Medical Assistance for the Period 2022-2032
- Historical Data and Forecast of Japan Medical Insurance Market Revenues & Volume By Level of Coverage for the Period 2022-2032
- Historical Data and Forecast of Japan Medical Insurance Market Revenues & Volume By Bronze for the Period 2022-2032
- Historical Data and Forecast of Japan Medical Insurance Market Revenues & Volume By Silver for the Period 2022-2032
- Historical Data and Forecast of Japan Medical Insurance Market Revenues & Volume By Gold for the Period 2022-2032
- Historical Data and Forecast of Japan Medical Insurance Market Revenues & Volume By Platinum for the Period 2022-2032
- Historical Data and Forecast of Japan Medical Insurance Market Revenues & Volume By Service Providers for the Period 2022-2032
- Historical Data and Forecast of Japan Medical Insurance Market Revenues & Volume By Public Health Insurance Providers for the Period 2022-2032
- Historical Data and Forecast of Japan Medical Insurance Market Revenues & Volume By Private Health Insurance Providers for the Period 2022-2032
- Historical Data and Forecast of Japan Medical Insurance Market Revenues & Volume By Health Insurance Plans for the Period 2022-2032
- Historical Data and Forecast of Japan Medical Insurance Market Revenues & Volume By Point of Service (POS) for the Period 2022-2032
- Historical Data and Forecast of Japan Medical Insurance Market Revenues & Volume By Exclusive Provider Organization (EPOS) for the Period 2022-2032
- Historical Data and Forecast of Japan Medical Insurance Market Revenues & Volume By Indemnity Health Insurance for the Period 2022-2032
- Historical Data and Forecast of Japan Medical Insurance Market Revenues & Volume By Health Savings Account (HSA) for the Period 2022-2032
- Historical Data and Forecast of Japan Medical Insurance Market Revenues & Volume By Qualified Small Employer Health Reimbursement Arrangements (QSEHRAS) for the Period 2022-2032
- Historical Data and Forecast of Japan Medical Insurance Market Revenues & Volume By Preferred Provider Organization (PPO) for the Period 2022-2032
- Historical Data and Forecast of Japan Medical Insurance Market Revenues & Volume By Health Maintenance Organization (HMO) for the Period 2022-2032
- Historical Data and Forecast of Japan Medical Insurance Market Revenues & Volume By Demographics for the Period 2022-2032
- Historical Data and Forecast of Japan Medical Insurance Market Revenues & Volume By Adults for the Period 2022-2032
- Historical Data and Forecast of Japan Medical Insurance Market Revenues & Volume By Minors for the Period 2022-2032
- Historical Data and Forecast of Japan Medical Insurance Market Revenues & Volume By Senior Citizens for the Period 2022-2032
- Japan Medical Insurance Import Export Trade Statistics
- Market Opportunity Assessment By Type
- Market Opportunity Assessment By Services
- Market Opportunity Assessment By Level of Coverage
- Market Opportunity Assessment By Service Providers
- Market Opportunity Assessment By Health Insurance Plans
- Market Opportunity Assessment By Demographics
- Japan Medical Insurance Top Companies Market Share
- Japan Medical Insurance Competitive Benchmarking By Technical and Operational Parameters
- Japan Medical Insurance Company Profiles
- Japan Medical Insurance Key Strategic Recommendations
Market Covered
The following segment groups are covered in the report.
By Type
- Products
- Solutions
By Services
- Inpatient Treatment
- Outpatient Treatment
- Medical Assistance
By Level of Coverage
- Bronze
- Silver
- Gold
- Platinum
By Service Providers
- Public Health Insurance Providers
- Private Health Insurance Providers
By Health Insurance Plans
- Point of Service (POS)
- Exclusive Provider Organization (EPOS)
- Indemnity Health Insurance
- Health Savings Account (HSA)
- Qualified Small Employer Health Reimbursement Arrangements (QSEHRAS)
- Preferred Provider Organization (PPO)
- Health Maintenance Organization (HMO)































