Japan Semiconductor Processing Equipment Market Size & Growth Rate
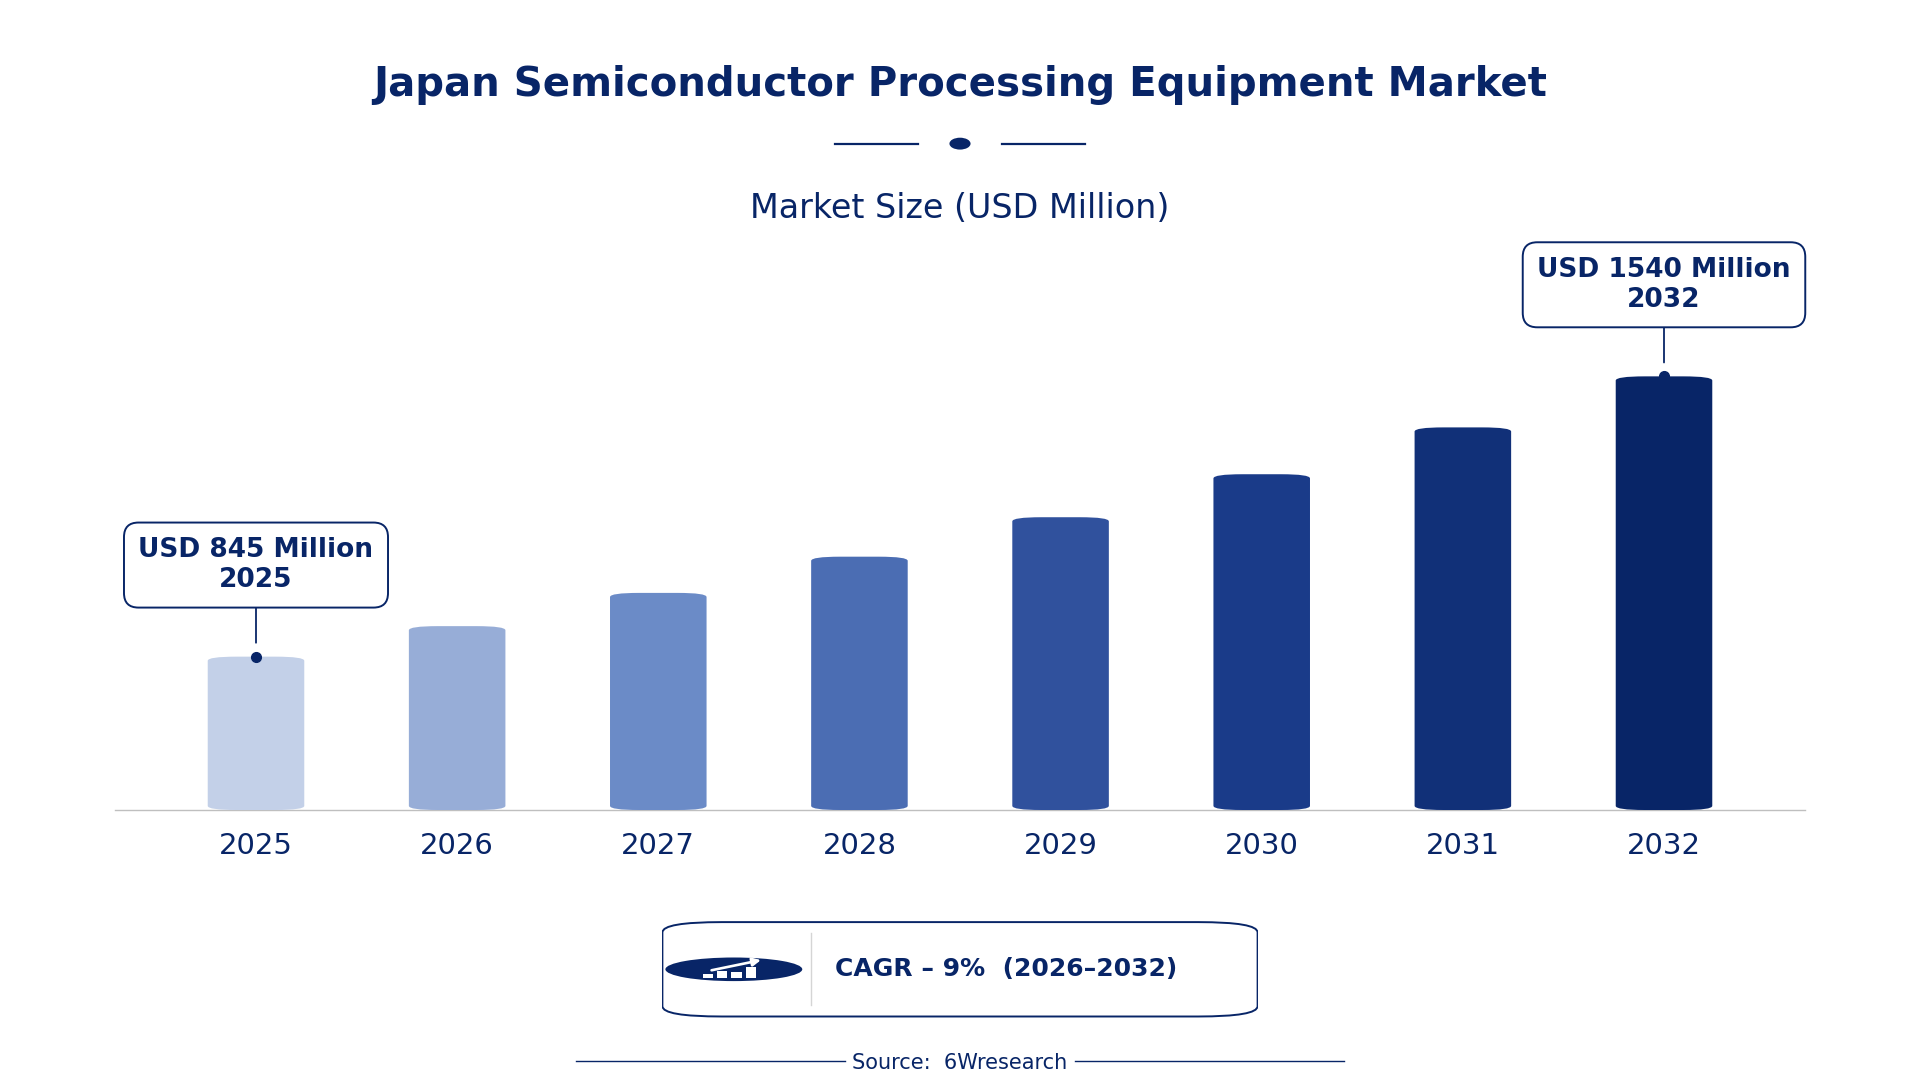
According to 6Wresearch internal database and industry insights, the Japan Semiconductor Processing Equipment Market was valued at USD 845 Million in 2025 and is projected to reach USD 1,540 Million by 2032, growing at a CAGR of approximately 9% during 2026–2032.
Japan Semiconductor Processing Equipment Market Highlights
| Report Metric | Details |
| Report Name | Japan Semiconductor Processing Equipment Market (2026-2032) |
| Market Size 2025 | USD 845 Million |
| Market Size 2032 | USD 1,540 Million |
| Absolute Growth 2025–2032 | USD 695 Million |
| CAGR 2026–2032 | 9% |
| Peak Annual Growth | 9.4% in 2032 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Equipment Type, 2025 | Lithography Machines (45% share) |
| Leading Process Step, 2025 | Patterning (42% share) |
| Leading Automation Level, 2025 | Fully Automated (40% share) |
| Leading End User, 2025 | Wafer Foundries (45% share) |
| Fastest-Growing Equipment Type | Etch Tools (12.5% CAGR) |
| Fastest-Growing Process Step | Dry/Wet Etch (13.1% CAGR) |
| Fastest-Growing Automation Level | Semi-Automated (12.0% CAGR) |
| Fastest-Growing End User | IDMs (12.1% CAGR) |
| Growing Sector | IDMs |
| Key End Users | Wafer Foundries, IDMs, Fab Equipment Integrators, Semiconductor Manufacturers |
Japan Semiconductor Processing Equipment Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
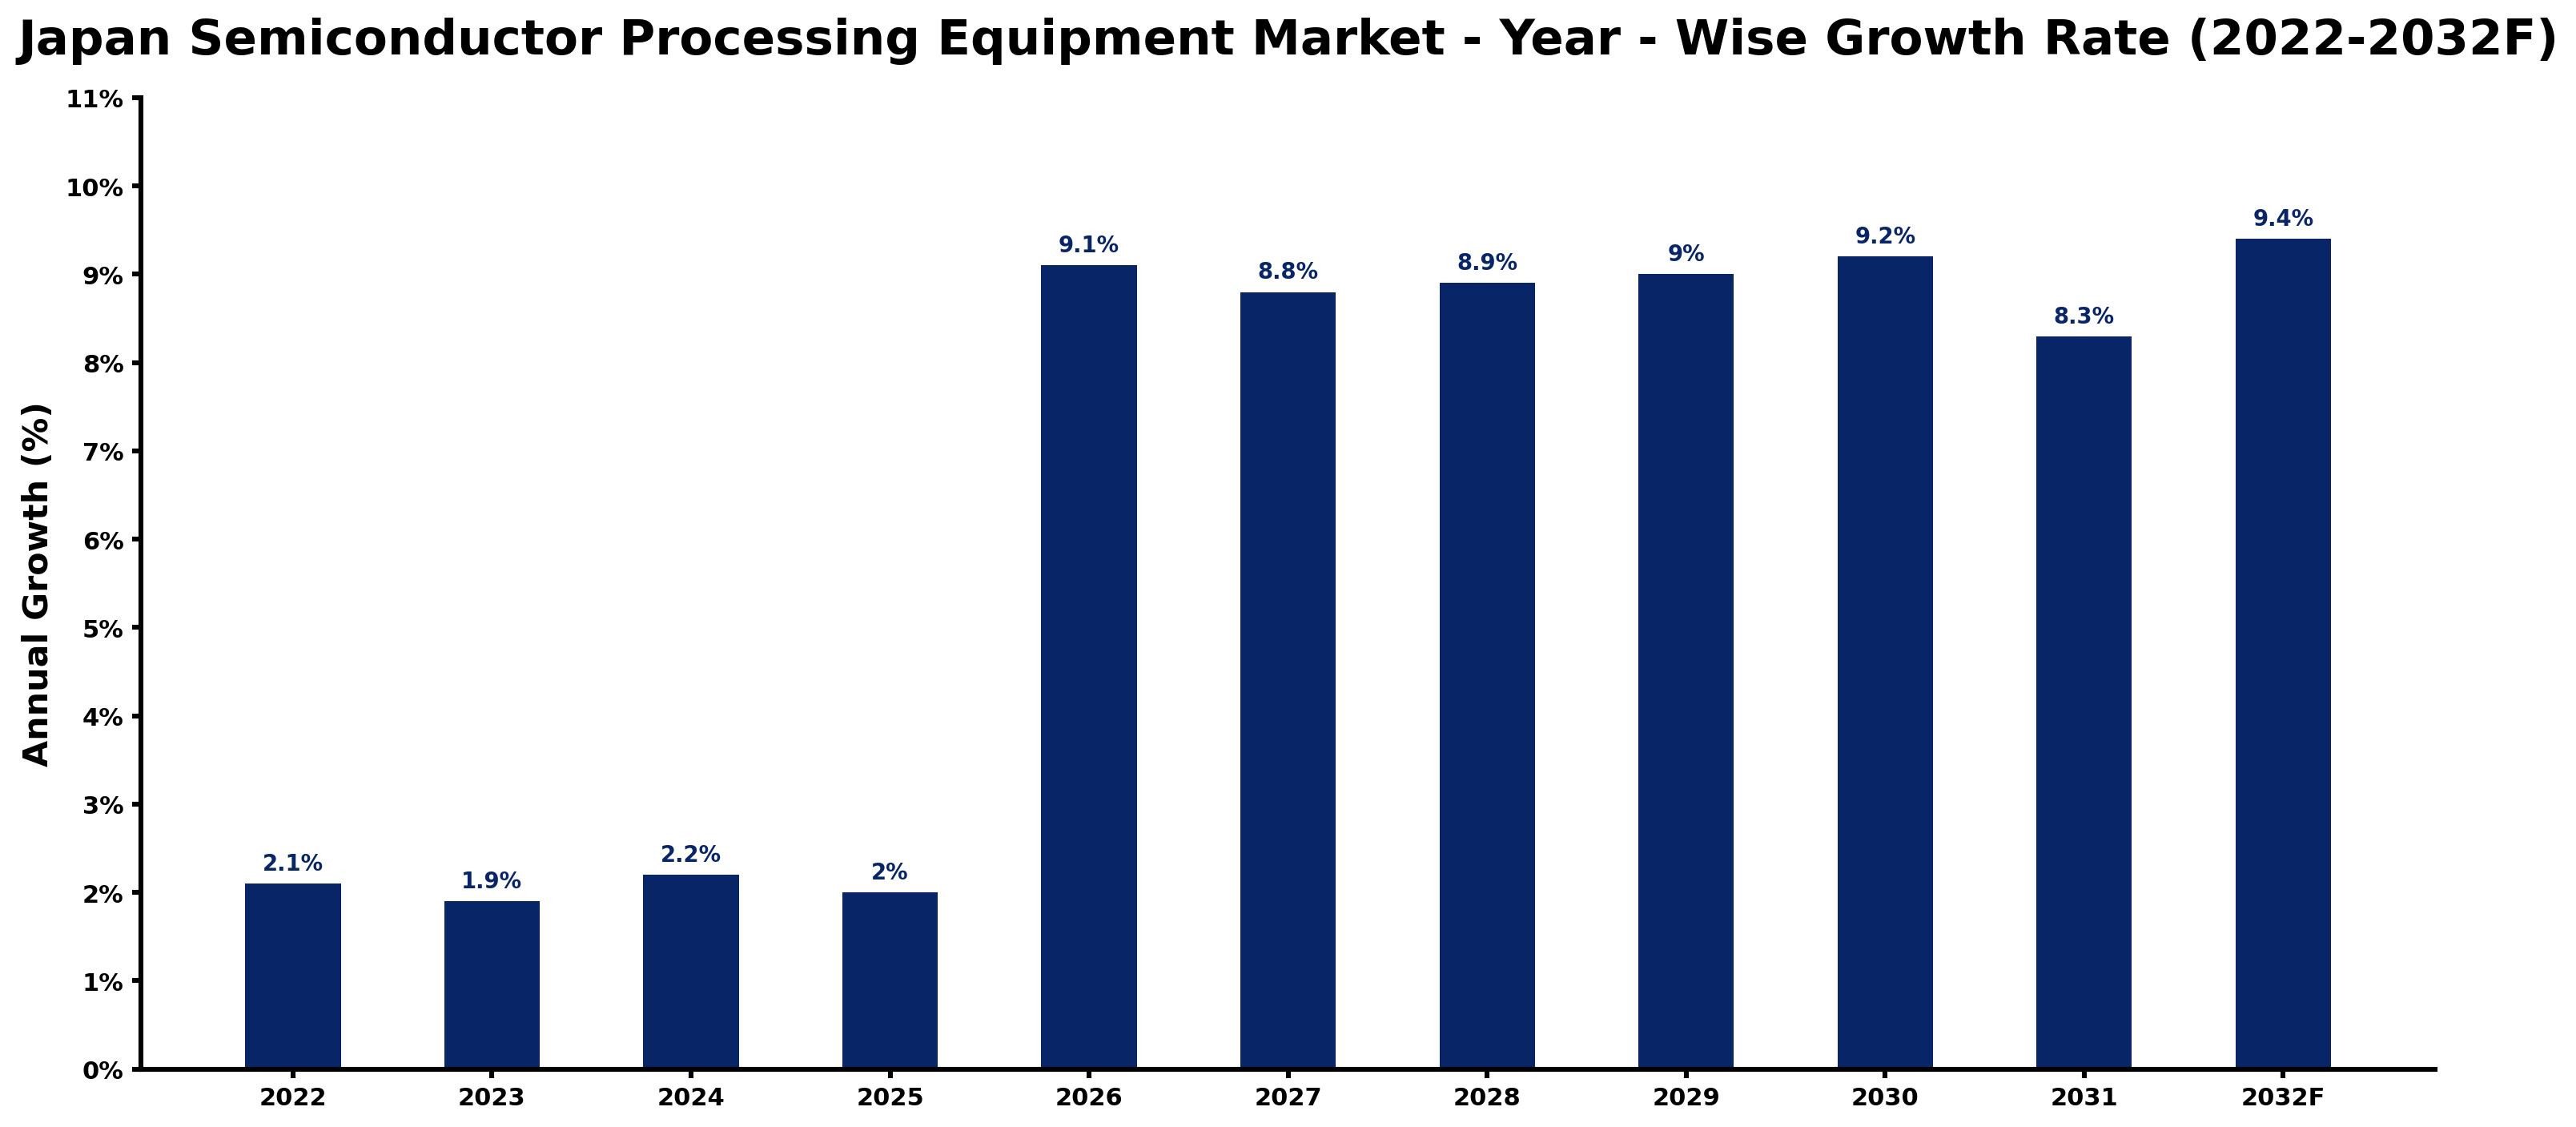
Below, each year's estimated growth is shown next to the factor that most influenced it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 2.1 | The market experienced steady growth with increasing demand from domestic manufacturers. |
| 2023 | 1.9 | Growth slowed slightly as manufacturers adjusted to market conditions and supply chain fluctuations. |
| 2024 | 2.2 | Production increased as companies ramped up investments in semiconductor technology and capacity. |
| 2025 | 2.0 | Growth decelerated as the market stabilised after previous expansions in production capabilities. |
| 2026 | 9.1 | Demand surged as manufacturers focused on improving production efficiency and meeting global needs. |
| 2027 | 8.8 | Growth moderated slightly as the market adjusted to new technological advancements and investments. |
| 2028 | 8.9 | Production capacity expanded further, driven by rising global demand for semiconductor devices. |
| 2029 | 9.0 | Demand continued to rise as manufacturers sought to optimise their production processes. |
| 2030 | 9.2 | Growth accelerated as new technologies were adopted across the semiconductor manufacturing sector. |
| 2031 | 8.3 | The market saw a slowdown as companies consolidated gains from previous years' expansions. |
| 2032 | 9.4 | Demand peaked as manufacturers fully embraced advanced technologies and increased production capacity. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
Japan Semiconductor Processing Equipment Market Synopsis
Semiconductor processing equipment includes technologies essential for fabricating semiconductor devices, produced through advanced manufacturing processes involving precision engineering. The Japan Semiconductor Processing Equipment Market is expanding due to rising demand from wafer foundries, which account for 60% of equipment demand. The government's initiatives aim to boost domestic production capacity by 30% by 2026, driving overall market growth and attracting new buyers.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increasing production capacity among wafer foundries | Driver | High | Wafer Foundries |
| Technological advancements in semiconductor processing | Driver | High | Etch Tools |
| Rising demand for advanced semiconductor devices | Opportunity | High | Deposition Tools |
| Government initiatives to support semiconductor production | Opportunity | High | Patterning |
| Fluctuating global supply chain dynamics | Restraint | Medium | CMP Tools |
| High costs associated with advanced equipment | Restraint | Medium | Lithography Machines |
| Talent shortages in semiconductor manufacturing | Challenge | High | Semiconductor Manufacturers |
| Long lead times for equipment delivery | Challenge | Medium | Fab Equipment Integrators |
Evaluation of Drivers in Japan Semiconductor Processing Equipment Market (2026–2032)
The main growth drivers and the segments they affect most are set out below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased production capacity among wafer foundries | Wafer Foundries | Wafer foundries accounted for 60% of semiconductor processing equipment demand in Japan, driving purchases. |
| Technological advancements in semiconductor processing | Etch Tools | The introduction of new etching technologies has improved production efficiency, leading to higher demand for equipment. |
| Growing demand for advanced semiconductor devices | Deposition Tools | The market for advanced devices necessitates more deposition equipment for layer application, boosting demand. |
| Government initiatives to support semiconductor production | Patterning | The government aims to increase domestic semiconductor production by 20% by 2025, enhancing demand for patterning equipment. |
| Rising exports of semiconductor products | CMP Tools | Japan's semiconductor exports reached ¥2 trillion in 2022, increasing the need for advanced processing equipment. |
Buyers are adding capacity as Japan's semiconductor industry produced 4.5 million wafers in 2022, reflecting strong demand for processing equipment. The Semiconductor Industry Association of Japan reported a 5% increase in production in 2023, resulting in higher equipment purchases. As manufacturers invest in new deposition tools, they enhance production capabilities to meet the needs of wafer foundries, which account for a significant share of demand.
Evaluation of Restraints in Japan Semiconductor Processing Equipment Market
The following restraints limit how fast demand can grow.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Fluctuating global supply chain issues | CMP Tools | Supply chain disruptions have affected the availability of critical components, delaying production timelines by 15%. |
| High costs associated with advanced equipment | Lithography Machines | The investment required for advanced lithography machines can deter smaller manufacturers from upgrading, costing them market share. |
| Talent shortages in semiconductor manufacturing | Semiconductor Manufacturers | A lack of skilled workers in the semiconductor sector has hindered production capabilities and efficiency, limiting output by 20%. |
| Long lead times for equipment delivery | Fab Equipment Integrators | Extended delivery times for specialized equipment can disrupt project schedules and increase costs by 10%. |
| Regulatory compliance costs | Etch Tools | Meeting stringent safety and environmental regulations adds to the overall cost of equipment production, increasing expenses by 5%. |
Japan Semiconductor Processing Equipment Market Challenges
Producers face challenges with outdated technology in semiconductor processing, as many facilities continue to depend on legacy systems that impede efficiency. This issue arises from the high costs linked to upgrading equipment, resulting in production delays of up to 20% for manufacturers. Suppliers struggle to attract skilled workers, as the current workforce lacks training in advanced semiconductor processes, which raises their operational costs. Compliance with regulations such as JIS Z 2801 complicates operations for suppliers, potentially delaying product launches for producers by several months and increasing their overall expenses.
Trends in the Japan Semiconductor Processing Equipment Market
Below are the shifts with the largest effect on the Japan Semiconductor Processing Equipment Market.
- Shift from Manual to Fully Automated Processes: Tokyo is witnessing a transition towards fully automated semiconductor manufacturing processes, with a projected 40% share in 2025. This change is motivated by the need for greater efficiency and lower labour costs, benefiting manufacturers who invest in automation solutions.
- Emergence of Advanced Etching Technologies: Wafer foundries are progressively adopting advanced etching technologies, with a projected CAGR of 12.5% for Etch Tools. This trend is transforming production capabilities, enabling manufacturers to create smaller, more intricate semiconductor devices, thereby improving competitiveness.
- Focus on Sustainable Manufacturing Practices: The Semiconductor Technology Research Association is advocating for sustainable practices in semiconductor manufacturing, reflecting a growing industry emphasis on environmental responsibility. This shift is anticipated to influence equipment design and production methods, promoting greener technologies.
- Adoption of Industry 4.0 Standards: Since 2023, semiconductor manufacturers have started implementing Industry 4.0 standards to enhance operational efficiency. This trend is resulting in greater integration of IoT technologies in processing equipment, driving demand for advanced solutions.
Investment Opportunities in the Japan Semiconductor Processing Equipment Market
Where to invest in the Japan Semiconductor Processing Equipment Market: the main openings are set out below.
- Timing for Investment: With Japan's semiconductor market projected to reach ¥4 trillion by 2025, there exists an opportunity for investment in advanced processing equipment. Wafer foundries are eager to upgrade their facilities to meet this demand, creating a market for suppliers.
- Growing Need for Automation: As manufacturers increasingly embrace fully automated processes, there is a rising demand for automation solutions. Semiconductor manufacturers are seeking partners to develop and implement these technologies, creating opportunities for collaboration.
- Investment in R&D: The government has allocated ¥1 billion for semiconductor technology initiatives in 2023, presenting opportunities for investment in research and development. This funding can support pioneering projects in the sector, promoting growth.
- Market for Advanced Devices: The expanding market for advanced semiconductor devices requires new equipment investments. Integrated device manufacturers are looking to improve their production capabilities to satisfy this demand, offering opportunities for suppliers.
Government Initiatives in the Japan Semiconductor Processing Equipment Market
The Semiconductor and Digital Industry Strategy, launched by the Ministry of Economy, Trade and Industry in June 2021, seeks to secure domestic semiconductor manufacturing. This strategy includes measures to increase production capacity by 20% and support technological advancements in the sector, improving the competitiveness of Japanese manufacturers.
The Ministry of Economy, Trade and Industry manages various funding programs, including the ¥1 billion initiative for semiconductor technology in 2023. This funding supports projects that enhance semiconductor production capabilities and encourage innovation in the industry.
Future Insight of the Japan Semiconductor Processing Equipment Market
By 2032, advancements in semiconductor processing technology will markedly influence demand, driven by the adoption of new manufacturing standards and greater automation. The government's initiative to increase semiconductor production capacity by 30% by 2026 will improve supply chain efficiency. Increased collaboration between research institutions and manufacturers will stimulate innovation, ensuring that suppliers remain competitive in the evolving global market.
Market Segmentation Analysis
Japan Semiconductor Processing Equipment Market report covers a detailed analysis of the following market segments:
By Equipment Type – Lithography Machines Lead, Etch Tools Expected to Grow Fastest
According to Saurav Kr Singh, Senior Research Analyst at 6Wresearch, Lithography Machines took 45% of equipment type revenue in 2025, more than any other category. Lithography machines hold the largest share due to their critical role in patterning circuits, which is essential for semiconductor production. This demand is particularly strong among Japan's over 300 semiconductor manufacturers focusing on advanced technology. Etch Tools are set to record the highest CAGR in this split, 12.5% over 2026–2032. Etch tools are experiencing rapid growth as they are essential for material removal in the fabrication process, a necessity as devices become increasingly complex. The industry's push for higher production efficiency further propels this demand. Suppliers should prioritise enhancing their offerings in etch tools to align with the rising demand from manufacturers.
By Process Step – Patterning Leads, Dry/Wet Etch Expected to Grow Fastest
Patterning held 42% of the Japan Semiconductor Processing Equipment Market by process step in 2025. Patterning is the leading process step as it is fundamental in chip design, establishing the foundation for all subsequent manufacturing processes. Japan's production of 4.5 million wafers in 2022 underscores the importance of this step in the semiconductor industry. The quickest growth will come from Dry/Wet Etch, forecast to expand at a CAGR of 13.1% between 2026 and 2032. Dry/wet etch is the fastest-growing segment due to its vital role in defining features on chips, which has become increasingly critical with advancing technology. The need for precision in feature definition drives manufacturers to invest more in this area. Buyers must ensure they are equipped with the latest dry/wet etch technologies to maintain competitiveness in the market.
By Automation Level – Fully Automated Leads, Semi-Automated Expected to Grow Fastest
Fully Automated accounted for 40% of the market by automation level in 2025. Fully automated systems dominate the market as they significantly increase production efficiency, crucial for meeting high demand. This trend is particularly relevant in Japan's advanced semiconductor facilities, where operational excellence is a key focus. Over 2026–2032, Semi-Automated is expected to post the fastest growth, at a CAGR of 12.0%. Semi-automated systems are experiencing rapid growth as they are commonly used in smaller fabs that require flexibility without sacrificing efficiency. The rise of smaller manufacturers seeking to optimise their operations is contributing to this segment's growth. Suppliers should consider developing semi-automated solutions to meet the needs of smaller fabrication facilities.
By End User – Wafer Foundries Lead, IDMs Expected to Grow Fastest
In 2025, Wafer Foundries led the end user split with a 45% share. Wafer foundries represent the largest end user segment because they are the major consumers of semiconductor processing equipment, essential for producing various chips. Their substantial operational scale in Japan ensures a consistent demand for advanced equipment. IDMs are projected to grow fastest, at a CAGR of 12.1% during 2026–2032. IDMs are the fastest-growing segment as they integrate design and manufacturing processes, allowing for greater control over production. The trend towards vertical integration among manufacturers is driving this rapid growth. Buyers in the IDM segment should focus on acquiring advanced equipment to streamline their integrated processes.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- Japan Semiconductor Processing Equipment Market Outlook
- Market Size of Japan Semiconductor Processing Equipment Market, 2025
- Forecast of Japan Semiconductor Processing Equipment Market, 2032
- Historical Data and Forecast of Japan Semiconductor Processing Equipment Revenues & Volume for the Period 2022-2032F
- Japan Semiconductor Processing Equipment Market Trend Evolution
- Japan Semiconductor Processing Equipment Market Drivers and Challenges
- Japan Semiconductor Processing Equipment Price Trends
- Japan Semiconductor Processing Equipment Porter's Five Forces
- Japan Semiconductor Processing Equipment Industry Life Cycle
- Historical Data and Forecast of Japan Semiconductor Processing Equipment Market Revenues & Volume By Equipment Type for the Period 2022-2032F
- Historical Data and Forecast of Japan Semiconductor Processing Equipment Market Revenues & Volume By Lithography Machines for the Period 2022-2032F
- Historical Data and Forecast of Japan Semiconductor Processing Equipment Market Revenues & Volume By Etch Tools for the Period 2022-2032F
- Historical Data and Forecast of Japan Semiconductor Processing Equipment Market Revenues & Volume By Deposition Tools for the Period 2022-2032F
- Historical Data and Forecast of Japan Semiconductor Processing Equipment Market Revenues & Volume By CMP Tools for the Period 2022-2032F
- Historical Data and Forecast of Japan Semiconductor Processing Equipment Market Revenues & Volume By Process Step for the Period 2022-2032F
- Historical Data and Forecast of Japan Semiconductor Processing Equipment Market Revenues & Volume By Patterning for the Period 2022-2032F
- Historical Data and Forecast of Japan Semiconductor Processing Equipment Market Revenues & Volume By Dry/Wet Etch for the Period 2022-2032F
- Historical Data and Forecast of Japan Semiconductor Processing Equipment Market Revenues & Volume By ALD, CVD, PVD for the Period 2022-2032F
- Historical Data and Forecast of Japan Semiconductor Processing Equipment Market Revenues & Volume By Surface Planarization for the Period 2022-2032F
- Historical Data and Forecast of Japan Semiconductor Processing Equipment Market Revenues & Volume By Automation Level for the Period 2022-2032F
- Historical Data and Forecast of Japan Semiconductor Processing Equipment Market Revenues & Volume By Fully Automated for the Period 2022-2032F
- Historical Data and Forecast of Japan Semiconductor Processing Equipment Market Revenues & Volume By Semi-Automated for the Period 2022-2032F
- Historical Data and Forecast of Japan Semiconductor Processing Equipment Market Revenues & Volume By Modular for the Period 2022-2032F
- Historical Data and Forecast of Japan Semiconductor Processing Equipment Market Revenues & Volume By Inline for the Period 2022-2032F
- Historical Data and Forecast of Japan Semiconductor Processing Equipment Market Revenues & Volume By End User for the Period 2022-2032F
- Historical Data and Forecast of Japan Semiconductor Processing Equipment Market Revenues & Volume By Wafer Foundries for the Period 2022-2032F
- Historical Data and Forecast of Japan Semiconductor Processing Equipment Market Revenues & Volume By IDMs for the Period 2022-2032F
- Historical Data and Forecast of Japan Semiconductor Processing Equipment Market Revenues & Volume By Fab Equipment Integrators for the Period 2022-2032F
- Historical Data and Forecast of Japan Semiconductor Processing Equipment Market Revenues & Volume By Semiconductor Manufacturers for the Period 2022-2032F
- Japan Semiconductor Processing Equipment Import Export Trade Statistics
- Market Opportunity Assessment By Equipment Type
- Market Opportunity Assessment By Process Step
- Market Opportunity Assessment By Automation Level
- Market Opportunity Assessment By End User
- Japan Semiconductor Processing Equipment Top Companies Market Share
- Japan Semiconductor Processing Equipment Competitive Benchmarking By Technical and Operational Parameters
- Japan Semiconductor Processing Equipment Company Profiles
- Japan Semiconductor Processing Equipment Key Strategic Recommendations
Market Covered
The following segment groups are covered in the report.
By Equipment Type
- Lithography Machines
- Etch Tools
- Deposition Tools
- CMP Tools
By Process Step
- Patterning
- Dry/Wet Etch
- ALD
- CVD
- PVD
- Surface Planarization
By Automation Level
- Fully Automated
- Semi-Automated
- Modular
- Inline
By End User
- Wafer Foundries
- IDMs
- Fab Equipment Integrators
- Semiconductor Manufacturers































