Japan Thermal Management Solutions Market Size & Growth Rate
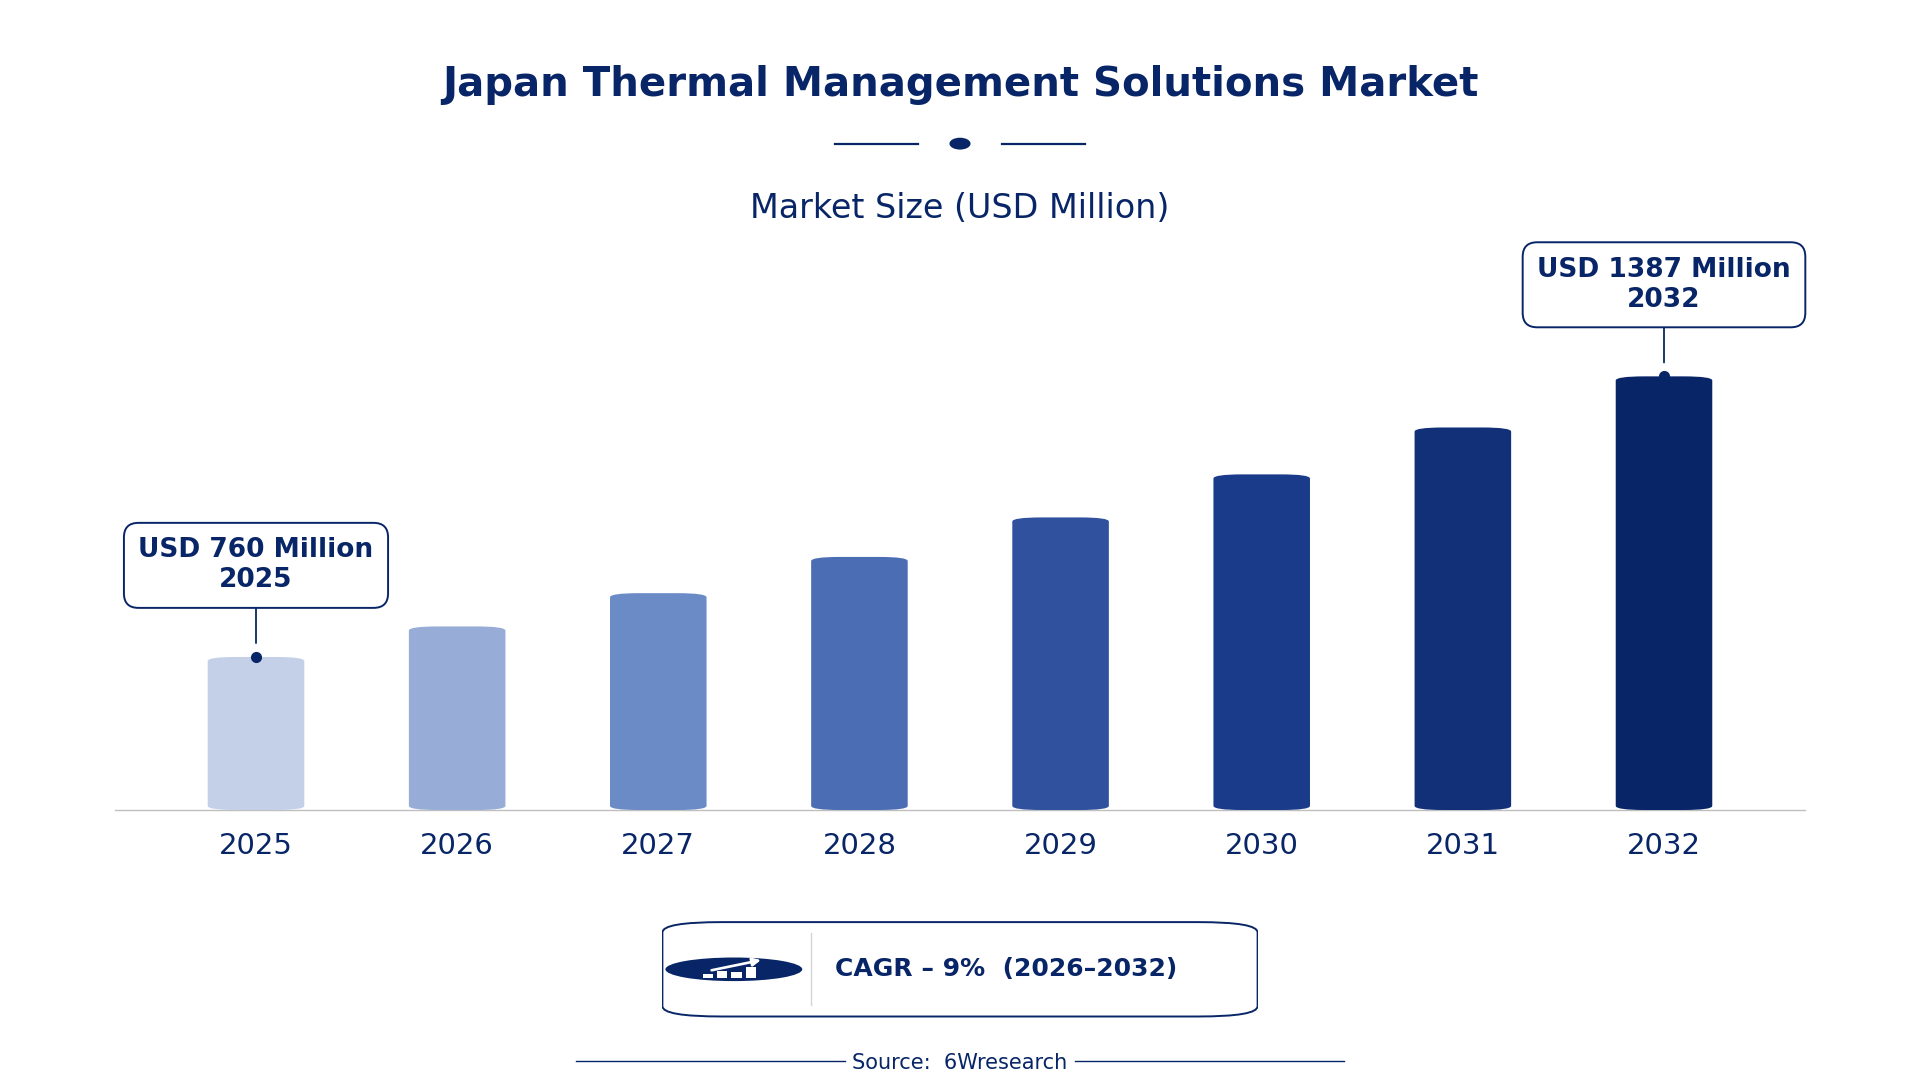
According to 6Wresearch internal database and industry insights, the Japan Thermal Management Solutions Market was valued at USD 760 Million in 2025 and is projected to reach USD 1,387 Million by 2032, growing at a CAGR of approximately 9% during 2026–2032.
Japan Thermal Management Solutions Market Highlights
| Report Metric | Details |
| Report Name | Japan Thermal Management Solutions Market (2026-2032) |
| Market Size 2025 | USD 760 Million |
| Market Size 2032 | USD 1,387 Million |
| Absolute Growth 2025–2032 | USD 627 Million |
| CAGR 2026–2032 | 9% |
| Peak Annual Growth | 9.7% in 2032 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Thermal Management Solutions, 2025 | Liquid Cooling Systems (52% share) |
| Leading Product Type, 2025 | Cold Plates (42% share) |
| Leading Technology, 2025 | Liquid Loop Cooling (43% share) |
| Leading Distribution Channel, 2025 | OEM Thermal Vendors (41% share) |
| Leading End User Industry, 2025 | HPC & Data Centers (52% share) |
| Fastest-Growing Thermal Management Solutions | Phase Change Materials (11.7% CAGR) |
| Fastest-Growing Product Type | PCM Sheets (12.6% CAGR) |
| Fastest-Growing Distribution Channel | System Integrators (11.3% CAGR) |
| Fastest-Growing End User Industry | Laptop/Desktop OEMs (12.4% CAGR) |
| Growing Sector | Consumer Electronics |
| Key End Users | Data Centers, HPC Facilities, Consumer Electronics Manufacturers, Automotive Manufacturers |
Japan Thermal Management Solutions Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
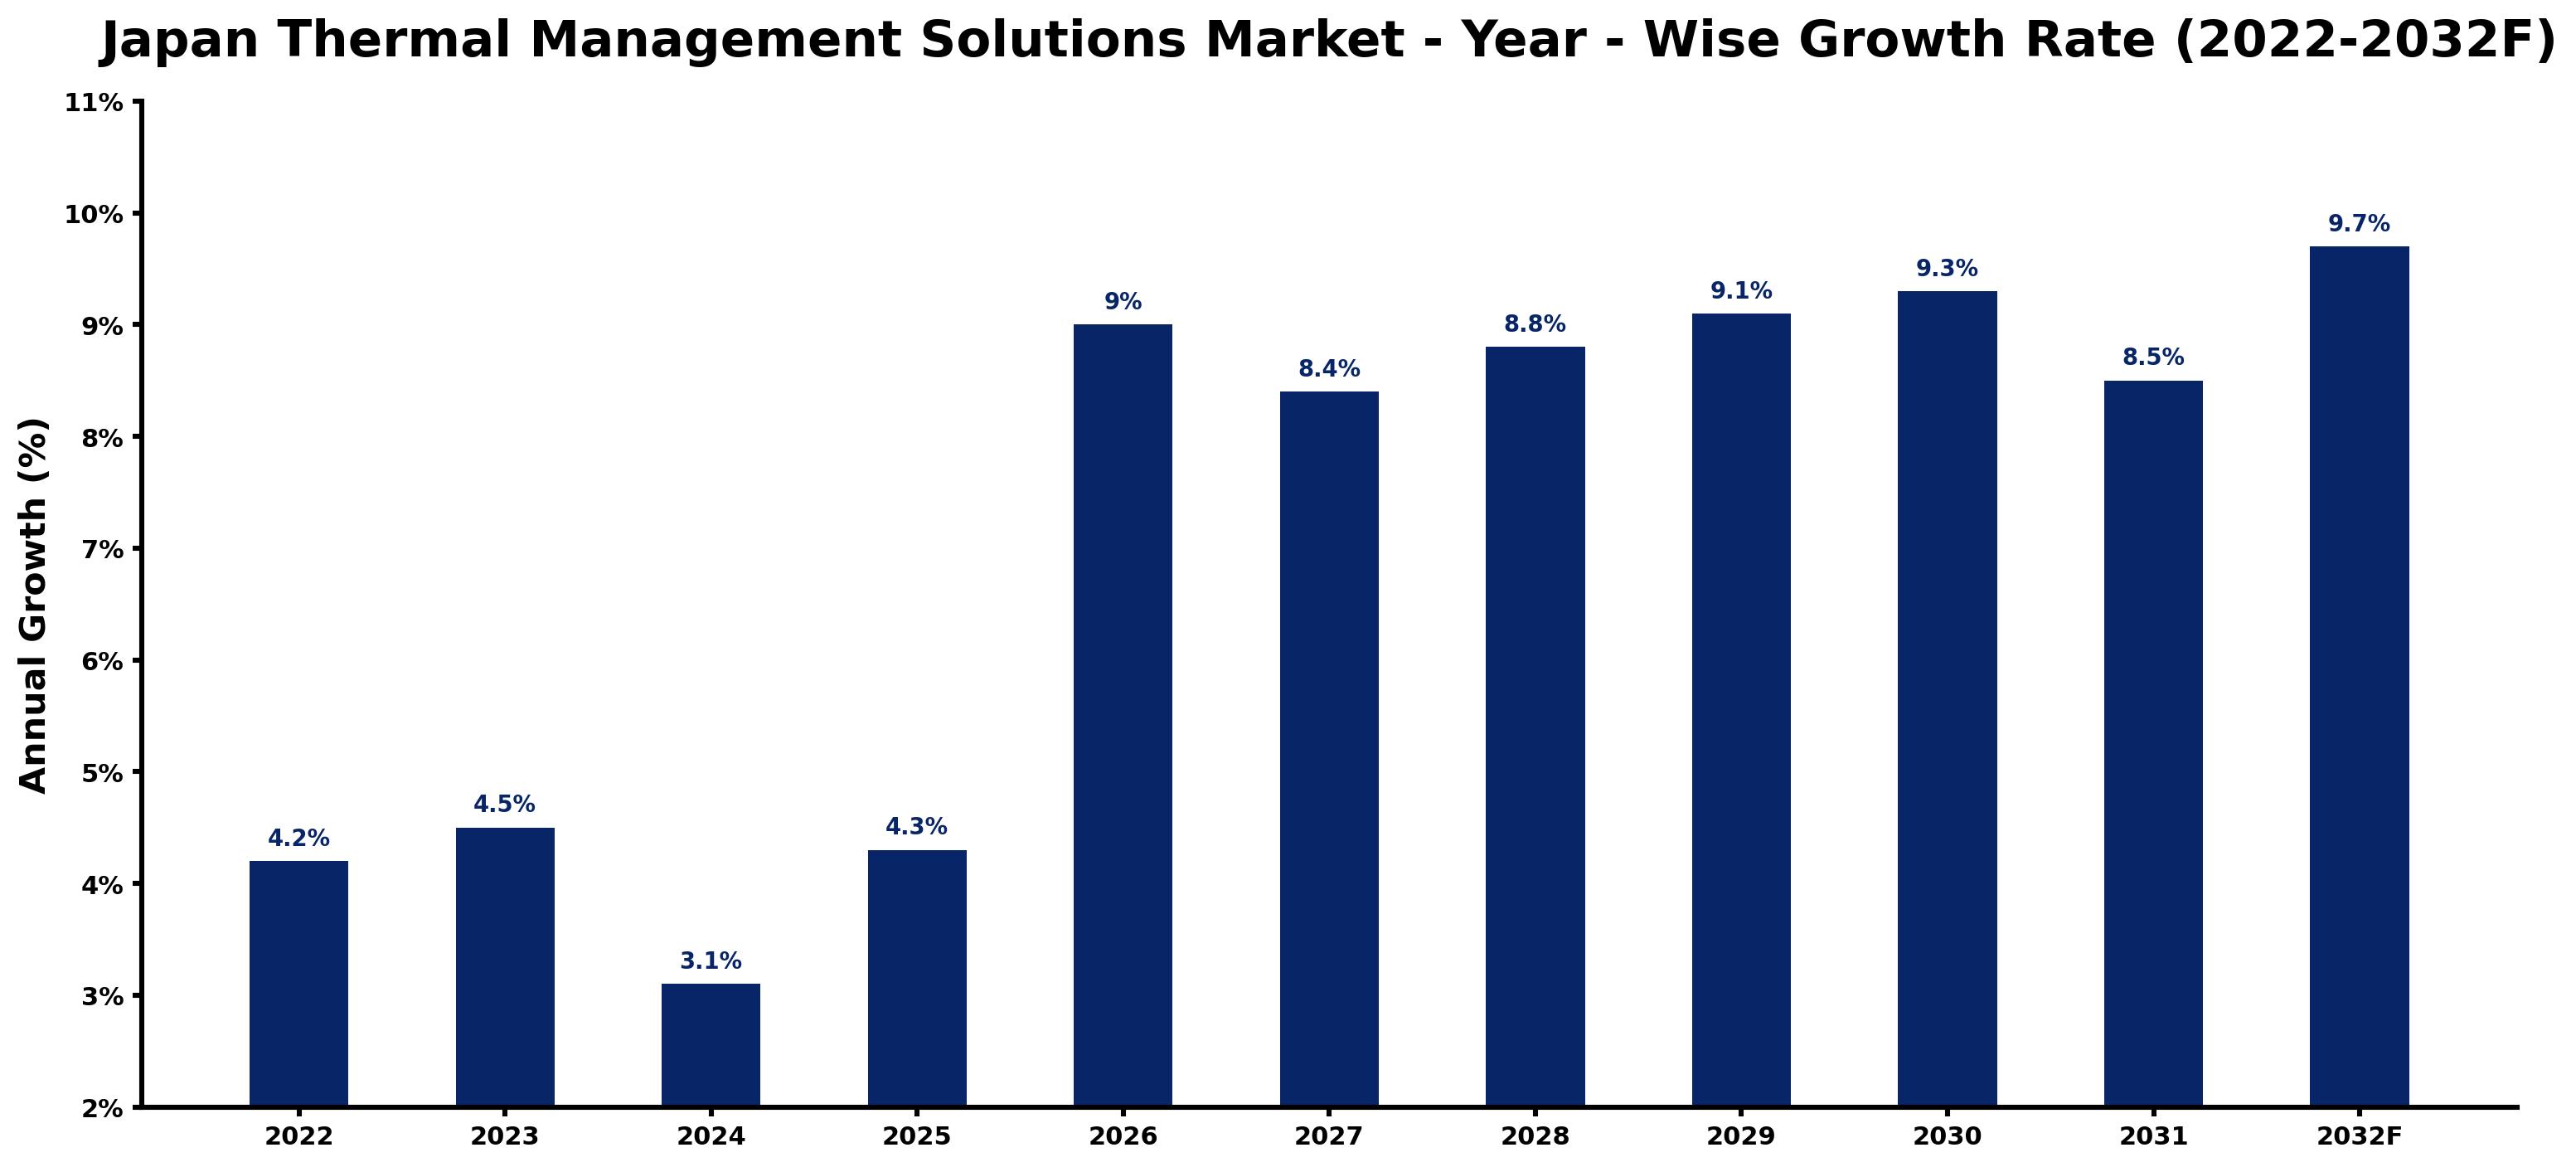
Year by year, the estimates below pair each growth rate with the development that shaped it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 4.2 | The market experienced steady growth due to ongoing demand in electronics. |
| 2023 | 4.5 | Growth accelerated as consumer electronics sales surged, reaching 3 trillion yen. |
| 2024 | 3.1 | Growth slowed as the market adjusted to previous high demand levels, impacting production. |
| 2025 | 4.3 | Demand increased again, driven by rising HPC facility requirements and expanding data centers. |
| 2026 | 9.0 | The market is set to expand rapidly with new cooling technologies gaining traction. |
| 2027 | 8.4 | Growth will moderate slightly as the market stabilises post-peak demand. |
| 2028 | 8.8 | Demand will rise again as HPC facilities continue to expand, increasing cooling needs. |
| 2029 | 9.1 | Growth is expected to remain strong due to increased electronics production and sales. |
| 2030 | 9.3 | Demand will continue to grow as energy efficiency becomes a priority for manufacturers. |
| 2031 | 8.5 | Growth will slow as the market reaches a more mature phase of development. |
| 2032 | 9.7 | The market will peak as advanced cooling technologies gain traction among buyers. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
Japan Thermal Management Solutions Market Synopsis
Thermal management solutions are technologies that control heat in electronic devices, produced through advanced manufacturing techniques. The Japan Thermal Management Solutions Market is expanding due to the thriving electronics sector, valued at approximately 10 trillion yen. Demand stems from high-performance computing facilities and data centers, with liquid cooling systems experiencing a 20% increase in adoption since 2022. The emphasis on energy efficiency and advanced cooling technologies will drive further market growth, with annual demand estimated at 500 million USD.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increasing demand for efficient cooling solutions in data centers | Driver | High | Liquid Cooling Systems |
| Rising consumer electronics sales driving thermal management needs | Driver | High | Thermal Interface Materials |
| Growing investment in HPC facilities requiring advanced cooling | Opportunity | High | Liquid Cooling Systems |
| Expansion of electric vehicle production increasing cold plate usage | Opportunity | High | Cold Plates |
| Challenges in sourcing high-quality materials for production | Restraint | Medium | Heat Pipe Assemblies |
| Regulatory compliance costs impacting smaller manufacturers | Restraint | Medium | Thermal Interface Materials |
| Competition from alternative cooling technologies | Challenge | High | Liquid Cooling Systems |
| Supply chain disruptions affecting material availability | Challenge | High | Heat Pipe Assemblies |
Evaluation of Drivers in Japan Thermal Management Solutions Market (2026–2032)
These are the developments adding the most demand over the forecast period.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Rising consumer electronics production | Thermal Interface Materials | Japan's consumer electronics sales reached 3 trillion yen in 2023, increasing demand for thermal solutions. |
| Growth in high-performance computing facilities | Liquid Cooling Systems | HPC facilities in Japan are projected to grow by 15% over the next five years, driving cooling needs. |
| Increased adoption of energy-efficient technologies | Cold Plates | The government aims to reduce energy consumption in electronics by 30% by 2030, boosting demand for efficient cooling solutions. |
| Expansion of data centers | Liquid Cooling Systems | Over 1,000 data centers in Japan require advanced cooling solutions, leading to higher purchases. |
| Technological advancements in thermal management | Heat Pipe Assemblies | New manufacturing techniques are improving product performance, attracting more buyers in the electronics sector. |
Purchasing is picking up as Japan's consumer electronics market, valued at approximately 10 trillion yen in 2023, drives demand for thermal management solutions. The growth of high-performance computing facilities, projected to rise by 15% over the next five years, necessitates advanced cooling technologies. The target to reduce energy consumption in electronics by 30% by 2030 encourages investments in energy-efficient thermal solutions. With over 1,000 data centers requiring effective cooling, the demand for liquid cooling systems is increasing. New manufacturing techniques are also improving the performance of heat pipe assemblies, further stimulating market growth.
Evaluation of Restraints in Japan Thermal Management Solutions Market
These restraints slow adoption and weigh on supplier margins.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| High costs associated with advanced material sourcing | Heat Pipe Assemblies | Sourcing quality materials for heat pipe assemblies can increase production costs, limiting smaller manufacturers' competitiveness. |
| Regulatory compliance requirements increasing operational costs | Thermal Interface Materials | Compliance with standards like JIS Z 8801 can impose additional costs on manufacturers, affecting pricing. |
| Limited availability of skilled workforce in advanced manufacturing | Liquid Cooling Systems | A shortage of skilled workers can delay production timelines, impacting supply and delivery. |
| Market saturation in certain thermal management segments | Cold Plates | As the market matures, growth rates may slow due to increased competition and limited differentiation among products. |
| Supply chain disruptions affecting material availability | Heat Pipe Assemblies | Global supply chain issues can lead to delays in material procurement, hindering production schedules. |
Japan Thermal Management Solutions Market Challenges
Producers encounter challenges with the JIS Z 8801 standard, complicating compliance and potentially delaying product launches by six months. Increasing manufacturing costs linked to advanced materials have raised production expenses by approximately 15%, affecting profit margins for suppliers. Supply chain disruptions from global semiconductor shortages have led to critical component delays, forcing buyers to extend lead times by an average of four weeks. Intense competition among local manufacturers has driven down prices, limiting investment in innovation and reducing product differentiation for producers.
Trends in the Japan Thermal Management Solutions Market
Four trends stand out in the Japan Thermal Management Solutions Market.
- Shift from Traditional to Advanced Cooling Solutions: Since 2022, Japan has seen a shift towards advanced cooling solutions in data centers, with liquid cooling systems adoption increasing by 20%. This trend reflects the growing need for efficient thermal management in high-performance computing environments.
- Emergence of Phase Change Materials in Electronics: Beginning in 2023, Phase Change Materials are increasingly being integrated into thermal energy storage systems, with a projected CAGR of 11.7%. This shift highlights the industry's focus on energy efficiency and effective thermal solutions.
- Growth of Cold Plates in Electric Vehicle Applications: In 2023, cold plates have become essential for cooling electric vehicle batteries, with significant adoption in the automotive sector. This trend aligns with the increasing focus on thermal management in electric mobility.
- Rise of Vapor Chambers in Gaming Laptops: Vapor chambers have become standard in high-end gaming laptops since 2023, reflecting the demand for effective thermal solutions in consumer electronics. This trend is driven by the growing gaming market in Japan.
Investment Opportunities in the Japan Thermal Management Solutions Market
The following areas offer the clearest openings for investors and suppliers in the Japan Thermal Management Solutions Market.
- HPC Facilities Seeking Advanced Cooling Solutions: High-performance computing facilities are rapidly expanding, creating a demand for advanced cooling solutions. With HPC facilities projected to grow by 15% in the next five years, suppliers can collaborate with system integrators to meet this need.
- Investment in Electric Vehicle Thermal Management: The electric vehicle market is growing, driving demand for thermal management solutions like cold plates. Suppliers can enter this market by partnering with automotive manufacturers to develop tailored cooling systems.
- Growing Demand from Consumer Electronics Manufacturers: Consumer electronics manufacturers are increasingly seeking efficient thermal management solutions. With consumer electronics sales reaching 3 trillion yen in 2023, suppliers can target this sector by offering effective products.
- Support for Energy-Efficient Technologies: The government’s target to reduce energy consumption by 30% by 2030 creates opportunities for suppliers of energy-efficient thermal solutions. Engaging with local partners can facilitate market entry and compliance.
Government Initiatives in the Japan Thermal Management Solutions Market
The Economic Security Promotion Act, enacted in 2022, supports supply-chain resilience for critical products, including thermal management solutions. This law builds on previous regulations, ensuring that manufacturers can secure essential materials and technologies for production, thus improving overall industry stability.
In 2023, a program with a budget of 5 billion yen was launched to support advanced cooling technology development. The Ministry of Economy, Trade and Industry oversees this initiative, aiming to promote innovation and efficiency in the thermal management sector, benefiting both producers and buyers.
Future Insight of the Japan Thermal Management Solutions Market
The adoption of advanced cooling technology will reshape demand by 2032, driven by government support for development programmes. Smart city initiatives in Tokyo will create new opportunities for thermal management solutions. As HPC facilities are set to grow by 15%, the need for efficient cooling systems will rise. With consumer electronics sales reaching 3 trillion yen, suppliers must adapt to meet increasing performance expectations.
Market Segmentation Analysis
Japan Thermal Management Solutions Market report covers a detailed analysis of the following market segments:
By Thermal Management Solutions – Liquid Cooling Systems Lead, Phase Change Materials Expected to Grow Fastest
According to Saurav Kr Singh, Senior Research Analyst at 6Wresearch, Liquid Cooling Systems held 52% of the Japan Thermal Management Solutions Market by thermal management solutions in 2025. Liquid cooling systems hold the largest market share due to their essential function in high-performance computing and data centers, particularly prevalent in the Tokyo region. With over 1,000 data centers operating in Japan, the need for efficient cooling solutions remains high. The quickest growth will come from Phase Change Materials, forecast to expand at a CAGR of 11.7% between 2026 and 2032. The rapid growth of phase change materials is attributed to their increasing utilisation in thermal energy storage systems, which are gaining recognition across various sectors. The government's support for advanced cooling technology development further accelerates this sub-segment's expansion. Suppliers should prioritise the development of advanced cooling technologies to align with the growing market demand.
By Product Type – Cold Plates Lead, PCM Sheets Expected to Grow Fastest
Cold Plates took 42% of product type revenue in 2025, more than any other category. Cold plates dominate the product type segment due to their essential role in liquid cooling systems for electronics, particularly in high-performance computing environments. Their widespread application in over 1,000 data centers in Japan reinforces their leading position. Over 2026–2032, PCM Sheets are expected to post the fastest growth, at a CAGR of 12.6%. PCM sheets are experiencing rapid growth as they find niche applications in thermal regulation, particularly in energy-efficient technologies promoted by the government. This trend highlights a shift towards more sustainable thermal management solutions. Buyers should explore diverse product types to enhance thermal efficiency and meet evolving regulatory standards.
By Technology – Liquid Loop Cooling Leads and Records the Fastest Growth
Liquid Loop Cooling accounted for 43% of the market by technology in 2025. Liquid loop cooling is the leading technology, primarily utilised in high-performance systems that demand effective heat management. Its efficiency in dissipating heat in critical applications, such as those in the Tokyo region, solidifies its market leadership. The same category is also set to grow fastest, at a CAGR of 11.5% during 2026–2032. Liquid loop cooling is also the fastest-growing technology, with continuous improvements expected to broaden its market dominance. The increasing demand for high-performance computing facilities will sustain this upward trajectory. Suppliers need to focus on advancing liquid loop cooling technologies to maintain competitiveness and meet market demands.
By Distribution Channel – OEM Thermal Vendors Lead, System Integrators Expected to Grow Fastest
In 2025, OEM Thermal Vendors led the distribution channel split with a 41% share. OEM thermal vendors are the main suppliers of thermal management solutions, directly catering to manufacturers with essential components. Their established relationships with major electronics producers ensure a steady demand for their products. System Integrators are set to record the highest CAGR in this split, 11.3% over 2026–2032. System integrators are rapidly growing as they increasingly incorporate thermal solutions into complete systems, indicating a market shift towards integrated solutions. This trend emphasises the importance of collaboration between suppliers and integrators. Suppliers should strengthen partnerships with system integrators to expand their market presence and enhance customer satisfaction.
By End User Industry – HPC & Data Centers Lead, Laptop/Desktop OEMs Expected to Grow Fastest
With 52% of end user industry revenue in 2025, HPC & Data Centers was the largest category. HPC and data centers represent the largest end user industry for thermal management solutions, driven by the need for advanced cooling technologies in high-performance environments. The projected 15% growth in HPC facilities will further escalate the demand for these solutions. The quickest growth will come from Laptop/Desktop OEMs, forecast to expand at a CAGR of 12.4% between 2026 and 2032. Laptop and desktop OEMs are the fastest-growing end user segment, as the rising number of personal computing devices boosts the need for effective thermal management. This growth reflects a broader trend towards advanced cooling solutions in various applications. Suppliers should tailor their offerings to meet the specific needs of laptop and desktop manufacturers to capitalise on emerging opportunities.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- Japan Thermal Management Solutions Market Outlook
- Market Size of Japan Thermal Management Solutions Market, 2025
- Forecast of Japan Thermal Management Solutions Market, 2032
- Historical Data and Forecast of Japan Thermal Management Solutions Revenues & Volume for the Period 2022-2032F
- Japan Thermal Management Solutions Market Trend Evolution
- Japan Thermal Management Solutions Market Drivers and Challenges
- Japan Thermal Management Solutions Price Trends
- Japan Thermal Management Solutions Porter's Five Forces
- Japan Thermal Management Solutions Industry Life Cycle
- Historical Data and Forecast of Japan Thermal Management Solutions Market Revenues & Volume By Thermal Management Solutions for the Period 2022-2032F
- Historical Data and Forecast of Japan Thermal Management Solutions Market Revenues & Volume By Heat Pipe Assemblies for the Period 2022-2032F
- Historical Data and Forecast of Japan Thermal Management Solutions Market Revenues & Volume By Liquid Cooling Systems for the Period 2022-2032F
- Historical Data and Forecast of Japan Thermal Management Solutions Market Revenues & Volume By Phase Change Materials for the Period 2022-2032F
- Historical Data and Forecast of Japan Thermal Management Solutions Market Revenues & Volume By Thermal Interface Materials for the Period 2022-2032F
- Historical Data and Forecast of Japan Thermal Management Solutions Market Revenues & Volume By Product Type for the Period 2022-2032F
- Historical Data and Forecast of Japan Thermal Management Solutions Market Revenues & Volume By Vapor Chambers for the Period 2022-2032F
- Historical Data and Forecast of Japan Thermal Management Solutions Market Revenues & Volume By Cold Plates for the Period 2022-2032F
- Historical Data and Forecast of Japan Thermal Management Solutions Market Revenues & Volume By PCM Sheets for the Period 2022-2032F
- Historical Data and Forecast of Japan Thermal Management Solutions Market Revenues & Volume By TIM Pastes for the Period 2022-2032F
- Historical Data and Forecast of Japan Thermal Management Solutions Market Revenues & Volume By Technology for the Period 2022-2032F
- Historical Data and Forecast of Japan Thermal Management Solutions Market Revenues & Volume By Vapor-Phase Cooling for the Period 2022-2032F
- Historical Data and Forecast of Japan Thermal Management Solutions Market Revenues & Volume By Liquid Loop Cooling for the Period 2022-2032F
- Historical Data and Forecast of Japan Thermal Management Solutions Market Revenues & Volume By Solid-Liquid Phase for the Period 2022-2032F
- Historical Data and Forecast of Japan Thermal Management Solutions Market Revenues & Volume By Metal/Graphite Pastes for the Period 2022-2032F
- Historical Data and Forecast of Japan Thermal Management Solutions Market Revenues & Volume By Distribution Channel for the Period 2022-2032F
- Historical Data and Forecast of Japan Thermal Management Solutions Market Revenues & Volume By OEM Thermal Vendors for the Period 2022-2032F
- Historical Data and Forecast of Japan Thermal Management Solutions Market Revenues & Volume By System Integrators for the Period 2022-2032F
- Historical Data and Forecast of Japan Thermal Management Solutions Market Revenues & Volume By Direct Sales for the Period 2022-2032F
- Historical Data and Forecast of Japan Thermal Management Solutions Market Revenues & Volume By Distributors for the Period 2022-2032F
- Historical Data and Forecast of Japan Thermal Management Solutions Market Revenues & Volume By End User Industry for the Period 2022-2032F
- Historical Data and Forecast of Japan Thermal Management Solutions Market Revenues & Volume By Laptop/Desktop OEMs for the Period 2022-2032F
- Historical Data and Forecast of Japan Thermal Management Solutions Market Revenues & Volume By HPC & Data Centers for the Period 2022-2032F
- Historical Data and Forecast of Japan Thermal Management Solutions Market Revenues & Volume By Battery Systems for the Period 2022-2032F
- Historical Data and Forecast of Japan Thermal Management Solutions Market Revenues & Volume By Consumer Electronics for the Period 2022-2032F
- Japan Thermal Management Solutions Import Export Trade Statistics
- Market Opportunity Assessment By Thermal Management Solutions
- Market Opportunity Assessment By Product Type
- Market Opportunity Assessment By Technology
- Market Opportunity Assessment By Distribution Channel
- Market Opportunity Assessment By End User Industry
- Japan Thermal Management Solutions Top Companies Market Share
- Japan Thermal Management Solutions Competitive Benchmarking By Technical and Operational Parameters
- Japan Thermal Management Solutions Company Profiles
- Japan Thermal Management Solutions Key Strategic Recommendations
Market Covered
The report covers the following segments.
By Thermal Management Solutions
- Heat Pipe Assemblies
- Liquid Cooling Systems
- Phase Change Materials
- Thermal Interface Materials
By Product Type
- Vapor Chambers
- Cold Plates
- PCM Sheets
- TIM Pastes
By Technology
- Vapor-Phase Cooling
- Liquid Loop Cooling
- Solid-Liquid Phase
- Metal/Graphite Pastes
By Distribution Channel
- OEM Thermal Vendors
- System Integrators
- Direct Sales
- Distributors
By End User Industry
- Laptop/Desktop OEMs
- HPC & Data Centers
- Battery Systems
- Consumer Electronics































