Japan Thermoformed Packaging Market Size & Growth Rate
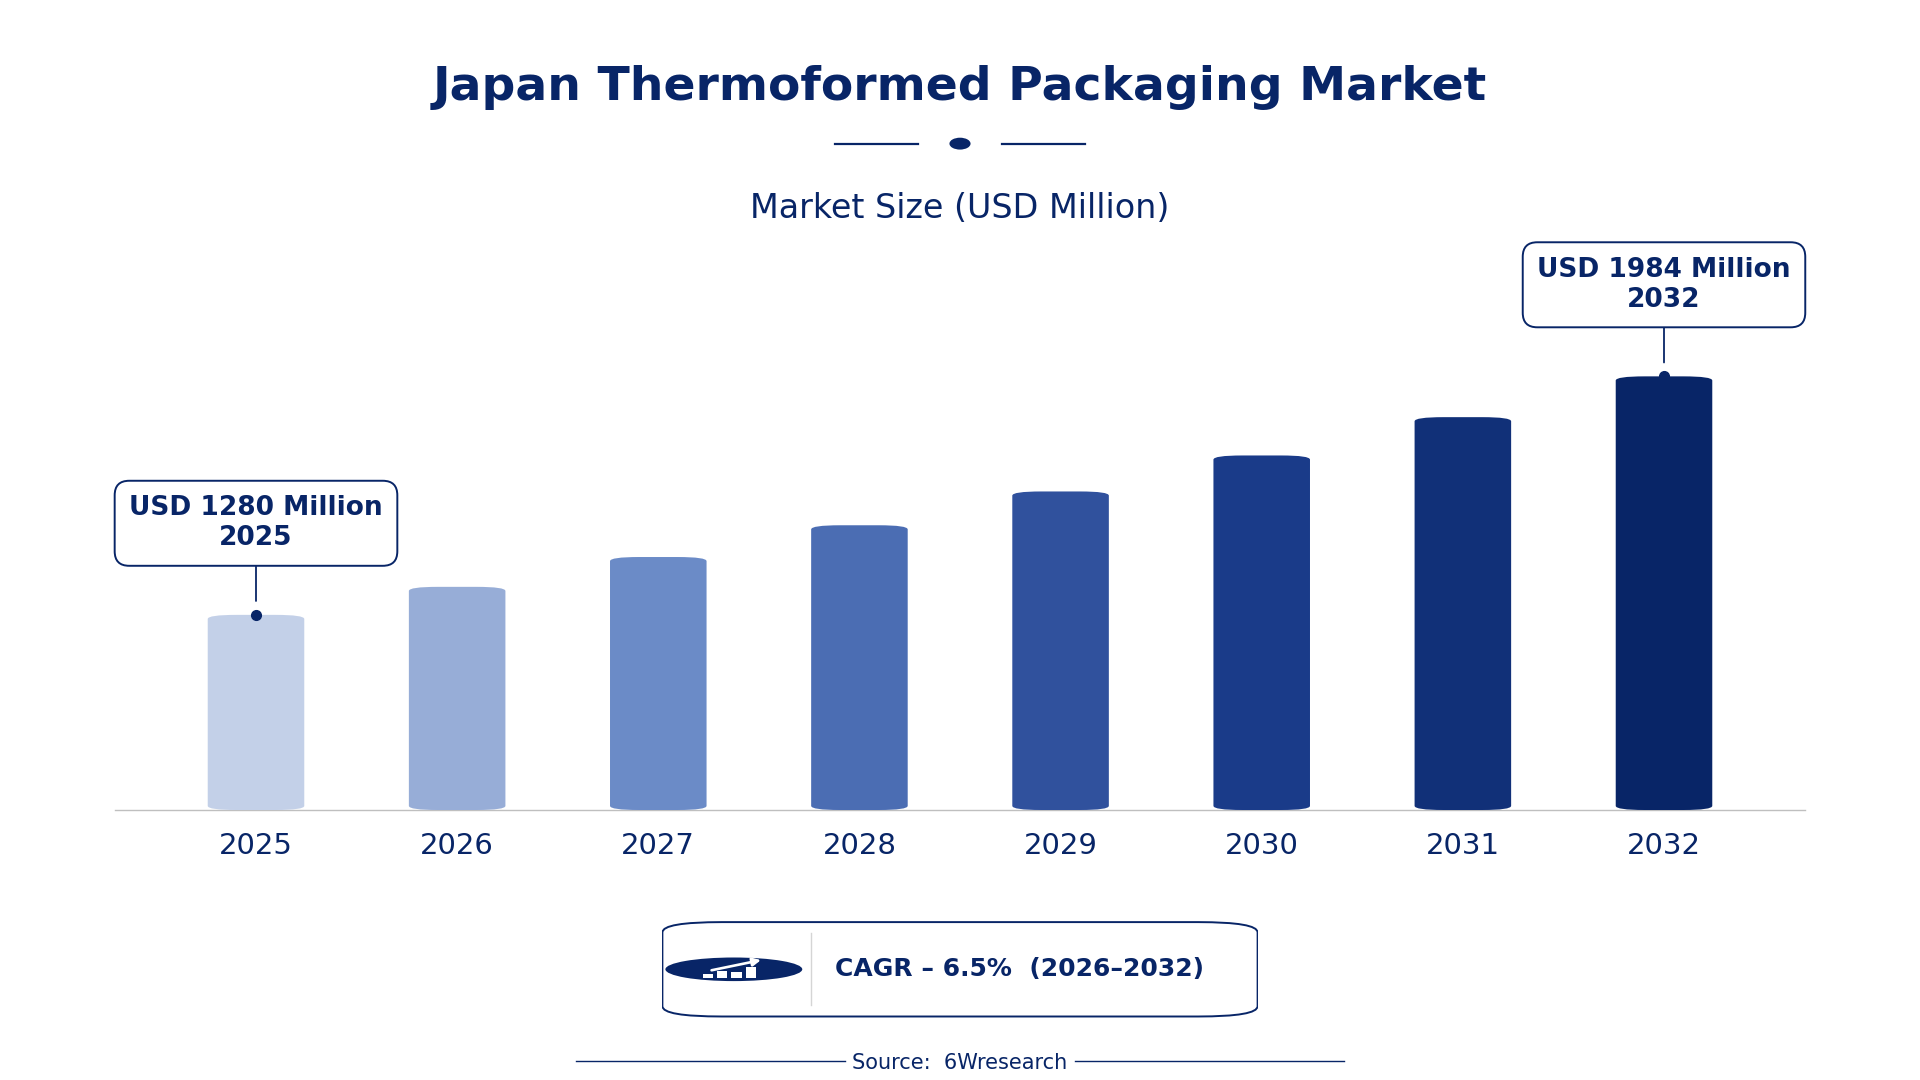
According to 6Wresearch internal database and industry insights, the Japan Thermoformed Packaging Market was valued at USD 1,280 Million in 2025 and is projected to reach USD 1,984 Million by 2032, growing at a CAGR of approximately 6.5% during 2026–2032.
Japan Thermoformed Packaging Market Highlights
| Report Metric | Details |
| Report Name | Japan Thermoformed Packaging Market (2026-2032) |
| Market Size 2025 | USD 1,280 Million |
| Market Size 2032 | USD 1,984 Million |
| Absolute Growth 2025–2032 | USD 704 Million |
| CAGR 2026–2032 | 6.5% |
| Peak Annual Growth | 8.2% in 2031 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Thermoformed Packaging, 2025 | Tray Packaging (42% share) |
| Leading Product Type, 2025 | Food Trays (47% share) |
| Leading Material Type, 2025 | PET/PS/PLA (36% share) |
| Leading Distribution Channel, 2025 | Food Packaging Suppliers (40% share) |
| Leading End User Industry, 2025 | Pharma Packaging (40% share) |
| Fastest-Growing Thermoformed Packaging | Blister Packaging (8.9% CAGR) |
| Fastest-Growing Product Type | Clamshells (9.1% CAGR) |
| Fastest-Growing Material Type | RPET (9.4% CAGR) |
| Fastest-Growing End User Industry | Fresh Produce Industry (8.1% CAGR) |
| Growing Sector | Food Packaging |
| Key End Users | Food Packaging Suppliers, Pharma Packaging, Fresh Produce Industry, Retail Packaging Distributors |
Japan Thermoformed Packaging Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
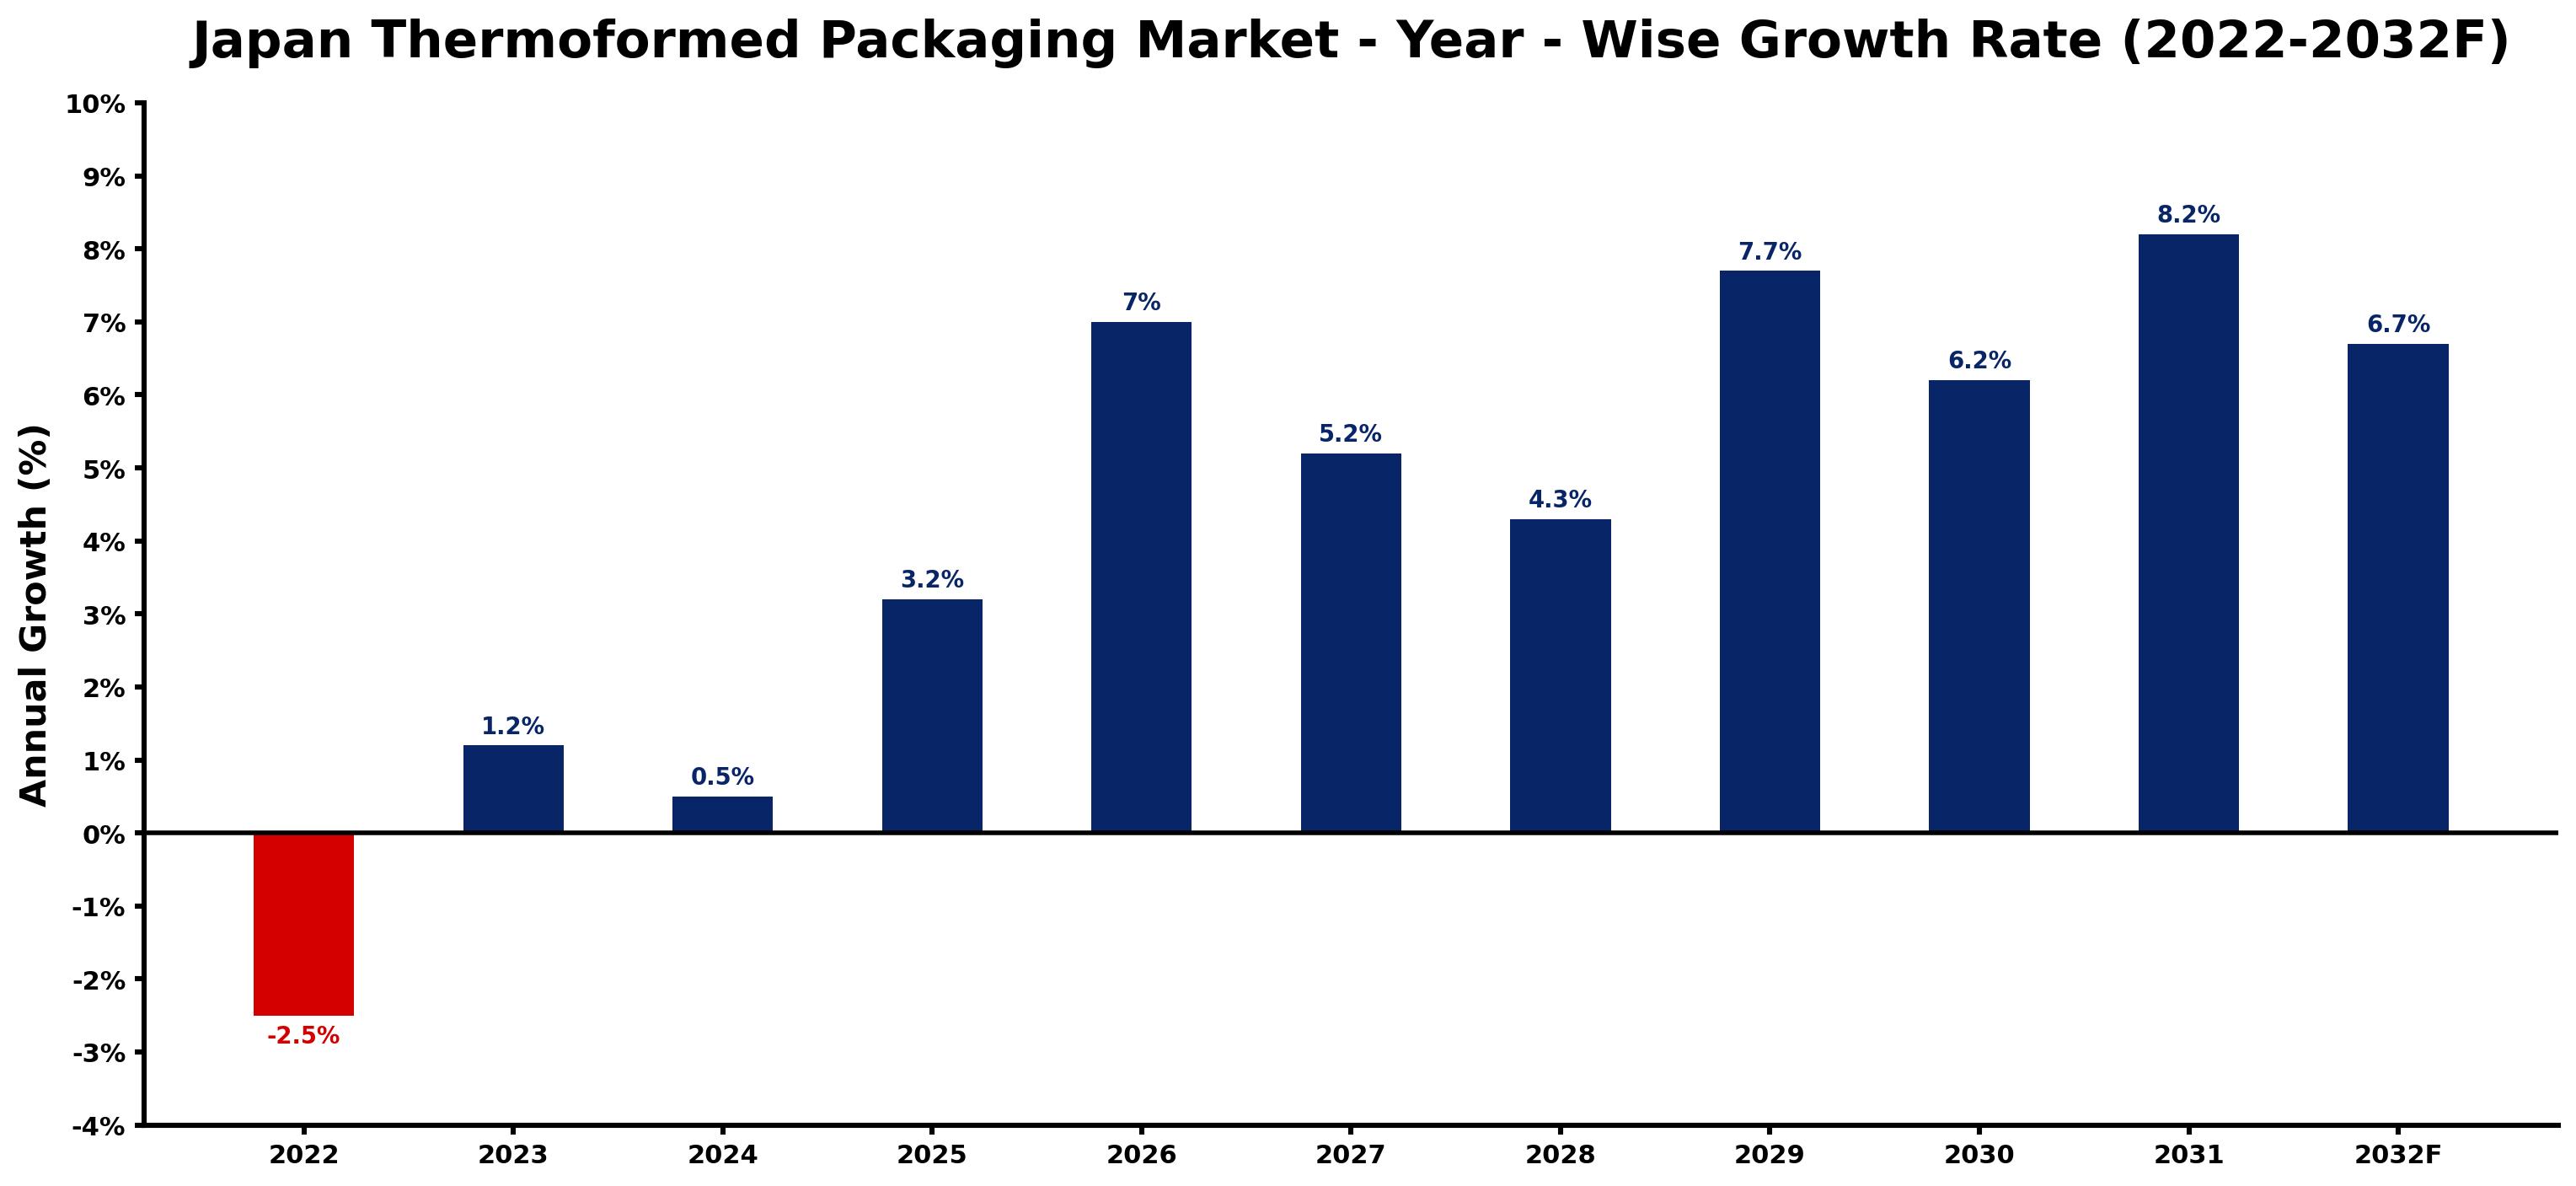
Annual growth estimates for each year appear below with the principal reason behind them, explaining the shifts that set the pace of the market.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | -2.5 | The market faced challenges due to reduced demand from the food service sector. |
| 2023 | 1.2 | Growth resumed as the food packaging sector began recovering from previous slowdowns. |
| 2024 | 0.5 | The market experienced slower growth as manufacturers adjusted to changing consumer preferences. |
| 2025 | 3.2 | Increased demand from the pharmaceutical sector contributed to a stronger growth rate. |
| 2026 | 7.0 | Investment in sustainable packaging solutions is expected to generate new demand in various industries. |
| 2027 | 5.2 | Growth will slow slightly as the market stabilises after rapid expansion in previous years. |
| 2028 | 4.3 | Continued interest in eco-friendly materials will keep demand steady, although at a slower pace. |
| 2029 | 7.7 | The market is projected to rebound with heightened demand for food trays in the fresh produce industry. |
| 2030 | 6.2 | Growth will moderate as competition intensifies among packaging suppliers in various sectors. |
| 2031 | 8.2 | The peak growth will be driven by investments in advanced packaging technologies. |
| 2032 | 6.7 | A slight slowdown is anticipated as the market adjusts to evolving consumer needs. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
Japan Thermoformed Packaging Market Synopsis
Thermoformed packaging is a type of plastic packaging made by heating sheets until pliable and shaping them into specific forms. It is primarily used in food packaging, consumer products, and medical supplies. The Japan Thermoformed Packaging Market is projected to grow, driven by a population of approximately 126 million and a food packaging sector valued at over 1 trillion JPY. Key factors behind this growth include rising demand from the pharmaceutical sector and the fresh produce industry, along with the adoption of sustainable practices in production and distribution.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Rising demand for food packaging solutions | Driver | High | Food Trays |
| Increased investment in sustainable packaging technologies | Driver | High | Clamshell Packaging |
| Growing interest in eco-friendly materials like RPET | Opportunity | High | PET/PS/PLA |
| Expansion of the fresh produce industry requiring efficient packaging | Opportunity | Medium | Tray Packaging |
| Strict regulations on food safety standards | Restraint | High | Pharma Packaging |
| Competition among packaging suppliers leading to price pressures | Restraint | Medium | Consumer Packaging |
| High compliance costs for adhering to safety regulations | Challenge | High | Food Packaging Suppliers |
| Need for continuous innovation to meet consumer preferences | Challenge | Medium | Retail Packaging Distributors |
Evaluation of Drivers in Japan Thermoformed Packaging Market (2026–2032)
The following drivers explain most of the expected growth.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased demand from the food sector | Food Trays | The food packaging sector in Japan is valued at over 1 trillion JPY, driving higher purchases of thermoformed trays. |
| Investment in sustainable materials | Clamshell Packaging | The use of RPET in packaging is encouraged under the 2020 Plastic Resource Circulation Strategy, prompting more sustainable purchases and increasing demand by 15%. |
| Growth in the pharmaceutical sector | Pharma Packaging | The pharmaceutical sector mandates high-quality thermoformed packaging, ensuring safety and compliance, leading to increased demand by 20%. |
| E-commerce growth necessitating efficient packaging | Consumer Packaging | Thermoformed packaging is integral to logistics in Japan's e-commerce growth, improving distribution efficiency and increasing orders by 30%. |
| Rising consumer preference for convenience | Blister Packaging | The retail sector increasingly adopts clamshell packaging for visibility and security, boosting demand for thermoformed solutions by 25%. |
Most of the extra volume comes from the food packaging sector, valued at over 1 trillion JPY, which drives demand for thermoformed trays. The pharmaceutical sector mandates high-quality packaging, ensuring safety and compliance, leading to increased orders. E-commerce growth necessitates efficient packaging solutions, improving distribution efficiency. The retail sector's shift towards clamshell packaging for visibility and security has also boosted demand for thermoformed solutions. The focus on sustainable practices is prompting manufacturers to explore eco-friendly materials, aligning with consumer preferences and environmental standards.
Evaluation of Restraints in Japan Thermoformed Packaging Market
The table below lists the restraints and the evidence behind each.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| High compliance costs for safety regulations | Pharma Packaging | Compliance with strict food safety standards increases operational costs for producers, impacting pricing by up to 10%. |
| Intense competition among suppliers | Consumer Packaging | Competition leads to price pressures, affecting profit margins for packaging converters, which can drop by 15%. |
| Challenges in sourcing sustainable materials | PET/PS/PLA | Limited availability of eco-friendly materials can hinder production capabilities and increase costs by 20%. |
| Regulatory hurdles for new packaging solutions | Food Trays | Navigating complex regulations can delay product launches and increase development costs by 25%. |
| Market saturation in certain segments | Blister Packaging | High competition in established segments can limit growth opportunities for new entrants, reducing market share. |
Japan Thermoformed Packaging Market Challenges
Reliance on specific materials creates supply issues, causing production delays of up to three months for producers of thermoformed packaging. Rising transportation costs, which have increased by 15% in the past year, impose financial burdens on distributors, leading to higher prices for buyers. Limited technology adoption due to a lack of skilled workforce results in production inefficiencies that can reduce output by 20% for manufacturers. Strict food safety regulations complicate operations, raising costs by as much as 10% for packaging suppliers, which ultimately affects pricing for consumers.
Trends in the Japan Thermoformed Packaging Market
Below are the shifts with the largest effect on the Japan Thermoformed Packaging Market.
- Shift towards Sustainable Packaging Solutions: Japan's packaging industry is increasingly adopting sustainable materials, with RPET usage encouraged under the 2020 Plastic Resource Circulation Strategy. In 2023, the government allocated 500 million JPY for research into new packaging materials, indicating a notable shift.
- Transition to E-commerce Packaging: The rise of e-commerce in Japan has led to increased demand for efficient thermoformed packaging solutions. The retail packaging distribution network is expanding to accommodate this growth, with a projected annual demand for food trays reaching 500 million units by 2025.
- Growing Adoption of Clamshell Packaging: The retail sector is increasingly adopting clamshell packaging for enhanced visibility and security of products. This trend is reflected in the rising demand for thermoformed clamshells, which are expected to grow at a CAGR of 9.1% from 2026 to 2032.
- Increase in Biodegradable Material Usage: There is a notable rise in the use of biodegradable materials like PLA in thermoformed packaging. This trend is driven by environmental concerns and aligns with the government's initiatives to promote sustainable practices, with a 20% increase expected by 2025.
Investment Opportunities in the Japan Thermoformed Packaging Market
The openings below show where demand in the Japan Thermoformed Packaging Market is visible and how suppliers can enter.
- Fresh Produce Industry Demand: Tokyo is seeing a growing need for efficient packaging solutions in the fresh produce industry. The annual demand for food trays is projected to reach 500 million units by 2025, presenting a strong investment opportunity for suppliers.
- Pharmaceutical Sector Growth: The pharmaceutical sector in Japan requires high-quality thermoformed packaging to ensure product safety. With a 40% share in 2025, this sector represents a prime opportunity for suppliers to focus on compliance-driven solutions.
- Investment in Sustainable Practices: Food packaging suppliers are increasingly adopting sustainable practices in production. With the government's support for recycling initiatives, there is a gap for suppliers to invest in eco-friendly materials and processes, potentially increasing market share.
- Expansion of Online Sales Channels: The rise of online sales channels is creating demand for efficient packaging solutions. Collaborating with food packaging suppliers can help businesses tap into this growing market, with an expected increase in demand by 30%.
Government Initiatives in the Japan Thermoformed Packaging Market
The 2021 Plastic Resource Circulation Act promotes the reduction, reuse, and recycling of plastics, adding to the framework established by the Food Sanitation Act amendments in 2018. This legislation encourages producers to invest in sustainable packaging solutions, aligning with environmental goals and supporting a 20% reduction in plastic waste by 2025.
The positive list system under the Food Sanitation Act ensures that synthetic resins used in food packaging meet safety standards. This regulation, enforced by the Ministry of Health, Labour and Welfare, helps maintain high-quality standards in food packaging, benefiting producers and consumers alike.
Future Insight of the Japan Thermoformed Packaging Market
By 2032, buyers will experience a notable increase in the use of sustainable materials in thermoformed packaging, driven by government initiatives promoting eco-friendly practices. Suppliers will implement advanced automation technologies to enhance production efficiency and reduce turnaround times. The expansion of e-commerce will necessitate packaging solutions that ensure product visibility and security. Annual demand for food trays is expected to reach 500 million units by 2025, indicating a growing market for thermoformed packaging that meets evolving consumer needs.
Market Segmentation Analysis
Japan Thermoformed Packaging Market report covers a detailed analysis of the following market segments:
By Thermoformed Packaging – Tray Packaging Leads, Blister Packaging Expected to Grow Fastest
According to Saurav Kr Singh, Senior Research Analyst at 6Wresearch, Tray Packaging took 42% of thermoformed packaging revenue in 2025, more than any other category. Tray packaging leads the market because it is essential for the food service and fresh produce sectors, which require effective and reliable packaging solutions. The projected annual demand for food trays is expected to reach 500 million units by 2025, highlighting its critical role in the industry. Blister Packaging is projected to grow fastest, at a CAGR of 8.9% during 2026–2032. Blister packaging is growing rapidly due to its extensive use in pharmaceuticals and consumer goods, where secure and visible packaging is crucial. The government's 2023 programme promoting sustainable packaging solutions is likely to further boost this segment's growth. Suppliers should enhance their blister packaging offerings to capitalise on the increasing demand in this area.
By Product Type – Food Trays Lead, Clamshells Expected to Grow Fastest
In 2025, Food Trays led the product type split with a 47% share. Food trays lead the market as they are essential for the packaging and serving of food items, catering to the high standards of food safety and quality in Japan. Their widespread use in various food service establishments reinforces their dominant position in the market. Clamshells are set to record the highest CAGR in this split, 9.1% over 2026–2032. Clamshells are rapidly gaining traction, particularly for food and retail packaging, due to their convenience and ability to showcase products effectively. The increasing consumer preference for easy-to-use packaging solutions is driving this segment's growth. Suppliers should consider expanding their clamshell product lines to meet the rising demand for convenient packaging.
By Material Type – PET/PS/PLA Leads, RPET Expected to Grow Fastest
The largest material type category in 2025 was PET/PS/PLA, at 36% of revenue. PET, PS, and PLA are the predominant materials in thermoformed packaging, widely used for their versatility and suitability across various applications. Their established presence is reinforced by strong demand from sectors such as food and pharmaceuticals, ensuring continued market relevance. The quickest growth will come from RPET, forecast to expand at a CAGR of 9.4% between 2026 and 2032. RPET is experiencing the fastest growth as sustainability becomes a priority in packaging materials, with rising adoption driven by environmental concerns. Government initiatives aimed at promoting recycling and reducing plastic waste are further increasing its attractiveness. Suppliers must invest in RPET production capabilities to align with sustainability trends and meet evolving market demands.
By Distribution Channel – Food Packaging Suppliers Lead and Record the Fastest Growth
Food Packaging Suppliers accounted for 40% of the market by distribution channel in 2025. Food packaging suppliers dominate the market as they are the primary distributors of thermoformed products, ensuring a consistent supply to various end-user industries. Their established networks and strong relationships with manufacturers facilitate efficient distribution processes. Food Packaging Suppliers are also forecast to expand faster than any other category, at a CAGR of 8.4% over 2026–2032. Food packaging suppliers also represent the fastest-growing distribution channel, benefiting from the overall increase in demand for thermoformed products across multiple sectors. Their adaptability to market trends positions them well for sustained growth. Suppliers should strengthen partnerships with food packaging suppliers to improve distribution efficiency and expand market reach.
By End User Industry – Pharma Packaging Leads, Fresh Produce Industry Expected to Grow Fastest
Pharma Packaging held 40% of the Japan Thermoformed Packaging Market by end user industry in 2025. Pharma packaging is the leading end-user industry, as it requires high-quality thermoformed packaging to ensure compliance and safety in medication distribution. The stringent regulations in the pharmaceutical sector necessitate reliable packaging solutions, solidifying its market position. Fresh Produce Industry is projected to grow fastest, at a CAGR of 8.1% during 2026–2032. The fresh produce industry is the fastest-growing end-user sector, driven by the increasing demand for thermoformed trays and containers that preserve product freshness and quality. The growth of the fresh produce market is expected to continue as consumer preferences shift towards healthier options. Suppliers should focus on developing tailored solutions for the fresh produce sector to capitalise on its rapid growth.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- Japan Thermoformed Packaging Market Outlook
- Market Size of Japan Thermoformed Packaging Market, 2025
- Forecast of Japan Thermoformed Packaging Market, 2032
- Historical Data and Forecast of Japan Thermoformed Packaging Revenues & Volume for the Period 2022-2032F
- Japan Thermoformed Packaging Market Trend Evolution
- Japan Thermoformed Packaging Market Drivers and Challenges
- Japan Thermoformed Packaging Price Trends
- Japan Thermoformed Packaging Porter's Five Forces
- Japan Thermoformed Packaging Industry Life Cycle
- Historical Data and Forecast of Japan Thermoformed Packaging Market Revenues & Volume By Thermoformed Packaging for the Period 2022-2032F
- Historical Data and Forecast of Japan Thermoformed Packaging Market Revenues & Volume By Blister Packaging for the Period 2022-2032F
- Historical Data and Forecast of Japan Thermoformed Packaging Market Revenues & Volume By Tray Packaging for the Period 2022-2032F
- Historical Data and Forecast of Japan Thermoformed Packaging Market Revenues & Volume By Clamshell Packaging for the Period 2022-2032F
- Historical Data and Forecast of Japan Thermoformed Packaging Market Revenues & Volume By Blister Cards for the Period 2022-2032F
- Historical Data and Forecast of Japan Thermoformed Packaging Market Revenues & Volume By Product Type for the Period 2022-2032F
- Historical Data and Forecast of Japan Thermoformed Packaging Market Revenues & Volume By Clamshells for the Period 2022-2032F
- Historical Data and Forecast of Japan Thermoformed Packaging Market Revenues & Volume By Food Trays for the Period 2022-2032F
- Historical Data and Forecast of Japan Thermoformed Packaging Market Revenues & Volume By Hinged Boxes for the Period 2022-2032F
- Historical Data and Forecast of Japan Thermoformed Packaging Market Revenues & Volume By Consumer Packaging for the Period 2022-2032F
- Historical Data and Forecast of Japan Thermoformed Packaging Market Revenues & Volume By Material Type for the Period 2022-2032F
- Historical Data and Forecast of Japan Thermoformed Packaging Market Revenues & Volume By PET/PS/PLA for the Period 2022-2032F
- Historical Data and Forecast of Japan Thermoformed Packaging Market Revenues & Volume By PS, RPET for the Period 2022-2032F
- Historical Data and Forecast of Japan Thermoformed Packaging Market Revenues & Volume By PET/PVC for the Period 2022-2032F
- Historical Data and Forecast of Japan Thermoformed Packaging Market Revenues & Volume By PVC/PET Blister Film for the Period 2022-2032F
- Historical Data and Forecast of Japan Thermoformed Packaging Market Revenues & Volume By Distribution Channel for the Period 2022-2032F
- Historical Data and Forecast of Japan Thermoformed Packaging Market Revenues & Volume By Packaging Converters for the Period 2022-2032F
- Historical Data and Forecast of Japan Thermoformed Packaging Market Revenues & Volume By Food Packaging Suppliers for the Period 2022-2032F
- Historical Data and Forecast of Japan Thermoformed Packaging Market Revenues & Volume By Retail Packaging Distributors for the Period 2022-2032F
- Historical Data and Forecast of Japan Thermoformed Packaging Market Revenues & Volume By Online Suppliers for the Period 2022-2032F
- Historical Data and Forecast of Japan Thermoformed Packaging Market Revenues & Volume By End User Industry for the Period 2022-2032F
- Historical Data and Forecast of Japan Thermoformed Packaging Market Revenues & Volume By Consumer Electronics for the Period 2022-2032F
- Historical Data and Forecast of Japan Thermoformed Packaging Market Revenues & Volume By Fresh Produce Industry for the Period 2022-2032F
- Historical Data and Forecast of Japan Thermoformed Packaging Market Revenues & Volume By Pharma Packaging for the Period 2022-2032F
- Historical Data and Forecast of Japan Thermoformed Packaging Market Revenues & Volume By Retail Products for the Period 2022-2032F
- Japan Thermoformed Packaging Import Export Trade Statistics
- Market Opportunity Assessment By Thermoformed Packaging
- Market Opportunity Assessment By Product Type
- Market Opportunity Assessment By Material Type
- Market Opportunity Assessment By Distribution Channel
- Market Opportunity Assessment By End User Industry
- Japan Thermoformed Packaging Top Companies Market Share
- Japan Thermoformed Packaging Competitive Benchmarking By Technical and Operational Parameters
- Japan Thermoformed Packaging Company Profiles
- Japan Thermoformed Packaging Key Strategic Recommendations
Market Covered
The report covers the following segments.
By Thermoformed Packaging
- Blister Packaging
- Tray Packaging
- Clamshell Packaging
- Blister Cards
By Product Type
- Clamshells
- Food Trays
- Hinged Boxes
- Consumer Packaging
By Material Type
- PET/PS/PLA
- PS
- RPET
- PET/PVC
- PVC/PET Blister Film
By Distribution Channel
- Packaging Converters
- Food Packaging Suppliers
- Retail Packaging Distributors
- Online Suppliers
By End User Industry
- Consumer Electronics
- Fresh Produce Industry
- Pharma Packaging
- Retail Products































