China Acute Care Services Market Size & Growth Rate
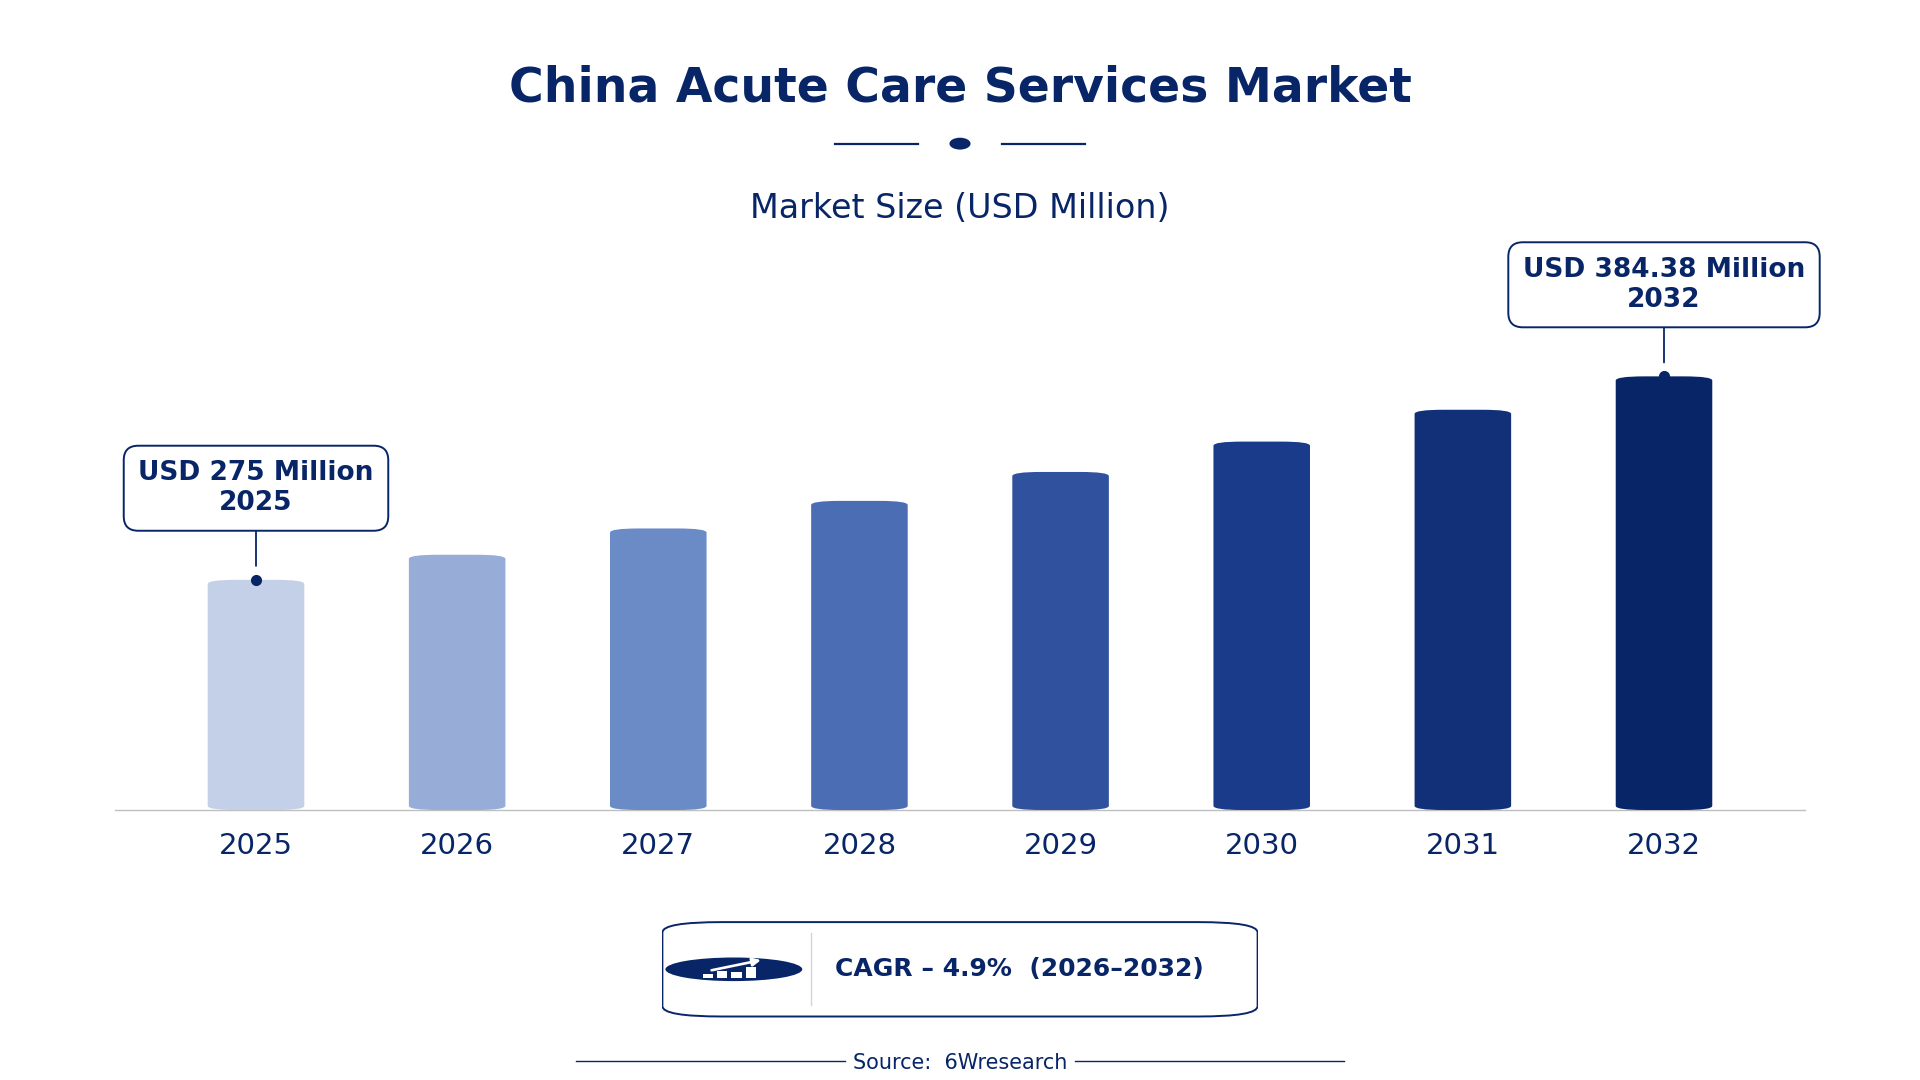
According to 6Wresearch internal database and industry insights, the China Acute Care Services Market was valued at USD 275.0 million in 2025 and is projected to reach USD 384.38 million by 2032, growing at a CAGR of approximately 4.9% during 2026–2032.
China Acute Care Services Market Highlights
| Report Metric | Details |
| Report Name | China Acute Care Services Market |
| Market Size 2025 | USD 275.0 million |
| Market Size 2032 | USD 384.38 million |
| Absolute Growth 2025–2032 | USD 109.38 million |
| CAGR 2026–2032 | 4.9% |
| Peak Annual Growth | 7.3% in 2027 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Product Type, 2025 | Emergency Care (35% share) |
| Leading Service Setting, 2025 | Hospital-Based (46% share) |
| Leading Distribution Channel, 2025 | Direct Sales (50% share) |
| Leading End User, 2025 | Hospitals (34% share) |
| Leading Service Type, 2025 | Life-Saving Care (34% share) |
| Fastest-Growing Product Type | Trauma Services (6.8% CAGR) |
| Fastest-Growing Service Setting | Ambulatory Services (7.3% CAGR) |
| Fastest-Growing End User | Trauma Centers (7.5% CAGR) |
| Fastest-Growing Service Type | Emergency Procedures (7.2% CAGR) |
| Growing Sector | Emergency Care |
| Key End Users | Hospitals, Trauma Centers, Government Health Agencies, Healthcare Providers |
China Acute Care Services Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
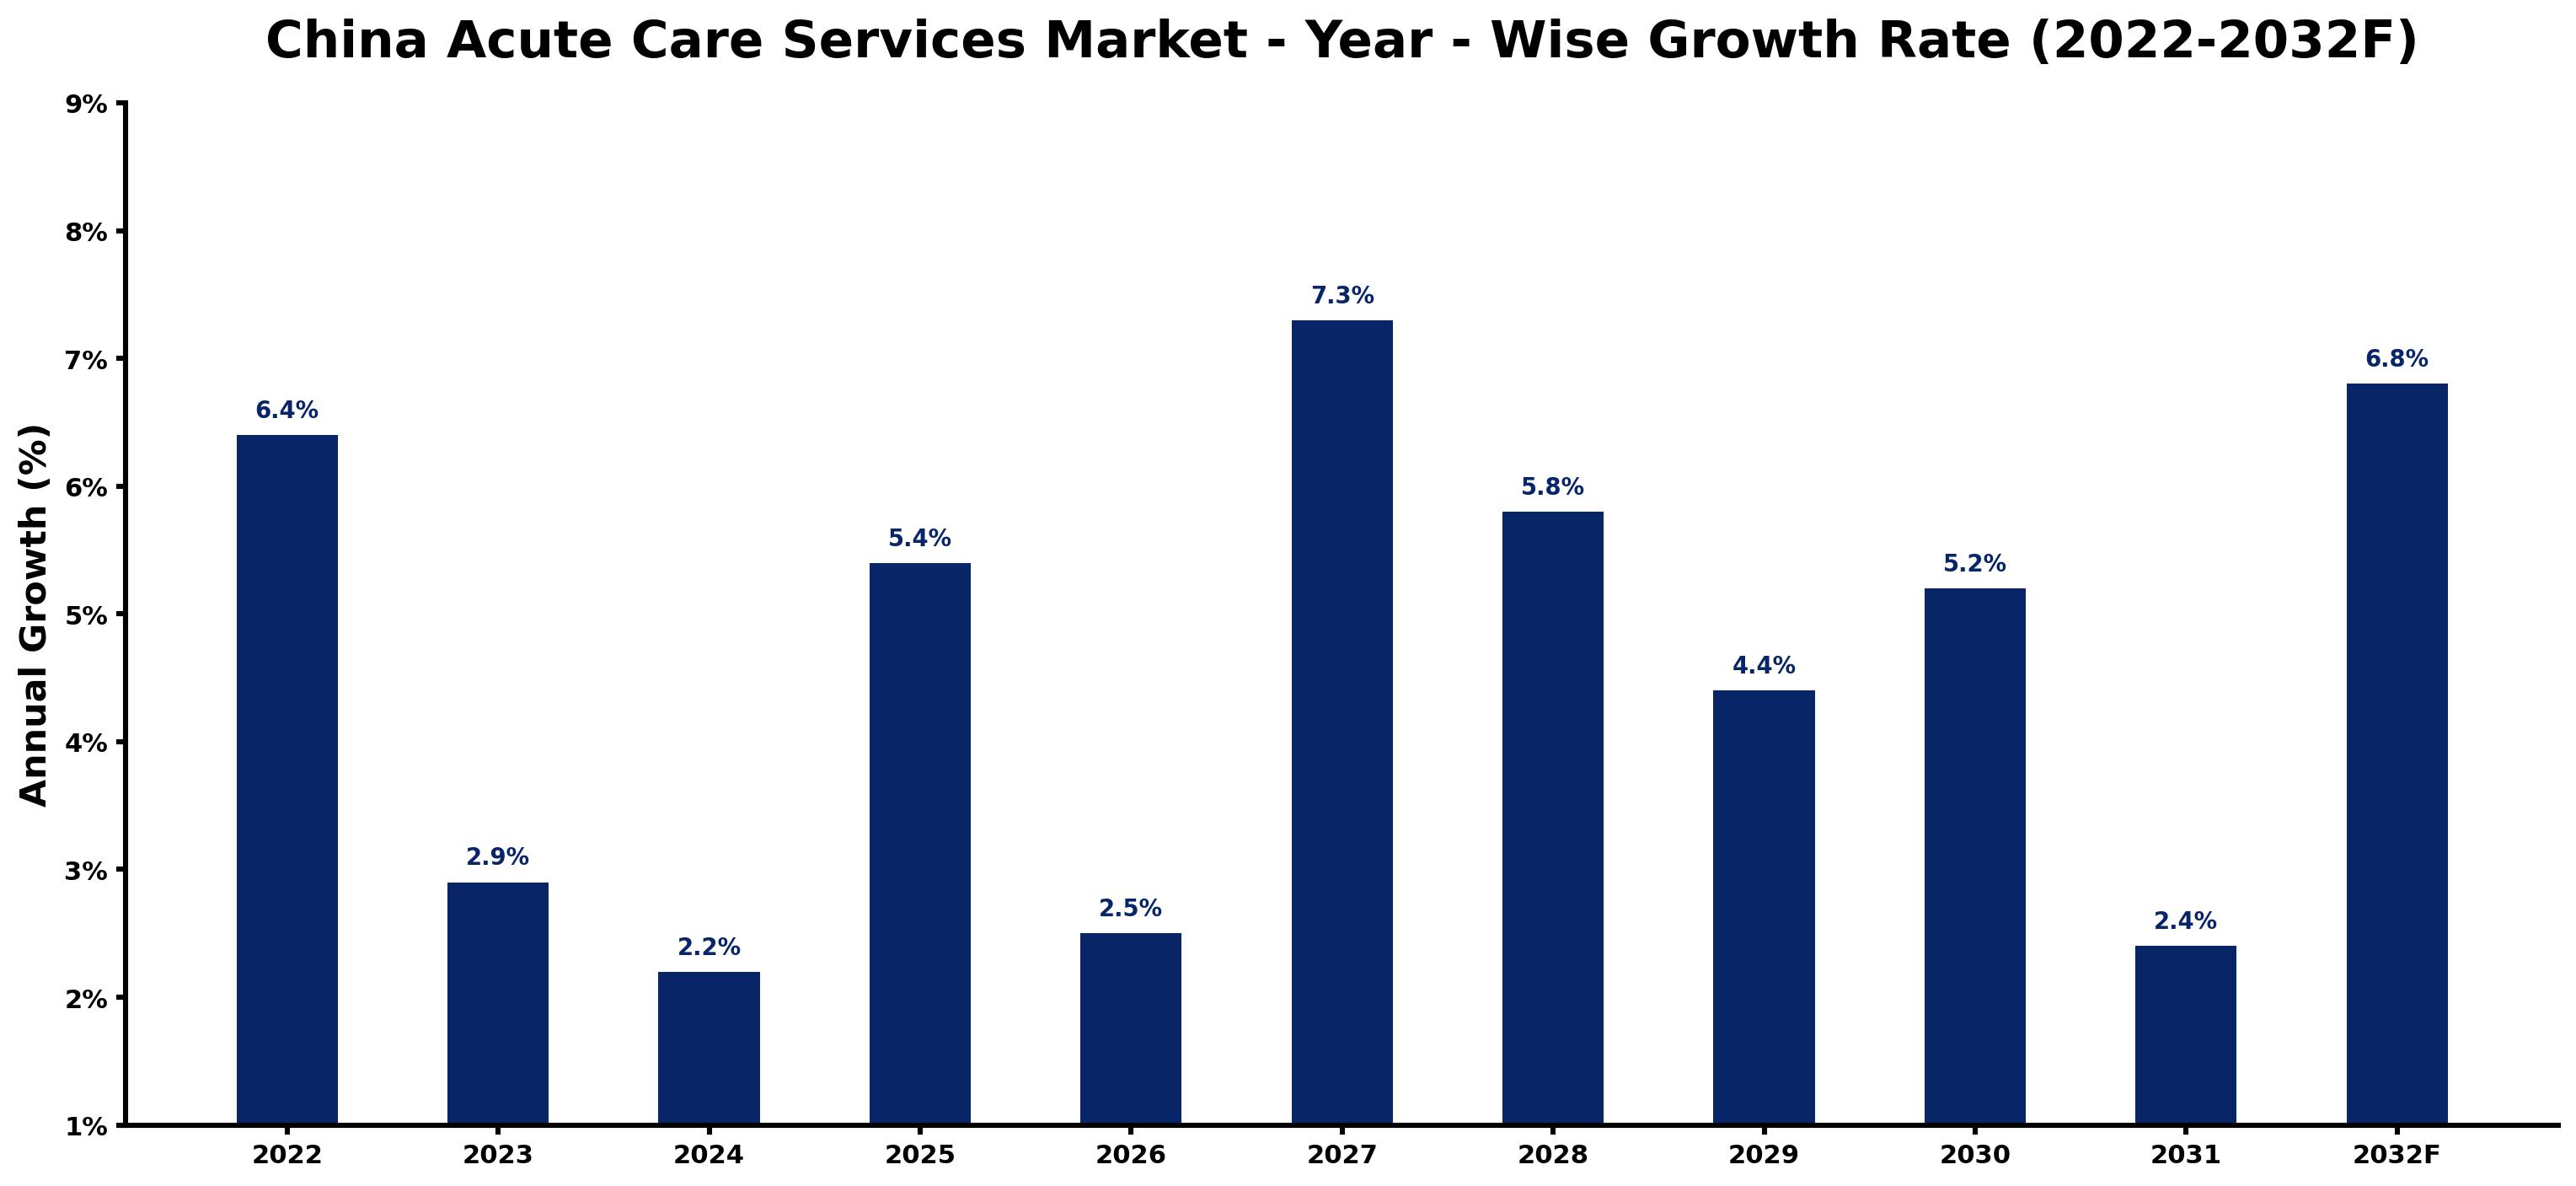
Year by year, the estimates below pair each growth rate with the development that shaped it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 6.4 | The market experienced solid growth due to rising healthcare demands and a focus on emergency services. |
| 2023 | 2.9 | Growth slowed as the healthcare sector adjusted to new standards and protocols. |
| 2024 | 2.2 | Continued adjustments in the healthcare sector contributed to a further slowdown in growth. |
| 2025 | 5.4 | Increased investments in hospital infrastructure led to a rebound in growth rates. |
| 2026 | 2.5 | Growth slowed again as the market stabilised after the previous year's surge. |
| 2027 | 7.3 | A peak in growth was driven by the implementation of new emergency care initiatives. |
| 2028 | 5.8 | Growth slowed as the market adjusted to the rapid expansion of services. |
| 2029 | 4.4 | The market continued to grow, albeit at a slower pace, due to ongoing healthcare reforms. |
| 2030 | 5.2 | A resurgence in growth occurred as hospitals expanded acute care services. |
| 2031 | 2.4 | Growth slowed as the market began to stabilise after several years of rapid expansion. |
| 2032 | 6.8 | An increase in demand for life-saving care contributed to a strong growth rate. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Acute Care Services Market Synopsis
Acute Care Services in China provide urgent medical treatments for severe health conditions, typically delivered in hospitals. These services are crucial for managing life-threatening injuries and critical illnesses. The China Acute Care Services Market is expanding due to a growing population and rising healthcare demands. The government's 'Healthy China 2030' initiative aims to improve healthcare access, further increasing demand. Investments in hospital infrastructure and emergency care services also play a key role in market expansion.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Rising population and healthcare demands drive the need for acute care services. | Driver | High | Emergency Care |
| Government initiatives to improve healthcare access are expanding service availability. | Driver | High | Intensive Care |
| Urban areas are experiencing a shortage of trauma services, creating a need for new facilities. | Opportunity | High | Trauma Services |
| The expansion of ambulatory services presents opportunities for investment in outpatient care. | Opportunity | High | Ambulatory Services |
| Limited funding for rural healthcare facilities restricts service availability in those areas. | Restraint | High | Post-Operative Care |
| The high cost of advanced medical equipment can limit service expansion in hospitals. | Restraint | Medium | Coronary Care |
| Regulatory approvals for new healthcare facilities can delay service availability. | Challenge | High | Hospital-Based |
| Shortages of trained medical personnel can impact service delivery in acute care settings. | Challenge | Medium | Trauma Services |
Evaluation of Drivers in China Acute Care Services Market (2026–2032)
The table below links each growth driver to the segment it affects and the evidence for it.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increasing investments in hospital infrastructure improve service delivery. | Emergency Care | In 2023, the government invested $10 billion in healthcare infrastructure improvements, leading to more emergency care facilities. |
| Government initiatives are expanding access to acute care services. | Intensive Care | The 'Healthy China 2030' initiative aims to improve healthcare access, resulting in more intensive care units in urban hospitals. |
| The growing urban population increases demand for trauma services. | Trauma Services | In 2023, urban areas are seeing a rise in trauma cases, necessitating more trauma centers. |
| Standardisation of life-saving care protocols improves service quality. | Life-Saving Care | Protocols set by the National Health Commission improve the effectiveness of life-saving procedures across hospitals. |
| Integration of cardiology units into emergency departments boosts service efficiency. | Coronary Care | Cardiology units in major cities streamline emergency responses to heart-related emergencies, increasing patient throughput. |
Market growth in China for Acute Care Services rests on increasing investments in hospital infrastructure, government initiatives to improve healthcare access, and a growing urban population. In 2023, the government allocated $10 billion for healthcare improvements, which improved service delivery. The 'Healthy China 2030' initiative is expected to increase the number of intensive care units in urban hospitals. Urban areas are experiencing a rise in trauma cases, necessitating more trauma centers. The integration of cardiology units into emergency departments is streamlining responses to heart-related emergencies, further driving demand.
Evaluation of Restraints in China Acute Care Services Market
The table below lists the restraints and the evidence behind each.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Limited funding for rural healthcare facilities restricts service availability. | Post-Operative Care | Rural areas often lack adequate funding, resulting in fewer post-operative care options for patients. |
| High costs of advanced medical equipment can limit service expansion. | Coronary Care | The financial burden of acquiring advanced equipment can deter hospitals from expanding coronary care services. |
| Regulatory approvals for new healthcare facilities can delay service availability. | Hospital-Based | Stringent regulatory processes can prolong the time it takes to establish new hospital services. |
| Shortages of trained medical personnel can impact service delivery. | Trauma Services | A lack of qualified staff in trauma centers can lead to delays in patient treatment. |
| Competition for government contracts can limit opportunities for private providers. | Direct Sales | Government contracts are often awarded to established providers, restricting access for new entrants. |
China Acute Care Services Market Challenges
Acute care services in China face a significant skills shortage, as training programs cannot keep pace with the healthcare demands of a population exceeding 1.4 billion, resulting in longer wait times for patients. Intense competition among hospitals drives down prices, which can lead to compromised quality and ultimately affect patient outcomes. Regulatory compliance with the National Health Commission's evolving standards increases operational costs for hospitals, delaying service delivery and straining resources. Rapid technological advancements often exceed the capabilities of existing infrastructure, causing inefficiencies that hinder effective patient treatment in many facilities.
Trends in the China Acute Care Services Market
Below mentioned are some of the trends shaping the China Acute Care Services Market growth.
- Integration of Cardiology Units into Emergency Departments: In 2023, cardiology units are increasingly integrated into emergency departments across major cities, improving response times for heart-related emergencies. This integration is projected to improve patient outcomes and streamline care delivery.
- Expansion of Ambulatory Services in Urban Areas: Since 2020, ambulatory services have been expanding rapidly in urban areas, with a growth rate of 15% annually. This trend is addressing the rising demand for outpatient care and reducing pressure on hospitals.
- Focus on Life-Saving Care Protocols: In 2023, life-saving care protocols are being standardised across hospitals, ensuring consistent quality of care. This standardisation is important for improving patient outcomes in emergency situations.
- Development of Trauma Centers in High-Risk Areas: The establishment of trauma centers in metropolitan areas with high accident rates is a priority. As of 2023, there are 1,200 certified trauma centers across China, improving emergency response capabilities.
Investment Opportunities in the China Acute Care Services Market
Several openings in the China Acute Care Services Market merit attention from investors.
- Investment in Trauma Centers in Urban Areas: Urban areas with high accident rates present opportunities for investment in trauma centers. With 1,200 certified trauma centers as of 2023, there is a notable gap in service availability.
- Expansion of Ambulatory Services: Ambulatory services are growing rapidly, with a 15% annual growth rate. Investing in these services can meet the increasing demand from urban populations seeking outpatient care.
- Development of Post-Operative Care Facilities: The need for post-operative care facilities is rising, especially in urban settings. Hospitals can benefit from investing in dedicated post-operative care units to improve recovery support.
- Enhancing Emergency Care Services: Emergency care services are essential, with over 80% of urban hospitals providing them. Investing in advanced emergency care technologies can improve service delivery and patient outcomes.
Government Initiatives in the China Acute Care Services Market
The National Health Commission oversees the implementation of various healthcare programs, including funding for acute care services. The 'Healthy China 2030' initiative aims to increase access to healthcare services in underserved regions. Additionally, the government has allocated resources for the development of trauma centers and emergency care facilities, ensuring that critical services are available where they are most needed. These efforts are supported by various funding schemes that focus on improving healthcare infrastructure and service delivery across the country.
The Ministry of Health approves and funds various healthcare initiatives. The 'Emergency Medical Service Development Plan' launched in 2021 enhances emergency response capabilities nationwide. This plan includes funding for new emergency care facilities and training programs for medical personnel, ensuring a more efficient response to critical health situations. The government also supports the 'National Trauma Care Strategy' to improve trauma care services in urban and rural areas.
Future Insight of the China Acute Care Services Market
By 2032, buyers and suppliers in the China acute care services market can expect substantial improvements driven by the 'Healthy China 2030' initiative, which aims to enhance healthcare access nationwide. Emergency response coverage is set to reach 90% by 2025, providing quicker access to essential services for urban and rural populations. The establishment of new trauma centers in high-accident areas will strengthen emergency care, while the integration of advanced medical technologies will optimise treatment processes. Continued investments in healthcare infrastructure will further support the growth of acute care services, resulting in improved patient outcomes.
Market Segmentation Analysis
The analysis below covers each segmentation, its leading category in 2025 and its fastest-growing category through 2032.
By Product Type – Emergency Care Dominated, Trauma Services Expected to Grow Fastest
According to Ravi Bhandari, Research Head at 6Wresearch, in 2025, Emergency Care led the product type split with a 35% share. Emergency care services lead the market due to their critical function in treating life-threatening conditions, with over 80% of urban hospitals equipped to deliver these services. This widespread availability ensures that a large segment of the population depends on emergency care for urgent medical assistance. Trauma Services are projected to grow fastest, at a CAGR of 6.8% during 2026–2032. Trauma services are rapidly expanding, propelled by rising accident rates, especially in metropolitan areas where there are currently 1,200 certified trauma centers. This growth indicates a heightened need for specialised care to effectively address serious injuries. Suppliers should focus on enhancing emergency care capabilities to meet the increasing demand for trauma services.
By Service Setting – Hospital-Based Dominated, Ambulatory Services Expected to Grow Fastest
The largest service setting category in 2025 was Hospital-Based, with a 46% share of total revenue. Hospital-based acute care services dominate the market as they are the primary environment for urgent medical treatment, supported by over 30,000 hospitals across China. This extensive network guarantees that acute care is accessible to a broad population. The quickest growth will come from Ambulatory Services, forecast to expand at a CAGR of 7.3% between 2026 and 2032. Ambulatory services are growing quickly, with a 15% annual increase in urban areas, responding to the outpatient treatment needs for less severe cases. This trend reflects a shift towards more accessible healthcare solutions. Buyers may benefit from a wider range of ambulatory services, improving access to timely care.
By Distribution Channel – Direct Sales Dominated and Is Expected to Record the Fastest Growth
Direct Sales accounted for a 50% market share by distribution channel in 2025. Direct sales account for the largest share in the distribution of acute care services, as they facilitate specific service agreements directly between providers and hospitals. This direct approach ensures that healthcare facilities receive tailored solutions to meet their acute care needs. Its lead should widen, with a projected CAGR of 6.5% during 2026–2032, the highest in this split. The direct sales channel is also the fastest-growing due to its efficiency in establishing service agreements, allowing for quicker response times in acute care delivery. This growth reinforces the importance of direct relationships in healthcare. Suppliers should prioritise direct sales strategies to capitalise on the increasing demand for acute care services.
By End User – Hospitals Dominated, Trauma Centers Expected to Grow Fastest
Hospitals held a 34% share of the China Acute Care Services Market by end user in 2025. Hospitals account for the largest share of end users in the acute care services market, as they are the main providers addressing the urgent needs of a vast population. With rising healthcare demands, hospitals are essential in delivering comprehensive acute care. Over 2026–2032, Trauma Centers are expected to post the fastest growth, at a CAGR of 7.5%. Trauma centers are seeing the fastest growth as they focus on managing severe injuries, particularly in urban areas with high accident rates. This emphasis on trauma care highlights the need for specialised facilities to effectively manage critical cases. Suppliers should consider targeting trauma centers to align with the increasing demand for specialised acute care services.
By Service Type – Life-Saving Care Dominated, Emergency Procedures Expected to Grow Fastest
Life-Saving Care took a 34% share of service type in 2025, more than any other category. Life-saving care services hold the largest market share as they are vital for addressing severe health emergencies, ensuring timely interventions for patients in critical conditions. The standardisation of life-saving care protocols across hospitals further underscores their significance in acute care. Emergency Procedures are projected to grow fastest, at a CAGR of 7.2% during 2026–2032. Emergency procedures are the fastest-growing service type, driven by a greater emphasis on urgent medical interventions in training programs nationwide. This focus on emergency procedures demonstrates a strong commitment to enhancing acute care responsiveness. Suppliers must improve their offerings in emergency procedures to support the growing need for life-saving interventions.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Acute Care Services Market Outlook
- Market Size of China Acute Care Services Market, 2025
- Forecast of China Acute Care Services Market, 2032
- Historical Data and Forecast of China Acute Care Services Revenues & Volume for the Period 2022 - 2032F
- China Acute Care Services Market Trend Evolution
- China Acute Care Services Market Drivers and Challenges
- China Acute Care Services Price Trends
- China Acute Care Services Porter's Five Forces
- China Acute Care Services Industry Life Cycle
- Historical Data and Forecast of China Acute Care Services Market Revenues & Volume By Product Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Acute Care Services Market Revenues & Volume By Emergency Care for the Period 2022 - 2032F
- Historical Data and Forecast of China Acute Care Services Market Revenues & Volume By Intensive Care for the Period 2022 - 2032F
- Historical Data and Forecast of China Acute Care Services Market Revenues & Volume By Trauma Services for the Period 2022 - 2032F
- Historical Data and Forecast of China Acute Care Services Market Revenues & Volume By Post-Operative Care for the Period 2022 - 2032F
- Historical Data and Forecast of China Acute Care Services Market Revenues & Volume By Coronary Care for the Period 2022 - 2032F
- Historical Data and Forecast of China Acute Care Services Market Revenues & Volume By Service Setting for the Period 2022 - 2032F
- Historical Data and Forecast of China Acute Care Services Market Revenues & Volume By Hospital-Based for the Period 2022 - 2032F
- Historical Data and Forecast of China Acute Care Services Market Revenues & Volume By Ambulatory Services for the Period 2022 - 2032F
- Historical Data and Forecast of China Acute Care Services Market Revenues & Volume By Urgent Care Centers for the Period 2022 - 2032F
- Historical Data and Forecast of China Acute Care Services Market Revenues & Volume By Specialty Clinics for the Period 2022 - 2032F
- Historical Data and Forecast of China Acute Care Services Market Revenues & Volume By Multi-Specialty Units for the Period 2022 - 2032F
- Historical Data and Forecast of China Acute Care Services Market Revenues & Volume By Distribution Channel for the Period 2022 - 2032F
- Historical Data and Forecast of China Acute Care Services Market Revenues & Volume By Direct Sales for the Period 2022 - 2032F
- Historical Data and Forecast of China Acute Care Services Market Revenues & Volume By Government Contracts for the Period 2022 - 2032F
- Historical Data and Forecast of China Acute Care Services Market Revenues & Volume By Online Platforms for the Period 2022 - 2032F
- Historical Data and Forecast of China Acute Care Services Market Revenues & Volume By Referrals for the Period 2022 - 2032F
- Historical Data and Forecast of China Acute Care Services Market Revenues & Volume By Insurance Partnerships for the Period 2022 - 2032F
- Historical Data and Forecast of China Acute Care Services Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Acute Care Services Market Revenues & Volume By Hospitals for the Period 2022 - 2032F
- Historical Data and Forecast of China Acute Care Services Market Revenues & Volume By Clinics for the Period 2022 - 2032F
- Historical Data and Forecast of China Acute Care Services Market Revenues & Volume By Trauma Centers for the Period 2022 - 2032F
- Historical Data and Forecast of China Acute Care Services Market Revenues & Volume By Surgical Centers for the Period 2022 - 2032F
- Historical Data and Forecast of China Acute Care Services Market Revenues & Volume By Cardiology Units for the Period 2022 - 2032F
- Historical Data and Forecast of China Acute Care Services Market Revenues & Volume By Service Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Acute Care Services Market Revenues & Volume By Short-Term Treatment for the Period 2022 - 2032F
- Historical Data and Forecast of China Acute Care Services Market Revenues & Volume By Life-Saving Care for the Period 2022 - 2032F
- Historical Data and Forecast of China Acute Care Services Market Revenues & Volume By Emergency Procedures for the Period 2022 - 2032F
- Historical Data and Forecast of China Acute Care Services Market Revenues & Volume By Recovery Support for the Period 2022 - 2032F
- Historical Data and Forecast of China Acute Care Services Market Revenues & Volume By Heart Care Services for the Period 2022 - 2032F
- China Acute Care Services Import Export Trade Statistics
- Market Opportunity Assessment By Product Type
- Market Opportunity Assessment By Service Setting
- Market Opportunity Assessment By Distribution Channel
- Market Opportunity Assessment By End User
- Market Opportunity Assessment By Service Type
- China Acute Care Services Top Companies Market Share
- China Acute Care Services Competitive Benchmarking By Technical and Operational Parameters
- China Acute Care Services Company Profiles
- China Acute Care Services Key Strategic Recommendations
Market Covered
The report offers an extensive study of the following market segments.
By Product Type
- Emergency Care
- Intensive Care
- Trauma Services
- Post-Operative Care
- Coronary Care
By Service Setting
- Hospital-Based
- Ambulatory Services
- Urgent Care Centers
- Specialty Clinics
- Multi-Specialty Units
By Distribution Channel
- Direct Sales
- Government Contracts
- Online Platforms
- Referrals
- Insurance Partnerships
By End User
- Hospitals
- Clinics
- Trauma Centers
- Surgical Centers
- Cardiology Units
By Service Type
- Short-Term Treatment
- Life-Saving Care
- Emergency Procedures
- Recovery Support
- Heart Care Services































