China Acute Care Treatment Market Size & Growth Rate
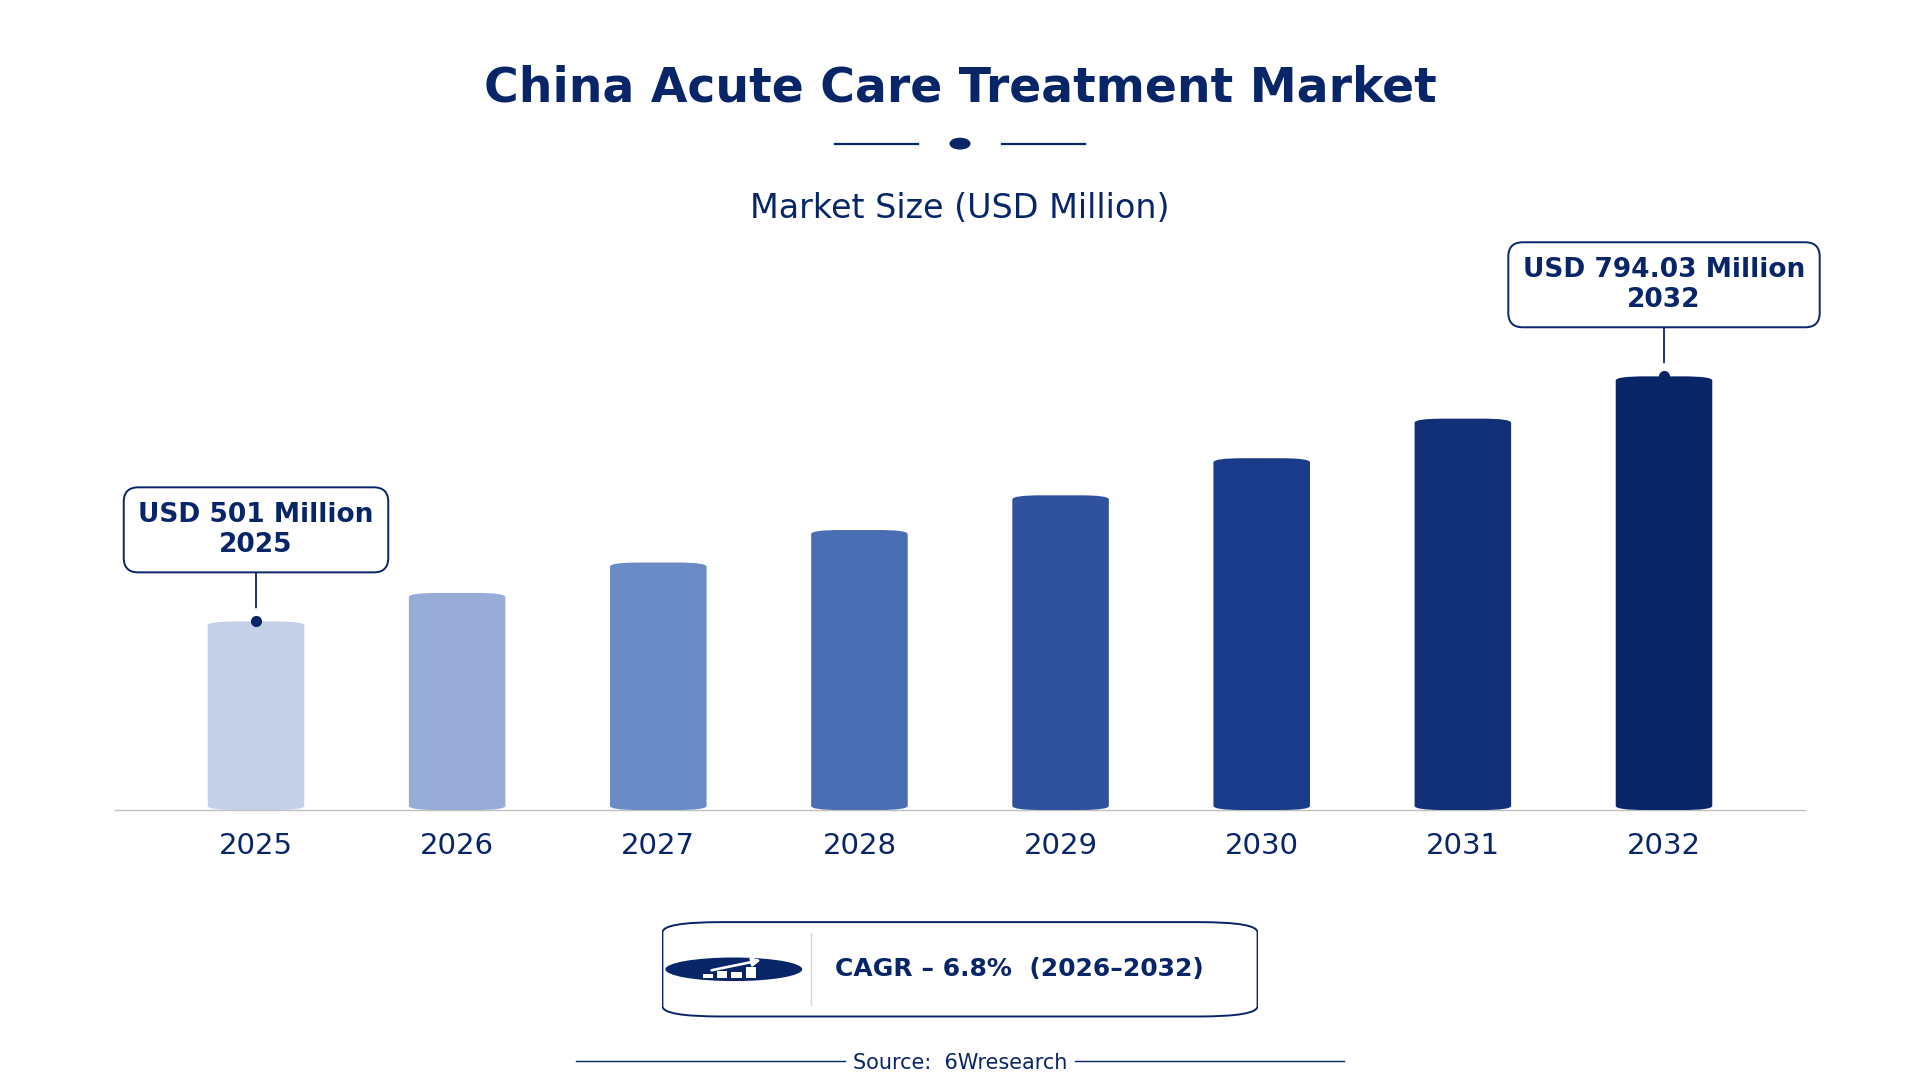
According to 6Wresearch internal database and industry insights, the China Acute Care Treatment Market was valued at USD 501.0 million in 2025 and is projected to reach USD 794.03 million by 2032, growing at a CAGR of approximately 6.8% during 2026–2032.
China Acute Care Treatment Market Highlights
| Report Metric | Details |
| Report Name | China Acute Care Treatment Market |
| Market Size 2025 | USD 501.0 million |
| Market Size 2032 | USD 794.03 million |
| Absolute Growth 2025–2032 | USD 293.03 million |
| CAGR 2026–2032 | 6.8% |
| Peak Annual Growth | 8.8% in 2032 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Treatment Type, 2025 | Drug Therapy (40% share) |
| Leading Delivery Mode, 2025 | Inpatient (49% share) |
| Leading Distribution Channel, 2025 | Hospital Procurement (53% share) |
| Leading End User, 2025 | General Hospitals (46% share) |
| Leading Duration, 2025 | Immediate Relief (34% share) |
| Fastest-Growing Treatment Type | Rehabilitation (9.0% CAGR) |
| Fastest-Growing Delivery Mode | Outpatient (8.3% CAGR) |
| Fastest-Growing Distribution Channel | Telehealth Services (8.0% CAGR) |
| Fastest-Growing End User | Critical Care Units (9.0% CAGR) |
| Fastest-Growing Duration | Symptom Relief (9.6% CAGR) |
| Growing Sector | Critical Care Units |
| Key End Users | General Hospitals, Emergency Rooms, Critical Care Units |
China Acute Care Treatment Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
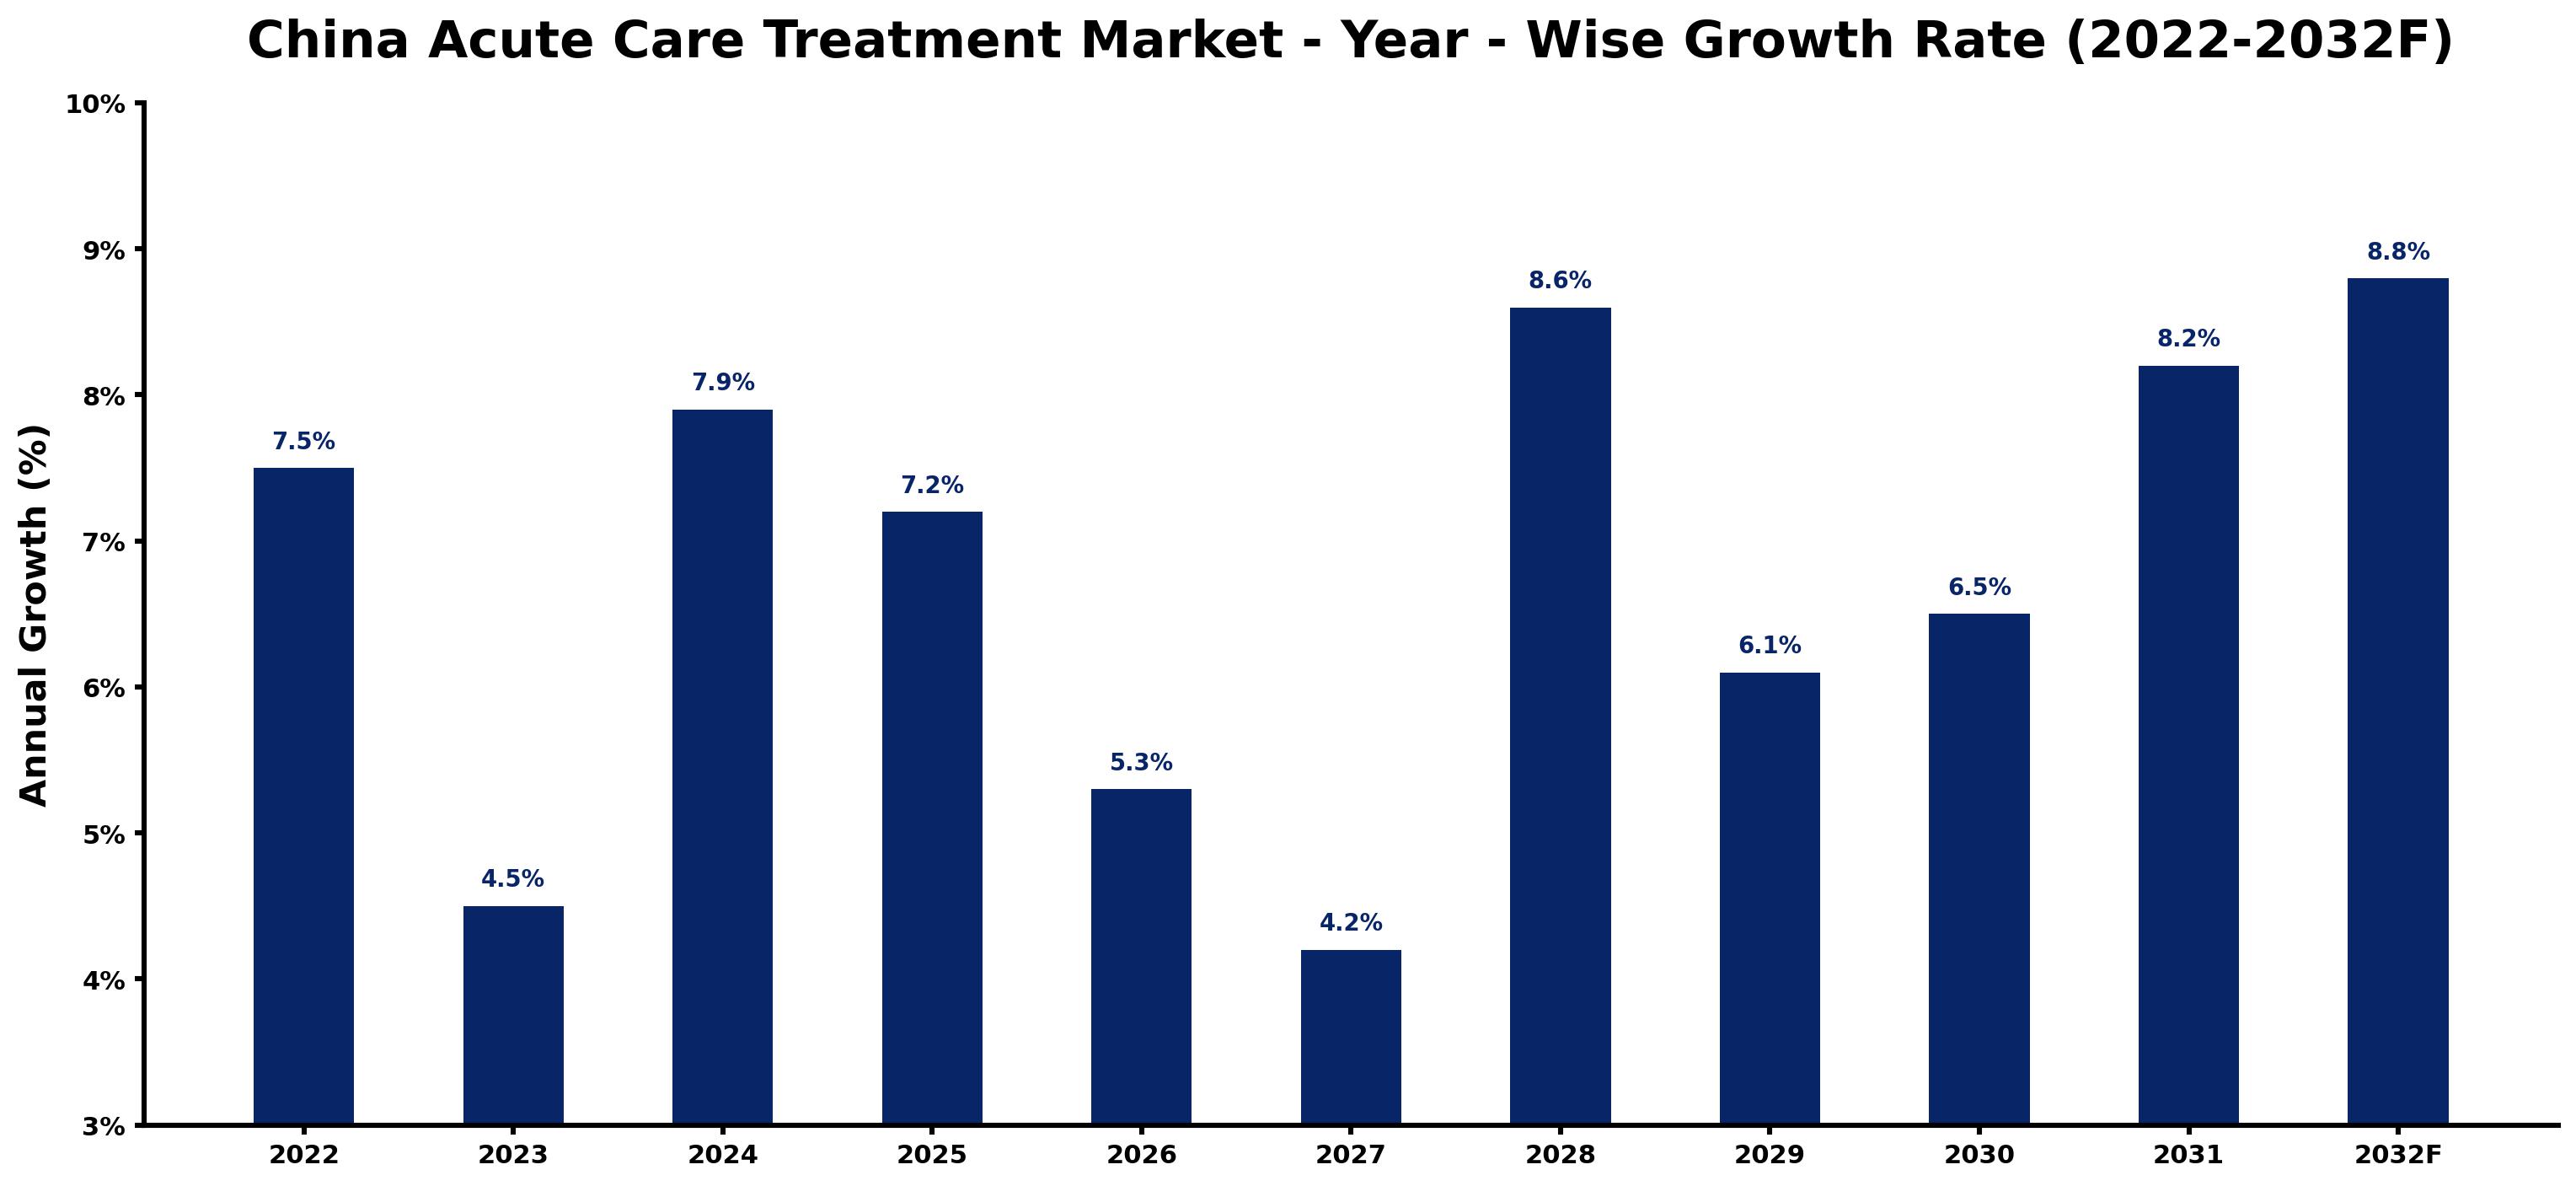
Annual growth estimates for each year appear below with the principal reason behind them, explaining the shifts that set the pace of the market.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 7.5 | The market experienced steady demand due to a high volume of emergency room visits. |
| 2023 | 4.5 | Growth slowed as healthcare expenditure adjustments took place amid rising operational costs. |
| 2024 | 7.9 | An increase in emergency room visits led to a faster growth rate compared to the previous year. |
| 2025 | 7.2 | Demand continued to grow, although at a slower pace as hospitals adjusted to increased patient loads. |
| 2026 | 5.3 | Healthcare funding constraints are expected to result in a slower growth rate amid rising operational challenges. |
| 2027 | 4.2 | A continued focus on improving acute care services will contribute to ongoing demand, albeit at a reduced rate. |
| 2028 | 8.6 | The market is projected to rebound with increased funding for critical care units, driving higher growth. |
| 2029 | 6.1 | Growth is expected to slow as hospitals face challenges in managing increased patient turnover in emergency rooms. |
| 2030 | 6.5 | An uptick in healthcare investments will lead to a rise in demand for acute care services. |
| 2031 | 8.2 | The market is projected to grow as hospitals expand their acute care capabilities to meet rising patient needs. |
| 2032 | 8.8 | Increased funding for acute care initiatives is expected to drive growth. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Acute Care Treatment Market Synopsis
Acute Care Treatment in China encompasses various medical interventions aimed at managing severe health conditions requiring immediate attention. This includes surgical procedures, drug therapies, and intensive monitoring techniques primarily utilised in hospitals and emergency care settings. The China Acute Care Treatment Market is expanding due to rising healthcare expenditure and increasing patient populations, with over 1.4 million emergency room visits annually in major cities. The launch of the 'Acute Care Improvement Program' in 2023 further improves treatment protocols and funding, contributing to the market's growth.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Rising healthcare expenditure | Driver | High | Drug Therapy |
| Increased emergency room visits | Driver | High | Intensive Monitoring |
| Growing demand for critical care services | Opportunity | High | Critical Care Units |
| Expansion of acute care facilities | Opportunity | High | General Hospitals |
| Funding constraints in healthcare | Restraint | High | Surgical Treatment |
| Inadequate trained professionals | Restraint | Medium | Pain Management |
| High operational costs | Challenge | High | Inpatient |
| Limited telehealth integration | Challenge | Medium | Outpatient |
Evaluation of Drivers in China Acute Care Treatment Market (2026–2032)
The factors lifting demand, and the evidence behind each, are summarised below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased healthcare expenditure | Drug Therapy | China's healthcare expenditure reached 6 trillion CNY in 2023, leading to more investments in drug therapies. |
| High volume of emergency room visits | Intensive Monitoring | With over 1.4 million emergency room visits annually, hospitals require intensive monitoring for patients. |
| Expansion of critical care units | Critical Care Units | A 10% increase in funding for critical care units in 2023 supports their expansion and demand. |
| Launch of acute care improvement initiatives | General Hospitals | The 'Acute Care Improvement Program' in 2023 improves protocols, increasing demand from general hospitals. |
| Standardisation of pain management protocols | Pain Management | Standardised protocols across major hospitals improve patient care, driving demand for pain management services. |
The Acute Care Treatment market in China is expanding, driven by increased healthcare expenditure, high volumes of emergency room visits, and the growth of critical care units. In 2023, healthcare expenditure reached 6 trillion CNY, enabling hospitals to invest more in acute care services. Over 1.4 million emergency room visits annually have surged the need for intensive monitoring. The introduction of improved treatment protocols has increased demand from general hospitals. Standardised pain management protocols across major hospitals have also improved patient care, driving further demand.
Evaluation of Restraints in China Acute Care Treatment Market
Below mentioned are some major restraints and their influence on market dynamics.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| High operational costs | Inpatient | Operational costs have risen significantly, impacting hospitals' ability to maintain high-quality inpatient care. |
| Inadequate trained professionals | Pain Management | The shortage of trained acute care professionals limits the effectiveness of pain management services. |
| Funding constraints in healthcare | Surgical Treatment | Funding limitations restrict hospitals' capabilities to invest in necessary surgical treatments. |
| Limited telehealth integration | Outpatient | Telehealth services for acute care have not been widely adopted, limiting outpatient treatment options. |
| Regulatory hurdles for new treatments | Drug Therapy | Stringent regulations delay the introduction of new drug therapies in the acute care market. |
China Acute Care Treatment Market Challenges
The China Acute Care Treatment market faces several practical issues, starting with high costs for buyers, as healthcare expenditure reached 6 trillion CNY in 2023, straining hospital budgets. Supply chain inefficiencies arise from the concentration of acute care services in urban hospitals, leading to delays in patient transfers and increasing pressure on emergency rooms, where turnover averages 5 patients per hour. Technology adoption lags, with telehealth services only increasing by 15% since 2020, limiting access for patients in rural areas. Competition intensifies as the 'National Acute Care Strategy' mandates facilities to invest heavily in upgrades, raising operational costs for hospitals.
Trends in the China Acute Care Treatment Market
The trends below show where the China Acute Care Treatment Market is heading.
- Shift towards Integrated Healthcare Delivery Systems: China is moving towards integrated healthcare delivery systems to streamline acute care services. The 'Integrated Healthcare Delivery System' initiative aims for better coordination across urban and rural areas, with a target implementation by 2025.
- Increase in Emergency Medical Services: The 'Emergency Medical Services Development Plan' updated in 2022 is improving response times in acute care settings. This initiative focuses on enhancing patient outcomes and is reflected in the increased funding for emergency services.
- Standardisation of Pain Management Protocols: Standardised pain management protocols have been adopted across major hospitals since 2021, improving patient comfort. This change is important for improving the overall quality of acute care treatments.
- Rise in Telehealth Services: Telehealth services for acute care have increased by 15% in urban areas since 2020, reflecting a shift towards more accessible healthcare solutions. This trend is expected to continue as technology improves.
Investment Opportunities in the China Acute Care Treatment Market
The following opportunities in the China Acute Care Treatment Market pair current demand with a clear way in.
- Expansion of Critical Care Units in Urban Areas: Urban hospitals are focusing on expanding critical care units to meet rising demand, with a 20% capacity increase reported in Shanghai since 2021. This presents opportunities for investment in facility upgrades.
- Investment in Acute Care Facilities: With the Chinese government allocating 500 million CNY for upgrading emergency medical equipment in 2023, there is an opportunity for suppliers to invest in acute care facilities across the country.
- Development of Pain Management Services: As standardised protocols for pain management become more prevalent, there is an opportunity to supply innovative pain relief solutions to hospitals, particularly in urban areas with high patient turnover.
- Enhancement of Telehealth Solutions: The rise in telehealth services presents an opportunity to develop and supply technology solutions for remote patient monitoring, especially in urban hospitals where demand is increasing.
Government Initiatives in the China Acute Care Treatment Market
In 2020, the State Council approved the 'Healthcare Infrastructure Improvement Initiative', allocating 1 billion CNY for upgrading acute care facilities nationwide. This initiative aims to improve the quality of acute care services across the country. Following this, the 'National Acute Care Strategy' was introduced in 2021 to standardise treatment across hospitals, aiming for implementation by 2025. This strategy will enhance the overall efficiency of acute care delivery in China.
The National Health Commission oversees the implementation of various healthcare initiatives, including the 'Acute Care Improvement Program' launched in 2023. This program improves treatment protocols and increases funding by 300 million CNY for better facilities. Additionally, the 'Emergency Medical Services Development Plan' updated in 2022 focuses on improving response times and patient outcomes in acute care settings, ensuring that hospitals are better equipped to handle emergencies.
Future Insight of the China Acute Care Treatment Market
Several forward-looking factors should support the China Acute Care Treatment market by 2032. The 'Acute Care Improvement Program' initiated in 2023 aims to refine treatment protocols, which should enhance patient outcomes across facilities. By 2025, the 'Integrated Healthcare Delivery System' initiative will streamline service integration, improving access for patients nationwide. The government’s allocation of 500 million CNY for upgrading emergency medical equipment will elevate standards significantly. As a result, buyers can anticipate improved service quality, while suppliers will likely encounter increased demand for advanced medical technologies.
Market Segmentation Analysis
The report offers a comprehensive study of the following market segments and their leading categories in the market.
By Treatment Type – Drug Therapy Dominated, Rehabilitation Expected to Grow Fastest
According to Ravi Bhandari, Research Head at 6Wresearch, in 2025, Drug Therapy led the treatment type split with a 40% share. Drug therapy holds the largest share in China's acute care treatment market due to its essential role in managing severe health conditions. For instance, with over 1.4 million emergency room visits annually, medications are crucial for effective treatment in these high-pressure situations. Rehabilitation is projected to grow fastest, at a CAGR of 9.0% during 2026–2032. Rehabilitation is experiencing rapid growth as healthcare facilities increasingly recognise the importance of post-acute care. The 'Acute Care Improvement Program' launched in 2023 highlights this shift towards comprehensive patient recovery. Suppliers should focus on enhancing drug therapy offerings while also investing in rehabilitation services to meet evolving healthcare demands.
By Delivery Mode – Inpatient Dominated, Outpatient Expected to Grow Fastest
With a 49% revenue share in 2025, Inpatient was the largest delivery mode category. Inpatient care dominates the acute care delivery mode in China, as serious cases often require extensive monitoring and treatment. The average length of stay in acute care hospitals is around 7 days, underscoring the need for inpatient services. The quickest growth will come from Outpatient, forecast to expand at a CAGR of 8.3% between 2026 and 2032. Outpatient services are gaining traction, particularly as urban hospitals adapt to increasing patient turnover rates. The recent 15% increase in telehealth services indicates a shift towards more accessible care options. Providers must adapt their strategies to include outpatient services, ensuring they cater to changing patient preferences and healthcare trends.
By Distribution Channel – Hospital Procurement Dominated, Telehealth Services Expected to Grow Fastest
The largest distribution channel category in 2025 was Hospital Procurement, with a 53% share of total revenue. Hospital procurement leads the distribution channel for acute care treatments, as hospitals directly acquire necessary medical interventions. This direct procurement is crucial for maintaining the supply chain in high-demand environments like emergency rooms. Telehealth Services are set to record the highest CAGR in this split, 8.0% over 2026–2032. Telehealth services are emerging as a faster-growing channel, particularly in urban areas where demand for remote consultations has surged. The integration of telehealth into acute care reflects a broader trend towards digital health solutions. Suppliers should explore partnerships with telehealth platforms to expand their reach and improve service delivery in acute care settings.
By End User – General Hospitals Dominated, Critical Care Units Expected to Grow Fastest
General Hospitals held a 46% share of the China Acute Care Treatment Market by end user in 2025. General hospitals are the primary users of acute care treatments, accounting for over 80% of services provided in urban areas. This concentration highlights the critical role these facilities play in managing acute health conditions. Over 2026–2032, Critical Care Units are expected to post the fastest growth, at a CAGR of 9.0%. Critical care units are witnessing rapid growth due to the increasing demand for specialised care in severe cases. The reported 20% increase in capacity in Shanghai's critical care units illustrates this urgent need. Stakeholders should prioritise partnerships with general hospitals and critical care units to ensure their products meet the specific needs of these key end users.
By Duration – Immediate Relief Dominated, Symptom Relief Expected to Grow Fastest
Immediate Relief accounted for a 34% market share by duration in 2025. Immediate relief is the primary goal of acute care, making it a crucial focus for healthcare providers. This urgency is reflected in the high turnover rates in emergency departments, with an estimated 5 patients per hour in urban hospitals. Symptom Relief is projected to grow fastest, at a CAGR of 9.6% during 2026–2032. Symptom relief is becoming increasingly important as part of the overall treatment strategy, with healthcare professionals recognising its role in patient satisfaction and recovery. The emphasis on symptom management aligns with the goals of the 'National Acute Care Strategy'. Healthcare providers should develop solutions that address both immediate and symptom relief needs to enhance patient outcomes in acute care.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Acute Care Treatment Market Outlook
- Market Size of China Acute Care Treatment Market, 2025
- Forecast of China Acute Care Treatment Market, 2032
- Historical Data and Forecast of China Acute Care Treatment Revenues & Volume for the Period 2022 - 2032F
- China Acute Care Treatment Market Trend Evolution
- China Acute Care Treatment Market Drivers and Challenges
- China Acute Care Treatment Price Trends
- China Acute Care Treatment Porter's Five Forces
- China Acute Care Treatment Industry Life Cycle
- Historical Data and Forecast of China Acute Care Treatment Market Revenues & Volume By Treatment Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Acute Care Treatment Market Revenues & Volume By Surgical Treatment for the Period 2022 - 2032F
- Historical Data and Forecast of China Acute Care Treatment Market Revenues & Volume By Drug Therapy for the Period 2022 - 2032F
- Historical Data and Forecast of China Acute Care Treatment Market Revenues & Volume By Rehabilitation for the Period 2022 - 2032F
- Historical Data and Forecast of China Acute Care Treatment Market Revenues & Volume By Intensive Monitoring for the Period 2022 - 2032F
- Historical Data and Forecast of China Acute Care Treatment Market Revenues & Volume By Pain Management for the Period 2022 - 2032F
- Historical Data and Forecast of China Acute Care Treatment Market Revenues & Volume By Delivery Mode for the Period 2022 - 2032F
- Historical Data and Forecast of China Acute Care Treatment Market Revenues & Volume By Inpatient for the Period 2022 - 2032F
- Historical Data and Forecast of China Acute Care Treatment Market Revenues & Volume By Outpatient for the Period 2022 - 2032F
- Historical Data and Forecast of China Acute Care Treatment Market Revenues & Volume By Home-Based for the Period 2022 - 2032F
- Historical Data and Forecast of China Acute Care Treatment Market Revenues & Volume By ICU for the Period 2022 - 2032F
- Historical Data and Forecast of China Acute Care Treatment Market Revenues & Volume By Clinical for the Period 2022 - 2032F
- Historical Data and Forecast of China Acute Care Treatment Market Revenues & Volume By Distribution Channel for the Period 2022 - 2032F
- Historical Data and Forecast of China Acute Care Treatment Market Revenues & Volume By Hospital Procurement for the Period 2022 - 2032F
- Historical Data and Forecast of China Acute Care Treatment Market Revenues & Volume By Pharmacies for the Period 2022 - 2032F
- Historical Data and Forecast of China Acute Care Treatment Market Revenues & Volume By Telehealth Services for the Period 2022 - 2032F
- Historical Data and Forecast of China Acute Care Treatment Market Revenues & Volume By Direct Purchase for the Period 2022 - 2032F
- Historical Data and Forecast of China Acute Care Treatment Market Revenues & Volume By Online Medical Stores for the Period 2022 - 2032F
- Historical Data and Forecast of China Acute Care Treatment Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Acute Care Treatment Market Revenues & Volume By General Hospitals for the Period 2022 - 2032F
- Historical Data and Forecast of China Acute Care Treatment Market Revenues & Volume By Emergency Rooms for the Period 2022 - 2032F
- Historical Data and Forecast of China Acute Care Treatment Market Revenues & Volume By Recovery Units for the Period 2022 - 2032F
- Historical Data and Forecast of China Acute Care Treatment Market Revenues & Volume By Critical Care Units for the Period 2022 - 2032F
- Historical Data and Forecast of China Acute Care Treatment Market Revenues & Volume By Day Care Centers for the Period 2022 - 2032F
- Historical Data and Forecast of China Acute Care Treatment Market Revenues & Volume By Duration for the Period 2022 - 2032F
- Historical Data and Forecast of China Acute Care Treatment Market Revenues & Volume By Short-Term for the Period 2022 - 2032F
- Historical Data and Forecast of China Acute Care Treatment Market Revenues & Volume By Immediate Relief for the Period 2022 - 2032F
- Historical Data and Forecast of China Acute Care Treatment Market Revenues & Volume By Stabilization Phase for the Period 2022 - 2032F
- Historical Data and Forecast of China Acute Care Treatment Market Revenues & Volume By Critical Illness for the Period 2022 - 2032F
- Historical Data and Forecast of China Acute Care Treatment Market Revenues & Volume By Symptom Relief for the Period 2022 - 2032F
- China Acute Care Treatment Import Export Trade Statistics
- Market Opportunity Assessment By Treatment Type
- Market Opportunity Assessment By Delivery Mode
- Market Opportunity Assessment By Distribution Channel
- Market Opportunity Assessment By End User
- Market Opportunity Assessment By Duration
- China Acute Care Treatment Top Companies Market Share
- China Acute Care Treatment Competitive Benchmarking By Technical and Operational Parameters
- China Acute Care Treatment Company Profiles
- China Acute Care Treatment Key Strategic Recommendations
Market Covered
Segments analysed in this report are listed below.
By Treatment Type
- Surgical Treatment
- Drug Therapy
- Rehabilitation
- Intensive Monitoring
- Pain Management
By Delivery Mode
- Inpatient
- Outpatient
- Home-Based
- ICU
- Clinical
By Distribution Channel
- Hospital Procurement
- Pharmacies
- Telehealth Services
- Direct Purchase
- Online Medical Stores
By End User
- General Hospitals
- Emergency Rooms
- Recovery Units
- Critical Care Units
- Day Care Centers
By Duration
- Short-Term
- Immediate Relief
- Stabilization Phase
- Critical Illness
- Symptom Relief































