China Additional Vehicle Lighting Systems Market Size & Growth Rate
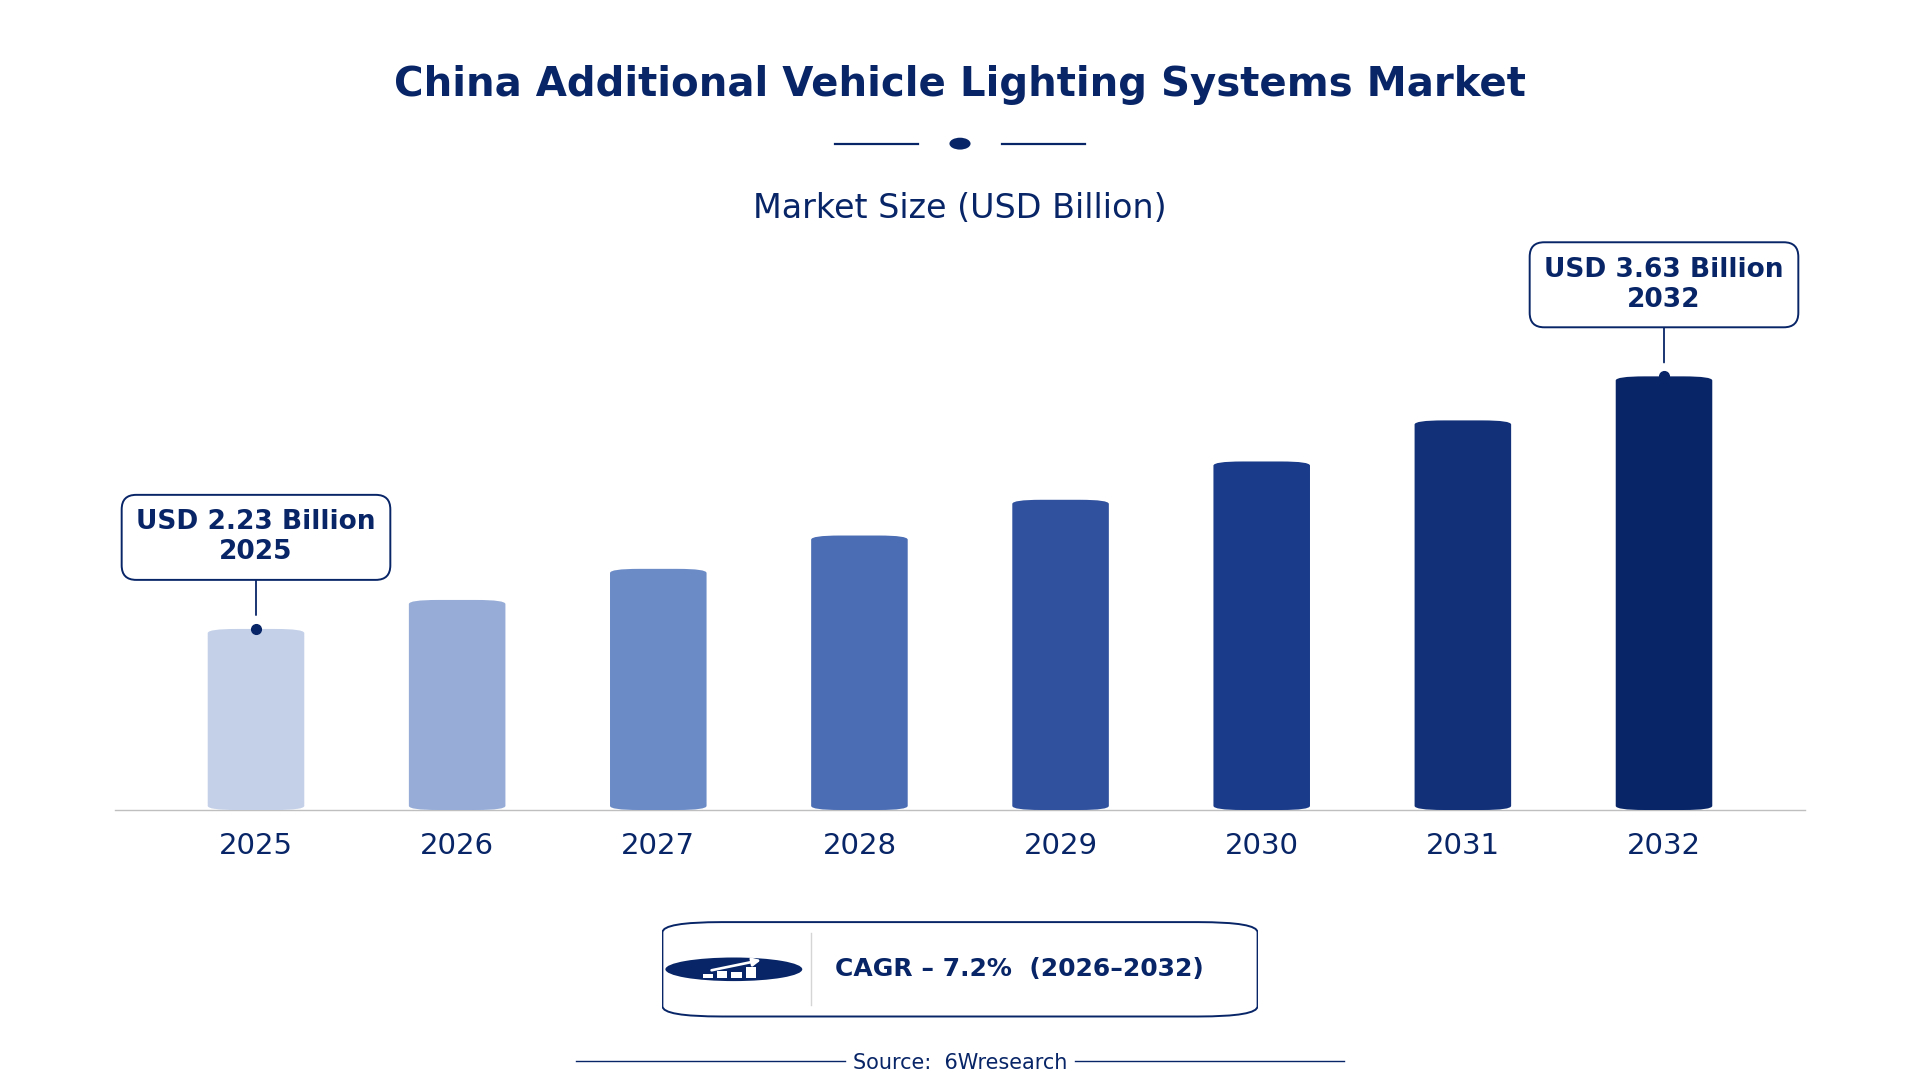
According to 6Wresearch internal database and industry insights, the China Additional Vehicle Lighting Systems Market was valued at USD 2.23 billion in 2025 and is projected to reach USD 3.63 billion by 2032, growing at a CAGR of approximately 7.2% during 2026–2032.
China Additional Vehicle Lighting Systems Market Highlights
| Report Metric | Details |
| Report Name | China Additional Vehicle Lighting Systems Market |
| Market Size 2025 | USD 2.23 billion |
| Market Size 2032 | USD 3.63 billion |
| Absolute Growth 2025–2032 | USD 1.40 billion |
| CAGR 2026–2032 | 7.2% |
| Peak Annual Growth | 9.5% in 2028 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Product Type, 2025 | LED Fog Lamps (42% share) |
| Leading Distribution Channel, 2025 | Direct Sales (43% share) |
| Leading End User, 2025 | Passenger Vehicles (44% share) |
| Fastest-Growing Product Type | Emergency Warning Lights (9.7% CAGR) |
| Fastest-Growing Distribution Channel | Online Platforms (9.1% CAGR) |
| Fastest-Growing End User | Commercial Trucks (9.6% CAGR) |
| Growing Sector | automotive lighting |
| Key End Users | automotive manufacturers, aftermarket retailers, commercial vehicle operators, SUV owners |
China Additional Vehicle Lighting Systems Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
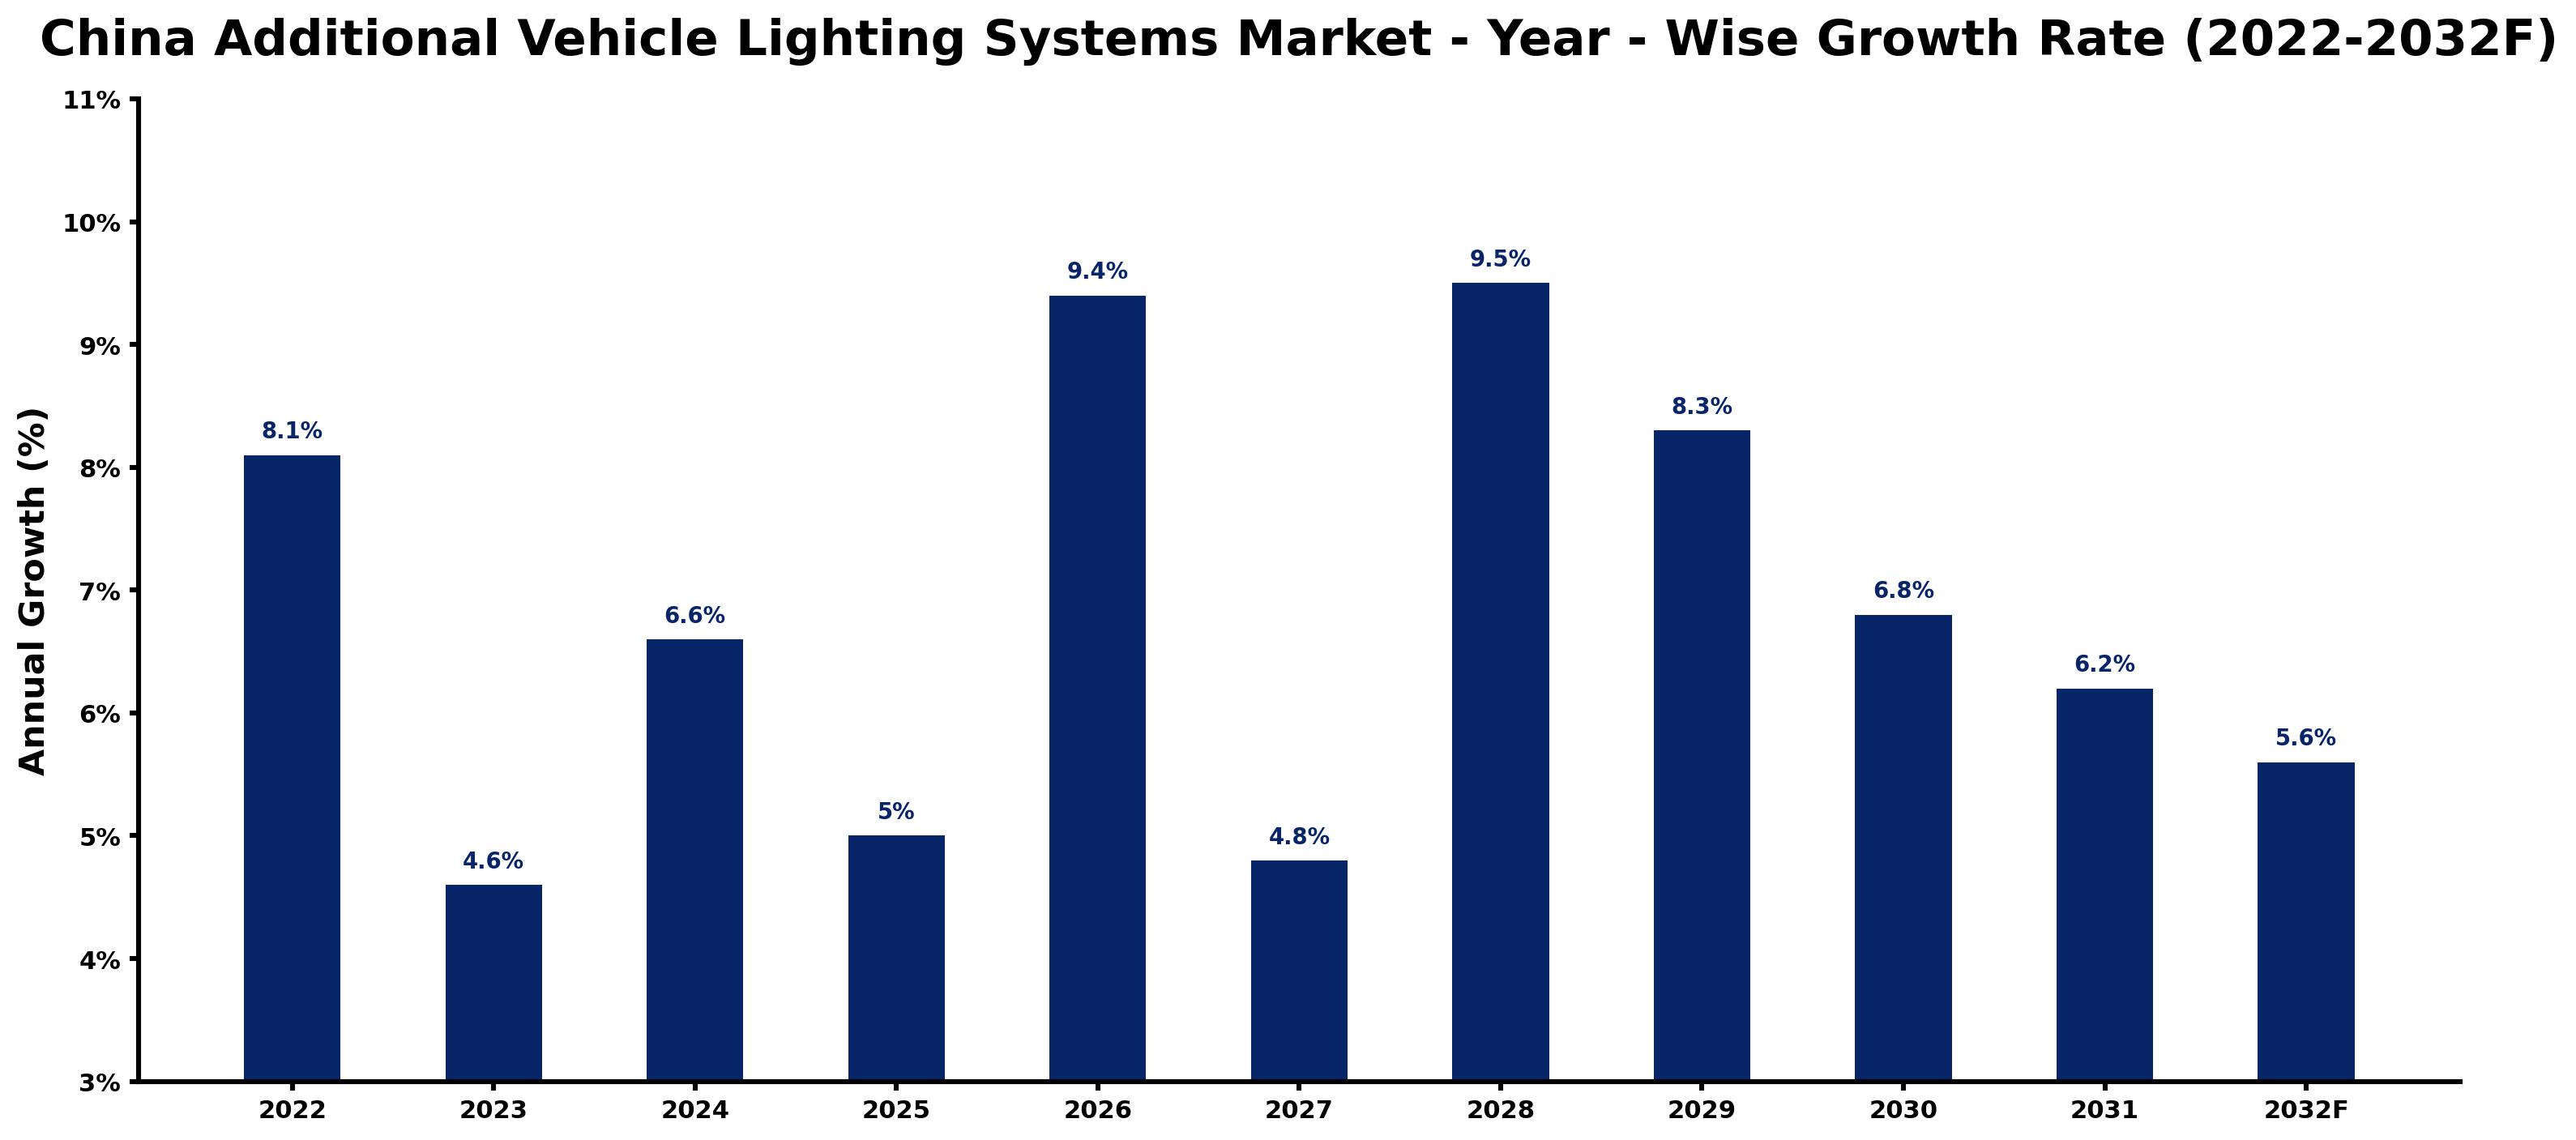
The table below sets out the estimated growth rate for each year and the main factor behind it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 8.1 | The market experienced strong demand due to increased vehicle sales and safety awareness. |
| 2023 | 4.6 | Growth slowed as the automotive sector faced supply chain challenges affecting production rates. |
| 2024 | 6.6 | Demand improved with rising vehicle sales and the introduction of new lighting standards. |
| 2025 | 5.0 | Growth slowed again as manufacturers adjusted to changing consumer preferences and economic conditions. |
| 2026 | 9.4 | A surge in demand for additional lighting systems arose from the National Development and Reform Commission's 2021 plan to improve automotive safety standards. |
| 2027 | 4.8 | Growth slowed as the market stabilised after the previous year's rapid expansion. |
| 2028 | 9.5 | The market peaked with heightened demand for emergency lighting amid stricter regulations from the Ministry of Transport. |
| 2029 | 8.3 | Growth slowed as manufacturers faced increased competition in the lighting segment. |
| 2030 | 6.8 | Demand continued to grow, driven by the increasing popularity of SUVs and off-road vehicles. |
| 2031 | 6.2 | Growth slowed as the market adjusted to the saturation of certain lighting products. |
| 2032 | 5.6 | The market is expected to grow steadily as urbanisation increases vehicle ownership. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Additional Vehicle Lighting Systems Market Synopsis
China Additional Vehicle Lighting Systems Market encompasses advanced lighting solutions designed to improve vehicle visibility and safety. These systems, primarily using LED technology, are essential for enhancing road visibility in adverse conditions. The market is expanding due to a thriving automotive sector, with over 30 million vehicle sales expected in 2023. Increased safety regulations and the growing popularity of SUVs are driving demand for additional lighting systems. The ongoing investment in automotive safety and technology will support market growth through 2032.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increased vehicle sales drive demand for additional lighting systems, particularly in passenger vehicles. | Driver | High | Passenger Vehicles |
| The growing popularity of SUVs and off-road vehicles boosts the demand for auxiliary driving lamps. | Driver | High | Auxiliary Driving Lamps |
| The expansion of online sales channels offers convenience for consumers seeking lighting upgrades. | Opportunity | High | Online Platforms |
| The automotive aftermarket, valued at over $200 billion, presents significant opportunities for lighting system suppliers. | Opportunity | High | Aftermarket Retailers |
| Supply chain disruptions have impacted the availability of components for lighting systems. | Restraint | High | LED Fog Lamps |
| Stringent safety regulations may increase compliance costs for manufacturers of lighting systems. | Restraint | Medium | Emergency Warning Lights |
| The market faces challenges related to technological advancements and the need for continuous innovation. | Challenge | High | Daytime Running Lights |
| Competition from low-cost alternatives can pressure pricing strategies for premium lighting systems. | Challenge | Medium | Auxiliary Driving Lamps |
Evaluation of Drivers in China Additional Vehicle Lighting Systems Market (2026–2032)
The main growth drivers and the segments they affect most are set out below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Rising vehicle sales increase demand for additional lighting systems in passenger vehicles. | Passenger Vehicles | The automotive sector in China is expected to exceed 30 million vehicle sales in 2023. |
| Growing safety regulations mandate the use of emergency warning lights in commercial vehicles. | Emergency Warning Lights | Emergency warning lights are increasingly used in commercial vehicles due to stricter safety regulations. |
| The popularity of SUVs drives demand for advanced auxiliary driving lamps. | Auxiliary Driving Lamps | The demand for auxiliary driving lamps is driven by the growing popularity of SUVs and off-road vehicles. |
| Online platforms provide convenient purchasing options for consumers upgrading vehicle lighting. | Online Platforms | Online sales of automotive parts have increased by 25% in 2023 compared to the previous year. |
| The automotive aftermarket's growth creates opportunities for lighting system upgrades. | Aftermarket Retailers | China's automotive aftermarket is valued at over $200 billion as of 2023. |
The automotive sector is projected to surpass 30 million vehicle sales in 2023, driving the need for additional lighting systems. Enhanced safety standards will necessitate emergency warning lights in commercial vehicles, contributing to improved road safety. The automotive aftermarket, valued at over $200 billion, offers substantial opportunities for suppliers in this space. Online platforms have experienced a 25% rise in automotive part sales, simplifying the process for consumers to upgrade their lighting systems.
Evaluation of Restraints in China Additional Vehicle Lighting Systems Market
The following restraints limit how fast demand can grow.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Supply chain disruptions affect the availability of components for lighting systems. | LED Fog Lamps | The production of LED fog lamps in China reached approximately 15 million units in 2022. |
| Compliance with stringent safety regulations increases costs for manufacturers. | Emergency Warning Lights | The National Development and Reform Commission launched a plan in 2021 to improve automotive safety standards. |
| Technological advancements necessitate continuous innovation in lighting systems. | Daytime Running Lights | Daytime running lights have been mandated by national standards for all new vehicles sold in China since 2017. |
| Competition from low-cost alternatives pressures pricing strategies for premium products. | Auxiliary Driving Lamps | The average age of vehicles on the road in China is around 5 years, driving demand for upgrades. |
| Market saturation in certain lighting segments limits growth potential. | Two-Wheelers | The market for two-wheeler lighting systems is expanding with over 50 million two-wheelers registered in China. |
China Additional Vehicle Lighting Systems Market Challenges
The China Additional Vehicle Lighting Systems market encounters several practical challenges, starting with cost. Producers face escalating raw material prices, which can inflate production costs by up to 15%, ultimately resulting in higher prices for buyers. Distributors experience supply chain disruptions; delays in component deliveries can extend lead times by several weeks, affecting product availability for retailers. Compliance with regulations poses another hurdle for suppliers; meeting the National Standard GB 14929.3-2018 demands significant investment in testing, costing thousands of dollars per product line. Intense competition among suppliers further squeezes profit margins, making it tough for smaller firms to survive in a market led by larger entities.
Trends in the China Additional Vehicle Lighting Systems Market
Four trends stand out in the China Additional Vehicle Lighting Systems Market.
- Shift towards LED Technology: The automotive sector is increasingly adopting LED technology for vehicle lighting, improving energy efficiency and durability. In 2023, the production of LED fog lamps reached approximately 15 million units, reflecting this trend's impact on manufacturers.
- Growing Online Sales Channels: Consumers are increasingly turning to online platforms for purchasing automotive lighting solutions. Online sales of automotive parts increased by 25% in 2023, indicating a shift in buying behaviour towards convenience.
- Increased Focus on Safety Regulations: The automotive industry is prioritising compliance with safety regulations, particularly for emergency lighting. The National Development and Reform Commission's 2021 plan aims to improve automotive safety standards, driving demand for compliant products.
- Rising Demand for Off-Road Lighting Solutions: The popularity of SUVs and off-road vehicles is driving demand for advanced auxiliary driving lamps. This segment is projected to see significant growth, supported by the increasing number of SUV sales.
Investment Opportunities in the China Additional Vehicle Lighting Systems Market
Below are the investment opportunities with the strongest case in the China Additional Vehicle Lighting Systems Market.
- Investment in R&D for Energy-Efficient Technologies: Manufacturers can channel investments into energy-efficient lighting technologies to satisfy growing consumer demand. The automotive lighting industry is poised for substantial investments in R&D for energy-efficient technologies, enhancing product offerings.
- Expansion of Online Sales Platforms: Online platforms offer a promising opportunity for suppliers to reach a wider audience. The increasing trend of online sales, which grew by 25% in 2023, facilitates easier market entry through partnerships with e-commerce platforms.
- Focus on Aftermarket Upgrades: The automotive aftermarket, valued at over $200 billion, presents considerable opportunities for lighting system upgrades. Suppliers can target aftermarket retailers to meet consumer demand for enhanced vehicle safety.
- Collaboration with Automotive Dealerships: Partnering with automotive dealerships can provide access to a large customer base. With over 30,000 dealerships nationwide, this approach can improve market penetration for additional lighting systems.
Government Initiatives in the China Additional Vehicle Lighting Systems Market
The National Standard GB 14929.3-2018 regulates vehicle lighting systems in China, ensuring that manufacturers adhere to safety and performance criteria. This standard mandates rigorous testing and certification processes for lighting products, impacting how producers design and market their offerings. Compliance with these regulations is essential for manufacturers to maintain market access and consumer trust. The Ministry of Industry and Information Technology oversees these regulations, providing guidance and support for compliance efforts.
The Automotive Industry Association of China advocates for safety standards and supports manufacturers in meeting regulatory requirements. This agency funds various initiatives aimed at improving automotive safety, including training programs for manufacturers and workshops on compliance. By facilitating knowledge sharing and best practices, the association helps ensure that producers can effectively navigate the regulatory environment while improving product quality and safety.
Future Insight of the China Additional Vehicle Lighting Systems Market
The China Additional Vehicle Lighting Systems market is set to evolve considerably by 2032, driven by several key factors. The growth of the automotive sector, with over 30 million vehicle sales expected in 2023, will stimulate demand for advanced lighting solutions. Stricter safety regulations will further propel market expansion, as initiatives from the Ministry of Transport aim to raise vehicle lighting standards. Urban population growth, which reached 900 million in 2023, will increase lighting needs for an expanding vehicle fleet. Rising investments in energy-efficient technologies will also influence the market's development.
Market Segmentation Analysis
The report offers a comprehensive study of the following market segments and their leading categories in the market.
By Product Type – LED Fog Lamps Dominated, Emergency Warning Lights Expected to Grow Fastest
According to Ravi Bhandari, Research Head at 6Wresearch, with a 42% revenue share in 2025, LED Fog Lamps was the largest product type category. LED fog lamps hold the largest market share in China due to their critical role in enhancing visibility during foggy conditions. With approximately 15 million units produced in 2022, they are indispensable for safe driving in adverse weather. Emergency Warning Lights are projected to grow fastest, at a CAGR of 9.7% during 2026–2032. Emergency warning lights are experiencing rapid growth, largely because of stricter safety regulations impacting commercial vehicles. This increased focus on road safety has led to a surge in demand for these systems, essential for alerting other drivers during emergencies. Suppliers must focus on expanding their product offerings in emergency warning lights to meet the growing regulatory demands.
By Distribution Channel – Direct Sales Dominated, Online Platforms Expected to Grow Fastest
In 2025, Direct Sales led the distribution channel split with a 43% share. Direct sales hold the largest market share as they provide a direct link between manufacturers and consumers, ensuring effective communication and product quality. This channel allows manufacturers to maintain better control over customer engagement and satisfaction. Online Platforms are set to record the highest CAGR in this split, 9.1% over 2026–2032. Online platforms are the fastest-growing distribution channel, experiencing a remarkable 25% increase in sales in 2023. This surge highlights the growing consumer preference for the convenience and accessibility of purchasing automotive lighting systems online. Suppliers need to strengthen their online strategies to cater to the increasing demand for convenient purchasing options from consumers.
By End User – Passenger Vehicles Dominated, Commercial Trucks Expected to Grow Fastest
Passenger Vehicles held a 44% share of the China Additional Vehicle Lighting Systems Market by end user in 2025. Passenger vehicles account for the largest market share as they are the primary users of additional vehicle lighting systems, significantly enhancing safety on the roads. With over 300 million registered passenger vehicles in China, this segment is crucial for the market's growth. Over 2026–2032, Commercial Trucks are expected to post the fastest growth, at a CAGR of 9.6%. Commercial trucks are the fastest-growing end-user segment, driven by their substantial need for safety and visibility enhancements. As regulations tighten, the demand for advanced lighting solutions in this segment is expected to rise sharply. Suppliers should tailor their products to address the specific safety requirements of commercial trucks, ensuring compliance with evolving regulations.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Additional Vehicle Lighting Systems Market Outlook
- Market Size of China Additional Vehicle Lighting Systems Market, 2025
- Forecast of China Additional Vehicle Lighting Systems Market, 2032
- Historical Data and Forecast of China Additional Vehicle Lighting Systems Revenues & Volume for the Period 2022 - 2032F
- China Additional Vehicle Lighting Systems Market Trend Evolution
- China Additional Vehicle Lighting Systems Market Drivers and Challenges
- China Additional Vehicle Lighting Systems Price Trends
- China Additional Vehicle Lighting Systems Porter's Five Forces
- China Additional Vehicle Lighting Systems Industry Life Cycle
- Historical Data and Forecast of China Additional Vehicle Lighting Systems Market Revenues & Volume By Product Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Additional Vehicle Lighting Systems Market Revenues & Volume By LED Fog Lamps for the Period 2022 - 2032F
- Historical Data and Forecast of China Additional Vehicle Lighting Systems Market Revenues & Volume By Emergency Warning Lights for the Period 2022 - 2032F
- Historical Data and Forecast of China Additional Vehicle Lighting Systems Market Revenues & Volume By Daytime Running Lights for the Period 2022 - 2032F
- Historical Data and Forecast of China Additional Vehicle Lighting Systems Market Revenues & Volume By Auxiliary Driving Lamps for the Period 2022 - 2032F
- Historical Data and Forecast of China Additional Vehicle Lighting Systems Market Revenues & Volume By Distribution Channel for the Period 2022 - 2032F
- Historical Data and Forecast of China Additional Vehicle Lighting Systems Market Revenues & Volume By Direct Sales for the Period 2022 - 2032F
- Historical Data and Forecast of China Additional Vehicle Lighting Systems Market Revenues & Volume By Online Platforms for the Period 2022 - 2032F
- Historical Data and Forecast of China Additional Vehicle Lighting Systems Market Revenues & Volume By Automotive Dealerships for the Period 2022 - 2032F
- Historical Data and Forecast of China Additional Vehicle Lighting Systems Market Revenues & Volume By Aftermarket Retailers for the Period 2022 - 2032F
- Historical Data and Forecast of China Additional Vehicle Lighting Systems Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Additional Vehicle Lighting Systems Market Revenues & Volume By Passenger Vehicles for the Period 2022 - 2032F
- Historical Data and Forecast of China Additional Vehicle Lighting Systems Market Revenues & Volume By Commercial Trucks for the Period 2022 - 2032F
- Historical Data and Forecast of China Additional Vehicle Lighting Systems Market Revenues & Volume By Sports Utility Vehicles for the Period 2022 - 2032F
- Historical Data and Forecast of China Additional Vehicle Lighting Systems Market Revenues & Volume By Two-Wheelers for the Period 2022 - 2032F
- China Additional Vehicle Lighting Systems Import Export Trade Statistics
- Market Opportunity Assessment By Product Type
- Market Opportunity Assessment By Distribution Channel
- Market Opportunity Assessment By End User
- China Additional Vehicle Lighting Systems Top Companies Market Share
- China Additional Vehicle Lighting Systems Competitive Benchmarking By Technical and Operational Parameters
- China Additional Vehicle Lighting Systems Company Profiles
- China Additional Vehicle Lighting Systems Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By Product Type
- LED Fog Lamps
- Emergency Warning Lights
- Daytime Running Lights
- Auxiliary Driving Lamps
By Distribution Channel
- Direct Sales
- Online Platforms
- Automotive Dealerships
- Aftermarket Retailers
By End User
- Passenger Vehicles
- Commercial Trucks
- Sports Utility Vehicles
- Two-Wheelers































