China AdTech Software Market Size & Growth Rate
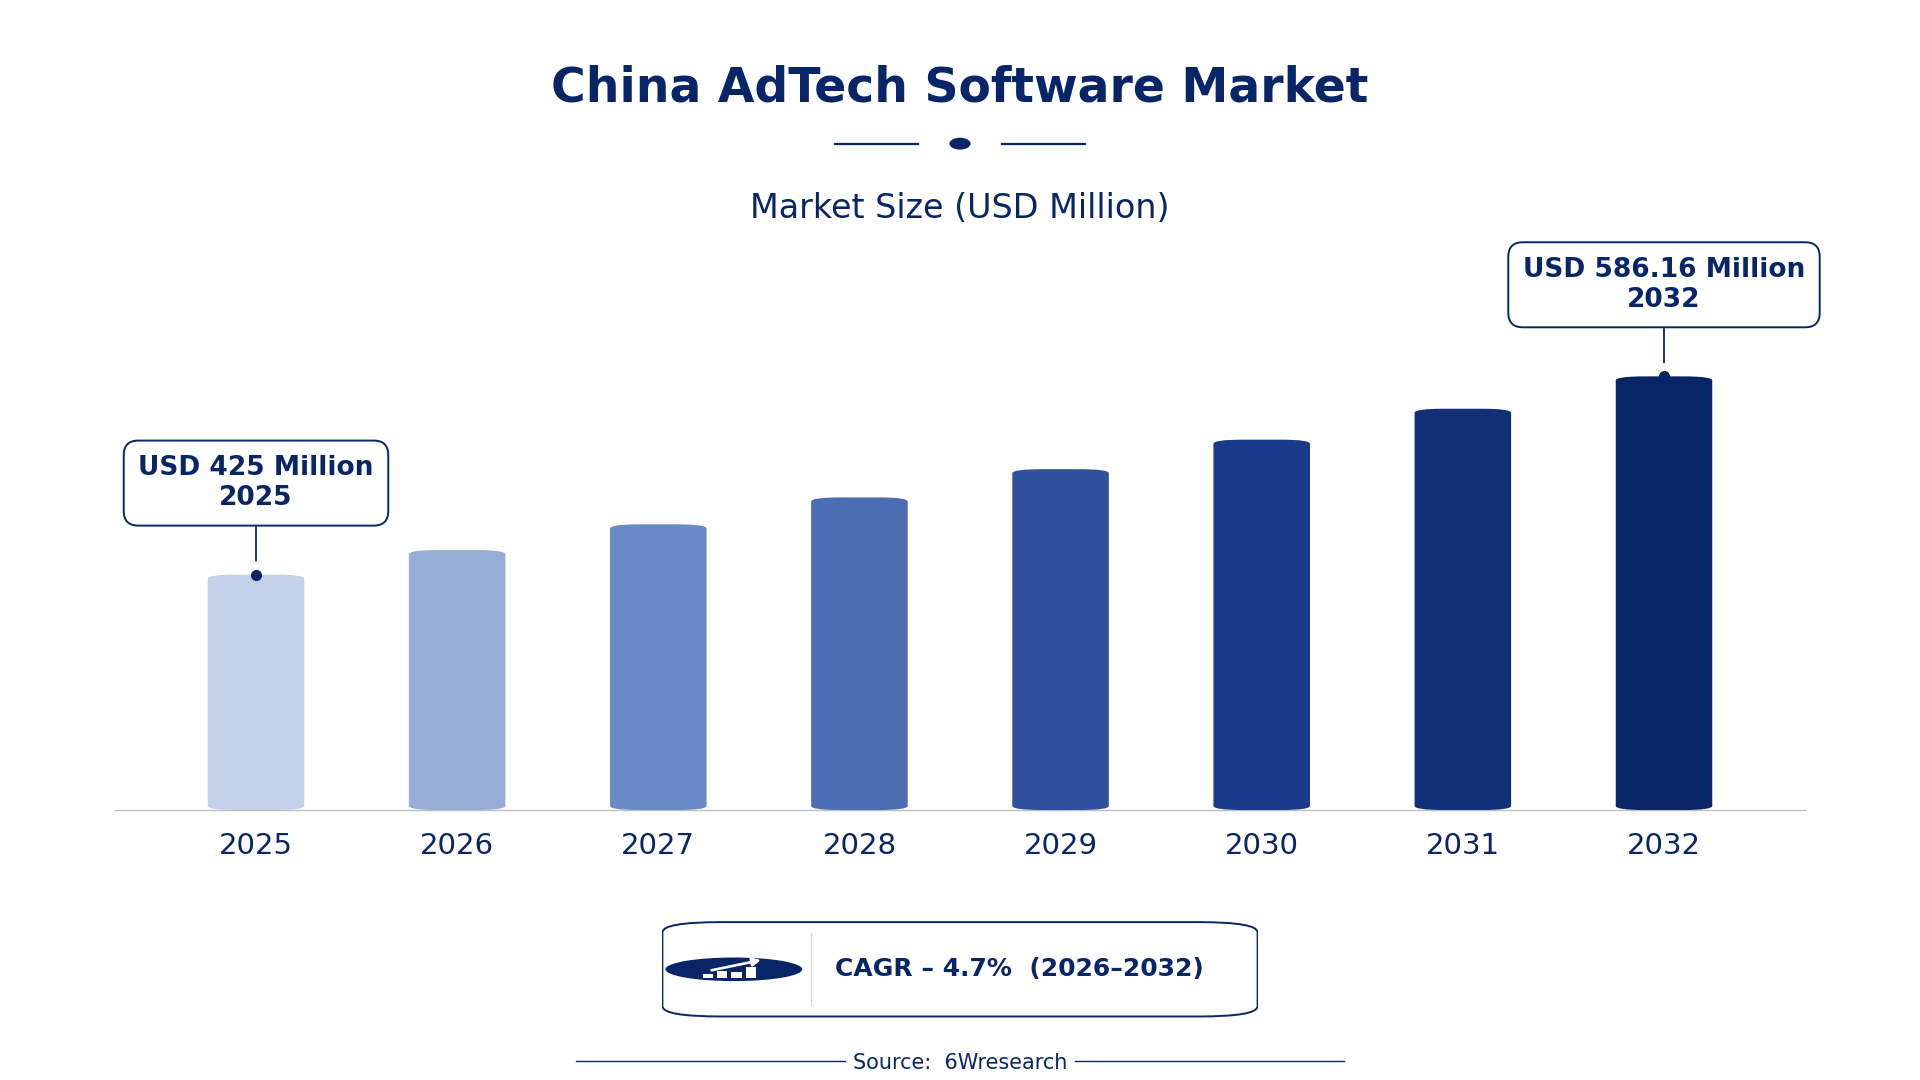
According to 6Wresearch internal database and industry insights, the China AdTech Software Market was valued at USD 425.0 million in 2025 and is projected to reach USD 586.16 million by 2032, growing at a CAGR of approximately 4.7% during 2026–2032.
China AdTech Software Market Highlights
| Report Metric | Details |
| Report Name | China AdTech Software Market |
| Market Size 2025 | USD 425.0 million |
| Market Size 2032 | USD 586.16 million |
| Absolute Growth 2025–2032 | USD 161.16 million |
| CAGR 2026–2032 | 4.7% |
| Peak Annual Growth | 7.2% in 2028 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Product Type, 2025 | Demand Side Platforms (DSP) (45% share) |
| Leading Solution Type, 2025 | Programmatic Buying (43% share) |
| Leading Deployment Mode, 2025 | Cloud-Based (44% share) |
| Leading Technology Used, 2025 | AI/ML Algorithms (42% share) |
| Leading End User, 2025 | Advertising Agencies (42% share) |
| Fastest-Growing Product Type | Data Management Platforms (DMP) (6.2% CAGR) |
| Fastest-Growing Solution Type | Audience Segmentation (6.9% CAGR) |
| Fastest-Growing Deployment Mode | SaaS (6.6% CAGR) |
| Fastest-Growing Technology Used | Big Data (5.8% CAGR) |
| Fastest-Growing End User | Publishers (7.0% CAGR) |
| Growing Sector | Advertising Agencies |
| Key End Users | Advertising Agencies, Digital Marketing Firms, Publishers, Media Companies |
China AdTech Software Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
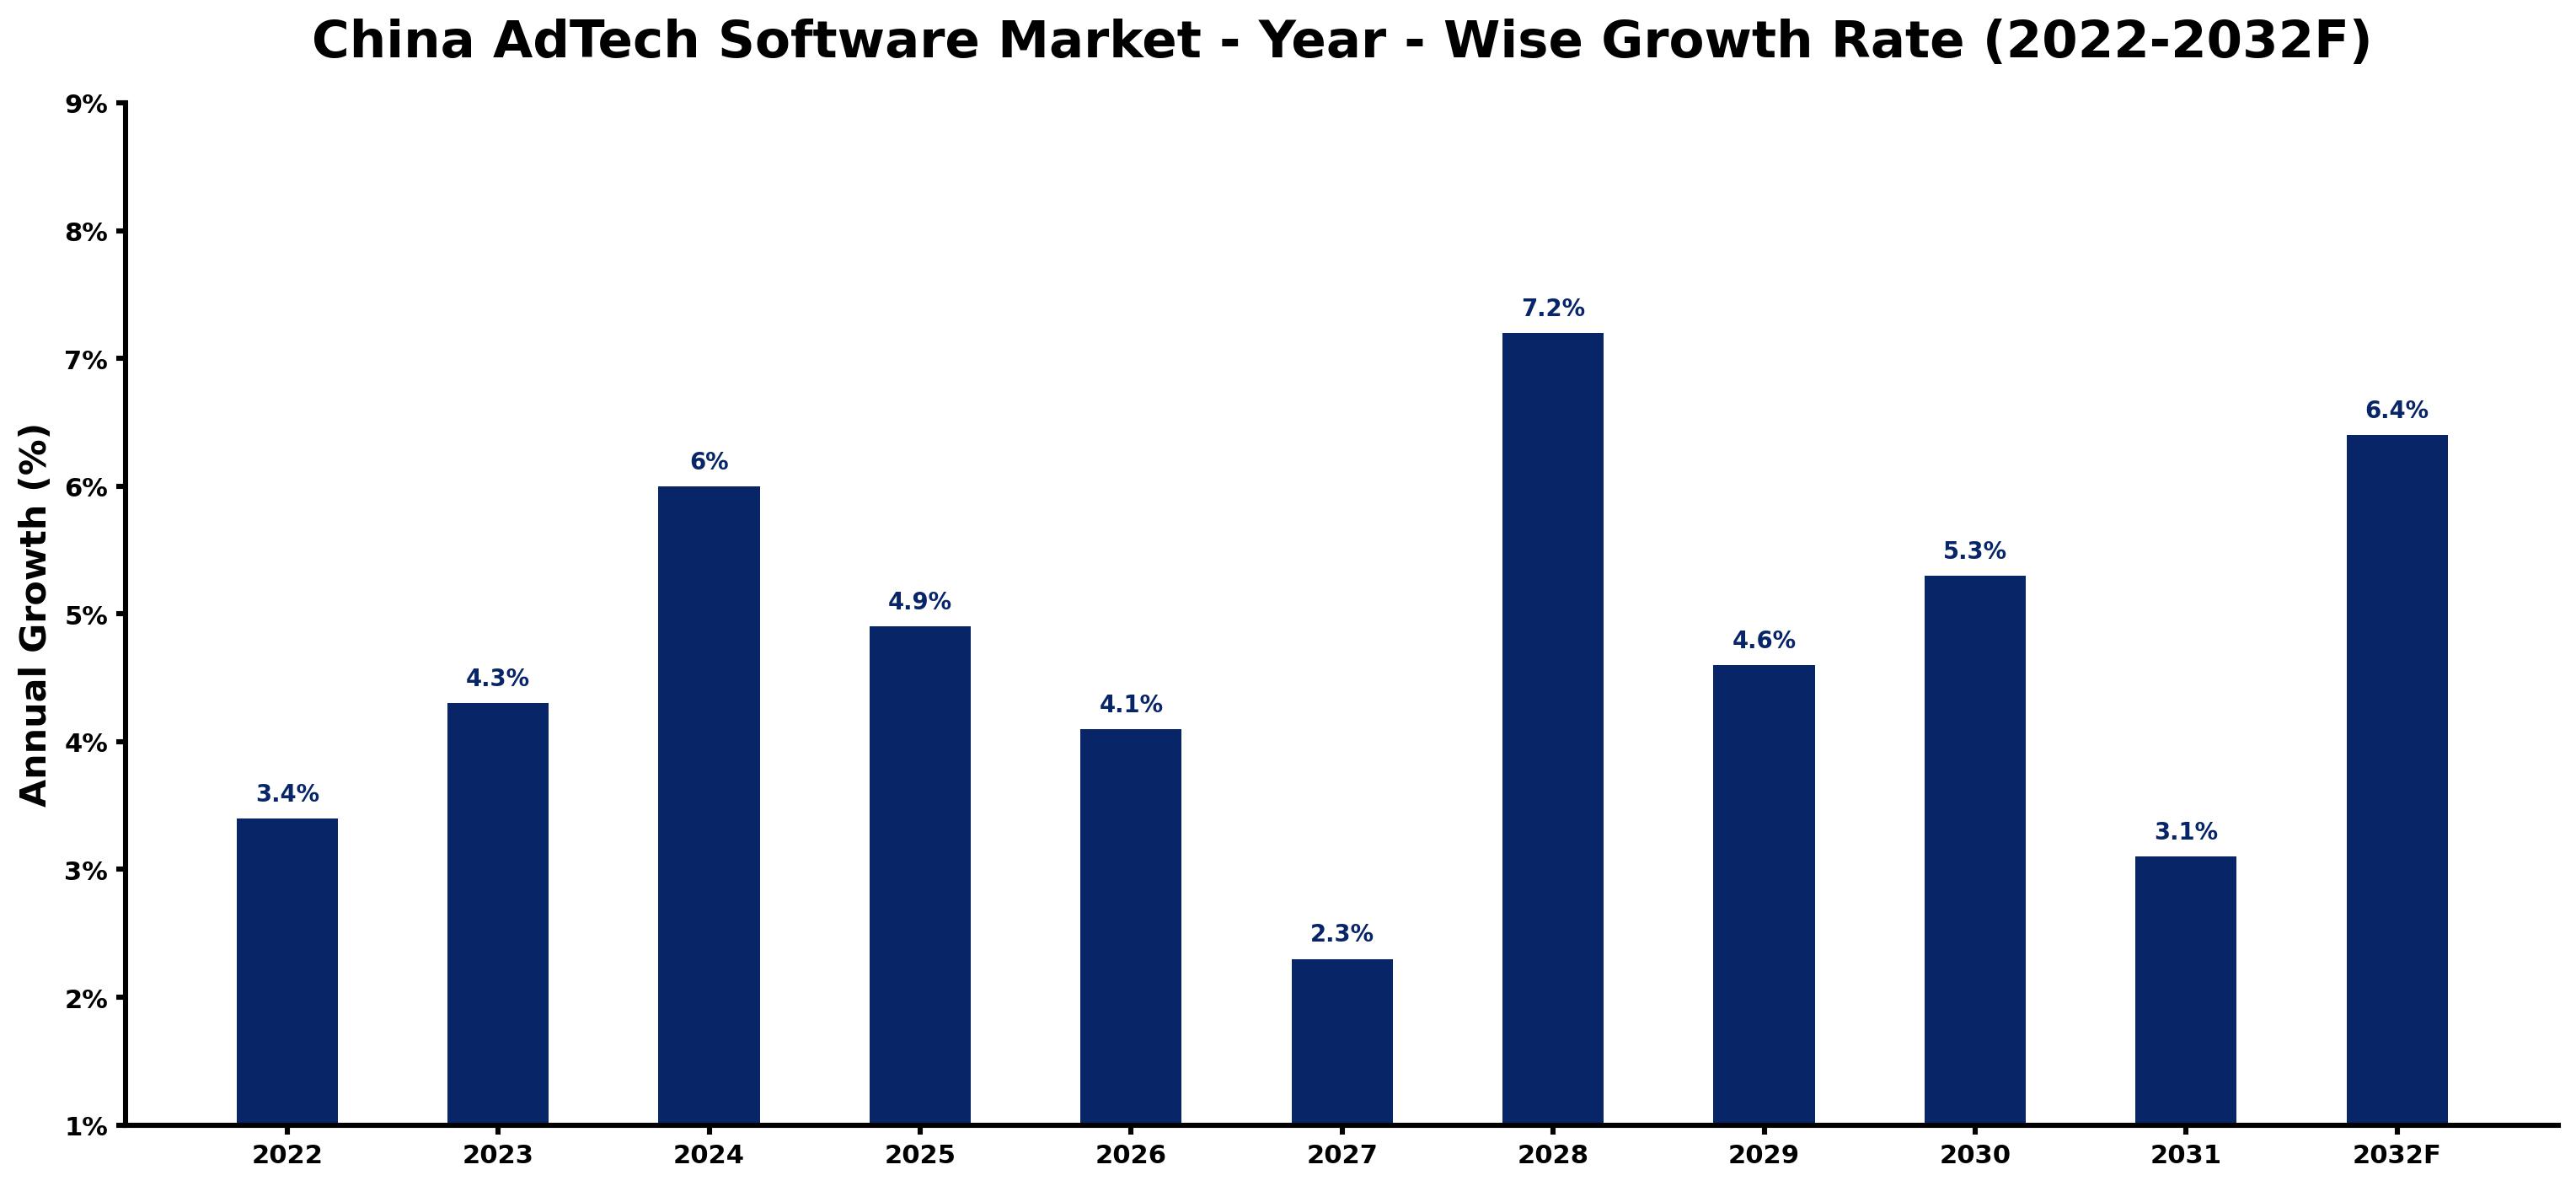
The table below sets out the estimated growth rate for each year and the main factor behind it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 3.4 | The market experienced steady growth as digital advertising expenditure reached approximately 1 trillion CNY. |
| 2023 | 4.3 | Increased online advertising budgets contributed to a faster growth rate compared to the previous year. |
| 2024 | 6.0 | The market saw heightened activity as programmatic ad spending gained traction among advertisers. |
| 2025 | 4.9 | Growth slowed slightly as the market adjusted to previous rapid expansions in digital ad spending. |
| 2026 | 4.1 | A further slowdown occurred as market conditions stabilise after a period of high growth. |
| 2027 | 2.3 | The market continued to grow, albeit at a slower pace, reflecting a maturing digital advertising sector. |
| 2028 | 7.2 | A resurgence in growth was driven by advancements in programmatic buying technologies and AI integration. |
| 2029 | 4.6 | Growth decelerated again as the market began to normalise after the peak in 2028. |
| 2030 | 5.3 | An uptick in growth is projected as new digital marketing strategies gain popularity among advertisers. |
| 2031 | 3.1 | The market is expected to experience a slowdown as competition intensifies among AdTech providers. |
| 2032 | 6.4 | Growth is projected to accelerate again due to increasing investments in digital advertising technologies. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China AdTech Software Market Synopsis
AdTech Software in China encompasses technologies for managing and optimising digital advertising campaigns. Developed through complex algorithms and data analytics, it is essential for programmatic advertising, audience targeting, and performance measurement. The China AdTech Software Market is expanding due to rising digital advertising budgets and the increasing number of internet users, which reached over 900 million. Initiatives like the 'Digital Economy Development Plan' are driving advancements in AdTech capabilities, further stimulating demand.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increasing digital advertising expenditure | Driver | High | Programmatic Buying |
| Growing internet user base | Driver | High | Demand Side Platforms (DSP) |
| Expansion of digital marketing firms | Opportunity | High | Digital Marketing Firms |
| Emerging AI technologies in advertising | Opportunity | High | AI/ML Algorithms |
| Regulatory constraints on online advertising | Restraint | Medium | Ad Analytics Tools |
| High competition among AdTech providers | Restraint | Medium | Supply Side Platforms (SSP) |
| Data privacy concerns affecting consumer trust | Challenge | High | Data Management Platforms (DMP) |
| Rapid technological changes necessitating constant updates | Challenge | Medium | Campaign Optimization |
Evaluation of Drivers in China AdTech Software Market (2026–2032)
The table below links each growth driver to the segment it affects and the evidence for it.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Rising digital advertising expenditure | Programmatic Buying | In 2022, digital advertising expenditure reached approximately 1 trillion CNY, prompting advertisers to invest more in programmatic solutions. |
| Growing internet user base | Demand Side Platforms (DSP) | With over 900 million internet users, advertisers are increasingly utilising DSPs to reach a vast audience. |
| Emergence of digital marketing firms | Digital Marketing Firms | The number of digital marketing firms in China is estimated to exceed 50,000 by 2025, driving demand for AdTech solutions. |
| Integration of AI technologies | AI/ML Algorithms | The Ministry of Industry and Information Technology promotes AI use in advertising, improving targeting and personalisation. |
| Increased focus on performance measurement | Ad Analytics Tools | Advertisers are prioritising tools that measure campaign effectiveness, leading to higher demand for analytics solutions. |
Expansion of the AdTech Software market in China is supported by increasing digital advertising expenditure, a larger internet user base, and the rise of digital marketing firms. In 2022, digital advertising expenditure reached around 1 trillion CNY, prompting advertisers to invest more in programmatic solutions. With over 900 million internet users, advertisers are turning to Demand Side Platforms to connect with a vast audience. The number of digital marketing firms in China is expected to exceed 50,000 by 2025, creating a strong demand for advanced solutions. The promotion of AI technologies in advertising is likely to improve targeting and personalisation, further driving demand.
Evaluation of Restraints in China AdTech Software Market
Below mentioned are some major restraints and their influence on market dynamics.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Regulatory constraints on online advertising | Ad Analytics Tools | The 'Regulations on Internet Advertising' issued in 2021 require transparency, which can limit the flexibility of analytics tools. |
| High competition among AdTech providers | Supply Side Platforms (SSP) | Intense competition leads to price wars, impacting profitability for providers in the SSP segment. |
| Limited awareness of AdTech benefits | Programmatic Buying | Some advertisers remain unaware of the advantages of programmatic buying, slowing market penetration. |
| Data privacy concerns affecting consumer trust | Data Management Platforms (DMP) | Growing concerns over data privacy can hinder the effectiveness of DMPs in audience targeting. |
| Rapid technological changes necessitating constant updates | Campaign Optimization | Frequent updates to technology can strain resources and increase operational costs for campaign optimisation. |
China AdTech Software Market Challenges
In 2022, digital advertising expenditure in China reached approximately 1 trillion CNY, highlighting intense competition among AdTech firms. This competition forces buyers to seek lower-cost solutions, which can erode profit margins for smaller providers. Many firms struggle to keep pace with rapid technological advancements, as they often lack the financial resources to invest in essential tools, delaying their market entry. Compliance with evolving regulations from the China Advertising Association incurs high costs, particularly for startups, diverting funds away from critical innovation efforts.
Trends in the China AdTech Software Market
Several trends are reshaping the China AdTech Software Market; the most important are set out below.
- Growth of Programmatic Buying: Beijing is undergoing a notable shift towards programmatic buying, with annual growth rates expected to reach 25%. This trend reflects the rising demand for automated ad purchasing solutions among advertisers.
- Shift Towards AI-Driven Advertising: The integration of AI technologies in advertising is becoming increasingly common, as highlighted by the 'National AI Development Plan' launched in 2020. This trend is set to enhance targeting capabilities and campaign performance.
- Emergence of Data Management Platforms: The rise of Data Management Platforms is reshaping how audience data is collected and analysed, with a projected CAGR of 6.2% from 2026 to 2032, indicating a stronger focus on data-driven advertising.
- Increase in Digital Marketing Firms: The number of digital marketing firms in China is anticipated to surpass 50,000 by 2025, reflecting the growing demand for AdTech solutions and the necessity for effective marketing strategies.
Investment Opportunities in the China AdTech Software Market
The following opportunities in the China AdTech Software Market pair current demand with a clear way in.
- Beijing as a Hub for AdTech Innovation: Beijing is emerging as a major hub for AdTech innovation, with substantial investments in technology. This environment creates opportunities for local partnerships and collaboration in the sector.
- Advertising Agencies Seeking Advanced Solutions: Advertising agencies are increasingly looking for advanced AdTech solutions to improve campaign effectiveness. With a projected market size of USD 586.16 million by 2032, suppliers can enter through local partnerships.
- Cloud-Based Solutions in High Demand: Cloud-based AdTech solutions are in high demand due to their scalability. The market for cloud-based solutions is anticipated to grow significantly, driven by the need for accessibility and flexibility.
- Investment in AI-Powered Tools: The growing need for AI-powered tools presents a valuable investment opportunity. With the Ministry of Industry and Information Technology promoting AI integration, firms can explore joint ventures to develop innovative solutions.
Government Initiatives in the China AdTech Software Market
The 'Regulations on Internet Advertising' issued by the State Administration for Market Regulation in 2021 aims to ensure transparency and fairness in online advertising practices, influencing how AdTech solutions are developed and marketed. The 'Guidelines for the Development of Digital Advertising', updated in 2022, focus on promoting ethical advertising practices and consumer protection, further shaping the operational environment for AdTech providers. The '14th Five-Year Plan for National Economic and Social Development', approved in 2021, underscores the importance of digital technologies, including AdTech, in driving economic growth. This plan encourages investment in digital infrastructure and innovation, affecting both AdTech producers and buyers.
In 2023, the government launched the 'Digital Economy Development Plan' to enhance digital advertising capabilities and promote innovation. The Ministry of Industry and Information Technology oversees this initiative, which aims to improve infrastructure and support the growth of AdTech companies. Additionally, the plan allocates funding for research and development in digital advertising technologies, benefiting both producers and buyers in the sector.
Future Insight of the China AdTech Software Market
Several forward-looking factors are poised to shape the AdTech Software market in China by 2032. The 'Digital Economy Development Plan' will strengthen capabilities, creating a more favourable environment for advertising technologies. By 2025, the number of digital marketing firms is projected to exceed 50,000, signalling robust industry growth. Programmatic ad spending is expected to grow annually at 25%, driving demand for effective advertising solutions. As user engagement on mobile platforms increases, opportunities for targeted advertising will expand significantly, benefiting both buyers and suppliers.
Market Segmentation Analysis
Each segment group is reviewed below, with the leader by share and the fastest grower by CAGR.
By Product Type – Demand Side Platforms (DSP) Dominated, Data Management Platforms (DMP) Expected to Grow Fastest
According to Ravi Bhandari, Research Head at 6Wresearch, Demand Side Platforms (DSP) took a 45% share of product type in 2025, more than any other category. Demand Side Platforms hold the largest share in the China AdTech Software Market as they are essential for advertisers to purchase ad space efficiently. The substantial digital advertising expenditure of approximately 1 trillion CNY in 2022 underscores their pivotal role in the advertising ecosystem. Over 2026–2032, Data Management Platforms (DMP) is expected to post the fastest growth, at a CAGR of 6.2%. Data Management Platforms are experiencing rapid growth due to the increasing need for aggregating and analysing audience data, which is crucial for targeted advertising. The projected annual growth rate of programmatic ad spending at 25% indicates a strong demand for these platforms. Suppliers should enhance features of Data Management Platforms to capitalise on this growth opportunity.
By Solution Type – Programmatic Buying Dominated, Audience Segmentation Expected to Grow Fastest
Programmatic Buying held a 43% share of the China AdTech Software Market by solution type in 2025. Programmatic Buying leads the market share as it is vital for automated ad purchasing, streamlining the advertising process for agencies. The vast number of digital ads in China, supported by over 900 million internet users, reinforces the importance of this solution. The quickest growth will come from Audience Segmentation, forecast to expand at a CAGR of 6.9% between 2026 and 2032. Audience Segmentation is expanding quickly as advertisers increasingly aim to effectively target specific demographics. Insights from the China Internet Report 2023 highlight a shift towards more personalised advertising strategies, driving demand for this solution. Buyers will gain a competitive edge by investing in Audience Segmentation tools to improve their targeting capabilities.
By Deployment Mode – Cloud-Based Dominated, SaaS Expected to Grow Fastest
In 2025, Cloud-Based led the deployment mode split with a 44% share. Cloud-Based deployment dominates the market due to its wide adoption for scalability and accessibility, making it a preferred choice for businesses. This trend is further supported by the anticipated growth in the number of digital marketing firms in China, estimated to exceed 50,000 by 2025. SaaS are set to record the highest CAGR in this split, 6.6% over 2026–2032. SaaS is rapidly gaining popularity owing to its subscription model and user-friendly nature, appealing to a diverse range of users. The convenience of SaaS solutions aligns with the increasing digital advertising budgets, propelling its growth. Suppliers should focus on developing user-friendly SaaS solutions to cater to the rising demand in the market.
By Technology Used – AI/ML Algorithms Dominated, Big Data Expected to Grow Fastest
The largest technology used category in 2025 was AI/ML Algorithms, with a 42% share of total revenue. AI/ML Algorithms command the largest market share as they improve targeting and personalisation, which are critical for effective advertising. The integration of these technologies is evident in the growing focus on automated and data-driven advertising strategies across China. Big Data is projected to grow fastest, at a CAGR of 5.8% during 2026–2032. Big Data is experiencing the fastest growth as it is crucial for processing extensive datasets, essential for optimising ad campaigns. The increasing complexity of digital advertising necessitates robust data processing capabilities, fuelling this segment's expansion. Buyers should invest in Big Data solutions to significantly enhance their advertising effectiveness.
By End User – Advertising Agencies Dominated, Publishers Expected to Grow Fastest
With a 42% revenue share in 2025, Advertising Agencies was the largest end user category. Advertising Agencies represent the largest share as they are the primary users executing campaigns across various platforms. Their central role in managing advertising strategies is highlighted by the expansive digital advertising landscape in China. Over 2026–2032, Publishers are expected to post the fastest growth, at a CAGR of 7.0%. Publishers are the fastest-growing segment as they play a key role in selling ad space, capitalising on the booming digital economy. The rise in online advertising budgets is creating more opportunities for publishers to effectively monetise their platforms. Suppliers should tailor their offerings to meet the specific needs of publishers to seize this growth opportunity.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China AdTech Software Market Outlook
- Market Size of China AdTech Software Market, 2025
- Forecast of China AdTech Software Market, 2032
- Historical Data and Forecast of China AdTech Software Revenues & Volume for the Period 2022 - 2032F
- China AdTech Software Market Trend Evolution
- China AdTech Software Market Drivers and Challenges
- China AdTech Software Price Trends
- China AdTech Software Porter's Five Forces
- China AdTech Software Industry Life Cycle
- Historical Data and Forecast of China AdTech Software Market Revenues & Volume By Product Type for the Period 2022 - 2032F
- Historical Data and Forecast of China AdTech Software Market Revenues & Volume By Demand Side Platforms (DSP) for the Period 2022 - 2032F
- Historical Data and Forecast of China AdTech Software Market Revenues & Volume By Data Management Platforms (DMP) for the Period 2022 - 2032F
- Historical Data and Forecast of China AdTech Software Market Revenues & Volume By Supply Side Platforms (SSP) for the Period 2022 - 2032F
- Historical Data and Forecast of China AdTech Software Market Revenues & Volume By Ad Analytics Tools for the Period 2022 - 2032F
- Historical Data and Forecast of China AdTech Software Market Revenues & Volume By Solution Type for the Period 2022 - 2032F
- Historical Data and Forecast of China AdTech Software Market Revenues & Volume By Programmatic Buying for the Period 2022 - 2032F
- Historical Data and Forecast of China AdTech Software Market Revenues & Volume By Audience Segmentation for the Period 2022 - 2032F
- Historical Data and Forecast of China AdTech Software Market Revenues & Volume By Inventory Management for the Period 2022 - 2032F
- Historical Data and Forecast of China AdTech Software Market Revenues & Volume By Campaign Optimization for the Period 2022 - 2032F
- Historical Data and Forecast of China AdTech Software Market Revenues & Volume By Deployment Mode for the Period 2022 - 2032F
- Historical Data and Forecast of China AdTech Software Market Revenues & Volume By Cloud-Based for the Period 2022 - 2032F
- Historical Data and Forecast of China AdTech Software Market Revenues & Volume By SaaS for the Period 2022 - 2032F
- Historical Data and Forecast of China AdTech Software Market Revenues & Volume By On-Premise for the Period 2022 - 2032F
- Historical Data and Forecast of China AdTech Software Market Revenues & Volume By Hybrid for the Period 2022 - 2032F
- Historical Data and Forecast of China AdTech Software Market Revenues & Volume By Technology Used for the Period 2022 - 2032F
- Historical Data and Forecast of China AdTech Software Market Revenues & Volume By AI/ML Algorithms for the Period 2022 - 2032F
- Historical Data and Forecast of China AdTech Software Market Revenues & Volume By Big Data for the Period 2022 - 2032F
- Historical Data and Forecast of China AdTech Software Market Revenues & Volume By Real-time Bidding for the Period 2022 - 2032F
- Historical Data and Forecast of China AdTech Software Market Revenues & Volume By Predictive Models for the Period 2022 - 2032F
- Historical Data and Forecast of China AdTech Software Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China AdTech Software Market Revenues & Volume By Advertising Agencies for the Period 2022 - 2032F
- Historical Data and Forecast of China AdTech Software Market Revenues & Volume By Publishers for the Period 2022 - 2032F
- Historical Data and Forecast of China AdTech Software Market Revenues & Volume By Media Companies for the Period 2022 - 2032F
- Historical Data and Forecast of China AdTech Software Market Revenues & Volume By Digital Marketing Firms for the Period 2022 - 2032F
- China AdTech Software Import Export Trade Statistics
- Market Opportunity Assessment By Product Type
- Market Opportunity Assessment By Solution Type
- Market Opportunity Assessment By Deployment Mode
- Market Opportunity Assessment By Technology Used
- Market Opportunity Assessment By End User
- China AdTech Software Top Companies Market Share
- China AdTech Software Competitive Benchmarking By Technical and Operational Parameters
- China AdTech Software Company Profiles
- China AdTech Software Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By Product Type
- Demand Side Platforms (DSP)
- Data Management Platforms (DMP)
- Supply Side Platforms (SSP)
- Ad Analytics Tools
By Solution Type
- Programmatic Buying
- Audience Segmentation
- Inventory Management
- Campaign Optimization
By Deployment Mode
- Cloud-Based
- SaaS
- On-Premise
- Hybrid
By Technology Used
- AI/ML Algorithms
- Big Data
- Real-time Bidding
- Predictive Models
By End User
- Advertising Agencies
- Publishers
- Media Companies
- Digital Marketing Firms































