China Advanced Aerospace Materials Market Size & Growth Rate
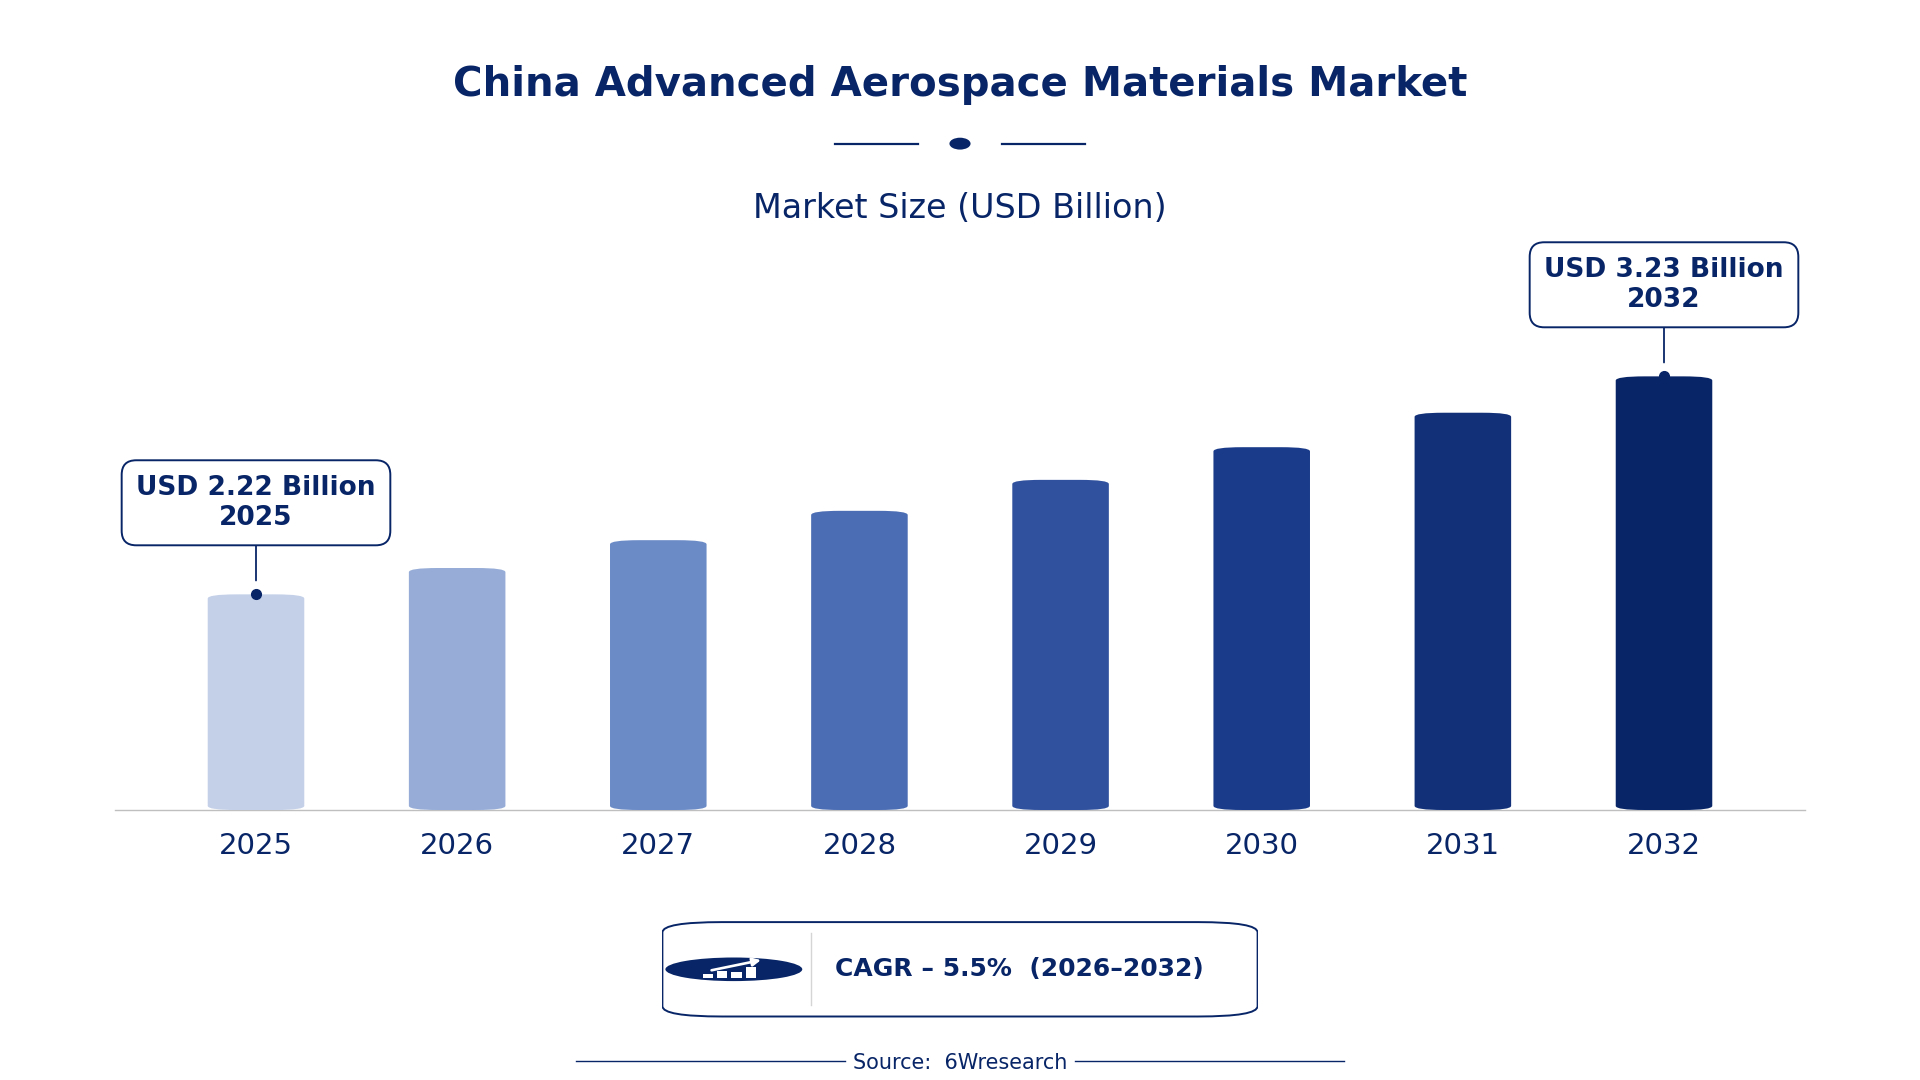
According to 6Wresearch internal database and industry insights, the China Advanced Aerospace Materials Market was valued at USD 2.22 billion in 2025 and is projected to reach USD 3.23 billion by 2032, growing at a CAGR of approximately 5.5% during 2026–2032.
China Advanced Aerospace Materials Market Highlights
| Report Metric | Details |
| Report Name | China Advanced Aerospace Materials Market |
| Market Size 2025 | USD 2.22 billion |
| Market Size 2032 | USD 3.23 billion |
| Absolute Growth 2025–2032 | USD 1.01 billion |
| CAGR 2026–2032 | 5.5% |
| Peak Annual Growth | 7.6% in 2031 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Material Type, 2025 | Titanium Alloys (40% share) |
| Leading Application, 2025 | Aircraft Structures (46% share) |
| Leading Form Type, 2025 | Sheets & Plates (44% share) |
| Leading Distribution Channel, 2025 | Direct Sales (39% share) |
| Leading End User Industry, 2025 | Aerospace Manufacturers (51% share) |
| Fastest-Growing Material Type | Carbon Composites (7.6% CAGR) |
| Fastest-Growing Application | Engine Components (6.7% CAGR) |
| Fastest-Growing Form Type | Prepregs (6.6% CAGR) |
| Fastest-Growing Distribution Channel | Online Platforms (7.9% CAGR) |
| Fastest-Growing End User Industry | Satellite Industry (7.2% CAGR) |
| Growing Sector | Engine Components |
| Key End Users | Aircraft Structures, Engine Components, Fuselage & Wings, Thermal Insulation |
China Advanced Aerospace Materials Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
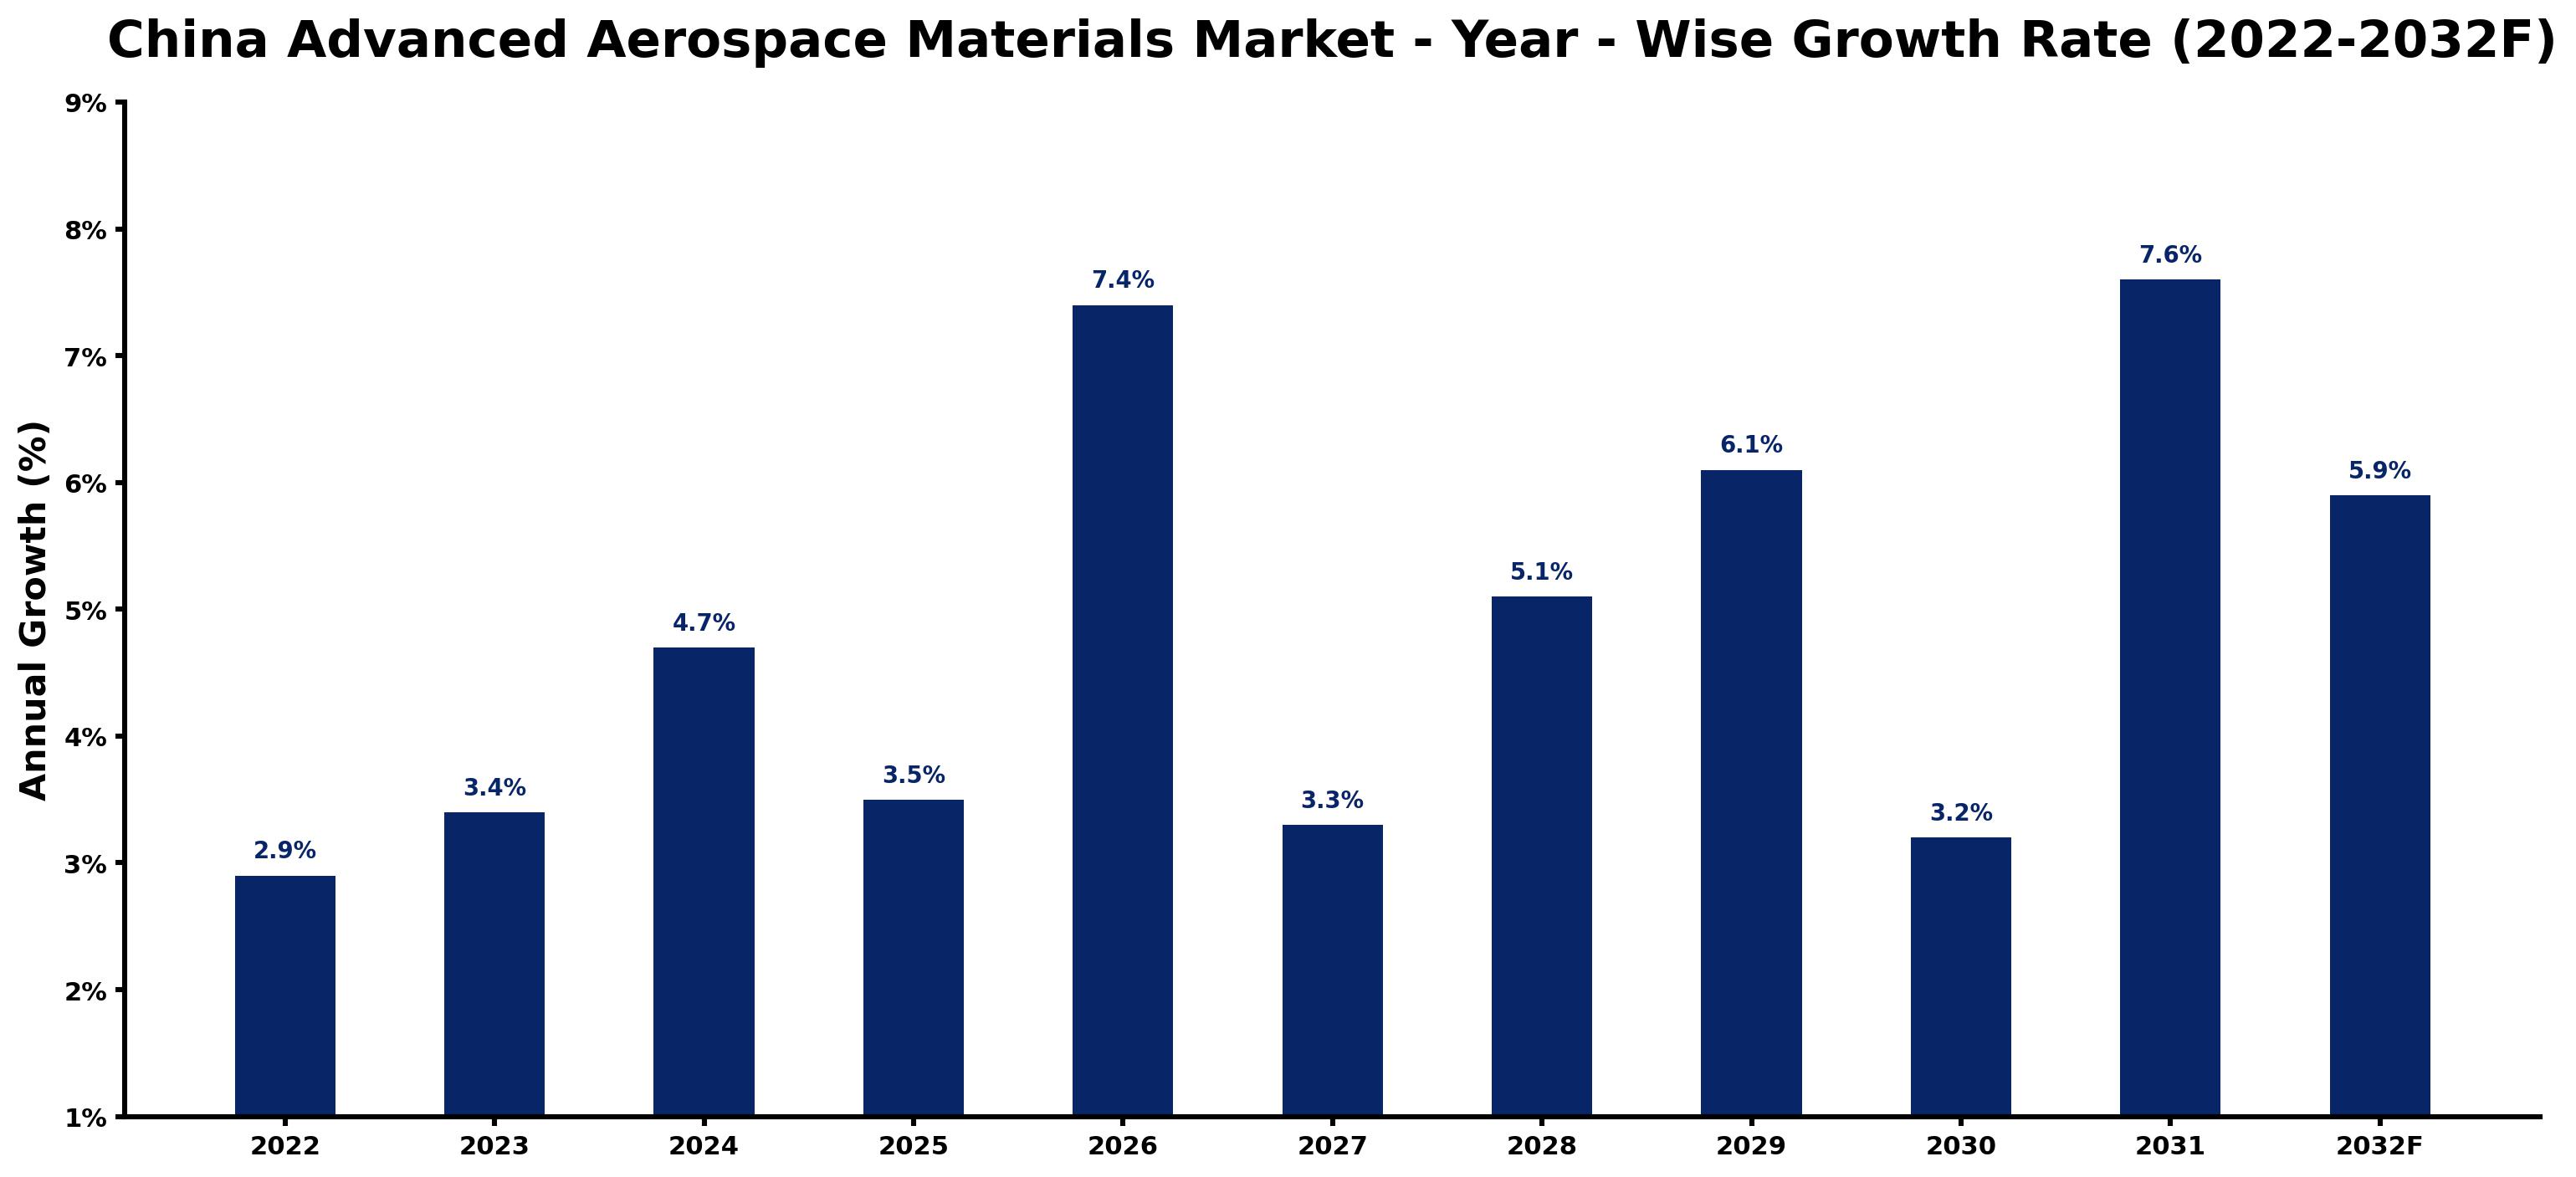
Each row of the following table gives one year's estimated growth and the event or demand shift that explains it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 2.9 | The aerospace sector showed stable demand, supported by ongoing production of commercial aircraft. |
| 2023 | 3.4 | Growth was driven by increased investments in aerospace technology and material development. |
| 2024 | 4.7 | Demand surged as the industry expanded production capabilities and improved material standards. |
| 2025 | 3.5 | Growth slowed slightly due to supply chain challenges affecting material sourcing. |
| 2026 | 7.4 | The market rebounded with accelerated demand for advanced materials in new aircraft designs. |
| 2027 | 3.3 | Growth slowed as manufacturers faced delays in regulatory approvals for new materials. |
| 2028 | 5.1 | Demand increased as the industry adopted advanced materials for enhanced performance. |
| 2029 | 6.1 | The sector grew steadily, driven by rising production rates in the satellite industry. |
| 2030 | 3.2 | Growth moderated as manufacturers adjusted to changing material costs and regulatory requirements. |
| 2031 | 7.6 | The market peaked with high demand for advanced materials in new aerospace projects. |
| 2032 | 5.9 | Growth slowed as the market stabilised, focusing on efficiency and sustainability. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Advanced Aerospace Materials Market Synopsis
The China Advanced Aerospace Materials Market encompasses high-performance materials such as titanium alloys and carbon composites, primarily used in aerospace applications. These materials are essential for aircraft structures, engine components, and thermal insulation systems. The market is expanding due to strong domestic demand from both commercial aviation and defense sectors, with the aerospace industry projected to reach a value of $1 trillion by 2030. Investments, including $10 billion allocated for aerospace technology development in 2021, are driving further growth.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Rising domestic demand from the commercial aviation sector | Driver | High | Aircraft Structures |
| Increased investment in aerospace technology development | Driver | High | Engine Components |
| Growing demand for lightweight materials in aircraft design | Opportunity | High | Carbon Composites |
| Expansion of aerospace manufacturing capabilities in Guangdong Province | Opportunity | Medium | Aluminum Alloys |
| Supply chain disruptions affecting material availability | Restraint | High | Titanium Alloys |
| Regulatory hurdles in material approvals slowing market entry | Restraint | Medium | Prepregs |
| High costs of advanced material production impacting pricing | Challenge | High | Thermal Insulation |
| Competition from alternative materials affecting market share | Challenge | Medium | Ceramic Matrix |
Evaluation of Drivers in China Advanced Aerospace Materials Market (2026–2032)
Key forces behind demand, with the segment each one moves most, are listed below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased production of commercial aircraft | Titanium Alloys | This drives demand for high-strength materials, with over 300 aircraft produced in 2022. |
| Investment in aerospace technology | Carbon Composites | The $10 billion allocated in 2021 supports material research and development. |
| Growing defense budgets | Aluminum Alloys | China's defense budget for 2023 includes substantial allocations for aerospace technology. |
| Expansion of aerospace research institutes | Engine Components | Over 20 institutes support advancements in material technologies across the country. |
| Rising demand for satellite construction | Thermal Insulation | The satellite industry is projected to consume advanced aerospace materials as it grows. |
Expansion of the Advanced Aerospace Materials market in China is driven by increasing domestic demand across various sectors and heightened investment in aerospace technology development. The aerospace industry is anticipated to reach a value of $1 trillion by 2030, fuelling further demand for advanced materials. In 2022, the production of over 300 commercial aircraft boosted the need for high-performance materials. The $10 billion allocated for aerospace technology development in 2021 supports material research and innovation. Additionally, the growing defence budget for 2023 includes substantial allocations for aerospace technology, further promoting market growth.
Evaluation of Restraints in China Advanced Aerospace Materials Market
The following restraints limit how fast demand can grow.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Supply chain disruptions affecting material availability | Titanium Alloys | Regulatory changes by the Civil Aviation Administration of China extend approval times, delaying sourcing. |
| Rising raw material costs impacting production expenses | Carbon Composites | Increased prices have inflated costs by 15%, affecting pricing strategies for suppliers. |
| Compliance challenges with quality standards | Aluminum Alloys | Meeting the National Standard GB/T 5237-2018 incurs costs exceeding 10% of project budgets. |
| Limited application of advanced materials in certain sectors | Ceramic Matrix | Specialised thermal protection systems restrict broader adoption in aerospace applications. |
| Technological barriers in material innovation | Prepregs | Development of new composite structures requires significant R&D investment, slowing market entry. |
China Advanced Aerospace Materials Market Challenges
Increasing supply chain disruptions in the China Advanced Aerospace Materials market have raised costs for producers, leading to delays in sourcing critical materials like titanium alloys. These disruptions stem from regulatory changes mandated by the Civil Aviation Administration of China, which can extend material approval times by six months, causing production delays for manufacturers. Rising raw material prices have inflated costs by 15% for suppliers, forcing them to pass these expenses onto buyers. Additionally, buyers face challenges in meeting the National Standard of China GB/T 5237-2018, resulting in compliance issues and potential quality assurance costs that can exceed 10% of project budgets.
Trends in the China Advanced Aerospace Materials Market
Four trends stand out in the China Advanced Aerospace Materials Market.
- Shift towards Lightweight Materials in Aerospace: China is increasingly adopting lightweight materials like carbon composites for aircraft structures. This shift began in 2021, driven by the need for improved fuel efficiency, with a projected growth rate of 7.6% for carbon composites from 2026 to 2032.
- Transition from Traditional to Advanced Manufacturing Techniques: The aerospace sector is moving towards advanced manufacturing techniques, such as additive manufacturing. This trend is supported by the establishment of over 20 aerospace research institutes, enhancing innovation and efficiency in material production.
- Emergence of Sustainable Aerospace Materials: There is a growing focus on sustainable materials in aerospace applications, particularly in response to environmental concerns. This trend gained momentum in 2023, as manufacturers seek to reduce their carbon footprint through innovative material solutions.
- Increase in Collaborative Research Initiatives: Collaborative research initiatives between academia and industry are expanding in China, promoting advancements in aerospace materials. The Aerospace Manufacturing Innovation and Development Program launched in 2022 supports these collaborations, fostering innovation.
Investment Opportunities in the China Advanced Aerospace Materials Market
Some of the investment opportunities in the China Advanced Aerospace Materials Market are mentioned below.
- Aerospace Manufacturers Seeking Advanced Materials: Aerospace manufacturers are increasingly looking for advanced materials to improve aircraft performance. The market is expected to grow to $2.22 billion by 2025, creating opportunities for suppliers to meet this demand.
- Partnerships with Research Institutions: Forming partnerships with aerospace research institutions can facilitate access to advanced material technologies. The National Standard GB/T 5237-2018 provides a framework for quality assurance, making collaboration beneficial.
- Investment in Aerospace Manufacturing in Guangdong Province: Guangdong Province is a key region for aerospace manufacturing, with significant growth potential. Investing in local production facilities can help tap into the expanding market, supported by the region's infrastructure.
- Expansion of Online Sales Channels: With the rise of digital platforms, there is an opportunity to expand online sales channels for aerospace materials. The growing trend of online platforms is projected to increase by 7.9% from 2026 to 2032.
Government Initiatives in the China Advanced Aerospace Materials Market
The National Aerospace Industry Development Plan (2021-2025) aims to enhance domestic aerospace material production and is overseen by the Ministry of Industry and Information Technology. This plan includes a budget of $15 billion to boost research in advanced materials and improve production capabilities. Furthermore, the National Standard GB/T 5237-2018 governs the quality of aerospace materials, ensuring that producers meet stringent requirements for material performance and safety. The Aerospace Manufacturing Innovation and Development Program (2022) promotes collaboration between research institutions and manufacturers to advance material technologies, fostering innovation in the sector.
The Ministry of Industry and Information Technology oversees the implementation of aerospace policies, approving projects related to advanced materials. The National Natural Science Foundation of China supports research projects focused on aerospace materials, ensuring continuous innovation and development. Additionally, the Civil Aviation Administration of China regulates aerospace standards, facilitating compliance for manufacturers and enhancing product quality.
Future Insight of the China Advanced Aerospace Materials Market
The China Advanced Aerospace Materials market will experience transformative changes by 2032, propelled by substantial government support and technological advancements. The allocation of $10 billion for aerospace technology development will drive material innovation, while over 20 aerospace research institutes will foster collaboration and research breakthroughs. By 2030, the aerospace industry is projected to reach a value of $1 trillion, creating substantial opportunities for suppliers and buyers alike. The Shanghai Free Trade Zone will play a pivotal role in promoting innovation and attracting new investments.
Market Segmentation Analysis
The report offers a comprehensive study of the following market segments and their leading categories in the market.
By Material Type – Titanium Alloys Dominated, Carbon Composites Expected to Grow Fastest
According to Ravi Bhandari, Research Head at 6Wresearch, in 2025, Titanium Alloys led the material type split with a 40% share. Titanium alloys dominate the market share as they are essential for their high strength and lightweight properties, crucial for aerospace applications. Their extensive use in the production of over 300 commercial aircraft in 2022 reinforces their leading position in the industry. The quickest growth will come from Carbon Composites, forecast to expand at a CAGR of 7.6% between 2026 and 2032. Carbon composites are experiencing rapid growth, primarily due to their high strength-to-weight ratio, which is vital for modern aircraft structures. As the aerospace sector increasingly prioritises fuel efficiency, demand for these materials is projected to rise significantly. Suppliers should focus on developing carbon composites to align with the growing demand in the advanced aerospace materials market.
By Application – Aircraft Structures Dominated, Engine Components Expected to Grow Fastest
With a 46% revenue share in 2025, Aircraft Structures was the largest application category. Aircraft structures hold the largest market share because they are critical for ensuring aircraft integrity and performance, directly affecting safety and efficiency. The production of over 300 commercial aircraft in 2022 highlights the importance of this application in the aerospace sector. Engine Components are projected to grow fastest, at a CAGR of 6.7% during 2026–2032. Engine components are witnessing the fastest growth due to their essential role in improving the efficiency and durability of aerospace engines. As advancements in engine technology continue, the demand for high-performance materials in this category will escalate. Buyers in the aerospace sector should prioritise sourcing high-quality materials for engine components to meet stringent industry performance standards.
By Form Type – Sheets & Plates Dominated, Prepregs Expected to Grow Fastest
Sheets & Plates held a 44% share of the China Advanced Aerospace Materials Market by form type in 2025. Sheets and plates are the leading form type in the market, widely utilised for structural applications in aerospace, providing necessary support and stability. Their prevalent use in manufacturing processes solidifies their strong market share. Prepregs are set to record the highest CAGR in this split, 6.6% over 2026–2032. Prepregs are rapidly gaining traction due to their precise material properties, which are crucial for composite structures in aerospace applications. As manufacturers aim to optimise performance, the demand for prepregs is set to grow significantly. Suppliers should consider expanding their product lines to include prepregs to meet the rising demand for advanced composite materials.
By Distribution Channel – Direct Sales Dominated, Online Platforms Expected to Grow Fastest
Direct Sales took a 39% share of distribution channel in 2025, more than any other category. Direct sales remain the primary distribution channel for aerospace materials, ensuring manufacturers have immediate access to essential supplies. This method aligns with the industry's need for reliability and efficiency in sourcing materials. Over 2026–2032, Online Platforms are expected to post the fastest growth, at a CAGR of 7.9%. Online platforms are emerging as the fastest-growing distribution channel, responding to the increasing demand for convenience and accessibility in material procurement. As more buyers transition to digital solutions, this trend is likely to continue expanding. Suppliers should enhance their online presence to capitalise on the growing trend of digital procurement in the advanced aerospace materials market.
By End User Industry – Aerospace Manufacturers Dominated, Satellite Industry Expected to Grow Fastest
The largest end user industry category in 2025 was Aerospace Manufacturers, with a 51% share of total revenue. Aerospace manufacturers are the largest consumers of advanced aerospace materials, driven by their need for high-performance components in aircraft production. Their significant role in the industry ensures a consistent demand for these materials. The quickest growth will come from Satellite Industry, forecast to expand at a CAGR of 7.2% between 2026 and 2032. The satellite industry is experiencing the fastest growth due to the rising demand for advanced materials in satellite construction. As space exploration and satellite technology advance, the requirements of this sector will continue to expand. Suppliers should explore partnerships with satellite manufacturers to tap into the growing market for advanced aerospace materials.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Advanced Aerospace Materials Market Outlook
- Market Size of China Advanced Aerospace Materials Market, 2025
- Forecast of China Advanced Aerospace Materials Market, 2032
- Historical Data and Forecast of China Advanced Aerospace Materials Revenues & Volume for the Period 2022 - 2032F
- China Advanced Aerospace Materials Market Trend Evolution
- China Advanced Aerospace Materials Market Drivers and Challenges
- China Advanced Aerospace Materials Price Trends
- China Advanced Aerospace Materials Porter's Five Forces
- China Advanced Aerospace Materials Industry Life Cycle
- Historical Data and Forecast of China Advanced Aerospace Materials Market Revenues & Volume By Material Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Aerospace Materials Market Revenues & Volume By Titanium Alloys for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Aerospace Materials Market Revenues & Volume By Carbon Composites for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Aerospace Materials Market Revenues & Volume By Ceramic Matrix for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Aerospace Materials Market Revenues & Volume By Aluminum Alloys for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Aerospace Materials Market Revenues & Volume By Application for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Aerospace Materials Market Revenues & Volume By Aircraft Structures for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Aerospace Materials Market Revenues & Volume By Engine Components for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Aerospace Materials Market Revenues & Volume By Thermal Insulation for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Aerospace Materials Market Revenues & Volume By Fuselage & Wings for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Aerospace Materials Market Revenues & Volume By Form Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Aerospace Materials Market Revenues & Volume By Sheets & Plates for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Aerospace Materials Market Revenues & Volume By Prepregs for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Aerospace Materials Market Revenues & Volume By Powders for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Aerospace Materials Market Revenues & Volume By Rods & Bars for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Aerospace Materials Market Revenues & Volume By Distribution Channel for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Aerospace Materials Market Revenues & Volume By Direct Sales for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Aerospace Materials Market Revenues & Volume By Online Platforms for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Aerospace Materials Market Revenues & Volume By Industrial Suppliers for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Aerospace Materials Market Revenues & Volume By Specialty Stores for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Aerospace Materials Market Revenues & Volume By End User Industry for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Aerospace Materials Market Revenues & Volume By Aerospace Manufacturers for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Aerospace Materials Market Revenues & Volume By Defense Contractors for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Aerospace Materials Market Revenues & Volume By Satellite Industry for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Aerospace Materials Market Revenues & Volume By Commercial Aviation for the Period 2022 - 2032F
- China Advanced Aerospace Materials Import Export Trade Statistics
- Market Opportunity Assessment By Material Type
- Market Opportunity Assessment By Application
- Market Opportunity Assessment By Form Type
- Market Opportunity Assessment By Distribution Channel
- Market Opportunity Assessment By End User Industry
- China Advanced Aerospace Materials Top Companies Market Share
- China Advanced Aerospace Materials Competitive Benchmarking By Technical and Operational Parameters
- China Advanced Aerospace Materials Company Profiles
- China Advanced Aerospace Materials Key Strategic Recommendations
Market Covered
The report offers an extensive study of the following market segments.
By Material Type
- Titanium Alloys
- Carbon Composites
- Ceramic Matrix
- Aluminum Alloys
By Application
- Aircraft Structures
- Engine Components
- Thermal Insulation
- Fuselage & Wings
By Form Type
- Sheets & Plates
- Prepregs
- Powders
- Rods & Bars
By Distribution Channel
- Direct Sales
- Online Platforms
- Industrial Suppliers
- Specialty Stores
By End User Industry
- Aerospace Manufacturers
- Defense Contractors
- Satellite Industry
- Commercial Aviation































