China Advanced Automotive Materials Market Size & Growth Rate
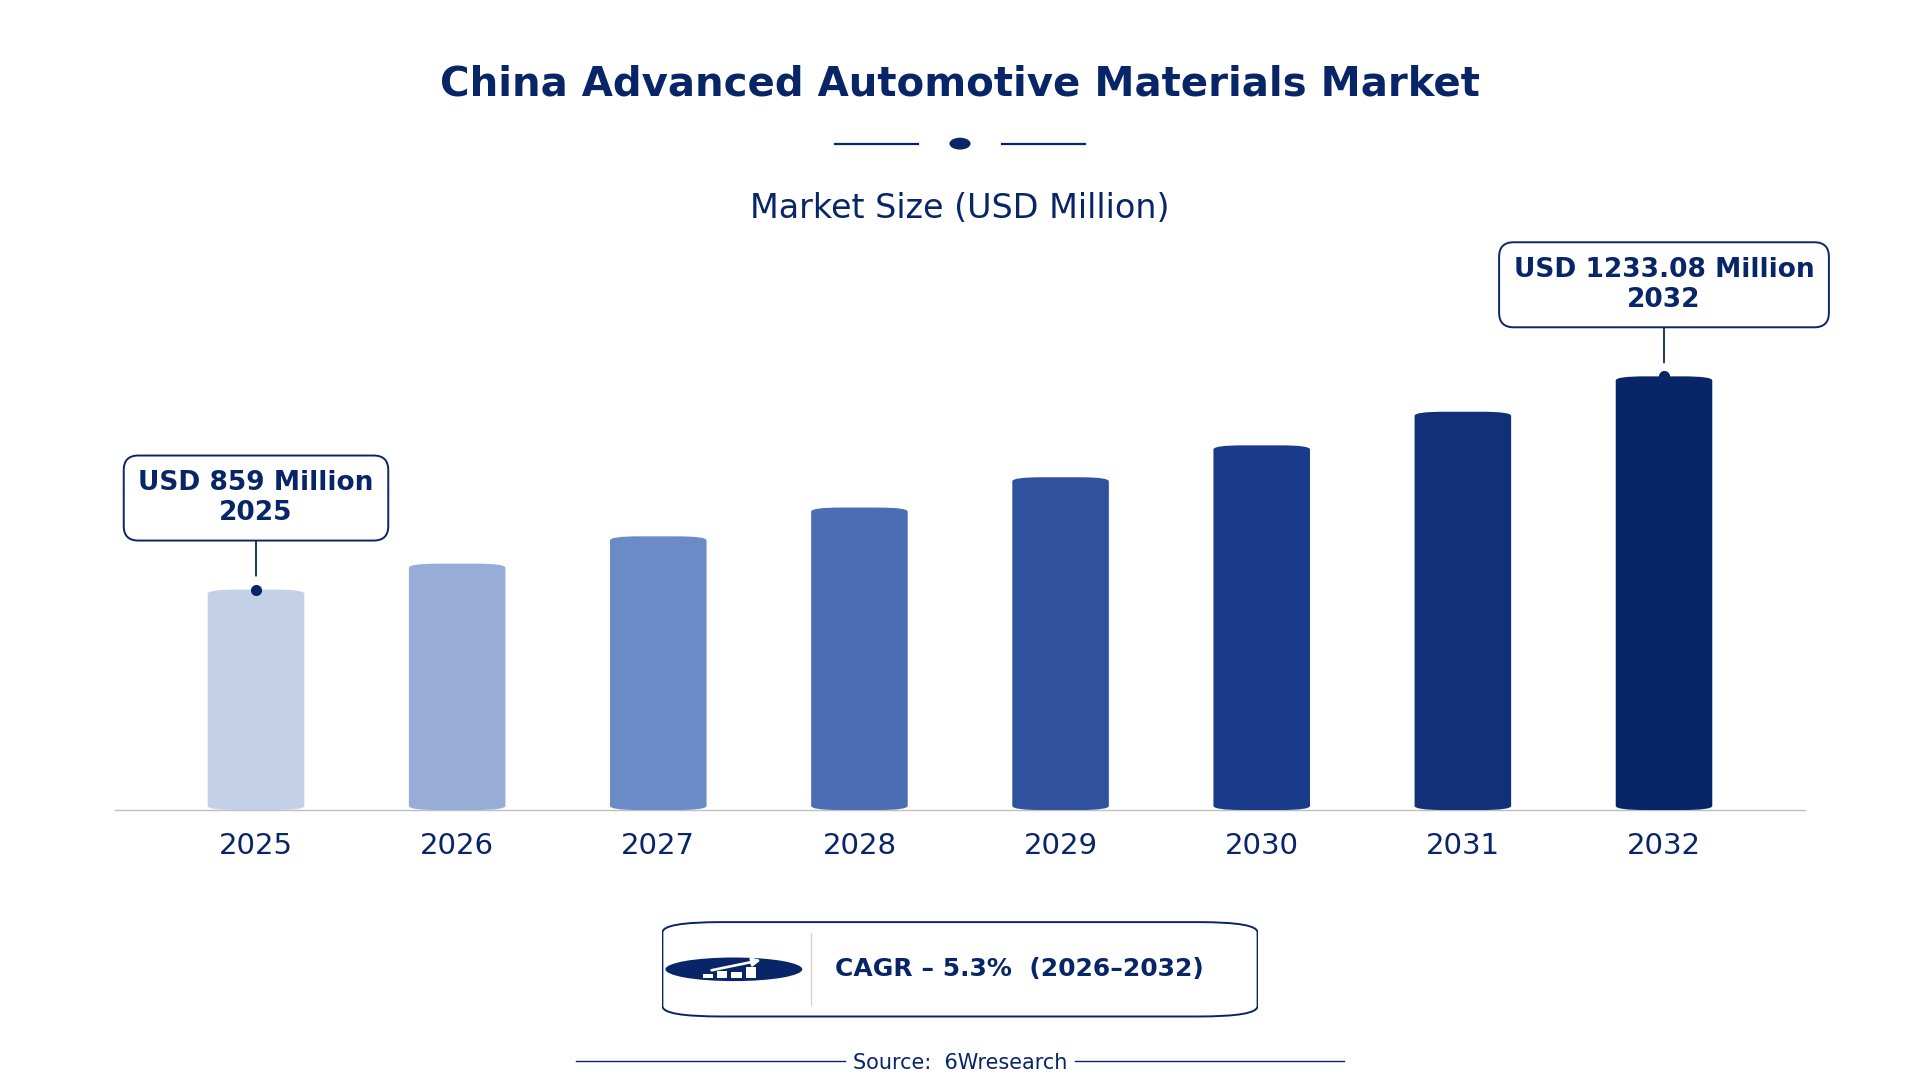
According to 6Wresearch internal database and industry insights, the China Advanced Automotive Materials Market was valued at USD 859.0 million in 2025 and is projected to reach USD 1,233.08 million by 2032, growing at a CAGR of approximately 5.3% during 2026–2032.
China Advanced Automotive Materials Market Highlights
| Report Metric | Details |
| Report Name | China Advanced Automotive Materials Market |
| Market Size 2025 | USD 859.0 million |
| Market Size 2032 | USD 1,233.08 million |
| Absolute Growth 2025–2032 | USD 374.08 million |
| CAGR 2026–2032 | 5.3% |
| Peak Annual Growth | 6.9% in 2031 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Material Type, 2025 | Aluminum Alloys (51% share) |
| Leading Application Area, 2025 | Body Structure (36% share) |
| Leading Vehicle Type, 2025 | Passenger Cars (38% share) |
| Leading Distribution Channel, 2025 | OEMs (52% share) |
| Leading End User Segment, 2025 | Auto Manufacturers (36% share) |
| Fastest-Growing Material Type | Carbon Fiber (7.4% CAGR) |
| Fastest-Growing Vehicle Type | Electric Vehicles (6.8% CAGR) |
| Fastest-Growing Distribution Channel | Direct Sales (7.0% CAGR) |
| Fastest-Growing End User Segment | EV Manufacturers (7.5% CAGR) |
| Growing Sector | Electric Vehicles |
| Key End Users | Auto Manufacturers, EV Manufacturers, Luxury Car Segment, Passenger Car Manufacturers |
China Advanced Automotive Materials Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
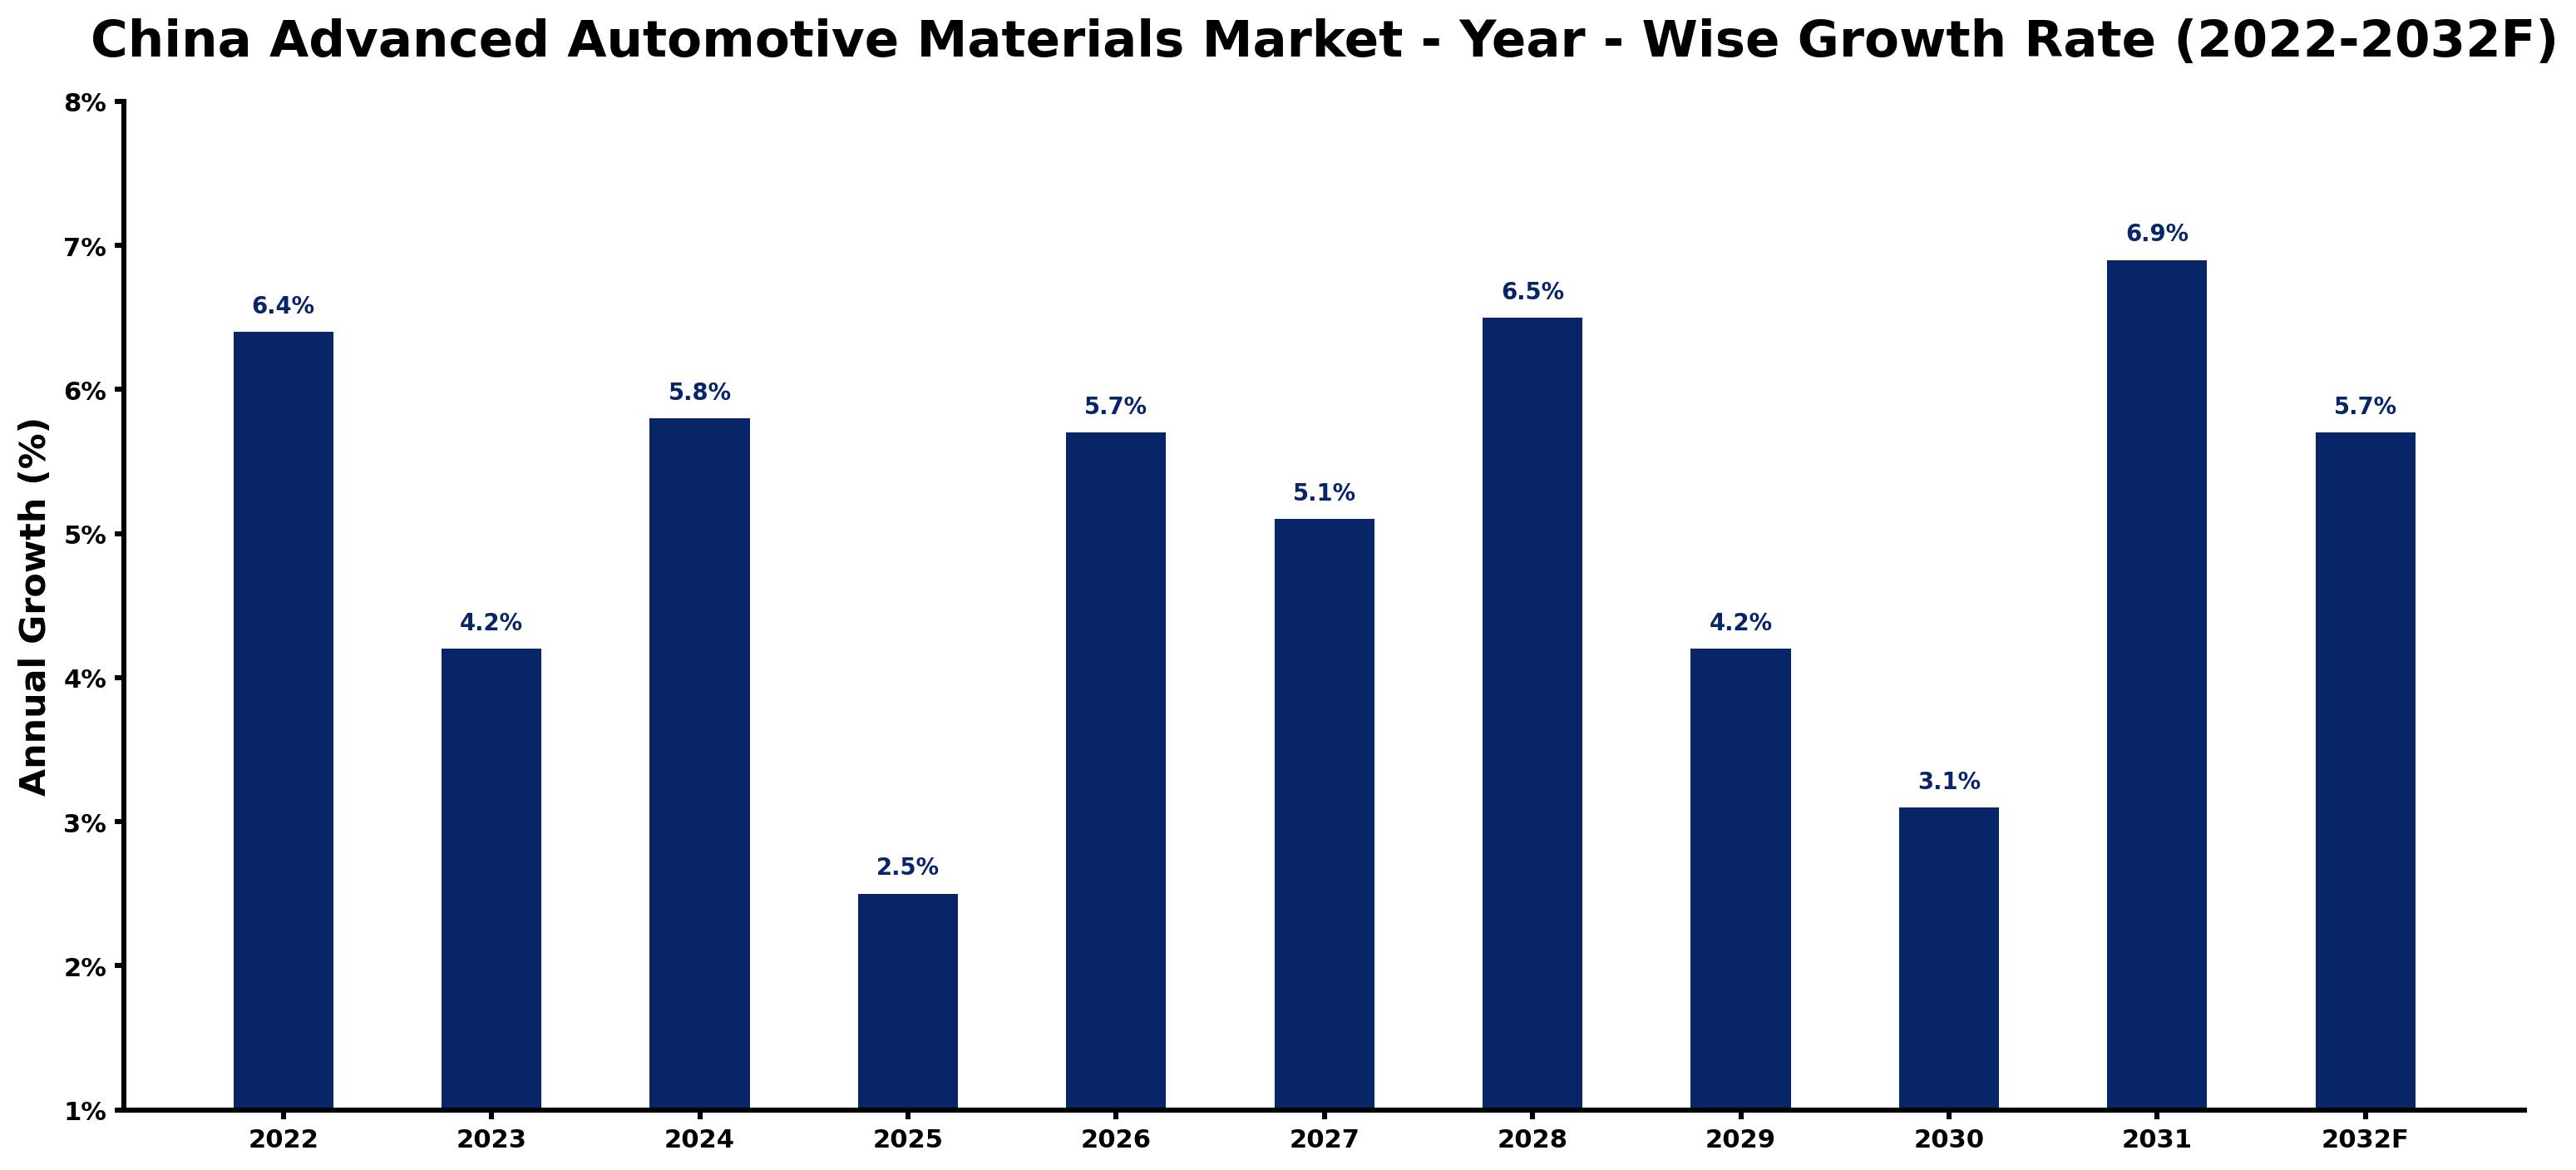
Annual growth estimates for each year appear below with the principal reason behind them, explaining the shifts that set the pace of the market.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 6.4 | The market experienced strong demand from domestic manufacturers and exports, particularly in electric vehicles. |
| 2023 | 4.2 | Growth slowed as manufacturers adjusted to changing material requirements and supply chain issues. |
| 2024 | 5.8 | Increased production of electric vehicles spurred demand for lightweight materials, boosting market growth. |
| 2025 | 2.5 | Market growth slowed as manufacturers faced challenges in sourcing advanced materials efficiently. |
| 2026 | 5.7 | Demand for advanced materials is expected to rise as the electric vehicle sector continues to expand. |
| 2027 | 5.1 | A slowdown is projected due to the 'New Energy Vehicle Industry Development Plan' encouraging efficiency improvements. |
| 2028 | 6.5 | A resurgence in demand for lightweight materials is anticipated as manufacturers seek to meet the 10% weight reduction goal by 2025. |
| 2029 | 4.2 | Market growth is expected to slow as manufacturers adapt to evolving standards and regulations in the sector. |
| 2030 | 3.1 | Demand is projected to slow as the market stabilises after rapid growth in previous years. |
| 2031 | 6.9 | The market is expected to experience growth driven by increased adoption of advanced materials in electric vehicles. |
| 2032 | 5.7 | Growth is projected to slow as the market matures and competition intensifies in the automotive sector. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Advanced Automotive Materials Market Synopsis
Advanced Automotive Materials in China include high-strength steel, carbon fiber, magnesium alloys, and aluminum alloys, which are engineered to enhance vehicle performance and safety. These materials are essential for improving fuel efficiency and reducing weight in vehicles. The China Advanced Automotive Materials Market is growing due to strong demand from domestic manufacturers and exports, particularly in the electric vehicle sector. The automotive industry in China is valued at approximately $500 billion as of 2023, with over 300 electric vehicle manufacturers contributing to this growth. The 'New Energy Vehicle Industry Development Plan' aims to increase EV production by 20% annually until 2025, further driving demand for these materials.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Growing demand for lightweight materials in electric vehicles | Driver | High | Electric Vehicles |
| Increased production of passenger cars requiring advanced materials | Driver | High | Passenger Cars |
| Rising investment in automotive manufacturing technologies | Opportunity | High | Auto Manufacturers |
| Expansion of the automotive supply chain in Guangdong province | Opportunity | Medium | Body Structure |
| Challenges in sourcing high-quality materials | Restraint | High | Aluminum Alloys |
| High production costs for advanced materials | Restraint | Medium | Carbon Fiber |
| Competition from alternative materials in automotive applications | Challenge | High | Magnesium Alloys |
| Regulatory compliance costs affecting manufacturers | Challenge | Medium | Engine Components |
Evaluation of Drivers in China Advanced Automotive Materials Market (2026–2032)
Key forces behind demand, with the segment each one moves most, are listed below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased production of electric vehicles | Electric Vehicles | This surge in production leads to higher demand for lightweight materials to improve efficiency. |
| Growing automotive manufacturing sector | Passenger Cars | The production of 25 million passenger cars in 2022 drives demand for advanced materials. |
| Investment in lightweight materials | Body Structure | The 'Made in China 2025' initiative focuses on improving material technology in automotive manufacturing. |
| Rising exports of vehicles | Auto Manufacturers | China's automotive exports reached 3 million units in 2022, increasing demand for advanced materials. |
| Technological advancements in material processing | Carbon Fiber | Projected carbon fiber usage of 15,000 tons by 2025 indicates rising demand for lightweight components. |
Growth across the Advanced Automotive Materials market in China is anchored in strong end-use demand from the automotive sector and a responsive supply chain. The production of 25 million passenger cars in 2022 boosts demand for lightweight options, as manufacturers strive for efficiency. With electric vehicle sales reaching 6.5 million units in 2022, manufacturers are increasingly sourcing advanced materials to meet efficiency targets. The projected carbon fiber usage of 15,000 tons by 2025 highlights the growing need for lightweight components in vehicle design.
Evaluation of Restraints in China Advanced Automotive Materials Market
The main factors holding the market back are set out below.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| High production costs for advanced materials | Carbon Fiber | The cost of producing carbon fiber remains high, limiting its widespread adoption in the automotive sector. |
| Challenges in sourcing quality materials | Aluminum Alloys | Manufacturers face difficulties in obtaining high-quality aluminum alloys, impacting production timelines. |
| Competition from alternative materials | Magnesium Alloys | Alternative materials are often more cost-effective, posing a challenge to the adoption of magnesium alloys. |
| Regulatory compliance costs | Engine Components | Manufacturers incur costs to comply with evolving regulations on material standards, affecting profitability. |
| Limited availability of advanced materials | Body Structure | Supply chain disruptions can lead to shortages of essential materials for vehicle production. |
China Advanced Automotive Materials Market Challenges
Buyers in the China Advanced Automotive Materials market face rising costs due to fluctuating raw material prices, which can elevate production expenses by up to 20%. Suppliers encounter challenges with outdated technology, as many lack the necessary infrastructure to implement modern manufacturing processes, resulting in delays that can extend lead times by four weeks. The supply chain experiences regional disparities, particularly in Guangdong and Jiangsu provinces, leading to logistical challenges that can postpone deliveries for automotive companies. A shortage of skilled workers in advanced manufacturing processes limits production capabilities, potentially reducing efficiency by 15% for automotive firms.
Trends in the China Advanced Automotive Materials Market
The trends below show where the China Advanced Automotive Materials Market is heading.
- Shift towards Lightweight Materials in EV Manufacturing: Electric vehicle manufacturers are increasingly prioritising lightweight materials to improve efficiency. The 'New Energy Vehicle Industry Development Plan' aims for a 20% annual increase in EV production until 2025, driving demand for advanced materials.
- Transition from Steel to Aluminum Alloys: The automotive industry is transitioning from traditional steel to aluminum alloys for vehicle structures. China's aluminum alloy production is expected to exceed 5 million tons by 2025, reflecting this shift in material preference.
- Emergence of Carbon Fiber in Automotive Applications: Carbon fiber is gaining traction in the automotive sector for its lightweight properties. Usage in the automotive sector is projected to reach 15,000 tons by 2025, indicating a growing trend.
- Prioritisation of Body Structure Materials: Manufacturers are focusing on advanced materials for body structures to improve safety and performance. Body structure materials are projected to hold a 36% market share by 2025, highlighting their importance.
Investment Opportunities in the China Advanced Automotive Materials Market
Below are the investment opportunities with the strongest case in the China Advanced Automotive Materials Market.
- Auto Manufacturers seeking lightweight solutions: Auto manufacturers are increasingly in search of lightweight materials to boost vehicle efficiency. With the automotive market valued at approximately $500 billion, there is a clear opportunity to supply advanced materials.
- Supply of Carbon Fiber for automotive applications: The rising demand for carbon fiber offers suppliers a chance to enter the market. With projected usage reaching 15,000 tons by 2025, partnerships with manufacturers can facilitate this entry.
- Investment in Guangdong's automotive supply chain: Guangdong province's automotive supply chain is expanding, creating investment opportunities in advanced materials. Collaborating with local manufacturers can improve market access.
- Entry through certification and standards compliance: Suppliers can enter the market by obtaining ISO 9001 certification, a quality management standard in automotive manufacturing. This compliance can lead to partnerships with major manufacturers.
Government Initiatives in the China Advanced Automotive Materials Market
The 'New Energy Vehicle Industry Development Plan', launched by the Ministry of Industry and Information Technology in 2021, aims to increase electric vehicle production by 20% annually until 2025. This initiative encourages the adoption of advanced materials to improve vehicle performance and efficiency. The updated 'Automotive Industry Development Policy' in 2020 promotes the use of lightweight materials in vehicle manufacturing, aligning with national goals for sustainability and innovation. These measures directly impact producers of advanced automotive materials by creating a more supportive environment for their adoption.
The State Administration for Market Regulation oversees the implementation of the 'New Energy Vehicle Industry Development Plan', providing funding and support for research in advanced automotive materials. The Ministry of Science and Technology announced a funding program in 2023 to support research in advanced automotive materials, ensuring that manufacturers have access to the latest technologies and standards. These initiatives help buyers in the automotive sector to adopt advanced materials that meet regulatory requirements and improve production capabilities.
Future Insight of the China Advanced Automotive Materials Market
The China Advanced Automotive Materials market is poised for transformation by 2032, driven by the 'New Energy Vehicle Industry Development Plan' and 'Made in China 2025'. Advanced manufacturing technologies will elevate material performance, supporting a 10% average weight reduction goal for vehicles. The demand for carbon fiber is expected to increase, contributing to improved fuel efficiency and safety. With over 300 electric vehicle manufacturers, the need for high-quality materials will create substantial opportunities for both buyers and suppliers in the automotive sector.
Market Segmentation Analysis
The analysis below covers each segmentation, its leading category in 2025 and its fastest-growing category through 2032.
By Material Type – Aluminum Alloys Dominated, Carbon Fiber Expected to Grow Fastest
According to Ravi Bhandari, Research Head at 6Wresearch, with a 51% revenue share in 2025, Aluminum Alloys was the largest material type category. Aluminum alloys hold the largest share in the China Advanced Automotive Materials Market because they are extensively used in lightweight structures that enhance fuel efficiency. The expected production of over 5 million tons of aluminum alloys by 2025 highlights their critical role in the automotive sector. Carbon Fiber is set to record the highest CAGR in this split, 7.4% over 2026–2032. Carbon fiber is projected to grow the fastest, largely due to its application in lightweight components that significantly boost vehicle efficiency. The anticipated consumption of 15,000 tons of carbon fiber by 2025 indicates a strong shift towards these advanced materials. Suppliers should concentrate on developing lightweight materials to meet the growing demand from manufacturers focused on efficiency.
By Application Area – Body Structure Dominated and Is Expected to Record the Fastest Growth
The largest application area category in 2025 was Body Structure, with a 36% share of total revenue. Body structure applications dominate the market share as they are crucial for vehicle safety and performance, making them a top priority for manufacturers. The emphasis on structural integrity in vehicle design underscores the importance of advanced materials in this area. Body Structure is also forecast to expand faster than any other category, at a CAGR of 7.9% over 2026–2032. The body structure segment is also the fastest-growing area, driven by increasing safety standards and performance expectations in vehicle manufacturing. As regulations tighten, the demand for advanced materials in body structures is set to rise. Manufacturers must invest in advanced materials to comply with safety standards and improve vehicle performance.
By Vehicle Type – Passenger Cars Dominated, Electric Vehicles Expected to Grow Fastest
Passenger Cars held a 38% share of the China Advanced Automotive Materials Market by vehicle type in 2025. Passenger cars account for the largest share of the market as they are the main segment utilising advanced materials to enhance performance and safety. The production of 25 million passenger cars in 2022 illustrates the significant demand for these materials. Electric Vehicles are projected to grow fastest, at a CAGR of 6.8% during 2026–2032. Electric vehicles represent the fastest-growing segment, propelled by the increasing need for lightweight materials that improve battery efficiency and overall performance. The sale of 6.5 million electric vehicles in 2022 showcases the rapid growth of this category. Suppliers should focus on creating lightweight materials tailored for electric vehicles to take advantage of this expanding market.
By Distribution Channel – OEMs Dominated, Direct Sales Expected to Grow Fastest
OEMs accounted for a 52% market share by distribution channel in 2025. OEMs hold the largest market share as they are the primary users of advanced materials in vehicle production, ensuring high demand. Their established relationships with material suppliers facilitate consistent procurement of necessary materials. The quickest growth will come from Direct Sales, forecast to expand at a CAGR of 7.0% between 2026 and 2032. Direct sales are the fastest-growing channel, catering to niche markets that require specialised materials for unique applications. This growth reflects a shift towards more personalised supply chains in the automotive sector. Suppliers should consider expanding their distribution strategies to include direct sales for niche markets.
By End User Segment – Auto Manufacturers Dominated, EV Manufacturers Expected to Grow Fastest
In 2025, Auto Manufacturers led the end user segment split with a 36% share. Auto manufacturers represent the largest end-user segment, utilising advanced materials to meet consumer demands for performance and safety. Their substantial production volumes drive the overall market share for these materials. EV Manufacturers are set to record the highest CAGR in this split, 7.5% over 2026–2032. EV manufacturers are the fastest-growing segment, as the rapid expansion of electric vehicle production necessitates advanced materials for improved efficiency and performance. The increasing focus on sustainability fuels this growth. Suppliers must align their offerings with the specific needs of EV manufacturers to seize emerging opportunities.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Advanced Automotive Materials Market Outlook
- Market Size of China Advanced Automotive Materials Market, 2025
- Forecast of China Advanced Automotive Materials Market, 2032
- Historical Data and Forecast of China Advanced Automotive Materials Revenues & Volume for the Period 2022 - 2032F
- China Advanced Automotive Materials Market Trend Evolution
- China Advanced Automotive Materials Market Drivers and Challenges
- China Advanced Automotive Materials Price Trends
- China Advanced Automotive Materials Porter's Five Forces
- China Advanced Automotive Materials Industry Life Cycle
- Historical Data and Forecast of China Advanced Automotive Materials Market Revenues & Volume By Material Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Automotive Materials Market Revenues & Volume By AHSS for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Automotive Materials Market Revenues & Volume By Carbon Fiber for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Automotive Materials Market Revenues & Volume By Magnesium Alloys for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Automotive Materials Market Revenues & Volume By Aluminum Alloys for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Automotive Materials Market Revenues & Volume By Application Area for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Automotive Materials Market Revenues & Volume By Body Structure for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Automotive Materials Market Revenues & Volume By Interior & Exterior for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Automotive Materials Market Revenues & Volume By Transmission Parts for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Automotive Materials Market Revenues & Volume By Engine Components for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Automotive Materials Market Revenues & Volume By Vehicle Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Automotive Materials Market Revenues & Volume By Passenger Cars for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Automotive Materials Market Revenues & Volume By Sports Cars for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Automotive Materials Market Revenues & Volume By Commercial Vehicles for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Automotive Materials Market Revenues & Volume By Electric Vehicles for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Automotive Materials Market Revenues & Volume By Distribution Channel for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Automotive Materials Market Revenues & Volume By OEMs for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Automotive Materials Market Revenues & Volume By Direct Sales for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Automotive Materials Market Revenues & Volume By Industrial Suppliers for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Automotive Materials Market Revenues & Volume By Online Platforms for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Automotive Materials Market Revenues & Volume By End User Segment for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Automotive Materials Market Revenues & Volume By Auto Manufacturers for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Automotive Materials Market Revenues & Volume By Luxury Car Segment for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Automotive Materials Market Revenues & Volume By Trucking Companies for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Automotive Materials Market Revenues & Volume By EV Manufacturers for the Period 2022 - 2032F
- China Advanced Automotive Materials Import Export Trade Statistics
- Market Opportunity Assessment By Material Type
- Market Opportunity Assessment By Application Area
- Market Opportunity Assessment By Vehicle Type
- Market Opportunity Assessment By Distribution Channel
- Market Opportunity Assessment By End User Segment
- China Advanced Automotive Materials Top Companies Market Share
- China Advanced Automotive Materials Competitive Benchmarking By Technical and Operational Parameters
- China Advanced Automotive Materials Company Profiles
- China Advanced Automotive Materials Key Strategic Recommendations
Market Covered
Segments analysed in this report are listed below.
By Material Type
- AHSS
- Carbon Fiber
- Magnesium Alloys
- Aluminum Alloys
By Application Area
- Body Structure
- Interior & Exterior
- Transmission Parts
- Engine Components
By Vehicle Type
- Passenger Cars
- Sports Cars
- Commercial Vehicles
- Electric Vehicles
By Distribution Channel
- OEMs
- Direct Sales
- Industrial Suppliers
- Online Platforms
By End User Segment
- Auto Manufacturers
- Luxury Car Segment
- Trucking Companies
- EV Manufacturers































