China Advanced Farming Automation Market Size & Growth Rate
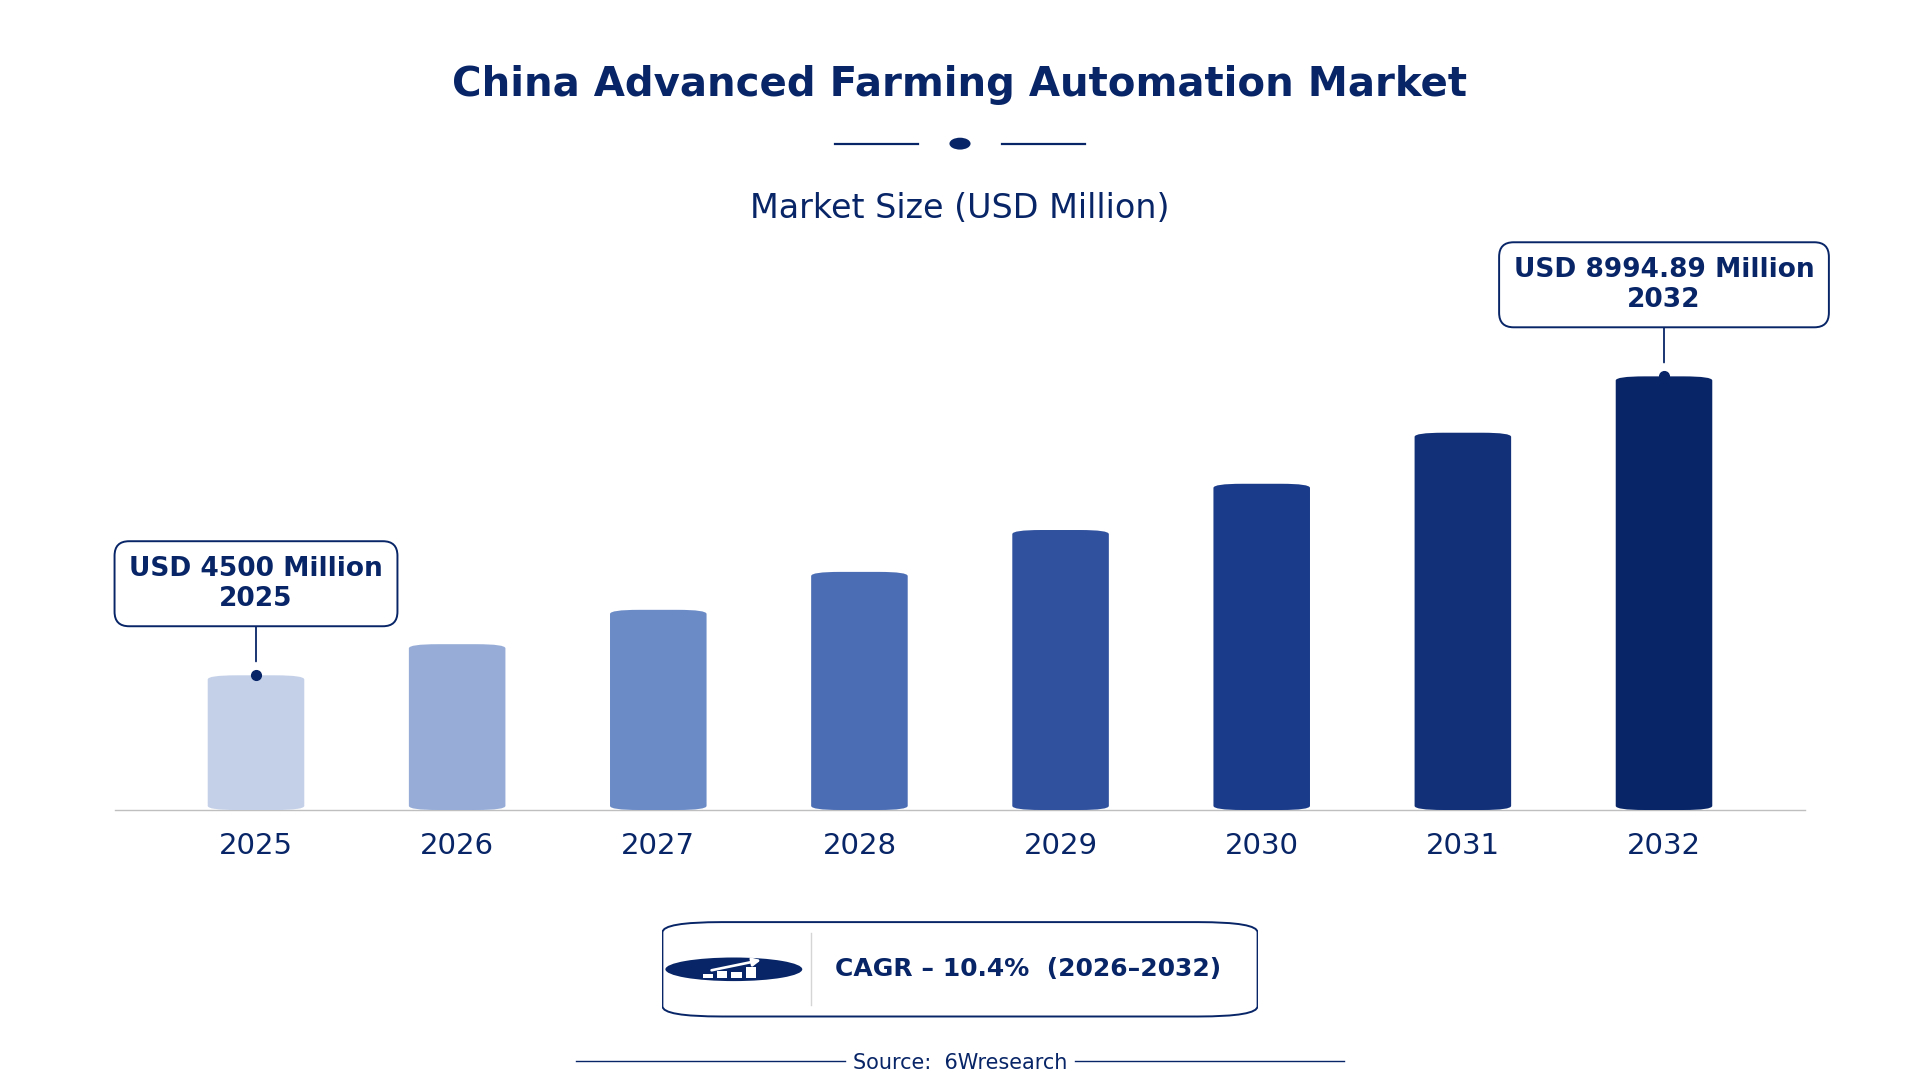
According to 6Wresearch internal database and industry insights, the China Advanced Farming Automation Market was valued at USD 4,500 million in 2025 and is projected to reach USD 8,994.89 million by 2032, growing at a CAGR of approximately 10.4% during 2026–2032.
China Advanced Farming Automation Market Highlights
| Report Metric | Details |
| Report Name | China Advanced Farming Automation Market |
| Market Size 2025 | USD 4,500 million |
| Market Size 2032 | USD 8,994.89 million |
| Absolute Growth 2025–2032 | USD 4,494.89 million |
| CAGR 2026–2032 | 10.4% |
| Peak Annual Growth | 12.6% in 2031 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Advanced Farming Automation Market, 2025 | Precision Planters (40% share) |
| Leading Automation Type, 2025 | Smart Machinery (39% share) |
| Leading Technology Used, 2025 | GPS and IoT (49% share) |
| Leading Distribution Channel, 2025 | Agricultural Suppliers (37% share) |
| Leading End User Sector, 2025 | Large-Scale Farmers (51% share) |
| Fastest-Growing Advanced Farming Automation Market | Drone Sprayers (13.2% CAGR) |
| Fastest-Growing Automation Type | UAV-Based Equipment (12.8% CAGR) |
| Fastest-Growing Technology Used | AI and Machine Vision (11.6% CAGR) |
| Fastest-Growing Distribution Channel | Direct Sales (12.3% CAGR) |
| Fastest-Growing End User Sector | Agri-Tech Companies (11.9% CAGR) |
| Growing Sector | Large-Scale Farmers |
| Key End Users | Large-Scale Farmers, Agri-Tech Companies, Crop Growers |
China Advanced Farming Automation Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
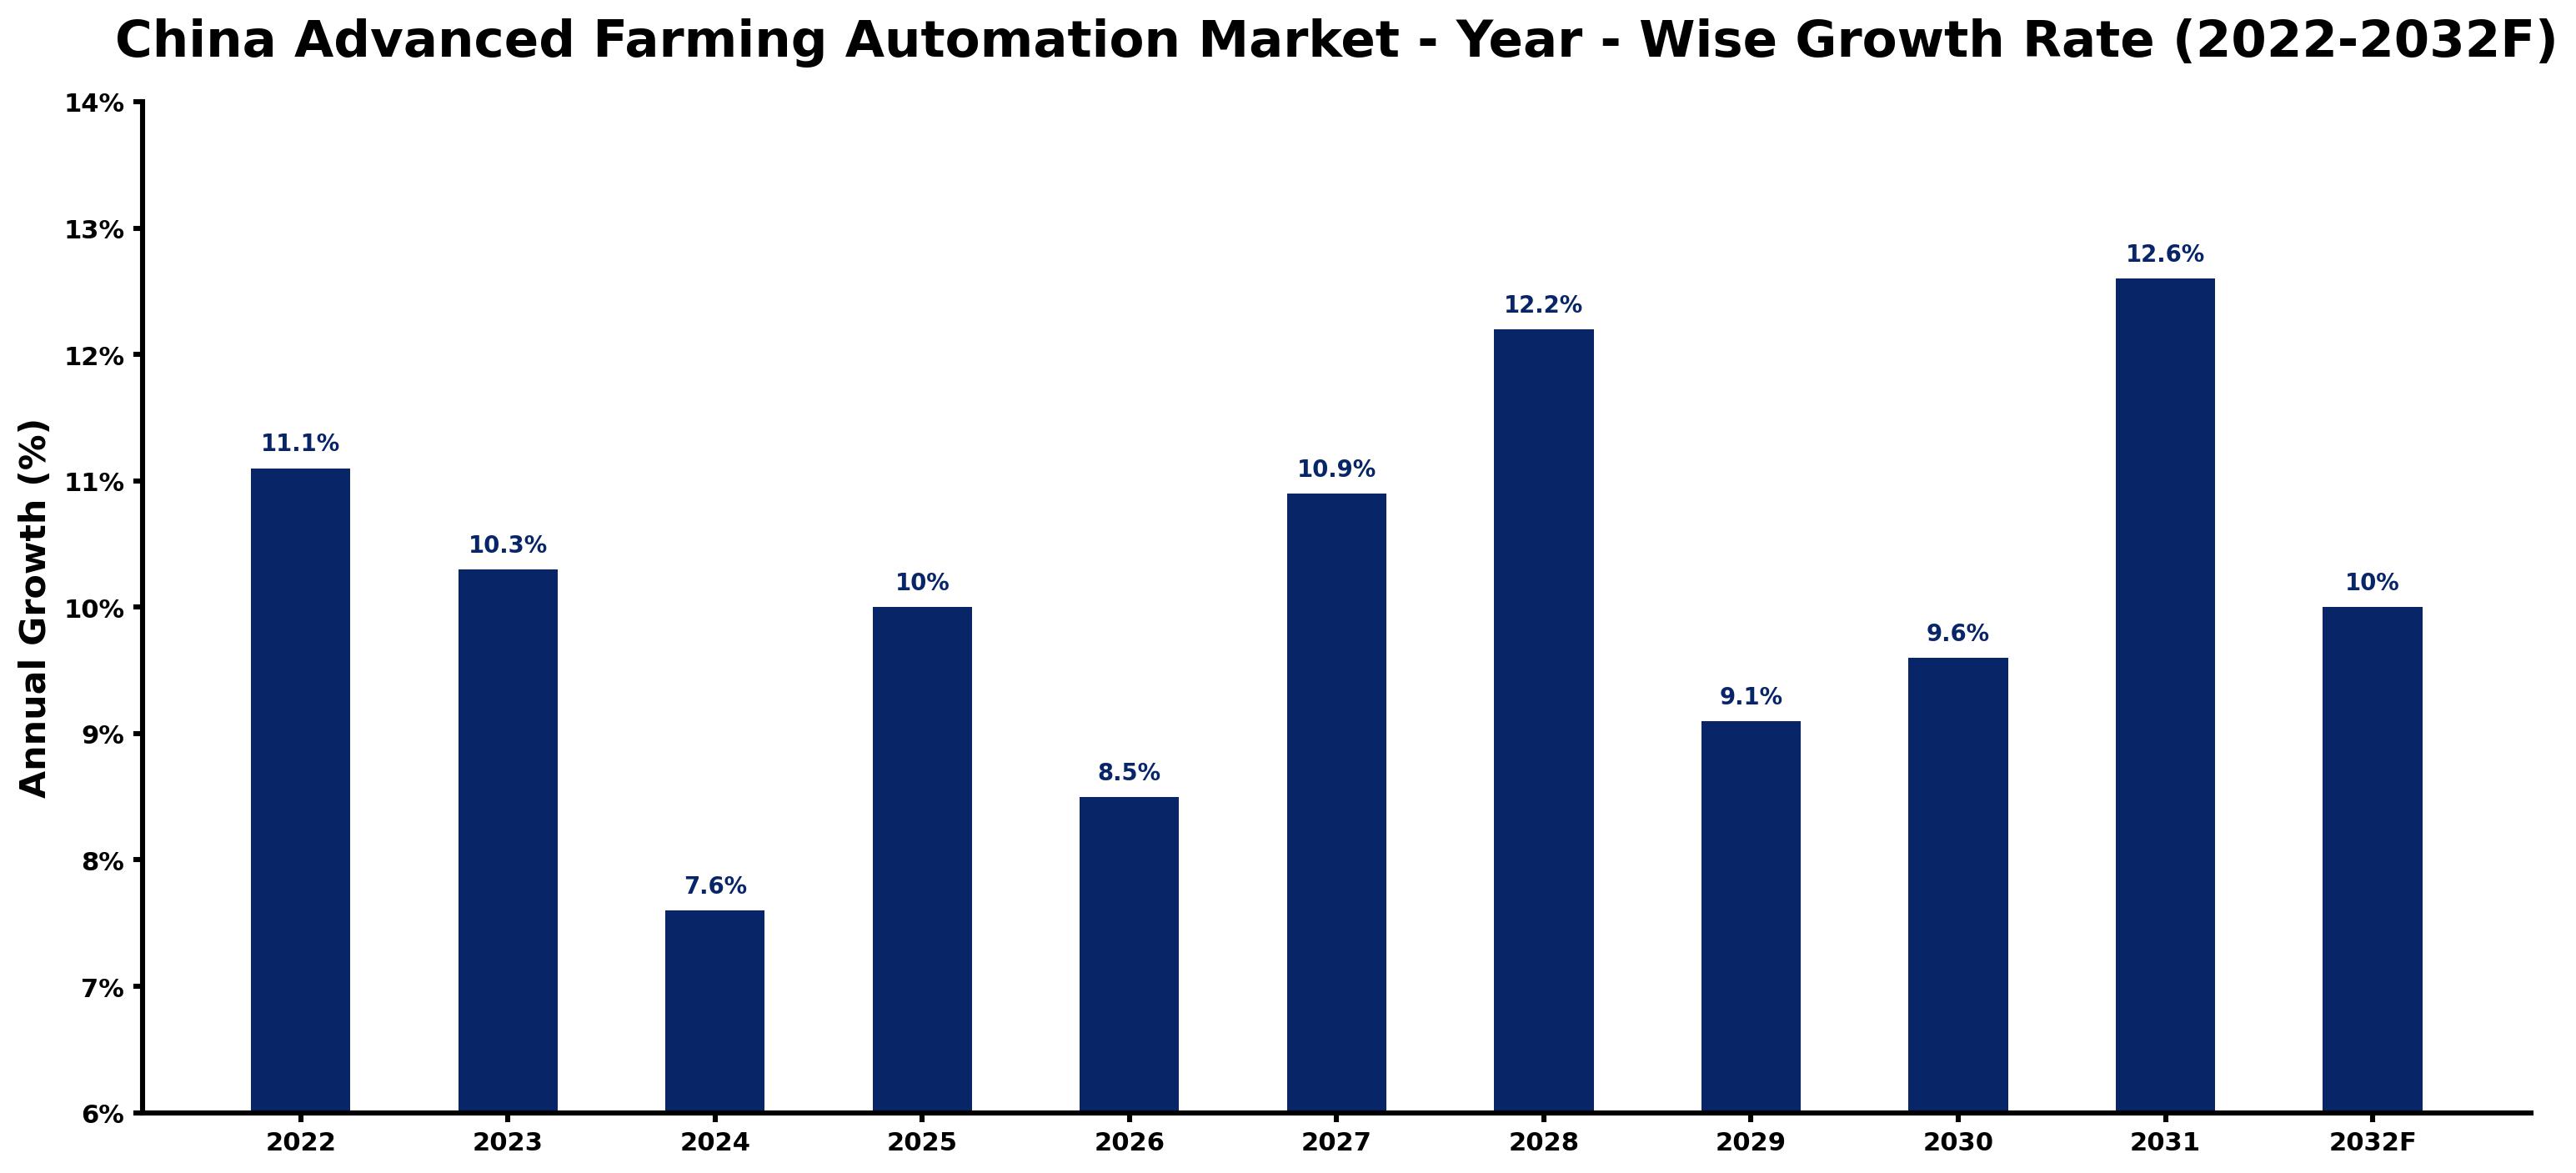
Year by year, the estimates below pair each growth rate with the development that shaped it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 11.1 | The market exhibited strong growth due to rising adoption of automation technologies among large-scale farmers. |
| 2023 | 10.3 | Growth slowed as some farmers faced challenges in integrating advanced systems into existing operations. |
| 2024 | 7.6 | The market continued to grow, albeit at a slower pace, as automation technologies became more mainstream. |
| 2025 | 10.0 | Demand accelerated again as the government promoted the Smart Agriculture Development Plan. |
| 2026 | 8.5 | Growth is expected to slow slightly due to the adjustment to new technology standards and practices. |
| 2027 | 10.9 | The market is projected to rebound with increased investment in agricultural automation technologies. |
| 2028 | 12.2 | Demand is expected to surge as more farmers recognise the benefits of automation for productivity. |
| 2029 | 9.1 | Growth will decelerate as market saturation begins to impact new adoption rates. |
| 2030 | 9.6 | Demand is projected to pick up again as technological advancements improve automation efficiency. |
| 2031 | 12.6 | The market is expected to peak with strong growth driven by innovations in smart machinery and AI integration. |
| 2032 | 10.0 | Growth is projected to moderate as the market stabilises after rapid advancements. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Advanced Farming Automation Market Synopsis
The China Advanced Farming Automation Market includes technologies like precision planting, autonomous vehicles, and drone applications that enhance agricultural efficiency. These systems optimise crop yields, lower labour costs, and improve resource management. The market is expanding due to strong domestic demand from large-scale farmers and agri-tech firms. By 2023, over 30% of large-scale farmers are expected to adopt automation, leading to increased investment in these technologies. Government support through initiatives such as the Smart Agriculture Development Plan further accelerates this growth.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increased investment in agricultural technology innovation | Driver | High | Precision Planters |
| Growing demand for efficient farming solutions due to population growth | Driver | High | Precision Planters |
| Expansion of agri-tech companies focusing on automation | Opportunity | High | Agri-Tech Companies |
| Development of the Yangtze River Delta as a hub for agricultural automation | Opportunity | High | Precision Planters |
| Challenges in integrating automation into traditional farming practices | Restraint | Medium | Precision Planters |
| High initial investment costs for advanced farming technologies | Restraint | Medium | Precision Planters |
| Limited skilled workforce to operate advanced farming systems | Challenge | High | Precision Planters |
| Regulatory compliance with updated agricultural machinery standards | Challenge | Medium | Precision Planters |
Evaluation of Drivers in China Advanced Farming Automation Market (2026–2032)
Below mentioned are some major drivers and their influence on market dynamics.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Investment in agricultural technology innovation | Precision Planters | The government's allocation of 5 billion CNY in 2023 supports innovation, encouraging farmers to adopt advanced systems. |
| Growing demand for efficient farming solutions | Precision Planters | China's population exceeding 1.4 billion drives the need for improved agricultural productivity. |
| Expansion of agri-tech companies | Agri-Tech Companies | With over 1,000 registered agri-tech companies in 2023, competition fuels technological advancements. |
| Government initiatives promoting automation | Precision Planters | The Smart Agriculture Development Plan aims to boost automation adoption by 2025, increasing rates. |
| Technological advancements in precision agriculture | Precision Planters | The integration of AI and IoT technologies improves operational efficiency, attracting more farmers. |
With over 1,000 registered agri-tech companies, competition stimulates technological advancements, leading to increased adoption of automation. The Smart Agriculture Development Plan aims to boost automation by 2025, further encouraging investment. As China's population exceeds 1.4 billion, the need for improved agricultural efficiency becomes critical, prompting large-scale farmers to invest in advanced systems.
Evaluation of Restraints in China Advanced Farming Automation Market
The following restraints limit how fast demand can grow.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Challenges in integrating automation into traditional farming practices | Precision Planters | Many farmers struggle to adapt to new technologies, slowing down adoption rates. |
| High initial investment costs for advanced farming technologies | Precision Planters | The upfront costs deter some farmers from investing in automation. |
| Limited skilled workforce to operate advanced farming systems | Precision Planters | A shortage of trained personnel hinders the effective use of advanced technologies. |
| Regulatory compliance with updated agricultural machinery standards | Precision Planters | New standards require additional investments in training and equipment for compliance. |
| Market saturation impacting new adoption rates | Precision Planters | As more farmers adopt automation, the market faces challenges in attracting new users. |
China Advanced Farming Automation Market Challenges
The China Advanced Farming Automation market encounters several practical problems, starting with supply chain disruptions that hinder producers. Limited access to essential components delays automation projects, which can increase costs for large-scale farmers by up to 15%. Rising expenses for agricultural technology compound the issue, as automation system prices have surged, straining budgets for agri-tech companies. Technological integration issues also arise, with many farmers struggling to adapt to new automation tools, leading to underutilisation of systems and inefficiencies. Skills shortages in the workforce further complicate matters, resulting in reduced productivity for producers reliant on advanced farming technologies.
Trends in the China Advanced Farming Automation Market
Below mentioned are some of the trends shaping the China Advanced Farming Automation Market growth.
- Shift Towards Precision Agriculture: Large-scale farmers are increasingly adopting precision agriculture techniques, utilising AI and IoT for better crop management. In 2022, over 15% of farms in China used drone technology for crop management, showcasing this trend.
- Growing Adoption of Drone Technology: The use of drone sprayers is on the rise, providing precise application of fertilizers and pesticides. The market for drone sprayers is projected to grow by 13.2% annually, indicating strong demand.
- Expansion of Agri-Tech Companies: The Yangtze River Delta region is emerging as a major hub for agricultural automation development. With over 200 million hectares of arable land available, this area is driving innovation and investment.
- Increased Focus on Smart Machinery: Smart machinery is becoming a preferred choice among farmers, improving operational efficiency. By 2025, smart machinery is projected to hold a 39% market share, reflecting its growing importance.
Investment Opportunities in the China Advanced Farming Automation Market
The following opportunities in the China Advanced Farming Automation Market pair current demand with a clear way in.
- Investment in Precision Planters: Large-scale farmers are seeking precision planters to optimise crop yields. The Yangtze River Delta region offers a strong market, with over 200 million hectares of arable land available for cultivation.
- Expansion of Direct Sales Channels: Direct sales are becoming increasingly popular among agricultural suppliers, allowing them to reach large-scale farmers directly. This trend is likely to grow as more suppliers enter the market.
- Collaboration with Agri-Tech Companies: Agri-tech companies are looking for partners to improve their automation offerings. Collaborating with local firms in regions like the Yangtze River Delta can facilitate market entry and innovation.
- Supply of UAV-Based Equipment: There is a growing demand for UAV-based equipment among large-scale farmers for aerial monitoring. Suppliers can tap into this opportunity by providing advanced drone technologies.
Government Initiatives in the China Advanced Farming Automation Market
The 'Smart Agriculture Development Plan' from the Ministry of Agriculture and Rural Affairs aims to advance automation in farming by 2025, with a focus on AI integration. This plan builds on the 'National Standard for Agricultural Machinery' updated in 2021, which established guidelines for incorporating automation technologies, ensuring safety and efficiency in agricultural practices. These measures enhance producers' capabilities and strengthen the market for buyers.
In 2023, the government allocated 5 billion CNY to support agricultural technology innovation through the Agricultural Technology Innovation Program. This initiative, managed by the Ministry of Agriculture and Rural Affairs, funds projects that promote automation and improve farming practices, benefiting farmers nationwide.
Future Insight of the China Advanced Farming Automation Market
The outlook for the China Advanced Farming Automation market through 2032 is bright, driven by key developments. The 'Smart Agriculture Development Plan' will modernise farming practices, while the government's 5 billion CNY investment in agricultural technology will spur innovation. By 2025, the 'National Agricultural Technology Innovation Program' aims to further boost automation adoption across farms. The increasing number of registered agri-tech companies will encourage competition, ultimately providing buyers and suppliers with improved products and services tailored to their needs.
Market Segmentation Analysis
The analysis below covers each segmentation, its leading category in 2025 and its fastest-growing category through 2032.
By Advanced Farming Automation Market – Precision Planters Dominated, Drone Sprayers Expected to Grow Fastest
According to Ravi Bhandari, Research Head at 6Wresearch, Precision Planters held a 40% share of the China Advanced Farming Automation Market by advanced farming automation market in 2025. Precision planters hold the largest market share in China because they are vital for accurate seed placement, which maximises crop yields. With over 30% of large-scale farmers adopting automation by 2023, these tools are essential for modern farming practices. Over 2026–2032, Drone Sprayers are expected to post the fastest growth, at a CAGR of 13.2%. Drone sprayers are experiencing rapid growth due to their ability to provide precise applications of fertilizers and pesticides, addressing the rising demand for efficient farming solutions. The adoption of drone technology for crop management reached over 15% of farms in China by 2022, indicating a strong upward trend. Suppliers should focus on enhancing their offerings in drone technology to capitalise on this growing demand.
By Automation Type – Smart Machinery Dominated, UAV-Based Equipment Expected to Grow Fastest
Smart Machinery accounted for a 39% market share by automation type in 2025. Smart machinery leads the market share as it plays a crucial role in enhancing operational efficiency within farming practices, making it indispensable for large-scale agricultural operations. The government's support of the 'Smart Agriculture Development Plan' further encourages the adoption of smart machinery. UAV-Based Equipment is set to record the highest CAGR in this split, 12.8% over 2026–2032. UAV-based equipment is the fastest-growing segment, driven by its applications in aerial monitoring and crop management, which are increasingly vital for modern agriculture. This growth aligns with the government's emphasis on technological innovation in agriculture. Buyers should consider investing in UAV-based solutions to stay competitive in the evolving agricultural landscape.
By Technology Used – GPS and IoT Dominated, AI and Machine Vision Expected to Grow Fastest
GPS and IoT took a 49% share of technology used in 2025, more than any other category. GPS and IoT technologies dominate the market share as they are essential for precision agriculture and data collection, which optimises farming operations. These technologies equip farmers with the necessary tools to enhance productivity and manage resources effectively. AI and Machine Vision is projected to grow fastest, at a CAGR of 11.6% during 2026–2032. AI and machine vision are rapidly gaining traction as they improve decision-making processes in farming, allowing for smarter operations. The increasing complexity of agricultural challenges necessitates the adoption of advanced technologies for better outcomes. Suppliers should prioritise AI and machine vision technologies to meet the demands of modern farming practices.
By Distribution Channel – Agricultural Suppliers Dominated, Direct Sales Expected to Grow Fastest
The largest distribution channel category in 2025 was Agricultural Suppliers, with a 37% share of total revenue. Agricultural suppliers account for the largest market share, providing essential tools and equipment necessary for farmers to implement advanced farming automation effectively. Their established networks and relationships with farmers make them a crucial link in the supply chain. The quickest growth will come from Direct Sales, forecast to expand at a CAGR of 12.3% between 2026 and 2032. Direct sales are the fastest-growing channel, enabling suppliers to reach large-scale farmers directly, facilitating quicker adoption of advanced technologies. This trend reflects the need for tailored solutions that meet the specific requirements of large agricultural operations. Suppliers should enhance their direct sales strategies to better serve the needs of large-scale farmers.
By End User Sector – Large-Scale Farmers Dominated, Agri-Tech Companies Expected to Grow Fastest
With a 51% revenue share in 2025, Large-Scale Farmers was the largest end user sector category. Large-scale farmers represent the largest user group of advanced farming automation, significantly benefiting from improved efficiency and productivity. Their substantial investment in automation technologies highlights the importance of this sector in driving market growth. Over 2026–2032, Agri-Tech Companies are expected to post the fastest growth, at a CAGR of 11.9%. Agri-tech companies are the fastest-growing sector, leading innovation and the adoption of new technologies in agriculture. Their focus on developing cutting-edge solutions positions them at the forefront of the advanced farming automation market. Suppliers must engage with agri-tech companies to leverage their innovative approaches and expand their market reach.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Advanced Farming Automation Market Outlook
- Market Size of China Advanced Farming Automation Market, 2025
- Forecast of China Advanced Farming Automation Market, 2032
- Historical Data and Forecast of China Advanced Farming Automation Revenues & Volume for the Period 2022 - 2032F
- China Advanced Farming Automation Market Trend Evolution
- China Advanced Farming Automation Market Drivers and Challenges
- China Advanced Farming Automation Price Trends
- China Advanced Farming Automation Porter's Five Forces
- China Advanced Farming Automation Industry Life Cycle
- Historical Data and Forecast of China Advanced Farming Automation Market Revenues & Volume By Advanced Farming Automation Market for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Farming Automation Market Revenues & Volume By Precision Planters for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Farming Automation Market Revenues & Volume By Autonomous Tractors for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Farming Automation Market Revenues & Volume By Drone Sprayers for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Farming Automation Market Revenues & Volume By Robotic Harvesters for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Farming Automation Market Revenues & Volume By Automation Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Farming Automation Market Revenues & Volume By Smart Machinery for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Farming Automation Market Revenues & Volume By Driverless Systems for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Farming Automation Market Revenues & Volume By UAV-Based Equipment for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Farming Automation Market Revenues & Volume By Automated Arms for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Farming Automation Market Revenues & Volume By Technology Used for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Farming Automation Market Revenues & Volume By GPS and IoT for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Farming Automation Market Revenues & Volume By AI and Machine Vision for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Farming Automation Market Revenues & Volume By Aerial Imaging for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Farming Automation Market Revenues & Volume By AI-Based Harvest Logic for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Farming Automation Market Revenues & Volume By Distribution Channel for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Farming Automation Market Revenues & Volume By Agricultural Suppliers for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Farming Automation Market Revenues & Volume By Direct Sales for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Farming Automation Market Revenues & Volume By Online Platforms for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Farming Automation Market Revenues & Volume By Equipment Dealers for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Farming Automation Market Revenues & Volume By End User Sector for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Farming Automation Market Revenues & Volume By Large-Scale Farmers for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Farming Automation Market Revenues & Volume By Agri-Tech Companies for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Farming Automation Market Revenues & Volume By Crop Growers for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Farming Automation Market Revenues & Volume By Organic & Vertical Farms for the Period 2022 - 2032F
- China Advanced Farming Automation Import Export Trade Statistics
- Market Opportunity Assessment By Advanced Farming Automation Market
- Market Opportunity Assessment By Automation Type
- Market Opportunity Assessment By Technology Used
- Market Opportunity Assessment By Distribution Channel
- Market Opportunity Assessment By End User Sector
- China Advanced Farming Automation Top Companies Market Share
- China Advanced Farming Automation Competitive Benchmarking By Technical and Operational Parameters
- China Advanced Farming Automation Company Profiles
- China Advanced Farming Automation Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By Advanced Farming Automation Market
- Precision Planters
- Autonomous Tractors
- Drone Sprayers
- Robotic Harvesters
By Automation Type
- Smart Machinery
- Driverless Systems
- UAV-Based Equipment
- Automated Arms
By Technology Used
- GPS and IoT
- AI and Machine Vision
- Aerial Imaging
- AI-Based Harvest Logic
By Distribution Channel
- Agricultural Suppliers
- Direct Sales
- Online Platforms
- Equipment Dealers
By End User Sector
- Large-Scale Farmers
- Agri-Tech Companies
- Crop Growers
- Organic & Vertical Farms






































