China Advanced IC Packaging Market Size & Growth Rate
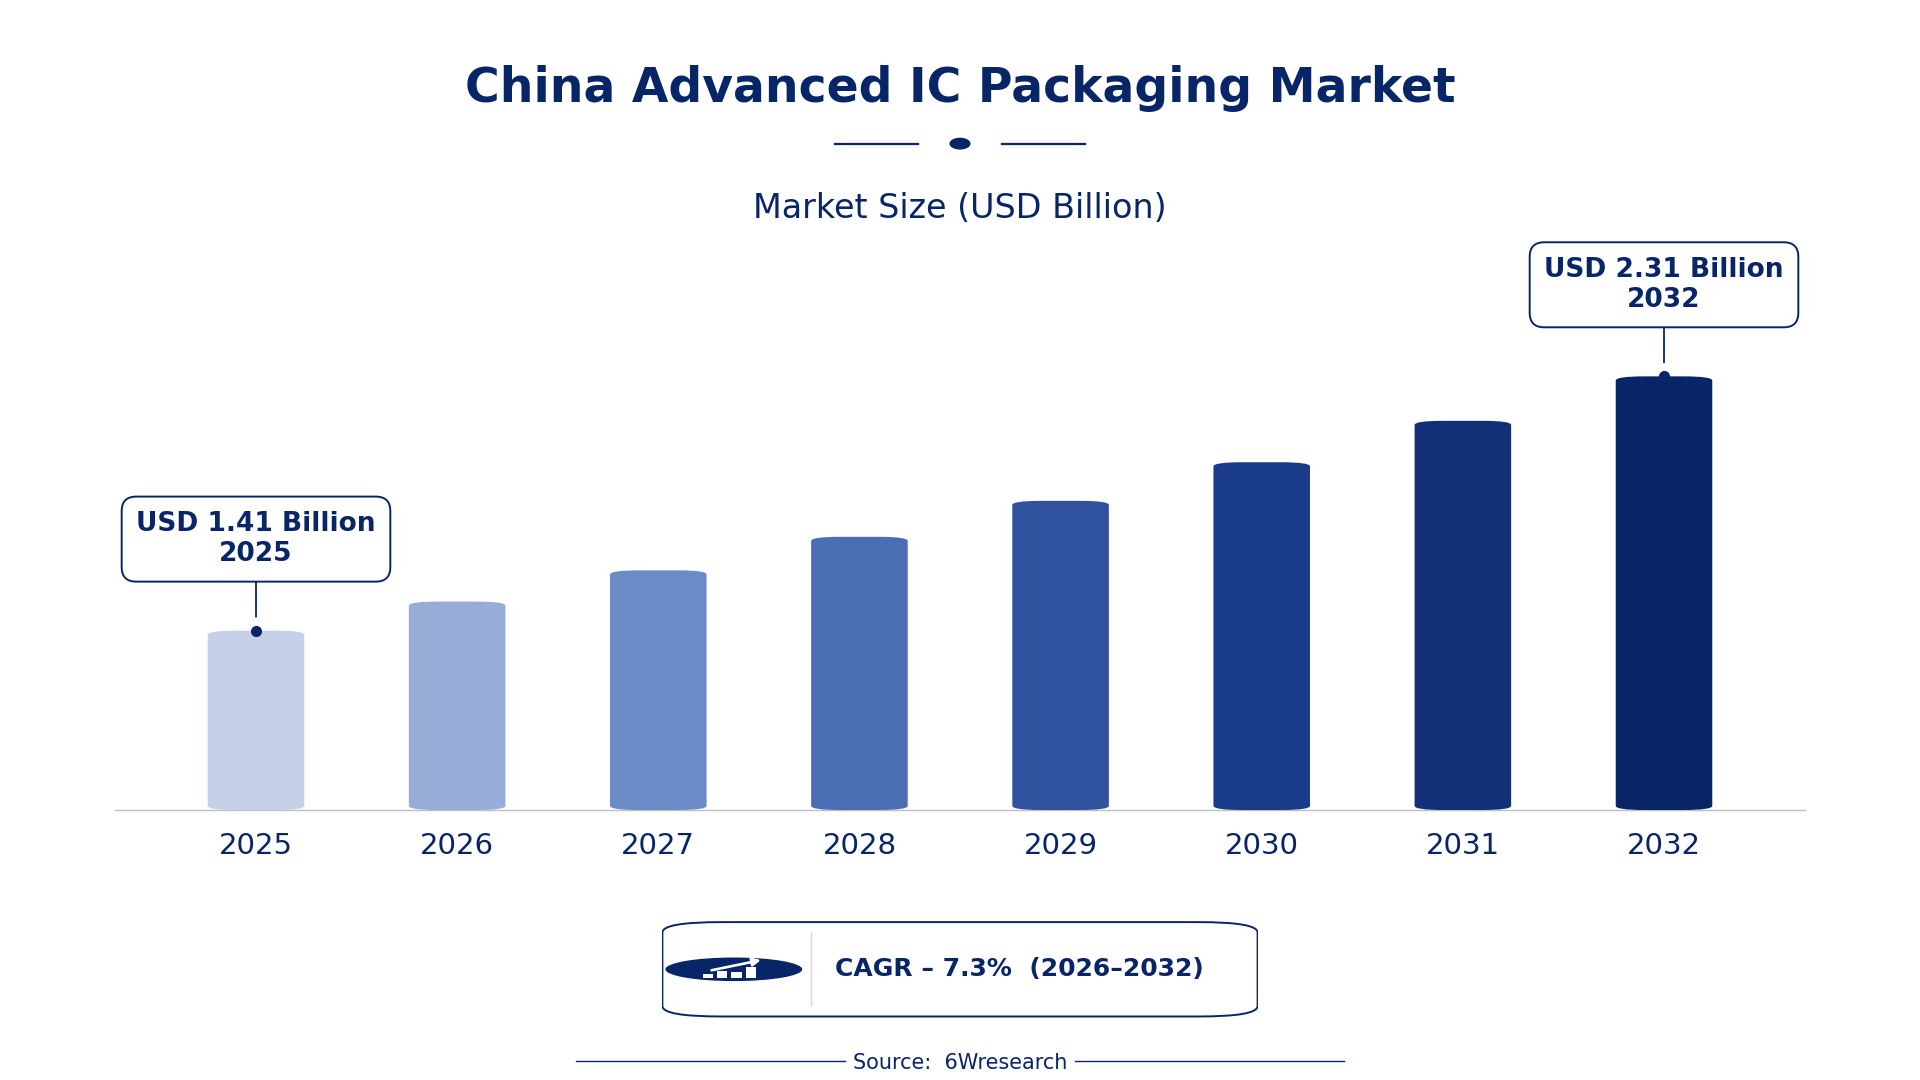
According to 6Wresearch internal database and industry insights, the China Advanced IC Packaging Market was valued at USD 1.41 billion in 2025 and is projected to reach USD 2.31 billion by 2032, growing at a CAGR of approximately 7.3% during 2026–2032.
China Advanced IC Packaging Market Highlights
| Report Metric | Details |
| Report Name | China Advanced IC Packaging Market |
| Market Size 2025 | USD 1.41 billion |
| Market Size 2032 | USD 2.31 billion |
| Absolute Growth 2025–2032 | USD 0.90 billion |
| CAGR 2026–2032 | 7.3% |
| Peak Annual Growth | 9.7% in 2029 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Advanced IC Packaging Market, 2025 | Fan-Out Wafer Level Package (45% share) |
| Leading Packaging Type, 2025 | 2.5D/3D Packaging (36% share) |
| Leading Interconnect Technology, 2025 | Through Silicon Via (TSV) (50% share) |
| Leading Material Used, 2025 | Silicon Substrates (40% share) |
| Leading End User Sector, 2025 | Chip Manufacturers (44% share) |
| Fastest-Growing Advanced IC Packaging Market | System in Package (SiP) (9.9% CAGR) |
| Fastest-Growing Interconnect Technology | Bump Interconnect (9.3% CAGR) |
| Fastest-Growing Material Used | Glass Interposer (8.3% CAGR) |
| Fastest-Growing End User Sector | IoT Devices (8.6% CAGR) |
| Growing Sector | IoT Devices |
| Key End Users | Chip Manufacturers, Consumer Electronics, IoT Devices, Wearable Devices |
China Advanced IC Packaging Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
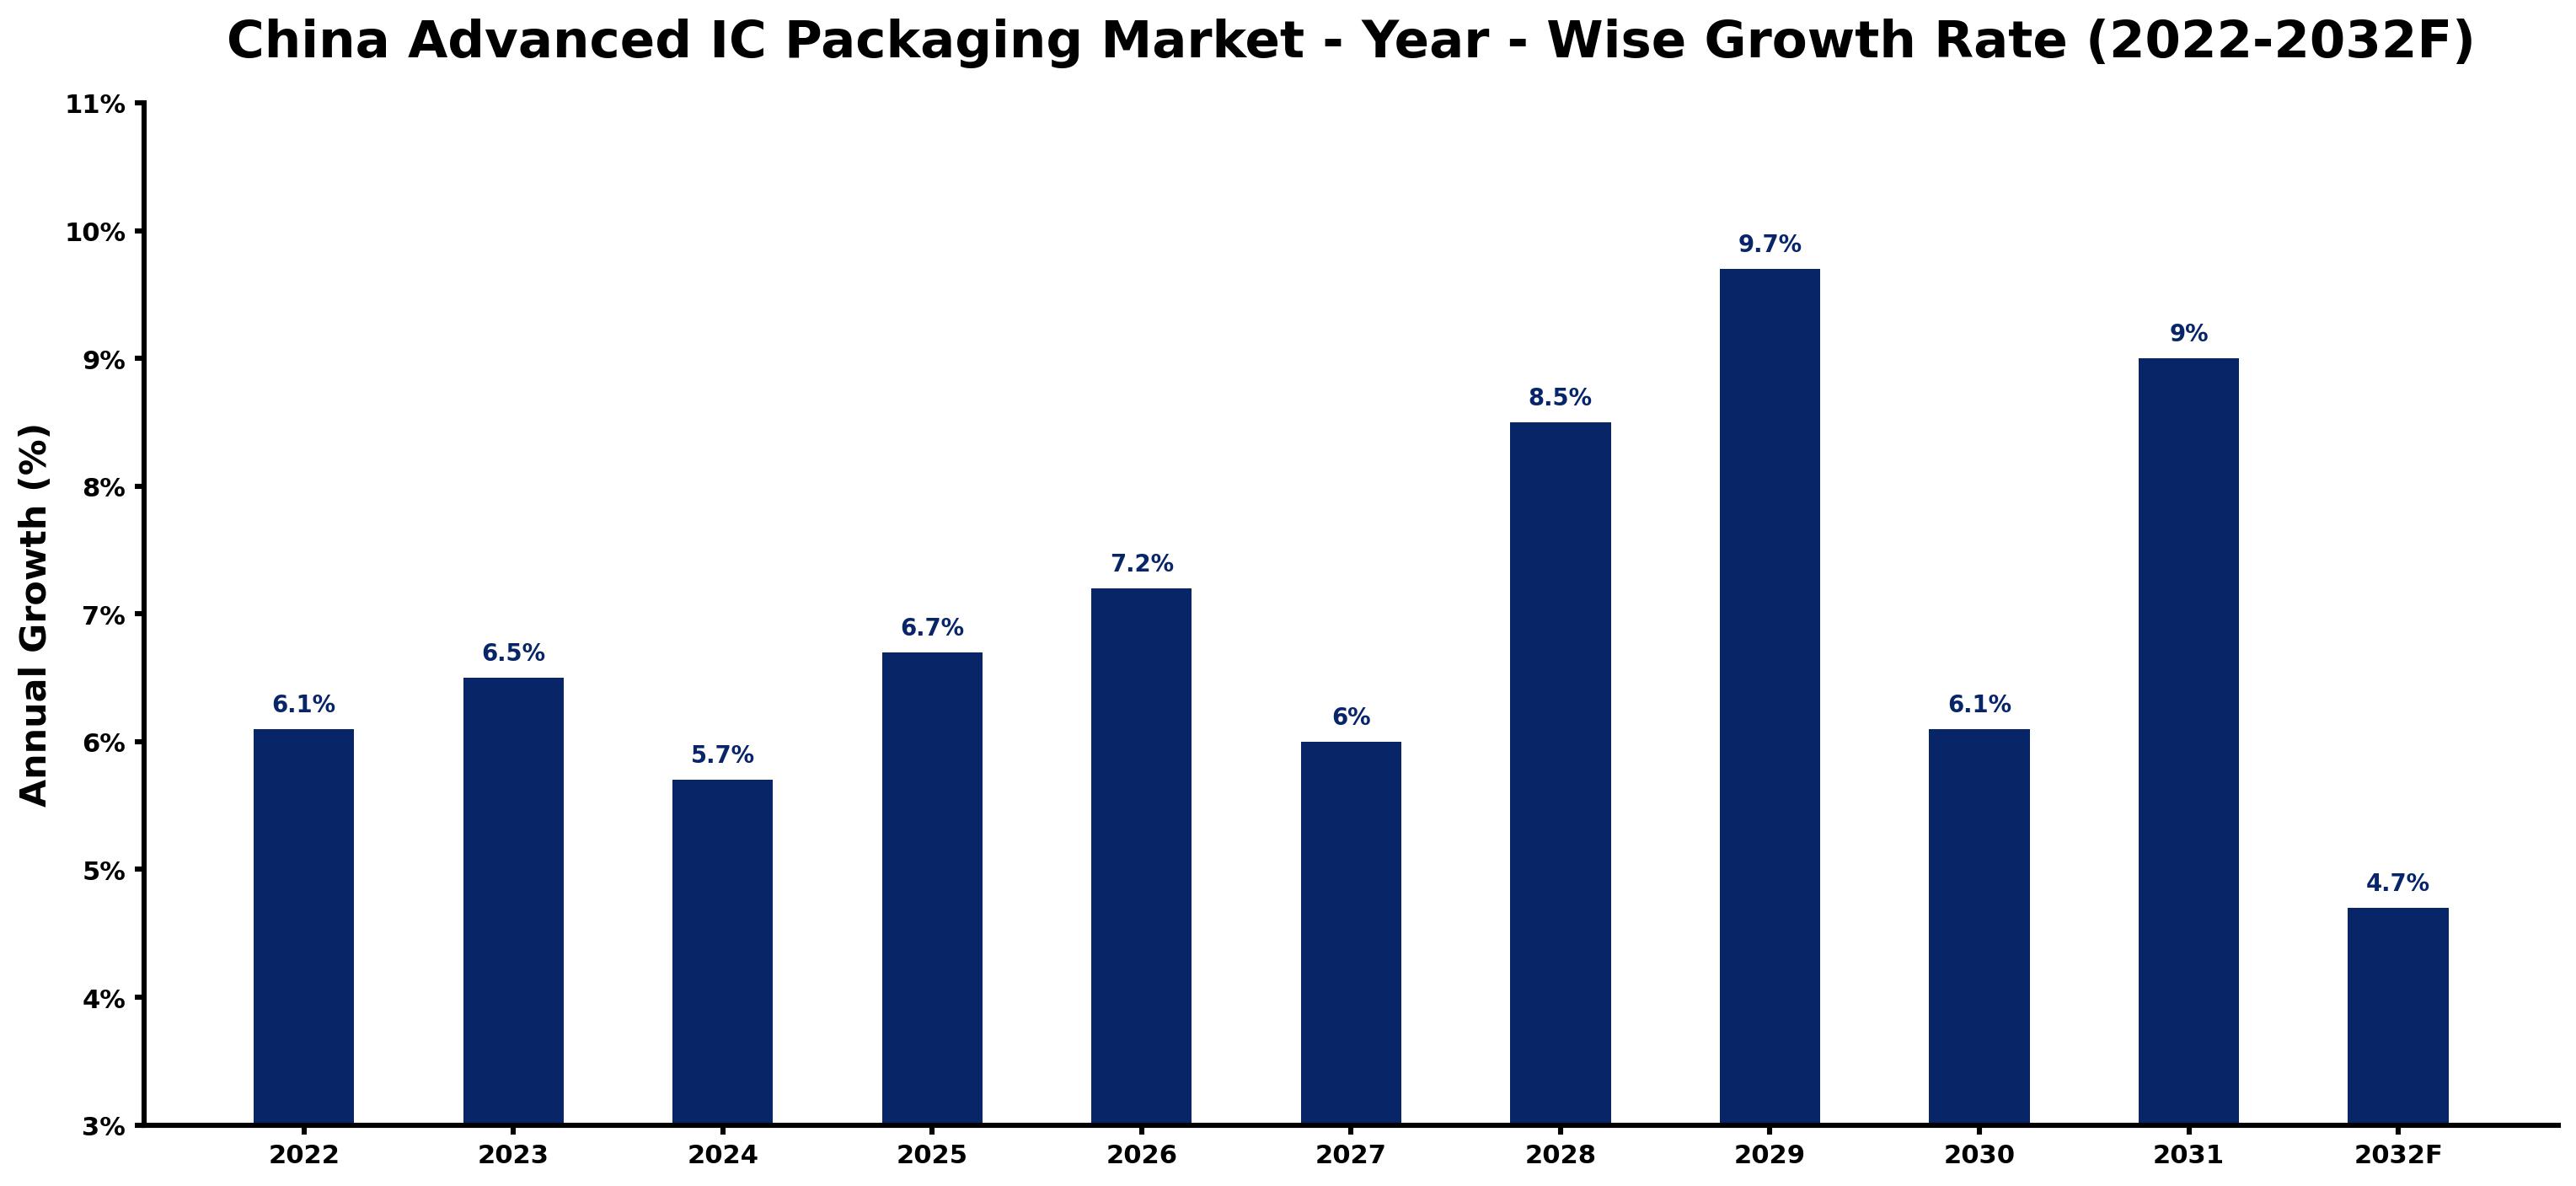
Below, each year's estimated growth is shown next to the factor that most influenced it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 6.1 | The market experienced steady growth due to strong domestic demand for advanced packaging technologies. |
| 2023 | 6.5 | Investment in semiconductor R&D increased significantly, boosting market performance. |
| 2024 | 5.7 | Growth slowed slightly as manufacturers adjusted to evolving technology standards. |
| 2025 | 6.7 | The market rebounded with increased production capacity and consumer electronics demand. |
| 2026 | 7.2 | Investment in advanced packaging technologies continued to rise, supporting market expansion. |
| 2027 | 6.0 | A slight slowdown occurred as manufacturers faced supply chain challenges. |
| 2028 | 8.5 | Demand surged as the installed base of consumer electronics expanded significantly. |
| 2029 | 9.7 | The market peaked due to heightened investment in advanced computing applications. |
| 2030 | 6.1 | Growth slowed as the market adjusted to new technological advancements. |
| 2031 | 9.0 | Increased demand from IoT devices drove market growth higher again. |
| 2032 | 4.7 | The market is expected to grow at a slower rate as it stabilises post-peak. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Advanced IC Packaging Market Synopsis
Advanced IC Packaging in China encompasses the technology used to encase integrated circuits, improving performance while minimising size. This sector includes processes such as wafer-level packaging and chip stacking, with applications spanning consumer electronics and IoT devices. The China Advanced IC Packaging Market is expanding due to robust domestic demand and considerable investments in semiconductor R&D. In 2023, the installed base of consumer electronics reached 1.5 billion units, further propelling the need for advanced packaging solutions. Government support through initiatives like the 'National Integrated Circuit Industry Investment Fund' plays a crucial role in this growth.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Strong domestic demand for advanced packaging technologies is driving growth. | Driver | High | Fan-Out Wafer Level Package |
| Investment in semiconductor R&D is enhancing production capabilities. | Driver | High | System in Package (SiP) |
| The growing consumer electronics sector presents significant opportunities for suppliers. | Opportunity | High | Consumer Electronics |
| The increasing number of patents in advanced packaging technologies indicates innovation potential. | Opportunity | Medium | Flip-Chip Packaging |
| High production costs can limit profit margins for manufacturers. | Restraint | High | Wafer-Level CSP |
| Supply chain disruptions have impacted the availability of materials. | Restraint | Medium | 2.5D/3D Packaging |
| The need for compliance with evolving standards can delay product launches. | Challenge | High | Chip Scale Packaging |
| Technological advancements require continuous investment, straining budgets. | Challenge | Medium | Through Silicon Via (TSV) |
Evaluation of Drivers in China Advanced IC Packaging Market (2026–2032)
The table below links each growth driver to the segment it affects and the evidence for it.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased investment in semiconductor R&D drives demand for advanced packaging. | System in Package (SiP) | The Ministry of Industry and Information Technology reported a 20% increase in investment in semiconductor R&D in 2022, leading to higher demand for advanced packaging solutions. |
| Growing consumer electronics production enhances the need for advanced IC packaging. | Fan-Out Wafer Level Package | The installed base of consumer electronics reached 1.5 billion units in 2023, driving demand for efficient packaging technologies. |
| Expansion of IoT devices creates new opportunities for advanced packaging. | Chip Scale Packaging | The rising adoption of IoT devices is increasing the demand for compact and efficient packaging solutions, with projections indicating an 8.6% CAGR for IoT devices over the next several years. |
| The push for miniaturisation in electronics is driving innovation in packaging. | 2.5D/3D Packaging | The 'Made in China 2025' initiative emphasises advancements in semiconductor technologies, enhancing the demand for innovative packaging. |
| The need for efficient thermal management in high-performance computing drives packaging solutions. | Flip-Chip Packaging | With the semiconductor industry employing over 1 million people, demand for high-performance chips necessitates advanced packaging technologies. |
Growth in the Advanced IC Packaging market in China comes from increased investment in semiconductor R&D, expanding consumer electronics production, and the rise of IoT devices. The installed base of consumer electronics reached 1.5 billion units in 2023, driving the need for efficient packaging technologies. The growing demand for high-performance computing is creating opportunities for advanced packaging solutions like System in Package (SiP). These factors are expected to create a dynamic environment for growth in the sector, with significant investments anticipated in the coming years.
Evaluation of Restraints in China Advanced IC Packaging Market
The main factors holding the market back are set out below.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| High production costs limit profit margins for manufacturers. | Wafer-Level CSP | The average annual salary for semiconductor engineers in China is around $25,000, contributing to higher production costs. |
| Supply chain disruptions impact material availability. | 2.5D/3D Packaging | Ongoing global supply chain issues have affected the procurement of essential materials for advanced packaging, delaying production timelines. |
| Compliance with evolving standards can delay product launches. | Chip Scale Packaging | The China Electronics Standardization Association has set stringent standards for advanced packaging technologies, which can slow down development and approvals. |
| Limited access to skilled labour affects production capabilities. | Fan-Out Wafer Level Package | The 'Integrated Circuit Talent Development Program' aims to cultivate skilled professionals, but the demand still outstrips supply, impacting production efficiency. |
| Technological advancements require continuous investment, straining budgets. | Through Silicon Via (TSV) | The need for ongoing investment in technology can limit the financial resources available for other operational needs, affecting overall growth. |
China Advanced IC Packaging Market Challenges
Advanced IC Packaging in China faces technological challenges stemming from rapid advancements in semiconductor requirements. This technology gap can delay product development timelines for manufacturers, potentially leading to revenue losses estimated at 15% annually. Suppliers experience intense competition, which drives prices down and compresses profit margins, making it challenging for them to invest in necessary innovations. Regulatory hurdles, particularly compliance with standards set by the China Electronics Standardization Association, can extend approval timelines, costing suppliers valuable time and resources. Supply chain disruptions in the Guangdong province can lead to material shortages, causing delays that impact production schedules for manufacturers.
Trends in the China Advanced IC Packaging Market
The trends below show where the China Advanced IC Packaging Market is heading.
- Growth of Semiconductor Manufacturing Hubs: Guangdong province is rapidly expanding its semiconductor manufacturing capabilities, reflecting a strong trend in the industry. In 2023, the installed base of consumer electronics reached 1.5 billion units, driving the demand for advanced IC packaging solutions.
- Surge in Demand for IoT Devices: The demand for IoT devices surged in 2023, leading to an increase in the need for compact packaging solutions. This trend is projected to continue, with an 8.6% CAGR for IoT devices over the next several years.
- Shift in Manufacturing Practices: In 2023, over 10,000 patents related to advanced packaging technologies were filed in China, indicating a shift towards innovation in manufacturing practices. This trend supports the growing need for advanced IC packaging solutions.
- Focus on Sustainable Packaging Materials: With increasing environmental standards, there is a growing demand for sustainable packaging materials. This shift, initiated in 2023, is prompting manufacturers to invest in eco-friendly solutions to meet regulatory requirements.
Investment Opportunities in the China Advanced IC Packaging Market
Below are the investment opportunities with the strongest case in the China Advanced IC Packaging Market.
- Investment in Advanced Packaging Facilities: Guangdong province is currently expanding its semiconductor manufacturing capabilities, creating opportunities for investment in advanced packaging facilities. The market is projected to reach USD 1.41 billion by 2025, making local partnerships essential for entry into this growing sector.
- Supply of Efficient Packaging Solutions: The demand for advanced IC packaging is rising, particularly in high-performance computing applications. Suppliers can focus on providing efficient solutions to chip manufacturers, capitalising on the projected growth in this segment.
- Collaboration with Local Manufacturers: There is an opportunity for joint ventures with local manufacturers in the semiconductor sector, especially in Guangdong province. This collaboration can help navigate regulatory requirements and enhance market presence in the region.
- Focus on Sustainable Packaging Materials: With increasing environmental standards, there is a growing demand for sustainable packaging materials. Suppliers can invest in eco-friendly solutions to meet the needs of manufacturers looking to comply with new regulations.
Government Initiatives in the China Advanced IC Packaging Market
In 2023, the Ministry of Science and Technology initiated the 'Semiconductor Innovation and Development Program' with a budget of $5 billion to support R&D in the semiconductor sector. This program builds on previous initiatives like the '14th Five-Year Plan for the Development of the Semiconductor Industry' launched in 2022, which aimed to improve local production capabilities and self-sufficiency in semiconductor manufacturing. These measures directly impact advanced IC packaging by fostering innovation and enhancing production standards.
The National Development and Reform Commission (NDRC) oversees the 'Subsidy Program for Semiconductor Equipment', which provides financial incentives for local manufacturers. This program, introduced in 2021, aims to stimulate growth in the semiconductor sector by funding equipment purchases and technological upgrades. As a result, producers can enhance their production capabilities and improve product quality, benefiting the overall advanced IC packaging market.
Future Insight of the China Advanced IC Packaging Market
Several forward-looking factors should support the Advanced IC Packaging market in China over the coming years. The 'National Integrated Circuit Industry Investment Fund' is set to inject $10 billion into local manufacturers, significantly enhancing their production capabilities. A 20% increase in semiconductor R&D investment will likely spur innovation in packaging techniques. The 'Made in China 2025' initiative will drive advancements in semiconductor technologies, benefiting both buyers and suppliers by improving product quality. With over 10,000 patents related to advanced packaging technologies, the market is poised for notable growth.
Market Segmentation Analysis
The report offers a comprehensive study of the following market segments and their leading categories in the market.
By Advanced IC Packaging Market – Fan-Out Wafer Level Package Dominated, System in Package (SiP) Expected to Grow Fastest
According to Ravi Bhandari, Research Head at 6Wresearch, in 2025, Fan-Out Wafer Level Package led the advanced ic packaging market split with a 45% share. The Fan-Out Wafer Level Package leads the market share due to its extensive use in high-density applications, particularly in consumer electronics. This technology is essential for meeting the performance requirements of the 1.5 billion units of installed consumer electronics in China. The quickest growth will come from System in Package (SiP), forecast to expand at a CAGR of 9.9% between 2026 and 2032. The System in Package segment is rapidly growing, driven by the rising demand for compact designs that integrate multiple functions, particularly for IoT devices. The surge in related patents, exceeding 10,000 in 2023, indicates a strong push towards this technology. Suppliers should prioritise advancements in Fan-Out Wafer Level Packages to effectively meet the increasing demand in the Chinese market.
By Packaging Type – 2.5D/3D Packaging Dominated and Is Expected to Record the Fastest Growth
2.5D/3D Packaging accounted for a 36% market share by packaging type in 2025. 2.5D/3D Packaging holds the largest market share due to its essential role in advanced computing applications, which are increasingly prevalent in China. This technology is pivotal for meeting the demands of high-performance computing, aligning with national strategies like 'Made in China 2025'. 2.5D/3D Packaging is also forecast to expand faster than any other category, at a CAGR of 10.0% over 2026–2032. 2.5D/3D Packaging is also the fastest-growing segment, driven by the rising need for enhanced performance and efficiency in semiconductor applications. The ongoing investments in advanced computing technologies will further propel this segment's growth trajectory. Suppliers should focus on 2.5D/3D Packaging solutions to remain competitive in the rapidly evolving semiconductor landscape.
By Interconnect Technology – Through Silicon Via (TSV) Dominated, Bump Interconnect Expected to Grow Fastest
The largest interconnect technology category in 2025 was Through Silicon Via (TSV), with a 50% share of total revenue. Through Silicon Via (TSV) commands the largest market share as it is crucial for establishing vertical interconnects in 3D integrated circuits, which are vital for advanced applications. The substantial semiconductor production in China, valued at approximately $143 billion in 2022, highlights the importance of this interconnect technology. Bump Interconnect is set to record the highest CAGR in this split, 9.3% over 2026–2032. Bump Interconnect is experiencing rapid growth due to its essential function in facilitating connections within advanced packaging solutions for high-performance devices. The increasing complexity of modern semiconductor designs drives the demand for effective interconnect technologies. Suppliers need to enhance their Bump Interconnect offerings to capitalise on the growing demand for advanced packaging solutions.
By Material Used – Silicon Substrates Dominated, Glass Interposer Expected to Grow Fastest
With a 40% revenue share in 2025, Silicon Substrates was the largest material used category. Silicon Substrates dominate the market share as they are the fundamental material for integrated circuits, critical to the semiconductor industry in China. Their widespread application across various sectors ensures their sustained prominence in the market. Glass Interposer is projected to grow fastest, at a CAGR of 8.3% during 2026–2032. The Glass Interposer segment is rapidly expanding, significantly improving performance in high-speed applications essential for modern electronics. As the demand for high-speed solutions continues to rise, this segment is well-positioned for further growth. Buyers should explore innovative materials like Glass Interposers to improve performance in their semiconductor applications.
By End User Sector – Chip Manufacturers Dominated, IoT Devices Expected to Grow Fastest
Chip Manufacturers took a 44% share of end user sector in 2025, more than any other category. Chip Manufacturers hold the largest market share as they are the primary users of advanced packaging technologies necessary for producing high-quality semiconductors. The employment of over 1 million people in the semiconductor sector underscores their critical role in this ecosystem. The quickest growth will come from IoT Devices, forecast to expand at a CAGR of 8.6% between 2026 and 2032. IoT Devices represent the fastest-growing sector, driven by the increasing demand for integrated solutions that enhance connectivity and functionality in everyday applications. The expanding IoT market will continue to elevate the need for advanced packaging technologies. Suppliers should tailor their offerings to meet the specific needs of the IoT Devices sector to leverage this growth opportunity.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Advanced IC Packaging Market Outlook
- Market Size of China Advanced IC Packaging Market, 2025
- Forecast of China Advanced IC Packaging Market, 2032
- Historical Data and Forecast of China Advanced IC Packaging Revenues & Volume for the Period 2022 - 2032F
- China Advanced IC Packaging Market Trend Evolution
- China Advanced IC Packaging Market Drivers and Challenges
- China Advanced IC Packaging Price Trends
- China Advanced IC Packaging Porter's Five Forces
- China Advanced IC Packaging Industry Life Cycle
- Historical Data and Forecast of China Advanced IC Packaging Market Revenues & Volume By Advanced IC Packaging Market for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced IC Packaging Market Revenues & Volume By Fan-Out Wafer Level Package for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced IC Packaging Market Revenues & Volume By Flip-Chip Packaging for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced IC Packaging Market Revenues & Volume By System in Package (SiP) for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced IC Packaging Market Revenues & Volume By Wafer-Level CSP for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced IC Packaging Market Revenues & Volume By Packaging Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced IC Packaging Market Revenues & Volume By 2.5D/3D Packaging for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced IC Packaging Market Revenues & Volume By Die-to-Substrate for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced IC Packaging Market Revenues & Volume By Multi-Chip Module for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced IC Packaging Market Revenues & Volume By Chip Scale Packaging for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced IC Packaging Market Revenues & Volume By Interconnect Technology for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced IC Packaging Market Revenues & Volume By Through Silicon Via (TSV) for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced IC Packaging Market Revenues & Volume By Bump Interconnect for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced IC Packaging Market Revenues & Volume By Wire Bonding for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced IC Packaging Market Revenues & Volume By Redistribution Layer for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced IC Packaging Market Revenues & Volume By Material Used for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced IC Packaging Market Revenues & Volume By Silicon Substrates for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced IC Packaging Market Revenues & Volume By Gold Bumps for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced IC Packaging Market Revenues & Volume By Epoxy Molding for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced IC Packaging Market Revenues & Volume By Glass Interposer for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced IC Packaging Market Revenues & Volume By End User Sector for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced IC Packaging Market Revenues & Volume By Chip Manufacturers for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced IC Packaging Market Revenues & Volume By Consumer Electronics for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced IC Packaging Market Revenues & Volume By IoT Devices for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced IC Packaging Market Revenues & Volume By Wearable Devices for the Period 2022 - 2032F
- China Advanced IC Packaging Import Export Trade Statistics
- Market Opportunity Assessment By Advanced IC Packaging Market
- Market Opportunity Assessment By Packaging Type
- Market Opportunity Assessment By Interconnect Technology
- Market Opportunity Assessment By Material Used
- Market Opportunity Assessment By End User Sector
- China Advanced IC Packaging Top Companies Market Share
- China Advanced IC Packaging Competitive Benchmarking By Technical and Operational Parameters
- China Advanced IC Packaging Company Profiles
- China Advanced IC Packaging Key Strategic Recommendations
Market Covered
Segments analysed in this report are listed below.
By Advanced IC Packaging Market
- Fan-Out Wafer Level Package
- Flip-Chip Packaging
- System in Package (SiP)
- Wafer-Level CSP
By Packaging Type
- 2.5D/3D Packaging
- Die-to-Substrate
- Multi-Chip Module
- Chip Scale Packaging
By Interconnect Technology
- Through Silicon Via (TSV)
- Bump Interconnect
- Wire Bonding
- Redistribution Layer
By Material Used
- Silicon Substrates
- Gold Bumps
- Epoxy Molding
- Glass Interposer
By End User Sector
- Chip Manufacturers
- Consumer Electronics
- IoT Devices
- Wearable Devices






































