China Advanced Lightweight Material Market Size & Growth Rate
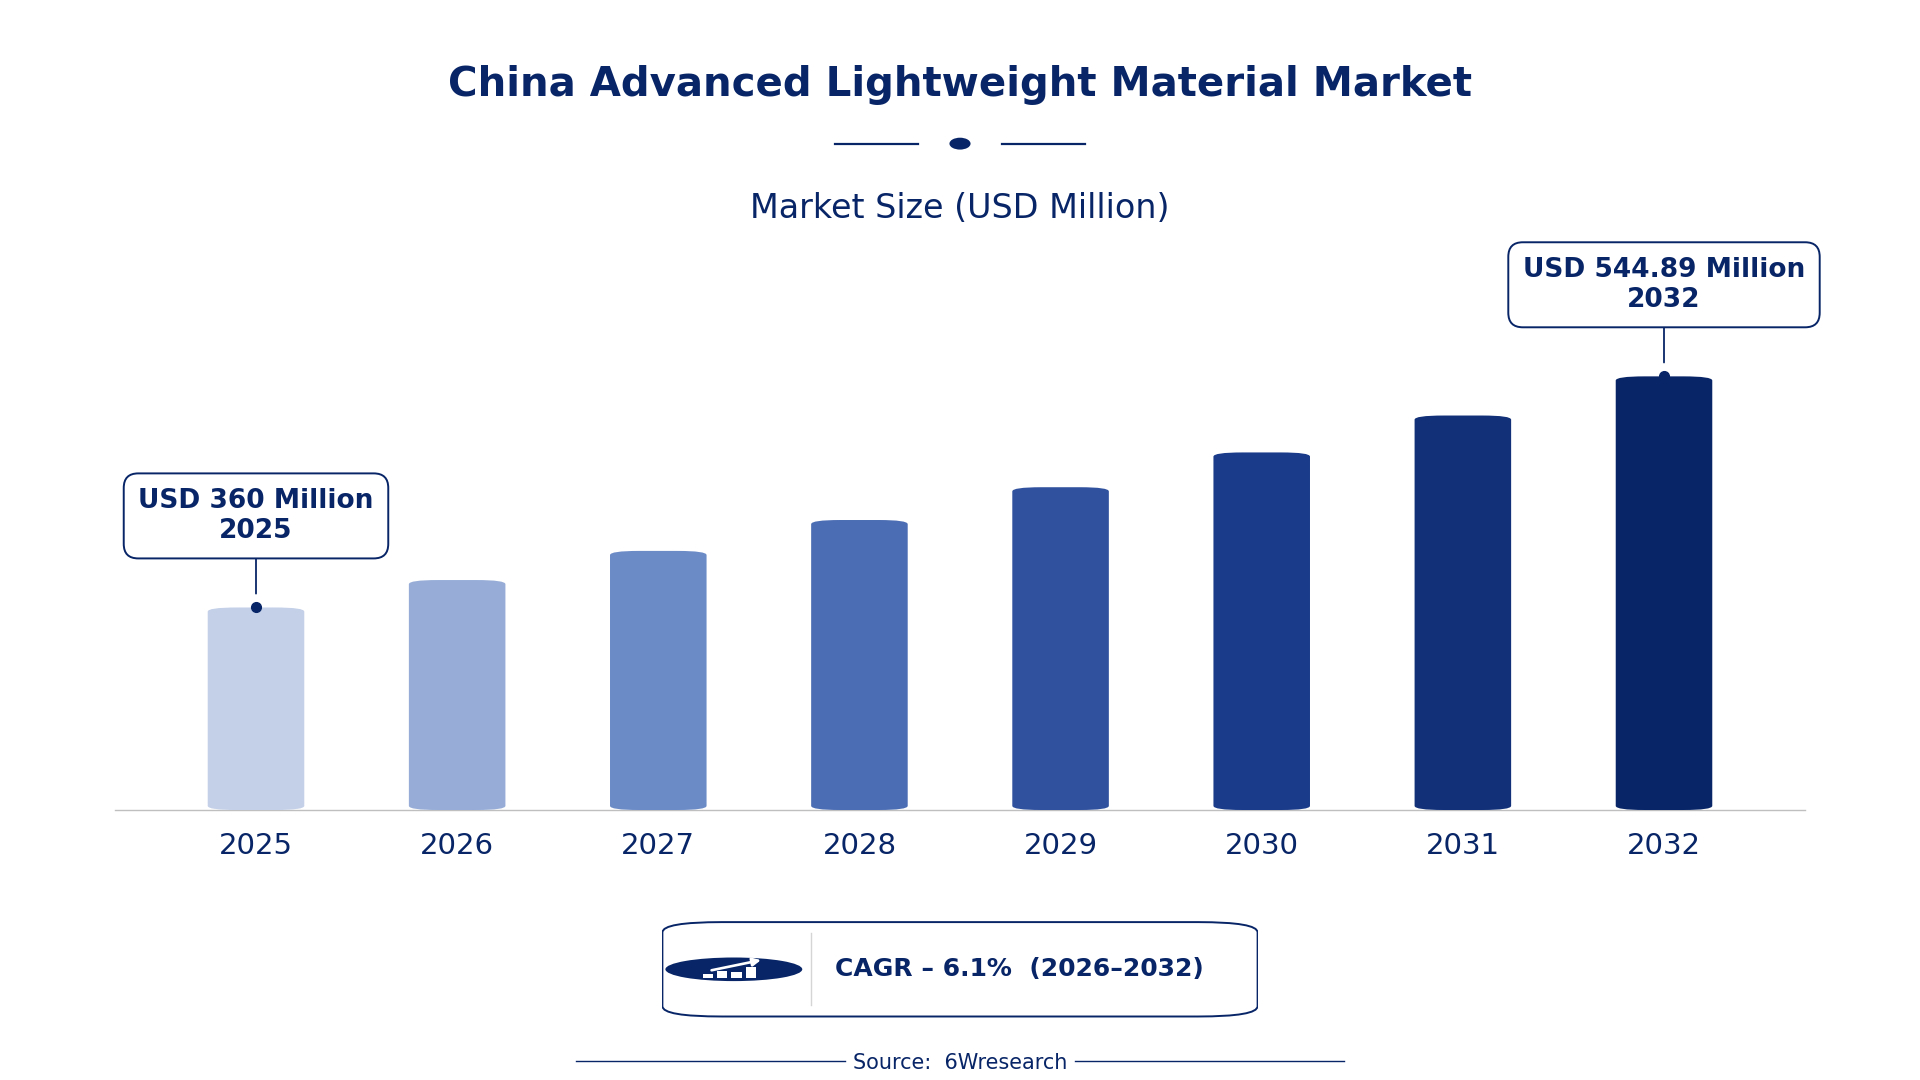
According to 6Wresearch internal database and industry insights, the China Advanced Lightweight Material Market was valued at USD 360.0 million in 2025 and is projected to reach USD 544.89 million by 2032, growing at a CAGR of approximately 6.1% during 2026–2032.
China Advanced Lightweight Material Market Highlights
| Report Metric | Details |
| Report Name | China Advanced Lightweight Material Market |
| Market Size 2025 | USD 360.0 million |
| Market Size 2032 | USD 544.89 million |
| Absolute Growth 2025–2032 | USD 184.89 million |
| CAGR 2026–2032 | 6.1% |
| Peak Annual Growth | 8.0% in 2031 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Advanced Lightweight Material Market, 2025 | Carbon Fiber Reinforced Polymer (54% share) |
| Leading Material Type, 2025 | Composite (39% share) |
| Leading Composition Type, 2025 | Epoxy Matrix (39% share) |
| Leading Structural Use Case, 2025 | Aircraft Panels (44% share) |
| Leading End User Sector, 2025 | Aerospace Manufacturers (53% share) |
| Fastest-Growing Advanced Lightweight Material Market | Magnesium Alloys (7.6% CAGR) |
| Fastest-Growing Composition Type | Ti-6Al-4V (7.2% CAGR) |
| Fastest-Growing Structural Use Case | Engine Components (8.4% CAGR) |
| Fastest-Growing End User Sector | Defense Vehicles (7.7% CAGR) |
| Growing Sector | Defense Vehicles |
| Key End Users | Aerospace Manufacturers, Defense Vehicles, Aviation Interiors, Spacecraft Components |
China Advanced Lightweight Material Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
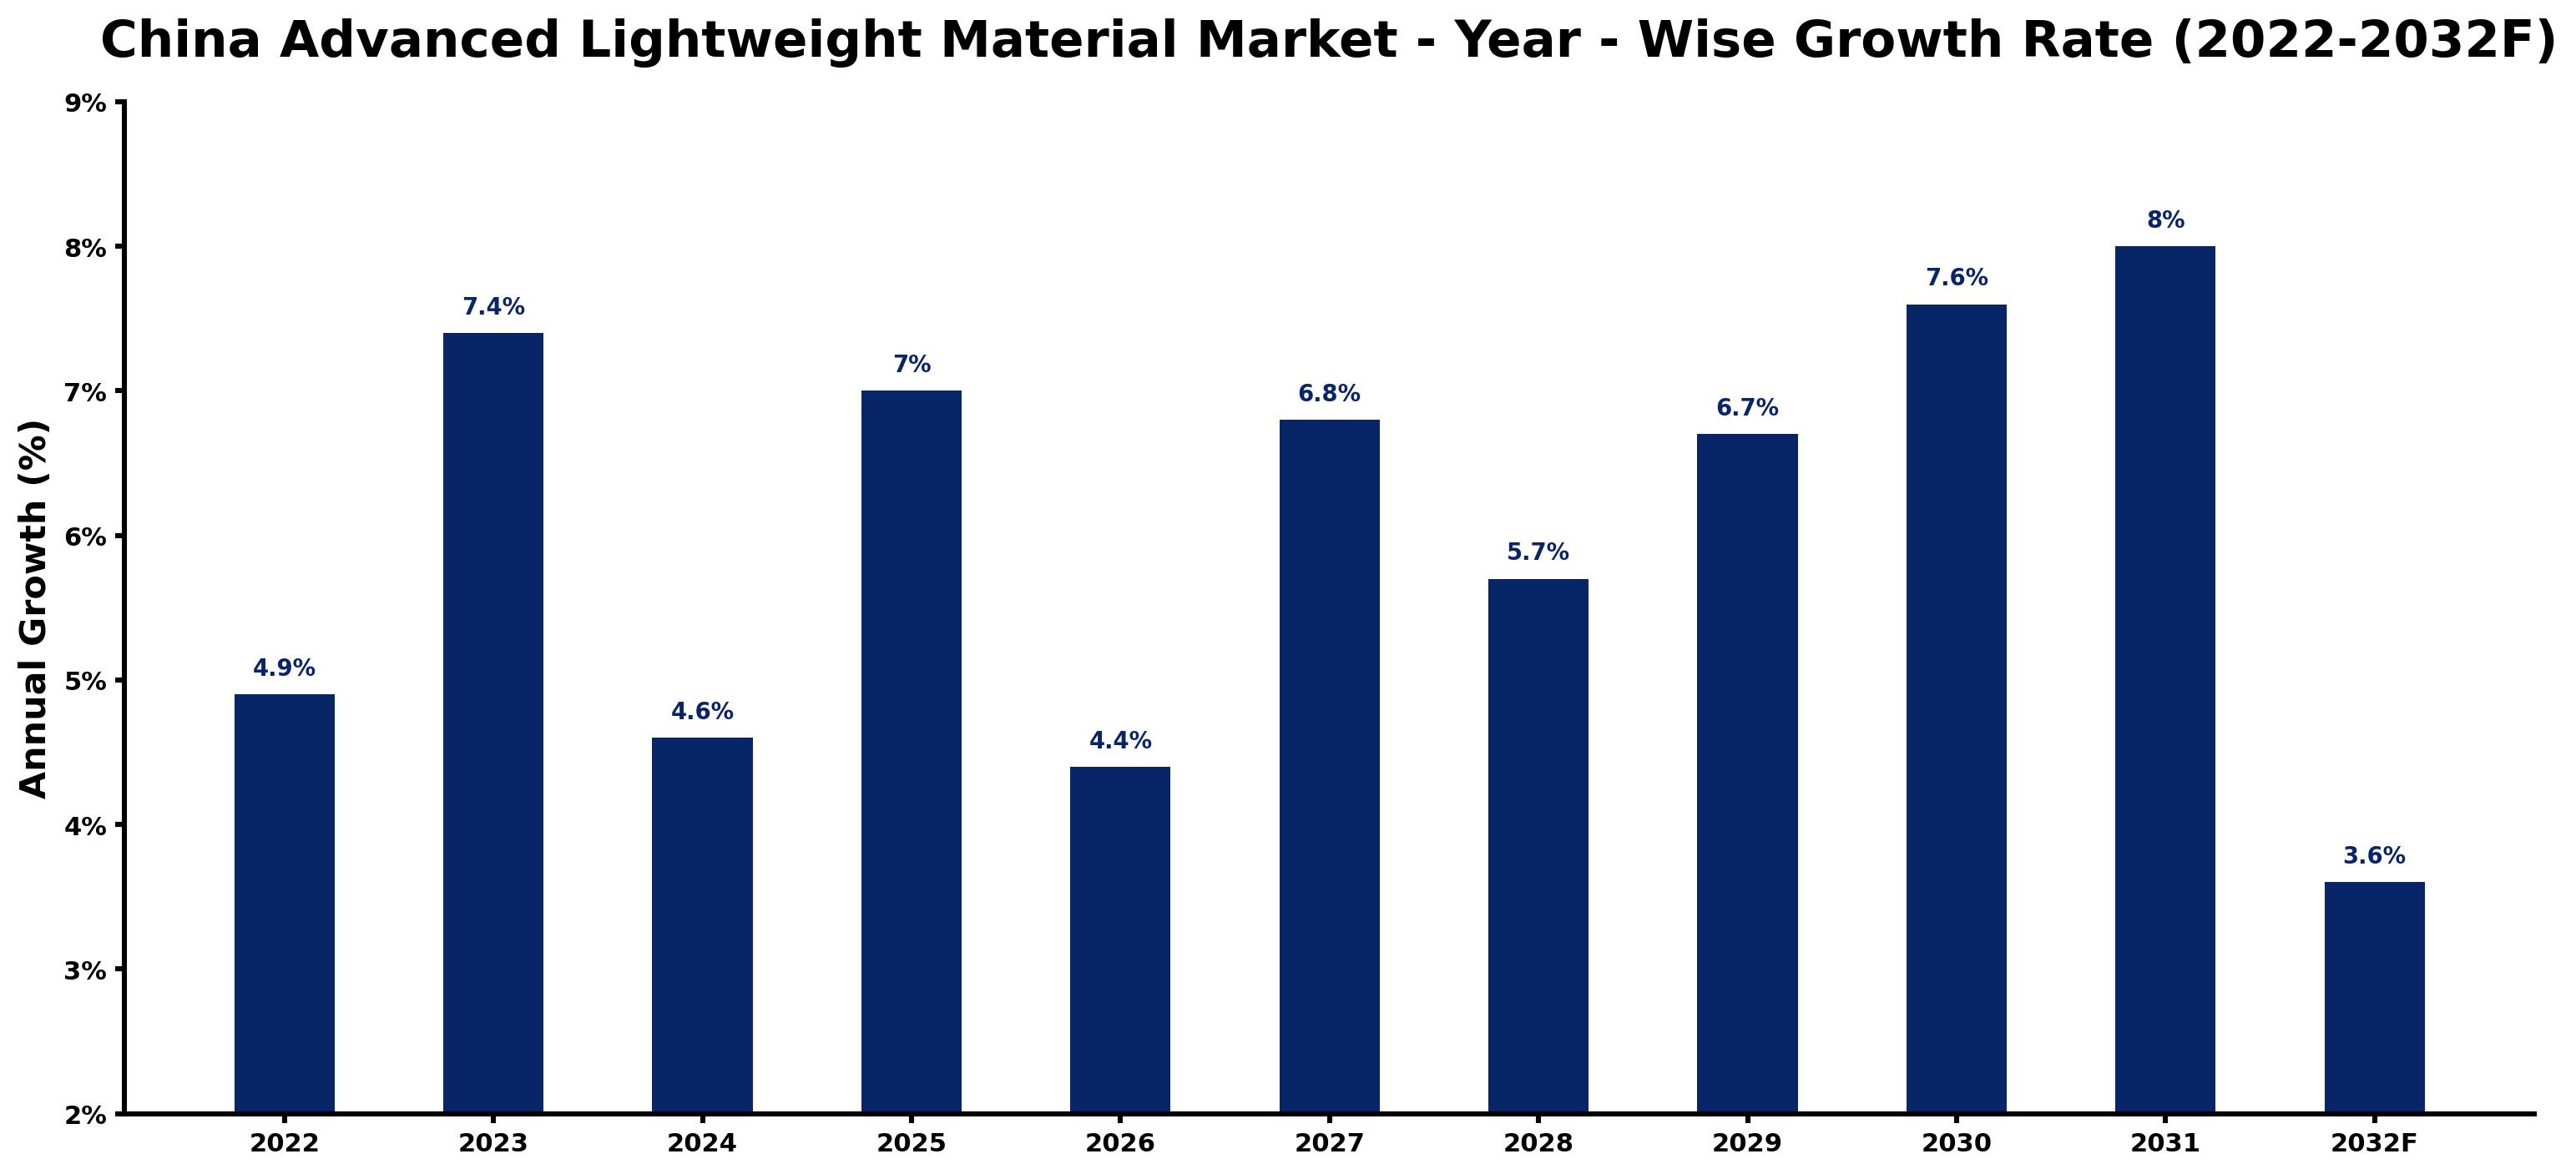
Annual growth estimates for each year appear below with the principal reason behind them, explaining the shifts that set the pace of the market.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 4.9 | The market exhibited steady demand from domestic manufacturers and exports. |
| 2023 | 7.4 | The aerospace sector's expansion significantly boosted demand for lightweight materials. |
| 2024 | 4.6 | Growth slowed as manufacturers adjusted to supply chain challenges. |
| 2025 | 7.0 | Increased production of carbon fiber reinforced polymers drove faster growth. |
| 2026 | 4.4 | A temporary slowdown occurred as the market stabilised after rapid growth. |
| 2027 | 6.8 | Demand surged again due to rising investments in aerospace manufacturing. |
| 2028 | 5.7 | Growth decelerated as the market began to normalise after previous peaks. |
| 2029 | 6.7 | A renewed focus on lightweight materials in automotive applications spurred growth. |
| 2030 | 7.6 | The aerospace sector's growth trajectory continued to support demand for materials. |
| 2031 | 8.0 | A peak in growth was reached, driven by advancements in manufacturing technologies. |
| 2032 | 3.6 | Growth slowed as the market matured, but demand remained strong. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Advanced Lightweight Material Market Synopsis
The Advanced Lightweight Material Market in China includes engineered composites such as carbon fiber reinforced polymers and magnesium alloys, crafted for high strength-to-weight ratios. These materials are developed using techniques like pultrusion and additive manufacturing. Growth in this market stems from robust demand in the aerospace and automotive sectors. The aerospace industry is expected to reach $1 trillion by 2035, further increasing the need for lightweight materials. Government initiatives like the 'Advanced Material Innovation Program' are driving progress in this area.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increased production capacity for carbon fiber reinforced polymers | Driver | High | Carbon Fiber Reinforced Polymer |
| Growing demand from the aerospace sector | Driver | High | Aerospace Manufacturers |
| Investment in automotive lightweighting technologies | Opportunity | Medium | Magnesium Alloys |
| Expansion of aerospace manufacturing hubs | Opportunity | High | Carbon Fiber Reinforced Polymer |
| High production costs of advanced materials | Restraint | High | Composite |
| Limited awareness of lightweight material benefits | Restraint | Medium | Titanium Alloys |
| Supply chain disruptions affecting material availability | Challenge | High | Magnesium Alloys |
| Competition from alternative materials | Challenge | Medium | Carbon Fiber Reinforced Polymer |
Evaluation of Drivers in China Advanced Lightweight Material Market (2026–2032)
The factors lifting demand, and the evidence behind each, are summarised below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Expansion of carbon fiber production capabilities | Carbon Fiber Reinforced Polymer | China produced 200,000 tons of carbon fiber in 2022, increasing availability for manufacturers. |
| Rising investments in aerospace projects | Titanium Alloys | The aerospace sector's growth to $1 trillion by 2035 will drive demand for lightweight materials. |
| Increased adoption of lightweight materials in automotive | Magnesium Alloys | China's magnesium alloy production reached 1 million tons in 2022, primarily for automotive applications. |
| Government support for advanced material innovation | Composite | The 'Advanced Material Innovation Program' initiated in 2021 promotes lightweight materials in strategic sectors. |
| Growing installed base of commercial aircraft | Aircraft Panels | The installed base of commercial aircraft is expected to exceed 7,000 by 2030, boosting demand for lightweight materials. |
Market growth for Advanced Lightweight Material in China is underpinned by significant investments in aerospace projects, increasing the demand for lightweight structures. The aerospace sector's growth to $1 trillion by 2035 will drive purchases of advanced materials. In 2022, China produced 200,000 tons of carbon fiber, enhancing availability for manufacturers. With the installed base of commercial aircraft expected to exceed 7,000 by 2030, demand for lightweight materials will continue to rise.
Evaluation of Restraints in China Advanced Lightweight Material Market
The following restraints limit how fast demand can grow.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| High production costs of advanced lightweight materials | Composite | Production costs remain elevated, limiting affordability for manufacturers and end-users. |
| Limited awareness of lightweight material benefits among manufacturers | Titanium Alloys | Many manufacturers are unaware of the advantages of lightweight materials, hindering adoption. |
| Supply chain disruptions affecting material availability | Magnesium Alloys | Global supply chain issues have led to material shortages, impacting production timelines. |
| Competition from alternative materials | Carbon Fiber Reinforced Polymer | Alternative materials are often cheaper, making them appealing to cost-sensitive buyers. |
| Regulatory hurdles in material certification | Composite | Stringent certification processes delay the introduction of new lightweight materials into the market. |
China Advanced Lightweight Material Market Challenges
Producers in the China Advanced Lightweight Material Market face intense competition, which compresses profit margins and compels them to lower prices. Automotive manufacturers are grappling with rising costs as the demand for lightweight materials escalates, potentially leading to budget overruns and project delays. Supply chain disruptions, worsened by recent global events, hinder timely access to essential materials, causing delays for producers and jeopardising contract fulfilment. A lack of skilled workers in advanced manufacturing techniques limits production efficiency, resulting in longer lead times for automotive and aerospace buyers who require materials urgently.
Trends in the China Advanced Lightweight Material Market
Four trends stand out in the China Advanced Lightweight Material Market.
- Shift from Traditional to Advanced Lightweight Materials: In 2021, the 'Green Manufacturing Program' initiated a shift towards advanced lightweight materials to lower emissions in manufacturing. This trend is evident as manufacturers increasingly adopt these materials to comply with environmental standards, with demand projected to rise by 15%.
- Transition from Metal to Composite Materials: The aerospace sector is moving from traditional metals to composites, motivated by the need for weight reduction. The National Standard for Composite Materials updated in 2022 supports this transition, improving quality control, and is expected to boost composite usage by 20%.
- Emergence of Magnesium Alloys in Automotive: Magnesium alloys are becoming popular in the automotive sector as manufacturers pursue weight reduction. With China's magnesium alloy production reaching 1 million tons in 2022, this trend is forecasted to grow, increasing demand by 10%.
- Growing Focus on Aerospace Manufacturing Hubs: The Shanghai region is evolving into a key hub for aerospace manufacturing, hosting multiple advanced lightweight material producers. This focus is expected to enhance production capacity by 25% over the next five years.
Investment Opportunities in the China Advanced Lightweight Material Market
The following opportunities in the China Advanced Lightweight Material Market pair current demand with a clear way in.
- Aerospace Manufacturing Hubs: The Shanghai region is broadening its aerospace manufacturing capabilities, generating a demand for advanced lightweight materials. As the aerospace sector is projected to expand, suppliers can forge partnerships with local manufacturers to satisfy this need.
- Automotive Lightweighting Solutions: With China's magnesium alloy production reaching 1 million tons in 2022, there is a rising opportunity for suppliers to offer lightweight materials to automotive manufacturers. Collaborating with automotive OEMs can facilitate market entry.
- Research and Development in Lightweight Materials: The 'Advanced Material Innovation Program' backs research in lightweight materials, presenting opportunities for investment in new solutions. Engaging with research institutions can enhance product offerings.
- Certification Services for Lightweight Materials: As regulatory challenges exist in material certification, there is an opportunity for certification bodies to offer services to manufacturers. This can streamline the approval process for new lightweight materials.
Government Initiatives in the China Advanced Lightweight Material Market
The '14th Five-Year Plan for National Economic and Social Development', issued by the National Development and Reform Commission in 2021, highlights the advancement of lightweight materials. This plan encourages investment in research and production capabilities, promoting progress in the sector. Additionally, the 'National Standard for Composite Materials' was updated in 2022 by the Standardization Administration of China to improve quality control in lightweight materials, ensuring that products meet stringent safety and performance criteria.
In 2023, the 'Aerospace Industry Development Fund' was established with an initial budget of $500 million to support innovations in lightweight materials. This fund, administered by the Ministry of Industry and Information Technology, aims to boost research and development efforts in the aerospace sector. Furthermore, the 'Green Manufacturing Program' initiated in 2021 promotes the use of lightweight materials to reduce emissions in manufacturing processes, aligning with national sustainability goals.
Future Insight of the China Advanced Lightweight Material Market
By 2032, the China Advanced Lightweight Material Market will experience notable changes driven by key initiatives. The 14th Five-Year Plan will prioritise advancements in lightweight materials, particularly for aerospace and automotive applications. The aerospace sector's growth is expected to generate strong demand for advanced composites, with the installed base of commercial aircraft projected to exceed 7,000 by 2030. The Advanced Material Innovation Program will stimulate research and development, enabling suppliers to refine production processes and meet evolving market demands.
Market Segmentation Analysis
Each segment group is reviewed below, with the leader by share and the fastest grower by CAGR.
By Advanced Lightweight Material Market – Carbon Fiber Reinforced Polymer Dominated, Magnesium Alloys Expected to Grow Fastest
According to Ravi Bhandari, Research Head at 6Wresearch, the largest advanced lightweight material market category in 2025 was Carbon Fiber Reinforced Polymer, with a 54% share of total revenue. Carbon fiber reinforced polymers dominate the market due to their essential role in the aerospace sector, which is expected to reach $1 trillion by 2035. Their unparalleled strength-to-weight ratio makes them vital for constructing lightweight aircraft, ensuring sustained demand. Magnesium Alloys are projected to grow fastest, at a CAGR of 7.6% during 2026–2032. The magnesium alloys segment is set for rapid growth, largely due to their significant application in the automotive industry for weight reduction. With production reaching 1 million tons in 2022, demand for these materials is anticipated to rise sharply in the near future. Suppliers need to scale production to satisfy the growing demand for advanced lightweight materials in both aerospace and automotive applications.
By Material Type – Composite Dominated and Is Expected to Record the Fastest Growth
Composite held a 39% share of the China Advanced Lightweight Material Market by material type in 2025. Composite materials lead the market thanks to their extensive use across various industries, delivering high performance and durability. Their adaptability is essential for manufacturers focused on enhancing efficiency and minimising weight in their products. Its lead should widen, with a projected CAGR of 7.3% during 2026–2032, the highest in this split. The composite segment is also the fastest-growing, driven by continuous innovations and expanding applications in sectors such as aerospace and automotive. As manufacturers increasingly embrace composites for their lightweight benefits, growth in this area is expected to accelerate significantly. Buyers should prioritise investments in composite materials to leverage their performance advantages and weight reduction capabilities across a range of applications.
By Composition Type – Epoxy Matrix Dominated, Ti-6Al-4V Expected to Grow Fastest
With a 39% revenue share in 2025, Epoxy Matrix was the largest composition type category. Epoxy matrix materials hold the largest share as they are critical for bonding in composite materials, ensuring structural integrity in various applications. Their widespread use in aerospace components underlines their importance in the advanced lightweight materials market. Over 2026–2032, Ti-6Al-4V is expected to post the fastest growth, at a CAGR of 7.2%. Ti-6Al-4V is gaining traction as the fastest-growing composition type, primarily due to its standardisation in aerospace components. As demand for high-performance materials increases, this titanium alloy's growth will likely continue to rise. Suppliers need to focus on developing advanced epoxy and titanium-based materials to cater to the evolving needs of the aerospace industry.
By Structural Use Case – Aircraft Panels Dominated, Engine Components Expected to Grow Fastest
Aircraft Panels accounted for a 44% market share by structural use case in 2025. Aircraft panels represent the largest share in structural use cases, as they are the primary application in aerospace manufacturing. The increasing installed base of commercial aircraft in China, expected to exceed 7,000 by 2030, drives demand for these panels. The quickest growth will come from Engine Components, forecast to expand at a CAGR of 8.4% between 2026 and 2032. Engine components are the fastest-growing structural use case, essential for performance in aerospace engines. As the aerospace sector expands, the need for lightweight and efficient engine components will continue to rise. Manufacturers should prioritise the development of advanced materials for engine components to capitalise on the growing aerospace market.
By End User Sector – Aerospace Manufacturers Dominated, Defense Vehicles Expected to Grow Fastest
In 2025, Aerospace Manufacturers led the end user sector split with a 53% share. Aerospace manufacturers are the largest consumers of advanced lightweight materials, motivated by the need for high-performance components in aircraft. The sector's anticipated growth underscores the increasing reliance on lightweight materials for aerospace applications. Defense Vehicles are projected to grow fastest, at a CAGR of 7.7% during 2026–2032. Defense vehicles are the fastest-growing end user sector, as military applications increasingly demand lightweight materials to enhance performance. The ongoing modernisation of military capabilities will further drive growth in this sector, creating new opportunities for suppliers. Suppliers should focus on the defense sector to capitalise on emerging opportunities within the advanced lightweight materials market.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Advanced Lightweight Material Market Outlook
- Market Size of China Advanced Lightweight Material Market, 2025
- Forecast of China Advanced Lightweight Material Market, 2032
- Historical Data and Forecast of China Advanced Lightweight Material Revenues & Volume for the Period 2022 - 2032F
- China Advanced Lightweight Material Market Trend Evolution
- China Advanced Lightweight Material Market Drivers and Challenges
- China Advanced Lightweight Material Price Trends
- China Advanced Lightweight Material Porter's Five Forces
- China Advanced Lightweight Material Industry Life Cycle
- Historical Data and Forecast of China Advanced Lightweight Material Market Revenues & Volume By Advanced Lightweight Material Market for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Lightweight Material Market Revenues & Volume By Carbon Fiber Reinforced Polymer for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Lightweight Material Market Revenues & Volume By Magnesium Alloys for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Lightweight Material Market Revenues & Volume By Thermoplastics for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Lightweight Material Market Revenues & Volume By Titanium Alloys for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Lightweight Material Market Revenues & Volume By Material Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Lightweight Material Market Revenues & Volume By Composite for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Lightweight Material Market Revenues & Volume By Metal Alloy for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Lightweight Material Market Revenues & Volume By Polymer for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Lightweight Material Market Revenues & Volume By Lightweight Metal for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Lightweight Material Market Revenues & Volume By Composition Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Lightweight Material Market Revenues & Volume By Epoxy Matrix for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Lightweight Material Market Revenues & Volume By Mg-Zn-Zr Composition for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Lightweight Material Market Revenues & Volume By Polyether Ether Ketone for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Lightweight Material Market Revenues & Volume By Ti-6Al-4V for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Lightweight Material Market Revenues & Volume By Structural Use Case for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Lightweight Material Market Revenues & Volume By Aircraft Panels for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Lightweight Material Market Revenues & Volume By Frame & Chassis for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Lightweight Material Market Revenues & Volume By Interior Panels for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Lightweight Material Market Revenues & Volume By Engine Components for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Lightweight Material Market Revenues & Volume By End User Sector for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Lightweight Material Market Revenues & Volume By Aerospace Manufacturers for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Lightweight Material Market Revenues & Volume By Defense Vehicles for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Lightweight Material Market Revenues & Volume By Aviation Interiors for the Period 2022 - 2032F
- Historical Data and Forecast of China Advanced Lightweight Material Market Revenues & Volume By Spacecraft Components for the Period 2022 - 2032F
- China Advanced Lightweight Material Import Export Trade Statistics
- Market Opportunity Assessment By Advanced Lightweight Material Market
- Market Opportunity Assessment By Material Type
- Market Opportunity Assessment By Composition Type
- Market Opportunity Assessment By Structural Use Case
- Market Opportunity Assessment By End User Sector
- China Advanced Lightweight Material Top Companies Market Share
- China Advanced Lightweight Material Competitive Benchmarking By Technical and Operational Parameters
- China Advanced Lightweight Material Company Profiles
- China Advanced Lightweight Material Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By Advanced Lightweight Material Market
- Carbon Fiber Reinforced Polymer
- Magnesium Alloys
- Thermoplastics
- Titanium Alloys
By Material Type
- Composite
- Metal Alloy
- Polymer
- Lightweight Metal
By Composition Type
- Epoxy Matrix
- Mg-Zn-Zr Composition
- Polyether Ether Ketone
- Ti-6Al-4V
By Structural Use Case
- Aircraft Panels
- Frame & Chassis
- Interior Panels
- Engine Components
By End User Sector
- Aerospace Manufacturers
- Defense Vehicles
- Aviation Interiors
- Spacecraft Components






































